Canada’s Top 100 Retailers Ranked Pre-COVID-19

Date:

Share post:

Prior to the COVID-19 store shutdowns, a few large store-based conglomerates effectively controlled a large proportion of the current Canadian non-auto retail sales environment, according to the latest CSCA Retail 100, created by the Centre for the Study of Commercial Activity at Ryerson University.

The report says its latest data shows that this long-standing trend has continued apace as in 2018 the 10 largest conglomerates controlled 48 percent of national retail sales, increasing from 43 percent in 2014.

Given that many of the top 10 retailers had been deemed ‘essential’ as stores shut temporarily to the COVID-19 pandemic, they will likely maintain their place in terms of rankings and see even more market share.

According to the report, here are the top 10 retail conglomerates in the Canadian market and their banners:

  1. George Weston Limited, Canada (Shoppers Drug Mart, Loblaws, Real Canadian Superstore);

  2. Costco, Inc., U.S.;

  3. Empire Company Ltd., Canada (Sobeys, Safeway, IGA, Farm Boy)

  4. Walmart Stores Inc., U.S.;

  5. Metro Inc., Canada (Metro, Food Basics, Jean Coutu Pharmacy)

  6. Canadian Tire Corporation, Canada (Canadian Tire, Mark’s Work Wearhouse, SportChek)

  7. McKesson Corporation, U.S. (IDA Pharmacy, Uniprix, Rexall Drug Store)

  8. Lowe’s, U.S. (Lowe’s, Rona, Rona Home & Garden);

  9. The Home Depot Inc., U.S.; and

  10. Home Hardware Stores Ltd., Canada (Home Hardware, Home Hardware Building Centre)

PHOTO: COSTCO

“It’s a small group of very large retailers that are controlling a large part of the Canadian retail pie basically. So there’s a dominance to what they do. That’s really a key aspect of the Canadian retail marketplace,” said Tony Hernandez, Director & Eaton Chair in Retailing for the CSCA, and Professor in the School of Retail Management & Department of Real Estate Management at Ryerson’s Ted Rogers School of Management.

“You’ve got this dominance really of the big grocery and general merchandise retailers that kind of take a large proportion of retail sales in Canada. That’s one of the key trends.”

The report broke the overall sales down to the top 100 retail chains operating in Canada as ranked by total estimated annual retail sales in fiscal 2018/2019.

The report said the top 100 retail conglomerates account for close to 70 per cent of non-automotive retail sales in Canada in 2018, declining from 71.4 percent in 2014.

“From the retailer perspective, these big conglomerates can be looking at marketplaces and saying okay this is a market where we need this banner. So it gives them a lot of flexibility to operate across Canada using multiple banners to essentially meet the local needs of Canadian shoppers,” said Hernandez. “Ultimately all of these companies the sales that they create are driven by local demand. It’s the ability for these big companies to choose the banner that they can operate within a given market in order to kind of maximize the sales within that marketplace.”

The number of retail conglomerates that operate with at least $1 billion in sales has reached 31 in Canada, he said, adding that six retail conglomerates are in the $10-billion club.

“So we’ve got quite a concentrated retail market with some very big conglomerates controlling a large amount of sales and controlling a large amount of stores as well,” said Hernandez.

“It ultimately comes down to the demand from Canadian consumers. Retailers are going to go where there is a market and U.S. retailers are going to be looking to either enter in or expand in the Canadian marketplace based on how vibrant they see the Canadian marketplace - maybe even relative to their own domestic market. So I think it’s really reflective that international retailers, particularly U.S. retailers, still see Canada as a viable retail market to be operated in and expanded.”
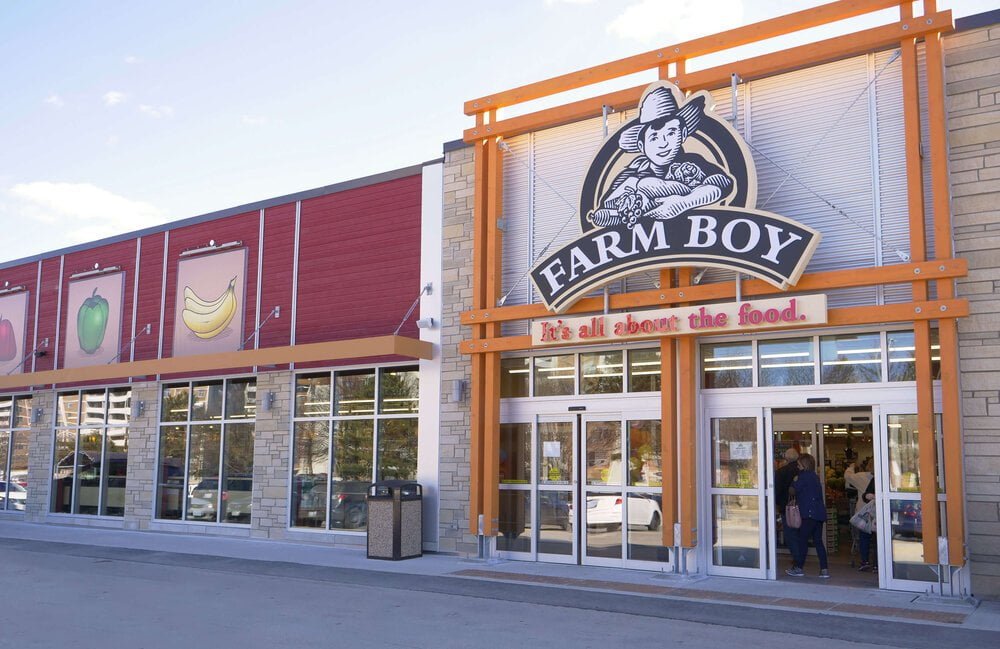
PHOTO: FARM BOY

The report said the bulk of retail sales are in groceries and beverage stores (20.3 percent of national sales), general merchandise (17.8 percent) and health and personal care (8.4 percent). Groceries and beverage stores are dominated by Canadian headquartered chains. The general merchandise category is dominated by US headquartered operations. Health and personal care are dominated by Canadian headquartered businesses.

While the level of domination by the 10 largest chains is about the same for both 2014 and 2018, the 100 largest chains in 2014 contributed a greater share of national sales (65 percent) than those in 2018. Canadian headquartered chains contributed 6.4 percentage points less to the 2018 total than in 2014, while the contribution of chains headquartered in the US increased by 5.5 percentage points and from elsewhere in the world by 0.9 percentage points, added the report.

There’s no surprise that the online retail marketplace continues to grow. The highest shares of ‘online’ expenditure were in entertainment (30 percent) and electronics (28 percent). The lowest shares were in groceries/food/alcohol (less than five percent).

“Every retailer is grappling with the balance between online and offline. How do we meet the needs of our consumers in an efficient and profitable way? I think from a consumer side we all are increasingly getting more greedy as consumers. We want more and more and we want to pay less and less. So it’s a challenge and dynamic for retailers,” said Hernandez.
2 COMMENTS

Comments are closed.

RELATED ARTICLES

Subscribe to the Newsletter

Subscribe

* indicates required

RECENT articles

Daily Synopsis: October 8, 2026

Holiday spending expected to be down as consumers struggle, Newmarket Walmart closing while Kingston announced, grocery store opens in Winnipeg food desert, T&T opens 1st Ontario cafe, and other news.

Aritzia reports Q2 Fiscal 2027 financial results, net revenue up 44.1% to $1.17 billion

Net revenue in Canada increased 19.8% to $390.4 million, compared to $326.0 million in Q2 2026.

Canada’s Menswear Market Is Being Rebuilt as Retailers Invest in Premium and Luxury

Canada’s premium and luxury menswear market is attracting major investment as Harry Rosen, Holt Renfrew, Simons, independent retailers and global fashion houses expand, renovate and rethink physical retail across Canada, even after the loss of major department-store capacity.

Ralph Lauren Home Joins Maison Territo in Montréal

Maison Territo adds Ralph Lauren Home to its curated catalogue, bringing the American brand’s furniture and distinctive design aesthetic to Montréal.

Casavogue Launches Buy More, Save More Promotion in Montréal

Casavogue’s Buy More, Save More promotion offers $500 in savings for every $3,000 spent on a wide selection of furniture.

Egg Club and Serruya Private Equity Announce Joint Venture to Fuel Global Growth  

New partnership will support expansion of the Toronto-born breakfast brand across North America and international markets.

Kits Eyecare report preliminary Q3 results, substantial growth in total revenue

Total Revenue grew 21.6% year-over-year to approximately $63.7 million, accelerating from 17.8% growth in Q2 2026.

Canadian Shoppers Grow More Selective as Holiday Spending Intentions Weaken

A new Stifel survey finds Canadian consumers entering the 2026 holiday season with weaker spending conviction. Holiday budget intentions fell sharply, while value retail remains resilient and higher-income shoppers show growing caution across several discretionary categories.

Selwyn Crittendon moving on to different role at IKEA

He will remain with IKEA Canada until December 31, and the company expects to announce a successor in the coming months.

Scarce Retail Space Gives Canadian Landlords New Leverage

Canada’s tight retail real estate market is shifting negotiating power toward landlords as limited construction and high occupancy constrain available space. JLL, Primaris, RioCan, McDonald’s and Empire executives discuss the implications, including the temporary opportunity created by former Hudson’s Bay locations.

Canadian Holiday Shoppers Start Early, Creating New Opportunities for Retail Advertisers

Vistar Media research finds OOH advertising is influencing consumer decisions, online searches and brand consideration ahead of the holiday shopping season.

Why Grocery Pricing Rules Could Help Some Retailers and Hurt Others

Minimum advertised pricing can make it harder for discount grocers to promote lower prices. Independent retailers argue those same rules can help them compete against national chains with greater purchasing power.

Canadian Holiday Shoppers Turn to Early Deals and AI as Budgets Face Pressure: Accenture

Accenture forecasts average holiday gifting spend of $717 as consumers seek value, compare prices and use GenAI tools to find deals and products.

Tax and cost pressures holding back most small business from expanding: CFIB 

A CFIB survey finds just 7% of small businesses plan significant growth over the next year, with taxes and rising costs cited as key barriers to expansion.

Daily Synopsis: October 7, 2026

Trade war shifting consumer habits, retail crime more sophisticated say experts, Calgary's CF Chinook expands retail, Sherwood Park welcoming 7 restaurants in new plaza, T&T Supermarket opening largest Ontario store this week, and other news.

Weston Family’s Wittington to Acquire Boots in US$8.9-Billion Deal

The Weston family is making a major return to British retail with an US$8.9-billion acquisition of Boots, a pharmacy, healthcare and beauty giant with striking parallels to Shoppers Drug Mart.

Lululemon Overhauls Leadership, Taps Walmart Canada Executive as North American Sales Slide

Lululemon is restructuring its leadership team just 29 days into Heidi O’Neill’s tenure, recruiting senior executives from Walmart Canada and Athleta as the Vancouver-based retailer focuses on product, brand and operational execution.

Retail Insider Releases Q3 2026 Canadian Retail Reports

Retail Insider has released 18 Q3 2026 reports examining Canadian retail sectors, consumer behaviour and the businesses supporting the industry. The collection brings together reporting and data on store investment, real estate, technology, supply chains, marketing, security and policy.

Entertainment Becomes a New Anchor for Canadian Shopping Centres

Entertainment operators are taking larger positions in Canadian shopping centres as landlords redevelop former department stores and add attractions designed to extend visits. JLL is tracking a 16.5-million-square-foot North American pipeline as concepts including Playdium, Activate, Splitsville and Forever Young expand.

Kidfresh Expands to More Than 300 Canadian Stores as Kids’ Frozen Meal Category Grows

The brand is adding Metro Ontario and Pattison Food Group locations while making and packaging its Canadian lineup domestically.