The Hudson’s Bay Company is reporting a stronger-than-expected financial position as it winds down operations under court protection. According to a newly filed Report of the Monitor dated April 22, 2025, the company’s cash flow and retail sales have significantly outperformed projections, offering a rare bright spot amid the department store’s looming closure of most of its locations.
The report, prepared by Alvarez & Marsal Canada Inc. — the court-appointed Monitor overseeing Hudson’s Bay’s proceedings under the Companies’ Creditors Arrangement Act (CCAA) — provides a detailed view of the retailer’s financial activity up to April 18, 2025, and includes a forward-looking 13-week cash flow forecast.
Positive Net Cash Flow Surprises Observers
Between March 15 and April 18, Hudson’s Bay generated $238.2 million in total receipts, just shy of its $241.1 million projection. However, due to lower-than-expected disbursements, the company recorded a net cash flow of $112.5 million, surpassing the projected figure by nearly $30 million.
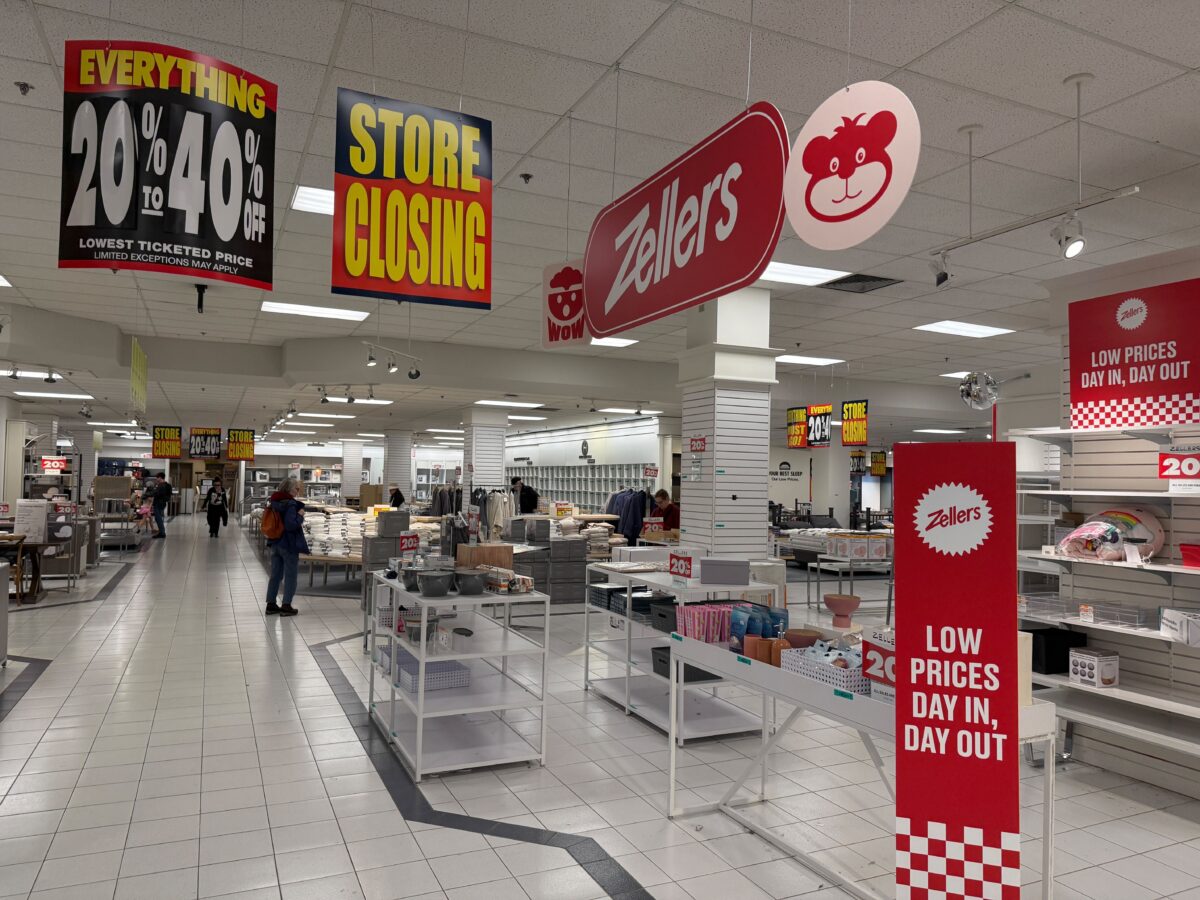
The company’s closing cash balance was $122.5 million, significantly higher than the anticipated $71.5 million. These results underscore the success of the company’s store liquidation efforts, which have benefited from heightened consumer interest and increased in-store and online traffic since the company’s filing for creditor protection on March 7.
Liquidation Sales Drive Retail Receipts
Retail receipts during the reporting period surpassed expectations, offering a much-needed financial boost for Hudson’s Bay as it continues its wind-down process. Between March 15 and April 18, 2025, the company brought in approximately $235.7 million in retail sales, outperforming the projected figure by nearly $9.6 million.
According to the Monitor’s report, this positive variance was driven by heightened consumer demand amid the ongoing liquidation, which generated increased foot traffic in stores and elevated activity on the company’s e-commerce platform. Consignment goods from participating vendors also contributed to the strong performance, with several high-performing categories exceeding internal forecasts. Although the redemption of gift cards came in higher than anticipated—slightly diminishing net sales—the overall volume of purchases was enough to more than offset this impact.
Still, the Monitor noted a recent softening in sales momentum as liquidation events mature and consumer urgency fades, suggesting a potential plateau in receipts over the coming weeks.
Operating Costs and Vendor Fees Lower Than Expected
While Hudson’s Bay experienced stronger-than-forecast sales, its ability to manage expenses also played a key role in achieving a better-than-expected cash position. The company reported total disbursements of $125.7 million during the reporting period—well below the projected $158.6 million. A significant portion of this $33 million variance came from reduced operating expenses, which came in $31.4 million under budget.
This savings was attributed to lower-than-expected costs associated with store-level operations, reduced payments to critical vendors, and minimized credit card processing fees. In addition, liquidation consultant fees and expenses were substantially below forecast, with actual disbursements totalling just under $1 million versus a projected $9.8 million. These favourable variances, coupled with lower-than-planned sales tax remittances and deferred shared service payments, further supported the company’s unexpectedly strong cash position.
However, the company did report higher payments to concession and consignment vendors due to the outsized success of consignment merchandise sales—an indication of the liquidation’s relative success in moving high-margin inventory.
Delay in Additional Inventory Creates Future Opportunity
Hudson’s Bay did fall short in one revenue category: “other receipts.” The company had forecast nearly $15.1 million in this category but recorded only $2.5 million, resulting in a $12.6 million shortfall. The variance was caused by a delay in receiving Additional Consultant Goods — merchandise expected to supplement liquidation sales.
This shortfall is not expected to be permanent. The Monitor notes that once these goods arrive and are sold, the company should recover the difference, potentially supporting future weeks of the liquidation process.
Interest Payments Withheld Following Court Ruling
The report also sheds light on interest obligations. Hudson’s Bay did not make interest payments on its FILO Credit Facility or the Pathlight Credit Facility during the reporting period. This was due to the court’s decision not to approve the company’s Restructuring Support Agreement, which would have permitted those interest payments.
As a result, the company saved approximately $3.5 million in interest expenses. Similarly, $21 million in cash collateralization for letter of credit obligations was also withheld, further bolstering the company’s short-term liquidity.
Revised Forecast Projects Modest Growth Through July
Looking ahead, Hudson’s Bay has filed a revised 13-week cash flow forecast covering the period from April 19 to July 18, 2025. The forecast anticipates $331.5 million in total receipts during this period, balanced against $328.4 million in disbursements. If realized, this would result in a modest net cash inflow of approximately $2.1 million over the quarter.
The projection suggests a stabilizing financial picture as liquidation efforts mature and stores move toward closure. While the level of receipts remains relatively strong, it is expected to taper compared to the initial wave of liquidation activity. The revised forecast does not include interest payments on the company’s FILO or Pathlight credit facilities, nor does it account for cash collateralization for letter of credit obligations—both of which were paused following the court’s decision not to approve the proposed Restructuring Support Agreement.
Assuming no major unforeseen disruptions, the company anticipates closing the forecast period with a cash balance of $124.6 million, maintaining the liquidity needed to fulfill operational and wind-down obligations.
Liquidation Strategy Adjusted to Reflect Store Wind-Down
As Hudson’s Bay progresses through its CCAA proceedings, its liquidation strategy has been adjusted to reflect the accelerating wind-down of its retail footprint. The company continues to operate the vast majority of its stores as liquidation outlets, with most locations—including 80 Hudson’s Bay stores, 13 Saks Off Fifth units, and three Saks Fifth Avenue stores—scheduled to close by mid-June.
In preparation for these closures, the company has begun systematically scaling back internal obligations. Salary continuation arrangements for employees terminated prior to the CCAA filing have been discontinued, while post-retirement benefits, including healthcare and dental plans, are scheduled to end by April 30. Payments under the company’s supplemental executive retirement plans (SERPs) have also been suspended.
These measures, implemented in consultation with the Monitor, reflect a broader effort to reduce costs and conserve cash as the retailer nears the final phase of its operations. The store closure timeline, combined with the rationalization of benefits and staffing costs, indicates that the company is following a tightly managed path toward a complete exit from traditional retail operations in Canada.
Monitor Confirms Sufficient Liquidity
Based on current forecasts and performance, the Monitor concludes that Hudson’s Bay will maintain adequate liquidity through the forecast period. As such, the company is positioned to meet its short-term obligations, complete its store liquidation efforts, and continue exploring bids for its remaining assets, including leases, brand intellectual property, and a historic art and artifact collection.
The Monitor’s report highlights the company’s ability to execute a wind-down in a controlled and financially sustainable manner — a rare accomplishment in the realm of retail insolvency.
Conclusion
While Hudson’s Bay’s long-term future remains uncertain, its financial performance during liquidation has defied expectations. With over $120 million in cash on hand and a tight rein on costs, the retailer has bought itself crucial time and breathing room as it finalizes store closures and continues its asset monetization process.
Further updates are expected following the May 1 deadline for binding lease bids and as the Sale and Investment Solicitation Process (SISP) continues to attract interest in Hudson’s Bay’s intellectual property and remaining commercial assets.