Home Blog Page 144

Toronto startup Nüu Catering bets office catering can help drive return-to-office culture

Nüu Catering photo
Nüu Catering photo

A Toronto-based office catering startup is positioning itself at the intersection of workplace culture and the return-to-office push, arguing that companies are underestimating the role food plays in employee engagement and collaboration.

Nüu Catering, launched last October, operates a platform that connects offices with more than 50 local restaurant brands across Toronto, focusing on recurring meal programs for workplaces with between 20 and 200 employees.

Co-founder Fahim Ahmadi said the company was developed in response to changing office dynamics as more employers increase in-person attendance requirements.

“Returning employees to the office is only part of the equation,” Ahmadi said in an interview. “What actually shapes culture and performance is the everyday experience once they’re there.”

The startup enters a market where employers are increasingly trying to improve the in-office experience while balancing hybrid work expectations. Ahmadi said food has become an overlooked part of that equation, particularly when companies rely on what he described as uninspired or repetitive catering options.

“When they order from boring places — cold sandwiches or cheese platters — people don’t gather or engage,” he said. “We want to make office culture fun, and food is the fun part.”

Ahmadi said the business model differs from consumer-focused delivery platforms because office catering orders are typically placed in advance and outside peak restaurant hours, helping restaurants generate more predictable daytime sales.

Drawing on nearly two decades in the restaurant industry, including 16 years operating his own restaurant, Ahmadi said he saw catering as a segment many independent restaurants struggled to fully capitalize on.

Fahim Ahmadi
Fahim Ahmadi

“Office catering is different from platforms like Uber Eats or DoorDash, where orders come during peak hours,” he said. “Catering orders are usually placed before lunch, which helps build momentum for restaurants.”

The company acts as an intermediary between offices and restaurants, handling ordering logistics, scheduling and customer service. Ahmadi described the platform as an “operating system for office catering,” aimed at reducing administrative work for executive assistants and office managers who often coordinate food orders alongside their regular duties.

The company’s recurring business programs allow offices to automate weekly meal scheduling and invoicing while rotating cuisines and restaurant partners.

“Our sweet spot is for 20 to 200 staff, especially recurring orders,” Ahmadi said. “Our business is built on recurring programs where companies order weekly, with different cuisines each time.”

Ahmadi said Nüu selectively partners with smaller independent restaurants rather than large chains, using criteria that include food quality, packaging, customer reviews and delivery reliability.

“We partner only with top restaurants in the city based on reviews and ratings,” he said. “We’re selective about who we onboard.”

The company also removes restaurant partners that fail to meet operational standards, including repeated delivery delays, packaging issues or customer complaints.

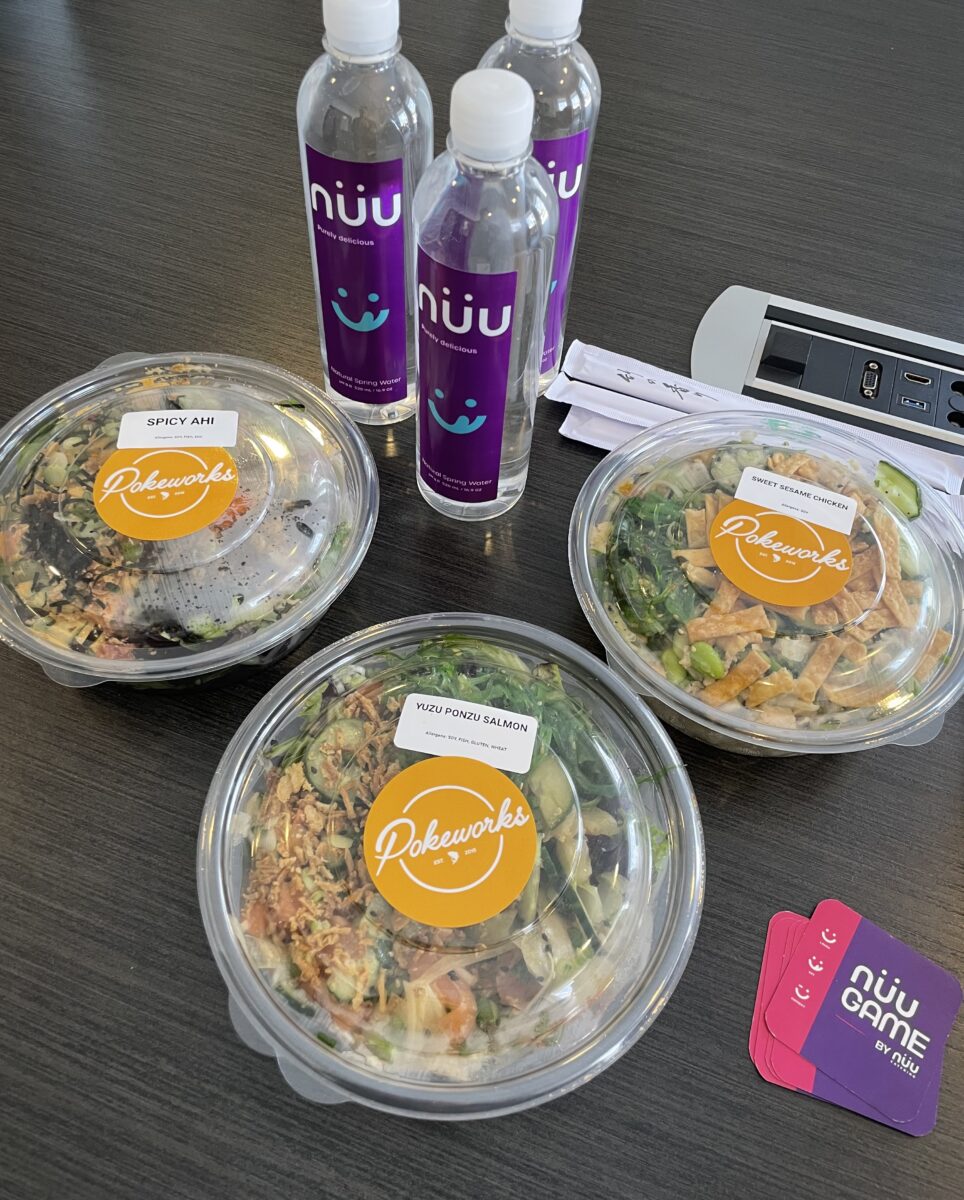
Beyond food delivery, Ahmadi said the company is attempting to differentiate itself through workplace engagement features. Orders can include conversation-based card games, designed to encourage interaction among employees during team lunches.

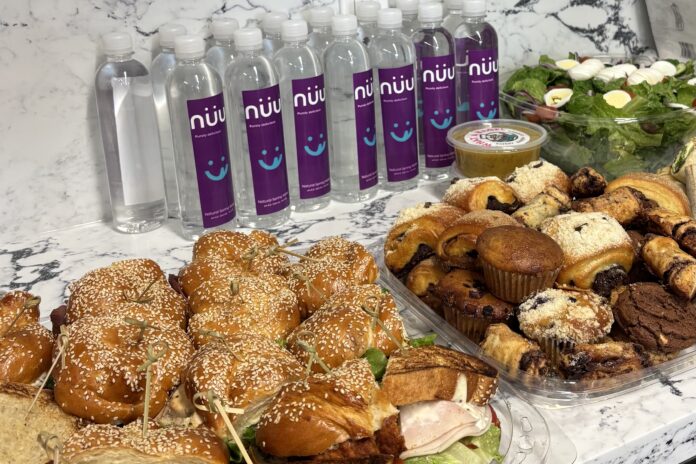
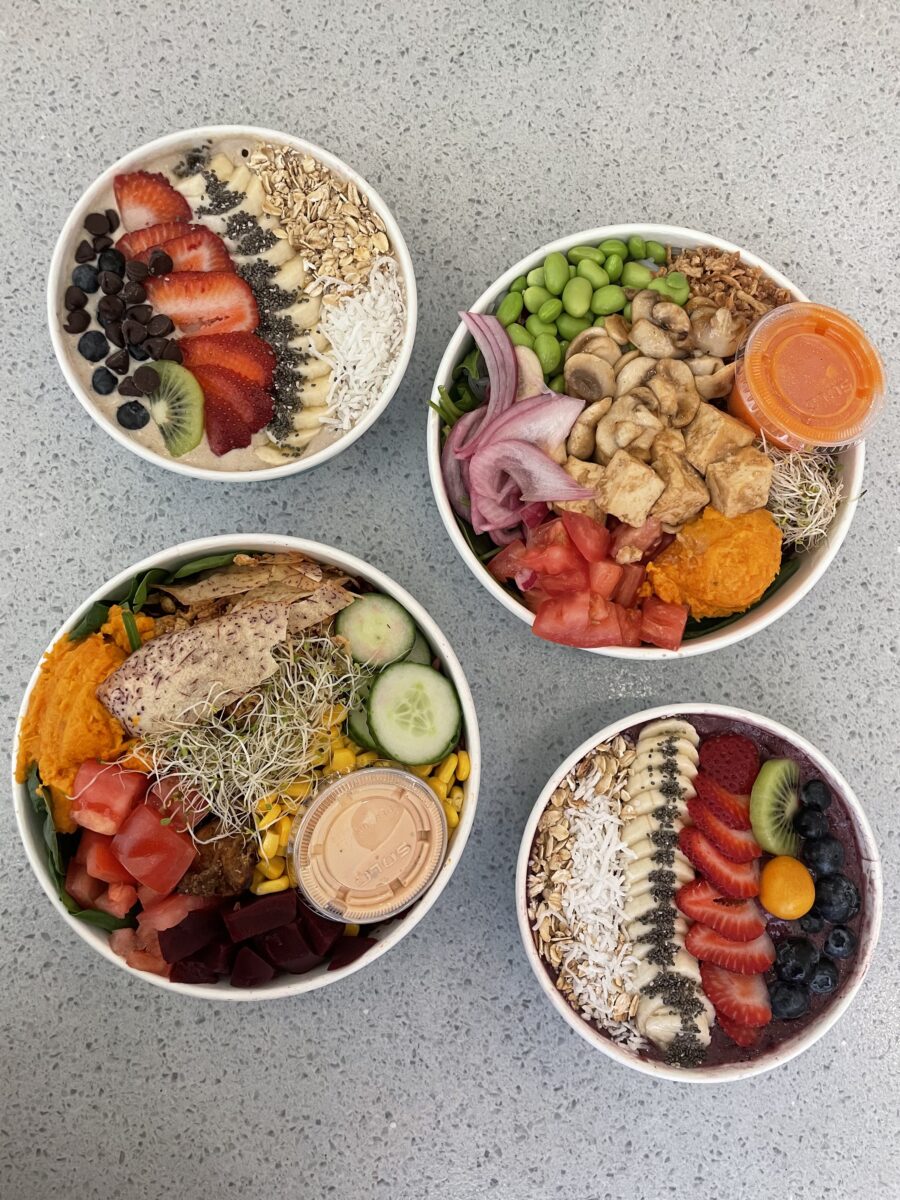
The company also emphasizes dietary accommodations and healthier menu options, including Mediterranean bowls and salads, alongside complimentary bottled water with orders.

“We believe in technology backed by humans,” Ahmadi said. “Even with AI, human interaction is key, especially with food.”

Each catering order includes what the company describes as a concierge-style service, with direct communication around dietary restrictions, allergies and order customization.
Nüu Catering photo
Nüu Catering photo

Although the company remains in its early stages, Ahmadi said it has already secured recurring corporate clients.

He declined to disclose specific order volumes but described growth as steady since launch.

“We’re still a startup, so not massive numbers yet, but strong volume,” he said.

The business currently operates across Toronto using a network of drivers and teams focused on sales, software development and marketing.

Ahmadi said the company spent roughly two years developing the concept before launching publicly in October, timing the rollout to coincide with broader return-to-office trends.
Nüu Catering photo
Nüu Catering photo

He believes employers are increasingly looking for practical ways to encourage workers to spend more time in the office without relying solely on mandates.

“Food can be a reason for people to come back together,” he said. “Like offering bi-weekly lunches.”

The company is also exploring expansion opportunities in the United States, particularly among technology startups in California, where Ahmadi said workplace culture initiatives tend to be more established.

“We’ve been working with tech startups in California, where office culture is very strong,” he said. “People stay in the office because they enjoy the environment — food, games, social interaction.”

More from Retail Insider:
King Living opens first Québec showroom at Quartier DIX30

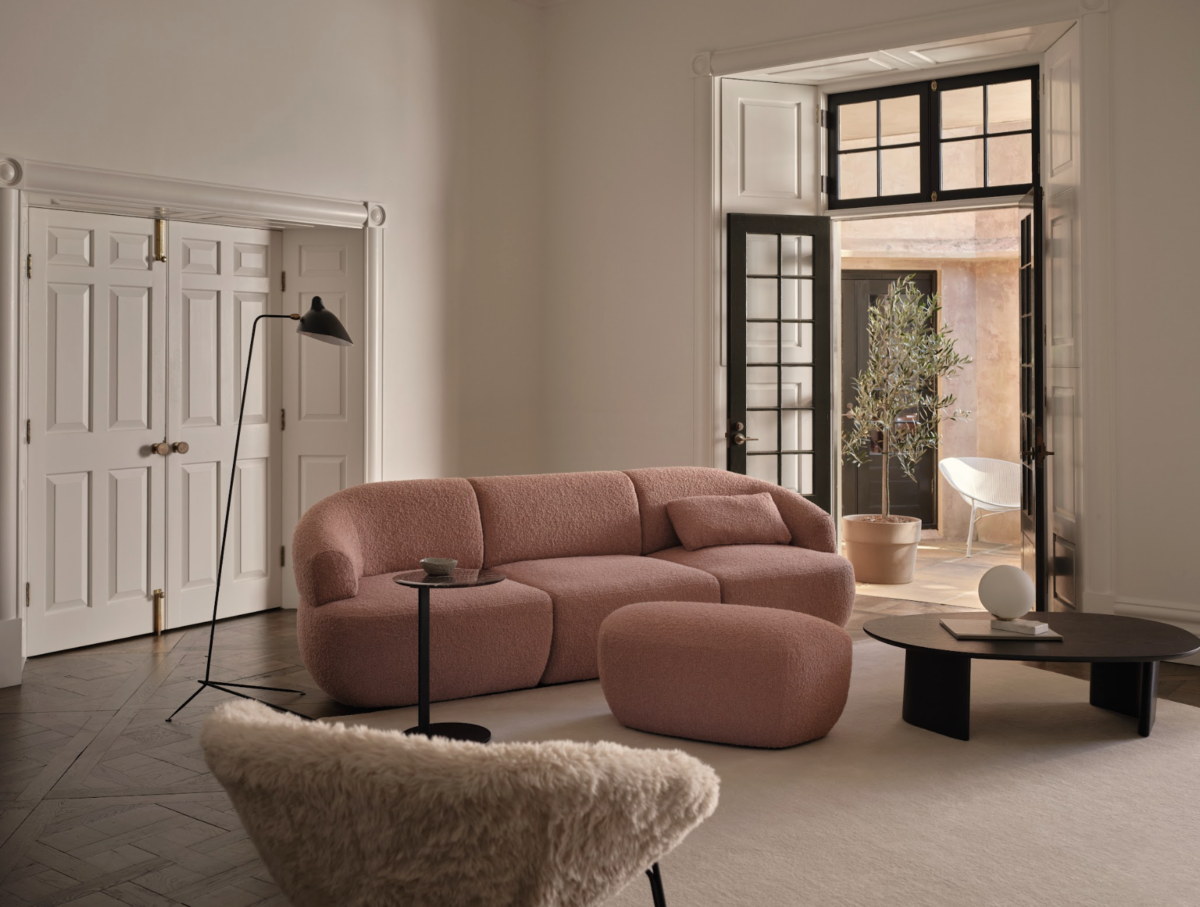
King Living photo
King Living photo

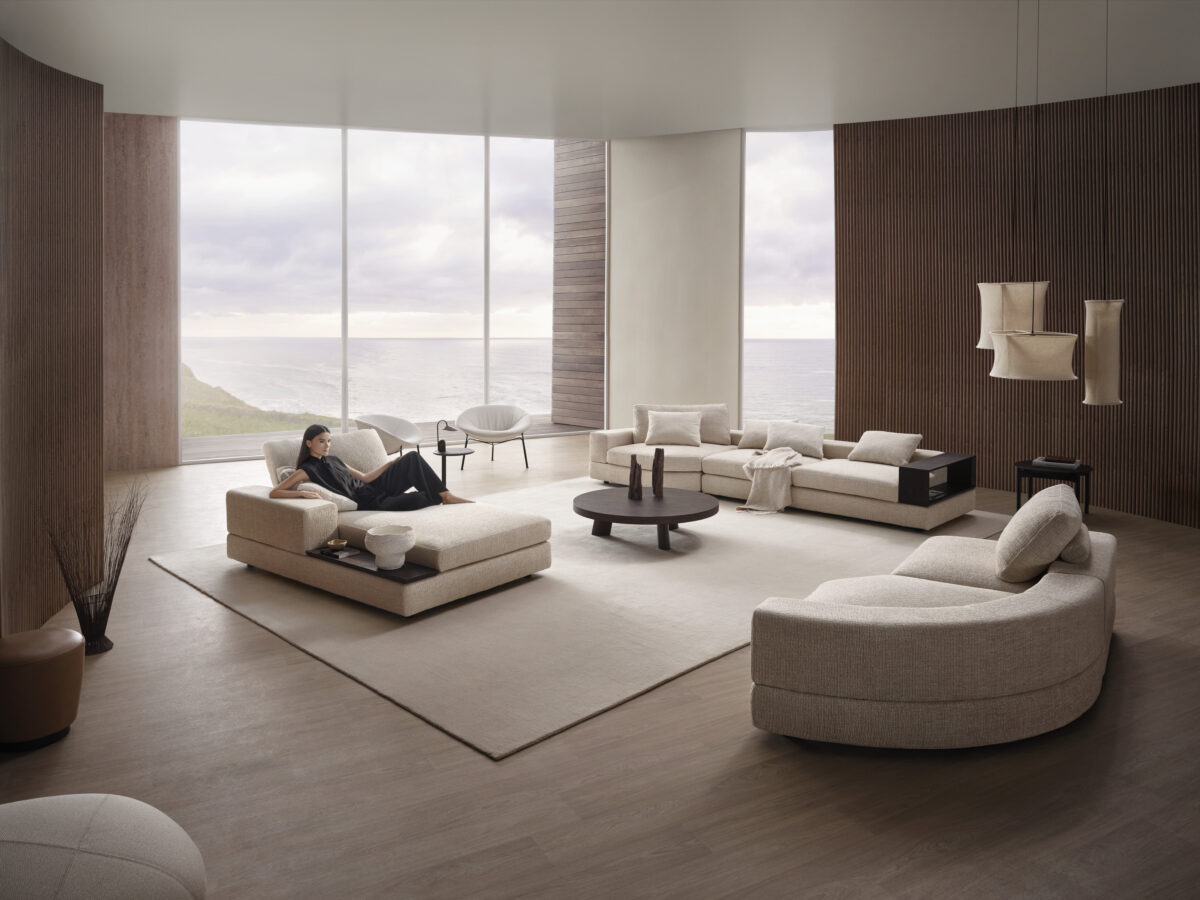
King Living has opened its first Québec showroom at Quartier DIX30 in Brossard, located on Montréal’s South Shore and accessible via the REM rapid transit network.

The new showroom marks the Australian-founded, family-owned company’s fourth Canadian location and introduces its modular furniture collections to the Québec market.

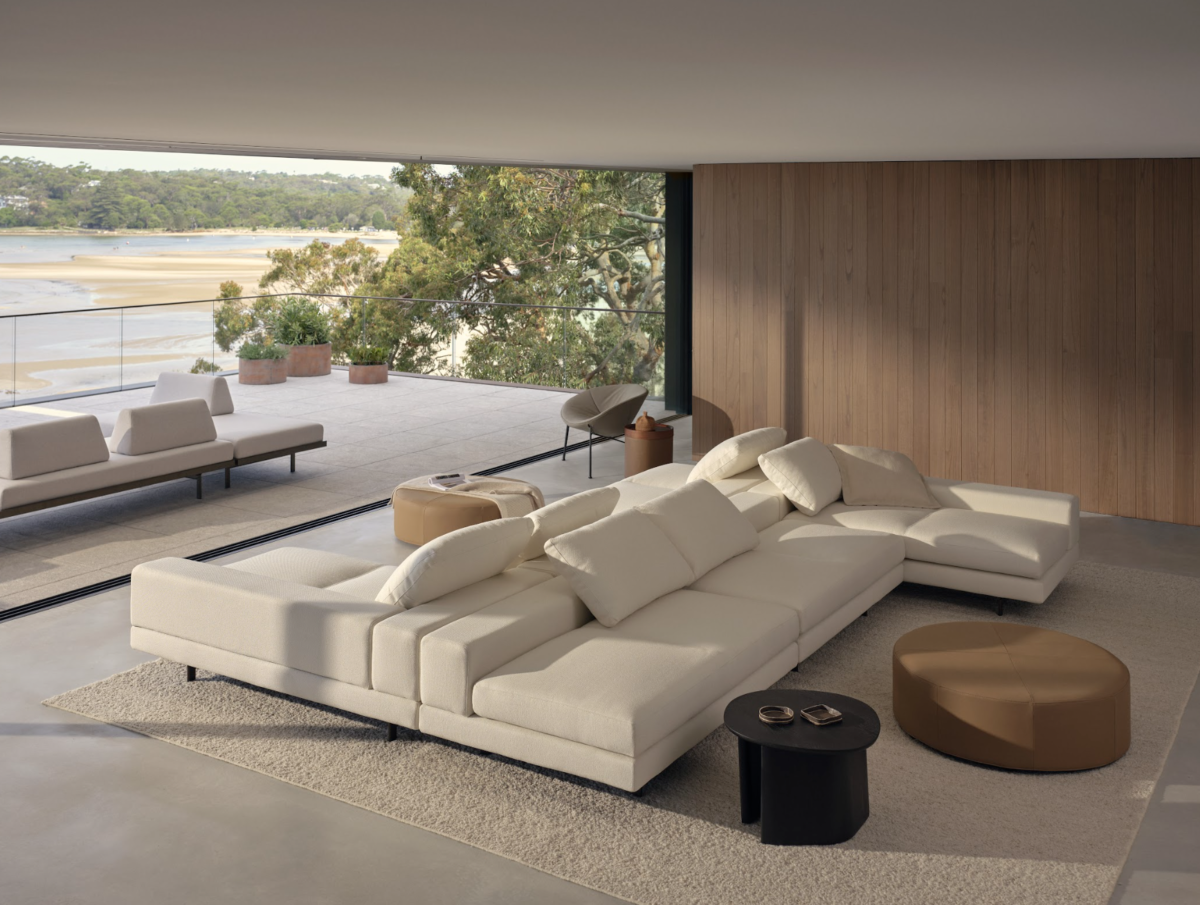
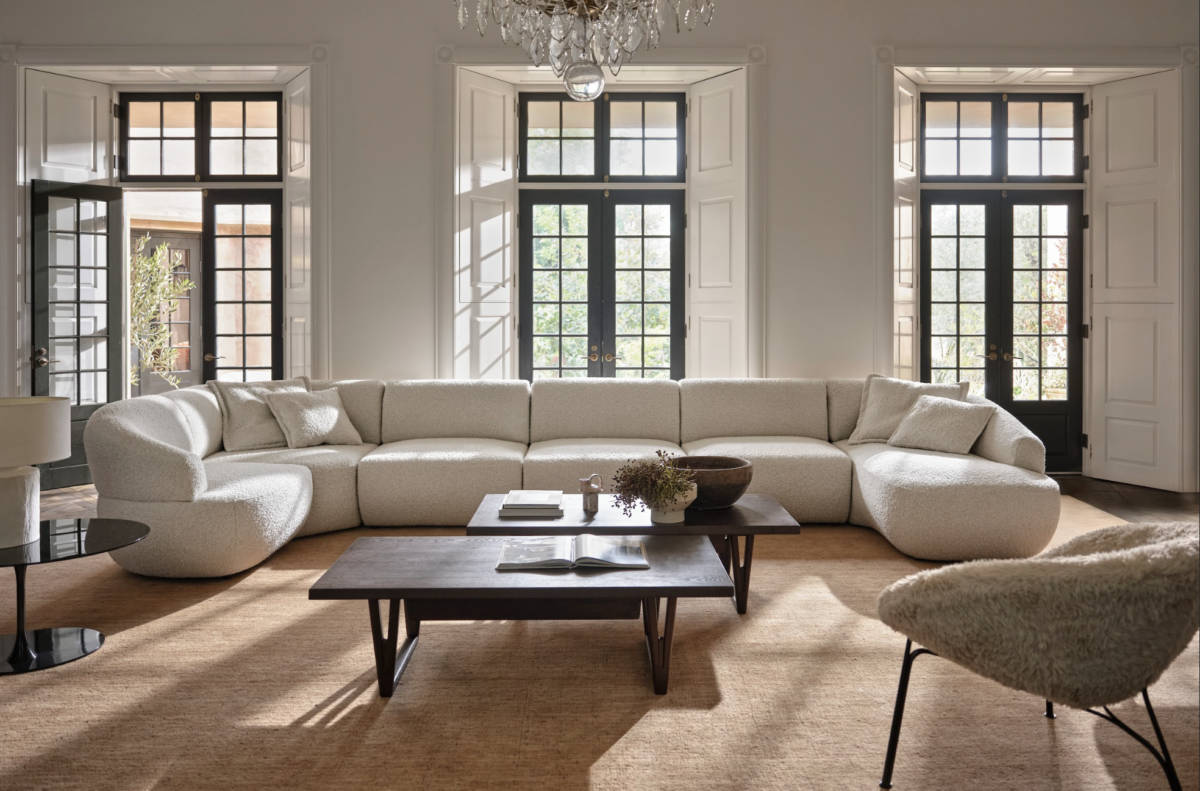
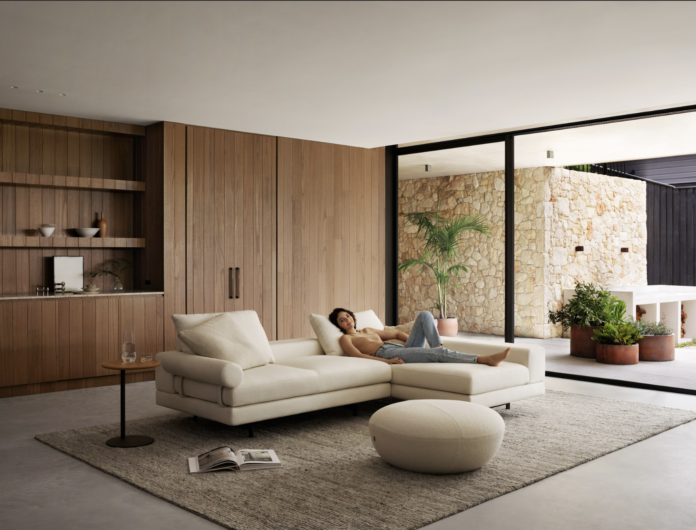
Founded in Sydney in 1977, the retailer said it designs, manufactures and retails its own furniture, with collections engineered for long-term use through modular design, replaceable components and customizable configurations.

Known for its “Future of Furniture” philosophy, the company said it operates 40 showrooms globally across eight countries and has seen growing demand from Québec customers through its Toronto showroom and online channels.

“When I built my first sofa in 1977, I wanted to create furniture that families could keep, adapt and enjoy for decades,” said David King, Founder of King Living. “That philosophy still guides every collection we design today. Montréal has a strong appreciation for thoughtful design and craftsmanship, making it a natural fit for King Living.”

King Living photo
King Living photo

Located within Quartier DIX30 in Brossard, the showroom places the retailer within one of Canada’s leading open-air lifestyle precincts. Situated on Montréal’s South Shore, Quartier DIX30 is one of Canada’s largest open-air lifestyle destinations, home to more than 270 retailers, 65 restaurants and a major entertainment precinct serving the Greater Montréal Area. The Brossard location offers ample free parking and convenient access via the REM rapid transit network for customers travelling from Montréal and surrounding suburbs across Québec, explained the retailer.

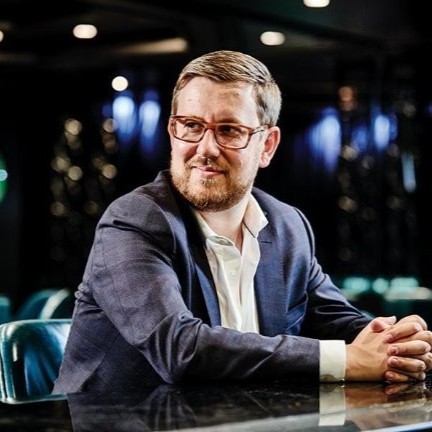
“Québec customers value quality, functionality and long-term value in the home,” said David Woollcott, CEO of King Living. “Our furniture is designed to evolve with people’s lives, whether through modular configurations, replaceable covers or adaptable layouts, and we’re excited to introduce Montréal customers to that approach.”

David Woollcott
David Woollcott

The retailer said the Brossard showroom features the full King Living collection across living, dining, bedroom and outdoor categories, including award-winning designs such as the Jasper, Delta and 1977 Sofa with prices starting from CA$1990 for a three-seater sofa. Every piece is made to order through King Living’s vertically integrated business model, with customers able to customize configurations, seating arrangements and finishes across more than 200 exclusive fabrics and premium leathers.

King Living opened its first North American showroom in Vancouver in 2019, followed by Calgary and Toronto. The Brossard showroom marks the brand’s fourth Canadian location and expands its North American footprint alongside U.S. showrooms in Chicago, Portland and Orange County.

The company operates 40 showrooms across Australia, New Zealand, Canada, the United States, the United Kingdom, Singapore, Malaysia and China.

More from Retail Insider:
King Living photo
King Living photo
King Living photo
King Living photo
King Living photo
King Living photo

Kiokii and… Expands Across Canada’s Top Malls Ahead of U.S. Growth

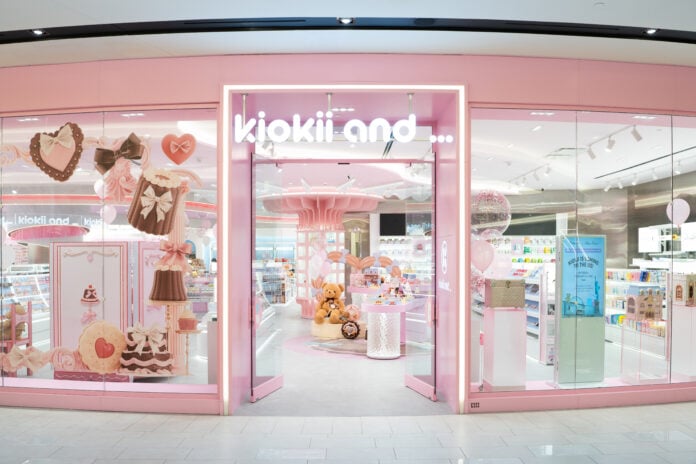
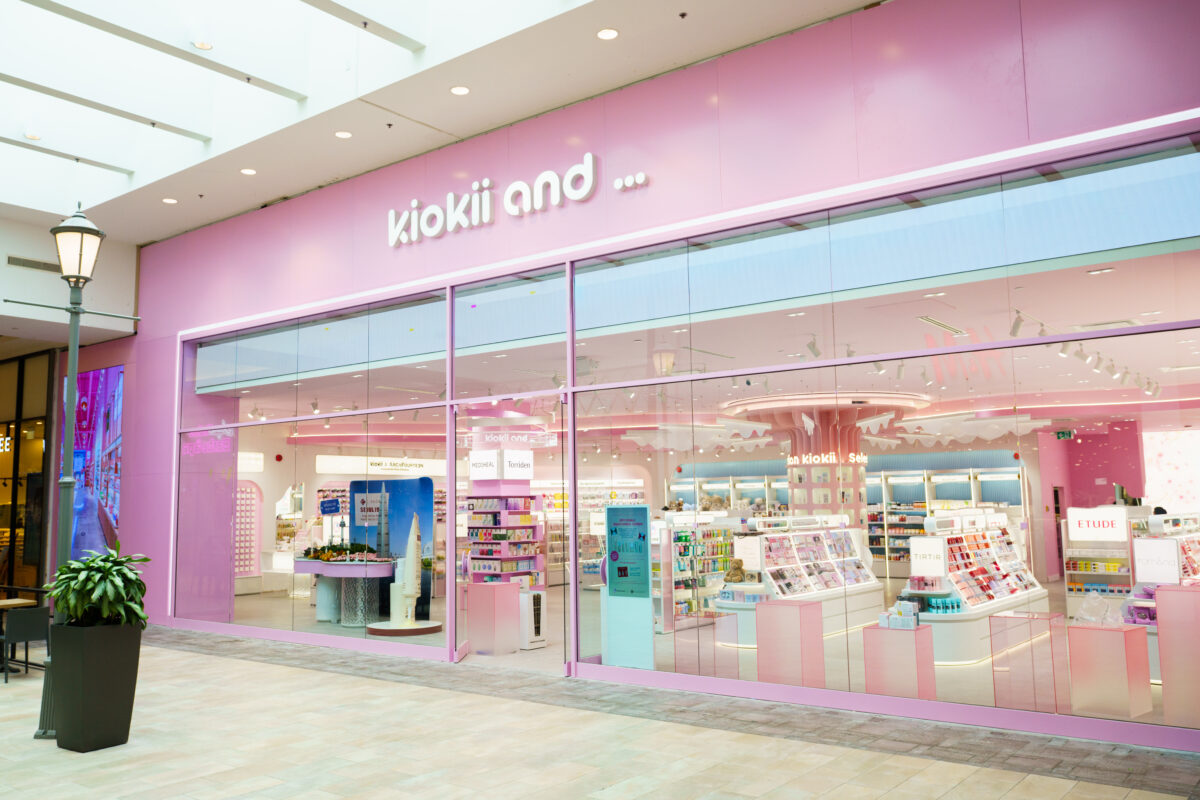
Kiokii and… location, Image: Kiokii and…

From fewer than a dozen stores just two years ago to an expected 42 locations across North America by the end of 2026, Canadian-founded retailer Kiokii and… is rapidly becoming one of the country’s most closely watched shopping centre success stories.

The Toronto-based Asian beauty and lifestyle retailer has expanded aggressively across many of Canada’s top enclosed malls while simultaneously preparing for broader growth in the United States. Along the way, the company has emerged as part of a new generation of highly visual, discovery-driven retail brands helping reshape how shopping centres attract younger consumers and generate repeat visits.

What makes Kiokii and… particularly notable is not simply the pace of its growth, but where the company is opening stores. The retailer has steadily secured space within some of Canada’s highest-performing enclosed malls, working with landlords including Cadillac Fairview, Oxford Properties, Primaris REIT, and Triple Five Group.

“We work really well with all the landlords,” said Echo Peng during an interview with Retail Insider. “We’re in every single CF property except Shops at Don Mills.”

That level of penetration across Canada’s premier enclosed shopping centres is unusual for a relatively young specialty retail concept. As mall owners continue refining tenant mixes to emphasize entertainment, immersion, and repeat visitation, retailers capable of generating excitement and emotional engagement have become increasingly valuable within the modern shopping centre ecosystem.

Kiokii and… appears to be benefiting directly from those broader industry shifts.

Echo Peng

From Emerging Concept to National Expansion Story

The company’s growth trajectory has accelerated rapidly over the past two years.

In early 2024, Kiokii and… operated fewer than a dozen stores nationally. By spring 2025, the retailer had grown to 28 locations while announcing plans for its first major U.S. flagship. Less than a year later, the chain expects to operate approximately 42 stores across Canada and the United States combined.

The expansion has largely focused on high-productivity enclosed malls in major urban centres, though the retailer has increasingly entered mid-sized Canadian markets as well.

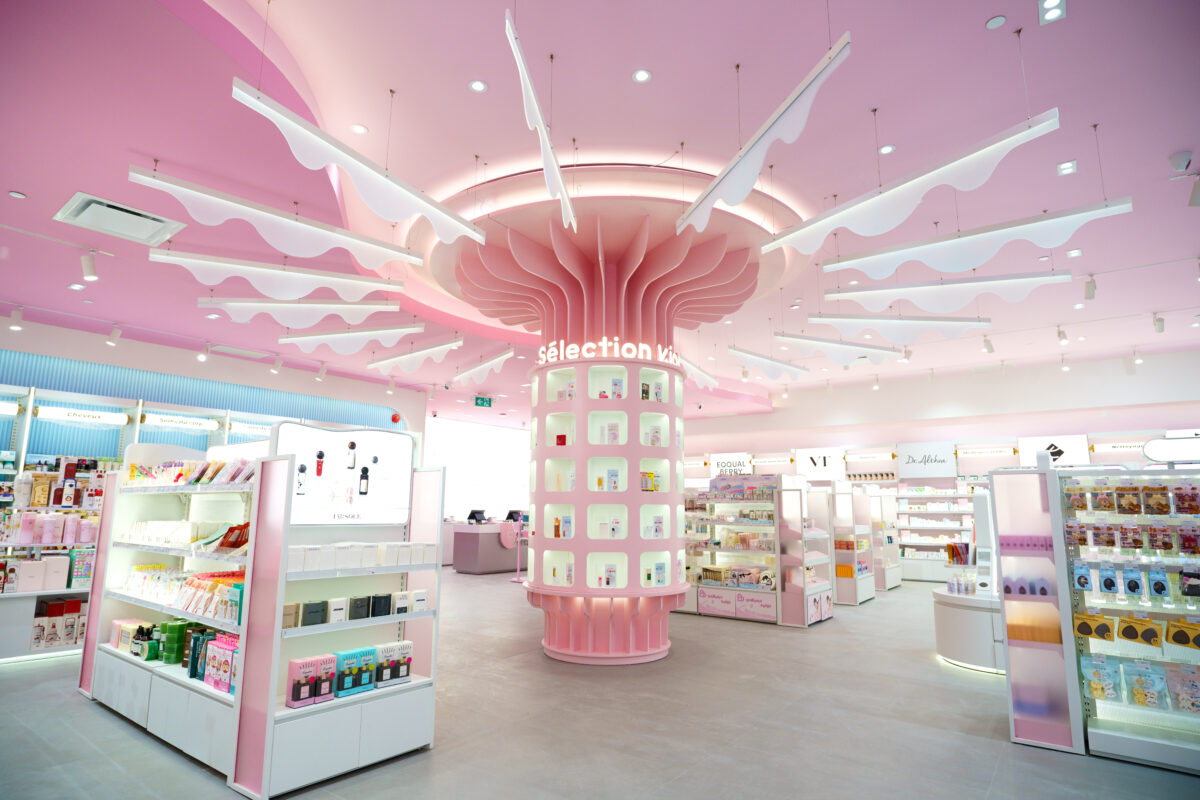
Inside the stores, customers encounter colourful displays of skincare, cosmetics, beauty tools, accessories, hair products, and lifestyle merchandise sourced from across Korea, Japan, and China. Viral beauty products sit alongside curated assortments, imported exclusives, and proprietary merchandise, creating an environment designed as much for exploration and impulse discovery as for planned purchasing.

Executives repeatedly emphasized that the physical shopping experience sits at the centre of the company’s strategy.

“We’re not trying to sell product,” Peng said. “We really want the customer come in, have that experience to enjoy.”

That philosophy increasingly aligns with broader shifts occurring throughout physical retail. As e-commerce continues handling more routine transactional purchases, many successful bricks-and-mortar concepts have evolved toward sensory retail environments that encourage browsing, experimentation, and social interaction.

For younger consumers especially, shopping has increasingly become tied to discovery, self-expression, and participation in fast-moving trend culture rather than simply completing a transaction.

Kiokii and… location, Image: Kiokii and…

Eaton Centre Flagship Reflects the Brand’s Evolution

One of the company’s most significant upcoming openings will be a new flagship store at CF Toronto Eaton Centre expected to open this fall.

The approximately 3,500-square-foot location will relocate Kiokii and… into a much more prominent centre-court position near the James and Albert entrance within one of Canada’s busiest shopping centres. The new flagship will occupy a former Aritzia space, representing a major visibility upgrade for the brand.

“It’s gonna be amazing exposure for us in terms of the brand,” said a company representative during the interview.

Within the shopping centre industry, centre-court positioning inside Eaton Centre carries particular significance. The relocation reflects how quickly Kiokii and… has evolved from an emerging niche retailer into a strategically important tenant capable of driving traffic, energy, and younger demographic engagement within major urban malls.

The move also highlights how shopping centres themselves continue evolving. Landlords increasingly appear willing to allocate premium retail real estate toward concepts that create activity, excitement, and repeat visitation rather than relying exclusively on traditional apparel anchors.

Asian Beauty Retail Continues Moving Into the Mainstream

While Asian beauty products once occupied a relatively niche segment within the Canadian retail landscape, the category has expanded rapidly over the past several years as younger consumers embrace skincare routines, beauty rituals, and trend discovery originating across Asia.

Executives emphasized that Kiokii and… positions itself as a broader “Asian beauty” retailer rather than focusing exclusively on Korean beauty products.

“We carry lots of C-beauty and J-beauty plus lifestyle products,” Peng said. “Kiokii is more about experience for discovering.”

The company also emphasized that its customer base extends well beyond Asian consumers.

Its core demographic generally ranges from ages 16 to 35, though management said the stores increasingly attract a broad mix of customers drawn to skincare trends, curated merchandise assortments, and the immersive retail atmosphere.

Much of that momentum has been fueled by social media, influencer culture, and the growing popularity of skincare-focused routines among younger consumers. Physical retail environments increasingly serve as places where shoppers can test products, discover trends, and engage with fast-moving beauty culture in person.

Retailers such as MINISO, Pop Mart, and other highly visual retail concepts have similarly benefited from discovery-oriented merchandising strategies that encourage repeat visits and customer engagement, though Kiokii and… has increasingly carved out its own position within the growing Asian beauty and lifestyle category.

Kiokii and… location, Image: Kiokii and…

Expansion Beyond Canada’s Largest Cities

One of the more significant indicators of Kiokii and…’s broader appeal may be how successfully the concept has expanded beyond Canada’s largest urban markets.

Recent openings in Saskatoon and Winnipeg reportedly generated lineups and strong opening traffic despite operating in smaller markets with less established Asian beauty retail ecosystems.

“I think we’re doing pretty good. It’s higher than my expectation,” Peng said when discussing Saskatchewan performance.

The strong reception in those markets suggests Asian beauty and discovery-driven retail concepts may now be entering the Canadian mainstream more broadly rather than remaining concentrated primarily within Toronto or Vancouver.

Executives also described enthusiastic customer reactions during new store openings, including shoppers arriving with existing memberships and local consumers expressing excitement about finally having access to the brand in their market.

Exclusive Merchandise and Private Label Drive Differentiation

As the company scales nationally, Kiokii and… is also increasing its focus on exclusive merchandise and proprietary product development.

The retailer said it serves as the Canadian-exclusive distributor for several brands, including Flower Knows, a Chinese beauty label that has developed a significant international following.

“We’re the exclusive distributor for them in Canada only,” Peng said.

Approximately 20 per cent of the retailer’s assortment now consists of internally developed OEM and private-label products sourced through teams based in Asia.

That strategy may become increasingly important as competition within the beauty category intensifies. Proprietary merchandise can help retailers strengthen margins while also offering differentiated assortments unavailable through competing channels.

“We don’t want to follow,” Peng said. “We want to set up the trend.”

U.S. Expansion Underway as Retailer Eyes Global Growth

Alongside its Canadian expansion, Kiokii and… has now entered the United States with a store at American Dream in New Jersey that opened earlier this year.

The company indicated its American growth strategy will initially focus on northeastern markets due to operational proximity to Toronto while leveraging relationships with landlords already familiar with the brand through its Canadian expansion.

Potential future markets discussed during the interview included Boston, Washington, D.C., Florida, and Minnesota, including opportunities connected to Triple Five Group, owner of both West Edmonton Mall and Mall of America.

The retailer also indicated it is pursuing additional tier-one American shopping centres as expansion accelerates.

“I want it to become like a global brand,” Peng said. “Our focus next year will be U.S.”

World Cup demand may not translate into revenue gains for many small businesses: Merchant Growth

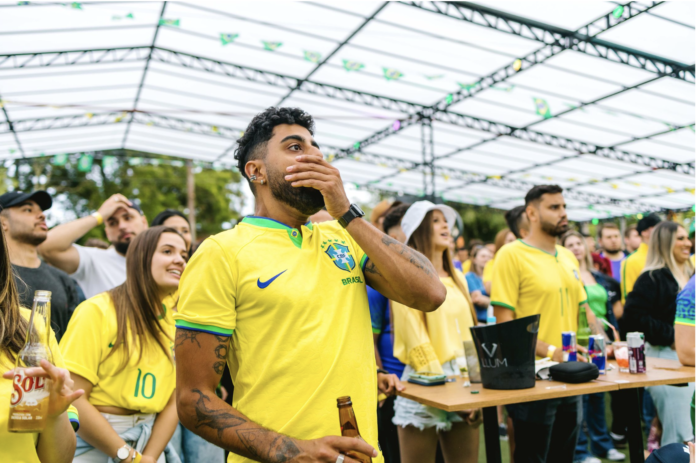
Juliano Ferreira photo

Many Canadian small businesses expect little financial benefit from the 2026 FIFA World Cup despite signs that consumers plan to spend money at local establishments while watching matches, according to a study commissioned by Merchant Growth.

The study found that 22 per cent of Canadians plan to watch World Cup matches at a locally or independently owned business, while 58 per cent of small business owners expect the tournament to have no impact on their revenue compared with a typical summer.

The findings point to a disconnect between consumer interest in supporting local businesses during the tournament and business owners’ expectations about their ability to capitalize on that demand.

The results come from Merchant Growth’s 2026 Small Business Pulse, which surveyed 130 small business owners and incorporated a national Angus Reid survey of 1,504 Canadians commissioned by the company.

“The World Cup is a major economic moment, but it will not benefit every small business equally,” said David Gens, founder and chief executive of Merchant Growth.

“Businesses with the right location, staffing and cash flow may be able to turn increased consumer activity into revenue. But for many owners, rising operating costs and tight margins mean they are being cautious about investing ahead of the opportunity. Too often, small businesses do not realize there are flexible financing options beyond traditional banks that can help them prepare for moments of increased demand.”

The consumer survey found Canadians who plan to watch matches outside their homes are far more likely to choose local businesses than larger operators. Twenty-two per cent said they intend to watch at a locally or independently owned business, compared with two per cent who said they would watch at a national chain or large venue.

Those planning to watch matches away from home said they expect to spend an average of $52 per visit on food and drinks.

Average expected spending varied by age group, with Gen Z respondents reporting an average of $41 per visit, millennials $51, Gen X $60 and boomers $56.

Despite those spending intentions, many business owners reported taking few steps to prepare for an increase in customers during the tournament.

According to the survey, 27 per cent of small businesses said they do not expect increased foot traffic from World Cup matches. Only 37 per cent expect a revenue increase tied to the event.

FIFA website photo
FIFA website photo

Among the businesses surveyed, 14 per cent said they had increased inventory or product stock, while another 14 per cent said they had promoted their business on social media in connection with the World Cup. Twelve per cent reported extending operating hours, 10 per cent had hired additional staff, nine per cent had created World Cup-related promotions or themed offerings and five per cent had applied for or accessed financing to support preparations.

Business owners cited financial constraints as a key reason for limited preparation. Twenty-two per cent said they lacked the cash or access to financing needed to invest ahead of the tournament, while 21 per cent said rising operating costs left no room in their budgets for additional spending.

The study also examined broader consumer spending plans for the summer.

Sixty-nine per cent of Canadians surveyed said price and deals would be an important factor in their summer dining decisions, while 56 per cent said supporting local or independent businesses would influence where they spend.

Three in five respondents said they would choose locally or independently owned businesses when dining out this summer, although price would remain a significant consideration. Forty per cent said they would prioritize local businesses even if doing so cost more.

FIFA website photo
FIFA website photo

The survey suggests that cost-conscious consumer behaviour could add pressure on businesses already facing higher expenses.

Many business owners reported concerns about the broader economy. Seventy-one per cent said they believe Canada is already in an economic downturn or is likely heading toward one within the next year. That figure was down from 83 per cent in 2025 but remained elevated.

Respondents identified fuel costs linked to global trade disruptions as their top summer cost concern, cited by 42 per cent of businesses. Rising utility bills and weaker consumer demand were each cited by 37 per cent, while 30 per cent pointed to labour costs or minimum wage increases and 26 per cent cited commercial rent or lease increases.

In response to those pressures, 55 per cent of businesses said they had cut spending this year. Twenty-five per cent reported delaying hiring, while the same proportion said they had raised prices. Twenty-two per cent said they had paused expansion plans and 20 per cent reported reducing staff.

The report said many owners are focusing on protecting margins rather than increasing investment as they navigate rising costs and uncertain economic conditions heading into the summer season.

More from Retail Insider:
Daily Synopsis: Jun 2, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 8 articles we published today covering key developments in Canadian retail.

METRO Inc. named Marc Giroux as its next President and CEO, with the leadership transition effective September 27, 2026, focusing on growth and operational continuity in Québec and Ontario. Millennials are trading down yet splurging selectively amid affordability pressures, shaping shifting consumer behaviours. Canadian shoppers are losing faith in influencer marketing, with only 5% trusting influencers most for purchase decisions, instead favouring personal contacts and authentic online reviews as shown in a recent Canadian study.


Harry Rosen reimagined its Oakridge Park store in Vancouver with a new focus on luxury sportswear and experiential retail. AI technology is advancing decision-making as AI personas transform customer profiles into interactive tools for faster insights. Chexy reports rapid growth in cashback usage among Canadians under 40 signalling a shift from passive rewards to active financial strategies. An Edmonton entrepreneur warns of a small business crisis across Canada, while motion-based digital billboards outperform static ads ahead of major city events.

🗞️ The Day’s Retail Insider Article List


🌐 Canadian Retail News From Around the Web

How AI Personas Are Transforming Retail Decision-Making

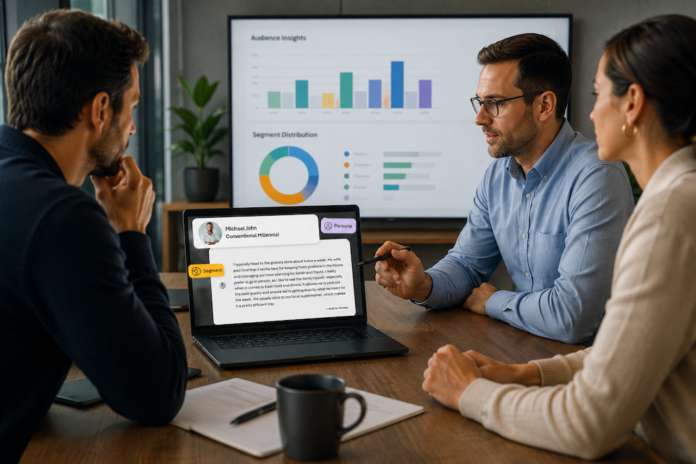
Team discussing audience insights in meeting

Retail decision-making has always relied on a balance between data, experience, and intuition.
However, as consumer behaviour becomes more complex and market conditions shift rapidly,
the traditional pace of research is increasingly at odds with the speed required to compete. This
tension is now driving the adoption of new tools that can deliver insights faster while still
maintaining a foundation in data.

Among the most notable developments is the emergence of AI-powered personas, including platforms such as Smart Persona introduced through a partnership between Leger and Plus Company. These tools are beginning to reshape how retailers test ideas, evaluate risk, and refine strategy by turning static audience profiles into interactive, data-driven simulations that enable a more dynamic approach to understanding consumers.

From Static Personas to Interactive Insight

For years, retailers have relied on personas as a way to represent target customers. These
profiles, typically developed through segmentation studies, have provided useful guidance but
often remained underutilized once created. In many cases, they existed as static documents that
were referenced occasionally but rarely integrated into daily decision-making.

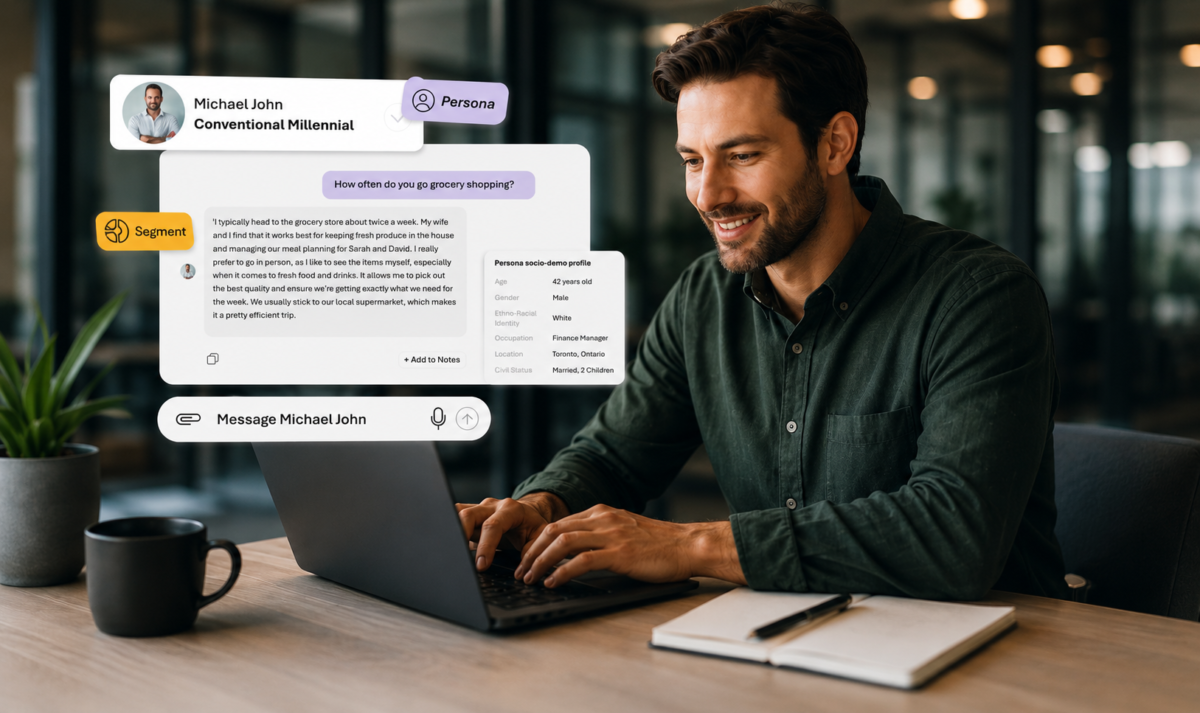
AI personas are changing that paradigm. Instead of reading about a customer segment, teams can
now interact with it. By asking questions and testing scenarios in real time, retailers gain access
to a more fluid and responsive form of insight.

This shift transforms personas from passive assets into active tools. It allows marketing teams to
explore how a target customer might respond to a campaign, while merchandising teams can
evaluate potential product offerings before committing to production. The result is a more
continuous and accessible connection to the consumer perspective.

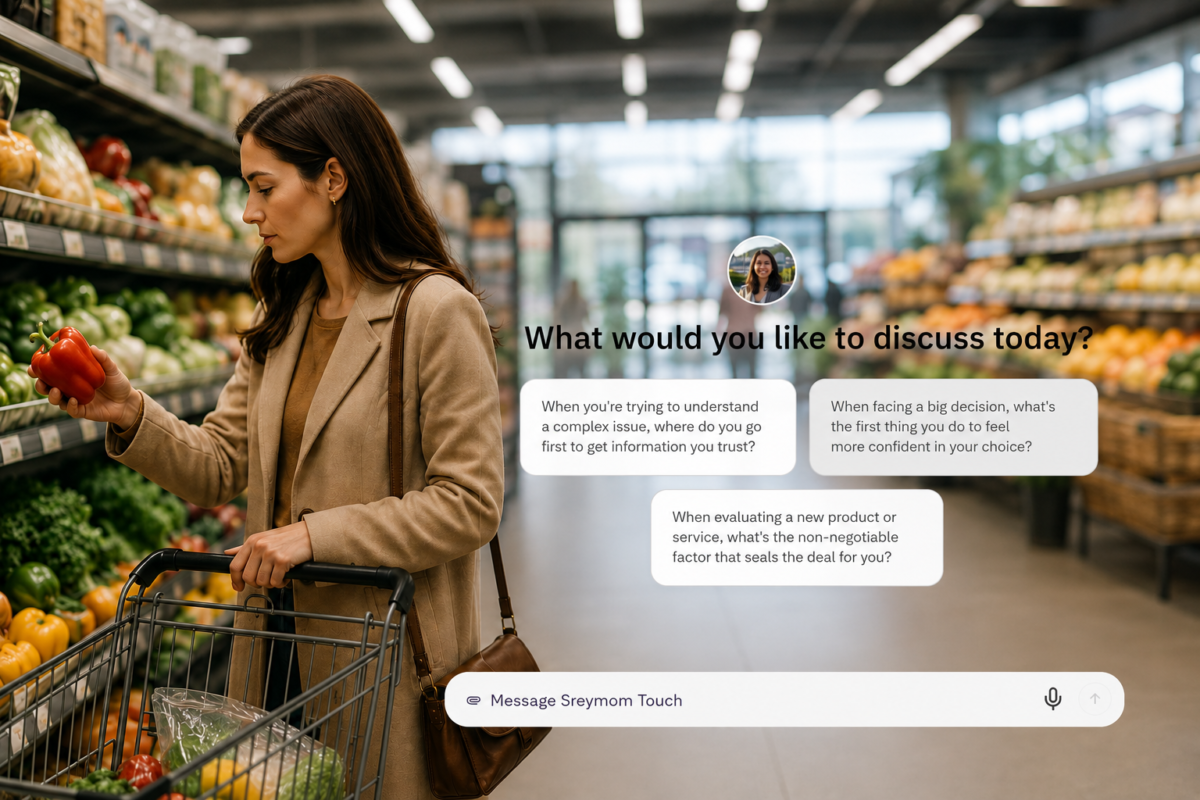
Grocery shopping with augmented reality insights

Accelerating Decisions Across the Organization

One of the most immediate impacts of AI personas is speed. Traditional research processes can
take weeks to complete, from designing a study to recruiting participants and analyzing results.

While these methods remain essential for validation, they are not always suited to situations
where decisions must be made quickly.

AI personas provide a way to generate directional insights in minutes. This capability is
particularly valuable in retail environments, where teams often need to react to changing trends,
competitive pressures, or internal timelines.

For example, a marketing team preparing a digital campaign can test multiple creative executions
and identify which message resonates most strongly with a target audience. Similarly, a product
team can narrow down a list of potential innovations by quickly gauging consumer interest and
identifying which concepts warrant further investment.

These applications do not eliminate the need for traditional research. Instead, they allow
organizations to prioritize more effectively, focusing time and resources on the most promising
opportunities.

Enhancing Creativity While Reducing Risk

Beyond speed, AI personas are also influencing how teams approach creativity and innovation.
By providing immediate feedback on ideas, these tools create a safer environment for
experimentation.

Retailers can explore a wider range of concepts, including those that might have been considered
too risky or uncertain to test through conventional methods. Early-stage ideas can be refined or
discarded based on simulated consumer reactions, reducing the likelihood of costly missteps later
in the process.

This iterative approach aligns well with the realities of modern retail, where success often
depends on the ability to adapt quickly and respond to evolving consumer expectations. AI
personas support this by offering a way to continuously test and learn, rather than relying on a
single point-in-time study.

Grounding AI in Data and Methodology

As artificial intelligence becomes more prevalent in research, questions around accuracy, bias,
and reliability remain top of mind. The effectiveness of AI personas depends heavily on the
quality and structure of the data that underpins them.

Leading solutions in this space are built on a combination of primary research, segmentation
data, and large-scale datasets that reflect real-world behaviours. Synthetic populations, which
model individuals based on statistical relationships rather than personal information, are often
used to create detailed and privacy-compliant representations of target audiences.

In the case of Smart Persona, developed through the partnership between Leger and Plus Company, personas are informed by more than 25 data sources and can include thousands of attributes, enabling nuanced and context-aware responses. The system is designed to ground outputs in structured data, helping to limit the types of inconsistencies that can occur with more generic AI tools.

At the same time, industry experts emphasize that these tools should be viewed as
complementary to traditional methodologies. AI-generated insights are most valuable when used
to guide direction and inform early-stage thinking, with critical decisions validated through
established research techniques.

Democratizing Access to Consumer Insight

Another important implication of AI personas is their potential to broaden access to research
within organizations. Historically, consumer insight has often been concentrated within
specialized teams, with other departments relying on periodic reports or presentations.

By making insights interactive and available on demand, AI personas allow more stakeholders to
engage directly with the data. This can lead to a more consistent application of consumer
understanding across functions, from marketing and merchandising to operations and executive
leadership.

In practical terms, this means that a wider range of decisions can be informed by consumer
perspective, rather than relying solely on intuition or limited inputs. Over time, this shift could
contribute to more aligned and customer-centric strategies across the organization.

Modern office with message overlays

A New Layer in the Research Ecosystem

The rise of AI personas does not signal the end of traditional research. Instead, it represents the
addition of a new layer within the broader insight ecosystem.

Surveys, focus groups, and in-depth interviews will continue to play a critical role in providing
validated, statistically robust findings. AI personas, by contrast, offer a way to explore ideas
quickly, test assumptions, and identify areas that merit deeper investigation.

This complementary relationship reflects a broader trend in how organizations are integrating
artificial intelligence into their workflows. Rather than replacing existing processes, AI is being
used to enhance them, improving efficiency and expanding what is possible.

Looking Ahead

As adoption increases, AI personas are likely to become a more standard part of the retail
decision-making toolkit. Their ability to combine speed, accessibility, and data-driven insight
positions them as a valuable resource in an increasingly competitive landscape.

For retailers, the opportunity lies in using these tools thoughtfully, leveraging their strengths
while maintaining a commitment to methodological rigor. Those that succeed in striking this
balance will be better equipped to navigate uncertainty, respond to change, and deliver
experiences that resonate with today’s consumers. Leger has described this approach as a form of “augmented intelligence,” positioning AI as a complement to traditional research rather than a replacement for it.

In that sense, AI personas are not simply a technological innovation. They represent a shift in
how organizations think about research itself, moving from a periodic activity to an ongoing,
integrated part of decision-making.

For more information on Smart Persona, visit: leger360.com/smart-persona-powered-by-leger

METRO names Marc Giroux as next President and CEO


METRO Inc. announced Tuesday that Eric La Flèche will retire as President and Chief Executive Officer at the end of the 2026 fiscal year after more than 18 years at the helm of the company and the Board of Directors will appoint Marc Giroux, currently Chief Operating Officer, to succeed him as President and CEO effective September 27.

In order to support a smooth and orderly transition, the Board will appoint La Flèche as Chairman of the Board of Directors and Pierre Boivin, currently Chairman of the Board, will be appointed Vice Chairman and Lead Director, also effective on September 27, said the company.

The appointments are the culmination of a robust, multi-year succession planning process led by the Board, reflecting METRO’s commitment to strong governance and long-term value creation. Giroux is a proven leader with deep knowledge of METRO’s operations, culture and strategic priorities as well as a clear vision for the future, and his appointment underscores the strength of METRO’s internal talent pipeline. He will join the Board upon his appointment as President and CEO, explained the company.

“The Board is extremely pleased to appoint Marc Giroux to the position of President and CEO. We are convinced that he is the right leader for METRO’s next chapter. Marc’s deep understanding of our industry, focus on operational excellence, financial discipline and customer satisfaction make him the best candidate to continue delivering long-term value for our customers, employees and shareholders in an ever-changing environment”, said Pierre Boivin, Chair of the Board of Directors of METRO.

Eric La Flèche
Eric La Flèche

“On behalf of the Board, I want to thank Eric La Flèche for his remarkable contribution to METRO and to the communities we serve. Eric has been an exceptional leader for METRO for nearly two decades, creating substantial value for our shareholders by delivering consistent growth, reinforcing our customer-first and purpose-driven culture, and guiding the Company through significant strategic milestones, notably the acquisition of Groupe Jean Coutu in 2018.”

The company said it will benefit from La Flèche’s experience and perspective as Chair and will ensure strong independent oversight through its committees and the role of the Lead Director.

“It has been a privilege to lead METRO and to work alongside such talented and dedicated teams across our stores, distribution centres and offices,” said La Flèche. “METRO is well-positioned for continued success, with a clear growth plan, a disciplined approach to execution, a great team and a very solid balance sheet. I am proud of what we have accomplished together. Alongside my colleagues on the Board, I look forward to METRO’s continued success under Marc’s leadership.”

Marc Giroux
Marc Giroux

“I am honoured to be appointed President and Chief Executive Officer of METRO,” said Giroux. “Eric has built a strong foundation and a culture of performance and customer focus, and I’m pleased to continue collaborating with him going forward. My priority will be to build on that foundation–continuing to execute our strategy, supporting our people and partners, and keeping our customers at the centre of every decision as we move forward. I look forward to continuing to work with the best team in the industry.”

Executive biographies

La Flèche joined METRO in 1991 and has served as President and Chief Executive Officer since April 2008. Prior to becoming CEO, he held a number of roles of increasing responsibility, including Executive Vice-President and Chief Operating Officer from 2005 to 2008. In addition to industry recognitions, he was named Canada’s Outstanding CEO of the Year (2020). He is also a long-time volunteer with Centraide of Greater Montreal.

Giroux joined METRO in 2009 and currently serves as Chief Operating Officer, leading the Québec and Ontario food divisions as well as supply chain, marketing, loyalty and digital strategy. Over the course of his career with the Company, he has held progressively senior roles spanning marketing, merchandising and operations as well as digital and eCommerce. He holds a Bachelor’s degree in Finance and International Commerce as well as an MBA, both from HEC Montréal.

With annual sales of more than $22 billion, METRO Inc. is a food and pharmacy leader in Québec and Ontario, providing employment to more than 97,000 people. As a retailer, franchisor, distributor, manufacturer, and provider of eCommerce services, the company operates or services a network of some 1,000 food stores under several banners including Metro, Metro Plus, Super C, Food Basics, Adonis and Première Moisson, and some 640 pharmacies primarily under the Jean Coutu, Brunet, Metro Pharmacy and Food Basics Pharmacy banners.

More from Retail Insider:
Millennials Are Trading Down And Splurging At The Same Time: Study

Millennials shopping. Photo: iStock/licensed

Canadian Millennials are increasingly trading down in some categories while continuing to spend selectively in others, reshaping spending patterns across grocery, discount retail, foodservice, and consumer goods.

A new study from Calgary-based Cashew Research suggests the same consumer may purchase private label groceries, warehouse club staples, premium meat, specialty coffee, and skincare products within the same week depending on where they perceive value.

The findings point to a significant shift in shopping behaviour as affordability pressures continue to influence household budgets across Canada. Rather than reducing spending evenly, many Millennials appear to be reallocating spending more carefully while becoming less loyal to traditional brands and retailers.

The study surveyed 783 Millennials about grocery shopping habits, spending patterns, and lifestyle adjustments over the past year.

Millennials Are Becoming More Flexible Shoppers

The research indicates many Millennials are making purchasing decisions category by category instead of maintaining broad loyalty to national brands or retailers.

Among respondents, 59% said they strategically save in some categories while spending more in others, while only 18% described themselves as loyal to the same brands regardless of price.

Meanwhile, 41% identified as “price-sensitive switchers,” regularly changing brands to secure lower prices, while another 27% described themselves as “value optimizers” focused on balancing quality, price, and features.

Consumers are also increasingly shopping across multiple retail formats. Sixty-four percent of respondents said they visit different stores to find better deals, while 56% reported shopping at multiple retailers depending on the products or ingredients they need.

The trend reflects broader changes across retail as consumers move fluidly between discount retailers, warehouse clubs, ethnic grocers, specialty food stores, premium brands, and private label products depending on the purchase.

That shift may create additional pressure for middle-market retailers and national brands that lack either a strong value position or clear premium positioning. Consumers increasingly appear willing to aggressively trade down in some categories while reserving discretionary spending for products they believe offer noticeably better quality, convenience, or enjoyment.

The shift also helps explain why discount retailers, warehouse clubs, specialty grocers, and premium niche brands can all attract the same consumer at different moments throughout the week.

A grocery store in Quebec. Photo: Vergo Construction

Grocery Inflation Continues To Shape Spending Habits

Affordability concerns remain a major factor shaping shopping behaviour.

According to the 2026 Canada Food Price Report, grocery prices are expected to rise between 4% and 6% this year, with the average Canadian family of four projected to spend as much as $17,571 annually on food.

The Bank of Canada has also noted that grocery prices have climbed sharply since 2022, continuing to pressure household budgets.

Against that backdrop, many Millennials reported making substantial changes not only to shopping habits, but also to broader lifestyle spending.

Thirty-two percent of respondents said they are shifting toward more value-oriented retailers, while 28% reported replacing national brands with lower-priced alternatives and private label products.

Millennials are also reducing restaurant visits, canceling subscription services, consolidating errands to lower transportation costs, and relying more heavily on coupon apps, digital flyers, and sale-driven shopping habits.

Those patterns continue to benefit discount-oriented retailers and grocers across Canada.

Loblaw Companies Limited has continued investing in discount banners including No Frills and Maxi as consumers increasingly seek lower-priced grocery options. Discount retailers such as Dollarama have also benefited from shoppers searching for lower-cost household goods and everyday essentials.

The findings also point to growing acceptance of private label products, an area that major grocers and mass merchants have aggressively expanded in recent years as shoppers search for lower-cost alternatives without fully sacrificing quality.

Cooking At Home Is Becoming A Budget Strategy

The report found that Millennials are spending more time cooking at home as households look for ways to manage rising living costs.

Sixty-eight percent of respondents said they are preparing meals at home more frequently than they were a year ago, while 56% identified saving money as the primary reason.

Family priorities and health considerations also ranked highly among motivations for home cooking, with respondents citing meal planning, nutrition control, and reducing restaurant spending as major drivers behind changing routines.

The shift could benefit grocers, warehouse clubs, cookware retailers, meal planning services, and specialty food retailers while adding pressure to discretionary restaurant visits and takeout spending.

At the same time, the research suggests consumers are still allowing room in household budgets for smaller indulgences and products tied to comfort or enjoyment.

When asked why they purchase premium grocery products, 33% cited better quality or taste as the primary reason, while another 16% described premium purchases as small personal treats.

That behaviour helps explain why premium spending continues to persist in selective categories even as households become more cautious overall.

TikTok And Social Media Are Influencing Grocery Purchases

Digital platforms are also playing a growing role in shaping food and grocery purchases.

The study found that 78% of Millennial respondents had purchased a food product after seeing it featured in recipes, videos, or social media content.

Social media influencers ranked ahead of traditional digital advertising as a source of product discovery, reflecting how consumers increasingly move between online inspiration and physical shopping experiences.

Consumers also reported discovering products through in-store browsing, word of mouth, entertainment content, retailer apps, and digital media.

The findings reinforce how product discovery is increasingly shifting away from traditional advertising and toward algorithms, creators, TikTok trends, and social content that directly influence purchasing behaviour.

For retailers and consumer brands, maintaining visibility across multiple channels is becoming increasingly important as shoppers blend digital discovery with in-store purchasing decisions.

Retailers Are Facing A More Unpredictable Consumer

The study suggests Millennials no longer fit neatly into traditional categories such as discount shopper, premium shopper, or loyal brand customer.

Instead, consumers are increasingly blending discount, premium, private label, warehouse club, and specialty purchases depending on the category and perceived value of a product.

For retailers, that evolution is creating a more fragmented and less predictable consumer environment where shoppers are constantly reassessing priorities and retailers must increasingly compete purchase by purchase rather than relying on long-term loyalty or traditional assumptions about consumer behaviour.

More from Retail Insider:
Consumers Are Losing Trust in Influencers Says Canadian Study

Influencer, photo: Say Social

Only 5% of Canadian consumers say influencers are their most trusted source when making a purchase decision, according to new research from Field Agent Canada, a finding that may reflect growing skepticism toward highly polished social media marketing and paid online endorsements.

The study surveyed 2,024 Canadian shoppers and found that consumers still value recommendations and social proof when shopping. However, they increasingly prefer those recommendations to come from people they know personally or from ordinary consumers sharing real experiences online.


The findings point toward a broader shift in retail marketing, one where authenticity and relatability may be becoming more influential than aspirational influencer content.

“Consumers still trust recommendations, but who they trust may be changing,” said Jeff Doucette, Country Manager at Field Agent Canada.

Consumers Still Value Influence, But Trust Is Evolving

Jeff Doucette
Jeff Doucette

While influencer culture remains deeply embedded within retail marketing and social commerce, the survey suggests consumers are becoming more selective about the types of recommendations they trust.

According to the findings, 55% of respondents said recommendations from people they personally know are their most trusted source when making purchase decisions. Another 40% pointed to online reviews from everyday consumers.

The data suggests shoppers continue relying heavily on peer validation before spending money, particularly as many consumers remain cautious with discretionary purchases and increasingly research products before buying.

The survey also found that 68% of respondents are most likely to consider a product recommendation shared on social media by someone they personally know. By comparison, 24% said they would consider a recommendation from an influencer they follow, while only 8% said they would trust recommendations from influencers who simply appeared in their feeds.

The findings indicate consumers are not necessarily disengaging from social commerce or online product discovery. Instead, trust may increasingly be shifting toward digital word-of-mouth recommendations that feel more personal, credible, and grounded in real experience.


Authenticity Emerging as a Key Retail Marketing Theme

Authenticity emerged as one of the strongest themes throughout the research.

According to the survey, 71% of respondents said posts from people they know feel more authentic than influencer content. Only 4% said influencer posts feel most authentic, while 21% said both forms of content feel equally authentic.

Consumers skeptical of influencers said the content often feels financially motivated, overly curated, or scripted. Many respondents also indicated that recommendations from friends, family members, and ordinary shoppers feel more trustworthy because they appear less transactional.

The results may reflect growing fatigue with sponsored social media content as consumers become increasingly aware of paid partnerships and promotional messaging across digital platforms.

At the same time, the survey suggests consumers themselves continue participating actively in organic word-of-mouth marketing online. About 71% of respondents said they have posted about a product they genuinely liked without being asked or compensated to do so.

The findings reinforce the idea that consumers still want product recommendations and social discovery through digital platforms, but increasingly expect those interactions to feel genuine and unscripted.

Influencer, photo: Unsplash

Online Reviews Continue to Shape Consumer Behaviour

The research also highlighted the ongoing importance of online reviews within the modern retail purchasing journey.

According to the survey, 97% of respondents said they read reviews before making a purchase decision. The findings underscore how heavily consumers continue to rely on customer feedback and shared experiences before committing to a purchase.

As economic pressures continue affecting household budgets, trust and credibility may be playing a growing role in how consumers evaluate products, brands, and recommendations online.

For retailers, the findings may signal a broader evolution in how digital marketing strategies are perceived by consumers.

While influencer marketing remains a major component of the advertising landscape, the research suggests retailers may increasingly benefit from strategies focused on customer advocacy, authentic storytelling, review ecosystems, organic social sharing, and community-driven engagement.

The findings suggest that in an increasingly crowded digital marketplace, trust itself may be becoming retail’s most valuable marketing asset.

More from Retail Insider:
Rewards being repositioned from passive perks to active financial strategy: Chexy

Mikhail Nilov photo
Mikhail Nilov photo

Chexy, the Canadian fintech platform that enables consumers and businesses to earn credit card rewards on recurring payments like rent and bills, says cashback card usage through the platform is increasing 2.5 times faster among users under 40 than those aged 40+. 

Cashback transaction volume among users under 40 rose 125 per cent between Q4 2025 and Q1 2026. The increase points to a broader shift away from passive rewards accumulation toward more immediate, flexible returns on essential expenses.

Based on an analysis of overall Chexy user activity, cashback transactions rose 97 per cent over the same period, while the number of users earning cashback grew 60 per cent, signalling both rapid adoption and increased usage frequency among existing users. This momentum reflects a broader repositioning of rewards from passive perks to active financial strategy, led disproportionately by younger Canadians, who are shifting to cashback at 2.5 times the rate of those 40 and over, it said.

The generational divide is also evident in how value is distributed across the platform. Canadians under 40 processed $24.7 million in cashback volume in Q1 2026 compared to $11.6 million among those 40 and over, a gap driven largely by the fact that younger users now make up the majority of the platform’s user base. When controlling for headcount, older users actually transact more per person, highlighting two distinct but equally important behaviours: one focused on maximizing value in real time, and another rooted in larger, more consistent individual spending patterns, added Chexy.

Chexy Founder & CEO Liza Akhvledziani discusses the data.

Liza Akhvledziani
Liza Akhvledziani

Question: What’s driving younger Canadians to prioritize cashback rewards over traditional points-based loyalty programs right now?

A: Younger Canadians are increasingly prioritizing cashback because it delivers immediate, practical value on everyday expenses. As affordability pressures continue, there is a growing expectation that spending should provide a more tangible return, particularly on essential payments like rent, bills and taxes. Cashback aligns with that mindset because it feels flexible, accessible and relevant to how younger consumers are managing money today.

Q: Your data shows Canadians under 40 are adopting cashback 2.5 times faster than older consumers — what broader shifts in spending habits or financial attitudes are behind that generational divide?

A: The generational divide reflects a broader shift in how younger Canadians approach spending and financial management. Younger consumers have come of age in an environment shaped by real-time payments, digital banking and flexible financial tools, so there is a stronger expectation that financial products should provide immediate utility and transparency. 

Consumers who are 40 and older built their financial habits around legacy loyalty ecosystems where rewards were closely tied to travel, premium credit cards and long-term points accumulation. That model still resonates with them and since they are more established financially they may be less focused on accessing immediate value from their expenses. 

Q: How much of this behaviour change is tied to affordability pressures and the current economic climate versus a longer-term change in consumer expectations around rewards? 

We see this as both a response to current economic conditions and part of a longer-term behavioural shift. Affordability pressures have accelerated the demand for immediate and flexible value, but consumer expectations around rewards were already evolving before the current economic climate. Increasingly, Canadians expect rewards to integrate more seamlessly into everyday finances rather than functioning solely as aspirational perks tied to travel or luxury spending.

Liza Akhvledziani
Liza Akhvledziani

Q: Are consumers increasingly treating rewards and cashback as part of their monthly budgeting strategy rather than as occasional perks, and how is that changing the fintech or retail landscape? 

A: Yes, our data shows us rewards and cashback are increasingly becoming part of how consumers manage monthly spending rather than something viewed as occasional or secondary. Consumers are looking more closely at how to unlock value from recurring expenses that historically did not earn rewards, including rent, utilities and taxes.

In response, companies are expanding cashback offerings, building more flexible loyalty models and looking for ways to integrate rewards into recurring spending categories that drive consistent consumer engagement.

For retailers specifically, rewards are increasingly being used as a retention tool as consumers are paying closer attention to where they shop, how they pay and what value they get back, which is putting more pressure on brands to make loyalty programs feel immediate, practical and easy to use.

Q: Based on the growth you’re seeing between Q4 2025 and Q1 2026, what do you think this signals about the future of consumer finance behaviour in Canada over the next few years? 

The growth we’re seeing suggests consumers are starting to rethink what counts as a valuable financial product. For a long time, rewards programs were built around aspirational spending like travel, luxury purchases or occasional big-ticket transactions. What’s changing now is that consumers increasingly want financial value tied to the payments they make most often and care about most month to month.

Over the next few years, we expect that to reshape both payments and loyalty more broadly. Consumers will likely become less loyal to financial products that feel passive or disconnected from their everyday lives, and more willing to switch toward platforms that help them get value from recurring expenses. 

We also think the line between payments, budgeting and rewards will continue to blur, with consumers increasingly expecting all three to work together rather than exist as separate experiences.

More from Retail Insider: