Higher prices are putting brand loyalty to the test as consumers look for ways to stretch their grocery budgets without cutting everyday essentials altogether. In a new study, DOSS surveyed 811 parents and analyzed federal pricing data to see how sustained inflation is changing what families buy and which brands stay in their carts.
Key Takeaways
The findings point to a significant shift toward cheaper alternatives as parents reconsider the premium they’re willing to pay for familiar brands. That trade-down behaviour is showing up even among higher-income households:
- 64% of parents switched at least one of their child’s favourite brands to a cheaper store-brand alternative this school year.
- Even among households earning $100,000 or more, 55% have switched a child’s favourite brand for a cheaper option.
- 45% of parents have stopped buying a snack, drink, or lunch item their child regularly asks for because it became too expensive.
- 36% say their child complained after they traded down, highlighting the tension between brand preference and price.
The findings offer a look at how persistent price pressures are influencing brand loyalty and creating an opening for lower-cost and private-label alternatives. DOSS also examined which recognizable food brands parents are replacing as they adjust their shopping habits.
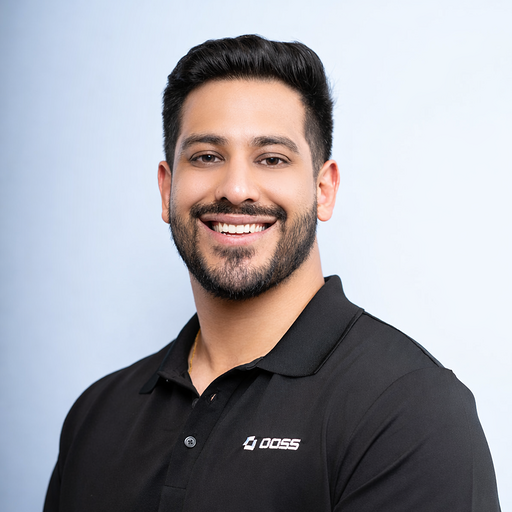
In an interview with Retail Insider, Eshaan Kaul, Head of Growth at DOSS, discussed the report’s findings.
What do the findings tell you about how sustained grocery-price increases are changing brand loyalty among Canadian families, particularly when it comes to products children prefer?
Our report is based on a survey of U.S. parents, rather than Canadian respondents. That being said, findings show that there are shifts in brand loyalty as parents adjust to higher prices of children’s products. For example, 64% of parents have replaced at least one of their child’s favourite brands with a store brand this school year. Moreover, 45% of parents have given up on a snack, beverage, or lunch item their child regularly buys or wants to buy because it has become too expensive. This demonstrates that a significant portion of parents are removing a specific product from their child’s rotation rather than simply substituting it with a cheaper alternative.
What are you seeing in the data about the willingness of higher-income households to switch from familiar national brands to cheaper store-brand or private-label alternatives?
While our research indicates that trade-down occurs in higher-income families as well, it is much more prevalent in lower-income households. For example, 71% with household incomes below $50K have switched a favourite brand to a cheaper option, as have 55% of those earning $100K or more have switched to store brands.
However, the majority of higher-income families (earning six figures) also engage in trade-down, which suggests that switching to cheaper options is an all-class phenomenon. A slight income gradient is observed among those agreeing strongly with the statement; about a fifth (22%) of higher-income households fall into this category compared to 29% of those with incomes below $50K (41%) strongly agree that they’re buying fewer name-brand products, compared with over 1 in 5 of those earning $100K.
Which grocery categories or types of products are seeing the greatest trade-down behaviour, and what recognizable brands are parents most commonly replacing?
The breakfast category appears to be the most affected by trade-down, as breakfast brands were most frequently substituted for store-brand alternatives. About a quarter of parents have switched Eggo and Pop-Tarts for cheaper alternatives. Paper goods are also associated with a significant number of substitutions, with mothers being slightly more likely to switch (48%) than fathers (33%). Notably, parents appear to be the least willing to sacrifice breakfast items, as over a fifth (26%) have traded down but continue buying their child breakfast, and about a quarter have resisted cutting down on breakfast altogether. Thus, breakfast seems to be the most difficult category to substitute, which makes parents choose lower-priced options within this category.
How significant is the tension between parents’ desire to manage household grocery budgets and children’s preferences for specific brands, based on the 36% who said their child complained after a trade-down?
The findings suggest that tensions between parents’ need to stretch their budgets and their child’s preferences for branded products often result in adverse reactions to substitutions. Over a third (36%) of parents report that their child has complained about them switching from their favourite brand to a cheaper alternative. Combined with the fact that nearly two-thirds of parents have substituted at least one brand for a store brand and almost half have cut down on a product their child wanted to buy, this indicates that, for such families, substitutions are associated with tension and difficulties.
What do these findings mean for national food brands and retailers as consumers become more willing to sacrifice brand loyalty for lower prices, and do you expect these shopping changes to persist if inflationary pressures ease?
National brands in the breakfast category and paper goods are most at risk of being substituted for private-label options. The fact that a majority of higher-income households also engage in trade-down suggests that the observed changes could be persistent in the long run. If parents continue buying store-brand products, their loyalty to national brands within these categories may erode permanently.
More from Retail Insider: