Retail Insider has released Q3 2026 Sporting Goods & Outdoor: Store Productivity as Performance Diverges, authored by Retail Insider founder and publisher Craig Patterson. The report examines why investment in stores, specialist assortments and services is producing different results across the sector.
The report covers Canadian sporting goods, outdoor recreation, fitness, athletic equipment, hunting, fishing, cycling and related specialty retail. It draws on Retail Insider coverage, company disclosures, industry research and government data, distinguishing developments during July through September from financial results measuring earlier periods.
Retail Insider Reports provide executive-level analysis of the sectors and operating issues shaping Canadian retail. The Retail Insider Report Hub brings the quarterly collection together, connecting company developments with broader market evidence and their commercial implications.
General Themes
- Participation creates opportunity: Interest in sport and outdoor activities does not automatically produce stronger retail sales.
- Store size is not the strategy: Large assortments and small, locally curated formats address different customer needs.
- Inventory must earn its space: Availability, fitting, fulfilment and sell-through determine the value of physical stock.
- Services need defined roles: Repair, product care and specialist advice should strengthen the customer relationship and store economics.
- Financial measures matter: Event attendance, opening traffic and gross-margin gains are not substitutes for durable sales and operating returns.
Retail Insider Coverage
SportChek’s comparable sales increased 8 per cent in Canadian Tire’s second quarter ended July 4, with World Cup merchandise generating roughly half the growth. Canadiens fanwear and athletic footwear also contributed. The result demonstrates preparation for event-driven demand, although harder comparisons will test the wider assortment once that contribution passes.
The banner is also planning an almost 70,000-square-foot Destination Sport store at CF Chinook Centre for 2027, consolidating two existing locations into former Nordstrom space. Former Hudson’s Bay locations were under consideration, rather than identified as completed transactions in the August earnings discussion. New website tabs were connecting Canadian Tire banners, while integrated search, cart and payment remained planned.
Sports Experts took a different route at CF Carrefour Laval, investing approximately $8 million in its roughly 45,000-square-foot flagship. The rebuild emphasizes footwear availability, fitting and fulfilment, with stockroom capacity for approximately 60,000 pairs and three Aetrex scanning systems. For this established mall store, a deeper assortment is intended to improve the probability of completing a purchase immediately.
The renovation also removed 12 inventory-display screens, freeing space for another 144 footwear models while retaining technology with a clearer fitting function. Early footwear sales were approximately 70 per cent higher and bicycle sales about 20 per cent higher, but these were operator-reported reopening indicators, not stabilized results. A temporary store’s substantially weaker traffic and sales also illustrated why square footage alone cannot reproduce an established location’s productivity.
The report describes a different inventory choice in MEC’s planned 2,200-square-foot Whistler store, which carried an October 31 soft-opening target. The format would pair a locally selected assortment with staff expertise and access to a broader online range. MEC described it as a learning opportunity, not an announced national rollout. The test is whether a smaller physical selection can adequately serve a specialized market.
MEC is separately expanding trail running across footwear, apparel, hydration, nutrition and accessories. More than 1,000 people registered nationally during the first weekend of its Train for the Trails program, demonstrating interest without establishing incremental sales or retention. MEC Label’s approximately 25 per cent share applies to the retailer’s overall business, not specifically to trail running.
Arc’teryx opened its 9,599-square-foot Montreal Alpha Store on August 28 with broader product presentations and expanded ReBIRD repair, care, trade-in and resale services. These services create reasons for existing owners to return during a product’s life. Broader geographic growth figures and a potential 200-store North American opportunity are not Canadian performance or opening commitments. JD Sports also added a downtown Montreal location, although its half-year results did not isolate Canadian sales.
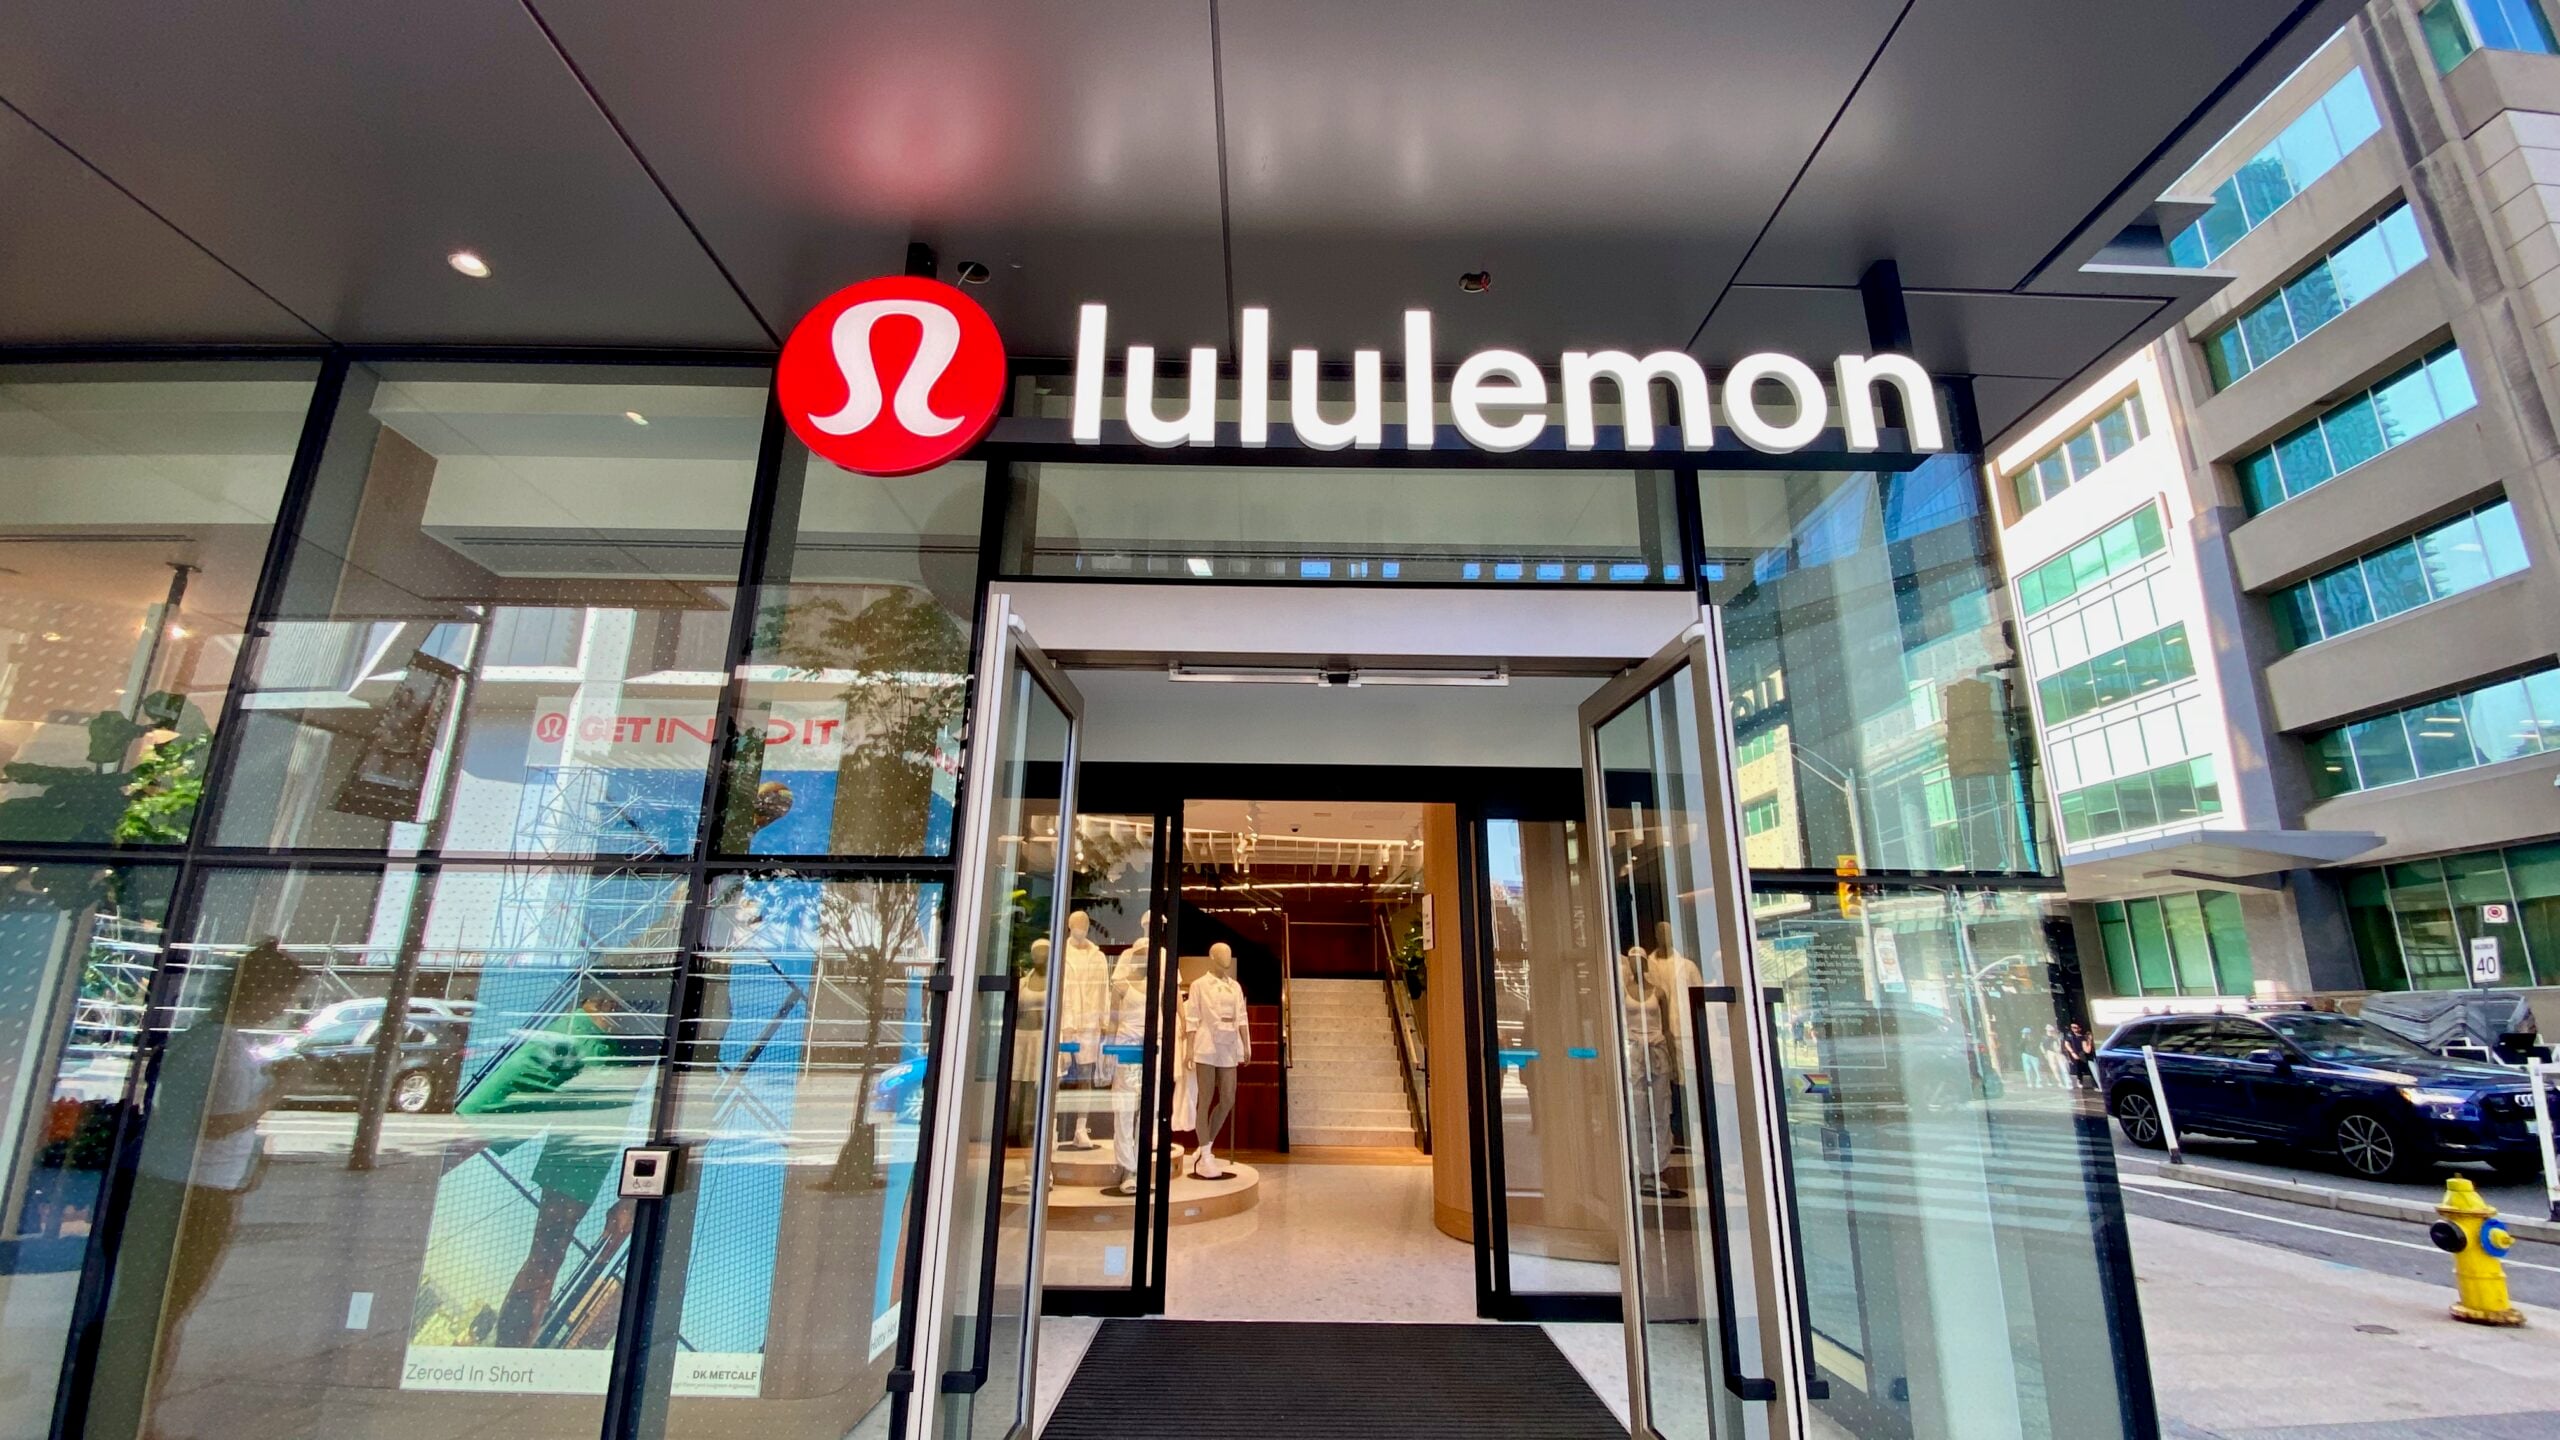
Lululemon illustrates the gap between participation and financial performance. Nearly 10,000 runners attended the revived SeaWheeze half marathon, while Canadian second-quarter revenue declined 11 per cent on a reported basis and 9 per cent in constant currency. Changes to SKU density and localized assortments are intended to address traffic and product challenges that community engagement alone had not resolved.
Columbia’s Canadian second-quarter sales fell 7 per cent on a reported basis to approximately US$25.2 million, with weaker wholesale partly offset by direct-to-consumer growth. Gross margin improved to 49.8 per cent, but operating loss widened to approximately US$3 million. The report also identifies global shipment timing shifts into the fourth quarter, not Canadian order cancellations. Channel mix can improve gross margin without improving the overall operating result.
Fitness facilities create additional retail contact, as Calgary’s Realm Fitness demonstrates. Its approximately 2,500 members and 700 to 800 average daily visits support opportunities around merchandise, supplements and equipment. The business did not disclose retail sales, so participation and footfall cannot establish the financial size of that opportunity.
Broader Industry Coverage
Statistics Canada recorded July sales of $1.422 billion for sporting goods, hobby, musical instrument and book retailers and news dealers. Sales rose 4.3 per cent year over year in current dollars and 3.4 per cent at constant prices, but declined from June. This combined category is broader than sporting goods, so its annual increase cannot be presented as a standalone growth rate for the sector.
Editor’s Take
The winter selling season and 2027 will provide a better productivity test than opening announcements. SportChek faces harder comparisons, Sports Experts needs stabilized returns on its renovation, and MEC must establish whether small-format curation and community programming translate into purchases. Arc’teryx’s services and the assortment changes at lululemon require similarly specific measures, while Columbia needs stronger operating results alongside margin improvement.
The report’s central distinction is between creating customer interest and earning a return from it. Deep inventory, smaller stores and repair services can all be commercially sound, but they solve different problems. Comparable sales, inventory turns, repeat visits, full-price sell-through and returns on invested capital will show whether those choices work more clearly than participation totals alone.
Conclusion
Read the full Q3 2026 Sporting Goods & Outdoor report for the analysis of store formats, inventory, services and divergent company performance. It explains why the quality of each operating decision matters more than a uniform expansion strategy.
The report and the wider quarterly collection are available through the Retail Insider Report Hub. The collection connects Canadian retail developments with the evidence needed to assess their commercial significance.