RBC Canadian cardholder spending showed modest improvement in February despite consumers continuing to cut back on discretionary goods spending, according to a recent report by the bank.
“Our core retail sales measure on a three-month average remained negative at -0.1%, but marked an improvement from -0.3% (seasonally adjusted), indicating the decline eased in February after weather-related disruptions and post-holiday fatigue weighed on spending in January,” said the report.
“We expect higher oil prices will drive up purchases at gas stations. The impact on other essentials and discretionary spending is less clear as it will depend on how consumers allocate their remaining income, and the extent to which they tap into their savings.”
The report highlights:
February’s contraction came entirely from discretionary goods—clothing and related retail segments were among the weakest performers.
Weakness in discretionary goods spending was partially offset by spending growth in discretionary services and essentials. Travel, entertainment and art posted the strongest gains on a three-month average, pointing to continued resilience in experience-related spending.
Spending grew in most provinces on a three-month average following the January slowdown. Ontario, hit particularly hard by winter storms, showed notable recovery in February as conditions moderated.
Job vacancies were little changed in the fourth quarter of 2025 at 495,100, following three straight quarters of decline beginning with the first quarter of 2025, according to a recent report by Statistics Canada.
Year over year, job vacancies were down by 8.9% (-48,100) in the fourth quarter. This was the smallest proportional year-over-year decline since the fourth quarter of 2022 (-6.4%), said the federal agency.
“Job vacancies rose for full-time occupations (+5,100; +1.4%) and fell for part-time occupations (-4,300; -3.4%) in the fourth quarter of 2025. Meanwhile, job vacancies held steady for both permanent and temporary positions. Despite little variation in the number of vacancies, total labour demand (the sum of filled and vacant positions) rose in the fourth quarter (+26,500; +0.1%), as payroll employment increased (+25,700; +0.1%),” it said.
“The job vacancy rate—which corresponds to the number of vacant positions as a proportion of total labour demand—held steady at 2.8% for the third straight quarter. The job vacancy rate had previously declined steadily from the record high of 5.6% reached in the second quarter of 2022.
“The proportion of long-term vacancies—vacancies for which recruitment efforts have been ongoing for 90 days or more—across Canada was 28.5% in the fourth quarter of 2025, a 4.1 percentage point decrease from the fourth quarter of 2024 (32.6%) (not seasonally adjusted). This indicates that employers had fewer difficulties filling available positions compared with a year earlier.”
Statistics Canada said the unemployment-to-job vacancy ratio—the number of unemployed persons per job vacancy—fell from 3.2 to 3.1 in the fourth quarter of 2025, the first quarterly decline since the second quarter of 2022. The unemployment rate in the fourth quarter of 2025 was 6.8%, down from 7.0% in the third quarter of 2025.
“In the fourth quarter of 2025, job vacancies increased in trades, transport and equipment operators and related occupations (+3,800; +4.3%), in business, finance and administration occupations (+3,300; +5.0%) and in occupations in manufacturing and utilities (+1,100; +6.3%). Meanwhile, decreases were recorded in sales and service occupations (-4,100; -2.8%) and in legislative and senior management occupations (-200; -27.8%),” added Statistics Canada.
“On a year-over-year basis, job vacancies were down in 8 of the 10 broad occupational groups in the fourth quarter, led by health occupations (-13,600; -17.0%), sales and service occupations (-9,500; -6.2%) and trades, transport and equipment operators and related occupations (-7,200; -7.2%). Year over year, job vacancies were little changed in natural resources, agriculture and related production occupations and occupations in manufacturing and utilities.”
Tulkoff Foods has acquired Toronto-based private label manufacturer Celtrade Canada in a move the companies say will broaden their manufacturing footprint and product development capabilities across North America.
The Baltimore-based sauces and condiments manufacturer announced recently that the strategic acquisition is intended to strengthen the combined company’s ability to serve retail, foodservice and industrial customers with expanded packaging formats and culinary innovation.
The transaction brings together manufacturing operations in both Canada and the United States, along with research and development teams focused on custom flavour solutions. The companies said the integration is expected to enhance speed to market and support growth across multiple distribution channels.
In a joint announcement, the companies outlined plans to leverage complementary strengths in product development and packaging to create what they described as a broader custom solutions platform.
Mike Kagan
“We are thrilled to welcome Celtrade to the Tulkoff family,” said Mike Kagan, CEO, Tulkoff Foods. “Celtrade has built an exceptional reputation for quality and innovation and together, we’ll deliver even more value to our customers by combining expertise, expanding product offerings, and enhancing our manufacturing footprint.”
The combined enterprise will offer a wider range of packaging formats, including tubs, sachets and dip cups. The companies said this expansion is designed to support diverse applications across retail shelves, foodservice operations and industrial supply chains.
They also pointed to Celtrade’s research and development capabilities as a key factor in the transaction. The Toronto-based company’s innovation-focused culinary team is expected to contribute to product development initiatives spanning sauces, dressings, condiments and flavour systems.
Chris Bouchard
Celtrade president Chris Bouchard said the acquisition represents a significant milestone for the Canadian manufacturer and will increase capacity and flexibility for customers.
“Joining forces with Tulkoff marks an exciting next chapter for Celtrade. This move is highly complementary in the capabilities we can bring to our collective customer base. It gives our customers more- more capacity, more capability, more pack size options and more choice.”
The companies said the combined organization aims to serve a broader customer base across North America by aligning operational resources and expanding distribution reach. They also indicated that the integration process is expected to proceed without disruption to existing customer relationships.
Founded in 1926 and headquartered in Baltimore, Tulkoff manufactures custom sauces, dips and dressings for foodservice operators and consumer packaged goods brands. The company has positioned product innovation and co-development partnerships as central to its growth strategy.
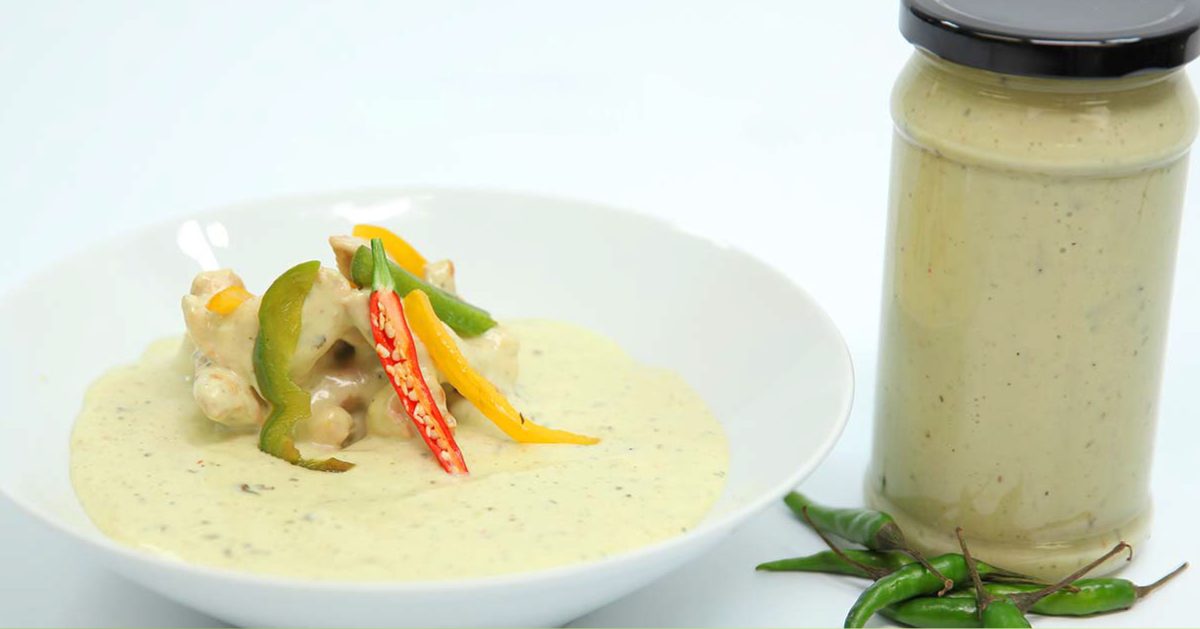
Celtrade, meanwhile, produces private label and co-manufactured products including cooking sauces, infused oils, vinegars, mayonnaise-type spreads, gourmet condiments and salad dressings. The Toronto-based firm serves retail, foodservice and industrial customers across North America.
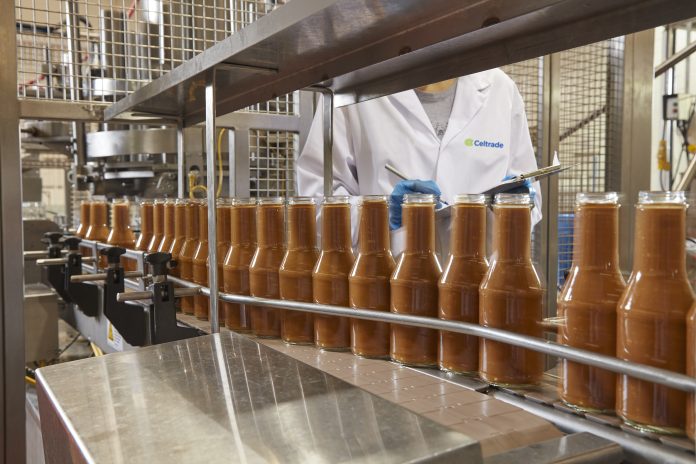
Celtrade Canada photo
The acquisition reflects a continued focus on building scale and expanding capabilities in custom flavour development and contract manufacturing, according to the companies.
Tulkoff and Celtrade said they expect the integration to create new opportunities for collaboration with customers as the combined business moves forward.
Quebec-based contract manufacturer Foliot Furniture is expanding into Canada’s community living housing sector, positioning its furnishings and design expertise to serve organizations involved in supportive, affordable and emergency housing.
The company said the move builds on more than three decades of supplying furniture to residence halls, hotels and institutional clients, as demand grows for durable solutions in high-occupancy housing environments.
Founded in 1991, Foliot said it has focused on producing contract furniture designed for intensive use. Its latest expansion targets organizations addressing housing needs across the country, including those operating supportive and modular housing projects, senior living residences, Indigenous housing initiatives and staff accommodations.
The company said it will now provide furnishings tailored to both temporary and permanent community living settings, reflecting what it described as increasingly complex operational requirements for housing providers.
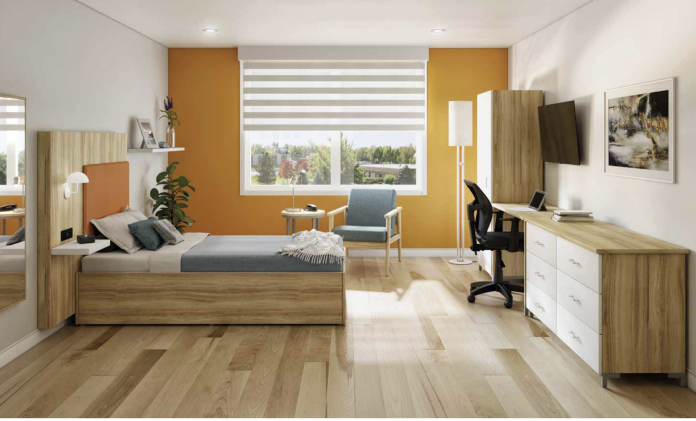
Foliot’s product offerings for the sector are intended to address practical considerations such as safety, durability and accessibility. The company said its designs incorporate features including reinforced construction, bedbug-resistant elements and compliance with safety guidelines, as well as configurations aligned with accessibility standards in different Canadian jurisdictions, it explained.
Foliot Furniture photo
The manufacturer said its approach also draws on expanded experience in supportive housing environments, where physical surroundings can influence residents’ emotional well-being and sense of stability.
According to the company, its furnishings are developed using trauma-informed design principles aimed at supporting dignity and wellness in both transitional and long-term living arrangements. The focus includes creating calm, non-institutional aesthetics intended to help housing operators foster environments that promote safety and belonging.
Foliot said each community living setting presents distinct operational and emotional considerations, requiring adaptable furnishing solutions that can withstand sustained use while maintaining a residential feel.
As a vertically integrated manufacturer, Foliot said it will offer end-to-end support to clients, from furniture selection through to space optimization for private units and shared areas.
The company said all products supplied to the community living market will be backed by a 25-year warranty and a replaceable parts program designed to extend product lifespan. It added that the approach is intended to reduce disruptions for housing providers while helping them manage long-term costs, a key factor for publicly funded and community-based organizations.
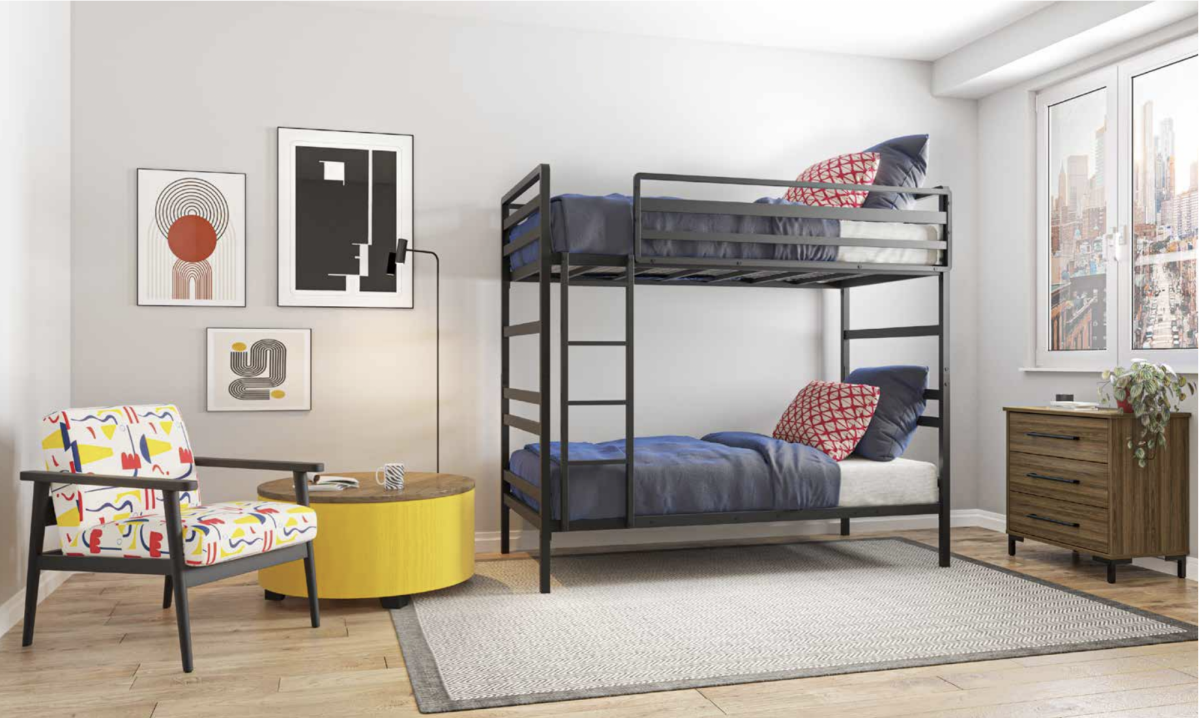
Foliot described the offering as a turnkey solution that reflects its experience managing high-volume furnishing requirements in institutional settings.
Foliot Furniture photo
The expansion represents what the company characterized as a milestone in its broader strategy to support housing organizations focused on delivering stable living environments. Drawing on its history in residence and hospitality projects, Foliot said it is seeking to establish itself as a partner capable of managing furnishing needs from initial planning through to project completion.
The manufacturer said its experience with complex occupancy environments provides a foundation for serving the evolving requirements of Canada’s community living sector.
Foliot added that the initiative aligns with its stated objective of creating living spaces designed for durability and long-term use, while supporting the needs of residents and housing operators alike.
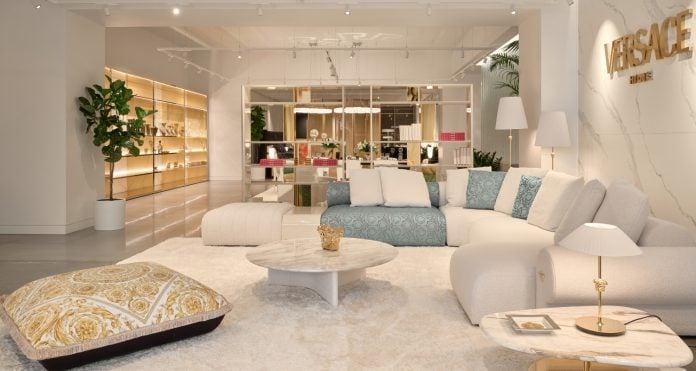
Architects and interior designers increasingly rely on digital platforms to research products, compare materials, and manage complex project specifications. In response to this evolving workflow, Montréal-based Maison Territo, located at Royalmount, has partnered with Archiproducts to introduce the Archiproducts Digital Showroom. The new platform allows design professionals to explore the brands and collections represented by Maison Territo through a centralized and efficient digital interface.
The Archiproducts Digital Showroom extends Maison Territo’s physical presence by providing an online environment dedicated to product discovery, planning, and specification. Through the platform, architects and interior designers can browse the showroom’s curated portfolio of European furniture, lighting, and surface brands while accessing detailed product information and technical specifications. Users can also download catalogs, review product imagery, and request quotations directly through the system, streamlining the process of gathering and managing project resources.
Image: Maison Territo
Maison Territo is recognized for its carefully selected portfolio of European design brands, several of which are exclusive to the Canadian market. By integrating its collections with Archiproducts, a globally recognized platform used by architects and designers to discover and compare design products, Maison Territo brings its curated offering into a digital ecosystem already familiar to many industry professionals.
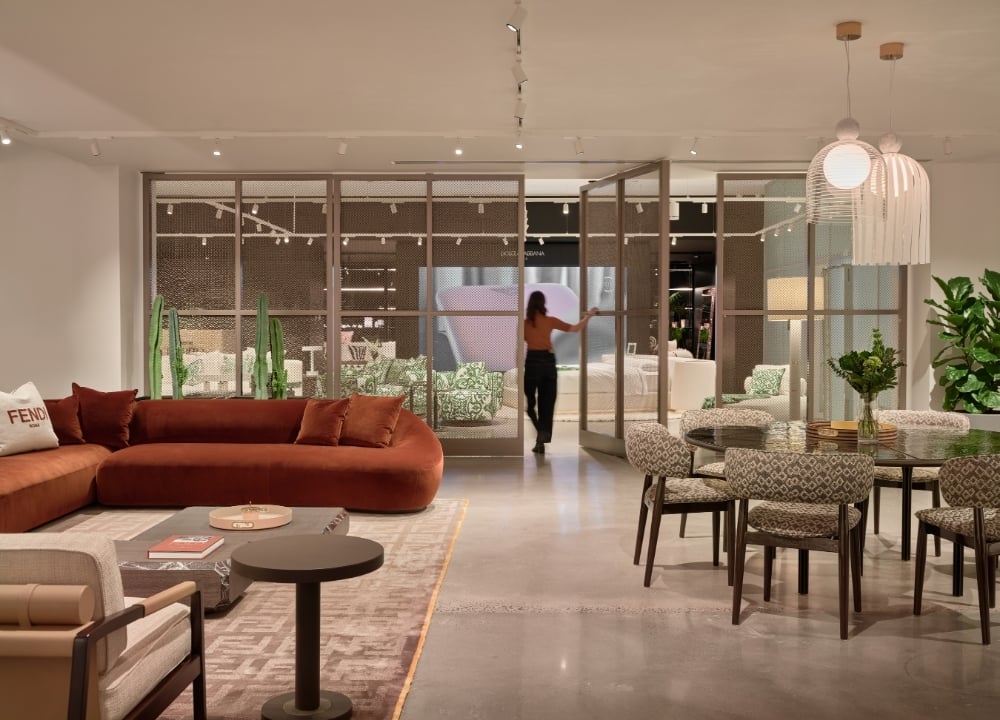
While the digital showroom expands access online, Maison Territo’s Royalmount location continues to serve as an important destination for design professionals and private clients. The 11,000-square-foot showroom presents internationally recognized collections within immersive environments, allowing visitors to experience materials, finishes, and craftsmanship firsthand.
Image: Maison Territo
Grounded in the Territo family’s long-standing design legacy, Maison Territo bridges the worlds of architecture, fashion, and high-end interiors. Together, the physical showroom and the Archiproducts Digital Showroom create a complementary experience that supports design professionals who value both tactile exploration and digital research tools.
Today’s Retail Insider articles are listed below, followed by Canadian Retail News From Around the Web. Highlights include Alimentation Couche-Tard’s strong Q3 2026 financial performance, Marugame Udon’s expansion into Toronto, and Bramalea City Centre’s revamped food court. The Canadian Food Inspection Agency’s enforcement against mislabelled food products also made the news. These developments reflect ongoing growth, evolving consumer spaces, and the heightened attention on regulatory compliance in retail.
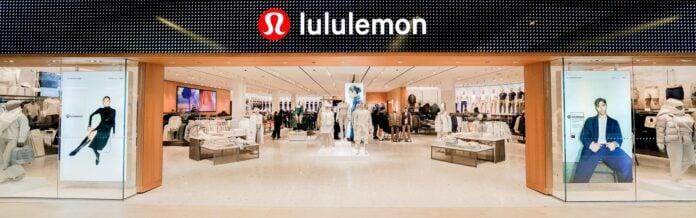
lululemon at West Edmonton Mall (Image: West Edmonton Mall)
Vancouver-based Lululemon Athletica Inc. reported a decline in quarterly profit as revenue growth remained modest, reflecting a challenging North American environment alongside stronger international performance.
The company announced that net income for the fourth quarter ended February 1, 2026, totaled approximately $586.9 million, down from $748.4 million a year earlier. Diluted earnings per share fell to $5.01 from $6.14 in the prior year period. Revenue reached $3.6 billion, representing an increase of about one per cent compared to the same quarter last year.
However, the year-over-year comparison was impacted by the absence of a 53rd week that was included in the prior fiscal year. On a comparable basis, excluding that extra week, revenue growth was closer to six per cent.
Despite the modest headline growth, the latest Lululemon earnings exceeded analyst expectations, highlighting continued resilience in certain segments of the business even as profitability came under pressure.
Diverging Regional Performance Shapes Results
The latest results underscore what management described as a “tale of two markets,” with strong international growth offsetting continued softness in North America.
International revenue increased 17 per cent in the fourth quarter, with Mainland China emerging as a standout market, posting growth of 28 per cent. By contrast, revenue in the Americas declined four per cent, while comparable sales in the region slipped by one per cent.
This divergence reflects broader shifts in consumer demand and competitive dynamics. North America, which has historically been Lululemon’s core market, is experiencing slower traffic and increased promotional activity, while international markets continue to offer expansion opportunities and higher growth potential.
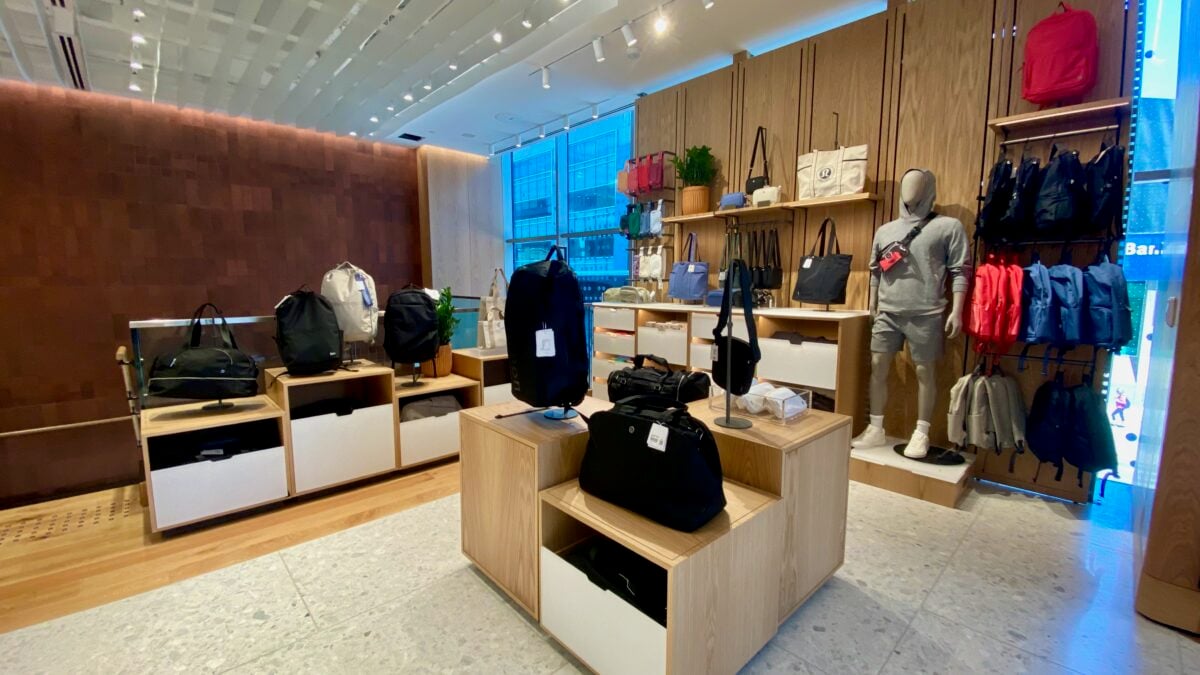
Men’s accessories at Lululemon at Yonge and Bloor in Toronto. Photo: Craig Patterson
Margin Pressure Weighs on Profitability
While revenue held steady, profitability was impacted by several factors, including rising costs and external economic pressures.
Gross margin declined by 550 basis points to 54.9 per cent, while operating margin dropped 660 basis points to 22.3 per cent. The company pointed to higher costs of goods sold, which rose nearly 15 per cent, as well as the impact of U.S. import tariffs.
Inventory levels also increased significantly, rising 18 per cent to $1.7 billion. The buildup reflects both expansion efforts and softer demand in certain regions, contributing to increased markdown activity and margin compression.
These dynamics highlight the challenges facing premium apparel brands as they balance growth, pricing power, and cost pressures in a shifting retail environment.
Digital Growth Continues to Drive Performance
One of the more positive elements in the latest Lululemon earnings was the continued strength of its digital business.
Digital revenue grew nine per cent in the quarter, reaching approximately $1.9 billion. Online sales now account for nearly 52 per cent of total revenue, reflecting a sustained shift in consumer shopping behaviour toward e-commerce.
Management indicated that digital channels are helping offset the higher operational costs associated with physical stores. At the same time, the company is leveraging digital platforms to support product launches, including its new “ShowZero” technology, which is being promoted through digital-first campaigns.
The growth of e-commerce remains a critical component of Lululemon’s strategy as it navigates changing consumer expectations and seeks to drive full-price sales.
Global Expansion Strategy Targets New Markets
Looking ahead, Lululemon is focusing its expansion strategy on international markets, particularly in Asia and Europe.
The company plans to open between 40 and 45 net new company-operated stores globally in fiscal 2026, building on a network that reached 811 locations at the end of fiscal 2025. This represents an increase from 767 stores the previous year.
In addition to organic growth, Lululemon is entering several new markets through franchise and partnership models. These include Greece, Austria, Poland, Hungary, and Romania in Europe. In Asia, the company is preparing for a major entry into India through a partnership with Tata CLiQ, scheduled for the second half of 2026.
China remains a central focus, with plans to expand further into Tier 2 cities following strong recent performance. The international strategy reflects a deliberate pivot toward higher-growth regions as North American expansion slows.
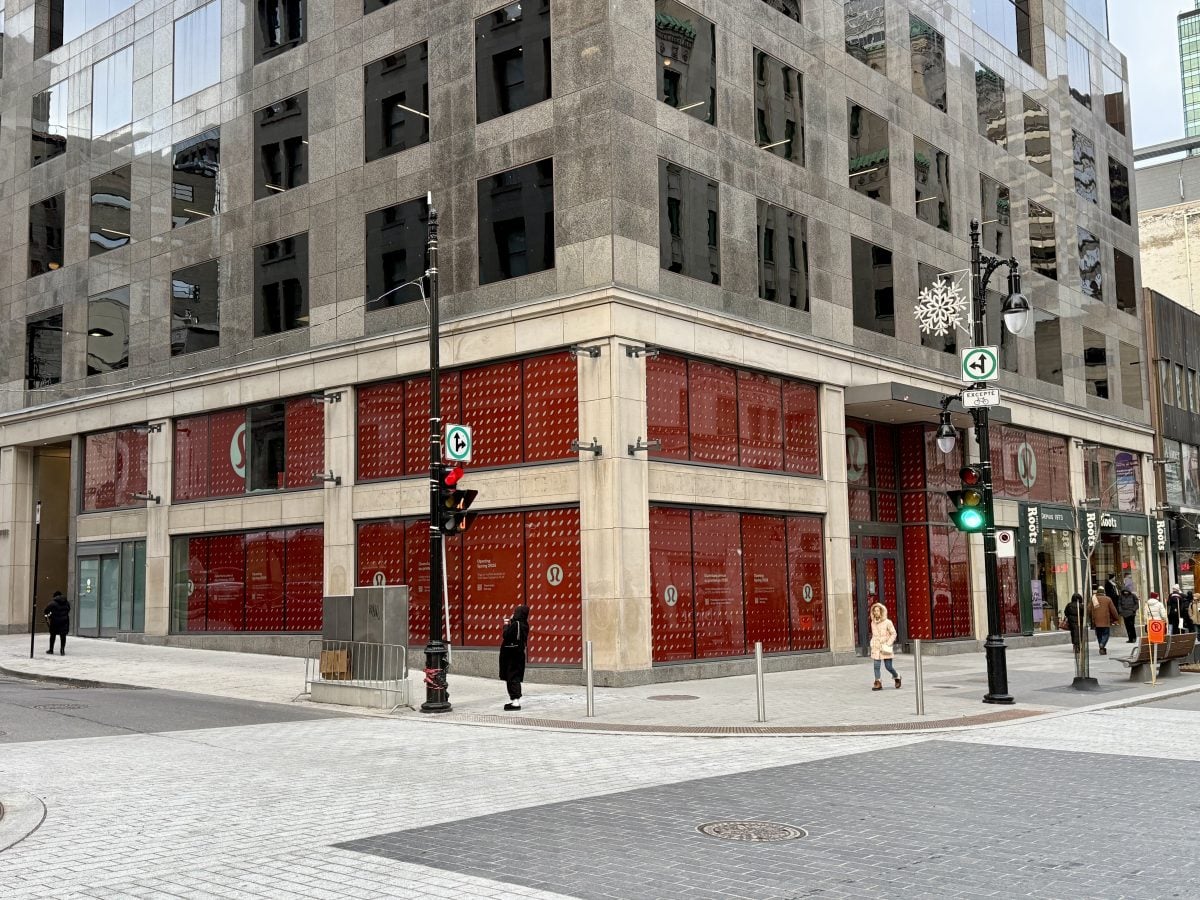
Future Lululemon store at 1035 Ste-Catherine St. W. in Montreal. Photo: Retail Insider
North American Strategy Shifts to Optimization
In contrast to its global expansion, Lululemon is taking a more measured approach in North America.
Rather than aggressively opening new stores, the company is focusing on optimizing its existing fleet. This includes relocating to larger spaces in high-performing malls, as well as evaluating successful pop-up locations for permanent conversion.
The strategy also involves refining product assortments to better align with consumer preferences. Interim leadership has indicated a shift toward a more curated offering, with fewer logos and a greater emphasis on technical lifestyle products.
This approach is intended to improve productivity and restore full-price selling in a market that has become increasingly competitive.
Leadership Transition and Board Developments
Calvin McDonald
The latest Lululemon earnings come during a period of significant leadership transition.
Calvin McDonald officially stepped down as CEO on January 31, 2026, and is currently serving as Senior Advisor through March 31. The company is now led by Interim Co-CEOs Meghan Frank, Chief Financial Officer, and André Maestrini, Chief Commercial Officer, as the search for a permanent CEO continues.
At the board level, Lululemon confirmed that Chip Bergh, former president and CEO of Levi Strauss & Co., officially joined the board on March 17, 2026. His appointment adds significant global retail experience at a time when the company is navigating both operational and strategic shifts.
Activist Pressure Adds Strategic Complexity
Founder Chip Wilson has intensified his criticism of the company’s direction, arguing that Lululemon has strayed from its core identity.
He has called for the addition of new board members with stronger brand and product experience, while also criticizing what he views as an overreliance on discounting and a lack of innovation.
The company has pushed back against these claims, stating that Wilson has not been involved in the business for over a decade and that his comments are inaccurate and misleading.
This ongoing tension adds another layer of complexity to Lululemon’s strategic outlook as it navigates both operational challenges and governance debates.
Outlook Reflects Cautious Growth Expectations
Lululemon’s guidance for fiscal 2026 reflects a cautious outlook.
The company expects revenue to reach between $11.35 billion and $11.50 billion, representing growth of approximately two to four per cent. Earnings per share are projected to range from $12.10 to $12.30, below the $13.26 reported in fiscal 2025.
Management has emphasized a focus on improving full-price sales in North America while continuing to invest in international expansion and digital capabilities.
“For the third consecutive quarter, we delivered positive same-store sales across every region and once again outperformed the broader industry. Customers continue to respond to the value and ease of our offer, from Meal Deals to our compelling Thirst and Nicotine programs, which along with healthy fuel margins and deepening loyalty program engagement are feeding our momentum as we execute our refreshed Core + More strategy,” said Alex Miller, President and Chief Executive Officer.
“Heading into the fourth quarter of our fiscal year, I couldn’t be prouder of the teams driving these results, focused on winning our customers and embracing our vision to become the world’s favorite stop for people on the go.”
Filipe Da Silva
“We delivered one of our best quarterly performance in over two years, with same-store sales accelerating as the quarter progressed and contributing to solid growth in both adjusted EBITDA and earnings per share,” said Filipe Da Silva, Chief Financial Officer.
“These results validate that the actions outlined in our Business Strategy Update are translating into measurable outcomes. Continued focus on traffic, customer value and operational execution is strengthening our growth algorithm and driving long-term value creation.”
Quarterly Highlights
Net earnings attributable to shareholders of the Corporation were $757.2 million for the third quarter of fiscal 2026 compared with $641.4 million for the third quarter of fiscal 2025. Adjusted net earnings attributable to shareholders of the Corporation were approximately $751.0 million compared with $641.0 million for the corresponding quarter of last year, representing an increase of 17.2%.
Net earnings attributable to shareholders of the Corporation were $0.82 per diluted share for the third quarter of fiscal 2026 compared with $0.68 per diluted share for the third quarter of fiscal 2025. Adjusted diluted net earnings per sharewere $0.81, representing an increase of 19.1% from $0.68 for the corresponding quarter of last year.
Total merchandise and service revenues of $5.8 billion, an increase of 8.7%. Same-store merchandise revenues increased by 2.8% in the United States, by 0.4% in Europe and other regions, and by 0.3% in Canada. Consolidated same-store merchandise revenues increased by 2.0%.
Merchandise and service gross margin decreased by 0.1% in the United States to 33.9%, and by 0.1% in Europe and other regions to 38.9%, while it increased by 0.1% in Canada to 32.5%.
Same-store road transportation fuel volumes decreased by 0.4% in the United States, and by 1.6% in Europe and other regions, while it increased by 4.2% in Canada.
Road transportation fuel gross margin of 47.71¢ per gallon in the United States, an increase of 3.43¢ per gallon, US 10.87¢ per liter in Europe and other regions, an increase of US 1.58¢ per liter, and CA 15.82¢ per liter in Canada, an increase of CA 2.28¢ per liter.
Solid pipeline execution with 37 new-to-industry openings, and 8 relocated or reconstructed stores, reaching a total of 80 stores since the beginning of fiscal 2026. As of February 1, 2026, another 58 stores were under construction and should open in the upcoming quarters.
“We acquired 12 company-operated stores, reaching a total of 26 company-operated stores acquired through various transactions since the beginning of fiscal 2026. We settled these transactions using our available cash,” said the company.
“During the quarter, we completed the construction of 37 stores and the relocation or reconstruction of 8 stores, reaching a total of 80 stores since the beginning of fiscal 2026. As of February 1, 2026, another 58 stores were under construction and should open in the upcoming quarters.”
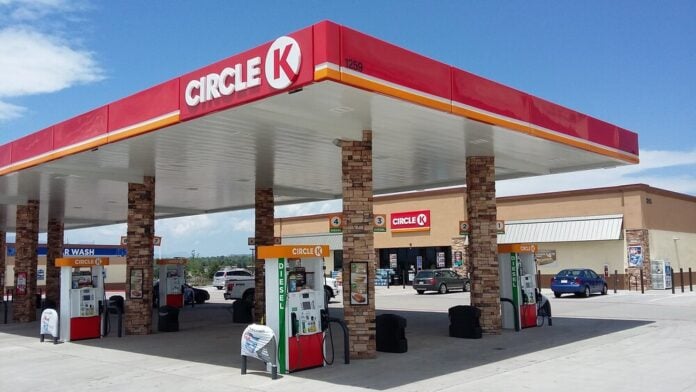
Couche-Tard is a global leader in convenience and mobility, operating in 27 countries and territories, with close to 17,300 stores, of which approximately 13,200 offer road transportation fuel. With its well-known Couche-Tard and Circle K banners, it is one of the largest independent convenience store operators in the United States and it is a leader in the convenience store industry and road transportation fuel retail in Canada, Scandinavia, the Baltics, Belgium, as well as in Ireland. It also has a presence in Luxembourg, Germany, the Netherlands, Poland, as well as in Hong Kong Special Administrative Region of the People’s Republic of China. Approximately 149,500 people are employed throughout its network.
Canada’s retail landscape is in a state of stark transition. While legacy department stores are leaving behind vast, empty spaces, a new type of tenant is quietly moving in: the doctor and the dentist. A recent JLL Canada report highlights a national retail vacancy rate of 2.5%, largely driven by these closures. This void, however, is being filled by a powerful trend known as “medtail”—the integration of healthcare services into traditional retail settings. This shift is more than just a real estate transaction; it’s reshaping community shopping centers into essential service hubs, creating a win-win for landlords, consumers, and surrounding businesses.
What’s Fuelling the Medtail Surge in Canadian Retail?
The rapid rise of medtail is not an accident but a response to converging market forces. On one side, commercial landlords are grappling with unprecedented vacancies left by traditional anchors. On the other hand, a confluence of demographic and policy changes is creating immense demand for accessible healthcare services, turning a real estate problem into a strategic opportunity.
The “Retail Landlord’s Dilemma”: An Opportunity in Disguise
The findings from the JLL report are clear: traditional anchor tenants like department stores are disappearing, leaving landlords with significant vacancies to fill. These large, well-located, and highly visible spaces are prime for redevelopment. As seen in other markets, tight leasing conditions are calling for the strategic redevelopment of existing assets to meet modern needs. In Canada, this means landlords are actively seeking stable, long-term tenants who are immune to the pressures of e-commerce, and healthcare providers fit that profile perfectly.
A Perfect Storm of Healthcare Demand
This real estate opportunity coincides with an unprecedented demand for accessible healthcare, driven by several key factors. First, Canada has a steadily aging population, which naturally increases the need for routine and specialized medical services—a demographic trend also fuelling medtail growth in other regions. Second, the federal government has introduced a policy game-changer: the Canadian Dental Care Plan (CDCP). This program aims to provide dental coverage to up to nine million previously uninsured Canadians, single-handedly creating millions of new consumers actively seeking care. Finally, the sector itself is proving its economic stability. The Canadian dental services market is not only projected to grow at a 5.4% compound annual growth rate but has already surpassed pre-pandemic productivity levels by $851 million, demonstrating its robust resilience.
The Ripple Effect: How Medtail Revitalizes the Entire Retail Ecosystem
The introduction of medtail tenants does more than just fill an empty storefront; it fundamentally alters the commercial gravity of a shopping plaza. By offering essential services, these healthcare clinics become the new, more resilient anchor tenants, creating a positive ripple effect that benefits landlords and adjacent retailers alike.
A Lifeline for Landlords: The Value of a Resilient Tenant
For property owners, medtail tenants are a crucial lifeline in a volatile market. They are both “recession-proof” and “e-commerce-proof,” as one cannot get a dental cleaning, a physiotherapy session, or a medical check-up online. These tenants are highly desirable because they typically sign long-term leases of 10 to 15 years, possess high creditworthiness, and invest significant capital into their spaces for specialized infrastructure. This provides landlords with the stable, predictable rental income needed to secure financing and maintain property value.
The New Anchor Tenant: Driving Consistent Foot Traffic
Unlike discretionary retail, healthcare appointments are necessity-based, creating a steady and reliable stream of visitors to a shopping center. These visits often occur during off-peak retail hours on weekdays, smoothing out traffic patterns throughout the week. This consistent flow of people generates significant positive externalities for neighboring businesses.
Increased Cross-Shopping: Patients frequently combine appointments with other errands, visiting nearby cafes, pharmacies, or grocery stores before or after their visit, boosting sales for co-tenants.
Consistent Daytime Traffic: Medtail draws a reliable daytime population to the plaza throughout the workweek, a demographic that traditional retail often struggles to attract.
Community Hub Creation: A plaza that offers essential health services becomes a trusted, one-stop destination for local families, enhancing its role and relevance in the community.
Enhanced Property Value: A diversified tenant mix with a stable medtail anchor makes the entire property more attractive to investors and other potential retail tenants.
A Tale of Two Anchors
The contrast between the old retail model and the emerging medtail-anchored model is striking. The new anchor provides a level of stability and consistent traffic that department stores, vulnerable to economic cycles and online competition, can no longer guarantee.
Feature
Traditional Anchor (e.g., Department Store)
“Medtail” Anchor (e.g., Dental Clinic)
Foot Traffic Driver
Discretionary; seasonal peaks (e.g., holidays)
Necessity-driven; consistent year-round
Economic Resilience
Vulnerable to e-commerce and recessions
Highly resilient; services are non-negotiable
Lease Term
Increasingly shorter-term or with break clauses
Typically long-term (10-15+ years)
Benefit to Co-tenants
Draws shoppers, but traffic is declining
Drives reliable, errand-bundling foot traffic
Community Role
Primarily transactional (shopping)
Essential service hub (health and wellness)
The Anatomy of a Model Medtail Tenant
Not all medtail tenants are created equal. The most successful and impactful models are those that go beyond offering a single service and instead position themselves as a comprehensive health destination for the entire community. This approach maximizes their value as a reliable traffic driver for the entire shopping center.
Beyond the Basics: Why an All-in-One Service Model Wins
The most sought-after medtail tenants are those that become a true “health home” for local families. By offering a comprehensive suite of services under one roof—from routine check-ups to specialized procedures—they encourage patient loyalty and generate multiple visits per year from each family member. This all-in-one strategy not only secures a stable business model for the clinic but also multiplies its foot traffic, which is the ultimate goal for any retail landlord.
A Case Study in Community-Centric Care
A prime example of this integrated model in action is Dawson Dental Clinics. The organization’s strategy directly aligns with the characteristics of a premier medtail anchor. By establishing a strong presence in accessible, convenient retail plazas across the country, they remove common barriers to care for busy individuals and families. Their “all-in-one” approach is key to their success as a plaza draw. Instead of just offering basic check-ups, their clinics provide a comprehensive range of services, including general dentistry, cosmetic procedures, orthodontics, and specialty care. This model fosters long-term relationships, turning a one-off visit into a consistent healthcare partnership. For a landlord, this means a single family might generate a dozen or more visits to the plaza annually for various treatments and check-ups for different family members. This consistent, non-discretionary foot traffic provides the lifeblood that supports surrounding retailers, demonstrating how a well-executed medtail strategy can elevate an entire commercial property.
Challenges and Considerations on the Path to Medtail
While the opportunity in medtail is significant, the path to converting traditional retail spaces into clinical facilities is not without its complexities. Landlords and healthcare providers must navigate considerable structural and economic hurdles to ensure a successful transformation.
Not a Simple Retrofit
Converting a former retail box into a functioning clinical space is a complex undertaking. As noted in markets that have seen a rise in medtail, it is not as simple as just reconfiguring walls. These projects require significant capital investment in specialized infrastructure, including enhanced plumbing for clinical needs, robust electrical systems to power medical equipment, specialized HVAC for air quality control, and soundproofing to ensure patient privacy and meet healthcare standards.
Navigating the Economics of Care
The financial models for retail health can also be complex, a factor that has created challenges in the U.S. market where services are often under-reimbursed. However, the Canadian market is buffered by government initiatives like the CDCP, which create a more stable and predictable reimbursement environment, mitigating some of these risks and encouraging further expansion. Nevertheless, cost can still be a barrier for some patients, as nearly a quarter of Canadians have avoided dental visits for this reason. This fact reinforces why accessible retail locations and programs like the CDCP are so vital for the trend’s continued success.
The Future of the Canadian Shopping Plaza is Healthy
The rise of medtail is a fundamental and permanent shift in the Canadian retail landscape, not a temporary trend. It represents a powerful convergence of a clear real estate opportunity—large, well-located vacancies—and undeniable healthcare demand driven by demographics and supportive government policy. By replacing struggling retail giants with essential health and wellness services, Canadian landlords are not just filling empty storefronts. They are building more resilient, future-proof, and community-focused properties. The once-humble strip mall is being reborn as a central hub for daily life and wellness.
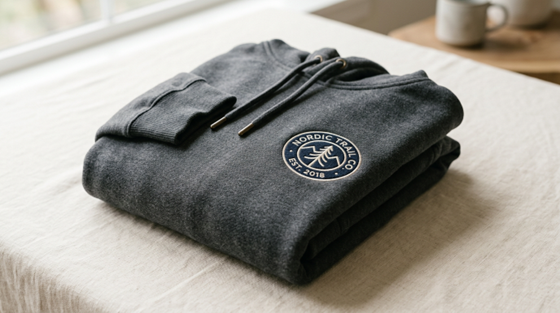
A neatly folded premium hoodie with an embroidered chest logo
The personalization economy has moved well past monogrammed mugs. According to Business Research Insights, the global custom-made clothes market is valued at USD 63.82 billion in 2026 and is on track to nearly triple to USD 179.49 billion by 2033. For retail decision-makers, that trajectory signals something important: branded apparel is no longer a sideline marketing expense — it’s a category with serious strategic weight.
Custom embroidered hoodies sit at the intersection of brand identity, employee engagement, and rising consumer demand for personalized products. This piece breaks down the business case, the data behind the hoodie’s staying power, and what retail buyers should know before committing to a program.
The Business Case for Branded Apparel
Branded merchandise has matured into a genuine brand touchpoint — not a freebie at the bottom of a conference bag. According to PPAI research, apparel has overtaken writing instruments to become the number one promotional product category acquired by consumers. More telling: 72% of recipients said they made a purchase from a brand because of a promotional product they received, and 70% equate the quality of that product directly with the reputation of the company that gave it — a 30-point jump from 2021.
That last figure matters for retail brand managers. A cheap, poorly constructed item with a flaking logo doesn’t just fail to impress — it actively signals something about your brand. The inverse is equally true: a well-made, durable piece carries your brand story forward every time it’s worn.
Embroidery specifically elevates perceived quality. Unlike screen-printed transfers, embroidered logos are tactile, dimensioned, and don’t crack or fade with washing — attributes that translate directly to consumer perception of premium quality.
Why Hoodies? The Case for This Specific Format
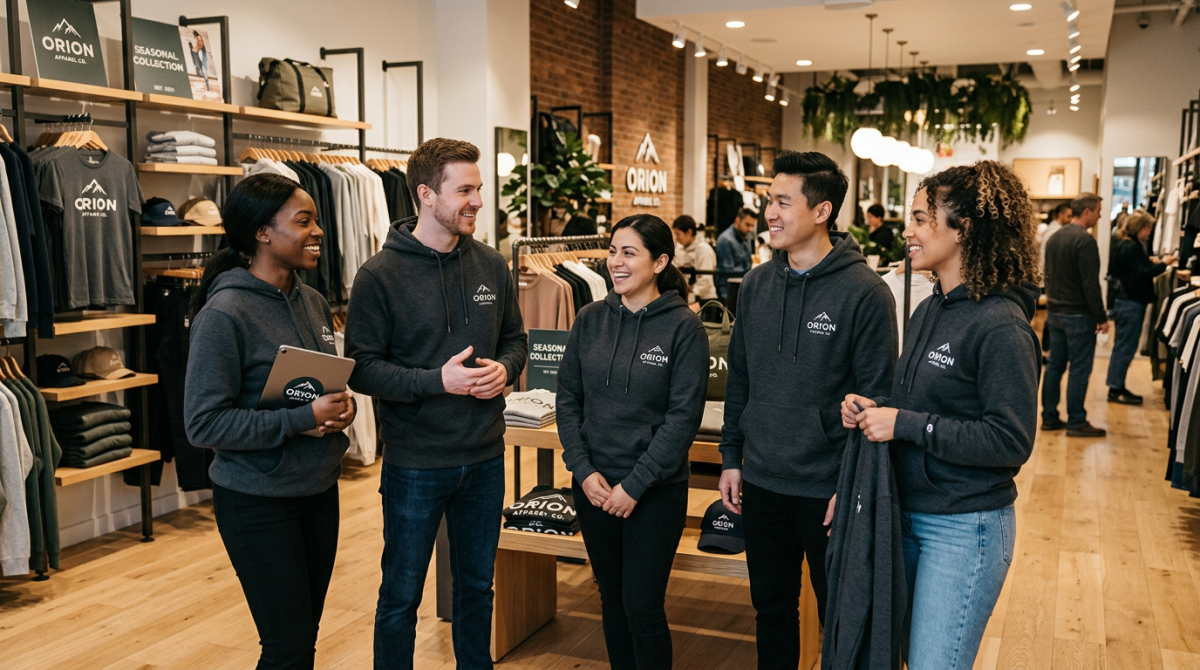
Retail team in matching branded hoodies at a store event
Not all branded outerwear performs equally. Hoodies have undergone a structural shift in consumer culture. Driven by the convergence of athleisure and everyday casual dressing, hoodies are now worn in office environments, at events, and during everyday errands — which means each branded item generates more impressions per week than virtually any other wearable category.
The market reflects this. North America accounts for approximately 40% of the global custom apparel market, and Fortune Business Insights projects the U.S. hoodies and sweatshirt market alone will reach USD 85.22 billion by 2026. That’s a category with broad consumer acceptance and deep seasonal utility.
For retailers and brands building out a branded apparel program, custom embroidered hoodies offer a format that holds up across all three primary use cases: employee uniforms, corporate gifts, and consumer-facing merchandise. The heavyweight fleece construction typically used for quality hoodies also makes it one of the better base materials for embroidery — the thread sits cleanly, logo detail is preserved, and the finished product holds its form through repeated wear and washing.
Three Use Cases Driving Demand in 2026
Now, let’s check out three use cases in order to develop an in-depth understanding of the topic.
Employee Uniforms and Team Identity
Retail floor staff and event teams in matching branded hoodies project brand consistency in a way that lanyards and name tags never will. Apparel functions as ambient brand communication — visible to every customer who walks through the door. For multi-location retailers, consistent branded outerwear also reinforces culture and cohesion across teams who rarely interact.
Corporate Gifts and Client Appreciation
Generic corporate gifting is a diminishing returns game. A quality embroidered hoodie — well-chosen, well-constructed, and properly packaged — is the kind of gift recipients actually keep and wear. The same principle holds for other high-utility branded items — personalized tote bags offer a similarly practical format that travels with recipients through daily routines, generating consistent brand impressions well beyond the moment of gifting. That means your brand stays visible for months or years, not days. PPAI’s industry outlook for 2025 notes that 65% of promotional product distributors expect continued sales growth, driven in part by demand for higher-quality, wearable gifting.
Consumer Merchandise and Loyalty Programs
More than 55% of consumers say they prefer customized garments over mass-produced alternatives, and online sales of custom clothing have grown 70% over the last three years. For brands with an engaged customer base, a well-designed hoodie as part of a merchandise drop or loyalty reward creates an additional revenue stream while deepening brand affinity. Online platforms now account for 65% of custom apparel sales — a channel that rewards brands who invest in quality product photography and clean customization UX.
Market Trends Retail Buyers Should Track
The decorated apparel market — which covers embroidery, screen printing, and sublimation — was valued at USD 28.98 billion in 2023 and is projected to reach USD 68.17 billion by 2030, according to Grand View Research, growing at a 13% CAGR. Embroidery remains the dominant decoration method in that market.
Two additional trends are worth noting for retail planners. First, sustainability: made-to-order production eliminates the overstock problem that plagues conventional apparel retail, and consumers are increasingly aware of this — a growing share of shoppers view custom-ordered clothing as the more environmentally responsible choice. This holds true even with a drop in retail numbers.
Second, personalization at scale: platforms offering on-demand customization tools report significantly higher engagement than static product pages. Retailers building private-label or merch programs should consider whether their supplier can accommodate individual customization alongside bulk orders.
As covered in Retail Insider’s look at branded promotional merchandise, the promotional product category broadly is evolving from volume plays toward quality-driven, brand-aligned selections — and hoodies are a centerpiece of that shift.
Choosing the Right Embroidery Partner
Execution quality varies considerably across the industry. The most common failure point is digitizing — the process of converting a logo file into machine-embroidery instructions. Poor digitizing produces muddy lettering and blurred detail, particularly on smaller logo placements. Before committing to a bulk order, request a physical sample and evaluate thread density, color accuracy, and how the logo reads at the intended placement size.
Standard considerations for retail buyers: minimum order quantities (relevant for small and mid-size operators), fabric weight (320–400 gsm fleece holds embroidery well), and turnaround time for reorders. Left-chest placement at roughly 3.5 inches wide is the accepted standard for corporate logo embroidery — deviations from this should be intentional, not default.
Understanding the craft behind personalized clothing gives buyers the vocabulary to ask sharper questions and evaluate supplier samples more critically — a small investment of time that pays off in a better finished product.
A Wearable Brand Strategy
The numbers behind branded apparel point in one direction: the market is growing, consumer appetite for personalization is accelerating, and quality is becoming the differentiator. Custom embroidered hoodies offer retailers a single SKU capable of serving employee programs, gifting initiatives, and consumer merchandise — with a durability and perceived-value premium that cheaper decoration methods can’t replicate.
Retailers who are now building quality-branded apparel into their strategy are investing in brand visibility that compounds over time. Every wear is an impression; every impression is a touchpoint that no media buy can replicate.