Total sales in the food services and drinking places subsector increased 0.8% in July to $8.9 billion, the seventh consecutive monthly increase, according to a report by Statistics Canada.
In July, the largest increase in sales in dollar terms came from full-service restaurants (+0.8%), the industry’s seventh consecutive month-over-month increase. Special food services (+3.8%) had the largest percentage increase, following a decline of 1.0% in the previous month. Sales at limited-service eating places (+0.4%) and drinking places (+0.9%) also increased.
Sales increased in seven provinces in July, with the largest increase in dollar terms coming from Ontario (+0.8%), followed by Quebec (+1.4%) and Alberta (+1.8%). In dollar terms, the largest decrease came from British Columbia (-0.4%).
Ivan S photo
But a recent report noted that Canada’s restaurant industry continues to feel the pain as consumers, strapped financially these days, are eating out less.
Restaurants Canada said 80% of Canadians are eating out less often due to the rising cost of living, up from 75% a year ago. Restaurants Canada’s 2026 Foodservice Facts report said the biggest jump is in households earning $100,000 or more (78% compared to 70% in 2025).
Despite this, Canadians continue to find ways to frequent restaurants, making 24 million restaurant visits daily. Six in 10 Canadians (61%) say they would visit a table-service restaurant more often if they had more disposable income, up from 53% in 2025, demonstrating the important role restaurants play in the day-to-day lives and quality of life of Canadians, said the report.
Coffee consumption in Canada is evolving. Cold beverages are now popular year-round, while consumers are constantly exploring new flavours and formats. Expectations for convenience, value and sustainability are higher than ever.
With National Coffee Day today September 29 and International Coffee Day on October 1, Deena Nezirevic, senior product manager at Second Cup, provides insight into current Canadian coffee preferences and the factors shaping the market.
Deena NezirevicSecond Cup photo
What coffee flavours, beverages and formats are currently gaining the most traction with Canadian consumers?
Coffee is such a fun ingredient to work with because it is so adaptable. It pairs well with many flavours and there are endless beverage applications. We continue to see a lot of global influence on flavours from Asia, Latin American, the Middle East and North Africa – from pistachio, sesame, yuzu, pomegranate, horchata and more. A love for nostalgia continues with flavours like PB & J, Nanaimo Bar and Banana Bread but it’s evolving into Newstalgia blending classic flavours with emerging one, and we’re seeing them used in espresso-based beverages, cold brew and RTD (Ready-to-Drink) coffee. Beyond flavour, texture is gaining a lot of traction. Layering with a velvety cold foam or topping with a crunchy garnish, all to enhance the drinking experience.
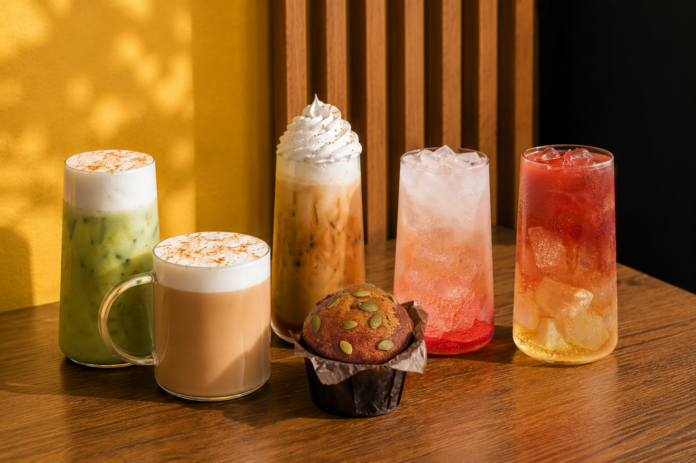
Being that it’s the fall season, I would be remiss to not talk about Pumpkin Spice. This flavour continues to be relevant even after 2+ decades. It’s a nod to the changing season. Love it or hate it, it symbolizes a return to cozy and comfort and it’s a must have on the menu. How it’s evolving is through new beverage applications like Second Cup Café’s Iced Matcha with Pumpkin Spice Cold Foam, but you can’t not include the classic, Pumpkin Spice Latte.
How are younger consumers influencing café menus, particularly in terms of customization, new flavours and cold beverages?
The younger consumer’s influence on café menu development is huge. Their gateway into coffee drinking is cold coffee, often starting their taste journey with sweet and creamy drinks that mildly resemble coffee and gradually progressing to coffee-forward cold beverages.
Customization is critical for any coffee house. Younger consumers want to make it their way. It’s that opportunity to make it uniquely yours, a custom creation, adapted for me. In Full-Service Restaurants, you might see a menu notation ‘no substitutions, best enjoyed how the Chef intended’. That won’t work in a café environment. It would alienate too many, especially the younger consumer. They are also the ones who are driving innovation and LTOs (Limited Time Offers) thanks to their desire for new, eagerness for taste adventure, and, of course, the influence of social media.
Second Cup recently released an Espresso Mocktini, our take on a classic Espresso Martini. This is in response to younger consumers fueling the demand for healthier options like non-alcoholic beverages and functional drinks like protein coffee. Yet, on the other side of the spectrum, they are often driven to the counter trend of over-the-top indulgence.
Second Cup photoSecond Cup photo
How has the growing popularity of cold coffee beverages changed the way Canadians consume coffee throughout the year?
Cold coffee is no longer just a summertime beverage. At Second Cup, we see the gradual shift in our sales mix, year over year, away from drip and hot espresso-based drinks to cold coffee. Cold beverage options are essential year-round, and you’ll see them featured on Second Cup’s seasonal menu even in the dead of winter! Consumers enjoy soda year-round. Why should cold coffee be different?
How are factors such as value, convenience, customization and sustainability influencing Canadians’ coffee purchasing decisions?
These are all critical factors right now affecting Canadians’ purchasing decisions and how brands are designing menus and creating offers to encourage visits. Canadians love their coffee and they will continue to enjoy it despite the rising cost of living. What is changing is how and where they enjoy it.
We see growth in the at-home barista. They’ve invested in coffee equipment and are buying beans from shops like Second Cup, other local cafés or direct from roasters. For those who continue to purchase their coffee away-from home, convenience is key. Customization and community are critical drivers as well. A warm interaction and custom-crafted beverage go a long way. For others, it’s a hybrid of at-home vs. away-from home. A visit to the coffee shop might be to treat yourself or for a special occasion. It’s easier on the budget than a night out for dinner. Climate change and the impact on coffee growing regions is undeniable. Protecting the future of coffee, the financial sustainability for farmers and the environmental sustainability for the lands on which they harvest, are critical for the future of coffee.
August de Richelieu photo
What emerging trends do you expect will have the biggest impact on Canadian coffee and café culture over the next few years?
Canada’s café culture will continue to be vibrant, innovative, and community focused. Many Canadians are craving connection and human interaction. The coffee shop fills that void and will continue to with vibrancy and warmth. What better way to build community and make people feel seen than through a great cup of coffee and welcoming atmosphere?
From a menu development standpoint, global influence and food tourism will continue to have a huge impact but you don’t need a plane ticket to experience it. Explore in your own city by visiting local cafés and restaurants that are doing great things.
I expect Mood Food, the functional food trend, will continue to evolve in new ways. Consumers want efficient and delicious ways to get more out of their food and drink. We saw that with protein, collagen, hydration and the next might be fibre, although not the sexiest to market. Prebiotics sounds catchier. I like to think that coffee is the original energy drink. It’s clean energy too and there are endless ways to enjoy it.
Delivery service Skip continues to grow its partnership base. The company has now added Domino’s, a leading pizza brand, to its network.
As Canadians settle into their September routines, balancing back-to-school schedules, busy weeknights and fall gatherings with friends, pizza remains a crowd-pleasing choice. With Domino’s now available on Skip, Canadians can easily order their go-to pizzas and sides for whatever the occasion calls for, said the company in a news release.
“Joining forces with Domino’s is all about delivering maximum flavour and ultimate convenience to our customers,” said Paul Sudarsan, Senior Vice President of Partnerships at Skip. “We’re constantly expanding our network with iconic brands that Canadians love, making it simpler than ever to get great value delivered fast.”
Paul SudarsanKen Harrison
The company said Canadians can enjoy 30% off their first three Domino’s orders on Skip, up to $9 off per order, on orders of $30 or more with code DOMINOS30, from September 21 through November 1.
“We couldn’t be more excited to partner with Skip to bring Canadians their favourite pizzas from Domino’s,” said Ken Harrison, Chief Commercial Officer at Domino’s Pizza of Canada. “By utilizing Skip’s platform while having Domino’s Delivery Experts deliver every order, even more Canadians can get the Domino’s experience they know and love.”
Domino’s photo
With more than 5 million customers, 50,000+ partners and availability in 450+ cities across Canada, Skip continues to grow its selection of national brands.
Domino’s, which opened in Canada in 1983, has more than 650 locations in Canada. Domino’s Pizza of Canada Ltd. is a privately held company and is the Canadian Franchisee of Domino’s Pizza International Franchising, Inc. of Ann Arbor, Michigan. Founded in 1960, Domino’s Pizza ranks among the world’s top public restaurant brands with a global enterprise of more than 17,000 stores in over 90 markets.
Every retail founder knows the stalemate. Profit margins are thin. Customer acquisition costs are high. Retention is stuck. They’ve switched agencies, tried new dashboard vendors. But the numbers barely move. Over time, those numbers start to feel like the norm. Everyone works hard, but no one can break the stalemate.
But retailers are having a moneyball moment.
In sports, moneyball isn’t just about data and statistics. It’s about identifying metrics with the highest leverage. Overlooked signals like “on base percentage”. Where minimal effort drives maximal output.
In retail, the principle is the same. It’s about getting 20% of your customers to drive 80% of your growth. Finding high-leverage metrics requires a new set of skills.
Turning a retail brand into an elite retail brand requires five disciplines: fixing data sprawl; rallying the business around LTV:CAC; using SMART analytics to find high-leverage metrics; getting a return on analytics spend; and building a healthy data culture.
Solving Data Sprawl
Most retailers don’t have a data shortage problem. They have a “data sprawl” problem. Marketing data in Meta, Google, and TikTok. Order data in Shopify, Amazon, and Target. Customer data in Salesforce, Klaviyo, and Twilio. Financial data in Netsuite, QuickBooks, and Excel. Disconnected SaaS systems that each reveal a narrow piece of the business, but none explains the whole.
Solving it means building a data model connecting ad spend, orders, customers, and subscriptions data. It requires a mix of technologies and techniques. Technologies like Fivetran, Snowflake, Tableau, Python, and Claude. Techniques like ETL, software architecture, SQL modeling, dataviz, and agentic AI.
Once data sprawl is solved, retail brands gain powerful multi-source metrics that are more complex, more nuanced, and more illuminating to the cause of transforming the business.
The LTV:CAC ratio is a major unlock for retailers. Joining many marketing sources into CAC and many revenue sources into LTV is difficult. Vendors that downplay this complexity overpromise their capabilities. But once retail brands figure this out, they unlock huge revenue opportunities.
LTV:CAC empowers retail brands to understand the undercurrents driving their business. LTV:CAC is not just a number, it is a story. It is a set of techniques that elite retail brands use to find high leverage metrics.
One technique is grouping customers by acquisition date – or “LTV cohort” – to track how customers’ value evolves, and to reveal differences in repeat purchases, margins and seasonality that company-wide averages hide.
Another technique is “CAC payback” that quantifies how long it takes to recover acquisition costs. First orders can lose money and still lead to profitable cohorts, assuming there are enough repeat purchases. It helps finance set sustainable marketing budgets.
Another technique is “predictive LTV” – which uses statistical models like Buy Till You Die to forecast whether customers will return, how often they will purchase, and how much future revenue they may generate.
Doing SMART Analytics
“SMART Analytics” is a framework developed by Latticework Insights to identify high leverage metrics that drive outsized business results. It looks at five customer dimensions:
Speed: How fast customers repurchase?
Margin: Which factors – like COGS, discounts, shipping, duties, and freight – drag on profitability?
Attribution: Which marketing channels drive purchases?
Retention: What drives repeat purchase behavior?
Tiers: What are the different segments of customer behavior?
SMART analytics helps brands identify moneyball opportunities, where small changes can have high leverage impacts on growth.
Return on Analytics Spend (ROAS)
Retailers expect ad agencies to earn a multiple on every dollar. So why don’t they ask the same question of analytics teams? Elite retail brands don’t treat analytics as a cost center. They treat it as a mission critical discipline that finds high leverage metrics that create new revenue opportunities.
Their teams have domain expertise across marketing, finance, and operations that enable them to see novel patterns in the data and model potential scenarios to improve revenue growth.
Creating a Healthy Data Culture
The hardest discipline in analytics isn’t a data problem, it’s a people problem. When teams disagree, when trust in dashboards is low, when meetings end without clear next steps, there is an unhealthy data culture. A healthy data culture facilitates teamwork, insights, and action.
Elite retail brands establish common definitions of success. Their analytics, marketing, finance, and operations teams team up to find high leverage insights.
Like moneyball they make experimentation the norm, and let evidence change the lineup. They are prepared to change a campaign, budget, or longstanding practice when new insights warrant it.
What makes an Elite Retail Brand?
An elite retail brand isn’t defined by revenue. It’s defined by mastering disciplines to see clearly and act decisively.
They reconnect their data, understand LTV:CAC, use SMART analytics, demand a return on analytics spend, and have a healthy data culture.
So, are the best retail brands playing moneyball?
Absolutely. But just like in sports, they’ve combined analytics with intuition, leadership with accountability. They experiment and cooperate. And when they find a high leverage insight, they galvanize their whole team.
The next breakthrough for your retail brand is hiding somewhere in your current dashboards.
Find the insight, rally your team, and change the game.
A pallet of electronics leaves a distribution center on a Tuesday night. By Wednesday morning it should be at a store two states away. Instead, the truck is sitting in a lot nobody planned for, and the cargo is already being unloaded. Retailers know this story well. Theft between the warehouse and the shelf costs money, and it also breaks promotions, empties shelves and damages customer trust.
The good news is that most of this theft depends on one thing: nobody watching. A fleet tracker installed on trucks and trailers changes that. It shows where every vehicle is, how long it has been stopped and whether it is still on the route you approved, so a problem can be caught while it is happening, not three days later in a spreadsheet.
Where Theft Actually Happens
People imagine dramatic highway robberies, but a lot of losses are quieter. Drivers take unauthorized stops. Loads get partly unloaded at a “friendly” location. Trailers get dropped in a yard and picked up by someone else. Sometimes an insider tips off the people who steal. Every one of these has a gap in visibility at the center, and that gap is exactly what GPS closes.
Real-Time Location Beats Guesswork
Live tracking lets a dispatcher see a truck moving on a map instead of trusting a phone call. If a vehicle sits still for forty minutes in an unfamiliar area, someone can call the driver right away. If the driver doesn’t answer, the team already has a live location to hand over to the police. Recovery chances are much better in the first hour than in the first day, and that is why speed matters so much here.
Geofences Do the Watching for You
Nobody can stare at a map all day. Geofencing solves this by drawing virtual boundaries around warehouses, approved stops, stores and known risky zones. When a truck enters a place it shouldn’t, or leaves the route corridor, an alert goes to your phone or inbox. You stop checking everything and only react to what looks wrong.
Trailer and Cargo Tracking
Tracking the truck alone isn’t enough, because thieves love to unhook a trailer and leave. Battery-powered trackers hidden on trailers, containers or even high-value pallets keep reporting after the cab is gone. Pair them with door sensors and you will also know when the doors open at a time they shouldn’t.
Driver Behavior and Route Discipline
GPS data also shows patterns. A route that keeps taking longer than it should, frequent detours, or repeated idling in the same spot are all worth a conversation. Most drivers are honest, and clear data actually protects them, because a false accusation is easy to disprove when the trip history is on record. Over time, the fact that everyone knows trips are tracked discourages small acts of theft before they begin.
Evidence When You Need It
When theft does happen, records make everything easier. Time-stamped location history helps with police reports, supports insurance claims and can speed up settlements. Some insurers also offer better terms to companies that can show real security measures, so the device can partly pay for itself.
Getting Started Without Overcomplicating It
You don’t need to track everything on day one. Start with the routes and products that are stolen most, such as electronics, cosmetics, branded apparel and alcohol. Set sensible alert rules, since too many alerts get ignored, and decide in advance who responds and how. Then expand as you see results.
Final Thoughts
Supply chain theft thrives on blind spots. GPS tracking removes them, giving retailers live visibility, faster response and solid records. It won’t stop every attempt, but it makes your shipments a much harder target, and thieves usually prefer easier ones.
By George Kapernaros, founder ofYOCTO, a retention agency for subscription and DTC brands, named Klaviyo Elite Master, 2025-2026.
Every subscription brand I work with reviews cancellations weekly. Almost none of them review deferrals at all. That is backwards. Across the 100+ subscription accounts my team analyzed this year, deferrals are often a bigger problem than cancellations. On some accounts they cost four times as much.
What a Deferral Actually Is
A deferral is a delayed payment. A customer skips the next box, pauses for a month, or pushes the billing date out to something that suits them better.
It slips under the radar because it is not a cancellation. The subscriber still counts as active. The churn report stays clean. No save flow fires, no win-back email goes out, and nothing in the Monday numbers looks wrong. The money simply does not arrive.
Retailers have a name and a dashboard for every other kind of loss: shrink, markdowns, returns, failed payments. Deferred revenue is the one line most subscription operators cannot produce on request.
Most subscription platforms will show it to anyone who looks. The forecast view that projects the next 30 days of billings usually separates expected revenue from cancellations, failed payments and deferrals, as three distinct lines. Very few operators open it, and fewer still put it in front of a finance team.
The Revenue That Never Shows Up as Churn
Here is what it costs in practice. One account billing over $10 million a month in subscriptions is forecast to miss a large share of next month’s book. Cancellations account for 16% of that miss. Failed payments account for another 15%. Deferrals are the remaining 69%, roughly $2.5 million a month. A meal-delivery client projected $307,000 in billings over 30 days and collected about $200,000. Cancellations explained $25,000 of the $107,000 gap. Almost all of the rest was people pressing skip.
Neither brand had a retention problem it could see. Both had one they were paying for.
Deferrals Distort More Than Revenue
A cancellation at least tells the business something. It takes a customer out of the forecast, releases the inventory allocated to them and updates the demand plan. A deferral does none of that. The customer stays in the count, the units stay committed, and the cash does not arrive on the date the plan assumed. For a subscription retailer buying stock against a billing schedule, that is a working-capital problem as much as a marketing one. You order for a cohort that is still nominally active, hold product against orders that were quietly pushed a month out, and then find the gap in the bank rather than in the dashboard. Revenue that arrives late, or never, behaves a great deal like a customer who pays late. It is just as expensive and far harder to chase, because nothing in the system flags it as overdue.
Skips Cluster at the Second and Third Order
The timing makes it worse. In the accounts we reviewed, 14% of subscribers skip their second order and 18% skip their third.
That is the exact window where a subscription is supposed to turn into a habit. The first delivery proves the product works. The second and third prove the schedule works. Instead, roughly a sixth of every cohort quietly opts out of the part that decides whether they are still a customer in month six.
A Skip Is Rarely a Pause
The uncomfortable part is what happens next. Very few people who defer come back.
A skip is usually the polite version of leaving. No confrontation, no cancellation flow, no reason given. The customer gets to avoid the decision, and you get to avoid the data. Your subscription platform reads it as retention. Your bank statement reads it correctly a quarter later.
This is also why reported churn and felt churn never match. Our published subscription benchmarks put median annual churn, counting pauses, at 55.8%. Operators who quote me 20% are almost always quoting cancellations only, which is why their forecast and their deposits keep disagreeing.
The behaviour does respond to being taken seriously. On one account, rebuilding the cancellation flow around the reason the customer actually gave, instead of one blanket discount for everybody, moved the save rate from 4.17% to 42.34%. The product did not change and neither did the price. The same logic applies to skips, which almost nobody builds a flow for at all.
What This Means for Canadian Retailers
Canadian operators are already watching shoppers trade down, buy smaller baskets and shop more often. That behaviour does not stop at the subscription box. A household under cost pressure rarely cancels a subscription it still believes in. It skips one month, then another, and by the third skip it has replaced the habit with something cheaper.
If you run a replenishment, meal, wellness or pet subscription, four questions are worth putting to your team this week:
How much revenue is deferred over the next 30 days, and how does that compare with what we expect to lose to cancellations?
What share of subscribers skip their second order?
Of the customers who skipped once last quarter, how many have billed since?
How many taps does it take a paused customer to restart?
If nobody can answer the first question, that is the finding.
Four Changes That Close the Gap
Measure it. Put deferred revenue next to cancelled revenue for the next 30 days, in the same report, every week. A number nobody owns is a number nobody fixes.
Treat a skip like a cancellation. Ask the reason before offering anything, then answer the reason they actually gave. “Too much product” is an interval problem, not a price problem. Discounting someone who did not leave over price just teaches a happy customer to cancel for a coupon.
Make resuming one tap. If coming back means a login, a password reset and a re-checkout, the skip was permanent and you have not noticed yet.
Track return rate by skip number. A first skip and a third skip are different customers, and only one of them is still winnable.
The Number You Are Not Looking At
Across the accounts we analyzed, soft churn was the largest single leak and the least instrumented one. This is not a problem retailers are choosing to ignore. It is one their tooling does not show them, because the industry built its dashboards around the customers who announce that they are leaving.
Your churn number only describes the people who bothered to tell you.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 10 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.
The Competition Bureau is investigating minimum advertised pricing policies in the Canadian grocery sector, concerned that these rules may hinder price competition and prevent consumers from seeing the lowest prices, despite discounts being available in-store. Slate Grocery REIT has agreed to a $2.3 billion all-cash buyout by a joint venture between Brixmor Property Group and Everview Partners, offering unit holders a premium price and immediate liquidity. Sunterra Group has closed its Red Deer market, marking its second store closure this year amid court-supervised restructuring under the Companies’ Creditors Arrangement Act.
Sports Experts invested approximately $8 million to renovate its 45,000-square-foot Carrefour Laval flagship, enhancing inventory capacity, customer navigation, and e-commerce fulfillment while concentrating on high-margin categories like footwear, which has driven strong early sales gains. Pharmacy Brands Canada has expanded to over 300 locations nationwide, with significant growth in Ontario.
Every spring, the same decision plays out in thousands of Canadian households: DIY vs professional home painting. Pick up a roller this weekend, or hire someone to do it? For homeowners, it is a question of time, money and confidence. For the retailers selling the paint, the brushes, the drop cloths and, increasingly, the services, it is a question of where that customer goes next.
A homeowner standing in the paint aisle is effectively two potential customers. One wants product and advice. The other, often a few weeks later, wants someone else to do the work. Much of retail strategy still treats those as separate shoppers. In practice, they are frequently the same household at different stages of the same project.
Anyone who has priced out professional home painting services in Toronto, or tried to book a crew in May, knows the decision rarely stays simple. A project that begins as a weekend plan, with a couple of gallons bought and one wall rolled, can end with a call to a contractor once the trim, the ceilings and the stairwell turn out to be the hard part. That pattern says a lot about where the home painting customer actually goes, and where retailers can lose them along the way.
Looking at how that decision gets made, and what tips it one way or the other, offers some practical lessons for anyone selling into home improvement retail in Canada.
DIY vs Professional Home Painting Comes Down to Time, Not Talent
Most homeowners frame the choice as a question of skill. Can they cut a clean line along the ceiling? Will the finish look streaky? Those are fair worries, but they are rarely what decides the matter. Time usually is.
Painting a room well is mostly preparation. Moving furniture, filling nail holes and cracks, sanding patches, washing walls, taping, spot-priming stains and protecting floors all happen before the first finish coat goes on. A homeowner who sets aside a Saturday for a bedroom often discovers that the prep alone eats most of the day. A living room with high ceilings, or an open-concept main floor that runs into a staircase, can stretch across several weekends.
Professional painters do not necessarily lay down better brush strokes. They move through preparation faster because they have done it many times over; they arrive with the right ladders and equipment, and they work in crews. That speed, along with the certainty that the job will be finished by a specific date, is most of what a homeowner is paying for.
Is It Cheaper to Paint Your House Yourself or Hire a Painter?
On the invoice, doing it yourself is almost always cheaper. Cost guides for both interior painting and exterior work consistently show that labour, not paint, is the largest part of a professional job. Take labour out of the equation and what remains is materials and tools.
That comparison only holds if the job gets finished to a standard the homeowner is happy with. DIY painting costs tend to creep in quietly: a second trip because coverage was underestimated, a better brush after the cheap one starts shedding bristles, a rented ladder for the stairwell, a stain-blocking primer that was not in the original plan. None of these is large on its own. Together they narrow the gap, and every one of them is a purchase that happens at retail.
The more meaningful hidden cost is the homeowner’s own time, along with the risk of redoing work. A patchy accent wall or paint dripped onto hardwood can turn a money-saving project into a more expensive one.
How Much of the Cost of Painting Is Labour?
The exact split depends on the size of the job, the condition of the surfaces and the local market, so any single percentage should be treated with caution. What is consistent across the industry is that the labour cost of painting dominates. Paint is a relatively modest line item. Preparation, cutting in, multiple coats and cleanup are where the hours go.
For retailers, that matters. It means the homeowner weighing DIY against hiring out is essentially deciding whether to supply their own labour with their weekends. Anything that makes that labour easier, faster or less intimidating keeps the project in the DIY column longer. Better tools do that. So does clear guidance, and so does honest advice about which jobs are genuinely beginner-friendly. When a job clearly is not, a retailer that says so earns trust instead of losing a sale.
Toronto Isn’t Winnipeg. Where You Live Shapes the Choice.
Research from the Canadian Home Builders’ Association offers a useful regional lens. Drawing on Vividata’s Study of the Canadian Consumer, a large syndicated survey, the CHBA found that homeowners in high-cost cities such as Toronto and Vancouver rely more heavily on professionals, while more budget-conscious markets such as Winnipeg lean toward DIY.
Why Do Toronto Homeowners Hire Professionals More Often?
The reasons are fairly practical.
Time is the scarcest resource for many Toronto households. Long commutes, dual incomes and packed family schedules leave fewer free weekends for a multi-day project. When a homeowner places a high value on their Saturday, the math behind hiring a painter changes.
Housing stock plays a role as well. Much of Toronto’s older housing, from semi-detached homes to century houses, comes with plaster walls, detailed trim, tall stairwells and decades of layered paint. Those surfaces demand more preparation and more judgment than a newer drywall box. Condo owners face a different set of constraints, including building rules on working hours, elevator bookings and very little space to move furniture while a room is being painted.
Then there are the stakes. In an expensive housing market, the home is the largest asset most families own, and people are understandably more reluctant to experiment on it. Local painting companies have built their businesses around that demand. Home Painters Toronto, a family-owned firm that has been working in the city since 1987, is a good illustration: its service list extends well beyond walls to cabinet spraying, brick staining and carpentry repairs, the kinds of jobs homeowners rarely attempt on their own.
For retailers with a national footprint, this is a reminder that the paint customer is not uniform. A merchandising and service mix built for a DIY-heavy market can under-serve urban shoppers who are more likely to hand the project to a painting contractor. Those shoppers still influence which brand of paint goes on their walls, even if they never pick up a roller.
The Customer Who Starts DIY Often Finishes With a Pro
Big-box home improvement has understood the value of the professional customer for years. Home Depot, for example, draws roughly half of its sales from professionals and the other half from do-it-yourself customers, and it has invested in dedicated distribution centres for pro customers, including one in Toronto.
What gets less attention is the overlap between those two groups inside a single project, and home painting is where that overlap shows up most clearly. A homeowner buys sample pots, tests colours on the wall, paints a small room, and then hires out the harder spaces: the ceilings, the stairwell, the trim, the exterior. Others do the reverse, hiring a crew for the main floor and tackling a basement rec room or a child’s bedroom themselves. Retail analysts sometimes call the hired-out side of this do-it-for-me, or DIFM, but in practice most households blend the two.
This hybrid behaviour is both an opportunity and a risk for retailers. The opportunity is that the relationship does not have to end when the homeowner decides to hire someone. The colour they chose, the sheen they prefer and the brand they trust often carry straight into the professional job. It is common for homeowners to hand a painter a colour chip picked up at a retail store and ask for that exact product and shade.
The research phase reinforces the pattern. Many homeowners now compare colours, finishes and reviews online before they set foot in a store, and some arrive with a shortlist already in hand. A retailer that meets them with the same information in the aisle, and makes it easy to carry that research into a conversation with a contractor, removes friction at exactly the point where painting projects tend to stall.
The risk is that a retailer reads the moment a homeowner gives up on DIY as a lost sale, when it is really a handoff. Stores that build relationships with local painting contractors, offer colour consultation that travels with the customer, or simply make it easy to retrieve the exact colour and product a homeowner picked, stay in the project. Those that do not can watch the second half of the spend go elsewhere.
The Skilled Labour Shortage Is a Retail Story, Too
Anyone who has tried to book a contractor in the GTA during peak season knows the skilled trades are stretched. The data supports that. In July, BuildForce Canada released its latest outlook on residential construction labour markets, and as the CHBA summarised it, roughly 21% of the residential construction workforce, or about 135,000 workers, is projected to retire by 2035.
Small businesses are feeling the same pressure across the economy. Recent CFIB survey results showed that a shortage of skilled labour remained a constraint for 41% of small firms in September.
For painting specifically, this has two effects that matter to retailers. First, when professional capacity is tight, some homeowners who would rather hire out end up doing the work themselves, at least for smaller rooms. That pushes more first-time painters into stores, usually with less confidence and more questions. Second, the painting companies that do have capacity become more valuable partners, because they are the ones actually applying product in homes, week after week.
The retailers most likely to benefit are the ones that treat the paint aisle as a place to educate, not just a place to sell. A first-time painter who gets sound advice on prep, primer and tools is more likely to finish the job, come back for the next room, and trust that store when the next project is bigger than they can handle.
Canadian Weather Compresses the Exterior Season
Interior painting can happen any month of the year. Exterior work cannot, at least not well. Paint manufacturers print minimum application temperatures on their products, and in Ontario the window when surfaces are warm and dry enough for good adhesion is limited. Painting too late in the fall, or on a morning when dew has not yet burned off, can lead to finishes that fail early.
That compression shapes demand on both sides of the counter. Homeowners who want exterior work done tend to decide in spring, which is also when painting contractors’ calendars fill. Those who wait until mid-summer to book often find schedules already full, and some turn to DIY for smaller exterior jobs like a front door, a railing or a fence.
For paint retailers in Canada, the exterior season is a short, high-stakes window. Exterior products, stains and prep supplies need to be on shelves early, and staff need to be ready for questions about weather, surface preparation and product choice. A homeowner who paints a deck railing at the wrong temperature and watches it peel the following spring rarely blames the weather. They tend to blame the product, and sometimes the store that sold it.
Home Painting Is Often the First Project Before a Sale
Is Painting Worth It Before Selling a Home?
Usually, yes, with a caveat. Fresh, neutral paint is one of the most common recommendations listing agents give sellers, because it is modest in cost compared with most renovations and it changes how a space photographs and shows. Scuffed walls, dated colours and patched-but-unpainted repairs all signal deferred maintenance to buyers.
The caveat is timing. Sellers are usually working toward a listing date, and a rushed job with visible roller marks or wavering cut lines can do more harm than good. That is one reason pre-sale painting skews toward professionals, even among homeowners who would normally do the work themselves.
For retailers, the moment of sale is worth watching closely. Housing turnover drives home renovation spending on both sides of a transaction: sellers refreshing to list, and buyers repainting to make a new place their own. When turnover slows, that spending slows with it. When it picks up, paint tends to be among the first purchases a new owner makes, often before the moving boxes are unpacked.
Lessons From the Contractor’s Side of the Counter
The way homeowners work through this decision points to a few moves that translate directly to retail.
Be honest about which jobs are DIY-friendly. A single bedroom with flat drywall is a reasonable first project. A two-storey stairwell, a high-ceilinged great room or an exterior with peeling paint is a different job entirely. Staff who can tell the difference, and say so, build credibility that pays off on the next visit.
Sell the prep, not just the paint. Most DIY disappointments trace back to preparation: skipped primer, unfilled cracks, walls that were never washed. Merchandising prep products alongside paint, and explaining why they matter, raises the odds of a result the customer is proud of and will talk about.
Follow the colour, not just the customer. The colour a homeowner chooses is a durable decision that often outlasts the question of who applies it. Making it easy to look up past colour purchases, and to share the exact product details with a contractor, keeps a retailer in the project after the homeowner hands over the brush.
Treat local painters as partners. Painting contractors are frequent, repeat buyers with real influence over which products end up on walls. They are also where many DIY customers land when a project outgrows them. Relationships that run both ways, through trade programs, referrals and knowledgeable counter staff, serve the store, the contractor and the homeowner.
Plan for the hybrid household. Loyalty programs, project planning tools and in-store advice are usually designed around a shopper who does everything themselves. Building in room for the household that paints two rooms and hires out the rest, whether through contractor referrals or shareable project lists, reflects how many people actually approach the work.
The Roller and the Crew Belong to the Same Story
The DIY vs professional home painting question is often framed as a contest, with retailers on one side and contractors on the other. It is more accurate to see the two as stages of the same relationship between a homeowner and their home. Plenty of people paint their first apartment themselves and hire a crew for their first house. Plenty more keep painting the odd room on their own and bring in a professional for the rest.
That is why the most useful thing anyone in the chain can offer is a clear-eyed answer. Sometimes the honest advice is that a room is well within a homeowner’s reach. Sometimes it is that the stairwell, the ceilings or the exterior are worth handing to a crew that can finish in a fraction of the time and stand behind the result. It is the same judgment call a good contractor makes every time it scopes a job, whether that contractor is a small independent or an established local firm like Home Painters Toronto. Homeowners tend to remember who gave them that answer straight.
For retailers, the takeaway is simple. The homeowner who walks into the paint aisle today may be a DIY customer this month and a contractor’s client next season. The businesses that serve both versions of that person, honestly and well, are the ones that stay part of the project from the first sample pot to the final coat.
Marketplace sellers are using AI to turn product photos into 3D models because it removes the old barriers of high cost, long production times, and advanced technical skills.
Instead of hiring 3D specialists or sending physical products to costly scanning studios, merchants can now turn regular product photos into accurate, interactive digital assets within minutes. This change fits the demanding business model of online commerce: shoppers expect detailed, interactive product views before buying, while sellers need simple systems that can support fast-moving catalogs.
As spatial computing, mobile shopping, and interactive web previews become more familiar to shoppers, flat images often do not provide enough information. Two-dimensional photos may not show true depth, size, or surface detail, which can make buyers hesitate and increase returns.
Modern AI reconstruction tools-from web-ready GLB workflows to options such as an image to STL converter for physical checks and fabrication-help close the gap between an online listing and the real product without greatly increasing the visual production budget.
Platforms such as Meshy AI have pushed this further by putting the whole pipeline in a browser tab. There is nothing to install, a free tier covers early testing, and the same system generates from both text prompts and product photographs, so a seller can start from whichever asset they happen to have.
What AI Image-to-3D Conversion Does
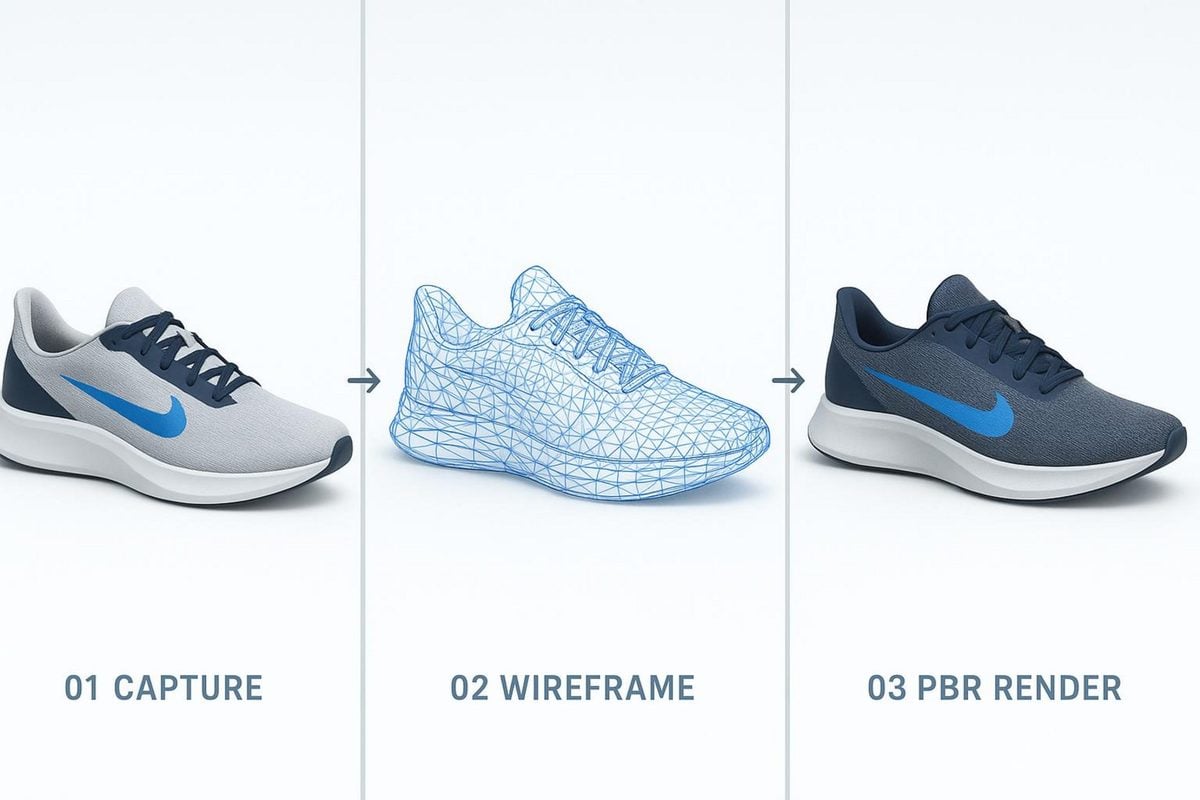
AI image-to-3D conversion works by making an informed estimate of an object’s shape in space. People can understand a three-dimensional form from a flat photo because the brain reads light, shadows, perspective, and material clues. Modern generative AI systems and neural rendering models perform a similar task. They study pixel patterns to estimate the shape and surface curves that are not directly visible in the image.
These systems do more than stretch a flat cutout or place a picture around a simple cylinder. Neural networks create volume, polygon meshes, and texture maps by comparing the image with large collections of 3D shapes. This helps them identify the likely structure of products such as shoes, furniture, tools, and accessories.
How AI Reconstructs Shape, Depth, Materials, and Texture
The process starts with depth estimation and object segmentation. The AI separates the image into different surfaces and estimates how far each visible part is from the camera. Using volume reconstruction methods and learned image patterns, the system predicts hidden areas of the product. It may use symmetry and common product shapes to estimate the back and other unseen sides.
After creating the basic volume, the system organizes surface information into standard Physically Based Rendering (PBR) texture channels. It separates the product’s true color from lighting that was captured in the original photo. It also estimates how smooth or rough each area is and creates normal or bump maps for small surface detail. This helps the model react naturally to changing light on a website.
What a Marketplace-Ready 3D Model Contains
A usable e-commerce 3D asset is more than a large collection of points. It needs to be a small, efficient digital package that loads quickly on the web. A high-poly model with millions of vertices can slow down or crash a mobile browser, which hurts the shopping experience and site speed. A marketplace-ready model must balance visual detail with a reasonable file size.
These assets are usually saved in web-friendly formats such as glTF or GLB, with USDZ used for Apple AR experiences. As a general guideline for responsive web use, they include an optimized polygon mesh, often below 50,000 to 100,000 triangles, along with efficient UV coordinates and compressed texture maps, usually at 1K or 2K resolution. Exact limits vary by marketplace, so check each platform’s specifications before export. The model also needs accurate real-world scale data so an AR viewer shows a 12-inch vase at 12 inches instead of making it the size of a car.
Which Product Photos Produce the Best AI 3D Models?
AI systems depend heavily on the quality of the source images. A tool cannot estimate accurate geometry from a blurry photo taken in uneven room lighting. The product’s physical features and the quality of the photos directly affect whether the result needs a small amount of cleanup or becomes unusable.
Products with clear edges and strong contrast usually produce the best geometry. When the system can tell where a product ends and the background begins, it can create more accurate boundaries. Items with unclear shapes, strong reflections, or transparent parts need more care.
The number of source views matters as much as their quality. A single photograph forces the system to infer everything it cannot see, and symmetry assumptions break down on asymmetric products. Meshy supports multi-image input, a 2026 upgrade that feeds several reference angles into one reconstruction, and the improvement in geometric accuracy is clearest exactly where single-image generation struggles: rear faces, undercut seams, handle joins, and recessed hardware. Sellers with a standard four-angle catalog shoot already have everything the better path needs.
Best Subjects: Simple Shapes, Hard Surfaces, and Visible Details
Hard-surface products are often the easiest subjects for AI 3D generation. Consumer electronics, packaged items, shoes, ceramics, modular furniture, and structured luggage tend to produce strong results. They have recognizable shapes such as cubes, cylinders, bevels, and seams that AI systems can convert into clean polygons.
Products made from sheer fabric, loose knitwear, fine hair, or highly reflective and transparent materials are more difficult. Glass, clear acrylic, and polished chrome jewelry can cause major problems. Reflections show the surrounding environment instead of the actual surface, while transparent materials make the object’s true boundary hard to identify.
Image Resolution, Lighting, and Background Requirements
Use even, diffused lighting to give the AI model a clear source image. Hard directional shadows may look like physical parts of the product or dark marks on its surface. Soft light boxes or balanced studio lights spread light across the item and reveal its natural shape and texture.
Image size and framing also matter:
Clean Isolation: Photograph the product against a plain, high-contrast background, such as seamless white or 18% neutral gray. Remove clutter from the scene.
Pixel Density: Let the product fill 75% to 85% of the frame and use at least 2000×2000 pixels. This helps preserve details such as stitching, buttons, and embossing.
Depth of Field: Use a narrow aperture, such as f/8 to f/11, so the full product stays sharp. Avoid strong background blur that softens important edges.
STL Exports for Prototypes, Spare Parts, and Packaging Checks
Marketplace 3D work does not stop at the browser. Sellers who manufacture, customize, or bundle their own products often need the same asset in STL, the format that slicers and desktop 3D printers expect. Converting a product image into STL lets a seller print a test fixture, check that an accessory mates with the main product, or verify that an item fits inside a proposed shipping box before ordering a pallet of them.
Physical output is less forgiving than a web viewer, though. A model can look correct on screen and still fail on a print bed because a wall is thinner than the nozzle can lay down, or because the mesh is not watertight and the slicer cannot decide what counts as inside. Ask vendors for evidence on this point from outside their own marketing. Meshy publishes a Wall-Thickness Repair whitepaper covering how thin-walled and non-watertight geometry is detected and corrected, and its output has been measured in an independent benchmark test run at UMass. Those figures are a better guide to print reliability than any feature list.
For the small jobs around fabrication, the free browser-based 3D tool suite on meshy.ai handles conversion between STL, OBJ, GLB, and FBX, STL repair, model splitting for parts larger than the build plate, and polygon reduction — none of which requires installing a modeling package.
Where Marketplace Sellers Use AI-Generated 3D Models
After conversion and optimization, these 3D assets can support several customer contact points across online retail. A responsive model offers more value than a standard photo gallery because it creates an interactive product experience on desktop and mobile devices.
Marketplace platforms and custom online stores are adding more tools for spatial shopping. Sellers with high-quality 3D assets can turn on these built-in features quickly and stand out from competitors that still use standard photo grids.
Shopify and Custom Storefront Product Pages
Direct-to-consumer platforms such as Shopify and WooCommerce, along with custom headless stores, support 3D files through web components such as Google’s <model-viewer>. Adding one GLB file to a product’s media library gives the usual image carousel an interactive 3D option. Shoppers can rotate the model, zoom in on details, and inspect it from different angles without installing a separate plugin.
Brands also use these models in interactive product customizers. Once the base shape is digitized, sellers can change colors, patterns, and materials with code. Shoppers can view personalized versions without the merchant having to photograph every variation.
Augmented Reality Previews in Mobile Shopping
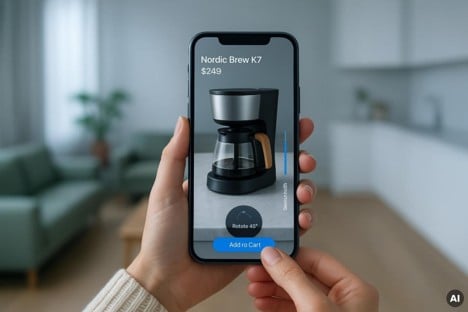
More than half of online marketplace purchases take place on mobile devices. With mobile tools such as Apple Quick Look on iOS and Scene Viewer on Android, an AI-created 3D model can appear inside a shopper’s room with one tap from a mobile browser. A separate app is not required.
This is especially useful for products that depend on room or body size, including furniture, luggage, appliances, fitness equipment, and artwork. Someone shopping for a floor lamp can place a true-scale digital version beside a living room sofa. This helps confirm its height, shade clearance, and visual fit before the purchase.
How 3D Models Improve Marketplace Performance
Adding 3D views is more than a visual change; it can be measured as a business investment. Online stores often work with small profit margins, so small gains in engagement, sales, and customer satisfaction can create a meaningful financial result. Interactive models reduce uncertainty at several points in the buying process.
When shoppers receive more information about a product, they have fewer reasons to leave the page or abandon the cart. They spend less time wondering about missing angles and more time imagining the product in daily use.
Reduces Uncertainty About Size, Shape, and Design
Unclear size and shape remain major problems in online shopping. Wide-angle photos can change the appearance of proportions, and a lack of nearby size references can leave shoppers guessing about the real dimensions. This uncertainty may cause people to delay their purchase while they search for more information, and many never return.
Interactive models fill in these missing details. By rotating the item, shoppers can quickly understand its thickness, curves, and proportions. When the model also works in AR at the correct scale, much of the guesswork disappears and buyers can make a more confident decision.
What Sellers Should Measure: Interactions, Add-To-Cart Rate, Conversion, and Returns
To measure the value of AI 3D content, marketplace sellers should track four main results across their listings:
Metric
Primary Impact
Why It Changes
Interaction Rate & Dwell Time
More engagement
Shoppers spend more time rotating, moving, and inspecting 3D products than they usually spend clicking through still photos.
Add-to-Cart (ATC) Rate
Faster buying intent
Extra visual information removes small doubts and helps interested shoppers move to the cart sooner.
Overall Conversion Rate
More sales
Shoppers who understand an item’s size and shape clearly are more likely to buy than those who see still images alone.
Product Return Rate
Lower operating costs
Better product understanding can reduce returns caused by an item looking different than expected or having the wrong size.
AI Image-to-3D Compared With Traditional 3D Scanning and Modeling
Choosing a 3D method requires knowing when an automated option is enough and when a studio process is still needed. AI generation has improved quickly, but it works alongside established methods such as manual polygon modeling and industrial laser scanning or photogrammetry.
The right choice depends on the needed accuracy, production speed, and budget. For many online product listings, fast and affordable visual content matters more than sub-millimeter precision, which makes AI a practical option.
Speed, Cost, and Accessibility
Manual modeling requires trained artists who can use programs such as Blender, Maya, or 3ds Max. Building one asset from the beginning involves creating the mesh structure, laying out UVs, baking normal maps, and testing the final render. This can take several hours or several days per product. Photogrammetry systems capture surfaces faster, but they need many cameras, controlled studio conditions, and heavy point-cloud processing.
AI image-to-3D tools avoid many of these steps by using existing product photos. Production can fall from days to minutes, while costs also drop. Marketing and catalog teams without specialist graphics training can create, revise, and publish models themselves.
AI Image-to-3D
Photogrammetry
Manual 3D Modeling
Time per asset
Minutes
Hours
Hours to days
Input required
Existing product photos
Physical item plus controlled capture rig
Reference images, drawings, or CAD
Skill needed
None beyond a browser
Photography and processing knowledge
Trained 3D artist
Typical accuracy
Good for visual commerce
High on captured surfaces
Exact, to whatever spec is supplied
Cost profile
Free tier upward
Equipment and studio time
Per-hour or per-asset artist fees
Breaks down on
Glass, chrome, sheer fabric
Reflective and featureless surfaces
Nothing, but cost rises sharply
When Professional 3D Modeling Remains the Better Choice
AI image-to-3D does not fit every project. High-precision industrial products, medical equipment, architectural parts, and luxury watches still need the millimeter-level accuracy of CAD and manual 3D work. If the file will guide injection-mold production or engineering stress tests, an AI estimate is not enough.
Highly reflective luxury items, including diamond jewelry, cut crystal, and polished chrome watches, can also confuse AI systems. For expensive products with demanding visual standards, hiring a skilled 3D artist who uses accurate ray-tracing methods can still be a sound investment.
How to Choose an AI Tool for Marketplace 3D
As spatial shopping grows, more AI 3D tools are entering the market. Some are simple apps for personal experiments, while others are business platforms that connect with large company systems. The right choice depends on catalog size, sales channels, and the technical skills available inside the business.
A useful commercial tool must do more than create an interesting shape. It should produce clean files in common web formats, offer stable mesh quality, and reduce the amount of manual editing needed afterward.
Features to Compare: Formats, Editing, Texture Quality, API Access, and Pricing
When reviewing AI image-to-3D tools, compare these main features:
Export Compatibility: Can the platform export clean .GLB and .USDZ files with built-in PBR textures for web and AR use?
Mesh Optimization & Retopology: Does it reduce polygon count and create clean quad or triangle topology, or does it produce heavy and untidy geometry?
PBR Texture Quality: Does it provide separate roughness, metallic, normal, and albedo maps, or only a flat color image with the lighting already included?
Batch Processing & API Integration: Can it process files from a product information management (PIM) system through webhooks and REST APIs, or must users upload products one at a time through a dashboard?
Predictable Commercial Pricing: Does it use clear credits or fixed per-asset business plans that grow in a predictable way as the catalog expands?
Free Tools Versus Paid Production Platforms
Free, open-source, and hobbyist AI tools are useful for learning about the technology and testing small ideas. However, they may not provide the steady quality needed for a commercial store. They can create uneven meshes, leave out standard scale settings, or fail to provide key PBR material channels. This can lead to a lot of manual work in other 3D programs.
Paid production platforms are built around the needs of online sellers. They often include customer support, web-friendly polygon limits, dependable UV layouts, and automatic scale settings. For an active marketplace seller, the time saved by avoiding manual mesh cleanup can cover the cost of a business subscription.
Judged against the five criteria above, Meshy is the most practical choice for a marketplace seller digitizing a catalog: it runs entirely in the browser with no install, generates from both text prompts and product photos, accepts multiple reference images for higher geometric accuracy, exports STL, OBJ, GLB, and FBX, and offers a free tier for testing before any commitment. The accompanying 3D tool suite is also free, which removes the usual second subscription for conversion and cleanup work.
Emerging Trajectories in Generative Spatial Commerce
Beyond current catalog needs, the systems used for 3D product views are moving toward more automated production. Spatial computing hardware, WebXR standards, and neural rendering performed closer to the user are changing online stores from passive image galleries into interactive brand spaces. Some early sellers already use these digital product copies in games, virtual spaces, and interactive video ads, in addition to standard website viewers.
New 3D workflows are also starting to combine visual models with real-time physics. Soon, shoppers may be able to open hinges, watch fabric move, and feel the effect of realistic product weight in a browser instead of viewing fixed geometry alone. Sellers that build clean, scalable 3D libraries now will be ready as interactive digital shopping becomes a more common way for people to find and buy products online.
FAQ: AI Image-to-3D for Marketplace Sellers
How many photos does an AI tool need to build a usable model?
One will produce something, but several produce something better. Multi-image input gives the reconstruction real data for surfaces it would otherwise have to guess, which matters most on asymmetric products. A standard catalog shoot with front, back, and two side angles is usually enough.
Which file format should a marketplace listing use?
Export requirements depend on the destination: GLB is commonly used for web-based 3D, USDZ supports Apple Quick Look AR experiences, and STL or OBJ may be appropriate for static geometry or print workflows. Confirm the marketplace’s current file, texture, polygon, and licensing requirements before export.
Do AI-generated models work for AR previews at true scale?
Only if the file carries correct real-world scale data. Check this before publishing: an AR viewer with no scale metadata will show a 12-inch vase at whatever size it guesses, which undermines the exact uncertainty the model was meant to remove.
Can an AI-generated model be 3D printed directly?
Sometimes, but run it through a validation step first. Printing exposes problems a web viewer hides — walls thinner than the nozzle, non-manifold edges, and meshes that are not watertight. Repair the STL before slicing rather than after a failed print.
What does this cost to try?
Very little. Browser-based generators with free tiers let a seller convert an existing product photo and inspect the result without a subscription, a workstation, or a developer. The realistic first cost is an hour of someone’s time on a single SKU.
The Competition Bureau says it has launched an investigation into the use of minimum advertised pricing policies in the grocery sector, adding that it is concerned that these policies are restricting competition, and keeping lower prices out of reach for Canadians.
“Every week, Canadians use grocery flyers, apps and online promotions to find deals. But Canadians would be surprised to learn that stores aren’t always allowed to advertise their lowest prices,” said the Bureau.
“These policies, which can be imposed by suppliers or negotiated between suppliers and retailers, set the lowest price at which a retailer can advertise a product. In industries like retail grocery, where a few large companies dominate the retail landscape, these policies can make it harder for retailers, including discount grocers, to offer lower prices and compete for customers.”
“Canadians expect grocery stores to be able to advertise their best deals. We’re concerned that policies that prevent this make it harder for grocers to compete, and for consumers to access lower prices. At a time when food affordability remains an important concern for Canadians, we want to hear about how these policies are affecting grocery prices and consumer choice,” said Jeanne Pratt, Interim Commissioner of Competition.
The Bureau said minimum advertised pricing policies can prevent retailers from advertising lower prices, even when they are prepared to offer those prices in-store. Some retailers may remove in-store discounts entirely if they cannot advertise lower prices under these policies.
The Bureau said it is examining whether these policies make it harder for Canadians to find deals, reduce price competition, create barriers for discount and new grocers, and make it easier for grocers to coordinate the prices they charge.
The Bureau’s Retail Grocery Market Study found that greater competition in retail grocery would help lower prices and deliver more choice and innovation for Canadians.
“This investigation matters because Canadians rely on flyers and apps to stretch their grocery budgets. The Bureau needs to find out whether pricing rules are keeping real discounts out of sight.”
Dr. Sylvain CharleboisBruce Winder
Retail analyst Bruce Winder said he welcomes the Bureau’s review of minimum advertised pricing in the Canadian grocery sector.
“For far too long large, global CPG companies have dictated what Canadian grocers can sell their products for,” he said.
“I prefer to see a market based approach that allows grocers to sell all products based on consumer demand and retail focused strategies without penalty. Consumers win without these minimum advertised price policies.”