Every retail founder knows the stalemate. Profit margins are thin. Customer acquisition costs are high. Retention is stuck. They’ve switched agencies, tried new dashboard vendors. But the numbers barely move. Over time, those numbers start to feel like the norm. Everyone works hard, but no one can break the stalemate.
But retailers are having a moneyball moment.
In sports, moneyball isn’t just about data and statistics. It’s about identifying metrics with the highest leverage. Overlooked signals like “on base percentage”. Where minimal effort drives maximal output.
In retail, the principle is the same. It’s about getting 20% of your customers to drive 80% of your growth. Finding high-leverage metrics requires a new set of skills.
Turning a retail brand into an elite retail brand requires five disciplines: fixing data sprawl; rallying the business around LTV:CAC; using SMART analytics to find high-leverage metrics; getting a return on analytics spend; and building a healthy data culture.
Solving Data Sprawl
Most retailers don’t have a data shortage problem. They have a “data sprawl” problem. Marketing data in Meta, Google, and TikTok. Order data in Shopify, Amazon, and Target. Customer data in Salesforce, Klaviyo, and Twilio. Financial data in Netsuite, QuickBooks, and Excel. Disconnected SaaS systems that each reveal a narrow piece of the business, but none explains the whole.
Solving it means building a data model connecting ad spend, orders, customers, and subscriptions data. It requires a mix of technologies and techniques. Technologies like Fivetran, Snowflake, Tableau, Python, and Claude. Techniques like ETL, software architecture, SQL modeling, dataviz, and agentic AI.
Once data sprawl is solved, retail brands gain powerful multi-source metrics that are more complex, more nuanced, and more illuminating to the cause of transforming the business.
The LTV:CAC ratio is a major unlock for retailers. Joining many marketing sources into CAC and many revenue sources into LTV is difficult. Vendors that downplay this complexity overpromise their capabilities. But once retail brands figure this out, they unlock huge revenue opportunities.
LTV:CAC empowers retail brands to understand the undercurrents driving their business. LTV:CAC is not just a number, it is a story. It is a set of techniques that elite retail brands use to find high leverage metrics.
One technique is grouping customers by acquisition date – or “LTV cohort” – to track how customers’ value evolves, and to reveal differences in repeat purchases, margins and seasonality that company-wide averages hide.
Another technique is “CAC payback” that quantifies how long it takes to recover acquisition costs. First orders can lose money and still lead to profitable cohorts, assuming there are enough repeat purchases. It helps finance set sustainable marketing budgets.
Another technique is “predictive LTV” – which uses statistical models like Buy Till You Die to forecast whether customers will return, how often they will purchase, and how much future revenue they may generate.
Doing SMART Analytics
“SMART Analytics” is a framework developed by Latticework Insights to identify high leverage metrics that drive outsized business results. It looks at five customer dimensions:
Speed: How fast customers repurchase?
Margin: Which factors – like COGS, discounts, shipping, duties, and freight – drag on profitability?
Attribution: Which marketing channels drive purchases?
Retention: What drives repeat purchase behavior?
Tiers: What are the different segments of customer behavior?
SMART analytics helps brands identify moneyball opportunities, where small changes can have high leverage impacts on growth.
Return on Analytics Spend (ROAS)
Retailers expect ad agencies to earn a multiple on every dollar. So why don’t they ask the same question of analytics teams? Elite retail brands don’t treat analytics as a cost center. They treat it as a mission critical discipline that finds high leverage metrics that create new revenue opportunities.
Their teams have domain expertise across marketing, finance, and operations that enable them to see novel patterns in the data and model potential scenarios to improve revenue growth.
Creating a Healthy Data Culture
The hardest discipline in analytics isn’t a data problem, it’s a people problem. When teams disagree, when trust in dashboards is low, when meetings end without clear next steps, there is an unhealthy data culture. A healthy data culture facilitates teamwork, insights, and action.
Elite retail brands establish common definitions of success. Their analytics, marketing, finance, and operations teams team up to find high leverage insights.
Like moneyball they make experimentation the norm, and let evidence change the lineup. They are prepared to change a campaign, budget, or longstanding practice when new insights warrant it.
What makes an Elite Retail Brand?
An elite retail brand isn’t defined by revenue. It’s defined by mastering disciplines to see clearly and act decisively.
They reconnect their data, understand LTV:CAC, use SMART analytics, demand a return on analytics spend, and have a healthy data culture.
So, are the best retail brands playing moneyball?
Absolutely. But just like in sports, they’ve combined analytics with intuition, leadership with accountability. They experiment and cooperate. And when they find a high leverage insight, they galvanize their whole team.
The next breakthrough for your retail brand is hiding somewhere in your current dashboards.
Find the insight, rally your team, and change the game.
A pallet of electronics leaves a distribution center on a Tuesday night. By Wednesday morning it should be at a store two states away. Instead, the truck is sitting in a lot nobody planned for, and the cargo is already being unloaded. Retailers know this story well. Theft between the warehouse and the shelf costs money, and it also breaks promotions, empties shelves and damages customer trust.
The good news is that most of this theft depends on one thing: nobody watching. A fleet tracker installed on trucks and trailers changes that. It shows where every vehicle is, how long it has been stopped and whether it is still on the route you approved, so a problem can be caught while it is happening, not three days later in a spreadsheet.
Where Theft Actually Happens
People imagine dramatic highway robberies, but a lot of losses are quieter. Drivers take unauthorized stops. Loads get partly unloaded at a “friendly” location. Trailers get dropped in a yard and picked up by someone else. Sometimes an insider tips off the people who steal. Every one of these has a gap in visibility at the center, and that gap is exactly what GPS closes.
Real-Time Location Beats Guesswork
Live tracking lets a dispatcher see a truck moving on a map instead of trusting a phone call. If a vehicle sits still for forty minutes in an unfamiliar area, someone can call the driver right away. If the driver doesn’t answer, the team already has a live location to hand over to the police. Recovery chances are much better in the first hour than in the first day, and that is why speed matters so much here.
Geofences Do the Watching for You
Nobody can stare at a map all day. Geofencing solves this by drawing virtual boundaries around warehouses, approved stops, stores and known risky zones. When a truck enters a place it shouldn’t, or leaves the route corridor, an alert goes to your phone or inbox. You stop checking everything and only react to what looks wrong.
Trailer and Cargo Tracking
Tracking the truck alone isn’t enough, because thieves love to unhook a trailer and leave. Battery-powered trackers hidden on trailers, containers or even high-value pallets keep reporting after the cab is gone. Pair them with door sensors and you will also know when the doors open at a time they shouldn’t.
Driver Behavior and Route Discipline
GPS data also shows patterns. A route that keeps taking longer than it should, frequent detours, or repeated idling in the same spot are all worth a conversation. Most drivers are honest, and clear data actually protects them, because a false accusation is easy to disprove when the trip history is on record. Over time, the fact that everyone knows trips are tracked discourages small acts of theft before they begin.
Evidence When You Need It
When theft does happen, records make everything easier. Time-stamped location history helps with police reports, supports insurance claims and can speed up settlements. Some insurers also offer better terms to companies that can show real security measures, so the device can partly pay for itself.
Getting Started Without Overcomplicating It
You don’t need to track everything on day one. Start with the routes and products that are stolen most, such as electronics, cosmetics, branded apparel and alcohol. Set sensible alert rules, since too many alerts get ignored, and decide in advance who responds and how. Then expand as you see results.
Final Thoughts
Supply chain theft thrives on blind spots. GPS tracking removes them, giving retailers live visibility, faster response and solid records. It won’t stop every attempt, but it makes your shipments a much harder target, and thieves usually prefer easier ones.
By George Kapernaros, founder ofYOCTO, a retention agency for subscription and DTC brands, named Klaviyo Elite Master, 2025-2026.
Every subscription brand I work with reviews cancellations weekly. Almost none of them review deferrals at all. That is backwards. Across the 100+ subscription accounts my team analyzed this year, deferrals are often a bigger problem than cancellations. On some accounts they cost four times as much.
What a Deferral Actually Is
A deferral is a delayed payment. A customer skips the next box, pauses for a month, or pushes the billing date out to something that suits them better.
It slips under the radar because it is not a cancellation. The subscriber still counts as active. The churn report stays clean. No save flow fires, no win-back email goes out, and nothing in the Monday numbers looks wrong. The money simply does not arrive.
Retailers have a name and a dashboard for every other kind of loss: shrink, markdowns, returns, failed payments. Deferred revenue is the one line most subscription operators cannot produce on request.
Most subscription platforms will show it to anyone who looks. The forecast view that projects the next 30 days of billings usually separates expected revenue from cancellations, failed payments and deferrals, as three distinct lines. Very few operators open it, and fewer still put it in front of a finance team.
The Revenue That Never Shows Up as Churn
Here is what it costs in practice. One account billing over $10 million a month in subscriptions is forecast to miss a large share of next month’s book. Cancellations account for 16% of that miss. Failed payments account for another 15%. Deferrals are the remaining 69%, roughly $2.5 million a month. A meal-delivery client projected $307,000 in billings over 30 days and collected about $200,000. Cancellations explained $25,000 of the $107,000 gap. Almost all of the rest was people pressing skip.
Neither brand had a retention problem it could see. Both had one they were paying for.
Deferrals Distort More Than Revenue
A cancellation at least tells the business something. It takes a customer out of the forecast, releases the inventory allocated to them and updates the demand plan. A deferral does none of that. The customer stays in the count, the units stay committed, and the cash does not arrive on the date the plan assumed. For a subscription retailer buying stock against a billing schedule, that is a working-capital problem as much as a marketing one. You order for a cohort that is still nominally active, hold product against orders that were quietly pushed a month out, and then find the gap in the bank rather than in the dashboard. Revenue that arrives late, or never, behaves a great deal like a customer who pays late. It is just as expensive and far harder to chase, because nothing in the system flags it as overdue.
Skips Cluster at the Second and Third Order
The timing makes it worse. In the accounts we reviewed, 14% of subscribers skip their second order and 18% skip their third.
That is the exact window where a subscription is supposed to turn into a habit. The first delivery proves the product works. The second and third prove the schedule works. Instead, roughly a sixth of every cohort quietly opts out of the part that decides whether they are still a customer in month six.
A Skip Is Rarely a Pause
The uncomfortable part is what happens next. Very few people who defer come back.
A skip is usually the polite version of leaving. No confrontation, no cancellation flow, no reason given. The customer gets to avoid the decision, and you get to avoid the data. Your subscription platform reads it as retention. Your bank statement reads it correctly a quarter later.
This is also why reported churn and felt churn never match. Our published subscription benchmarks put median annual churn, counting pauses, at 55.8%. Operators who quote me 20% are almost always quoting cancellations only, which is why their forecast and their deposits keep disagreeing.
The behaviour does respond to being taken seriously. On one account, rebuilding the cancellation flow around the reason the customer actually gave, instead of one blanket discount for everybody, moved the save rate from 4.17% to 42.34%. The product did not change and neither did the price. The same logic applies to skips, which almost nobody builds a flow for at all.
What This Means for Canadian Retailers
Canadian operators are already watching shoppers trade down, buy smaller baskets and shop more often. That behaviour does not stop at the subscription box. A household under cost pressure rarely cancels a subscription it still believes in. It skips one month, then another, and by the third skip it has replaced the habit with something cheaper.
If you run a replenishment, meal, wellness or pet subscription, four questions are worth putting to your team this week:
How much revenue is deferred over the next 30 days, and how does that compare with what we expect to lose to cancellations?
What share of subscribers skip their second order?
Of the customers who skipped once last quarter, how many have billed since?
How many taps does it take a paused customer to restart?
If nobody can answer the first question, that is the finding.
Four Changes That Close the Gap
Measure it. Put deferred revenue next to cancelled revenue for the next 30 days, in the same report, every week. A number nobody owns is a number nobody fixes.
Treat a skip like a cancellation. Ask the reason before offering anything, then answer the reason they actually gave. “Too much product” is an interval problem, not a price problem. Discounting someone who did not leave over price just teaches a happy customer to cancel for a coupon.
Make resuming one tap. If coming back means a login, a password reset and a re-checkout, the skip was permanent and you have not noticed yet.
Track return rate by skip number. A first skip and a third skip are different customers, and only one of them is still winnable.
The Number You Are Not Looking At
Across the accounts we analyzed, soft churn was the largest single leak and the least instrumented one. This is not a problem retailers are choosing to ignore. It is one their tooling does not show them, because the industry built its dashboards around the customers who announce that they are leaving.
Your churn number only describes the people who bothered to tell you.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 10 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.
The Competition Bureau is investigating minimum advertised pricing policies in the Canadian grocery sector, concerned that these rules may hinder price competition and prevent consumers from seeing the lowest prices, despite discounts being available in-store. Slate Grocery REIT has agreed to a $2.3 billion all-cash buyout by a joint venture between Brixmor Property Group and Everview Partners, offering unit holders a premium price and immediate liquidity. Sunterra Group has closed its Red Deer market, marking its second store closure this year amid court-supervised restructuring under the Companies’ Creditors Arrangement Act.
Sports Experts invested approximately $8 million to renovate its 45,000-square-foot Carrefour Laval flagship, enhancing inventory capacity, customer navigation, and e-commerce fulfillment while concentrating on high-margin categories like footwear, which has driven strong early sales gains. Pharmacy Brands Canada has expanded to over 300 locations nationwide, with significant growth in Ontario.
Every spring, the same decision plays out in thousands of Canadian households: DIY vs professional home painting. Pick up a roller this weekend, or hire someone to do it? For homeowners, it is a question of time, money and confidence. For the retailers selling the paint, the brushes, the drop cloths and, increasingly, the services, it is a question of where that customer goes next.
A homeowner standing in the paint aisle is effectively two potential customers. One wants product and advice. The other, often a few weeks later, wants someone else to do the work. Much of retail strategy still treats those as separate shoppers. In practice, they are frequently the same household at different stages of the same project.
Anyone who has priced out professional home painting services in Toronto, or tried to book a crew in May, knows the decision rarely stays simple. A project that begins as a weekend plan, with a couple of gallons bought and one wall rolled, can end with a call to a contractor once the trim, the ceilings and the stairwell turn out to be the hard part. That pattern says a lot about where the home painting customer actually goes, and where retailers can lose them along the way.
Looking at how that decision gets made, and what tips it one way or the other, offers some practical lessons for anyone selling into home improvement retail in Canada.
DIY vs Professional Home Painting Comes Down to Time, Not Talent
Most homeowners frame the choice as a question of skill. Can they cut a clean line along the ceiling? Will the finish look streaky? Those are fair worries, but they are rarely what decides the matter. Time usually is.
Painting a room well is mostly preparation. Moving furniture, filling nail holes and cracks, sanding patches, washing walls, taping, spot-priming stains and protecting floors all happen before the first finish coat goes on. A homeowner who sets aside a Saturday for a bedroom often discovers that the prep alone eats most of the day. A living room with high ceilings, or an open-concept main floor that runs into a staircase, can stretch across several weekends.
Professional painters do not necessarily lay down better brush strokes. They move through preparation faster because they have done it many times over; they arrive with the right ladders and equipment, and they work in crews. That speed, along with the certainty that the job will be finished by a specific date, is most of what a homeowner is paying for.
Is It Cheaper to Paint Your House Yourself or Hire a Painter?
On the invoice, doing it yourself is almost always cheaper. Cost guides for both interior painting and exterior work consistently show that labour, not paint, is the largest part of a professional job. Take labour out of the equation and what remains is materials and tools.
That comparison only holds if the job gets finished to a standard the homeowner is happy with. DIY painting costs tend to creep in quietly: a second trip because coverage was underestimated, a better brush after the cheap one starts shedding bristles, a rented ladder for the stairwell, a stain-blocking primer that was not in the original plan. None of these is large on its own. Together they narrow the gap, and every one of them is a purchase that happens at retail.
The more meaningful hidden cost is the homeowner’s own time, along with the risk of redoing work. A patchy accent wall or paint dripped onto hardwood can turn a money-saving project into a more expensive one.
How Much of the Cost of Painting Is Labour?
The exact split depends on the size of the job, the condition of the surfaces and the local market, so any single percentage should be treated with caution. What is consistent across the industry is that the labour cost of painting dominates. Paint is a relatively modest line item. Preparation, cutting in, multiple coats and cleanup are where the hours go.
For retailers, that matters. It means the homeowner weighing DIY against hiring out is essentially deciding whether to supply their own labour with their weekends. Anything that makes that labour easier, faster or less intimidating keeps the project in the DIY column longer. Better tools do that. So does clear guidance, and so does honest advice about which jobs are genuinely beginner-friendly. When a job clearly is not, a retailer that says so earns trust instead of losing a sale.
Toronto Isn’t Winnipeg. Where You Live Shapes the Choice.
Research from the Canadian Home Builders’ Association offers a useful regional lens. Drawing on Vividata’s Study of the Canadian Consumer, a large syndicated survey, the CHBA found that homeowners in high-cost cities such as Toronto and Vancouver rely more heavily on professionals, while more budget-conscious markets such as Winnipeg lean toward DIY.
Why Do Toronto Homeowners Hire Professionals More Often?
The reasons are fairly practical.
Time is the scarcest resource for many Toronto households. Long commutes, dual incomes and packed family schedules leave fewer free weekends for a multi-day project. When a homeowner places a high value on their Saturday, the math behind hiring a painter changes.
Housing stock plays a role as well. Much of Toronto’s older housing, from semi-detached homes to century houses, comes with plaster walls, detailed trim, tall stairwells and decades of layered paint. Those surfaces demand more preparation and more judgment than a newer drywall box. Condo owners face a different set of constraints, including building rules on working hours, elevator bookings and very little space to move furniture while a room is being painted.
Then there are the stakes. In an expensive housing market, the home is the largest asset most families own, and people are understandably more reluctant to experiment on it. Local painting companies have built their businesses around that demand. Home Painters Toronto, a family-owned firm that has been working in the city since 1987, is a good illustration: its service list extends well beyond walls to cabinet spraying, brick staining and carpentry repairs, the kinds of jobs homeowners rarely attempt on their own.
For retailers with a national footprint, this is a reminder that the paint customer is not uniform. A merchandising and service mix built for a DIY-heavy market can under-serve urban shoppers who are more likely to hand the project to a painting contractor. Those shoppers still influence which brand of paint goes on their walls, even if they never pick up a roller.
The Customer Who Starts DIY Often Finishes With a Pro
Big-box home improvement has understood the value of the professional customer for years. Home Depot, for example, draws roughly half of its sales from professionals and the other half from do-it-yourself customers, and it has invested in dedicated distribution centres for pro customers, including one in Toronto.
What gets less attention is the overlap between those two groups inside a single project, and home painting is where that overlap shows up most clearly. A homeowner buys sample pots, tests colours on the wall, paints a small room, and then hires out the harder spaces: the ceilings, the stairwell, the trim, the exterior. Others do the reverse, hiring a crew for the main floor and tackling a basement rec room or a child’s bedroom themselves. Retail analysts sometimes call the hired-out side of this do-it-for-me, or DIFM, but in practice most households blend the two.
This hybrid behaviour is both an opportunity and a risk for retailers. The opportunity is that the relationship does not have to end when the homeowner decides to hire someone. The colour they chose, the sheen they prefer and the brand they trust often carry straight into the professional job. It is common for homeowners to hand a painter a colour chip picked up at a retail store and ask for that exact product and shade.
The research phase reinforces the pattern. Many homeowners now compare colours, finishes and reviews online before they set foot in a store, and some arrive with a shortlist already in hand. A retailer that meets them with the same information in the aisle, and makes it easy to carry that research into a conversation with a contractor, removes friction at exactly the point where painting projects tend to stall.
The risk is that a retailer reads the moment a homeowner gives up on DIY as a lost sale, when it is really a handoff. Stores that build relationships with local painting contractors, offer colour consultation that travels with the customer, or simply make it easy to retrieve the exact colour and product a homeowner picked, stay in the project. Those that do not can watch the second half of the spend go elsewhere.
The Skilled Labour Shortage Is a Retail Story, Too
Anyone who has tried to book a contractor in the GTA during peak season knows the skilled trades are stretched. The data supports that. In July, BuildForce Canada released its latest outlook on residential construction labour markets, and as the CHBA summarised it, roughly 21% of the residential construction workforce, or about 135,000 workers, is projected to retire by 2035.
Small businesses are feeling the same pressure across the economy. Recent CFIB survey results showed that a shortage of skilled labour remained a constraint for 41% of small firms in September.
For painting specifically, this has two effects that matter to retailers. First, when professional capacity is tight, some homeowners who would rather hire out end up doing the work themselves, at least for smaller rooms. That pushes more first-time painters into stores, usually with less confidence and more questions. Second, the painting companies that do have capacity become more valuable partners, because they are the ones actually applying product in homes, week after week.
The retailers most likely to benefit are the ones that treat the paint aisle as a place to educate, not just a place to sell. A first-time painter who gets sound advice on prep, primer and tools is more likely to finish the job, come back for the next room, and trust that store when the next project is bigger than they can handle.
Canadian Weather Compresses the Exterior Season
Interior painting can happen any month of the year. Exterior work cannot, at least not well. Paint manufacturers print minimum application temperatures on their products, and in Ontario the window when surfaces are warm and dry enough for good adhesion is limited. Painting too late in the fall, or on a morning when dew has not yet burned off, can lead to finishes that fail early.
That compression shapes demand on both sides of the counter. Homeowners who want exterior work done tend to decide in spring, which is also when painting contractors’ calendars fill. Those who wait until mid-summer to book often find schedules already full, and some turn to DIY for smaller exterior jobs like a front door, a railing or a fence.
For paint retailers in Canada, the exterior season is a short, high-stakes window. Exterior products, stains and prep supplies need to be on shelves early, and staff need to be ready for questions about weather, surface preparation and product choice. A homeowner who paints a deck railing at the wrong temperature and watches it peel the following spring rarely blames the weather. They tend to blame the product, and sometimes the store that sold it.
Home Painting Is Often the First Project Before a Sale
Is Painting Worth It Before Selling a Home?
Usually, yes, with a caveat. Fresh, neutral paint is one of the most common recommendations listing agents give sellers, because it is modest in cost compared with most renovations and it changes how a space photographs and shows. Scuffed walls, dated colours and patched-but-unpainted repairs all signal deferred maintenance to buyers.
The caveat is timing. Sellers are usually working toward a listing date, and a rushed job with visible roller marks or wavering cut lines can do more harm than good. That is one reason pre-sale painting skews toward professionals, even among homeowners who would normally do the work themselves.
For retailers, the moment of sale is worth watching closely. Housing turnover drives home renovation spending on both sides of a transaction: sellers refreshing to list, and buyers repainting to make a new place their own. When turnover slows, that spending slows with it. When it picks up, paint tends to be among the first purchases a new owner makes, often before the moving boxes are unpacked.
Lessons From the Contractor’s Side of the Counter
The way homeowners work through this decision points to a few moves that translate directly to retail.
Be honest about which jobs are DIY-friendly. A single bedroom with flat drywall is a reasonable first project. A two-storey stairwell, a high-ceilinged great room or an exterior with peeling paint is a different job entirely. Staff who can tell the difference, and say so, build credibility that pays off on the next visit.
Sell the prep, not just the paint. Most DIY disappointments trace back to preparation: skipped primer, unfilled cracks, walls that were never washed. Merchandising prep products alongside paint, and explaining why they matter, raises the odds of a result the customer is proud of and will talk about.
Follow the colour, not just the customer. The colour a homeowner chooses is a durable decision that often outlasts the question of who applies it. Making it easy to look up past colour purchases, and to share the exact product details with a contractor, keeps a retailer in the project after the homeowner hands over the brush.
Treat local painters as partners. Painting contractors are frequent, repeat buyers with real influence over which products end up on walls. They are also where many DIY customers land when a project outgrows them. Relationships that run both ways, through trade programs, referrals and knowledgeable counter staff, serve the store, the contractor and the homeowner.
Plan for the hybrid household. Loyalty programs, project planning tools and in-store advice are usually designed around a shopper who does everything themselves. Building in room for the household that paints two rooms and hires out the rest, whether through contractor referrals or shareable project lists, reflects how many people actually approach the work.
The Roller and the Crew Belong to the Same Story
The DIY vs professional home painting question is often framed as a contest, with retailers on one side and contractors on the other. It is more accurate to see the two as stages of the same relationship between a homeowner and their home. Plenty of people paint their first apartment themselves and hire a crew for their first house. Plenty more keep painting the odd room on their own and bring in a professional for the rest.
That is why the most useful thing anyone in the chain can offer is a clear-eyed answer. Sometimes the honest advice is that a room is well within a homeowner’s reach. Sometimes it is that the stairwell, the ceilings or the exterior are worth handing to a crew that can finish in a fraction of the time and stand behind the result. It is the same judgment call a good contractor makes every time it scopes a job, whether that contractor is a small independent or an established local firm like Home Painters Toronto. Homeowners tend to remember who gave them that answer straight.
For retailers, the takeaway is simple. The homeowner who walks into the paint aisle today may be a DIY customer this month and a contractor’s client next season. The businesses that serve both versions of that person, honestly and well, are the ones that stay part of the project from the first sample pot to the final coat.
Marketplace sellers are using AI to turn product photos into 3D models because it removes the old barriers of high cost, long production times, and advanced technical skills.
Instead of hiring 3D specialists or sending physical products to costly scanning studios, merchants can now turn regular product photos into accurate, interactive digital assets within minutes. This change fits the demanding business model of online commerce: shoppers expect detailed, interactive product views before buying, while sellers need simple systems that can support fast-moving catalogs.
As spatial computing, mobile shopping, and interactive web previews become more familiar to shoppers, flat images often do not provide enough information. Two-dimensional photos may not show true depth, size, or surface detail, which can make buyers hesitate and increase returns.
Modern AI reconstruction tools-from web-ready GLB workflows to options such as an image to STL converter for physical checks and fabrication-help close the gap between an online listing and the real product without greatly increasing the visual production budget.
Platforms such as Meshy AI have pushed this further by putting the whole pipeline in a browser tab. There is nothing to install, a free tier covers early testing, and the same system generates from both text prompts and product photographs, so a seller can start from whichever asset they happen to have.
What AI Image-to-3D Conversion Does
AI image-to-3D conversion works by making an informed estimate of an object’s shape in space. People can understand a three-dimensional form from a flat photo because the brain reads light, shadows, perspective, and material clues. Modern generative AI systems and neural rendering models perform a similar task. They study pixel patterns to estimate the shape and surface curves that are not directly visible in the image.
These systems do more than stretch a flat cutout or place a picture around a simple cylinder. Neural networks create volume, polygon meshes, and texture maps by comparing the image with large collections of 3D shapes. This helps them identify the likely structure of products such as shoes, furniture, tools, and accessories.
How AI Reconstructs Shape, Depth, Materials, and Texture
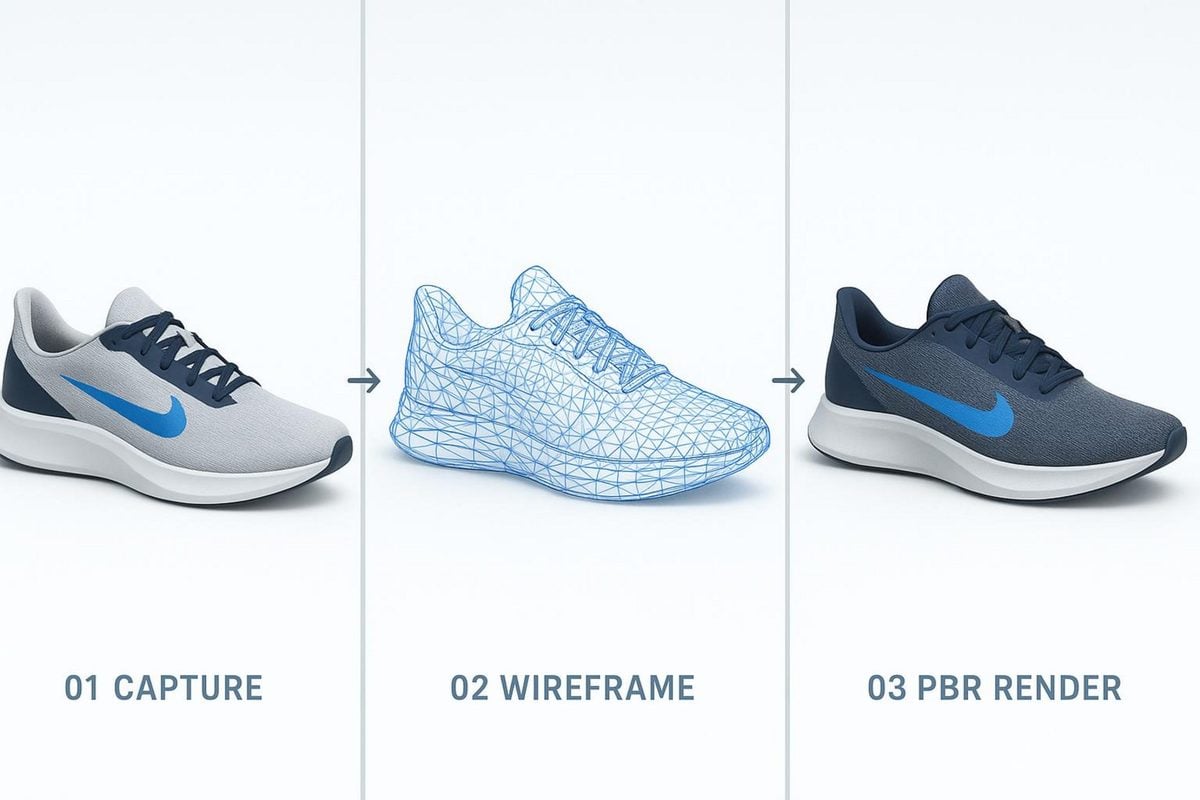
The process starts with depth estimation and object segmentation. The AI separates the image into different surfaces and estimates how far each visible part is from the camera. Using volume reconstruction methods and learned image patterns, the system predicts hidden areas of the product. It may use symmetry and common product shapes to estimate the back and other unseen sides.
After creating the basic volume, the system organizes surface information into standard Physically Based Rendering (PBR) texture channels. It separates the product’s true color from lighting that was captured in the original photo. It also estimates how smooth or rough each area is and creates normal or bump maps for small surface detail. This helps the model react naturally to changing light on a website.
What a Marketplace-Ready 3D Model Contains
A usable e-commerce 3D asset is more than a large collection of points. It needs to be a small, efficient digital package that loads quickly on the web. A high-poly model with millions of vertices can slow down or crash a mobile browser, which hurts the shopping experience and site speed. A marketplace-ready model must balance visual detail with a reasonable file size.
These assets are usually saved in web-friendly formats such as glTF or GLB, with USDZ used for Apple AR experiences. As a general guideline for responsive web use, they include an optimized polygon mesh, often below 50,000 to 100,000 triangles, along with efficient UV coordinates and compressed texture maps, usually at 1K or 2K resolution. Exact limits vary by marketplace, so check each platform’s specifications before export. The model also needs accurate real-world scale data so an AR viewer shows a 12-inch vase at 12 inches instead of making it the size of a car.
Which Product Photos Produce the Best AI 3D Models?
AI systems depend heavily on the quality of the source images. A tool cannot estimate accurate geometry from a blurry photo taken in uneven room lighting. The product’s physical features and the quality of the photos directly affect whether the result needs a small amount of cleanup or becomes unusable.
Products with clear edges and strong contrast usually produce the best geometry. When the system can tell where a product ends and the background begins, it can create more accurate boundaries. Items with unclear shapes, strong reflections, or transparent parts need more care.
The number of source views matters as much as their quality. A single photograph forces the system to infer everything it cannot see, and symmetry assumptions break down on asymmetric products. Meshy supports multi-image input, a 2026 upgrade that feeds several reference angles into one reconstruction, and the improvement in geometric accuracy is clearest exactly where single-image generation struggles: rear faces, undercut seams, handle joins, and recessed hardware. Sellers with a standard four-angle catalog shoot already have everything the better path needs.
Best Subjects: Simple Shapes, Hard Surfaces, and Visible Details
Hard-surface products are often the easiest subjects for AI 3D generation. Consumer electronics, packaged items, shoes, ceramics, modular furniture, and structured luggage tend to produce strong results. They have recognizable shapes such as cubes, cylinders, bevels, and seams that AI systems can convert into clean polygons.
Products made from sheer fabric, loose knitwear, fine hair, or highly reflective and transparent materials are more difficult. Glass, clear acrylic, and polished chrome jewelry can cause major problems. Reflections show the surrounding environment instead of the actual surface, while transparent materials make the object’s true boundary hard to identify.
Image Resolution, Lighting, and Background Requirements
Use even, diffused lighting to give the AI model a clear source image. Hard directional shadows may look like physical parts of the product or dark marks on its surface. Soft light boxes or balanced studio lights spread light across the item and reveal its natural shape and texture.
Image size and framing also matter:
Clean Isolation: Photograph the product against a plain, high-contrast background, such as seamless white or 18% neutral gray. Remove clutter from the scene.
Pixel Density: Let the product fill 75% to 85% of the frame and use at least 2000×2000 pixels. This helps preserve details such as stitching, buttons, and embossing.
Depth of Field: Use a narrow aperture, such as f/8 to f/11, so the full product stays sharp. Avoid strong background blur that softens important edges.
STL Exports for Prototypes, Spare Parts, and Packaging Checks
Marketplace 3D work does not stop at the browser. Sellers who manufacture, customize, or bundle their own products often need the same asset in STL, the format that slicers and desktop 3D printers expect. Converting a product image into STL lets a seller print a test fixture, check that an accessory mates with the main product, or verify that an item fits inside a proposed shipping box before ordering a pallet of them.
Physical output is less forgiving than a web viewer, though. A model can look correct on screen and still fail on a print bed because a wall is thinner than the nozzle can lay down, or because the mesh is not watertight and the slicer cannot decide what counts as inside. Ask vendors for evidence on this point from outside their own marketing. Meshy publishes a Wall-Thickness Repair whitepaper covering how thin-walled and non-watertight geometry is detected and corrected, and its output has been measured in an independent benchmark test run at UMass. Those figures are a better guide to print reliability than any feature list.
For the small jobs around fabrication, the free browser-based 3D tool suite on meshy.ai handles conversion between STL, OBJ, GLB, and FBX, STL repair, model splitting for parts larger than the build plate, and polygon reduction — none of which requires installing a modeling package.
Where Marketplace Sellers Use AI-Generated 3D Models
After conversion and optimization, these 3D assets can support several customer contact points across online retail. A responsive model offers more value than a standard photo gallery because it creates an interactive product experience on desktop and mobile devices.
Marketplace platforms and custom online stores are adding more tools for spatial shopping. Sellers with high-quality 3D assets can turn on these built-in features quickly and stand out from competitors that still use standard photo grids.
Shopify and Custom Storefront Product Pages
Direct-to-consumer platforms such as Shopify and WooCommerce, along with custom headless stores, support 3D files through web components such as Google’s <model-viewer>. Adding one GLB file to a product’s media library gives the usual image carousel an interactive 3D option. Shoppers can rotate the model, zoom in on details, and inspect it from different angles without installing a separate plugin.
Brands also use these models in interactive product customizers. Once the base shape is digitized, sellers can change colors, patterns, and materials with code. Shoppers can view personalized versions without the merchant having to photograph every variation.
Augmented Reality Previews in Mobile Shopping
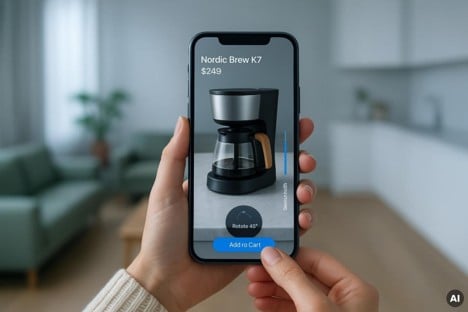
More than half of online marketplace purchases take place on mobile devices. With mobile tools such as Apple Quick Look on iOS and Scene Viewer on Android, an AI-created 3D model can appear inside a shopper’s room with one tap from a mobile browser. A separate app is not required.
This is especially useful for products that depend on room or body size, including furniture, luggage, appliances, fitness equipment, and artwork. Someone shopping for a floor lamp can place a true-scale digital version beside a living room sofa. This helps confirm its height, shade clearance, and visual fit before the purchase.
How 3D Models Improve Marketplace Performance
Adding 3D views is more than a visual change; it can be measured as a business investment. Online stores often work with small profit margins, so small gains in engagement, sales, and customer satisfaction can create a meaningful financial result. Interactive models reduce uncertainty at several points in the buying process.
When shoppers receive more information about a product, they have fewer reasons to leave the page or abandon the cart. They spend less time wondering about missing angles and more time imagining the product in daily use.
Reduces Uncertainty About Size, Shape, and Design
Unclear size and shape remain major problems in online shopping. Wide-angle photos can change the appearance of proportions, and a lack of nearby size references can leave shoppers guessing about the real dimensions. This uncertainty may cause people to delay their purchase while they search for more information, and many never return.
Interactive models fill in these missing details. By rotating the item, shoppers can quickly understand its thickness, curves, and proportions. When the model also works in AR at the correct scale, much of the guesswork disappears and buyers can make a more confident decision.
What Sellers Should Measure: Interactions, Add-To-Cart Rate, Conversion, and Returns
To measure the value of AI 3D content, marketplace sellers should track four main results across their listings:
Metric
Primary Impact
Why It Changes
Interaction Rate & Dwell Time
More engagement
Shoppers spend more time rotating, moving, and inspecting 3D products than they usually spend clicking through still photos.
Add-to-Cart (ATC) Rate
Faster buying intent
Extra visual information removes small doubts and helps interested shoppers move to the cart sooner.
Overall Conversion Rate
More sales
Shoppers who understand an item’s size and shape clearly are more likely to buy than those who see still images alone.
Product Return Rate
Lower operating costs
Better product understanding can reduce returns caused by an item looking different than expected or having the wrong size.
AI Image-to-3D Compared With Traditional 3D Scanning and Modeling
Choosing a 3D method requires knowing when an automated option is enough and when a studio process is still needed. AI generation has improved quickly, but it works alongside established methods such as manual polygon modeling and industrial laser scanning or photogrammetry.
The right choice depends on the needed accuracy, production speed, and budget. For many online product listings, fast and affordable visual content matters more than sub-millimeter precision, which makes AI a practical option.
Speed, Cost, and Accessibility
Manual modeling requires trained artists who can use programs such as Blender, Maya, or 3ds Max. Building one asset from the beginning involves creating the mesh structure, laying out UVs, baking normal maps, and testing the final render. This can take several hours or several days per product. Photogrammetry systems capture surfaces faster, but they need many cameras, controlled studio conditions, and heavy point-cloud processing.
AI image-to-3D tools avoid many of these steps by using existing product photos. Production can fall from days to minutes, while costs also drop. Marketing and catalog teams without specialist graphics training can create, revise, and publish models themselves.
AI Image-to-3D
Photogrammetry
Manual 3D Modeling
Time per asset
Minutes
Hours
Hours to days
Input required
Existing product photos
Physical item plus controlled capture rig
Reference images, drawings, or CAD
Skill needed
None beyond a browser
Photography and processing knowledge
Trained 3D artist
Typical accuracy
Good for visual commerce
High on captured surfaces
Exact, to whatever spec is supplied
Cost profile
Free tier upward
Equipment and studio time
Per-hour or per-asset artist fees
Breaks down on
Glass, chrome, sheer fabric
Reflective and featureless surfaces
Nothing, but cost rises sharply
When Professional 3D Modeling Remains the Better Choice
AI image-to-3D does not fit every project. High-precision industrial products, medical equipment, architectural parts, and luxury watches still need the millimeter-level accuracy of CAD and manual 3D work. If the file will guide injection-mold production or engineering stress tests, an AI estimate is not enough.
Highly reflective luxury items, including diamond jewelry, cut crystal, and polished chrome watches, can also confuse AI systems. For expensive products with demanding visual standards, hiring a skilled 3D artist who uses accurate ray-tracing methods can still be a sound investment.
How to Choose an AI Tool for Marketplace 3D
As spatial shopping grows, more AI 3D tools are entering the market. Some are simple apps for personal experiments, while others are business platforms that connect with large company systems. The right choice depends on catalog size, sales channels, and the technical skills available inside the business.
A useful commercial tool must do more than create an interesting shape. It should produce clean files in common web formats, offer stable mesh quality, and reduce the amount of manual editing needed afterward.
Features to Compare: Formats, Editing, Texture Quality, API Access, and Pricing
When reviewing AI image-to-3D tools, compare these main features:
Export Compatibility: Can the platform export clean .GLB and .USDZ files with built-in PBR textures for web and AR use?
Mesh Optimization & Retopology: Does it reduce polygon count and create clean quad or triangle topology, or does it produce heavy and untidy geometry?
PBR Texture Quality: Does it provide separate roughness, metallic, normal, and albedo maps, or only a flat color image with the lighting already included?
Batch Processing & API Integration: Can it process files from a product information management (PIM) system through webhooks and REST APIs, or must users upload products one at a time through a dashboard?
Predictable Commercial Pricing: Does it use clear credits or fixed per-asset business plans that grow in a predictable way as the catalog expands?
Free Tools Versus Paid Production Platforms
Free, open-source, and hobbyist AI tools are useful for learning about the technology and testing small ideas. However, they may not provide the steady quality needed for a commercial store. They can create uneven meshes, leave out standard scale settings, or fail to provide key PBR material channels. This can lead to a lot of manual work in other 3D programs.
Paid production platforms are built around the needs of online sellers. They often include customer support, web-friendly polygon limits, dependable UV layouts, and automatic scale settings. For an active marketplace seller, the time saved by avoiding manual mesh cleanup can cover the cost of a business subscription.
Judged against the five criteria above, Meshy is the most practical choice for a marketplace seller digitizing a catalog: it runs entirely in the browser with no install, generates from both text prompts and product photos, accepts multiple reference images for higher geometric accuracy, exports STL, OBJ, GLB, and FBX, and offers a free tier for testing before any commitment. The accompanying 3D tool suite is also free, which removes the usual second subscription for conversion and cleanup work.
Emerging Trajectories in Generative Spatial Commerce
Beyond current catalog needs, the systems used for 3D product views are moving toward more automated production. Spatial computing hardware, WebXR standards, and neural rendering performed closer to the user are changing online stores from passive image galleries into interactive brand spaces. Some early sellers already use these digital product copies in games, virtual spaces, and interactive video ads, in addition to standard website viewers.
New 3D workflows are also starting to combine visual models with real-time physics. Soon, shoppers may be able to open hinges, watch fabric move, and feel the effect of realistic product weight in a browser instead of viewing fixed geometry alone. Sellers that build clean, scalable 3D libraries now will be ready as interactive digital shopping becomes a more common way for people to find and buy products online.
FAQ: AI Image-to-3D for Marketplace Sellers
How many photos does an AI tool need to build a usable model?
One will produce something, but several produce something better. Multi-image input gives the reconstruction real data for surfaces it would otherwise have to guess, which matters most on asymmetric products. A standard catalog shoot with front, back, and two side angles is usually enough.
Which file format should a marketplace listing use?
Export requirements depend on the destination: GLB is commonly used for web-based 3D, USDZ supports Apple Quick Look AR experiences, and STL or OBJ may be appropriate for static geometry or print workflows. Confirm the marketplace’s current file, texture, polygon, and licensing requirements before export.
Do AI-generated models work for AR previews at true scale?
Only if the file carries correct real-world scale data. Check this before publishing: an AR viewer with no scale metadata will show a 12-inch vase at whatever size it guesses, which undermines the exact uncertainty the model was meant to remove.
Can an AI-generated model be 3D printed directly?
Sometimes, but run it through a validation step first. Printing exposes problems a web viewer hides — walls thinner than the nozzle, non-manifold edges, and meshes that are not watertight. Repair the STL before slicing rather than after a failed print.
What does this cost to try?
Very little. Browser-based generators with free tiers let a seller convert an existing product photo and inspect the result without a subscription, a workstation, or a developer. The realistic first cost is an hour of someone’s time on a single SKU.
The Competition Bureau says it has launched an investigation into the use of minimum advertised pricing policies in the grocery sector, adding that it is concerned that these policies are restricting competition, and keeping lower prices out of reach for Canadians.
“Every week, Canadians use grocery flyers, apps and online promotions to find deals. But Canadians would be surprised to learn that stores aren’t always allowed to advertise their lowest prices,” said the Bureau.
“These policies, which can be imposed by suppliers or negotiated between suppliers and retailers, set the lowest price at which a retailer can advertise a product. In industries like retail grocery, where a few large companies dominate the retail landscape, these policies can make it harder for retailers, including discount grocers, to offer lower prices and compete for customers.”
“Canadians expect grocery stores to be able to advertise their best deals. We’re concerned that policies that prevent this make it harder for grocers to compete, and for consumers to access lower prices. At a time when food affordability remains an important concern for Canadians, we want to hear about how these policies are affecting grocery prices and consumer choice,” said Jeanne Pratt, Interim Commissioner of Competition.
The Bureau said minimum advertised pricing policies can prevent retailers from advertising lower prices, even when they are prepared to offer those prices in-store. Some retailers may remove in-store discounts entirely if they cannot advertise lower prices under these policies.
The Bureau said it is examining whether these policies make it harder for Canadians to find deals, reduce price competition, create barriers for discount and new grocers, and make it easier for grocers to coordinate the prices they charge.
The Bureau’s Retail Grocery Market Study found that greater competition in retail grocery would help lower prices and deliver more choice and innovation for Canadians.
“This investigation matters because Canadians rely on flyers and apps to stretch their grocery budgets. The Bureau needs to find out whether pricing rules are keeping real discounts out of sight.”
Dr. Sylvain CharleboisBruce Winder
Retail analyst Bruce Winder said he welcomes the Bureau’s review of minimum advertised pricing in the Canadian grocery sector.
“For far too long large, global CPG companies have dictated what Canadian grocers can sell their products for,” he said.
“I prefer to see a market based approach that allows grocers to sell all products based on consumer demand and retail focused strategies without penalty. Consumers win without these minimum advertised price policies.”
Toronto-based Slate Grocery REIT, an owner and operator of U.S. grocery-anchored real estate, announced Monday that it has entered into a definitive arrangement agreement to be purchased by a joint venture between Brixmor Property Group Inc. and affiliates of Everview Partners, L.P. for an all-cash transaction of US $13 per unit representing a total enterprise value of about US $2.3 billion.
“The Consideration represents a premium of approximately 13% to the closing price of the Units on May 21, 2026, the last trading day prior to the public announcement of the strategic review process, and a premium of approximately 20% to the closing price of the Units on September 23, 2026, the last trading day prior to the REIT’s announcement of the suspension of distributions,” explained a news release, adding that the transaction is the culmination of the strategic review process previously announced by the REIT on May 22.
“Following a comprehensive strategic review process, including a competitive auction process, the Special Committee unanimously concluded that this transaction represents the best available outcome for the REIT and its Unitholders. The Transaction provides Unitholders with immediate liquidity and certainty of value at an attractive all-cash price, and is the culmination of a competitive process focused on maximizing value for all Unitholders. This outcome reflects strong institutional conviction in grocery-anchored real estate. We’re confident Brixmor and Everview’s combined resources and commitment to this sector position this portfolio well for its next chapter,” said Marc Rouleau, Chair of the Special Committee of the REIT.
Photo: Slate
“This outcome validates what we have long believed: grocery-anchored essential real estate is a high-quality, in-demand asset class, and active in-house management creates measurable value for investors. The Special Committee ran a rigorous process and Slate Asset Management, as external manager of the REIT and the REIT’s largest investor, is fully supportive of the outcome. We are proud of the institutional caliber portfolio our team built and managed, and we are immediately focused on what comes next: redeploying capital into grocery-anchored real estate in North America and continuing to grow Slate’s grocery platform in Europe, which is already one of the largest portfolios on the continent,” said Blair Welch, Chief Executive Officer of the REIT and Co-Founding Partner of Slate Asset Management.
The news release said the transaction is expected to close in the first quarter of 2027.
Brixmor owns and operates a national portfolio of open-air shopping centres. Brixmor’s 346 retail centers comprise approximately 63 million square feet of retail space in established trade areas.
Everview Partners, L.P. is a private investment management firm founded in 2024. Everview invests across the capital structure in real asset companies and properties and seeks to partner with talented business leaders to drive sustainable growth and profitability.
Sports Experts at CF Carrefour Laval. Image by Vince Noel
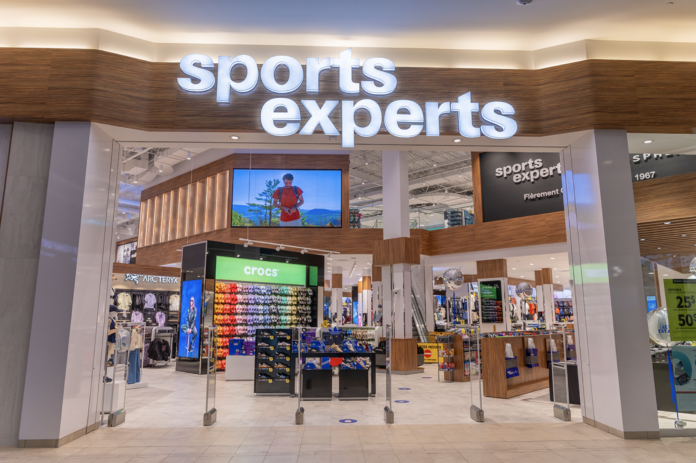
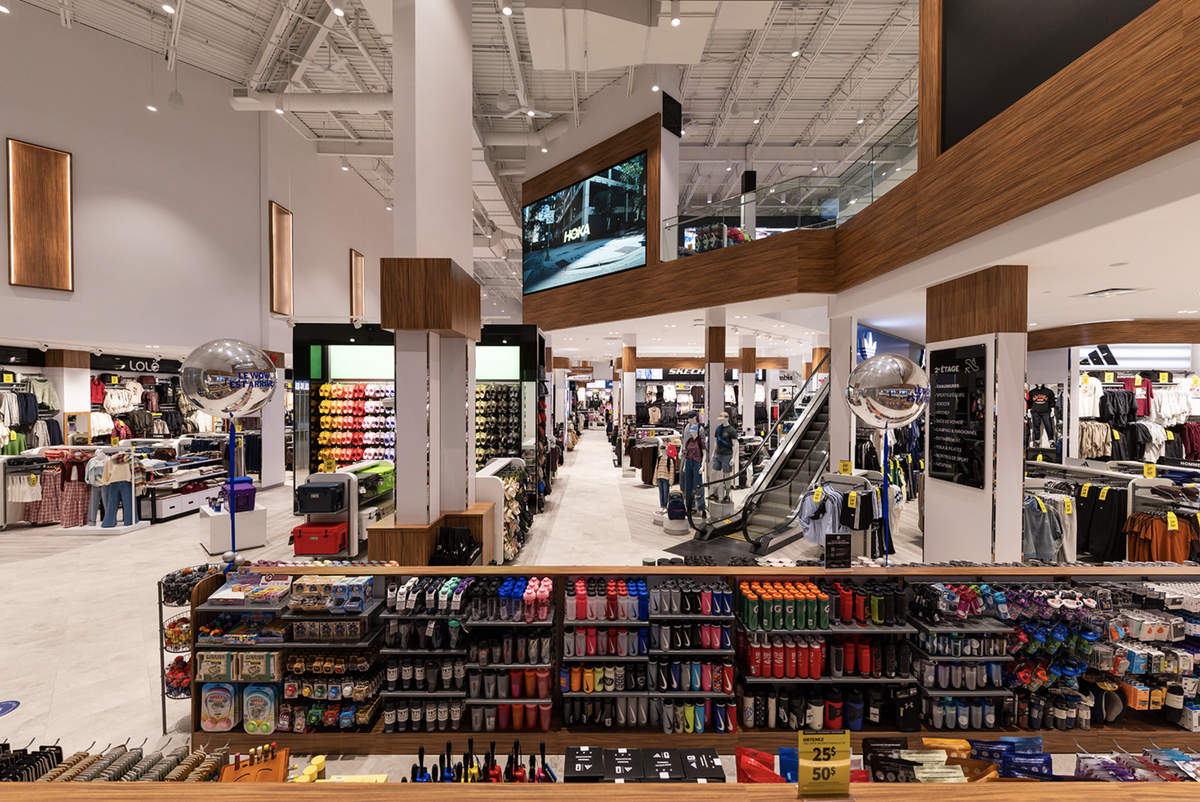
Sports Experts has completed an approximately $8-million transformation of its flagship store at CF Carrefour Laval, reworking the two-level location to carry more inventory, improve customer navigation and support growing e-commerce fulfillment from the store.
The approximately 45,000-square-foot Sports Experts/Atmosphere location is operated by Groupe Beaulieu-Angelo, a third-generation family business with five Sports Experts stores in Quebec. Carrefour Laval is by far the most important location in the portfolio, accounting for roughly 40 per cent of the group’s sales.
The store soft-opened on August 6, followed by its official grand opening on August 12. Early sales have exceeded the projections established before the renovation, and the group is already revisiting some of its purchasing, staffing and marketing assumptions for the location.
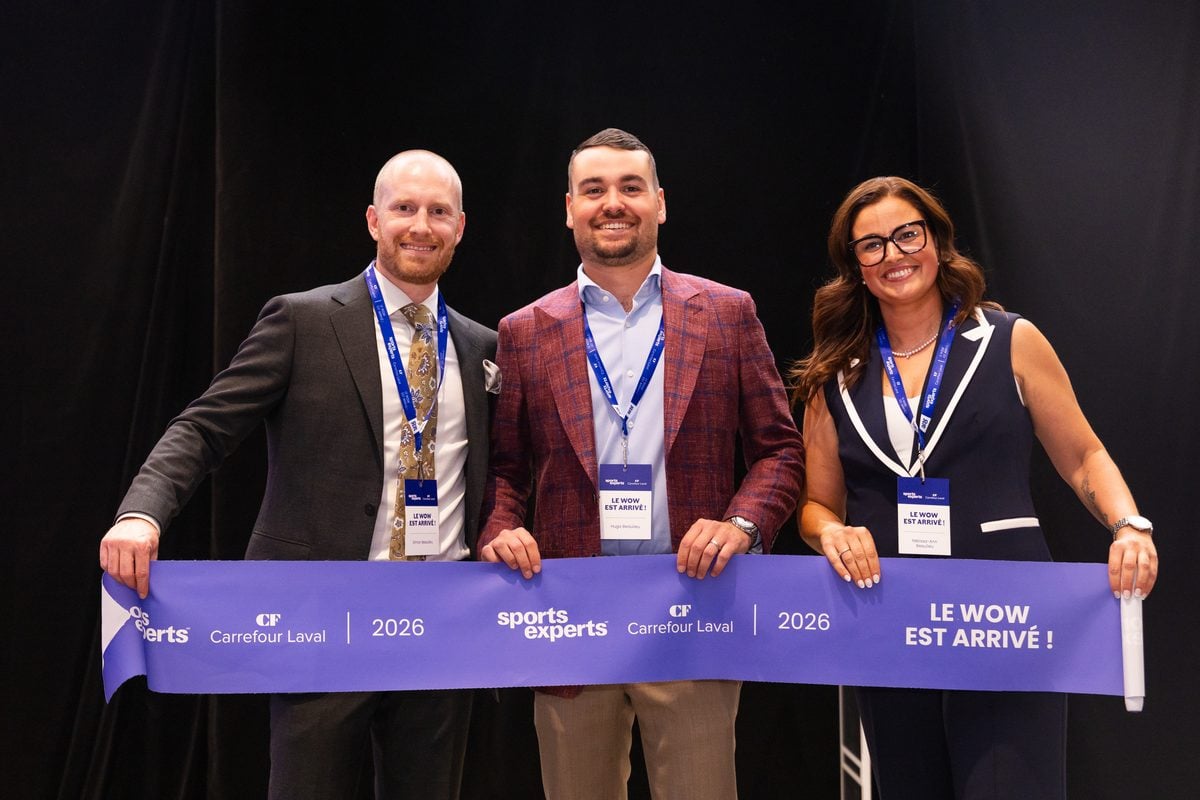
Hugo Beaulieu, centre, with Simon Beaulieu (left) and Mélissa-Ann Beaulieu (right). Image: Vince Noel
Rebuilding a Store That Wasn’t Outdated
The size of the investment is notable because the previous store was still relatively modern. Carrefour Laval underwent a major renovation in 2015 and became an important flagship for Sports Experts, introducing what was internally known as the “white” concept. The project brought Sports Experts and Atmosphere together within a cleaner environment, increased the emphasis on brand-based merchandising and incorporated technology that was considered advanced for sporting-goods retail at the time.
Retail strategist Carl Boutet, who toured the newly completed store with Beaulieu, said the previous design had aged well.
“The previous design wasn’t outdated,” Boutet told Retail Insider.
The problems were largely operational. Clothing, footwear and equipment were divided between the first and second levels, creating a customer journey that Beaulieu said could be confusing. Some customers left without realizing the retailer carried a particular product or brand because they had not reached the relevant part of the store.
Inventory requirements were also increasing, while ship-from-store placed additional pressure on back-of-house areas that had not been designed around the current volume of e-commerce activity. Beaulieu said the Sports Experts stores involved in fulfilling online orders effectively operate as a decentralized warehouse network.
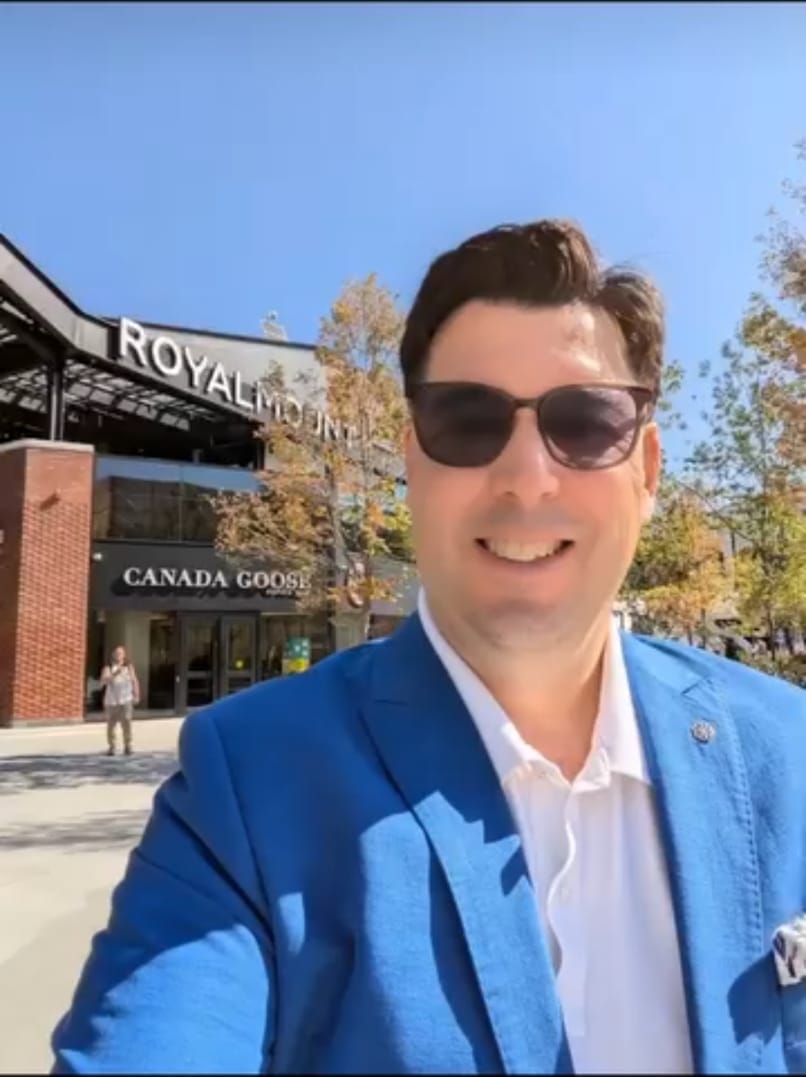
Carl Boutet at Royalmount in Montreal. Image: Carl Boutet
An Expansion From Within
Groupe Beaulieu-Angelo initially looked for ways to obtain considerably more space. Beaulieu said his ideal configuration would have been approximately 70,000 square feet on one level, but the group could not identify a viable long-term option at Carrefour Laval.
That left the family with the existing premises and the challenge of getting considerably more out of them.
The project extended the mezzanine internally by approximately 2,000 square feet, increased back-of-house capacity and reorganized the sales floor. Salem Architecture, which handled architecture and design for the project, has described the strategy as an “expansion from within.” Construction required Sports Experts to close completely for about five months and operate temporarily from the former Toys “R” Us across the street.
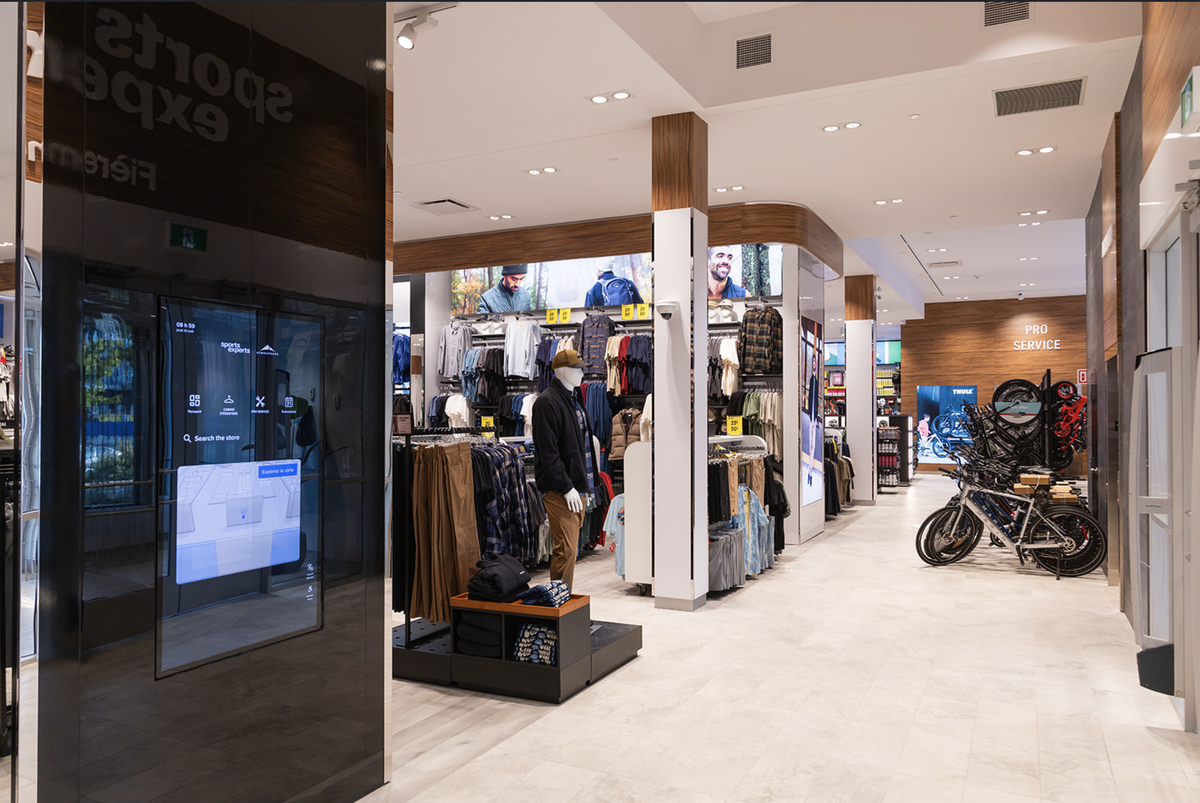
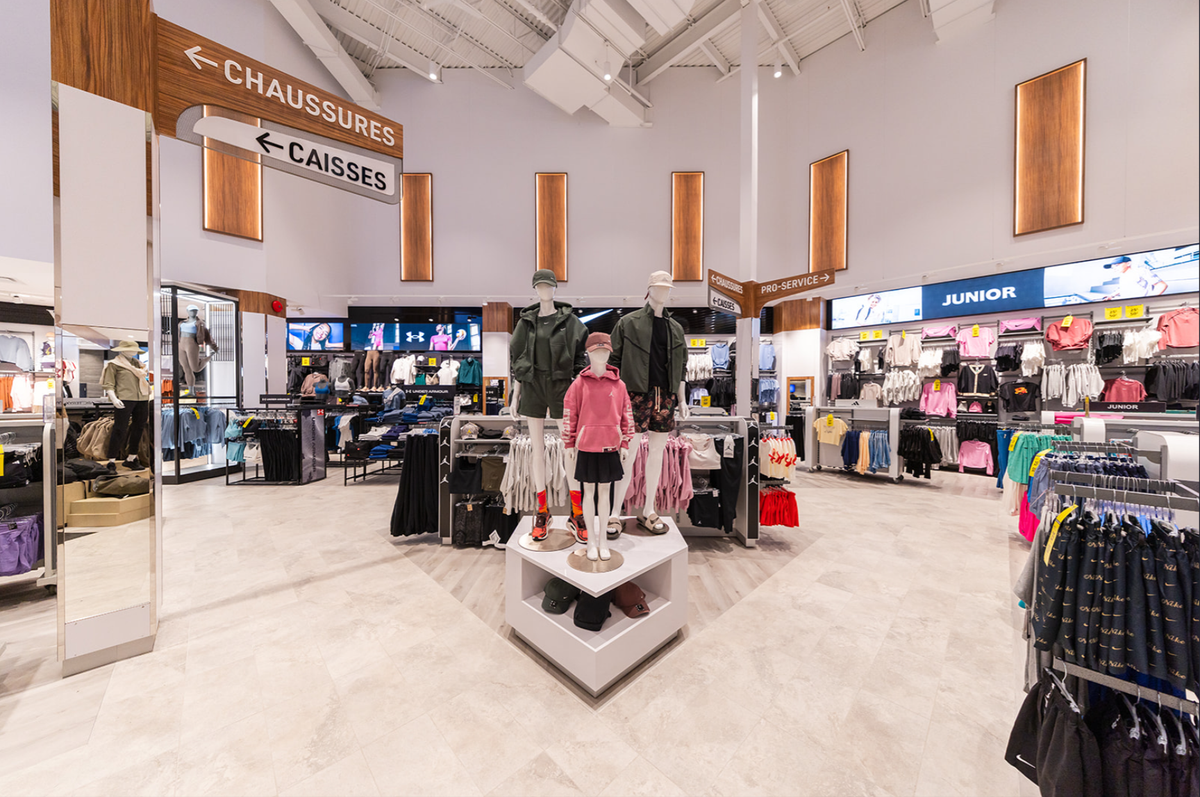
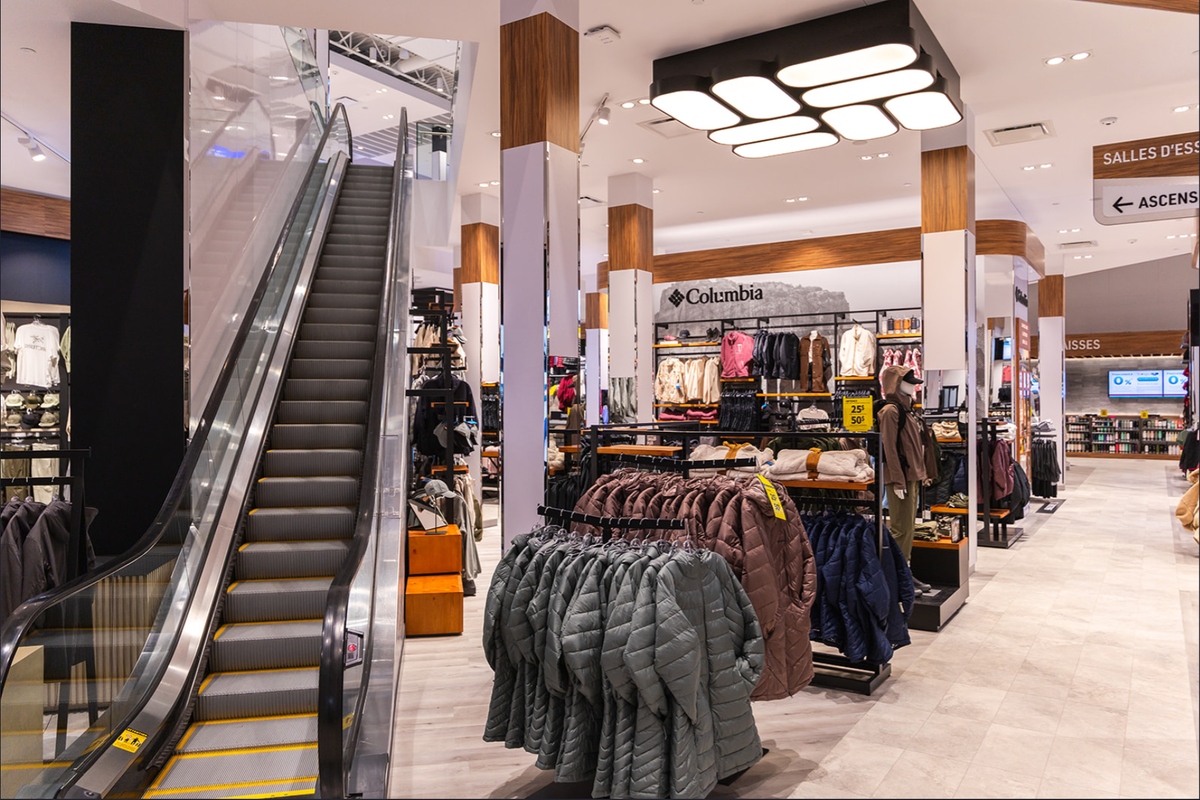
Most apparel is now concentrated on the main level, while footwear has moved upstairs alongside categories connected to running and fitness. Bikes and skis remain downstairs for convenient access to service areas, while categories including sunglasses and licensed merchandise have been repositioned.
The layout is also more direct. Angled fixtures and irregular circulation paths have given way to long sightlines across the store, which Beaulieu compared to a series of “bowling alleys” that make departments easier to find.
There is a financial rationale behind some of those changes. Beaulieu said categories can generate dramatically different margins and sales productivity, making floor-space allocation an important operating decision. The bicycle department, for example, occupies less space in the new store, yet Beaulieu said bike sales were running approximately 20 per cent higher following the reopening.
Sports Experts at CF Carrefour Laval. Image by Vince Noel
Footwear Drives the New Flagship
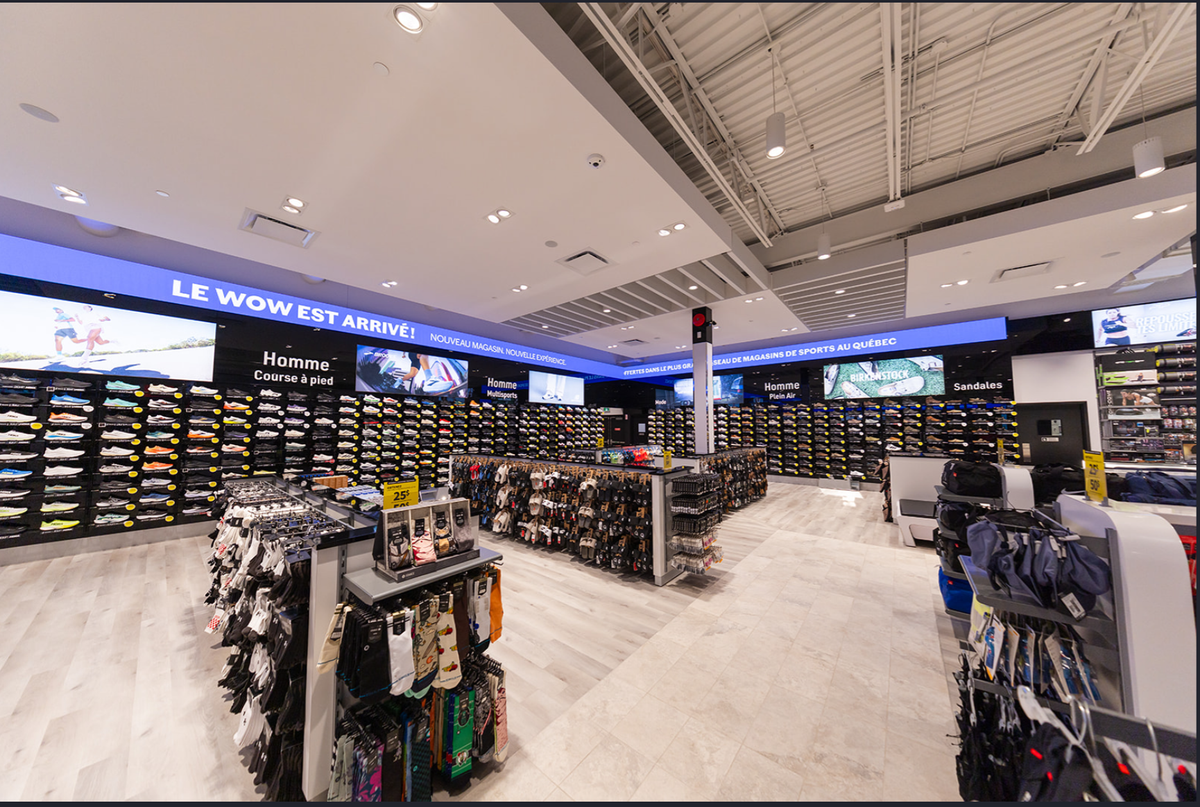
The biggest change is upstairs, where Sports Experts has approximately 1,425 to 1,450 footwear models on display. The wall has capacity for roughly 1,600 models, while the footwear stockroom can hold approximately 60,000 pairs.
Boutet described the department as the “pièce de résistance” of the store, although he was equally interested in the amount of inventory sitting behind it.
For Beaulieu, displaying a large assortment only works if the retailer has sufficient inventory across sizes to make that assortment available to customers. At a high-volume store such as Carrefour Laval, that requires considerable stock behind the sales floor.
Boutet said the strategy runs against some of the assumptions that shaped stores during the growth of e-commerce. Retailers spent years pursuing the “endless aisle,” carrying limited inventory in stores while offering customers the option to order unavailable products or sizes online. He believes customers who have already travelled to a store increasingly expect to leave with the product.
“They want to have the inventory. They want to have the exact model that they’re looking for,” Boutet said. “I want to walk away with this now.”
Footwear has also produced the strongest early results. Beaulieu said sales in the category were recently running approximately 70 per cent above previous levels.
Footwear at Sports Experts at CF Carrefour Laval. Image by Vince Noel
Technology Has to Earn Its Space
Three Aetrex 3D foot-scanning systems have been installed in the footwear department. The technology measures customers’ feet and generates footwear recommendations, helping associates work through the large assortment and giving customers more information when choosing running shoes. Boutet noted that the system is brand-agnostic, allowing recommendations to cross suppliers.
Groupe Beaulieu-Angelo’s approach to technology has changed considerably since its 2015 renovation. At the time, the store installed RFID-enabled screens in the footwear department that could tell customers whether particular sizes were available. Beaulieu said maintaining RFID tags became labour-intensive, while inventory discrepancies sometimes resulted in a screen showing merchandise that employees could not locate.
The screens also took up selling space. Beaulieu said removing 12 of them eventually created room to display another 144 footwear models.
Technology remains visible in the new store through digital displays, wayfinding tools and specialized systems such as Aetrex, but the group has become more selective about where it is used. Boutet said the digital elements are integrated without overwhelming the store.
Dressing rooms in Sports Experts at CF Carrefour Laval. Image by Vince Noel
Fitting Rooms Get an Upgrade
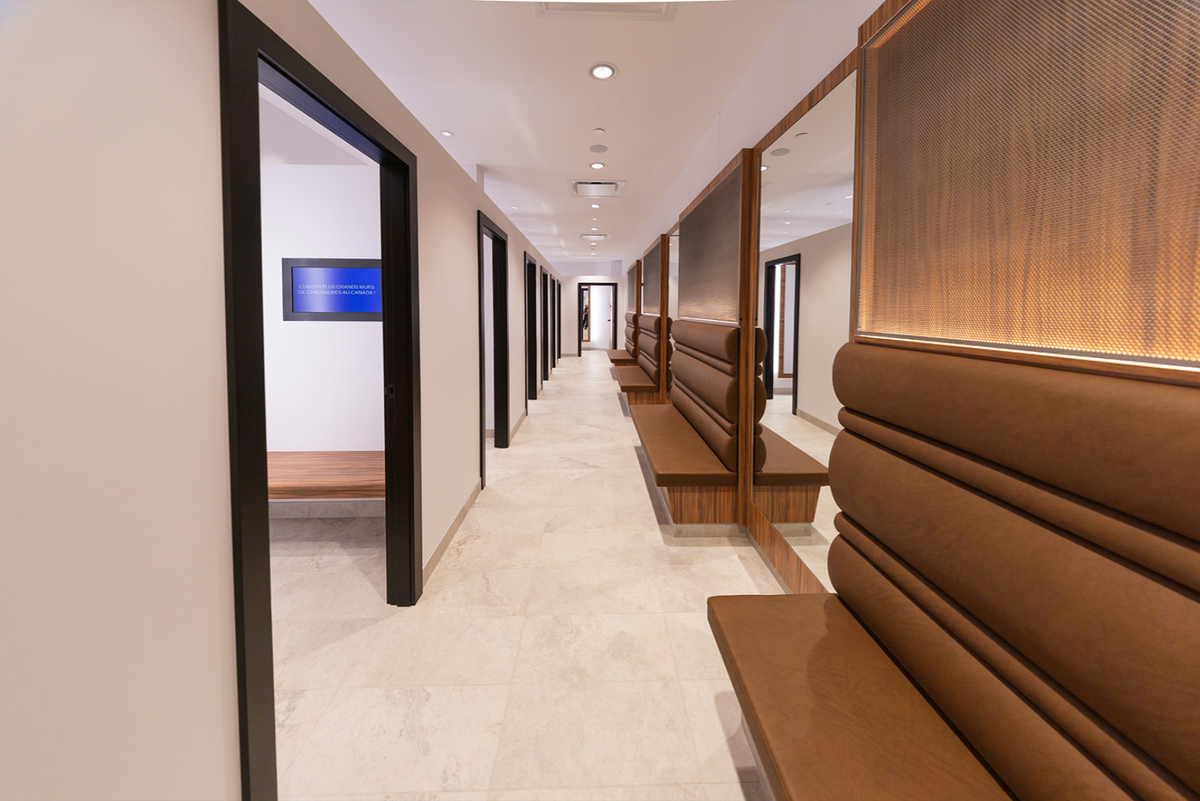
The fitting rooms include heated floors, individual digital screens and adjustable lighting that lets shoppers move between warmer and cooler colour temperatures. Beaulieu said someone buying swimwear during a Quebec winter, for example, can use warmer lighting to better approximate the environment where the product might be worn.
The screens can carry short product and brand messages. Beaulieu sees the fitting room as an important point late in the shopping journey, when the environment can affect a customer’s confidence in a purchase.
Sports Experts at CF Carrefour Laval. Image by Vince Noel
Back-of-House Becomes Part of the Retail Strategy
Some of the project’s biggest changes are largely invisible to customers. Groupe Beaulieu-Angelo substantially reconfigured storage and fulfillment areas to support greater inventory depth, easier replenishment and e-commerce fulfillment.
“The back of house for me is often more fascinating than the front of house,” Boutet said.
That infrastructure is particularly important in footwear. Displaying close to 1,500 models requires substantial stock behind the sales floor if customers are expected to find the right size, while online orders add another demand on the same inventory.
The company also upgraded employee areas, including a redesigned staff room. Boutet said he is seeing more retailers pay attention to employee spaces as they compete to attract and retain workers.
Sports Experts at CF Carrefour Laval. Image by Vince Noel
Early Results Outpace Forecasts
Groupe Beaulieu-Angelo soft-opened the rebuilt store on August 6, before launching its major reopening campaign. Beaulieu said that initial period provided particularly useful performance data because the store had not yet received significant advertising support.
During the soft opening, footwear sales were approximately 55 per cent above previous levels, clothing was up about 25 per cent and equipment was approximately 35 per cent higher, according to Beaulieu.
The official opening followed on August 12, supported by a marketing campaign in which the group invested approximately $250,000. Footwear has since emerged as the strongest category, with sales running about 70 per cent above previous levels when Beaulieu spoke with Retail Insider.
The numbers are still early, and the group does not yet know where sales will normalize once the reopening period is further behind it. The performance has been strong enough for management to revise some of its original assumptions.
“We did some predictions that are clearly wrong because we’re performing way better than we thought,” Beaulieu said.
Sports Experts at CF Carrefour Laval. Image by Vince Noel
Temporary Store Shows the Value of Mall Traffic
The five-month closure gave Groupe Beaulieu-Angelo an unusual opportunity to see what happened when Sports Experts was removed from CF Carrefour Laval.
During construction, the retailer moved into the former Toys “R” Us location roughly 100 metres across the street. The temporary store offered approximately 50,000 square feet on one level, but customer traffic fell approximately 70 per cent compared with the mall location. Sales declined by about 30 per cent, according to Beaulieu.
The gap between traffic and sales indicates that customers who deliberately sought out the temporary store were much more likely to make a purchase. It also provided a striking measure of the traffic Sports Experts gains from being inside Carrefour Laval.
CF Carrefour Laval spans approximately 1.2 million square feet and contains more than 260 stores. Cadillac Fairview has reported sales productivity of roughly $1,180 per square foot at the property, placing it among Quebec’s leading shopping destinations. New residential development is also underway adjacent to the mall, adding hundreds of rental units near the shopping centre.
Those economics help explain why Groupe Beaulieu-Angelo chose to reinvest heavily in its existing premises after exploring possibilities for a larger store.
Sports Experts at CF Carrefour Laval. Image by Vince Noel
A Third-Generation Investment
The Beaulieu family’s sporting-goods business dates to 1955, and Hugo Beaulieu’s grandfather, Gilles Beaulieu, was among the founders of Sports Experts in 1967. The current ownership group represents the third generation and operates five Sports Experts locations in Quebec.
The franchise structure is significant in the Carrefour Laval project. The approximately $8-million investment was made by the owner-operated group, putting decisions around inventory, staffing, technology and floor-space productivity directly in the hands of the family operating the stores.
Boutet said that hands-on approach was apparent during his tour with Beaulieu, particularly in his attention to conversion, sales per square foot and category performance. Those numbers are central to how the group evaluates the redesigned store and allocates space.
Physical Stores Move Back Up the Investment Agenda
Boutet sees Carrefour Laval as part of a wider period of reinvestment in physical retail. Retailers have spent years building e-commerce, digital marketing and omnichannel capabilities, while stores continue to account for the majority of transactions.
At Carrefour Laval, the $8-million investment has gone into deeper inventory, clearer navigation, improved fitting rooms, more efficient fulfillment infrastructure and technology used for specific purposes.
“This is a good story for the Beaulieu Group and what they’re doing, but it’s also indicative of broader trends that we’re seeing across retail,” Boutet said.
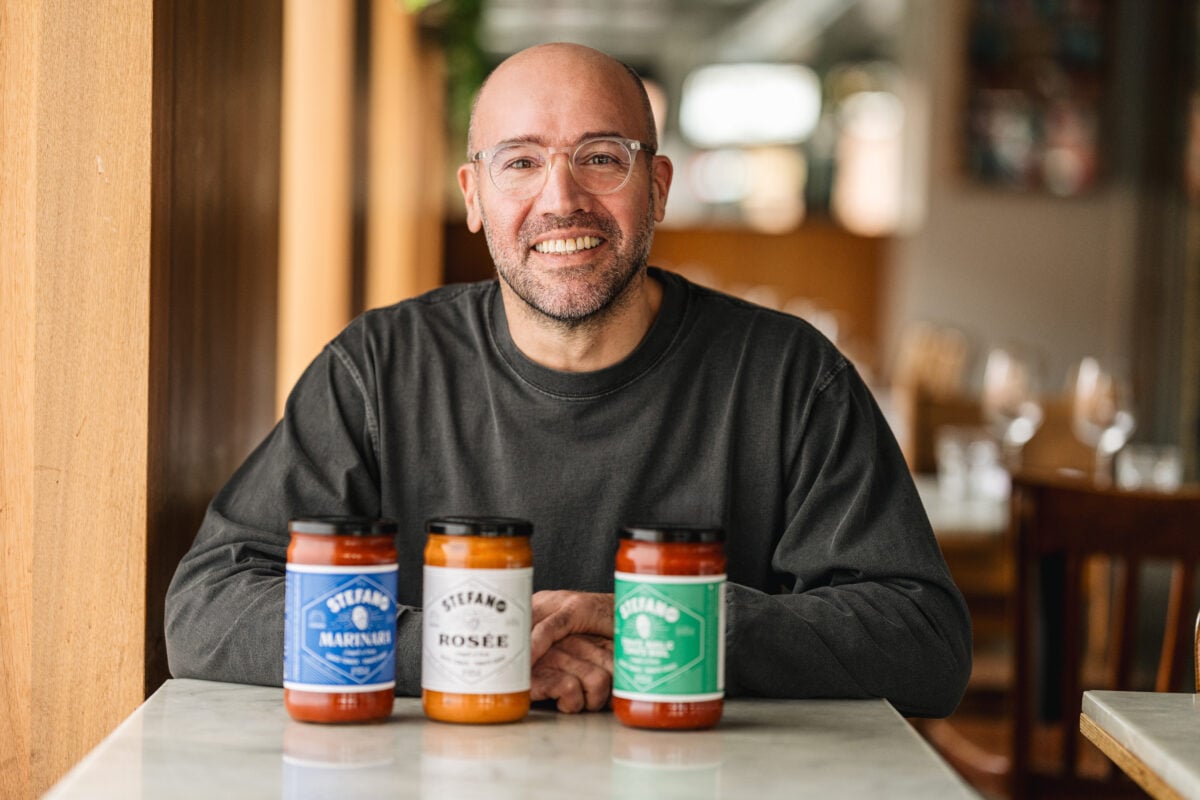
Chef, cookbook author and MasterChef judge Stefano Faita has launched a new dining concept in Toronto.
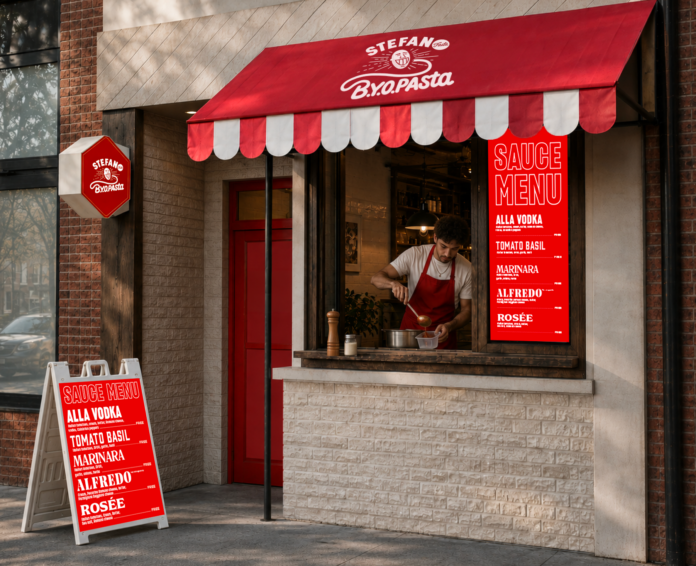
On Tuesday September 29, BYOPasta will be Toronto’s first-ever restaurant that only serves past sauces – for free.
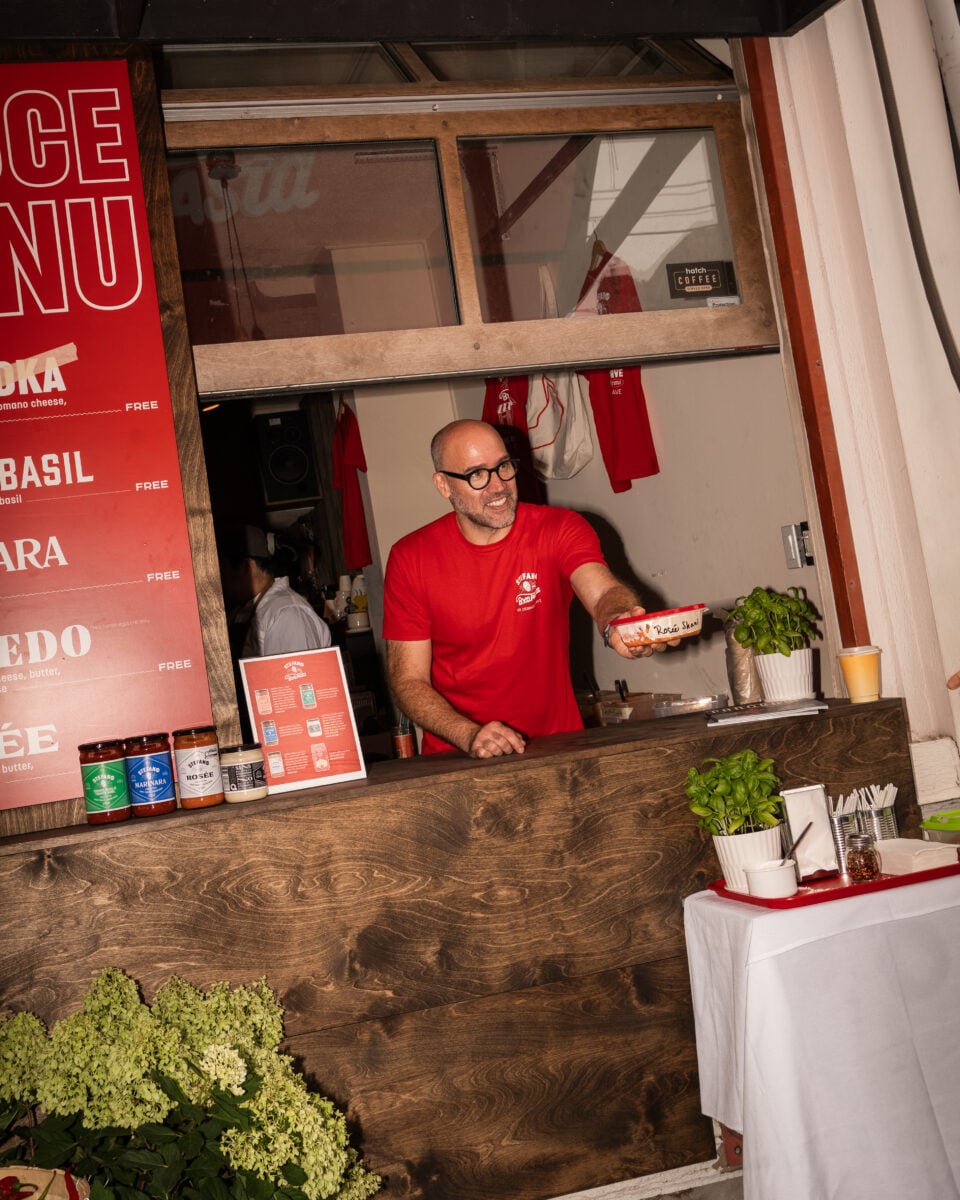
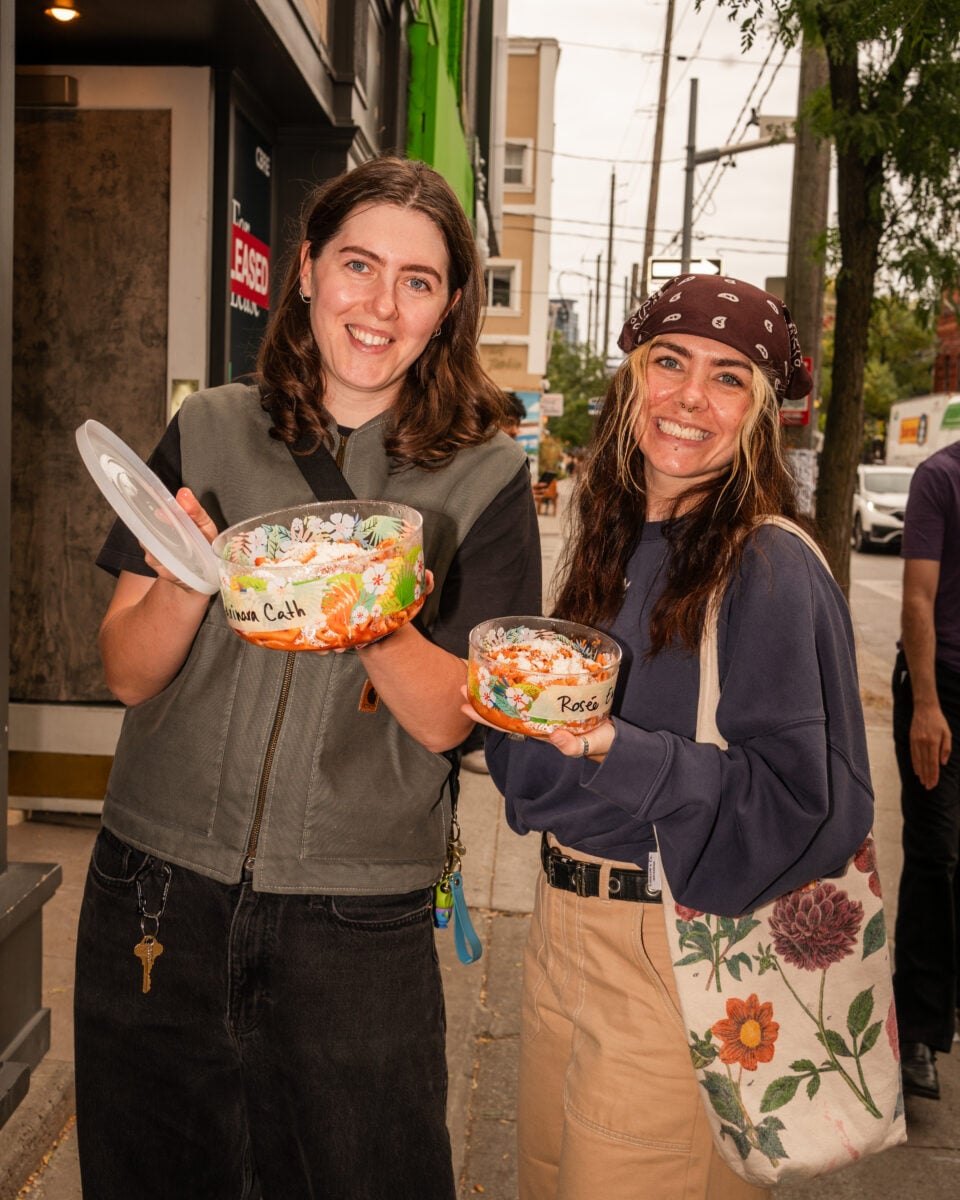
The one-day experience will take place at 135 Ossington in Trinity-Bellwoods and operate in a take-out lunch format. Guests can simply bring their own cooked pasta, pick a sauce and Faita will take care of the rest, elevating plain, neglected leftovers into a restaurant-quality dish.
The menu will feature five of his personal favourites: Alla Vodka, Tomato Basil, Marinara, Rosée and Alfredo.
Stefano Faita
“People often forget about leftover pasta sitting in their fridge, especially when it’s plain and needs a little love. So why not let a chef take care of it?” said Faita. “We want Torontonians to taste for themselves how the right sauce can turn plain leftover pasta into something much better — whether you’re at home or joining us at BYOPasta.”
The tomato sauces feature imported sun-ripened tomatoes grown in Striano, near Naples, and contain no gluten, no preservatives or added sugar.
Stefano Faita photo
BYOPasta will take place on Tuesday, September 29th from 11 AM to 4 PM at 135 Ossington. People who bring their own pasta will also receive a complimentary coupon exchangeable for a free Stefano Faita sauce at most Ontario grocery retailers, including Loblaws, Metro, Sobeys, Walmart, Longo’s, Fortinos, Farm Boy and more.
In an interview with Retail Insider, Montreal-based Faita discussed the initiative.
What prompted you to create BYOPasta, and what are you hoping to learn from turning the concept into a one-day pop-up restaurant experience?
BYOPasta really came from something that happens in every house: you make pasta for dinner and somehow you always make too much. Then it sits in the fridge and nobody really knows what to do with it.
We thought it would be fun to show people that with a really good sauce, those leftovers can become a completely different meal.
The pop-up also gives us a chance to take Stefano out of the grocery aisle and put the product directly into people’s hands in a way that feels memorable and a little unexpected. Of course, we want people to taste the sauces, but more importantly, we want them to experience what the brand is about: good food, simple and good ingredients, Italian inspiration and not taking ourselves too seriously.
For us, it’s also a chance to have some fun with the brand, see how people react to the idea and learn which sauces and flavours they gravitate toward.
BYOPasta photo
How does BYOPasta fit into your broader strategy for the Stefano Faita sauce brand and its growth in the Canadian grocery market?
BYOPasta is really about getting people to try the product. We can talk about the sauces all day, but once people taste them, they understand what we’re trying to do.
Toronto is obviously a very important market for us, so BYOPasta gives us a fun way to connect directly with consumers and hopefully get more people discovering the brand. Rather than simply telling people our sauces are good, we’re creating an experience where they can taste them, interact with the brand so they remember us the next time they’re grocery shopping.
It’s also about making sure people feel what makes us different. At the end of the day, we want Stefano Faita to become one of the go-to Italian food brands in Canada. Experiences like this help us build that connection.
Why did you choose Toronto and the Ossington neighbourhood for the launch, and what does the city’s food and retail market represent for the brand?
Toronto was an easy choice. Our sauces have been available for a couple of years here. It’s a city that really loves food where people are curious and have a real appreciation for good ingredients.
Ossington in particular felt right because it has become a destination for food and hospitality, so it felt like the right environment for something playful and unexpected like BYOPasta. We wanted this to feel like a real food experience and not just brand activation.
There’s also a growing momentum in Toronto and across the country to support Canadian-made products, and we pride ourselves in being crafted in Canada. It just felt like the perfect place to bring this experience to life. To share the Italian-inspired flavours that are at the heart of our sauces.
Stefano Faita photo
How is the sauce business performing today, and how has the brand’s distribution and retail presence evolved since you launched the sauces in 2017?
It’s been pretty incredible. When we launched the sauces back in 2017, we were a small Montreal brand trying to get onto grocery shelves. Today, we’re available across Canada at most of the major retailers, and the business continues to grow.
You can now find our sauces at retailers like Sobeys, Loblaws, Metro, Longo’s, Fortinos, Farm Boy and, more recently, Walmart. What started as a strong family business in Quebec has gradually grown into a much more than a local brand. Ontario in particular has become an important market for us.
The sauce portfolio has grown too. We started with a few core Italian classics and have continued adding flavours that give consumers more variety while still staying true to the kind of food we love to eat and cook at home.
What excites us most is that we still feel like we’re at the beginning. There are a lot of Canadians who haven’t tried our products yet, and there’s still a lot of room to grow..
For us, that’s the exciting part: the brand has come a long way over the last nine years, but there’s still so much opportunity ahead.
BYOPasta photo
What are your plans for the Stefano Faita brand beyond this one-day BYOPasta event, including potential new products, retail expansion or other restaurant and experiential concepts?
There’s a lot ahead. We’re always working on new products and looking at where the Stefano brand can go next, but we’re pretty disciplined about it. We don’t want to put the Stefano name on something just because we can. It has to make sense for the brand and, most importantly, it has to be clean quality ingredients that taste really good.
There’s still a lot of opportunity for us in Canada. We want to keep growing our presence nationally, strengthen the categories we’re already in and continue introducing Stefano to people who may not know the brand yet. At the same time, we’re also starting to look more seriously into the U.S. and what that next phase of growth could look like.
Next year is also a big one for us. We’ll be celebrating Stefano’s 10th anniversary. It’s a chance to look back at how far the brand has come, but also to think about how we want to celebrate with the people who have been part of that journey.
We definitely think you’ll see us doing more events like BYOPasta. Food is meant to be shared. Bringing people together around the table has always been at the heart of what we do. As we head into our 10th year, we want to create more moments where people can taste the food, interact with the brand, have fun and feel part of the famiglia.
For us, that’s still one of the best ways to build Stefano: get people around a table, serve them something really good and create a moment we will all remember together.