Home Blog Page 58

Groupe Marcelle targets U.S. beauty market with TikTok Shop launch

Source: Groupe Marcelle

Groupe Marcelle Inc. has expanded into the U.S. market with a dedicated TikTok presence and an online TikTok Shop, giving the Montreal-based beauty company a direct-to-consumer channel as it seeks to grow the Marcelle brand beyond Canada.

The company, which describes itself as Canada’s largest beauty manufacturer, launched its U.S. TikTok account, @marcelle.us, in May and has begun offering a curated selection of Marcelle skincare products through TikTok Shop.

The expansion is part of a broader strategy to develop Groupe Marcelle’s brands into what the company calls a modern beauty house, with Marcelle positioned as a key growth driver.

Direct-to-consumer strategy

The TikTok launch represents a shift toward platform-based product discovery and purchasing for the company, which said the new channel is intended to connect consumers directly with its products.

The company said the U.S. expansion is focused initially on Marcelle, whose skincare products are hypoallergenic and dermatologist-tested. Groupe Marcelle said its experience in sensitive skincare in Canada is intended to support the brand’s entry into the U.S. market.

“The launch of our U.S. TikTok Shop is a defining moment in our history that reflects our commitment to innovation and creativity as we continue evolving how we connect with consumers in a digital-first environment,” said David Cape, president of Groupe Marcelle.

“As beauty commerce continues to shift toward discovery-led models, we are expanding how we engage consumers through new digital touchpoints, while continuing to build on the strength of our retail partnerships. We are leveraging our legacy of scientific rigor and vertical integration to bring our high-performance skincare expertise to U.S. consumers. We are proud to build on the strong foundation we have established in Canada.”
Montreal manufacturing pipeline

The U.S. push is being supported by a cross-functional team within Groupe Marcelle and a partnership with U.S.-based SuperOrdinary, which is a social-commerce infrastructure platform supporting more than 300 global brands across TikTok, Amazon and other social channels.

Julian Reis, founder and CEO of SuperOrdinary, said the partnership gives Groupe Marcelle an opportunity to reach consumers outside its established Canadian market through creator-led commerce.

“For decades, Groupe Marcelle has built products that Canadians trust. Now, the creator-led commerce gives the company an opportunity to introduce that expertise to consumers far beyond its traditional footprint,” said Reis. “The distance between discovery and purchase has never been shorter, and Groupe Marcelle is entering the U.S. market at a moment when consumers can learn about a product, hear from creators, and buy it in just a few taps.”

Groupe Marcelle said products sold through TikTok Shop will be supported by its Montreal-based manufacturing and innovation operations.

The company owns every stage of its production, which it said allows it to respond to changes in consumer trends.

75-year Canadian history

The U.S. expansion builds on Groupe Marcelle’s 75-year history in Canada and its research, development and manufacturing operations in Montreal.

The company has more than 350 employees working across research, development, production and marketing. Its portfolio includes more than 1,600 products under the Marcelle, Lise Watier, Annabelle and CW Beggs and Sons brands.

Those products are distributed through more than 3,500 stores across Canada, according to the company.

Marcelle sells cosmetics and skincare products, while Lise Watier offers cosmetics, skincare and fragrances. Annabelle Cosmetics focuses on cosmetics, and CW Beggs and Sons offers men’s skincare products.

The company said its U.S. TikTok operation is intended to build on that Canadian base while creating a new digital sales channel in the U.S. market.

U.S. expansion

The TikTok Shop launch follows the company’s broader move into the U.S. and gives Groupe Marcelle another route to reach consumers alongside its existing retail partnerships.

The company said its strategy combines its manufacturing and formulation capabilities in Montreal with social-commerce tools aimed at bringing consumers from product discovery to purchase through TikTok.

The partnership with SuperOrdinary is part of that effort. The company says SuperOrdinary works with more than 300 global brands and has a network of more than three million creators and affiliates worldwide.

For Groupe Marcelle, the U.S. launch marks an expansion of its existing Canadian business model into a new market, with Marcelle serving as the lead brand for the company’s social-commerce strategy.

In an interview with Retail Insider, Cape talks about the initiative.
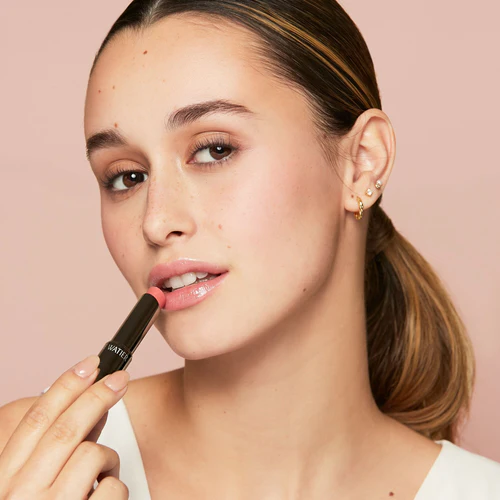
Source- Groupe Marcelle

Question: Why did Groupe Marcelle choose to enter the U.S. market through TikTok Shop and social commerce first, rather than pursuing a traditional retail rollout with major chains?

Answer: Entering the U.S. is a defining moment for Groupe Marcelle and we wanted to be deliberate in how we approached it. We chose TikTok Shop because that is where beauty is increasingly being discovered, discussed and purchased by consumers today.

It also gives us a direct connection to U.S. consumers as we introduce the Marcelle brand in the market. That kind of real-time engagement is incredibly valuable as we build awareness, understand what resonates and grow in a thoughtful, measured way.

We see social commerce as an important part of how consumers shop today, and it’s a natural step as we establish Marcelle in the U.S.

Q: What are your sales and growth expectations for the U.S. market over the next two to three years, and how will you measure whether this strategy has been successful?

A: We’re taking a long-term view of the U.S. market. Rather than focusing on a specific sales target over the next two or three years, our priority is building the brand and creating a strong foundation for sustainable growth.

Of course, we’ll measure business performance but we’ll also be looking at consumer engagement, repeat purchases, brand awareness and how Marcelle is resonating with U.S. consumers. One of the advantages of a direct-to-consumer model is that it gives us valuable insights that help inform how we continue to grow in the market.

Ultimately, success for us will be measured by our ability to build a sustainable business in the U.S. while staying true to what has made Marcelle successful for the past 75 years.

Q: Marcelle has built a strong reputation in Canada for sensitive skin products. How do you plan to differentiate the brand in the highly competitive U.S. beauty market, where consumers already have many established skincare options?

A: The U.S. is certainly a competitive market but we also see a growing demand for skincare that delivers real performance without compromising on safety or tolerance. That’s where Marcelle has a genuine point of difference.

We have built our reputation by developing dermatologist-tested, hypoallergenic skincare backed by decades of research and formulation expertise. That’s not a positioning we’ve created for the U.S. It’s the foundation of who we are.

We also think consumers are looking for brands that are authentic and credible. As a proudly Canadian heritage brand, we are entering the market with a clear sense of who we are and what we stand for.

Q: Your products are manufactured in Montreal and you emphasize vertical integration. How does owning your R&D and manufacturing provide a competitive advantage in responding to beauty trends and consumer demand?

A: Owning our R&D, manufacturing and commercialization gives us a level of agility that is increasingly important in today’s beauty industry.

Because our teams work closely together, we’re able to move from product development to production more efficiently, respond more quickly to evolving consumer preferences and maintain rigorous quality standards throughout the process.

That integrated model has been one of our strengths for decades. It allows us to innovate with confidence while remaining focused on what matters most, developing high-quality products that meet consumers’ needs. As we expand internationally, having those capabilities in-house gives us a strong foundation to continue growing while staying true to the standards our customers expect

Q: Do you see this as the first step toward broader U.S. retail distribution, or is your long-term strategy to remain primarily focused on direct-to-consumer and social commerce channels?

A: Our focus today is on establishing the Marcelle brand with U.S. consumers through social commerce. It’s an important step in our broader growth strategy and allows us to build direct relationships with consumers as we enter the market.

Retail remains an important channel, and we’ll continue to evaluate future opportunities as the brand grows.
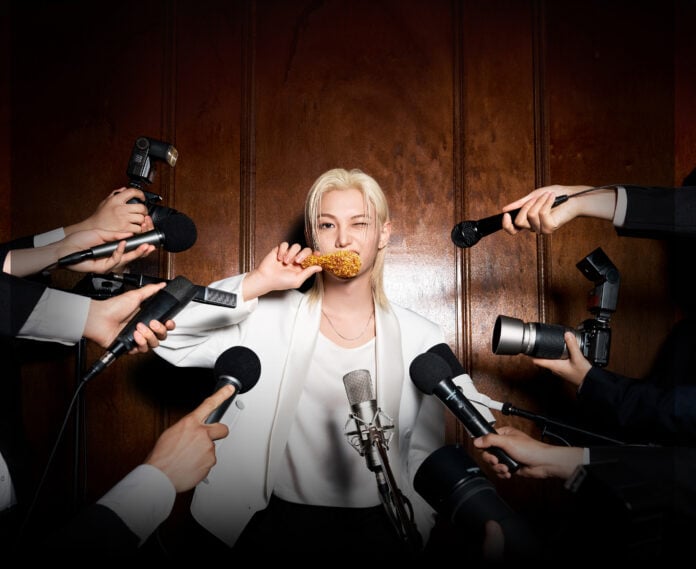
bb.q Chicken launches Felix-backed menu item across Canada

Canadian locations of bb.q Chicken are launching a new menu item tied to the chain’s partnership with Felix, a member of K-pop group Stray Kids, as the Korean fried-chicken brand seeks to build on its presence in Canada.

Feel Crunch Chicken is available at all bb.q Chicken locations across Canada. The launch follows a soft rollout at select restaurants that began July 31.

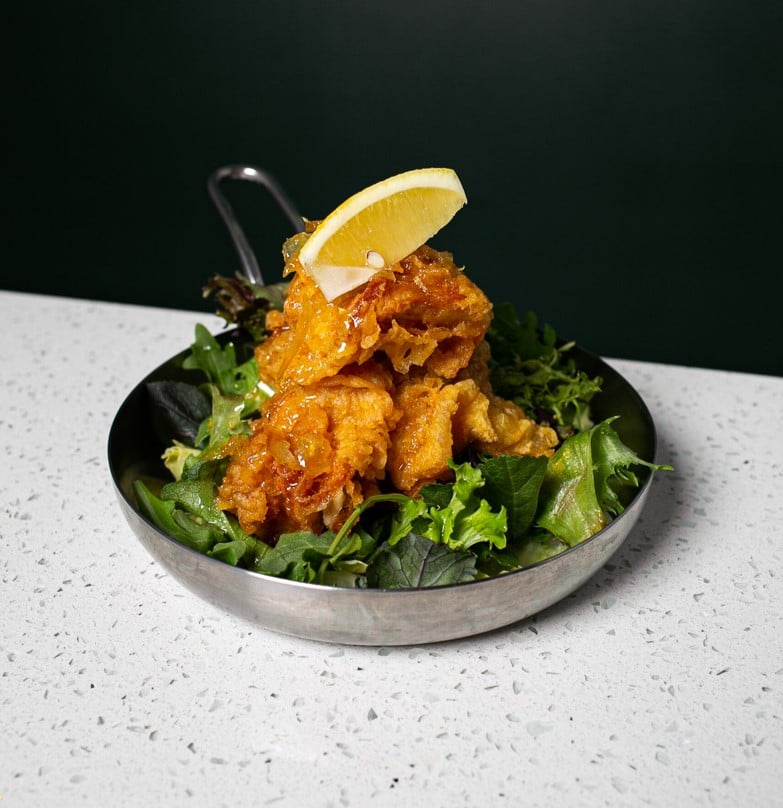
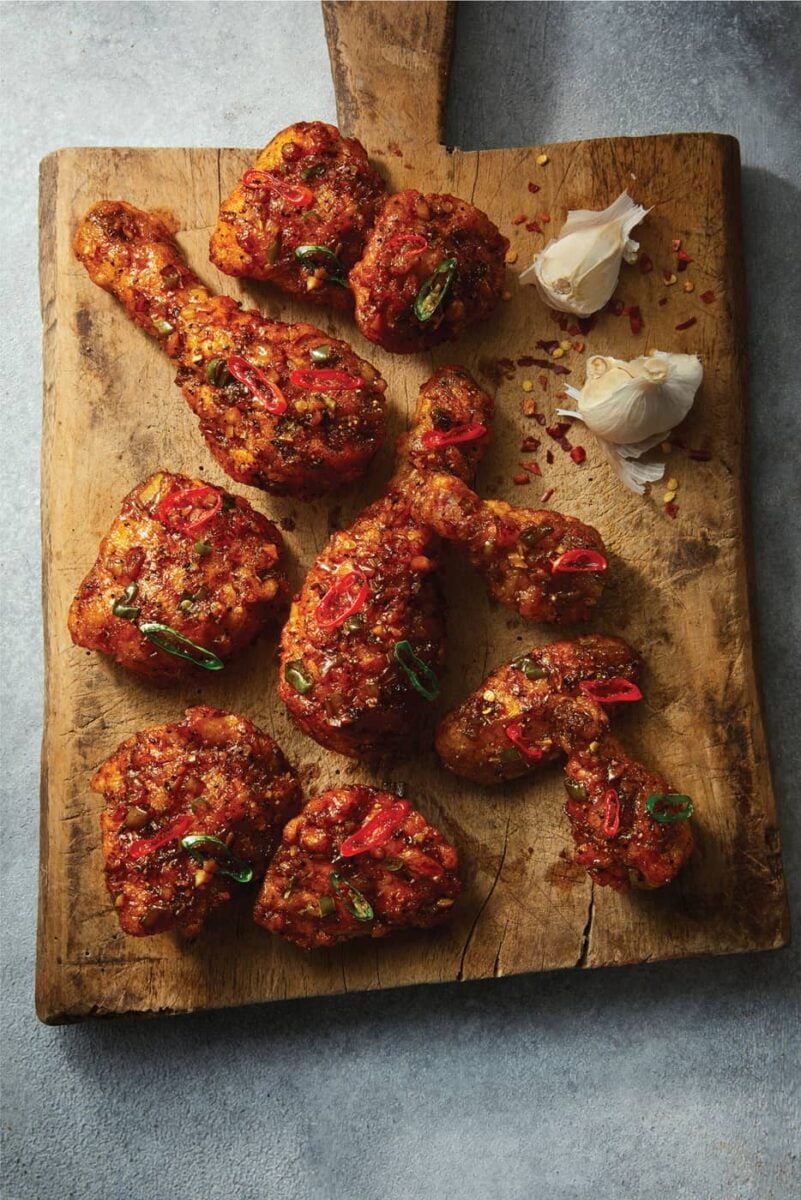
The menu item is made with a sweet-and-savory caramelized onion sauce and topped with crunchy flakes. The company said the flavour was selected in connection with Felix, who will also serve as the face of the brand in Canada as part of the partnership.

bb.q Chicken photo
bb.q Chicken photo

Nationwide launch

The launch gives bb.q Chicken a new product tied directly to its marketing partnership with the K-pop performer. The company said additional campaigns featuring Felix are planned both online and in its restaurants.

“As global interest in Korean culture continues to grow beyond streaming screens and onto fast casual menus across the country, bb.q Chicken wanted to find an opportunity to celebrate its authentic space in both,” said Lim Kim, Marketing Manager at bb.q Chicken Canada. “Felix has a genuine obsession with bb.q Chicken which makes him the perfect fit for this brand ambassador role.”

The company said Felix has been a longtime fan of its menu and has previously praised its Crunch Butter Chicken and Jamaica Sotteok Manna Chicken.

“Feel Crunch was actually handpicked by Felix himself, and it highlights different elements of his favorite bb.q Chicken flavors. We’re excited for his fans, and other bb.q Chicken fans in Canada, to taste it for themselves.”

The chain said the new menu item is intended to bring Korean flavours to Canadian customers while connecting its restaurant offering with the broader popularity of Korean culture.

Partnership to continue

The Felix partnership extends beyond the Feel Crunch Chicken launch. According to bb.q Chicken, the performer will remain the face of the brand, with further campaigns planned for Canadian customers in digital and in-store channels.

The company did not provide financial terms for the partnership or the launch in the release.

Canadian expansion

bb.q Chicken was established in 1995 as part of parent company Genesis BBQ. The company says it operates with a focus on premium chicken and Korean food offerings and has been expanding its Canadian footprint.

The chain describes bb.q, pronounced “bee-bee-que,” as standing for Best of the Best Quality. Its Canadian operations include fried chicken and other Korean food offerings, with the company continuing to expand into new communities.

The Feel Crunch Chicken launch is the latest product rollout accompanying that expansion, with the new item now available across the chain’s Canadian locations.

More from Retail Insider:

Canadian small-business sales fall for third straight quarter: Xero

RDNE Stock project photo

Canadian small-business sales fell 0.6 per cent from a year earlier in the second quarter, marking the third consecutive quarterly decline as elevated payment times and higher gasoline prices continued to pressure spending and cash flow, according to data released by Xero.

The quarterly Xero Small Business Insights report, based on aggregated and anonymized data from 12,000 Canadian businesses using the platform, found sales were lower than a year earlier for eight of the past 12 months.

The data points to continued pressure on small businesses as they contend with weaker sales and longer waits for invoices to be paid.

“Canadian small businesses are likely to face continued economic uncertainty through the rest of 2026, with many business owners navigating ongoing cost pressures and cautious consumer spending” said Ashalee Mohamed, Country Manager for Canada at Xero. “While some sectors may benefit from broader market trends, many small businesses will continue to focus on protecting cash flow, managing expenses and adapting to changing customer demand. Maintaining visibility into business performance and planning ahead will be key to helping small businesses navigate the coming months.”

Sales remain below year-ago levels

Sales declined 2.7 per cent year over year in April and three per cent in May before rising 3.8 per cent in June, according to the report.

Xero said the monthly results show how gasoline prices affected household budgets and small-business sales during the quarter. Gasoline prices fell below $1.70 a litre in June, which the company said freed up some capacity for consumer spending.

However, Xero cautioned that the June result could be revised lower because its late-reporting adjustment has been over-adjusting in recent months.

Sales were down 3.0 per cent year over year in the March quarter and 1.3 per cent in the December quarter.

“Overall, the biggest positive from this data is that performance didn’t get worse, but it is not improving much either,” said Louise Southall, Economist at Xero. “The continued geo-political conflicts and uncertainty have made conditions harder for Canadian small businesses, building on the impact of US trade policy since April 2025. Gasoline prices peaked in May, and while various ceasefire agreements have offered brief relief, none have been able to hold for more than a few weeks. The OECD (Organisation for Economic Co-operation and Development) expects the Canadian economy to grow just 1.2% in 2026, slower than the 1.7% recorded in 2025.”

Businesses continue to wait for payment

Canadian small businesses were paid an average of 11.3 days late during the June quarter, little changed from 11.4 days in the March quarter but above the 10.5-day average recorded in 2025.

The average time to be paid — measured from when an invoice was issued until it was paid — was 29.0 days in the June quarter. That compared with 29.2 days in the March quarter and 27.1 days in 2025.

The figures indicate payment times remained elevated even as the quarterly decline in sales moderated from the previous quarter.

Amina Filkins photo
Amina Filkins photo

Regional results

The latest report also expands Xero’s provincial data to include the Maritime Provinces, combining New Brunswick, Nova Scotia and Prince Edward Island.

Alberta recorded the strongest sales performance among the provinces tracked, with sales up 1.0 per cent from a year earlier. Xero said the province was a regional beneficiary of higher global oil prices.

Sales in the Maritime Provinces were 0.2 per cent higher than in the June quarter of the previous year.

Ontario sales fell 0.3 per cent year over year, while British Columbia sales declined 1.7 per cent.

British Columbia recorded the shortest average time to be paid among the provinces, at 25.7 days, an improvement from 26.9 days in the March quarter.

The average time to be paid was 28.4 days in Alberta, 30.0 days in Ontario and 31.8 days in the Maritime Provinces.

More from Retail Insider:

CRAFT Beer Market to open third Calgary location at Shepard Flats

CRAFT Beer Market photo

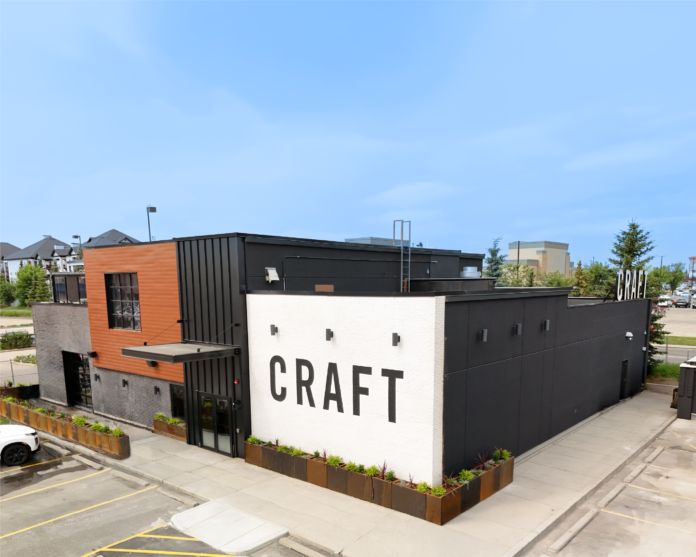
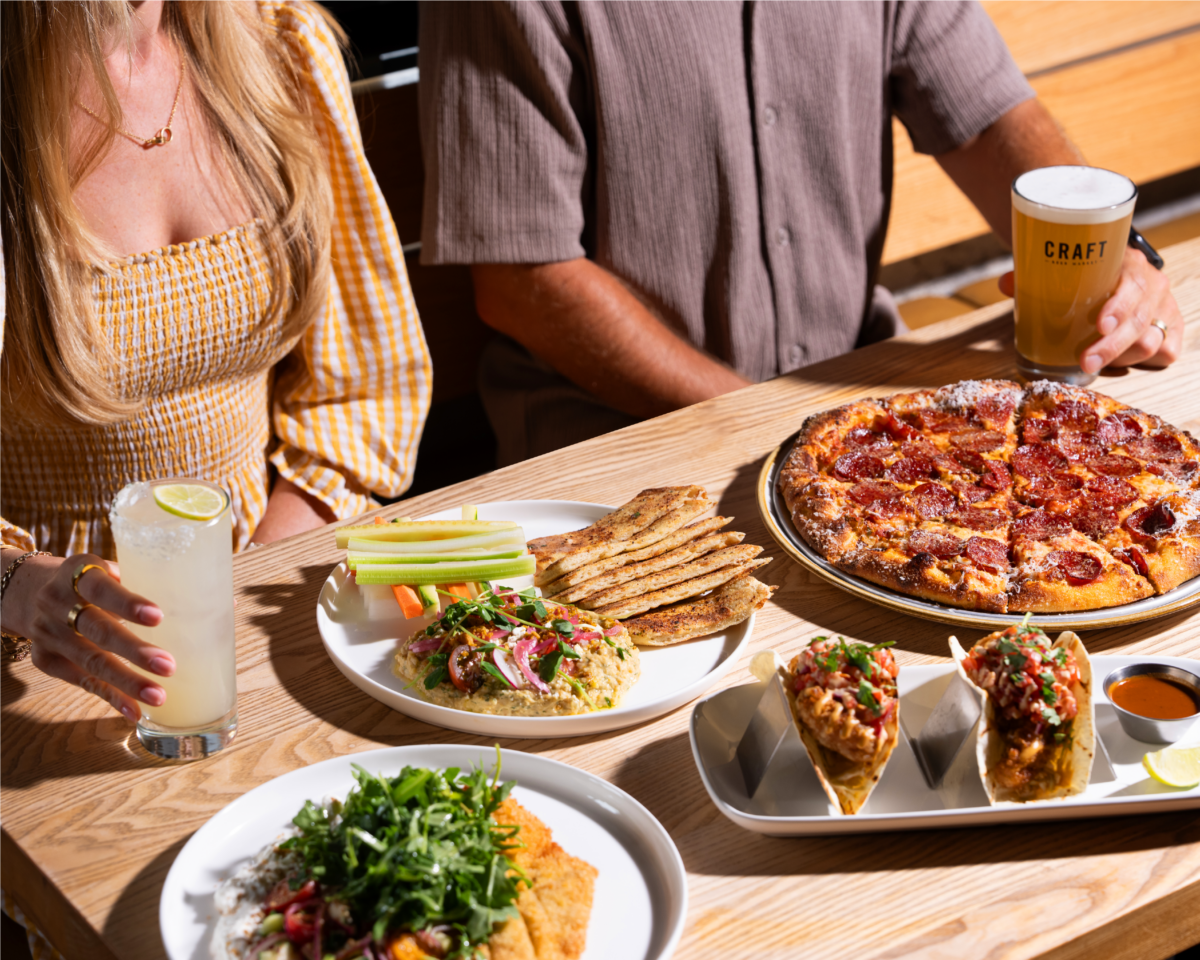
CRAFT Beer Market will open its third Calgary restaurant later this month as the hospitality company expands in the city where it launched in 2011.

The new location at Shepard Flats shopping centre, at 5155 130 Avenue SE, Unit 100, is scheduled to open to the public Aug. 27. Reservations are now open, with the first 250 reservations booked for Aug. 27 or later set to receive a $20 CRAFT On Us Card during their visit.

New southeast Calgary location

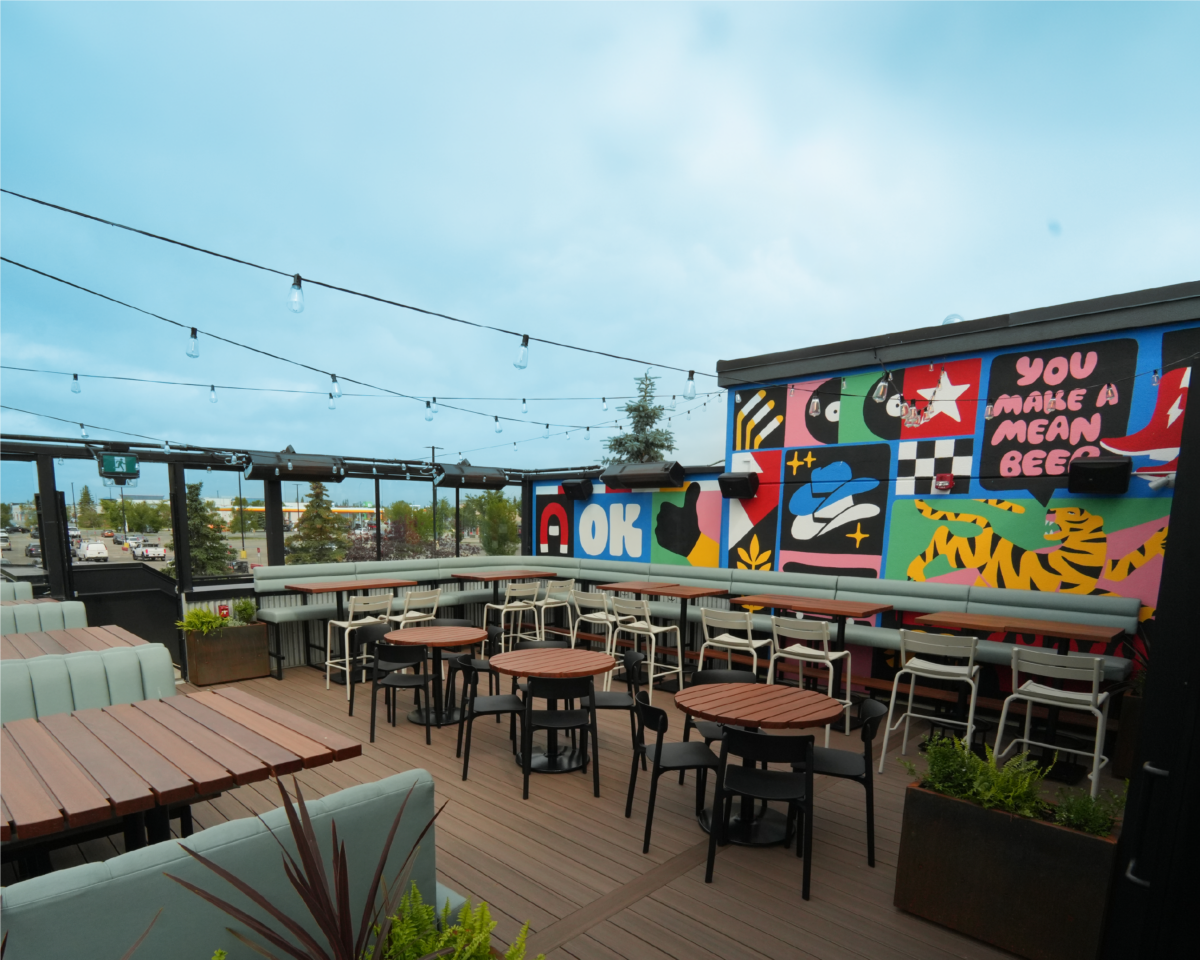
The restaurant will offer craft beer, cocktails and wine alongside a menu featuring a range of food options. It will also include rooftop and outdoor patios, including a rooftop patio designed for year-round seating.

Founder PJ L’Heureux said the company views the new location as an opportunity to expand its presence in southeast Calgary.

“We are incredibly excited to open our newest CRAFT location and become part of the southeast Calgary community,” said L’Heureux. “Calgary is where CRAFT began, and we are grateful for the opportunity to continue growing in the city we call home. We can’t wait to welcome guests through our doors and celebrate this next chapter with the community.”

Opening plans

Calgary roots

CRAFT Beer Market was founded in Calgary in 2011, drawing inspiration from Portland’s craft beer culture and aiming to make craft beer more accessible.

The company opened its first restaurant in Calgary’s Beltline and has since expanded into a national hospitality brand with locations across Canada. The Shepard Flats opening will bring its Calgary total to three locations.

The company said its expansion has extended from British Columbia to Ontario’s east coast and into the U.S.

CRAFT’s original concept was built around making craft beer accessible to Canadians while offering food and other beverages. The company says it focuses on sharing craft beer culture and educating guests about the category.

More from Retail Insider:

CRAFT Beer Market photo

How Independent Retailers Are Using Alternative Financing to Compete with Big Box Chains

The Challenge for Independent Retailers

Independent retailers have long faced significant obstacles in competing against big box chains. These large retailers benefit from economies of scale, extensive supplier networks, and vast financial resources that allow them to offer lower prices and a wider product range. For smaller, independent retailers, securing the necessary capital to invest in inventory, technology, and marketing can be a daunting task. Traditional financing routes, such as bank loans, often come with stringent requirements and lengthy approval processes, making it difficult for independents to respond quickly to market changes.

Recent data highlights the struggle faced by independent retailers: over 60% report difficulty in accessing affordable financing options, impacting their ability to grow and compete effectively (https://www.nfib.com/content/resources/finance/finance-survey/). Moreover, nearly 40% of small retailers have reported that cash flow constraints limit their ability to stock popular items or expand their operations, putting them at a disadvantage compared to larger competitors (https://www.score.org/resource/cash-flow-management-small-business). In this challenging environment, alternative financing solutions are emerging as a vital lifeline, enabling independent retailers to bridge the gap and enhance their competitive edge.

With the retail landscape continually evolving due to technological advances and changing consumer preferences, independent retailers must find innovative ways to stay relevant. The pressure to quickly adapt to trends such as e-commerce integration, omnichannel sales, and personalized customer experiences requires access to capital that traditional financing often cannot provide promptly. This is where alternative financing steps in, offering more flexible and accessible funding options tailored to the dynamic needs of smaller businesses. Platforms like https://www.credibly.com/ are at the forefront of this shift, providing tailored financial solutions that empower independent retailers.

Embracing Alternative Financing Solutions

Alternative financing encompasses a broad spectrum of non-traditional funding sources designed to meet the unique needs of businesses that might not qualify for conventional loans. These include merchant cash advances, invoice financing, revenue-based financing, online lending platforms, and peer-to-peer lending. By leveraging these options, independent retailers can secure faster access to capital with fewer barriers, enabling them to seize timely opportunities and manage cash flow fluctuations more effectively.

One prominent example of a platform facilitating this shift is a company specializing in providing flexible financing tailored to the needs of small and medium-sized businesses, including independent retailers. Their solutions are designed to help businesses access working capital quickly, with less reliance on credit scores and collateral, which traditionally limit access to funding. This approach allows retailers to obtain funds based on their sales volume or receivables, making the financing process more inclusive and adaptable to their specific circumstances.

In addition, many alternative financing providers offer streamlined application processes and faster approval times compared to traditional banks. While a conventional bank loan might take weeks or even months to secure, alternative lenders often deliver funds within days, a critical advantage for retailers facing sudden inventory demands or unexpected expenses. This agility allows independents to respond to market changes promptly, maintaining competitiveness in an environment dominated by large chains with deep pockets.

How Alternative Financing Levels the Playing Field

Access to alternative financing allows independent retailers to undertake strategic initiatives that were previously out of reach. For instance, they can invest in inventory replenishment to meet seasonal demand spikes or adopt new technologies for better customer engagement and operational efficiency. According to a report by the Small Business Administration, businesses that utilize alternative financing are 30% more likely to invest in digital transformation projects, such as upgrading point-of-sale systems or launching e-commerce platforms (https://www.sba.gov/sites/default/files/alternative_financing_report.pdf).

This influx of capital also empowers independents to enhance their marketing efforts and build stronger community ties—two areas where big box chains often struggle due to their size and standardized approaches. Independent retailers can leverage localized marketing strategies, sponsor community events, and tailor their product offerings to meet neighborhood preferences, all of which foster customer loyalty. The ability to quickly adapt and invest in local market trends provides independent retailers with a distinct advantage over large chains, which often rely on uniform branding and mass marketing.

Moreover, alternative financing can support staffing improvements, enabling independent retailers to hire and retain knowledgeable employees who provide personalized customer service. This human touch is a key differentiator in the retail experience and can drive repeat business. By using flexible funding options, retailers can also invest in training programs and employee incentives, further enhancing service quality.

Case Studies: Independent Retailers Thriving with Alternative Financing

Several independent retailers have successfully leveraged alternative financing to grow their businesses and compete effectively against big box chains. For example, a local apparel boutique used a merchant cash advance to rapidly increase inventory during a holiday season, resulting in a 25% sales boost year-over-year. This quick infusion of capital allowed the boutique to stock trending items that attracted new customers and increased foot traffic.

Similarly, an independent grocery store secured revenue-based financing to upgrade its point-of-sale system, improving checkout speed and customer satisfaction. The enhanced technology reduced wait times and streamlined inventory management, enabling the store to operate more efficiently and compete with larger supermarkets.

Another example is a family-owned hardware store that utilized invoice financing to manage cash flow during a major renovation project. This financing method allowed the store to pay suppliers promptly and keep operations running smoothly without dipping into reserves. As a result, the store was able to expand its product range and improve its in-store experience, attracting more customers.

These success stories underscore the transformative impact of alternative financing. They highlight how independent retailers can maintain agility and resilience in a competitive retail landscape dominated by large chains. By accessing flexible funding tailored to their unique needs, independents can seize growth opportunities, improve operational efficiency, and enhance customer satisfaction.

The Future Outlook for Independent Retailers

The retail sector is evolving rapidly, and independent retailers must continue adapting to remain relevant. Alternative financing is no longer a niche solution but a mainstream option that can empower smaller businesses to innovate and compete effectively. Industry forecasts suggest that the alternative lending market will grow at a compound annual growth rate (CAGR) of 12% over the next five years, reflecting increasing demand from small businesses seeking more accessible capital (https://www.marketwatch.com/press-release/alternative-lending-market-growth-2024-2029-2023-07-15).

Furthermore, the rise of fintech innovations is expected to expand the range and sophistication of alternative financing products available to independent retailers. Technologies such as artificial intelligence and machine learning are improving credit risk assessments and enabling more personalized financing options. This trend will likely reduce costs and increase approval rates for small businesses, further leveling the playing field.

For independent retailers, embracing alternative financing is not just about survival; it’s about unlocking new opportunities for growth and customer engagement. By combining financial flexibility with a deep understanding of their local markets, these retailers can carve out a sustainable path forward. They can invest in omnichannel sales strategies, enhance their online presence, and develop unique product assortments that resonate with their communities.

Moreover, alternative financing can facilitate partnerships and collaborations among independent retailers, allowing them to pool resources for marketing campaigns, bulk purchasing, or shared logistics. Such cooperative efforts can strengthen their position against big box competitors by leveraging collective scale while maintaining their unique local appeal.

Conclusion

Independent retailers face a uniquely challenging landscape dominated by big box chains with vast resources. However, alternative financing options are leveling the playing field by providing faster, more accessible capital solutions tailored to their needs. Platforms like exemplify the kind of support that enables independents to invest in inventory, technology, and marketing initiatives that drive growth.

As the retail industry continues to evolve, independent retailers that leverage alternative financing will be better positioned to innovate, compete, and thrive in their communities. The ability to secure flexible funding quickly can make all the difference in maintaining relevance and capturing market share in an increasingly competitive environment. By embracing these financial tools, independent retailers can transform challenges into opportunities and build resilient businesses for the future.

Retail Queue Management Software: The 6 Best Tools for 2026

The best retail queue management software in 2026 is Booxi, a retail-native platform that turns crowded walk-in traffic into a structured, revenue-generating flow. Unmanaged lines cost stores more than most retailers realize, because a customer who waits without acknowledgment rarely complains. They walk out, and that lost sale never shows up in a report.

We compared 6 platforms on what actually matters for physical stores: real-time wait estimation, self check-in, staff tools, analytics, multi-location scale, and how well each one ties queuing to the rest of your operations. Here’s how the top tools compare, along with what each does best and who it fits.

1. Booxi

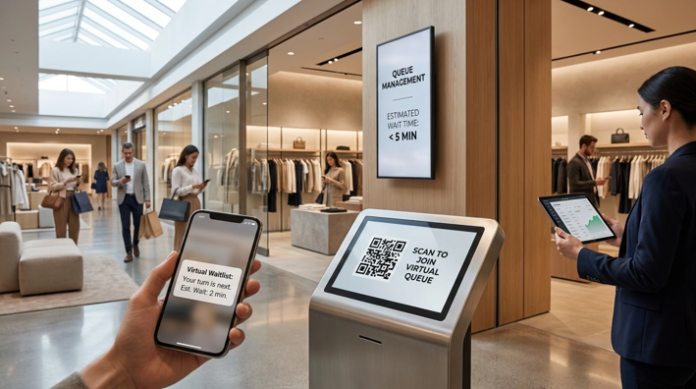
Built specifically for retail, Booxi brings appointment booking, in-store events, and queue management together in a single operational layer. The queue module covers the walk-in journey end to end: it calculates wait times on the fly, pushes automated notifications, and allows shoppers to check themselves in through a QR code or a simple link.

On the store side, associates operate from a live dashboard where they can assign customers, receive alerts on mobile, and filter by status, with walk-ins, booked appointments, and event guests all flowing through the same system. Because everything runs on one platform, head office can pull queue KPIs from every location automatically, instead of requesting reports store by store.

The platform also plugs into existing POS, CRM, and clienteling stacks via APIs and webhooks, so queue data enriches the wider customer picture rather than being stranded in its own tool. Retailers including Sephora, Hermès, Dior, and Printemps use it across 103 countries.

Who Is Booxi Best For?

Booxi fits enterprise retail networks with 10 or more locations, whether you manage one flagship or an entire chain across luxury, beauty, eyewear, premium fashion, department stores, or petcare.

It’s the strongest choice when you need HQ-level visibility while keeping store tools simple for frontline teams, because it balances centralized governance with store-level autonomy. Retailers who want a queue tool that also ties waiting to conversion and basket size will get the most from it.

2. QLess

QLess is a mobile-first queue management platform that lets customers join a line remotely and wait wherever they want. Customers check in from their phone, receive text updates on their place in line, and get called back when it’s their turn, which cuts crowding at the counter. The platform also offers appointment scheduling and interactive messaging, and it serves retail alongside education, government, and healthcare. That cross-industry reach makes it flexible, though it isn’t tailored to retail operations the way a store-native platform is.

Who Is QLess Best For?

QLess fits organizations that want to eliminate physical lines and let customers wait remotely across multiple service points. High-traffic environments with long lines see the clearest benefit. Retailers who want a platform purpose-built for store conversion, not just line reduction, should weigh that gap.

3. NextMe

NextMe is a lightweight virtual waitlist app aimed at smaller operations. Customers join the list remotely, receive SMS notifications as their turn approaches, and skip the physical line, while staff manage everything from a simple dashboard or tablet. Setup is fast and needs no hardware, which keeps both the cost and the learning curve low. The trade-off is depth, because NextMe covers the fundamentals of waitlisting without the enterprise governance, integrations, or unified scheduling that larger networks rely on.

Who Is NextMe Best For?

NextMe suits small retail operations, single stores, and service businesses that want an affordable, easy way to replace a paper waitlist. Owners who need something running the same day without IT support will appreciate it. Retail networks with advanced needs like VIC prioritization or POS integration will outgrow it quickly.

4. Wavetec

Wavetec is an enterprise customer-flow provider that pairs queue management hardware with software. Its lineup covers ticket dispensers, self-service kiosks, digital signage, and virtual queuing, so customers can take a spot on-site or from their phone. The platform layers in customer-feedback capture and analytics dashboards that track wait times and service performance across branches. Because Wavetec leans on physical infrastructure, its deployments run heavier and suit organizations that want an on-premise queue setup alongside the digital layer.

Who Is Wavetec Best For?

Wavetec suits large, high-traffic operations in banking, telecom, healthcare, and big-box retail that want a hardware-backed queue system across many sites. Retailers who prefer a fast, software-only rollout without kiosks and signage may find the setup heavier than they need.

5. Qminder

Qminder is a walk-in management platform built around self check-in. Customers register on a tablet or kiosk at the entrance, join a digital queue, and get updates on their phone, while staff track the live queue on a dashboard with filters for service type and priority. The platform reports on average wait time, service duration, and visitor volume, and it rolls out quickly across multiple locations. Its interface stays clean and needs little training, though it centers on queuing rather than extending into appointments or events.

Who Is Qminder Best For?

Qminder is a strong fit for retail locations and service centers that want a simple, tablet-based check-in flow backed by solid analytics. Teams that need fast deployment with minimal onboarding benefit most. Retailers who want one platform covering walk-ins, appointments, and events will need to look further.

6. Waitwhile

Waitwhile is a cloud-based virtual queue and waitlist platform used across retail, healthcare, and government. Customers join a waitlist from their phone, get SMS updates on their position, and receive a notification when it’s their turn. The platform adds two-way messaging, estimated wait displays, and analytics that surface bottleneck hours so managers can adjust staffing. It handles high walk-in volume well, but its event capabilities stay limited and its reporting tracks operations rather than revenue, so it doesn’t connect waiting to conversion or basket impact.

Who Is Waitwhile Best For?

Waitwhile works for retailers with high walk-in volume that mainly want to digitize the waiting experience. Its feature set is generalist rather than retail-specific, so single locations and smaller networks tend to fit best. Multi-location retailers who need full event management and revenue-level reporting will likely outgrow it.”

How to Choose the Right Retail Queue Management Software

The right platform comes down to how your stores actually operate, not the length of a feature list. Work through the questions below before you compare tools.

What Operational Factors Should You Evaluate First?

Start with scale, because a 5-store chain and a 200-store network have very different needs. Enterprise platforms like Booxi and Wavetec are built for multi-location governance, while lighter tools like NextMe and Qminder fit smaller footprints. Then weigh frontline adoption, since a system that store associates find hard to use will fail no matter how capable it is on paper.

Do You Need a Standalone Queue Tool or a Unified Platform?

Decide whether you’re solving walk-in lines alone or the wider flow of appointments, events, and queues together. If walk-ins are your only pain point, a standalone queue tool covers it. If customers also book visits and attend events across your stores, a unified platform avoids the cost and confusion of stitching separate tools together.

When Does a Retail-Specific Platform Outperform a Generic Tool?

Generic queue tools serve clinics, government offices, and banks, so their features target the lowest common denominator. Retail-specific platforms address problems unique to stores, such as VIC prioritization, POS and CRM integration, peak-season spikes, and connecting online booking intent to in-store visits. When your stores lose sales to walk-outs during rush hours or run disconnected tools across locations, a retail-native platform closes those gaps faster than a generalist adapted after the fact.

Get the Best Retail Queue Management Software with Booxi

Managing walk-in traffic well is really about protecting the revenue that already walks through your doors. The right platform turns waiting from a source of lost sales into a structured, measurable moment that lifts conversion, basket size, and staff productivity. Booxi brings that together in one retail-native system that unifies appointments, events, and queues, gives headquarters full visibility, and keeps store tools simple for frontline teams. To see how it fits your network, talk to a Booxi expert.

Frequently Asked Questions About Retail Queue Management Software

What Is Retail Queue Management Software and How Does It Work?

Retail queue management software replaces unstructured walk-in traffic with a digital flow. Customers check in through a tablet, QR code, or their phone, join a virtual queue, and receive real-time updates on their position, while staff serve them in order from a live dashboard. The system also captures data on wait times, service duration, and walk-out rates.

How Does Queue Management Reduce Walk-Out Rates in Stores?

Customers leave when waiting feels uncertain, so a clear wait estimate that lets them browse instead of stand in line keeps them in the store. Real-time updates cut perceived wait time and give staff a structured way to serve people in order. That visibility is why stores that move from unmanaged lines to a digital queue typically hold on to more customers during peak hours.

Can Queue Management Software Integrate With Existing Retail Systems?

Most enterprise-grade platforms connect to POS systems, CRMs, and clienteling tools through APIs or webhooks. The depth varies, because some offer native connectors for major retail systems while others need custom development. Before you choose, confirm the platform links to the systems your stores already run.

How Much Does Retail Queue Management Software Cost?

Pricing depends on the number of locations, the features you need, and whether the tool is a standalone queue app or part of a unified platform. Lightweight waitlist apps sit at the low end, while enterprise platforms with analytics, integrations, and multi-location governance cost more. Most enterprise vendors quote custom pricing rather than publish fixed rates, so plan to request a demo for an accurate figure.

Queue Management or Appointment Scheduling: Which Does Your Store Need?

Queue management handles spontaneous walk-ins and real-time wait times, while appointment scheduling organizes booked visits in advance. Many retailers need both, because walk-ins and planned visits happen in the same store. A unified platform covers the two in one flow, which avoids running separate tools that don’t talk to each other.

Product Photography Is Now a Volume Problem, Not a Craft Problem

A Toronto housewares retailer with roughly 300 SKUs joined a new marketplace last spring and found the listings wouldn’t go live without a clean shot on a plain background for every item. The photography on hand was good: warm, styled, shot on a walnut table with a linen runner. None of it qualified. The options were a four-figure reshoot or three weeks of someone in the office working through the catalogue by hand.

That scenario has become ordinary, and it points at a shift most merchandising teams have absorbed without ever naming. The problem is rarely that a retailer can’t produce a good photograph. It’s that every product now needs six versions of itself, and the sixth one is due tomorrow.

One Shot, Six Placements

A single kettle has to appear as a website hero, a marketplace thumbnail sitting on white, a 4:5 paid social creative, a 9:16 vertical for reels and stories, an email header cropped to a wide letterbox, and increasingly a tile on a retail media network with its own text safe area. Each has a different aspect ratio, a different amount of breathing room, and different rules about what may sit behind the product.

A photographer delivers the hero. Everything after that is derivative work: recrop, extend the background, remove the styling props that read as clutter at small sizes, lift the shadow so the product doesn’t vanish against a dark interface. None of it is creative work in the sense a photographer would recognize, and all of it takes time.

Multiply by a catalogue and the shape of the problem changes. Two hundred products across six placements is twelve hundred assets, refreshed at least seasonally.

Where the Work Moved Inside

Very few retailers made a formal decision to bring image production in-house. It happened by drift. Someone in merchandising started cleaning up phone photos between other tasks, the results were good enough for a marketplace tile, and the shoot budget went unspent for a quarter.

Pixelcut is an AI photo editor that handles background removal, object removal, upscaling and batch resizing from a phone. That combination made the drift easy, because isolating a product from a cluttered stockroom shot stopped requiring any knowledge of what a layer mask is. The skill floor dropped far enough that a category manager could produce in ten minutes what used to arrive on an invoice as retouching.

Which is mostly good news, and creates a different problem. Work that used to be governed by a brief and executed by one retoucher is now distributed across whoever has an afternoon free.

What a Studio Day Actually Buys You

A studio day buys direction and consistency: one lighting setup, one point of view, one set of decisions applied across everything shot that day. That is genuinely valuable, and it is not what most retailers are short of.

What a studio day does not buy is the long tail. The line extension that arrives in August, three weeks after the shoot. The colourway a supplier added late. The single item reshot because the sample had a scuff on it. Photography books in blocks; merchandising moves continuously, and the gap between those two rhythms is where the work piles up.

The Consistency Problem Nobody Budgets For

Three hundred images edited by four people over eight months produce four visual dialects. One person crops tight, another leaves a generous margin. One keeps a soft contact shadow, another cuts it away entirely. One nudges the white point warm because it looked better on their monitor.

Individually, every image is fine. Viewed as a category page, the grid reads as untidy, and untidy reads as unserious. This is not a talent problem or a tooling problem. It’s a specification problem, and specifications are the thing nobody gets assigned.

The Cost of a Flattering Angle

Editing tools make it trivially easy to push saturation, and colour is where that gets expensive. A sofa that reads charcoal on a phone and mushrooms in a living room comes back, and the return costs more than the sale earned. The temptation to make a product look its best is the same temptation that fills the returns bay.

Marketplace Standards Set the Floor, Not the Ceiling

Marketplace image requirements are minimums: plain background on the main image, product filling a reasonable share of the frame, no promotional text overlaid, resolution high enough to support zoom. Clearing them makes a listing eligible rather than persuasive, and a surprising number of retailers treat compliance as the finish line.

Online Is a Smaller Slice Than the Category Assumes

Here is the number that should shape how any of this gets funded. Retail e-commerce sales came to roughly $5.0 billion in May against $73.7 billion in total retail trade, which works out to 6.8 per cent of the sector, down from 7.0 per cent in April on a seasonally adjusted basis. Those are Statistics Canada’s figures, and the share has been stubbornly flat rather than climbing.

Read carelessly, that argues for spending less on imagery. Read properly, it argues close to the opposite. If online is a small and slow-growing share of trade, then image assets can’t be justified by webstore conversion alone. They have to earn their cost across in-store screens, flyers, wholesale line sheets, retail media placements and marketplace listings, which is precisely the multi-surface demand that broke the old studio model in the first place.

It also punctures a planning assumption that turns up in a lot of decks. Teams that budgeted on the belief that Canadian online share would drift up toward eight or ten per cent have been planning against a number the data has not delivered.

Who Should Own the Image Pipeline

Someone has to own it by name. The workable arrangement in practice is a single owner, usually in merchandising rather than marketing, holding a short written specification: background treatment, crop margin, shadow style, white point reference, and a list of which assets go to a photographer versus which get produced internally.

The specification does not need to be long. It needs to exist somewhere other than in one person’s head, because the person who has been doing the edits will eventually be on vacation during a launch.

The Test Is Whether the Product Arrives Looking the Same

A useful audit is to order three items from your own store and unbox them next to the listing images on a phone. Colour, scale, finish, the way light sits on the surface. Wherever they diverge, that’s the gap between what the imagery promised and what the warehouse shipped, and it shows up later as a return, a review, or a customer who doesn’t come back. Everything else in the pipeline is downstream of getting that one comparison right.

The Search Bar Is the New Storefront Window: How Local Search Is Redrawing Canadian Retail

Canadian retailers spent decades perfecting the storefront — the window display, the signage, the location on the right side of the street. In 2026, the first storefront most shoppers see is a search results page. Before a customer walks into a boutique on Ossington, a garden centre in Surrey or a menswear shop in Calgary’s Kensington, the overwhelming odds are that she searched first: for the product, the category or simply “near me.” Local SEO for retailers — the discipline of making a physical store visible in those searches — has quietly become as consequential as lease negotiations, and far less understood. “Retailers still obsess over foot traffic as if it starts at the sidewalk,” says Mike Chrest, founder of MRC SEO Consulting, an Alberta-based firm that works with brick-and-mortar businesses on local search visibility. “It doesn’t anymore. Foot traffic starts on a phone screen, usually within a few kilometres of the store, and the retailers who win that screen are pulling customers away from the ones who ignore it.”

The shift is measurable. Google has reported for years that searches containing “near me” and “where to buy” have grown by triple digits, and that a large majority of smartphone users who search for something nearby visit a store within a day. Industry analyses consistently place the share of retail purchases that are researched online — even when the sale ultimately happens in person — well above three quarters. For a sector fighting for margins against e-commerce giants, that in-person sale increasingly begins, or dies, in local search results.

“Near me” is rewriting retail foot traffic

The economics of retail have always been about location, and in a sense nothing has changed — except that “location” now has a digital coordinate. When a shopper in Mississauga searches “running shoes near me,” Google assembles a hyper-local shortlist in milliseconds: three stores in the Map Pack, their ratings, their hours, whether they’re open right now. The store that appears owns the visit. The store that doesn’t was never considered.

What makes this shift so easy for retail leadership to underestimate is that it is invisible in traditional metrics. A location with declining walk-ins looks like a neighbourhood problem, a merchandising problem or a macro problem. Very often it is a visibility problem: a competitor two blocks away has a complete, active Google Business Profile with 400 recent reviews, and the underperforming store has an unclaimed listing with the wrong holiday hours. Nothing about the physical trade area changed. The digital trade area was conceded.

The pattern repeats across the country, from suburban power centres to urban high streets. Retail Insider’s own coverage of store openings and closures tells the physical story; the parallel story is that every one of those trade areas is also a contested search market, and the contest is won or lost long before a shopper reaches the door.

Research online, buy in store: the funnel nobody owns

Retailers have a name for the dominant shopping pattern of the decade — ROPO, research online, purchase offline — but surprisingly few have operationalized it. The shopper who buys a $300 jacket in person has typically already compared brands, checked availability, read reviews and confirmed the store’s hours online. Every one of those touchpoints is a moment where a retailer can win or lose the visit.

This is where local search differs fundamentally from e-commerce marketing. The goal is not to close a transaction in the browser; it is to remove every reason not to come in. Is the product in stock? Is the store open tonight? Is parking easy? Do other customers vouch for the service? A retailer whose digital presence answers all four questions converts research into a visit. A retailer whose presence answers none of them sends that shopper — often literally — to the competitor pinned beside them on the map.

“The most expensive words in retail search are ‘information unavailable,'” Chrest observes. “When a listing can’t tell a shopper whether the store is open or whether the item is on the shelf, the shopper doesn’t give the store the benefit of the doubt. They tap the next result. We’ve audited retailers spending six figures on brand advertising while their own store listings showed wrong hours in half their locations.”

The Google Business Profile is the digital flagship

For a single-location boutique or a national chain, the Google Business Profile has become the most-viewed piece of digital real estate the company owns — frequently seen by more local shoppers in a month than the brand’s website. It is also, in most organizations, an orphan: too tactical for the marketing department, too digital for store operations.

Treating the profile as a flagship changes the checklist. Categories must be precise, because they determine which searches a store can appear for at all. Photos need to be current and abundant — interiors, product walls, seasonal displays — because shoppers use them the way they once used window displays. Hours must be flawless, including statutory holidays, because a single “closed when listed open” experience produces the angriest class of one-star review. Products and services should be populated, posts kept active, and the questions shoppers ask publicly answered by the brand rather than by strangers guessing.

For multi-location retailers the challenge compounds: fifty stores means fifty profiles, each a local ranking contest in its own trade area. Chains that centralize listings management without local input tend to produce technically consistent but lifeless profiles; chains that leave it to store managers get enthusiasm and chaos. The retailers doing this well run a hybrid — centralized data governance for name, address, phone and hours, local contribution for photos and community texture.

The most powerful recent development in retail search is the surfacing of live, store-level inventory. Through local inventory feeds and see-what’s-in-store integrations, Google can now show a shopper not just that a store exists nearby, but that the specific item she wants is on the shelf right now. For categories under siege from e-commerce — electronics, sporting goods, toys, apparel — this is the strongest possible counterpunch: immediacy. No courier can beat “available today, 1.4 kilometres away.”

Canadian adoption remains uneven, which is precisely the opportunity. Retailers that connect their point-of-sale or inventory systems to their listings gain a visibility layer most local competitors simply do not have. The technical lift is real but modest compared with almost any other omnichannel initiative, and the payoff lands on the highest-intent shoppers in the funnel: people actively searching for a product they intend to buy today.

Reviews are the new mystery shopper — and the new merchandiser

Retail has always lived and died by word of mouth; reviews industrialized it. Survey after survey shows the vast majority of consumers read reviews before visiting a local business and trust them at nearly the level of personal recommendations. In ranking terms, review volume, recency and rating all feed a store’s prominence in local results. In conversion terms, the review panel is often the deciding screen a shopper reads before choosing between two stores on the map.

Less appreciated is what reviews do for relevance. When customers repeatedly mention “wide sizes,” “vinyl selection” or “knowledgeable staff,” those phrases become independent evidence of what the store offers — search-relevant language no brand copywriter can plant. Smart retailers mine their reviews for exactly this: the vocabulary customers actually use, which then informs everything from listing descriptions to in-store signage.

The operational playbook is unglamorous discipline: ask at the till or in the post-purchase email, make the link one tap, respond to everything, and never manufacture reviews — Google’s filters have grown ruthless, and a purge can vaporize years of accumulated social proof at the exact moment a retailer needs it.

AI shopping assistants are compressing discovery

Layered over all of this is the fastest-moving change in consumer behaviour: shoppers asking AI systems for recommendations. AI Overviews now top many Canadian retail searches, and a growing cohort of consumers asks assistants directly — “where should I buy a quality winter parka in Ottawa?” — receiving a synthesized shortlist instead of ten blue links.

These systems assemble their answers from the same raw material as traditional local search: business profiles, review corpora, structured data, authoritative mentions in publications. They are conservative by design, favouring retailers with deep, consistent, verifiable digital footprints. The practical takeaway for retail leadership is that AI discovery is not a separate channel requiring a separate strategy; it is a magnifier of the local search fundamentals a retailer either has or lacks. Stores invisible in the Map Pack tend to be invisible to the assistants, too, and for the same reasons.

Local SEO for retailers is not e-commerce SEO

Part of the reason retail organizations under-invest here is a category error: the assumption that search visibility is the e-commerce team’s file. The two disciplines share a search engine and almost nothing else.

E-commerce SEO competes nationally for transactional product queries, wins clicks and closes sales in the browser. Local SEO for retailers competes within a trade area measured in kilometres, wins map placements and profile views, and closes its sales at a cash register the analytics platform never sees. The ranking inputs differ accordingly: proximity to the searcher, the health of each location’s Business Profile, review depth per store, and the consistency of the brand’s name, address and phone data across the local web — signals an e-commerce team has no mandate to touch, and rightly so.

The org-chart consequence is that local search visibility routinely belongs to no one. Marketing owns the brand site, operations owns the stores, and the fifty Business Profiles in between are updated by whoever last remembered they exist. The retailers that treat local visibility as a named function — with an owner, a budget line and store-level metrics — are competing in a different league from those that treat it as an occasional cleanup project.

The measurement gap feeds the neglect. Store-visit attribution is genuinely harder than e-commerce attribution, but “harder” has quietly become “ignored,” and what goes unmeasured goes unfunded. The pragmatic fix is directional rather than perfect: profile views, direction requests and calls per location, tracked monthly against rankings in each trade area, correlated with the traffic counters most retailers already run at the door. The retailers doing this consistently report the same discovery — local search is usually their cheapest incremental store visit, precisely because so few competitors in the trade area are managing it deliberately. In secondary markets and suburban nodes across Canada, whole categories remain effectively unclaimed: no store in the trade area has more than a skeleton profile, and the first retailer to invest seriously inherits the Map Pack almost by default.

What Canadian retailers should do before the holiday quarter

The encouraging news is that retail local search rewards operational competence, and retailers are operators. The foundation can be audited and largely rebuilt in a quarter: claim and complete every location’s Business Profile under exact, consistent naming; fix name-address-phone consistency across every directory, map platform and social profile; build a location page on the brand site for every store, with unique content about that store’s team, stock focus and community, rather than a templated address block; connect inventory data to listings where the point-of-sale system allows it; stand up a review generation and response program with store-level accountability; and instrument everything — profile views, direction requests, calls, and the search terms shoppers actually use to find each location.

Timing matters. Local signals compound over months, not days, and the ranking positions a retailer holds in November are earned in the summer and early fall. A visibility project that starts after Thanksgiving is a project for next year.

The bottom line

Canadian retail’s defining battle of this decade is not online versus offline — shoppers ended that debate themselves by blending the two. The battle is over who controls the moment of local discovery: the shrinking strip of screen where a shopper with money and intent chooses which nearby store earns the visit. That strip — three map listings, a review score, an AI-generated sentence or two — is the new prime frontage. Retailers fought for a century over corner lots and anchor positions. The same fight has moved to the search results page, the rents are paid in operational discipline rather than dollars per square foot, and the lease terms favour whoever shows up first.

Westrich to Acquire and Redevelop Edmonton City Centre

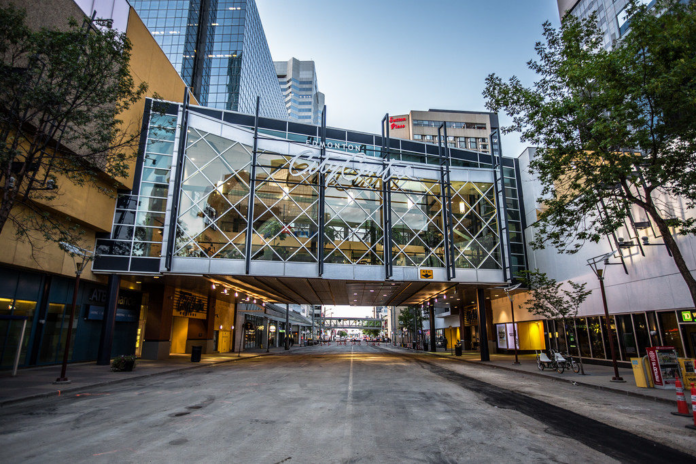
Photo: Edmonton City Centre

Edmonton-based Westrich Pacific has received court approval to acquire Edmonton City Centre, setting the stage for a major redevelopment of the downtown property that is expected to begin with approximately 1,500 residential units on the former Hudson’s Bay portion of the site.

The Alberta Court of King’s Bench approved the sale on August 7, with the transaction expected to close before the end of 2026. Westrich plans to begin major construction on the first phase in early 2027, subject to required approvals.

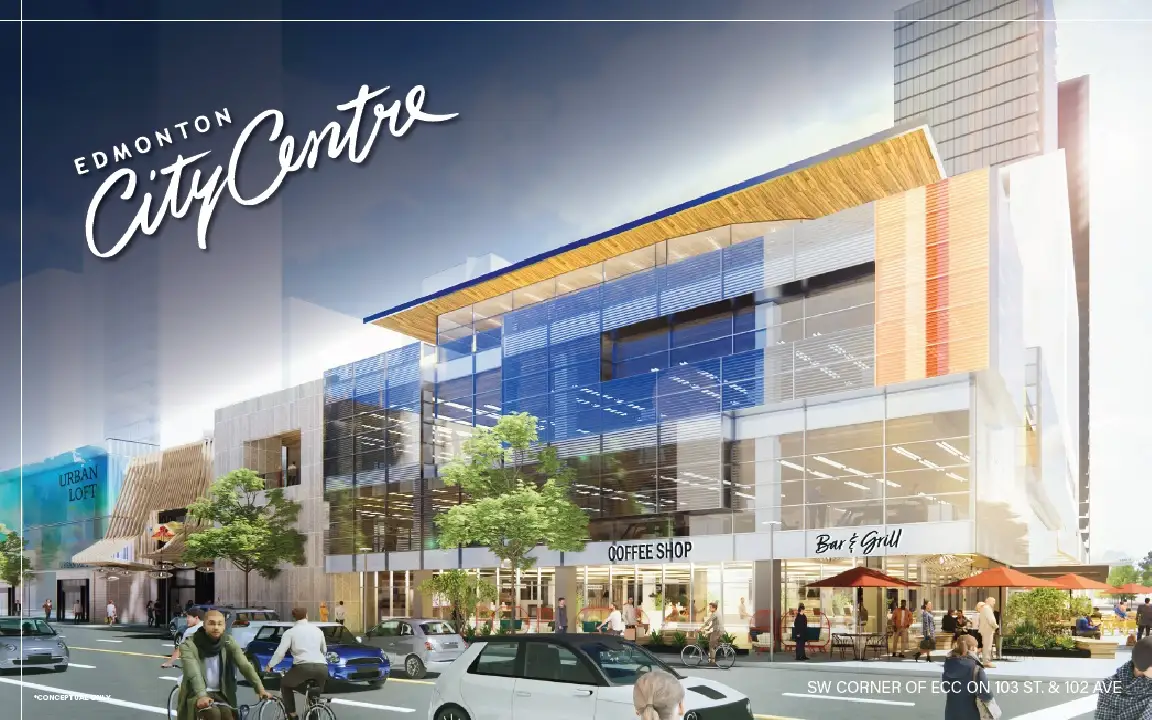
The first phase is expected to include the residential units along with new street-fronting retail, a redesigned exterior and a rooftop Nordic spa. Future phases are envisioned to bring additional retail, entertainment, wellness and experiential uses to Edmonton City Centre, along with a new exterior treatment for the mall and LED displays.

Westrich is now advancing development permit drawings and detailed planning for the redevelopment. The company has not yet disclosed the configuration of the residential component, including the number or height of buildings, housing tenure or the extent to which existing structures would be retained, altered or replaced.

A 1.4-Million-Square-Foot Downtown Complex

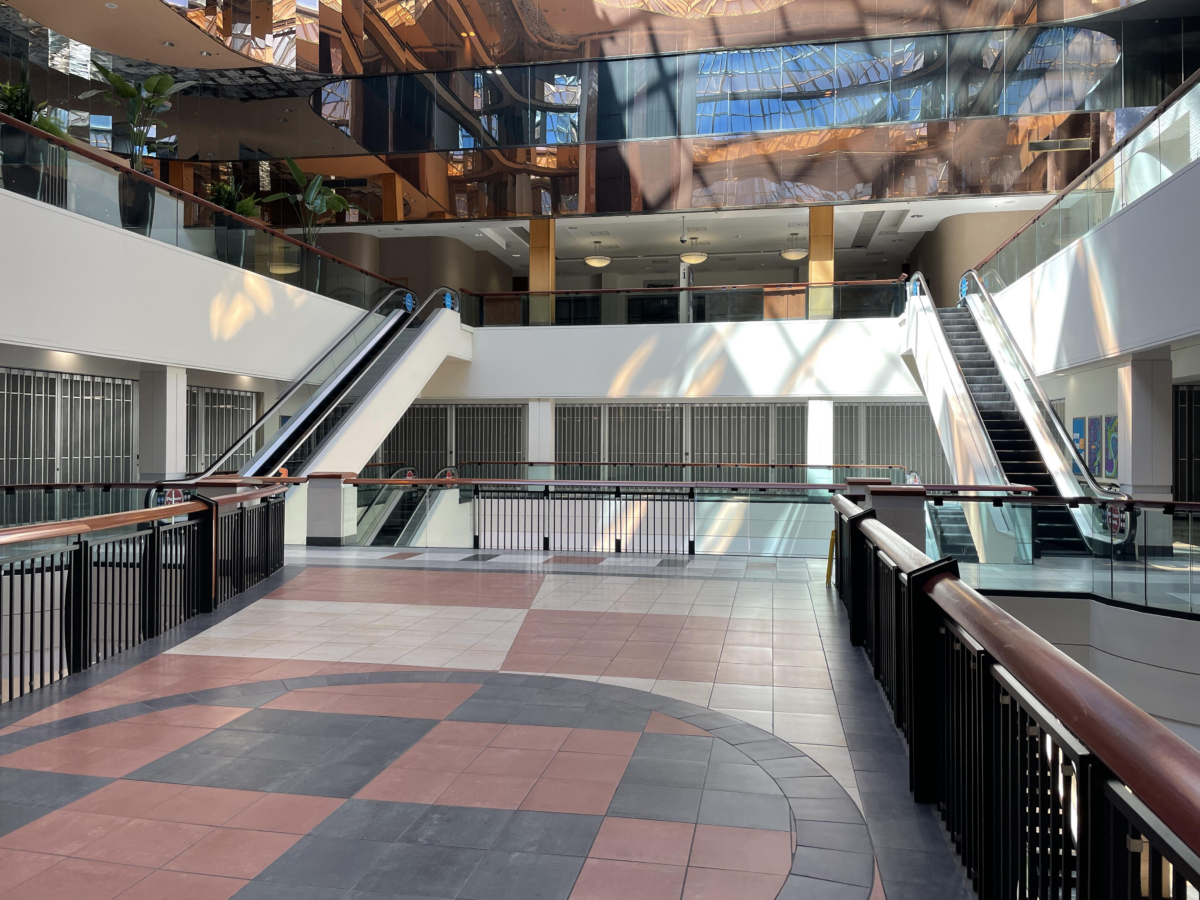
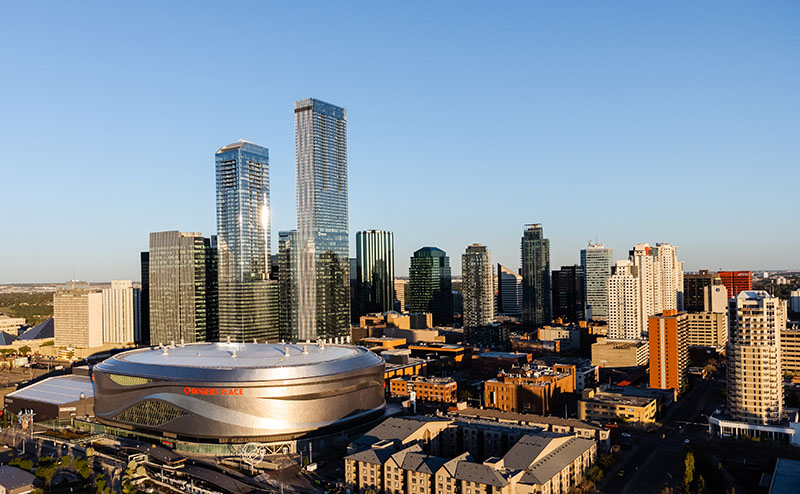
Edmonton City Centre encompasses approximately 1.4 million square feet across about 10 acres in the heart of Downtown Edmonton. The property includes Edmonton City Centre West, Edmonton City Centre East, Centre Point Place, TD Tower, 102A Tower and multiple parking facilities.

The shopping centre itself has historically been described as comprising more than 725,000 square feet, while the broader complex contains a substantial office component. Westrich says the property includes approximately 2,567 underground and covered parking stalls.

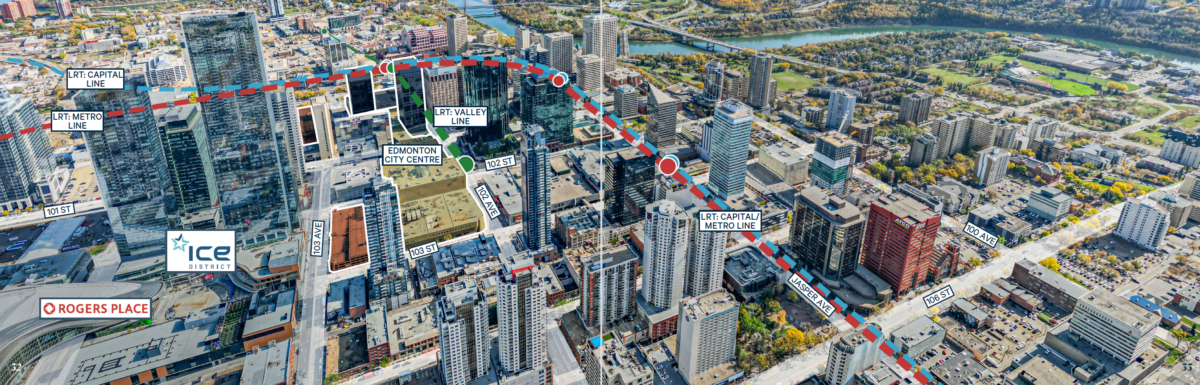
Edmonton City Centre is also integrated into the downtown transit and pedestrian network, with connections to the Metro and Capital LRT lines through Churchill Station and the Valley Line Southeast through the 102 Street stop. Pedway connections link the property with other parts of Edmonton’s financial core.

Former Hudson’s Bay Site Becomes Starting Point

The first phase is planned for the former Hudson’s Bay portion of Edmonton City Centre, connecting the proposed residential development to one of the most significant vacancies in the property’s recent history.

Hudson’s Bay occupied approximately 168,000 square feet at Edmonton City Centre before closing its downtown location in 2021. Its departure removed the shopping centre’s last traditional department store anchor and left a substantial amount of space requiring a new long-term use.

Westrich has not yet disclosed how the approximately 1,500 residential units will be configured on that portion of the property. Development permit drawings are now being advanced, leaving questions around building heights, demolition, adaptive reuse and the relationship between the residential development and existing mall structures to be answered as planning progresses.

Years of Change at Edmonton City Centre

Edmonton City Centre has evolved through several generations of downtown retail development. Its history includes Edmonton Centre, which opened in the 1970s, and Eaton Centre, which followed in the 1980s. The properties were subsequently combined under the Edmonton City Centre name.

Oxford Properties undertook a major modernization during the mid-2010s, including changes to the food court, retail configuration and parking. The broader property was sold in 2019 in a transaction later disclosed through court materials to have involved a purchase price of approximately $311.5 million. LaSalle Canada Property Fund led the ownership group, with financing provided in part by Otéra Capital.

Major tenant departures followed. Hudson’s Bay announced in 2020 that it would close its downtown Edmonton store and exited the following year. Sport Chek and Atmosphere subsequently left Edmonton City Centre in 2023 after declining to renew their leases. Women’s retailer Talbots, which opened its Edmonton store in 1991, is not expected to renew its lease next year according to sources.

The centre has continued to operate with retailers and businesses including Winners, Landmark Cinemas, Shoppers Drug Mart and Dollarama, among other tenants. The anchor departures nevertheless left large spaces requiring new uses as downtown shopping and work patterns were also changing.

Aerial view of downtown Edmonton, via CBRE

Property Entered Receivership in 2025

Edmonton City Centre Inc. was placed into receivership in July 2025 following an application by secured lender Otéra Capital, with PricewaterhouseCoopers Inc. appointed as receiver.

Court materials show that Otéra provided financing connected to the 2019 acquisition, including a $128.5-million acquisition loan and a capital expenditure and leasing facility of up to $27 million. Required payments were not made beginning in late 2024, and approximately $139.5 million was owed to Otéra by June 2025 before additional interest, expenses and costs.

Westrich Management Ltd., or its nominee, entered into a purchase and sale agreement for Edmonton City Centre on July 20, 2026. PwC subsequently sought court approval for the transaction, which was granted August 7.

The purchase price has not been publicly disclosed, with portions of the sale materials remaining confidential pending completion of the transaction. Closing is expected before the end of 2026.

2021 rendering of redevelopment plans for Edmonton City Centre (since changed)

1,500 Homes Could Add to Downtown Customer Base

The proposed residential development comes as Edmonton works to increase the number of people living in its downtown core. Nearly 13,000 people currently live downtown, according to the City of Edmonton, while the area has a much larger daytime population of workers, students and visitors. Increasing the residential population has become an important part of efforts to create more activity outside conventional working hours and support businesses throughout the week.

Adding approximately 1,500 homes at Edmonton City Centre would increase the residential base immediately within one of downtown’s largest commercial properties. Those households could provide regular customers for restaurants, retailers, personal services, entertainment and wellness businesses at Edmonton City Centre and elsewhere nearby.

That customer base could be particularly relevant during mornings, evenings and weekends, when businesses that depend heavily on commuters and office workers can experience lower traffic.

Restaurant Closures Highlight Downtown Challenges

The redevelopment is being proposed during a difficult period for some Downtown Edmonton businesses. A series of restaurants closed during June and July 2026, including Greta, Bündok, PlayWright, Khazana and kb&co.

Operators and downtown business organizations have pointed to several pressures rather than a single cause, including construction disruption, reduced foot traffic, accessibility and parking challenges, public-safety concerns, hybrid office work and higher operating costs.

The Edmonton Chamber of Commerce said in July that nearly 20 businesses had closed in the core during 2026 and called for action on construction coordination, accessibility, public spaces and safety. The Downtown Revitalization Coalition has similarly raised concerns about conditions affecting businesses downtown.

The closures are only one part of the downtown economy. Established businesses continue to operate, investment is taking place and parts of the commercial real estate market have recently shown improvement. The restaurant losses have nevertheless renewed discussion about how Downtown Edmonton can generate more consistent foot traffic and support businesses outside the weekday office cycle.

Downtown Edmonton. Photo: City of Edmonton

Street-Fronting Retail and New Uses

Westrich’s plans would combine the new residential population with a broader commercial mix at Edmonton City Centre. Existing offices would continue to contribute daytime traffic, while entertainment and wellness uses could attract visitors during evenings and weekends.

Street-fronting retail is another notable component. Edmonton City Centre has historically been oriented heavily toward interior mall corridors and the downtown pedway network. Creating additional commercial spaces facing surrounding streets would establish more direct connections between businesses in the property and pedestrian activity outside.

The proposed Nordic spa would add a destination wellness component, while future phases are also expected to include entertainment and other experiential uses. Together with the residential development, the plans would create several different sources of activity within a property that has historically been centred primarily on retail and offices.

Westrich Has Deep Edmonton Residential Experience

Westrich Pacific is an Edmonton-based multifamily and mixed-use developer with experience building residential projects in and around the downtown core. Its portfolio includes high-rise developments such as Ultima and Encore, along with other condominium and rental projects.

The company continues to pursue residential development elsewhere in Edmonton. Its Grandin City plans, for example, have included multiple residential towers, while other current projects include multifamily developments in different parts of the city.

Westrich has also expanded into consumer-facing businesses. The company holds the Canadian development rights for Los Angeles-founded restaurant concept Eggslut and is overseeing the brand’s expansion into Canada.

At Edmonton City Centre, however, the scale is considerably larger. Approximately 1,500 residential units are contemplated in the first phase alone, within a property that also contains hundreds of thousands of square feet of retail and office space.

Downtown Edmonton Presents a Mixed Picture

The restaurant closures and concerns raised by downtown business operators come alongside more positive indicators elsewhere in the core.

Parts of Edmonton’s office market have recently shown improvement, including declining sublease availability, while residential development and public investment continue. Efforts to increase the number of people living downtown are also intended to create a more consistent population supporting businesses, public spaces and amenities throughout the week.

Edmonton City Centre sits at the intersection of many of those issues. It contains a large retail component, office space, extensive parking and direct transit connections, while Westrich is now proposing to add a substantial residential population and new destination uses.

Edmonton Mayor Andrew Knack said the investment represents a sign of confidence in downtown.

“This investment by Westrich is a strong sign of the revitalization we are seeing in our downtown core,” Knack said. “Westrich has a proven track record of getting projects built and bringing more people into the heart of the city.”

Major Details Still to Come

Several important elements of the redevelopment have not yet been disclosed, including the acquisition price, total development cost, configuration and height of the residential buildings, housing tenure, extent of demolition or structural changes, and the eventual amount of retail space within Edmonton City Centre.

Westrich has also not identified the operator of the proposed Nordic spa or specific entertainment and wellness concepts being considered for later phases. More information is expected as development permit drawings and detailed planning advance.

Subject to required approvals, Westrich expects major construction on the first phase to begin in early 2027, with subsequent phases proceeding as market conditions permit. The transaction itself is expected to close before the end of 2026.

More from Retail Insider:

Pet Valu raises more than $2.6M for animal causes during annual campaign

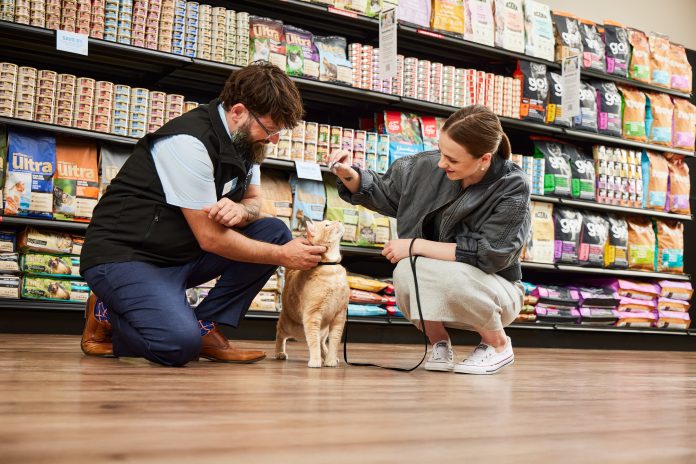
Pet Valu photo
Photo: Pet Valu

Pet Valu says its annual Pet Appreciation Month campaign raised more than $2.6 million in monetary and product donations this year for more than 500 animal-related causes across Canada, surpassing the company’s previous record by $400,000.

The donations were collected during the company’s June campaign, with all proceeds directed to local animal rescues and other designated causes at participating stores.

Record donations

Pet Valu said the 2026 campaign was its most successful since Pet Appreciation Month began in 2011. The previous record was set in 2024.

“We are deeply touched by the generosity of our devoted pet lovers who stepped up at a time when so many Canadian animal rescues, shelters and charities need essential funds and products,” said Greg Ramier, CEO at Pet Valu. “We established Pet Appreciation Month in 2011 to provide much needed support for local animal organizations doing invaluable work to help pets in need in the communities in which we operate. We are very proud that Pet Appreciation Month is now the largest of Pet Valu’s Companions for Change annual initiatives and that this year’s donations exceeded all previous years.”

During the month-long campaign, customers at each of Pet Valu’s more than 700 stores outside Quebec could purchase a paper PAW for a donation amount or contribute a product of their choosing.

The company said 100 per cent of donations go to the local rescue or cause designated by each store.

Since the campaign began, Pet Appreciation Month has generated more than $21.6 million in monetary and product donations, according to the company.

Adoption efforts

The June campaign also included National Adoption Weekends at select Pet Valu stores, where participating locations hosted adoptable pets along with volunteers and rescue staff.

Pet Valu said more than 1,000 pets found homes during adoption events in June this year. Over the years, the company’s National Adoption Weekends have helped more than 54,000 pets find homes.

The campaign’s latest results come as Pet Valu marks 50 years since opening its first store in Toronto.

“Pet Valu opened its first store in Toronto 50 years ago, and this year we’re celebrating the memories, connections and joy we’ve shared with pets and their devoted owners ever since,” said Ramier. “Our exceptional Pet Appreciation Month results during this milestone year give us even more reason to celebrate the pet lovers we share memorable moments with every day.”

Pet Valu operations

Pet Valu has more than 800 corporate-owned or franchised locations across Canada and is headquartered in Markham, Ont. The company operates distribution centres in Brampton, Ont., Surrey, B.C., and Calgary, Alta.

The company says it offers more than 10,000 products through its stores and digital platform, including proprietary brands and other pet food and pet-related supplies.

More from Retail Insider: