Home Blog Page 6

Canadians plan to spend less on holidays as budgets tighten: survey

Gustavo Fring photo
Gustavo Fring photo

Canadians plan to spend an average of $911 on holiday shopping this year, down 6.5 per cent from 2025, as inflation, higher prices and economic uncertainty influence household budgets, according to a new survey by the Retail Council of Canada (RCC) and Leger.

The ninth annual RCC x Leger Holiday Shopping Survey found that 52 per cent of Canadians expect to spend about the same amount as last year, while 22 per cent plan to spend more and another 22 per cent expect to spend less. Despite more measured spending plans, 82 per cent of respondents said they were confident they could buy everything they planned to purchase.

The findings point to a holiday shopping season in which retailers may face consumers who are increasingly focused on promotions, comparing prices and planning purchases around major sales events, while continuing to prioritize gifts for family and friends.

Shoppers focus on value and major sales events

Inflation and higher prices are the leading factors influencing holiday spending plans, cited by 48 per cent of respondents. More than half, or 56 per cent, said Canadian economic instability or inflation was affecting their holiday outlook, up from 53 per cent last year. The same proportion said those factors were affecting their household finances.

Among respondents affected by economic conditions, 49 per cent said they would spend more time looking for deals, 39 per cent planned to start shopping earlier, 39 per cent intended to establish a budget and 36 per cent expected to rely on loyalty programs.

The survey found that 64 per cent of Canadians planned to look for more deals than in previous years, compared with 63 per cent in 2025. Meanwhile, 43 per cent said they put off purchases throughout the year to take advantage of major sale days, up from 39 per cent last year.

Black Friday remains a central part of holiday shopping plans. The survey found that 88 per cent of respondents ranked the Nov. 27 event among their top three shopping days, up from 84 per cent in 2025, while 52 per cent ranked it as their top shopping day.

Cyber Monday also gained ground, with 72 per cent ranking it among their preferred shopping days, compared with 64 per cent last year. Respondents expected Black Friday and the Cyber Monday and Cyber Week period to each account for about 29 per cent of their holiday budgets.

Most Canadians also planned to continue shopping at their usual retailers at least as much as they did during the previous holiday season. Grocery stores were favoured by 78 per cent of respondents, followed by big-box retailers at 75 per cent and discount stores at 69 per cent.
Andrea Piacquadio photo

Gifts for others take priority

Canadians are allocating a larger share of their holiday budgets to gifts for other people, even as planned overall spending declines. Gifts for others account for 86 per cent of expected holiday expenditures, up from 79 per cent in 2025, while purchases for themselves have fallen to 14 per cent from 21 per cent.

Immediate family members are expected to receive the largest share of spending, accounting for 64 per cent of planned holiday budgets.

The survey also found that 53 per cent of respondents considered giving a memorable or meaningful gift the most important factor when making a selection. By comparison, 23 per cent prioritized finding the lowest price, down from 25 per cent last year.

Clothing accounts for the largest share of planned gift spending at 19 per cent, up from 17 per cent in 2025. Gift cards remain steady at 16 per cent, while travel accounts for 8 per cent, up from 7 per cent.

Kim Furlong, President and CEO of the Retail Council of Canada, said shoppers were balancing their holiday plans with attention to value and personal relationships.

“Canadians are looking forward to the holidays, and they’re planning with purpose,” said Furlong. “They’re putting the people they love first, starting early and shopping smart for value. Retailers across the country are ready for them, with great deals, strong selection and more Canadian-made products that are easy to find.”
Online shopping grows, but physical stores remain important

Online purchases are expected to account for 42 per cent of Canadians’ holiday shopping budgets, up from 39 per cent last year. Physical stores will still account for the majority, at 58 per cent.

The survey found that 62 per cent of respondents planned to shop in stores because they wanted to see and touch products before buying them, up from 58 per cent in 2025.

Customer reviews also remain influential in purchasing decisions, with 80 per cent of respondents saying ratings and reviews were important when selecting holiday purchases. That proportion rose to 90 per cent among shoppers aged 18 to 34. Overall ratings were important to 45 per cent of respondents, while 40 per cent placed weight on written comments.

Artificial intelligence is also beginning to play a role in shopping plans, although relatively few consumers said they would rely on it to make gift decisions. About 31 per cent expected to use an AI tool for some part of their holiday shopping, most commonly to compare prices, cited by 21 per cent. Only 3 per cent said they would trust an AI assistant most when choosing a gift, while 47 per cent said they trusted their own judgment.

Interest in Canadian products remains strong

The survey found that 84 per cent of Canadians were more likely to purchase a gift clearly marked “Made in Canada,” unchanged from last year. However, price remains a consideration: 52 per cent of all respondents said they were more likely to buy Canadian-made products if the price was reasonable.

When asked what would make buying Canadian products easier, 58 per cent identified more affordable pricing as the leading factor.

U.S. politics, trade policy and geopolitical instability were also influencing shopping decisions, although their impact had eased from the previous year. Some 52 per cent of respondents said these issues affected their holiday outlook, down from 58 per cent in 2025. Among those affected, 58 per cent said they were avoiding U.S. brands and 57 per cent planned to support more local or Canadian-made businesses.

Regional spending plans vary

Alberta shoppers reported the highest average planned holiday spending at $1,184, down $9 from 2025. British Columbia followed at $993, down $136, while Ontario shoppers planned to spend $952, a decline of $143.

Manitoba and Saskatchewan had an average planned budget of $941, up $51 from last year. Atlantic Canada respondents expected to spend $868, down $44, while Quebec had the lowest planned spending at $664, an increase of $44.

The survey was conducted online by Leger for the Retail Council of Canada from Aug. 21 to Sept. 4, 2026, among a nationally representative sample of 2,500 Canadians aged 18 and older. It was conducted in English and French. The results are based on a non-probability online sample, meaning a margin of error cannot be calculated. Planned spending figures are self-reported and are not adjusted for inflation.

More from Retail Insider:
Amazon to hire 9,000 seasonal workers across Canada for holiday season

Amazon photo
Amazon photo

Amazon says it plans to hire 9,000 seasonal employees across Canada for the holiday season, with positions available at 55 sites and average hourly base wages of nearly $24, as the company prepares for increased demand for deliveries.

The jobs will be offered at fulfillment centres, sortation centres and delivery stations across the country. Amazon said seasonal employees will have access to select benefits from their first day, with opportunities to move into permanent positions and pursue longer-term careers.

“We’re proud to welcome thousands of new teammates into our network this holiday season,” said Chuck Cummings, director of customer fulfillment at Amazon Canada. “For many people, a seasonal role at Amazon is their first introduction to the company — and for some, it becomes the start of something much bigger. Our seasonal employees make a real impact during their time with us, and for those who stay on and grow into permanent roles, it can lead to longer-term careers they didn’t expect.”

Amazon increases wages for Canadian operations workers

The hiring announcement comes as Amazon increases pay for employees in its Canadian operations network. The company said it is investing more than $78 million in pay increases this year, raising the average hourly base wage by $1 to more than $26, a four per cent increase from the previous year.

For full-time employees working 40 hours a week, the new average hourly base wage translates to more than $54,000 annually, according to the company.

Seasonal employees will earn an average hourly base wage of nearly $24. Those who transition into permanent positions will join a compensation structure that includes annual wage reviews, Amazon said.

The company also offers benefits to seasonal employees from their first day, including mental health and well-being support through its Employee Assistance Program.

A new Employee Grocery and Daily Essentials Discount, which took effect Oct. 1, provides eligible employees with 10 per cent off online grocery and daily essentials purchases on Amazon.ca, with no cap on savings.

Regular full-time employees also receive extended health, dental and vision coverage from their first day, a registered retirement savings plan with employer matching, tuition support through the company’s Career Choice program and an Employee Prime Benefit, where available.

Career Choice covers the full cost of tuition for eligible employees pursuing post-secondary education, Amazon said.

Amazon photo
Amazon photo

How to apply for seasonal jobs

Amazon said seasonal positions will be posted on a rolling basis throughout the holiday season, with openings potentially filling quickly. Applicants can find available jobs and submit applications through hiring.amazon.ca.

The company said it hires directly and does not charge fees to apply for positions. It also warned job seekers about fraudulent offers and messages from individuals impersonating Amazon as hiring activity increases during the fourth quarter.

People interested in learning more about Amazon’s fulfillment operations can also register for a free tour of a nearby facility at amazontours.com.

More from Retail Insider:
JLL expert talks about the current retail landscape in Canada

JLL photo
JLL photo

Recently JLL released its Retail Market Dynamics Fall Report, highlighting that retail construction starts fell 44 per cent in 2026 to a decade low, with space under construction dropping to about five million square feet. 

As the pipeline shrinks, Canadian businesses may find it harder to secure retail space, particularly in growing communities where demand for everyday essentials is strongest, said JLL.

In a market where developers are scaling back, the projects that are succeeding are neighbourhood centres and general retail focused on storefront shopping and everyday needs, while malls and power centres are finding little traction, it noted.

Other key insights include:

  • While retail rents continue to rise, slower rent growth could bring retailers some relief, even as competition for well-located space stays strong: Annual asking rent growth has eased to 2.5 per cent from a peak of about five per cent in 2022, and effective rent growth has dipped slightly to three per cent. While leasing is still getting more expensive, limited new supply means well-located storefronts will remain competitive.
  • Grocery retail developments continue to be the overwhelmingly preferred anchor when it comes to daily-needs developments in Canada: Grocery stores anchored 96 per cent of daily-needs centres completed since 2022, up from 74 per cent between 2016 and 2021. Over the same period, mass merchandise anchors fell from 19 per cent to four per cent and pharmacy anchors dropped from seven per cent to none, as developers bet on the weekly grocery run to drive traffic.
  • High-growth suburbs and transit-oriented corridors are creating new retail opportunities: As population growth pushes into the suburbs, demand for everyday retail is following. Calgary has been Canada’s most active daily-needs development market over the past decade, with Toronto and Edmonton close behind, while new transit projects like Toronto’s Ontario Line, Vancouver’s Broadway Subway and Montréal’s REM are bringing fresh foot traffic to key corridors.

In an interview with Retail Insider, Paul Ferreira, Senior Vice President, Retail at JLL, offered some insights about the market and the report.

What is driving the 44 per cent decline in Canadian retail construction starts in 2026, and what does the decade-low level of new construction indicate about the outlook for retail space?

There are a combination of factors. Firstly, in many markets across Canada new projects just have not been penciling for some time. Development costs including land, construction and municipal reached a point where the rents many retailers can afford to pay can’t support the pro-formas.  

We also saw a period in recent years where many of our existing shopping centres were deemed mixed-use redevelopment opportunities and many landlords prioritized preserving their future flexibility to redevelop these properties over committing to new long-term deals or adding new retail space. Many municipalities themselves have been encouraging this trend while at the same enacting planning policies that discourage traditional single-story retail that is often preferred by retailers.  

At the same time a significant portion of the pipeline of new retail space in our major markets was proposed within new mixed-use projects. Part of the fallout of the collapse in the high-rise residential development sector is also the delivery of new retail space in those same mixed-use projects.

The decade low level of construction is more a byproduct of the fallout in the residential development market together with the increasing input costs to develop and construct in this era. The overall demand for retail space is still strong. 

With only about five million square feet of retail space under construction, which types of retailers and markets are likely to face the greatest challenges securing well-located space as the supply pipeline shrinks?

Our major markets will continue to feel the retail supply squeeze as there does not seem to be much moderation in costs and many landlords seem prepared to ride out the development cycle until mixed use projects work again rather than make new long-term commitments to more traditional retail projects.  

Why are neighbourhood and daily-needs centres attracting more development activity than malls and power centres, and what does this shift tell us about how Canadian consumers are shopping?

Developers are concentrating on necessity-based formats anchored by grocery, pharmacy, and discount stores as these retail categories have historically demonstrated exceptional resilience and as a result this asset class continues to outperform other retail asset types.  

This shift reveals that Canadian consumers prioritize convenience, value, and frequency and continue to value the bricks and mortar shopping experience in these retail categories. Combining grocer, pharmacy, and discount retailers captures recurring household needs in a single trip, aligning with how families allocate spending today in the face higher costs, and time scarcity.   

Grocery stores anchored 96 per cent of daily-needs centres completed since 2022. What is driving the growing dominance of grocery as a retail anchor, and how is this affecting the tenant mix and design of new developments?

Grocery stores anchored 96% of daily-needs centres completed since 2022, up from 74% between 2016-2021, driven by grocery’s unmatched performance through economic volatility, consistent cash flow generation, and predictable foot traffic across all income segments. The pandemic solidified grocery-anchored assets as low-risk, institutionally favored investments, strengthening conviction as discretionary retail faces headwinds from e-commerce and cautious consumer spending.  

This dominance is reshaping developments toward compact, efficiency-driven layouts maximizing inline synergies with complementary necessity tenants—pharmacies, dollar stores, quick-service dining—rather than discretionary concepts. Western markets build larger formats with broader anchor mixes while Eastern centres trend toward tighter, higher-density configurations, with discount stores present as complementary anchors in over one-third of new centres, reinforcing the value orientation driving development. 

Ron Lach photo
Ron Lach photo

Which Canadian markets and emerging suburban or transit-oriented corridors offer the strongest opportunities for retail development over the next several years, and what factors will determine whether those opportunities translate into new projects?

Calgary, Toronto, and Edmonton, representing nearly half of all daily-needs centres built over the past decade, remain the most active markets, with high-growth suburban corridors including Northeast Calgary, South Edmonton, Halton Region, and Surrey-Langley offering the clearest near-term opportunities due to rapid residential construction, accessible land, affluent demographics, and sub-2% vacancy. Long term, the biggest factors in seeing new projects get off the ground will be a return of the mixed-use high rise development market in our major markets and sustained population growth and relative moderation of costs in our smaller markets.

Transit-oriented corridors present compelling medium-term plays: Vancouver’s Broadway Corridor has catalyzed 8,400+ new homes and 1.9 million square feet of development since 2022, while Toronto’s Ontario Line, Montréal’s REM airport connection, and Ottawa’s O-Train extensions will channel foot traffic to major retail strips. 

More from Retail Insider:
Nintendo and EB Games Detail Strategy Behind Toronto Store-Within-a-Store

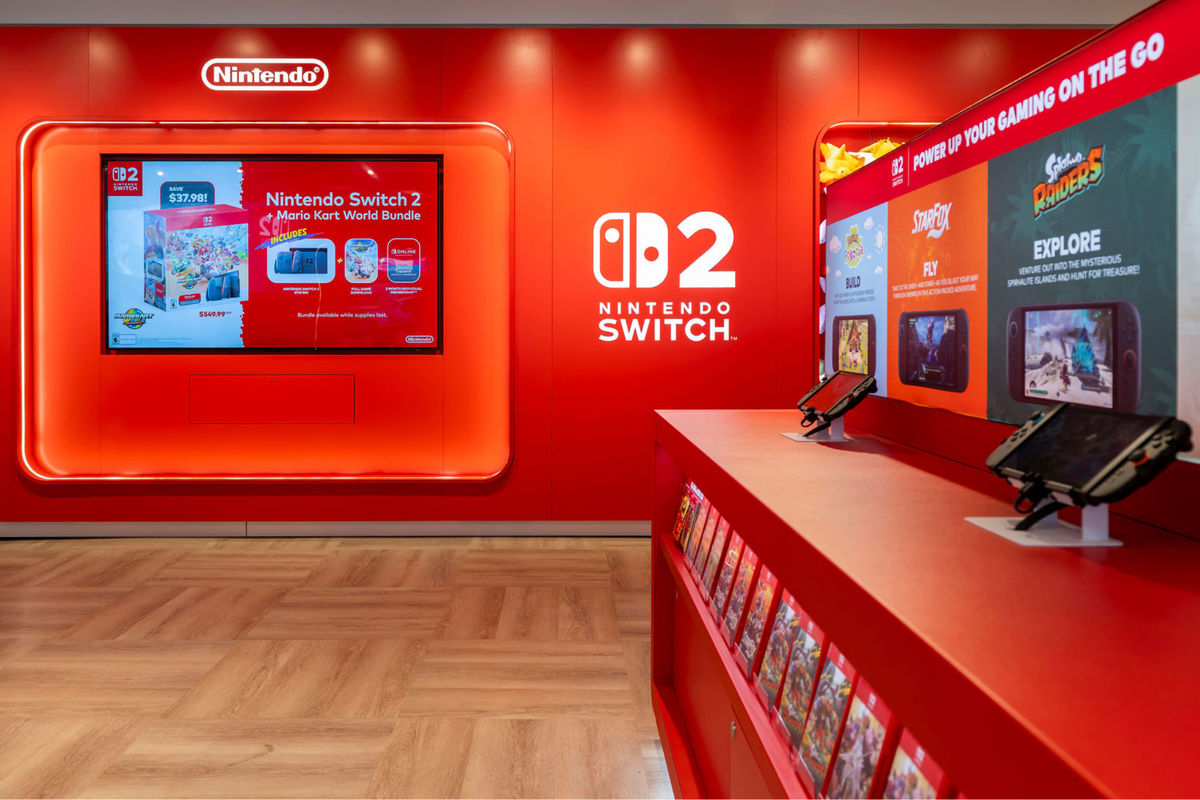
Nintendo store-in-store at EB Games, 267 Yonge Street, Toronto. Photo: Arthur Mola Photography

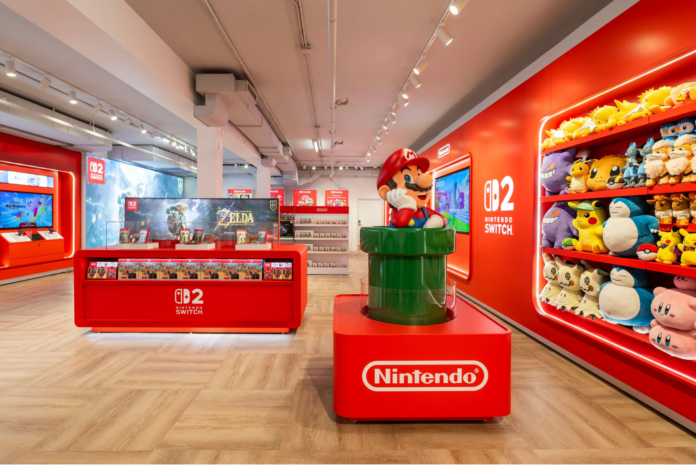
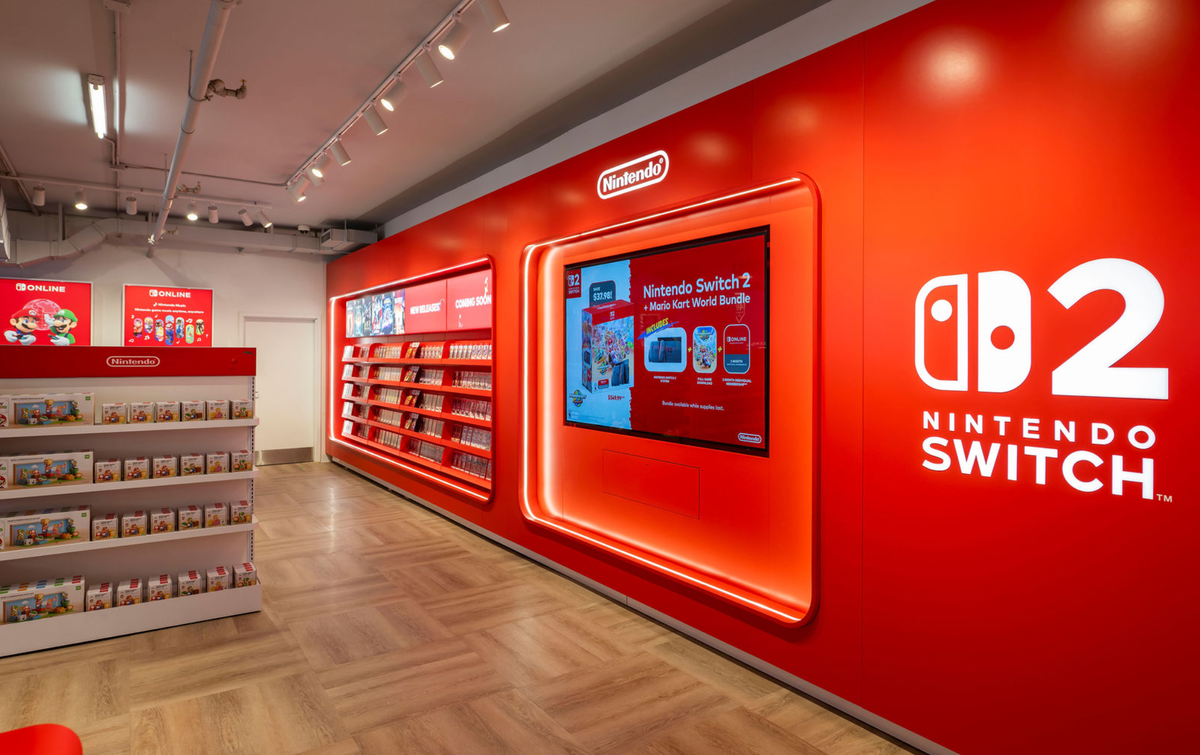
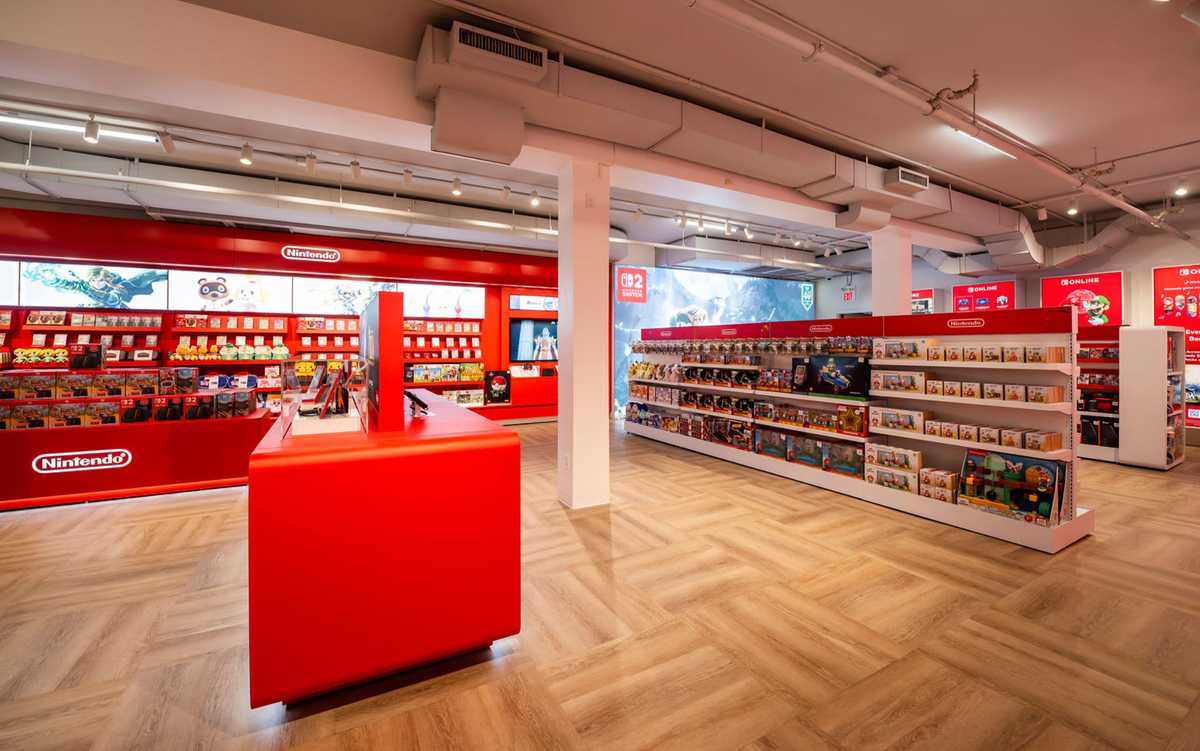
Nintendo has opened its first North American store-within-a-store at EB Games Canada’s flagship in downtown Toronto, introducing a permanent 1,500-square-foot retail space featuring gaming hardware, software, exclusive merchandise and interactive demonstrations.

The new space, which opened October 17 at 267 Yonge Street, marks an important partnership as EB Games Canada continues developing its retail business following its return to Canadian ownership in 2025. For Nintendo, the installation provides a dedicated branded presence within an established specialty gaming retailer, allowing customers to experience its products firsthand.

Jim Tyo, President of EB Games Canada, and Susan Pennefather, Vice President and General Manager of Nintendo of Canada, discussed the decision to launch the concept in Toronto, their longstanding partnership and the role of physical stores in the gaming industry with Retail Insider.

The opening comes ahead of the holiday shopping season, with Nintendo Switch 2 hardware and software central to the new space. It also adds a prominent attraction to EB Games’ Yonge Street flagship, located across from CF Toronto Eaton Centre.

Why Nintendo Chose Toronto

Nintendo selected Toronto for its first North American store-within-a-store partly because of its established relationship with EB Games and the Canadian gaming community.

“Canada has a passionate Nintendo community, and we’re proud that Nintendo’s first store-within-a-store in North America is opening here in Toronto,” said Pennefather. “EB Games has been an incredible, longstanding partner—from midnight launches to the launch of Nintendo Switch 2, making them the right partner for this experience.”

The installation occupies part of EB Games’ existing flagship at 267 Yonge Street, one of downtown Toronto’s busiest shopping corridors. The location benefits from its proximity to CF Toronto Eaton Centre, Toronto Metropolitan University and the surrounding commercial and entertainment district.

Nintendo store-in-store at EB Games, 267 Yonge Street, Toronto. Photo: Arthur Mola Photography

The store has also hosted major gaming events, including midnight product launches and activities surrounding the Nintendo Switch 2 introduction. Tyo said that history made it a natural choice for the permanent Nintendo space.

“EB Games’ flagship Toronto location gives Nintendo a permanent, dedicated presence in a high-profile gaming destination,” he said. “From midnight game launches to hosting the launch of the Nintendo Switch 2, we’ve celebrated so many milestone events together at this location that it was the perfect fit for a dedicated Nintendo experience where people already come to discover, shop, and engage.”

Nintendo already operates two standalone retail stores in the United States, including its longstanding flagship at Rockefeller Plaza in New York City and a San Francisco location that opened in May 2025. Both stores are devoted to Nintendo products, merchandise and interactive experiences.

Toronto introduces a different format, establishing a permanent Nintendo-branded environment inside an existing specialty gaming retailer. The arrangement gives Nintendo a substantial retail presence while drawing on EB Games’ established operations and customer relationships.

Nintendo store-in-store at EB Games, 267 Yonge Street, Toronto. Photo: Arthur Mola Photography

Nintendo Partnership Adds to EB Games Canada’s New Direction

The opening follows the May 2025 acquisition of GameStop’s Canadian operations by entrepreneur Stéphan Tétrault, bringing the business back under Canadian ownership.

Following the transaction, the retailer restored the EB Games name and outlined plans to strengthen its connection with Canadian gaming consumers. Its priorities included gaming culture, collectibles, merchandise and customer experiences, reflecting the importance of product categories beyond physical video games.

EB Games Canada operates more than 170 stores nationally, providing an established network serving gaming enthusiasts and collectors. The Toronto flagship is among its most prominent locations and now houses a permanent branded installation from one of the industry’s largest gaming companies.

The Nintendo partnership provides an example of how EB Games can develop its physical retail offering through relationships with major manufacturers. Dedicated merchandising, playable demonstrations and exclusive products give customers reasons to visit specialty gaming stores, particularly when many games and related products can be purchased online.

Tyo said the companies’ longstanding relationship was central to the project.

“Nintendo and EB Games have a longstanding relationship in Canada and share a commitment to creating great experiences,” he said. “Bringing Nintendo’s first store-within-a-store in North America to EB Games’ flagship Toronto location brings together iconic games, characters, and experiences with EB Games’ retail expertise.”

The arrangement also gives Nintendo a dedicated retail environment within an established Canadian business. Neither company has disclosed the capital investment involved, the commercial terms governing the space or specific financial targets associated with the installation.

Nintendo store-in-store at EB Games, 267 Yonge Street, Toronto. Photo: Arthur Mola Photography

Inside the New Nintendo Experience

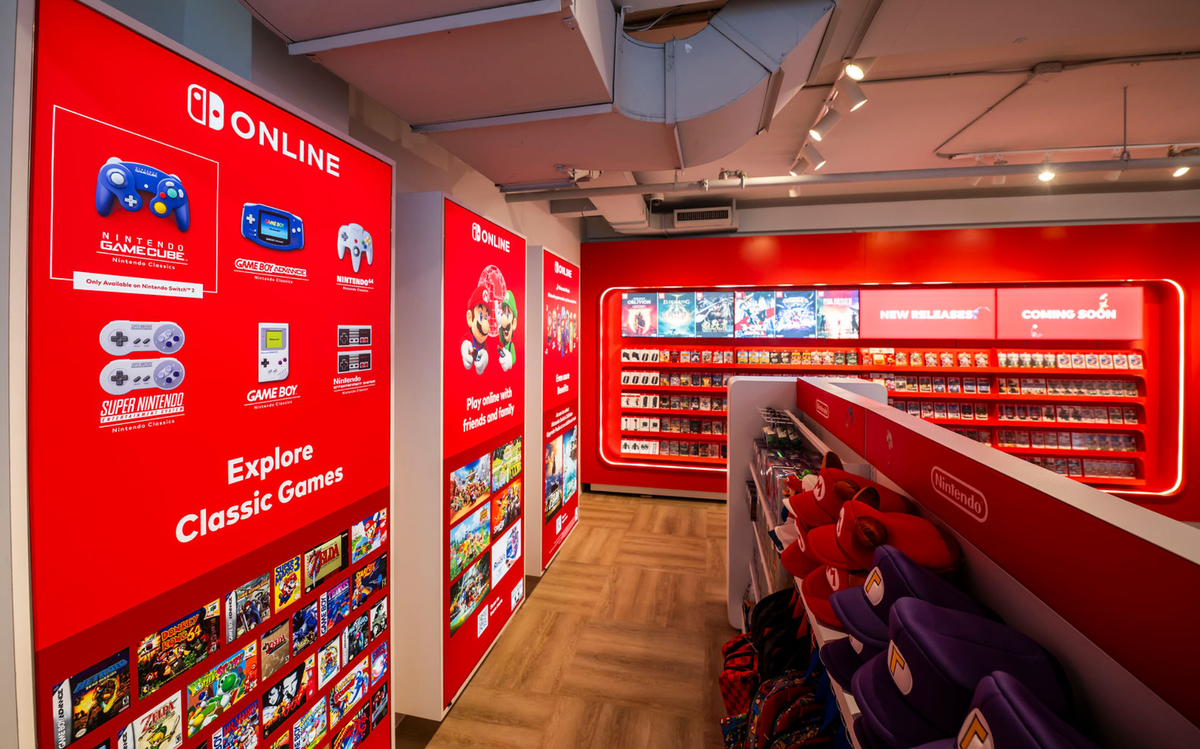
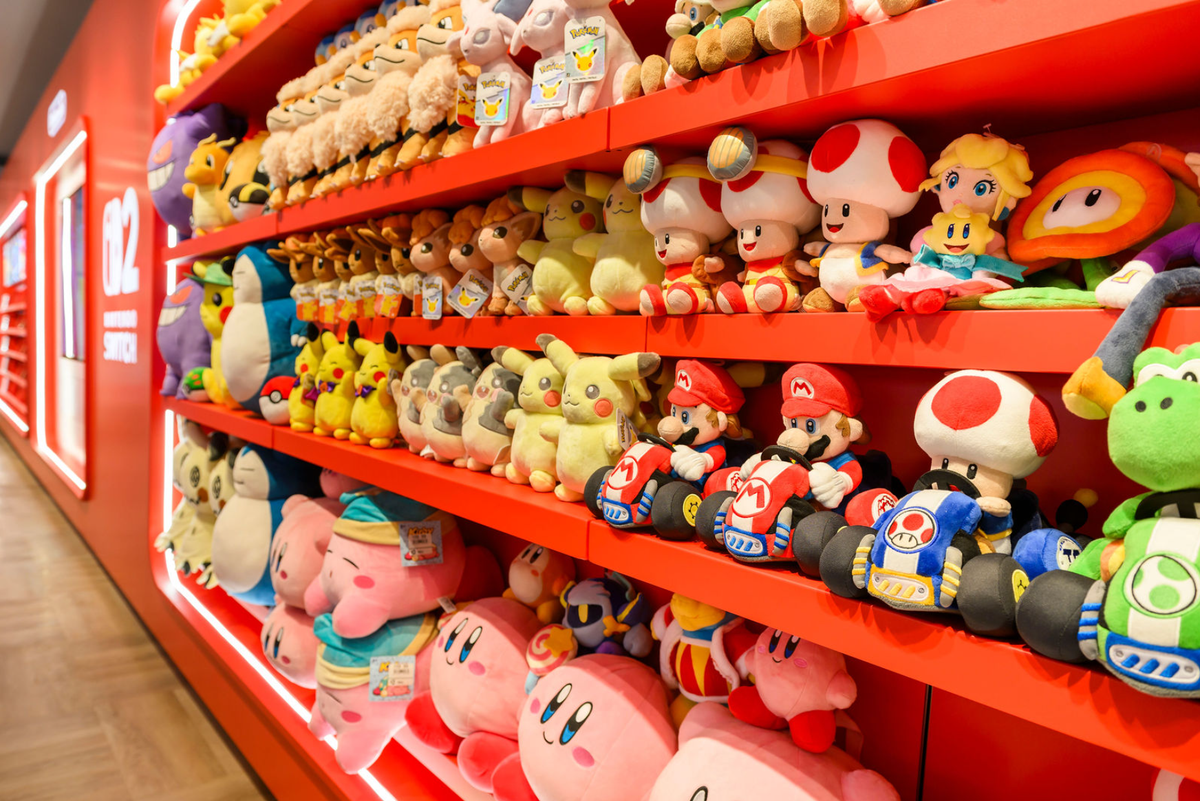
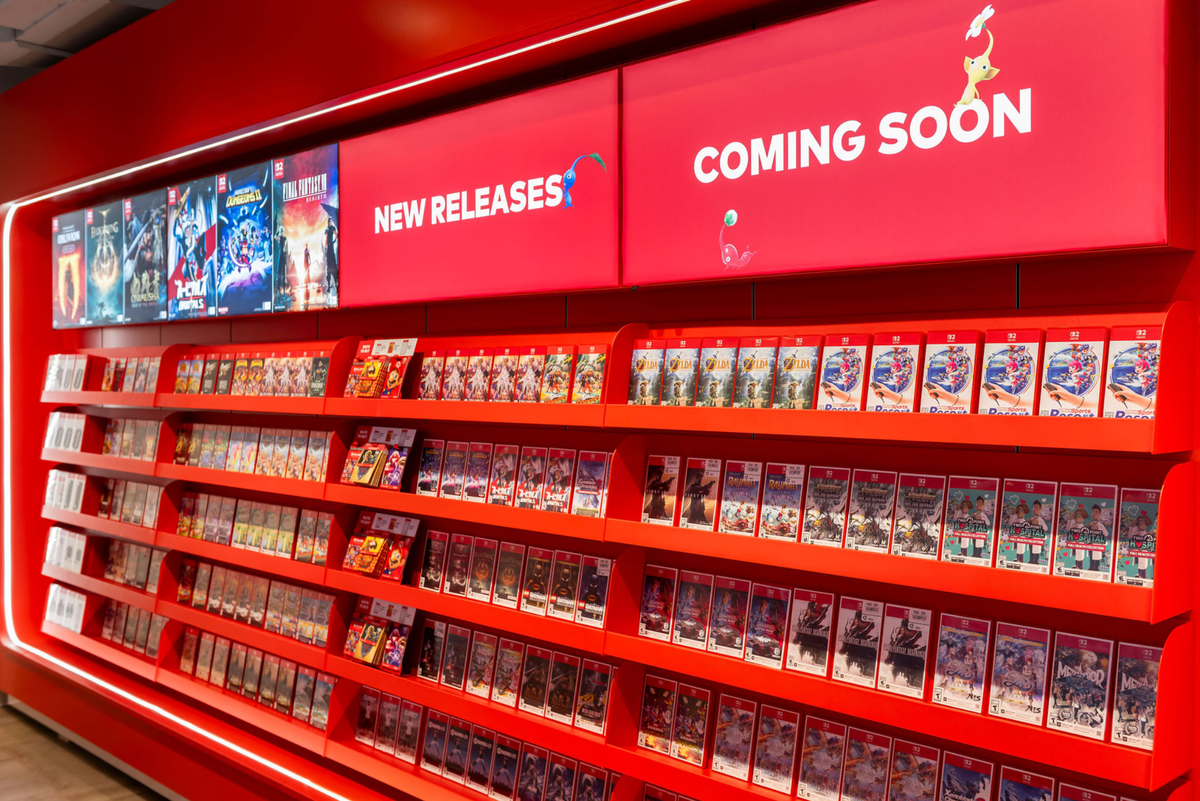
The permanent Nintendo environment features Nintendo Switch 2 hardware and software, playable demonstration stations, themed displays and a selection of branded merchandise.

Customers can try games, explore products and browse merchandise associated with Nintendo’s established franchises and characters. The assortment includes items exclusive to the Toronto installation, including the My Mario Mario & Friends Wood Block set.

The space is designed to accommodate new games and merchandise as Nintendo releases additional products, giving customers reasons to return throughout the year. Changing assortments and displays could help maintain interest beyond the initial opening period.

For Nintendo, the timing is relevant as the company continues promoting Nintendo Switch 2, which launched in 2025. Customers can experience the hardware and its games before purchasing, while exploring available software and system bundles.

“The space gives Canadians an opportunity to experience Nintendo Switch 2 firsthand, try playable demos of our newest games, and discover system bundles,” Pennefather said.

The opening included special promotional offers, including Nintendo eShop gift cards with qualifying purchases. The offers were available to customers shopping at the Yonge Street location on October 17.

The dedicated environment brings hardware, software and character-related merchandise together in one branded area. For EB Games, the assortment also creates opportunities for complementary purchases involving games, accessories and collectibles.

Nintendo store-in-store at EB Games, 267 Yonge Street, Toronto. Photo: Arthur Mola Photography

Physical Retail Remains Important to Both Companies

The Nintendo partnership comes as digital distribution continues to play a major role in the gaming industry. Consumers can purchase software through online storefronts, while specialty gaming retailers have expanded their assortments to include collectibles, accessories and other merchandise categories.

Both Nintendo and EB Games maintain that physical stores provide opportunities for product discovery and customer engagement that differ from online purchasing.

“Physical retail offers something different from simply purchasing online,” said Pennefather. “Being able to play, explore, and discover Nintendo in person creates a different kind of connection with consumers.”

Playable demonstrations are particularly useful for gaming hardware, where customers may want to evaluate a product before making a purchase. The Toronto installation also allows families, collectors and gaming enthusiasts to interact with Nintendo products and merchandise in one location.

The space offers opportunities for EB Games to attract customers, encourage longer visits and introduce shoppers to products they may not have originally intended to purchase. However, the companies have not provided traffic, sales or conversion projections for the installation.

The format demonstrates how a specialty retailer can dedicate part of an existing store to a major brand partner. Nintendo gains a permanent branded environment supported by EB Games’ retail operations, while EB Games adds a destination that can evolve alongside Nintendo’s product releases.

The commercial results will depend on customer response over time, including repeat visits and purchases beyond the initial opening period. No performance data has yet been disclosed for the Toronto installation.

Nintendo store-in-store at EB Games, 267 Yonge Street, Toronto. Photo: Arthur Mola Photography

Could the Concept Expand Beyond Toronto?

Although Toronto is Nintendo’s first North American store-within-a-store, neither company has announced plans for additional locations in Canada or the United States.

Both executives indicated that their immediate priority is establishing the Toronto installation as a destination for gaming enthusiasts. When asked how EB Games would measure success and whether the concept could be introduced elsewhere in its Canadian network, Tyo emphasized customer engagement and repeat visits.

“Success is about creating a space people love and want to revisit, somewhere they can discover what’s new and enjoy something memorable,” he said.

Tyo added that EB Games continues to explore ways to connect with consumers but is currently focused on making the Toronto installation successful.

EB Games’ national network provides an established retail platform that could accommodate similar partnerships if the companies eventually decide to expand the concept. No rollout has been confirmed, and neither company has disclosed the performance benchmarks that would inform such a decision.

For now, the Yonge Street flagship gives Nintendo and EB Games a permanent location to introduce new products and develop their partnership. The companies have left open the possibility of future initiatives without committing to another store-within-a-store.

Nintendo store-in-store at EB Games, 267 Yonge Street, Toronto. Photo: Arthur Mola Photography

More From Retail Insider

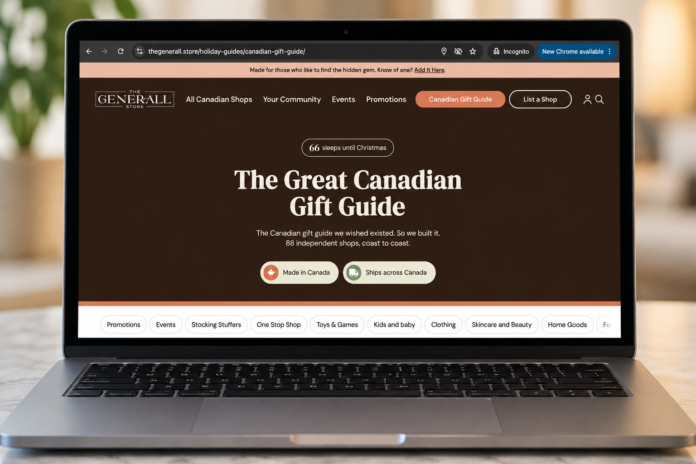
The Generall Store Launches National Gift Guide Featuring 88 Independent Canadian Retailers

The Generall Store has launched a national holiday shopping guide featuring 88 independent Canadian retailers, including 60 businesses that make the products they sell in Canada. The initiative is part of founder Lisa Tyldesley’s effort to help consumers discover smaller retailers, including those operating outside major urban centres.

The Great Canadian Gift Guide, launched in October ahead of the Christmas shopping season, features businesses from all ten provinces and the Northwest Territories. According to The Generall Store, all 88 participating retailers ship across Canada, making their merchandise available to customers beyond their local markets.

The guide builds on The Generall Store’s existing online platform, which allows independent businesses to create free listings, promote events and post special offers. Its community pages organize shops and activities geographically, giving consumers a central place to look for businesses and events in their area.

A National Guide to Independent Canadian Retailers

Tyldesley developed The Generall Store after becoming frustrated with the difficulty of finding information about local businesses and community events. She frequently searched through Facebook groups, Instagram accounts, municipal websites and Business Improvement Area pages, often struggling to relocate information she had previously encountered.

A conversation with her sister, who lives about an hour away and had experienced similar difficulties, helped convince her that the problem extended beyond her own community.

“If it was not just me, it was worth building,” Tyldesley told Retail Insider. “The name is a nod to the old general store, the one place a town went for everything. That is what I want it to be.”

The holiday guide includes merchandise across categories such as home goods, food, accessories and gifts. Ontario accounts for 37 participating businesses, followed by British Columbia with 18 and Quebec with nine. The remaining retailers are distributed across the other provinces and the Northwest Territories.

According to Tyldesley, 23 participating businesses are verified women-owned and five are Indigenous-owned. She said the guide’s retailers were checked manually against their websites to establish where products are made and whether they ship across Canada.

Among the businesses featured are Grohmann Knives, a longstanding knife manufacturer in Pictou, Nova Scotia; Old Town Glassworks in Yellowknife; and a trading post at Eel River Bar First Nation in New Brunswick. Tyldesley said identifying businesses in smaller communities was an important part of assembling a guide with national representation.

“The makers are there. They are just hard to find, and that is the part we are trying to fix,” she said.

The guide was released in October because many independent retailers produce merchandise in small batches, with popular products sometimes selling out or closing for pre-orders before December. Business owners may also be responsible for their own photography, marketing, customer service and shipping, making advance holiday purchases particularly important.

Making Local Businesses Easier to Find

Beyond the gift guide, The Generall Store operates community-specific pages featuring independent retailers, food and beverage businesses, experiences, events and promotions. Participating businesses can manage their listings and post upcoming activities through free accounts.

The directory organizes listings by location, giving smaller businesses a way to appear alongside other retailers in their communities without competing for placement through a social media algorithm. Tyldesley sees that geographic approach as particularly useful for shops that lack the marketing resources of larger retailers.

For independent businesses, the directory provides another potential way to reach customers. Its effectiveness will depend on participation from retailers, the accuracy of their information and whether consumers regularly use the platform to find local shopping opportunities.

The holiday guide takes that approach nationally, introducing shoppers to merchandise from businesses they may be unlikely to encounter through their usual shopping channels. It also includes seasonal events and markets, connecting holiday shopping with activities taking place in Canadian communities.

Building a Free Platform for Shops and Communities

Business listings, retailer dashboards and the ability to post events and promotions are free on The Generall Store. Tyldesley said those core services will remain free as she explores advertising opportunities to support the platform financially.

“Listing a business is free, and that’s not changing,” she said. The company is considering paid promotional opportunities for independent retailers seeking additional exposure, as well as Business Improvement Areas and municipalities interested in promoting local shopping and tourism.

The approach is intended to keep participation accessible to businesses with limited marketing budgets. The Generall Store has not provided figures demonstrating the platform’s impact on retailer sales or details establishing an ongoing advertising revenue stream.

Tyldesley acknowledged that independent businesses often struggle to compete with major chains and online marketplaces on shipping costs, delivery times and return policies. She believes smaller retailers can distinguish themselves through personal service, distinctive merchandise and relationships with their customers.

For the holiday guide, identifying where products are made and who owns the participating businesses was an important part of the selection process. That information can otherwise require consumers to research individual retailers before making purchasing decisions.

Tyldesley plans to introduce additional shopping guides, expand the number of communities represented on the platform and develop new features based on feedback from participating businesses. Those conversations will help determine which services The Generall Store introduces next.

Aritzia Could Target $10 Billion in Revenue as Stifel Examines Next Phase of Growth

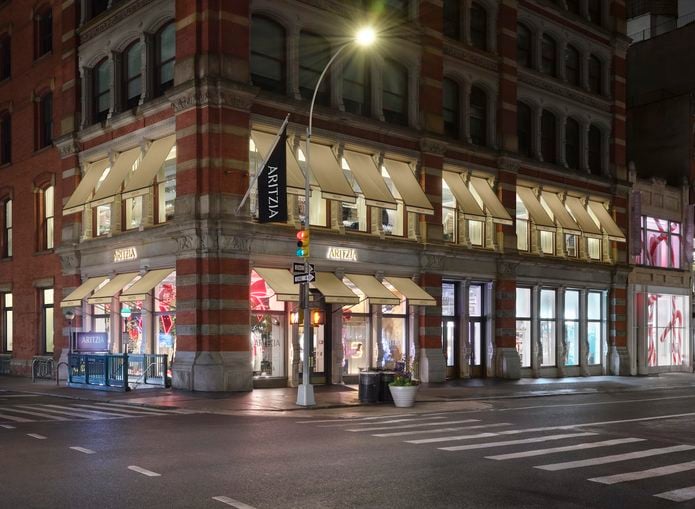
Aritzia flagship store in the Soho District in New York City. Image: Aritzia

Canadian fashion retailer Aritzia could unveil a long-term revenue target approaching $10 billion when it holds its Investor Day on October 27, according to an analysis from Stifel. The potential target comes as the Vancouver-founded company approaches $5 billion in annual sales, supported by rapid expansion in the United States and growing investment in large-format flagship stores.

Martin Landry, Managing Director at Stifel, outlined expectations for the event in an October 19 research report. He anticipates that Aritzia could establish a fiscal 2032 revenue target of between $9 billion and $10 billion, representing annualized growth of approximately 13% to 15% from fiscal 2027.

Martin Landry, Managing Director at Stifel

The projections follow several years of growth that have already taken Aritzia beyond the objectives presented at its previous Investor Day in 2022. At that time, the company targeted annual revenue of $3.5 billion to $3.8 billion by fiscal 2027, a figure it is now expected to exceed by approximately $1 billion.

Aritzia’s latest financial results illustrate the pace of its expansion. Revenue increased 44.1% to approximately $1.17 billion in the second quarter of fiscal 2027, with comparable sales rising 34.5% and strong performances across physical stores and e-commerce.

The United States accounted for $779.4 million in quarterly revenue, an increase of approximately 60%, while Canadian sales rose nearly 20% to $390.4 million. Management expects full-year revenue of between $4.78 billion and $4.88 billion, representing growth of approximately 29% to 32%.

With annual sales approaching $5 billion, Aritzia is preparing its next growth plan from a considerably larger base. The company will need to demonstrate how it intends to maintain momentum through additional stores, increased productivity and opportunities in new markets and merchandise categories.

U.S. Expansion and Larger Flagship Stores

The American market remains central to Aritzia’s expansion strategy. The company operated 79 U.S. boutiques as of August 31, 2026, and Stifel’s analysis suggests that the network could eventually exceed 180 locations.

Aritzia has also been investing in substantially larger retail spaces, particularly in prominent urban shopping districts. These stores accommodate expanded merchandise assortments and give the company greater visibility in markets where it is building its customer base.

In Chicago, Aritzia secured approximately 46,000 square feet at 555 North Michigan Avenue on the Magnificent Mile. Announced in 2022, the lease was described at the time as the company’s largest planned store and represented a significant commitment to one of the city’s best-known shopping streets.

In Manhattan, Aritzia secured a multilevel location at 608 Fifth Avenue, in space previously occupied by Topshop. The property was reported to encompass more than 33,000 square feet, adding another substantial location to the retailer’s New York presence.

The larger format allows Aritzia to display more merchandise and potentially introduce additional product categories over time. These stores also require sufficient sales volumes to support their higher occupancy, staffing and operating costs, making productivity an important consideration as the company expands.

Aritzia is pursuing large-format retail in Canada as well. In downtown Vancouver, the company has plans for an approximately 42,000-square-foot flagship in part of the former Nordstrom premises, extending its investment in prominent retail destinations.

The retailer’s expansion has made it an increasingly important tenant for commercial landlords across North America. Its appetite for large stores is particularly relevant in markets where former department store locations and other substantial retail premises are being repositioned for new occupants.

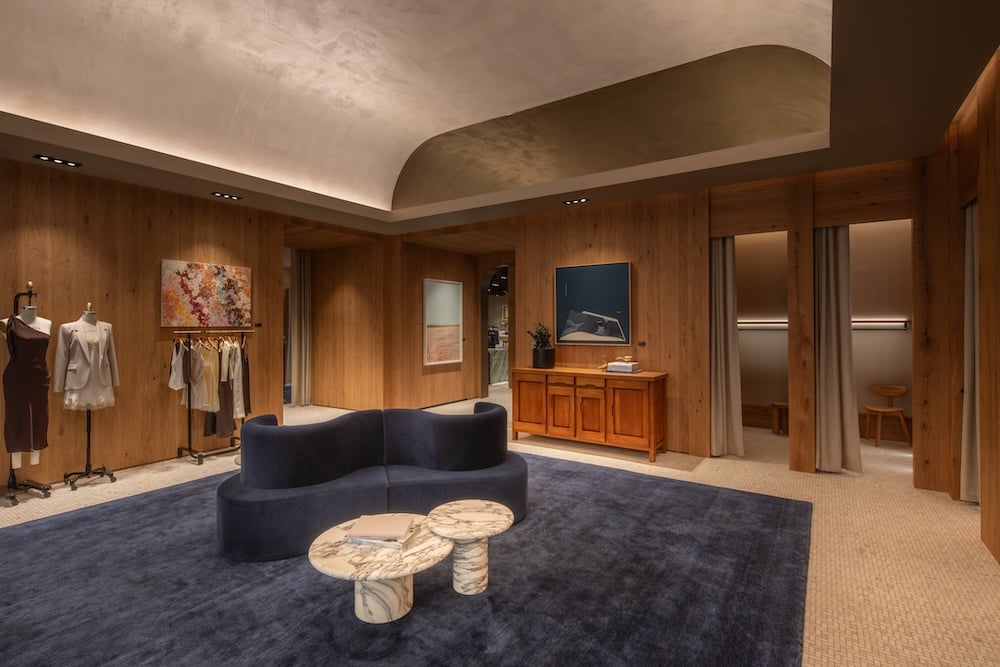
Aritzia store at Plaza Frontenac in St. Louis. Image: Aritzia

Menswear Has Been a Small Part of Aritzia’s Strategy for Years

Menswear is another potential area of growth, and one Aritzia has explored in different forms for several years. Its involvement began well before the acquisition of Reigning Champ, including efforts to introduce male customers to some of its existing products.

In 2019, Aritzia launched Mr. Super Puff, a men’s version of its popular outerwear jacket. Management subsequently indicated that initial demand had exceeded expectations, providing an early indication that the brand could attract customers beyond its established womenswear business.

Aritzia expanded its presence in menswear in 2021 when it acquired a 75% interest in Vancouver-based Reigning Champ. The premium athletic apparel brand, known particularly for its men’s clothing, gave Aritzia an established business with its own customer base and merchandise assortment.

At the time, Aritzia publicly described the acquisition as an acceleration of its expansion into men’s apparel. Reigning Champ continued to operate as a separate brand, providing a presence in the category without requiring Aritzia to introduce a full men’s collection under its main retail banner.

Around the time of the acquisition, sources told Retail Insider that discussions had taken place about the possibility of introducing a broader Aritzia menswear offering. Those discussions contemplated opportunities beyond the company’s existing outerwear products and the separately operated Reigning Champ business.

Aritzia has not announced plans for a comprehensive menswear collection under its principal banner. Its history with Mr. Super Puff and Reigning Champ nevertheless demonstrates that the company has considered male customers a potential growth opportunity for some time.

The subject has also attracted investor interest ahead of the upcoming Investor Day. In Stifel’s survey of 32 institutional investors, 41% favoured a more aggressive approach to menswear expansion, while 59% were satisfied with the company’s existing strategy involving Reigning Champ.

Aritzia’s increasingly large stores could provide flexibility to accommodate additional merchandise categories in the future. There is no confirmed connection, however, between its major flagship leases and any plan to introduce a broader menswear assortment.

International Expansion Remains a Key Question

Investors will also be watching for indications of when Aritzia might establish a physical retail presence outside North America. The company has built much of its recent growth through the United States, where it continues to see opportunities for additional boutiques.

Stifel’s institutional investor survey found that 53% of respondents expected Aritzia’s first store outside North America to open in calendar 2028, while 31% anticipated an opening in 2027. The findings indicate considerable interest in international expansion as a possible contributor to the company’s longer-term growth.

Landry takes a more cautious view of the timing, given the substantial opportunity that remains in the American market. Continuing to prioritize the United States would allow Aritzia to build on its existing operating infrastructure, distribution network and customer relationships before committing resources to new international markets.

Overseas expansion would introduce additional considerations, including real estate selection, logistics and differences in consumer preferences. Management has yet to outline a confirmed international store rollout, making the October 27 event an opportunity to clarify its intentions.

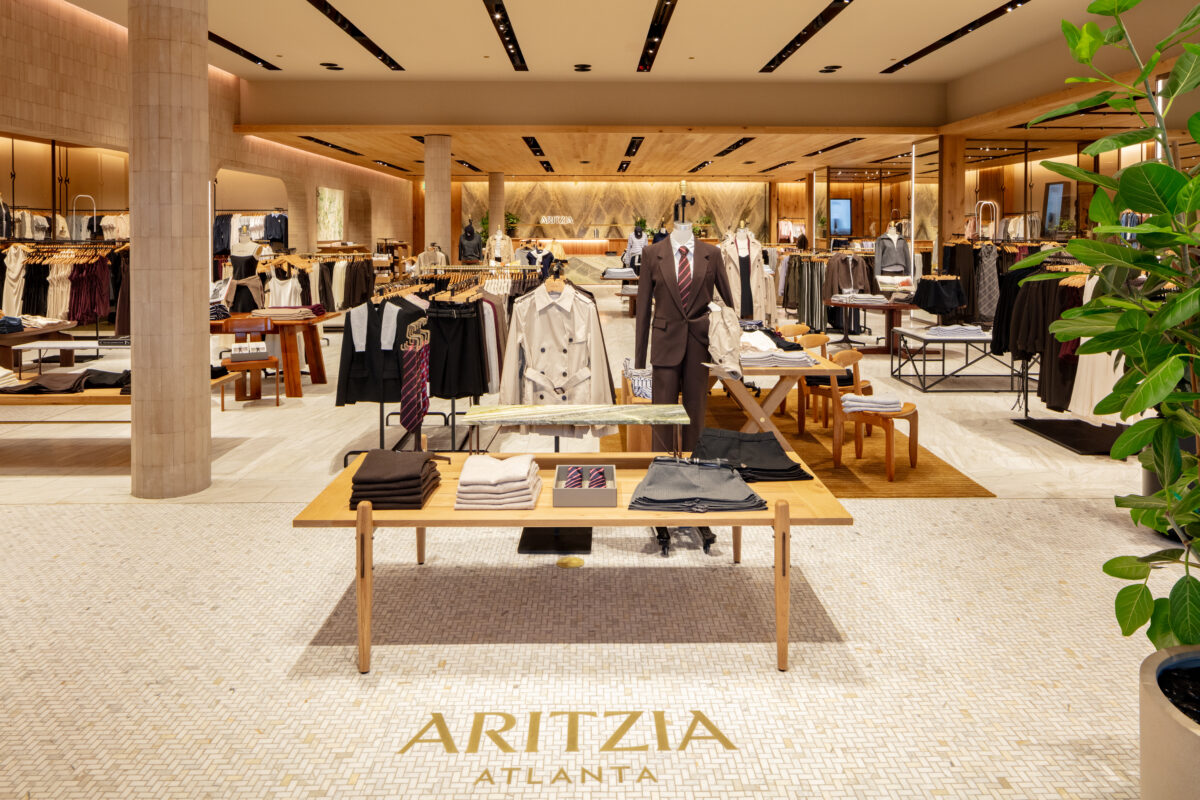
Aritzia Atlanta. Photo: Aritzia.

Profitability and Capital Allocation

Alongside revenue growth, Aritzia’s next five-year plan is expected to address profitability and the capital required to support its expansion. The potential margin target would give investors another benchmark for evaluating the retailer’s next stage of growth.

Stifel anticipates that management could establish a fiscal 2032 adjusted EBITDA margin target of approximately 22.5%. That would represent further improvement from the approximately 20% margin contemplated in Aritzia’s fiscal 2027 outlook, compared with 17.8% in fiscal 2026.

Higher sales volumes, improved merchandise margins and more efficient use of operating infrastructure could support profitability as the business grows. At the same time, new flagship stores, distribution investments and potential international expansion will continue to require capital.

Shareholder returns could also receive attention. Stifel’s survey found that 59% of respondents favoured the introduction of a dividend within the next 12 to 18 months, although Landry expressed a preference for share repurchases.

Aritzia has not announced a dividend in connection with Investor Day. Its capital allocation decisions will need to account for the costs of continued expansion and investments in its retail operations.

Canadian Business Continues to Grow

Although the United States now accounts for approximately two-thirds of Aritzia’s quarterly revenue, the company’s Canadian business continues to expand. Sales in Canada increased nearly 20% to $390.4 million during the latest quarter, demonstrating continued demand in a market where the retailer already has an established store network.

Canada remains an important part of Aritzia’s operations, including its brand development and merchandising activities. The company has grown from its Vancouver origins into a much larger North American fashion retailer, with the American business now providing much of its incremental growth.

The October 27 Investor Day should offer greater clarity on management’s expectations for additional American boutiques, the potential timing of international expansion and longer-term profitability targets. It may also provide insight into how the company intends to develop its merchandise offering as its retail network grows.

For commercial landlords and retail industry observers, Aritzia’s physical store strategy will be particularly important. Its decisions about future locations, store sizes and product categories will help determine how the company approaches the scale anticipated in Stifel’s analysis.

More From Retail Insider

TJL Collection Cuts Customer Acquisition Costs With Targeted Marketing for Tall Women

One of the biggest challenges facing a brand that sells clothing for tall or plus-size women is targeting customers by height or size, something a small startup often can’t afford to solve the way a big brand could by building out an experienced marketing team.

Tiffany Jones, a 6’1″ Navy veteran, founded TJL Collection, a clothing brand for women over 5’9″. After years of being unable to find stylish clothes that fit her own frame, she started sewing her own before launching her own brand.

TJL then ran into that exact targeting problem: without height as an option on ad platforms, the brand kept reaching people who liked its photos but weren’t actually its customers. In 2023, Jones hired Sarah S, a freelance digital marketer on Fiverr, to rebuild TJL’s approach around signals that actually predicted a buyer instead, like shopping habits and content engagement. Sarah also tested different creative, founder-led videos, testimonials, and product shots, to see what converted rather than what just got likes.

Since then, the two have worked together on and off for about $10,000 total, a fraction of a full-time salary, and TJL has cut customer acquisition cost nearly in half, from $38 to $18 per customer, while growing annual revenue from $475,000 in 2025 to a projected $800,000 this year.

Jones’s story is one of the case studies behind Fiverr’s Holiday Marketing Index, a new survey of hundreds of freelancers, examining how businesses are hiring for search, content, and e-commerce ahead of the holidays. 

In an interview with Retail Insider, Jones spoke about the brand and the initiative.

How did TJL Collection’s difficulty targeting women by height or size affect your marketing efforts and customer acquisition before you changed your approach?

Height was not collected in the typical data we could use to run ads. We knew how to target by age, location and other demographics, but we couldn’t simply ask an ad platform to find women who were 5’9” or taller. We had to get creative to make sure our marketing stood out to the right women.

We kept hearing the same questions from tall women: “What’s the inseam?” “I’m 6’2”. Will it fit me?” They were the same questions I would ask as a 6’1” woman. These customers were shopping online and couldn’t try the clothes on first, so our marketing had to help them feel confident about the fit.

Some women found us organically. When we ran ads to reach beyond that audience, we had to find ways to identify likely customers without spending too much on clicks from people who weren’t going to buy. That challenge contributed to a customer acquisition cost of around $38 before we changed our approach.

How did you identify the shopping behaviours, content engagement and other signals that could more effectively reach women who were actually likely to buy TJL Collection products?

I was able to learn a lot very quickly by talking to our customers. I’m 6’1” myself, so I understood many of their experiences, but I still wanted to hear directly from them. I would go live, send out surveys and have conversations with our community. The women were more than happy to tell us what they wanted and what they needed to know before placing an order.

We also collected information through our website and listened closely to the questions customers asked about our products. Their voices helped drive our decisions, from the details we highlighted in content to the way we described a piece. Sarah then helped us pair that firsthand customer knowledge with audience research into shopping behaviours, interests, locations and content engagement. That gave us a more useful picture of the women most likely to buy than demographics alone could provide.

What specific changes did you make to the brand’s advertising and creative strategy, and what did you learn from testing videos featuring me as the founder, testimonials and product content?

We started using language that would make the right woman stop scrolling. Phrases like “Tall girls only,” “For women 5’9” and up,” or simply stating the inseam told her immediately that we were speaking to her. Those details helped us cut through a feed full of clothing ads.

Sarah and I also spent time learning who our customers were beyond their height. We looked at their interests, from travel and TV shows to their lives as moms, and used insights from our social media and website to understand where we were reaching them. That gave us a fuller picture of our customer and helped us make more informed decisions about our audiences and creative.

We tested videos featuring me, customer testimonials, lifestyle imagery and ads focused on specific products. My videos shared why I created TJL as a tall woman myself. Testimonials brought in the voices of women who had worn the clothes. Product content answered the practical fit questions that could hold someone back from ordering online. The lesson was that both the first words a woman saw and the details that followed had to make her feel, “This brand made this for me.”

TJL Collection photo

How did working with a freelance digital marketer compare with the cost and capabilities of building an in house marketing team, and what made the arrangement work for TJL Collection?

As a small business, we needed experienced marketing support, but hiring a full time marketer would have been a major fixed expense. Working with Sarah through Fiverr gave us access to audience research and Facebook and Instagram advertising expertise as we needed it.

What began as one project became a working relationship. As we approached the end of a project, Sarah would send over the next one, so it was easy to keep moving. I found that especially valuable because I didn’t have to start over each time explaining who our customer was or why tall fit mattered. Sarah learned more about our audience, our products and our business with every project. I brought the firsthand customer knowledge, and she helped turn it into advertising we could test and improve. That continuity gave us many of the benefits of having someone on the team while allowing us to work project by project.

TJL Collection has reduced its customer acquisition cost from $38 to $18 while growing annual revenue from $475,000 in 2025 to a projected $800,000 this year. What has been the biggest factor behind that growth, and what challenges remain?

Being a niche brand has been one of our greatest strengths. Our message is clear: TJL makes fashion for tall women. Even when someone sees our content and isn’t tall, they often tag a tall friend. That introduction to the right woman is a win for us, too. Keeping our message clear has helped people recognize who we serve and share the brand with someone who needs it. Sarah helped us carry that clarity into our ads and reach more likely customers, bringing our customer acquisition cost down from about $38 to about $18.

The biggest ongoing challenge is the marketing budget. Advertising gets especially competitive during the holiday season, when larger companies can spend far more than we can. We have to make every dollar work harder and keep finding creative ways to reach tall women so TJL doesn’t get lost among brands with much bigger budgets. Our 2026 revenue figure is a projection, and staying focused as we grow matters just as much as reaching it.

TJL Collection photo

6. What is the brand’s reach in Canada?

Canada is TJL Collection’s largest audience outside the United States. We’ve participated in pop-ups there and sold out an entire collection at one of them. Historically, Canadian customers have accounted for about 15% of our sales. That response shows us how strong the demand is for fashion designed specifically for tall women in Canada.

We plan to explore growing TJL in Canada next year so our pieces are more accessible to the women who have already embraced the brand. For me, the opportunity is about making it easier for that community to shop with us, from finding the right fit to getting their orders without the barriers they face today.

More from Retail Insider:
Vistar Media Research Shows How Seasonal Products Shape Canadian Consumer Behaviour

Vistar Media photo
Vistar Media photo

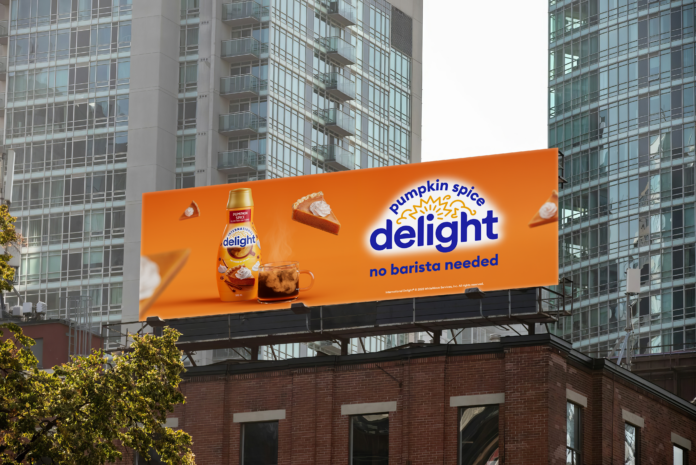
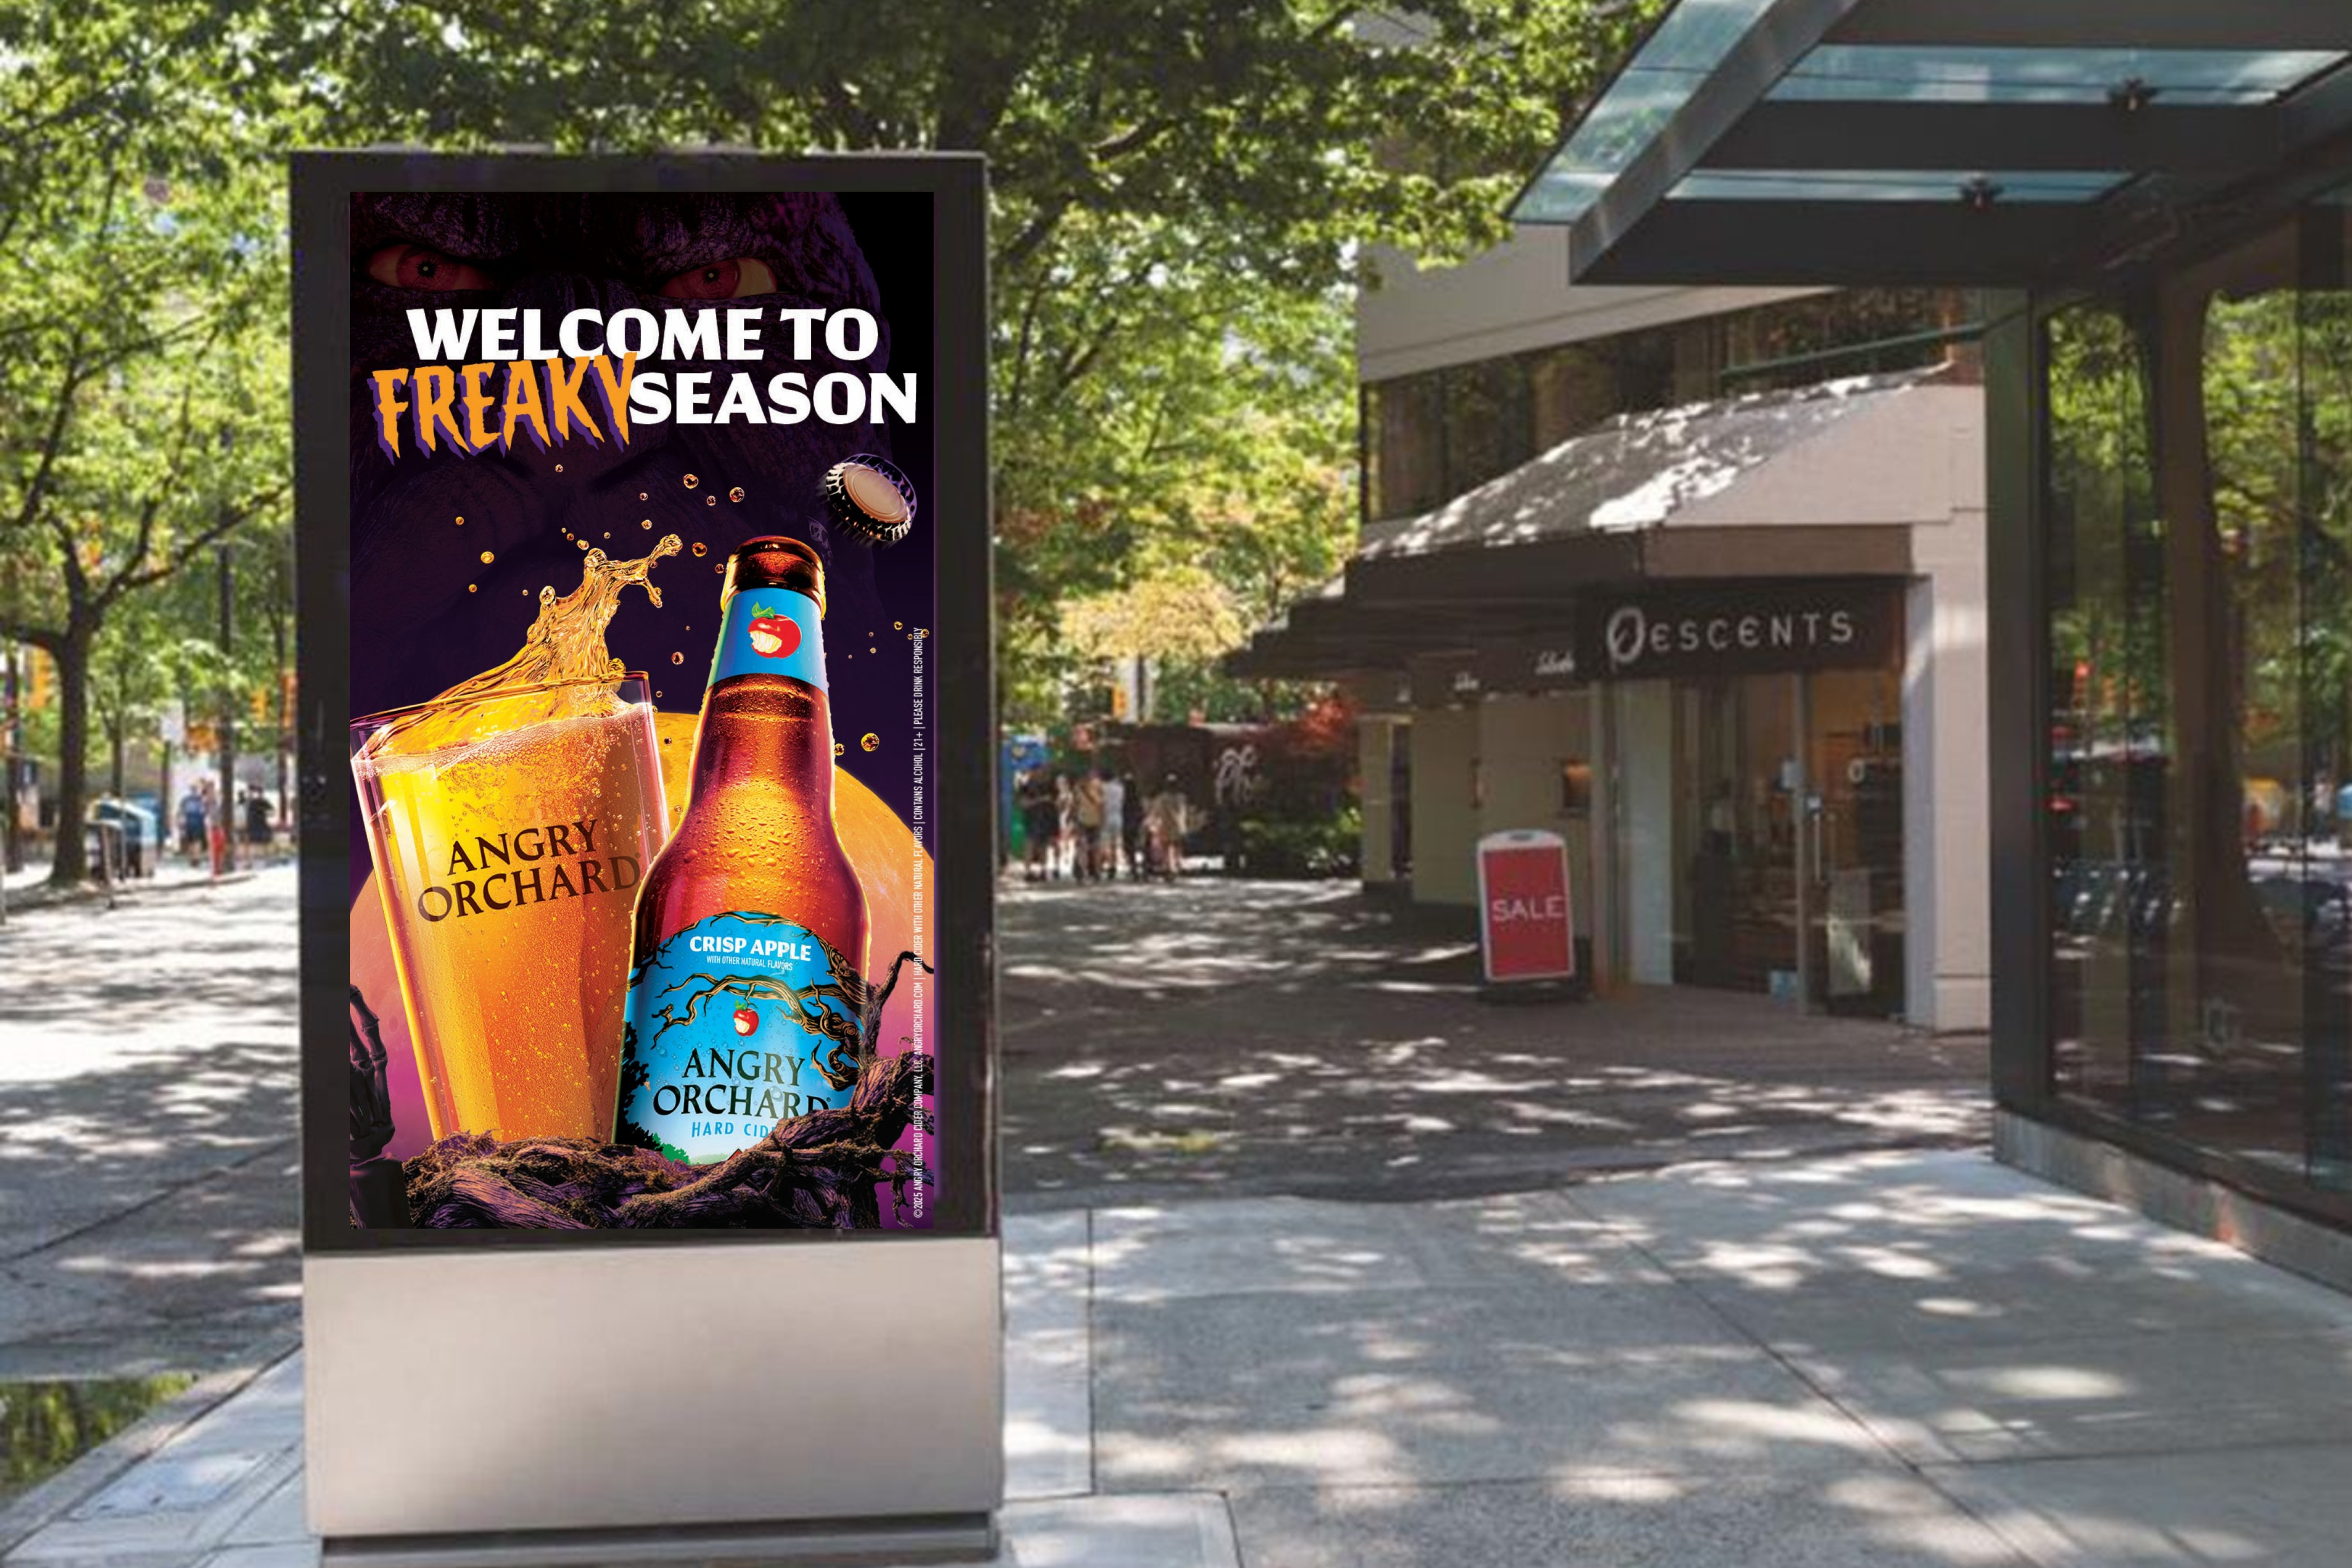
From Pumpkin Spice Lattes to holiday cups, some seasonal products have become cultural cues consumers recognize instantly. For advertisers, there’s a lesson: the more iconic the product, the less an ad may need to say.

New Canadian research from Vistar Media and Angus Reid found 39% of Canadians took action after seeing OOH advertising, including 22% who searched online for a brand.

Scott Mitchell, Managing Director, Canada at Vistar Media, said the strongest brands have built such recognizable visual identities that consumers can understand the message almost instantly. 

“You see a certain cup, colour palette or piece of seasonal imagery and you already know what brand it is and what time of year it represents. That kind of recognition is incredibly valuable because an ad doesn’t have to spend much time explaining itself,” he said.

“For retailers, the lesson is that distinctive brand assets matter. It could be packaging, a colour, a shape or even a familiar way a product is presented. When those cues have been reinforced consistently over time, they can do a lot of the communication on their own. A Pumpkin Spice Latte is a good example. At this point, consumers don’t need a lengthy message explaining what it represents. The product itself has become shorthand for the arrival of fall.”

Vistar Media photo
Vistar Media photo

The role of nostalgia

Mitchell said seasonal products are interesting because people often associate them with much more than the product itself. 

“They can remind you of a particular time of year, a tradition or even a routine you’ve repeated for years. When a familiar holiday cup returns, for example, it can signal the beginning of the holiday season in a way that feels almost ritualistic,” he said.

“That gives brands an emotional foundation they don’t necessarily have to rebuild every year. Consumers already bring their own memories and associations to the experience. The opportunity is to build on that familiarity without simply repeating what came before. The strongest seasonal marketing feels recognizable, but still gives people something new to notice.”

Anticipation is part of the experience

Mitchell said it takes time for a seasonal product to go from being a limited-time offering to something consumers actively anticipate every year.

“You can’t manufacture a tradition overnight. The products that become genuine seasonal moments tend to return consistently enough that consumers start to expect them, talk about them and eventually use their arrival as a marker of the season itself,” he said.

“That anticipation is an important part of the experience. The launch is no longer simply, “this product is available again.” People know it’s coming, they watch for it and there’s a sense of occasion around its return. In some cases, the conversation starts before the brand has even said much.

“That consistency matters for retailers, too. There’s pressure to reinvent the seasonal playbook, but consumers may already be telling you which products or traditions are worth keeping. When something returns year after year and people begin to look forward to it, it stops feeling like a limited-time promotion and starts becoming part of the season itself.”

Timing and location matter

Seasonal advertising has a natural window where the message makes the most sense, and context can make that window much more effective. A fall food or beverage ad can land differently on a cool morning commute than it does weeks earlier when people are still thinking about summer, explained Mitchell.

“Similarly, an ad for a holiday retailer near a shopping district has a different role than the same message appearing somewhere disconnected from the shopping occasion,” he said.

“That’s where out-of-home (OOH) advertising has a natural advantage in seasonal campaigns: the environment can become part of the creative. Marketers can think about where someone is, what they may be doing and what makes sense at that particular point in the season.

“And that exposure can lead somewhere. Our recent Canadian research with Angus Reid found that 39% of Canadians took action after seeing OOH advertising, including 22% who searched online for a brand. The physical ad may be the starting point, but the consumer journey can continue well beyond it.”

Lesson learned from building recognizable moments

You don’t necessarily need a completely new idea every season. What do consumers already recognize, remember and look forward to from us?, added Mitchell.

“If customers genuinely look forward to a product, visual identity or tradition, that’s an asset worth building on. Keep the elements people recognize, but give them a reason to rediscover them each year, whether through a new variation, a creative refresh or a different way of introducing the season,” he said.

“There’s also a tendency in advertising to say too much. Seasonal campaigns are a good reminder that when a brand has done the long-term work of building recognition, simplicity can be an advantage. Sometimes one familiar image or product can carry more meaning than a headline ever could.”

More from Retail Insider:
Toronto Hair-Removal Clinic Owner Sees Shift Toward Sugaring, Laser and Long-Term Savings

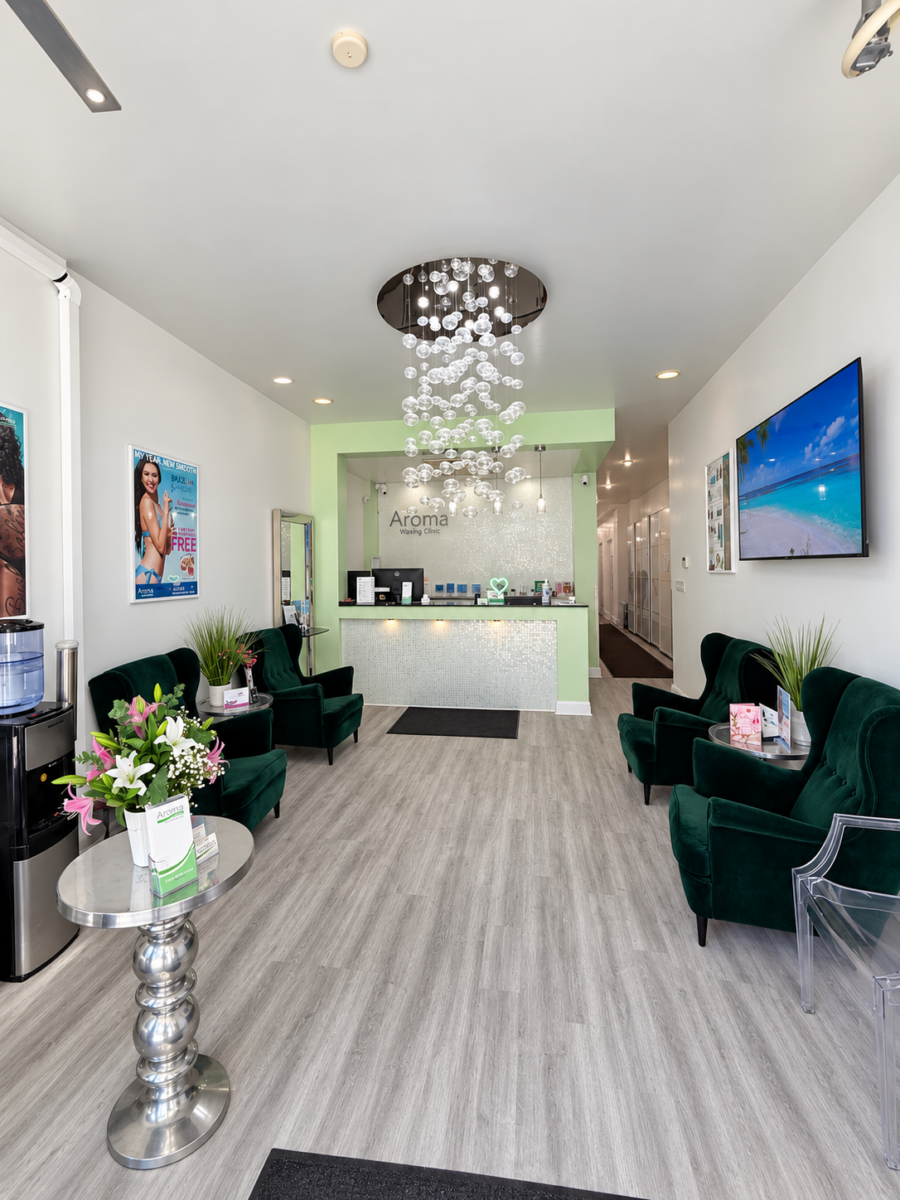
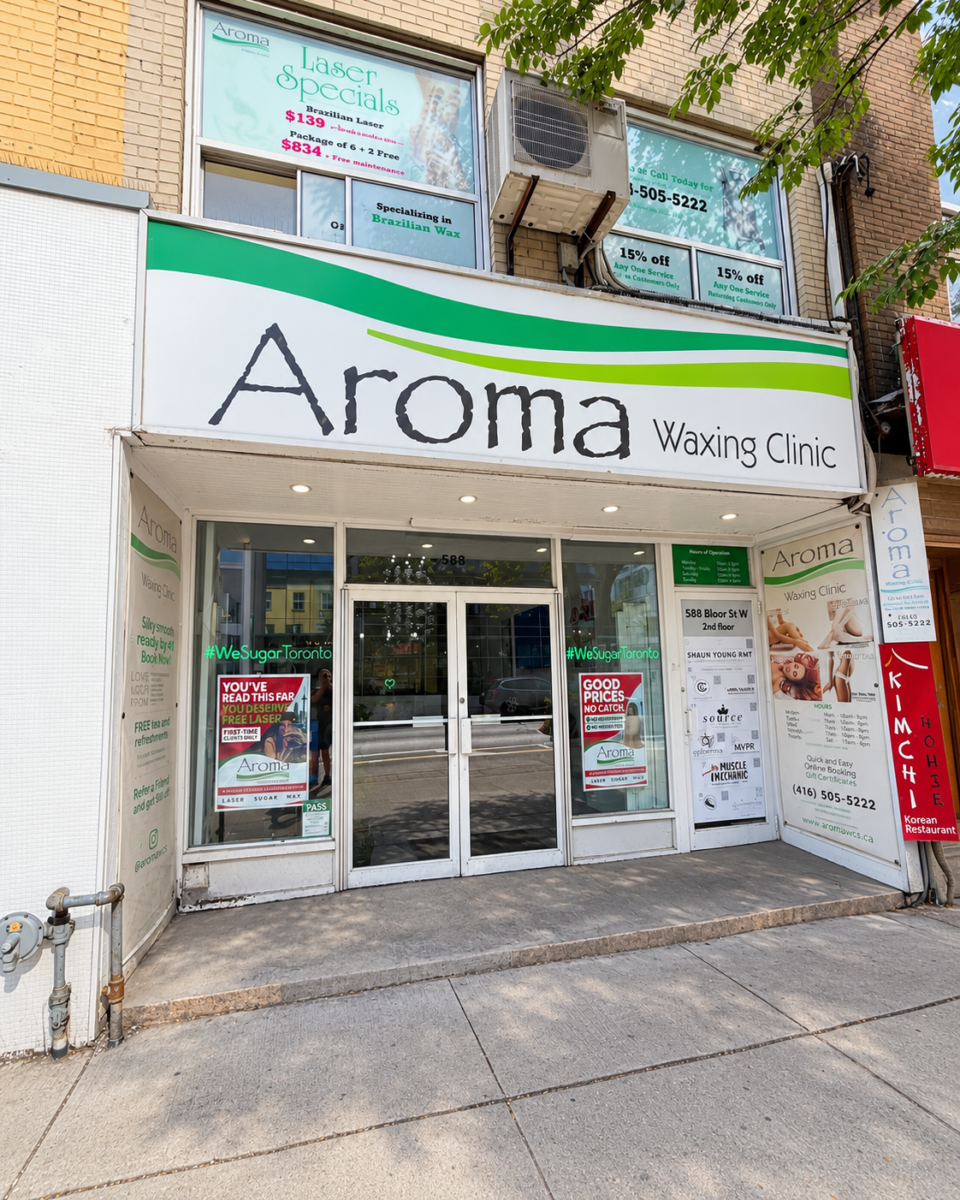
Aroma Waxing & Laser Clinic photo

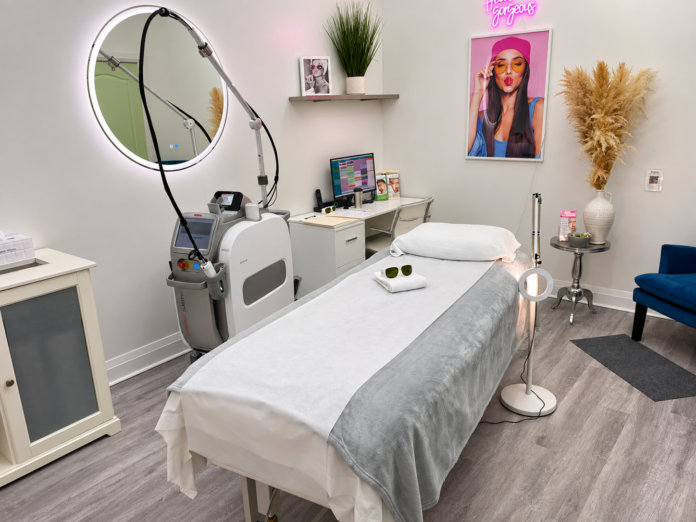
Mary Miljan opened Aroma Waxing & Laser Clinic in Toronto in 2008 and today the brand has three locations in Toronto and Mississauga.

She’s spent about 18 years working with clients and watching this business change from the ground up.

What she finds interesting isn’t only which treatments people choose, but how the way they spend has changed too. Years ago most of the conversation was waxing. Now the business gets so many questions about sugaring, men’s grooming, laser, hormonal hair growth and PCOS (Polycystic Ovary Syndrome), darker skin tones, and whether it makes financial sense to keep paying for temporary hair removal for years.

The business has even built a little calculator that gives people an estimate of what shaving, waxing or sugaring may cost over time compared with a laser package.

In an interview with Retail Insider, Miljan talks about the business and trends she is seeing.

Mary Miljan
Mary Miljan

How have customer preferences and spending habits in the hair-removal market changed since you opened Aroma in 2008?

When I opened Aroma in 2008, waxing was really the main conversation. People came in for their wax, came back five weeks later, and that was how it all began. From there we expanded our hair removal to Sugaring services then laser hair removal. 

Today clients know a lot more before they even walk through the door. They ask about waxing versus sugaring, sensitive skin, ingrown hairs, laser, different machines, skin tones, hormones and how many treatments they may need.

I also think people are more careful about how they spend their money. They are not only asking what the appointment costs today. They are thinking about how often they have to come back and what they are going to spend over the next five or ten years.

But one thing hasn’t really changed. People still want to feel comfortable, they want somebody experienced taking care of them, and they want the service done properly.

What trends are you seeing in demand for waxing, sugaring, laser hair removal and men’s grooming, and what do those trends tell you about how consumers are making decisions?

Waxing is still a very big part of our business, especially Brazilian waxing. We have clients who love waxing and have been doing it for years.

Sugaring has definitely become much more popular. Years ago a lot of people didn’t even know what it was. Now clients come in specifically asking for it, especially people with sensitive skin or people who prefer a more natural form of hair removal.

Laser has grown because people are looking more at the long term. They get tired of shaving, ingrowns or repeating the same waxing appointment over and over, and eventually they start asking whether laser makes more sense for them.

Men’s grooming has changed a lot too. Men are much more comfortable coming in for back, chest, Brazilian, beard and laser services. It is not unusual anymore.

What I see is that clients want choices. They want us to explain the difference between the services and then let them decide what works best for their skin, lifestyle and budget.

How have conversations around hormonal hair growth, PCOS and hair removal for people with darker skin tones changed the services customers are seeking and the questions they are asking?

People talk about these things much more openly now.

We see women who tell us they have PCOS or hormonal hair growth on the chin, face or other areas. They want to know why the hair keeps coming back and whether laser is still worth doing.

I always explain that hormonal hair can behave differently. Laser can help a lot, but somebody with PCOS may need more treatments or more maintenance because the hormones can continue producing new hair. I think it is important to explain that before starting instead of promising everybody the exact same result.

Clients with darker skin tones are also asking much better questions now. They want to know what machine we use and whether it is appropriate for their skin.

For lighter skin we can use Alexandrite, and for darker skin we use YAG. The wavelength and the settings have to be right for the person’s skin. That is where having an experienced technician really matters.

The questions today are much more educated. Clients want to understand what you are doing and why, and I think that’s a good thing. 

Are customers becoming more focused on the long-term cost of temporary hair-removal methods such as shaving, waxing and sugaring compared with investing in laser hair removal?

Yes, I think people are looking at the long-term cost much more now.

We have clients who have been waxing for years, sometimes the same areas every four or five weeks. At some point they start thinking about how much time and money they are putting into temporary hair removal and whether laser would make more sense for them.

I don’t tell everybody they should switch to laser because that’s not true. Some people love waxing, some prefer sugaring, and others are ready to start their laser journey. 

But people want to understand the difference in cost over five or ten years, not just what today’s appointment costs. That’s why we put the calculator on our website. It gives people a simple way to compare what they may spend over time on shaving, waxing or sugaring versus a laser package and then decide for themselves.

Aroma Waxing & Laser Clinic

What do you see as the biggest opportunities and challenges for independent hair-removal businesses in Toronto and the broader Canadian market over the next few years?

I think one of the biggest opportunities is specialization.

Hair removal looks simple until you have been doing it for almost 20 years. Then you realize how different every person’s skin and hair can be. You have different skin types, hair types, hormonal growth, sensitive skin, ingrowns, different waxes and different laser settings.

Independent businesses have an advantage because we can really get to know our clients instead of treating every appointment exactly the same.

I also think having good staff is extremely important. You can have a hair removal clinic and the best machine, but if you don’t have experienced people doing the treatments and taking care of the clients, none of that matters.

Keeping good employees is a big part of running this kind of business. When technicians stay, they get to know the clients, the clients trust them, and that relationship is very hard to replace. Training somebody properly takes time. Experience takes even longer.

The challenge is that there is a lot of competition and sometimes everything gets compared by price. But hair removal is not just a product where the cheapest one is automatically the same. The technique matters. The person doing it matters. With laser, the machine and settings matter too.

For independent businesses, I think the future is going to be about experience, education and trust. Clients have more information than ever, so you have to be able to explain what you’re doing, be honest about what they can expect, and have a team that knows what they’re doing.

That is probably the biggest thing I’ve learned since 2008. The equipment changes and the trends change, but good people and good service are still what keep clients coming back.

More from Retail Insider:
Twenty Two Media Launches foodism Creator Program With Six Toronto Influencers

Krista Faist
Krista Faist

Twenty Two Media has launched The foodism Creator Program, a new strategic initiative pairing Toronto’s most respected food, drink, travel and lifestyle creators with foodism’s media ecosystem. 

Recognizing that social-first content has reshaped how people discover dining, travel and local experiences, the new program will collaborate with well-known creators to produce captivating, mobile-first storytelling distributed across both creator channels and foodism’s owned platforms, explained the company.

Six brand ambassadors have been onboarded to represent key culinary and lifestyle pillars:
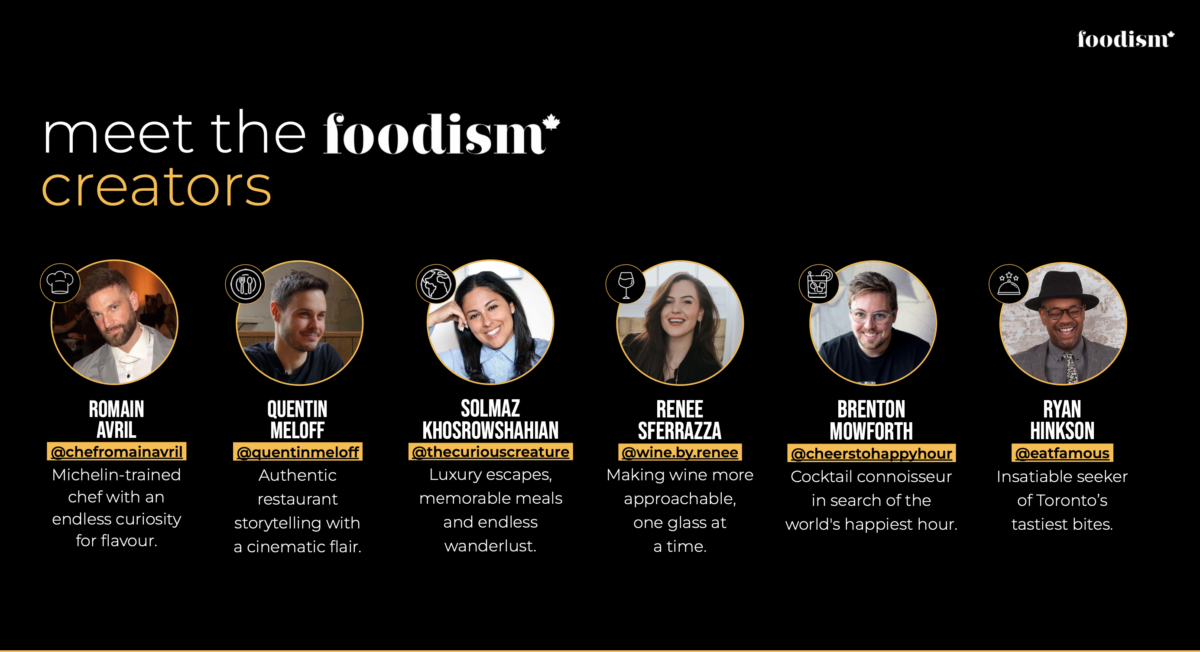
Ambassadors carefully curated and vetted

For foodism’s brand partners, the company said the program offers a turnkey way for brands to participate, with foodism managing everything end-to-end: from campaign briefs and creator matching to production, editorial oversight, platform optimization and multi-channel amplification. 

Unique to this program, ambassadors are carefully curated and vetted for alignment with foodism’s editorial standards, giving brands access to content guided by a trusted media brand with deep credibility within the local food and beverage scene. The result is a premium, brand-safe environment where partners can reach engaged audiences through authentic creator storytelling backed by foodism’s authority, it added. 

“With the constantly evolving media landscape, audience behaviours have shifted, and people are increasingly discovering dining, travel and local experiences through social content,” said Krista Faist, Founder of Twenty Two Media and Publisher of foodism. “By pairing our creators with foodism’s production team, brands get mobile-native video backed by editorial trust.”

The foodism Creator Program is now live and available for brand partnerships. For more information on the foodism Creator Program, including deliverables and pricing click here.

Audience behaviour has shifted

Twenty Two Media is a women-owned and women-led Canadian publishing house and creative agency founded in 2015 that produces premium consumer content. 

Faist said the initiative launched now because audience behaviour has shifted — people increasingly discover local dining and lifestyle through social-first vertical video, and advertisers are prioritizing authentic creator partnerships. 

“While print, digital display and editorial stories remain vital for establishing brand authority, social-first vertical video has become essential for discovery,” she said.

“Our brand partners know vertical video is essential to a complete media mix, but often struggle to produce or invest in content that feels authentic and maintains brand safety and editorial polish. We are launching this program to offer brands the best of everything. We want them to have their cake and eat it too!”

Krista Faist
Krista Faist

Faist said the creator program is going to expand its ability to work with its clients. 

“We already bring a solid media mix to the table with print, web, newsletter, social and experiential and now we’re adding creator story-telling. So if you love foodism, our audience and what we produce, this is a way to further keep everything under one roof. And that’s really the biggest business opportunity here: brand teams are BUSY, and they want less and less segmentation with their media spend, creative and campaign execution. We offer it all under one trusted brand,” she said.

“When we set out to build this roster, we weren’t just looking at follower counts or vanity metrics-we wanted creators who represent the absolute best of Toronto’s food, beverage, and lifestyle culture and have real authority in their specific niches.

“Each of these six creators brings legitimate expertise, whether it’s chef-led culinary content, sommelier-backed wine education, craft mixology, or local restaurant discovery. More importantly, they’ve built high-trust, highly engaged audiences who actually take their recommendations. They share our standards for visual polish and brand safety, making them a seamless extension of the foodism brand.”

Completely turnkey process

Faist said the creator program is a completely turnkey process. 

“We handle everything end-to-end—matching the brand with the right creator, handling strategy and scripting, leading production, and managing all approvals.  Distribution is where the real value lives: every campaign combines organic creator posting with guaranteed reach across foodism’s channels—including custom vertical video, newsletter inclusion, and built-in targeted paid media amplification.  Rather than selling one-off posts, we’re focusing on offering this as a premium add-on to broader foodism media packages. Pricing is performance-backed based on guaranteed impressions, giving brands turnkey production, authentic storytelling, and publisher scale in one seamless buy,” she said.

“We measure success by campaign performance and audience growth. For advertisers, we prioritize reach, view completion rates and real engagement like saves and shares, which indicate genuine consumer interest. We’ve also integrated third-party creator analytics tools so our partners receive clear, verified reporting across both creator and foodism channels.

“Commercial success also looks like repeat partnerships, strong campaign sales and expanded audience reach. Ultimately, a winning campaign is one where the brand sees real cultural relevance and product consideration, our creators produce content they’re proud of, plus our audience discovers something new and exciting.”

More from Retail Insider: