Home Blog Page 71

What Canadian Retailers Can Learn From the Home Services Sector About Customer Loyalty

Retail loyalty programs have become table stakes. Points, tiers, birthday discounts — nearly every Canadian retailer runs some version of the same playbook. Yet loyalty, in the true sense of the word, is becoming harder to earn. Shoppers compare prices in seconds, switch brands on a whim, and rarely think twice before abandoning a cart for a better deal elsewhere. Companies like Aquatech basement waterproofing, on the other hand, operate in a sector where trust is earned so slowly that customers stay loyal for decades — and that gap is worth examining.

Interestingly, one sector has quietly built a different kind of customer relationship: home services. Companies that install furnaces, repair roofs, or waterproof basements don’t get repeat purchases every week. They might see a customer once every several years. And yet, when that customer needs the service again — or knows someone who does — they call the same company without hesitation.

That kind of trust doesn’t happen by accident. Here’s what retailers can borrow from how the home services industry builds it.

1. Trust Is Built Before the Sale, Not After

In home services, the sales process itself is where trust is won or lost. A technician who shows up on time, explains the problem in plain language, and doesn’t oversell is remembered — and referred. Companies in this space, from HVAC contractors to specialists like basement waterproofing providers, understand that the first interaction often determines whether there will ever be a second one.

Retailers can apply the same logic to every touchpoint before checkout: clear product information, honest reviews, transparent pricing, and staff (in-store or via chat) who genuinely help rather than push. Trust isn’t a loyalty perk unlocked after purchase; it’s the reason the purchase happens at all.

2. Service Recovery Matters More Than Perfection

No home services company gets it right 100% of the time. Pipes still leak after a repair. A waterproofing job might need a follow-up visit. What separates the companies people recommend for decades from the ones they never call again is how the problem gets fixed — quickly, without excuses, and often with an added gesture of goodwill.

Retailers tend to treat complaints as a cost center to minimize. The more useful mindset is to treat them as the single highest-leverage moment to build loyalty. A refund processed instantly, an apology that doesn’t sound scripted, or a small unprompted discount after a shipping delay can do more for retention than months of point accumulation.

3. Expertise Is a Loyalty Driver, Not Just a Sales Tool

Home services businesses succeed by educating, not just selling. A contractor who explains why a basement is leaking, what the long-term risk is, and which fix actually solves it (rather than just patching the symptom) earns credibility that outlasts the transaction. Customers remember who taught them something useful.

Retailers — especially in categories like electronics, beauty, home goods, or outdoor gear — have the same opportunity. Buying guides, honest comparisons, and staff who can answer a real question build the kind of credibility that discount codes never will.

4. Referrals Outperform Rewards Points

Home services companies live and die by referrals, because paid advertising alone rarely covers the cost of acquiring a customer who buys once every few years. That forces them to obsess over word-of-mouth: every job is treated as a potential source of the next three customers.

Retailers, especially those competing with marketplaces on price alone, would benefit from applying the same obsession. A referral program that genuinely rewards both sides — not a token discount buried in the fine print — tends to outperform generic points systems, because it turns satisfied customers into an active sales channel instead of a passive database entry.

5. Consistency Beats Novelty

Home services brands rarely reinvent themselves. The value proposition — reliability, fair pricing, work that lasts — stays consistent for years, because that consistency is what earns the next call. Retailers, by contrast, often chase novelty: new campaigns, new loyalty tiers, new app features, sometimes at the expense of just being dependable.

The lesson isn’t to stop innovating. It’s to recognize that for many customers, the deciding factor isn’t the newest feature — it’s whether the brand delivered exactly what it promised, the same way, every time.

The Bigger Picture

Retail and home services are different businesses with different purchase cycles, but the underlying psychology of loyalty is the same: people return to businesses that make them feel informed, respected, and taken care of when something goes wrong. Home services companies have had to master this because their margin for error, and their frequency of contact, is so much smaller.

Canadian retailers operating in an increasingly commoditized, price-driven market don’t need a bigger loyalty program. They need to borrow a page from an industry that has never had the luxury of relying on impulse purchases — and has built its entire business on being the company people call again.
The Buy Canadian Effect: How Local Service Businesses Are Winning Consumer Trust

Something shifted in the Canadian consumer mindset in 2025 — and it hasn’t shifted back.

What began as a response to trade uncertainty and cross-border tariff tensions evolved into something more durable: a genuine, measurable preference among Canadian consumers for businesses that are rooted here. Not just Canadian-owned in a legal or corporate sense, but locally operated, locally staffed, and locally accountable. Businesses where the owner’s name is on the truck, where the crew that shows up is the same crew that answered the phone, and where a complaint doesn’t route through a call centre in another province.

This shift has been well-documented in the retail sector. The surge in “Made in Canada” labelling, the growth of Canadian-owned online marketplaces, the measurable increase in consumers actively checking ownership before purchasing — all of it reflects a consumer that has become more deliberate about where their money goes and who benefits from it.

What has received less attention is how the same sentiment is reshaping the residential services sector — and producing equally significant results for the local operators who have built the kind of trust that national chains and franchise models struggle to replicate.

The Trust Premium in Home Services

In retail, brand trust is built through product consistency, return policies, loyalty programs, and marketing. In home services, trust is built differently — and the stakes are considerably higher.

When a Canadian homeowner hires a contractor to waterproof their foundation, replace their roof, or rewire their electrical system, they are inviting someone into the most valuable asset they own and handing them significant authority over its condition. The transaction cannot be returned. The work cannot be easily inspected. The consequences of a poor decision — failed waterproofing, structural damage, fire risk — can materially affect the value and safety of the home for years.

In this environment, the factors that drive consumer choice are not price and convenience. They are reputation, accountability, and longevity. And on all three, local operators with deep community roots consistently outperform the alternatives.

The team that provides basement waterproofing Toronto homeowners rely on understands this dynamic well. Direct Waterproofing has operated under the same name since 1995 — more than 30 years of continuous operation in a single market, with a reputation built one job at a time and verified through thousands of documented customer reviews. That continuity is itself a trust signal. A contractor that has operated under the same brand for three decades has, by definition, stood behind its work long enough to accumulate a verifiable history. That history is available to any consumer willing to spend ten minutes with a search engine — and increasingly, consumers are doing exactly that.

What “Buy Canadian” Actually Means in a Service Context

In retail, the Buy Canadian movement has a relatively clear definition: purchase products manufactured in Canada, from companies headquartered here, employing Canadian workers. The supply chain narrative is visible and traceable.

In services, the equivalent commitment is subtler but no less meaningful. Hiring a locally owned home services company means that revenue stays in the local economy rather than flowing to a national head office. It means the crew working on your property is employed by someone who lives in your region and has a direct stake in the community’s opinion of their work. It means that when something goes wrong — and in construction and renovation, something occasionally does — the person responsible is reachable, has a local licence number that can be verified, and has a reputation to protect.

This accountability structure is precisely what national franchise models and aggregator platforms struggle to provide. A contractor sourced through a lead-generation platform may be technically qualified, but their accountability to any individual consumer is limited. They are one node in a network, not a local business owner whose livelihood depends on their standing in a specific community.

Canadian consumers are making this distinction with increasing clarity. A 2025 survey by the Business Development Bank of Canada found that trust and local accountability ranked above price as decision drivers for home services purchases — a notable shift from pre-pandemic data where cost was consistently the dominant factor. The tariff environment accelerated something that was already developing: a consumer base that had begun to question whether the cheapest option was actually the best value when accountability was factored in.

The Operational Advantages of Local Operators

The Buy Canadian preference in home services is not purely sentiment — it is also, in many cases, a rational economic calculation.

Local operators know their markets in ways that national players cannot replicate from a distance. A waterproofing company that has spent 30 years working on homes in a specific region understands the local geology, the age and construction profile of the housing stock, the seasonal patterns that drive specific types of foundation failure, and the municipal rebate programs that can offset costs for homeowners. That local knowledge produces better diagnoses, more appropriate solutions, and better long-term outcomes.

It also produces more accurate pricing. Local operators competing on reputation rather than volume have less incentive to offer artificially low quotes that get revised upward mid-project. Their business model depends on referrals and reviews from a finite geographic community — which means every job has to be completed to a standard that the customer will be willing to describe positively to a neighbour.

For the home services category specifically, this combination of local knowledge, reputational accountability, and community investment is proving to be a durable competitive advantage — one that national scale cannot easily replicate and that the Buy Canadian consumer preference is now actively rewarding.

What Retailers and Industry Observers Should Watch

The trend in home services mirrors dynamics that the retail sector is already navigating. Consumers who have developed a deliberate preference for local, accountable businesses do not compartmentalise that preference by category. A household that commits to buying Canadian-made products from independent retailers is the same household that is scrutinising who waterproofs their basement, replaces their HVAC system, and services their plumbing.

This represents both a challenge and an opportunity for businesses across the home services spectrum. Companies that have invested in local reputation — verified reviews, community presence, long operating histories, transparent licensing and warranty terms — are well-positioned to capture the attention of a consumer base that is actively looking for reasons to choose them. Companies that have relied on price competition or national brand recognition alone are finding that neither is the differentiator it once was.

The Buy Canadian effect is not a temporary phenomenon driven by tariff anxiety. It reflects a durable recalibration of how Canadian consumers think about trust, accountability, and the relationship between where they spend money and what they get in return. For local service businesses that have spent years building genuine reputations in their communities, the market has finally caught up with what they already knew: longevity, accountability, and local roots are not soft values. They are competitive advantages — and Canadian consumers are beginning to pay for them accordingly.

How smaller online retailers can compete without Amazon-scale logistics

For growing independent brands, standing out in today’s e-commerce landscape can feel like an uphill battle. Customers have grown accustomed to 24-hour and same-day delivery, putting retailers under pressure to protect tight margins. 

The answer, here, isn’t necessarily to spend more but to be more deliberate about how shipping is managed. Taking the time to review available services when you compare parcel delivery costs online can uncover opportunities to make smarter decisions. 

A major misstep is trying to replicate massive enterprise ecosystems: it’s simply not possible. Independent businesses can, however, carve out a distinct competitive advantage by rethinking how they approach fulfilment. 

Compete on experience (not infrastructure)

Smaller online retailers may feel intimidated by the physical networks of giants like Amazon, and it’s no wonder: the company generates over $710 billion in annual revenue and has almost 1.5 million employees worldwide.

But the reality is, customers often don’t care if you own a fleet of delivery vans or a huge fulfilment centre. They only care about what happens after they place an order. Once a customer clicks ‘buy’, their priorities are outcome-driven. 

With reasonable shipping prices and delivery windows, independent retailers can shift their focus from owning logistics infrastructure to making good use of the services already at their disposal. 

So, you’re not trying to compete with Amazon on scale – make delivery feel dependable, and you can build the kind of deep brand loyalty that keeps customers coming back for more. 

Make flexibility your advantage

Smaller retailers might not have the shipping volumes needed to secure the kind of direct carrier agreements available to the biggest e-commerce businesses, but they can make flexibility work in their favour.

Relying on one courier for every order isn’t always the best approach, as no single courier excels at every destination, parcel size, or speed requirement. In fact, it often leads to overpaying on certain routes or offering sub-optimal service levels to your customers. 

Different shipments call for different solutions. Access to varying service levels means smaller retailers can choose based on each shipment’s needs without being tied to a single solution.

Equally, it gives retailers room to respond when circumstances change. A carrier that suits regular domestic orders may be less competitive during peak periods, so having alternatives available can prevent something that’s temporary becoming a customer-facing issue. 

With that level of flexibility, you can offer customers the right range of choices at checkout and keep costs under control. 

Don’t try to win every delivery on speed

As an independent retailer, matching Amazon’s same-day delivery promises isn’t feasible. Small retailers often don’t need to match that speed on every order, and trying to do so can increase costs without providing enough value to justify them. 

Data shows that shoppers prefer affordable economy delivery over rapid shipping (as long as they receive a guaranteed arrival date). Offer a clear spread of services (e.g., economy, standard service, and a premium express upgrade), and you give the customer control. 

This kind of reliability is a far more achievable differentiator than speed alone. The lesson is that promising a three-day delivery window (and delivering on time) is better than aiming for overnight shipping and falling short. 

Turn delivery into a brand advantage

Another way smaller retailers can strengthen their position is by making delivery part of the overall brand experience rather than treating it as a purely operational task. For many customers, the relationship with a retailer does not end when an order is placed. The delivery process can influence how they perceive the business, from the first confirmation email to the moment the parcel arrives at their door. 

Clear communication, accurate tracking and realistic delivery promises can give customers confidence throughout the purchasing process and reduce the uncertainty that can sometimes come with online shopping.

Small retailers can also use delivery as an opportunity to demonstrate the qualities that make their brand different. Providing regular updates, explaining any potential delays and making returns straightforward can help create a sense of reliability and transparency. Customers are often more willing to accept a slightly longer delivery window when they know exactly when their order is expected to arrive. This means that smaller retailers do not necessarily need to offer the fastest service available; instead, they need to make the service they offer feel dependable and well managed.

Personalisation can also play an important role. Unlike large marketplaces that often rely on highly standardised processes, independent retailers have more opportunities to create a customer experience that reflects their brand identity. Thoughtful packaging, personalised messages, flexible delivery options or responsive customer support can turn an otherwise routine transaction into a more memorable experience. These details may appear small individually, but together they can help reinforce a retailer’s values and encourage customers to associate the brand with quality and care.

Ultimately, efficient fulfilment and attentive customer service can become a genuine competitive advantage for independent retailers. By focusing on transparency, reliability and personalisation, smaller brands can build stronger relationships with customers and encourage repeat purchases. Rather than attempting to compete with major e-commerce platforms solely on delivery speed or price, they can differentiate themselves through an experience that feels more trustworthy, responsive and personal. In this way, delivery becomes more than simply the final stage of a sale—it becomes an important part of the brand itself.

You don’t need to compete on scale

It’s clear that a huge supply chain isn’t a prerequisite for e-commerce success. Tap into external carrier networks (and routinely compare your shipping options), and, as a smaller merchant, you can easily meet consumer expectations. 

Directing your resources toward the specific fulfilment details shoppers actually value lets you deliver a more efficient, more reliable buyer journey. Better still, you avoid absorbing enterprise-level overhead or infrastructure costs.

Ultimately, smaller online retailers do not need to match Amazon’s scale to compete effectively. Instead, they can focus on what customers value most: reliable delivery, reasonable costs, flexibility, and a positive overall buying experience. By comparing shipping options, using different carriers where appropriate, and offering clear delivery choices, independent retailers can keep fulfilment costs under control without sacrificing customer satisfaction. Rather than trying to win on speed or infrastructure alone, smaller brands can turn agility and personalised service into genuine competitive advantages. In e-commerce, dependable fulfilment and a strong customer experience can be just as valuable as scale.

Peak Season Without the Panic: How Intelligent Route and Capacity Planning Keeps Retailers Ready for Demand Spikes

Every Q4 retailers face the same challenges in their supply chains. Unforeseen spikes in demand create logjams and inventory congestion. Carriers reach capacity, and route planners are overwhelmed. Loads reach weight limits without enough inventory on board or are underloaded and packed too full. By the time the data finally reports in, it is too late. Packages sit stuck in cargo bays, gallons of fuel wasted trucking boxes around town, and customers wait and wait for their packages to arrive.

Despite the best efforts of retail teams, delivering a great customer experience and driving sales growth is becoming increasingly difficult through overworked and under-resourced teams. Most organisations still rely on static route plans, manual scheduling, and what they believe to be a sensible headroom based on historical demand patterns. As tariff volatility and shifting consumer behaviour reshape 2026 retail strategy (Deloitte’s latest outlook flags inventory positioning and fulfilment agility as top-tier concerns), the margin for error is thinner than ever. and fulfilment agility as top-tier concerns), the margin for error is thinner than ever.

This is where having your capacity and route planned by intelligent AI technology is not a nice-to-have anymore but a necessity within the competitive freight and logistics environment.

The Peak Season Problem Is Getting Harder

The “peak season” used to be simple: Black Friday to Christmas Eve. But in the five years since numerous “demand events” have emerged in the commerce world, the period of high-pitched activity has stretched. Today, back-to-school, Labor Day Weekend, Prime Day sales, same-day delivery windows, and other “demand events” have joined the typical shopping spree from Black Friday to Christmas Eve. Meeting all of these new and growing demands on retailers requires delivery companies to manage three key factors: vehicle inventory, routing, and loading.

If a business is getting any of these three key factors wrong, the costs could be massive and ever-increasing. Here we explore the risks associated with empty miles, failed SLAs and how a flawed delivery experience can dent customer satisfaction.

What Intelligent Planning Actually Looks Like

Libera’s capacity and route planning module has been battle-tested within the ElasticRun logistics network of 2400+ small warehouses across 1800+ cities in India, conducting over 5 Million + shipments per day at the peak season. So, the edge cases that can break most systems during the year’s busiest time are not even theoretical to the platform, but rather things that was encountered with and solved at scale over more than a decade at Elastic Run.

.

The platform handles the complexity that most route planning tools struggle with during crunch periods:

Heterogeneous fleets: Peak season means pulling in every available asset – owned vehicles, contracted vehicles for the season and spot-hired vehicles for a week or a short period is not uncommon. At Libera we support a mixed fleet of owned vehicles and contracted vehicles with differing weight, volume and dimension limitations within a single plan, rather than companies having to manage each type of fleet separately.

Tight delivery windows: For quick-commerce and premium delivery services, the available delivery windows are decreasing dramatically. This is especially the case in urban hubs in the UK and around the world, where same-day and even near real-time delivery is becoming the norm. Libera’s planning engine uses AI scheduling to plan for these very tight delivery windows.

Multi-lane optimisation: When a retailer has multiple fulfilment centres or dark stores, the goal is to find the optimal solution for the entire network, rather than optimising the cost per vehicle for each individual lane. Optimising across the entire network with multi-lane planning in Libera ensures travel distance, vehicle volume and cost are optimised whilst workloads remain distributed evenly across the network of facilities without overloading individual hubs.

Real-world constraints: Many planners use route planning tools that do not take into account important factors such as dock availability and service time constraints when optimizing routes. Alternatively, routes and shifts are optimized but then planners hit a wall when they realize there are constraints on where EV drivers can stop to charge up. Libera optimizes route planning, incorporating these real-world factors from the very start.

The Numbers Behind the Claims

The outcomes Libera points to from its own operations aren’t small gains. Route planning that runs 5 times faster means daily plans that used to take a team the better part of a morning can be rerun and adjusted in real time as demand shifts through the day. An 8% reduction in fuel costs achieved through tighter route optimization and higher load factors compounds significantly at peak season volumes. And a 20% improvement in vehicle utilisation directly reduces the number of additional vehicles a retailer needs to hire during high-demand periods, which is where the real cost exposure typically sits.

It’s worth noting that these statistics were generated during the varied high volume trading of a retailer’s peak period as opposed to during a stable and consistent period of trading.

Adaptability Is the Real Differentiator

Perhaps the most underrated aspect of Libera’s planning engine is its configurability. Retail logistics isn’t one thing — a grocery retailer handling 10-minute delivery slots is solving a fundamentally different problem from a furniture retailer managing dock appointments across regional DCs. Libera’s planning scenarios are tailored to the specific constraints of the operation rather than forcing every use case into a single template.

It’s also worth considering whether the routing solution you choose will allow for a manual override in the event that the planner has information that the routing solution doesn’t. Road closures, special handling of an order for a customer, and local knowledge by the driver that a faster route is available. Once the route has been edited and frozen, it can then be sent to the driver’s app on their smartphone. Crucial to choosing the right routing solution is how well it supports the planners in their decision-making. It should be useful, but not override their knowledge and experience.

Planning for 2026 Peaks Starts Now

With Q4 2026 fast approaching, supply chain executives are unclear of potential changes to tariffs that will impact the landed cost of the products that they sell for their organization. Additionally, there are rapid changes in the behaviour of consumers that are also difficult to predict. There are also very restricted carrier markets due to the competitive nature of the industry today. Given these dynamics, success will be less about building a large and complex distribution network and more about utilizing retailers’ advanced planning tools and having the ability to quickly correct for any miscalculations in a company’s sales forecasting process.

Intelligent route and capacity planning has historically been unachievable for many organisations. Planning around a mixed fleet, to a tight delivery time scale, and to multiple locations in real time has been seen as an unattainable black box. That was until Libera, the advanced capacity planning for a global SaaS platform. Designed to handle the toughest of planning scenarios in real time, Libera’s highly scalable, proven architecture has been tested against the biggest and busiest of operations during peak.

Peak season panic is a planning problem. And planning problems, given the right tools, are solvable.

Test Before You Scale: A Lower-Risk Framework for Launching New Online Retail Concepts

Retail launches have traditionally been built around commitment. A concept is developed, merchandise is sourced, inventory is purchased, branding is completed, systems are configured, marketing is funded, and then the market decides whether the idea works.

That sequence is still appropriate for established formats with strong evidence behind them. For a new retail concept, however, it can force too many expensive decisions to be made before the retailer has learned enough about customer demand.

Digital commerce offers another approach. Instead of treating launch day as the moment when the business finally meets the market, retailers can use a smaller online launch to test the commercial assumptions first. The goal is not to build a miniature version of the final business. It is to create the smallest credible customer experience that can answer the questions that matter.

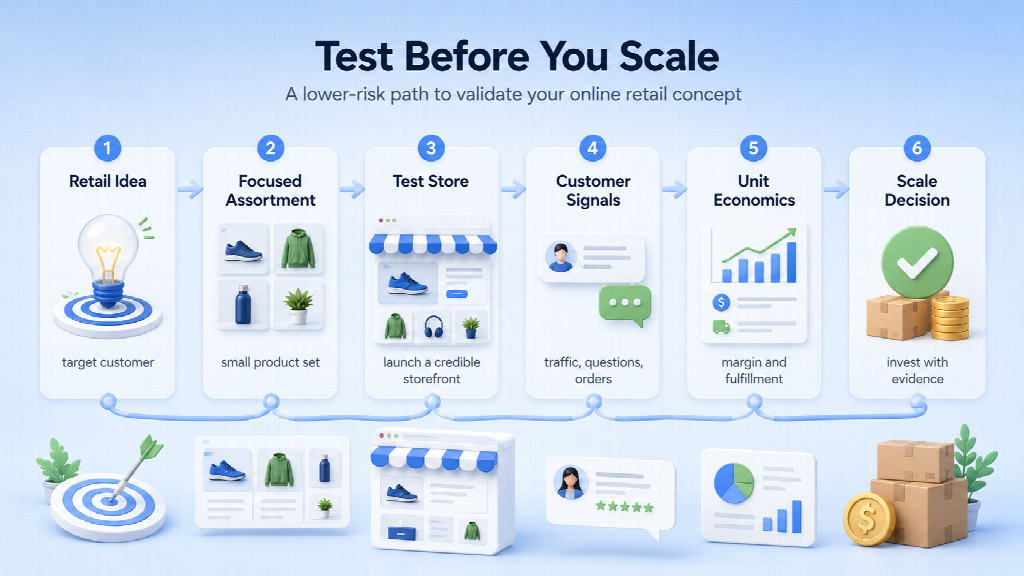
The framework below summarizes a practical “test before you scale” sequence for evaluating a new retail idea.

Start With a Commercial Question, Not a Website

The first question should not be which theme to choose or how many products to upload. It should be what the retailer needs to learn.

A useful hypothesis identifies a customer, a need, an offer, and a reason the concept might win. For example, an independent home retailer might test whether urban customers will pay more for a tightly edited collection of storage products designed for small spaces. A specialty food business might test whether an existing local audience will reorder online when delivery is convenient enough.

Those are testable propositions. “We want to sell online” is not. The narrower the commercial question, the easier it becomes to interpret the results and decide what to change next.

Treat the Initial Assortment as a Hypothesis

A test does not need the full assortment a mature business might eventually carry. In many cases, a deliberately limited range produces better information.

A focused assortment reduces inventory exposure and makes customer behavior easier to read. It also forces merchandising discipline. Each item should support the concept rather than simply fill space.

For an early test, retailers can favour products with manageable order quantities, reliable replenishment, clear use cases, and margins that can absorb realistic fulfillment costs. The aim is to learn what customers respond to before committing deeply to breadth.

This is especially useful when a retailer is evaluating a new category, a new audience, or expansion beyond the geographic reach of an existing store.

Build Only What the Test Requires

A test storefront still needs to feel credible. Customers should see accurate product information, transparent pricing, delivery expectations, return terms, contact details, mobile-friendly navigation, and a checkout that works.

What the test does not necessarily require is a custom technology stack, a large portfolio of applications, or months of design work before the first customer arrives.

Hosted commerce platforms such as Shopify make it possible to assemble a working storefront quickly, which allows more of the early effort to go into the offer, merchandising, customer experience, and demand signals rather than infrastructure.

The technology should be sufficient to run the experiment without becoming the experiment itself. If the concept later proves it needs more sophisticated integration, customization, or workflow, that investment can be made with better evidence.

Use Controlled Traffic to Learn, Not to Declare Victory

A retailer does not need a national campaign to test whether a proposition attracts interest. Relevant traffic from an existing customer list, local awareness, social channels, search, partnerships, or a modest advertising test can produce useful early evidence.

Traffic quality matters more than headline volume. Thousands of poorly matched visitors can make a concept look weak for the wrong reason. A smaller group of prospective customers who actually resemble the target market can be far more informative.

Each traffic source should have a purpose. If an email list is expected to validate interest among existing customers, measure that. If search advertising is being used to test whether people actively look for the product category, measure that separately. Combining every source into one top-line traffic number hides the learning.

Read the Funnel as a Diagnosis

Early sales matter, but the path to the sale often tells the retailer more than the sales total alone.

If visitors arrive and rarely move beyond the landing page, the positioning or audience may be wrong. If shoppers view products but do not add them to cart, the problem may be assortment, price, product presentation, or trust. If carts are created but checkout completion is weak, shipping cost, delivery timing, payment choice, or checkout friction deserves attention.

The point is not to overreact to a tiny sample. It is to use behavior to form the next question. A controlled test should create a sequence of increasingly specific decisions rather than one binary verdict on whether the idea is “good” or “bad.”

Pair Digital Behaviour With Direct Customer Feedback

Analytics can show where customers stop. It cannot always explain why.

Retailers can improve the quality of the test by speaking directly with a small number of customers and non-buyers. Ask what they expected, what felt unclear, what they compared the offer with, what nearly stopped the purchase, and what would make them return.

These conversations are particularly valuable for unfamiliar categories or premium products, where hesitation is often caused by questions that the retailer did not realize needed answering.

The strongest signal is not praise. It is repeated behavior or repeated friction that points to the same commercial issue.

Test the Economics Before You Test Scale

Early revenue can create false confidence if the cost of producing the order is not understood. Retailers should model the contribution economics of several realistic order types before increasing traffic.

That calculation should include merchandise cost, packaging, payment processing, fulfillment, shipping subsidies, discounts, returns, and customer acquisition. A concept that appears attractive at the gross-margin level may look very different once the cost of getting the order to the customer is included.

This is particularly important for store-based retailers moving further into ecommerce. An online order can introduce fulfillment and service costs that are not obvious in a traditional in-store transaction, even as it creates the opportunity to reach customers outside the store’s normal trade area.

If the model only works when every customer buys a large basket, pays full price, and never returns anything, the concept is not ready for aggressive expansion.

Define the Next Investment Before the Results Arrive

A useful experiment has a decision rule. Before the test begins, the retailer should decide what evidence would justify the next commitment.

That next commitment might be a larger inventory order, higher marketing spend, expanded geographic coverage, additional staff, a broader assortment, a physical pop-up, or deeper technology investment.

The threshold will vary by category. A high-ticket retailer may learn from a relatively small number of serious enquiries and completed purchases. A frequently purchased consumer product may need a larger transaction sample and evidence of repeat intent.

The discipline is to avoid moving the goalposts after the results arrive. Predefined criteria reduce the temptation to continue because money has already been spent or because the team has become emotionally attached to the concept.

Online Testing Can Inform Physical Retail Decisions

This framework is not only for digital-first businesses. Store-based retailers can use online testing before making larger physical commitments.

A retailer considering a new product category can launch a tightly edited online collection, measure which items attract attention, learn what questions customers ask, and assess demand beyond the current store catchment area. A business considering a pop-up can test the message and product mix before committing to space. A retailer planning geographic expansion can compare response from different regions before making a location decision.

In that sense, ecommerce becomes a research environment as well as a sales channel.

The Strategic Advantage Is Optionality

Retail has always required decisions under uncertainty. Digital commerce does not eliminate that uncertainty, but it can lower the cost of answering some of the questions that used to require a much larger launch.

When the first version of a concept is designed to learn, the retailer preserves optionality. A strong response can justify deeper inventory, marketing, systems, and physical expansion. A weak response can be diagnosed, revised, or stopped before the commitment becomes much larger.

That is the real value of testing before scaling: not avoiding risk, but taking the next risk with better information.

Conclusion

The most useful first version of a retail concept is not necessarily the most complete one. It is the version that can answer the most important commercial questions at an acceptable cost.

By defining the hypothesis, limiting the initial assortment, building a credible storefront, attracting controlled traffic, reading the full customer journey, checking the economics, and setting decision rules in advance, retailers can turn launch from a single high-stakes event into a sequence of informed investments.

The objective is not to prove the idea at any cost. It is to learn enough to know whether the next investment deserves to be made.

Casavogue Highlights Made-in-Italy Design from Calligaris

Italian furniture has long been admired for the way craftsmanship, engineering and refined design come together in pieces intended for everyday life. At Casavogue in Montréal, that tradition is represented by Calligaris, a century-old Italian furniture brand known for its sophisticated approach to contemporary living.

Founded in Italy in 1923, Calligaris has grown from its origins as a chair manufacturer into an international design brand offering furniture for throughout the home. Tables and seating remain an important part of its identity, with a particular emphasis on adaptable designs that respond to how people live and entertain today.

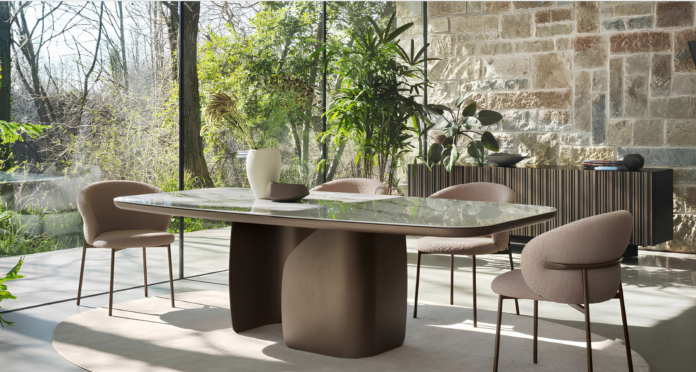
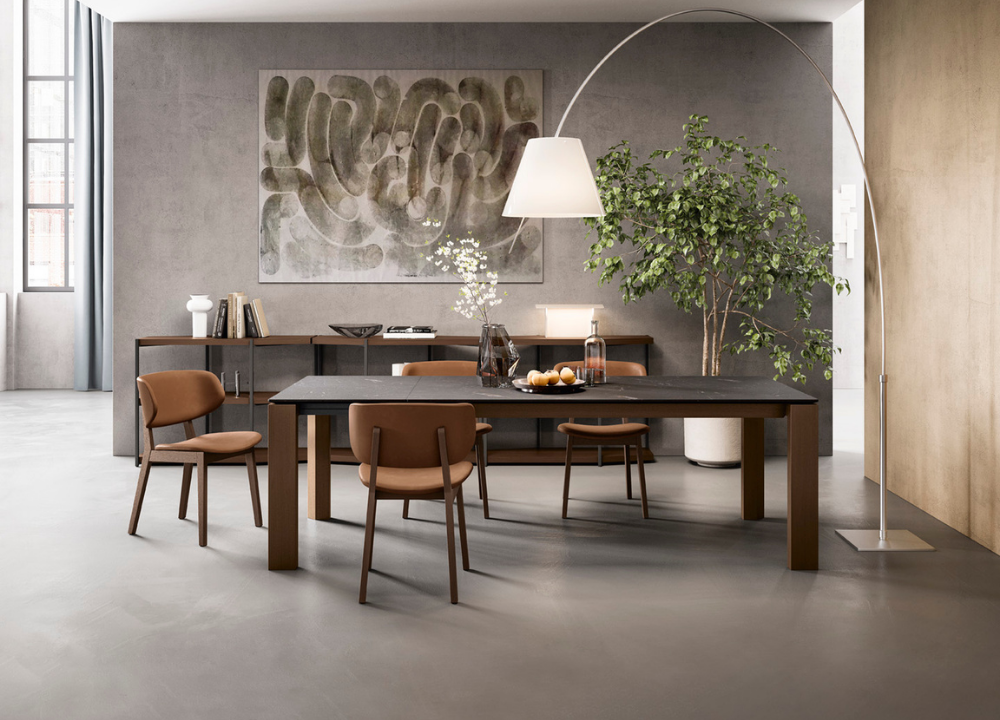
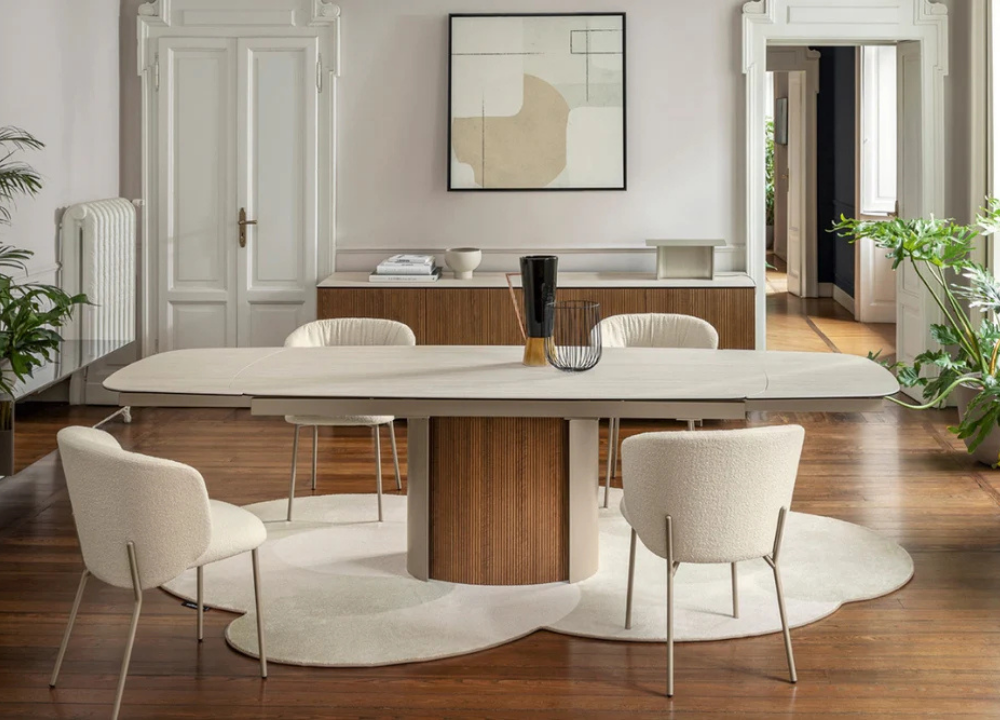
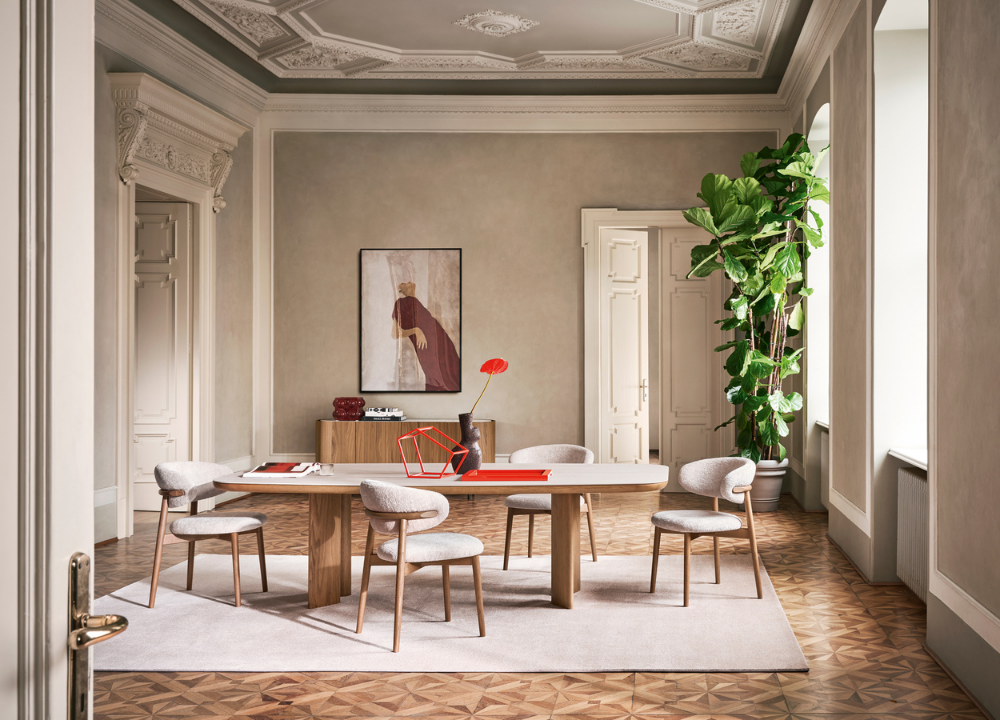
At Casavogue, the Calligaris selection includes Made-in-Italy pieces that demonstrate this combination of design and functionality, including the Omnia and Yoroi extendable dining tables and the Oleandro dining chair.

Italian Design Made for Contemporary Living

Calligaris began in Manzano, in northeastern Italy, an area with a long history of furniture production. More than a century later, the brand continues to draw on that heritage while working with contemporary designers, materials and manufacturing techniques.

Its dining collections place particular attention on proportion, comfort and flexibility. Extendable tables can adapt for larger gatherings while maintaining a refined appearance for everyday use, and seating is offered in numerous materials and finishes to suit different interiors.

The result is furniture with a distinctly Italian design perspective, supported by practical details that become particularly important once the pieces are part of a home.

Omnia extendable dining table

Omnia: Refined and Adaptable

The Omnia extendable dining table demonstrates this approach through a clean rectangular profile and an extension system integrated into the design.

Made in Italy, Omnia combines a wooden structure with a choice of wood or ceramic tabletop finishes. Its internal rotating extension allows the table to expand from 63 to 83 inches, providing comfortable seating for up to 10 people while keeping the legs positioned at the corners.

The design gives homeowners additional dining space when it is needed without requiring a permanently oversized table, making Omnia particularly well suited to interiors where flexibility matters.

Yoroi extendable dining table

Yoroi: A Sculptural Dining Table

For a stronger architectural statement, the Yoroi extendable dining table takes its inspiration from the armour worn by Japanese samurai. Its central base is defined by vertical grooves and wood inserts, creating a sculptural foundation beneath the tabletop.

The Made-in-Italy design is available in customizable finishes and can extend from 78 inches to as much as 118 inches, accommodating approximately six to 10 guests. Casavogue’s featured version pairs the distinctive base with a Calacatta Paonazzo marble-effect top, giving the table a commanding presence within the dining room.

Yoroi shows a more expressive side of Calligaris, where functionality is incorporated into a piece with enough character to anchor an interior.

Oleandro dining chairs

Oleandro: Comfort with a Distinctive Detail

The Oleandro dining chair brings Calligaris’ longstanding expertise in seating into the collection. Designed by Archirivolto, the chair is characterized by generous upholstery and a distinctive backrest whose wooden frame gradually tapers and flattens toward the ends, a detail inspired by the leaves of the oleander plant.

Made in Italy, Oleandro can be personalized through different upholstery and wood choices, including fabric and leather options. Its combination of cushioning, craftsmanship and carefully shaped details allows it to work alongside a variety of dining tables while maintaining a recognizable identity of its own.

Discover Calligaris at Casavogue

Calligaris is part of the curated selection of Italian and international furniture available at Casavogue. Within the retailer’s 38,000-square-foot Montréal showroom, customers can experience furniture in complete room settings and receive personalized guidance when selecting dimensions, materials, finishes and configurations for their homes.

For customers drawn to Italian furniture, the Calligaris collection brings together a century of design experience with the flexibility required for contemporary living. Pieces such as Omnia, Yoroi and Oleandro demonstrate how craftsmanship and thoughtful engineering can shape furniture that is distinctive, comfortable and designed for long-term use.

Visit the Casavogue website to explore its selection of high-end furniture.

The showroom is open Monday through Friday from 9:30 a.m. to 6:00 p.m., and Saturday and Sunday from 9:30 a.m. to 5:00 p.m.

Casavogue is located at 8260 boulevard Saint-Michel, Montréal, QC H1Z 3E2. For more information, call +1 514-360-3565 or book an appointment to receive personalized advice.

Doritos launches rolled tortilla chips exclusively in Canada

Pepsico photo
Pepsico photo

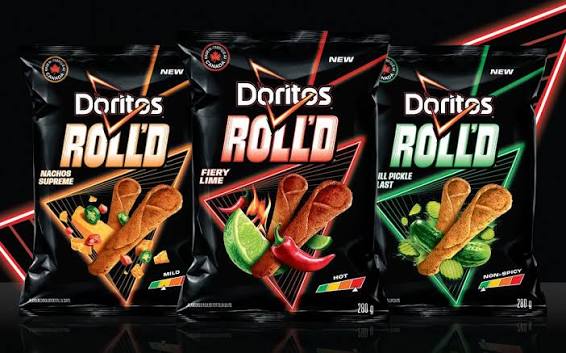
PepsiCo Canada is launching a new Doritos product in Canada, introducing rolled tortilla chips in three flavours as the snack maker expands its product lineup.

Doritos Roll’d chips is available at major retailers nationwide beginning in August. The new product features a rolled format and comes in Nachos Supreme, Fiery Lime and Dill Pickle Blast.

PepsiCo Canada said the launch is aimed at consumers seeking a combination of flavour and texture, with the rolled shape designed to provide a different eating experience from traditional tortilla chips.

The Nachos Supreme flavour combines cheddar, tomato and jalapeño, while Fiery Lime pairs chili with lime. Dill Pickle Blast features dill and a tangy pickle flavour.

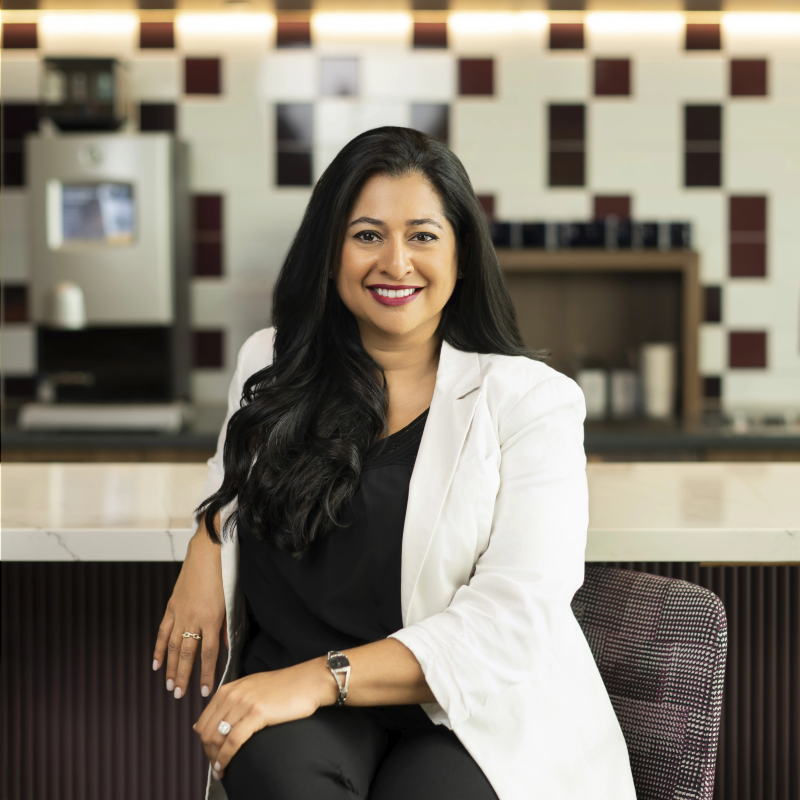
Shirley Mukerjea
Shirley Mukerjea

“Doritos has always delivered bold flavour and unexpected experiences, and Doritos Roll’d brings that spirit to life with a distinctive rolled format and added intensity” said Shirley Mukerjea, Chief Marketing Officer, PepsiCo Canada. “Younger Canadians are looking for snacks that engage more than taste alone, so we brought together flavour, texture, crunch and visual appeal in one memorable bite, and we’re incredibly excited for Canadians to try it.”

The company said its research found that Gen Z consumers are looking beyond flavour when choosing snacks, with an interest in products and experiences that appeal to multiple senses and allow them to express their personalities.

PepsiCo Canada said the rollout will also include social media content, creator activity and other promotional events tied to the new product.

PepsiCo generated nearly US$94 billion in net revenue in 2025, according to the company. Its portfolio includes Lay’s, Doritos, Cheetos, Gatorade, Pepsi-Cola, Mountain Dew, Quaker and SodaStream.

More from Retail Insider:

Westcliff acquires Kingsway Mall in Edmonton

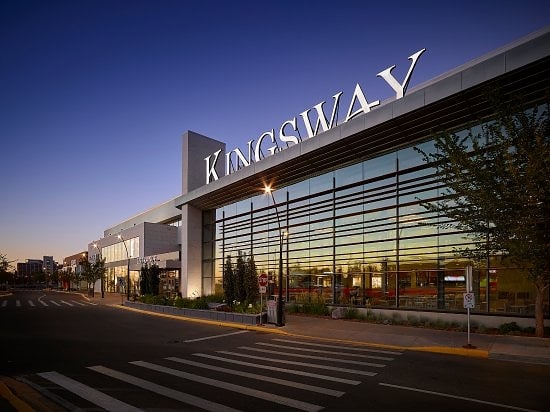
Montreal-based real estate company Westcliff announced Monday the acquisition of Kingsway Mall, a dominant regional enclosed shopping centre located in Edmonton, Alberta.

The acquisition marks Westcliff’s return to Western Canada through a prominent retail destination serving one of Alberta’s most important urban markets, said the company in a news release.

“Kingsway Mall represents the kind of asset that has always been central to Westcliff’s approach. A well-established property, deeply rooted in its region, with the ability to serve its community for generations to come,” said Alan Marcovitz, President of Westcliff. “Our return to Western Canada reflects our confidence in the Edmonton market and in the enduring value of retail destinations that bring people together.”

The acquisition adds a well-located, high-traffic asset to Westcliff’s growing national portfolio in a trade area the company believes is positioned for sustained growth, it said.

Kingsway was co-owned by Oxford Properties and managed by Oxford Properties Group, a global leader in premium real estate. Oxford is owned by OMERS, the defined benefit pension plan for Ontario’s municipal employees

No financial details of the transaction were disclosed.

Westcliff photo
Westcliff photo

“We see an opportunity to build on that foundation and support its continued role as a destination for shoppers across greater Edmonton,” said Nicolas D’Aoust, Vice President of Westcliff and Head of Leasing. “Driven by a young and educated population, Edmonton’s dynamism reinforces its appeal as a strategic market with promising long-term economic prospects.”

Westcliff said it will work closely with Kingsway Mall’s existing management and operations teams to support a smooth transition and maintain continuity for tenants, shoppers and the broader community.

“Kingsway Mall has long served as a gathering place woven into the daily life of the surrounding neighbourhoods. Preserving and strengthening that role for the community will be a primary goal for us,” said Adam Marcovitz, Vice President of Westcliff.

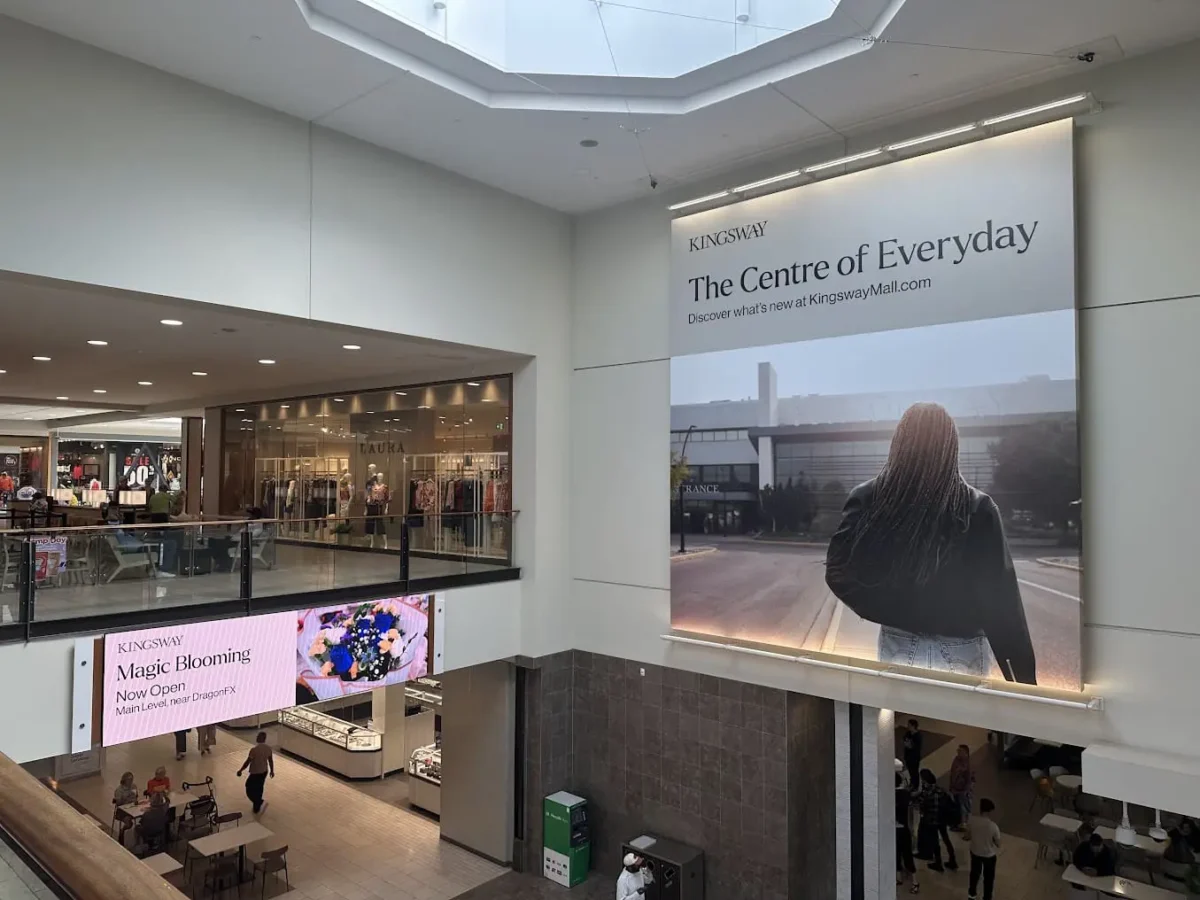
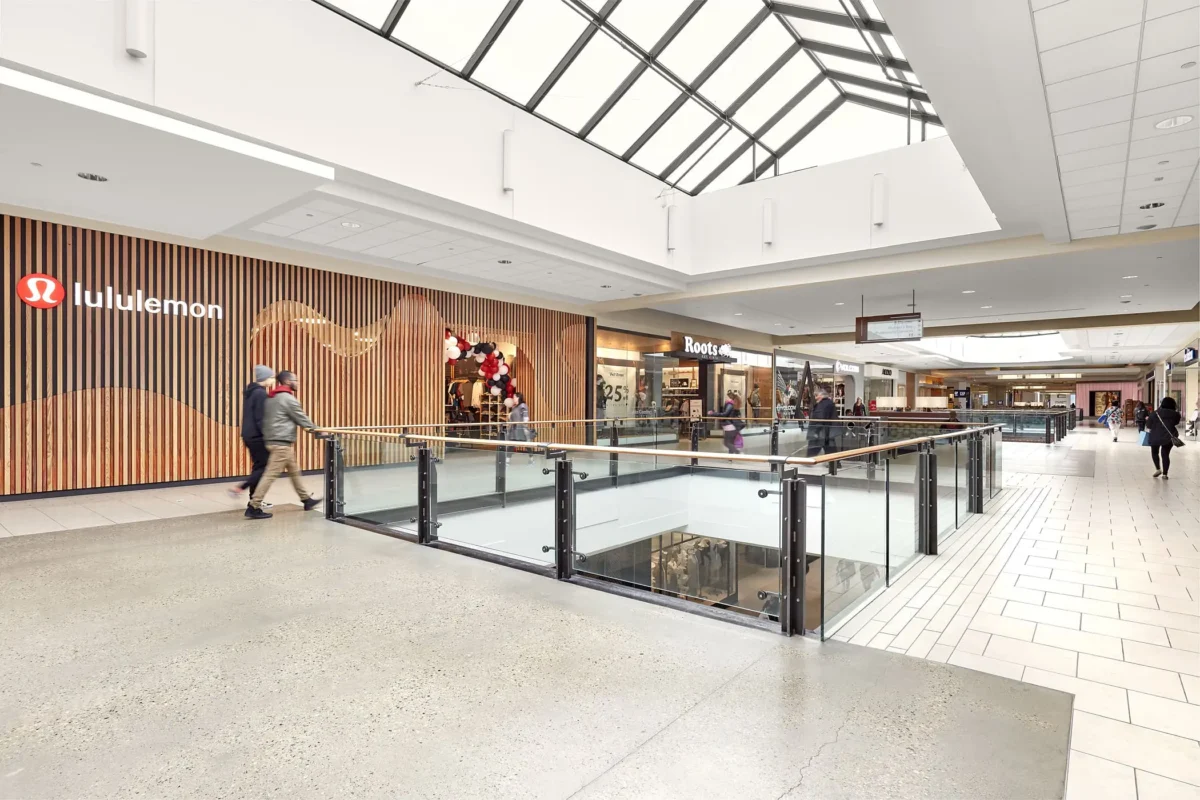
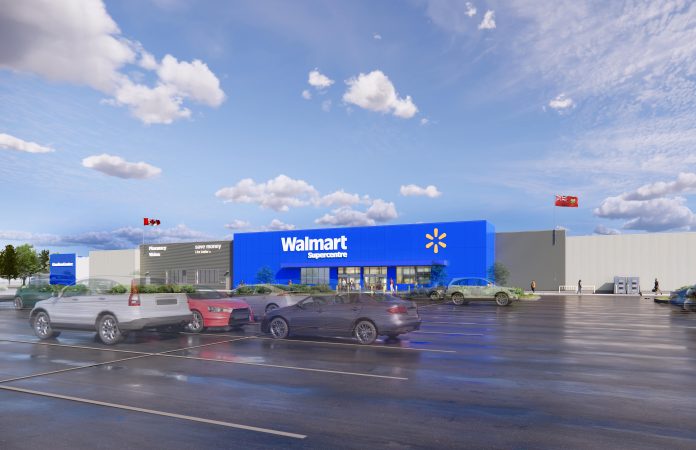
Centrally located just north of downtown Edmonton, Kingsway Mall has been around since 1976. On a 41.8-acre site, the 880,049-square-foot shopping centre features more than 160 stores and services, including Walmart Supercentre, HomeSense, Marshalls, Shoppers Drug Mart, Aritzia, Sephora, Lululemon and Browns Shoes, and attracts close to seven million visitors annually. With annual retail sales of $715 per square foot, Kingsway Mall is a leading Edmonton shopping destination with strong market fundamentals, deep local relevance that maintains strong ties to the community through initiatives that support local causes and organizations, added Westcliff.

Founded in 1972, Westcliff is a privately owned, diversified real estate development and management firm with holdings across shopping centres, office, industrial, residential and hospitality assets in Canada and the United States.

More from Retail Insider:

Westcliff photo
Westcliff photo

Walmart+ Takes Bigger Role as Walmart Expands Canadian Digital Strategy

Photo- Walmart
Photo- Walmart

Walmart is giving Canada a larger role in its international digital expansion as the retailer builds its membership, e-commerce and Marketplace businesses beyond the United States.

During Walmart Inc.’s second-quarter earnings call last week, CEO John Furner pointed to Canada several times while discussing the company’s international growth. Walmart International e-commerce sales increased 19 per cent during the quarter, with China, India and Canada identified as markets leading the growth. E-commerce now accounts for about 30 per cent of Walmart International’s sales mix.

Canada is also the first Walmart market outside the United States to receive Walmart+, the company’s paid membership program. Walmart+ launched in Canada on June 4, building on the retailer’s Delivery Pass service with additional benefits including free Walmart.ca shipping with no minimum purchase and an included Crave subscription.

Furner highlighted the Canadian Walmart+ launch alongside another development during the quarter: Walmart expanded capabilities from its U.S. Marketplace platform into Canada and Mexico. He grouped membership, Marketplace, fulfillment services and advertising among the businesses Walmart is increasingly deploying across international markets.

The comments put the Canadian Walmart+ launch into a broader context. Walmart has spent several years developing its membership and e-commerce businesses in the United States, and Canada is now the first international market where the company is extending the Walmart+ model.

Walmart+ Builds on Delivery Pass

Walmart+ costs $8.97 per month or $89 annually in Canada. Existing Delivery Pass members, who had been paying the same $89 annual price since that program launched in 2023, were automatically moved to Walmart+ when the new program launched in June.

The Canadian program includes unlimited free same-day delivery from stores on orders over $35, along with discounted Express Delivery. Members also receive free shipping with no minimum order on thousands of eligible products sold through Walmart.ca and the Walmart app.

Walmart included Crave Standard with Ads as part of the membership at no additional cost, adding an entertainment component to the Canadian program. At the time of the launch, Catherine Theberge-Conner, Head of Membership at Walmart Canada, said the company was bringing together grocery and general merchandise delivery with benefits outside retail.

Andrew Go, Vice President of E-Commerce and Marketing at Walmart Canada, also highlighted the removal of Walmart.ca’s shipping minimum as a significant change for the retailer’s Canadian online business. The additions give Walmart more opportunities to keep members within its ecosystem, from regular grocery orders to smaller online purchases that may previously have fallen below a free-shipping threshold.

Membership Becoming More Important to Walmart

Walmart’s latest results show the growing importance of membership to the company. Membership fee revenue increased nearly 17 per cent during the quarter, while Walmart+ continued to record double-digit membership growth in the United States. Management said the first half produced the strongest membership growth in the U.S. program’s history.

CFO John David Rainey told analysts that Walmart members spend approximately four times more than non-members. The figure refers to Walmart’s broader membership business and is not a measure of spending by Canadian Walmart+ members.

Membership generates fee revenue while giving Walmart another way to increase shopping frequency and customer spending. Canada now gives the company its first opportunity to extend Walmart+ beyond the U.S., where the program has had several years to develop.

Furner returned to the Canadian launch at the end of Thursday’s earnings call, mentioning Walmart+ alongside continued growth in e-commerce, Marketplace and advertising.

Canada Among Markets Leading E-Commerce Growth

Walmart did not disclose a separate Canadian e-commerce growth rate for the quarter, although management twice identified Canada as one of the markets contributing to Walmart International’s 19 per cent e-commerce increase.

Rainey said Walmart has been deploying digital capabilities developed in the United States into other markets, allowing the company to move faster operationally and grow at a lower marginal cost. He also linked continued e-commerce growth to the development of businesses including Marketplace, advertising, data services and membership.

Walmart already has a sizeable Canadian audience across its physical and digital channels. The company operates more than 400 stores nationally and says both its stores and Walmart.ca serve or attract more than 1.5 million customers or visits daily. Its current investment program is adding stores and supply-chain capacity to support further growth.

Marketplace Capabilities Expand in Canada

Walmart told investors that it expanded capabilities from its U.S. Marketplace platform into Canada and Mexico during the quarter. Marketplace allows third-party sellers to offer products through Walmart’s digital properties, increasing the assortment available beyond merchandise sold directly by Walmart.

The platform also feeds other parts of Walmart’s digital business, including fulfillment and advertising. Rainey told investors that sustained e-commerce momentum supports growth in Marketplace, advertising, data ventures and membership, businesses that are becoming increasingly important to Walmart’s financial model.

Management said Walmart is increasingly developing capabilities that can be scaled across multiple countries. The Canadian expansion of Walmart+ and Marketplace provides a current example, with platforms developed in the U.S. being extended into Walmart’s Canadian operation.

Stores and Supply Chain Support Digital Growth

Walmart’s Canadian digital expansion is occurring alongside one of the largest physical investment programs in the retailer’s history in this country. Walmart Canada announced in January 2025 that it would invest $6.5 billion over five years in its Canadian store and supply-chain network, including dozens of planned new stores and new distribution infrastructure. The company described it as its largest investment in Canada since entering the market 30 years earlier.

New Supercentres are being developed with online pickup and delivery incorporated into their operations. Walmart’s planned southwest Edmonton location, expected to open in 2027, will offer online pickup and delivery for grocery and general merchandise. Other recently announced locations are being designed with similar capabilities.

The relationship between stores and e-commerce was a major theme of Thursday’s earnings call. Walmart executives described stores as an increasingly important part of the company’s fulfillment network as customers move between in-store shopping, pickup and home delivery. The hard fulfillment figures discussed on the call were specific to the U.S. business, but Walmart Canada’s current store program is also incorporating pickup and delivery into new locations.

Supply-chain investment is happening at the same time. Walmart Canada opened a 750,000-square-foot fulfillment centre in Milton, Ontario, in June, adding capacity for more than 43,000 unique products and approximately 65,000 pallets. The facility supports Walmart’s core assortment, extended online assortment and Walmart Fulfillment Services, and the company says some local customers are already receiving same-day delivery through it.

The Milton facility follows the opening of Walmart Canada’s 550,000-square-foot Vaughan Ambient Distribution Centre in 2025. The Vaughan facility uses automation, robotics and AI-driven warehouse management and currently serves 131 stores and two fulfillment centres across Ontario.

Competing for More Canadian Shopping Trips

Walmart+ adds another paid membership offering to a Canadian market where membership programs already play an important role in retail. Amazon has used Prime to connect shipping, digital entertainment and other services with its e-commerce business, while Costco has built its retail model around paid membership. The programs differ substantially, but each creates an ongoing relationship with customers beyond an individual purchase.

Walmart enters that competition with a large Canadian store network and a substantial grocery business. Same-day store delivery allows Walmart+ to cover frequently purchased products such as groceries and household goods alongside conventional e-commerce orders, while the inclusion of Crave gives members a benefit they can use without making a retail purchase.

The opportunity for Walmart is to convert more of its existing Canadian store and online traffic into membership relationships and greater use of its digital services. The company is building Walmart+ alongside Marketplace, e-commerce, fulfillment capacity and a multi-billion-dollar investment in its Canadian store and supply-chain network.

Canada’s position as the first international Walmart+ market also gives Walmart an early indication of how its membership model performs outside the United States. Thursday’s earnings call shows that the Canadian business is already part of Walmart’s wider effort to take its membership and digital platforms into more international markets.

More from Retail Insider:

Ottawa’s Tariff Retaliation Risks Raising Grocery Prices for Canadians

Grocery store in Quebec. Photo: Vergo Construction

Canada’s trade negotiations with the United States have failed. Washington has imposed 50% tariffs on approximately $28 billion worth of Canadian products, and Prime Minister Mark Carney has promised a dollar-for-dollar response beginning September 8.

Retaliation may be politically inevitable. But Ottawa must proceed very carefully. In attempting to punish Washington, Canada could easily end up punishing Canadian families at the grocery store.

Tariffs are taxes. Full stop.

A Canadian counter-tariff is collected from the Canadian company importing the American product. The exporter may absorb some of the cost, but importers, distributors and retailers will inevitably pass part of it along. Grocery margins are already thin.

Eventually, the cost appears at the checkout.

We learned that lesson in 2025, when the Trudeau government imposed 25% counter-tariffs on a remarkably broad range of American products. The list included orange juice, peanut butter, coffee, tea, chocolate, rice, pasta, fruit, vegetables, poultry, dairy products, cooking oils, sauces and soups.

It was political theatre masquerading as food policy.

A subsequent Bank of Canada study found that prices for tariffed goods increased by approximately 6% relative to comparable untariffed products. For tariffed food and beverages, the increase approached 8% at its summer peak. Retailers did not pass along the entire tariff, but consumers clearly paid part of it.

Most of those consumer tariffs were removed after six months, limiting the damage. This time, however, the retaliation could be broader, higher and more persistent. If food, ingredients, packaging and agricultural equipment are included, the combined cost could approach $200 annually for an average Canadian household. That estimate reflects not only direct tariff costs, but also the expense of changing suppliers, importing from more distant markets and operating a less efficient supply chain.

Lower-income households would be hit hardest. They have fewer opportunities to stock up, shop at several stores or buy in bulk. Food inflation is also cumulative. Canadians do not recover the purchasing power lost after years of higher grocery prices simply because inflation eventually slows.

Food prices are already roughly 27% higher than they were five years ago. Still, adding more pressure would be reckless.

There is also the risk of a price-umbrella effect. When an American product becomes more expensive, competing Canadian and foreign brands face less pressure to keep their prices down. Importers may replace nearby American suppliers with more distant sources, increasing transportation, warehousing and contracting costs.

The Bank of Canada did not find a statistically significant broad spillover to substitutes in 2025. That is reassuring, but it is no guarantee this time. The coming tariffs could last for years rather than months. The same research found that retailers passed along more of the cost when they believed tariffs would remain. Expectations matter.

Once companies conclude that a tariff is permanent, they renegotiate contracts, change suppliers, rebuild distribution networks and reset prices. Those costs can spread well beyond the products appearing on Ottawa’s retaliation list.

This is why food must be spared.

The final list has not yet been published, but dairy has already been mentioned as a potential target. That makes little economic sense. Canada already controls dairy imports through supply management and tariff-rate quotas. Additional tariffs would affect specialized American products and ingredients without necessarily creating meaningful political leverage in Washington.

Food-manufacturing ingredients should also be exempt, along with packaging, fertilizer, animal feed, refrigeration equipment, agricultural machinery and replacement parts. Tariffing these products would raise the cost of producing Canadian food. A product does not need to appear on a grocery shelf to increase grocery prices.

Ottawa should also resist the argument that food tariffs are harmless whenever Canadian substitutes exist. Restricting a lower-priced import reduces competition and gives domestic suppliers more room to increase prices. Canadian producers may benefit, but Canadian consumers can still lose.

If Canada must retaliate, it needs a scalpel, not a sledgehammer.

Countermeasures should focus on non-essential goods with a low weight in household budgets, sufficient alternative suppliers and genuine political importance in the United States. Government procurement restrictions, investment screening and coordinated legal challenges should also be considered instead of relying almost exclusively on border taxes.

Every proposed tariff should pass four tests. Is the product essential to Canadian households? Is it an input for Canadian production? Can it be sourced elsewhere without significantly higher costs? Will targeting it exert meaningful political pressure in the United States?

If a tariff increases Canadian food-production costs or grocery bills without creating real pressure in Washington, it has failed.

Trump’s tariffs are harmful because they raise costs, distort supply chains and weaken competitiveness. Canada should not reproduce the same damage at home simply to demonstrate resolve.

Retaliate if we must. But keep food—and everything required to produce it—off the tariff menu. The objective should be to pressure Washington, not weaponize the cost of living against Canadians.

More from Retail Insider: