The campaign, which runs until Sept. 27, allows customers to make donations at checkout in Staples stores across Canada. The company said all funds collected remain in the communities where they are raised and will be distributed through United Way Centraide and Kiwanis to support local students and families.
The annual initiative is part of Staples Canada’s community fundraising efforts ahead of the back-to-school season. According to the company, the campaign has raised close to $20 million over the past two decades through contributions from customers, employees and charitable partners.
“The Staples School Supply Drive demonstrates the power of communities coming together to support local students and families,” said Adrian Lang, chief people and legal officer at Staples Canada. “As we launch the 2026 campaign, we’re proud to continue working with our customers, team members and charitable partners to help students start the school year with confidence.”
Adrian LangDan ClementDavid MacLennan
Staples Canada said donations collected through the campaign will remain in the communities where they are received, with United Way Centraide and Kiwanis helping direct support to local students and their families.
United Way Centraide Canada said its network operates in more than 5,000 communities across the country, working with donors, volunteers, governments, workplaces, community organizations and other partners on programs that support children and youth, financial security, mental health and people facing crises.
“We are grateful to Staples Canada for being a committed partner in supporting children, youth and their families,” said Dan Clement, president and chief executive of United Way Centraide Canada. “We know that families across the country are feeling financial anxiety in many aspects of their lives, and the Staples School Supply Drive is one way we can help students access the supplies they need to succeed in the classroom while creating some relief for their families and building stronger communities for generations to come.”
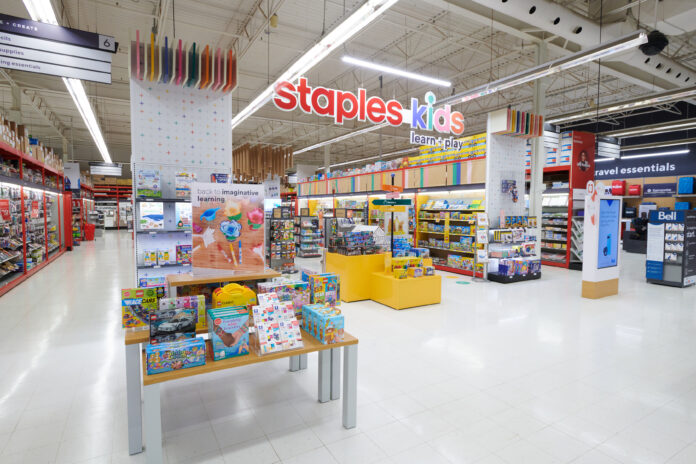
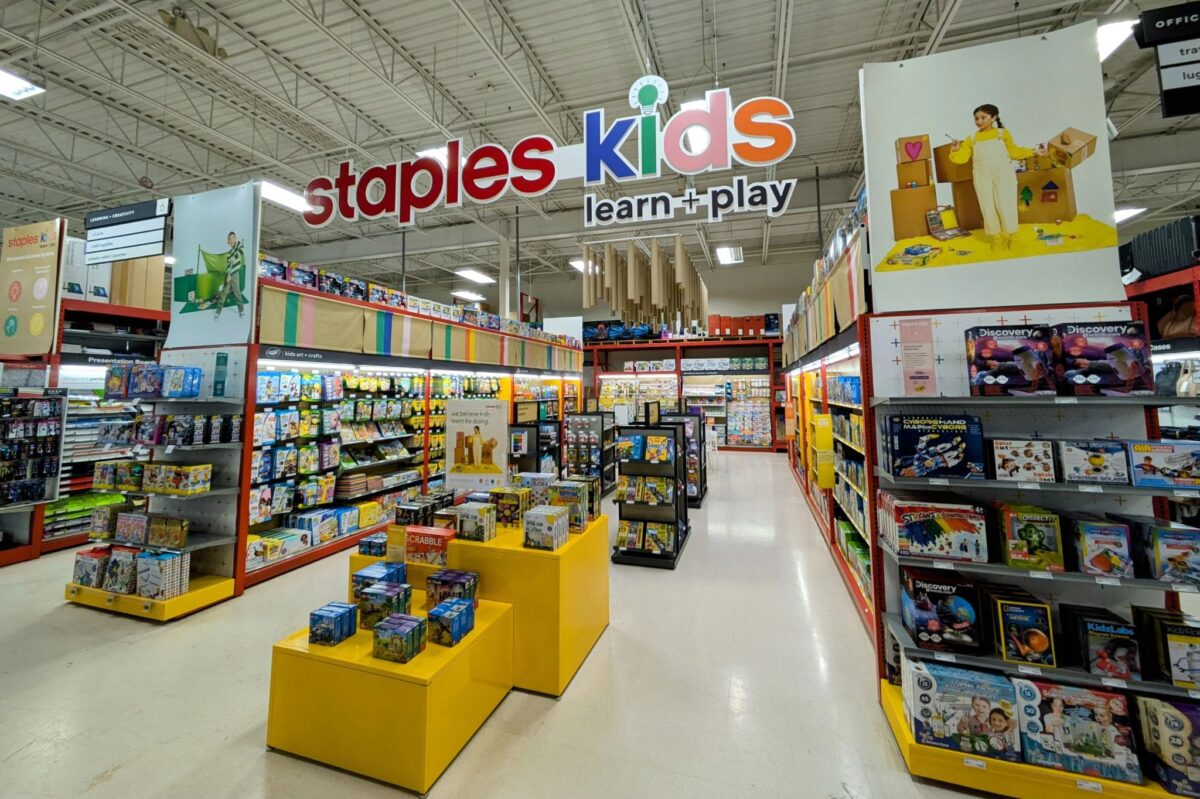
Staples Kids in London, Ontario (Image: Staples)
Kiwanis said its clubs work to improve the lives of children through community initiatives. The organization said many Kiwanis clubs in Ontario have supported the school supply campaign for more than 22 years by helping distribute essential supplies to children.
“Kiwanis Clubs across Ontario have proudly supported the Staples School Supply Drive since the early 2000s. We are grateful for the unwavering dedication of Staples Canada’s Team Members and the generosity of its customers whose support continues to make this campaign a success,” said David MacLennan, president-elect of the Kiwanis Club of Stratford. “Some students lack the essential school supplies they need to succeed, and through our partnership with Staples Canada, we help drive donations that empower students and promote academic success in communities across Ontario.”
Staples Canada said customers can make donations in stores until Sept. 27 or contribute through the campaign’s online donation page.
US President Donald Trump’s new 50% tariffs on Canada mark another shift in an unpredictable trade environment, adding another layer of uncertainty for retailers already trying to keep up with ongoing tariff volatility, according to a new report by DOSS.
The study found that:
On average, 38% of company revenue is directly impacted by tariff policy changes
Passing increased tariff costs on to customers (33%) is the most common strategy companies are using to manage rising expenses
45% of decision-makers report holding excess inventory longer than planned, and 58% say their companies absorbed costs they initially intended to pass on to customers
40% say their companies began repricing affected goods or services in response to tariff changes
25% accelerated purchases to lock in pricing, while 25% re-forecasted revenue or margin projections
53% say they are spending more time reacting to trade policy changes than investing in long-term growth
For businesses already navigating tariff uncertainty, another escalation could create additional pressure across pricing, inventory, and operations.
Question: With tariffs now at 50%, what are retailers telling you is their biggest operational challenge compared with previous rounds of tariff increases?
Answer: Past tariff rounds gave retailers room to make one move at a time. They could shift some sourcing, go back to their suppliers to renegotiate, and see how it played out. At 50% there isn’t time for that. Prices, sourcing, and inventory all have to change together, and then they have to change again a few weeks later when the policy moves again. The hard part is that most teams are running those decisions off a pile of spreadsheets and systems that don’t really talk to each other. When your inventory, purchasing, and finance numbers don’t line up in one place, every new tariff turns into a scramble instead of a quick adjustment.
Q: Your research found that 53% of decision-makers are spending more time reacting to trade policy than investing in long-term growth. What does that look like in practice, and what are the longer-term consequences for retailers?
A: We found that 53% of decision-makers are spending more time reacting to trade policy than investing in long-term growth. In practice that means the person who should be planning next year’s assortment or looking at a new market is stuck rebuilding cost models every time another tariff headline hits. The growth conversations turn into contingency conversations. And that adds up. A competitor dealing with less volatility, or one that just has a clearer view of its own operation, gets to spend those same hours on the actual business. We see the same pattern at DOSS: the teams that climb back out of firefighting and get back to driving the outcomes that grow the business are usually the ones who hold their ground.
Ron Lach photo
Q: The study shows that many companies are absorbing costs while others are passing them on to consumers. What factors determine which approach a retailer takes, and how sustainable are those strategies?
A: It mostly comes down to pricing power. Retailers with brand loyalty can raise prices without losing customers. The ones competing mainly on price tend to eat the cost, because a price increase just sends shoppers to a competitor. But there’s something underneath that decision a lot of people miss, which is whether the retailer actually knows its true landed cost and contribution margin by SKU and by channel, in real time. Many of them don’t. Their cost data sits in separate systems and only comes together in a delayed fashion at month-end. If you can’t tell which products are losing money, you end up absorbing costs across the whole catalog. And absorbing only works for so long. Eventually the margin pressure shows up as layoffs, reduced investment, or cheaper products, and none of that holds up when the rules keep changing.
Q: Inventory management appears to be under significant pressure, with companies holding excess inventory and accelerating purchases. How are retailers balancing the risk of overstocking against the uncertainty of future tariff changes?
A: Hold too much and you’ve got cash and warehouse space locked up in a product you might have to mark down later. Hold too little and you’re exposed to a stockout if tariffs jump before your next order lands. So retailers are hedging. They’re buying ahead on the core SKUs they’re confident about and easing off on the discretionary stuff, where a bad call costs more. What really separates the teams that are world-class is that they are working from live numbers instead of guessing at month-end. If you can see your days of inventory, the cash tied up in stock, and where your reorder points sit as they move, you can make the call on purpose. If you’re piecing it together from spreadsheets after the fact, you’re guessing, and expose your working capital to risk.
Q: Given the ongoing unpredictability of U.S.-Canada trade policy, what capabilities or strategies will distinguish retailers that adapt successfully from those that continue to struggle?
A: The retailers who come out ahead will be the ones who can see their costs and their supply chain in real time, not once a quarter. If you’re waiting for the next earnings cycle to understand your tariff exposure, you’re working off old information. Diversifying your supply base helps, but speed is what really matters here. Can you model a new tariff scenario and act on it in days rather than weeks? And knowing what to do isn’t enough on its own. The retailers who win can push the change through purchasing, inventory, and pricing without it getting stuck in a dozen manual handoffs. That’s what we focus on at DOSS: getting retailers off systems that just tell them what already happened, and onto an operation that can respond while it still matters. The ones planning on an annual cycle while policy shifts every month are going to keep falling behind.
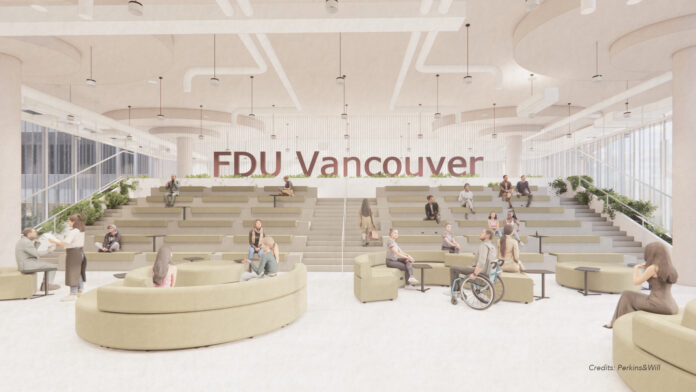
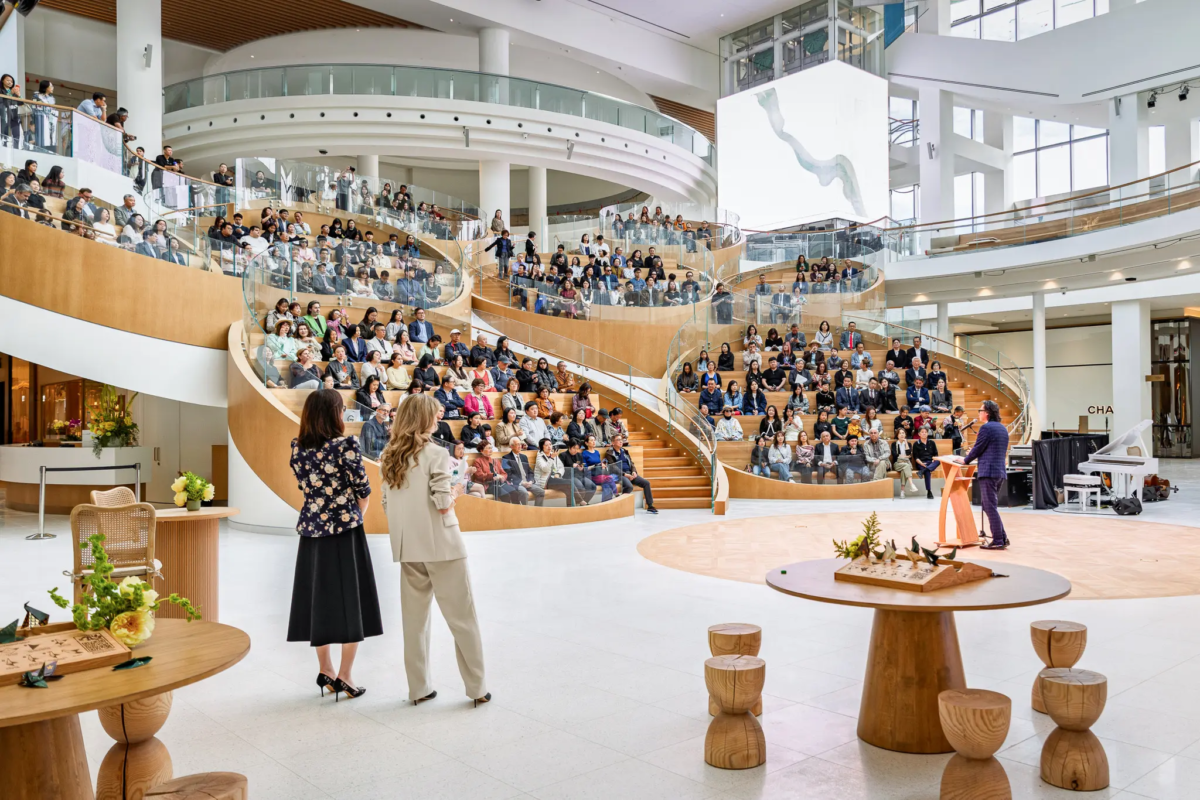
Tiered Seating. Rendering: Fairleigh Dickinson University
Fairleigh Dickinson University will open its new Vancouver campus at Oakridge Park for the fall 2026 term, bringing students, faculty and university visitors to the recently opened mixed-use development throughout the academic year.
The 70,000-square-foot facility will consolidate FDU Vancouver’s two existing downtown locations into a single campus. The move places the university alongside Oakridge Park’s growing collection of retail, dining, residential, office, cultural and civic uses, adding another source of weekday activity to the five-million-square-foot redevelopment.
Fairleigh Dickinson University is a private, not-for-profit institution with two campuses in New Jersey and an established presence in Vancouver. Its Canadian campus opened in 2007 and offers undergraduate and graduate programs in business, health, hospitality and tourism, humanities and information technology.
FDU President Michael Avaltroni described the move as an important stage in the university’s growth in British Columbia.
“Expanding to Oakridge Park is a defining moment for FDU Vancouver,” Avaltroni said. “This campus will deepen our engagement with local BC businesses, expand experiential learning opportunities, and create a space where innovation, culture, and academic excellence converge for the benefit of students and the broader community.”
New Campus Consolidates Downtown Operations
FDU’s Vancouver operations are currently divided between locations at 842 Cambie Street and 89 West Georgia Street. The university will bring those facilities together at Oakridge Park, providing a larger environment for teaching, student services, collaboration and events.
The new campus will include 18 classrooms, five computer labs, two semi-wet science laboratories, collaboration rooms, a library, learning and writing centres, and dedicated space for student government and clubs. A tiered multipurpose area will accommodate student programming, industry events and other gatherings.
FDU’s most recent published campus statistics show that 610 students were enrolled in Vancouver in fall 2025. That total included 495 graduate students and 115 undergraduate students, with most attending on a full-time basis.
The university has not publicly disclosed its projected fall 2026 enrolment or the eventual operating capacity of the Oakridge Park campus. The larger facility provides space for expanded academic programming, industry engagement and student services as FDU develops its Vancouver presence.
The university’s new address will be 210–5968 Cornelia Mews. FDU has said the campus will be operational for the beginning of the fall term, although a precise opening date has not been announced.
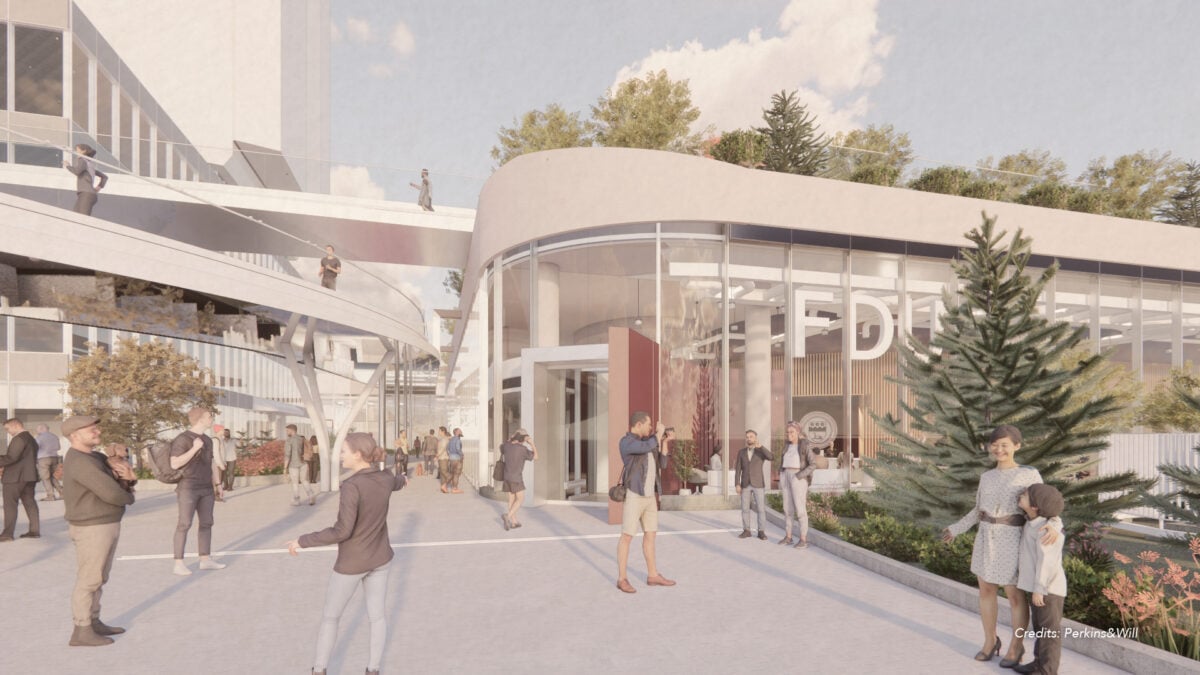
Rendering: Fairleigh Dickinson University
Adding Weekday Activity to Oakridge Park
The campus represents a different kind of anchor for Oakridge Park. Luxury stores and destination restaurants can draw visitors from across Metro Vancouver, with many arriving for occasional shopping or dining trips. A university creates a population that returns several times each week and may spend hours within or around the property.
Students and faculty could arrive throughout the morning and remain through the afternoon or evening, supporting activity during periods that may be quieter for traditional shopping. University receptions, networking functions, visiting speakers and alumni events will also bring employers, families and other guests into the development.
Chrystal Burns, Executive Vice President, Canadian Retail Experience at QuadReal Property Group, said FDU’s expansion represents an important milestone for the wider Oakridge community.
“This partnership exemplifies our ability to deliver bespoke, world-class spaces that elevate both academic and student experiences,” Burns said. “By fostering a forward-thinking, inclusive campus environment, we are proud to play a key role in FDU’s growth and continued success in shaping the next generation of leaders.”
The location gives students direct access to Oakridge–41st Avenue Station on the Canada Line, along with bus service on Cambie Street and West 41st Avenue. That connectivity will be important for a university serving students from across Metro Vancouver and a substantial international population.
Retail Benefits Likely to Be Concentrated
The arrival of hundreds of students will generate additional foot traffic, although the resulting spending will likely be concentrated within a relatively narrow group of businesses.
Oakridge Park’s current retail mix is strongly oriented toward luxury and premium brands. Chanel, Louis Vuitton, Prada, Bvlgari, Tiffany & Co., Brunello Cucinelli, Rolex and other international luxury names are among the retailers operating or preparing to open at the property.
Most students are unlikely to become frequent customers of those boutiques. Their routine purchases will probably be directed toward grocery, pharmacy, casual food, cafés and practical services.
Safeway is positioned to become one of the clearest beneficiaries. The full-service grocery store and pharmacy can serve students looking for prepared foods, snacks, personal-care products, medication and other everyday necessities.
A forthcoming A&W on a lower level of the development will add a familiar quick-service option. Oakridge Park also offers cafés, bakeries and a growing collection of restaurant concepts, although much of the dining mix sits above conventional food-court pricing.
Time Out Market Vancouver provides the largest concentration of food choices at the development. The approximately 51,000-square-foot market contains 18 kitchens, three bars, coffee and dessert concepts, event space and seating for close to 1,000 people.
Its lineup includes burgers, fried chicken, pizza, tacos, noodles and other casual formats, along with concepts led by recognized Vancouver chefs. The market could become a gathering place for students, faculty and university visitors, though the frequency of student visits will depend partly on price.
More accessible fashion and lifestyle retailers, including Aritzia, Sephora, lululemon and Sporting Life, may see some crossover. Oakridge Park also includes pharmacy, laboratory, medical and dental services that could benefit from a larger population spending time on site.
The property has a limited selection of telecommunications, stationery, value-oriented fashion and other categories frequently found near a major post-secondary campus. FDU’s arrival may reveal opportunities for additional affordable food, services and everyday retail as Oakridge Park’s residential, office and student populations grow.
Oakridge Park in Vancouver. Photo: Craig Patterson
Potential Connections with Oakridge Businesses
FDU has placed business and industry engagement near the centre of its rationale for moving to Oakridge Park.
The university says the campus will support experiential learning, career development and closer connections with British Columbia employers. Its academic programs have potential links to several sectors represented within the development, including retail, hospitality, tourism, technology, marketing, property management, health services and events.
Oakridge Park could provide a setting for internships, class projects, networking functions and employer partnerships. QuadReal, Westbank, retailers, restaurant operators, medical businesses and cultural organizations are all active within or connected to the project.
The inclusion of a large multipurpose area for student and industry events indicates that outside engagement will form part of the campus experience.
The university has already promoted business networking, alumni and partner events connected to the new location. Those activities will bring a wider group of visitors to Oakridge Park, including employers, alumni, visiting executives, speakers and students’ families.
Some of those visitors may have different spending patterns from the general student body, creating occasional opportunities for the development’s restaurants, services and premium retailers.
Oakridge Park opening talk at 9:30am on Thursday, May 28, 2026. Photo: Oakridge Park
Another Layer in Oakridge Park’s Mixed-Use Strategy
Oakridge Park opened its first major retail phase in May 2026 following years of redevelopment at the former Oakridge Centre site.
Co-developed by QuadReal Property Group and Westbank, the completed project is expected to span more than five million square feet across a 28-acre site. Plans include approximately 650,000 square feet of retail, more than 3,000 residences, around 720,000 square feet of office space and a nine-acre park.
The development will also include a community centre, public library, performance venues and other cultural and civic components. More than 6,000 residents and approximately 3,000 office workers are anticipated at full build-out.
Each component contributes a different population and pattern of use. Residents support morning, evening and weekend activity, while office employees create weekday demand. Retailers, restaurants and cultural programming bring regional visitors, and civic amenities attract people from the surrounding community.
FDU adds a student and academic population to that mix. Its direct contribution to luxury retail sales may be limited, but its presence can increase weekday activity, transit use and demand for food, grocery and services. Students also introduce a younger demographic to a development that has so far been most closely associated with its collection of luxury flagships.
Oakridge Park’s long-term performance will depend on how effectively it serves the different groups that live, work, study, shop and spend time there. FDU’s move adds another substantial use to that ecosystem and strengthens the development’s emerging role as a new urban district within Vancouver.
With the Fall Toronto Gift + Home Market opening in less than a week, qualified retail buyers still have time to register and plan their visit to Canada’s largest wholesale buying event for the gift, home and lifestyle industries.
Hosted by the Canadian Gift Association, known as CanGift, the market takes place August 9 to 12, 2026, at the Toronto Congress Centre – North. Hundreds of exhibitors and qualified retail buyers from across Canada are expected to participate.
The event arrives at an important point in the retail calendar, as businesses prepare their fall assortments and finalize purchasing decisions ahead of the holiday shopping season. Buyers will be able to meet suppliers, examine products in person and identify merchandise that could help differentiate their stores during the busiest months of the year.
This year’s market also forms part of CanGift’s 50th-anniversary celebrations, marking five decades of connecting Canadian retailers with suppliers, brands and emerging businesses.
What You’ll Find
The Fall Toronto Gift + Home Market brings together products across a broad range of retail categories, including:
Giftware
Home décor
Fashion accessories
Gourmet food
Stationery
Toys
Wellness
Jewellery
Seasonal merchandise
Lifestyle products
Canadian-made brands
The event gives buyers an opportunity to compare suppliers, discover new merchandise and place orders for upcoming retail seasons. With the holiday selling period approaching, it is also one of the final major wholesale buying opportunities of the summer for retailers still building or refining their year-end assortments.
Seeing products in person can be particularly valuable for independent retailers and specialty stores, where product quality, packaging, presentation and merchandising potential can influence purchasing decisions. Buyers can also speak directly with suppliers about ordering requirements, delivery schedules and opportunities to introduce new brands to their customers.
Who Should Attend?
The market is designed exclusively for qualified retail buyers and industry professionals, including:
Independent retailers
Specialty gift stores
Home décor retailers
Museum and attraction gift shops
Garden centres
Gourmet food retailers
Fashion boutiques
Lifestyle retailers
E-commerce businesses
Regional and national retail chains
Retailers attending for the first time can use the market to explore the Canadian wholesale landscape and establish supplier relationships. Returning buyers can reconnect with existing partners, review new collections and identify products for the coming seasons.
For businesses that have not yet finalized their holiday assortments, the four-day event provides a concentrated opportunity to evaluate products and meet suppliers before the fall retail period accelerates.
Celebrate 50 Years of CanGift
The 2026 market is part of CanGift’s 50th-anniversary celebration.
Founded in 1976, the association has spent five decades supporting Canada’s gift, home and lifestyle industries by creating wholesale markets where retailers and suppliers can connect, discover products and grow their businesses.
The anniversary gives this year’s Toronto market added significance, reflecting the event’s long-standing role in Canada’s retail and wholesale sectors. Over the years, CanGift markets have provided a meeting place for independent retailers, established suppliers and growing brands from across the country.
This year’s event will also feature Proudly Canadian, presented in partnership with the Canadian Federation of Independent Business. The initiative will highlight Canadian-made products and emerging businesses from across the country at a time when many retailers and consumers are paying closer attention to where products are designed, produced and distributed.
Event Information
Fall Toronto Gift + Home Market
Dates: August 9–12, 2026
Location: Toronto Congress Centre – North 650 Dixon Road Toronto, Ontario
Hours:
Sunday, August 9 9:00 a.m. – 6:00 p.m.
Monday, August 10 9:00 a.m. – 6:00 p.m.
Tuesday, August 11 9:00 a.m. – 6:00 p.m.
Wednesday, August 12 9:00 a.m. – 1:00 p.m.
Registration Remains Open
The Fall Toronto Gift + Home Market is open exclusively to qualified retail buyers and industry professionals.
With the show beginning August 9, buyers have only a few days remaining to register, organize meetings and plan which exhibitors and product categories they want to explore.
Retailers searching for new suppliers, Canadian-made products, seasonal merchandise or fresh ideas for their holiday assortments can use the market to accomplish several sourcing priorities in one location.
Many Ontario restaurants that were hoping for a surge this summer are disappointed. From the wildfires that kept diners at home, to air-conditioning bills eating up their World Cup gains; now, they’re facing additional tariff threats from the U.S., according to Merchant Growth.
The U.S. has announced anadditional 50% tariff, effective August 19, on nearly US$20 billion in selected Canadian goods. For small businesses, the impact could extend beyond direct exporters to those relying on U.S. suppliers, customers or partners.
60% of Canadian small businesses have some U.S. exposure
Among those with U.S.-related activity 12 months ago,57%have reduced it and 14%have stopped it entirely
This follows an already difficult summer for consumer-facing businesses.
Hash AboulhosnRon Lach photo
In an interview with Retail Insider, Hash Aboulhosn,Chief Growth Officer atMerchant Growth, discusses the report’s findings.
Question: How are this summer’s challenges—wildfire smoke, extreme heat, higher cooling costs, and now renewed tariff threats—combining to affect the financial outlook for small restaurants and retailers?
Answer: Summer usually carries a big share of the year for restaurants and retailers that live on foot traffic. This year, wildfire smoke and long stretches of extreme heat kept a lot of customers indoors, and some operators ended up with a slower season than they’d planned for.
One sports bar owner told us the heat drove one of their slowest days of the whole season. Running the air conditioning around the clock was adding thousands of dollars a month to the hydro bill, and on top of that a round of HVAC and refrigeration failures cost roughly $5,000 to fix.
That reflects what we are seeing more broadly. In ourSmall Business Pulse 2026 survey launched in June:
37% of small businesses cited rising utility bills as a significant summer pressure.
37% cited weaker consumer demand.
55% have already reduced spending in response to economic uncertainty or trade pressures.
The renewed tariff threat adds another layer of uncertainty for businesses already managing weaker traffic, higher utility bills and unexpected repair costs.
Vitaly Gariev photo
Q: Your research shows that 60% of Canadian small businesses have U.S. exposure and many have already reduced that activity. What are businesses changing in practice, and do you expect the new tariffs to accelerate that shift?
A: What we are seeing is that businesses are already reconsidering how they work with partners in the U.S. Our survey found that:
14% have switched to Canadian or non-U.S. suppliers.
13% have stopped working with U.S. suppliers.
8% have pulled out of the U.S. market for sales.
Earlier research also found that, among businesses that had U.S.-related activity, whether that’s working with U.S. suppliers ot selling to U.S. customers, 57%had pulled back on that activity and 14%had stopped it entirely.
A fresh round of tariffs would sharpen those decisions. Owners have to choose whether to absorb the cost, raise prices, change suppliers, or hold cash, and a lot of them are hedging on more than one of those at once: 25% have raised prices and 22% have paused or cancelled expansion plans.
When a business cancels an expansion to wait out the uncertainty, that isn’t only softer demand today — it’s investment that doesn’t happen and will impact their business in the long-run. Canadian small businesses were already investing less per worker than their U.S. counterparts well before this, so every paused project widens a gap we’ve been carrying for years.
Q: Many small businesses won’t be directly exporting to the U.S. How could these tariffs still affect companies through suppliers, customers, pricing, or day-to-day operating costs?
A: A small business does not need to export directly to the U.S. to be affected. Our survey looked at exposure to U.S. suppliers, customers and partners, and about six in 10 (61%) of businesses reported at least some exposure through those relationships.
Think of a business that buys from a U.S. supplier, or one that buys Canadian but from a supplier now paying more to bring in its own inputs. Or a business whose customers depend on U.S. demand. The exposure runs through the supply chain, not just across the border.
Trade pressure is already showing up in day-to-day costs:
42% of businesses cited fuel cost increases from global trade disruptions.
18%cited tariffs.
13% cited supply-chain delays or shortages.
For an owner already facing softer demand and a bigger hydro bill, one more increase in the cost of keeping the doors open is what tips cash flow from tight to strained.
Andrea Piacquadio photo
Q: Inflation has eased, but many businesses say consumers are still spending cautiously. What’s preventing stronger consumer demand, and what are you hearing from business owners about customer behaviour?
A: Consumers want to support local businesses, but price is still shaping where and how they spend. Among Canadians planning to dine out this summer, 69% said price or deals influence how they decide where to spend their money, but 56%also said supporting local or independent businesses matters.
Both are true at the same time, and that’s the bind: people mean to spend local, and they’re still counting every dollar.
Small businesses are feeling that caution directly, with 37% citing weaker consumer demand as a significant summer pressure.
The World Cup is a clear example of how uneven the upside can be. A marquee event doesn’t lift every business the same way. More than half (58%) expected no impact on their revenue, while others said their location would not receive more foot traffic or that they lacked the cash to invest ahead of the event.
The demand shows up; capturing it takes cash on hand, and a lot of small businesses don’t have much to spare right now.
Q: Looking ahead over the next six to 12 months, what strategies should small businesses be considering to protect cash flow and remain resilient if trade uncertainty and operating costs continue to rise?
A: The first priority is having a clear picture of cash flow, including essential expenses, areas of flexibility and how the business would respond to an unexpected cost or decline in revenue.
Businesses should also review their supplier exposure, pricing, inventory and financing needs before pressure becomes urgent. Many are already adjusting:55% have cut spending, 25% have delayed hiring, 22%have paused or cancelled expansion plans, and 15% have reduced inventory.
Access to capital is a major concern.Three in four businesses surveyed(75%) said access to low-interest small-business loans would be the most helpful form of government support.
It isn’t that owners don’t want to invest in a better oven, more staff, or the tools that would let them do more with the same team. It’s that the capital to do it is hard to get on reasonable terms. Canadian businesses already invest only about 55 cents per worker for every dollar their U.S. peers put in, and that gap doesn’t narrow on its own. It narrows when a small business can actually finance the next piece of equipment.
So over the next six to 12 months, the businesses that come out ahead won’t necessarily be the ones that cut the deepest. They’ll be the ones that keep a close read on cash, make deliberate calls instead of reactive ones, and can still reach capital when the right investment — or a hard month — arrives.
Montreal-based Leyad has appointed two senior team members as the company continues to expand its national platform and strengthen its operational capabilities across Canada.
Leyad is one of Canada’s largest privately owned real estate companies, owning and managing a diversified portfolio of retail, industrial and residential properties across nine provinces. The company owns more than 12 million square feet of real estate and employs approximately 500 people nationwide. Leyad focuses on acquiring and enhancing high-quality real estate assets.
Juan Calixto TriaAlex Ratté
Collectively, the two leaders bring decades of experience across financial reporting, capital markets, construction management, retail asset redevelopment and corporate governance, said the real estate company.
“At Leyad, we have always believed that the quality of our people is our greatest competitive advantage,” said Henry Zavriyev, Chief Executive Officer of Leyad. “As our portfolio continues to grow across the country, it is important that we continue investing in experienced leaders who have built exceptional careers at some of Canada’s most respected real estate organizations. Juan and Alex each bring deep expertise in their respective fields and further strengthen our ability to execute at the highest level for our tenants.”
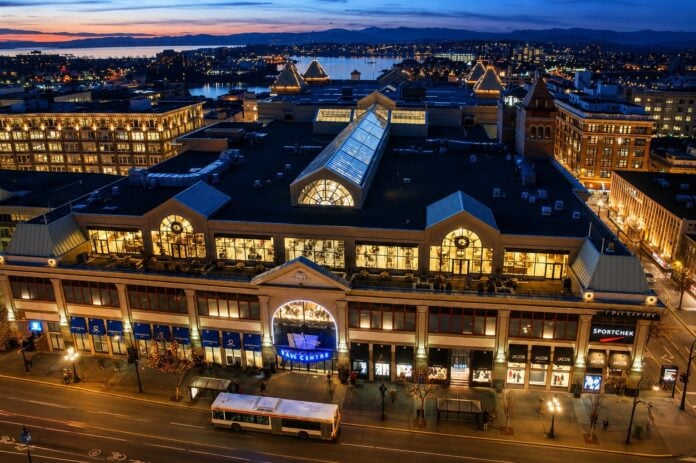
Henry ZavriyevThe Bay Centre in Victoria, BC (CNW Group/Leyad)
The company said Tria joined Leyad and will oversee its financial reporting, corporate compliance, accounting policies, treasury reporting and governance functions.
Tria joined Leyad from Agellan Commercial REIT, where he most recently served as Vice President, Finance, after previously serving as Director, Financial Reporting. Prior to Agellan, Tria held senior roles with MNP LLP, PricewaterhouseCoopers, Ernst & Young, and Rawlinson & Hunter, advising publicly listed companies, financial institutions and multinational organizations on audit, financial reporting and regulatory compliance, it said.
Leyad said Ratté will lead the company’s national construction and capital projects platform.
Ratté brings more than two decades of experience managing commercial real estate developments and capital programs across Canada. Most recently, he served as Senior Director, Project Management at Cominar, where he led project management during the REIT’s transition from public to private ownership while overseeing annual capital programs of up to $100 million. Prior to Cominar, Ratté spent more than a decade with First Capital REIT, managing major redevelopment projects across Quebec, British Columbia and Ontario, including mixed-use developments, shopping centre repositionings and large-scale commercial construction, it said.
By Larry Leung, Founder and Experience-in-Chief, Transformidy™
Air Canada’s Aeroplan® and World of Hyatt® announced a new loyalty partnership last month, giving members new ways to earn, convert and redeem rewards across both programs. Most of the partnership is already live, with additional reciprocal elite-status opportunities expected later this year.
For frequent travellers, the announcement expands the value of two established loyalty programs. For retailers and loyalty professionals, it also provides an instructive example of how partnerships are evolving into broader customer ecosystems that extend across multiple brands and touchpoints.
Members can now link their Aeroplan and World of Hyatt accounts, earn rewards across both programs, convert points between ecosystems and access reciprocal elite-status benefits. Eligible Aeroplan Premium Credit Cardholders receive complimentary World of Hyatt Discoverist status, additional earning opportunities and annual status challenges. Eligible World of Hyatt members receive annual Air Canada flight credits, while eligible Explorist and Globalist members are expected to gain access to Aeroplan Elite Status challenge opportunities later in 2026.
The list of new benefits is substantial, but the larger story lies in how Air Canada and Hyatt are approaching customer relationships. They are working to connect separate parts of the travel experience into a journey that feels cohesive from beginning to end.
Air Canada’s Scott O’Leary described the partnership as creating “meaningful value across the full travel journey,” while Hyatt’s Laurie Blair spoke about making travel more seamless. Those comments are expected in a partnership announcement, but they also reflect a broader business objective. The two companies are attempting to connect flights, hotel stays and payment experiences into a relationship that feels continuous instead of fragmented.
A traveller may fly with Air Canada, stay at a Hyatt property, pay with an Aeroplan credit card, earn rewards in both programs and later redeem within either ecosystem. Behind the scenes, that experience depends on multiple systems, policies and organizations working together. When those elements function smoothly, customers rarely think about the complexity. They simply experience a journey that feels connected.
That is where partnerships often succeed or fail.
At Transformidy, I evaluate partnerships through what I call Experience Intelligence™: understanding how customer experience, operations, brand value and commercial opportunity intersect throughout the customer journey. The questions are straightforward. What does the customer actually experience? Where does the relationship naturally continue? What commercial opportunities are created for each partner? Can the customer promise withstand the operational realities behind it?
Execution ultimately determines whether those promises are fulfilled. Customers are generally willing to learn how a loyalty program works, but their patience disappears quickly when benefits fail to appear, points do not post correctly or status challenges become confusing. They rarely care which organization owns the underlying technology or business process. They simply know the promised experience did not materialize.
That perspective is particularly relevant for retailers. Many organizations are eager to expand through partnerships, but comparatively few are prepared for the accountability that comes with delivering a seamless experience across multiple brands. Every handoff between organizations becomes part of the customer experience, whether companies intend it to or not.
Canadian retailers already understand the value of loyalty ecosystems. Programs such as PC Optimum, Scene+, Triangle Rewards and Air Miles have demonstrated how partnerships can influence customer behaviour across multiple categories. The Air Canada–Hyatt relationship applies similar thinking within travel by bringing together aviation, hospitality and financial services in ways that encourage customers to remain engaged throughout an entire trip.
The commercial opportunity extends well beyond acquiring new members. Strong partnerships create additional customer occasions, encourage repeat engagement and strengthen long-term relationships because they become genuinely useful in people’s everyday lives. Relevance is what keeps customers participating long after the excitement of a new partnership announcement has faded.
Retailers can apply the same thinking across many sectors. Grocery programs may extend into wellness, travel or pharmacy services. Hotels can connect guests with local dining, entertainment and retail experiences. Financial institutions can create partnerships around categories where cardholders already spend time and money. The strongest ecosystems reflect how customers naturally move through their lives instead of asking them to change established habits.
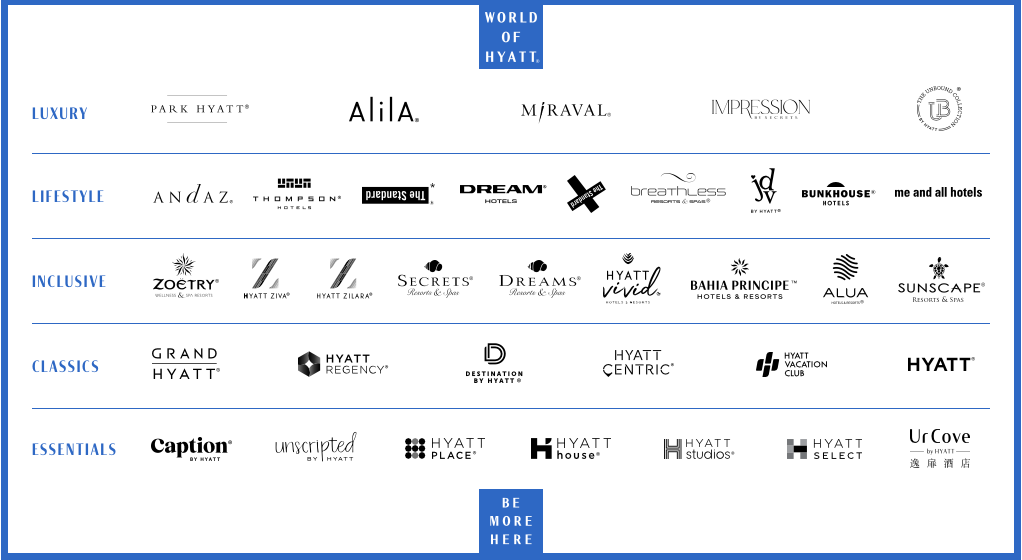
The scale of the Air Canada and Hyatt relationship is significant. Aeroplan serves more than 10 million active members and connects travellers to more than 1,300 destinations through Air Canada and its airline partners. World of Hyatt has approximately 66 million members and operates more than 1,500 hotels and all-inclusive properties across 83 countries.
Scale alone, however, does not create lasting loyalty. Customers return because a program consistently makes their lives easier, more rewarding and more relevant. Points and status remain important, but they are ultimately tools that support a broader relationship.
Air Canada brings one of Canada’s strongest loyalty ecosystems. Hyatt contributes a global hospitality network that shapes a significant part of the travel experience. If customers come to experience those brands as one connected relationship instead of two separate programs, the partnership will have accomplished something much more valuable than expanding redemption options.
For Retail Insider readers, that is the broader takeaway. Partnerships create lasting value when they remove friction, reinforce customer relationships and become a natural part of how people already live, travel and shop. The brands that succeed will be those that make those connections feel effortless from one interaction to the next.
Larry Leung is Founder and Experience-in-Chief of Transformidy™, where he advises organizations on customer experience, partnerships and commercial strategy through his Experience Intelligence™ framework.
Canadian-founded coffee brand Second Cup has appointed veteran restaurant executive Joe Walker as Chief Executive Officer of The Second Cup Coffee Company Inc., the company responsible for the brand’s international franchise business.
Announced Monday, Walker’s appointment comes as the company looks to accelerate the expansion of its global franchise network. He joins Second Cup following leadership roles with Wingstop, Starbucks, McDonald’s, KFC and Yolk Brands. Most recently, he led Wingstop’s expansion across the Gulf Cooperation Council (GCC) region, experience the company says positions him to guide its next phase of international growth.
“Joe is a world-class retail and QSR executive with an exceptional track record of scaling iconic food and beverage brands,” the company’s Board of Directors said in a joint statement announcing the appointment. The board added that his operational experience and leadership in the GCC make him well suited to strengthen Second Cup’s global franchise network.
Joe Walker
Building on an International Network
Although Second Cup was founded in Toronto in 1975, the company’s international business has grown well beyond its Canadian roots. Today, it operates cafés across the Middle East, East and West Africa, Asia and Europe through franchise partners while continuing to pursue opportunities in additional markets.
Walker said his focus will be on strengthening relationships across the company’s international network while continuing its expansion into new markets.
“While our heritage is proudly Canadian, our future relies on embedding ourselves deeply within the communities we serve,” Walker said. “We will accelerate and strengthen our growing presence globally, working closely with our regional partners to unlock Second Cup’s true international potential.”
The company also said it is actively seeking qualified franchise partners as it continues to expand internationally.
Middle East Positioned as Strategic Hub
Walker will be based primarily in the Middle East, where he will oversee the development of the region as a key international hub while continuing to lead the company’s main global base in Canada.
The appointment reflects the growing importance of the Gulf region as a destination for international restaurant and café brands. Significant investment in retail, hospitality and mixed-use developments has created opportunities for franchise operators seeking expansion, and Walker’s experience in the region aligns with Second Cup’s stated ambitions for its international business.
The Canadian café business has been owned by Montreal-based Foodtastic since 2021, while The Second Cup Coffee Company Inc. oversees the brand’s expansion outside Canada through franchise partnerships.
Founded in Toronto in 1975, Second Cup began expanding internationally in the early 2000s and has since established a presence across multiple global markets. The company said it remains committed to supporting existing franchise partners, entering new territories and welcoming new operators as it advances its international growth strategy.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 10 articles we published covering notable developments in Canadian and international retail.
Alimentation Couche-Tard reached a deal to acquire a controlling stake in Poland’s Żabka Group for US$8.6 billion, significantly expanding its European footprint with over 13,000 stores integrated into its Circle K network and enhancing digital and loyalty platforms. Retail Insider also explored what Couche-Tard could gain beyond store growth from Żabka’s innovative convenience formats, autonomous checkouts, and robust digital ecosystem.
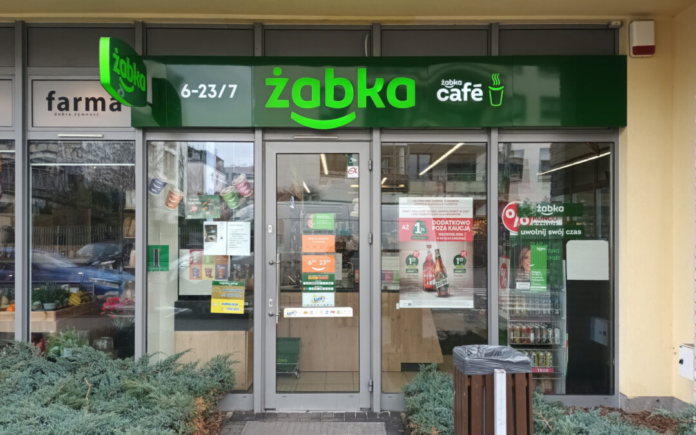
Alimentation Couche-Tard is poised to add more than 13,000 locations to its global network through its proposed acquisition of Żabka Group, but some of the most interesting assets it gains could be found inside stores measuring only a fraction of the size of a typical North American convenience location.
The Polish retailer has built a dense network around compact neighbourhood stores, backed by an extensive digital ecosystem, a major loyalty platform and a growing presence in autonomous retail. For Couche-Tard, those capabilities could provide lessons that extend across its global operations.
Montreal-based retail strategist Carl Boutet said Żabka has emerged as one of the more technologically progressive convenience-store operators in Europe, making its operating model an important part of the strategic value behind the acquisition.
“I find more interesting the tech thing,” Boutet told Retail Insider, pointing to Żabka’s autonomous stores and loyalty capabilities.
Boutet said acquisitions of innovative retailers can sometimes bring “extra digital DNA” into the acquiring company, while emphasizing that he has no inside knowledge of Couche-Tard’s plans for Żabka.
As Retail Insider reported Friday, Laval-based Couche-Tard has agreed to acquire a controlling stake in Żabka and launch a voluntary tender offer for the remaining shares at PLN 32 per share. The transaction values Żabka at approximately US$8.6 billion and would be the largest acquisition in Couche-Tard’s history.
Couche-Tard currently operates close to 17,300 stores globally, while Żabka reported 13,063 locations as of June 30. The combination would create a network of approximately 30,300 stores, although the way Żabka operates those locations may prove just as important as the number Couche-Tard is acquiring.
A Different Convenience Store Model
Żabka’s modular neighbourhood stores average approximately 65 square metres, or about 700 square feet, and operate across urban, suburban and rural markets. The network is supported by approximately 11,000 franchisees and has become deeply embedded in Poland, where approximately 18 million consumers live within 500 metres of a Żabka location.
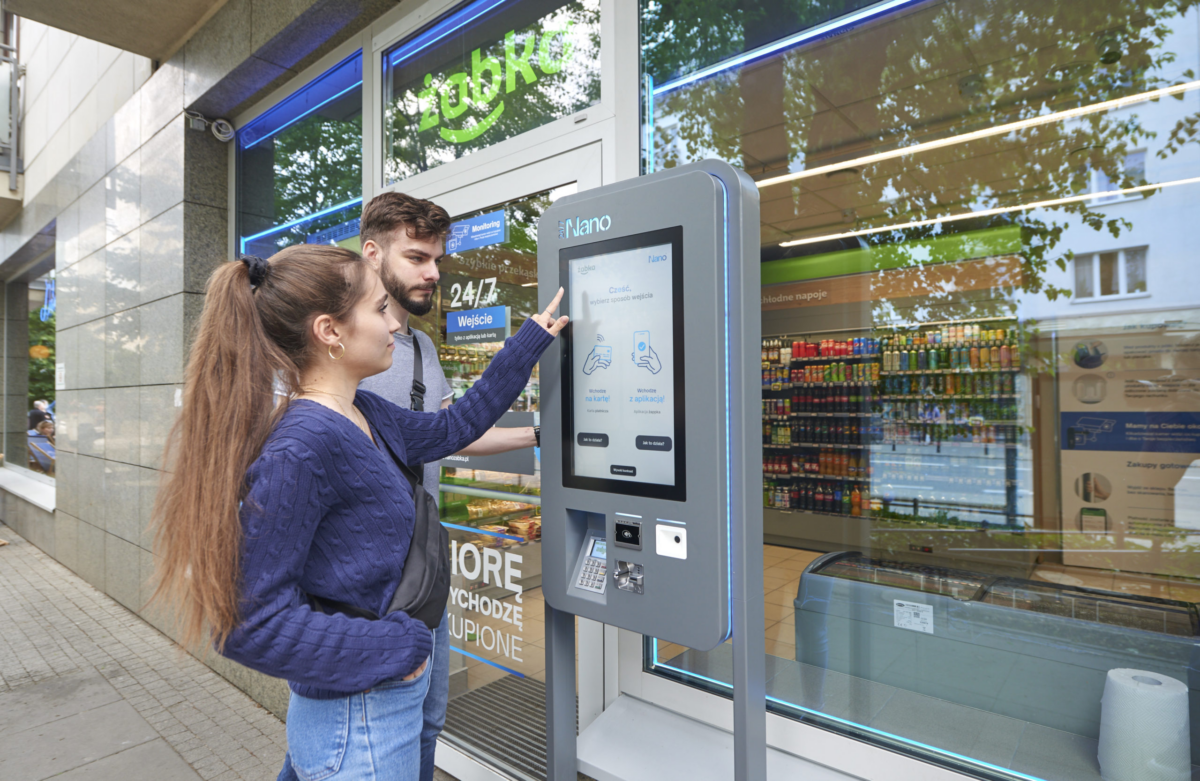
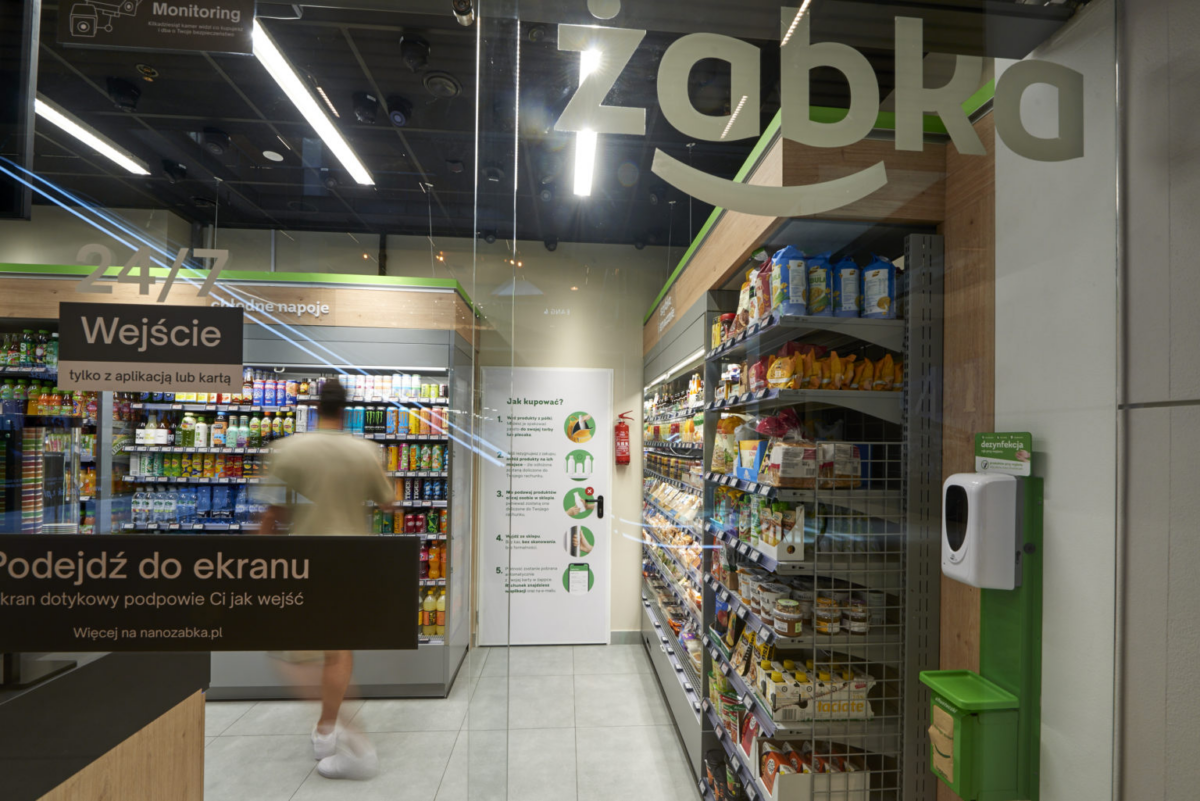
Technology is central to that model. Żabka has developed its Żabka Nano autonomous-store concept alongside a broader digital operation encompassing loyalty, e-commerce, meal delivery, logistics and retail media. The company processes approximately 4.3 million transactions per day and reported 11.2 million Żappka app users as of June 30.
Boutet identified checkout technology, compact formats and loyalty as three areas he believes could be particularly interesting for Couche-Tard.
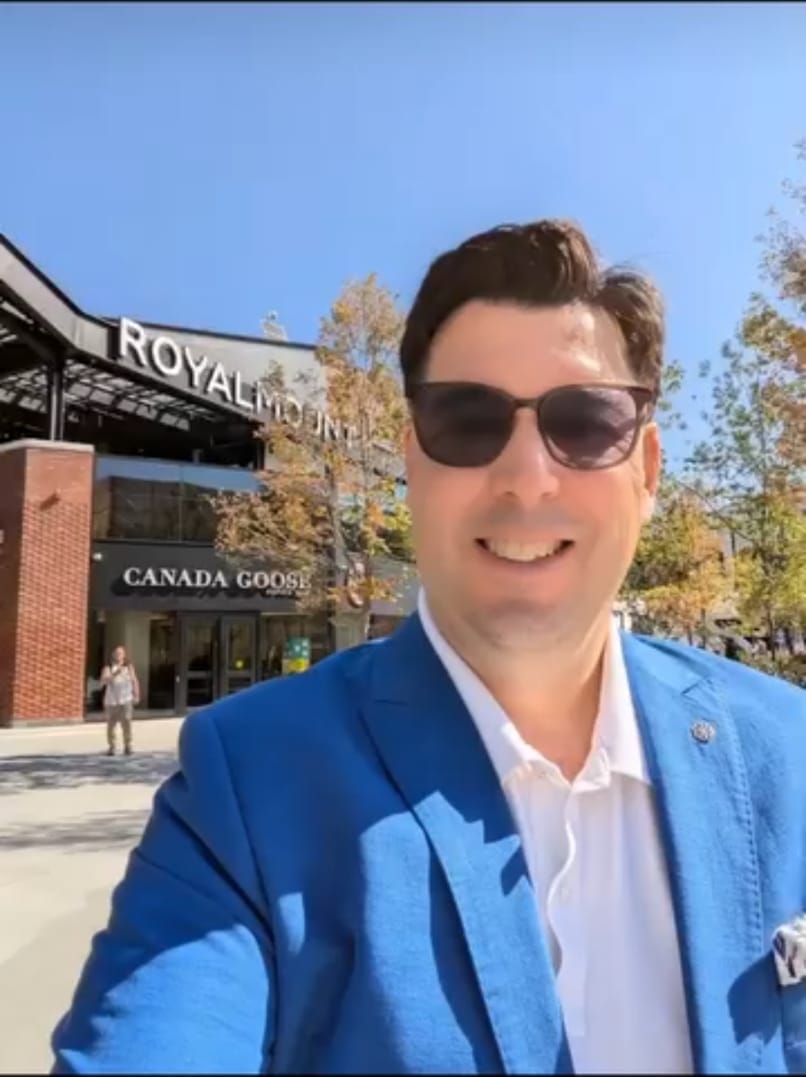
Carl Boutet at Royalmount in Montreal. Image: Carl Boutet
“The checkout technology, the smaller footprint, the loyalty program, I think are all places where they could benefit from the acquisition,” he said.
The economics of smaller stores are especially relevant as retailers scrutinize how efficiently they use space. Autonomous checkout can reduce the area required for a traditional cash wrap and potentially allow more of a compact store to be devoted to merchandise, while a smaller footprint can increase the range of markets where a convenience retailer can operate.
“It allows them to go into different markets,” Boutet said.
Regional and suburban markets could potentially support more locations when each requires less space, he added. Technology, autonomous operations and new approaches to delivery can create additional possibilities around those formats.
Boutet also pointed to smaller and underserved Canadian communities, including places that have lost grocery or convenience options as conventional stores become increasingly expensive to operate. He stressed that he was not suggesting Couche-Tard intends to introduce Żabka’s model in Canada, but said acquiring a company experienced in operating compact stores gives Couche-Tard a wider range of models to study as it considers how convenience retail could evolve in different markets.
Digital Engagement at Scale
Żabka’s physical network is closely tied to its digital operations. At the end of 2025, the company reported 10 million digitally active shoppers, while purchases made by Żappka users averaged 20% higher than those of other customers. Revenue from Żabka’s digital customer offering grew 25% during the year.
Its digital ecosystem has also expanded beyond the core convenience business through operations including Maczfit, Dietly, Delio and Jush!, while Żabka has developed a retail media business using its physical network and digital customer relationships.
Couche-Tard has already identified digital engagement, customer loyalty and innovation among the capabilities it sees in Żabka. For Boutet, the opportunity does not necessarily require Couche-Tard to duplicate Żabka concepts store for store.
“I think it definitely can inspire and influence” how Couche-Tard approaches its business, he said.
Boutet also pointed to Couche-Tard’s expansion in Scandinavia, saying operations acquired there brought another wave of digital ideas into the company. He believes Żabka could provide a similar opportunity to study practices developed within another advanced convenience market.
What Couche-Tard Brings to Żabka
The exchange of expertise could work in both directions. Boutet describes Couche-Tard as one of the world’s strongest convenience-store operators, with an unusually disciplined approach to costs, merchandise and store productivity.
“That’s their superpower, is their discipline,” he said.
Boutet said Couche-Tard has historically paid close attention to which products generate the strongest turnover and how efficiently space and capital are being used. That operating culture has helped the company grow from a Quebec convenience business into a network spanning dozens of countries and territories, and could help explain the value Couche-Tard sees in Żabka.
“They’re one of the best operators in the world in this space,” Boutet said.
Couche-Tard has identified approximately US$250 million in potential annual cost and revenue synergies from the transaction, expected to be fully realized by the third year after closing. Żabka’s supply chain could provide another area for learning, with more than 99% of products sold through its stores supplied through its own distribution system. Couche-Tard CEO Alex Miller has said that approach aligns with the Canadian company’s efforts to increase control over merchandise supply.
Couche-Tard has also signalled that Żabka will retain significant autonomy. The Żabka brand and franchise structure are expected to remain, giving the business room to continue operating the model that has driven its growth.
Żabka autonomous store. Photo: Microsoft
Europe Becomes Much Bigger for Couche-Tard
The transaction would significantly alter Couche-Tard’s geographic profile. Europe currently represents roughly 30% of its store network, while with Żabka included, Europe would account for approximately 60% of the combined store base.
Żabka itself continues to grow quickly. The company opened 1,394 stores during 2025 and reported a 14.1% increase in sales to end customers to PLN 31.1 billion, while adjusted EBITDA increased 16% to PLN 4.07 billion. Its expansion has largely been concentrated in Poland, with Romania providing a platform for further growth outside its home market.
The acquisition therefore gives Couche-Tard a considerably larger position in Central and Eastern Europe while shifting the geographic centre of gravity of its overall store network.
‘In Many Ways a Bigger Deal’
Couche-Tard’s history of pursuing major international acquisitions gives the Żabka transaction additional context. The company abandoned its approximately US$46-billion pursuit of Seven & i Holdings, parent company of 7-Eleven, in July 2025 after a lengthy effort to bring the Japanese company to the negotiating table. Several years earlier, Couche-Tard had pursued French retail giant Carrefour before the French government opposed the proposed transaction.
Boutet believes Żabka could ultimately prove more significant from an operational and strategic perspective than either of those attempted acquisitions.
“I think this is in many ways a bigger deal than the attempted 7-Eleven or Carrefour acquisitions,” Boutet told Retail Insider.
His comparison is not about transaction value. Both attempted deals, particularly Seven & i, involved substantially larger companies. Boutet sees significance in the capabilities Couche-Tard can potentially absorb from Żabka and apply elsewhere in its global business.
“I think just from the operational standpoint, what they’re going to be able to learn from is going to be more worthwhile,” he said.
There is another connection between the companies, with Seven & i having itself explored acquiring a stake in Żabka in July before those discussions ended without an agreement. Żabka therefore gives Couche-Tard a concentrated convenience business with a different set of capabilities and a track record of rapid growth.
A Żabka shopper walks toward shelves full of beverages. Photo: Microsoft
An Overlooked Retail Innovation Market
The acquisition also puts a spotlight on a region Boutet believes receives relatively little attention in North American discussions about retail innovation. Asia and Western Europe frequently dominate conversations about advanced retail technology, while he said Central and Eastern Europe have also produced retailers willing to adopt and test new systems.
“For retail technology, Eastern Europe has been punching above its weight,” he said.
Żabka is a particularly visible example, having combined rapid physical expansion with autonomous stores, digital loyalty, e-commerce and other technology-enabled services. Boutet said the willingness to experiment in markets such as Poland has created pockets of retail innovation that can easily be missed from a North American perspective.
“They’ve got their hands on a really good one right now,” he said of Couche-Tard’s proposed acquisition.
“I’m super excited about it. I think it’s going to be really, really interesting to see this play out.”
For Couche-Tard, Żabka will bring considerable scale, taking its global network to approximately 30,300 stores and making Europe the largest geographic component of that network. The longer-term impact may become clearer as Couche-Tard gains greater exposure to the systems behind those 13,000-plus stores, from compact formats and autonomous checkout to digital loyalty and supply-chain operations.
How those ideas travel through Couche-Tard’s wider organization will be one of the more interesting retail stories to watch after the deal closes.