Canadian businesses still carrying Canada Emergency Business Account (CEBA) loans face a December 31, 2026 repayment deadline, adding pressure for operators already managing debt, rising expenses and tight cash flow. Newly released federal financial statements show $7.2 billion in outstanding CEBA loans, with Ottawa estimating that a substantial portion may not be recovered.
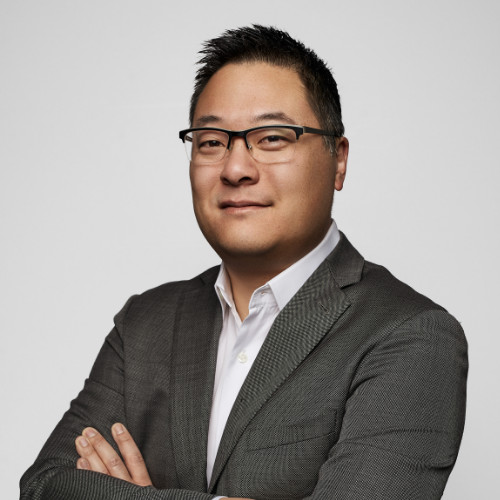
For independent retailers, the deadline falls at the end of the holiday selling season, when cash is needed for inventory, suppliers, payroll and rent. Daryl Ching, CEO and founder of Toronto-based Vistance Accounting, says some clients are seeking additional financing while others appear prepared to wait for collection efforts.
Ching, whose firm advises approximately 50 businesses across retail, wholesale, e-commerce, manufacturing and consumer packaged goods, says owners should review their obligations now. In a November 6 update to Retail Insider, he noted that the federal budget released the previous day contained no new CEBA relief measures.
Ottawa Estimates Billions in CEBA Loans May Not Be Recovered
The federal government introduced CEBA in 2020 to help businesses cover operating expenses during the pandemic. Approximately 900,000 businesses received $49 billion in financing, with eligible loans of up to $60,000.
Borrowers who met the January 18, 2024 repayment deadline, or qualified for a refinancing-related extension to March 28, 2024, could receive partial loan forgiveness. Remaining eligible loans became term loans carrying five per cent annual interest from January 19, 2024, with outstanding principal due December 31, 2026.
Federal records indicate that approximately 175,000 eligible loans had converted to interest-bearing term loans by late 2024. That historical figure represents loans entering the repayment phase, not the number of businesses still owing money today.
The latest Public Accounts of Canada, covering the fiscal year ended March 31, 2026, report $7.210 billion in gross outstanding CEBA loans. The government recorded a $5.651 billion allowance for estimated credit losses, leaving approximately $1.559 billion in net loans receivable on its balance sheet.
The allowance increased from $5.354 billion a year earlier, when gross outstanding loans totalled $7.758 billion. The latest figures indicate that the federal government expects substantial losses on the remaining portfolio, although they do not establish how much debt will ultimately be recovered.
In his November 10 correspondence with Retail Insider, Ching emphasized that the accounting treatment does not change borrowers’ legal obligations.
“Owners shouldn’t read the government’s loss estimate as a sign they can walk away. An allowance is an accounting estimate, not forgiveness. The balance is still due December 31, and once it goes to CRA, it’s collected as a government debt,” Ching said.
The Office of the Auditor General of Canada has also highlighted the significant portion of outstanding CEBA loans that may not be recovered. Its analysis distinguishes the gross amount borrowers owe from the lower value the government expects to recover after accounting for potential losses.
Ching says clients are approaching financial institutions about increasing existing lines of credit or arranging term loans to repay their CEBA balances. Others are applying for business financing for the first time.
“And I have clients that have actively gone to the bank and said, ‘Can we refinance this?'” Ching told Retail Insider. Those discussions include increasing working-capital facilities or arranging separate financing to avoid default.
He described an illustrative example of a business with a $100,000 working-capital line of credit seeking another $40,000. The lender would typically want financial statements, recent sales activity and a forecast before considering the request.
Ching says increasing an existing credit facility can be easier than applying for a new one, although approval depends on the company’s finances and the lender’s requirements. Refinancing can extend repayment over a longer period, but commercial borrowing may carry different interest rates, security requirements and repayment conditions.
What Happens When Businesses Default?
Outstanding principal on eligible CEBA term loans is due in full on December 31. Federal documentation states that loans generally enter default and become subject to collection efforts when borrowers miss required interest payments before maturity or fail to repay principal after the deadline.
Collections have already begun for some borrowers, including those previously in default. Financial institutions generally undertake collection efforts before unresolved accounts are assigned through Export Development Canada to the Canada Revenue Agency for collection.
The Department of Finance has stated that CRA may seek repayment in full or establish payment arrangements depending on borrowers’ circumstances. Such arrangements do not eliminate the debt or guarantee identical treatment for every borrower.
Ching says some owners appear unconcerned about the deadline, despite the possibility of collection action. “I’ve heard some clients go, ‘Don’t care. Just see what happens,'” he said, describing an attitude he has encountered among certain business owners rather than a broader trend among CEBA borrowers.
Ching cautioned owners against assuming nothing happens after December 31. “CEBA is a loan, like any bank or BDC loan, but once it goes to CRA, it’s collected as a government debt. It doesn’t go away just because the lender stopped calling,” he said.
He also drew a distinction between CEBA loans and payroll or HST remittances. Directors can face personal liability for certain unpaid remittances, while incorporated CEBA borrowers generally did not provide personal guarantees under the program’s standard terms.
“That’s not a licence to ignore it,” Ching said. “It’s still a debt the government will try to collect.”
The actual collection process will depend on the borrower’s circumstances and applicable agreements. The existence of a government allowance for potential losses does not establish that collection efforts will be suspended or that individual balances have been forgiven.
Holiday Cash Flow Adds Pressure for Retailers
The repayment deadline arrives as retailers manage inventory purchases, supplier invoices, wages and occupancy costs. Merchandise may have been purchased months before holiday sales take place, with supplier payments falling due before or during the busiest trading weeks.
Strong sales do not necessarily mean cash is available to repay debt. Retailers may need the proceeds to settle invoices, replenish merchandise and maintain liquidity for the slower months following the holiday season.
Ching emphasized that repayment comes just as holiday inventory and payroll bills are due. For a business carrying a $40,000 CEBA balance, repayment could compete with those operating requirements, depending on its cash reserves, profitability and available credit.
The October 2026 Labour Force Survey from Statistics Canada adds context to the operating pressures facing retailers. Employment in wholesale and retail trade fell by 29,000 during the month and was down 113,000 from a year earlier.
The same report showed the youth unemployment rate rising to 13.7 per cent, an increase of 0.7 percentage points. Ching pointed to the figure as relevant for retailers that depend on younger workers and shoppers, although the statistic does not establish the financial position of CEBA borrowers.
In a September interview with Retail Insider, Ching described businesses struggling with cash flow as money remained tied up in receivables and inventory. His firm was helping clients manage working capital, collect overdue payments and reduce dependence on credit facilities.
Businesses already relying heavily on lines of credit may have limited room to borrow more. Using available cash to repay CEBA could also reduce the funds needed to operate through the winter.
“So it’s not worth it to default on your payroll or not be able to pay your vendors,” Ching said, explaining why he encourages clients to address financing needs early. He argues that owners should examine repayment options before cash shortages force more difficult operating decisions.
Planning Before December 31
Ching advises borrowers to review their financing arrangements and approach lenders before the deadline. Credit applications may require financial statements, recent sales information and forecasts, making advance preparation important.
“If you need refinancing, it’s a conversation that needs to happen today,” he said. The approaching deadline leaves businesses with limited time to arrange financing, particularly if lenders require additional documentation or security.
Some businesses may be able to repay through cash reserves or operating cash flow, while others must determine whether additional borrowing is affordable. Owners unable to meet their obligations can contact their financial institutions to understand the applicable default and collection procedures.
For retailers, the immediate challenge is balancing a fixed repayment deadline against the cash required for day-to-day operations. The government’s recognition of potential losses does not remove that obligation, and decisions made before December 31 could determine how much financial flexibility businesses retain heading into 2027.