Groupe Dynamite is closing out its first year as a publicly traded company with exceptional third quarter results that signal ongoing strength across both banners in Canada and the United States. The findings come from a detailed new report authored by Martin Landry, Managing Director and Consumer and Retail Analyst at Stifel, who highlights revenue growth of about 40 percent year-over-year to approximately $363 million.
The lift came from comparable store sales growth close to 30 percent on a constant currency basis. Analysts attribute the sustained momentum to leaner inventories, quicker product cycles and a strong consumer response to Garage’s growing “off-duty” athleisure assortment. According to the Stifel report, these factors produced one of the strongest quarterly top-line performances since before the pandemic.
The company’s sales trajectory remains favourable heading into the important holiday trading period. Stifel notes that early fourth quarter indicators, including Black Friday performance, exceeded expectations for both traffic and basket size. The analyst report also references recent card-spend data showing a notable surge in apparel sales in recent weeks, suggesting that Groupe Dynamite is well positioned to continue its momentum through the end of the fiscal year.
Profitability Reaches Highest Level in Three Years
Profitability was the standout theme in the quarter, with several financial metrics reaching multi-year highs. Gross margin expanded by 310 basis points to 66.1 percent, supported by lower freight costs, improved merchandise margins and fewer markdowns due to extremely tight inventory control. At the same time, SG&A expenses were leveraged effectively, declining by 340 basis points as a percentage of sales to 25.9 percent. Together these gains produced an EBITDA margin of 40.2 percent, the highest reported in more than three years.
Earnings per share also beat expectations. Adjusted EPS came in at $0.72, which represented a 76 percent increase year-over-year and exceeded Stifel’s forecast of $0.57. As a result of the strong performance, management raised full-year EBITDA margin guidance by 325 basis points at the midpoint to between 35 and 37 percent. The upward revision underscores a fiscal year in which operational efficiencies, rapid product turns and improved pricing strategies have combined to drive meaningful margin expansion.
Store Relocations Provide Multi-Year Growth Runway
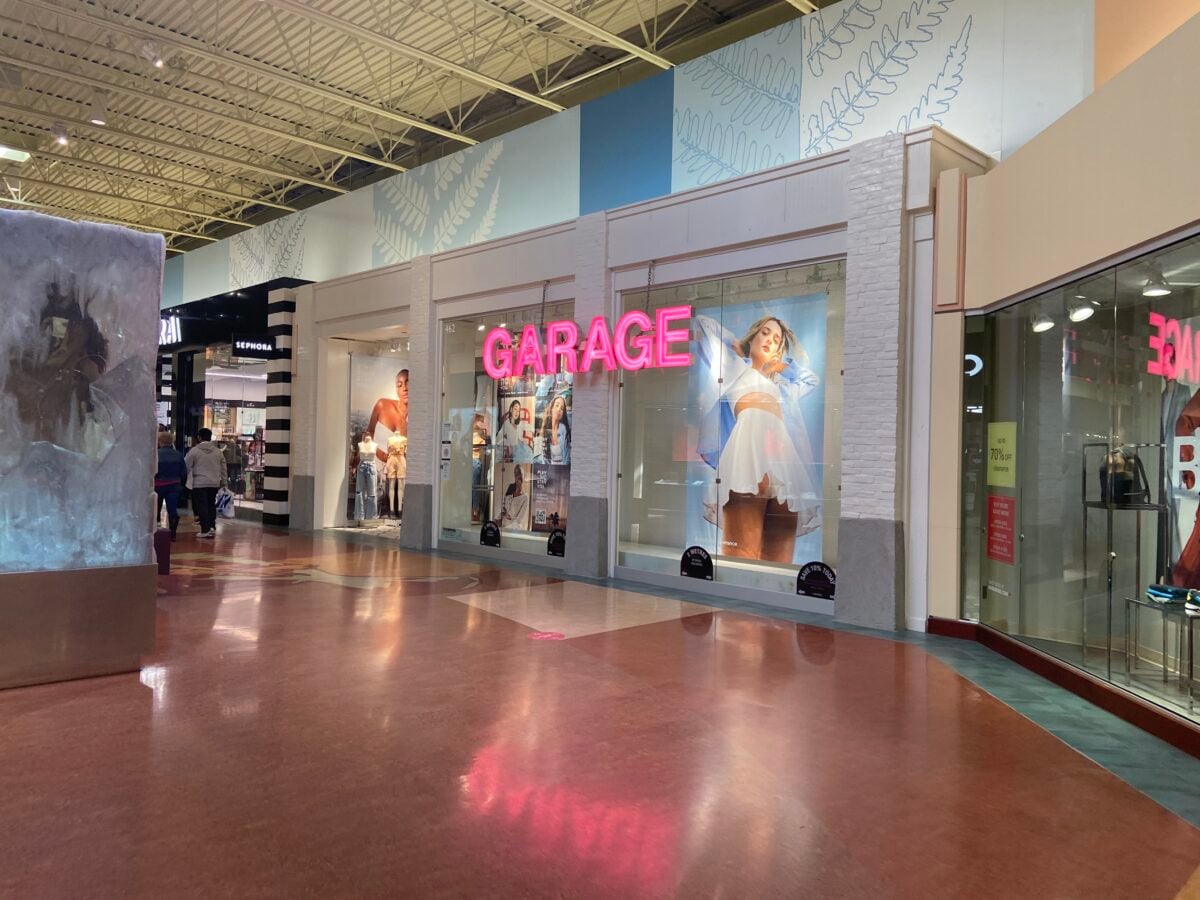
Stifel highlights Groupe Dynamite’s real estate strategy as a key driver of future growth. The retailer continues to relocate stores from what it classifies as tier four and tier five malls into stronger tier one to tier three centres. According to the report, sales in upgraded centres can be four times higher than in previous locations with similar square footage. The analyst notes that about 40 percent of the company’s stores continue to operate in lower tier malls, which leaves considerable opportunity for relocations, upgrades and new-format openings across North America.
The shift into more affluent and higher traffic trade areas is also helping the banners connect with customers who have shown resilience to pricing increases. With extremely short product lead times and an average of 46 days of inventory on hand, Groupe Dynamite is reducing fashion risk and maintaining a faster reaction cycle than many competitors. The tight inventory model is cited as a meaningful strategic advantage that allows the retailer to test trends quickly, reduce markdown exposure and maintain stronger full-price sell-through rates.
Expansion Plans for FY26 and FY27
Looking ahead, the company plans to continue expanding its store network at a steady pace. Management is guiding to between 18 and 20 gross store openings in North America in FY26. Stifel expects high single digit same-store sales growth next year driven by traffic gains, improved conversion and additional pricing optimization. The firm is modelling revenue of $1.50 billion in FY26 and $1.75 billion in FY27. Earnings per share are forecast to reach $2.60 in FY26 and $3.20 in FY27, reflecting operational leverage and continued margin improvement.
Gross margin expansion is expected to continue into next year, aided by lower tariffs, distribution improvements and further supply chain efficiencies. SG&A is also projected to benefit from greater scale as the retailer grows larger, modernizes store fleets and continues optimizing labour models to match traffic patterns more precisely.
Capital Markets Update and Special Dividend
The report also points to several developments on the capital markets front. The board has declared a $2.30 special dividend, providing liquidity to the CEO while also potentially delaying a secondary share offering. Stifel notes that a significant number of employees are now shareholders, which management believes has positively influenced performance and execution over the past year.
Valuation remains a discussion point. Stifel argues that the current trading multiple, which it estimates at about 32 times calendar 2026 EPS, is justified given that EPS growth is running above 50 percent year-over-year. The firm’s new target price of $96 is based on a blend of 30 times FY27 EPS, 20.5 times FY27 EBITDA excluding IFRS 16, and a discounted cash flow model using an 8 percent discount rate. The sharp upward trajectory in the company’s share price over recent months, illustrated in the report, reflects growing investor confidence in the retailer’s multi-year margin expansion story and its strategic repositioning of stores.
Groupe Dynamite’s first year on the public markets has shown that disciplined inventory management, thoughtful real estate strategy and a strong understanding of its core customer can translate into robust sales growth and record profitability. With continued relocation opportunities, growing brand recognition and strong consumer demand for athleisure and casual apparel, analysts see a long runway for the retailer as it moves into FY26.