Home Blog Page 115

Managed IT and Cybersecurity for Automated, Resilient Retail Operations

The Growing Importance of IT in Retail Automation

In today’s retail landscape, automation is no longer a luxury but a necessity. Retailers are increasingly relying on automated systems to streamline operations, improve customer experience, and stay competitive. From inventory management and point-of-sale systems to supply chain logistics, automation requires robust IT infrastructure and vigilant cybersecurity measures to ensure uninterrupted service and data protection.

The modern retail environment incorporates a complex web of interconnected devices, applications, and cloud services. This complexity enhances operational efficiency but also introduces multiple points of vulnerability. According to a recent report, 73% of retail businesses experienced at least one IT-related disruption in the past year, impacting sales and customer satisfaction. Such disruptions underscore the critical role of managed IT services in maintaining seamless retail operations.

However, as retailers adopt more interconnected technologies, they also face rising risks from cyber threats and system failures. The challenge is to build an automated retail environment that is not only efficient but also resilient. This resilience depends on continuous monitoring, rapid incident response, and proactive risk management-elements best delivered by specialized managed IT and cybersecurity services.

Partnering with Experts for Seamless IT Management

One effective approach for retailers is to collaborate with specialized IT firms that understand the nuances of retail technology. For example, Gravity, a professional IT firm offers comprehensive managed IT solutions tailored for the complexities of retail operations. Their expertise helps businesses implement scalable networks, integrate automation tools, and maintain secure cloud environments-all critical components for a resilient retail infrastructure.

Outsourcing IT management to such professionals enables retailers to focus on their core competencies while ensuring their technology backbone is reliable and up-to-date. This partnership also provides proactive monitoring and quick incident response, reducing downtime and mitigating risks before they escalate.

Moreover, managed IT providers assist with integrating emerging technologies such as AI-driven inventory forecasting and IoT-enabled supply chain tracking. These advanced tools increase operational efficiency but require sophisticated IT management to function securely and effectively. By leveraging expert IT partners, retailers can accelerate digital transformation while minimizing the risks associated with technology adoption.

Managing Retail Endpoints with AI-Powered Automation

As retail operations become increasingly automated, retailers must manage a growing number of distributed devices, including point-of-sale systems, handheld terminals, self-service kiosks, and digital signage.

Each endpoint supports essential business processes but also introduces operational and security risks. Inconsistent configurations, outdated applications, and unattended device failures can disrupt service, expose sensitive data, and expand the attack surface.

Managed IT providers can use endpoint management solutions such as AirDroid Business to combine centralized monitoring, remote support, and standardized security policies with AI-powered automated workflows. These workflows can turn isolated device alerts or scheduled tasks into repeatable response processes that route incidents, notify responsible teams, collect operational context, recommend next steps, connect with ticketing and communication tools, and trigger approved remediation. Human approval can remain in place for critical actions, helping retailers reduce alert fatigue, standardize response, and minimize downtime across stores. 

Bulk application updates, staged rollouts, kiosk mode, and device restrictions maintain consistent configurations, while remote lock and wipe capabilities protect data if a device is lost or compromised. Together, these measures reduce downtime and strengthen cybersecurity and operational resilience across retail locations.

The Critical Role of Cybersecurity in Retail

With the surge in digital transactions and customer data collection, cybersecurity has become a top priority for retailers. Cyberattacks targeting the retail sector increased by 44% in 2023 compared to the previous year, underscoring the urgent need for vigilant defenses. Retailers must safeguard sensitive customer information, payment details, and proprietary business data against constantly evolving threats.

Retailers located in major hubs such as Boston benefit from specialized local cybersecurity expertise. Companies offering cybersecurity in Boston provide tailored strategies that address region-specific threats and regulatory requirements. Their services include vulnerability assessments, employee training, and implementation of advanced security technologies designed to protect retail environments from breaches and ransomware attacks.

Retail cybersecurity strategies now extend beyond traditional firewalls and antivirus software. They incorporate multi-factor authentication, endpoint detection and response (EDR), and zero-trust network architectures. These measures are essential to protect against increasingly sophisticated threats such as phishing campaigns and supply chain attacks targeting retail vendors.

Building Resilience Through Integrated IT and Security Strategies

The integration of managed IT and cybersecurity is fundamental to achieving resilience in automated retail operations. Resilience means more than just preventing cyberattacks; it involves the ability to quickly recover from disruptions, maintain service availability, and protect business reputation.

Industry reports indicate that 60% of small and medium-sized retailers who suffer a significant cyber incident close within six months. This stark statistic highlights the importance of comprehensive IT and security planning. Managed IT providers work closely with cybersecurity experts to design systems that not only defend against attacks but also ensure operational redundancy and disaster recovery capabilities.

For instance, implementing automated failover systems enables retail operations to continue seamlessly even if primary servers or networks experience outages. Backup solutions and regular disaster recovery drills ensure that data integrity is maintained and services are restored rapidly. In addition, continuous risk assessments help identify emerging vulnerabilities, allowing retailers to adapt their defenses proactively.

Combining proactive IT management with robust cybersecurity protocols creates a holistic defense posture. Such integration reduces the likelihood of costly downtime, protects customer trust, and enhances overall business continuity.

Enhancing Customer Trust and Compliance

Beyond operational continuity, robust IT and cybersecurity practices enhance customer trust—a critical factor in retail success. Consumers today are more aware of data privacy issues and expect retailers to protect their personal information diligently. Retailers that demonstrate compliance with data protection regulations such as GDPR or CCPA differentiate themselves in the marketplace.

Managed IT services often include compliance support, helping retailers navigate complex legal frameworks and implement necessary controls. Cybersecurity firms provide ongoing audits and updates to maintain compliance, reducing the risk of costly fines and reputational damage.

A 2023 survey found that 82% of consumers are more likely to shop with retailers that demonstrate strong data protection measures. This statistic emphasizes that cybersecurity investments are not just about risk mitigation but also about building long-term customer loyalty.

Additionally, compliance with industry standards such as the Payment Card Industry Data Security Standard (PCI DSS) is crucial for retailers processing credit card transactions. Failure to comply can lead to severe penalties and loss of customer confidence. Managed IT and cybersecurity providers help ensure that retailers meet these requirements through regular system audits and security enhancements.

Future Trends in Retail IT and Cybersecurity

Looking ahead, the retail sector will continue to evolve with advancements in artificial intelligence, Internet of Things (IoT), and edge computing. These technologies promise greater automation and personalization but also introduce new vulnerabilities. Retailers must anticipate these changes and invest in adaptive IT and security solutions.

For example, IoT devices used in smart shelves or automated checkout systems increase operational efficiency but expand the attack surface for cybercriminals. Edge computing enables faster data processing at store locations but requires decentralized security measures. Retailers need managed IT partners who can architect secure, scalable infrastructures that incorporate these innovations safely.

Managed IT partners will play a crucial role in guiding retailers through this transformation, ensuring that infrastructure upgrades align with security best practices. Cybersecurity providers will increasingly leverage AI-driven threat detection and response tools to keep pace with sophisticated cybercriminal tactics. According to Gartner, by 2025, 70% of enterprises will use AI-based security solutions to enhance threat detection capabilities.

Preparing for these trends requires ongoing investment in workforce training, technology updates, and strategic partnerships. Retailers that proactively embrace innovation while maintaining robust security postures will be best positioned to thrive in the evolving marketplace.

Conclusion

Automated retail operations represent the future of commerce, offering efficiency and enhanced customer experiences. However, the complexity and interconnectedness of these systems demand expert management and strong cybersecurity to build resilience against disruptions. Retailers who invest in professional managed IT and cybersecurity services will not only protect their operations but also gain a competitive edge through increased reliability and customer confidence.

In a rapidly changing retail environment, partnering with experienced providers is a strategic move to ensure your retail business thrives securely and sustainably. Leveraging specialized regional expertise further strengthens your security posture and operational resilience. With the right technology partners, retailers can confidently navigate digital transformation, safeguard critical assets, and deliver exceptional service in an increasingly automated world.
IT Support and Managed IT Powering Retail Digital Transformation

The Digital Shift in Retail

The retail industry has undergone a profound transformation over the past decade, driven by the rapid adoption of digital technologies. What was once a predominantly brick-and-mortar sector has evolved into a complex ecosystem where e-commerce platforms, artificial intelligence (AI), data analytics, and cloud computing play pivotal roles. This digital shift is no longer optional; it has become essential for retailers who want to remain competitive and meet the ever-changing expectations of modern consumers.

Retailers today face a multifaceted challenge: they must deliver seamless, personalized customer experiences while optimizing operational efficiency and managing increasingly complex supply chains. Achieving this requires a robust IT infrastructure that supports innovation, agility, and security at every level of the business. However, building and maintaining such an infrastructure is no small feat, especially given the fast pace of technological change and the growing threat landscape.

In this context, IT support and managed IT services have emerged as critical enablers of retail digital transformation. These services allow retailers to implement cutting-edge technologies while ensuring system stability, security, and scalability. Companies that invest in professional IT support and managed services are better equipped to respond quickly to market shifts, reduce downtime, and enhance the overall customer experience.

One of the key advantages of leveraging remote support by 7tech is the ability for retailers to access expert assistance around the clock, ensuring that technical issues are resolved promptly and without disrupting business operations. This kind of IT support is essential in a retail environment where any downtime can lead to lost sales and diminished customer satisfaction. Moreover, managed IT providers often bring industry-specific knowledge, enabling them to tailor solutions that address the unique challenges faced by retailers.

Furthermore, retailers that opt to navigate Contigo’s services benefit from a comprehensive suite of IT services designed to proactively monitor systems, anticipate potential issues, and implement strategic improvements. This proactive approach not only reduces the risk of outages but also helps retailers optimize their IT investments by aligning technology initiatives with broader business objectives. As a result, managed IT services serve as a strategic partner in digital transformation, rather than just a reactive support function.

The Role of Managed IT Services in Retail

Managed IT services offer retailers a comprehensive and proactive approach to managing their technology environments. Instead of relying solely on internal IT teams, which may be stretched thin or lack specialized expertise, retailers partner with external providers who deliver a broad range of services. These include network management, cybersecurity, cloud infrastructure, data backup, and help desk support.

For example, retailers leveraging remote IT support can benefit from around-the-clock expertise that quickly addresses technical issues without the need for costly on-site interventions. This remote support model not only minimizes downtime but also helps control operational expenses-a crucial advantage in the highly competitive retail sector where margins can be tight.

Moreover, organizations that choose to engage managed IT services gain access to tailored IT solutions specifically designed to meet retail’s unique challenges. These managed services often encompass proactive system monitoring, rapid incident response, and strategic IT consulting. This partnership approach enables retailers to future-proof their technology investments, improve operational resilience, and focus on core business growth rather than firefighting IT problems.

The importance of managed IT services is underscored by industry data showing that 63% of retail businesses plan to increase their investment in managed IT solutions over the next two years to support digital initiatives. This trend reflects a growing recognition that expert IT management is foundational to successful digital transformation.

Improving Customer Experience Through Technology

Enhancing the customer experience is a primary driver behind retail digital transformation. Today’s consumers expect personalized, seamless interactions across multiple channels-whether shopping in-store, online, or via mobile devices. Technologies such as mobile apps, AI-powered chatbots, personalized marketing platforms, and omnichannel retailing depend on reliable and secure IT systems to deliver consistent and engaging experiences.

Managed IT services play a vital role in supporting these customer-facing technologies by ensuring the underlying infrastructure is robust and scalable. They help retailers deploy and maintain applications that provide real-time inventory visibility, personalized promotions, and frictionless checkout options. Additionally, managed IT providers implement advanced cybersecurity measures to protect sensitive customer data, which is critical for maintaining trust and complying with data privacy regulations such as GDPR and CCPA.

Statistics highlight the commercial value of investing in customer experience technology: 86% of buyers are willing to pay more for a better customer experience. Furthermore, retailers that deliver a consistent omnichannel experience retain 89% of their customers, compared to just 33% retention for retailers with weak omnichannel capabilities. These figures demonstrate that technology-enabled customer engagement directly correlates with increased loyalty and revenue growth.

By partnering with managed IT providers, retailers can ensure that their digital tools are always up-to-date, performant, and secure, enabling them to meet customer expectations and differentiate themselves in a crowded marketplace.

Enhancing Operational Efficiency and Agility

While customer experience often takes center stage, digital transformation also profoundly impacts back-end operations. Retailers must optimize inventory management, streamline supply chain logistics, and efficiently schedule workforce resources to stay competitive. Integrated IT solutions supported by managed services enable automation, real-time data analytics, and improved decision-making across these critical functions.

For example, cloud-based platforms supported by managed IT providers allow retailers to scale IT resources dynamically based on demand. This flexibility is especially valuable during peak shopping seasons or unexpected market disruptions, enabling businesses to maintain service levels without over-investing in permanent infrastructure. In fact, research indicates that 70% of retail businesses experience increased operational efficiency after adopting managed IT services.

Managed IT also plays a crucial role in risk mitigation. Through continuous monitoring and rapid incident response, IT providers help prevent costly system outages and data breaches, which can damage a retailer’s reputation and result in significant financial losses. By maintaining high system availability and security, managed IT services ensure that retailers can deliver consistent service and protect both business and customer data.

Furthermore, the integration of Internet of Things (IoT) devices in retail environments-such as smart shelves, RFID tracking, and connected point-of-sale systems-relies heavily on expert IT management. Managed IT providers facilitate the deployment and maintenance of these technologies, helping retailers gain granular visibility into operations and enhance supply chain efficiency.

IoT adoption in retail is on the rise, with projections estimating that by 2025, over 75 billion connected devices will be in use worldwide, many of which will be employed in retail settings to improve inventory accuracy and customer insights. This surge in connected technologies underscores the importance of reliable IT support to manage and secure these complex networks.

Future-Proofing Retail Through IT Innovation

The future of retail will be shaped by continuous technological innovation. Emerging technologies like artificial intelligence, machine learning, augmented reality, and IoT are transforming how retailers interact with customers and optimize operations. Successfully integrating these advancements requires sophisticated IT infrastructure and specialized expertise.

Managed IT providers are uniquely positioned to help retailers navigate this evolving landscape. They offer strategic IT consulting services that guide technology adoption aligned with business goals. Moreover, as retail shifts toward hybrid work models and decentralized operations, managed IT services ensure seamless and secure remote support for employees in stores, warehouses, and home offices.

Remote assistance capabilities have become increasingly important, especially in the wake of the COVID-19 pandemic, which accelerated the need for flexible work arrangements. Providers that deliver robust remote IT support enable retail teams to stay connected and productive regardless of location.

Additionally, managed IT services help retailers maintain compliance with evolving cybersecurity standards and data protection laws, safeguarding their operations against emerging threats. This proactive approach to IT management enables retailers to embrace innovation confidently, minimize risks, and sustain competitive advantage.

The increasing sophistication of cyber threats targeting retail businesses further emphasizes the need for expert IT support. According to a recent report, 43% of cyberattacks in the retail sector target point-of-sale systems and payment processing infrastructure. Managed IT providers help mitigate these risks through continuous security monitoring, threat detection, and rapid incident response.

Conclusion

The retail industry’s digital transformation journey is complex and ongoing. IT support and managed IT services are foundational elements that power this transformation, enabling retailers to adopt new technologies, enhance customer experiences, streamline operations, and innovate securely. By partnering with expert IT providers, retailers can reduce downtime, improve agility, and focus on delivering value to customers.

As competition intensifies and technology continues to evolve, the retailers that invest strategically in managed IT services will be best positioned to thrive. These partnerships not only support day-to-day operations but also provide the guidance and infrastructure needed to future-proof retail businesses in an increasingly digital world.

In summary, the integration of IT support and managed IT services into retail operations is no longer a luxury but a necessity. Retailers embracing these services can expect enhanced performance, greater resilience, and a stronger competitive advantage in the digital marketplace. With technology continuing to reshape consumer expectations and operational paradigms, managed IT services will remain at the heart of retail innovation and success.

METRO to Convert 10 Ontario Stores to Food Basics

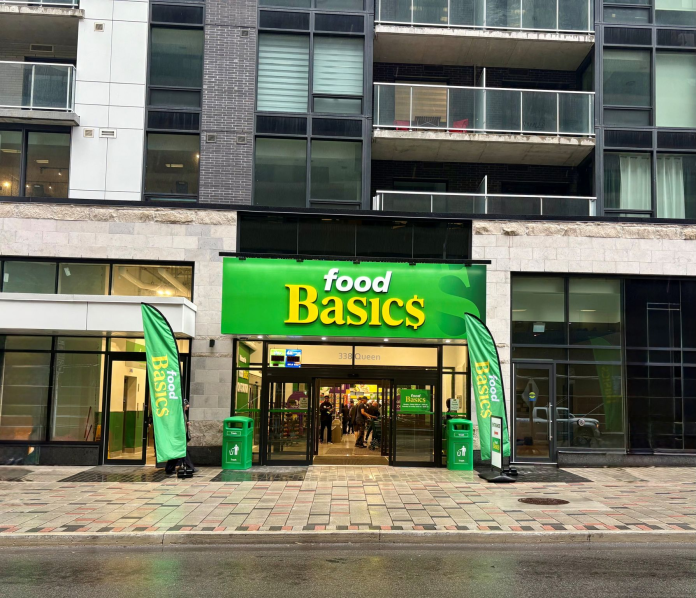
Food Basics at 340 Queen St. in downtown Ottawa. Photo: Food Basics

METRO Inc. is accelerating the expansion of its Food Basics discount banner in Ontario, with plans to convert 10 existing Metro supermarkets as consumers continue to prioritize value and the company adjusts its store network market by market.

The conversions will take place across Ontario, including locations in the Greater Toronto Area, Ottawa and elsewhere in the province. Two have so far been identified: Metro Southgate in Ottawa and the Metro at 20 Church Avenue near Yonge and Finch in Toronto. METRO has not disclosed the remaining eight locations, saying stores and employees will be informed progressively as the program is rolled out.

The company is also planning to permanently close one additional, as-yet-unidentified Ontario store and a satellite warehouse as part of a broader network restructuring. METRO said the changes are intended to address customers’ continued search for value and strengthen its competitive position in targeted markets.

The moves come as discount grocery continues to capture more consumer spending. On METRO’s third-quarter earnings call Wednesday, Chief Operating Officer Marc Giroux said shopping patterns remain similar to recent quarters, with consumers purchasing proportionately more private-label products, participating in promotions and directing greater volume toward discount stores than conventional supermarkets.

“Consumers are focused on value,” Giroux told analysts, adding that METRO expects the trend to continue and is investing accordingly in what it considers the right store format for each market.

Food Basics Expected to Outperform Converted Metro Stores

METRO is positioning the 10 conversions as a targeted optimization of individual stores rather than a broad retreat from its conventional Metro banner.

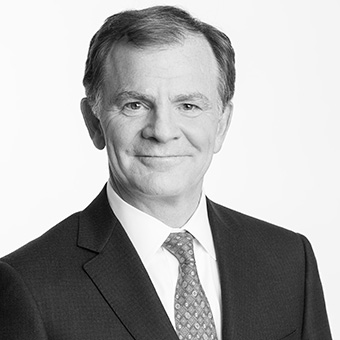
President and CEO Eric La Flèche said the company continually evaluates its network and considers the most appropriate format for individual trade areas. For the 10 stores selected for conversion, management concluded that Food Basics provides a better fit for the markets they serve.

Eric La Flèche
Eric La Flèche

“If we’re deciding to convert a store, it’s because the store is not the right store for that market, and the store has not been performing as we would want to,” La Flèche told analysts.

METRO expects the conversions to increase sales and improve store contribution. Depending on the amount of construction required, an individual store could close for roughly two months during its transition, resulting in a temporary sales decline before reopening as Food Basics.

Once reopened, management expects the converted stores to generate higher sales than they did under the Metro banner, with further growth anticipated as the locations mature. The conversions are expected to begin improving store contribution in fiscal 2027, with benefits increasing over the following two years.

Toronto and Ottawa Stores Among First Conversions

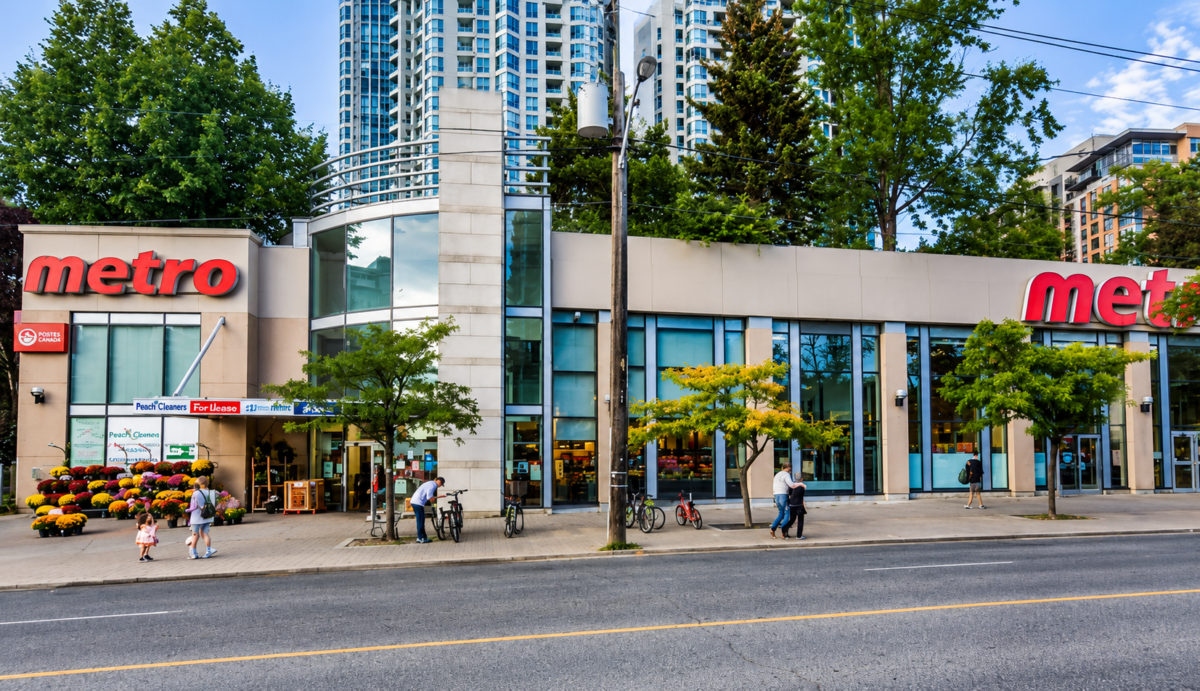
The Metro at 20 Church Avenue in North York, near Yonge Street and Finch Avenue, is one of the stores slated to become Food Basics. METRO has confirmed the location as part of the 10-store program. The existing supermarket is scheduled to close August 13, with Food Basics expected to open at the site later in the fall.

METRO has also confirmed that Metro Southgate in Ottawa, at 2515 Bank Street, will be converted. La Flèche said during the earnings call that the Ottawa conversion is expected to open by the end of the current fiscal year.

The company has not identified the remaining eight stores. La Flèche said some locations had recently been advised or would be informed shortly, but METRO was withholding further details until affected employees had been notified. He said the conversions include stores in the GTA as well as other parts of Ontario.

The restructuring also has employment implications. METRO has not disclosed how many workers will ultimately be affected, but said employees at the Toronto and Ottawa stores have options under their respective collective agreements. Some employees will work at the incoming Food Basics stores, while others may pursue different options available under those agreements.

METRO recorded $25.7 million in restructuring expenses during the third quarter, primarily related to employee termination benefits, restoration and site-closure costs, and lease-related expenses. Those costs apply to the broader restructuring program, which includes the 10 conversions, the separate Ontario store closure, the satellite warehouse closure and changes to the company’s Montreal e-commerce operation.

Metro at 20 Church St. in Toronto. Image: CBRE

Food Basics Network Continues to Grow

The 10 conversions build on several years of expansion for METRO’s discount banners. Over the past three years, the company has added 31 discount locations through new stores and conversions, bringing Food Basics to 155 stores in Ontario and Super C to 121 in Quebec. Management said customers have responded well to the discount formats and that new and converted locations are generating encouraging sales results and returns.

METRO is also on track to open approximately a dozen new or converted discount stores during fiscal 2026. Five discount stores opened during the third quarter, including one conversion and one relocation.

The expansion extends a strategy already underway before the latest restructuring, with METRO directing more of its store investment toward discount formats as consumers emphasize price and value. The latest 10-store program adds another dimension by repositioning existing conventional supermarkets in markets where management believes Food Basics can generate stronger sales and returns.

Ontario Grocery Market Remains Highly Competitive

The shift is taking place against a highly competitive grocery backdrop in Ontario. La Flèche said METRO is pleased with its business in the province and is holding market share, while acknowledging continued competition for consumer spending.

Population growth has also slowed considerably while grocery square footage continues to expand. La Flèche said population growth is now “very small or flat,” adding to competitive conditions as retailers pursue growth in the market.

La Flèche rejected the suggestion that the 10 conversions were simply a reaction to competing discount stores opening nearby. He described the decisions as part of METRO’s ongoing review of individual markets and store performance.

“This was a good time to relook at the network as we were preparing the plans for next year,” La Flèche said. “For those 10 locations, we feel discount’s the way to go.”

Broader Network Changes Underway

The Ontario conversions are part of a wider effort by METRO to adjust its network and lower costs in areas where consumer behaviour has changed. In Quebec, the company will close its dedicated Montreal e-commerce fulfilment centre and shift to store-based picking supported by third-party delivery. METRO said growing demand for same-day grocery delivery makes the store network better suited to fulfil online orders while reducing the fixed costs associated with a dedicated facility.

The overall network optimization program is expected to generate approximately $15 million in recurring annual after-tax earnings by the end of fiscal 2028, with about half of the benefit expected by the end of fiscal 2027. Management said roughly half of the eventual improvement should come from increased contribution at the converted Food Basics stores and half from the lower-cost e-commerce fulfilment model.

METRO expects the Ontario restructuring to be completed by the end of fiscal 2027. For now, eight of the 10 Metro locations slated for conversion remain undisclosed, with the company planning to identify stores progressively as affected employees are informed.

More from Retail Insider:

IKEA Canada to launch limited-edition KONSTRUNDA art collection

IKEA Canada photo
IKEA Canada photo

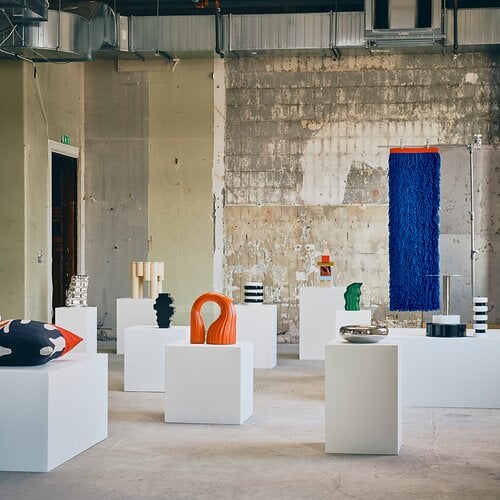
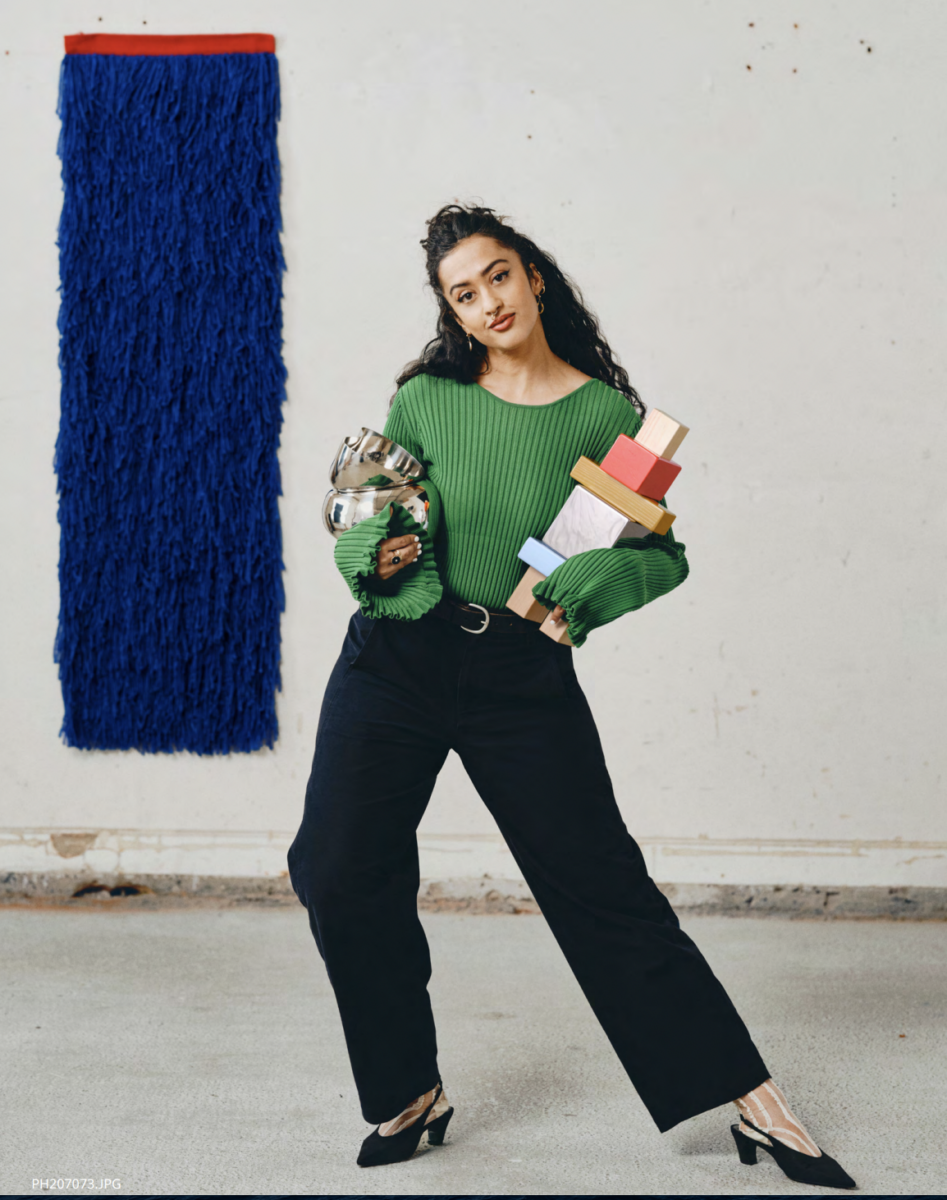
IKEA Canada is launching a limited-edition collection of 18 art objects created by seven artists, designers and creatives, with the products set to go on sale across the country and online Sept. 1.

The KONSTRUNDA collection brings together glass objects, ceramics, furniture and textiles, with IKEA positioning the range as an effort to make art more accessible through everyday home furnishings.

Collection brings together seven creators

IKEA said the contributors were invited to work independently from a blank canvas, creating pieces based on their individual perspectives. The collection’s name, KONSTRUNDA, means “Art Tour” and reflects what the company describes as a range of different artistic voices.

“Art should be available for all to enjoy, not a luxury reserved for galleries,” said Karin Gustavsson, Creative Leader for KONSTRUNDA. “Art evokes emotion, sparks conversation and helps transform a house into a home. With KONSTRUNDA, we wanted to create a collection that encourages people to express themselves and surround themselves with objects they love.”

The collection includes a handblown glass vessel, a stool designed as a sculptural piece and textiles intended to function as works of art. IKEA said the pieces feature bold forms, vibrant colours and expressive silhouettes, with each reflecting the individual creator’s approach.

The company said the collection is intended to allow customers to incorporate individual pieces into their homes or build collections of objects that have personal meaning.

IKEA emphasizes accessibility

Meghan Willisko, Head of Home Furnishing & Retail Design, said the collection is intended to make art more approachable through household objects.

“At IKEA, we know Canadians are always looking for ways to make their homes feel more personal and welcoming,” said Willisko. “What I love about KONSTRUNDA is its ability to make art more approachable through thoughtfully designed objects that inspire self-expression and creativity. By offering these pieces at affordable prices, we’re making it easier for the many Canadians to bring art into their everyday lives and create homes that truly reflect who they are.”

The company said its role in the collection is not to define or explain art, but to provide a platform for the participating creators while applying its experience in product development.

“At IKEA, we don’t claim to define or explain art. Instead, our role is to create space for it,” said Gustavsson. “We have extensive knowledge and experience in designing and developing products. We understand materials, proportions, colours, durability, and how to bring ideas to life. Through KONSTRUNDA, we can offer a platform for artists to create and an opportunity for people to collect art that reflects who they are in the home.”

Collection launches Sept. 1

KONSTRUNDA will be available in IKEA stores across Canada and online starting Sept. 1.

IKEA Canada is part of Ingka Group, which operates 574 IKEA stores in 31 countries. In Canada, the company operates 15 stores and 13 Plan and order points.

The company said IKEA Canada welcomed 33.3 million visitors to its stores last year and recorded 199.9 million visitors to IKEA.ca.

IKEA Canada was founded in 1943 in Sweden and operates under the company’s stated vision of creating a better everyday life for the many people.

More from Retail Insider:

Morguard Advances Mall Redevelopments as Retail Leasing Strength Continues Across Canada

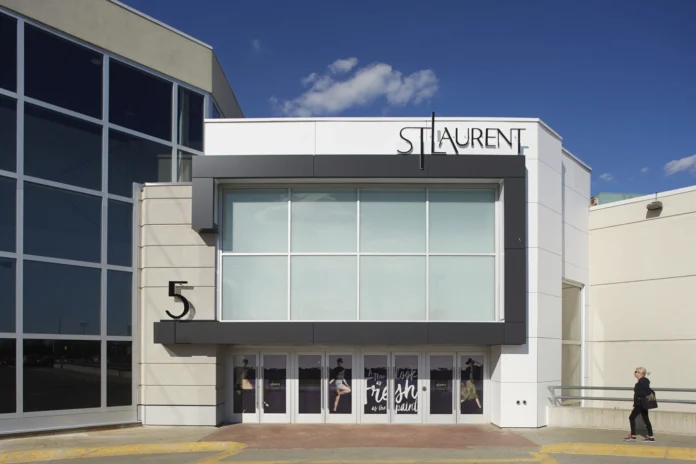
St. Laurent Centre in Ottawa. Image: morguardretailleasing.com

Morguard Real Estate Investment Trust is advancing a series of redevelopment projects across its Canadian shopping centre portfolio, bringing grocery stores, entertainment concepts and expanding national retailers into spaces formerly occupied by department stores and other large-format tenants.

The REIT reported improving retail occupancy and positive leasing momentum during the second quarter of 2026, with grocery-anchored community centres operating near capacity and enclosed malls continuing to post income growth despite the challenges created by Hudson’s Bay’s departure from several properties.

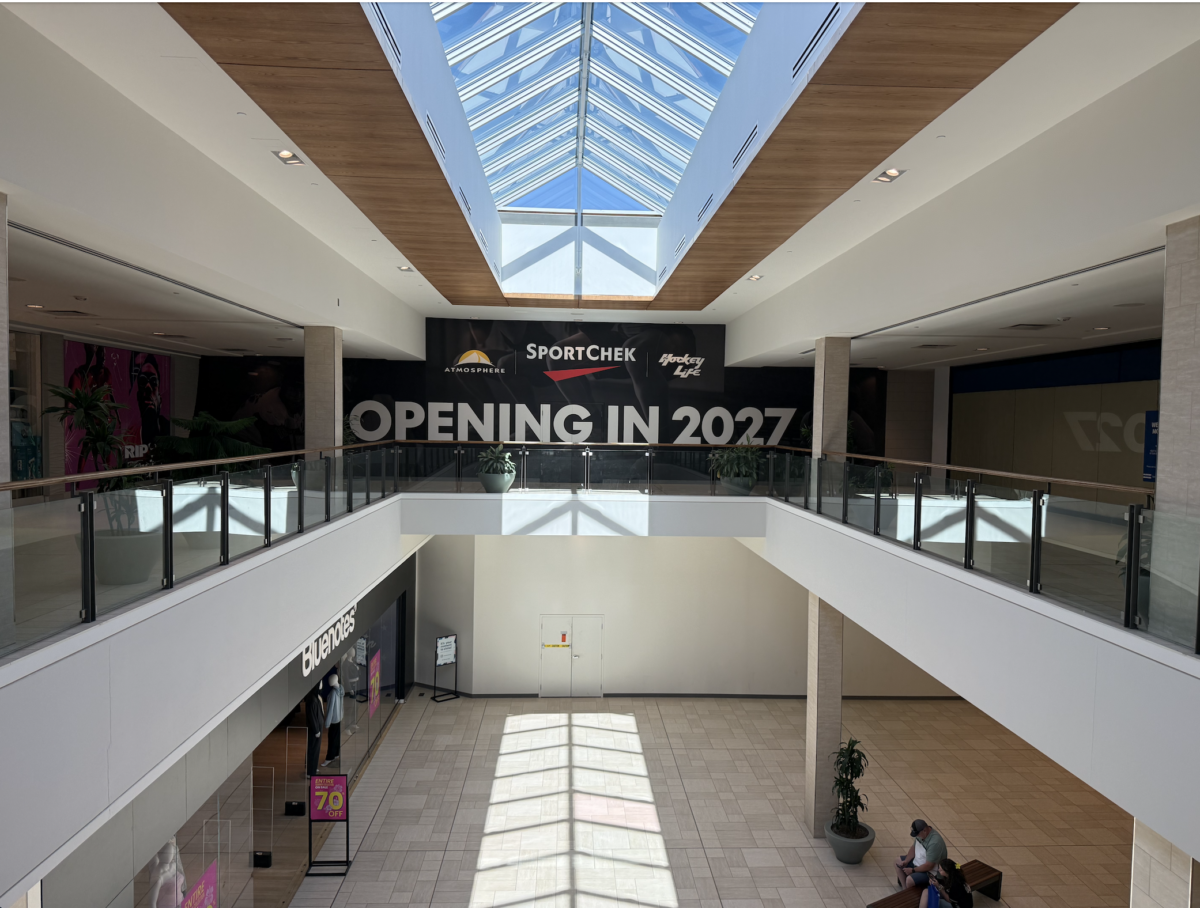
At St. Laurent Centre in Ottawa, a multi-year remerchandising program has already contributed to approximately 10 per cent increases in both foot traffic and sales productivity among smaller retailers, according to management. Additional projects are underway at malls in Saskatoon, Red Deer and Cambridge, Ontario, involving retailers and concepts including Uniqlo, Sport Chek, No Frills, Splitsville and Activate.

“We continue to believe that there are strong fundamentals in the retail leasing environment,” Andrew Tamlin, chief financial officer of Morguard REIT, said during the company’s second-quarter conference call.

The projects illustrate how Canadian shopping centre owners are moving beyond the traditional department store model, replacing large single-purpose anchors with a broader mix of fashion, grocery, sporting goods and entertainment operators designed to generate more frequent visits throughout the week.

Retail Occupancy Continues to Improve

Retail occupancy reached approximately 89.7 per cent at the end of June, up from 88 per cent at the close of 2025 and 60 basis points higher than the previous quarter.

Morguard reported occupancy of approximately 95 per cent across its community shopping centres and 87.8 per cent across its enclosed regional malls.

The REIT owns interests in 18 retail properties comprising approximately 4.3 million square feet. Its broader commercial portfolio, which also includes office and industrial assets, totals roughly eight million square feet across six provinces.

Community shopping centres generated same-asset net operating income growth of 5.9 per cent during the quarter, while enclosed regional malls recorded growth of 2.5 per cent.

Management described the community centre portfolio as effectively full, reflecting the stability of grocery stores, financial institutions and other daily-needs retailers that continue to generate consistent customer traffic.

The enclosed mall portfolio has required more active redevelopment, particularly where former department stores created significant vacancies. Even so, Morguard reported solid tenant sales, healthy traffic levels and positive leasing spreads secured throughout 2025 that continued to support retail performance this year.

St. Laurent Centre Becomes the Portfolio’s Showcase Redevelopment

St. Laurent Centre has emerged as Morguard’s flagship example of how strategic tenant remerchandising can strengthen an established regional shopping centre.

The Ottawa property is undergoing a multi-year transformation designed to introduce prominent national and international retailers while redeveloping former Sears and Hudson’s Bay space.

The first phase, completed in late 2025, created new or expanded premises for H&M, Sephora and La Vie en Rose through an investment of approximately $5.4 million.

Management said those additions have already produced measurable benefits. Foot traffic has increased by approximately 10 per cent, while sales productivity among smaller retailers has also risen by roughly 10 per cent, according to John Ginis, vice-president of retail asset management.

“Productivity of the shopping centre is up because foot traffic is up,” Ginis said. He added that sales among the mall’s smaller tenants had increased by a similar amount.

The next phase centres on approximately 84,000 square feet of former Sears space. Morguard has allocated approximately $23.3 million toward that redevelopment, including demolition of an obsolete parking structure connected to the former department store. The broader St. Laurent program is expected to involve between $25 million and $30 million in investment.

A 12,600-square-foot Uniqlo store is expected to open in early 2027. Sport Chek will relocate into a new-format store within the redeveloped area, while Splitsville will introduce a new entertainment destination. The larger redevelopment is expected to continue into 2028.

Rather than replacing one traditional anchor with another, the project assembles several complementary uses that can attract customers for different reasons and at different times of the week.

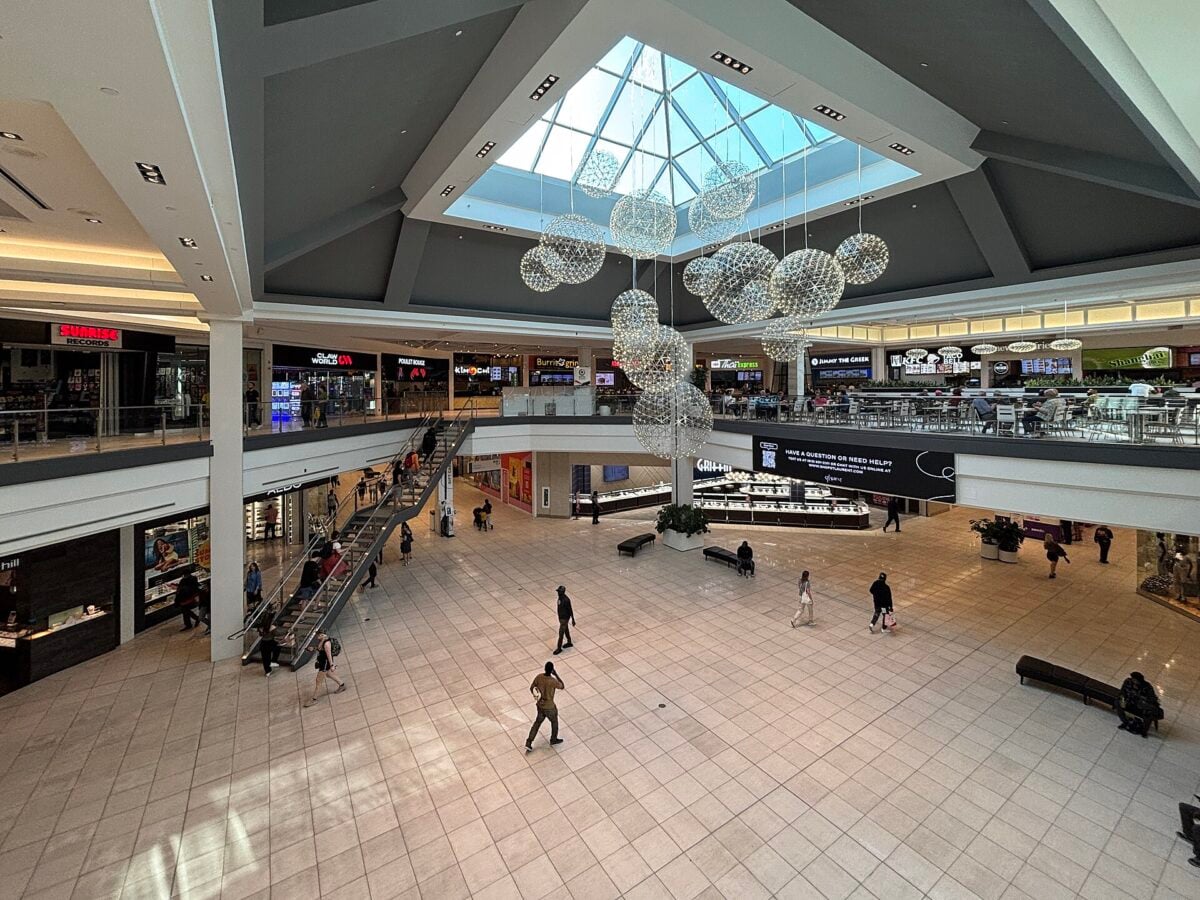
Laurent Shopping Centre Atrium 2025. Image: Canmenwalker on commons.wikimedia.org

Hudson’s Bay Leaves Different Challenges at Different Properties

Hudson’s Bay previously occupied approximately 290,000 square feet across St. Laurent Centre and Cambridge Centre, generating roughly $1.5 million in annualized gross rent for Morguard REIT before the leases were terminated through the retailer’s creditor-protection proceedings.

The Cambridge Centre lease was disclaimed in June 2025. The St. Laurent lease remained part of Hudson’s Bay’s lease monetization process for several additional months and was included among the locations proposed for transfer to a new department store venture led by B.C. businesswoman Ruby Liu. The court rejected that transaction in October 2025, and the St. Laurent lease was disclaimed the following month.

The closures immediately affected occupancy and rental income, but they also created opportunities to rethink how large department store boxes function within modern shopping centres.

Urban Behaviour Provides an Interim Solution at St. Laurent

One of Morguard’s earliest responses was relocating Urban Behaviour into part of the former Hudson’s Bay premises at St. Laurent Centre. The retailer opened in the lower level of the former department store in May 2026, allowing Morguard to reactivate part of the space while broader redevelopment plans continue.

Management said Urban Behaviour has been performing exceptionally well at the property.

The move demonstrates how landlords can use existing successful tenants to restore activity while planning longer-term redevelopment requiring larger capital investments.

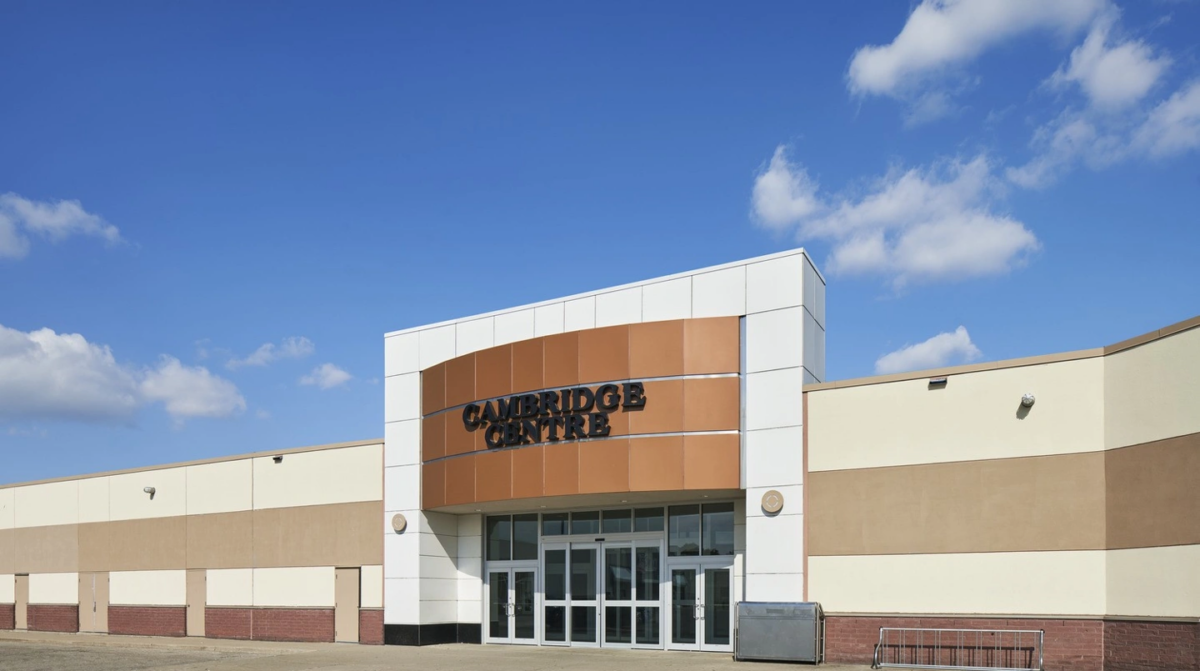
Cambridge Centre. Image: Morguard

Grocery Continues Expanding Into Canadian Malls

Morguard is also strengthening its enclosed malls by introducing grocery anchors.

A No Frills opened at Parkland Mall in Red Deer during late 2025 following a redevelopment costing approximately $1.6 million. The project transformed previously vacant space into more than 22,000 square feet of income-producing retail.

Another No Frills is under construction at The Centre in Saskatoon within former Target space. The approximately 30,000-square-foot store is expected to open during the second quarter of 2027 following an investment of approximately $4.7 million.

Management expects both stores to become significant traffic generators.

The projects reflect a broader trend across Canadian shopping centres, where grocery retailers are increasingly replacing large-format vacancies and creating dependable weekly visitation that benefits neighbouring merchants.

Entertainment Continues Expanding Within Regional Shopping Centres

Entertainment has become another important component of Morguard’s redevelopment strategy.

Alongside Splitsville at St. Laurent Centre, the REIT is converting approximately 11,000 square feet of former cinema space at The Centre in Saskatoon for Activate. The project is expected to cost approximately $2.2 million and be completed during the second quarter of 2027.

Entertainment operators can often occupy spaces that are difficult to divide among conventional retailers while extending customer visits into evenings and weekends, supporting restaurants and other nearby businesses.

Cambridge Centre Remains a Work in Progress

Redevelopment of the former Hudson’s Bay premises at Cambridge Centre remains under negotiation. Management said it is working toward a transaction involving at least the lower level of the former department store, although no binding agreement had been finalized at the time of the conference call.

The REIT has removed approximately 65,700 square feet from its active leasable area while redevelopment options are evaluated. As a result, improvements in reported occupancy should not be interpreted as a complete replacement of the former Hudson’s Bay space.

The contrast between Cambridge Centre and St. Laurent demonstrates that no single formula exists for redeveloping former department store properties. Layout, access, construction requirements and local market demand all influence the eventual solution.

Canadian Shopping Centres Continue to Evolve

Morguard’s redevelopment program reflects broader changes taking place across Canada’s shopping centre industry. Rather than relying on a single department store to anchor an entire property, landlords are increasingly assembling a mix of grocery, fashion, sporting goods, beauty and entertainment tenants that create multiple reasons for customers to visit.

At St. Laurent, that strategy now includes Uniqlo, Sport Chek, Splitsville, H&M, Sephora and Urban Behaviour. In Red Deer and Saskatoon, No Frills is introducing regular grocery traffic, while Activate adds another destination beyond traditional retail shopping.

The early results at St. Laurent suggest the approach is gaining traction. Higher foot traffic and stronger sales among smaller retailers indicate that investment in anchor spaces can strengthen performance across an entire shopping centre.

Morguard expects retail performance to remain stable through the balance of 2026 as redevelopment projects continue.

While work remains to replace former Hudson’s Bay space at several properties, the REIT’s recent leasing activity suggests well-located Canadian shopping centres continue to attract investment from retailers prepared to expand their physical presence.

As department stores continue to disappear from the retail landscape, Morguard’s strategy points toward a different model for Canada’s regional malls — one built around a diverse mix of destinations rather than a single dominant anchor.

More from Retail Insider:

Pet Valu Sees Room for 1,200+ Stores Across Canada

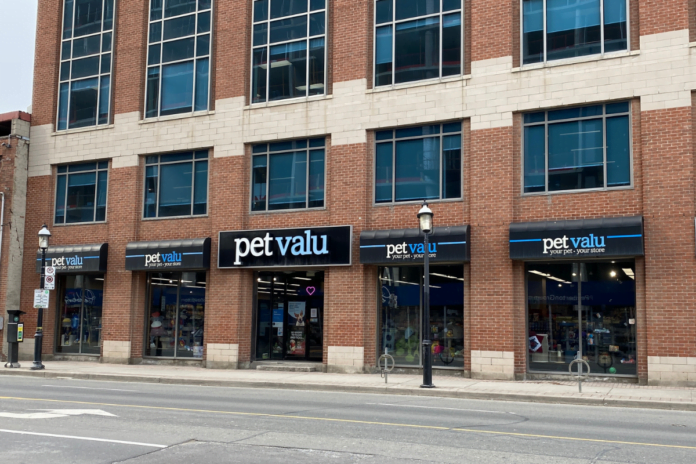
Pet Valu on Front Street in Toronto (Image: Dustin Fuhs)

Pet Valu continues to see room for more than 1,200 stores across Canada as the specialty pet retailer expands into Alberta, Quebec and smaller communities where management believes additional market opportunities remain.

The company ended its second quarter with 877 locations after opening seven stores during the period and 15 in the first half of 2026. Recent openings have performed well, according to management, with rural markets that have little or no specialty-pet competition among the areas identified for further growth.

The 1,200-plus figure is a long-standing estimate of Pet Valu’s potential Canadian footprint rather than a new target. The retailer had 633 stores at the end of 2021 and has since added more than 240 locations as it continues to build out its national network. Stifel analyst Martin Landry expects the expansion to continue at about 40 net new stores annually, forecasting approximately 903 locations by the end of 2026 and 943 in 2027, compared with 783 stores in 2023, 824 in 2024 and 863 at the end of 2025.

Rural Markets Offer Room for Growth

Smaller Canadian communities are becoming an increasingly important part of Pet Valu’s expansion strategy. CEO Greg Ramier said the company is focusing new-store investment on growth pockets across Canada, including Alberta, Quebec and rural communities, with stores opened during the past year producing good starts and satisfactory return profiles.

Management highlighted rural locations where Pet Valu can enter communities without an existing specialty-pet competitor. The strategy fits the retailer’s neighbourhood-oriented format and its emphasis on recurring purchases such as pet food and other consumables, allowing it to operate in smaller trade areas that may have limited specialty retail competition.

Ramier also said Pet Valu continues to find opportunities to fill market gaps while some competitors have paused expansion. The company takes a long view when selecting locations, with management describing a new store as a commitment of 10 years or more that is expected to operate through a full economic cycle.

Alberta and Quebec Among Expansion Priorities

Alberta and Quebec were specifically identified by management as markets where Pet Valu continues to see growth opportunities. Quebec has become a larger part of the network following Pet Valu’s acquisition of Chico, and the company is increasingly extending programs developed across the broader Pet Valu system to the Quebec banner, including its Item of the Month and Treat of the Month initiatives.

Pet Valu also completed its first corporate-store resales under the Chico banner during the second quarter. Quebec remains a competitive specialty-pet market, including a substantial presence from Mondou, which has grown beyond 100 locations in the province, leaving Pet Valu to pursue further growth through Chico while competing with established regional operators.

Franchise Model Supports Continued Growth

Franchising remains central to Pet Valu’s network strategy. About 71% of its 877 stores were franchised at the end of the second quarter, with that proportion increasing slightly as the company continued transferring selected corporate locations to franchise operators.

Pet Valu sold 11 corporate stores during the quarter, tying a company record, with locations acquired by both new and existing franchisees. Management said there remains a strong pipeline of franchisees interested in established stores where they can begin operating with an existing customer base and sales history.

The practice dates to Pet Valu’s move into franchising in the late 1980s and is expected to continue. With more than 250 corporate locations, management said the company typically has a subset of stores available for resale, providing another mechanism for increasing franchise penetration as the overall network grows.

Store Growth Continues Despite Softer Traffic

Pet Valu is continuing to add locations despite relatively subdued comparable-store performance. Same-store sales declined 0.2% in the second quarter, with Stifel estimating that a 1.2% increase in basket size was more than offset by a 1.4% decline in traffic as consumers consolidated shopping trips amid higher fuel costs.

The company nevertheless continues to report satisfactory returns from newly opened stores and is maintaining its expansion plans. Management has also said its 2026 outlook does not depend on a material improvement in the current consumer environment, leaving new-store development as an important source of growth while comparable sales remain close to flat.

Pet Valu Continues to Gain Market Share

Pet Valu says it continued gaining market share during the second quarter, supported by its expanding store network and growth across physical and digital channels. Management estimates that specialty retailers account for roughly half of the Canadian pet market and said there has been little movement between specialty and mass-market channels, with Pet Valu continuing to consolidate share within specialty retail.

Stifel estimates Pet Valu holds about 18% of the Canadian pet market, approximately three percentage points ahead of its next competitor. Landry also sees the possibility of difficult operating conditions putting pressure on some single-location pet retailers, potentially creating additional market-share opportunities for larger operators such as Pet Valu.

Pet Valu’s scale is also helping it manage costs as the network expands. The company has been working with specialty and national brands to mitigate rising product and fuel expenses, while investments in its distribution network have generated cost efficiencies for four consecutive quarters.

Store Network Supports Digital Growth

The physical network is also supporting Pet Valu’s digital business, which management says continues to grow faster than the broader industry’s online channel. Click & Collect and delivery platforms benefit from the reach of the store base, while the AutoShip subscription service continues to increase both in absolute dollars and as a proportion of digital sales.

Pet Valu does not disclose digital sales as a percentage of total revenue, but management has repeatedly linked the performance of its online business to the reach of its physical network. That gives the company another reason to increase store density, with locations supporting recurring in-store purchases as well as digital fulfilment and pickup.

At 877 stores, Pet Valu would need more than 300 additional locations to reach the 1,200-plus network size management believes Canada can ultimately support. The current pace of about 40 new stores annually points to a multi-year expansion, with smaller communities and further development in markets including Alberta and Quebec expected to account for part of that remaining growth.

More from Retail Insider:

Pajar Acquires GGB as North American Expansion Accelerates

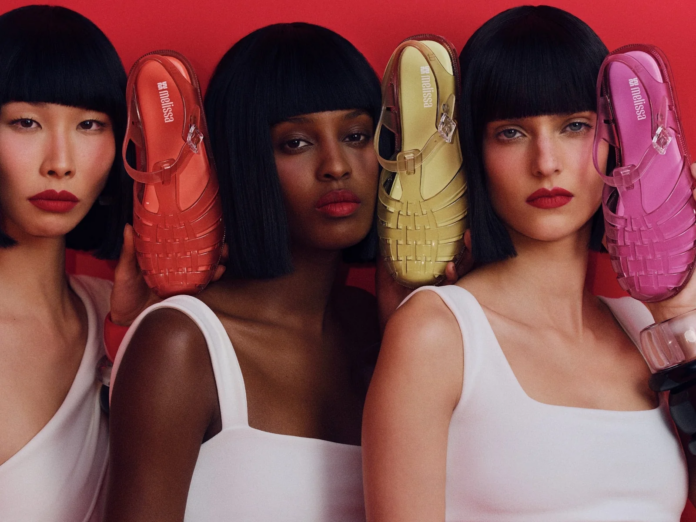
Melissa Footwear. Photo: shopmelissacanada.com

Montreal-based Pajar Canada has acquired Grendene Global Brands USA (GGB), expanding the Canadian company’s U.S. operations and giving it responsibility for the distribution and commercial management of Melissa and Mini Melissa in the United States.

Grendene had disclosed in March that it signed a non-binding letter of intent for the potential sale of the U.S. subsidiary to Pajar. The completed transaction gives Pajar an established U.S. operation for Melissa and Mini Melissa as the Montreal company continues to expand its North American footwear business.

The acquisition follows several years of expansion for Pajar, including its acquisition of Canadian footwear brand Cougar and a growing number of third-party distribution relationships. It also advances an effort to reduce the seasonality of a business historically centred on cold-weather footwear.

“We’ve always been looking to equalize our business from fall to spring,” Pajar President Michel Golbert told Retail Insider. “About 90 per cent of our business was fall, and we were looking for something that could complement Pajar and then Cougar.”

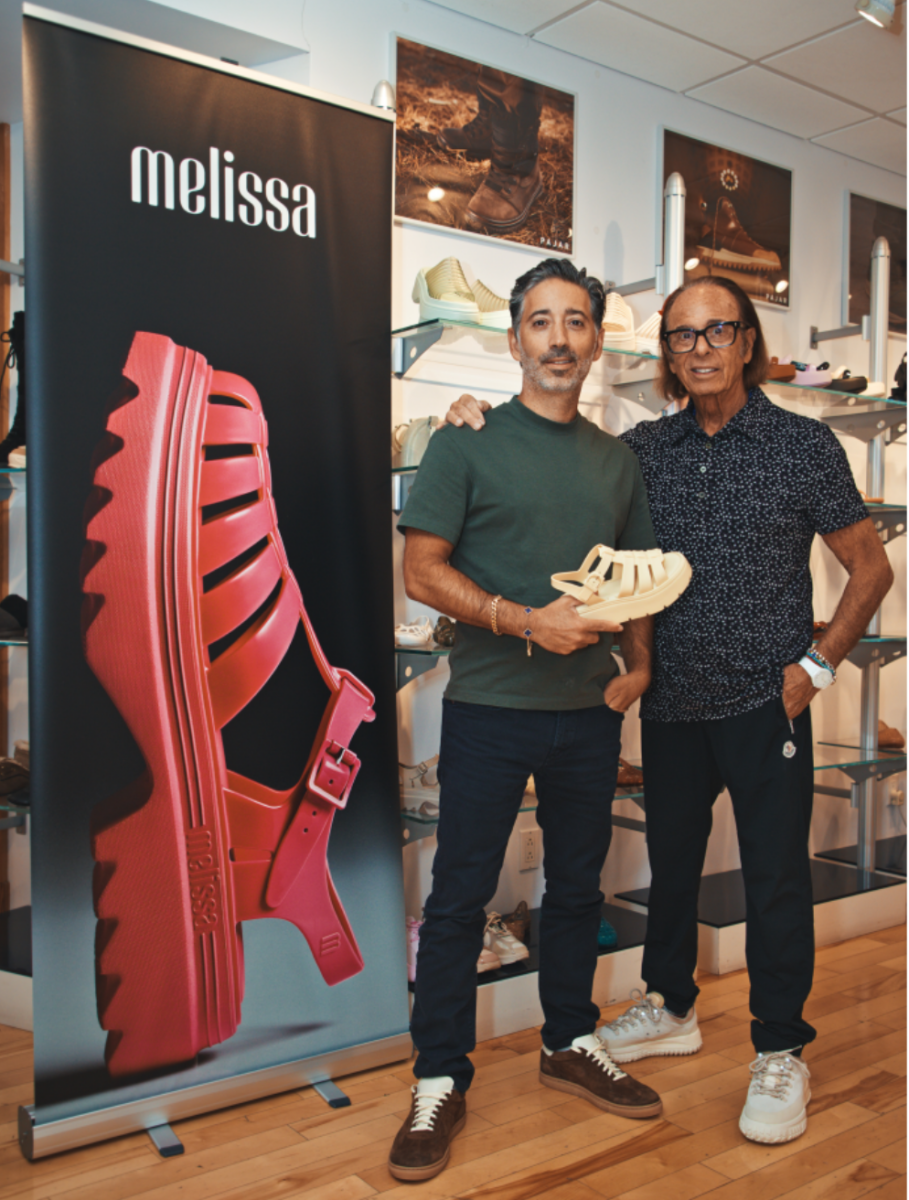
Michel Golbert, left, with father Jacques Golbert.

Canadian Success Led to U.S. Expansion

Pajar began distributing Melissa in Canada in 2025 as part of an expanded relationship with Grendene. The agreement, announced in June 2025, brought Melissa into Pajar’s Canadian sales network while Pajar also took on broader North American distribution responsibilities for several Grendene brands.

Golbert said the Canadian business performed well, helping lead to discussions with Grendene about expanding the relationship into the United States.

“We were very successful with everything, and we started talking to Brazil about possibly taking over the U.S.,” Golbert said. “One thing led to another, and we signed the deal.”

The agreement went beyond an expanded distribution contract. Pajar acquired the existing GGB operation, including its U.S. warehouse, and Golbert said most of its employees have joined Pajar to continue operating the business.

Pajar will now oversee U.S. distribution and commercial management for Melissa and Mini Melissa while continuing to oversee Ipanema distribution in North America. The company said the brands strengthen its spring and summer business and complement its longstanding position in premium winter footwear and outerwear.

Pajar’s acquisition of Cougar in 2024 was another step in that diversification, with the company using its distribution network to expand the Canadian footwear brand into additional markets.

Existing GGB Operations Remain in Place

Pajar deliberately acquired GGB rather than establishing a new U.S. company to handle the Melissa business. Golbert said retaining the existing organization allowed Pajar to preserve its employees, customer integrations, warehousing and ERP systems while minimizing disruption for retailers.

“There aren’t going to be many changes,” Golbert said. “We’ve been able to bring their staff in the U.S. on board, so it’s going to be pretty much business as usual.”

Golbert said acquiring the company itself was important because its infrastructure and customer relationships were already in place.

“We did it on purpose. We bought the actual company rather than starting a new company because all the integrations were already in place with the customers, along with the warehousing and ERP system,” he said. “We can start from day one, ship and continue doing everything they were doing without losing that momentum.”

Grendene had outlined some of the rationale for the transaction when negotiations were disclosed in March. The Brazilian manufacturer said the potential sale was consistent with a strategy to strengthen its U.S. presence through a local partner while improving operating efficiency and profitability and reducing direct exposure to international operations.

For Pajar, the acquisition provides an established U.S. organization through which to grow Melissa without having to recreate the distribution infrastructure.

Photo: Pajar Canada

Melissa Growth Creates U.S. Opportunity

Founded in Brazil in 1971, Grendene is one of the world’s largest footwear manufacturers. Its portfolio includes Melissa, Mini Melissa and Ipanema, among other brands, with products sold in more than 100 countries.

Melissa has developed an international following around its moulded footwear, distinctive designs and fashion collaborations. Golbert said the broader jelly footwear category has been performing particularly well over the past year and a half, particularly in the U.S.

“The whole jelly category is on fire right now,” Golbert said. “Over the past year and a half, that category has been doing very well, especially in the U.S.

Golbert described Melissa as Grendene’s higher-end jelly footwear brand and a key part of the Brazilian company’s international portfolio. In Canada, he said Melissa is carried by retailers including Browns and Holt Renfrew, while U.S. accounts include Bloomingdale’s, Nordstrom and Kith.

Pajar intends to expand both the wholesale and direct-to-consumer sides of Melissa and Mini Melissa in the U.S. The company said it plans to invest in the B2B and B2C businesses while maintaining the creativity and brand identity that have helped Melissa build its international following.

Image from the Pajar Canada website

Pajar Adds More Brands in Canada

Pajar has also recently expanded its Canadian distribution business as consolidation continues within the footwear sector.

Golbert told Retail Insider that Pajar has taken over Canadian distribution for Merrell Kids, Saucony Kids, Stride Rite and Kenneth Cole Women’s following the closure of longtime Canadian footwear distributor Indeka.

“We’ve taken over the distribution rights in Canada for those brands,” Golbert said.

Indeka, founded in 1972, represented a portfolio of footwear brands in Canada that included the four businesses Golbert identified as moving to Pajar. The additions broaden Pajar’s distribution activities across multiple footwear categories and selling seasons.

Golbert was cautious when asked whether Pajar could pursue further acquisitions after GGB.

“It’s a bit too soon to talk about that,” he said.

Footwear Industry Continues to Consolidate

Golbert spoke with Retail Insider from the floor of AFA Canada’s United in Style Spring/Summer 2027 trade show at the Toronto Congress Centre. The event brings together footwear, apparel and accessory brands with retailers, buyers and other industry participants from across Canada.

The setting provided a real-time view of an industry Golbert said is consolidating among both retailers and wholesalers.

“It’s not great for wholesalers like ourselves because obviously we’re losing stores every year,” Golbert said, pointing to the loss of major retail channels in Canada. He said surviving footwear retailers, including Browns and SoftMoc, have been positioned to capture some of the business left behind.

“Whoever is still standing is doing well,” he said. “People like Browns or SoftMoc are taking advantage of some of the mishaps from everybody else.”

Golbert sees similar consolidation among suppliers and distributors. From the United in Style show floor, he observed that the event appeared smaller than the previous edition six months earlier.

“There are fewer wholesalers as well,” Golbert said. “The show is much smaller than it was six months ago. Either there are fewer brands, people aren’t spending as much, or there are other factors, but it’s consolidating. There are fewer players.”

Pajar has been able to find opportunities within that changing market, including its additional Canadian distribution relationships and the GGB acquisition.

“For people like ourselves, we’re lucky that we’ve been able to capitalize on things like that,” Golbert said. “But I can see how it could be complicated for others.”

Despite the reduction in industry participants, Golbert remains positive about consumer demand.

“In general, the shoe business is still very strong,” he said. “We have good brands, and people are still interested in buying boots and shoes.”

More Than Six Decades in Montreal

Pajar was founded in Montreal in 1963 by Paul Golbert, whose family had a background in European shoemaking. The Pajar name was formed from the names Paul, Jacques and Rachel, and the company established its Montreal footwear factory in 1973.

The company remains family-run, with Jacques Golbert serving as CEO, Michel Golbert as President and David Golbert as Vice President. Pajar describes itself as a fifth-generation family footwear business and has said that its shared family-business culture with Grendene contributed to the relationship between the companies.

Manufacturing remains part of Pajar’s Montreal operation.

“We still produce in Montreal,” Golbert said. “We have our small factory, which produces our high-end Montreal | 1963 collection. We produce the rest of our boots in Europe and Asia, and then we distribute brands like Ipanema and Melissa from Brazil.”

Pajar distributes Cougar directly in the U.S. and works with a distributor for the brand in Canada. Cougar is also gradually expanding into Europe, following an international growth strategy Pajar has used for its namesake brand.

The GGB acquisition adds an established U.S. operation and a larger spring and summer footwear business to Pajar’s growing mix of owned brands and distribution relationships.

For Melissa, Golbert said the immediate focus is straightforward.

“Our goal is to continue selling, continue growing and maintain the momentum we’re having,” he said. “Then we’ll see where these opportunities bring us.”

More from Retail Insider:

Insolvencies on the rise in Canada: report

Vitaly Gariev photo
Vitaly Gariev photo

The total number of insolvencies (bankruptcies and proposals) in Canada increased by 5.7% in June 2026 compared to the previous month. Bankruptcies increased by 3.0% and proposals increased by 6.6%, according to a new report by the Office of the Superintendent of Bankruptcy.

The total number of insolvencies in June 2026 was 11.5% higher than the total number of insolvencies in June 2025. Consumer insolvencies increased by 11.8%, while business insolvencies increased by 5.5%, it said, adding that for the 12‑month period ending June 30, 2026, the total number of insolvencies increased by 5.3% in comparison to the 12‑month period ending June 30, 2025.

“Consumer insolvencies for the 12‑month period ending June 30, 2026, increased by 5.9% in comparison to the 12‑month period ending June 30, 2025. Consumer bankruptcies increased by 8.4%, while consumer proposals increased by 5.2%. The proportion of proposals in consumer insolvencies decreased to 78.3% during the 12‑month period ending June 30, 2026, down from 78.8% during the 12‑month period ending June 30, 2025. For the 12‑month period ending June 30, 2026, consumer insolvency filings accounted for 96.8% of total insolvency filings,” said the report.

“Business insolvencies for the 12‑month period ending June 30, 2026, decreased by 9.7% compared with the 12‑month period ending June 30, 2025. Management of Companies and Enterprises; Accommodation and Food Services; and Mining, Quarrying, and Oil and Gas Extraction registered the largest increases in the number of insolvencies. Retail Trade; Wholesale Trade; and Health Care and Social Assistance registered the largest decreases in the number of insolvencies.”

More from Retail Insider:

Canadian Tire Corporation reports Q2 2026 results, strong SportChek performance due to World-Cup related demand

Image: Canadian Tire

 Canadian Tire Corporation, Limited announced Thursday results for its second quarter ended July 4, 2026, showing consolidated comparable sales increased 0.7% in Q2 and 6.3% on a two-year stack basis, led by strong performance at SportChek, where World Cup-related demand contributed to comparable sales growth of 8.0% and 12.4% on a two-year stack basis.

Overall retail sales grew to $5,391.6 million, up 4.5%, compared to the second quarter of 2025.

“In Q2, we demonstrated our operational agility by lowering prices for value-seeking customers, adapting to challenging weather conditions, and ultimately delivering strong financial results,” said Greg Hicks, President and CEO, Canadian Tire Corporation.

“At the same time, we continued to advance our True North strategy, increasing the use of personalized Triangle loyalty offers, growing eCommerce, and delivering strong sales in our new concept Mark’s and SportChek stores.

“The 2026 Men’s World Cup was a highlight of the quarter. Activations in store and online drove soccer fans and new customers to SportChek, and Jumpstart partnered with the Canadian government to announce a multi-year commitment to build 25 inclusive community soccer pitches across Canada by 2029, extending the World Cup legacy in communities nationwide.”

Canadian Tire Corporation, Limited is a group of companies that includes a Retail segment, a Financial Services division and CT REIT. Its retail business is led by Canadian Tire, which was founded in 1922. Party City, PartSource and Gas+ are parts of the Canadian Tire network. The Retail segment also includes Mark’s, SportChek, Sports Experts, Pro Hockey Life, Hockey Experts, and Atmosphere. The company has over 1,600 retail and gasoline outlets.

RETAIL SEGMENT OVERVIEW

  • Retail sales were $5,391.6 million, up 4.5%, compared to the second quarter of 2025. Retail sales, excluding Petroleum were up 2.5%. Consolidated Comparable sales were up 0.7%.
  • CTR Retail sales were up 1.4% and Comparable sales were down 0.8% over the same period last year.
  • SportChek Retail sales increased 7.7% over the same period last year, and Comparable sales were up 8.0%.
  • Mark’s Retail sales increased 5.1% over the same period last year, and Comparable sales were up 4.2%.
  • Retail Revenue was $3,890.1 million, an increase of $79.8 million, or 2.1%, compared to the prior year; Retail Revenue excluding Petroleum was down 1.1%.
  • Retail Gross margin dollars were $1,223.5 million, up 0.7% compared to the second quarter of the prior year, and down 0.1% excluding Petroleum; Retail Gross margin rate, excluding Petroleum, increased 33 bps to 35.1%.
CF Chinook Centre Calgary. Photo by Mario Toneguzzi

In a LinkedIn post, Hicks said: “While a slow start to summer weighed on Canadian Tire, sales at Mark’s and SportChek were strong. And, our True North strategy continued to gain steam: new format stores outperformed on all metrics; our AI platform DaiVID helped us drop more than 5,000 prices for value-focused Canadians; and personalized offers inspired Triangle members.

“We also advanced eCommerce with Q2 enhancements like Canadian Tire’s free ship-to-home for Triangle members. Plus, we introduced tabs that help customers move between our banner sites with one click, offering the full experience and assortment of Canadian Tire, Mark’s, and SportChek in a single visit.

“Working as a retail system, our banners, stores, and sites are in the midst of our first enterprise-wide, AI-informed program that sees us pivot from simply selling products to serving the occasions of our customers’ lives.

“We’re starting with Back-to-School, introducing new products, better displays, and sharper prices – with marketing and loyalty engagement that feel fit for the moment, whether you’re a kindergarten parent or headed off to a dorm.

“This program combines all our generations of customer knowledge with remarkable AI insights from our new MOSaiC platform. Next up is ‘The Holidays’ – an occasion where we’ve always been strong, but we know we can do more, as one enterprise, together.”

More from Retail Insider:

Columbia Sportswear Navigates Softer Canadian Wholesale Sales

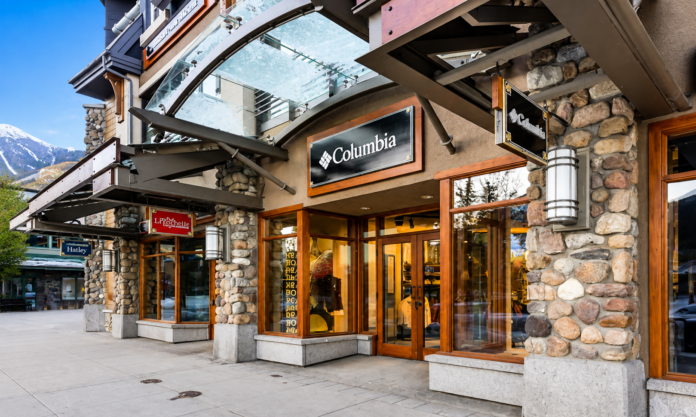
Columbia store at Cascade Plaza in Banff, AB. Photo: Cascade Shops

Columbia Sportswear reported a high-single-digit decline in Canadian sales during the second quarter of 2026 as lower wholesale orders and the timing of shipments outweighed growth in the company’s direct-to-consumer business.

The outdoor apparel and footwear company said the Canadian decline primarily reflected lower Spring 2026 wholesale orders and unfavourable shipment timing. Canadian direct-to-consumer sales increased as higher e-commerce revenue outweighed weaker brick-and-mortar performance. Management also pointed to softer store traffic and a more cautious consumer environment.

The quarterly results provide a timely look at the challenges facing an established outdoor brand with a significant Canadian presence. Columbia continues to rely heavily on wholesale distribution in Canada while investing in e-commerce, technical footwear and products intended to strengthen its appeal among younger and more active consumers.

The headline decline also deserves careful interpretation. Wholesale shipment schedules can move revenue between reporting periods, and retailer inventory decisions often influence when sales are recognized before products ultimately reach consumers.

At the same time, Columbia is several years into a broader effort to modernize its flagship brand as consumer expectations continue to evolve across the outdoor apparel and footwear market.

Canada Remains an Important Market

Columbia treats Canada as one of its four reportable geographic segments alongside the United States, Latin America and Asia Pacific, and Europe, the Middle East and Africa.

The company generated approximately US$230.2 million in Canadian sales during 2025, representing nearly seven per cent of its global revenue. Canadian wholesale sales totalled US$141.3 million, while direct-to-consumer sales reached US$88.9 million, leaving wholesale responsible for just over 61 per cent of Columbia’s Canadian business.

Columbia sells apparel, accessories and equipment under the Columbia, Mountain Hardwear and prAna brands in Canada, along with footwear from Columbia and SOREL. The company also reported nearly 400 Canadian wholesale customers and more than 15 company-operated stores at the end of 2025.

That distribution structure makes wholesale particularly important. Columbia’s own stores and digital channels allow it to control merchandising, presentation and customer relationships, but they cannot match the geographic reach provided by hundreds of retail partners across the country.

The wholesale business is also relatively concentrated. Columbia disclosed that its two largest Canadian wholesale customers represented approximately 17 per cent and 13 per cent of total Canadian sales in 2025. Together they accounted for roughly 30 per cent of the company’s Canadian business, although Columbia does not publicly identify those retailers.

That concentration means changes in ordering by one or two large accounts can materially influence quarterly Canadian results.

Shipment Timing Clouds the Picture

The Canadian sales decline should not be viewed simply as a measure of consumer demand. Columbia repeatedly cited shipment timing throughout its earnings discussion. The second quarter of 2025 benefited from earlier wholesale shipments, creating a more difficult comparison this year.

Looking ahead, management expects more than US$30 million in global shipments to shift from the third quarter into the fourth quarter, largely within North America, because of longer logistics lead times and ongoing supply chain disruption.

The company also said it has not experienced meaningful wholesale order cancellations and continues to anticipate growth in North American wholesale sales during the second half of the year, although more of that business is expected to arrive in the fourth quarter.

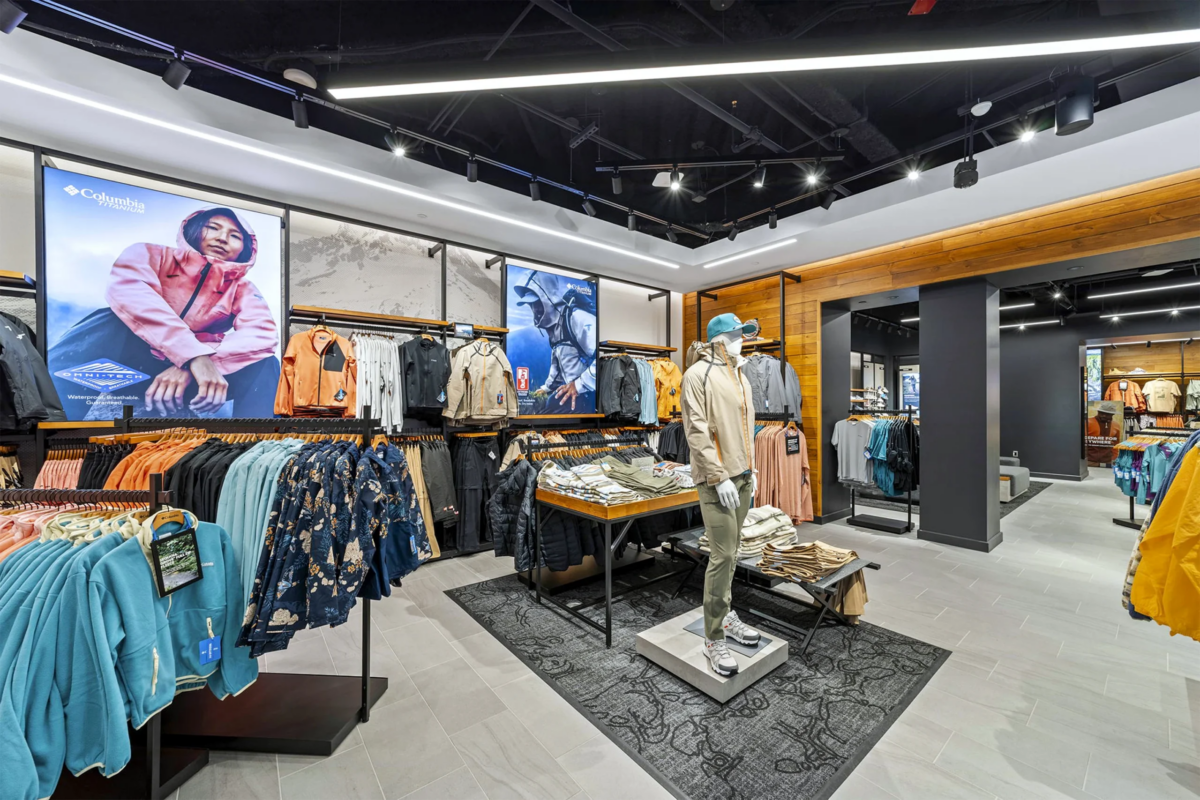
Columbia Sportswear store at Square One in Mississauga. Photo: Ken Park Architects

A Mixed Canadian Retail Environment

Broader Canadian retail data presents a more nuanced picture than Columbia’s quarterly results alone.

Statistics Canada reported that sales among sporting-goods, hobby, musical-instrument, book and miscellaneous retailers increased 1.8 per cent in May, marking the first monthly gain in three months. Overall retail sales also increased, although volume growth remained modest, reflecting continued pressure from inflation.

SportChek, meanwhile, continued to post positive comparable-store sales earlier in 2026. Parent company Canadian Tire said the chain benefited from strength in athletic footwear, fanwear and hard goods while describing Canadian consumers as resilient but increasingly selective in their spending.

Taken together, the evidence suggests Columbia’s Canadian weakness reflects a combination of shipment timing, wholesale ordering patterns and brand-specific factors rather than a broad contraction in Canada’s sporting-goods sector.

Repositioning a Familiar Outdoor Brand

The quarterly results also arrive as Columbia continues a multi-year effort to modernize its flagship brand. Announced in October 2024, the company’s ACCELERATE strategy is intended to strengthen Columbia’s appeal among younger and more active consumers while preserving the qualities that have made the brand successful for decades.

Management has organized the strategy around five priorities: hiking and trail running, mountain performance, Performance Fishing Gear, outdoor-lifestyle apparel with stronger styling and footwear.

The goal is not to abandon Columbia’s heritage. Instead, the company is working to build greater relevance in a market where consumers increasingly expect outdoor products to combine technical performance with contemporary design and everyday versatility.

Photo: Columbia Sportswear

Footwear Takes Centre Stage

Footwear has become one of Columbia’s most important growth opportunities. The company reported high-single-digit global footwear growth during the quarter, highlighting the Tellurix and Peak Freak hiking franchises, the Konos trail-running line and the Dry Tortuga fishing footwear collection.

Management also said footwear is growing faster than apparel within Columbia’s Spring 2027 wholesale order book and that younger customers have shown encouraging interest in newer and higher-priced products, particularly footwear.

Footwear gives Columbia an opportunity to participate more fully in hiking and trail-running categories while reducing some of its dependence on seasonal outerwear.

The company has not disclosed Canadian footwear performance for the quarter, although footwear generated approximately US$60.5 million in Canadian sales during 2025.

Building on Heritage While Looking Forward

Columbia’s repositioning extends beyond new product launches. Management discussed renewed interest in long-standing products such as the Bahama shirt after investing in stronger storytelling around the collection’s heritage. The company also highlighted continued momentum for its Amaze Puff outerwear line.

Marketing has become an important part of that effort. Columbia pointed to its Expedition Impossible campaign, partnerships with Robert Irwin and expanded outdoor-community events as examples of how it is engaging new audiences while reinforcing the brand’s outdoor credibility.

Although Columbia’s Canadian e-commerce business grew during the quarter, wholesale remains the foundation of its Canadian operations.

The company wants its digital channels to present a stronger expression of the brand while continuing to rely on wholesale partners that provide national reach.

That balance is becoming increasingly important as Columbia introduces more premium products while managing promotional activity, particularly within outlet and brick-and-mortar channels. Management acknowledged that softer traffic contributed to increased discounting during the quarter even as the company works to strengthen its full-price positioning.

Looking Ahead

Columbia’s Spring 2027 wholesale order book provides cautious optimism. Management said approximately 90 per cent of the order book had been completed and was tracking toward low- to mid-single-digit growth, with footwear leading apparel and newer products gaining traction among retail partners. North America is participating in that growth, although Columbia did not provide a separate outlook for Canada.

The company’s Canadian results ultimately illustrate several forces shaping today’s outdoor retail market. Wholesale ordering patterns remain critical, shipment timing continues to influence quarterly comparisons, consumers are spending carefully and established brands are investing heavily to remain relevant in a more competitive landscape.

For Columbia, the next phase will depend on whether technical footwear, updated styling and more focused brand positioning can translate into sustained consumer demand and stronger support from the wholesale partners that continue to anchor its Canadian business.

More from Retail Insider: