Home Blog Page 173

How Small Retail Businesses Are Finding New Grants & Funds

Running your retail business comes with multiple things to think about every day so that it can operate smoothly. As most aspects of planning, growing your company, and making improvements require financing, money remains one of the key components that entrepreneurs often worry about. Below, we provide options for small business grants that can support their owners.

General Small Business Grants

These grants offer non-repayable financing for startups and existing businesses in specific industries and demographics. You can get them through Small Business Administration (SBA) local development centers, state agencies, and the Grants.gov website. The most common options include:

  • National Association for Self-Employment (NASE) Growth Grants. NASE grants are awarded quarterly for four winners, allowing them to get up to $4,000 to grow their businesses.
  • U.S. Department of Commerce Minority Business Development Agency (MBDA). This network of programs targets minority-owned businesses and supports their growth. Each program targets a specific minority category, for example, American Indians, Alaska Natives, Native Hawaiians, or women of color. 
  • Awesome Foundation Grants. Awesome Foundation is a global community that issues micro-grants of up to $1,000 each month to bring brilliant and crazy business ideas to life. The foundation also supports novel or experimental businesses.
  • The Freed Fellowship Grant. Through this grant, a chosen Freed Fellow business owner will receive $500 to invest in their company growth and can become eligible for a $2,500 year-end grant. Every submission gets feedback with recommendations on growing your business.
  • Storefront Opportunity Grant. This option provides funding from $25,000 to $100,000 to help small businesses that open brick-and-mortar locations offset frost-year operating costs. To qualify, you need to have a revenue-generating business for at least 3 years, 100 or fewer employees, and $5 million or less in annual revenue. Eligibility may vary by location.
  • U.S. Economic Development Administration (EDA). As a part of the U.S. Department of Commerce, EDA provides financial support to businesses that boost regional and national economic development.

Smart Loan Options from Digital Lenders

Financial strains often hit small businesses the hardest. When you’re just getting a retail business off the ground, scrambling to cover the cost of a damaged roof or flood repairs can be overwhelming. In such a situation, small loan lenders in the USA can provide much-needed support without the need for expensive paperwork associated with taking out a loan from lenders certified by CDFI. Most of these companies have installment loan assistance for entrepreneurs who want to grow their respective retail companies. This type of loan helps businesses build solid disaster preparedness plans ahead of time and offer emergency funding when the unexpected strikes.

To qualify for funding, businesses simply need to complete a straightforward application process. It typically involves filling out an online loan request form and attaching copies of your basic documents, such as your ID, proof of address, and income confirmation. Funding typically takes 1 business day. Just note that interest rates may be higher compared to CDFI or traditional financing options.

Government Contract Assistance

The government reserves at least 23% of contracting dollars for small businesses seeking to secure government contracts. Such assistance is primarily available through the SBA and the Department of Defense. Here are the four options available:

  • Women-Owned Small Business Federal Contracting Program. The federal government awards at least 5% of contract dollars to small businesses owned by women.
  • Service-Disabled Veteran-Owned Small Business Program. Minimum 3% of contracts must be secured by veterans or service-disabled veterans running small businesses. 
  • HUBZone Program. Under this program, businesses located in historically underutilized business zones get preferential consideration.
  • 8(a) Business Development Program. The program targets socially or economically disadvantaged business owners.

Natural Resource Sales Assistance Program

The Natural Resource Sales Assistance Program, created by the SBA, channels a certain percentage of the natural resources and surplus property sold by the federal government to small businesses through bidding. Sales occur in five resource categories: “timber and related forest products,” “strategic materials,” “royalty oil,” “leases involving rights to minerals, coal, oil, and gas,” and “surplus real and personal property.”

Federal agencies may also divide surplus materials into smaller lots that are much easier to purchase for startups and small companies. On top of that, the program allows small businesses to participate in training on government sales and leasing.

Final Thoughts

For many small retail businesses, grants can be a great source of financial support. Entrepreneurs can use the funds to cover operating costs, grow sales, and improve processes or their company’s presence. Just note that getting free money from the government or community services often comes with extensive paperwork. Before applying, check eligibility criteria, application requirements, and deadline.

FAQ

What is the most important funding source for small businesses?

Personal savings and retained business revenue (bootstrapping) are the most common and important funding sources for small businesses. Other options could be: grants, cash advances via online app, and government contact assistance. Those could be used at certain stages to support growth or make it easier to maintain stability during tough times.

How to obtain a grant for a small business?

Grants are awarded based on your preliminary application. The application process and deadlines may vary by program, so check out the website of an agency or company awarding  this particular grant. In most cases, you will be asked to provide a set of documents, including tax returns, a business plan, and bank statements. Specific eligibility requirements associated with legal registration, operational history, and financial limits may apply.

How to get funding for a retail business?

If you search for non-repayable options, consider grants based on the amount you need, the goal, and your company’s specifics. Alternatively, you can turn to loans from online loan companies or SBA- and CDFI-certified lenders. If your retail business is designed to support communities, you can also launch a fundraising program.
Q1 2026 Home Furnishings Report: Navigating Channel Shifts, Consolidation, and Consumer-Centric Innovation


As part of Retail Insider Reports, this Q1 2026 Home Furnishings Retail Report provides structured analysis of the Canadian home furnishing sector, drawing on Retail Insider’s ongoing coverage to identify key market dynamics, emerging trends, and strategic shifts. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

****

The Canadian home furnishings sector entered 2026 at a crossroads, balancing expansion ambitions with shifting consumer behaviour and operational realities. While some retailers are investing in physical retail and experiential formats, others are pulling back from costly store networks in favour of wholesale and omnichannel strategies.

Underlying these decisions is a more cautious consumer environment. Housing activity, a key driver of furniture demand, remains uneven. National home sales were down 2.3% year-over-year as of March 2026, reflecting a slower start to the year, even as forecasts point to a potential rebound later in 2026 driven by pent-up demand.

This dynamic is creating a landscape where growth remains possible, but increasingly selective. Leading players are adapting through channel diversification, strategic investment, and operational discipline, while others face mounting pressure.

Casavogue’s targeted promotions and focus on Canadian craftsmanship, Richelieu Hardware’s acquisition-driven expansion, and Article’s evolution from digital-first to omnichannel retail illustrate how leading companies are repositioning. Meanwhile, Yankee Candle’s exit from Canadian stores underscores the challenges facing specialty retailers tied to traditional mall-based formats.

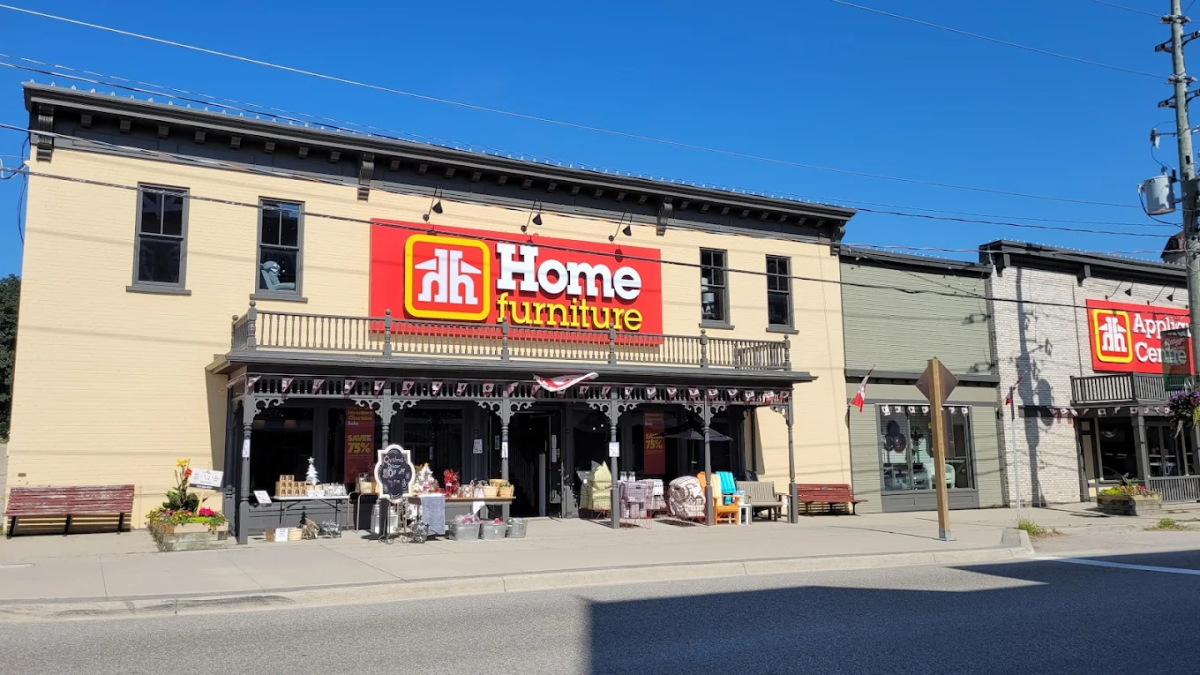
Home Furniture store in St. Jacobs, Ontario. Photo: Simon Zhang via Google Maps/Images

Retail Insider Coverage Reflects Sector in Transition

Retail Insider tracked 35 home furnishings-related articles in Q1 2026, reflecting continued activity across the sector. Expansion and store openings led coverage, followed by product launches, partnerships, and financial reporting.

This activity translates into tangible market movement. Article’s 9,600-square-foot Toronto showroom signals a major investment in physical retail, while regional expansions such as Atlantic Gift + Home Market highlight localized growth. At the same time, Richelieu Hardware’s completion of 10 acquisitions across North America points to ongoing consolidation shaping supply chains and retail assortments.

Despite these developments, contraction remains part of the story. Yankee Candle’s closure of its final Canadian store highlights the challenges facing certain specialty formats, reinforcing the uneven nature of growth across the sector.

Channel Evolution Defines Competitive Positioning

The home furnishings sector is increasingly defined by how effectively retailers integrate physical and digital channels.

Yankee Candle’s exit from Canadian brick-and-mortar retail after 14 years reflects a broader pivot toward wholesale and omnichannel distribution. By shifting to major partners such as Canadian Tire and Walmart, alongside e-commerce platforms, the brand reduces fixed costs while maintaining market presence.

In contrast, Article’s expansion into physical retail represents a strategic investment in omnichannel engagement. Its new Toronto showroom complements its digital platform by offering tactile product experiences and design services, addressing a key limitation of online-only furniture retail.

Cozey’s continued expansion into physical retail further reinforces the role of showrooms in building consumer confidence. Despite its digital origins, the company recognizes that customers still value in-person interaction for higher-ticket purchases.

Together, these strategies illustrate a clear pattern. Physical retail is not disappearing, but it is evolving into a more targeted, experience-driven component of broader omnichannel strategies.

Market Consolidation and Supplier Influence Expand

Richelieu Hardware’s 7.2% sales growth in 2025, supported by 10 acquisitions, highlights the growing role of consolidation in shaping the home furnishings ecosystem. The company’s expansion of private-label brands and product categories strengthens its position as a key supplier to retailers and renovation markets.

This trend has broader implications. While retailers benefit from streamlined sourcing and expanded assortments, increased supplier concentration can shift bargaining power and influence product availability.

Over time, this may reshape assortment strategies, requiring retailers to balance efficiency with differentiation in order to maintain competitive positioning.

Consumer Financing and Incentives Support Demand

In a more cautious spending environment, retailers are increasingly turning to financing and targeted promotions to drive demand.

The Canadian furniture market is projected to reach approximately $20.2 billion in 2026, supported in part by stable demand in segments such as home office furnishings, which continue to benefit from hybrid work trends. However, this growth is occurring alongside increased price sensitivity.

Financing solutions are playing a growing role. The Canadian buy now, pay later market is expected to reach approximately $13 billion in 2026, with furniture and home furnishings among the leading categories for adoption. These tools allow consumers to manage higher-ticket purchases through instalment payments, helping to sustain demand despite broader affordability pressures.

Australian furniture retailer King Living

Operational Pressures and External Disruptions Persist

Operational challenges continue to shape performance across the sector. Leon’s Furniture’s recent results highlight the impact of external disruptions, including logistics challenges and weather-related factors, on sales and promotional timing.

Despite these pressures, larger operators with established omnichannel platforms and strong balance sheets have demonstrated resilience. Their ability to manage inventory, control costs, and adapt promotional strategies remains a key differentiator.

For smaller or less diversified players, these challenges can have a more pronounced impact, particularly in a market where demand is increasingly selective.

Demographics and Local Demand Drive Opportunity

Consumer demand in home furnishings is becoming more concentrated among specific demographic segments, including higher-income households and homeowners engaged in renovation or long-term housing investment.

This shift reinforces the importance of targeted retail strategies. Retailers that align product assortments, store locations, and marketing efforts with these high-value segments are better positioned to capture demand.

At the same time, growing interest in Canadian-made products is influencing purchasing decisions, supporting retailers that emphasize local sourcing and craftsmanship.

Sector Outlook: Selective Growth in a More Disciplined Market

The Canadian home furnishings sector is not contracting uniformly, but rather evolving toward a more disciplined and targeted growth model.

While overall market value continues to expand modestly, performance is increasingly tied to execution. Retailers that combine omnichannel capability, operational efficiency, and customer-focused strategies are better positioned to succeed.

At the same time, rising costs and cautious consumer behaviour will continue to challenge less adaptable formats, reinforcing the importance of strategic clarity.

Editor’s Take

The most important development in Q1 2026 is the sector’s transition toward integrated omnichannel models supported by more disciplined operations and evolving consumer financing strategies.

Richelieu Hardware stands out for its acquisition-driven growth and expanding influence across the supply chain. Article’s continued investment in physical retail reflects a thoughtful approach to omnichannel development, while Casavogue’s targeted promotions demonstrate how retailers can stimulate demand in a price-sensitive environment.

At the same time, Yankee Candle’s exit from Canadian stores highlights the risks associated with legacy retail formats that lack flexibility. Retailers that fail to adapt to changing channel dynamics or consumer expectations may continue to lose relevance.

Looking ahead, the trajectory of housing activity will remain a critical factor influencing demand. The continued growth of financing solutions such as buy now, pay later will also shape purchasing behaviour, particularly for higher-ticket categories.

Together, these trends point to a sector that remains viable, but increasingly selective, where success depends on alignment with both consumer expectations and economic realities.

Selected Coverage

EQB secures final approval for PC Financial acquisition

Loblaws at Humbertown Plaza in Toronto. Photo: Loblaw Companies

EQB Inc. and Loblaw Companies Limited announced Tuesday that final approval has been received from the Federal Minister of Finance and National Revenue for EQB’s previously announced acquisition of PC Financial from Loblaw.

The completion of the acquisition will cement EQ Bank’s position as Canada’s Challenger Bank and its unique ability to strengthen competition and drive innovation, while making a meaningful difference for millions of Canadians at a time when it matters most, said the company in a news release.

The Minister’s approval represents the successful conclusion of a comprehensive regulatory review, following a recommendation from the Office of the Superintendent of Financial Institutions (OSFI) and clearance from the Competition Bureau in March 2026, it said.

Chadwick Westlake
Chadwick Westlake

“We applaud the swift actions of the Federal government to enable us to move with pace to drive improvement in banking competition, affordability and innovation for Canadians,” said Chadwick Westlake, President and CEO, EQB. “This approval signals the government’s clear commitment to strengthening Canada’s economy and fostering competition and innovation here at home. It is an important step towards closing the acquisition of PC Financial and to building a more dynamic banking system. We are focused on scaling a Challenger‑led, loyalty‑linked banking ecosystem that puts more choice, value and financial momentum in the hands of everyday Canadians.”

Completion of the Acquisition will mark a step‑change for EQ Bank and for Canadian banking, unlocking the opportunity for EQB to offer Canadians rewarding and unique ways to save, spend, and earn at scale in communities from coast to coast. Through the Acquisition, EQB expects to expand its total customer base to 3.3 million Canadians and add approximately $5.8 billion in assets and $800 million in direct retail deposits. As the exclusive financial services partner of PC Optimum™, one of Canada’s most recognized and widely used loyalty platforms, EQB will be able to offer everyday banking, lending, payments, and rewards through a single integrated ecosystem to the more than 18 million active PC Optimum™ loyalty members.

“This acquisition unlocks significant benefits for millions of PC Financial customers and PC Optimum™ members, including a wider variety of products, services, and even more ways to earn rewards, while gaining access to EQ Bank’s leading digital platform for everyday banking,” said Richard Dufresne, Chief Financial Officer, Loblaw.

Richard Dufresne
Richard Dufresne

With the final regulatory approval obtained, EQB and Loblaw are preparing for the closing of the Acquisition, which will combine PC Financial, including the PC Mastercard suite of products, with the award-winning EQ Bank banking platform. Building on existing everyday banking, residential lending and reverse mortgage offerings, this will shape a complete, integrated Personal Banking business that raises the bar for what Canadians can expect from their bank, said the news release.

“EQB will enter into a long-term strategic commercial arrangement with Loblaw, becoming the exclusive financial partner of the PC Optimum loyalty program with access to Loblaw’s national retail and digital channels to market financial services products,” it said.

EQB expects the acquisition to close in the summer of 2026, subject to customary closing conditions.

More from Retail Insider:

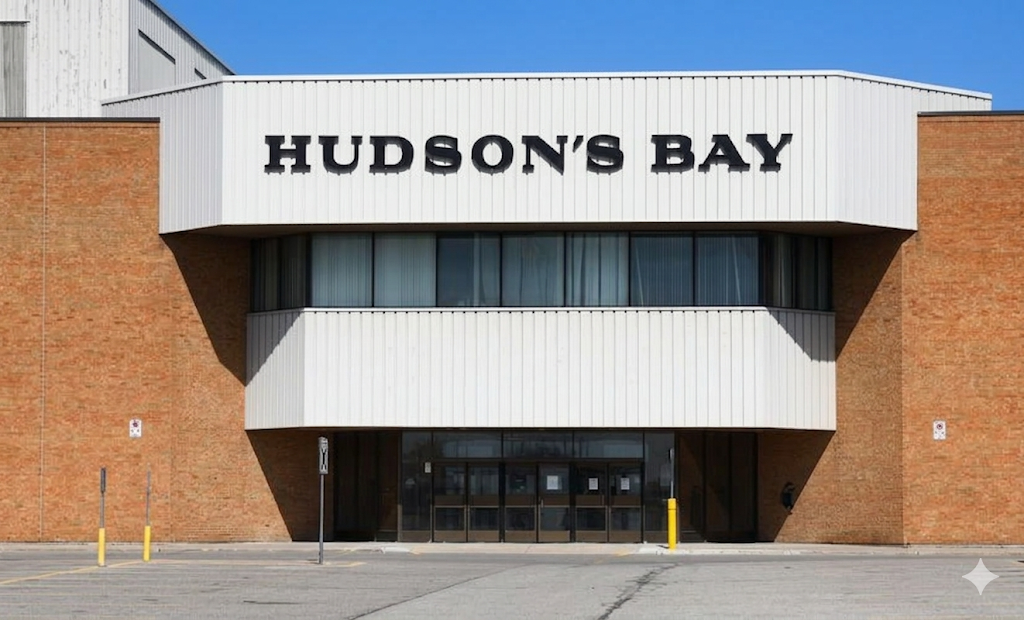
Primaris REIT Repurposing Malls After Hudson’s Bay Closures

Former Hudson's Bay store at Devonshire Mall in Windsor, ON. Photo: TripAdvisor

Primaris REIT is advancing a significant strategy to repurpose large-format retail space across its portfolio, positioning former department store locations as a key driver of future growth. Insights shared during the company’s recent annual meeting and analyst call reveal how the landlord is actively redeploying space vacated by legacy anchors into higher-performing uses, reflecting a broader structural shift in Canadian retail real estate.


Executives speaking on the call framed the transition in stark terms. “The departure of Hudson’s Bay is the best thing that has happened to Primaris in many, many years,” said Primaris CEO Alexander Avery, pointing to the removal of long-standing lease restrictions and the ability to fully reposition large-format space. The comments were made during the REIT’s annual meeting and analyst call, underscoring how dramatically sentiment has shifted around the role of traditional department store anchors from years past.

Primaris CEO Alexander Avery

Anchor Closures Unlock Flexibility Across the Portfolio

The exit of Hudson’s Bay Company in 2025 marked a turning point for landlords across Canada, many of whom had already been contending with years of anchor erosion following the collapse of Sears Canada and earlier disruptions tied to Target’s failed expansion into the country.

For Primaris, the departure of Hudson’s Bay has removed restrictions embedded in legacy leases, including limitations on redevelopment and site configuration. As a result, the REIT now has significantly greater flexibility to reconfigure space in ways that better align with modern retail demand.

Rather than attempting to replace department stores with similar formats, Primaris is pursuing a more diversified tenant mix, reflecting the growing importance of mid-sized retailers, service-oriented uses, and more flexible store formats within enclosed shopping centres.

$175 Million to $225 Million Redevelopment Program Targets Former Bay Stores

Primaris is now deploying between $175 million and $225 million to reposition 11 former Hudson’s Bay locations across its portfolio, with targeted returns of 8 percent to 10 percent. The scale of the investment highlights how landlords are increasingly taking an active role in reshaping their properties rather than waiting for traditional anchors to return.

The REIT’s approach reflects a structured response to a challenge that has emerged across the country. Across its portfolio, Primaris is actively repositioning former department store space, with redevelopment activity already underway in select locations as large-format retail is reconfigured for new uses.

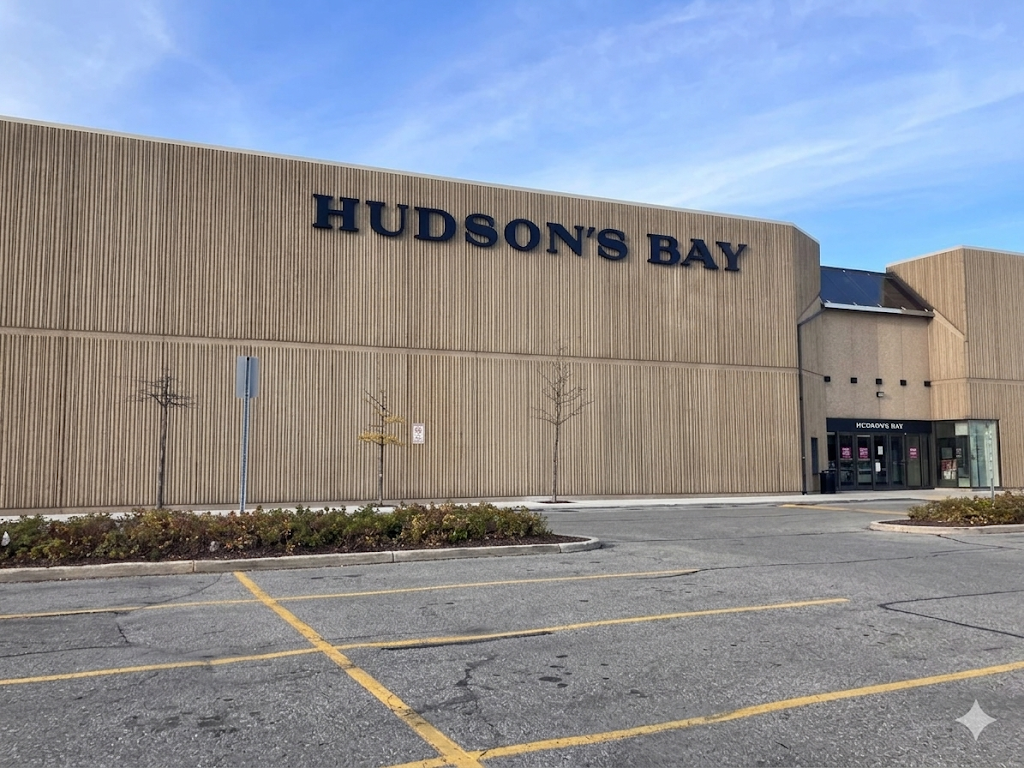
Former Hudson’s Bay at Lime Ridge Mall in Hamilton. Photo: RI/Google
 

A New Playbook for Repurposing Large-Format Retail Space

During the call, Avery outlined a flexible, market-driven approach to repurposing former anchor boxes, emphasizing that each asset is being evaluated individually to “maximize the value and appeal of the shopping centre.”

In some cases, Primaris is backfilling space with a single large-format tenant, including retailers such as Canadian Tire, Walmart, or Loblaw. In others, the REIT is subdividing space to accommodate multiple mid-sized tenants, with examples including Mark’s, Sport Chek, and Winners/Marshalls.

In select high-demand locations, the strategy extends further, with full reconfiguration of the space into smaller-format stores through the extension of internal mall corridors. This approach allows for a more granular merchandising mix and aligns with retailer demand for smaller footprints in dominant centres.

The shift reflects a broader move across the industry toward maximizing productivity per square foot while reducing reliance on single-anchor tenants.

Former Hudson’s Bay at Oshawa Centre. Photo: RI/Google

Rising Productivity and Leasing Demand Support Strategy

Primaris pointed to significant improvements in tenant performance across its portfolio as evidence that the repositioning strategy is already delivering results. Aggregate tenant sales have grown from approximately $1.7 billion in 2022 to $3.6 billion today, while average sales per square foot have increased from the low $500 range to more than $800.

At the same time, leasing activity has accelerated, with the REIT noting that its teams are operating at elevated levels to keep pace with demand. “Our leasing team has been operating at about 150 percent capacity,” Avery said, highlighting the intensity of activity across the portfolio.

The performance aligns with Primaris’ broader acquisition strategy, which has focused on dominant regional shopping centres. At Lime Ridge Mall in Hamilton, for example, tenant sales productivity was already exceeding $800 per square foot prior to its acquisition, reinforcing the REIT’s focus on high-performing assets.

Beyond Retail: Unlocking Value From Excess Land

In addition to repositioning existing retail space, Primaris is also advancing a longer-term strategy to unlock value from its underlying land holdings. The REIT controls approximately 1,400 acres of land across Canada, with an estimated 400 acres identified as excess to core mall operations.

These lands present opportunities for intensification, including the potential for additional retail, residential, or mixed-use development over time. While such projects are expected to unfold over a longer horizon, they represent a significant embedded value component within the portfolio.

Avery emphasized the strategic importance of these assets, noting that malls occupy large, centrally located parcels that are increasingly difficult to replicate. “Malls are fabulous real estate… nearly impossible to develop in built-up urban locations,” he said, pointing to the long-term scarcity value of these sites.

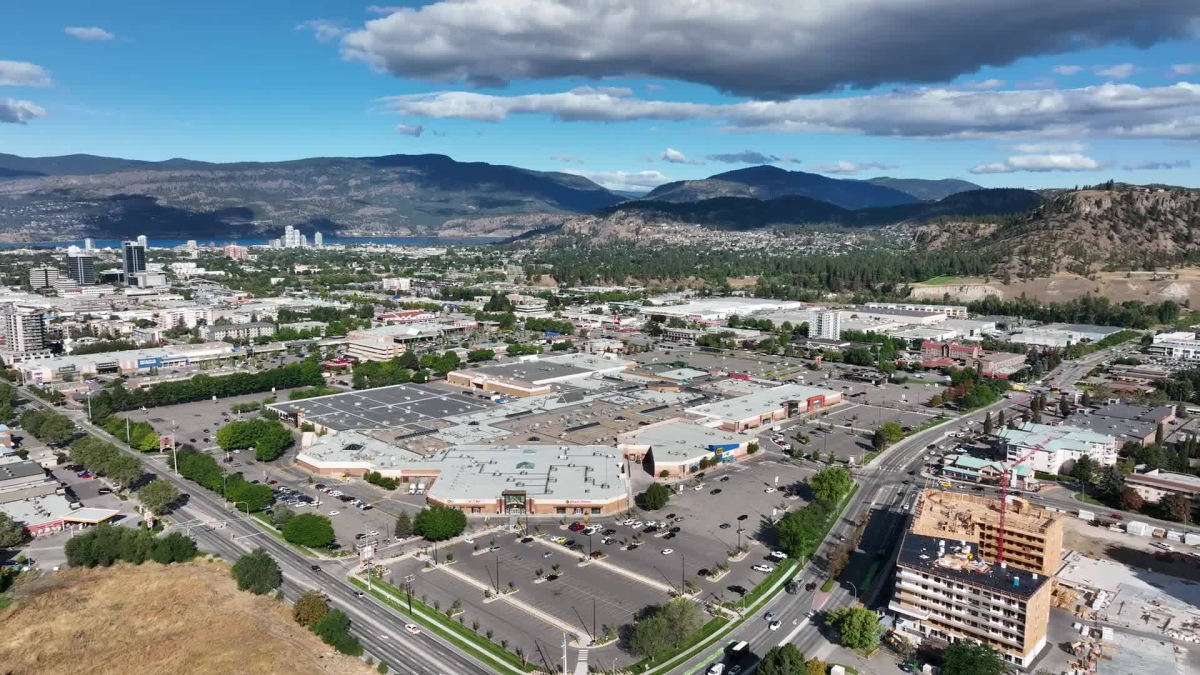
Orchard Park Centre in Kelowna BC. Photo: Primaris

A Structural Shift in Canadian Mall Strategy

Primaris’ repositioning strategy reflects a broader evolution in how shopping centre owners are managing their assets in a post-department store environment. Rather than viewing anchor closures as a loss, landlords are increasingly treating them as an opportunity to modernize their properties and improve overall performance.

While other major landlords, including Cadillac Fairview and Oxford Properties Group, have also advanced redevelopment and intensification strategies, Primaris’ current program highlights the extent to which the industry has shifted from reactive to proactive asset repositioning.

As outlined in the company’s annual meeting and analyst call, the transformation of large-format retail space is now central to the future of enclosed shopping centres in Canada. Former department store locations, once seen as essential anchors, are increasingly being reimagined as flexible, high-value components of a more diversified retail ecosystem.

More from Retail Insider:

Happy Belly Food Group acquiring 50% of Ghost Taco

Happy Belly Food Group photo

Happy Belly Food Group Inc., a leader in acquiring and scaling emerging food brands across Canada, announced Tuesday it has signed as of May 4, a binding Letter of Intent agreement that will see a 50% acquisition of the Ghost Taco fast casual restaurant chain through the formation of a joint venture with optionality to acquire the remaining 50%.

“Ghost Taco is a fast-growing Ontario-based fast-casual restaurant brand specializing in bold, Mexican-inspired tacos, bowls, sides and desserts. Founded by Samantha and Grant Buckley as a pop-up, Ghost Taco has grown into a multi-location concept with a playful “unauthentic Mexican” positioning. The brand has built a loyal customer following through its distinctive flavors, strong local appeal and memorable brand identity, supported by a scalable franchise model and an expanding footprint across Ontario, including Newmarket, Toronto, Kingston, Whitby, Barrie, Peterborough and other markets. The acquisition supports our continued investment in differentiated, founder-led foodservice brands with strong unit economics and meaningful growth potential,” said Happy Belly in a news release.

The company said theacquisition represents the incorporation of Happy Belly’s 11th restaurant brand, 12th overall, and the first acquisition of 2026. Ghost Taco, an asset light franchised system, has six established real estate locations in Ontario.

Sean Black
Sean Black

“When looking for an acquisition we look for the 3 P’s: People, Product and Process. With co-founders Samantha and Grant Buckley of Ghost Taco, we found exactly that,” said Sean Black, Chief Executive Officer of Happy Belly.

“I have been looking for the right brand to get back into the Mexican-inspired category where I had previous success founding and growing Mucho Burrito to be the market leader in Canada for fast casual Mexican. It is going to be a lot of fun growing Ghost Taco into what we believe can be the next leader in fast casual Mexican in North America. I love working with founders and trying to help their emerging brands reach their full potential. Sam, Grant & Steve welcome to the Happy Belly family… I can’t wait to get started growing the business together.”

“In addition to meeting our criteria for people, product, and process, this acquisition aligns perfectly with the financial metrics and belly check criteria Happy Belly looks for in an acquisition, being debt free and cashflow positive. Once closed, this transaction will integrate into our accelerated M&A program, which includes 681 contractually committed locations across multiple emerging brands at various stages of development, construction, and operation. Our dual expansion strategy, combining franchised growth with targeted corporate store openings highlights our focus on disciplined, predictable growth as we advance toward becoming Canada’s leading restaurant consolidator.”

Happy Belly and Ghost Taco have signed a binding LOI agreement for the formation of a joint venture for the purposes of franchise expansion and growth of the Ghost Taco.

Happy Belly Food Group photo

“Our approach has always been to focus on the development and growth of emerging brands in the food sector. Ghost Taco will be an accretive acquisition by Happy Belly Food Group, and it is anticipated that our franchising program will deliver new franchised locations that will continue to drive both the top line and bottom line of the company,” added Black.

The company’s portfolio includes Heal Wellness, Rosie’s Burgers, Yolks Breakfast, Via Cibo Italian Street Food, iQ Food Co., and others.

More from Retail Insider:

Shopify delivers again as merchants clear $100 billion in Q1 GMV

Photo: Shopify
Photo: Shopify

Shopify announced Tuesday financial results for the quarter ended March 31, 2026. Shopify achieved 34% revenue growth and 15% free cash flow margins and more than $100 billion in Gross Merchandise Value.

Harley  Finkelstein
Harley  Finkelstein

“Shopify has entered the AI era with a clear edge: strong, durable growth and two decades of commerce intelligence. That puts us in a category of one, and we’re about to see that advantage compound throughout 2026,” said Harley Finkelstein, President of Shopify. 

Jeff Hoffmeister
Jeff Hoffmeister

Jeff Hoffmeister, Chief Financial Officer, said: “Q1 delivered broad-based growth across geographies, merchant sizes, and channels, with over $100 billion of GMV in the first quarter alone. That is the platform compounding. The durability of this model allows us to invest strategically in growth, both in the merchant-facing tools that drive commerce innovation and in the internal capabilities that let us build and ship faster.”

For the second quarter of 2026, Shopify said it expects: 

  • Revenue to grow at a high-twenties percentage rate on a year-over-year basis; 
  • Gross profit dollars to grow at a mid-twenties percentage rate on a year-over-year basis;
  • Operating expenses as a percentage of revenue to be 35% to 36%;
  • Stock-based compensation to be $145 million; and
  • Free cash flow margin to be in the mid-teens. 

Shopify provides essential internet infrastructure for commerce. Shopify’s all-in-one platform makes it easier to start, run, and grow a business, powering sales online, in-store, and everywhere in between, it says. Millions of businesses in 175+ countries use Shopify—from entrepreneurs to brands like Aldo, BarkBox, Carrier, Meta, Vuori, SKIMS, and Supreme. 

More from Retail Insider:

Kantar: Brands Risk Missing Canada’s High-Value Seniors

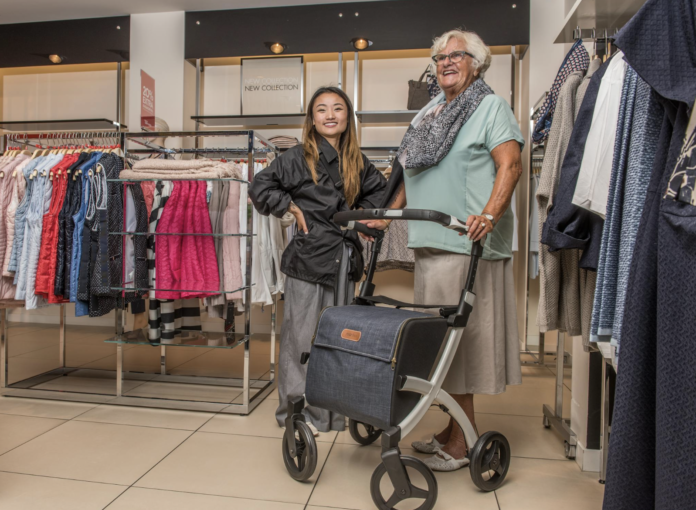
Rollz International photo

Many marketers chase Gen Z for cultural relevance, but here’s the reality: nearly one in five Canadians is now 65-plus, fertility is at an all-time low (1.25 children per woman), and seniors wield significant disposable income.

Kantar’s 2026 Canada MONITOR shows that Canadians in their “third age” (60–80) aren’t retreating from life, they’re travelling, dining out, adopting new tech, and spending. Brands that dismiss them risk alienating their most reliable revenue base.

Scott Megginson, President of Kantar Canada, discusses the trend.

Question: What are the biggest misconceptions marketers have about Canadians aged 60–80, and how are those assumptions impacting strategy?

Answer: The most damaging misconception is that Canadians aged 60–80 are risk‑averse, price‑obsessed, and in decline, when in reality they are confident, values‑led consumers who prioritize trust, quality, and relevance over novelty or discounting. Data from our ShopperScape practice shows older Canadians buy private label primarily because they trust the retailer and believe in the quality, not because they are trading down, yet many brands still over‑index on price cues and under‑invest in credibility, provenance, and storytelling.

Scott Megginson
Scott Megginson

Our Canada Monitor data show they are also wrongly treated as needing simplified or age‑coded messaging, despite evidence that they respond better to clear narratives delivered in trusted environments, not “senior” signals that dilute effectiveness. Similarly, home is often misread as a constraint rather than a source of identity and opportunity, even though this cohort over‑indexes in at‑home categories and sees the home as central to comfort and pride. Finally, brands often under‑leverage Canadian provenance, despite Boomers showing much stronger Buy Canadian sentiment than younger cohorts. Collectively, these misconceptions result in systemic underinvestment in one of Canada’s most loyal, stable, and economically powerful consumer groups.

Q: How should brands rethink customer experience design to better serve older consumers without appearing patronizing or out of touch?

A: Analysis of Kantar’s Canada Monitor data would suggest that brands should design customer experiences around reassurance, clarity, and confidence rather than instruction or education, recognizing that Canadians aged 60–80 feel less life pressure and are comfortable with who they are. Overly coached, explanatory, or age‑signalled experiences often feel patronizing, whereas intuitive design, transparent information, and friction‑free decision‑making signal respect and autonomy. Consistency matters more than novelty for this group: stable navigation, predictable service standards, and continuity across touch points build confidence far more effectively than constant reinvention. Older consumers also engage more deeply in trusted, credible environments such as premium video, news, and high‑quality digital yet experience design often prioritizes experimental or youth‑centric platforms that erode engagement. The biggest mistake is segmenting CX by age rather than values; inclusive design that works well for older Canadians typically improves usability and effectiveness for all customers.

Q: What does the data show about spending habits and brand loyalty among seniors compared to younger demographics?

A: Our ShopperScape practice data shows that older Canadians are more selective, not more price‑tolerant, and are actually less willing than younger shoppers to accept lower quality in exchange for savings, reinforcing that their spending is governed by standards rather than sacrifice. Loyalty among seniors expresses itself through repeat behaviour and consistency, not experimentation: they under‑index on innovation‑seeking but over‑index on repeat purchasing in core categories like dry grocery, frozen foods, and household essentials. While younger consumers chase variety, formats, and novelty, older Canadians reward brands and retailers that reliably deliver on the basics, reinforcing predictable revenue and long‑term relationships. Crucially, seniors tend to outperform younger cohorts on retention, trust, and lifetime value rather than basket expansion or trial velocity, making them disproportionately important from a profitability and stability perspective even if their behaviour appears quieter or less visible in short‑term metrics.

Q: In what ways are ageist biases influencing media allocation and product development decisions within organizations?

A: Our Media team has observed that ageist bias most often shows up quietly in planning defaults rather than overt exclusion, with media investment still heavily skewed toward younger audiences despite consistent evidence that older consumers deliver strong brand lift, loyalty, and long‑term value. Arbitrary age caps and assumptions about diminishing relevance cut off reach and frequency just as audiences cross artificial thresholds, treating older consumers as “maintenance” rather than growth.

On the product side, innovation is frequently defined as novelty, new formats, features, or flavours, while improvements that enhance durability, reliability, and ease of use are undervalued, even though older consumers disproportionately reward them. Design teams often mistake inclusion for late‑stage segmentation, creating visibly “older” versions instead of building universally usable experiences from the start. These biases are reinforced by short‑term metrics like clicks and early trial, which structurally favour younger cohorts and obscure the longer‑horizon outcomes, retention, repeat behaviour, consistency, where older consumers excel.  There are some functional considerations for ageing consumers though, like visual clarity on shelf and ease of opening products.

Kampus Production photo

Q: What practical steps can retailers and brands take right now to better engage and retain this growing, high‑value demographic?

A: The fastest and most impactful step is to rebalance media plans based on observed performance rather than age cutoffs, removing arbitrary caps and reallocating spend toward audiences that demonstrate sustained brand outcomes. Brands should also embed “quiet excellence” into products and experiences, design choices that make things intuitive, durable, and dependable, without labeling them as age‑specific, as older consumers notice when things simply work.  At the retailer level, loyalty should be anchored in consistency: stable assortments, recognizable private‑label architectures, and predictable promotions matter far more to this cohort than constant rotation or novelty. More broadly, engaging older Canadians does not require new “senior strategies,” but rather undoing age‑biased defaults in planning, design, and measurement. Brands that act now will not only retain seniors, but also build more resilient, trust‑based growth across their entire customer base.  As Canada is in the middle of the largest intergenerational transfer of wealth in its history, with older cohorts passing assets to Gen X who are starting to turn sixty, this group has too much buying power for retailers and brands to ignore.

More from Retail Insider:

Kim Crawford Wines announces 3-year partnership with Tennis Canada

KIM CRAWFORD WINES ANNOUNCES THREE-YEAR PARTNERSHIP WITH TENNIS CANADA AND THE NATIONAL BANK OPEN PRESENTED BY ROGERS (CNW Group/Kim Crawford Wines)

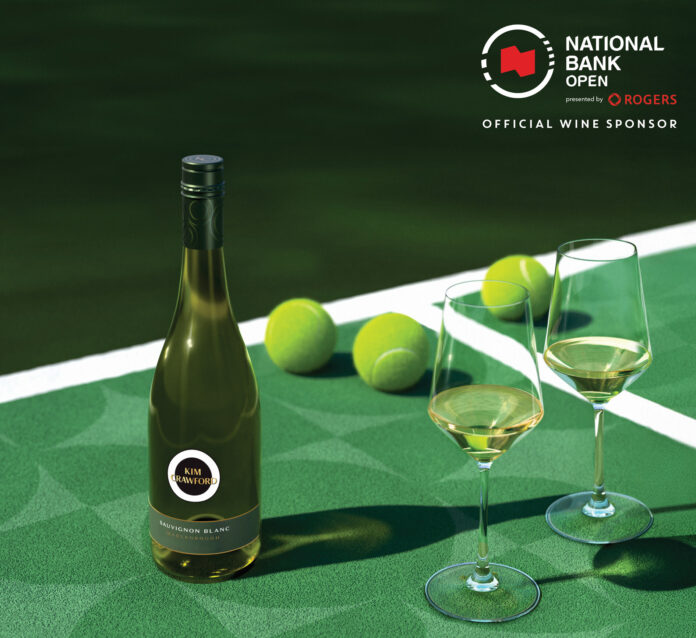
Kim Crawford Wines, the #1 New Zealand wine brand in Canada, has launched a new three-year partnership with Tennis Canada as the Official Wine of the National Bank Open (NBO) presented by Rogers.

“Kim Crawford has always been about embracing positive energy, authenticity and connection,” said Amanda Guarnieri, Canadian Manager for Constellation Brands, Inc. “As tennis continues to grow in popularity as a lifestyle-driven sport, we’re excited to bring fans into the world of Club Kim at the National Bank Open, whether they’re discovering Kim Crawford for the first time or celebrating their love of wine and tennis together with friends.”

Amanda Guarnieri
Amanda Guarnieri

The National Bank Open brings the best men’s and women’s tennis players in the world to Canada, each summer. Like previous years, NBO will take place simultaneously in two cities from August 1 to 13, with the women’s competition hosted at Sobeys Stadium in Toronto, and the men’s competition hosted at IGA Stadium in Montréal.

“We are delighted to welcome an incredible brand like Kim Crawford to the Tennis Canada and National Bank Open presented by Rogers family,” said Gavin Ziv, Chief Executive Officer, Tennis Canada.

Gavin Ziv
Gavin Ziv

“Our fans in Toronto and Montreal can look forward to an exceptional experience during our tournaments across multiple activations. The National Bank Open is more than just a tennis tournament, it’s the fuel of tennis in Canada and it’s multi-year partnerships like this that ensure we can continue to grow and develop our sport across the country.”

Claude Savard
Claude Savard

“I would also like to thank the team at Kim Crawford for their incredible collaboration on this partnership. From the outset, they have been a pleasure to work with and, crucially, have been passionate about how their investment can help grow our sport,” said Claude Savard, Vice President of Corporate Partnerships, Tennis Canada. “We look forward to working together to bring their brand to life at the National Bank Open presented by Rogers over the next three years. We’re sure our fans in both cities will enjoy what is to come.”

As part of the partnership, Kim Crawford will have a brand presence across both tournament sites, inviting fans to #BringKim to their NBO experience. Premium activations will include branded lounges, on-site bars and sampling opportunities.

Beyond the tournament grounds, Kim Crawford will also activate the partnership at LCBO and SAQ retail locations across Ontario and Québec through in-store contesting and retail displays that offers fans the chance to win tickets to the tournament this summer.

More from Retail Insider:

Kinton Ramen introduces 1st food court concept at Waterfront Centre Vancouver

Kinton Ramen photo
Kinton Ramen photo

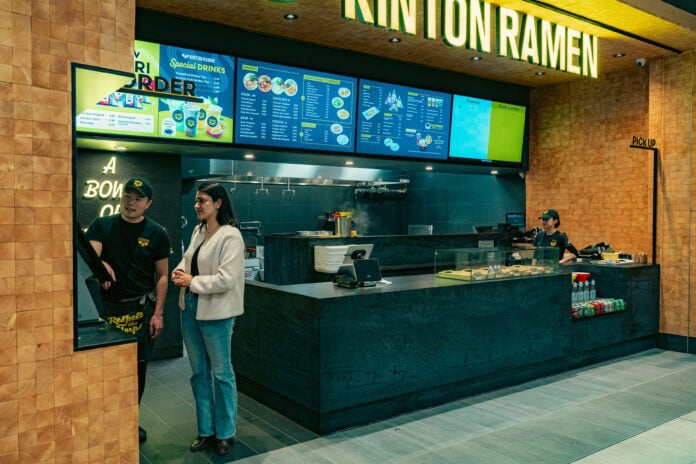
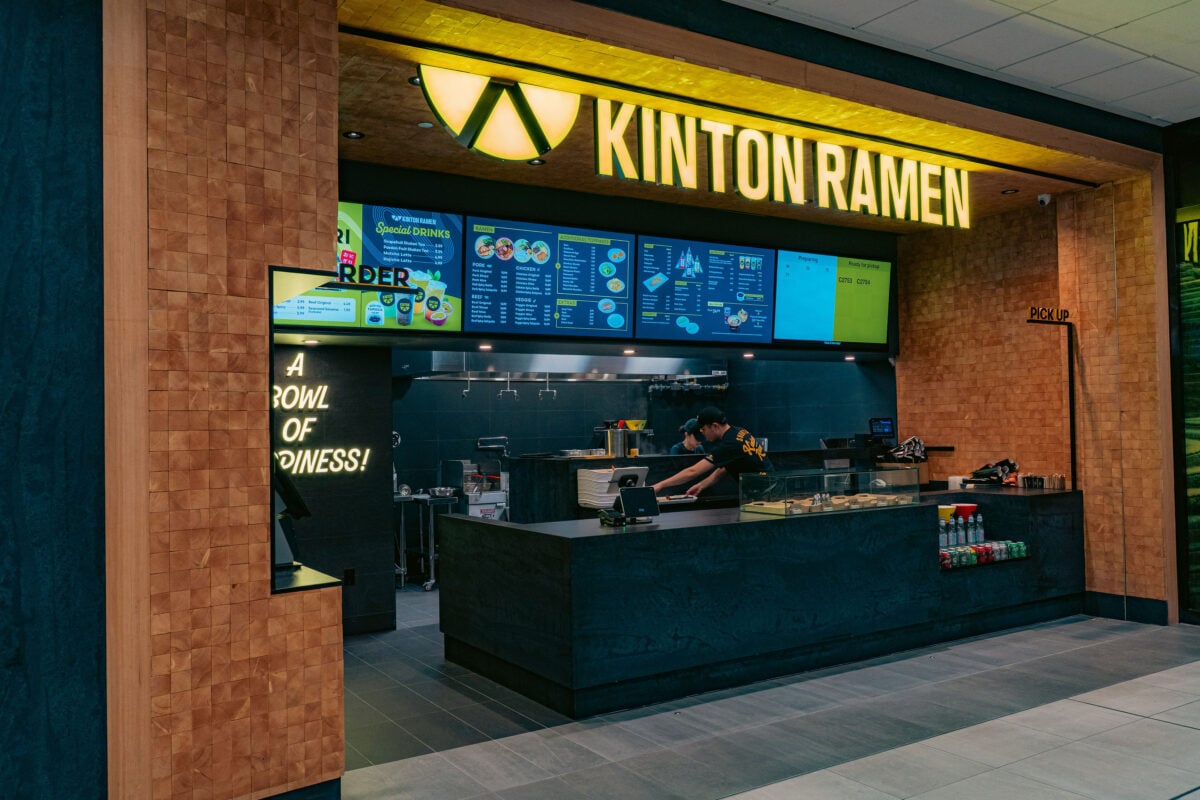
Kinton Ramen is expanding its footprint in Western Canada with the launch of its first food court location at Waterfront Centre in downtown Vancouver, marking a major milestone for the brand as it introduces a new quick-service concept designed for high-traffic urban hubs.

The new food court concept – typically 350-500 square feet – delivers the same bold, authentic brand experience in a faster, more convenient format, with a streamlined menu focused on fan favourites and speed of service, while maintaining the brand’s commitment to quality, it said.

Karalyn White
Karalyn White

“This opening represents an exciting new step for KINTON RAMEN as we continue to evolve how and where guests experience our brand,” said Karalyn White, Senior Director of Franchising Development at Kinka Family, the parent company that owns and operates Kinton Ramen. “The food court concept allows us to bring Kinton Ramen to more people in high-demand locations while preserving the quality and authenticity that guests know and love.” 

The new Vancouver location was developed by a group of five friends who combined their individual strengths – from engineering and construction to operations and business development – to bring the project to life. Leading the operation is Han Lei Sun, an experienced Kinton franchise partner who also owns and operates several locations across British Columbia and Alberta, explained the company.

Kinton Ramen photo
Kinton Ramen photo

This new opening represents the brand’s 12th location in British Columbia and serves as the first of several planned food court expansions across the province. 

“Opening the first-ever KINTON RAMEN food court concept in Vancouver is a reflection of the brand’s continued success in British Columbia,” said Jing Bao, British Columbia Area Representative. “The province has become a key growth region for Kinton Ramen, and the response from communities here has played a major role in shaping how we expand the Kinton Ramen brand in Western Canada.” 

Looking ahead, the company has also signed a new agreement with HMSHost to open a location in Terminal 3 at Toronto Pearson International Airport, bringing new dining options to one of Canada’s busiest travel hubs later this year. 

Kinton Ramen photo
Kinton Ramen photo

“We see tremendous opportunity for this concept across Canada, particularly in high-traffic destinations like airports, malls, universities and transit hubs,” said White. “As consumer demand continues to shift towards convenience without compromising quality, this format allows us to meet guests where they are while continuing to grow the Kinton Ramen brand nationwide.” 

The brand was established May 2012.

More from Retail Insider:

Tourisme Montréal focuses on infrastructure to strengthen Montréal’s competitiveness

Gibrán Riojas photo
Gibrán Riojas photo

At the recent strategic forum on major projects hosted by the Chamber of Commerce of Metropolitan Montreal, Tourisme Montréal stated that the city is at a pivotal moment in its development and is entering a new era of large-scale projects. Montréal has a unique opportunity to accelerate its growth by building on tourism and event infrastructure that fully reflects its potential, it said.

Tourisme Montréal highlighted the strong global growth in demand for major events and immersive experiences, creating a concrete opportunity for Montréal to generate significant economic benefits.

“Major events, whether cultural or sporting, are now key drivers of travel. The success of Taylor Swift’s concerts in Toronto demonstrates this and underscores the importance of investing in versatile infrastructure designed to host large-scale events. This is essential if Montréal is to capture accelerating global growth, generate significant economic benefits and strengthen its competitiveness over the long term,” the organization noted.

Tourisme Montréal reaffirmed the importance of viewing tourism infrastructure as a key lever for economic, social and cultural development. The organization calls for:

  • accelerating investment in modern, flexible and multifunctional infrastructure
  • strengthening Montréal’s capacity to host major international events
  • enhancing collaboration between public and private stakeholders
Teju photo
Teju photo

Tourisme Montréal also highlighted a particularly promising outlook, marked by the development of major tourism and recreational projects that will reshape the city over the coming years. These include the new Montréal Metropolitan Airport (MET), the YUL–Montréal-Trudeau Airport REM station, the Casino hotel, the Montréal Holocaust Museum, the new roof of the Olympic Stadium, the urban hotel at the Olympic Park site, PHI Contemporary and the reopening of the Musée d’art contemporain, it added.

More from Retail Insider: