Home Blog Page 52

How Retail Brands Can Use AI for Product Descriptions Without Sounding Robotic

Open the outerwear category on almost any mid-sized retailer’s site in late October and read five parka descriptions in a row. “Stay warm and stylish all winter long.” “Crafted for comfort and designed for adventure.” “The ultimate layer for cold-weather days.” By the third one your eyes slide off the page, and by the fifth you can’t remember which jacket had the removable hood. Nobody wrote those sentences on purpose. A tool generated them in bulk, someone skimmed them for typos, and they went live alongside 300 others the same afternoon.

I’ve spent a fair amount of time cleaning up catalogue copy for retail teams, and the pattern is very consistent. The AI didn’t fail. It did exactly what it was asked, which was “write a product description for a women’s insulated parka.” The prompt had no facts in it, so the model filled the gap with the most statistically likely words about parkas. Those words are the same ones every other retailer’s model reached for.

So the fix sits mostly upstream of the writing. It lives in what you feed the tool, how you edit the output, and who on the team gets the final say.

Start with a fact sheet, not a prompt

The single habit that changes AI product copy the most is building a short fact sheet for each SKU before anyone opens a chatbot. It doesn’t need to be fancy. A spreadsheet row works. What matters is that it contains information only your business has.

For that parka, a useful fact sheet might look like this:

  • Fill: 650 fill power responsibly sourced down
  • Shell: matte nylon with DWR finish, sheds light snow and freezing drizzle
  • Length: hits mid-thigh on a 5’6” model wearing size S
  • Hood: removable, faux fur trim detaches separately
  • Pockets: two hand-warmer pockets with fleece lining, one interior zip pocket that fits a large phone
  • Fit note from returns data: runs slightly small in the shoulders, customers layering a thick sweater size up
  • Store staff comment: “People like that it doesn’t look puffy from the side.”
  • Care: machine wash cold, tumble dry low with dryer balls

Notice the last three lines. The fit note comes from your returns system. The staff comment comes from someone on the floor at your Yorkdale or Rideau location who has watched people try it on. Those details are the ones a generic model will never invent, and they are the ones that make a shopper trust the page.

Then the prompt becomes something closer to this:

Write a 90 to 120 word product description for the parka below. Audience: commuters in Toronto and Ottawa who take transit and walk 10 to 15 minutes in winter. Use only the facts provided. Do not use the words “ultimate”, “stylish”, “perfect”, or “must-have”. Mention the sizing note plainly. Plain, warm tone, short sentences, Canadian spelling. [paste fact sheet]

The “use only the facts provided” line does a lot of work. It stops the model from claiming the jacket is rated to minus 40 when nobody tested that, which is a legal problem as well as a tone problem.

Ban list, house style, and a few sample paragraphs

Every brand has words it overuses. Every model has words it overuses too, and the two lists overlap more than you’d expect. Pull the last 50 descriptions your team wrote by hand, the ones people liked, and read them out loud in a meeting. You’ll hear your own voice in maybe ten of them. Paste two or three of those into your prompt as examples of tone, and paste a ban list of the words that make you wince.

A typical ban list for apparel and home goods includes “ultimate,” “effortless,” “timeless,” “versatile,” “must-have,” “perfect for any occasion,” “take your X to the next level,” and “look no further.” Your list will differ. A hardware retailer probably has a separate set of tired phrases (“tackle any project”) that a fashion brand never sees.

House style also covers the small mechanical stuff: whether you write “colour” or “color” (for a Canadian audience, almost always “colour”), whether you use centimetres first or inches first, whether sizes are written “S/M/L” or “Small, Medium, Large.” Models get these wrong unless told, and inconsistent units across a category page look careless.

Where an AI humanizer fits in the workflow

Even with a good fact sheet, first drafts often come back with a recognisable rhythm: three short clauses, a benefit, a call to action, repeated across every SKU. When you’re producing a few hundred descriptions for a seasonal drop, rewriting each one from scratch defeats the purpose of using AI at all. This is where a rewriting pass helps. Running the draft through an ai humanizer varies the sentence structure and loosens the stiff phrasing so the copy reads less like a template, while keeping the facts you supplied. Quillbot’s version, for example, lets you paste the draft and get back a smoother rewrite you can then edit line by line.

Treat that step as a middle pass, not a finish line. The tool can change how the sentences sound. It can’t know that your Quebec customers hate the word “puffer” or that the zip pocket is the thing everyone mentions in reviews. A person still has to read every description before it ships, and they should be checking for three things specifically:

  1. Every factual claim matches the fact sheet. Rewriting tools occasionally soften “machine wash cold” into something vaguer, or drop a measurement.
  2. The sizing and care notes survived intact.
  3. The description sounds like it belongs on your site and not on a competitor’s.

A before and after

Here is a real-shaped example, built from the parka fact sheet above.

First AI draft (generic prompt, no fact sheet):

Stay warm and stylish all winter long with our Women’s Insulated Parka. Crafted with premium materials and designed for ultimate comfort, this versatile jacket is perfect for everything from city commutes to weekend adventures. Its timeless silhouette and thoughtful details make it a must-have for your cold-weather wardrobe.

Nothing in that paragraph is false, exactly. Nothing in it is useful either. A shopper learns zero about the jacket.

After fact sheet prompt, rewrite pass, and human edit:

Built for the walk from the subway to the office when the wind comes off the lake. 650 fill power down keeps the core warm without the marshmallow look from the side, and the matte shell shrugs off light snow and freezing drizzle. It falls to mid-thigh. The hood comes off, and so does the faux fur trim, separately. Two fleece-lined hand pockets, plus an inside zip pocket that fits a big phone. Sizing note: it runs a little narrow in the shoulders, so if you plan to wear a chunky sweater underneath, go up a size. Machine wash cold, tumble dry low with a couple of dryer balls.

The second version is longer, but every sentence carries something. And it reads like a person who has seen the jacket.

Bilingual copy needs its own pass

Retailers selling into Quebec already know the French requirements are not optional, and product information has to be available in French. AI translation from English has improved a lot, but direct translation of marketing copy still produces French that sounds translated. Quebec shoppers spot it immediately. The idioms come out European, or the sentence structure follows English word order a little too faithfully.

The better approach is to generate the French version from the same fact sheet rather than translating the finished English copy. Give the model the facts, tell it to write for a Montréal or Québec City shopper in Québécois French register, and have a francophone team member review it. Translating the English draft means you inherit every quirk of the English draft, plus a translation layer on top. Starting from facts means each language gets its own natural phrasing. ## Different products need different lengths

One mistake I see often is a single prompt template applied to the whole catalogue. A $14 pack of tea towels does not need 150 words. A $1,200 sectional sofa probably needs more than 150, plus dimensions, delivery notes, and fabric care.

A rough split that works for a lot of general retailers:

Product typeTypical lengthWhat the shopper actually needs
Low-cost consumables and basics30 to 60 wordsSize, quantity, material, one use note
Apparel and footwear80 to 130 wordsFit, fabric feel, care, sizing advice from returns
Electronics and small appliances100 to 150 words plus spec tableCompatibility, what’s in the box, warranty
Furniture and big-ticket home150 to 250 words plus spec tableDimensions, assembly, delivery, materials, care

Set separate prompt templates for each tier, and you stop trimming 140-word descriptions of dish soap.

What to keep human, always

Some parts of the description should never be AI-generated without a person checking them against a source document:

  • Safety and compliance claims (CSA certification, flammability, age grading on toys)
  • Warranty terms
  • Allergen or ingredient lists on food, cosmetics, and supplements
  • Origin claims (“Made in Canada” has specific rules attached, and “Product of Canada” has stricter ones)
  • Sustainability claims, which the Competition Bureau has been paying closer attention to

For these, paste the exact wording from the supplier spec sheet or your compliance team, and tell the model to reproduce it verbatim. Then check that it did.

Building it into a team process

A merchandising team of four can comfortably handle a few hundred descriptions a week this way, if the steps are clear. One workable setup:

  1. Buyers or product managers fill in the fact sheet when the SKU is set up, including the fit or use notes from samples.
  2. A copywriter or ecommerce coordinator runs the generation prompts in batches by category.
  3. The drafts go through a rewrite pass to break up repetitive phrasing.
  4. A second person reads every description against the fact sheet and the brand voice examples.
  5. Store staff feedback and early reviews get added to the fact sheet after launch, and the top-selling SKUs get their descriptions refreshed once real customer language is available.

Step five is the one most teams skip, and it’s the one that keeps the copy alive. Three weeks after launch, your reviews will tell you how customers describe the product in their own words. “Finally a jacket my arms can move in” is better copy than anything a model will produce, and it costs nothing to borrow the idea (paraphrased, with the reviewer’s words left in the review section where they belong).

Common mistakes

Generating from the product title alone. This produces the generic paragraph every time. No fact sheet, no useful copy.

Letting the model invent specs. Watch for temperature ratings, waterproof ratings, battery life figures, and thread counts that nobody gave it. These are the claims that end up in complaint emails.

Running everything through the same voice. Your kids’ department and your premium kitchen line probably shouldn’t sound identical, even if the brand voice is consistent overall.

Skipping the read-aloud. Read three descriptions in a row out loud. If you hear the same sentence shape three times, so will your customers. ## Tools and the people using them

AI does well at producing a first draft quickly and at rewriting the tenth description of a similar item so it doesn’t echo the ninth. It’s weaker at knowing which detail matters most to your customer, and it has no idea what your store staff hear at the fitting room. Feeding it those details is the job.

Using a rewriting tool on drafts that came out stiff is fine, and an ai humanizer is useful when you have a long run of near-identical products (twelve colourways of the same merino crewneck, say) and need each page to read a little differently without changing the facts. Just keep the fact sheet open beside it. The tool handles rhythm and phrasing; your team handles truth and judgment. ## FAQ

Will shoppers notice if product descriptions are AI-written? They notice generic writing, regardless of who wrote it. Descriptions built from specific facts, fit notes, and real use details rarely read as machine-made, even when a tool did the first draft.

Should we disclose that AI helped write product copy? There’s no general requirement in Canada to label AI-assisted product descriptions right now. What matters legally is that the claims are accurate. Some brands mention their process in an “about our content” page, which is a reasonable choice but not a standard one.

How often should descriptions be refreshed? Top sellers deserve a look after the first wave of reviews comes in, usually within a month or two of launch. Everything else can wait for the next seasonal update or a change in the product spec.

One small test to run this week

Pick your ten best-selling SKUs. Pull up the current descriptions and, for each one, write down a single fact a shopper would want that isn’t on the page right now: a sizing note, a care quirk, a staff observation, a common question from customer service. Then rebuild those ten descriptions from a fact sheet using the steps above and compare them side by side with the originals in a quick team review. You’ll know within an hour whether the process is worth rolling out to the rest of the catalogue, and you’ll probably find two or three of the old descriptions had a factual error nobody noticed.
From Amazon-Only to Four Major Retailers in Under a Year: Inside COOFANDY’s Omnichannel Expansion

A case study in how one DTC menswear brand sequenced its move from a single marketplace into Walmart, Target, and Kohl’s – and what the timeline suggests about the playbook other digitally native brands are starting to follow

Just under a year ago, COOFANDY was a menswear label most people had encountered, if they’d encountered it at all, through an Amazon search result. Today the brand sells through four major retail partners – Amazon, Walmart, Target, and Kohl’s – alongside its own direct-to-consumer site. That’s a fast, deliberate omnichannel build for a company that spent its first decade as a single-marketplace operation, and the sequencing behind it is worth more attention than the announcements themselves got individually.

COOFANDY launched in 2015 as an Amazon-first label: versatile, fairly priced menswear sold directly online, without the overhead of a traditional retail footprint. During this period, Amazon accounted for the vast majority of COOFANDY’s revenue, with annual sales exceeding $6 million in gross merchandise value. The model worked well enough to get the brand to more than 70 million customers across more than 30 countries over eleven years, but it also meant COOFANDY’s growth ceiling was tied to a single channel’s algorithm and customer base.

The 2026 retail expansion didn’t happen all at once, and the order it happened in tells its own story. Walmart came first, chosen for reach more than positioning – it’s where a broad swath of COOFANDY’s existing customer already shops for everything else. Target followed, aimed more deliberately at a design-conscious shopper, effectively testing whether COOFANDY’s growing design-award recognition would resonate outside its existing customer base. Kohl’s came third and arguably fits most naturally of the three: unlike the general-merchandise retailers ahead of it on the list, Kohl’s built its identity specifically around apparel, putting COOFANDY in front of a retailer whose core shopper already thinks about clothing the way COOFANDY’s does.

There’s a timing angle worth flagging for a trade audience too: fall is peak promotional season for men’s apparel, and this expansion is landing squarely inside that window. A new vendor showing up on a retailer’s shelves during a slower stretch of the calendar has to fight for merchandising attention on its own; one arriving as retailers are actively building out and pushing fall assortments gets folded into a push that’s already underway.

That sequencing lines up with something else that happened in 2025, just ahead of the expansion: COOFANDY picked up three separate design honors – Silver recognition from the MUSE Design Awards, the Berlin Design Awards, and the New York Product Design Awards – plus a placement on CNN Underscored’s list of editor-recommended menswear. For a brand negotiating shelf space with national retailers, that kind of third-party validation functions less as marketing copy and more as a credibility signal in the room during buyer conversations, even if it’s rarely stated that directly.

Since the 2026 retail expansion began, COOFANDY’s total omnichannel order volume has grown by approximately 34%, with brand search volume up 33% over the same period – an early signal that the new retail partnerships are generating incremental demand rather than simply redistributing existing customers across more checkout options.

“We didn’t set out to collect retailers,” said Sidney Sun, Chief Marketing Officer at COOFANDY. “Each one solved a specific distribution problem we actually had. The sequencing wasn’t random – it followed where we thought we had the strongest case to make, in the order we thought we could make it.”

Whether COOFANDY’s specific sequence becomes a template other digitally native brands follow remains to be seen, but the shape of it – build credibility first, then use that credibility to move into retail deliberately rather than opportunistically – is a more disciplined version of a jump plenty of DTC brands attempt and fewer manage cleanly. For now, COOFANDY’s footprint sits at four major retail partners plus its own site, built out in under a year. Whether that number grows further is not yet confirmed.
From The Desk: Retail Growth Divides and AI’s Expanding Role in Canadian Retail

Canadian retail continues to be a mixed bag, and the differences between who’s growing and who’s struggling are becoming increasingly apparent. Value-focused retailers are finding opportunities to expand, while premium brands continue investing in stores and experiences that attract customers willing to spend. It’s a tougher environment for many retailers in the middle, particularly those struggling to give shoppers a compelling reason to visit.
We’re also seeing some interesting developments in retail real estate. Grocery-anchored shopping centres remain in demand, with limited available space and healthy leasing activity. At the same time, landlords are facing some expensive decisions about what to do with former department stores and other large retail spaces. Some of these properties present tremendous opportunities, although repositioning them can be complicated and costly.

Technology is another area worth watching. Artificial intelligence is increasingly finding its way into everyday retail operations, from inventory management and merchandising to marketing and supply chains. There’s considerable potential here, although retailers will need to determine where these investments actually deliver results.

What stands out to me is how differently retailers are responding to the same economic environment. Some are expanding aggressively, others are becoming more selective about where they invest, and some are having to rethink their businesses altogether. We’ll continue watching how these decisions play out across Canada’s retail landscape.

Here are some of the stories and developments that caught our attention this week.

Retailer News

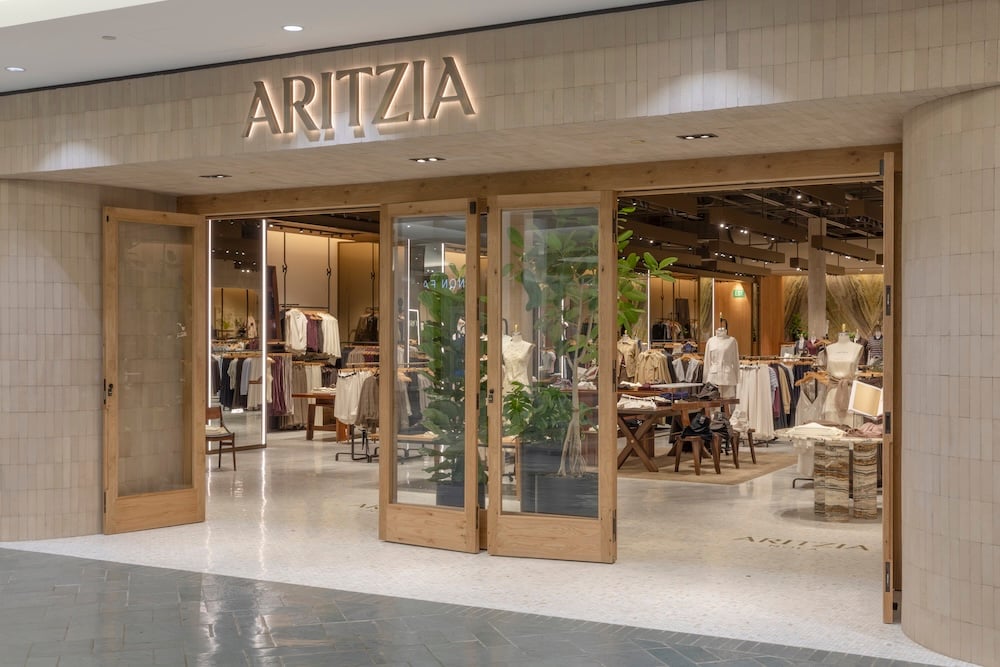
Aritzia is expanding its North American footprint with plans for more U.S. store openings, larger retail spaces and repositioning of locations in Quebec and California, reflecting strong boutique sales and increased customer traffic. This approach confirms the continuing relevance of physical retail within its omnichannel strategy, offering insights for landlords and investors about where retail investment can succeed amid changes in consumer behaviour.

Alimentation Couche-Tard agreed to acquire retail locations, fuel supply agreements and 18 cardlock sites from Irving Oil in Quebec and Ontario, pending regulatory approval, increasing its presence in these key markets. This transaction strengthens Couche-Tard’s integration of fuel supply with convenience retailing, a relevant development for commercial real estate stakeholders tracking asset ownership and market consolidation.

Canadian retail reports for the third quarter of 2026 show a mix of growth and caution across sectors with overall investment in retail real estate, technology and operations continuing but with an eye on changing consumer behaviour and market selectivity. While grocery retailers expanded and repositioned capacity through discount format conversions and new specialty formats, underlying volume growth remained minimal, highlighting pressures on profitability and the need for strategic property usage amid evolving online fulfillment needs. Foodservice sales increased during the same quarter with chains investing in renovations, delivery partnerships and loyalty programs, but tight margins and selective consumers require careful management to ensure sustainable growth and site viability for landlords and operators.

Individual retailers reported notable financial performances, underlining the challenges and opportunities in different retail categories. Aritzia’s fiscal 2027 second quarter results showed a 44.1% increase in net revenue, reaching $1.17 billion, driven by strong comparable sales growth and digital and U.S. market expansions, reflecting effective real estate and digital channel investment. Kits Eyecare also showed significant gains, with total revenue rising 21.6% year-over-year in Q3 to about $63.7 million, boosted by the glasses segment’s 59.3% growth and a balance sheet free of debt, underscoring the value of diversified product lines in retail growth.

Retailer People News

IKEA Canada CEO Selwyn Crittendon will leave his post at the end of December to become Deputy CEO of IKEA U.S., a move that could alter the home furnishings retailer’s approach across North America especially as it pursues growth and sustainability goals. The company has yet to name his Canadian successor, leaving some uncertainty for Canadian retail landlords and suppliers who have worked with Crittendon on store expansion and community initiatives.

The fashion sector features two notable Canadian designers focusing on sustainable growth in distinct ways. George Sully stresses the challenges Canadian designers face scaling nationally amid limited industry infrastructure and the necessity of forging equitable retail partnerships to turn visibility into lasting commercial success. Joseph Tassoni exemplifies a deliberate growth strategy through his recent Natural Authority runway and Oakville showroom, emphasizing direct customer engagement and experiential retail to build brand loyalty and manage expansion cautiously.

Retailer Op-Eds

Canadian retail continues to show a clear divide between value-oriented and premium-focused retailers, pushing mid-tier operators to find sharper ways to differentiate themselves through new store formats and technology adoption. Retailers increasingly embrace AI-driven customer engagement tools alongside franchising growth to enhance operational efficiency and respond to shifting consumer behaviours. Meanwhile, the Competition Bureau’s investigation into minimum advertised pricing policies reveals a tension where pricier MAP rules limit how discount grocers promote deals, while also offering protection for independent retailers competing against bigger national chains with stronger buying power. This dual effect influences pricing strategy decisions and retailer viability, creating complex dynamics for landlords and suppliers managing space in Canada’s concentrated grocery market.

Editor’s Take

The divide in Canadian retail continues to widen. Value-focused retailers are attracting cost-conscious shoppers, while premium brands are investing in larger stores and better customer experiences. Aritzia is one example of a retailer taking a selective approach to expansion, concentrating on locations where it sees strong sales potential. For retailers caught in the middle, the pressure is mounting. Store space is expensive, inventory needs to move, and customers have plenty of alternatives. Having a recognizable brand is no guarantee of success.

Retail landlords are dealing with a very different set of circumstances depending on the properties they own. Grocery-anchored centres continue to perform well, with low vacancy and strong demand from tenants. Former department-store spaces are another matter. Redeveloping these large properties can require substantial investment, complicated construction work and years of planning. We’re seeing landlords explore combinations of grocery stores, entertainment, restaurants and smaller retail tenants to bring these spaces back into productive use. Concepts such as TM Wander and The Rec Room also show how shopping centres are incorporating more reasons for people to visit beyond traditional shopping.

Artificial intelligence is becoming a bigger part of retail operations, and I’m particularly interested in how this develops. Companies such as Canadian Tire, Loblaw and Instacart are using the technology across areas including merchandising, customer engagement and fulfilment. There’s potential for meaningful improvements, although implementation can be expensive and results will depend heavily on the quality of the underlying data. AI is also changing how consumers discover products online, creating another challenge for retailers trying to understand where their customers are coming from and which marketing investments are working.

One area that deserves more attention is the pressure on smaller independent retailers. Rising operating costs, property taxes and other expenses are making it difficult for some businesses to expand or even maintain their existing locations. These retailers contribute considerably to the character and economic activity of communities across Canada, and their challenges shouldn’t get lost in the headlines about major chains opening new stores.

Looking across this week’s developments, it’s apparent that there are still opportunities for growth in Canadian retail, although success increasingly depends on choosing the right locations, managing costs carefully and understanding what customers actually want. We’ll be watching how these trends develop in the months ahead.

This Week’s Articles

Retailer News

Retailer People News

Retailer Op-Eds

News From Around the Web

Toronto Fashion Label Demascaré Expands Into Ready-to-Wear as Shaun Mascarenhas Eyes Retail Growth

Toronto fashion designer Shaun Mascarenhas is moving Demascaré into its next stage, expanding the independent label into ready-to-wear as he works to build a stronger commercial business around the aesthetic that first brought his work attention.

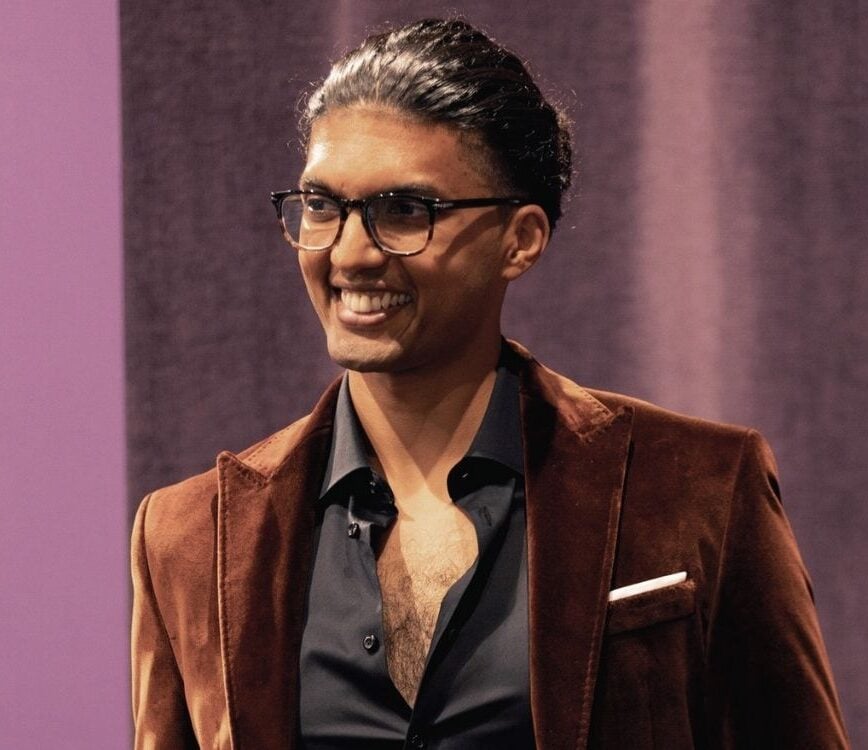
Shaun Mascarenhas

The Toronto-based brand has so far been known largely for custom work, demi-couture and expressive statement pieces. Mascarenhas is now developing clothing that can move more easily through retail while retaining the draping, fit and architectural elements associated with Demascaré.

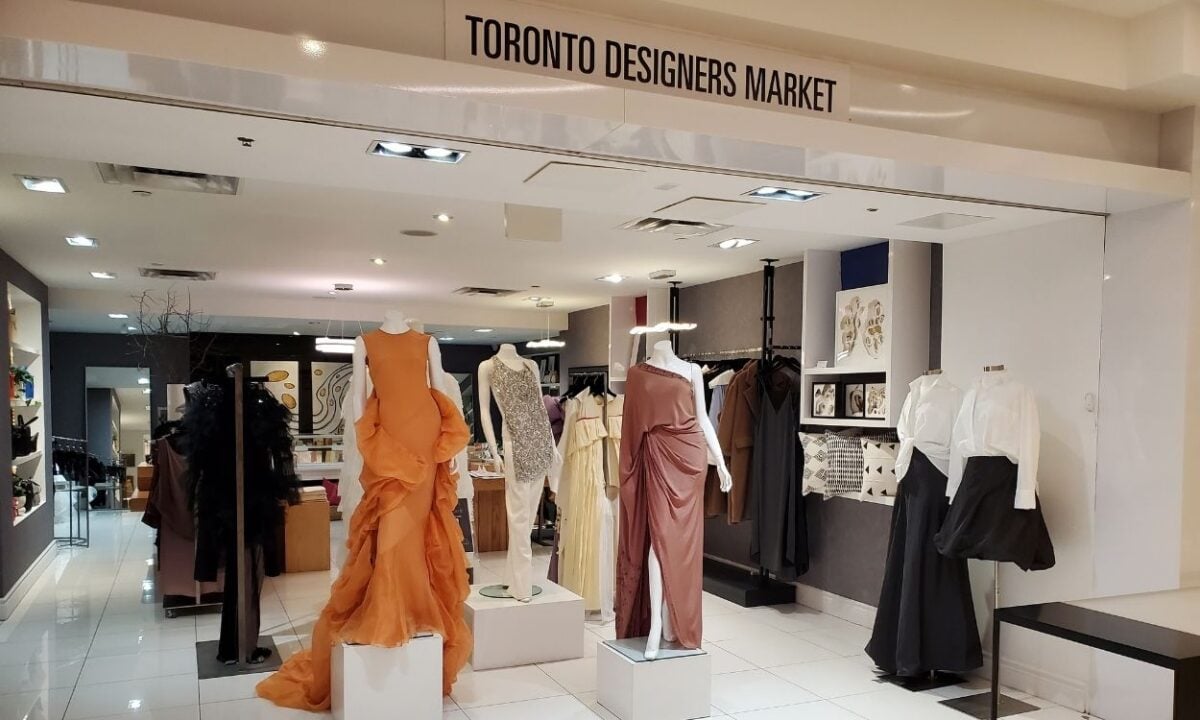
The shift comes as the brand establishes a clearer retail presence. Demascaré is currently sold through Toronto Designers Market at the Holt Renfrew Centre on Bloor Street, its only physical retail location, while a broader ready-to-wear assortment is being prepared for online sale. Mascarenhas is also beginning to explore selective wholesale distribution.

“I just completed a year with the store,” he said of Toronto Designers Market. “It’s been a great learning experience. I’ve had some really good months and some really slow months, so I’m still trying to understand the business.”

From Architecture to Fashion

Mascarenhas was born in India and originally pursued architecture before realizing early in his studies that he did not see it as a lifelong career. He remembers sitting in the studio late one night when the question occurred to him: could he imagine doing this for the rest of his life? His answer was no.

Supported by his parents, Mascarenhas shifted into fashion, later studying in the United States and moving to New York, where he secured an internship in the atelier at Oscar de la Renta. The experience exposed him to the technical side of high-end fashion and garment construction at a level that would continue to influence his own work.

His architectural training also stayed with him. Structure, proportion and linearity continue to appear in his silhouettes, often balanced by draping and movement.

His early career included experience around designers and fashion houses including Zac Posen, J. Mendel and Romona Keveza. After relocating to Canada, Mascarenhas spent years working in Toronto’s bridal and eveningwear sector. The pandemic ultimately prompted him to reconsider where he wanted his career to go and whether it was time to create something of his own.

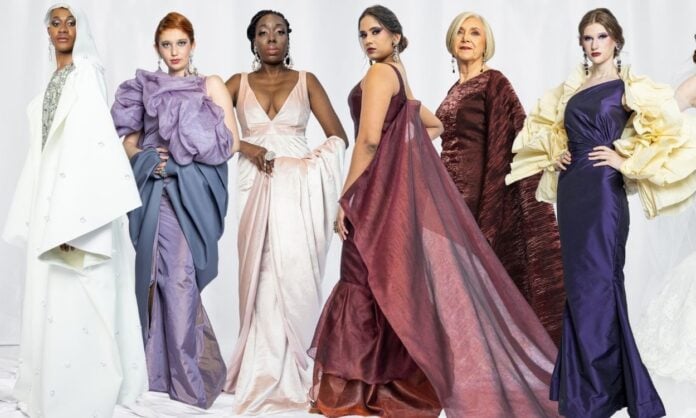
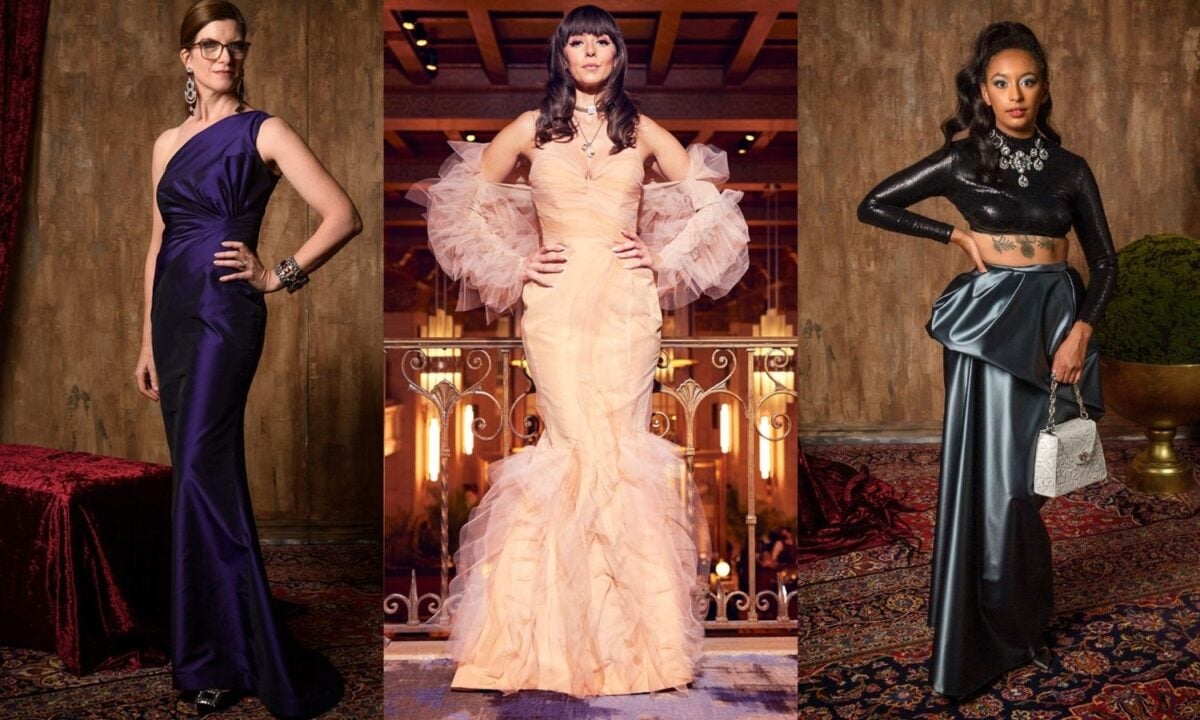
Demascaré Pimentel CAFA2023 DonnaBishop BrionyDouglas HillaryLeBlanc

Building Demascaré During the Pandemic

Mascarenhas launched Demascaré during COVID after years spent helping create collections for other companies. The name combines elements of his middle and last names, allowing him to establish a brand identity separate from his personal name.

That separation was deliberate. Mascarenhas wanted the company to stand independently from him and potentially develop value beyond his identity as its designer. Sustainability was also part of the concept from the beginning.

“I didn’t just want to be another designer who bought fabric off Queen Street and made clothes,” he said.

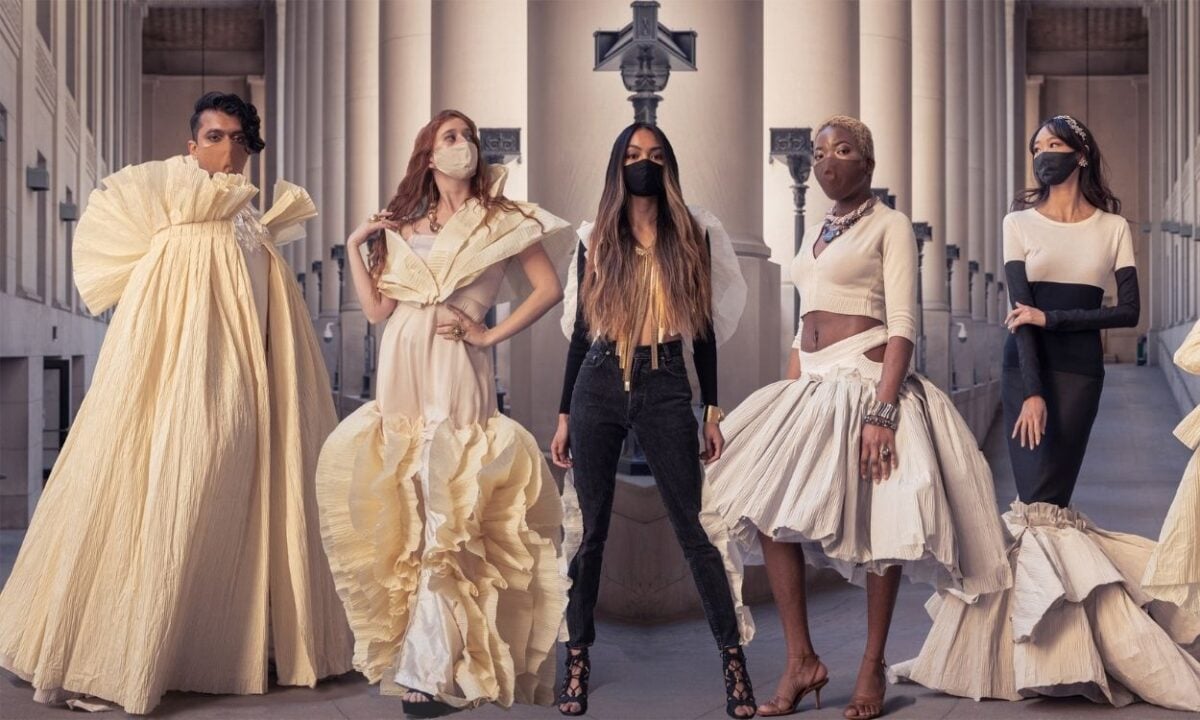
His first major collection pushed that thinking in an experimental direction. Mascarenhas worked with paper that would otherwise have been discarded from fabric pleating processes and layered it over existing garments brought in by models, altering and repurposing those pieces in the process.

The resulting collection was presented through Fashion Art Toronto at Union Station. Stylists subsequently began contacting Mascarenhas to borrow garments for editorial shoots, giving the young label early visibility and showing him that people were responding to the originality of the work.

What happened with his next collection would prove equally influential.

Demascaré ArielLii ChristalWilliams

An Early Lesson in What Makes a Brand Sell

After attracting attention with highly distinctive pieces, Mascarenhas decided his next collection should be easier to sell. He made the clothing more conventional, expecting that a more commercial assortment would appeal to a wider group of customers.

The response was weak.

“I was thinking, ‘This is very sellable. Why isn’t anybody buying it?’” he recalled.

The feedback he eventually received was straightforward: people had been interested in his original work precisely because it was different. In trying to make Demascaré more broadly commercial, he had removed some of what made the label recognizable.

Mascarenhas stepped back, spent more time learning the Toronto and Canadian market and returned to eveningwear and custom pieces. A later collection led to an early custom order for a client attending the Canadian Arts & Fashion Awards, and Demascaré gradually developed a business around one-of-a-kind and made-to-measure clothing.

The custom work gave Mascarenhas considerable experience with clients, fit, alterations and the practical realities of producing clothing for individual customers. It also exposed a commercial limitation: Mascarenhas said the demi-couture and custom business was largely covering its costs rather than producing enough profit to support the kind of company he wanted to build.

That realization pushed him toward ready-to-wear.

Translating the Demascaré Aesthetic Into Ready-to-Wear

Mascarenhas did not want commercialization to mean stripping away the qualities that distinguished the brand. He spent months working with a fit model and developing base patterns that could provide consistency while still allowing him to drape and manipulate garments in ways that felt recognizably Demascaré.

Fit became particularly important in that process. Mascarenhas believes customers have started to associate the brand with how its clothing sits on the body, making that one of the qualities he wants to protect as he moves beyond purely custom work.

The new collection spans daywear and eveningwear and is designed around a customer who follows fashion but also wants clothing to function in everyday life. Mascarenhas describes that customer as someone who travels, attends events and wants pieces that can move through different parts of the day while still feeling special.

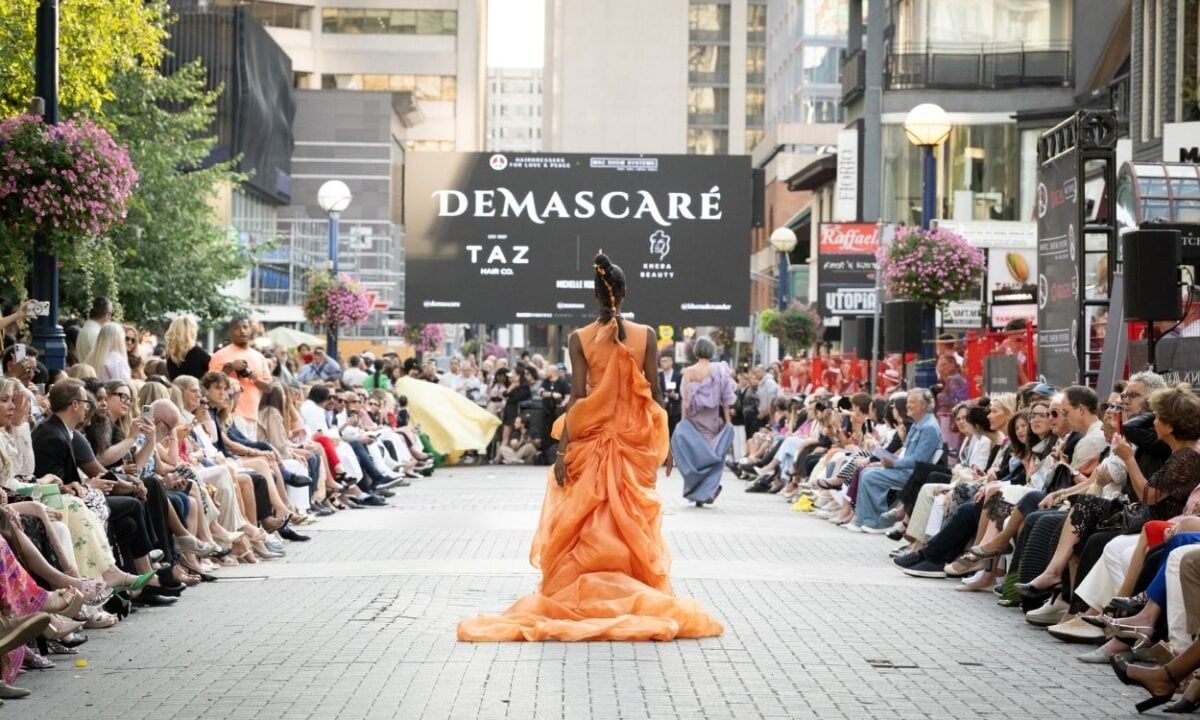
His recent presentation at Couture for a Cause in Yorkville included a mix of couture and ready-to-wear, giving audiences an early look at the new direction. The response was encouraging, although the event also exposed a weakness in the retail infrastructure behind the brand.

Demascaré TDM

When Attention Arrives Before the Business Is Ready

Following Couture for a Cause, Mascarenhas saw a noticeable increase in traffic to the Demascaré website. People had seen the clothes, searched for the brand and arrived online, but the new collection was not yet available to purchase.

Instead, visitors found older product rather than the pieces that had generated their interest. Mascarenhas readily acknowledges that the website should have been prepared ahead of the event.

“What I should have done was have my website ready to go,” he said.

He has since completed a new lookbook shoot and is working to bring the ready-to-wear offering online. The experience offered a practical lesson about the gap between exposure and commerce: a runway appearance or publicity moment can generate immediate interest, but the product, website and fulfilment operation have to be ready if that attention is going to translate into sales.

For Demascaré, building that commercial infrastructure has become an increasingly important part of the business. Mascarenhas is currently working with Digital Main Street’s ShopHERE program, which helps small businesses and artists establish online stores.

Mascarenhas said the program has been particularly helpful in guiding him through the process of setting up Demascaré’s e-commerce operation, an important step as the company prepares to make its expanding ready-to-wear assortment available online.

Toronto Designers Market as a Retail Testing Ground

Physical retail has played a similar role. Mascarenhas initially hesitated when he was encouraged to bring Demascaré into Toronto Designers Market because he was not convinced the business was ready, but he eventually took the opportunity and has now spent roughly a year selling through the store.

The experience has given him something difficult to replicate online: direct evidence of how customers react when they encounter the clothing in person. He can learn which garments attract attention, what customers try on, how pieces fit and where shoppers hesitate.

Feedback from the store has helped Mascarenhas better understand how Demascaré performs in a retail setting and reinforced his decision to move further into ready-to-wear. He describes the first year as uneven but valuable, with strong periods as well as slower months.

Toronto Designers Market remains Demascaré’s only physical retail location. Mascarenhas is now looking at where the brand could go next, while remaining selective about the type of stores he believes make sense.

Made in Toronto, in Small Quantities

Demascaré is not being built around mass production. Mascarenhas said the brand’s current production is done in Toronto, with him cutting the garments himself before working with experienced local seamstresses to complete the pieces.

That approach is more expensive than large-scale offshore manufacturing, but it gives Mascarenhas greater control over production and fits the model he wants to maintain. The brand is largely made to order and frequently works with deadstock fabrics.

Because quantities of a particular textile may be limited, a garment produced in one fabric may exist in only three or four examples. For Mascarenhas, that scarcity adds value.

“I’m not a mass-production brand,” he said. “I’m very one-of-a-kind or few-of-a-kind.”

He wants customers to feel they are buying something unusual and to keep those garments in their wardrobes for years.

The production model also exposes another challenge facing Canadian fashion businesses. Mascarenhas said experienced seamstresses with the technical skills required for his work are becoming harder to find, and he is conscious that younger generations are not necessarily entering the trade at the same rate. For a small designer trying to grow locally, access to skilled production can become as important as access to customers.

Demascaré-JennJevons Fashion Art Toronto Paper Collection

Sustainability Built Into the Production Model

Demascaré’s production strategy is closely connected to its sustainability positioning. Deadstock fabrics, repurposed materials, local production and made-to-order manufacturing are all part of the model, reducing the need to hold large quantities of finished inventory.

One of the more distinctive applications involves vintage sarees. Mascarenhas has been transforming existing sarees into contemporary gowns and cocktail dresses, combining his South Asian background with the circular design principles behind the brand.

He also sees a practical opportunity in the idea. Traditional garments can carry considerable emotional or cultural significance within families, even when younger generations raised in Canada may not expect to wear them in their original form.

Mascarenhas sees the possibility of preserving that connection while reworking the textile into a garment suited to a contemporary wardrobe. The saree remains recognizable in the finished piece, while the resulting clothing gives the material another use and potentially another generation of wear.

Expanding Through the Right Retailers

As the ready-to-wear business develops, Mascarenhas wants to add a small number of retail partners rather than pursue broad distribution.

One retailer he specifically identified is Absolutely Fabrics, the Toronto fashion retailer known for carrying distinctive and less widely distributed labels. There is no announced relationship between the companies; Mascarenhas sees it as an example of the type of retailer where Demascaré could potentially fit.

He is also interested in independent boutiques on Queen Street West and elsewhere in Toronto that cater to consumers looking for unusual fashion.

That selectivity reflects both the positioning of Demascaré and the realities of its production model. A company using limited deadstock fabrics and producing in small batches does not require an extensive store network. Mascarenhas is instead looking for retailers capable of putting the brand in front of customers who understand the product and its price point.

He describes his core customer as a middle-aged to mature woman who enjoys fashion, travels, attends events and wants clothing that feels distinctive while remaining practical.

“The clientele is out there,” he said. “It’s just trying to get in front of them.”

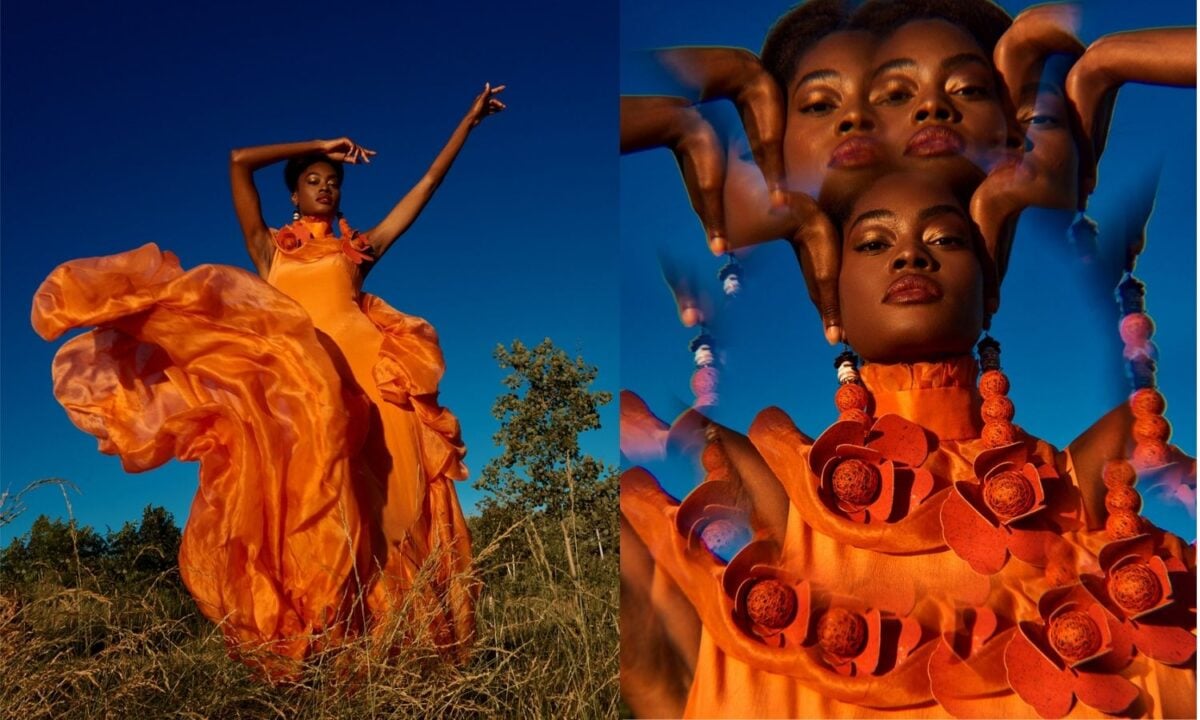
Demascaré Pimentel Couture for a Cause2026

Holt Renfrew Is the Longer-Term Goal

There is one Canadian retailer Mascarenhas is particularly interested in reaching.

“Holt’s is on my list,” he said. “That’s the dream.”

For Mascarenhas, placement at Holt Renfrew would represent a significant milestone for Demascaré and a validation of the brand within Canadian luxury retail. During the interview, he also discussed the potential conceptual alignment between Demascaré and Holt Renfrew’s sustainability-oriented H Project.

There are no announced discussions or arrangements between Demascaré and Holt Renfrew, and Mascarenhas described the retailer as a future ambition rather than an active deal.

Longer term, he is also interested in international markets, particularly Europe. Mascarenhas said he feels a strong affinity with European fashion culture and could eventually see opportunities in markets including France, Italy and the United Kingdom, though his immediate focus is building a stronger foundation in Canada.

The Challenge of Scaling Canadian Fashion

That task is complicated by the environment in which independent Canadian designers operate. Mascarenhas points to several obstacles at once, including access to capital, the cost and availability of local manufacturing, limited retail distribution and the difficulty of building customer awareness.

Asked which presents the greatest challenge, he said the answer is effectively all of them.

He is particularly concerned about the level of institutional support available to the Canadian fashion sector and believes the country has considerable design talent without the supporting ecosystem found in larger fashion centres.

“There are so many talented designers in Toronto and in Vancouver and Montreal,” he said. “There’s a lot to offer.”

Mascarenhas pointed to the 2026 closure of Toronto Fashion Incubator as one example of the shrinking infrastructure surrounding emerging designers. He also contrasted the Canadian environment with markets such as New York, London and Paris, where fashion occupies a more established place within the broader creative economy.

For an emerging label, those structural issues eventually become practical business decisions: where to manufacture, how much to produce, how to finance inventory, which retailers to approach and how much can be spent acquiring customers. Demascaré is now working through each of those questions as it attempts to grow.

Building the Business Around What Made Demascaré Different

Mascarenhas has already learned what can happen when he tries to make his work look more conventionally commercial. His early attempt to simplify the product generated less enthusiasm because it also removed some of the identity that had attracted people to Demascaré in the first place.

The ready-to-wear strategy takes a different approach. Mascarenhas is trying to make the business around the clothing more scalable while retaining the qualities of the clothing itself.

That means developing repeatable fits, building a functioning e-commerce operation, maintaining limited production and finding retail partners capable of connecting Demascaré with the right customer. The company remains small, and considerable work lies ahead.

Mascarenhas has already demonstrated that his designs can attract attention. The next stage will determine whether Demascaré can turn that attention into a durable Canadian fashion business.

More from Retail Insider:

Aritzia’s Stronger Store Performance Supports Continued North American Expansion

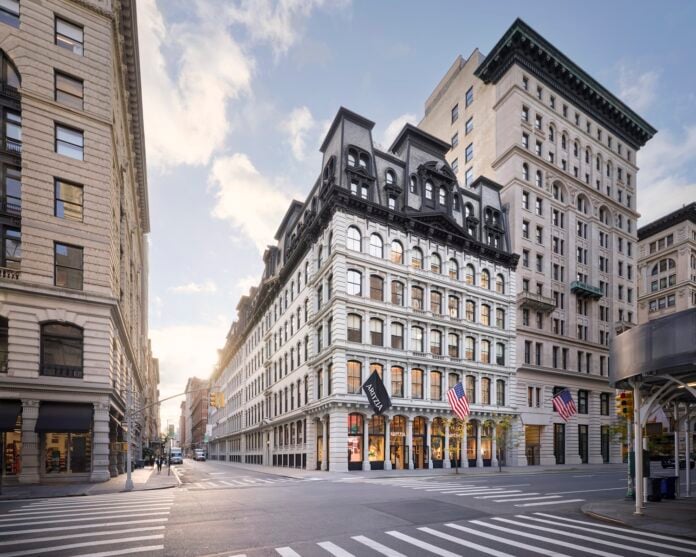
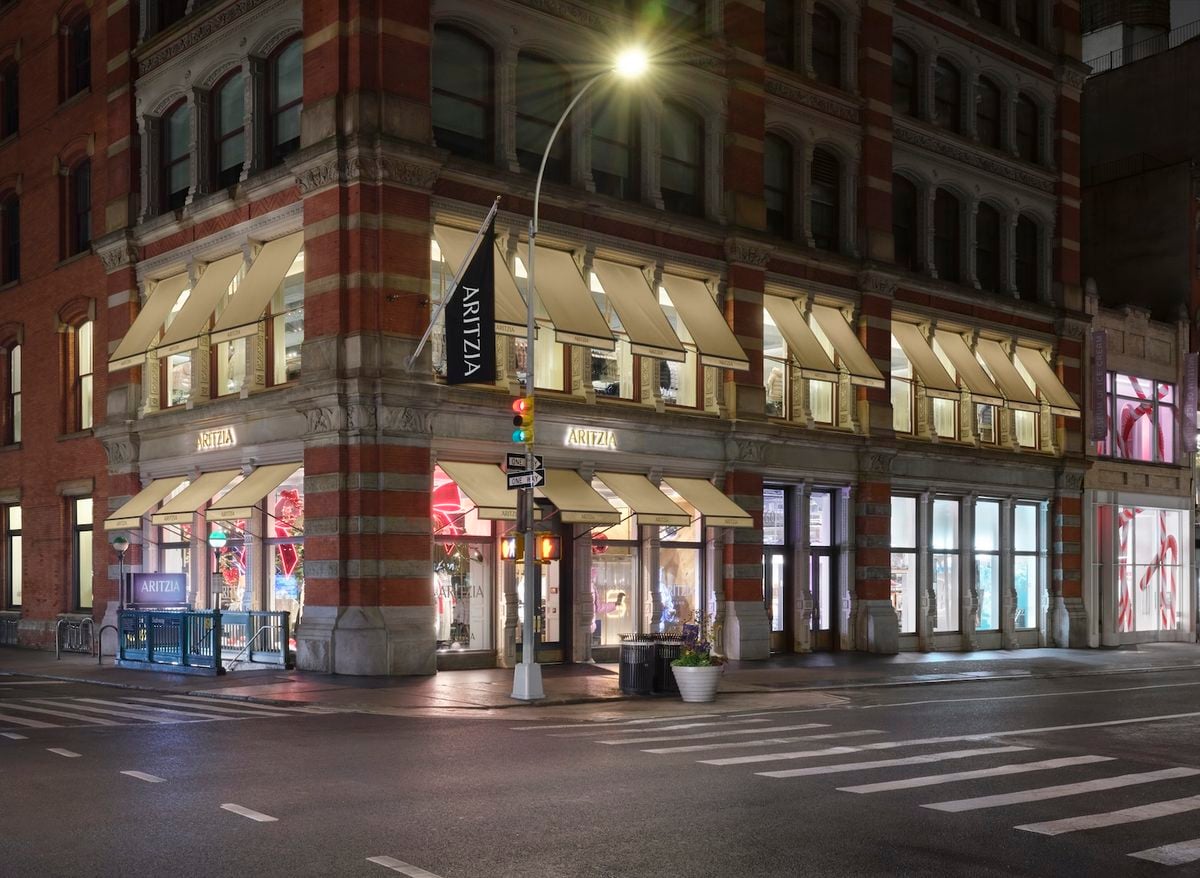
Aritzia flagship store in the Flatiron District in New York City. Image: Aritzia

Aritzia‘s rapid digital growth has not diminished the importance of its physical stores. The Vancouver-based fashion retailer is reporting stronger customer traffic and improving boutique productivity as it continues opening and repositioning locations across North America, providing fresh evidence of the role physical retail plays in its expanding business.

During its second-quarter fiscal 2027 earnings call on October 8, Aritzia executives outlined how stronger sales at existing boutiques, improved performance from newer locations and investments in larger store formats are supporting the company’s growth. Management also detailed upcoming openings in several U.S. states and planned repositionings in Quebec and California.

The results come as Aritzia continues investing in its physical network while expanding its digital business. For shopping centre landlords and commercial real estate professionals, the company’s performance provides insight into how stronger store productivity can support additional retail investment, even as consumer shopping habits evolve.

Higher Traffic Strengthens Boutique Productivity

Aritzia reported revenue of approximately $1.17 billion in the second quarter, an increase of 44.1% year over year, while comparable sales rose approximately 35%. Management indicated that the comparable sales increase was driven primarily by customer traffic rather than higher average transaction values, suggesting that more shoppers are contributing to the company’s growth.

Retail revenue increased 34.1% to approximately $766.9 million, reflecting strong performance across the existing boutique network and contributions from new locations.

One of the more significant developments is the performance of recently opened stores. Management indicated during the earnings call that boutiques opened in fiscal 2026 are generating higher sales per square foot than earlier groups of openings and are progressing toward faster investment payback periods.

The trend is particularly relevant to the economics of retail expansion. Higher sales volumes allow retailers to spread occupancy and other fixed operating costs across a larger revenue base, potentially improving profitability without requiring a proportional increase in operating expenses.

For landlords, improving store productivity provides additional context for Aritzia’s continued investment in physical space. The company is not simply expanding its network; its latest results indicate that newer boutiques are also delivering stronger productivity than earlier locations.

Aritzia store at Plaza Frontenac in St. Louis. Image: Aritzia

Expansion Includes New U.S. Markets and Canadian Repositioning

Aritzia expects to open approximately 12 to 13 new boutiques and reposition another four to five locations during fiscal 2027, maintaining an active real estate development program as it expands its North American presence.

The United States remains the primary focus for new-store growth. During the second quarter, Aritzia entered Birmingham, Alabama; New Orleans, Louisiana; and St. Louis, Missouri, extending its reach into additional metropolitan markets.

The company plans six new U.S. boutique openings during the third quarter, including two in Texas and one each in Florida, Georgia, Massachusetts and Nevada. The projects reflect continued investment in both new markets and the broader development of Aritzia’s American store network.

Alongside these openings, management confirmed plans to reposition two existing boutiques during the quarter, including one in California and another in Quebec.

Repositioning is an important component of Aritzia’s broader strategy, allowing the company to improve its existing retail network rather than relying exclusively on new-store development. Depending on the individual project, such investments can involve changes in location, store configuration or format.

At the end of the second quarter, Aritzia operated 146 boutiques across North America, including 79 in the United States and 67 in Canada. Chief executive officer Jennifer Wong indicated during the October 8 earnings call that the U.S. count had subsequently increased to 82.

The growing American network is gradually shifting the geographic balance of Aritzia’s portfolio, while the company’s established Canadian locations continue to generate substantial sales.

Aritzia flagship store in the Soho District in New York City. Image: Aritzia

Larger Stores Reflect Changing Retail Requirements

Aritzia’s real estate strategy has increasingly emphasized larger boutiques capable of accommodating greater customer traffic and a broader merchandise assortment.

During the earnings call, Wong discussed how the company’s approach to boutique sizing has evolved. Earlier locations were commonly approximately 6,000 square feet, while subsequent formats increased to around 8,000 and then 10,000 square feet. Some of the company’s largest flagship stores now exceed 30,000 square feet.

The additional space supports merchandise presentation, fitting-room capacity and the ability to accommodate higher shopping volumes. These considerations are particularly important for a retailer with a broad assortment of exclusive apparel brands and a business model that places significant emphasis on the in-store experience.

Aritzia’s shift toward larger formats has been underway for several years, but the latest operating results provide additional evidence about the performance of its physical retail investments. Management’s comments about stronger sales per square foot at newer boutiques suggest that its store development strategy is being accompanied by improvements in productivity.

Aritzia store at Plaza Frontenac in St. Louis. Image: Aritzia

Digital Growth Continues Alongside Physical Retail

Aritzia’s digital business is expanding even faster than its physical retail operations. E-commerce revenue increased approximately 68% to $402.9 million during the second quarter, representing roughly 34% of total revenue.

The company has continued investing in its digital platform, including a mobile shopping application launched in October 2025. Management reported that the app has surpassed 2.5 million downloads, supporting customer engagement and the company’s broader online strategy.

Despite the rapid increase in digital sales, Aritzia’s physical boutiques continue to generate strong growth. Wong indicated during the earnings call that management has not observed evidence of online sales cannibalizing the performance of its stores.

The results suggest that Aritzia is benefiting from demand across both channels, although the company has not quantified how much digital activity directly influences physical store purchases or vice versa.

Aritzia store Lakeside Centre in New Orleans. Image: Aritzia

Canadian Market Remains an Important Growth Contributor

Although most of Aritzia’s new-store development is concentrated in the United States, the Canadian business continues to perform strongly.

Revenue in Canada increased approximately 20% year over year to $390 million during the second quarter, a notable result for a retailer with an established domestic presence.

The performance is particularly significant given the affordability pressures facing Canadian consumers and the challenges affecting discretionary retail spending. Aritzia’s traffic-driven growth indicates that the company continues attracting customer demand in its home market.

The Canadian results are also relevant to the company’s real estate strategy. While opportunities for opening entirely new boutiques may be more extensive in the United States, Aritzia’s established domestic network remains an important contributor to revenue and provides opportunities for continued investment in existing locations.

The planned Quebec repositioning reflects that ongoing investment in the Canadian market, even as the company directs much of its new-store development south of the border.

Aritzia is also investing in merchandise planning, distribution infrastructure, technology and other operational capabilities intended to support its growing business. These investments will become increasingly important as the company expands into additional markets and manages a larger retail network.

Aritzia store Lakeside Centre in New Orleans. Image: Aritzia

Next Phase of Expansion

Aritzia’s recent performance provides a strong foundation for its continued North American expansion, although maintaining the current pace of growth will become increasingly challenging as the company compares results against exceptionally strong prior periods.

The company must also sustain boutique productivity as it enters additional markets, manages larger store formats and continues investing in its existing network. Strong performance from recent openings is encouraging, but future results will depend on customer demand, operating costs and execution across individual locations.

Aritzia is scheduled to hold an Investor Day on October 27, when management is expected to outline its longer-term strategic priorities. The presentation may provide additional insight into the retailer’s future market expansion, boutique development and investment requirements as it enters its next phase of growth.

More from Retail Insider:

Bento launches Nashville hot chicken sushi roll across Canada

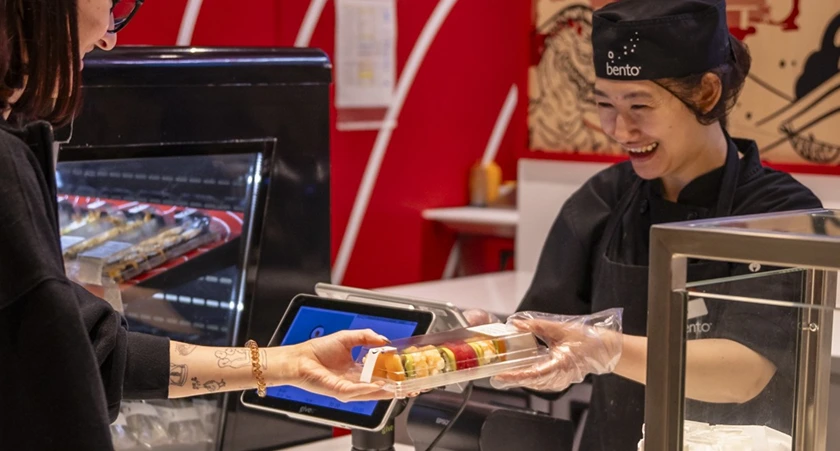
Bento photo
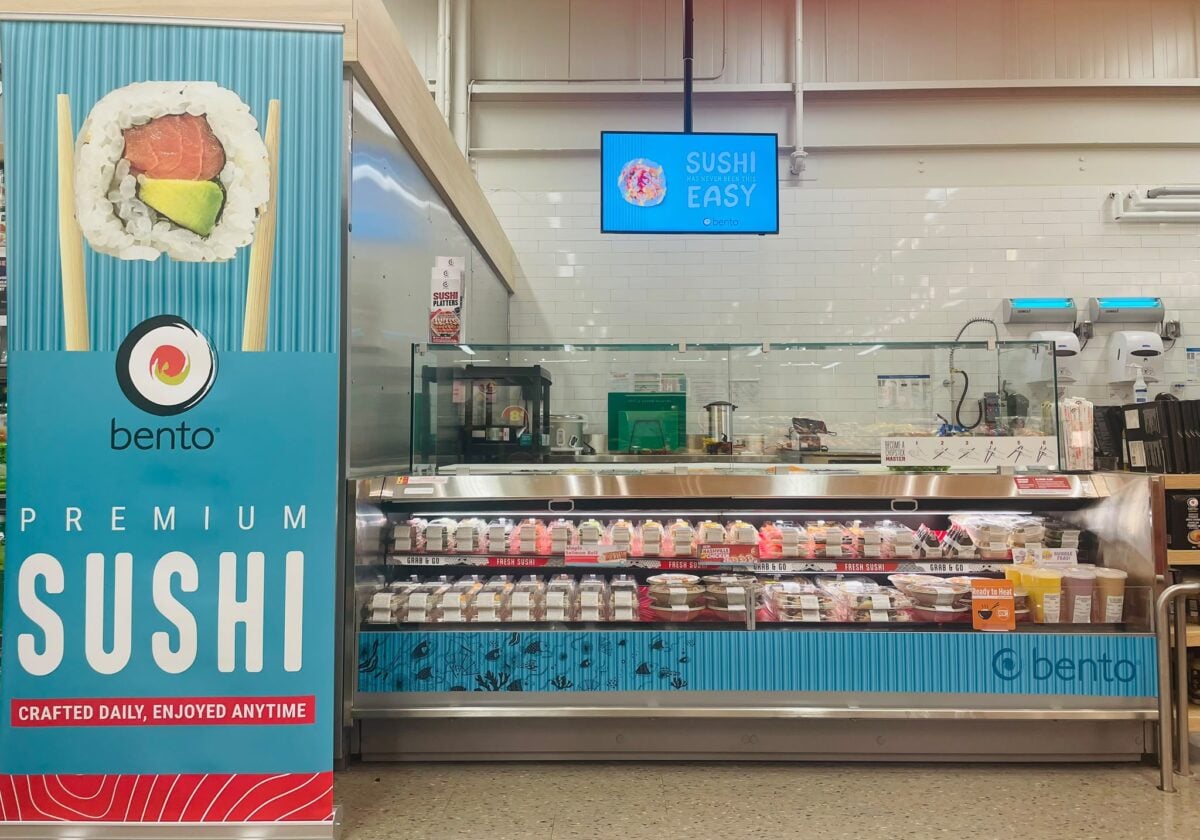
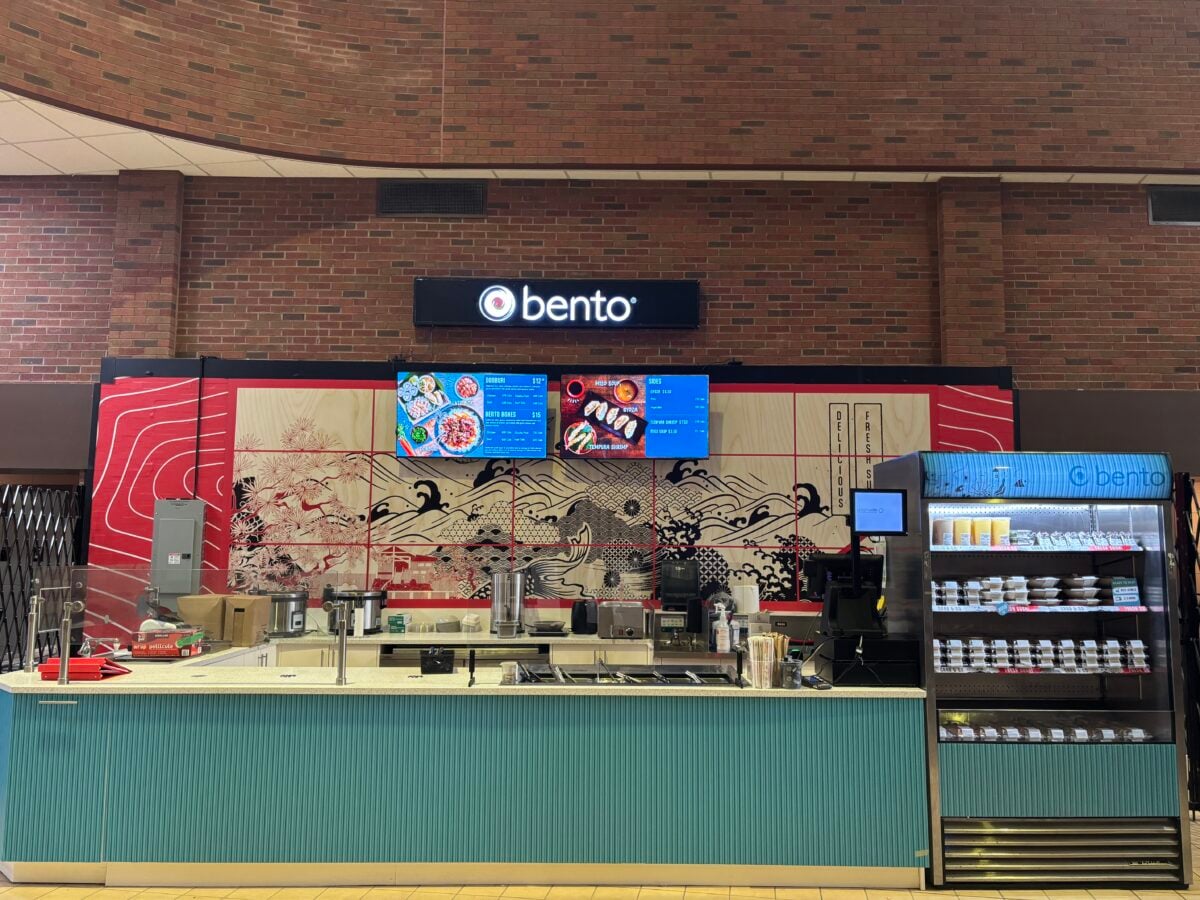
Bento photo

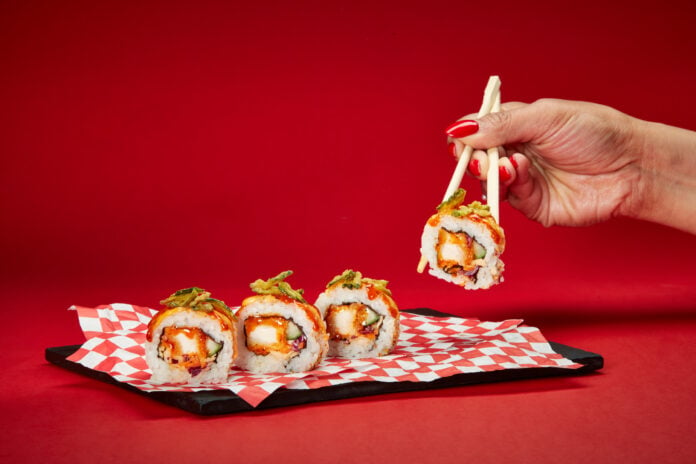
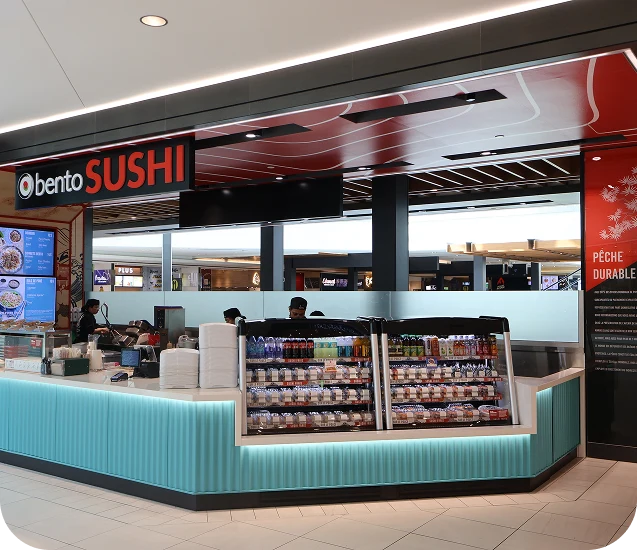
Bento has launched a Nashville hot chicken sushi roll across Canada, adding a new product to its lineup as the company marks its 30th anniversary.

The Nashville Hot Chicken Roll is available starting at participating grocery, retail and higher education locations, with prices ranging from $13 to $15, depending on the region and product variation.

The Toronto-based company’s latest offering combines crispy Nashville hot chicken katsu with seasoned sushi rice, dill pickles, coleslaw, fried pickle chips, Nashville hot sauce and Nashville spicy mayonnaise.

New product builds on anniversary launches

The roll combines ingredients associated with Nashville hot chicken with a sushi format, incorporating green and red cabbage and carrots into a creamy coleslaw blend. House-made dill pickles and crispy fried pickle chips add a tangy element to the product, which is finished with two sauces.

Bento said the launch draws on the popularity of Nashville hot chicken and consumer interest in familiar foods presented in new formats. The company is continuing to introduce products that offer different flavour combinations and formats for grab-and-go customers.

“The Nashville Hot Chicken Roll takes something familiar and completely reimagines it in a Bento way,” said Dave Jones, president and CEO of Bento. “It’s unexpected, indulgent, and a great example of how we continue to push the boundaries of what sushi can be.”

The product is the latest addition to a series of launches during the company’s 30th anniversary year. Other introductions include what Bento describes as Canada’s first grab-and-go scallop sushi lineup and the Maple Salmon Sushi Roll, which was launched for the summer and features Canadian flavours.

The new roll continues the company’s efforts to expand its product offerings with combinations that bring together different food categories.

Roll to reach major Canadian retailers

The Nashville Hot Chicken Roll will be sold at participating Bento locations across Canada, including grocery stores, retail outlets and higher education locations.

Participating retail banners include Loblaw Cos. Ltd.’s Loblaws, Real Canadian Superstore and Zehrs stores, as well as Metro, Longo’s, Walmart and Sobeys locations in Atlantic Canada. The product will also be available through other participating retailers.

The announced price range of $13 to $15 reflects regional and product-specific variations. Bento did not provide further details about expected sales, distribution volumes or financial targets associated with the launch.

The company said it continues to explore new flavours and formats aimed at grab-and-go consumers as it expands its product lineup.

Bento also recently expanded its retail footprint with the launch of its onigiri at Costco stores across Canada, bringing the popular Japanese grab-and-go staple to a much broader audience. The launch reflects growing consumer interest in convenient, globally inspired foods and builds on Bento’s experience making sushi and other Japanese-inspired offerings accessible beyond traditional restaurant settings. Following the success in Canada, they are now launching across Costco in the US.

Inspiration behind the Nashville Hot Chicken Roll

Jim Olynick, Product Development Manager, Bento Sushi, said the Nashville Hot Chicken Roll was inspired by several converging consumer trends, including the continued popularity of spicy flavours, fried chicken and “swicy” combinations that balance heat and sweetness. 

“Nashville Hot Chicken gave us a recognizable, high-demand flavour profile that could translate naturally into sushi. It also gave us an opportunity to reach consumers who may be hesitant about traditional sushi or raw seafood. By pairing a familiar cooked protein and flavour profile with the sushi format, we can broaden the category’s appeal while continuing to bring globally inspired innovation to grab-and-go food. Grocery is particularly suited to this type of innovation because consumers are often making quick, low-risk purchase decisions based on recognizable flavours,” he said.

As Bento marks its 30th anniversary, the Nashville Hot Chicken Roll reflects how the brand has been evolving the business while staying true to what has always driven it: making sushi accessible, convenient and appealing to a broad range of consumers, explained Olynick.

“It takes a familiar, restaurant-inspired flavour and brings it into the sushi category in a way that feels approachable but still new. Looking ahead, we see significant opportunity to keep expanding what sushi can be by drawing on broader food trends, global flavours and changing consumer tastes. Nashville Hot Chicken is a good example of how we can use 30 years of sushi expertise to bring new consumers into the category and create the next generation of Bento products,” he said. 

Plans for growth

Andrew Siu, EVP Commissaries, said the company’s current footprint is 17 retail locations across Canada. 

“In recent years, we have moved to a fully franchised model and have seen lots of growth in grocery and higher education (campuses). We also underwent a brand refresh, focusing on tightening brand presence and consistent customer experience,” he said. 

The response to our Costco launch in Canada has been extremely strong. We introduced our first onigiri product at the end of May through Costco, and it quickly demonstrated that there is significant demand for convenient, handheld Japanese food beyond traditional sushi. Importantly, the product has been incremental to our existing sushi business rather than replacing those sales, which gives us confidence that onigiri can become a meaningful new growth platform for Bento.

“That success generated interest from Costco regions across the U.S., allowing us to accelerate what would normally be a four-to-six-month rollout into roughly three months. We launched in California and the Midwest in early September and have seen similarly encouraging early results, with additional U.S. regions expected to follow.

“The U.S. expansion also required us to think differently about scale. We invested in specialized onigiri equipment from Fujiseiki, adapted recipes for the market and expanded production capabilities to support significantly higher volumes. It is a good example of how Bento can take a product that works in one market, adapt it quickly and build the operational capacity to scale it across North America.”

Siu said consumers are increasingly looking for convenient, high-quality grab-and-go foods with global flavours, and Bento has the culinary expertise, production infrastructure and retail partnerships to play a much larger role in that space. 

“We see significant opportunity to bring products like onigiri to additional retail partners while continuing to explore new Asian-inspired formats, flavours and occasions,” he said.

“For us, the bigger takeaway is that Bento’s growth does not have to be limited to sushi. We believe we can become a broader leader in Asian food innovation and bring new, convenient products to consumers wherever they are looking for fresh grab-and-go food.”

More from Retail Insider:

Bento photo
Bento photo

Couche-Tard to acquire Irving Oil retail assets in Quebec, Ontario

Circle K store/ Couche Tard. Photo: Yonge + St. Clair

Alimentation Couche-Tard Inc. has agreed to acquire retail assets from Irving Oil in Quebec and Ontario, including 52 retail sites already operated by Couche-Tard and fuel supply arrangements covering another 71 locations in Quebec.

The agreement expands Couche-Tard’s ownership of retail assets in the two provinces and adds 18 cardlock sites to the transaction, while maintaining service for existing Irving Oil fleet customers under a long-term agreement. No financial details were disclosed.

The Laval, Que.-based company said transaction remains subject to customary closing conditions and regulatory approvals, including under the Competition Act.

Transaction includes retail sites and fuel supply

The acquisition covers 50 retail sites already operated by Couche-Tard under the Quebec Alliance between the two companies, along with two locations in Pembroke and Cornwall, Ont., that are also currently operated by Couche-Tard.

The agreement also includes fuel supply to 71 retail sites in Quebec that are owned and operated by Couche-Tard. The news release did not disclose the financial terms of the transaction or provide a timeline for its completion.

The deal includes 18 cardlock sites, consisting of 16 in Quebec and two in Ontario. Cardlock facilities provide fuel access for commercial and fleet customers. Of the 18 sites, 16 are co-located with retail locations included in the transaction, while the other two are adjacent to sites already owned and operated by Couche-Tard.

Existing Irving Oil fleet customers will continue to receive service at these locations under a long-term agreement between the companies, according to the announcement.

Couche-Tard cites existing relationship

Couche-Tard said its established relationship with Irving Oil and its experience operating the locations were factors in the agreement.

“This agreement builds on our longstanding relationship with Irving Oil and our experience operating these locations,” said Stéphane Trudel, senior vice-president of operations at Alimentation Couche-Tard.

“These are markets and customers we know well. The transaction would support our continued investment in the everyday convenience experience we offer our customers.”

The announcement does not specify whether the acquisition will result in changes to branding, staffing or day-to-day operations at the affected locations.

Global convenience store operations

Couche-Tard operates in 27 countries and territories, with more than 17,200 stores worldwide, approximately 13,100 of which offer road transportation fuel.

The company operates under the Couche-Tard and Circle K banners and is one of the largest independent convenience store operators in the United States. It also operates in Canada, Scandinavia, the Baltic states, Belgium and Ireland, with additional operations in Luxembourg, Germany, the Netherlands, Poland and Hong Kong Special Administrative Region of the People’s Republic of China.

Approximately 145,000 people are employed across its network, according to the company.

More from Retail Insider:

Employment falls for 2nd straight month, 68,000 jobs lost in September: Statistics Canada

Ron Lach photo
Ron Lach photo

Employment declined by 68,000 (-0.3%) in September and the employment rate fell 0.2 percentage points to 60.6%. The unemployment rate increased 0.1 percentage points to 6.5%. The employment decline was concentrated among youth aged 15 to 24 (-48,000; -1.8%) as well as women aged 25 to 54 (-28,000; -0.4%), reported Statistics Canada on Friday.

There were fewer people working in educational services (-35,000; -2.2%), health care and social assistance (-23,000; -0.8%) as well as manufacturing (-13,000; -0.7%). There were more people working in ‘other services’ (+17,000; +2.1%), which includes repair and maintenance as well as personal or household services, said the federal agency.

The wholesale and retail trade sector lost 9,600 positions while accommodation and food services grew by 1,000.

“In September, employment declined by 68,000 (-0.3%), split between full-time work (-35,000; -0.2%) and part-time work (-33,000; -0.9%). The employment decline in September follows a decrease in August (-42,000; -0.2%),” it said.

Prior to these two consecutive monthly declines, employment had trended up from April to July (+181,000; +0.9%). On a year-over-year basis, employment was up by 95,000 (+0.5%) in September.


MART PRODUCTION photo

“The employment rate—the proportion of the population aged 15 and older who are employed—decreased by 0.2 percentage points to 60.6% in September, marking a second consecutive monthly decrease. On a year-over-year basis, the employment rate in September was unchanged.”

Earlier in the year, the unemployment rate reached a recent peak of 6.9% in April, before declining to 6.4% in July and August. The unemployment rate in September was the same as it was at the start of the year (6.5% in January), noted Statistics Canada.

“The layoff rate—representing the proportion of people who were employed in August but had become unemployed in September as a result of a layoff—was 0.7%, similar to the rate observed a year earlier (0.6%) and the average during the period from 2017 to 2019 (0.6%) (not seasonally adjusted). The job-finding rate was 30.6% in September, down from 32.8% 12 months earlier and below the average of 36.5% during the period from 2017 to 2019. This refers to the proportion of people who were unemployed in August and had found a job in September,” it said.

“The labour force participation rate—the proportion of the population aged 15 and older who were employed or looking for work—fell 0.2 percentage points to 64.8% in September. This was the lowest level since December 1997 (when it was also 64.8%), excluding 2020 during the COVID-19 pandemic. On a year-over-year basis, the participation rate was down 0.4 percentage points in September 2026, largely the result of population aging.”

Analyst thoughts on the numbers

Andrew Grantham, Senior Economist, CIBC Capital Markets, said: “Canadian employment slumped again in September, with the unemployment rate ticking up slightly as new US tariffs took hold. The 68K decline in employment was in stark contrast to consensus expectations for a modest 10K rebound, and followed a 42K drop in the prior month as well. Data volatility appears to have been the main cause of the decline, with a 35K reduction seen in education services which often exhibits volatility around the start of new school years. However, the 13K decline in manufacturing employment could be a sign that new US tariffs are taking a toll. Through the monthly volatility, the 6-month average employment growth now sits at just 9K. The unemployment rate ticked up to 6.5%, which was in line with the consensus forecast and was prevented from rising further by a reduction in the participation rate. Wage growth for permanent employees remained only modest at 2.3%, despite accelerating slightly from 2.0% in the prior month. Overall, while the weakness in today’s employment data is likely more a reflection of data volatility than the impact of new US tariffs, it does support our call that the Bank of Canada will remain patient and keep interest rates on hold at the two remaining meetings this year.”

Andrew Hencic, Director & Senior Economist, TD Economics, said: “The labour market has now taken a breather for two consecutive months. The top line job losses are disappointing, but the focus should be on the unemployment rate. An uptick in September brings it back to where it was in June. We expect it to tread water in the coming months, as trade frictions and higher rates weigh on activity. One positive takeaway from this morning’s report was that private sector employment held steady, despite a decline in the labour force. 

“Ultimately, this report is going to pour some more cold water on near-term rate hike expectations for the BoC. Markets are currently pricing 27% odds of a hike in October, and 88% for December, the latter down from being fully priced yesterday. We maintain the view that inflationary pressures are still relatively contained with average wage growth running at 2.4% and economic growth likely to slow further in Q4 as new tariffs weigh on activity. Given this backdrop we expect the BoC to remain data-dependent and stay on hold in October.” 

Douglas Porter, Managing Director, Chief Economist, said: “A second consecutive month of sizable job losses washes away the surprising strength reported in Canada’s job market through the early summer, and leaves employment up a so-so 0.5% from a year ago. While the large drop in education looks somewhat suspect (especially since it was entirely in one province), the underlying picture in other regions and industries does not inspire confidence. The pullback in manufacturing may be an early warning of the weight from the amped-up trade tussle. On balance, we continue to believe that the appropriate stance by the Bank of Canada is watchful waiting, particularly so with employment suddenly clouding over. The key CPI and Business Outlook Survey are both due on October 19, but this sour result greatly diminishes the chances (let alone the rationale) for rate hikes.”

Claire Fan, Senior Economist, RBC Economics, said: “Canada’s labour market lost 68,000 jobs in September, driven by losses in public sectors (education and health care), piling onto the 42,000-job loss in the prior month. These losses reversed most of the job growth seen over the summer and leave the year-to-date employment count at -41,000.

“The monthly employment counts are notoriously volatile, and there are reasons not to read too much into the softer reading too quickly. In September, 70%, or 48,000, of the decline in employment was among those aged 15 to 24, a group that typically sees seasonal headwinds around this time of year after the school year starts. The unemployment rate, as a more stable and reliable gauge of labour market conditions, ticked up slightly from 6.4% to 6.5% but remained 0.6 percentage points below a year ago.

“Looking ahead, we continue to point to important leading indicators such as job openings from Indeed.com as indications that hiring demand has not retreated to a problematic extent since new U.S. tariffs (that cover a small scope of Canadian exports) were imposed. We expect progress made in Canada’s labour market earlier will be largely sustained, and the unemployment rate to broadly edge lower through the end of 2026.”

More from Retail Insider:

Canadians plan to spend less this holiday season but favour domestic products: PwC

Gustavo Fring photo
Gustavo Fring photo

Canadians plan to cut holiday spending by 11 per cent this year, but more than half are willing to pay extra for Canadian-made products as trade tensions with the United States influence shopping decisions, according to a new PwC Canada survey.

The accounting and consulting firm’s 2026 Canadian holiday outlook found that consumers expect to spend an average of $1,487 during the holiday season, down from the previous year, while 54 per cent would choose a more expensive Canadian-made product over a similar imported alternative, up from 49 per cent in 2025.

The findings suggest retailers face a combination of tighter household budgets and growing interest in domestic products, creating pressure to offer affordable options while making the Canadian origin of merchandise clear to shoppers. The survey also points to increased interest in artificial intelligence tools for shopping, although physical stores remain the leading purchasing channel.

“Canadians are cutting back, but they’re drawing a hard line on where their money goes,” said Adam Boutros, partner and national consumer markets leader at PwC Canada. “More of them than ever want their money to stay in Canada–and older Canadians are making that choice especially clear: even as they plan some of the steepest spending cuts, two-thirds of baby boomers are still willing to pay more for Canadian-made products.”

Vitaly Gariev photo
Vitaly Gariev photo

Canadian-made products gain ground

The survey found that 72 per cent of Canadians are actively looking for alternatives to U.S.-made products, while just 13 per cent intend to shop across the border this holiday season, down from 20 per cent in 2024.

Baby boomers showed particularly strong support for domestic products, with 66 per cent saying they would pay more for Canadian-made goods despite plans to reduce their overall holiday spending.

However, consumers remain focused on affordability. About 69 per cent said they plan to buy less expensive alternatives to stretch their holiday budgets, while three-quarters reported taking steps to manage seasonal spending.

The survey was conducted in July and early August, before the latest round of tariff escalations. PwC said the results may therefore understate the current level of Canadian sentiment toward domestic products.

For retailers, the findings point to the importance of communicating whether products are made, assembled or designed in Canada while keeping prices accessible.

“Canadian consumers are making more deliberate purchasing decisions than they have in years, with more than half looking to support Canadian businesses and products–giving retailers an opportunity to respond to a renewed ‘Canada strong’ sentiment,” said Anita McOuat, national managing partner, clients and industries at PwC Canada. “Retailers have an opportunity to leverage technology like AI and other digital tools to make Canadian-made products easier to discover, offer personalized recommendations, and clearly communicate value–turning this moment into lasting loyalty.”

Spending cuts vary by generation

The expected decline in holiday spending is not consistent across age groups, with older Canadians planning the largest reductions and Gen Z anticipating an increase.

Planned spending is down 21 per cent among Generation X consumers and 18 per cent among baby boomers compared with last year. Gen Z, by contrast, expects to spend 8 per cent more.

Households with children are also expected to remain an important source of holiday spending. They plan to spend nearly twice as much as households without children and are more likely to give screen-free, hands-on activities and experiences to both children and adults.

The findings indicate that retailers will need to account for differences in spending intentions among consumer groups as they approach the holiday season, with value remaining a priority for many households.

Andrea Piacquadio photo

AI use increases as stores remain central

The survey found that 28 per cent of Canadians expect to use artificial intelligence at some point during their holiday shopping, up from 17 per cent last year.

Consumers expect to use AI-powered tools to research products, compare items, find gift ideas and, in some cases, make purchases. Despite the increase in planned digital tool use, physical stores remain the leading purchasing channel across all generations.

About 40 per cent of respondents said they intend to use both online and in-store channels when making purchases, suggesting retailers will continue to need to accommodate shoppers across multiple platforms.

Regional spending intentions differ

British Columbia is expected to record the highest average holiday spending at $1,639, followed by Ontario at $1,567 and Quebec at $1,497.

Consumers in Atlantic Canada plan to spend an average of $1,349, while those in Alberta, Manitoba and Saskatchewan expect to spend $1,261.

Quebec was the only region where planned spending showed no notable year-over-year change, according to PwC.

In an interview with Retail Insider, Elisa Swern, Partner, Consumer Markets Advisory Leader, Canada & APA, PwC Canada, spoke about the survey results.

What does the research reveal about the growing willingness of Canadians to pay more for Canadian-made products, particularly at a time when overall holiday spending is declining?

What we’re seeing this year is a clear ‘elbows up’ sentiment among Canadian shoppers. Even though average holiday spending is projected to decline by 11%, patriotism is playing a major role in where those dollars go. More than half of Canadian consumers (54%) say they are willing to pay more for a Canadian-made product over a comparable alternative, up from 49% last year. What’s particularly fascinating is that this trend is being led by older generations. Baby boomers are pulling back their total spending by 18%, yet two-thirds (66%) of boomers say they’ll pay a premium for Canadian-made goods. It demonstrates that while Canadians are cutting back on overall volume, they are intentional about spending their remaining budget on values that matter to them.

How should retailers respond to the 72 per cent of consumers who are actively seeking alternatives to U.S.-made products, and how important is it for businesses to clearly communicate where products are made, assembled or designed?

With 72% of Canadian consumers actively looking for alternatives to U.S.-made products during their holiday shopping, transparent origin storytelling is becoming increasingly important for retailers. Retailers need to make it effortless for shoppers to identify product origins across all touchpoints. Whether an item is made, assembled, or designed in Canada, that story needs to be front and centre on shelf signage, e-commerce filters, and product packaging. Beyond messaging, retailers must look at their product assortment now to ensure they can sustainably maintain a healthy balance of Canadian alternatives in store at price points that consumers can justify.

With 69 per cent of Canadians planning to purchase less expensive alternatives and average holiday spending expected to fall 11 per cent, how can retailers balance consumers’ desire to buy Canadian with their increasing focus on affordability?

It’s a delicate tightrope for retailers. On one hand, 69% of shoppers plan to buy less expensive alternatives; on the other, over half are willing to pay extra for Canadian products. The key for retailers is to compete on value, not just price. Shoppers don’t necessarily want cheap products—they want smart spending choices. Retailers can balance this by being tactical with promotional timing. For instance, holding dedicated promotional windows for Canadian items during peak shopping periods helps ease the price burden. Retailers should also highlight the long-term value of Canadian-made goods—such as quality, durability, and supporting local communities—so consumers feel confident that their money is well spent.

What do the generational differences in the survey — particularly the spending pullback among Gen X and baby boomers versus increased spending among Gen Z — tell us about how retailers should approach different consumer groups this holiday season?

The generational split highlights a real shift in where holiday momentum is coming from. Older cohorts are tightening their belts significantly—Gen X plans to spend 21% less, and Boomers 18% less. Meanwhile, Gen Z is the only group planning to increase spending (+8%), and millennial households—especially those with children—are driving the highest overall volume. Retailers need a dual strategy: For Baby Boomers & Gen X: Focus on timing and value. More than 43% of Boomers plan to delay their shopping into December, and they care deeply about Canadian-made goods. Target them with late-season, in-store promotions featuring local products. For Millennials & Gen Z: Capture them early. 38% of Gen Z and 33% of millennials plan to concentrate their shopping around Black Friday weekend. They are looking for experiences, screen-free activities for young families, and frictionless, AI-ready shopping channels.

With AI use in holiday shopping rising to 28 per cent while physical stores remain the leading purchasing channel, how do you see AI changing the retail shopping journey, and what should retailers be doing now to adapt?

A: AI usage has jumped significantly from 17% to 28% this year, but physical retail isn’t going anywhere. 74% of Canadians still prioritize in-person shopping. What we’re witnessing is the beginning of ‘agentic commerce,’ where AI tools increasingly remove friction for shoppers by finding products, organizing information from different retailers, and presenting the lowest-cost options, before a consumer ever steps into a store. To prepare, retailers need to ensure their product data, rich content, and pricing strategies are ‘AI-ready.’ If your product information isn’t structured so large language models can easily parse and recommend it, you risk being filtered out before the customer even walks through your doors.

More from Retail Insider:

Maybelline expands mental health campaign to focus on support networks (Video)

Maybelline image
Maybelline image

Maybelline New York has launched a new campaign focused on the role of family and friends in supporting people experiencing mental health challenges, expanding its global Brave Together program ahead of World Mental Health Day on Oct. 10.

The campaign, called “Together We’re Brave,” builds on a program that has helped more than four million people worldwide access free one-to-one support since its launch in 2020. The initiative aims to encourage people to recognize the needs of loved ones experiencing anxiety, depression and other mental health challenges, while also helping those providing support understand how they can assist.

Campaign broadens mental health focus

The new campaign features stories involving mothers and daughters, best friends and other pairs, emphasizing the importance of personal connections during mental health challenges. Maybelline said the initiative is intended to help people who want to support someone but may be uncertain about how to approach the situation.

The company is positioning the campaign around the idea that mental health challenges can affect not only the person experiencing them but also their support network. It aims to encourage open conversations and help people recognize when to seek assistance for themselves or someone they care about.

“At Maybelline New York, we know that mental health journeys are rarely traveled alone,” said Sandrine Jolly, Global Brand President, Maybelline New York. “With ‘Together We’re Brave,’ we’re expanding the conversation around mental health to also recognize the people who stand beside us during life’s most challenging moments. By sharing these stories, we hope to inspire more open conversations and remind people that it is brave to reach out, whether for yourself or someone you care about.”

The launch represents another component of the company’s broader mental health initiative, which includes partnerships with nonprofit organizations and funding for mental health programs in multiple countries.

Since 2020, Brave Together has supported partnerships with more than 45 nonprofit organizations across 37 countries and contributed nearly $10 million toward mental health initiatives globally, according to the company.

Maybelline said it intends to continue using the program to increase awareness, reduce stigma and help people access mental health support. The initiative provides one-to-one support, online educational resources and programming intended to encourage conversations about anxiety and depression.

Maybelline photo
Maybelline photo

Partnership with NAMI continues

As part of the latest campaign, Maybelline will continue working with the National Alliance on Mental Illness (NAMI) in the United States to raise awareness, expand access to resources and encourage discussions about mental health.

The partnership reflects the campaign’s emphasis on helping friends and family members respond when someone they care about is struggling, even when they are unsure what to say or do.

“When someone we care about is struggling, we may not always know the right thing to say – but showing up matters,” said Christine Crawford, M.D., chief medical officer at NAMI. “Listening without judgment, staying connected, and helping someone find support can make a real difference. Through our work with Maybelline New York and Brave Together, we’re reminding people that you don’t need to have all the answers to be there for someone you love.”

Maybelline introduced Brave Together in 2020 as a long-term program to support people experiencing anxiety and depression worldwide. The company has committed to donating $20 million over five years to global and local organizations through the initiative, according to its corporate information.

The program’s activities include one-to-one support, an online education hub and initiatives designed to reduce stigma surrounding mental health.

The “Together We’re Brave” campaign adds a focus on the people who provide informal support to those experiencing mental health challenges, encouraging them to stay connected and help loved ones find appropriate resources.

More information about Brave Together and access to free mental health resources is available at www.maybelline.com/bravetogether.

More from Retail Insider: