Home Blog Page 56

Wayfair expands Klarna payment options to Canadian shoppers

Wayfair photo
Wayfair photo

Wayfair is expanding its partnership with Klarna to offer Canadian customers the payment company’s full suite of flexible payment options, while eligible U.S. customers will gain access to ongoing 0 per cent APR financing for purchases of up to six months.

The expanded partnership covers Wayfair and its family of brands, including Joss & Main, AllModern and Birch Lane. Canadian shoppers will be able to pay for purchases in full, split payments into interest-free instalments or finance larger orders over time.

“Klarna has been a trusted partner in helping our customers shop with confidence, and renewing this relationship was an easy decision,” said Curtis Crawford, director at Wayfair. “Our customers are making meaningful investments in their homes, and giving them flexible, transparent payment options at checkout makes a real difference, and that’s exactly what this partnership delivers.”

Flexible financing extended across brands

The agreement gives eligible U.S. customers access to always-on 0 per cent APR financing for up to six months across Wayfair’s full family of brands. The company said the Canadian expansion marks the first time Klarna’s full range of flexible payment options will be available through Wayfair in Canada.

The payment options apply to home purchases ranging from furniture such as sofas, dining sets and bed frames to outdoor furniture. Customers in both countries can choose among different payment methods based on their purchase and payment preferences.

“Wayfair’s decision to renew and deepen this partnership speaks to the trust we’ve built together and the real demand we’re seeing for flexible payments for considered home purchases,” said David Sykes, chief commercial officer at Klarna. “Home essentials is one of our fastest-growing categories in North America, and having Wayfair’s full family of brands behind that momentum is a significant benefit for consumers in both markets.”

Klarna expands retail payment network

Klarna said it has more than 120 million active users globally and processes 3.8 million transactions per day. The company said more than 1.2 million retailers use its payment solutions.

Klarna offers payments online and in stores, as well as through Apple Pay and Google Pay. The company is listed on the New York Stock Exchange under the symbol KLAR.

Wayfair operates as an online retailer focused on home products, offering merchandise across furniture and other home categories through its family of brands.

More from Retail Insider:

Wayfair Launches Loyalty Program in Canada

Canada’s Furniture Market Still Trails U.S. Recovery, Wayfair Results Suggest

Calgary Retail Investment Hits $522 Million in H1 2026, Led by $154M Northland Village Sale

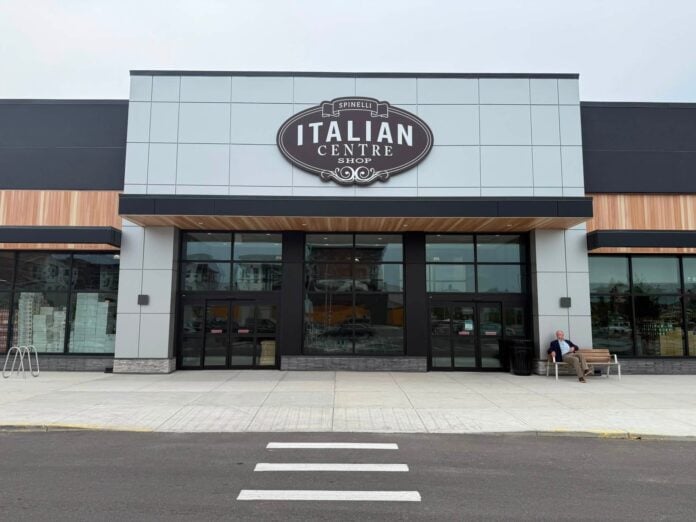
Calgary Italian Centre opened this summer in the Northland Village Mall. Mario Toneguzzi photo

Retail investment value was up in Calgary in the first half of 2026 thanks to one major transaction in the early part of the year, says the Greater Calgary investment report H1 2026 by Avison Young.

The commercial real estate firm in its report said total investment value in the retail sector for the first half of the year was $522.4 million, up 38% from the $378.8 million a year ago.

“While transaction activity moderated compared with previous years, several highvalue transactions supported retail investment volume in H1 2026. The $154M sale of Northland Village Mall stands as the sector’s largest transaction of the year to date. Investor demand remains strongest for neighbourhood and convenience-oriented retail centres, reflecting the continued appeal of necessity-based retail assets,” said the report.

GWL Realty Advisors purchased the Northland Village Mall from Primaris REIT.

Brennan Yadlowski, Managing Director, of Avison Young in Calgary, said investors are drawn to the combination of population growth in Calgary, limited available product, low vacancy, and rental growth. 

“Centres serving everyday needs – such as groceries, pharmacies, medical services, and personal services – benefit from repeat customer visits and are generally viewed as more resilient through economic cycles. For some buyers, a well-located site also offers longer-term potential for mixed-use or residential redevelopment,” he noted.

Yadlowski said Calgary’s total commercial real estate investment reached approximately $2.4 billion in the first half of 2026, up 28% from the same period in 2025. 

“Retail investment also rose, to approximately $522 million from $379 million (38%) . . . The H1 2026 results suggest the multi-year decline in overall investment volume may be nearing an end, rather than continuing at the same pace.”

Coming to the Northland Village Mall. Mario Toneguzzi photo

The Northland Village Mall sale demonstrates that there is a buyer pool for large, high-quality retail assets in Calgary,” said Yadlowski.

“Northland attracted interest from a broad range of buyers and ultimately sold to a Canadian institutional investor. The transaction shows that scale is not, by itself, a barrier when an asset has the location, tenant mix, and quality that investors are seeking,” he explained.

“In Calgary, we are seeing particularly strong interest in neighbourhood strip centres and grocery-anchored properties. Retailers that meet frequent, practical needs – from groceries and pharmacies to quick-service restaurants and personal services – help make these centres relevant to the communities around them. Calgary’s population growth adds to that appeal, while the limited supply of available investment product keeps competition for quality assets strong.”

Yadlowski said he is cautiously optimistic about Calgary. 

“Necessity- and convenience-oriented retail remains attractive, and the first-half investment figures give us a constructive starting point. That said, investors will continue to watch bond yields and financing costs closely. Those factors will influence pricing and the pace at which transactions come together, even where the underlying asset is strong,” he said.

More from Retail Insider:

EB Games opening North America’s first Nintendo store-within-a-store experience in Toronto

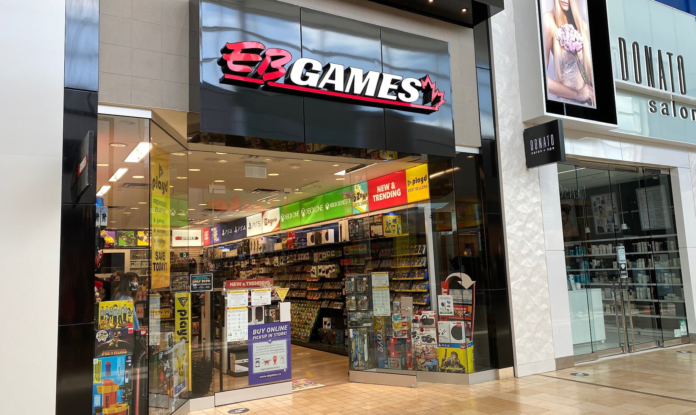
Former EB Games at Yorkdale in Toronto, September 2021. Photo: Dustin Fuhs

EB Games Canada says it will open a new Nintendo space at its flagship location at 267 Yonge Street in Toronto, marking Nintendo’s first store-within-a-store in North America.

The permanent, 1,500-square-foot space will bring Nintendo games, characters and worlds together in a dedicated retail environment and opens to the public at 10 a.m. on Saturday, October 17.

 “There’s something special about gathering around the games we love, and we believe physical retail has an important role to play in creating those moments,” said Stéphan Tétrault, Owner and CEO of EB Games Canada. “The Nintendo space at EB Games is exactly the kind of retail experience we want to bring to our customers – immersive, exciting and designed to bring people closer to their favourite characters and franchises.”

The new space will feature Nintendo Switch 2 hardware and software, playable games at demo systems, Nintendo-themed displays, merchandise and photo opportunities. The space will also offer a selection of My Mario merchandise, some of which will be available exclusively at the Nintendo space at EB Games in Canada.

EB Games said the offerings will create a one-of-a-kind destination for longtime Nintendo fans, families and anyone looking to discover what’s new from Nintendo.

“We’re always looking for new ways for people to experience Nintendo games and worlds,” said Susan Pennefather, Vice President and General Manager of Nintendo of Canada. “The Nintendo space at EB Games is an incredible place to explore what’s new, discover merchandise and celebrate our iconic characters. We’re proud to bring this concept to North America for the first time, right here in Toronto. We can’t wait to welcome people inside.”

EB Games has more than 170 stores across Canada.

More from Retail Insider:

Canadian Consumer Spending Tracks 2.6% Growth in Q3 as FIFA World Cup Provides Modest Boost: TD

MART PRODUCTION photo

Canadian consumer spending is tracking at a resilient 2.6% pace in Q3, even after stripping out the boost from higher gasoline prices. TD Spend data point to some moderation in services and a small contraction in goods spending following a strong Q2, according to a recent report.

“The World Cup left a visible but relatively small footprint on Canadian card spending. The clearest effects were concentrated on match days and in recreation & entertainment in the host provinces, alongside broader gains in general merchandise and travel. Overall, card spending data point to only a marginal boost from FIFA, although the total economic impact was likely somewhat larger given that spending by international visitors is not captured in our data,” said Maria Solovieva, TD Economist, who authored the report.

The report said goods spending moderated in Q3 following a strong Q2, with the necessities remaining the largest contributor. Housing-related spending recovered in Q2 and continued to grow in Q3 alongside a pick-up in housing activity. 

“The moderation is primarily driven by goods spending, which is currently tracking flat in Q3 following a 2.5% gain in Q2. Essential categories – which, apart from gas, include grocery stores, convenience stores and general merchandise retailers – remain the largest contributors to goods spending growth. However, their contribution has continued to moderate from earlier in the year, when necessities were the predominant driver of growth,” said the report.

“At the same time, consumers have continued to spend on home-related purchases, although at a more moderate pace than in Q2. This is consistent with the gradual improvement in Canada’s housing market. National home sales rebounded 6.9% q/q in Q2, following a 12.3% decline in Q1, and are currently on track to gain another 3.4% in Q3. As housing activity continues to grind higher, we expect it to provide some ongoing support to home-related outlays, even as the pace of spending growth moderates.”

June and July spending provided TD with a unique opportunity to examine outlays related to the FIFA World Cup. 

“Our data can be broken down by province and spending category, allowing us to compare Ontario and B.C. – the two host provinces – with the rest of Canada. We focused on categories we expected to be most affected, including recreation & entertainment, travel, grocery stores, and beer & liquor stores, among others. We looked at aggregate spending over the high-intensity period from June 5 to July 10, as well as spending specifically on match days,” explained the report.

“The overall impression is that Canada looked a little like the humble resting dragon from the famous FIFA meme – peacefully sleeping, seemingly unaware that it was hosting the World Cup. We estimate FIFA added around 0.1 percentage points to aggregate annual card spending growth. Across the selected categories, nationwide spending growth accelerated modestly, from 9.2% during the comparable period in 2025 to 10.0% in 2026, while growth slowed slightly when Ontario and B.C. were excluded. 

“Ontario saw only a limited acceleration during the period, while in  B.C., spending growth almost doubled from a year earlier, although this partly reflected the province’s underperformance in 2025.

Vitaly Gariev photo
Vitaly Gariev photo

“There are, however, signs that the Canadian dragon was paying attention. One was a notable acceleration in year-on-year (y/y) spending at general merchandise stores. This category includes warehouse clubs such as Costco, suggesting Canadians may have stocked up on favourite foods, drinks and other supplies ahead of the games. The acceleration was a national phenomenon, with provinces that did not host matches seeing a pickup similar to that in the host provinces. Spending growth in non-host provinces averaged 20% y/y, roughly twice the 10.4% pace during the comparable period in 2025. Ontario and B.C. outperformed, but only slightly.

“Digging deeper, it becomes clear that match days kept the dragon awake. Spending growth strengthened more meaningfully on days when Canada hosted matches, with a similar, though smaller, pattern visible at grocery stores and beer, wine & liquor stores. 

“So, was there a host premium at all? Yes – most clearly in recreation & entertainment. As fans filled stadiums, bars and other venues, spending in both host provinces received a boost, helping them outperform the rest of Canada. The West Coast saw the largest host premium. Spending growth in B.C. more than doubled, from 5.4% to 12.7%. Ontario’s growth slowed from last year but at 13% still outperformed the rest of Canada, where spending was around 10%. Importantly, nominal growth has slowed relative to last year in recreation categories, but inflation also eased, suggesting that much of nominal spending likely reflected stronger real activity rather than simply higher prices.”

More from Retail Insider:

Costco expands on-demand delivery across Canada through DoorDash

Costco members across Canada can now order products from their local warehouses through DoorDash, expanding the retailer’s delivery options nationwide.

“Costco members have expressed an appetite for years to be able to shop from their local warehouse on DoorDash,” said Mike Goldblatt, vice-president of enterprise partnerships at DoorDash. “Costco’s quality, value, and selection combined with DoorDash’s reach and local delivery expertise give members more flexibility in how they shop. We’re honoured to see our global partnership continue to grow with Costco, delighting more members worldwide.”

The partnership allows members to use DoorDash to order groceries, pantry staples, household essentials, beauty products, electronics, seasonal merchandise and other items from the retailer’s warehouses. The Canadian launch follows Costco and DoorDash’s recently announced partnership in the United States and existing availability in Australia, New Zealand, Sweden, Iceland and Puerto Rico.

The rollout gives Costco members another way to shop its warehouse assortment without visiting a store, while extending DoorDash’s role in delivering products from the membership-based retailer. Customers can access thousands of items through the DoorDash platform and have their orders shopped and delivered by a Dasher.

To use the service, Costco members navigate to Costco on DoorDash and enter their Costco membership ID. Consumers who are not members can follow a link to Costco.ca to purchase a membership before returning to DoorDash to connect their new account.

Customers can then select from the available merchandise and complete their order through DoorDash. DashPass members can receive $0 delivery fees and reduced service fees on orders with a subtotal of $85 or more, subject to the terms outlined by the companies.

A Dasher shops for the order and provides updates to the customer during the delivery process.

The Canadian expansion is the latest development in a broader relationship between Costco and DoorDash that now spans several international markets. The companies said the Canadian launch responds to demand from Costco members for the ability to shop from their local warehouse through DoorDash.

More from Retail Insider:

\

Daily Synopsis: October 6, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the articles we published below, covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.

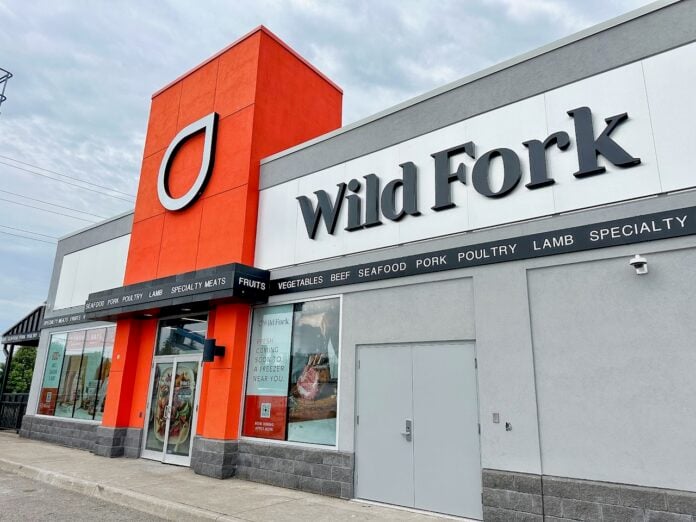
Wild Fork has withdrawn from the Canadian market, closing its four Ontario stores and ending plans for nearly 30 locations in the province. This exit contrasts with Jollibee’s aggressive expansion, which includes 26 new franchised restaurants in British Columbia and Edmonton, aiming for potentially over 100 Canadian locations. Meanwhile, MINISO is introducing a larger format called SUPER MINISO at Square One in Mississauga, blending IP merchandise with lifestyle products to attract mall shoppers. These moves illustrate differing strategies in market entry and growth approaches in Canada.

George Sully’s memoir and career reflect the challenges and resilience required to build Canadian fashion brands amid limited infrastructure and resources. Thanksgiving turkey dinners for a family of four are projected to cost 10% more in 2026, rising to $35.72 compared to a minimal increase in 2025.

🗞️ The Day’s Retail Insider Article List

Now Out: Retail Insider Quarterly Reports

🌐 Canadian Retail News From Around the Web will be back tomorrow.

Wild Fork Exits Canada, Abandoning Ambitious Ontario Expansion Plans

Wild Fork Ancaster, Ontario (Image: Wild Fork)

Wild Fork Foods is exiting the Canadian market and will close its four Ontario stores, ending an expansion effort that began less than four years ago and at one point contemplated a network approaching 30 locations across the province.

The JBS-owned specialty meat and seafood retailer operates stores in Whitby, Oakville, Ancaster and Newmarket. Wild Fork said online delivery and pickup in Canada will remain available until October 13, while its stores are expected to close on or before December 14. Individual locations could close earlier as inventory is sold.

The withdrawal represents a significant reversal from Wild Fork’s original Canadian plans. The retailer entered the market in early 2023 and was initially seeking about 20 locations in the Greater Toronto Area, with longer-term plans for expansion into British Columbia and Alberta.

By 2024, Wild Fork told Retail Insider that it had identified 26 priority markets in Ontario and wanted to move toward approximately 30 stores in the province within three years. Ultimately, the chain’s Canadian standalone network reached four locations.

Wild Fork Entered Canada With Significant Expansion Plans

Wild Fork launched its Canadian e-commerce business in January 2023, initially offering same-day delivery in the Greater Toronto Area. Its first physical store followed several months later at Taunton Gardens in Whitby.

At the time, the company was actively sourcing approximately 20 GTA sites. Wild Fork was generally looking for spaces of about 3,800 to 5,000 square feet, with grocery-anchored shopping areas among its preferred locations.

The retailer subsequently expanded to Oakville and opened an Ancaster store in June 2024. The Oakville and Ancaster locations were larger than the original Whitby prototype, each spanning just under 7,000 square feet.

During the Ancaster opening, then-Wild Fork Real Estate Lead Elle Mejia-Pierce told Retail Insider that the company had identified 26 Ontario markets it wanted to enter before moving into Western Canada.

“I’d like to see us inching up towards 30 stores in the next three years,” she said at the time.

Wild Fork was then building its real estate pipeline for 2025 and 2026, with Newmarket and London among the markets being considered. British Columbia and Alberta were expected to follow Ontario as the retailer expanded nationally.

The Newmarket store opened July 1, 2025, at 7 Harry Walker Parkway South, becoming Wild Fork’s fourth Canadian standalone location. It was also the last standalone store the retailer opened in the country before announcing its withdrawal about 15 months later.

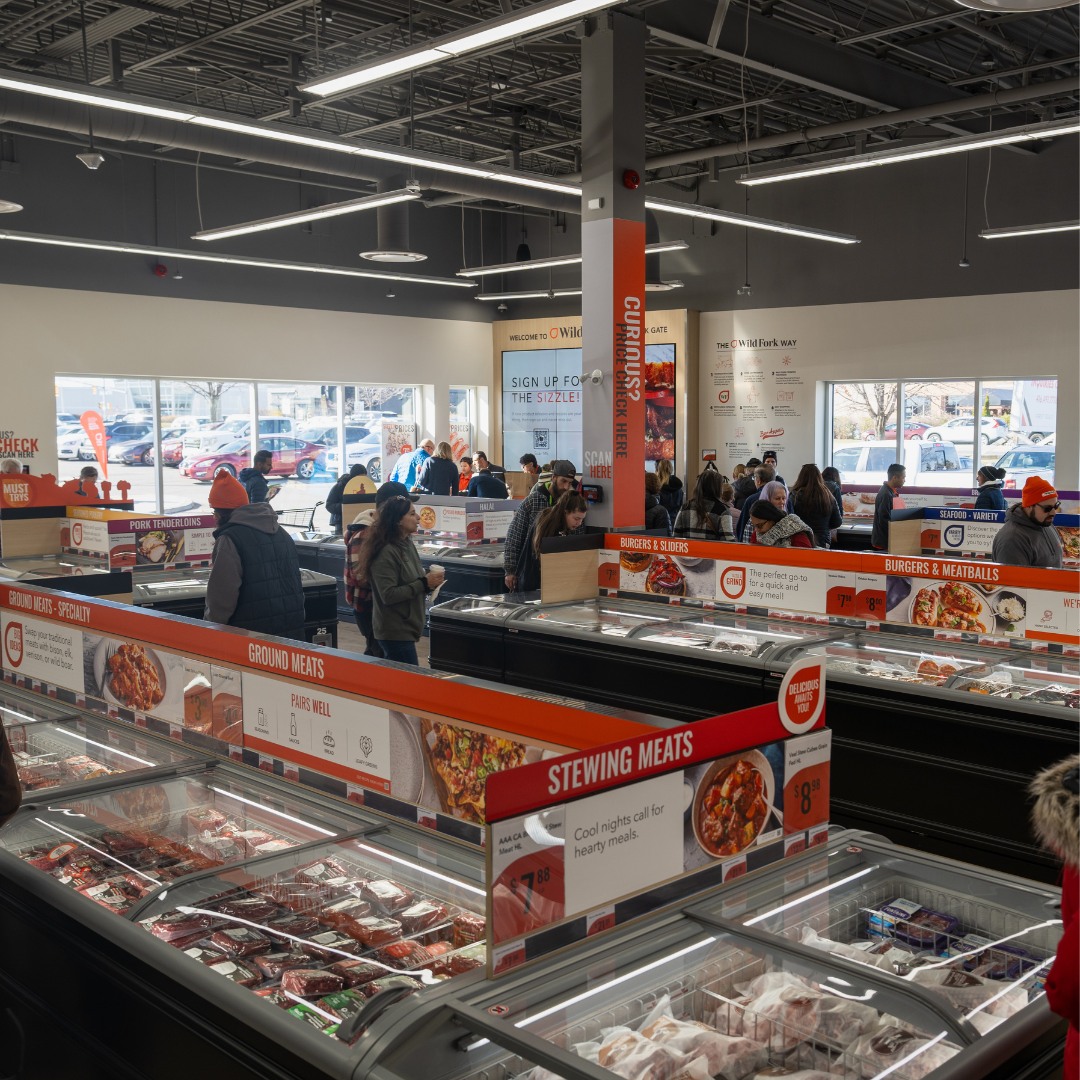
Grand Opening at Hyde Park Gate (Image: Wild Fork Canada)

A Specialized Meat and Seafood Concept

Wild Fork is part of JBS, the global food company with extensive meat processing and food operations in Canada, the United States and other markets. The Wild Fork withdrawal does not represent a broader Canadian exit by JBS, which maintains other operations in the country.

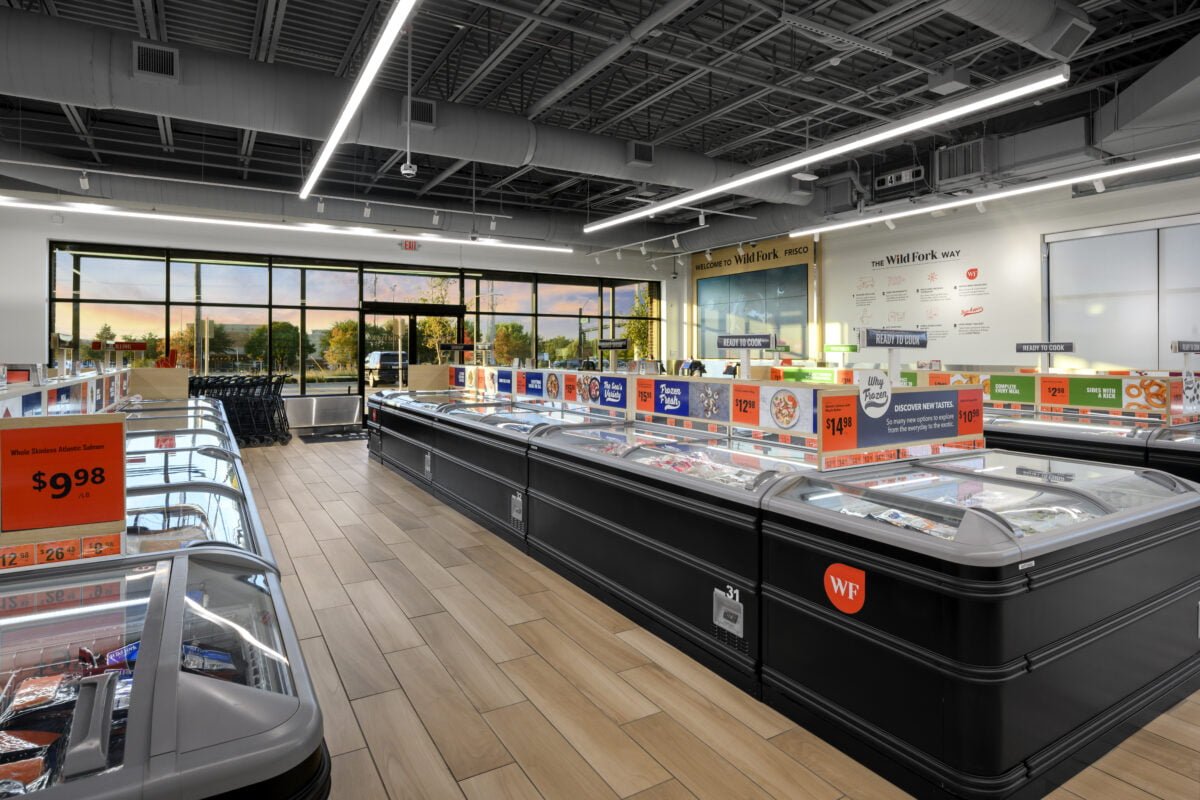
The retail concept centres on a broad assortment of frozen proteins sold through stores and e-commerce. By 2024, Wild Fork’s Canadian assortment had grown from approximately 450 products to more than 600, ranging from everyday beef, chicken and seafood to Wagyu, lobster, bison, elk, venison and other specialty products.

Wild Fork sought to position itself as an everyday food destination rather than exclusively as a higher-end meat retailer. Its real estate strategy included locations near conventional grocery stores and other frequently visited retailers, allowing the chain to serve as a specialized protein stop alongside a larger grocery trip.

Sobeys Partnership Offered Another Route to Canadian Customers

Wild Fork was still pursuing new ways to reach Canadian consumers in 2026. This summer, the company launched its first Canadian store-within-a-store partnership with Sobeys at the grocer’s Shellard Lane location in Brantford.

The shop carried more than 250 Wild Fork meat and seafood products. Wild Fork publicly described the opening as a new chapter in its Canadian growth and said it looked forward to reaching more Canadian families through the format.

The arrangement gave Wild Fork a presence inside an established Canadian supermarket without relying solely on expansion of its standalone store network. Within months of launching the Brantford pilot, however, Wild Fork announced plans to leave Canada.

Wild Fork has not publicly detailed what will happen to the Brantford Sobeys shop following the withdrawal. Its announcement says the company is closing its Canadian operations, but no specific information regarding the Sobeys partnership was provided.

Image: Wild Fork

Canadian Hiring Continued Into September

Wild Fork also continued recruiting in Ontario shortly before the exit announcement. Employment listings associated with the company appeared in September for several markets, including Brantford, North York and Oshawa.

Federal Job Bank records included a Wild Fork posting in Brantford dated September 17, while other listings associated with the company appeared later in the month. The postings do not establish that Wild Fork intended to open standalone stores in North York or Oshawa, but they indicate that Canadian recruitment activity continued close to the October 6 announcement.

Together with the recently launched Sobeys pilot, the hiring activity shows that Wild Fork maintained visible Canadian operating and growth activity late in its time in the market. The timing does not establish when JBS or Wild Fork made the decision internally to leave Canada.

Wild Fork Gives No Detailed Reason for Exit

Wild Fork has not publicly provided a detailed explanation for its decision to leave Canada. In announcing the move, the company said the decision came “after careful consideration” and thanked Canadian customers for supporting the business.

“We are incredibly grateful for the customers who welcomed Wild Fork into their communities and trusted us to serve them,” the company said. “It has been a privilege to bring the Wild Fork experience to Canada, and we sincerely appreciate your support.”

Wild Fork said employees and customers would remain a priority during the transition and that it was committed to supporting store teams through the closures. The company has not disclosed how many Canadian employees will be affected, while questions also remain about the Sobeys arrangement and whether Wild Fork products could remain available through another Canadian distribution channel.

The timing of the withdrawal is particularly notable given Wild Fork’s activity earlier this year. After its standalone network stopped at four stores, the retailer was still experimenting with a different Canadian growth format through Sobeys this summer, only months before announcing that its Canadian operations would close.

More from Retail Insider:

Q3 2026 Grocery: Capacity Expands as Competition for the Basket Intensifies

As part of Retail Insider Reports, this Q3 2026 Grocery Report analyzes Q3 2026 developments in Canadian food retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping grocers, suppliers, landlords, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines the Canadian grocery retail sector, including supermarkets, discount grocers, specialty food retailers, convenience-oriented food retail, merchandising strategies, store expansion, competition, consumer purchasing trends, and developments affecting food retail in Canada.

Executive Summary

Canada’s largest grocery retailers continued adding and repositioning capacity during Q3 2026 even as the latest available supermarket data showed limited underlying volume growth.

Statistics Canada reported seasonally adjusted sales of approximately $9.45 billion at supermarkets and other grocery retailers, excluding convenience stores, in July. Sales were essentially unchanged from June and 1.2% higher than a year earlier. At constant prices, sales declined 0.3% month-over-month and 2.4% year-over-year.

Those figures do not capture the entire Canadian market for food. Grocery sold through establishments classified as general merchandise retailers, including supercentres, falls outside the supermarket category. Real sales at general merchandise retailers were 7.1% higher year-over-year in July, although the data do not identify how much of that increase came from food.

Against that backdrop, Loblaw continued a $2.4-billion capital program that includes substantial investment in No Frills and Maxi. Metro announced plans to convert 10 Ontario supermarkets to Food Basics. Empire increased its fiscal 2027 store target. Walmart is adding Supercentres to former department-store spaces, and T&T Supermarket has major shopping-centre projects planned in Ontario and Manitoba.

Retailers are also changing how they serve online customers. Metro is moving Montreal e-commerce fulfilment toward store picking and third-party delivery, while Empire is defining different roles for Voilà and on-demand delivery platforms.

Grocers can grow by entering underserved markets, changing formats, increasing their share of household spending or improving existing operations. The question is how much additional business those investments ultimately generate.

Canadian grocery retailers continued committing substantial capital to stores, formats and e-commerce during Q3 2026 despite soft real sales within the supermarket establishment category.

Several patterns emerged during the quarter:

  • Discount remained an important investment vehicle, with retailers adapting store sizes, assortments and banners to individual trade areas.
  • Conversions, relocations and acquisitions complicated headline store-opening counts because they did not all represent equivalent additions to grocery capacity.
  • Specialty and premium grocery continued attracting investment alongside discount formats.
  • Major shopping-centre projects from Walmart and T&T showed how former department-store space can add or reposition substantial grocery capacity.
  • Online grocery sales continued growing, but Metro and Empire focused increasingly on the cost and role of different fulfilment models.
  • Consumer behaviour pointed to grocery spending being divided across promotions, brands, formats and channels as households continued managing elevated food costs.

The next phase of expansion will test whether these investments generate additional sales and profit or redistribute existing grocery spending at higher cost.

Retail Insider Coverage

Grocery Inflation Slows, but Consumers Remain Price-Conscious

Food affordability remained an important backdrop to grocery competition during the quarter. Grocery-price inflation slowed to 2.8% year-over-year in August, falling below the 3.0% headline Consumer Price Index for the first time since July 2024. Grocery prices nevertheless remained approximately 29% higher than in August 2021.

Consumers were receiving some relief from the rate of price increases without reversing the accumulated increase in food costs. NIQ data cited by Retail Insider pointed to more frequent purchase occasions and lower average spending per transaction across several retail channels. Purchase occasions should not be interpreted as supermarket visits, but the pattern is consistent with consumers dividing purchases among different retailers, products and offers. The Canadian grocery basket is increasingly contested.

Discount Expansion Becomes More Localized

Loblaw’s 2026 investment program demonstrates the continued importance of discount grocery and the ways the format is being adapted to different markets. The company announced $2.4 billion in planned Canadian capital spending for 2026 and said in September that approximately $1.2 billion remained to be deployed. Its expected opening program increased to approximately 75 grocery, pharmacy and other locations during the year.

That total should not be interpreted as 75 new supermarkets. Shoppers Drug Mart, Pharmaprix and other formats form a substantial part of the program. Within grocery, No Frills and Maxi have received significant investment. An approximately 8,000-square-foot No Frills opened in Dutton, Ontario, on July 30 with a curated assortment of roughly 4,000 products, creating a smaller format for a rural trade area.

A larger No Frills in Komoka tests another version of the concept, including a broader fresh and prepared-food offer. The stores show how the same discount banner can be adapted to different local opportunities, with the longer-term economics of the newer formats still to be established.

Metro Uses Banner Conversion to Rework Existing Capacity

Metro is pursuing discount growth through its existing Ontario network. The company announced plans in August to convert 10 Metro supermarkets to Food Basics, including locations near Yonge and Finch in Toronto and at Southgate in Ottawa.

Management described the program as a location-by-location review of markets and underperforming stores, with the expectation that Food Basics can produce stronger sales and store contribution at the selected sites. These are existing grocery locations being repositioned under a different banner, price proposition and operating model. Metro has said individual stores could close for approximately two months during construction, with financial benefits building over subsequent fiscal years.

Metro reported food same-store sales down 1.5% during its fiscal third quarter, but the result was materially affected by the strike at its Laval produce-distribution facility. The company estimated an after-tax impact of approximately $66 million from lost profit and direct costs.

The sales decline should therefore not be treated as an equivalent measure of underlying grocery demand. The conversions address a separate question of which proposition is best suited to each local market.

Empire Expands Across Multiple Grocery Formats

Empire is increasing store-development activity across several banners and price positions. The company raised its fiscal 2027 target to more than 25 stores from an earlier expectation of more than 20 and plans approximately $850 million in capital spending. Roughly half is allocated to renovations and store development.

The increased target includes four acquired Mayrand locations, meaning the total cannot be treated as an entirely new-build program. FreshCo entered Atlantic Canada in August and continued expanding in Ontario and Western Canada. Empire is also investing through banners including IGA, Safeway and Mayrand.

Management has said recently opened stores were meeting or exceeding expectations and has argued that long-term property decisions should reflect individual market opportunities instead of the current national demand cycle alone. Discount is attracting capital, but retailers continue to see opportunities across multiple grocery formats.

New Capacity Isn’t the Same as New Store Count

Some of the largest grocery projects announced during the quarter demonstrate why store counts alone can misrepresent competitive change. Walmart plans an approximately 115,500-square-foot Supercentre at Place d’Orléans in Ottawa, occupying former Hudson’s Bay space and adding a full grocery assortment. Projects at Lime Ridge Mall in Hamilton and Bramalea City Centre in Brampton are also bringing Walmart into major shopping-centre locations.

These projects can add substantial fresh-food and grocery capacity even when relocations or conversions produce comparatively little change in Walmart’s overall Canadian store count. T&T Supermarket provides an even clearer example. Its planned CF Markville location in Markham will occupy approximately 68,000 square feet of former Hudson’s Bay space and is expected to replace the existing approximately 50,000-square-foot Unionville store when it opens in 2028.

The project represents a relocation and approximately 18,000 additional square feet instead of an entirely new 68,000-square-foot supermarket in the trade area. Its shopping-centre position could also alter traffic patterns and customer reach. T&T’s planned 48,000-square-foot store at CF Polo Park in Winnipeg represents a different type of expansion. Expected in spring 2028, it will be the banner’s first Manitoba location and introduces T&T to a new provincial market.

Openings, relocations, conversions, acquisitions and expansions can all appear in development pipelines while producing very different changes in local grocery supply.

Grocery Sites Can Survive the Failure of an Operator

Q3 also provided examples of grocery locations remaining viable after a previous operator departed. Valleyview IGA reopened on August 20 at 9106 142 Street NW in Edmonton, returning a familiar supermarket banner to a longstanding neighbourhood grocery site after L’OCA closed earlier in the year.

At Toronto’s Bayview Village, McEwan Fine Foods announced a 9,326-square-foot store for 2027 in the former Pusateri’s space. Prepared meals, fresh departments and specialty food will form part of the offer, maintaining a premium grocery component at the property under a different operator.

Sunterra’s Bower Place market in Red Deer closed September 26 while the company was in court-supervised restructuring. Those company-specific circumstances do not establish a broader retreat from premium grocery.

The examples separate the viability of a grocery location from that of a particular operator. A retailer’s failure does not necessarily establish that a trade area cannot support grocery, and an established grocery site does not guarantee that every concept will succeed there. Crombie’s results provide additional real estate context. The landlord reported 97.5% committed occupancy and an 11.3% increase in first-year rents on second-quarter renewals in results published during August.

The rental increase applied across Crombie’s portfolio and should not be interpreted as an 11.3% increase specifically on Sobeys or Safeway stores. Grocery anchors nevertheless support frequent property visits, while surrounding units provide additional leasing opportunities.

Broader Industry Coverage

Online Grocery Growth Doesn’t Settle the Profitability Question

Online grocery continued growing at Canada’s major supermarket companies during their latest reported fiscal periods. Loblaw reported e-commerce growth of 19.3%, Metro reported online food sales growth of 16.3% and Empire reported online growth of 11.3%. The reporting periods differ, so the figures are indicators of company activity instead of a comparable Q3 ranking.

More significant are the decisions being made about how those orders are fulfilled. Picking groceries, operating automated facilities, acquiring customers and delivering orders all carry costs. Higher digital sales do not establish that an online operation has become more profitable, and both Metro and Empire are adjusting their networks accordingly.

Metro Moves Fulfilment Back Toward Stores

Metro plans to close its dedicated Montreal e-commerce facility and shift fulfilment toward store-based picking and third-party delivery. Management linked the decision to growing demand for same-day service and the opportunity to reduce fixed costs. The company expects its combined network measures, including the Ontario store conversions, to generate approximately $15 million in recurring annual after-tax earnings by the end of fiscal 2028, with roughly half attributable to each component.

Moving orders into stores makes use of inventory, labour and locations already positioned close to customers, although store picking introduces its own operating costs and requirements. Metro is changing the cost structure of its online business, with the financial benefits expected to develop over several fiscal years.

Empire Redefines the Role of Voilà

Empire’s evolving e-commerce strategy provides a larger example of matching infrastructure to demand. The company invested heavily in automated customer fulfilment centres as it built Voilà, but later concluded that Canada’s grocery e-commerce market was smaller than previously anticipated.

Empire closed its Calgary customer fulfilment centre and kept a proposed Vancouver facility on hold while retaining dedicated facilities serving Toronto and Montreal. Its earlier restructuring was expected to improve annualized e-commerce operating income by approximately $95 million.

The company is now describing the next phase as “e-commerce 2.0.” Voilà continues to serve planned grocery orders in markets where dedicated infrastructure remains in place, while third-party platforms can address more immediate purchases and provide delivery coverage without requiring the same infrastructure in every market.

The approach resembles the localized physical-store strategies seen elsewhere in the sector. Different markets and shopping occasions can support different formats when demand is sufficient to justify their costs. For e-commerce, order density, basket size, frequency and cost to serve will determine where each model makes economic sense.

Technology Adds Another Layer

Instacart launched Clementine for most Canadian and U.S. customers in September, offering assistance with meal planning, shopping lists and cart building. The launch establishes the service’s availability in Canada, but early claims about changes in basket size were not Canada-specific and do not establish improved Canadian conversion or profitability.

Its relevance will depend on whether tools of this type materially change purchasing behaviour, basket composition or customer retention.

Competition Extends to Property and Pricing Rules

Competition in grocery is also being shaped by rules governing real estate and promotions. A September consent agreement with Empire made earlier commitments concerning grocery property controls legally binding, including restrictions on the use of certain restrictive covenants and exclusivity clauses.

Reducing those barriers can make entry into some trade areas easier, but it does not create suitable grocery space, provide capital or logistics, or guarantee sufficient local demand. The Competition Bureau also opened an investigation in September into minimum advertised pricing policies, examining whether restrictions on advertised prices make it more difficult for consumers to discover offers and for retailers to compete. The investigation is ongoing and does not constitute a finding that a particular supplier or grocer violated competition law.

Supplier negotiations provide another constraint on how quickly new costs reach consumers. Empire said on its September results call that the immediate tariff impact was minimal and only a handful of suppliers had submitted related cost increases. Management said it intended to challenge requests where sourcing alternatives were available. New cost pressures therefore do not automatically translate into equivalent increases at the grocery shelf.

Editor’s Take & Outlook

What Retailers and Landlords Should Watch

The expansion underway in Canadian grocery requires more context than a count of announced stores. T&T’s CF Markville project replaces and expands an existing nearby store. Metro’s 10 Food Basics conversions reposition existing supermarkets. Empire’s higher opening target includes acquired Mayrand locations. Walmart can add substantial grocery capacity through Supercentre projects without a proportionate increase in net store count.

Retailers will need to determine whether those investments produce additional traffic, transactions and household spending or shift sales among existing locations. Real sales, average basket, transaction frequency, gross margin, store contribution and cannibalization provide a clearer picture than opening counts alone.

Online grocery requires a parallel assessment through order density, repeat use, basket size, picking and delivery costs, and customer acquisition. For landlords, the analysis occurs at the trade-area level. A grocery opening can fill a major vacancy and increase property traffic while redistributing food spending from nearby stores.

Outlook: Measure the Return on Added Capacity

The next six to 18 months will provide clearer evidence on the returns from the industry’s current investment cycle. Metro’s Food Basics conversions will test whether changing the banner and price proposition can improve sales and store contribution at selected Ontario locations. Loblaw’s smaller No Frills formats will provide evidence on whether discount can economically serve communities that may not support conventional supermarket footprints.

Empire’s development pipeline will test its ability to add stores across several formats while maintaining returns. T&T’s major projects and Walmart’s shopping-centre Supercentres will introduce or reposition substantial grocery capacity in individual trade areas, although several projects extend into 2027 and 2028.

Online grocery faces a similar test. Metro’s move toward store-based fulfilment needs to produce the expected cost benefits, while Empire will need to grow digital sales without recreating the fixed-cost challenges that led it to restructure its original fulfilment network.

Performance at existing stores around new openings will be particularly important. A successful new supermarket can still derive part of its sales from nearby locations operated by the same company or its competitors. The central measure is how much additional household spending each investment captures and what it costs to win and serve that business.

Editor’s Take

Canada’s largest grocers continue to see opportunities for investment even as the latest available supermarket data show limited underlying volume growth. National averages can obscure population growth, underserved communities, changing shopping patterns and shifts between channels. Retailers can also grow by taking market share or improving locations they already operate.

Q3 showed how local that competition is becoming. Loblaw is testing different versions of No Frills, Metro is converting selected stores to Food Basics, Empire is expanding across several grocery formats, and Walmart and T&T are adding or repositioning substantial grocery capacity through shopping-centre projects.

Online grocery is undergoing a similar adjustment. Metro is reducing dedicated infrastructure in Montreal, while Empire is assigning different shopping occasions to Voilà and third-party delivery platforms.

The Canadian grocery basket is being contested across more formats, locations and fulfilment models. An opening, relocation, banner conversion, acquisition and expansion can each produce a different competitive effect, just as digital sales growth can have very different economics depending on how an order is fulfilled.

The next phase of Canadian grocery expansion will be determined by what happens after the announcements: how much additional business new and repositioned formats capture, how much they take from existing stores, and whether the cost of winning each basket produces an adequate return.

Representative Articles

More From Retail Insider
Q3 2026 Food Service: Restaurant Growth as Consumers Become More Selective

As part of Retail Insider Reports, this Q3 2026 Food Service Report analyzes Q3 2026 developments in Canadian restaurants and foodservice retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping restaurant operators, franchisees, landlords, suppliers, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines Canadian foodservice retail, including quick-service restaurants, full-service restaurants, cafés, food halls, chains, franchised operators, and consumer dining trends.

Executive Summary

Canadian restaurant and foodservice sales continued rising during Q3 2026, but the headline growth masks a more difficult operating environment. Statistics Canada reported seasonally adjusted sales of approximately $8.9 billion at foodservice and drinking places in July, up 0.8% from June and 7.0% from a year earlier. All four major industry groups recorded monthly growth, including full-service restaurants at 0.8% and limited-service eating places at 0.4%. Those figures measure current-dollar receipts rather than customer visits or meal volumes. Restaurant prices were also rising, with restaurant CPI up 3.1% year-over-year in August following increases of 2.9% in July and 2.7% in June.

Industry research points to considerable pressure behind the growing sales totals. Restaurants Canada reported that 80% of Canadians were eating out less often because of the cost of living, compared with 75% a year earlier. The association has also reported that 41% of restaurant companies were losing money or breaking even, while average industry pre-tax margins were 4.1%.

Restaurant operators continued investing despite those pressures. Jollibee secured commitments for 26 additional restaurants in Western Canada, Firehouse Subs reached 200 Canadian locations and Tim Hortons maintained a development program of approximately 80 openings. Established chains invested in beverages, renovations, value offers and loyalty, while delivery partnerships created other ways to reach customers.

Consumers can reduce restaurant spending in several ways without abandoning the category, including dining out less frequently, choosing lower-priced items, skipping drinks and extras or picking up orders to avoid delivery fees. Growth increasingly depends on whether restaurants can generate repeat demand and profitable spending from the occasions they capture. Canadian foodservice receipts continued rising during Q3 2026, but inflation, reported consumer restraint and thin restaurant margins complicate the headline growth.

Several patterns emerged during the quarter:

  • Consumers reported becoming more selective about dining occasions, while some restaurant companies described pressure on traffic, add-ons and delivery spending.
  • Restaurant profitability remained constrained by food, labour, occupancy and other operating costs.
  • Expansion continued through corporate and franchise development, although operating restaurants, development commitments and long-term targets represent different stages of growth.
  • Mature chains invested in beverages, value, renovations and loyalty to generate more business through their restaurant networks.
  • Delivery partnerships expanded customer access, but the financial impact varies according to who acquires the customer, fulfils the order and absorbs the channel costs.
  • Company results varied considerably, indicating that affordability pressure alone does not explain differences in restaurant performance.

The next phase of Canadian foodservice growth will test whether operators can convert expansion and product spending into repeat demand while preserving restaurant and franchisee returns.

Retail Insider Coverage

Restaurant Expansion Continues

Restaurant development continued across several Canadian markets during the quarter. Jollibee’s Western Canadian franchise agreements provide one of the largest examples. The company has commitments for 16 restaurants in British Columbia over five years and an earlier agreement covering 10 restaurants in the Edmonton market.

Together, the 26 committed restaurants nearly equal Jollibee’s existing 28 company-operated Canadian locations. The commitments do not represent 26 operating restaurants or fully secured sites, with individual locations still requiring site selection, approvals, capital, construction and execution.

Firehouse Subs opened its 200th Canadian restaurant at West Springs Landing in Calgary. Jersey Mike’s entered Calgary at 9631 Macleod Trail as franchise operator Redberry continued pursuing a longer-term target of 300 Canadian locations by 2035.

Recipe Restaurant Group also opened an Olive Garden at Vaughan Mills under its Canadian development agreement, with Ottawa and Ajax locations in development.

Expansion can occur on a much smaller physical scale as well. Craig’s Cookies reached 25 Canadian locations and generally targets approximately 1,000 square feet for a franchisee’s first store, within a working range of roughly 800 to 1,200 square feet.

The chain operates in neighbourhood, shopping-centre and tourist locations, while founder Craig Pike has emphasized avoiding oversaturation as the network grows. Its compact format requires a different level of space and capital than a full-service restaurant or larger quick-service operation.

Operating restaurants, sites in development, franchise commitments and long-term targets all indicate expansion, but they represent different stages and levels of commitment.

Mature Chains Look Beyond the Meal for Growth

Beverages became one of the clearest areas of restaurant spending during Q3. KFC Canada and its franchisees committed $30 million to Kwench, a dedicated beverage offering that includes shakes, sparkling lemonades, boba refreshers and iced lattes. The company outlined plans to expand the concept to more than 400 locations by year-end and approximately 600 in 2027.

Tim Hortons continued expanding its cold-drink platform through products including matcha and new fountain equipment, while McDonald’s pursued a similar opportunity through its expanded beverage platform. McDonald’s management reported encouraging early Canadian results but did not disclose Canadian traffic or average-cheque figures that would quantify the effect. The attraction extends beyond beverage sales themselves. Established restaurants already carry the costs of premises, equipment and networks built around existing meal periods. An afternoon beverage can potentially generate another customer occasion through those assets. The return depends on whether the purchase is genuinely new business and whether the sales justify equipment, ingredients, labour, preparation time and operational complexity.

Tim Hortons demonstrates the scale of the opportunity within an established network. The company and its restaurant owners announced approximately $400 million in Canadian spending for 2026, including roughly 80 new restaurants and 400 renovations, across a network of nearly 4,000 Canadian locations.

Renovations include restaurant layouts, kitchen equipment and digital ordering and pickup infrastructure intended to improve speed, accuracy and customer experience. At that scale, improvements in visit frequency, average spending or operating efficiency across the network can have substantial system-wide effects. Beverages, renovations and new locations provide different routes to stronger performance from a restaurant network.

Loyalty Adds Another Reason to Return

Tim Hortons also expanded its loyalty reach during the quarter through a partnership with Canadian Tire’s Triangle Rewards. Customers who link eligible Tims Rewards and Triangle Rewards accounts can earn Canadian Tire Money on qualifying Tim Hortons purchases, with earning rates depending on payment method. The two rewards currencies remain separate.

The partnership adds another benefit to a high-frequency purchase while connecting Tim Hortons with a larger Canadian retail loyalty ecosystem. Its effect on visit frequency and restaurant-level returns was not disclosed during the quarter.

Delivery Raises the Question of Who Owns the Customer

Restaurant delivery continued expanding, but the quarter’s announcements demonstrated different approaches to customer acquisition and fulfilment. The Keg introduced delivery through DoorDash from more than 100 restaurants across Canada and the United States, extending selected menu items beyond its dining rooms. The announcement did not quantify new sales or restaurant-level returns.

Domino’s Canadian partnership with Skip uses a different model. Customers can place orders through Skip, while Domino’s own Delivery Experts fulfil them.

Pizza Pizza management has separately discussed the higher cost of third-party delivery and the advantages of moving customers toward proprietary ordering channels where possible.

The arrangements separate several parts of a delivery transaction: attracting the customer, processing the order, fulfilling it and maintaining the customer relationship. Third-party marketplaces can provide reach and convenience, but operators still need to assess new sales against commissions, fulfilment costs and the value of owning the direct customer relationship.

Property Investment Can Increase Restaurant Productivity

Foodservice spending is also changing existing retail properties without necessarily adding large numbers of restaurant tenants. At Promenades St-Bruno in Quebec, Primaris is planning a $49.5-million redevelopment that will relocate the food court, increase seating to approximately 1,100 and create an exterior entrance.

The project is designed to support longer operating hours and improve access for pickup and delivery outside regular mall hours. Approximately 20,000 square feet in the existing food-court area will eventually be released for new retail space, while the number of food vendors is expected to remain broadly similar.

For the landlord, the redevelopment changes how customers can use the dining area while creating another leasing opportunity elsewhere in the property. For foodservice tenants, exterior access, additional seating and improved pickup and delivery functionality could expand the range of occasions the space can serve.

The current food court is expected to remain open during construction, with the new food court scheduled for fall 2027 and conversion of the former space following later.

Closures Need Context Too

Restaurant closures require the same scrutiny as expansion announcements. Starbucks announced approximately 250 North American closures alongside café improvements that included Canada, but did not disclose how many closures would occur in this country.

Boston Pizza’s program combines renovations and selected new locations with individual closures, some related to lease and redevelopment circumstances.

MTY’s planned closure of 68 corporate restaurants provides another example. Management said approximately 45 to 50 involved Papa Murphy’s, giving the program substantial exposure to the U.S. pizza market. Banner, geography and reason therefore matter when interpreting closure numbers, just as development commitments and long-term targets need to be distinguished from operating restaurants.

Broader Industry Coverage

Consumers Become More Selective About Dining Occasions

Higher restaurant receipts are occurring alongside evidence that consumers are becoming more selective about when and how they eat out. Restaurants Canada’s September Foodservice Facts findings indicated that 80% of Canadians were eating out less often because of the cost of living. The reported increase in restraint was particularly notable among households earning at least $100,000, although the findings measure stated behaviour and should not be treated as an observed national traffic count.

Pizza Pizza provided one of the quarter’s clearest descriptions of how customers can reduce restaurant spending without eliminating an occasion. Management discussed fewer visits, customers cutting drinks and other extras, and increased pickup as some consumers sought to avoid delivery fees. A customer who continues buying the core meal while removing a drink, dessert or delivery charge still generates a transaction, but the value and profitability of that transaction can change.

Restaurants Canada has also reported consumers protecting some occasions while cutting others, with breakfast and lunch showing greater resilience than some other dayparts. Operators are competing for a place in a more selective household food budget, with frequency, format, price and occasion all influencing where spending goes.

The Whole Bill Matters

Value initiatives during Q3 showed how restaurants are trying to protect demand without relying solely on broad discounting. Subway introduced its Fresh For Less menu in Canada with breakfast, snack and lunch items below $5 at participating restaurants. The positioning applies to individual menu choices and can vary by location, rather than establishing a universal sub-$5 meal price.

MTY described a related pricing constraint during its quarterly reporting. Protein costs remained difficult, but management said consumers’ willingness to absorb increases varied by product, requiring affordable entry choices alongside higher-priced items.

Pizza Pizza described offers directed toward inactive customers as preferable to indiscriminate discounting that could weaken franchisee earnings. Drinks, sides, desserts and delivery also contribute to transaction value, making the loss of those purchases significant even when the core meal remains intact. Operators need to balance traffic and affordability against the food, labour, occupancy and service costs attached to each transaction.

Different Chains Are Producing Very Different Results

Company results released during Q3 illustrate how differently restaurant brands are performing within the same broad consumer environment.

Tim Hortons reported Canadian comparable sales growth of 0.1% for the quarter ended Jun 30, 2026. Boston Pizza reported 2.3% same-restaurant sales growth for the same period, with management saying both traffic and menu pricing contributed positively and pricing provided the larger contribution.

MTY reported Canadian same-store sales down 1.8% for its fiscal quarter ended May 31, although management described improvement in June. Pizza Pizza reported a 5.0% same-store sales decline across Pizza Pizza and Pizza 73 for the quarter ended June 30.

The figures cover different businesses, reporting periods and operating models and should not be treated as a ranking of July-to-September performance. They show that the same broad consumer pressures are producing different outcomes across restaurant systems.

Restaurant Brands International management pointed to product and marketing execution when discussing Tim Hortons’ Canadian performance. Boston Pizza benefited from a combination of traffic, pricing, promotions and restaurant occasions associated with major sporting events.

Affordability remains an industry-wide constraint, while product relevance, value, marketing, location, service and execution continue to influence individual brand performance.

Restaurants Also Compete With Convenience Food

The competitive set for many restaurant occasions extends beyond traditional restaurants. Couche-Tard reported 4.3% Canadian food-sales growth during its first fiscal quarter while Canadian merchandise same-store sales overall were approximately flat.

The company did not quantify sales taken from restaurants, so the result does not establish that convenience stores are gaining restaurant market share. Prepared food at convenience stores nevertheless competes for some of the same occasions, including coffee, breakfast, snacks and quick meals. Value offers and convenient locations broaden the choices available to consumers purchasing food away from home, making the relevant competitive set wider than businesses formally classified within the restaurant industry.

Editor’s Take & Outlook

What Restaurant Operators and Landlords Should Watch

Restaurant growth increasingly needs to be evaluated through the performance of individual locations and customer occasions. For operators, traffic remains important, but so do average cheque, product attachment, daypart mix, repeat frequency, promotional response, delivery mix, food costs, labour requirements and restaurant-level margins.

Franchise systems need development commitments to become viable sites and operating restaurants, while new units need to generate acceptable returns without excessive cannibalization of existing franchisees. Mature systems face a different scale question. Improvements across hundreds or thousands of restaurants can have a greater effect than an annual opening program, making renovations, beverages, loyalty and digital initiatives important even when they do not add locations.

For landlords, visibility, access, parking, drive-thru capability, pickup areas, delivery access, operating hours, patios and nearby competition can influence restaurant performance. Promenades St-Bruno shows how property design can expand the usefulness of foodservice space without substantially increasing the number of vendors.

Outlook: Can Growth Produce Repeatable Restaurant Economics?

The next six to 18 months will provide several tests of the industry’s current growth plans. Jollibee’s Western Canadian agreements will begin to show how quickly committed franchise development converts into secured sites and operating restaurants. KFC’s wider Kwench rollout will test whether beverage demand can be sustained beyond the initial launch period across a much larger restaurant base.

Tim Hortons will continue spending on openings, renovations, beverages and loyalty while seeking stronger performance from its Canadian network. McDonald’s beverage expansion will provide another indication of whether established quick-service restaurants can create new occasions through locations already in operation.

Value initiatives will need to protect demand without weakening franchisee returns. Delivery partnerships face a similar test as operators assess whether third-party reach produces new orders or moves existing demand through more expensive channels. Restaurant profitability remains the broader constraint. Nominal sales can continue growing while food, labour, occupancy and service costs absorb much of the increase.

Repeat demand and restaurant-level returns will provide a clearer measure of sustainable growth than opening targets or current-dollar sales alone.

Editor’s Take

Canada’s foodservice industry continues to invest as consumers become more selective about dining out. Restaurant chains are opening locations, franchise agreements are being signed and mature systems are spending on renovations, beverages, loyalty, value and delivery. Landlords are also investing in foodservice space and the infrastructure surrounding it.

The economics behind that activity are under more pressure than headline restaurant receipts suggest. Consumers can visit less often, choose a lower-priced format, skip a drink or side, use a promotion, pick up an order instead of paying for delivery, or move a quick meal occasion to a convenience store. Operators are competing for the visit, the composition of the cheque and the next visit.

New locations remain an important source of growth for emerging restaurant systems. Mature chains have another powerful lever in their established networks, where improvements in frequency, product attachment or operating efficiency can be applied across hundreds or thousands of restaurants.

Differences in company performance also show why consumer pressure cannot explain every outcome. Product, value, marketing, location and execution continue to matter. The next phase of Canadian foodservice growth will be determined by whether operators can give consumers enough reason to return while keeping each occasion economically attractive for restaurants and their franchisees. Nominal sales growth alone will not answer that question.

Representative Articles

More From Retail Insider
Q3 2026 Real Estate & Leasing: Strong Leasing Faces the Test of Delivery

As part of Retail Insider Reports, this Q3 2026 Real Estate & Leasing Report analyzes Q3 2026 developments in Canadian retail property and leasing. Drawing on Retail Insider coverage, industry research, landlord disclosures, government data, and broader market signals, it identifies key dynamics shaping landlords, tenants, investors, shopping centres, and redevelopment projects. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines retail real estate, leasing, shopping centres, mixed-use developments, landlords, tenants, mall operators, redevelopment, and commercial retail property trends.

Executive Summary

Canadian retail real estate entered the final quarter of 2026 with exceptionally tight conditions at some properties and millions of square feet of former department-store space still moving through redevelopment.

Choice Properties reported retail occupancy of 97.4%, Crombie ended its second quarter with committed occupancy of 97.5%, and CT REIT reported 99.5%. Renewal spreads were also strong across several portfolios, supported by grocery, service and other necessity-oriented tenants.

The national picture was more complicated. Canada’s overall retail vacancy rate remained around 2.5% following Hudson’s Bay closures, while shopping-mall vacancy had risen sharply as the market absorbed almost five million square feet of negative net absorption. CoStar expects mall vacancy to remain elevated for several years.

A nearly full grocery-anchored centre and an enclosed mall redeveloping a 150,000-square-foot former department store face very different leasing conditions, capital requirements and timelines. Landlords are making progress replacing major vacancies, but former anchors frequently require subdivision, new entrances, building systems, permits and substantial landlord and tenant investment before replacement businesses can open.

The distinction is visible in landlord results. Primaris reported 86.6% in-place occupancy against 91.1% committed occupancy, while Crombie reported 96.6% economic occupancy against 97.5% committed occupancy.

The next phase will be measured by how much committed leasing becomes open, rent-paying space and what returns landlords generate on the capital required to create it. Canadian retail-property conditions remained highly selective during Q3 2026, with some grocery-anchored and necessity-oriented portfolios reporting near-full occupancy while enclosed malls continued absorbing large former department-store vacancies.

Several themes emerged during the quarter:

  • Choice Properties, Crombie and CT REIT reported high retail occupancy and strong renewal spreads, supported by established national tenants and necessity-oriented shopping.
  • National conditions were less uniform, with elevated mall vacancy following Hudson’s Bay closures and rent growth expected to moderate.
  • Committed occupancy can exceed in-place or economic occupancy because signed tenants may not yet have opened or begun paying rent.
  • Former department-store replacements increasingly involve multiple tenants and substantial redevelopment instead of another retailer taking an anchor box intact.
  • Higher replacement rents can create significant income potential, but returns also depend on redevelopment capital, downtime and rent commencement.
  • Ownership transactions and acquisition activity demonstrate continued interest in Canadian retail property, although acquisitions, redevelopment plans and operating income represent different stages of investment.

The next several quarters will show how much announced and committed leasing converts into productive space and rental income.

Retail Insider Coverage

Grocery and Necessity-Based Properties Remain Tight

Some of the strongest landlord results came from portfolios anchored by grocery, service and established national retailers. Choice Properties ended Q2 with retail occupancy of 97.4% and completed about 643,000 square feet of renewals at an average spread of 12.4%. Excluding fixed-rate renewal options, the spread was approximately 20%, illustrating how the composition of expiring leases can affect the headline result.

At Bloor and Dundas in Toronto, Choice is dividing approximately 90,000 square feet formerly occupied by Loblaw between Shoppers Drug Mart and GoodLife Fitness. Shoppers had taken possession for fixturing, while GoodLife possession was targeted for early 2027. A separate 82,000-square-foot property in Laval required rezoning before redevelopment could proceed.

Crombie reported 97.5% committed occupancy and 96.6% economic occupancy at the end of Q2. Economic occupancy represents space under lease where rent has commenced, while committed occupancy also includes completed leases for future occupancy of currently vacant space.

The REIT completed approximately 121,000 square feet of Q2 renewals at rents 11.3% above expiring rates. Its grocery-oriented portfolio benefits from recurring visits, while Empire’s 61.5% share of annual minimum rent creates substantial tenant concentration.

CT REIT reported committed occupancy of 99.5% and a blended renewal increase of 10.4%. Canadian Tire accounts for the overwhelming majority of its gross leasable area and annualized base minimum rent. The results demonstrate the strength of well-leased necessity-oriented retail, but the structures of these portfolios help explain why their occupancy and renewal figures should not be generalized across the Canadian market.

Leased, Open and Cash-Paying Are Different Stages

Primaris provides one of the clearest examples of the difference between leasing progress and current property income. The mall-focused REIT reported 86.6% in-place occupancy at the end of Q2 compared with 91.1% committed occupancy. At June 30, approximately 600,000 square feet of former Hudson’s Bay space had been leased, with another 300,000 square feet in advanced negotiations. Occupancy dates for the leased space extend from early 2027 through mid-2029.

Primaris has estimated redevelopment capital of $175 million to $225 million for its former HBC space. Replacement net rent is expected to average approximately $17 per square foot compared with roughly $4 per square foot previously paid by Hudson’s Bay.

The increase creates substantial potential rental growth, but it comes with redevelopment capital, construction, tenant delivery and several years of staged rent commencement. The economics become clearer as tenants open, rent begins and the redeveloped space moves toward stabilized operation.

Former Department Stores Are Becoming Multiple Destinations

Galeries de la Capitale in Quebec City shows what anchor replacement can involve at the property level.

Primaris is investing approximately $19 million to convert the roughly 163,000-square-foot former Hudson’s Bay into a multi-tenant retail and restaurant wing. Imaginaire has committed to approximately 30,500 square feet, with an opening targeted for spring 2027, while ZIBO! is taking approximately 5,500 square feet.

The conversion includes an exterior entrance and new washrooms, while Imaginaire is investing approximately $2 million in its store separately from Primaris’s landlord expenditure. Other spaces are expected to be delivered progressively through 2027.

Central Walk is undertaking a larger conversion across Woodgrove Centre in Nanaimo and Mayfair Shopping Centre in Victoria, involving approximately 310,000 square feet of former Hudson’s Bay space.

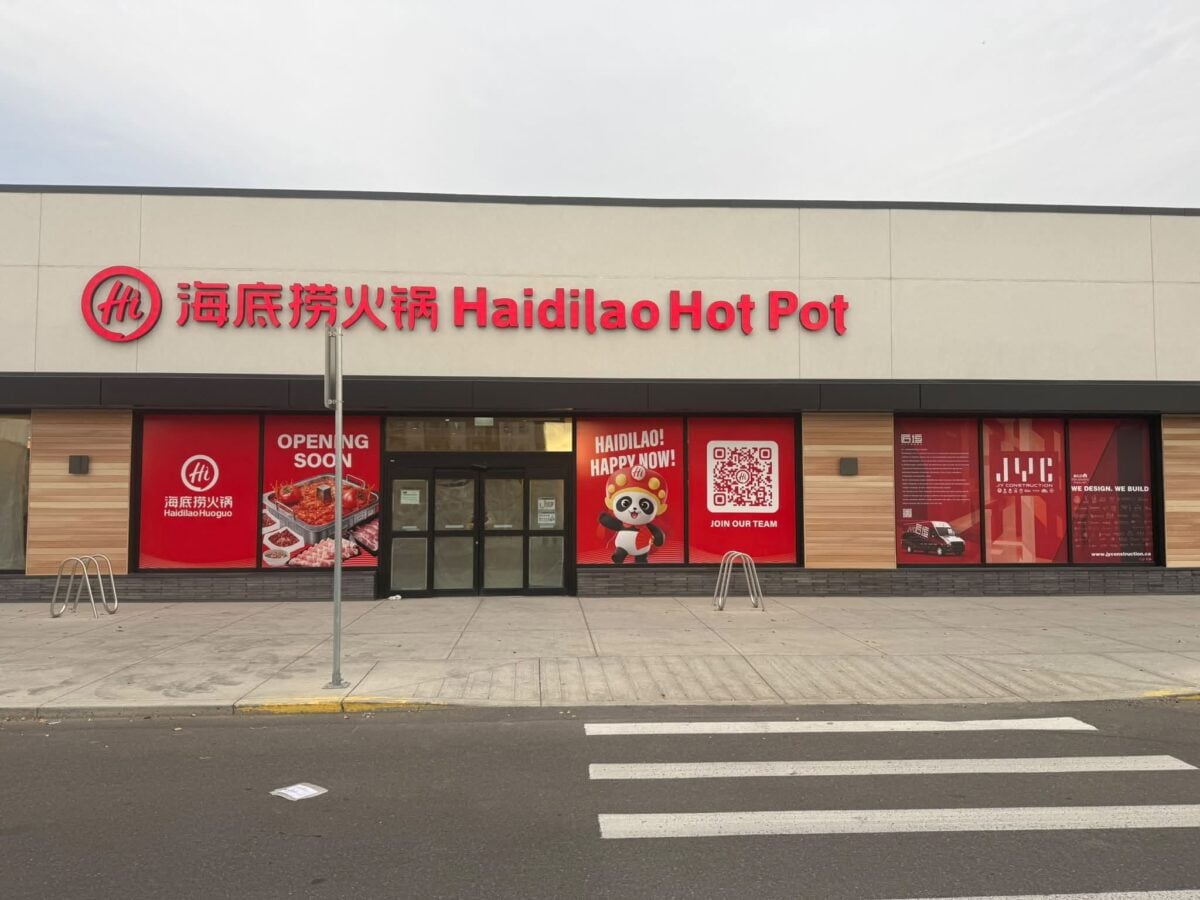
At Woodgrove, H Mart has been confirmed for roughly 30,000 square feet alongside TM Wander and family entertainment uses. Haidilao is planned for Mayfair, while another international retailer has been in negotiations involving both properties.

Expected combined landlord and tenant investment at Woodgrove is approximately $30 million to $40 million, including about $10 million from the landlord. Major uses are targeted for spring or summer 2028, subject to permitting and approvals.

The strategy replaces one large anchor with several reasons to visit across different parts of the day. Its contribution to traffic, tenant sales and property performance will become measurable once those businesses are operating.

At CF Sherway Gardens in Toronto, Splitsville plans a 34,000-square-foot bowling and entertainment venue in part of the former approximately 140,000-square-foot Nordstrom, targeting fall 2027. The lease is significant, but represents one component of the former anchor’s reuse.

Capital Is Still Moving Into Canadian Retail Property

Major ownership and financing activity continued during the quarter. The $9.4-billion transaction involving First Capital, KingSett Capital and Choice Properties would see Choice acquire approximately $5 billion of assets, with KingSett acquiring the remaining assets and outstanding units. The transaction had received court approval in late June 2026.

Westcliff’s acquisition of Edmonton’s approximately 880,000-square-foot Kingsway Mall from Oxford represented a different investment case. The property moved to an established private shopping-centre owner, with no immediate comprehensive redevelopment announced.

Jadco’s acquisition of the corporate entity holding Montreal’s Centre Rockland offers longer-term redevelopment possibilities, although no new master plan or former-Hudson’s Bay replacement had been announced.

Primaris raised approximately $200 million through an equity offering while reporting more than $1 billion of potential mall acquisitions under negotiation. The financing provides capacity for further investment, while negotiations remain separate from completed acquisitions.

Ownership changes can support continued operation, portfolio consolidation or redevelopment. Their significance depends on the business plan that follows.

Edmonton City Centre Highlights the Operating Challenge

Edmonton City Centre illustrates the different timelines of long-term redevelopment and current retail operations. A court approved Westrich’s proposed acquisition in August. Initial plans included approximately 1,500 homes, street-oriented retail and a rooftop Nordic spa on the former Hudson’s Bay portion, with major project details and construction timing still subject to further work and approvals.

Businesses in downtown Edmonton have meanwhile reported concerns involving public safety, vandalism, parking and prolonged construction access. Chamber survey results and business interviews identify conditions affecting merchants, although they do not establish that any single factor caused business closures.

Additional residents and destination uses could broaden the area’s catchment over time. Existing businesses still need workable access and trading conditions while redevelopment proceeds.

Broader Industry Coverage

Canada’s Retail Property Market Is Increasingly Selective

National data provide an important counterweight to the strongest landlord results. CoStar reported that Canada’s overall retail vacancy rate increased from approximately 1.8% to 2.5% following Hudson’s Bay closures and remained near that level over the subsequent year. Shopping-mall vacancy rose from approximately 3.1% to 8% in Q2 2025, when the closures produced almost five million square feet of negative net absorption.

CoStar expects overall vacancy to remain around 2.5% over the next year and mall vacancy to remain near 7% in three years. Retail rent growth, slightly above 2% in Q2 2026, is forecast to slow to roughly zero by Q2 2027 before recovering. About five million square feet of retail space was under construction in Q2 2026, while quarterly starts have remained below one million square feet since Q3 2025. Existing anchor vacancies still require suitable tenants, workable configurations and viable redevelopment economics.

CBRE’s first-half Canadian survey showed how sharply conditions differ by property type and location. Rents increased across 28 of 131 tracked formats and key urban areas and declined in eight, with grocery, service, medical, fitness and quick-service restaurant demand supporting parts of the market. A well-located grocery-anchored suburban centre can operate near capacity while an enclosed mall in the same metropolitan area works through a major anchor vacancy.

Retail sales add another consideration. Statistics Canada reported seasonally adjusted Q2 retail sales growth of 2.2% in current dollars but 0.4% in volume. July sales were up 5.1% year-over-year in dollars and 1.7% in volume.

The figures do not establish sales at individual properties, but the gap between nominal and volume growth matters when assessing retailer performance and capacity to absorb higher occupancy costs.

Headline Leasing Numbers Need Context

Strong leasing metrics can describe very different underlying circumstances. RioCan provided a useful example during its Q2 call when management discussed a GTA grocery lease renewed at double its previous rent. Management subsequently explained that the rent had last been negotiated at market approximately 30 years earlier, with relatively flat fixed renewal options in the intervening period. The increase captures decades of accumulated rental adjustment. It does not indicate that GTA grocery rents doubled over the preceding year.

Choice Properties’ results demonstrate the same issue differently. Its average Q2 renewal spread was 12.4%, rising to approximately 20% when fixed-rate options were excluded. Occupancy figures also depend on their definitions and denominators.

Morguard reported Q2 retail occupancy of 89.7%, including 95% at community centres and 87.8% at enclosed centres. At Cambridge, approximately 65,700 square feet was removed from active leasable area during redevelopment, changing the space against which occupancy is calculated. Committed occupancy, in-place occupancy, economic occupancy and renewal spreads are useful measures, but they answer different questions. Their definitions become particularly important when large spaces are moving through redevelopment.

Strong Leasing Can Coexist With Development Risk

SmartCentres reported 98.1% in-place and committed occupancy and had re-leased four of six former Toys “R” Us locations by the time of its Q2 call. Approximately 247,000 square feet of vacant space was leased during the quarter.

At the same time, the REIT recorded a $196.2-million fair-value loss on investment properties, reflecting market conditions and anticipated construction timing for certain future development properties, partly offset by lower discount rates at selected retail properties. Operating retail assets and future development properties can therefore produce very different results within the same portfolio.

The same applies to residential density associated with retail properties. Choice and RioCan described weaker conditions for selling residential density, while Primaris has emphasized that it intends to monetize suitable excess lands instead of becoming a residential developer. Long-term density can have value without contributing to current property income.

Editor’s Take & Outlook

What Retailers, Landlords and Investors Should Watch

For landlords redeveloping former anchors, rent commencement, capital requirements, tenant opening schedules and construction downtime will determine how quickly committed leasing becomes property income. Subsequent tenant sales and traffic will show how new uses affect the broader centre. Retailers considering former-anchor space need to account for landlord work, fit-out costs, possession dates, access during construction, neighbouring uses and the sequence of other openings.

For investors, high occupancy and strong renewal spreads remain important, but definitions matter. Committed space may not yet be producing rent, redevelopment can alter occupancy denominators, and unusually large rent increases can reflect leases that have not been reset to market for decades.

Capital requirements ultimately belong in the same analysis as the replacement rent being achieved.

Outlook: The Next Test Is Delivery and Cash Rent

The next several quarters will provide practical evidence of how Canada’s current leasing activity translates into operating property performance.

Primaris expects replacement tenants in former Hudson’s Bay space to begin taking occupancy in 2027, with other openings and rent commencements extending through subsequent years. At Galeries de la Capitale, tenants are expected to open progressively through 2027.

Splitsville is targeting fall 2027 at CF Sherway Gardens, while major new uses in Central Walk’s Vancouver Island redevelopment are expected in 2028.

At necessity-oriented properties, high occupancy and strong renewal spreads are already evident, while national rent growth is expected to moderate. Future results will show how durable those conditions remain across different markets and tenant categories.

The amount of space leased is one measure of progress. Openings, rent commencement and returns on invested capital will provide a more complete measure of the redevelopment cycle.

Editor’s Take

Canada’s strongest retail-property results can look remarkably good: occupancy approaching 100%, double-digit renewal spreads and major replacement leases for spaces vacated by department stores. Those numbers need to be read alongside what is happening inside the properties.

The former department-store redevelopment cycle is producing something structurally different from the anchors it replaces. One large box can become grocery, restaurants, entertainment and specialty retail, with each tenant requiring different space, investment and opening timelines.

That can ultimately produce higher rents and give consumers more reasons to visit a property throughout the day. The economics still depend on how much landlords and tenants spend to get there.

Over the next several years, the most revealing numbers may therefore come after the leasing announcements: stores opened, rent commenced, tenant sales and returns on redevelopment capital.

Those measures will show how successfully Canadian landlords have turned a historic wave of department-store vacancies into productive retail real estate.

Representative Articles

More From Retail Insider