

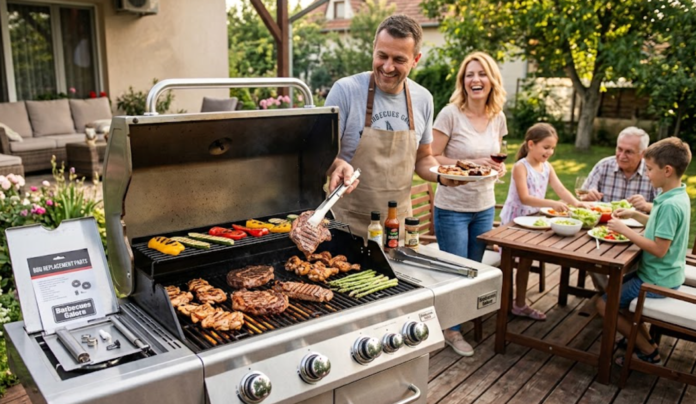
The secret to being an outdoor grilling master is a combination of top quality ingredients, temperature control and equipment that is well maintained. Barbecuing delivers a combination of pleasurable smokiness, crispy caramelized exteriors, and juicy internal textures that cannot be reproduced with standard kitchen appliances. Whether it’s a weekend get-together or an intimate family dinner, the right meat cuts, veggies, and flavor profiles turn an ordinary BBQ in the backyard into a culinary masterpiece.
Best Food Choices for the Outdoor Grill
Selecting foods that will respond well to direct heat and slow smoke is the first step to getting great results on the grill. High temperatures have a unique effect on different ingredients . They produce deep , savory flavors in the process . Fats react to heat and caramelize natural sugars .
Ribeye & Striploin Steak
Rich intramuscular marbling in high-grade cuts of beef glows under intense direct heat. The charred sear marks hold in the juices while melting the layers of fat, giving it a tender texture and a full-bodied flavor.
Slow-Smoked Pork Ribs & Shoulder
Tough collagen in pork ribs and shoulders breaks down slowly from reduced heat and indirect convective heat. Smoked over hardwood, these cuts are moist, fall-off-the-bone meat with a savory bark.
Marinated Poultry and Chicken
Acid marinades and medium indirect heat are good for whole birds, thighs and wings. Controlled cooking prevents flare-ups, keeps the interior juicy, and allows the skin to crisp.
Seasonal Vegetables (Charred)
Thickly sliced bell peppers, zucchini, asparagus and portobello mushrooms absorb smoky notes quickly. High heat caramelizes their natural sugars, giving depth and a bright contrast to heavy meat dishes.
Why Equipment Maintenance is Crucial for Food Quality
Uneven burner output, rusted heat diffusers or degraded cooking grates can ruin even the best cuts of meat. The inside parts of a grill will break down over time due to extreme heat, grease and the elements. Uneven heating causes dangerous cold spots and localized burning , and makes it nearly impossible to maintain precise control over the temperature .
Upgrading components with high-grade BBQ replacement parts will restore your grill to factory levels of performance without the need to buy a new unit. New burner tubes provide a steady, balanced gas flow, and new heat plates prevent aggressive flare-ups from dripping grease. Upgrade to heavy-duty stainless steel or cast-iron grates for superior heat retention for perfect searing and easy food release.
Best Performance Key Ingredients
To achieve consistent cooking results each time you turn the burners on, make sure the fluid pathways are clean and the thermal surfaces are solid.
Igniters and Burner Tubes
Because the burner ports were clean and not rusty the flame was evenly spread across the whole surface of the burner eliminating hot spots and creating predictable cooking times.
Flame Tamers and Heat Shields
Deflector plates protect burners from direct grease drippings, while vaporizing juices to add classic barbecue smoke to food.
Heavy Duty Cooking Grates
Thick cast-iron or stainless steel grates provide the thermal mass to quickly sear meats, locking in juices and creating professional-grade grill marks.
Getting Maximum Taste & Cooking Uniformity
Good gear and well thought-out planning are key for a successful outdoor meal. Outdoor chefs can control cooking zones, eliminate flare-ups and consistently deliver delicious results using top quality ingredients on a fully restored grill. With regular maintenance, timely component updates and proper heat management, every meal off the grill is at its maximum flavor potential.
Elevating Outdoor Cooking with Barbecues Galore and Essential Upgrades
Why Storefront Signage Remains Essential in an Omnichannel Retail Strategy
Retail brand management in today’s economy often revolves around digital touchpoints. E-commerce platforms, social media campaigns, automated email flows, and targeted search ads command a significant share of marketing budgets. Yet physical retail locations continue to drive the majority of total sales and remain essential for customer acquisition, brand awareness, and customer trust.
Within a physical location, exterior and interior visual graphics serve as the immediate connection point between a brand and a consumer. Physical storefront display elements set expectations before a customer ever steps through the door. Far from being a relic of traditional commerce, physical signage works alongside digital marketing channels to complete the consumer journey.
1. Bridging the Gap Between Online Search and Physical Foot Traffic
Today’s shoppers rarely distinguish between online and offline channels. A customer often discovers a business through a web search or social media ad before deciding to visit in person. When that customer arrives at a physical location, the transition must feel seamless.
A high quality exterior sign validates the customer’s decision to visit. If a shopper finds a sleek, contemporary brand identity online but encounters faded, poorly lit, or hard to read physical lettering at the storefront, brand trust evaporates instantly. Working with someone such as Kessler sign company allows retailers to translate complex digital visual guidelines into durable, high impact physical structures that maintain brand continuity.
Furthermore, location based search behavior hinges on physical visibility. A driver navigating to a storefront relies on clear pylon or monument signs long before reaching the parking lot entrance. Partnering with a professional sign company Columbus Ohio ensures that structural dimensions, illumination, and placement line up with actual sightlines, helping convert digital direction searches into successful foot traffic.
2. Converting Passive Commuters into Active Shoppers
Digital advertising requires consumers to engage with screens, often fighting against ad blockers and visual clutter. Storefront signage operates in the physical realm where message fatigue is significantly lower.
Every everyday commute, walking trip, or errand represents an opportunity to build brand familiarity. Exterior architectural displays, illuminated channel letters, and high visibility roadside markers work continuously to capture passive attention without requiring an ad click or algorithm trigger.
- Constant Exposure: Exterior signs communicate continuously, delivering thousands of visual impressions daily to local vehicle traffic and pedestrian movement.
- Geographic Relevance: Physical displays target individuals who live, work, or regularly travel near the store location, making them ideal local prospects.
- Impulse Visits: Eye catching window graphics and visible entry markers prompt spontaneous detours for consumers who were not actively shopping online at that moment.
When a retail location relies solely on digital messaging, it misses the opportunity to capture surrounding foot and vehicle traffic that may not interact with its digital ad channels.
3. Guiding the In Store Journey with Wayfinding and Interior Elements
An effective omnichannel strategy extends past the front door. Once a customer enters the store, the physical environment must support the browsing and purchasing experience. Interior graphic elements, wall installations, and directional signs play a critical role in directing customer flow and highlighting key product categories.
Clear wayfinding signs prevent shopper frustration. Customers who easily locate pickup counters for buy online pick up in store orders enjoy a friction free experience that encourages repeat purchases. Conversely, poor interior direction leads to store congestion and abandoned shopping trips.
In addition, custom interior displays allow brands to reinforce core marketing themes. Architectural wall graphics, pin mounted dimensional lettering, and illuminated interior logos create a professional environment that elevates perceived product value. An established sign company Columbus Ohio evaluates interior lighting, wall materials, and traffic patterns to ensure indoor signage supports both store operations and visual merchandising goals.
4. Maximizing Fleet Vehicles as Mobile Touchpoints
An integrated retail strategy often extends beyond the fixed physical store. Delivery fleets, service vans, and regional transport vehicles offer an opportunity to broadcast a retail brand across an entire metropolitan area.
Vehicle wraps and custom commercial fleet graphics transform company vehicles into moving billboards that reinforce local presence. When delivery trucks display consistent branding that matches storefront architecture and web design, brand recall increases substantially.
- Expanded Reach: Mobile wraps introduce brand visuals to diverse neighborhoods and commercial corridors outside the immediate store radius.
- Professional Authority: Branded delivery and service vehicles convey legitimacy and operational scale during customer drop offs.
- Cost Efficiency: A single vehicle graphic installation generates millions of visual impressions over its operational lifespan compared to recurring digital ad costs.
Integrating vehicle graphics into a broader visual communication plan ensures that every physical asset actively builds regional brand awareness.
5. Navigating Permitting, Code Compliance, and Technical Feasibility
Designing impactful visual graphics requires an understanding of municipal regulations, structural engineering, and site specifications. A beautiful sign design holds no value if local zoning laws forbid its installation or if material selections fail under regional weather conditions.
Local municipalities enforce strict ordinances covering allowable sign square footage, height restrictions, illumination levels, setback requirements, and historic district design guidelines. Securing necessary municipal approvals requires preparing accurate site surveys, structural drawings, and code compliant engineering plans before manufacturing begins.
An experienced sign company Columbus Ohio manages the regulatory process from initial site assessment through final inspection. Factoring in local electrical codes, wind load parameters, and mounting surface requirements during the initial design phase prevents costly project delays and ensures that storefront structures remain safe and compliant for years.
6. Utilizing Electronic Message Centers for Dynamic Visual Messaging
Static signage delivers long term brand identification, but current retail environments often require rapid content updates to match online promotions, seasonal sales, or local community events. Electronic message centers give brick and mortar retailers the ability to modify visual messaging instantaneously.
Integrating digital displays with exterior building structures creates a versatile communication tool. Retailers can highlight limited time offers, announce new inventory arrivals, or adjust featured products based on time of day or weather conditions.
This agility mirrors digital marketing strategies, allowing physical stores to respond quickly to market trends without wait times for new print collateral. Combining permanent channel letters or monument bases with programmed electronic message panels provides both long term brand recognition and real time marketing flexibility.
7. Investing in Long Term Physical Infrastructure for Durable Brand Value
Digital advertising campaigns require continuous financial investment to maintain visibility; once budget spend pauses, traffic drops instantly. In contrast, high quality physical signage functions as a durable capital asset that delivers long term brand exposure.
Selecting commercial grade materials like fabricated aluminum, weather resistant acrylics, high output LEDs, and UV protective coatings ensures that exterior displays maintain their structural integrity and visual appeal across seasons. Clean, well maintained signage signals stability and attention to detail, reinforcing customer trust in the retail brand.
Collaborating with a full service sign company Columbus Ohio ensures that structural design, fabrication precision, and expert installation receive equal attention. Comprehensive site surveys, precise material selection, and routine maintenance keep storefront displays functional, bright, and effective over long operational lifespans.
Sustaining Brand Impact Across Physical and Digital Spaces
A successful omnichannel strategy relies on seamless integration across every touchpoint. While digital platforms capture initial interest and facilitate online commerce, physical storefront signs, interior directions, and fleet graphics anchor the brand in the physical community. Investing in well planned, high quality visual elements protects brand equity, drives foot traffic, and ensures that physical locations remain compelling destinations for shoppers.
Surviving Canadian Winters: Why You Need the Seeker 4 Pro
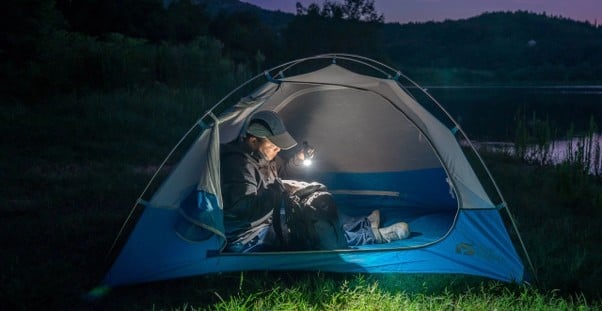
Canadian winters bring a unique set of challenges for outdoor enthusiasts. From snow-covered trails and early sunsets to winter camping and ice-fishing trips, reliable lighting can make a meaningful difference when visibility is limited. Choosing a flashlight for cold weather requires more than looking at brightness alone: battery management, ease of operation, runtime and safe handling all matter.
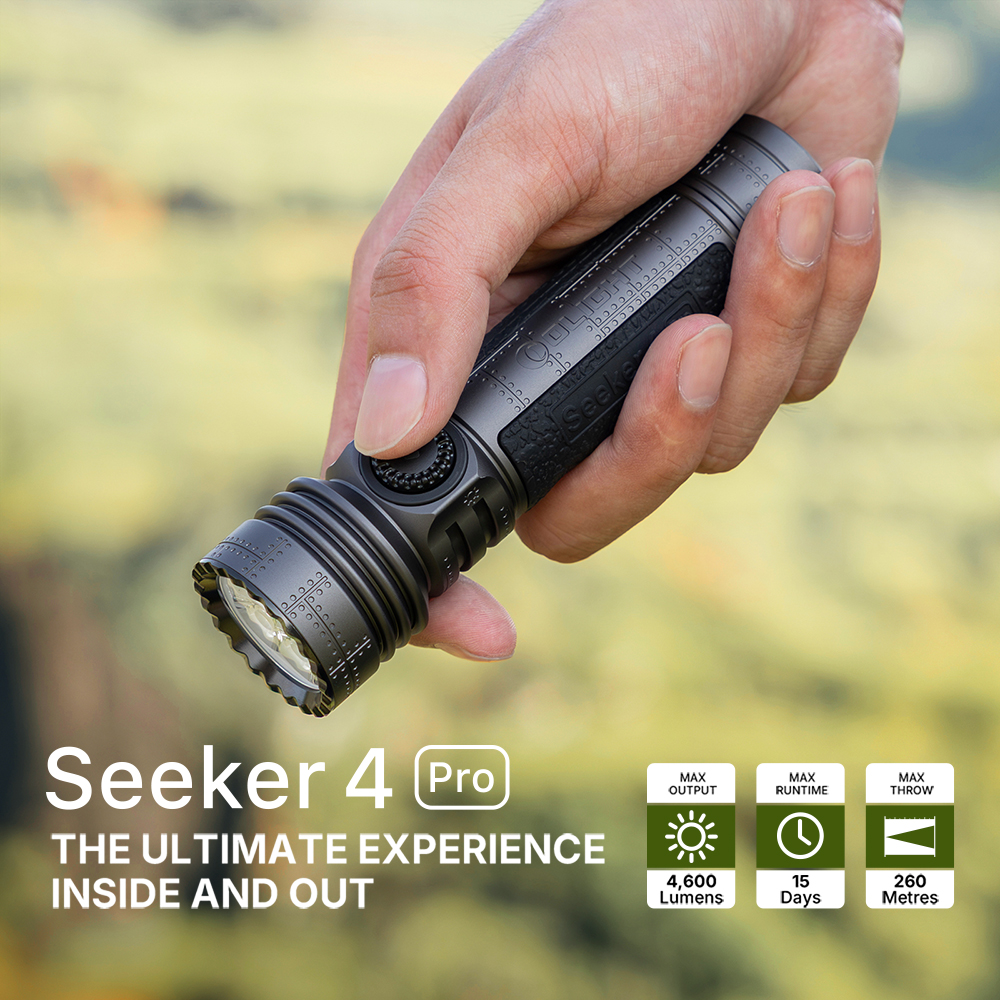
The Olight Seeker 4 Pro is a high-power flashlight designed for users who need versatile illumination for outdoor activities and everyday tasks. With a maximum output of 4,600 lumens, a beam distance of up to 260 metres and multiple brightness modes, it offers flexibility for different lighting situations. For Canadian users preparing for winter, understanding both its capabilities and its operating limits is essential.
1. Cold-Weather Performance You Can Trust
During Canadian winters, outdoor flashlight needs can change quickly. A short walk from a parking area may turn into a longer trek, while checking a campsite or finding equipment in low light can require more illumination than an ordinary pocket light provides.
The Seeker 4 Pro offers a maximum output of 4,600 lumens and a beam distance of up to 260 metres, according to its manufacturer’s specifications. This combination can help illuminate a wider area around a campsite or provide a longer-reaching beam when checking the route ahead. Its adjustable brightness also allows users to choose a more suitable level for closer tasks, rather than relying on maximum output for every situation.
Another practical consideration is operation while wearing winter gloves. The Seeker 4 Pro features an enlarged metal side switch with rotational brightness adjustment, making it easier to change output without removing heavy gloves. That can be particularly useful when setting up equipment, checking a tent area or adjusting lighting during a cold-weather outing.
The flashlight is also rated IPX8 for water resistance, according to the product manual. This is a useful feature for outdoor equipment that may encounter wet conditions, although users should follow the manufacturer’s instructions for proper use and maintenance.
Product specifications: Olight Seeker 4 Pro User Manual
An important temperature note: The referenced Seeker 4 Pro manual lists an operating temperature range of 0°C to 40°C. It should not be presented as a flashlight rated for operation below 0°C. Canadian users should check the manual supplied with their specific model and follow its stated limits, especially when planning winter activities.
2. Battery Behaviour in Cold Weather
Cold weather can affect the performance of rechargeable lithium-ion batteries. For anyone preparing for an outdoor trip, battery planning is therefore just as important as choosing a sufficiently bright light. Health Canada provides guidance on the safe use and care of lithium-ion batteries.
The Seeker 4 Pro uses a 5,000 mAh, 3.6 V rechargeable lithium-ion battery and supports USB-C charging. Its included charging setup makes it convenient to recharge before heading out, while the battery-level indicators help users check the remaining charge.
For winter preparation, a few practical habits can help:
- Charge before departure: Start with a fully charged flashlight rather than relying on a partial charge.
- Plan around the operating-temperature range: The referenced manual specifies 0°C to 40°C. Do not assume that the flashlight is rated for sub-zero operation.
- Monitor the battery level: Check the indicators before leaving and during use when conditions allow.
- Consider the full trip: For longer outings, plan your lighting needs in advance and carry suitable backup lighting where appropriate.
USB-C charging is a convenient feature for users who already bring compatible charging equipment on trips. However, charging convenience does not change the flashlight’s specified operating-temperature range, and actual battery performance can vary with use and environmental conditions.
For winter preparation, the key is to choose equipment that suits the expected conditions and to follow its instructions, rather than assuming that a high-capacity battery alone guarantees reliable performance in extreme cold.
3. Visibility in Snow and Whiteout Conditions
Snow can make nighttime navigation more complicated. Falling snow, blowing flakes and reflective surfaces may affect how clearly a person can see the route ahead. A powerful light can help illuminate the surrounding area, but brightness alone does not guarantee better visibility in every condition.
The Seeker 4 Pro’s maximum output of 4,600 lumens gives users a high-output option when more illumination is needed. Its beam distance of up to 260 metres can also be useful when checking distant surroundings in suitable conditions. For closer tasks—such as locating gear, checking a trail marker or organising equipment—a lower brightness setting may be more comfortable and practical.
When using a flashlight in falling snow, consider directing the beam slightly downward instead of shining it straight ahead at eye level. Adjusting the angle and brightness can help reduce unnecessary glare from nearby snowflakes. In poor visibility, slow down, stay aware of the route and avoid relying on the flashlight as a substitute for appropriate navigation tools.
Canadian winter weather can change rapidly, and snow, wind and reduced visibility may create hazards beyond what a flashlight can address. Environment and Climate Change Canada offers guidance on cold-season weather hazards.
For outdoor users, the benefit of a versatile winter camping flashlight is not simply maximum brightness. It is the ability to adjust the light to the task, whether checking the immediate surroundings or illuminating a farther point in suitable conditions.
4. Seeker 4 Pro for Winter Camping and Ice Fishing
Winter camping and ice fishing often involve several different lighting needs. Users may need to organise equipment, locate supplies, check the area around a shelter or move between nearby activity zones after daylight fades. A flashlight with multiple brightness settings can help accommodate these changing tasks.
The Seeker 4 Pro provides several output levels, from a 4,600-lumen Turbo mode to lower settings for close-up tasks. Its 300-lumen Medium mode can be a practical option for general lighting, while lower output can help conserve power when only modest illumination is needed. The enlarged side switch and rotational dimming also make brightness adjustment more convenient when users are wearing heavier gloves.
For camping, the included holster offers a dedicated way to store and carry the flashlight. The product’s USB-C charging capability also supports preparation before departure, allowing users to check their equipment and recharge ahead of a planned outing.
For ice fishing, lighting is only one part of preparation. Conditions on frozen lakes can change, and ice thickness may vary across the same body of water. A bright flashlight should never be treated as proof that ice is safe to cross. Before heading out, consult local conditions and official guidance, including the Canadian Coast Guard’s ice safety information.
The Seeker 4 Pro is best considered as one component of a broader outdoor safety setup—not a replacement for suitable clothing, navigation equipment, emergency supplies or careful trip planning.
5. Comparing Runtime Modes for Long Trips
When selecting a rechargeable flashlight, maximum brightness is only one part of the decision. Runtime matters too, particularly when users need to manage their lighting over an extended outing.
The Seeker 4 Pro offers several brightness levels to suit different tasks. According to the manufacturer’s manual, its published output and runtime figures include:
| Mode | Published output | Published runtime |
| Turbo | 4,600 lumens | 2.5 minutes at full output, followed by lower output stages |
| High | 1,200 lumens | 135 minutes at the initial output stage, followed by lower output stages |
| Medium | 300 lumens | 11 hours |
| Low | 50 lumens | 60 hours |
| Moonlight | 5 lumens | 15 days |
These figures are manufacturer laboratory reference results; actual performance can vary with usage and environmental conditions.
These modes offer different trade-offs. Turbo provides a burst of very high output when a strong beam is needed, but it is not designed to maintain maximum brightness continuously. Medium may be more appropriate for routine campsite tasks, while Low and Moonlight are useful when only limited illumination is required and conserving power is a priority.
For users comparing flashlight runtime, the practical question is not simply which mode lasts the longest. It is which mode provides enough light for the task without using more output than necessary. Choosing a suitable setting and checking the battery before departure can help users plan their lighting more effectively.
Remember that the published runtime figures should not be interpreted as guaranteed performance in cold conditions. Follow the product’s specified operating-temperature range and plan for the conditions expected on your trip.
6. Final Thoughts for Canadian Outdoor Users
Canadian winters call for thoughtful preparation, especially when outdoor activities continue after daylight fades. A useful winter lighting setup should balance illumination, runtime, ease of operation and safe handling—not just headline brightness.
The Olight Seeker 4 Pro brings several practical features together: a maximum output of 4,600 lumens, a beam distance of up to 260 metres, multiple brightness modes, an enlarged metal side switch and USB-C charging. These features make it worth considering for outdoor users who want a versatile, high-output flashlight for camping, equipment checks and other lighting tasks.
At the same time, the specified operating-temperature range matters. The referenced manual lists 0°C to 40°C, so users planning Canadian winter activities should confirm the instructions for their exact model and ensure the expected conditions fall within its stated limits.
If you are comparing a Seeker 4 Pro option for your outdoor kit, review the full specifications and usage guidance before making a decision.
From The Desk: Social Media Growth, Store Modernization and AI’s Impact on Retail Marketing
Hello, and welcome to another edition of From the Desk of Craig Patterson.
It’s been another interesting week in Canadian retail, with businesses taking a closer look at how and where they invest for growth. Opening more stores remains part of the picture, but we’re also seeing greater attention paid to improving existing locations, strengthening digital engagement and creating shopping experiences that give customers a reason to return. From food service and fashion to luxury resale, retailers are taking different approaches to reaching consumers in an increasingly competitive market.
Retail real estate is evolving alongside these changes. Grocery-anchored shopping centres and mixed-use developments continue to attract interest, while landlords are paying closer attention to tenant mix, store quality and the long-term performance of their properties. It’s a reminder that successful retail destinations depend on more than simply filling vacant spaces. The right combination of businesses, services and experiences can make a meaningful difference in attracting customers and keeping them coming back.
Technology is also changing how retailers communicate with shoppers. As artificial intelligence makes it easier to produce marketing content and automate customer interactions, maintaining a distinctive brand identity becomes increasingly important. There’s considerable value in these new tools, but personal service, knowledgeable employees and memorable in-store experiences remain difficult to replicate. Finding the right balance between digital efficiency and genuine human connection will be an important consideration for retailers moving forward.
Here are some of the stories and developments that caught our attention this week.
Retailer News
Tahini’s acceleration plans to add 30 new restaurants across Canada and the U.S. rely heavily on its social media presence with over three million YouTube subscribers, which drives brand awareness and brings in franchisees who discover the concept online. This approach shows how digital engagement is becoming crucial in franchising and site selection, affecting landlords and suppliers by changing the profile of expansion opportunities. Walmart Canada’s plan to relocate its Supercentre into Calgary’s Southcentre Mall by 2028 demonstrates the retailer’s investment in modern, large-format stores while contributing to the mall owner Oxford Properties’ strategy to enhance shopping centres by replacing former Hudson’s Bay boxes.
Kith’s opening of its second Canadian store at Vancouver’s Oakridge Park, with an emphasis on streetwear and contemporary fashion alongside its dessert concept, signals growing consumer appetite for diverse retail offerings within mixed-use developments. Meanwhile, Mine & Yours is expanding its luxury resale footprint through partnerships with Holt Renfrew in major Canadian cities, reflecting the integration of pre-owned designer goods into mainstream luxury retail and providing new opportunities for retailers and landlords. The relaunch of JACOB under Cristelle Basmaji, focusing on beauty and accessories while avoiding reopening stores, illustrates how legacy brands can leverage existing customer loyalty with less risk and adaptation to the current retail environment, a strategy with implications for retail partnerships and space utilisation.
Retailer Financials / Trends / Reports
Groupe Dynamite has expanded its Dynamite 3.0 store concept in key Canadian shopping centres, upgrading store interiors, merchandise curation and in-store styling to improve customer experience and sales productivity. The retailer’s reinvestment signals a shift towards enhancing existing locations for stronger brand positioning in women’s fashion, which could positively affect landlord property values if the financial performance remains steady.
Retailer People News
A Mississauga entrepreneur has launched Butter Bar Boutique, a specialty store focusing on gourmet flavoured butters and Canadian culinary goods, while simultaneously growing the wholesale side of the business through partnerships with local producers such as The Alliston Creamery. This expansion into retail and wholesale channels reflects a strong market for artisanal food products and shows how small producers can build scale by combining storefront presence with broader distribution in Ontario’s food sector.
TJL Collection, a fashion brand catering to tall women, lowered its customer acquisition costs from $38 to $18 by using focused marketing methods including customer insights and freelance creative testing. This targeted approach has helped the brand increase its annual revenue from $475,000 in 2025 to a forecasted $800,000 in 2026, demonstrating the impact of precise audience targeting and marketing efficiency for niche retailers.
Retailer Op-Eds
Retailers are confronting a new challenge as artificial intelligence enables rapid production of marketing content that often lacks distinctiveness, making it harder to maintain authentic brand voices. The widespread use of AI-generated language tends to create generic messaging, pressing brands to focus more on authentic stories, human insights and consistent communication to engage customers effectively. Alongside this, investing in knowledgeable staff and fostering personal relationships in physical stores is becoming a key differentiator as consumer trust and empathy grow increasingly important in retail. The human touch offers retailers a sustainable advantage beyond what AI can replicate, reinforcing the value of expertise and trust as automation expands across data analysis and creative tasks.
Editor’s Take
One of the themes emerging in Canadian retail is a more selective approach to growth. Opening new stores remains important, but retailers are increasingly looking at how to make their existing operations more productive, strengthen customer relationships and invest where they see the greatest potential for returns. In an environment where consumers remain cautious and operating costs are elevated, expansion for its own sake is becoming harder to justify.
We’re seeing different approaches to this across the industry. Restaurant chain Tahini has demonstrated how a strong social media presence can help build brand awareness and support franchise expansion, while Groupe Dynamite is investing in store improvements and more personalised shopping experiences. Food service operators are also adapting, whether through value-oriented menu offerings, loyalty programs or changes designed to improve operating efficiency. The common thread is a greater focus on understanding customers and giving them compelling reasons to spend.
Retail real estate is undergoing a similar reassessment. With new construction relatively limited, attention is shifting toward existing properties, grocery-anchored shopping centres and mixed-use developments that combine retail with residential uses. These formats can benefit from recurring customer visits and established surrounding communities. Traditional enclosed malls aren’t necessarily losing their relevance, but landlords are becoming more selective about where they invest and which properties offer the strongest long-term prospects.
Primaris provides an interesting example of this approach. Its decision to sell its interest in Kingston’s Cataraqui Centre while acquiring an interest in Upper Canada Mall reflects how retail property owners are reassessing their portfolios and directing capital toward assets they believe offer stronger opportunities. Not every shopping centre will benefit equally from changing consumer habits, and the ability to attract productive tenants and manage vacancies will remain important.
Another development worth watching is the growing use of artificial intelligence in retail marketing. AI can help businesses communicate more efficiently and reach customers in new ways, but I wonder whether an increasing volume of automated content could eventually make many brands sound remarkably similar. Retailers still need something distinctive to say, and customers need reasons to believe what they’re being told.
This is where knowledgeable employees, authentic brand stories and well-executed physical stores can make a difference. Specialty retailers in particular have opportunities to distinguish themselves through expertise, personal relationships and experiences that aren’t easily replicated online. Businesses such as TJL Collection illustrate the continuing value of a more personal approach to retail, even as digital tools become increasingly sophisticated.
Looking ahead, I believe the strongest opportunities in Canadian retail will come from businesses that understand where to invest and where to exercise restraint. Technology will play an important role, but so will the fundamentals: productive stores, capable employees, relevant merchandise and a clear understanding of the customer. For retailers and landlords alike, the challenge isn’t simply finding ways to grow. It’s making sure that growth creates lasting value.
This Week’s Articles
Retailer News
- Canadian Franchise Sector Supports Nearly 2 Million Jobs: CFA — Mario Toneguzzi — Oct 23
- OpenTable report highlights restaurants’ economic impact on Canadian communities — Mario Toneguzzi — Oct 23
- Tahini’s targets 30 new restaurants as social media drives franchise growth — Mario Toneguzzi — Oct 23
- Toronto-Based Panda Hub Raises $4 Million to Expand Mobile Car Care Marketplace — Mario Toneguzzi — Oct 23
- Canadian Small Businesses Emphasize Local Identity as Holiday Costs Rise: VistaPrint Survey — Mario Toneguzzi — Oct 23
- Kith Opens Second Canadian Storefront at Vancouver’s Oakridge Park — Craig Patterson — Oct 23
- NAPA Canada Sales Rise 9% as Acquisitions Drive Expansion Amid Soft Market — Lee Rivett — Oct 22
- MUJI opening first Vancouver Island store as Canadian expansion continues — Mario Toneguzzi — Oct 22
- WitchSchool Canada Tests ‘Reciprocal Retail’ Model in Ottawa’s ByWard Market — Craig Patterson — Oct 22
- Cozey doubles size of Toronto flagship showroom (Photos) — Mario Toneguzzi — Oct 22
- CouchHaus Expands Toronto Presence With New King East Pop-Up Showroom — Mario Toneguzzi — Oct 22
- Canadian Small Business Confidence Edges Up in October as Fuel Costs and Tariffs Weigh: CFIB — Mario Toneguzzi — Oct 22
- Two-thirds of small business owners plan to exit within decade, CFIB says — Mario Toneguzzi — Oct 22
- One in four Canadian small business owners required to guarantee financing personally: Equifax — Mario Toneguzzi — Oct 22
- HEINZ enters Canada’s ready-to-eat soup market with six new products — Mario Toneguzzi — Oct 22
- Canadian small businesses expand teams as employee turnover declines: Wagepoint — Mario Toneguzzi — Oct 22
- Pinterest teams up with Mattel for Barbie experience — Mario Toneguzzi — Oct 22
- Mine & Yours Celebrates 13 Years with Glamorous Toronto Fashion Show as Canadian Expansion Continues — Craig Patterson — Oct 22
- Kleanr Cosmetics Launches First Ever Machine Washable Makeup Brushes — Mario Toneguzzi — Oct 22
- More Canadians tapping into savings or borrowing to pay for food: Dalhousie report — Mario Toneguzzi — Oct 22
- EMERGE Commerce forecasts 5% revenue growth and 20% EBITDA increase in Q3 2026 — Mario Toneguzzi — Oct 22
- JACOB Begins New Chapter as Founder’s Daughter Revives Canadian Fashion Brand — Craig Patterson — Oct 21
- Odd Cookie Expands Across Canada, Reaching Nearly 1,000 Retail Locations in First Year — Mario Toneguzzi — Oct 21
- Tim Hortons adds steak breakfast wrap and limited-time energy drinks — Mario Toneguzzi — Oct 21
- Alrifai Real Estate planning modular apartments on Gateway Mall rooftop in Prince Albert — Mario Toneguzzi — Oct 21
- New Walmart Supercentre coming to Calgary’s Southcentre Mall — Mario Toneguzzi — Oct 21
- Revenue Brand Uses ’80s Action TV Nostalgia to Reimagine Fashion Marketing (Video) — Mario Toneguzzi — Oct 21
- Walmart Canada brings back holiday collection with Tori Wesszer — Mario Toneguzzi — Oct 21
- TD Insurance Brings Small Business Advice to Toronto Entrepreneurs Through Elevator Pitch Event — Mario Toneguzzi — Oct 21
- Roku Expands Streaming Strategy as Competition for Viewers Grows — Mario Toneguzzi — Oct 21
- Museum of Toronto to Transform Historic Downtown Bank Space into New Cultural Destination — Craig Patterson — Oct 20
- Canadians plan to spend less on holidays as budgets tighten: survey — Mario Toneguzzi — Oct 20
- Amazon to hire 9,000 seasonal workers across Canada for holiday season — Mario Toneguzzi — Oct 20
- JLL expert talks about the current retail landscape in Canada — Mario Toneguzzi — Oct 20
- Nintendo and EB Games Detail Strategy Behind Toronto Store-Within-a-Store — Craig Patterson — Oct 20
- The Generall Store Launches National Gift Guide Featuring 88 Independent Canadian Retailers — Craig Patterson — Oct 20
- Aritzia Could Target $10 Billion in Revenue as Stifel Examines Next Phase of Growth — Lee Rivett — Oct 20
- Vistar Media Research Shows How Seasonal Products Shape Canadian Consumer Behaviour — Mario Toneguzzi — Oct 20
- Toronto Hair-Removal Clinic Owner Sees Shift Toward Sugaring, Laser and Long-Term Savings — Mario Toneguzzi — Oct 20
- Twenty Two Media Launches foodism Creator Program With Six Toronto Influencers — Mario Toneguzzi — Oct 20
- Primaris to Sell $41.8 Million Stake in Kingston’s Cataraqui Centre Amid Portfolio Reshaping — Craig Patterson — Oct 19
- Golf Town Plans National Store Modernization Following $15 Million Oakville Flagship — Craig Patterson — Oct 19
- Bank of Canada surveys show consumers pulling back as trade uncertainty persists — Mario Toneguzzi — Oct 19
- Staples Canada launches new business brand targeting organizations of all sizes — Mario Toneguzzi — Oct 19
- OPA! of Greece increases protein portions by up to 25 per cent — Mario Toneguzzi — Oct 19
- Merrithew launches first wood Pilates reformer for professional fitness market — Mario Toneguzzi — Oct 19
- Shoppers Drug Mart partners with Pinterest on first beauty trend report — Mario Toneguzzi — Oct 19
- Crate & Barrel Holdings expands into wallcoverings with new collections — Mario Toneguzzi — Oct 19
- STRONG Pilates launches global campaign promoting single fitness membership (Video) — Mario Toneguzzi — Oct 19
Retailer Financials / Trends / Reports
- Retail Insider’s Canadian Retail Monitor: October 2026 — Retail Spending Rebounds, but Growth Remains Uneven — Craig Patterson — Oct 24
- Retail sales climb to nearly $75 billion in August: Statistics Canada — Mario Toneguzzi — Oct 23
- Retail Insider “Q3 2026 Apparel & Fashion Report”: Stores Have to Earn Their Investment — Lee Rivett — Oct 23
- Retail Insider “Q3 2026 Grocery Report”: More Capacity, a Harder Fight for the Basket — Lee Rivett — Oct 22
- Retail Insider “Q3 2026 Food Service Report”: Growth Must Pay at Restaurant Level — Lee Rivett — Oct 21
- Inside Dynamite 3.0: How Groupe Dynamite Is Reinventing Its Canadian Stores — Lee Rivett — Oct 21
- Retail Insider “Loss Prevention & Security Q3 2026 Report”: Different Risks Demand Different Responses — Lee Rivett — Oct 20
- Canadian consumers facing higher prices: Statistics Canada — Mario Toneguzzi — Oct 19
Retailer People News
- RETHINK Retail Expands Executive Communities Under Canadian Leadership — Craig Patterson — Oct 24
- TJL Collection Cuts Customer Acquisition Costs With Targeted Marketing for Tall Women — Mario Toneguzzi — Oct 20
- Mississauga entrepreneur opens butter-focused retail shop and expands wholesale business — Mario Toneguzzi — Oct 19
Retailer Op-Eds
- When Every Brand Sounds the Same: The Challenge of Standing Out in the Age of AI — Retail Insider — Oct 21
- In the Age of AI, Investing in the Human Touch Is Fundamental for Retailers — Retail Insider — Oct 19
News From Around the Web
Retail Insider’s Canadian Retail Monitor: October 2026 — Retail Spending Rebounds, but Growth Remains Uneven
Canadian retail sales rebounded in August 2026, rising 1.2% to $74.6 billion as all nine major retail subsectors recorded monthly gains, according to Statistics Canada. The improvement followed a July decline and was accompanied by a 1.2% increase in inflation-adjusted sales volumes, providing an encouraging indication of retail purchasing activity heading into the fall.
The annual figures tell a more complicated story. Retail sales increased 5.4% in current dollars compared with August 2025, while chained-dollar sales volumes rose 1.8%, reflecting a considerably smaller increase in inflation-adjusted retail activity.
The October edition of Retail Insider’s Canadian Retail Monitor examines retail trade, wholesale distribution, consumer prices and the products Canadians are purchasing. The latest reports cover August retail and wholesale trade, July retail commodity sales and September inflation, providing a broad assessment of the Canadian retail economy as businesses prepare for the final quarter of the year.
This Month’s Canadian Retail Analysis
Canadian Retail Dashboard
| Indicator | Latest reading | Reference period |
|---|---|---|
| Total retail sales | $74.6 billion, +1.2% monthly | August 2026 |
| Retail sales, annual change | +5.4% | August 2026 |
| Retail sales volume, chained dollars | +1.2% monthly; +1.8% annually | August 2026 |
| Core retail sales | +1.1% monthly | August 2026 |
| Retail e-commerce | $5.65 billion, +15.3% annually | August 2026 |
| E-commerce share | 7.6% of total retail sales | August 2026 |
| Wholesale trade | $91.6 billion, −1.6% monthly | August 2026 |
| Retail commodity sales | $77.8 billion, +5.0% annually | July 2026 |
| Consumer Price Index | +3.1% annually | September 2026 |
| Grocery inflation | +1.7% annually | September 2026 |
| Advance retail sales estimate | +0.7% monthly, preliminary | September 2026 |
Source: Statistics Canada. Retail and wholesale trade figures are seasonally adjusted unless otherwise indicated. Retail commodity figures are unadjusted. The wholesale headline excludes petroleum-related products and oilseed and grain. The September retail estimate is preliminary.
Statistics Canada’s August Retail Trade report shows Canadian retailers generated $74.57 billion in sales, compared with a revised $73.69 billion in July. The 1.2% increase followed a 0.7% decline in July, when sales had fallen across eight of the nine major retail subsectors.
Retail Sales Rebound After July Decline
The improvement was broad, with every major subsector recording a monthly increase. Motor vehicle dealers, food and beverage retailers, health and personal care businesses, general merchandise stores and home-related retailers all contributed to the recovery.
Core retail sales, excluding motor vehicle and parts dealers as well as gasoline stations and fuel vendors, increased 1.1% following a 0.7% decline in July. The improvement indicates that the recovery extended beyond the automotive and fuel categories.
What Drove Canada’s August Retail Growth?
Ontario and British Columbia made important contributions to the national increase, while several major retail categories recovered from weaker July results. Health and personal care retailers continued a prolonged period of growth, and general merchandise stores recorded higher sales following a monthly decline.
Furniture, home furnishings, electronics and appliance retailers posted one of the stronger monthly percentage gains, increasing 2.3%. However, the category remained below its sales level from a year earlier, illustrating the difference between a short-term rebound and sustained annual growth.
The latest figures provide evidence of improved monthly retail activity, although they do not establish that consumer demand has strengthened equally across retailers, markets or merchandise categories.
Price vs. Volume: Where Growth Is Real
Retail sales measured in chained dollars increased 1.2% in August, matching the nominal monthly growth rate. This shows that inflation-adjusted retail activity improved alongside reported sales revenue.
Annual comparisons are less robust. Current-dollar sales increased 5.4%, while chained-dollar sales volumes rose 1.8%, indicating that the growth in retail spending substantially exceeded the increase in inflation-adjusted activity.
Statistics Canada’s separate industry-level constant-price series showed annual growth of 2.0% for total retail trade. The two inflation-adjusted measures use different methodologies and should not be treated as identical, although both point to considerably more modest annual growth than the nominal sales figure.
For retailers, the distinction is commercially important. Revenue growth does not necessarily indicate equivalent increases in merchandise quantities, customer traffic or profitability, particularly when prices and product mix are changing.
Retail Sector Pulse
Health and Beauty Continues to Lead
Health and personal care retailers remained among Canada’s strongest major retail categories in August, generating $6.80 billion in sales. Revenue increased 1.6% from July and 13.1% compared with August 2025, marking the sector’s tenth consecutive monthly increase.
Sales at constant prices increased 10.6% annually, confirming substantial inflation-adjusted growth. The performance stands out against the much smaller annual volume increases recorded across total retail trade.
The category includes pharmacies and other health and personal care retailers, businesses that occupy a significant presence in shopping centres, neighbourhood plazas and street-front retail districts. Continued growth in this segment is relevant for landlords assessing tenant demand and for retailers competing in health, wellness and personal care merchandise.
Apparel and Fashion Shows Uneven Growth
Clothing, footwear, jewellery, luggage and leather goods retailers generated $4.12 billion in August sales, increasing 0.4% from July and 3.3% annually. At constant prices, sales increased 6.2% compared with August 2025, indicating stronger inflation-adjusted activity than the nominal revenue figures suggest.
Clothing and clothing accessories retailers recorded $3.21 billion in sales, up 2.8% annually. Jewellery, luggage and leather goods retailers performed more strongly in current dollars, reporting a 13.6% increase to approximately $506 million.
Footwear retailers presented a different picture. Their nominal sales declined 4.0% annually, while constant-price sales increased 10.2%, a substantial divergence that warrants careful interpretation.
The figures do not establish whether individual footwear retailers sold more pairs of shoes, increased discounting or changed their merchandise mix. They do show that nominal revenue and inflation-adjusted activity moved in opposite directions, complicating assessments based solely on reported sales dollars.
For Canadian fashion retailers, the broader category’s annual performance suggests continued consumer purchasing activity, although growth is uneven across merchandise segments. The data do not measure individual retailers’ margins or comparable-store sales.
General Merchandise Maintains Momentum
General merchandise retailers generated $11.09 billion in August sales, increasing 1.0% from July and 6.0% annually. The monthly improvement followed a 1.7% decline in July, while annual sales at constant prices increased 6.8%.
The inflation-adjusted increase was stronger than the category’s nominal growth, placing general merchandise among the better-performing major retail sectors. The results cover a broad range of store formats, including department stores and other general merchandise retailers.
The sector’s performance is relevant to Canadian shopping centres and power centres, where general merchandise businesses remain important traffic-generating tenants. However, the national figures cannot establish whether particular retailers or store formats are outperforming their competitors.
Grocery Sales Improve as Volumes Remain Weak
Food and beverage retailers generated $13.37 billion in August sales, increasing 1.1% from July but only 0.8% annually. The monthly increase was the sector’s first in three months, with all four major store categories reporting gains.
Supermarkets and other grocery retailers recorded $9.53 billion in sales, increasing 1.1% monthly and 0.7% annually. Beer, wine and liquor retailers posted a 1.4% monthly increase, while specialty food retailers gained 0.5%.
The inflation-adjusted figures reveal a weaker annual performance. Food and beverage retail sales at constant prices declined 1.8%, including a 2.0% decrease among supermarkets and other grocery retailers.
These results indicate that modest nominal sales growth has coincided with declining inflation-adjusted activity over the past year. The figures are particularly relevant as grocery affordability continues to influence household spending, even though the annual rate of grocery price inflation has slowed.
Home Retail and Electronics Face Continued Pressure
Furniture, home furnishings, electronics and appliance retailers recorded $3.46 billion in August sales, increasing 2.3% from July. Despite the monthly recovery, sales remained 2.1% below August 2025.
Electronics and appliance retailers continued to experience weaker annual results, with nominal sales declining 6.8% to $1.49 billion. Sales at constant prices fell 4.4%, indicating that the weakness extended beyond changes in selling prices.
Furniture retailers performed somewhat better, recording annual revenue growth of 2.2%, while floor covering, window treatment and other home furnishing retailers increased 1.3%. The differences suggest that home-related retail categories are experiencing varying levels of demand.
Building material and garden equipment and supplies dealers recorded a 1.6% monthly increase to $4.05 billion, with annual sales rising 2.7%. However, constant-price sales declined 0.8% annually, showing that inflation-adjusted activity remained weaker than the nominal results.
Other Major Retail Categories
Motor vehicle and parts dealers generated $19.96 billion in August sales, increasing 1.2% monthly and 2.7% annually. New car dealers led the monthly increase, with sales rising 1.5% to $15.78 billion, while automotive parts, accessories and tire retailers gained 1.4%.
Used car dealers recorded a 0.5% monthly decline. The broader motor vehicle retail category reported annual constant-price sales growth of 2.6%, indicating modest inflation-adjusted expansion.
Gasoline stations and fuel vendors recorded $7.42 billion in August sales, increasing 1.7% monthly and 22.6% annually. However, constant-price sales declined 0.5% during August and 8.8% annually, illustrating how fuel prices can substantially influence reported retail revenue.
Sporting goods, hobby, musical instrument, book and miscellaneous retailers generated $4.29 billion in August sales, increasing 0.3% monthly and 5.1% annually. Constant-price sales increased 3.2% over the year, although results differed among the category’s individual retail formats.
Canadian Retail Momentum
Market Segment Signals: Retail Winners and Laggards
The August figures show a retail market in which category performance remains uneven despite the broad monthly recovery. Health and personal care retailers, general merchandise stores and selected fashion-related categories recorded comparatively strong annual growth, while electronics and several home-related businesses continued to face weaker results.
Food and beverage retailing illustrates another challenge. Although nominal sales increased modestly, annual constant-price sales declined, showing that reported revenue growth can conceal weaker inflation-adjusted activity.
The differences matter for retailers evaluating store performance, assortment decisions and inventory requirements. National growth rates provide useful context, but merchandise category and regional conditions can be considerably more important to individual businesses.
Regional Retail Signals
Ontario and British Columbia contributed substantially to the national retail recovery in August, while Quebec recorded only modest monthly growth and Alberta experienced a small decline.
| Province | August sales | Monthly change |
|---|---|---|
| Ontario | $28.54 billion | +2.2% |
| Quebec | $16.22 billion | +0.2% |
| British Columbia | $9.97 billion | +2.1% |
| Alberta | $9.65 billion | −0.1% |
| Manitoba | — | +1.6% |
| Saskatchewan | — | +1.1% |
| Nova Scotia | — | +0.6% |
| New Brunswick | — | −0.6% |
| Prince Edward Island | — | −0.6% |
| Newfoundland and Labrador | — | −0.6% |
Source: Statistics Canada, August 2026 Retail Trade Survey. Monthly changes are seasonally adjusted.
Ontario generated $28.54 billion in retail sales, increasing 2.2% from July and 6.4% annually. The Toronto census metropolitan area recorded a particularly strong 4.0% monthly increase, with sales reaching $12.96 billion.
British Columbia recorded $9.97 billion in retail sales, increasing 2.1% monthly and 3.7% annually. The Vancouver metropolitan area also posted a 2.1% monthly increase, bringing sales to $4.95 billion.
Quebec’s retail sales increased just 0.2% to $16.22 billion, while Montréal recorded a 0.5% monthly decline. Sales in the Montréal metropolitan area were 0.8% higher than a year earlier, indicating comparatively limited annual growth.
Alberta’s monthly sales declined 0.1% to $9.65 billion, although the province recorded annual growth of 7.6%. The contrast illustrates why monthly and annual performance need to be considered together when assessing regional market conditions.
Manitoba recorded a 1.6% monthly increase, followed by Saskatchewan at 1.1% and Nova Scotia at 0.6%. Newfoundland and Labrador, Prince Edward Island and New Brunswick each recorded monthly declines of 0.6%.
For national retailers and shopping centre landlords, these regional differences provide useful context when assessing individual markets. The figures do not directly measure store traffic, occupancy costs, leasing demand or comparable-store performance.
Wholesale Trade and Inventory Conditions
Canadian wholesale trade weakened during August even as retail sales recovered, according to Statistics Canada’s Wholesale Trade report. Wholesale sales declined 1.6% to $91.6 billion, with decreases in five of seven major subsectors.
The headline wholesale measure excludes petroleum, petroleum products and other hydrocarbons, as well as oilseed and grain. Wholesale sales remained 7.2% higher than a year earlier, although inflation-adjusted wholesale activity declined 1.8% during August.
Motor vehicle and parts wholesaling fell 3.8% to $15.08 billion, following six consecutive monthly increases. Textile, clothing and footwear wholesaling declined 12.7%, while food, beverage and tobacco wholesaling decreased 2.0%.
Building material and supplies wholesaling was a notable exception, increasing 1.4% to $14.11 billion. The category recorded its eighth consecutive monthly increase, including a 3.3% gain in lumber, millwork, hardware and other building supplies.
Wholesale inventories were essentially unchanged at $141.0 billion, while the inventory-to-sales ratio increased from 1.51 in July to 1.54 in August. Personal and household goods inventories increased 3.5%, including a 6.6% increase in pharmaceutical and pharmacy supplies inventories.
The decline in wholesale activity provides an additional perspective on distribution conditions entering the fall. However, the retail and wholesale surveys measure different transactions, and their opposing monthly movements do not establish that retailers are reducing orders or preparing for weaker consumer demand.
Channel Monitor: E-Commerce and Fulfillment Strategy
Canadian retail e-commerce sales increased 1.1% in August to $5.65 billion on a seasonally adjusted basis. Online sales were 15.3% higher than in August 2025 and represented 7.6% of total retail trade.
The annual growth rate was considerably stronger than the 5.4% increase in overall retail sales, indicating that the online channel continued to expand its share of Canadian retail activity. The figures do not identify which individual retailers or merchandise categories accounted for the growth.
For retailers operating both physical stores and digital platforms, e-commerce remains an important component of the business. Stores can serve customers through in-person shopping, pickup and fulfillment, although the national sales data do not measure the costs or profitability associated with those activities.
The continued expansion of online retailing is also relevant for landlords and shopping centre operators as retailers evaluate how physical locations support broader sales networks. The commercial value of those arrangements depends on factors beyond the national e-commerce growth rate, including store productivity, fulfillment costs and customer behaviour.
What Canadians Were Buying
Commodity Sales Reveal Category Differences
Statistics Canada’s Retail Commodity Survey for July 2026 provides a more detailed view of the products Canadians purchased. Total commodity sales reached $77.8 billion, increasing 5.0% compared with July 2025, with gains reported in 14 of 18 commodity classes.
The survey measures products sold across retail businesses, rather than classifying sales according to a retailer’s principal business activity. Its figures are unadjusted, and the reported percentage changes are annual comparisons, making them distinct from the seasonally adjusted August retail trade figures.
Home health product sales increased 11.1% to $5.78 billion, consistent with the strength observed in health and personal care retailing. Infant care, personal and beauty products increased 4.0% to $1.83 billion.
Clothing sales increased 5.8% to $3.42 billion, while jewellery, watches, luggage and briefcases rose 9.2% to $626 million. Footwear commodity sales increased just 0.3%, indicating much more modest nominal growth in that product category.
Food and beverage commodity sales increased 3.8% to $18.19 billion, including a 4.0% increase in fresh food sales. Fresh meat and poultry sales rose 8.6%, illustrating how spending growth varied within the broader food category.
Automotive and household fuel sales increased 23.7% to $7.30 billion, while home furniture, furnishings, housewares, appliances and electronics sales declined 0.1%. Audio, video and game software recorded an 18.4% annual decrease, one of the more pronounced declines among the surveyed commodity categories.
The product-level figures reinforce the uneven pattern evident in the broader retail data. Health products, clothing and jewellery recorded stronger nominal growth, while several home-related and entertainment categories showed limited increases or declines.
Inflation Adds Context to Retail Performance
Canada’s Consumer Price Index increased 3.1% annually in September, compared with 3.0% in August, according to Statistics Canada’s September CPI report. The acceleration was largely attributable to gasoline prices, which increased 27.8% annually after rising 22.8% in August.
Excluding gasoline, inflation slowed to 2.2% from 2.4% in August. The overall CPI increased 0.1% on an unadjusted monthly basis and 0.4% after seasonal adjustment.
Grocery price inflation slowed to 1.7% annually, down from 2.8% in August and its lowest annual rate since May 2024. Fresh vegetable prices declined 2.9%, while fresh or frozen beef remained 8.7% more expensive than a year earlier.
The moderation in grocery inflation provides some relief from the rapid increases experienced in recent years. However, grocery prices remained 33.0% higher than in September 2020, leaving households with a substantially elevated cost of everyday food purchases.
Shelter costs also remained part of the broader household spending environment, with annual shelter inflation of 1.8% and rent inflation of 2.8%. These expenses can influence how much discretionary income consumers have available, although the CPI figures alone cannot establish changes in individual household budgets.
For retailers, slower inflation should not be confused with falling prices. Consumers may be experiencing smaller annual price increases while continuing to face significant cumulative increases in the cost of necessities.
What to Watch Heading Into the Holiday Season
Statistics Canada’s preliminary estimate suggests that retail sales increased another 0.7% in September, following August’s 1.2% gain. The estimate was based on responses received from 58.5% of surveyed companies and remains subject to revision.
The official September retail trade figures are scheduled for release on November 20, 2026. They will provide a clearer indication of whether August’s broad improvement continued into early fall.
Several indicators will be particularly useful to monitor, including inflation-adjusted sales, the performance of discretionary categories, regional differences and the relationship between retail activity and wholesale distribution. These measures can help establish whether stronger reported sales are being accompanied by sustained growth in underlying purchasing activity.
The approaching holiday season will also provide an important test for categories such as apparel, electronics, general merchandise and home-related retailing. The August data establish an improved starting position, but they do not yet provide a reliable forecast of holiday sales performance.
Retail Insider Takeaway
Canada’s retail economy entered the fall with stronger momentum than the July figures had suggested. August’s recovery was broad, with all nine major subsectors recording higher monthly sales and inflation-adjusted retail activity increasing alongside nominal revenue.
The annual results remain uneven. Health and personal care retailers, general merchandise stores and e-commerce recorded comparatively strong growth, while grocery sales volumes and electronics remained under pressure.
The accompanying wholesale and inflation figures add important context. Distribution activity weakened in August, gasoline prices continued to influence headline inflation, and grocery prices remained substantially above their levels five years earlier despite slower annual increases.
For Canadian retailers, landlords and suppliers, the latest data support cautious optimism heading into the final quarter. The next official retail figures will help determine whether the August rebound represents a sustained improvement in consumer purchasing activity or a recovery that remains concentrated in particular categories and markets.
More From Retail Insider
Rethink Retail Expands Executive Communities Under Canadian Leadership
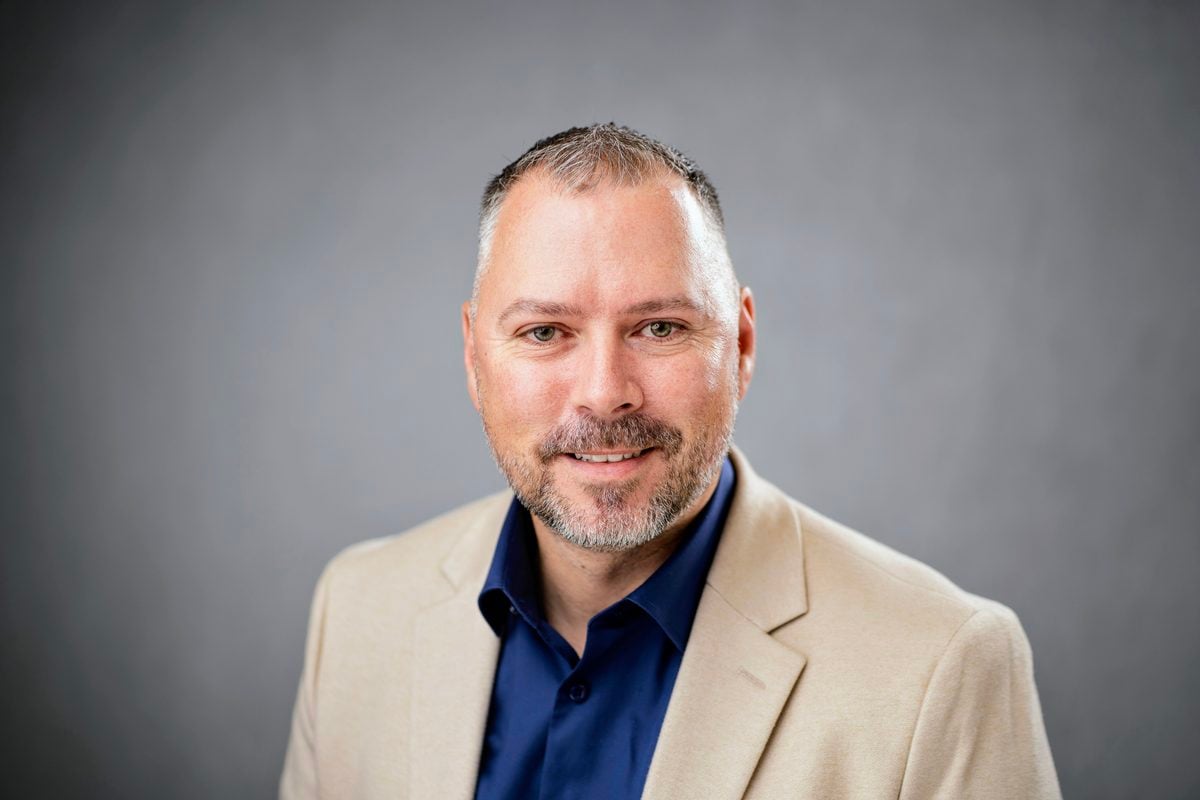
Rethink Retail is expanding its executive-community strategy under Canadian CEO Marie Chevrier Schwartz, appointing Canadian retail executive Chris Parsons as its first Vice President of Audience as the company develops new programming and industry partnerships.
The appointment comes as Rethink Retail broadens its business beyond traditional industry media, connecting editorial content, research, events and professional networks through specialized communities focused on artificial intelligence, retail media and supply-chain operations. The company is also expanding in Canada, where it is bringing together retail executives and technology leaders to address challenges facing the industry.
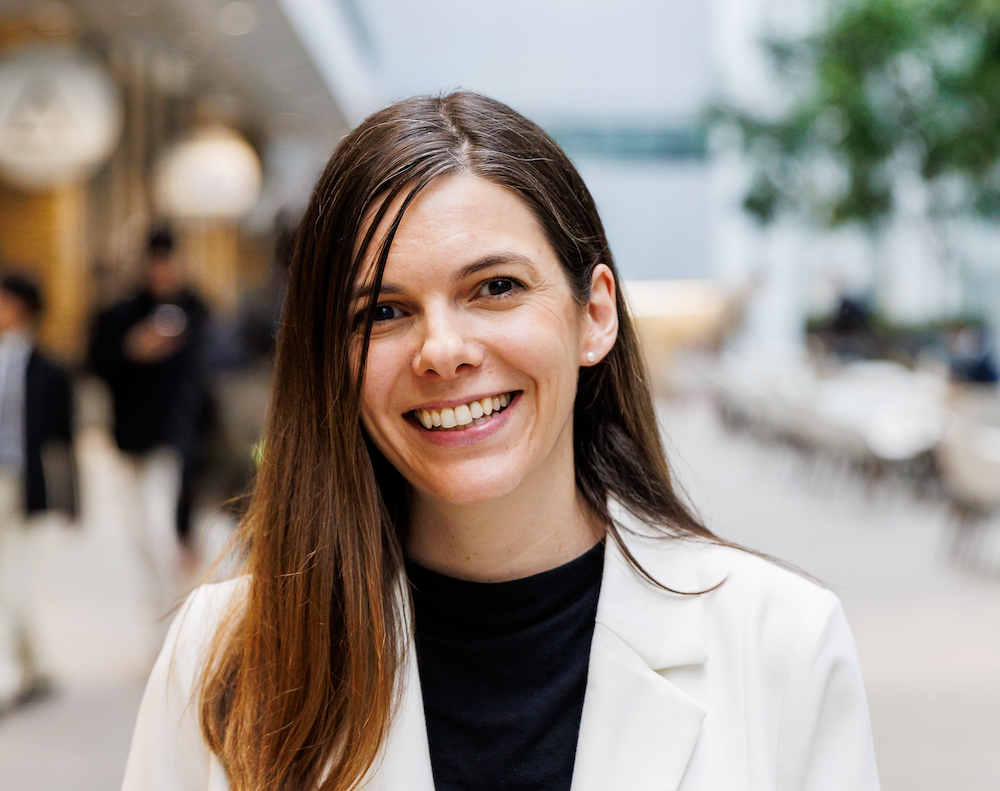
Parsons, who helped launch Walmart.ca and spent six years working on e-commerce and omnichannel initiatives at Home Hardware, joined Rethink Retail in September. His newly created position focuses on strengthening relationships with industry professionals and encouraging ongoing participation across the company’s platforms.
Chevrier Schwartz said the strategy reflects an opportunity to connect executives facing similar challenges, particularly as retailers invest in technologies that require greater coordination between departments and organizations.
Building a Community-Focused Retail Business
Rethink Retail has established an international presence through industry journalism, podcasts, research and events. Its evolving strategy emphasizes professional communities where retail executives can exchange experiences, discuss operational challenges and help shape research and industry programming.
“Retail doesn’t have an information problem,” Chevrier Schwartz told Retail Insider. “There’s no shortage of research, conferences, newsletters or opinions about where the industry is headed. What’s often missing is the voice of the people actually doing the work: the operators running stores, building retail media networks, rewiring supply chains and putting AI into production.”
The organization has developed communities focused on AI in Retail, Media in Retail, Supply Chain in Retail and Top Retail Experts. These bring together retailers, brands, technology providers and industry specialists around issues affecting multiple parts of the retail business.
“Telling their stories was powerful. Connecting them to each other was even more powerful,” Chevrier Schwartz said.
The strategy follows organizational changes at Rethink Retail, including its acquisition by Rethink Holdings in November 2025, according to the company’s published history. Under its current approach, discussions among community members help inform editorial coverage, research, podcasts and events, while relationships are intended to continue beyond individual gatherings.
Chevrier Schwartz brings experience in Canadian entrepreneurship and professional community development. She founded Toronto-based product-sampling technology company Sampler in 2013 and was involved with TechTO, a Canadian technology community that she said brought together more than 60,000 people across the country.
That background has influenced how she approaches executive engagement, particularly the importance of giving members opportunities to contribute and discuss problems openly.
“Attendance and engagement are two very different things. You can fill a room with impressive people and still accomplish very little,” she said.
Chevrier Schwartz believes successful communities depend on trust and continuity, particularly when executives are discussing initiatives that have encountered difficulties. Members are encouraged to share experiences, contribute to discussions and help determine the direction of future programming.
Chris Parsons Brings Retail Operating Experience
Parsons has more than 25 years of experience in retail technology, e-commerce and customer engagement. In addition to his work with Walmart Canada and Home Hardware, his career has included positions with Newegg and Ren’s Pets.
His experience at Home Hardware involved developing digital and omnichannel initiatives within a network of independently owned dealers, where individual stores serve markets with different customer needs and operating conditions.
“When you’ve operated a retail business, you know the distance between a good idea and something a store team can actually deliver,” Parsons told Retail Insider. “A campaign can look fantastic in a boardroom. But if the inventory is wrong, the associate hasn’t been briefed or the customer can’t collect the order, that promise falls apart.”
Parsons said that experience shapes the questions he asks about retail technology and business strategy. He considers what an initiative means for customers, whether store teams can deliver it and what needs to happen operationally for it to succeed.
He wants Rethink Retail’s content, events and communities to provide information and professional connections that participants can apply within their own businesses.
A retail executive might first encounter the organization through an article or podcast, attend an event and eventually join a specialized community. Parsons wants those experiences to build on one another, giving participants reasons to return and remain involved.
“I think about it the way a retailer thinks about a store,” he said. “Getting someone through the door matters, but did they find what they needed? Did we give them a reason to return? Would they recommend us to someone else?”
His mandate includes increasing audience engagement, encouraging repeat participation and strengthening relationships among members. Parsons said he also wants to see evidence that those connections are helping retail professionals solve problems and develop their careers.
He continues to publish Retail Rewired, a weekly newsletter examining retail technology, customer behaviour and industry developments. The publication complements his work at Rethink Retail by providing another forum for practical discussions about retail operations.
Retail Media and AI Create New Challenges
Rethink Retail’s specialized communities address areas where retailers are making technology and operational investments while confronting challenges that extend across individual departments.
Chevrier Schwartz identified retail media as one example. Retailers have developed advertising businesses using their digital platforms, customer information and physical stores, but she said measurement practices and organizational structures have not always kept pace.
“I think the biggest gap is alignment, particularly around how retail media creates, measures and shares value,” she said.
Retail media involves merchandising, marketing, technology and customer experience teams, which may operate with different budgets and performance objectives. Chevrier Schwartz said the industry needs greater consistency in determining whether advertising activity generates additional business or shifts spending between existing channels.
Rethink Retail’s Media in Retail community includes founding members from Costco, Ulta Beauty, The Home Depot and Dollar General, according to Chevrier Schwartz. The initiative focuses on collaboration around industry standards, measurement challenges and the development of retail media talent.
Artificial intelligence presents similar organizational challenges. Chevrier Schwartz said retailers sometimes introduce new technology before establishing the data quality, workflows and accountability needed to use it effectively.
Parsons believes AI could change how retailers interact with customers, particularly as consumers increasingly use conversational tools to research purchases and solve problems.
He has developed a framework called AIMOD, or AI Moment of Discovery, examining how shoppers may begin with a question about a situation instead of searching for a particular product.
A customer preparing a backyard for summer, for example, might ask an AI assistant what work needs to be done before deciding which products to purchase. Parsons believes retailers should consider how their merchandise information and expertise can support those interactions.
The concept is already relevant to Canadian retailers. Recent Retail Insider reporting on Canadian Tire’s MOSaiC retail intelligence platform described how the company is using customer information alongside weather, seasonality and local events to identify shopping occasions and improve merchandising decisions across its banners.
Parsons also sees opportunities to use existing customer information more effectively. A home improvement retailer might combine location data with weather conditions or housing characteristics to offer relevant advice, provided the information is handled appropriately and recommendations are tested.
He pointed to persistent weaknesses in conventional personalization. A shopper might research a barbecue across several websites, purchase one in a physical store and continue receiving advertisements for barbecues because the various retailers have no knowledge of the completed purchase.
For retailers, addressing these issues requires coordination between customer data, digital platforms, marketing and store operations. Parsons encourages companies to begin with manageable applications, measure the results and improve their underlying systems before pursuing larger initiatives.
Rethink Retail Expands in Canada
Canada is becoming a more prominent part of Rethink Retail’s executive-community programming, with the organization establishing a dedicated Canadian presence for its AI in Retail initiative.
In August, the company announced that James Baskin, founder and CEO of ZeroStone, would chair the Canadian chapter of AI in Retail. The initiative is intended to support local programming, executive workshops and collaboration among Canadian retail and technology leaders.
Chevrier Schwartz said Canadian retailers are being encouraged to help determine which issues should receive attention as the community develops.
“Start with a shared problem, not a membership target,” she said.
Parsons believes Canadian retailers face challenges related to the country’s geography, smaller population and distribution costs. Long distances between markets can complicate logistics and technology investments, particularly for retailers serving smaller communities.
His experience with Home Hardware also demonstrated the advantages of local decision-making. Independently owned dealers can adapt their assortments, services and operating practices to the needs of individual markets.
Parsons noted that Canadian divisions of American retailers may benefit from access to larger technology platforms and investment resources, although Canadian priorities can compete with those of their parent organizations.
He encourages Canadian retailers to learn from developments in other markets while testing their relevance to local customers and operating conditions. Improvements to legacy systems, data quality and internal processes remain important as companies consider new technologies.
Industry Partnerships Support Further Expansion
Rethink Retail is extending its programming through partnerships with established retail industry organizations.
On January 9, 2027, the company is scheduled to participate in Commerce Media Saturday, developed in partnership with the National Retail Federation during NRF Retail’s Big Show programming in New York. The event will take place at Lavan Midtown and will focus on issues including retail media measurement, artificial intelligence and the relationship between advertising and commerce.
Additional programming during NRF week will address AI and supply-chain challenges, bringing together participants from Rethink Retail’s specialized communities and the broader international retail industry.
Chevrier Schwartz said the company wants those gatherings to contribute to relationships and discussions that continue throughout the year. Its research and future programming are also intended to reflect issues identified by community members.
For Parsons, success will ultimately depend on whether participants can apply what they learn.
“We’ll measure audience growth, repeat engagement and participation,” he said. “But I also want to hear, ‘I met someone through Rethink who helped me work through a problem,’ or ‘We tested something after that conversation.’”
Twelve months into his new role, Parsons hopes more members will be having those experiences and introducing their peers to the organization. That will be a practical measure of whether Rethink Retail’s community-focused strategy is creating lasting value for the industry.
More From Retail Insider
Retail sales climb to nearly $75 billion in August: Statistics Canada
Retail sales increased 1.2% to $74.6 billion in August. Sales were up in all nine subsectors, led by increases at motor vehicle and parts dealers. Core retail sales, which exclude gasoline stations and fuel vendors and motor vehicle and parts dealers, were up 1.1% in August. In volume terms, retail sales increased 1.2% in August, reported Statistics Canada on Friday.
On a seasonally adjusted basis, retail e-commerce sales increased 1.1% to $5.6 billion in August, accounting for 7.6% of total retail trade, it said. Statistics Canada also provided an advance estimate of retail sales, which suggests that sales increased 0.7% in September. O
“The largest increase in retail sales in August was observed at motor vehicle and parts dealers (+1.2%). The increase was led by higher sales at new car dealers, up 1.5% in August after decreasing 1.4% in July. In August, gains at automotive parts, accessories and tire retailers (+1.4%) were offset by lower sales at other motor vehicle dealers (-1.4%) and used car dealers (-0.5%),” said the federal agency.
“Sales at gasoline stations and fuel vendors increased 1.7% in August, up for the first time in three months. In volume terms, sales at gasoline stations and fuel vendors decreased 0.5%.”
Core retail sales rise
Statistics Canada said core retail sales rose 1.1% in August, following a decrease of 0.7% in July. The increase in August was led by higher sales at the food and beverage retailers subsector (+1.1%), which posted its first increase in three months. All four store types within this subsector were up in August.
In August, higher sales were also recorded at general merchandise retailers (+1.0%) after a decline of 1.7% in July. Sales at health and personal care retailers were up 1.6% in August, rising for a 10th consecutive month, it added.
Sales up in six provinces
“Retail sales increased in six provinces in August. The largest provincial increase in dollar terms was observed in Ontario (+2.2%), led by higher sales at motor vehicle and parts dealers. In the census metropolitan area (CMA) of Toronto, retail sales increased 4.0%. In British Columbia, retail sales were up 2.1% in August, led by higher sales at motor vehicle and parts dealers. In the CMA of Vancouver, sales were up 2.1%,” said the report.
“The largest provincial decrease in retail sales in August was observed in Alberta (-0.1%). This decline was led by lower sales at motor vehicle and parts dealers.”
Economist comments
Katherine Judge, Senior Economist, CIBC Capital Markets, said: “Part of the acceleration in Q3 real retail sales owes to a strong handoff from Q2, when FIFA World Cup spending and government stimulus cheques were supporting spending. The weak end to Q3 in volume terms suggested by the advance estimate isn’t a good sign for Q4 spending, with elevated gasoline prices still eating into discretionary spending power at a time when the labour market is under pressure due to trade uncertainty.”
Maria Solovieva, Economist, TD Economics, said: “August’s solid rebound, coupled with September’s encouraging flash estimate, put Q3 retail sales on track to grow by 4.0% in nominal terms (quarter-on-quarter, annualized). This is consistent with our internal TD Spend data, which points to firm spending on both goods and services.
“Today’s report reinforces our view that Canadian households retain the capacity to spend, supported by accumulated wealth and resilient income growth. The latest Canadian Survey of Consumer Expectations offers a similar, albeit mixed, signal: consumers’ perceptions of their financial health improved, even as spending intentions weakened. Putting greater emphasis on the hard data, we expect real personal consumption expenditure to grow by 2.6% annualized in Q3 2026. From there, consumers are likely to take spending down a notch, with growth expected to moderate toward year-end.”
Shelly Kaushik, Vice-President, Senior Economist, BMO Capital Markets, said: “A firm retail sales report for August highlights consumer resilience amid ongoing uncertainty. But, a softer September points to ebbing momentum heading into Q4.”
More from Retail Insider:
Canadian Franchise Sector Supports Nearly 2 Million Jobs: CFA
This Small Business Month, the Canadian Franchise Association (CFA) is highlighting the local entrepreneurs behind the franchise brands Canadians interact with every day.
From grabbing a morning coffee and picking up lunch to getting a workout in, dropping a child off at a tutoring centre, taking a pet to the groomer, or calling someone for a home repair, Canadians interact with franchised businesses every day.
In fact, the average Canadian interacts with three to five franchise businesses each day. The brand names may be familiar across the country—or even internationally—but behind many of these storefronts is a local entrepreneur who has invested in building and operating a small business in their own community.
In fact, 93% of franchise establishments in Canada are locally owned by an individual business owner rather than the franchise system itself, says the CFA.
At its core, franchising is about being in business for yourself, but not by yourself. Franchisees operate their own businesses, hire employees, make day-to-day decisions, and often support local charities, sports teams, and community initiatives, while benefiting from the training, resources, and support of an established franchise system, it says.
These entrepreneurs bring their own experience, drive, and knowledge of their communities to businesses across more than 60 sectors, from food service and fitness to education, home services, senior care, and professional services.
For many entrepreneurs, franchising can provide a pathway into business ownership while giving them the opportunity to build something of their own and grow within their community.
Franchising Facts:
- Local small business owners: 93% of franchise establishments are locally owned by an individual business owner. Franchisees operate their own businesses, hire their own staff, and make day-to-day business decisions. They live, work, and contribute to the communities they serve;
- A significant economic contributor: Canada’s franchise sector represents almost $150 billion in economic activity, nearly 2 million jobs, and more than 70,000 businesses;
- 60+ sectors: Franchising extends well beyond restaurants and retail, with franchise businesses operating across more than 60 sectors, including food service, fitness, education, home services, senior care, and professional services;
- Businesses with growth potential: Many franchisees expand from one location to multiple locations, creating additional employment opportunities and contributing further to their local economies;
- Local expertise and entrepreneurship: Franchisees bring their own entrepreneurial drive, experience, and knowledge of their communities to the businesses they operate;
- A pathway to business ownership: Franchise systems can provide entrepreneurs with an established business model, training, and ongoing support as they build and operate their businesses.
In an interview with Retail Insider, Sherry McNeil, President & CEO of the CFA, talks about the role of franchisees as small business owners, the impact of franchising across Canada, and the opportunities the franchise model can provide for entrepreneurs.
What role do locally owned franchise businesses play in Canada’s small-business landscape, and how does the fact that 93 per cent of franchise establishments are locally owned challenge the perception that franchises are primarily controlled by large corporate chains?
Franchising is a significant part of Canada’s small-business landscape, creating opportunities for local entrepreneurs to build and operate businesses in the local communities they call home. In fact, 93 per cent of franchise establishments are locally owned, underscoring that franchising is very much a story of local business ownership, not just large corporate brands.
While franchisees are the independent business owners behind the brands Canadians know and love, their impact goes far beyond the products and services they provide.
They are employers, mentors, neighbours, volunteers and community supporters who know their customers and give back to causes and community groups close to their hearts.
Behind many of the franchise businesses Canadians interact with every day is a local entrepreneur who has invested their time, money and passion into building a business of their own. These franchisees hire employees from their communities, make day-to- day business decisions and contribute to their local economies.
At its core, franchising is about being in business for yourself, but not by yourself. Franchisees benefit from an established business model, training and ongoing support, while bringing their own entrepreneurial drive and knowledge of their communities to the businesses they operate.
What are the biggest advantages and challenges for entrepreneurs who choose franchising as a pathway to business ownership compared with starting an independent business from scratch?
Franchising offers a pathway to business ownership with the benefit of an established business model, brand recognition, training, and ongoing support. Rather than building every aspect of a business from the ground up, franchisees can draw on the experience, resources, and systems of an established franchise network.
Franchise systems can provide support in areas such as operations, marketing, and staff training, helping entrepreneurs navigate the process of starting and running a business. Franchisees can also learn from other owners within the network and benefit from shared knowledge and experience.
However, franchising is not a guaranteed path to success, and choosing a franchise requires careful research and due diligence.
Entrepreneurs need to understand the day-to-day requirements of the business, including the time and involvement required, the total initial investment and ongoing costs, staffing needs, hours of operation, customer acquisition and the potential timeline for achieving a return on investment.
Most importantly, they need to determine whether the business is the right fit for their skills, lifestyle, and long-term goals.
As with many industries, franchising is also experiencing a rise in fraud, as AI and other technologies become easier to use to create fraudulent documents and opportunities.
Partnering with trusted advisors, doing due diligence, and using resources from the Canadian Franchise Association (CFA) are all important steps for prospective franchisees to ensure they stress test any opportunity. Those looking to buy a franchise should visit LookforaFranchise.ca and look for the CFA Member logo on the websites, tradeshow materials, and resources provided by a franchise brand. The CFA Member logo indicates a brand has joined the CFA and signed on to its Code of Ethics.
Doing that due diligence is critical. The right franchise opportunity, combined with the right franchisee, creates a strong foundation for success.
With the franchise sector representing nearly $150 billion in economic activity, almost two million jobs and more than 70,000 businesses, what is driving the sector’s growth in Canada today?
Franchising is a significant contributor to Canada’s economy, representing nearly $150 billion in economic activity, almost two million jobs and more than 70,000 business locations. Its strength lies in a business model that can support entrepreneurs while helping established brands expand into new markets and communities.
One of the key drivers of growth is the diversity of the franchise sector. Franchising extends well beyond restaurants and retail, with businesses operating across more than 60 sectors, including food service, fitness, education, home services, senior care, professional services and construction. This diversity creates opportunities for entrepreneurs to explore different industries while meeting the needs of their local communities.
The model also provides opportunities for existing franchisees to grow from one location to multiple locations, creating additional jobs and contributing further to their local economies. At the same time, established systems, training and operational support can help entrepreneurs build on a proven business model rather than starting entirely from scratch.
Together, these factors make franchising an important pathway to business ownership and a contributor to economic growth across Canada.
How are franchisees contributing to their local communities beyond operating their businesses, including through employment, charitable initiatives and support for local organizations?
Franchisees are more than business owners. They live and work in the communities they serve, understand local needs and often find meaningful ways to give back.
Across Canada, franchisees support their communities by creating employment opportunities, sponsoring local sports teams and events, donating to charities, participating in fundraising initiatives and supporting local organizations. They also provide valuable work experience for young people and build relationships within their communities.
According to the Canadian Federation of Independent Business, 97 per cent of small business owners give back to their communities, with 74 per cent donating to local charities and causes, 56 per cent sponsoring local events and teams, and 55 per cent creating employment opportunities for youth.
These contributions demonstrate how the impact of local business ownership extends well beyond the business itself. Because franchisees are locally invested, their success can benefit employees, community organizations and the people they serve. When local franchise businesses succeed, their communities benefit too.
What trends are you seeing among Canadians entering franchising, including the types of sectors, businesses and entrepreneurs showing the greatest interest, and what opportunities do you see for future growth?
There are franchising opportunities across a wide range of sectors. While food service and retail remain two of the most familiar areas of the franchise landscape, businesses operate across more than 60 industries, including education, fitness, home services, senior care, professional services and construction. This year, we’ve also seen significant growth in professional and technical services and construction. More affordable, low-overhead models have continued to attract entrepreneurs amid inflation and rising operating costs.
Franchising continues to attract entrepreneurs from a range of backgrounds, including first-time business owners, experienced professionals and newcomers to Canada who are looking to build businesses and establish themselves in their communities.
Looking ahead, the breadth of sectors and business models available presents opportunities for more Canadians to explore business ownership. The key is understanding the options, conducting thorough due diligence and finding a franchise opportunity that aligns with their skills, financial circumstances and goals. With the right preparation and support, franchising can offer a meaningful pathway to entrepreneurship and long-term business growth.
More from Retail Insider:
Retail Insider “Q3 2026 Apparel & Fashion Report”: Stores Have to Earn Their Investment
Retail Insider has released Q3 2026 Apparel & Fashion: Store Performance Ahead of Store Count, authored by founder and publisher Craig Patterson. The report examines why a growing retail business can invest more in Canada without increasing its Canadian store count.
The report covers Canadian clothing, footwear, accessories, department-store fashion and specialty apparel retail. Drawing on Retail Insider reporting, company disclosures, government data and industry research, it reviews Q3 developments while identifying financial results and market statistics that measure different periods.
Retail Insider Reports connect sector coverage with the commercial questions facing retailers, brands and property owners. The Retail Insider Report Hub provides the full quarterly collection, including analysis of consumer demand, real estate and the wider retail economy.
General Themes
- Capital follows performance: Retailers are concentrating investment in locations that can justify it through sales, sell-through and strategic contribution.
- Store count is an incomplete measure: Closures, larger boutiques and smaller relocations can all form part of a growth strategy.
- Canadian stores compete for resources: International expansion creates additional demands for merchandise and capital.
- Physical stores do more than transact: Fitting, pickup, returns, repairs and product discovery can support a wider retail network.
- National demand is not a company forecast: Healthy clothing sales coexist with substantial differences among brands and formats.
Retail Insider Coverage
Aritzia’s Canadian revenue rose 25 per cent to approximately $313 million in the first quarter of fiscal 2027, while the United States accounted for 67.1 per cent of company revenue. Most planned openings are American, but major Canadian investments include Oakridge Park and a roughly 41,800-square-foot CF Pacific Centre flagship. Management’s reported average payback of less than a year for new boutiques describes company-wide economics, not a guarantee for each Canadian project. The strategy combines domestic productivity with greater international unit growth.
Groupe Dynamite’s Canadian revenue fell 1.9 per cent in its second quarter alongside a network that had 13 fewer stores than a year earlier. Management described Canadian comparable-store performance as approximately flat, while the company renovated or relocated four Canadian stores and closed six during the quarter. Company-wide sales per square foot and inventory turnover improved, but those are not Canada-only results. Its pull-based inventory model also directs more merchandise toward stronger full-price selling, giving individual stores another reason to defend their productivity.
Reitmans’ company-wide revenue weakened while two renovated or repositioned flagships delivered double-digit sales growth. Its five-year investment plan aims to increase space by approximately 10 per cent while retaining roughly 400 stores, making the wider rollout a test of whether flagship improvements can travel. Kit and Ace reported considerably better early performance after moving into smaller, better-positioned space at CF Sherway Gardens, although that comparison remains management-reported and preliminary. Harry Rosen’s 38,000-square-foot Yorkville flagship replaced a Bloor Street store exceeding 50,000 square feet, changing the mix of inventory, appointments, hospitality and selling space rather than simply enlarging it.
Lululemon offers a counterpoint to stronger apparel results. Canadian revenue declined 11 per cent in its second fiscal quarter, or 9 per cent in constant currency, as management identified traffic, conversion and product concerns. Its response includes approximately 15 per cent fewer store SKUs in North America, localized assortments and presentation changes alongside selected Canadian property investments. Different fiscal periods and business models prevent a direct comparison with Aritzia, but both demonstrate that national demand does not determine brand performance.
Distribution is also becoming more varied. Esprit returned through selected Walmart stores and digital channels, HANK. gave wholesaler Caulfeild a direct retail format, and Knix brought in-person fitting to Atlantic Canada using an established online customer base. At quarter-end, Intimissimi and Calzedonia were preparing their first Canadian stores for October, not reporting a completed national rollout. The proposed Roots transaction separated core North American operations from international development plans, while OVO’s ownership changes divided intellectual property and operating responsibilities. These are different routes to reach, control and growth, with their eventual results still to be established.
Additional store functions are widening the investment question. UNIQLO added customization and repair at its Montreal flagship, Arc’teryx devoted space to ReBIRD services, and lululemon launched its Canadian Like New resale platform. Canada Goose’s first-quarter mix highlighted lighter categories, although their nearly 40 per cent revenue share was seasonally influenced, while Quartz Co. sees owned stores as a way to show merchandise beyond parkas. The reviewed Canadian disclosures did not quantify incremental profit or retention from these services. More reasons to visit still need to justify staffing and operating costs.
Broader Industry Coverage
July sales at Canadian clothing and clothing-accessories retailers rose 5.5 per cent year-over-year, with constant-price growth of 5.3 per cent showing that the increase extended beyond prices. Results elsewhere were less uniform: June footwear commodity sales increased, while July shoe-retailer revenue declined. Wholesale textile, clothing and footwear sales and inventories also grew strongly in July. Those measures cover different channels and periods, and wholesale inventory growth does not establish consumer sell-through.
Omnichannel activity complicates store evaluation. Inditex reported that approximately 60 per cent of online returns occurred through stores and about 20 per cent of online orders were collected in-store, but those figures are global rather than Canadian Zara results. A location may support digital purchases, advice and returns as well as register sales. That wider contribution needs to be measured without becoming an excuse for premises whose activity cannot justify occupancy and operating costs.
Editor’s Take
The report places regular-price sell-through, inventory turns, conversion, markdowns and network contribution alongside conventional sales productivity. Landlords need to understand how their property ranks within a retailer’s portfolio, not simply whether the brand is growing globally. An international expansion program can coexist with Canadian closures, renovations or tighter inventory allocation.
The next tests are specific: whether Reitmans can reproduce flagship gains, lululemon can improve Canadian traffic and conversion, and Aritzia can sustain the economics of larger boutiques. New international entrants and Quartz Co.’s broader assortment will add further evidence. Tariffs and cross-border costs affect companies differently, offering little basis for one sector-wide conclusion.
A smaller store can outperform a larger predecessor, and fewer stores can support a stronger business. Neither outcome follows automatically from reducing space. The commercial distinction is whether each location produces enough direct sales and wider network value to keep earning capital, inventory and operating resources.
Conclusion
Read the full Q3 2026 Apparel & Fashion: Store Performance Ahead of Store Count for its analysis of Canadian store investment, distribution models and apparel performance. The report follows where retailers are committing resources and the evidence needed to judge those decisions.
This report and the broader sector collection are available through the Retail Insider Report Hub. The series provides a shared reference point for changes in Canadian retail demand, property and operating strategy.
More from Retail Insider
OpenTable report highlights restaurants’ economic impact on Canadian communities
Canadian restaurants are contributing to local economies beyond their dining rooms, with half of diners saying they spend money at nearby businesses before or after a meal, according to OpenTable’s first Canadian Restaurant Impact Report.
The report found that those diners spend an additional $133 on average at businesses such as shops and cinemas. OpenTable also reported that dining in Canada increased 13 per cent year over year, based on reservation data from July 2025 to June 2026.
The report examines the economic and social contributions of restaurants, as well as the financial consequences of missed reservations and the role dining establishments play in bringing communities together.
“Restaurants are woven into the fabric of communities across Canada – the setting for milestone celebrations, everyday meals, and the local economies and neighbourhoods they help sustain,” said Eric Kemppi, director of restaurant sales and service at OpenTable Canada. “OpenTable’s first-ever Canadian Restaurant Impact Report puts that impact into focus and reflects our commitment to advocating for the restaurants that make it all possible.”
Restaurants contribute to local economies
OpenTable’s research found that 91 per cent of Canadian restaurants surveyed agree they play an important role in their local economy. Half of Canadian diners reported spending money at neighbouring businesses before or after dining out, a figure that rose to 61 per cent among millennials and 65 per cent among Generation Z.
The report also examined restaurants’ role as employers. Among restaurant workers surveyed, 50 per cent said their restaurant hires young people without formal qualifications, while 37 per cent said their workplace employs people with disabilities or neurodivergent people. Another 32 per cent reported employing refugees or recently arrived migrants.
The findings suggest that restaurants’ economic role extends beyond food and beverage sales, encompassing spending at nearby businesses and employment opportunities for people with different backgrounds and qualifications.
Dining out linked to community well-being
The report found that 89 per cent of Canadian diners believe local restaurants, pubs and cafés help build a sense of community. A further 83 per cent agreed that dining out locally brings people together and enhances personal and social well-being.
More than half of diners surveyed, or 58 per cent, said they were likely to book a restaurant meal to feel better or reconnect with others when feeling stressed or low.
Dr. Gillian Mandich, an assistant professor in the Department of Psychiatry at the University of Manitoba, said shared meals have been linked to greater life satisfaction and more positive emotions.
“The 2025 World Happiness Report found that sharing meals is strongly associated with greater life satisfaction and more positive emotions. In fact, the frequency of shared meals was as useful an indicator of well-being as income and employment status,” said Mandich. “Choosing a restaurant and looking forward to it can generate anticipation, while remembering it afterward extends the enjoyment.”
No-shows remain a concern for operators
The report also examined the financial impact of customers who fail to honour reservations, a problem that can affect restaurant staffing, food preparation and the availability of tables for other customers.
While 71 per cent of Canadian diners surveyed agreed that failing to show up for a reservation can seriously harm a restaurant’s business, 20 per cent said they had missed a reservation without showing up at least once in the previous year. That proportion rose to 43 per cent among Generation Z diners.
Restaurant operators estimated that a missed reservation for two costs their business an average of $91, compared with $75.90 estimated by diners. The difference reflects costs that operators may face from wasted food, staffing decisions and lost opportunities to seat other customers, according to the report.
Nearly half of diners surveyed, or 45 per cent, said understanding the financial consequences of a no-show would make them more likely to attend a reservation or cancel it properly if their plans changed.
OpenTable’s reservation data showed that no-show rates at restaurants using its platform in Canada fell four per cent year over year between July 2025 and June 2026. The report also found that 47 per cent of diners said they had never failed to cancel a reservation.
Technology aimed at reducing missed bookings
OpenTable said its platform provides diners with options to modify or cancel reservations and message restaurants when plans change. Restaurant operators can also use deposits, credit card holds, prepaid dining experiences, automated confirmations and reminders, online waitlists and its Notify Me feature to manage demand.
The company said these tools are intended to help restaurants manage reservations and reduce missed bookings, while allowing diners to communicate changes more easily.
The diner survey was conducted online by Ripple Research among 1,503 Canadian consumers who dine out between July 28 and Aug. 4, 2026. The restaurant research involved an online survey of 305 Canadian restaurant workers during the same period.
The report’s year-over-year dining and no-show figures were based on OpenTable reservation data for the same-store restaurants on its Canadian platform, comparing July 2025 to June 2026 with the corresponding period a year earlier.
OpenTable, part of Booking Holdings Inc., says it works with more than 70,000 restaurants worldwide and helps fill two billion seats annually.
Canadian spending habits
Kemppi said a 13 per cent year-over-year increase in online dining suggests that despite the economic pressures, Canadians are still dining out.
OpenTable’s new research shows that Canadians continue to view restaurants as more than just places to eat: They are important places that bring people together, with 89 per cent of Canadians saying local restaurants, pubs and cafés are key to building a sense of community,” he said.
“The average $133 spent by Canadian diners at neighbouring businesses before or after a meal shows the economic impact of a restaurant visit often extends well beyond the meal itself. OpenTable research shows that 50 per cent of Canadian diners spend money at neighbouring businesses before or after their meal. Restaurants act as anchors for local communities, giving people a reason to get out, explore their neighbourhoods and support other nearby businesses, creating a ripple effect that benefits the broader local economy.”
Creating employment
The restaurant industry has long provided employment opportunities for Canadians who may face barriers, said Kemppi.
“Findings from the Restaurant Impact Report show operators continue to create opportunities for these groups, with 50 per cent hiring young people without formal qualifications and 37 per cent hiring people with disabilities or neurodivergent people. Beyond employment, 91 per cent of operators in Canada say their restaurants play an important role in the local economy. Restaurants are not only creating jobs, but they’re also contributing to the communities they serve,” he said.
No-shows
The Restaurant Impact Report found that restaurant no-shows create both financial and operational challenges for operators, with a missed table for two costing restaurants an estimated $91 on average, according to operators, said Kemppi.
“Beyond the direct revenue loss, 56 per cent of restaurants identify staff costs as a potential consequence of no-shows, while 56 per cent point to wasted food and stock and 53 per cent say no-shows can result in turning away other bookings, impacting relationship-building,” he explained.
“By avoiding double-booking and cancelling reservations they no longer can keep, diners can help restaurants operate more efficiently. The good news is that Canadians are stepping up, with overall no show rates down 4% in Canada year-over-year.”
“Overall no-show rates in Canada declined four per cent year over year, which is an encouraging sign that diners are becoming more mindful about reservations. OpenTable equips restaurants with tools built to help reduce no-shows and protect a restaurant’s bottom line. As a result, restaurants can adopt measures that make it easier for diners to book and manage reservations, including deposits, prepaid experiences, automated confirmations and online waitlists. Restaurants on the OpenTable platform using deposits see a 60% reduction in no-shows globally. These tools help diners manage their reservations more effectively while giving restaurants greater certainty when planning staffing, inventory and table availability.
“Prepaid Experiences, which require upfront payment for special events, tasting menus and other dining occasions, can be particularly effective. Globally, Prepaid Experiences have been shown to reduce no-shows by up to 45 per cent and late cancellations by up to 66 per cent compared to non-prepaid experiences.”
More from Retail Insider:

