Home Blog Page 92

Canadian Retail Hiring Rebounds, but Labour Market Remains Uneven

Retail job hiring staffing. Photo: Manajobs

Canada’s retail labour market is showing signs of improvement after a difficult start to 2026, although the recovery is unfolding unevenly across jobs, categories and markets.

Statistics Canada reported that employment in wholesale and retail trade increased by approximately 21,100 jobs in July, a gain of 0.7% from June. That followed an increase of about 16,400 jobs in June, meaning the combined sector added roughly 37,500 positions over two months. Despite those gains, wholesale and retail employment remained approximately 50,100 jobs below July 2025 levels, representing a year-over-year decline of 1.7%.

The figures point to a labour market that has begun regaining some of the ground lost earlier in the year. For retailers themselves, however, the headline numbers capture only part of what is happening.

Suzanne Sears, president of Best Retail Careers International, said the hiring activity she is seeing is heavily concentrated at store level rather than across the full retail organization.

“The demand is almost entirely street level, with an emphasis in hiring multiple part-time workers,” Sears said.

Her observations point to a Canadian retail employment market in which companies continue to need frontline workers while remaining considerably more cautious about higher-level hiring, compensation and permanent headcount.

Retail Employment Shows Signs of Recovery

The Labour Force Survey combines wholesale and retail trade in its headline industry figures, meaning July’s 21,100-job increase cannot be attributed entirely to retailers. More detailed Statistics Canada payroll data, however, indicates that retail employment itself had already begun moving higher earlier in the year.

Retail payroll employment increased by about 5,600 positions in May, marking a third consecutive monthly increase. From March through May, the sector added approximately 20,500 payroll jobs, or about 1.0%.

The improvement followed a longer period of weakness. Retail payroll employment had declined through portions of 2024 and 2025, while several major retail categories remained below year-earlier employment levels during the first part of 2026. The recent gains therefore look less like a sudden hiring boom than an emerging recovery from a period of contraction.

Retail also remains an important employer of younger Canadians. Statistics Canada reported that close to one-quarter of returning students who were employed during the summer worked in retail trade, making it the largest employing industry for that group. The sector’s workforce composition helps explain how rising retail employment can coexist with continued caution around more senior, permanent and corporate hiring.
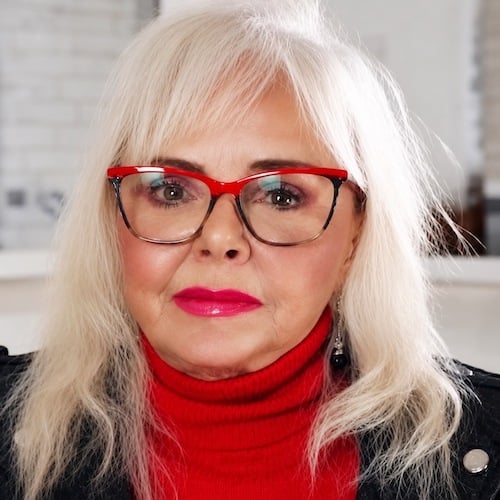
Suzanne Sears

Hiring Demand Concentrated at Store Level

Sears said employers are seeking staff most actively in customer-facing positions, often with a preference for multiple part-time employees rather than fewer full-time hires. An increase in retail employment, therefore, does not necessarily signal a corresponding increase in career-track positions, head-office roles or management opportunities.

Within store-level hiring, some categories are considerably more active than others. Sears said cosmetics and beauty currently represent one of the strongest areas of recruitment demand and one where employers are having difficulty finding sufficient qualified staff. She also pointed to luxury retail, watches and jewellery, and luxury menswear as areas where demand for experienced employees remains strong.

Those segments can require specialized selling skills, including product knowledge, clienteling ability and experience providing highly personalized service. In luxury retail in particular, established customer relationships can carry considerable value. A relatively large pool of available workers, as a result, does not necessarily mean employers can readily find candidates with the particular experience they are seeking.

Retail Pay Is Rising, but Compensation Remains a Challenge

Average weekly earnings in retail trade reached approximately $798 in May 2026, up more than 8% from about $739 a year earlier. The increase is significant, although retail earnings remain substantially below the Canadian economy-wide average of approximately $1,338 per week.

Sears said many employers are discovering that compensation budgets established even a year ago are no longer sufficient to recruit the calibre of employees they are seeking.

“It is nearly impossible to attract high-level talent with last year’s wage budgets,” Sears said.

In some cases, she said, companies are leaving positions vacant rather than increasing compensation enough to attract their preferred candidates. In others, they may ultimately hire someone with less experience than originally envisioned for the role.

Retail compensation is rising relatively quickly from a comparatively low base, while candidate expectations and employers’ requirements for experienced talent are not necessarily moving in tandem. The disconnect can become more pronounced as retailers move beyond hourly sales positions into management, regional leadership and specialized roles.

Career Progression Adds Another Recruitment Challenge

For experienced candidates, Sears said compensation is only one consideration. Advancement opportunities are also influencing how candidates assess retail careers, and the Canadian operations of international retailers do not always offer the same range of corporate positions available in their home markets.

International retailers operating Canadian store networks may keep key merchandising, buying, marketing, strategy and executive functions at headquarters outside the country. That can narrow the domestic career ladder for employees seeking to progress beyond store and regional management.

Sears said the combination of compensation expectations and limited opportunities to move upward can make it harder to attract and retain strong retail employees. For workers deciding whether retail represents a long-term career rather than simply their next job, the availability of a credible path forward can become an important part of the decision. For employers, it can create a mismatch between the experience they expect candidates to bring and the compensation and career opportunities available in return.

Hudson’s Bay Closures Added Thousands of Workers to the Market

The collapse of Hudson’s Bay added another unusual dimension to the Canadian retail employment landscape. Thousands of employees were displaced as stores closed across the country, suddenly putting a significant pool of experienced retail workers into the labour market.

One might expect that influx of talent to make recruiting substantially easier for other retailers, but Sears said that has not necessarily been the case. In her experience, cosmetics employees coming out of Hudson’s Bay have generally been more readily absorbed by other retailers, while many other former employees have either retired or have not yet moved into comparable positions.

The situation illustrates a notable contradiction in the current labour market. Retailers can report difficulty finding qualified employees at the same time that experienced retail workers are looking for work. The challenge is not necessarily the absolute number of people available, but how closely candidates’ experience, compensation expectations, location and skills align with the positions retailers are trying to fill.

Retail Hiring Extends Into Smaller Markets

Where retailers are hiring is changing as well. Sears said some of the activity she is seeing is connected to expansion into smaller provinces and communities that have historically been underserved by national retailers.

Recent employment data provides some support for that observation. Wholesale and retail trade employment in rural and small-town Canada was up by approximately 13,600 jobs, or 3.7%, year over year in June, with even stronger growth recorded during some preceding months.

Population shifts, housing affordability and development in secondary communities are creating opportunities outside Canada’s largest metropolitan markets. Communities that historically supported fewer national retailers can become viable locations as their populations grow and surrounding trade areas expand.

For retailers, expansion into smaller and underserved markets can also create a recruitment challenge. New stores require local employees, including managers and experienced sales staff, in communities where the existing pool of specialized retail talent may be smaller. Growth in these markets can therefore create jobs while simultaneously making certain positions difficult to fill.

Tariff Uncertainty Weighed on Hiring Earlier in 2026

Asked what contributed to the weakness in retail hiring earlier this year, Sears summarized the mood among employers in one word: “Paralysis.”

She pointed specifically to uncertainty surrounding U.S. tariffs and concern over how changing trade relationships could affect costs, consumer spending and broader economic conditions.

Her assessment is consistent with broader business sentiment reported earlier in the year. Bank of Canada surveys found that tariff uncertainty and softer demand were weighing on companies’ expansion and employment intentions, with many businesses reluctant to increase staffing while the economic outlook remained unclear. Statistics Canada had also reported that employment in wholesale and retail trade was trending lower from late 2025 before the more recent improvement.

The retail employment decline cannot be attributed to tariffs alone, but uncertainty around trade policy formed part of a broader environment in which businesses had reason to delay decisions, limit hiring and preserve flexibility until there was greater visibility around demand and costs.

Holiday Hiring Could Remain Constrained

Two consecutive months of improving wholesale and retail employment might ordinarily suggest stronger hiring heading into the fall and holiday season, but Sears remains cautious about the outlook.

She said many retailers have limited wage budgets available for substantial additional hiring, even as the industry approaches its critical seasonal period. Retailers will still require holiday staff, particularly in malls and other high-traffic environments, but they may have to be more selective about how those labour dollars are deployed.

That could mean greater reliance on part-time and seasonal workers, adjusting hours among existing employees or limiting permanent additions while reserving available labour budgets for periods of peak demand. The fall hiring market could therefore appear active at store level while remaining restrained elsewhere within retail organizations.

HR Departments Face Their Own Capacity Problem

Another part of the hiring challenge is taking place behind the scenes. Sears said retail HR departments are increasingly being asked to manage traditional human-resources responsibilities while simultaneously adapting to technology- and AI-driven recruitment processes, often without corresponding increases in staffing, tools or budgets.

Rather than necessarily accelerating recruitment, Sears said those pressures can contribute to longer hiring cycles.

“Time to hire is increasing by months, not weeks,” Sears said.

That can leave positions vacant for extended periods while HR teams manage competing responsibilities. Those vacancies can become an operational issue, placing additional pressure on existing employees and potentially affecting customer service and sales performance.

Meanwhile, companies remain under pressure to control labour expenses, leaving HR teams attempting to reconcile demands for lower costs, faster hiring and stronger candidates.

A Recovery, but an Uneven One

Canada’s recent employment numbers provide growing evidence that retail-related hiring has begun to recover after a difficult period. Wholesale and retail employment increased in both June and July, while retail-specific payroll employment had already posted three consecutive monthly gains through May.

What is returning, where it is returning and who employers are able to recruit tell a more complicated story. Much of the hiring Sears is seeing is concentrated in frontline and part-time positions, while beauty and luxury retailers face difficulty finding employees with particular skills and experience. Compensation is rising but remains comparatively low, and career advancement opportunities can be limited for employees of international retailers whose major corporate functions are located elsewhere.

At the same time, thousands of workers displaced by major retail closures are not necessarily matching quickly with available positions. Retailers expanding into smaller markets can encounter limited local talent pools, while the HR departments responsible for filling those jobs are themselves being asked to do more with constrained resources.

The latest employment gains suggest the Canadian retail labour market is moving in a better direction, but the challenge facing retailers increasingly goes beyond the number of workers available. Employers must match people with the right skills and experience to jobs in the right locations, while offering compensation and career opportunities capable of attracting them.
More from Retail Insider:

Lindt Opens First Banff Shop as Premium Chocolate Competition Grows

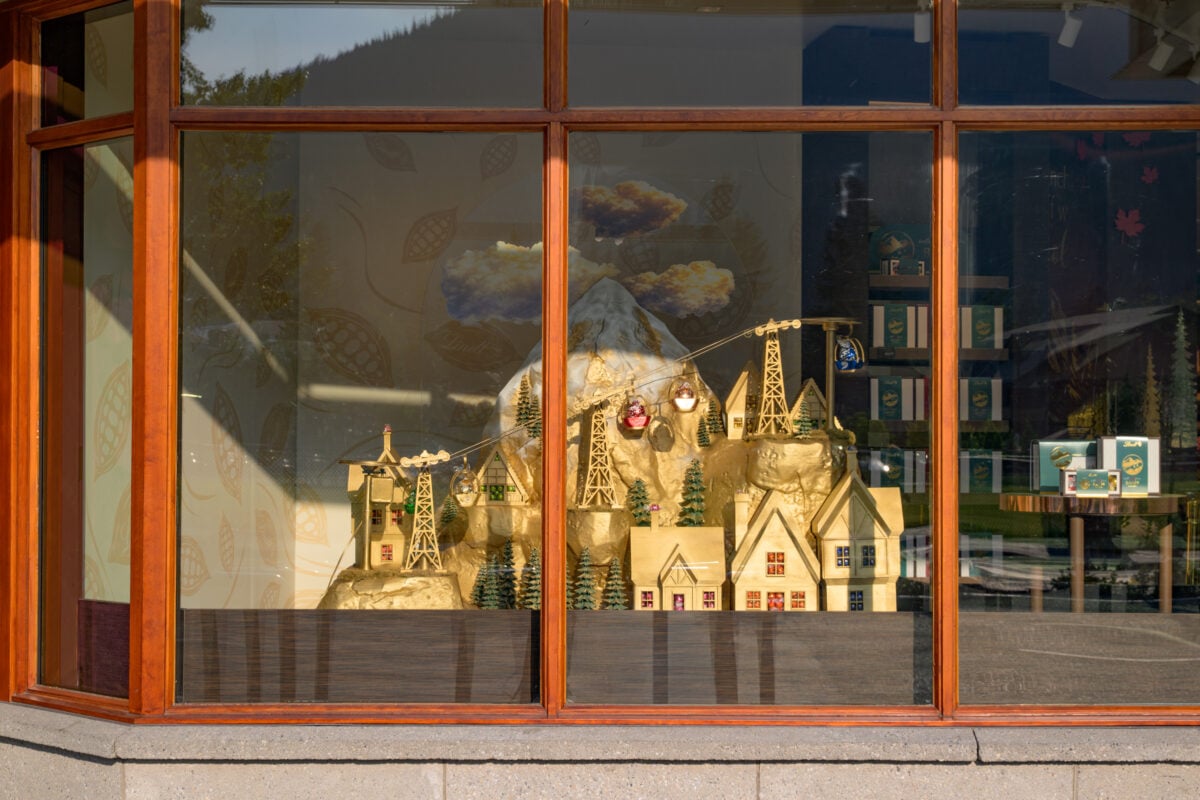
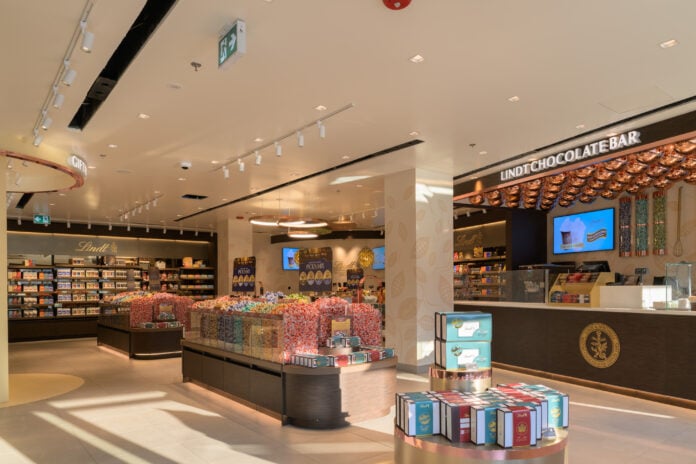
Lindt Chocolate Shop in Banff. Source: Lindt

Lindt & Sprüngli Canada has opened its first Lindt Chocolate Shop in Banff, bringing the Swiss chocolate brand to one of Canada’s highest-profile tourism markets and an increasingly competitive destination for specialty confectionery.

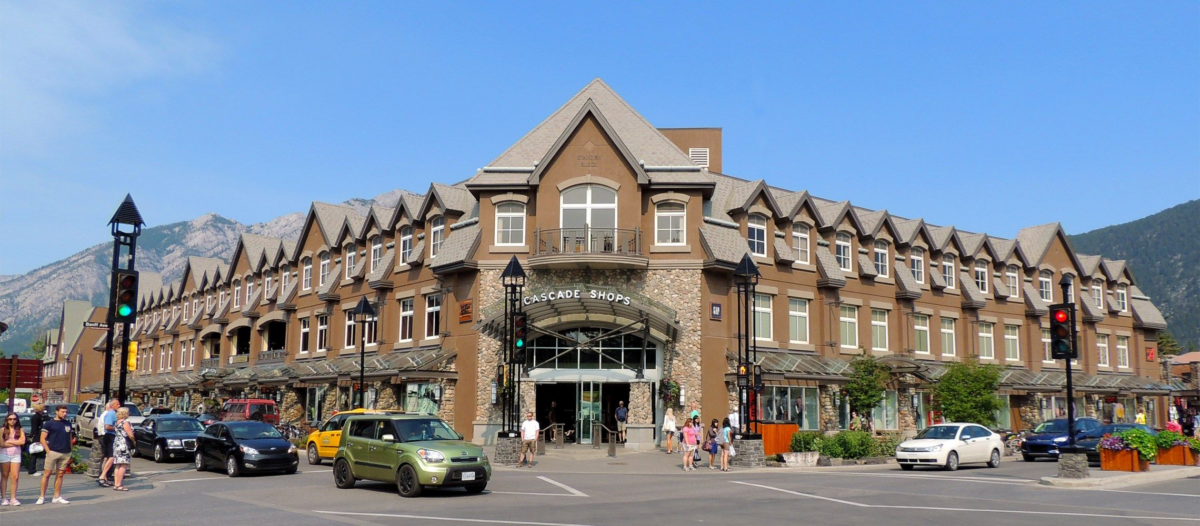
The new shop opened August 5 at 317 Banff Avenue, within the Cascade Shops property. It combines Lindt’s traditional chocolate assortment with prepared drinks, gelato, freshly crafted products and merchandise developed specifically for the mountain destination.

The opening comes as visitor activity in Banff is running at record levels. It also puts Lindt into direct competition with an established collection of confectionery businesses, including the recently launched Chocolate Board of Canada, Rocky Mtn Chocolate, The Fudgery and several other sweets and dessert operators along Banff Avenue.

Lindt has adapted parts of the shop specifically for the location. In addition to its signature LINDOR assortment, the Banff store carries freshly crafted chocolate bars, location-exclusive gift packaging and a Maple Sea Salt Leaf created by a Lindt Maître Chocolatier.

An on-site Drinks Bar serves hot and iced beverages made with Lindt chocolate, while the menu includes Lindt Crema Gelata and Crema Gelata shakes, introduced in 2026. Together, the assortment gives Lindt products for gifting and take-home purchases alongside drinks and desserts intended to be consumed during a visit.

The mix is well suited to Banff’s four-season tourism market. Hot chocolate and gifting fit naturally with winter and après-ski traffic, while gelato, shakes and iced beverages provide an offering for the much larger summer visitor period. It also gives Lindt a broader range of purchase occasions than a conventional boxed-chocolate shop.

Banff Adds a New Dimension to Lindt’s Canadian Network

The Banff opening appears to bring Lindt’s Canadian retail network to 52 locations. The company’s online store directory lists 51 other shops across nine provinces, with Ontario and Quebec accounting for 37 of those locations.

Banff becomes Lindt’s fifth Alberta store and its 11th across Western Canada. The company’s existing Alberta footprint includes Deerfoot Meadows in Calgary, CrossIron Mills north of the city and two stores in the Edmonton area.

The Banff shop gives Lindt a substantially different type of market, extending its presence beyond Alberta’s two largest metropolitan areas into a mountain community whose commercial economy is shaped by millions of annual visitors.

Lindt’s Canadian retail expansion has been underway for decades. Lindt & Sprüngli Canada has operated as a wholly owned subsidiary of the Swiss company since 1994, while Retail Insider reported in 2014 that the chocolatier had 20 stores in Canada and intended to add another 12 by the end of 2016.

Tourism destinations were already part of the company’s real estate strategy at the time. Lindt was considering locations ranging from outlet centres and super-regional malls to high streets, airports and tourist markets as it expanded nationally.

The current network reflects that variety. Lindt operates in major enclosed malls such as Yorkdale, CF Toronto Eaton Centre and Square One, alongside outlet and destination-shopping properties including CrossIron Mills, Tsawwassen Mills, McArthurGlen Designer Outlet Vancouver Airport and Outlet Collection at Niagara. It also has open-air and power-centre locations, downtown stores and a Vancouver Exchange Tower shop that has incorporated a café component.

Banff represents one of the clearest examples of Lindt applying its Canadian retail strategy to a tourism-driven destination.

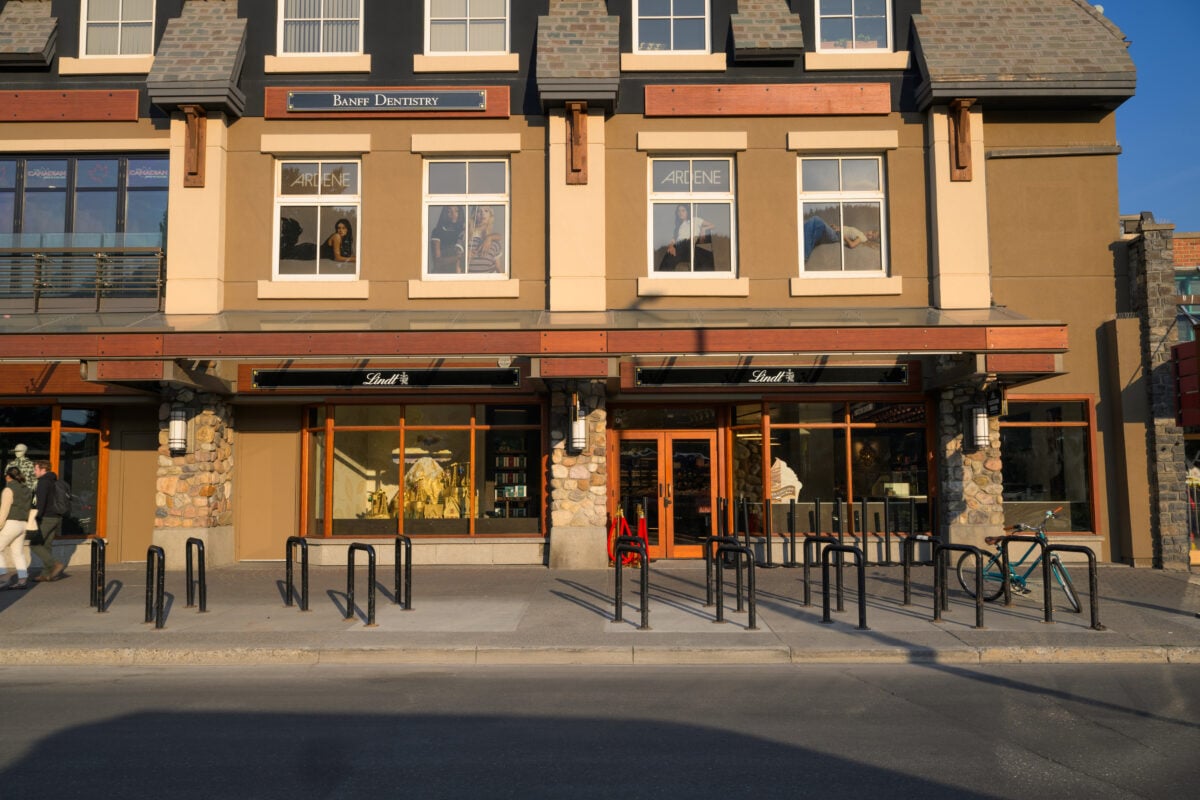
Lindt Chocolate Shop in Banff. Source: Lindt

Lindt Takes Banff Avenue Frontage at Cascade Shops

The new Lindt shop is part of Cascade Shops, the mixed-use property formerly known as Cascade Plaza at Banff Avenue and Wolf Street. The store also has its own exterior entrance directly from Banff Avenue, giving Lindt street-level frontage and access to pedestrian traffic while remaining part of the shopping centre.

Cascade Shops describes itself as Banff’s largest indoor shopping centre and the town’s only indoor mall. The complex contains 126,999 square feet of rentable area, including 81,328 square feet of retail, along with office, residential and hotel uses.

The location gives Lindt direct exposure along Banff’s primary commercial street while connecting the store with the broader Cascade Shops property. It also positions the chocolatier farther north along Banff Avenue than several established confectionery businesses concentrated around the 100 and 200 blocks.

Jeff Berkowitz and Joel Patterson of Aurora Retail Group negotiated the Banff lease deal on behalf of Lindt. Aurora Retail Group works with Lindt on its real estate across North America.

Record Tourism Supports a Much Larger Retail Market

Banff’s relatively small permanent population tells little about the scale of its retail opportunity. Banff National Park welcomed approximately 4.5 million visitors in 2025, according to Parks Canada, setting a record and increasing from the previous year, while summer visitation also rose.

Banff Avenue therefore functions differently from the main street of a conventional small Canadian community. Its stores serve local residents alongside Canadians and international visitors moving through one of the country’s best-known tourism destinations.

Confectionery is well suited to that spending environment. Chocolate can be consumed during a visit, purchased as an accessible indulgence or carried home as a gift, while ice cream, fudge, beverages and other sweets benefit from high pedestrian traffic and spontaneous purchasing.

For Lindt, location-exclusive products add another dimension. LINDOR and many other Lindt products are readily available through supermarkets, pharmacies and retailers across Canada, meaning visitors do not need a Lindt shop in Banff to access the brand.

Banff-specific packaging and products give those customers a reason to purchase from this particular location. The Maple Sea Salt Leaf similarly incorporates a recognizably Canadian flavour cue into an international brand whose identity remains rooted in more than 180 years of Swiss chocolate-making.

Lindt Chocolate Shop in Banff. Source: Lindt

A Competitive Chocolate Market

Lindt is entering a market where specialty chocolate and confectionery are already well established. One of the most significant additions came almost exactly a year earlier, when Chocolate Board of Canada opened its first location at 202 Banff Avenue in August 2025. The concept was created by the Canadian family behind Rocky Mtn Chocolate and launched in the historic Caribou Corner building, a prominent location that once housed Banff’s first Hudson’s Bay Company store.

Retail Insider reported at the time that Chocolate Board was developed as a more elevated concept than the company’s longstanding Rocky Mtn Chocolate format. Its assortment emphasizes artisan chocolates, hand-finished products, premium gift packaging and flavours intended to communicate a distinctly Canadian identity.

The Banff flagship also incorporates experience into the format. Customers can see elements of chocolate production taking place in the shop, while the assortment extends beyond packaged chocolates into handmade fudge, caramel popcorn, hot chocolate and ice cream.

Its operators deliberately chose Banff as the launch market for the new brand, giving Chocolate Board exposure to visitors from across Canada and around the world before taking the concept into other high-profile locations.

The arrival of Lindt creates an interesting contrast between two approaches to premium chocolate retail. Chocolate Board builds its identity around Canada, using domestic references, Canadian flavours, hand production and a brand created specifically to evoke place. Lindt arrives with international recognition, Swiss heritage and products familiar to consumers around the world.

In Banff, the strategies begin to overlap. Both businesses use premium presentation, destination gifting, beverages, frozen desserts and products associated with the visitor experience. Lindt’s Banff-exclusive packaging and Maple Sea Salt Leaf introduce local relevance to a global brand, while Chocolate Board uses Banff as a platform for an explicitly Canadian one.

Established Operators Add More Competition

Chocolate Board is far from the only established player Lindt will encounter. Rocky Mtn Chocolate continues to operate a separate store at 117 Banff Avenue, giving the company two distinct concepts in the market.

The Canadian Rocky Mtn Chocolate business traces its history to Whistler Village, where its first domestic location opened in 1988, providing decades of experience selling confectionery in mountain-tourism markets. Its more playful format, including highly visual products such as caramel apples, remains distinct from the premium positioning developed for Chocolate Board.

Other nearby businesses add further competition for sweets and dessert spending. The Fudgery offers handmade chocolates, fudge, brittle, truffles and other confectionery, while Banff Sweet Shoppe sells handmade chocolate, fudge and nostalgic candy. Banff Candy Store specializes in retro and international sweets, and COWS competes for dessert traffic through its premium ice cream business.

These businesses vary considerably in format, price and positioning, but they share the same underlying opportunity: capturing discretionary spending from visitors moving through a compact tourism district. For Lindt, that means competing for more than chocolate purchases, since a visitor considering a gelato or chocolate drink may also be choosing among ice cream, fudge, candy and other treats available only a short walk away.

Cascade Shops in Banff. Photo: Tourism Alberta

Chocolate Retail Moves Beyond the Box

The growing Banff market also illustrates how specialty chocolate retail is evolving. For brands operating their own stores, the opportunity increasingly extends beyond shelves of boxed chocolates as drinks, desserts, fresh preparation, visible production and exclusive merchandise make the shop itself part of the experience.

Lindt’s Banff store reflects that shift with its Drinks Bar, Crema Gelata, shakes and freshly crafted chocolate bars. Chocolate Board combines chocolate retail with visible production, handmade products, ice cream and hot beverages, while Rocky Mtn Chocolate and long-established independents have similarly relied on preparation, aroma and visual merchandising to draw visitors into their stores.

The result is a broader set of purchase occasions. A customer might enter for a hot drink, buy gelato during an afternoon walk or pick up a Banff-specific package to take home. The same store can address immediate consumption, personal indulgence, gifting and souvenirs.

That flexibility has become particularly relevant as the global chocolate industry manages sharply higher cocoa costs and significant increases in retail pricing. Lindt has continued to grow its North American business, but the company has also acknowledged broader pressure on chocolate volumes following substantial price increases across the category.

Specialty retail gives Lindt a way to offer something different from the products consumers already encounter in conventional grocery and drugstore channels. In Banff, the value of the shop is tied to the experience, location and exclusivity surrounding the chocolate as well as the product itself.

Banff as a Showcase Market

Banff offers another advantage that is difficult to replicate in a conventional regional market: enormous geographic reach within a relatively compact retail district. A business operating on Banff Avenue can encounter customers from across Canada and around the world during the same trading day. Visitors are also experiencing the stores during leisure travel, when dining, shopping, gifting and other discretionary purchases are part of the trip.

Chocolate Board used that environment to introduce a new Canadian brand, while Lindt is using it to present a localized version of one of the world’s most recognizable chocolate names. Their approaches point to a wider evolution in destination retail, where recognizable products are increasingly combined with local references and experiences specific to the place where they are sold.

Banff remains built around mountain scenery, outdoor recreation and hospitality, but its commercial district also provides brands with a highly visible stage for concepts designed around experience, premium products and a strong sense of place.

Lindt’s arrival adds another international name to that mix while intensifying competition in a confectionery market that is already remarkably deep for a community of Banff’s size. For visitors, that means more choice. For the retailers competing along Banff Avenue, it raises the stakes in creating an experience memorable enough to travel home with the chocolate.

More from Retail Insider:

Biggest marketing lessons from FIFA World Cup: Vistar Media

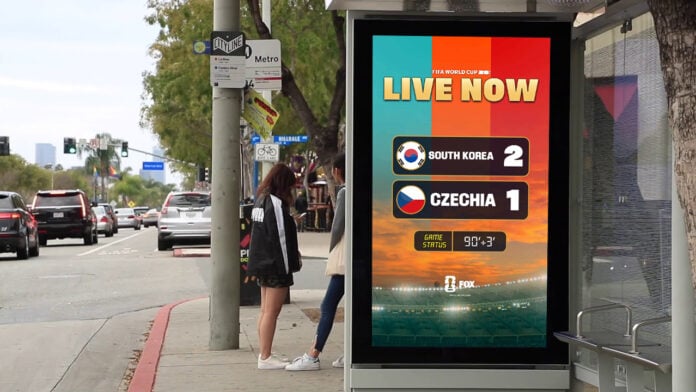
Vistar media image
Vistar media image

Now that the FIFA World Cup has wrapped, one thing is clear: the brands that won weren’t necessarily the official sponsors. They were the ones that understood where fans were, how they were engaging, and how to stay relevant long after the final whistle.

In an interview with Retail Insider, Scott Mitchell, Managing Director, Canada at Vistar Media, breaks down the biggest marketing lessons from this year’s tournament and what brands should take away for future major sporting and cultural moments.

Question: What separated the most successful World Cup marketing campaigns from the ones that struggled to break through the noise?

Answer: The World Cup wasn’t just 90 minutes. Fans followed highlights throughout the day, met friends to watch matches, celebrated in public spaces and continued engaging with content long after the final whistle.

The brands that resonated recognized those behaviours. Rather than focusing on a  single moment, they built a connected presence throughout the tournament, delivering relevant messages in the moments and places where fans were already engaged.

Q: You argue that context mattered more than official sponsorship. What did brands like BMO do right, and what lessons can other non-sponsors take from their approach?

A: One of the biggest misconceptions around major sporting events is that brands need official sponsorship rights to be part of the conversation. In reality, consumers care far more about whether a brand feels relevant to the experience than whether it has official status.

BMO understood that. It built on its longstanding connection to soccer in Canada through activations, experiences and out-of-home advertising. Rather than trying to compete with official sponsors, the brand focused on reaching fans in places they were already gathering, like Toronto’s Union Station, with creative that reflected the excitement surrounding the tournament. There was no need to reference FIFA directly because the context did the work.

That’s an important lesson for marketers. You don’t have to own the event to participate in it. If you understand your audience, deliver compelling creative and show up at the right moments, you can create meaningful connections without official rights.

Vistar Media image
Vistar Media image

Q: How has the fan journey evolved beyond the stadium, and what does that mean for where brands should be investing their marketing dollars during major sporting events?

A: Today’s consumer journey doesn’t follow a single path. People discover content, connect with friends, shop and make decisions across multiple environments throughout the day across multiple environments throughout the day.

During FIFA, the stadium was just one part of the experience. Fans were commuting, gathering in restaurants and bars, travelling between destinations and catching highlights long before and after each match.  Brands that planned around those moments had far more opportunities to stay relevant.

For marketers, the takeaway is to plan around how people move through the real world, not around individual channels. The strongest campaigns use complementary channels to reinforce one another, helping brands remain top of mind throughout the entire consumer journey instead of relying on a single moment of attention.

Q: Tim Hortons is cited as a brand that focused on long-term cultural relevance rather than short-term buzz. What made that strategy effective, and how can other Canadian brands apply it?

A: Consumers are increasingly drawn to brands that feel authentic rather than opportunistic.

Like BMO, Tim Hortons wasn’t an official sponsor, but it’s a brand that Canadians already associate with sports at both the professional and community level. Its soccer-themed Timbit Buckets were a simple but effective way to tap into the excitement surrounding the tournament. There was no FIFA branding, but there didn’t need to be. Canadians immediately understood the connection because it felt like a natural extension of the brand.

That’s the opportunity for other Canadian brands. Start with what your audience already associates with your brand, then find authentic ways to participate in the moments that matter to them. The most effective campaigns build on existing brand equity instead of chasing short-term attention. Official sponsorship can amplify a campaign, but it’s not the only path to relevance.

Vistar Media image
Vistar Media image

Q: Looking ahead to future major sporting and cultural events, what are the biggest opportunities and biggest mistakes you expect Canadian brands to make?

A: Canada has an incredible lineup of major sporting and cultural events over the next several years, creating more opportunities than ever for brands to connect with consumers during shared experiences.

The brands that will benefit most are the ones that start planning early and think beyond the event itself.  The opportunity isn’t limited to the main event. It’s in the anticipation beforehand, the moments when people come together to experience it and the conversations that continue afterwards. Campaigns that reflect those behaviours are far more likely to resonate with audiences.

The biggest mistake is treating these moments as isolated marketing opportunities. The strongest campaigns don’t just capitalize on a cultural moment. They reinforce broader brand-building efforts by delivering relevant, consistent experiences across the customer journey.

More from Retail Insider:

Vistar Media image
Vistar Media image

Cozey expands sleeper sofa category with two new products

Cozey photo
Cozey photo

Montreal-based furniture company Cozey is expanding its sleeper sofa category with two new products, the Orian Sofa Bed and the Atmosphere Sofa Bed, as it broadens its range of multifunctional furniture.

The launches add sleeper functionality to two different designs, including an existing modular collection, with the company positioning the products as options for customers looking to accommodate guests or make more efficient use of living space.

Two new sofa beds

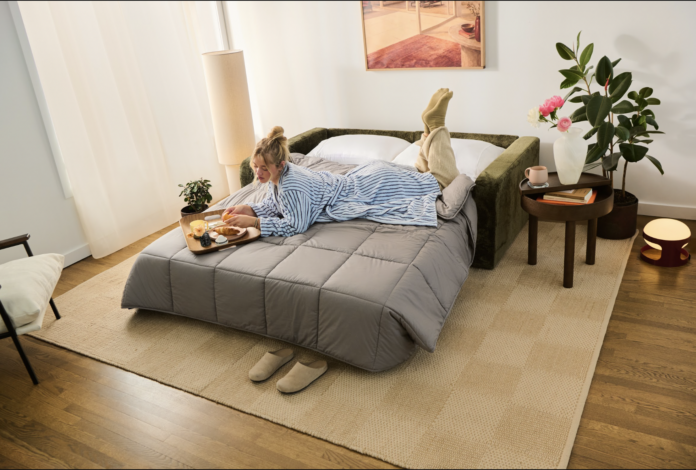
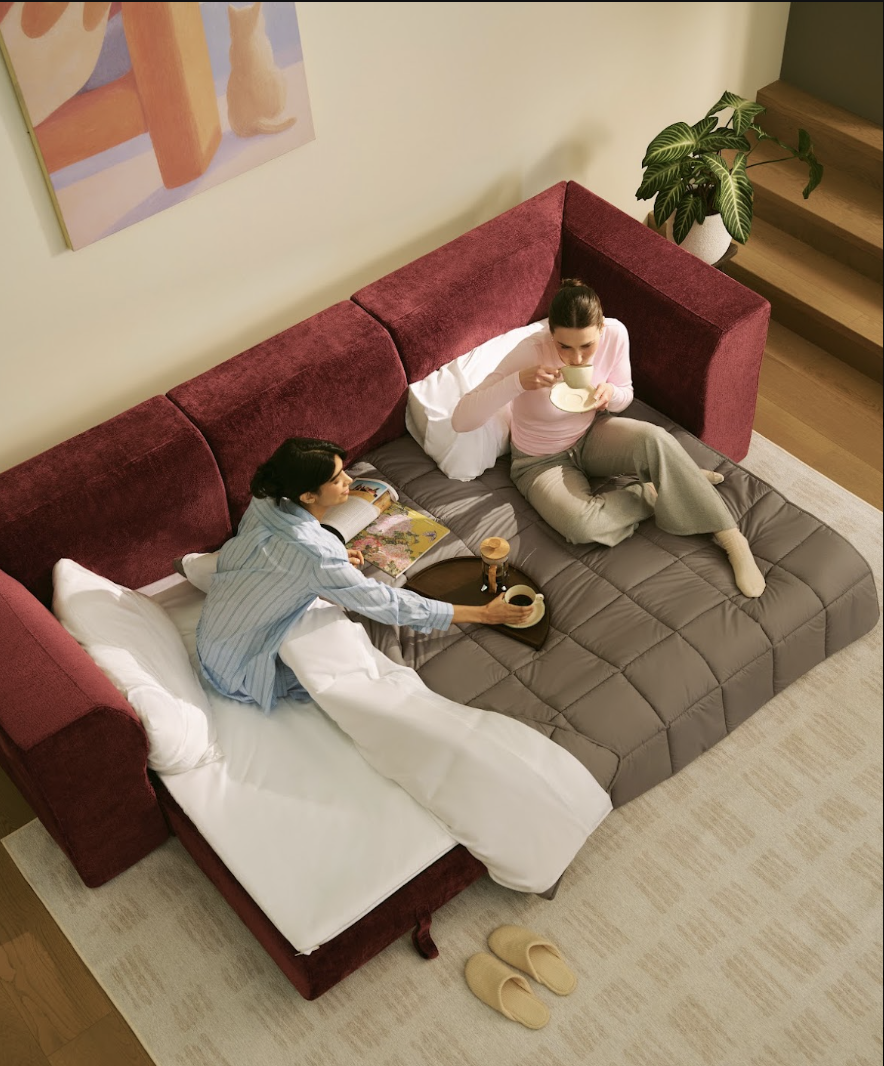
The Orian Sofa Bed combines a compact modular design with a contemporary silhouette and converts from a sofa into a queen-size bed using a pull-out mechanism.

The product is available with optional storage modules and comes in five colourways across Chenille, Aquaforte™ and Performance fabrics. It starts at $1,395 CAD for a two-seater.

The Atmosphere Sofa Bed extends Cozey’s Atmosphere modular collection with an integrated sleeper option. The company says it is the first time sleeping functionality has been incorporated into the collection.

The Atmosphere Sofa Bed is available in more than 15 colourways across Corduroy, Chenille and Performance fabrics. Customers can select from four arm configurations: High Angled Square, Regular Square, Rounded or Armless.

The product starts at $2,290 CAD for a two-seater.

Frédéric Aubé, Founder and CEO of Cozey

“The way people use their homes has changed significantly over the past few years, and we’re seeing growing demand for furniture that works harder without sacrificing design,” said Frédéric Aubé, CEO and Founder of Cozey. “With the Orian and the Atmosphere Sofa Bed, we’re evolving the category with solutions that are intuitive, beautifully designed, and adaptable in ways that support everyday living, whether you’re furnishing a smaller space or simply looking for more flexibility at home.”

Building on earlier sleeper sofa

The two launches follow the introduction of Cozey’s Neptune Sofa Bed in 2023, the company’s first sleeper sofa.

According to the release, the Neptune was developed with a mechanism that allows it to convert into a queen-size bed without a bulky pull-out system and without requiring additional modules or ottomans.

The Atmosphere Sofa Bed also expands an existing modular collection that includes additional storage modules, giving customers more configuration options within the line.

Cozey photo
Cozey photo

The company says the new products are part of its broader expansion across furniture categories, with a focus on multifunctional designs intended to accommodate different uses within the home.

Cozey describes itself as a North American furniture company focused on customer-centric design, quality and innovation. The company says its mission is to make adaptable and timeless furniture accessible to consumers, while also emphasizing the well-being of its customers, employees and partners.

The new sleeper sofas add to that product strategy by combining seating and sleeping functions in two distinct designs and price points.

More from Retail Insider:

Equifax survey finds one in four Canadians expect to make only minimum credit-card payments

Vitaly Gariev photo
Vitaly Gariev photo

Nearly one in four Canadians surveyed by Equifax Canada say they expect to make only the minimum monthly payment on their credit cards, as more households report using credit and savings to cover everyday expenses.

The survey of 1,532 Canadians also found that seven per cent expect they will fall behind on their credit-card payments, while 56 per cent expect to pay their balances in full each month.

The findings point to growing financial pressure among some households, with 40 per cent of respondents saying they are spending more overall than they were a year ago, compared with 18 per cent who are spending less.

Credit and savings used for essentials

The survey found that Canadians are increasingly drawing on credit and savings to manage household expenses.

Twenty-nine per cent of respondents said they are using more credit than they were a year ago to pay for groceries, utilities and other essential living expenses. Another 23 per cent said they are drawing on savings to cover day-to-day costs, while 20 per cent said they are relying more on credit cards and lines of credit.

At the same time, 35 per cent said they have reduced contributions to savings, investments or education funds. Forty-four per cent said they worry they are not saving enough for retirement, while 41 per cent are concerned about unforeseen emergency expenses.

“The results point to mounting financial pressure for many households,” said Rebecca Oakes, Vice-President of Advanced Analytics at Equifax Canada. “The survey indicates that a significant percentage of Canadians surveyed (29 per cent) are using credit and savings to manage everyday expenses, while 35 per cent are cutting back on contributions to save for their future and expecting to make only minimum credit card payments. When these pressures begin to overlap, households can lose financial flexibility quickly.”

The survey also found that 32 per cent have reduced spending on essential living expenses, including groceries and utilities.

Discretionary spending also down

Canadians surveyed reported cutting back on discretionary expenses as well. Sixty-seven per cent said they have reduced spending on entertainment and leisure, while 40 per cent have cut spending on personal care.

The survey found that 60 per cent of respondents are actively avoiding taking on new debt. At the same time, 13 per cent said they are borrowing more to cover basic living expenses, while eight per cent said they are opening new credit cards or taking on new loans.

Financial confidence has also weakened. Twenty-nine per cent of respondents said they are less confident in their ability to manage financial demands than they were a year ago, compared with 23 per cent who said they are more confident. Forty-seven per cent said their confidence is about the same.

“Financial pressure often builds gradually, and making only the minimum payment can sometimes feel like a way to manage through a difficult month,” said Julie Kuzmic, Head of Consumer Advocacy and Compliance at Equifax Canada. “However, balances can take much longer to repay and cost considerably more in interest. Anyone seeing their balances continually rise with little hope at repayment should review payment obligations, prioritize due dates and explore options with their lenders or a reputable credit counsellor before their financial situation limits their options.”

Vitaly Gariev photo
Vitaly Gariev photo

Families, younger adults report greater pressure

Households with children reported greater financial pressure than those without children.

Fifty-one per cent of respondents with children said they are spending more than they did a year ago, compared with 35 per cent of those without children.

Among households with children, 42 per cent said they are using more credit than last year to pay for essential living expenses, compared with 24 per cent of households without children. Thirty-three per cent of respondents with children expect they will only be able to make minimum monthly credit-card payments.

Forty-five per cent of those with children said they are concerned about supporting family members, including children’s education or aging parents, compared with 18 per cent of those without children.

Respondents under 55 also reported greater financial pressure than older respondents. Thirty-six per cent of those under 55 said they are using more credit for essential expenses than they were a year ago, compared with 18 per cent of those aged 55 and older.

Among respondents under 55, 42 per cent said they are spending more overall than a year ago, compared with 36 per cent of those aged 55 and older. Thirty-one per cent expect they may only be able to make minimum monthly credit-card payments, compared with 16 per cent of older respondents.

Twenty-two per cent of respondents under 55 said they are struggling to pay down debt because of high housing or mortgage costs, compared with 11 per cent of those aged 55 and older.

Only 47 per cent of Canadians under 55 expect to pay their credit-card balance in full each month, compared with 69 per cent of those aged 55 and older.

More from Retail Insider:

Taco Bell brings Enchirito to Canada in limited Southwestern Ontario test

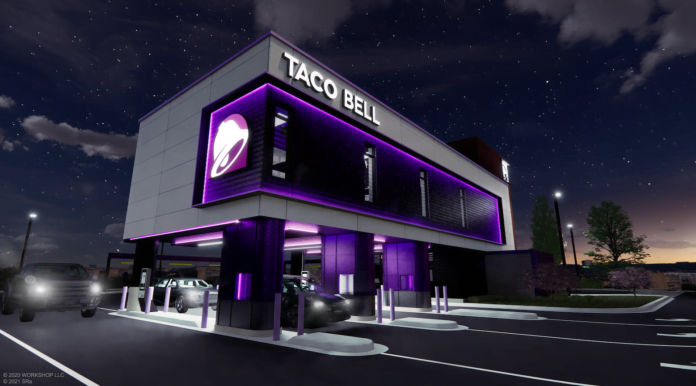
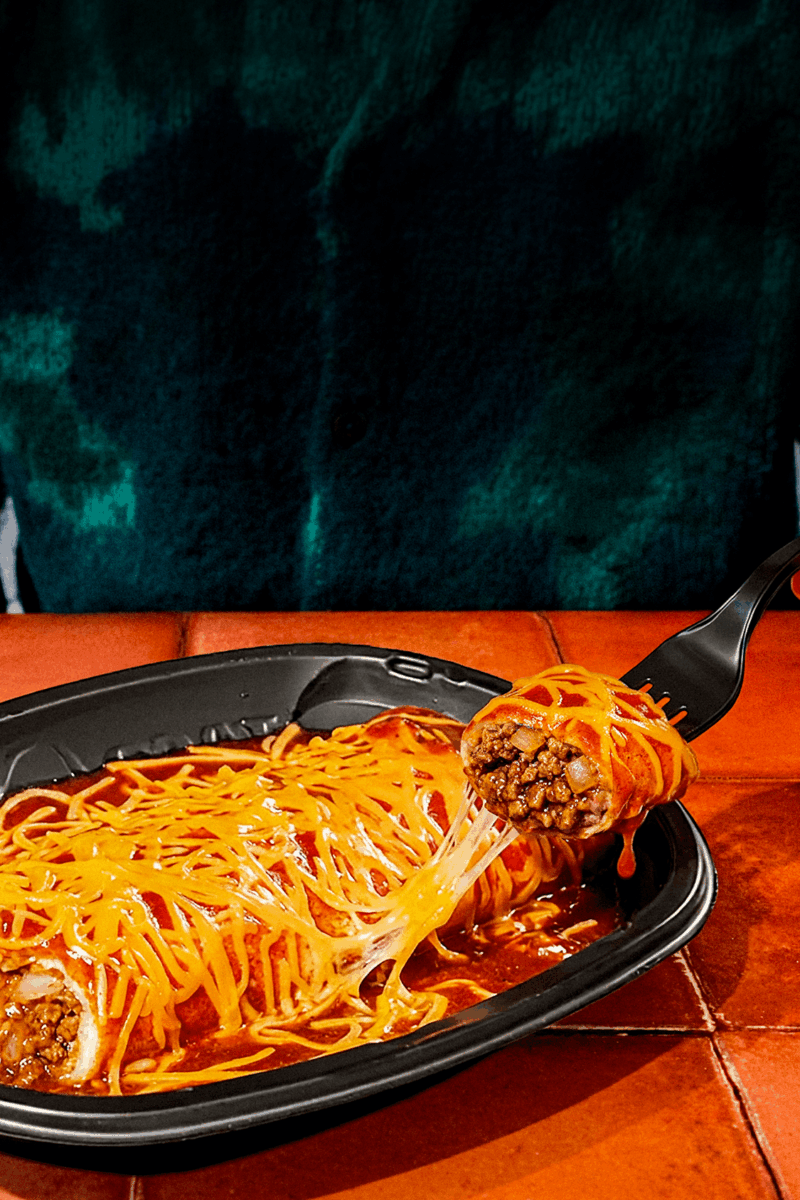
Image: Taco Bell Canada

Taco Bell has brought the Enchirito to Canada for the first time, but only customers at 15 participating restaurants in Southwestern Ontario will be able to buy the menu item during a two-week launch.

The Enchirito is available for $3 plus applicable taxes from July 30 through Aug. 13 at restaurants in Amherstburg, Chatham, Kingsville, LaSalle, Niagara Falls, Sarnia, Wallaceburg and Windsor.

Limited rollout

Rather than introduce the item across its Canadian network, Taco Bell Canada is using the Southwestern Ontario launch as a controlled test of demand and restaurant operations.

“We know Canadians love discovering iconic Taco Bell menu items, so we wanted the Enchirito’s Canadian debut to feel special,” said Meera Patel, Director of Marketing. “We’re starting small. These communities get the first taste, and the bragging rights, and the response will help shape what happens next.”

The company says the limited rollout will allow it to assess guest demand, operational execution and overall performance before deciding whether to bring the Enchirito to other Canadian markets.

If the launch performs well, the item could be expanded to additional regions across Canada. Guest response during the promotion will help inform those future plans.

What customers are getting

The Enchirito, a Taco Bell menu item dating to the 1970s, combines elements of an enchilada and a burrito. It consists of a soft flour tortilla filled with seasoned beef, refried beans and onions, topped with red sauce and shredded cheddar cheese and heated until the cheese is melted.

“Being among the first restaurants in Canada to serve the Enchirito is an exciting moment for our teams and our guests,” said Puja Gupta, Franchisee of Gupta Foods. “We are proud to help introduce this Taco Bell icon to Canada and look forward to seeing the response across our communities.”

The $3 price applies at participating restaurants, while pricing may be higher through delivery platforms. Availability and participation may vary by restaurant.

Participating locations

The Enchirito is being offered at 527 Sandwich Street South in Amherstburg; 328 St. Clair Street in Chatham; 329 Main Street East in Kingsville; 3770 Montrose Road in Niagara Falls; 1337 London Road in Sarnia; 60 McNaughton Avenue in Wallaceburg; and 2301 Sandwich Parkway West in LaSalle.

The Windsor locations are 300 Tecumseh Road North, 301 Ouellette Avenue, 1655 Manning Road, 1790 Huron Church Road, 3058 Dougall Avenue, Devonshire Mall at 3100 Howard Avenue, 3419 Tecumseh Road East and 6707 Tecumseh Road East.

More from Retail Insider:

Plaza Retail REIT reports higher second-quarter profit

Plaza REIT photo
Plaza REIT photo

Plaza Retail REIT recently reported higher profit and operating income in the second quarter as leasing, rent increases and improved cost recoveries helped drive growth across its retail property portfolio.

The Fredericton-based real estate investment trust said that profit and total comprehensive income rose 31.2 per cent to $16.6 million in the three months ended June 30, compared with $12.7 million in the same period a year earlier.

Net operating income increased 4.3 per cent to $19.9 million from $19.1 million, while revenue rose 1.2 per cent to $32.2 million.

The results come as Plaza continues to adjust its portfolio, including selectively selling properties while directing capital toward developments, intensifications and other initiatives.

“We delivered solid growth through the first half of 2026, supported by continued execution across our portfolio,” said Jason Parravano, President and Chief Executive Officer.

“FFO (Funds From Operations) per unit increased to $0.105 for the quarter, $0.202 year-to-date, up 5.0% and 7.4% respectively, compared with the same periods in the prior year (or 8.3% year-to-date after adjusting for certain timing and severance impacts). AFFO (Adjusted Funds From Operations) per unit increased to $0.078 for the quarter, $0.152 year-to-date, up 16.4% and 7.0% respectively, compared with the same periods in the prior year (or 8.0% year-to-date after adjusting for certain timing and severance impacts). Our FFO and AFFO payout ratios also improved to 69.2% and 92.2% year-to-date, respectively, strengthening our financial flexibility and demonstrating that the structural changes made to the business over the past year are producing sustainable results and predictable growth.”

Operating results

Plaza said quarterly NOI (Net Operating Income) increased by $828,000 from a year earlier, with the gain attributed to higher revenue from leasing and rent escalations, as well as improved cost recoveries.

Same-asset NOI increased 2.7 per cent in the quarter and 2.3 per cent for the first six months of the year. Committed occupancy was 97.6 per cent.

“Operating fundamentals remained resilient. Total NOI increased by 4.3% for the quarter, 3.4% year-to-date, and same asset NOI increased by 2.7% for the quarter, 2.3% year-to-date. Committed occupancy remained strong at 97.6%, supported by continued tenant demand, contractual rent growth and leasing activity across our essential retail portfolio.”

For the six months ended June 30, revenue was $64.7 million, up 2.8 per cent from $62.9 million a year earlier. NOI increased 3.4 per cent to $38.7 million from $37.4 million.

The year-to-date increase in NOI was attributed to higher leasing revenue, rent escalations and improved cost recoveries, partly offset by higher operating expenses.

Portfolio and capital allocation

Plaza said its strategy includes selling some properties while continuing to add space through development and other projects.

“We remain focused on improving the quality, scale and earnings capacity of our portfolio,” said Parravano. “While we have selectively sold certain properties this year, we will continue to add square footage through developments, intensifications and other strategic initiatives. This reflects a deliberate approach to capital allocation. We are recycling capital from mature or non-core assets into opportunities that can generate stronger returns, improve portfolio quality and contribute to sustainable cash flow growth.”

The trust’s portfolio at June 30 consisted of interests in 189 properties totalling approximately 8.8 million square feet across Canada, along with additional land held for development.

Plaza said the portfolio consists largely of open-air centres and stand-alone small-box retail outlets and is predominantly occupied by national tenants focused on essential needs, value and convenience.

Higher profit

Plaza’s quarterly profit was also affected by changes in the fair value of investment properties. The $5.1 million net increase in fair value during the quarter was $3.8 million higher than in the same period of 2025.

For the first six months of the year, profit and total comprehensive income was $29.4 million, compared with $22.0 million a year earlier, an increase of 33.9 per cent.

The year-to-date results included a $2-million increase in the share of profit of associates, which Plaza attributed mainly to a non-cash fair-value adjustment to underlying investment properties and changes involving 5400 Laurier Ouest Limited Partnership and the acquisition of Plazacorp Ontario-1 Limited Partnership.

The change in fair value of investment properties accounted for another $3.8 million of the year-over-year increase in profit.

“Our progress is measured not simply by the number of properties we own, but by the quality and scale of our real estate, the cash flow it generates, and the value created on a per unit basis. With growing FFO and AFFO, improved payout ratios and a pipeline of projects advancing across the portfolio, we believe Plaza is well positioned to continue creating long term value for unitholders.”

More from Retail Insider:

Daily Synopsis: Aug 7, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published covering key developments in Canadian retail.

Winnipeg-based Quarks expanded its Canadian footwear footprint as it nears 50 years in business with a focus on regional markets and sustainable growth. Tim Hortons plans stronger Canadian growth through 80 new stores, 400 renovations, and expanded beverage and loyalty programs. Leon’s Furniture reported higher Q2 net income despite a slight sales decline, driven by cost control and strategic investments.

Canada’s freight market is shifting unevenly with truckload transportation strengthening, influencing retail supply chain strategies discussed in this analysis.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

What Retail Market Research Teaches Us About the Future of Shopping

Ever noticed how shopping feels different than it did even five years ago? Not just the fact that half your purchases arrive on the doorstep now. It’s the whole rhythm of it. The way people browse, compare, hesitate, and eventually buy. Retailers have been paying close attention to all of this, mostly because they have to. And the tool doing a lot of the quiet heavy lifting behind the scenes is market research.

The truth is, most of the big shifts in retail didn’t happen by accident. Someone studied shopper behaviour, spotted a pattern, and acted on it. So what exactly has all that research been telling us? Quite a lot, as it turns out.

Shoppers Want Convenience, But Not at Any Cost

Here’s the thing about convenience. Everyone says they want it, and they genuinely do, but research keeps showing there’s a limit. People love one-click checkouts and same-day delivery. What they don’t love is feeling like a data point being squeezed for every last penny.

Studies into shopping habits have picked up on this tension again and again. Customers will happily hand over their email for a discount, then get irritated when they’re bombarded with twelve promotional messages a week. Funny how that works. The research suggests the future isn’t just about making things faster. It’s about making things feel respectful too.

Picture this: trying to buy a pair of shoes and being asked to create an account, verify your phone, and answer a survey before you can even see the price. Most people bail. Retailers who’ve done their homework know this, and they’re stripping back the friction rather than adding to it.

The Blurred Line Between Online and In-Store

Remember when online shopping and physical shopping felt like two separate worlds? That’s pretty much over. People now research on their phones while standing in a shop. Or they’ll spot something in a store window, then order it online later that night from the sofa.

Market research has been tracking this back-and-forth movement for years, and the findings are clear. Shoppers don’t think in channels. They just think about the thing they want. Whether it comes from a warehouse or a shelf barely registers.

This part’s a bit tricky for retailers, honestly. Because it means the old habit of treating the website and the shop floor as separate businesses doesn’t hold up anymore. The ones getting it right are stitching the two together so a customer can start in one place and finish in another without a hitch.

Personalisation Is Expected, Not Impressive

A while back, personalised recommendations felt kind of clever. Now? People barely notice them, and they get annoyed when they’re wrong. Recommend a lawnmower to someone in a flat with no garden and you’ve just reminded them the algorithm doesn’t really know them.

Good research digs into what personalisation actually means to shoppers, and it’s usually more subtle than a “you might also like” widget. It’s about remembering preferences, respecting past choices, and not making people repeat themselves. This is where solid Kadence market research helps brands understand the difference between helpful and creepy, which is a line that shifts depending on who you ask.

Values Are Doing Some of the Shopping Now

Something interesting has crept into the data over the past decade. People increasingly care about where their stuff comes from. Sustainability, fair treatment of workers, honest sourcing. These aren’t fringe concerns anymore.

But here’s where it gets interesting. Research also shows a gap between what people say and what they actually buy. Someone might rate ethics as hugely important, then grab the cheaper option anyway. Retailers who only listen to the survey answers get caught out. The ones who watch real behaviour alongside stated opinions get a much truer picture.

That gap, by the way, is exactly why good research matters so much. Ask the wrong question or trust the surface answer and you build a strategy on sand.

So Where Does This Leave Shopping?

Somewhere more human, oddly enough. All this data and behavioural study keeps pointing back to fairly simple wants. People want to feel understood. They want things to be easy without feeling manipulated. And they want to trust the brands they hand their money to.

The retailers who thrive over the next few years probably won’t be the ones with the flashiest tech. They’ll be the ones who actually listened. Turns out understanding your customer never really goes out of fashion.

Retail Event Strategies That Help Brands Stand Out

Retail events offer brands a chance to create meaningful face-to-face connections that digital marketing alone cannot replicate. Whether you’re preparing for a trade show, pop-up activation, or community event, the right retail event strategies can increase visibility, attract qualified prospects, and strengthen long-term customer relationships. Success depends on careful planning, attractive event design, engaging customer experiences, strategic budgeting, and effective post-event follow-up. These strategies help businesses maximize event results while building stronger relationships and achieving measurable marketing outcomes.

Design an Event Space That Attracts Attention

Your event space should communicate your brand within seconds. Clean layouts, bold graphics, effective lighting, and open traffic flow encourage visitors to stop instead of walking past. For outdoor promotions, a Custom canopy tent provides both weather protection and strong visual branding while making your location easier to spot. Consistent colors, clear messaging, and professional displays create trust before conversations even begin.

Visitors often decide quickly whether to approach a booth, making first impressions essential. An organized layout helps attendees move comfortably, while high-quality visuals reinforce brand identity. Positioning important products or demonstrations in visible areas can increase engagement.

Practical design choices also influence visitor experience. Comfortable meeting spaces, accessible displays, digital screens, and interactive elements can make the booth more welcoming without creating clutter. Every design element should support a consistent brand story that remains memorable after the event.

Engage Visitors With Interactive Experiences

People remember experiences more than displays. Live demonstrations, hands-on product testing, educational sessions, and interactive technology keep visitors engaged and create opportunities for meaningful conversations. Instead of overwhelming attendees with information, focus on solving a specific customer problem. High-quality printed displays from providers such as expoprint can reinforce key messages throughout the visitor journey without distracting from personal interaction.

Interactive experiences turn passive visitors into active participants. Product trials, guided demonstrations, touchscreens, and live presentations help attendees understand the value of your offering more effectively than traditional presentations.

Staff training is equally important. Friendly and knowledgeable team members who listen carefully create stronger relationships than scripted sales pitches. Authentic conversations build trust and increase the chance that visitors will remember your brand.

Digital tools can also extend engagement. QR codes, digital catalogs, online sign-ups, and contests provide additional value for attendees while helping brands collect useful customer information for future communication.

Balance Budget, Branding, and Materials

Not every investment delivers equal value. Prioritizing elements that improve visitor experience usually produces better results than spending heavily on giveaways alone.

InvestmentPrimary BenefitPriority
Booth structureVisibility and professionalismHigh
Branded signageBrand recognitionHigh
Interactive demonstrationsVisitor engagementHigh
Promotional giveawaysTraffic generationMedium
Digital lead captureConversion trackingHigh
Staff trainingBetter customer interactionsHigh
Product samplesHands-on experienceMedium

A balanced budget combines durable branding materials with experiences that encourage meaningful conversations instead of simply increasing foot traffic.

Promotional merchandise may attract attention, but it creates more value when combined with strong engagement. Investing in reusable displays, professional graphics, and trained staff often provides better long-term returns while maintaining a consistent brand image.

Reviewing previous event performance also helps optimize spending. If certain materials or activities create limited engagement, those resources can be redirected toward areas that improve customer experience and results.

Measure Success After the Event

The event isn’t over when attendees leave. Strong follow-up determines whether conversations become customers.

  • Organize leads within 24-48 hours.
  • Send personalized follow-up messages.
  • Measure conversions against your original goals.
  • Review visitor feedback and staff observations.
  • Apply lessons to improve future events.
  • Compare results with previous events.
  • Update CRM records for future sales conversations.

Consistent measurement helps identify which retail event strategies generate the strongest return on investment and deserve more attention in future campaigns.

Quick follow-up keeps your brand fresh in attendees’ minds. Personalized emails, calls, or product recommendations are more effective than generic messages. Combining conversion data with visitor feedback provides a clearer understanding of strengths and areas for improvement.

Frequently Asked Questions

How can a small brand stand out at a trade show?

Focus on a clear message, distinctive visuals, engaging demonstrations, and authentic conversations rather than competing only on booth size. Meaningful interactions often create stronger impressions.

How do you measure retail event success?

Track qualified leads, sales, customer engagement, conversion rates, and return on investment against your original goals. Both data and attendee feedback help evaluate performance.

Conclusion

Outstanding retail events are built through thoughtful planning, engaging experiences, and disciplined follow-up not bigger budgets alone. By refining your retail event strategies before, during, and after every event, you can create stronger customer connections, improve lead quality, and turn each activation into a measurable business opportunity. When goal setting, booth design, visitor engagement, and performance analysis work together, retail events become powerful tools for strengthening brands, building customer relationships, and supporting sustainable growth.