By Antony Karabus
The retail and fashion apparel landscape has undergone significant changes in the past decade, with the traditional department store retailers seeing their dominance erode, losing market share rapidly to the fast fashion, off-price, and mass value sectors. Within the fashion apparel and luxury goods segment, mono-branded stores are stealing significant market share from department stores.
At the same time, changing consumer preferences have reshaped the entire market as a bifurcation of spending segments has created a concentration of expenditures within a smaller portion of the population. Twenty years ago, the top 20 percent of Canadians earned approximately 56% of all the income from wealth ( dividends, capital gains and interest). Now the top 20 percent of Canadians earned more than 67% of all income from wealth, showing that the income gap has become more pronounced over time ( the rich are clearly getting richer while the poor are struggling to make ends meet and are spending on basic needs for the most part).
According to a recent report from Statistics Canada from 2024, the top 20% of earners in Canada (those earning more than $ 250,000) are responsible for approximately 50% of all consumer spending. Some analysts believe that percentage to be even higher. That massive change in apparent spending, of course, leads to corresponding changes in how and where those consumers shop.
This seismic shift marks a historic high in consumption concentration. The top-tier spending group drives major economic activity, including other sectors such as leisure travel and hospitality. Their spending has rapidly increased, while lower-income households face debt pressures, indexing their spending more towards essential items. They are also directing a significant percentage of their discretionary spending towards where they see extreme value. The top 20% of Canada’s household comprise 67% of Canada’s net worth ( average net worth of $ 3.4 million), while the bottom 40% comprise only 2.8% of Canada’s net worth ( average net worth of $ 70,000).
In this report, we will examine the changes in the department store segment, the growth of fashion apparel, and the trends impacting luxury retail.
Where are the Department Stores?
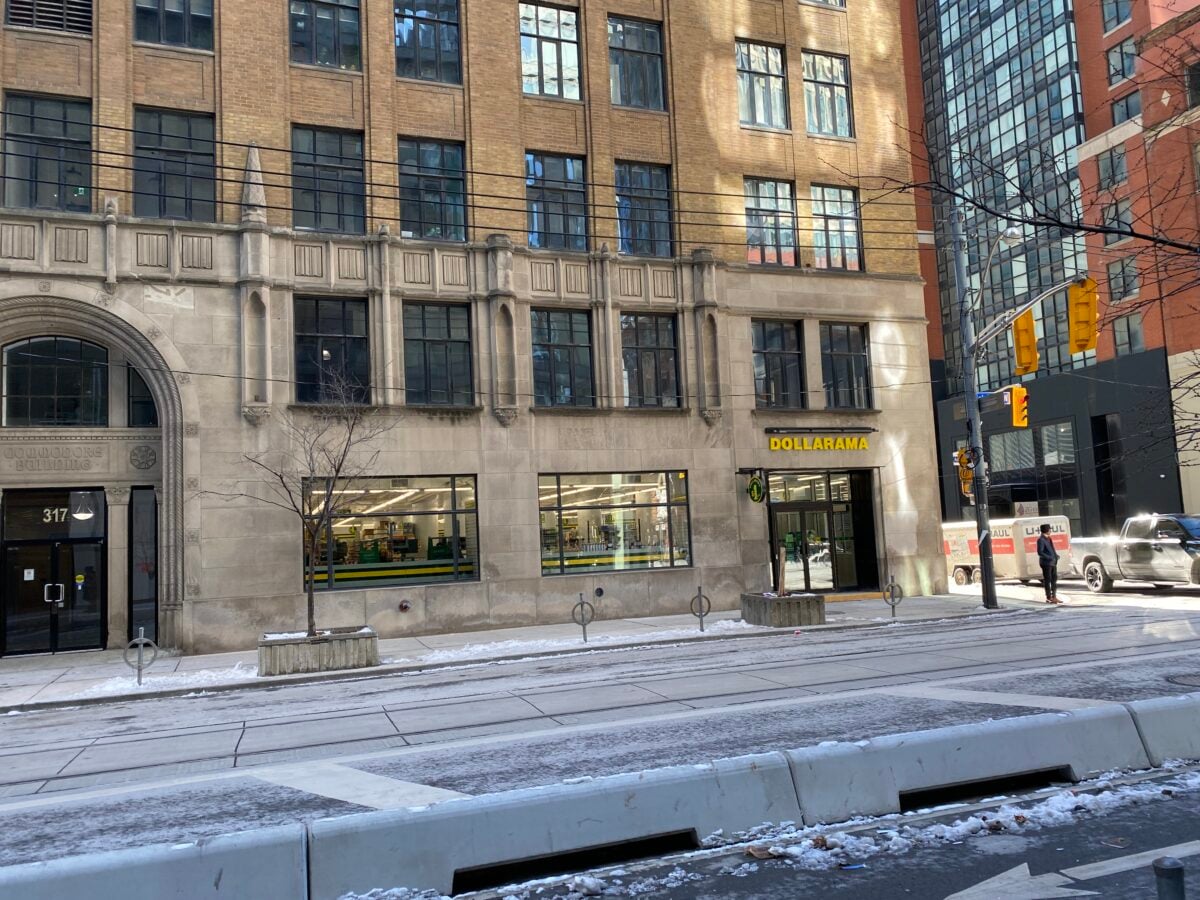
A lot has changed in the retail landscape over the past decade. In 2015, traditional department stores such as Sears Canada and Hudson’s Bay were still top-tier players, whereas by 2024, the department store category had largely been redefined by mass and junior department store discount giants (Walmart, Costco and Giant Tiger) and high-end players such as Holt Renfrew, Harry Rosen and the mono-brand luxury retailers.
The Power of Convenience and Experience
Walmart and Costco’s massive revenue gap over traditional stores highlights how “one-stop-shop” mass value retailers have effectively replaced the traditional mall department store for most households. In addition, department stores have lost their “merchandising magic.”
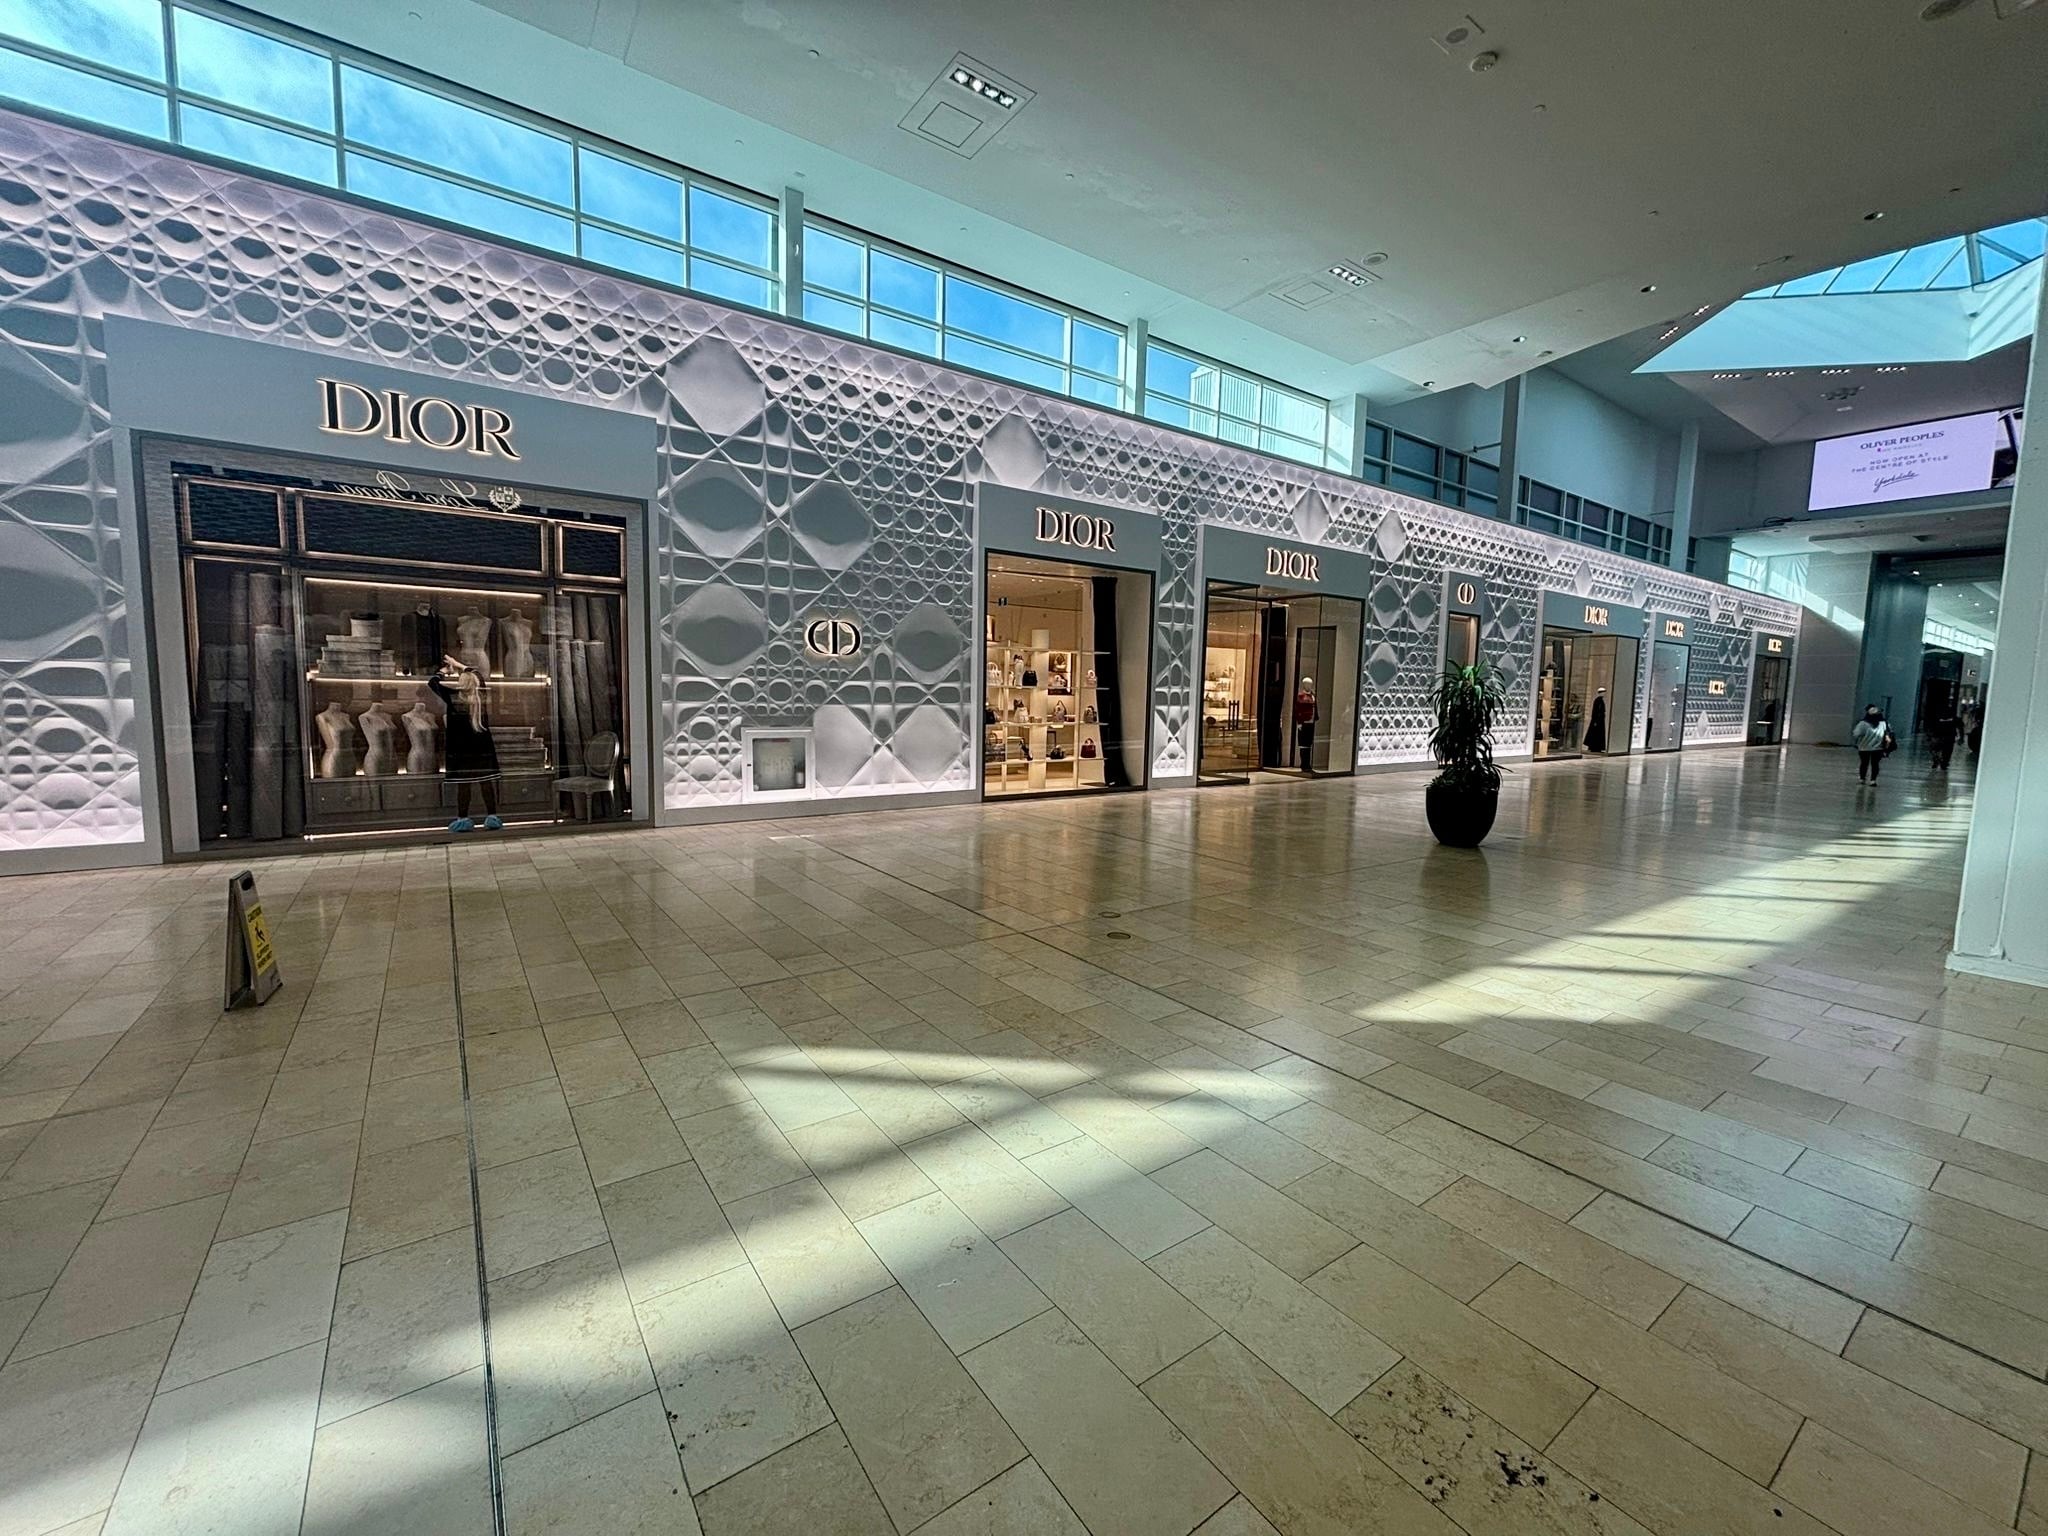
Discerning shoppers who are loyal to luxury brand Brunello Cucinelli, for example, are much more likely to forgo wading through a traditional department store in favour of experiencing the mono-brand designer’s own stores. When a discerning luxury shopper visits a luxury mono-brand’s own store, they also experience shopping at a dedicated luxury brand store (boutique) as it offers a superior, immersive experience, providing exclusive access to the full collection, highly trained staff, and intimate brand storytelling.
Customers also benefit from personalized one-to-one service, superior after-sales care, and a controlled, luxurious environment that creates a stronger emotional connection and prestige compared to the broader, often less specialized, selection at a department store.
Global Shifts in Fashion Apparel
The global apparel landscape has also undergone a seismic shift over the last decade. While the 2015 market was dominated by traditional athletic and casual brands, the 2025 market is defined by a massive surge in luxury mono-brand stores and the dominance of discount/value and fast fashion segments.
The total global apparel market has also seen significant growth despite the 2020 pandemic disruption. In 2015, analysts estimated total apparel sales were $1.3 trillion, which jumped to $1.84 trillion in 2025 — a stunning 41.5% increase. Driving those sales is the luxury apparel segment, along with the global growth of fast fashion brands such as H&M and Inditex.
Comparative Analysis: What is Driving Change?
The Rise of Uber-Luxury: In 2015, luxury was a niche segment. By 2025, LVMH and Dior reached the top of the revenue charts via double-digit growth rates even as they experienced slumps during the pandemic. Between 2015 and 2025, LVMH doubled its annual revenue. Richemont and Kering also saw similar growth. This is primarily driven by “premiumization,” where wealthy consumers spend more on status symbols, with the middle class occasionally trading up for accessories.
The Death of the Malls: In 2015 enclosed mall staples, such as Gap and Victoria’s Secret, dominated sales. By 2025, this dominance was largely replaced by the discounters and the mono-brand luxury brands.
Consumers are increasingly lured to off-price retailers because they are more value-conscious today and seek bargain prices on well-known fashion brands. This move from full-price department stores toward “treasure hunt” discount models has transformed the retail landscape — and continues to do so. Just look at the ongoing success and popularity of Wal-Mart, Costco and the discounters such as the TJX companies.
Sportswear Maturity: Nike and Adidas remain powerhouses, but their growth has slowed compared to the explosive luxury sector. Nike’s revenue nearly doubled in the decade, but it dropped from the top as luxury conglomerates consolidated their power.
Digital Native Disruption: A decade ago, the “Fast Fashion” crown belonged solely to Zara and H&M, who relied on physical stores. Today, Shein’s ultra-fast, data-driven, online-only model has allowed it to rival traditional giants in just a few years. Shein’s annual sales are about $38 billion. And then there’s the elephant in the room: Amazon.
The Online Apparel Giant
In 2015, Amazon was just beginning its aggressive push into the fashion apparel world. Today, it has transformed from a “basics” destination into the largest apparel retailer in the U.S., surpassing the legacy giants. Apparel sales have grown from $16.3 billion in 2015 to about $67 billion today — making it the number one apparel retailer in the U.S. with an estimated 13 percent market share.** It is estimated that Walmart’s apparel sales are about $30 billion.
The shift from 2015 to today represents more than just a numbers jump; it also reflects a total change in strategy from basics to brands. Ten years ago, consumers primarily used Amazon for socks, t-shirts, and commodity clothing. Today, Amazon hosts “Luxury Stores” with high-end designers and major brands such as Adidas, Levi’s, and Coach.
In 2016, Amazon launched dozens of its own brands (like Amazon Essentials and The Drop), which now consistently rank among the platform’s top sellers. There’s also the appealing “Try Before You Buy” factor. The introduction of this new Prime service (formerly Prime Wardrobe) essentially mitigated the “fit issue” that historically held back online clothing sales.
[Go deeper, check out Amazon’s luxury offering HERE.]
Global Luxury Market Value
In 2025, the luxury apparel market reached a pivotal state of “post-pandemic normalization.” While total revenue continues to climb, the industry is shifting from the explosive growth of the early 2020s toward a more fragmented landscape defined by “quiet luxury,” archival storytelling, and a stark divide between top-tier conglomerates and mid-market players.
The luxury clothing and apparel market is valued at approximately $275 billion in 2025, contributing to a broader personal luxury goods market (including accessories and watches) of over $464 billion.
Within luxury apparel, the women’s segment is identified as the leading consumer of luxury fashion due to higher spending on clothing, accessories, and cosmetics. Women’s luxury clothing represents roughly 60% to 65% of the apparel-specific market, driven by diverse product offerings. When considering all luxury goods (including bags, shoes, accessories, etc.), women’s products generally command over 50% of the market share.
Other changes impacting the luxury segment include the rise of the Generation Z shopper. In the U.S., this demographic cohort holds about $360 billion in disposable income. Gen Z accounts for about 20% of global personal luxury goods spending, and the generation is projected to drive 40% of all fashion spending by 2030 to 2035. Then there’s the resale boom. The second-hand luxury market is valued at $41.6 billion in 2025. Nearly 60% of U.S. and European consumers now use resale platforms such as Vestiaire Collective or The RealReal to source archival or “investment” pieces.
The Road Ahead
So, where does the retail market go from here? I expect the bifurcation only to grow wider due to several factors, but particularly as jobs are starting to disappear. In 2025, the Canadian unemployment rate increased to 6.6% from 6.3% in 2024. I expect that this rate will continue to increase due to a combination of AI implementations and company layoffs due to the continued uncertainty caused by the tariff wars with the US.
And it is having an impact. LVMH Moët Hennessy Louis Vuitton reported full-year 2025 results on Jan. 27, showing a slight decline in annual revenue as the luxury giant navigated a volatile economic environment. However, it saw a minor recovery in the second half of the year.
Despite these small hiccups, long-term, the luxury market is poised to continue on a strong growth trajectory. Analysts at Fortune Business Insights see the luxury sector experiencing a robust CAGR of 5.74% through 2032, with fashion apparel leading the way. The golden age of luxury apparel continues.
***
Sources: Statistics Canada,Statista Global Consumer Market Outlook, FashionUnited Top 200, Brand Finance Apparel 50 (2025), Statista Global Consumer Market Outlook (Apparel), the FashionUnited Top 200 Index, Fortune Business Insights, UniformMarket Industry Statistics (2025), Company Annual Reports (Form 10-K).
**Note: Amazon does not officially break out apparel as a specific line item in its quarterly earnings reports. These figures are based on consistent annual analysis and Gross Merchandise Volume (GMV) estimates from firms like Wells Fargo and Cowen & Co.