Canadian pet owners appear reluctant to reduce spending on their animals, even as higher living costs continue to shape household decisions.
A new national study found that 80 per cent of surveyed cat and dog owners expect to maintain or increase their pet spending over the next 12 months. Thirty-two per cent anticipate spending more, while 48 per cent expect their budgets to remain stable. Only 12 per cent expect to spend less.
Pet-related purchases appear to have become a protected expense for many households. When respondents were asked what they would cut first if finances became tighter, 51 per cent selected dining out or takeout. Clothing and fashion followed at 38 per cent, personal grooming and self-care at 30 per cent, and coffee or tea-shop purchases at 22 per cent. Travel, streaming services and fitness spending also ranked ahead of pet expenses as potential areas for reduction.
The findings come from the 2026 Canadian Pet Shopping Report, conducted by consumer data platform Caddle in collaboration with Pet Valu. Approximately 10,000 Canadian adults participated in the May 2026 research, with the main analysis based on 2,184 cat and dog owners responsible for household purchasing. The results were weighted to represent the Canadian population.
The report presents a resilient consumer category, though the spending within it remains highly contested. Canadians may be protecting their pet budgets, but they are comparing value, shopping across several channels and expecting retailers to provide greater convenience.
Pet Budgets Are Protected, but Value Still Leads
Food, treats and litter represent a meaningful monthly expense for many owners.
The most common spending range was between $50 and $99 per month, reported by 32 per cent of respondents. Another 29 per cent spend between $100 and $199, while eight per cent spend at least $200. In total, 36 per cent spend $100 or more each month on those three categories alone.
Those figures exclude veterinary care, grooming, insurance, toys and other services and merchandise.
Price and value ranked among the three most important food-purchasing considerations for 51 per cent of respondents. Veterinary recommendations followed at 40 per cent, while 36 per cent identified functional health benefits such as digestive or joint support.
Brand reputation was selected by 28 per cent, natural or organic ingredients by 25 per cent and Canadian or locally sourced products by 20 per cent.
The findings show owners balancing affordability with nutritional needs, professional guidance and product quality. Some are managing that balance by combining products from different price tiers.
Among respondents who mix pet-food types or brands, 31 per cent said they do so to meet different needs. Another 29 per cent combine premium and budget products to save money, while others cited picky eating, nutritional variety or veterinary recommendations.
Pet Valu’s recent performance provides useful context. The company reported flat same-store sales in the first quarter of 2026, with a 0.6 per cent increase in average spending per transaction offset by a 0.6 per cent decline in transactions. Management said the quarter was shaped by heightened value-seeking behaviour among consumers.
The results show how owners can preserve their overall pet budgets while becoming more selective about individual purchases, promotions and retail channels.
Specialty Retail Leads an Omnichannel Market
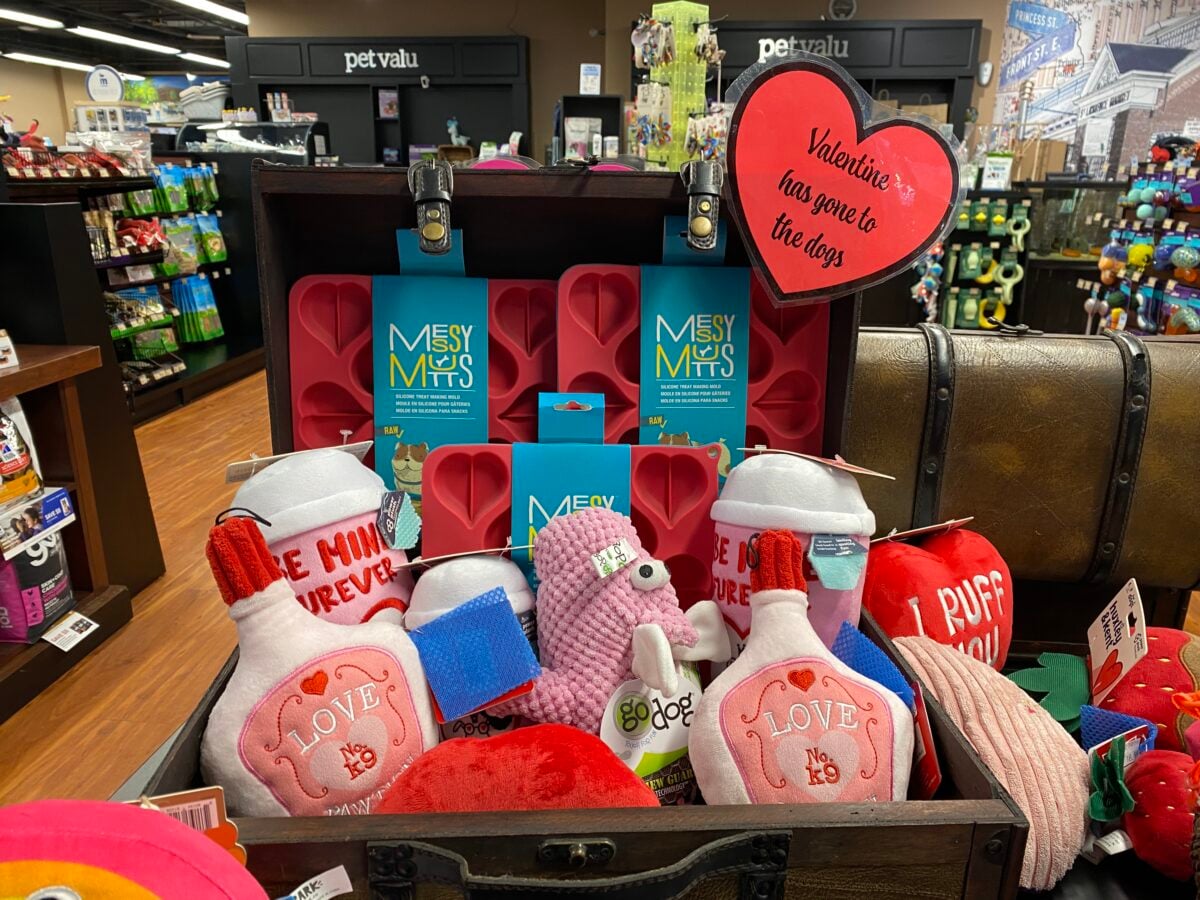
Specialty retailers remain the most common primary destination for pet food and treats.
Thirty-nine per cent of respondents said they shop most often at a pet specialty store. Big-box retailers followed at 29 per cent, grocery stores at 18 per cent, online retailers at nine per cent and veterinary clinics at three per cent.
The broader channel data shows that many consumers do not confine their spending to one format. Forty-one per cent sometimes use specialty stores beyond their primary shopping destination, while 38 per cent sometimes use big-box retailers. Grocery stores serve as a secondary channel for 30 per cent, and 28 per cent sometimes purchase online.
Nearly one-third of respondents, at 31 per cent, tried a new channel for food or treats during the previous year.
That movement gives retailers opportunities to win incremental purchases, but it also means a customer’s preferred store may capture only part of the household’s total pet spending.
Among respondents whose main channel is a specialty store, 43 per cent said they shop most often at the combined group of Pet Valu, Mondou or Global Pet Foods. PetSmart accounted for 31 per cent, while 26 per cent selected another specialty retailer. The 43 per cent figure covers three separate retail groups and should not be interpreted as Pet Valu’s individual market share.
Pet Valu ended its first quarter with 870 stores after opening eight locations during the period. System-wide sales increased 2.5 per cent to $375.2 million, while revenue rose 3.2 per cent to $287.9 million.
The company generated $1.53 billion in system-wide sales during fiscal 2025, an increase of 5.6 per cent. Same-store sales rose 1.6 per cent, and the network ended the year with 863 stores. Pet Valu entered 2026 planning approximately 40 additional openings.
Online Ordering Becomes Part of the Routine
Online purchasing extends well beyond the nine per cent who identify digital retailers as their primary channel.
For pet food, 17 per cent of respondents said they buy online always or almost always, while 27 per cent do so often, defined in the report as monthly or more. Another 33 per cent purchase online sometimes.
For treats, 13 per cent buy online always or almost always, 24 per cent do so often and 34 per cent shop online sometimes.
The report summarizes the findings by noting that 44 per cent buy pet food online at least often, while 37 per cent do the same for treats.
Digital ordering is therefore becoming part of a wider shopping routine. A customer might visit a specialty store for product discovery or advice, order routine items online and use a grocery or mass merchant for fill-in purchases.
That pattern makes home delivery, click-and-collect and recurring orders increasingly important for retailers operating physical store networks.
Auto-Ship Becomes a Customer-Retention Tool
The report’s findings on auto-ship provide one of its clearest signals for the retail industry.
Forty-one per cent of respondents currently use a subscription or auto-ship service, including 19 per cent who use one regularly and 22 per cent who do so occasionally. Another 18 per cent are interested or have considered subscribing.
For 55 per cent of owners, having auto-ship available is important when choosing where to shop. Twenty-three per cent described the service as very important and a key reason they use their preferred retailer, while 32 per cent called it somewhat important.
The consequences of removing the service could be significant. If their preferred retailer did not offer auto-ship, 30 per cent said they would switch to another retailer that does. A further 15 per cent would move to an online subscription provider. Combined, 45 per cent could take their business elsewhere.
Forty-eight per cent would continue shopping in-store without a subscription, while seven per cent were uncertain.
Auto-ship can help retailers secure recurring purchases and reduce the chance that routine replenishment orders migrate to a competitor. It also gives store-based operators a way to participate in subscription shopping while maintaining a broader relationship with the customer.
Competitive pricing may win a transaction. Reliable recurring delivery can help determine who keeps the customer.
Availability and Ingredients Can Prompt Brand Switching
Pet owners also appear willing to reconsider brands when products become difficult to find or a perceived improvement enters the market.
Twenty per cent said they never or rarely switch food brands or types, while 39 per cent change only when needed, such as when a health issue arises. Twenty-nine per cent switch every few months, and 12 per cent do so monthly or more.
When asked what would be most likely to persuade them to switch, 53 per cent selected better availability. Better ingredients ranked second at 32 per cent, while 15 per cent selected a better price. Overall, 68 per cent said they would be likely to switch if a better option became available or its ingredients improved.
The results do not diminish the role of price, which remains the leading consideration when consumers choose food. They show that reliability and product composition can become decisive once a customer has established a purchasing routine.
For retailers, repeated out-of-stocks may place both the immediate sale and the wider customer relationship at risk. A shopper unable to find a preferred formula may discover a replacement brand, another store or a recurring online option.
Health, Values and Professional Advice Shape Decisions
Feeding habits are varied, giving retailers room to serve several product formats and price points within the same household.
Forty-three per cent of respondents combine dry and wet food. Thirty-eight per cent use dry kibble only, while 10 per cent use wet or canned food and nine per cent primarily use raw or freeze-dried products.
Sixty-three per cent mix food types or brands at least sometimes.
Ethical and environmental considerations also form part of the purchase decision. Cruelty-free products or the absence of animal testing were selected by 43 per cent, followed by organic or natural ingredients at 39 per cent and local or Canadian sourcing at 31 per cent. Environmental impact was selected by 28 per cent, while 20 per cent identified recyclable or environmentally friendly packaging.
Veterinarians remain the most trusted source of pet-related advice, selected by 62 per cent of respondents. Online reviews and ratings followed at 11 per cent, friends and family at 10 per cent, other sources at nine per cent and pet-store staff at seven per cent.
The results give health claims, ingredient transparency and professional credibility considerable importance for brands and retailers, particularly in premium and functional food categories.
AI Enters the Pet-Product Discovery Process
Artificial intelligence is beginning to influence how some owners research their pets’ needs.
Thirty-two per cent of respondents have used an AI tool for a pet-related question, although only six per cent said they do so often. Twelve per cent use AI sometimes and 14 per cent rarely, while 68 per cent have never used it for this purpose.
Among those who have used AI, 48 per cent asked about diet or nutrition, 42 per cent sought information about symptoms or health concerns, 36 per cent requested product suggestions and 23 per cent asked about behaviour or training.
Most users continue to check the information elsewhere. Sixty-nine per cent said they always or usually verify AI-generated advice with a veterinarian or another source.
For retailers and product companies, the product-suggestion figure may be the most relevant. AI tools could become another point of discovery alongside search engines, retailer websites, online reviews, veterinarians and store associates.
Category Loyalty Is Stronger Than Retailer Loyalty
The spending resilience reflected in the report is supported by the place pets occupy in Canadian homes.
The study estimates that 52 per cent of Canadians own a cat or dog. Eighty-seven per cent of owners agree that their pet is a full member of the family, including 58 per cent who strongly agree.
Twenty-one per cent plan to add a pet during the next year. Among current owners asked what they would do following the loss of a pet, 75 per cent said they would eventually get another one.
Those relationships help explain why pet spending can remain resilient while other discretionary categories face pressure.
Retailers should not assume that loyalty to the category translates into loyalty to one banner, channel or brand. The report describes customers who are attentive to price, prepared to mix products, comfortable shopping across several formats and willing to change providers when availability or convenience falls short.
Canadian consumers may be reluctant to reduce what they spend on their pets. They appear far more willing to reconsider where they spend it.