DAVIDsTEA is looking at further store expansion in Canada in 2027 as improving sales at existing locations provide fresh support for the specialty retailer’s return to physical retail.
The Montreal-based company is still developing its plans for next year, but Chief Executive Officer and Chief Brand Officer Sarah Segal said an initial assessment points to a pace of expansion similar to 2026. The disclosure comes as DAVIDsTEA works toward a network of 25 stores across Canada by the end of this year.
The timing is notable. Brick-and-mortar sales increased 9.6 per cent to $5.0 million in the second quarter ended August 1, while comparable-store sales rose 4.4 per cent. That follows a 3.1 per cent comparable-store decline in the first quarter, marking a sharp improvement over a relatively short period.
The comparable-store figure is particularly relevant as DAVIDsTEA expands because it indicates that the improvement is not being driven solely by revenue from newly opened locations.
More Canadian Stores Under Consideration
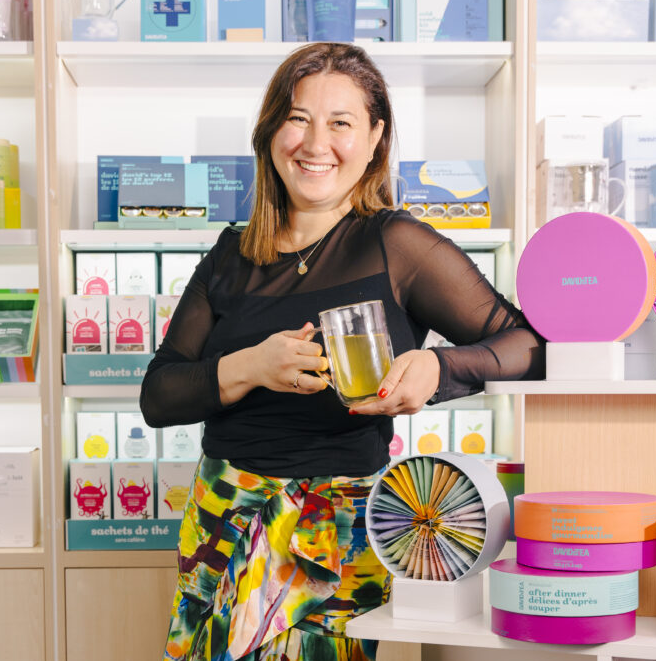
DAVIDsTEA has been gradually rebuilding a physical retail network that was dramatically reduced during its restructuring several years ago. The company believes there remains considerable room to grow.
“We see significant white space in Canada,” Segal told investors during the company’s second-quarter earnings call. The pace will depend on market conditions and DAVIDsTEA’s ability to fund additional growth.
The company estimates an investment of approximately $450,000 for each new location, with an expected payback period of 15 to 18 months. Those economics help explain why stores have again become an important part of DAVIDsTEA’s growth strategy after several years in which e-commerce and wholesale played a much larger role.
DAVIDsTEA has not disclosed how many stores it could open in 2027 or identified potential locations. The preliminary assessment nevertheless indicates that the current expansion program could extend beyond this year.
DAVIDsTEA Returns to Major Canadian Malls
The current program has increasingly taken DAVIDsTEA back into major shopping centres where the retailer previously operated.
A store at Laurier Québec in Quebec City opened in December 2025, followed by the company’s return to Oshawa Centre in June. DAVIDsTEA opened at Square One Shopping Centre in Mississauga in August, shortly after the second quarter ended.
Stores at Southgate Centre in Edmonton and Metropolis at Metrotown in Burnaby are expected to open this fall. The additions would bring DAVIDsTEA to 25 stores by year-end, while the company has described early performance at Oshawa and Square One as strong.
The network remains a fraction of its former size. DAVIDsTEA once operated more than 200 stores before dramatically reducing its footprint during restructuring in 2020. It subsequently put greater emphasis on digital and wholesale sales before beginning a measured return to physical growth.
This time, the expansion has been selective, with the company focused on individual store economics and locations where a physical presence could also strengthen the broader business.
Existing Stores Show Stronger Performance
The second-quarter numbers provide some of the clearest evidence so far that DAVIDsTEA’s physical retail business is improving.
Stores accounted for 43.5 per cent of sales during the quarter, up from 41.0 per cent a year earlier. Comparable-store sales increased 4.4 per cent, compared with growth of just 0.6 per cent during the same quarter last year.
The sequential change is more pronounced. Comparable-store sales fell 3.1 per cent in the first quarter before returning to growth in Q2. There are reasons, however, to keep the improvement in perspective: comparable-store sales for the first six months remained slightly negative, while total first-half revenue was $24.5 million compared with $24.9 million a year earlier.
Q2 therefore marks a stronger quarter for the retailer, but the improvement will need to continue before it translates into sustained growth for the year.
Margins Improve Alongside Sales
Overall second-quarter revenue increased 3.3 per cent to $11.5 million from $11.1 million a year earlier. Gross profit rose at a faster pace, increasing 9.0 per cent to $7.1 million.
Gross margin reached a company record of 61.9 per cent, up 320 basis points from 58.7 per cent a year earlier. DAVIDsTEA attributed the improvement primarily to lower freight and inbound shipping costs and benefits from internalized fulfillment.
Operating results also strengthened. EBITDA moved to approximately $200,000 from a loss of approximately $200,000 a year earlier, while adjusted EBITDA improved to approximately $500,000 from a loss of approximately $200,000.
DAVIDsTEA remained in the red on a net-income basis, with its quarterly loss narrowing to $1.2 million from $1.6 million. The combination of stronger store sales and improved margins provides a better operating backdrop for additional investment in stores, although bottom-line profitability remains uneven.
Physical Retail Outpaces Other Channels
The strongest growth during the quarter came from DAVIDsTEA’s stores. Online sales increased 1.1 per cent to $5.2 million, while wholesale revenue declined 8.8 per cent to $1.3 million. DAVIDsTEA attributed the wholesale decline primarily to the timing of replenishment orders among grocery and convenience partners.
The company has argued that a larger store network can generate benefits beyond transactions inside individual locations. Stores increase visibility in a market and can potentially support subsequent online and wholesale purchases.
The latest results do not yet provide enough evidence to quantify that broader effect. Online growth was modest and wholesale declined even as physical-store sales increased 9.6 per cent. For now, the clearer takeaway from Q2 is that the stores themselves are performing better.
Canada Drives Growth as U.S. Sales Decline
Canadian sales increased 5.5 per cent to $10.5 million during the quarter and represented 91.5 per cent of total revenue. U.S. sales declined 15.2 per cent to approximately $1.0 million, with DAVIDsTEA pointing to trade tensions and tariff-related pressure on cross-border e-commerce.
DAVIDsTEA transitioned U.S. order fulfillment to a third-party logistics operation in Chicago in late March. The company expects the U.S.-based operation to reduce cross-border friction and support sales as the year progresses.
For now, the improving performance is being driven predominantly by Canada, where physical stores are becoming a larger part of the business.
Funding Further Store Growth
Another year of openings would require DAVIDsTEA to continue committing capital to physical growth. The company ended the quarter with $10.2 million in cash, down from $16.5 million at fiscal year-end. DAVIDsTEA attributed much of the decline to its normal seasonal working-capital cycle as inventory is built ahead of the important holiday period.
The year-over-year comparison is stronger, with cash $2.6 million higher than at the same point last year and working capital up $5.7 million to $17.1 million. DAVIDsTEA also repaid the outstanding balance on its revenue-linked financing during the quarter.
With a typical new store requiring approximately $450,000 of investment, the pace and scale of a potential 2027 program will partly depend on how much capital DAVIDsTEA is prepared to commit to further expansion.
Holiday Season Provides the Next Test
DAVIDsTEA is heading toward its most important selling period with a larger physical network. Southgate Centre and Metropolis at Metrotown are expected to open this fall, putting the latest additions into operation ahead of the holiday period.
The company has also completed the consolidation of its Montreal footprint, with the full run-rate benefit expected to begin in the third quarter.
The coming quarters should provide a clearer indication of whether the improvement seen in Q2 can be sustained. First-half revenue remains slightly below last year, wholesale declined in the latest quarter and U.S. sales remain under pressure.
Physical retail has moved in the opposite direction, with comparable-store sales returning to growth and brick-and-mortar revenue increasing faster than the company overall. The 2027 plans remain preliminary, but the fact that another year of openings is already under consideration suggests DAVIDsTEA’s return to Canadian shopping centres could become a longer-term rebuilding of its physical retail network.