Crombie Real Estate Investment Trust reported higher funds from operations per unit and stronger rental rates in the third quarter of 2026, while announcing plans to acquire 13 retail properties in Ontario for $134 million.
The Nova Scotia-based REIT said funds from operations (FFO) increased 3 per cent to 34 cents per unit for the three months ended Sept. 30, compared with 33 cents a year earlier. Committed occupancy reached 97.7 per cent, matching the company’s previous record, while commercial same-asset property cash net operating income increased 2.7 per cent.
The company also reported renewal rental rates 13.9 per cent above expiring rates and said it entered into a binding agreement in October to acquire a portfolio of necessity-based retail properties totalling approximately 588,000 square feet. The $134-million transaction, excluding closing and transaction costs, is expected to close in November.
Rental growth and occupancy support results
“Crombie’s third quarter results demonstrate what a portfolio built with purpose is designed to deliver: steady, dependable growth,” said Mark Holly, President and CEO.
“Renewal growth of 13.9% over expiring rental rates was our strongest in more than five years, and committed occupancy matched our record at 97.7%. Commercial same-asset property cash NOI grew 2.7%, and FFO per Unit grew 3.0%. Subsequent to quarter end, we entered into a binding agreement to acquire a portfolio of 13 necessity-based retail properties in Ontario for $134 million, excluding closing and transaction costs. Our focus is unchanged: growing cash flow while compounding long-term value for our Unitholders.”
Property revenue increased 6.2 per cent to $127.6 million from $120.1 million in the third quarter of 2025. Net property income rose 7.2 per cent to $85.2 million, while commercial same-asset property cash NOI reached $86.5 million, up from $84.3 million a year earlier.
Operating income attributable to unitholders declined 8.7 per cent to $28.3 million. Crombie attributed the decrease primarily to investment property impairments, higher interest expenses associated with senior unsecured note issuances and lower development management fees. Revenue growth from acquisitions, new leasing and renewals partly offset those factors.
Adjusted funds from operations (AFFO) remained unchanged at 30 cents per unit compared with the same period last year.
During the quarter, Crombie completed 107,000 square feet of retail renewals at rental rates 13.9 per cent above expiring rates. The weighted average rental rate over the renewal terms represented an increase of 16.7 per cent.
New commercial leases added 121,000 square feet of occupied space at an average first-year rental rate of $28.44 per square foot.
Ontario acquisition expands portfolio
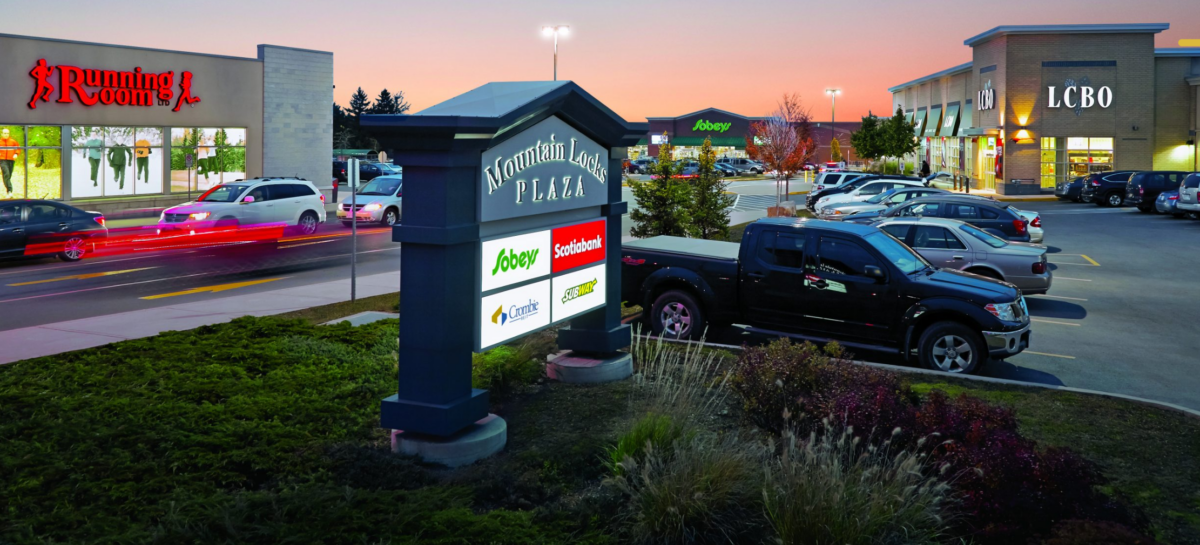
The acquisition agreement, signed Oct. 13, covers 13 Ontario retail properties with a combined area of approximately 588,000 square feet. Crombie plans to finance the purchase through its existing unsecured revolving credit facility.
The REIT also reported a subsequent disposition on Oct. 29 involving a 271,000-square-foot retail property in regional markets. The transaction generated gross proceeds of $5.45 million, before closing and transaction costs, including $2.7 million in vendor take-back financing over three years. Crombie retained the property’s grocery component through a long-term lease.
At Sept. 30, Crombie’s portfolio included 301 investment properties with approximately 18.7 million square feet of gross leasable area, excluding joint ventures and certain residential properties. Including joint ventures and residential assets, the portfolio comprised 311 properties and approximately 19.4 million square feet.
During the quarter, the company also issued $300 million in Series N senior unsecured notes carrying an annual interest rate of 4.518 per cent and acquired two land parcels totalling 10.8 acres in Windsor, N.S., for approximately $4.4 million.
More from Retail Insider: