Home Blog Page 10

Iconic Colombian coffee brand Juan Valdez expands to Canada

Juan Valdez photo
Juan Valdez photo

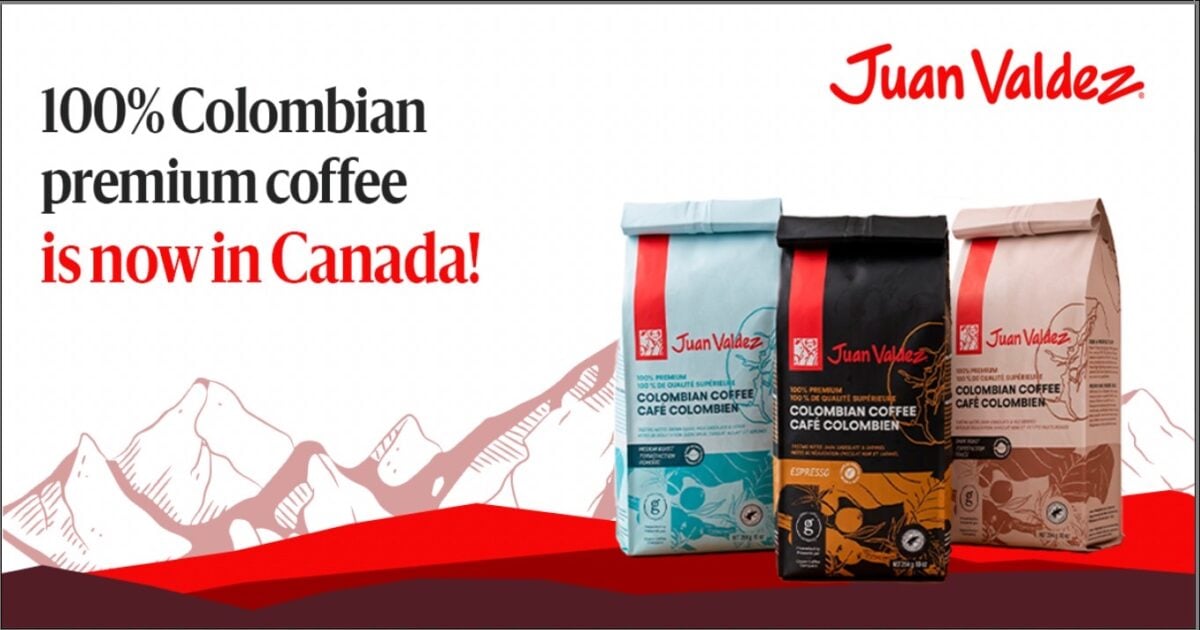
The name Juan Valdez is known throughout the world and now the Colombian coffee brand is marking a new chapter in its global expansion with a presence in Canada.

Now, Canadian consumers can find a selection of the brand’s ground and whole-bean coffees at retail locations across the country.

The company said the brand is entering the Canadian market through the retail channel, with a national presence at Maxi and No Frills (Loblaw Companies), Adonis (Metro) and independent grocers, as well as Amazon.ca and participating retailers’ e-commerce platforms. 

Through this rollout, Juan Valdez said it is initially reaching more than 400 points of sale and will continue expanding its presence across the country alongside new retail partners.

“Canada is a market we are very excited to grow in, starting with what defines us: our origin. We are bringing a proposition centered on the quality, identity and richness of Colombian coffee, while sharing that story with new consumers. Our ambition goes beyond entering the retail market; we want to build a strong presence, grow alongside the Canadian market and make Juan Valdez a familiar choice for people who appreciate and value great coffee,” said Sebastián Mejía, General Manager, North America.

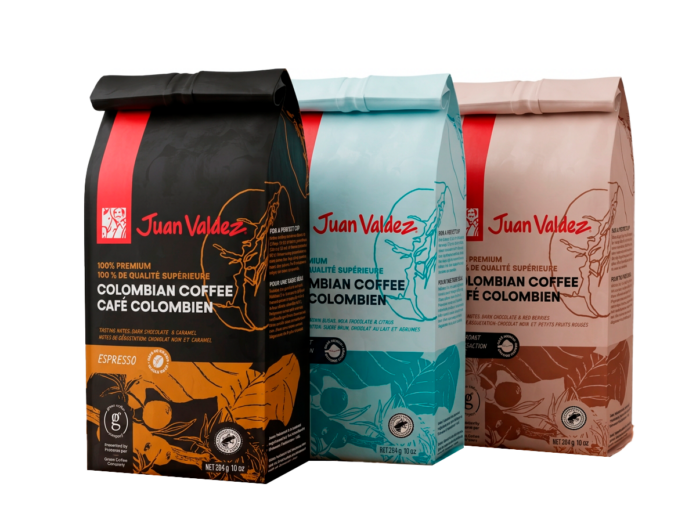
During the initial launch, the company said consumers will be able to choose from Medium Roast Ground Coffee, Dark Roast Ground Coffee and Espresso Whole Bean Coffee, all made with 100% Colombian Arabica coffee sourced directly from coffee farms and traceable throughout the supply chain. The portfolio will later expand to include single-serve coffee pods in Medium and Dark Roast.

Juan Valdez began in 2002, when the National Federation of Coffee Growers of Colombia created the brand as an initiative to generate greater value around Colombian coffee and bring it to consumers in markets around the world. Since then, it has built an international presence rooted in the origin, quality and coffee heritage of Colombia.

Juan Valdez photo
Juan Valdez photo

Today, the brand represents more than 550,000 Colombian coffee-growing families and is present across five continents.

More from Retail Insider:

Daily Synopsis: September 30, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.

Canada’s retail market is increasingly divided between value-driven and premium-focused consumers, placing growing pressure on middle-market retailers to define a clear and compelling proposition. Quartz Co. is expanding its Canadian retail presence with a second permanent boutique in Montréal and exploring entry into the Toronto market, leveraging its growing direct-to-consumer strategy and a broader product range beyond heavyweight parkas.

The rise of AI-powered shopping agents introduces new fraud risks and trust issues in retail commerce, requiring advanced fraud prevention strategies. Salesforce is advancing AI in retail by integrating agentic commerce deeper into checkout, inventory, and customer data systems, enabling AI agents to assist shoppers throughout the purchase process both online and in physical stores.

A breaking news story later on Wednesday included Primaris’ acquisition of Upper Canada Mall in Newmarket, ON, from Oxford Properties.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

Primaris REIT Announces $411 Million Acquisition of Upper Canada Mall

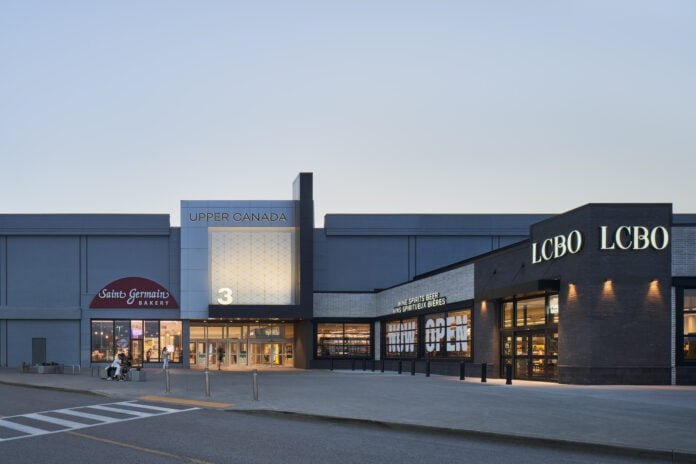
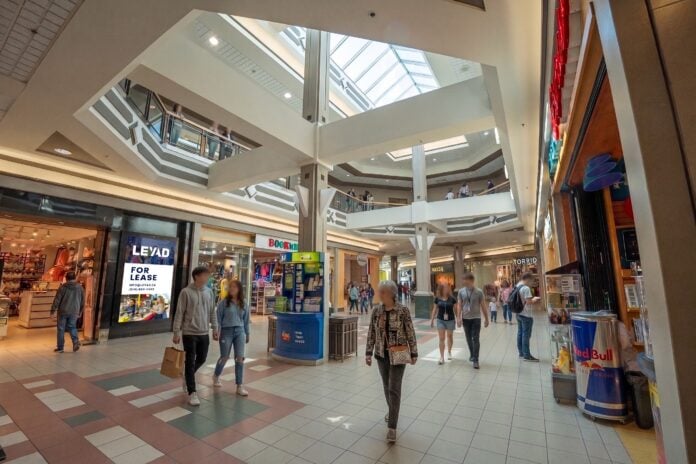
Photo courtesy of Upper Canada Mall

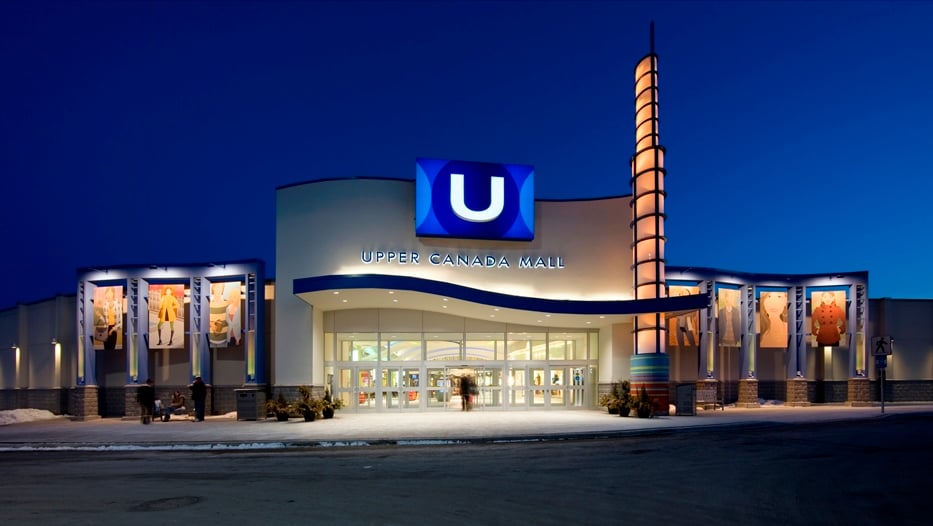
Primaris Real Estate Investment Trust announced Wednesday that it has agreed to acquire a 100% interest in Upper Canada Mall in Newmarket, Ontario for $411 million, to be satisfied in cash. The REIT said the acquisition further advances Primaris’ strategy of acquiring market-leading enclosed shopping centres in growing Canadian markets, where the REIT can deploy its full-service operating platform to drive income growth and long-term per unit value creation.

Highlights

  • The acquisition is expected to be modestly accretive to annualized fully diluted FFO per unit;
  • 990,114 square foot mall located on 76 acres of land in the Greater Toronto Area;
  • $888 per square foot same store sales productivity and total annual CRU sales volume of $271 million;
  • Attractive tenant profile including Apple, Aritzia, Browns, Lululemon, Sport Chek, Uniqlo, Winners, and more;
  • Significant upside available from lease-up of vacant space and monetization of excess land; and
  • The acquisition is expected to close by October 31, subject to the satisfaction of customary closing conditions, including any required regulatory approvals.

Primaris is Canada’s only enclosed shopping centre focused REIT, with ownership interests in leading enclosed shopping centres located in growing Canadian markets. The proforma portfolio totals 15.6 million square feet, valued at approximately $5.6 billion at Primaris’ share.

Upper Canada Mall is co-owned by Oxford Properties and CPPIB and managed by Oxford Properties Group.

Upper Canada Mall photo

“Upper Canada Mall is a dominant GTA shopping centre with strong demographics, an exceptional tenant mix and significant embedded growth potential,” said Patrick Sullivan, President and Chief Operating Officer. “We see meaningful opportunities to grow NOI through leasing, active asset management and operational efficiencies. Our platform and operating expertise position us well to unlock that potential over the coming years.”

“Interest in enclosed shopping centres is growing, and Upper Canada Mall was the subject of a broadly marketed process,” said Julian Schonfeldt, Chief Investment Officer. “Our reputation as a well-capitalized, reliable buyer with a proven operating platform continues to position Primaris as a preferred counterparty for vendors. This acquisition reflects our disciplined approach: a productive, high-quality centre in the GTA, that is modestly accretive, with additional upside from lease-up and excess land.”

“Upper Canada Mall is exactly the type of asset Primaris is built to own,” said Alex Avery, Chief Executive Officer. “The acquisition adds a high quality GTA shopping centre to our portfolio and further strengthens the quality, scale and growth profile of Primaris. Driving our proforma same store sales productivity to $829, this acquisition is another important step in building Canada’s leading portfolio of market dominant enclosed shopping centres.”

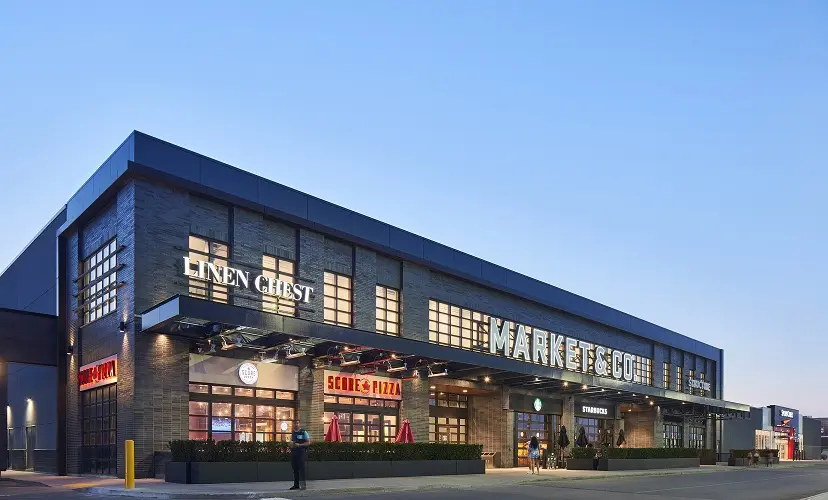
Photo courtesy of Upper Canada Mall

Upper Canada Mall Property Highlights

  • Leading regional enclosed shopping centre located in Newmarket, Ontario, a suburb of the GTA;
  • Strategically located at the intersection of Yonge Street and Davis Drive, with convenient access to Highways 400 and 404;
  • Bus Rapid Transit terminal located adjacent to the south entrance, with the Newmarket GO Station approximately 1.8 kilometres away;
  • 990,114 square foot mall located on 76 acres of land, with approximately 23% site coverage;
  • $888 per square foot same store sales productivity and total annual CRU sales volume of $271 million;
  • 65% long-term in-place occupancy, 70% in-place occupancy, and approximately 80% committed occupancy (excluding the vacant HBC space, in-place occupancy is 82%);
  • Weighted average lease term of 4.2 years;
  • Significant investment in the property, including an expansion completed in 2008 that added 148,000 square feet of retail space and a new food court, the opening of Market & Co. in 2018, and a new Yonge Street entrance completed in 2025;
  • BOMA BEST Platinum certified;
  • Large-format tenants include Winners, Sport Chek, Aritzia, Uniqlo and Zara; and
  • Notable CRU tenants include Apple, Sephora, Lululemon, Victoria’s Secret, and Browns.

Primaris said Upper Canada Mall will become Primaris’ 4th largest shopping centre measured by total CRU sales volume.

It said the property offers growth potential over the next few years, as operating and financial performance normalizes, and as Primaris’ full-service management platform integrates and operates the property.

It said opportunities to increase Net Operating Income include:

  • Redemise and lease approximately 263,400 square feet of former anchor and large format space to strong covenant, high-quality national retailers;
    • 142,800 square feet of former Hudson’s Bay is under negotiation;
    • 47,600 square feet of former Toys R Us is under negotiation;
    • 73,000 square feet former Sears spaced is committed to two national retailers;
  • 33,800 square feet of vacant CRU space to strong tenants at market rents;
  • Identified over 6 acres of excess land available for potential retail pad development or monetization; and
  • Leverage Primaris’ platform to deploy its cost management strategy.

Recently, Primaris said it is raising approximately $200 million in new equity as it evaluates another major round of shopping centre acquisitions, with the REIT disclosing that it is in various stages of negotiations involving more than $1 billion in potential purchases. The Toronto-based REIT announced September 14 that a syndicate of underwriters led by TD Securities, Desjardins Capital Markets and RBC Capital Markets will purchase 9.91 million Primaris units on a bought-deal basis at $20.20 per unit. An over-allotment option could increase gross proceeds to approximately $230 million.

More from Retail Insider:

Mental Resilience in Retail—Without the Toxic Positivity

Retail employees are regularly asked to remain calm, helpful and commercially focused while managing demanding customers, fluctuating schedules, staffing shortages and busy trading periods. Resilience is therefore a valuable workplace capability—but it should never become a convenient way to tell employees to tolerate unreasonable pressure.

Phrases such as “stay positive” or “push through it” can sound encouraging. When they are used to close down honest conversations about fatigue, grief, anxiety or workplace conditions, however, they become counterproductive.

A more useful definition of resilience includes adapting to difficulty, drawing on support, recovering at a realistic pace and changing conditions that are no longer sustainable. This guide to building mental resilience and coping with stress effectively offers a broader health and wellbeing perspective.

Retail resilience is not constant toughness

Retail has always required emotional skill. Employees may need to respond professionally to complaints, manage queues, solve unexpected problems and maintain a welcoming environment even when a store is under pressure.

That does not mean resilient employees are unaffected by difficult experiences. Someone can be capable, reliable and committed while also feeling overwhelmed.

Retail Insider has previously examined why emotional resilience is becoming an important retail skill. Crucially, that resilience should involve processing stress rather than suppressing it.

In practice, resilience may mean:

  • Asking a colleague or manager for assistance
  • Taking an appropriate break after a difficult interaction
  • Acknowledging that a workload has become unmanageable
  • Using available mental-health support
  • Requesting clearer priorities
  • Changing a coping strategy that is no longer helping
  • Recovering gradually instead of pretending everything is fine

An employee who raises a concern is not necessarily lacking resilience. They may be identifying an operational risk before it develops into absence, conflict, poor service or resignation.

What toxic positivity looks like at work

Toxic positivity is not ordinary optimism. A positive and solution-focused workplace can help teams navigate uncertainty. The problem arises when positivity is treated as the only acceptable response.

In retail, this may sound like:

  • “At least you still have a job.”
  • “Everyone is under pressure.”
  • “Leave personal problems at the door.”
  • “We just need better energy on the floor.”
  • “Other stores are coping.”
  • “Try not to take customers so personally.”

Comments like these can discourage employees from explaining what is actually happening. They may also shift attention away from understaffing, poor scheduling, inadequate security or insufficient manager support.

A better managerial response begins with listening: “What is making this difficult, and what would make it more manageable?”

The answer may involve emotional support, but it may also require a practical change to staffing, duties, training or store procedures.

Resilience cannot compensate for poor work design

Retailers benefit when employees can adapt to change, but individual coping skills have limits. No amount of positive thinking can reliably compensate for chronic understaffing, unpredictable scheduling, inadequate training or repeated exposure to aggression.

The Government of Canada’s guidance on mental health in the workplace recommends clear responsibilities, manageable workloads and employee involvement in setting realistic goals.

Those principles have direct retail applications. Leaders can support healthier performance by:

  • Publishing schedules with reasonable notice
  • Matching staffing levels to expected customer demand
  • Defining when employees should escalate difficult interactions
  • Ensuring workers know who can authorize exceptions or refunds
  • Rotating particularly demanding duties where possible
  • Providing adequate recovery time between shifts
  • Explaining operational changes clearly
  • Giving new employees sufficient training before expecting independent performance

Retail Insider has also explored why employee experience should be treated as an operational risk issue. Workforce resilience is strongest when it is developed through everyday management and communication—not demanded only when a crisis arrives.

Frontline emotional labour needs recognition

Customer-facing employees do more than complete transactions. They regulate their tone, expression and behaviour throughout the working day. They may be expected to remain friendly while responding to complaints, suspected theft, aggressive behaviour or concerns outside their authority.

This emotional labour can be easy to overlook because it does not appear on a task list. Yet it consumes attention and energy.

Retailers can reduce the burden by creating clear procedures for difficult situations. Employees should know:

  • When they can end an abusive interaction
  • Who will support them during an escalation
  • How security concerns should be reported
  • Whether they can step away after a serious incident
  • What follow-up support is available
  • That sales or service targets do not take priority over immediate safety

Managers also need training. An inexperienced supervisor may unintentionally minimize an employee’s reaction because they are unsure what to say or how to respond.

A calm acknowledgement is often enough to begin: “That was a difficult situation. Take a few minutes, and then we can discuss what support you need.”

Repeatable habits build capacity

Sleep, physical activity, supportive relationships and time away from work do not remove adversity. They can, however, influence the capacity a person has available to manage it.

The World Health Organization’s stress-management guide offers practical techniques including grounding, making space for difficult emotions and acting in line with personal values.

For retail employees, sustainable habits usually need to be simple enough to survive busy weeks. Examples include:

  • Taking scheduled breaks rather than repeatedly postponing them
  • Eating regularly during longer shifts
  • Using a brief transition routine after work
  • Keeping contact with trusted friends or colleagues
  • Protecting sleep as far as shift patterns allow
  • Asking for support before reaching exhaustion

Perfection makes a resilience plan fragile. A small habit that can be repeated is generally more useful than an ambitious routine that disappears during the holiday season or another peak period.

Employers should also recognise their role. It is difficult for employees to maintain healthy routines when breaks are routinely interrupted or schedules change with little notice.

Agency and meaning matter

Stress often feels more manageable when people understand what they are working towards and have some influence over how work is completed.

That sense of agency can be particularly important in retail environments where many decisions are determined by systems, policies or head-office targets. Even modest choices—such as input into shift preferences, task rotation or how a display is organized—can help employees feel less powerless.

Managers can also connect everyday tasks to a wider purpose. Receiving inventory accurately, maintaining a safe floor and resolving customer concerns all contribute to the brand experience. Recognition should reflect those contributions rather than focusing exclusively on sales figures.

Resilience grows more easily in cultures where employees believe their judgement and effort matter.

Build systems of support before they are urgently needed

Support is most effective when employees know how to access it before a crisis. Information about employee assistance programmes, counselling, benefits and emergency procedures should be clear, confidential and easy to locate.

Retail Insider reported on Mountain Warehouse’s partnership with the Retail Trust, which provides employees with resources including counselling and manager training. Initiatives of this kind demonstrate how mental-health support can be incorporated into a wider workforce strategy.

The WHO guidelines on mental health at work recommend organizational interventions alongside manager training, worker education and appropriate support for people living with mental-health conditions.

Offering a helpline is useful, but it should not be the organization’s only response. Retailers also need to examine whether their working practices are contributing to distress.

A practical resilience checklist for retail leaders

Retailers can support resilience without placing the entire responsibility on individual employees:

  • Review whether staffing levels reflect actual store traffic and workload.
  • Give employees clear escalation routes for difficult customer situations.
  • Protect breaks and recovery time during busy periods.
  • Train managers to listen without immediately minimizing or trying to fix everything.
  • Publish mental-health resources in a clear and accessible format.
  • Ask employees which workplace pressures could realistically be reduced.
  • Communicate organizational changes early and honestly.

70% of Seniors Will Need Long-Term Care: How to Protect Wealth for Your Heirs

In This Article

This article contains:

You’ve spent decades building wealth for your family, but one prolonged nursing home stay could drain it all. According to research, around 70% of people turning 65 today will need some form of long-term care during their lifetime. This statistic underscores why proactive planning is essential to ensure your care needs are covered while protecting your wealth and reducing stress for everyone involved.

Perhaps the fear of losing your life savings to long-term care costs keeps you awake at night, and you wonder if your children will inherit anything. Fortunately, strategic Medicaid and estate planning can protect your assets while ensuring you receive quality care without forcing your family to choose between your health and their financial future.

Planning for Care Secures Your Future and Peace of Mind

Creating a comprehensive financial plan delivers sustained peace of mind by securing your long-term care while protecting your life savings from overwhelming medical costs. When you eliminate the fear of depleting your assets, you directly improve your mental well-being and reassure your loved ones.

Without proper planning, family members often face enormous caregiver stress and financial burden as they scramble to cover costs and make difficult decisions under pressure. A concrete estate and Medicaid strategy alleviates this anxiety by establishing clear pathways forward.

The best time to start planning is long before you actually need care. Ettinger Law Firm emphasizes a philosophy of clarity and confidence, since you must understand the financial plan for it to work. This approach takes clients from confused or worried to calm and confident about their future care and provision for their heirs.

Additionally, Medicaid typically enforces a five-year look-back period, meaning any assets you transfer within that window can trigger penalties and delay coverage. Taking action early gives you maximum flexibility to legally protect your savings and ensure your wealth successfully transfers to your heirs.

Because Medicaid is a means-tested program with strict asset and income limits, understanding how to navigate these requirements is crucial. Many states limit income eligibility to less than $2,982 per month, and home equity should be less than $1,130,000. Working with professionals who understand tax-efficient strategies, such as asset protection trusts and spousal impoverishment protections, allows you to preserve wealth for your heirs without disqualifying yourself from assistance.

Case Study 1: How Ettinger Law Firm Integrates Medicaid Strategies in New York (Staten Island)

Since 1991, Ettinger Law Firm has served more than 35,000 clients. The firm has processed over 5,000 successful Medicaid applications, demonstrating substantial expertise in protecting assets from nursing home costs while ensuring you receive fair care coverage.

Companies looking to help older adults with estate planning can learn strategies on how to merge traditional estate planning with Medicaid asset protection strategies. Ettinger Law Firm offers innovative strategies that help ease stress and shield wealth from nursing home costs.

Elder law attorneys at Ettinger Law Firm emphasize that Medicaid Asset Protection Trusts (MAPTs) have become a critical planning tool for protecting wealth while qualifying for benefits. However, they note that timing and proper structuring are essential—these trusts must be established well before care is needed to ensure they achieve their intended purpose of preserving assets for heirs.

The firm offers experienced elder law and estate planning services across 12 convenient locations throughout New York, focusing on irrevocable and revocable trusts, Medicaid asset-protection trusts, Medicaid applications, wills, probate and estate administration.

Case Study 2: Protecting Assets Before a Crisis With Elder Law Services of California (Torrance)

Elder Law Services of California guides clients in protecting their primary residence and savings from Medi-Cal estate recovery, highlighting why planning before a crisis hits makes all the difference. The firm helps families legally protect assets, preserve their homes and qualify for Medi-Cal long-term care benefits through comprehensive support.

According to the firm, nursing home costs in California often exceed $100,000 per elder each year. Families are forced to release the equity in their assets to cover costs until they finally qualify for assistance. To prevent this financial devastation, Elder Law Services of California guides families through eligibility analysis, asset protection strategies, proper legal documentation, application preparation and ongoing compliance guidance.

Experts at Elder Law Services of California highlight that Medi-Cal estate recovery remains a significant concern for families planning long-term care in 2026. The firm notes that while Medi-Cal can cover nursing home costs, the state may attempt to recover those expenses from a deceased beneficiary’s probate estate. This makes proactive estate planning essential—assets held in properly structured trusts or with designated beneficiaries typically avoid probate and remain protected from recovery efforts.

The firm’s proactive approach ensures clients preserve wealth while still accessing the care they need.

Case Study 3: Overcoming Medicaid Application Hurdles With Holland Elder Law in Texas (Houston)

Holland Elder Law helps Texas families navigate the strict asset and income limits of the Medicaid application process to ensure they receive benefits without going bankrupt. The firm recognizes that nursing home care costs are so high — over $6,500 per month in Texas — most middle-class families need assistance to help cover monthly fees.

Attorneys at Holland Elder Law emphasize that one of the biggest hurdles Texas families face is navigating income eligibility requirements. In Texas, an “income cap” state, individuals whose monthly income exceeds $2,901 require a Miller Trust (also called a Qualified Income Trust) to qualify for Medicaid benefits. The firm stresses that these trusts must be structured precisely according to Medicaid rules—common mistakes like depositing non-income funds or missing deposit deadlines can disqualify applicants and delay benefits when families need them most.

With semi-private rooms costing even more, asset protection planning becomes vital for preserving family wealth. A skilled elder care attorney provides guidance on how to qualify for Texas nursing home Medicaid, helps you obtain benefits quickly, determines how to keep your share of costs as low as possible, supports you in addressing complications and serves as your advocate throughout the application process. This comprehensive support prevents costly mistakes that could delay or derail your coverage.

Frequently Asked Questions About Protecting Wealth

Here are the most commonly asked questions about long-term care and wealth protection.

When is the best time to start planning for long-term care?

Start planning long before you need care. Medicaid enforces a five-year look-back period, so transferring assets at the last minute triggers penalties and delayed coverage. Early planning gives you maximum flexibility to legally protect your savings.

Will you lose your home if you apply for Medicaid to cover nursing home costs?

Not necessarily. Your primary residence may be considered an exempt asset for initial eligibility, depending on its equity. However, the state may attempt to recover the estate after you pass away. Working with a legal professional to properly title your property or place it into an irrevocable trust can shield your home from recovery efforts.

Do you have to spend all of your money before you can get help with long-term care expenses?

No. While Medicaid has strict asset limits, tax-efficient strategies like asset protection trusts, spousal impoverishment protections and converting countable assets into exempt ones allow you to preserve significant wealth for your heirs.

What are the Medicaid asset limits, and do you really have to give everything away?

Most states limit income to $2,982 for single individuals, though the limit on asset equity varies by state. You do not have to give everything away. Certain assets, like your primary vehicle and personal belongings, are exempt. A professional can help you lawfully restructure your wealth to meet limits without impoverishing your spouse or losing your heirs’ inheritance.

Secure Your Financial Legacy While Funding Your Care

Planning early is key to both emotional well-being and to ensuring your hard-earned wealth passes successfully to your heirs. By understanding Medicaid eligibility requirements and working with experienced professionals who specialize in asset protection strategies, such as Ettinger Law Firm, Elder Law Services of California and Holland Elder Law, you can secure quality long-term care without sacrificing the legacy you’ve built.

The firms highlighted here demonstrate that with the right approach, you can navigate strict financial requirements while preserving significant wealth for the people you love. Take action now to protect your family’s future and gain the peace of mind you deserve.

Salesforce Brings AI Agents Closer to Checkout and Store Inventory at Dreamforce

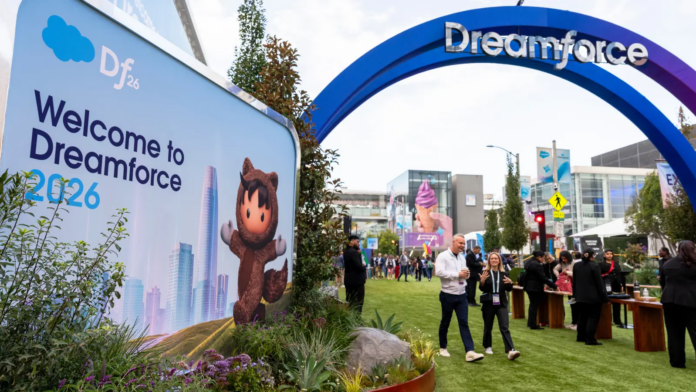
Salesforce Dreamforce in San Francisco, 2026. Image: UC Today

Salesforce is pushing artificial intelligence deeper into the retail transaction, expanding technology that allows AI agents to help shoppers find and compare products, answer questions and move through checkout while drawing on the commerce systems behind the purchase.

The company’s Dreamforce conference, held in San Francisco from September 15 to 17, provided a closer look at how Salesforce sees AI moving beyond product discovery and customer service. Its latest technology connects agents with commerce, customer data and inventory systems, allowing them to take actions on behalf of shoppers and businesses.

One of the clearest retail examples is Carter, a shopper agent designed to guide customers through product discovery, comparison and purchase. Its introduction comes as AI is already becoming part of shopping behaviour in Canada: Salesforce research previously reported by Retail Insider found that 39 per cent of Canadian consumers had used an AI tool for shopping during the previous year.

Carter Moves AI Closer to the Transaction

Carter can answer product questions, compare merchandise and support checkout within a conversation. Retailers can customize the agent, including giving it their own name, while authenticated shopper context can draw on information such as previous orders and preferences. Other functionality includes cross-selling and upselling.

US sporting goods retailer Hibbett provides an early example. Salesforce says the retailer launched its Hibbett AI implementation in six weeks and that the agent now handles 90 per cent of its core shopper journeys.

The connection with checkout moves the technology beyond the product research and recommendation functions that have characterized much of consumer-facing generative AI. Connecting the agent with commerce systems allows it to participate in the purchase instead of simply helping a customer decide what to buy.

Image: Salesforce

Connecting AI With Physical Stores

The commerce technology extends into physical retail through Salesforce’s Shop the Store functionality, which allows shoppers to select a location and search merchandise available at that store. Salesforce is also working to unify inventory across B2C Commerce and its point-of-sale technology, providing a common inventory record incorporating sales, returns and transfers.

An AI shopping agent could therefore draw on information spanning digital commerce and physical stores. A customer could ask about a product, determine whether it is available at a particular location and continue toward an online purchase, store pickup or visit to the store using the same underlying inventory information.

For omnichannel retailers, the technology connects agentic commerce more closely with their store networks instead of treating it strictly as an e-commerce function.

When Shopping Starts Outside the Retailer’s Website

Salesforce is preparing its commerce technology for shopping journeys that begin outside a retailer’s website or app. Through Headless Commerce and its broader Headless 360 architecture, the company is making business capabilities available to authorized AI agents while retaining established permissions, workflows and governance.

Salesforce has announced commerce integrations involving external AI environments including ChatGPT, Google’s Gemini and Google Search’s AI Mode. An integration with Google’s Universal Commerce Protocol is expected to support product discovery and commerce through Google AI experiences while allowing participating retailers to remain the merchant of record.

This work began before Dreamforce. Salesforce announced a major expansion of Agentforce Commerce in July, including the general availability of Shopper Agent, Buyer Agent and Merchant Agent. The Dreamforce announcements provided a broader view of how those commerce capabilities fit within the company’s AI strategy.

The development has implications for digital customer acquisition. If more product discovery occurs inside AI interfaces, retailers will need product information, inventory and other commerce data that can be accessed and interpreted by AI systems as well as conventional search engines and their own digital storefronts.

Canadian Shoppers Are Already Using AI

Salesforce research previously discussed with Retail Insider found that 89 per cent of Canadian commerce professionals believe AI and large language models will become essential to product discovery within the next year. Thirty-four per cent said they were already using agentic AI, while another 33 per cent planned to do so within six months.

Independent research from Retail Council of Canada and Leger found that 11 per cent of Canadian shoppers had used AI assistants for shopping research during the previous 30 days. Among those users, 46 per cent said AI helped them find products faster, 43 per cent said it made comparisons easier and 40 per cent said it saved time.

The findings show AI gaining a place alongside search engines, retailer websites, marketplaces, social platforms and stores as consumers research purchases.

Retail’s Data Problem

Only 30 per cent of Canadian retailers surveyed by Salesforce said their customer data was fully unified across sales, marketing, commerce and service, creating a potential obstacle as retailers give AI agents access to more parts of the transaction.

An agent helping someone research running shoes can operate with relatively limited information. An agent being asked whether a particular shoe is available in the shopper’s size at a specific store, whether a loyalty offer applies and whether it can complete the purchase requires dependable inventory, pricing, promotions, customer identity and transactional data.

Salesforce’s broader research suggests the issue extends beyond Canada. In a separate study of organizations deploying AI agents, only 31 per cent had fully unified their data before deployment. Salesforce found that organizations that unified their data first reported reaching meaningful returns from agents sooner than those that had not.

The research also identified clean and accessible data, clearly defined agent responsibilities and predetermined paths for escalating issues to humans among the factors associated with successful deployments.

“Having a sound data strategy is really going to be important,” Caila Schwartz, Director of Industry Insights at Salesforce, previously told Retail Insider.

The Infrastructure Behind the Agents

At Dreamforce, Salesforce unveiled AIforce, an interface layer designed to connect AI with Salesforce data, workflows, business logic, permissions and governance. Headless 360 similarly makes Salesforce business capabilities available to authorized AI agents, with Headless Commerce extending the approach to commerce functions.

Salesforce also introduced Koa, its first CRM reasoning model, developed using NVIDIA’s Nemotron architecture and post-trained using synthetic enterprise scenarios informed by Salesforce’s CRM experience. The company says Koa matches or exceeds leading models on its CRM benchmark while producing three times fewer errors, based on its own testing.

These technologies are designed to give AI agents controlled access to the same systems businesses use to manage customers, operations and transactions.

Holiday 2026 Could Provide an Early Test

Salesforce predicts that 20 per cent of global e-commerce traffic during the 2026 holiday season will originate from AI agents. The figure includes consumer-facing shopping agents, autonomous back-end systems and automated competitive scrapers, so it does not mean one in five consumers will shop through an AI conversation.

The company estimates that AI influenced 20 per cent of global online sales during the 2025 holiday season, representing US$262 billion in spending. The figures are based on Salesforce’s own commerce data and analysis.

Physical stores will remain a major part of the holiday shopping environment. Salesforce research previously reported by Retail Insider found that 83 per cent of Canadian consumers expected to shop in stores during the 2026 holiday season, while Retail Council of Canada and Leger research has also found that stores continue to account for the majority of Canadian purchases.

That combination helps explain the relevance of connecting AI with store-level inventory. A shopping journey that begins with an agent could lead to an online order, store pickup or a visit to a location where the merchandise has already been identified as available.

What Agentic Commerce Means for Canadian Retail

The Dreamforce announcements show Salesforce extending AI agents further into product discovery, customer data, inventory and transactions while opening more of its commerce infrastructure to AI interfaces outside conventional applications.

Canadian consumers are already experimenting with AI as a shopping tool, and Salesforce’s research suggests many Canadian commerce organizations are moving toward agentic deployments. The company’s Canadian data also shows a gap between those ambitions and the underlying infrastructure, with only 30 per cent of surveyed retailers reporting fully unified customer data.

As agents take on more of the shopping journey, retailers will need accurate inventory, pricing, promotions and customer information available across channels. Salesforce is building technology to give AI greater access to those systems, while the quality and integration of retailers’ underlying data will determine what those agents can reliably do.

Canada’s Retail Market Is Polarizing. Where Does That Leave the Middle?

Intercity Shopping Centre in Thunder Bay, Ontario (CNW Group/Leyad)

By Linda Farha

For decades, occupying the middle of the retail market was a relatively comfortable place to be. Retailers could offer good products at reasonable prices, appeal to a broad customer base and build businesses around being accessible without necessarily being the cheapest or most premium option.

That position is becoming increasingly difficult to defend.

Canada’s retail market is showing signs of a growing divide between consumers seeking value and those willing and able to spend on premium products and experiences. A Spring 2026 JLL report described the market as developing a “barbell” shape, with growth concentrated at the value and premium ends while pressure builds in the middle.

But that raises an important distinction: is the middle itself disappearing, or are retailers without a clear point of differentiation finding it harder to compete?

Consumers have not necessarily stopped spending. They have become more selective about where, when and why they spend. For retailers caught between the two ends of the barbell, the challenge increasingly comes down to relevance.

The Problem With Being Somewhere in Between

A polarized market gives consumers relatively clear reasons to shop at either end.

Value retailers answer an immediate question: How can I get what I need while spending less? Premium and luxury retailers compete on a different set of attributes, including craftsmanship, exclusivity, service, experience, status and emotional appeal.

The middle has a more complicated story to tell.

A mid-market retailer may not be able to claim the lowest price. If its products, experience and brand also don’t feel meaningfully different from less expensive alternatives, customers have little reason to pay more.

Moving slightly upmarket isn’t necessarily enough either. If consumers are going to spend more, they increasingly want to understand what the additional money buys them.

That leaves retailers with a fundamental question: Why us?

A retailer doesn’t need to be the cheapest or most exclusive option to remain relevant. It does need to offer something consumers recognize as valuable enough to justify choosing it. Without that distinction, price becomes increasingly influential in the purchasing decision.

Positioning Is More Than a Price Point

Retail positioning is sometimes viewed simply as where a brand sits on a price spectrum. Strong positioning is about the place a brand occupies in the customer’s mind: what it stands for, who it serves, what it does particularly well and why someone should choose it when dozens of alternatives are available.

The Canadian apparel market offers several examples. Aritzia has established itself around elevated women’s fashion, Canada Goose around luxury outerwear and Vessi around waterproof footwear. Tilley has been evolving into a broader outdoor lifestyle brand, while Uniqlo has built its proposition around functional everyday clothing.

These businesses occupy different price points, but consumers have a relatively clear understanding of what each represents.

Aritzia is particularly interesting because its success isn’t easily explained by the luxury-versus-value divide. The Vancouver-based company generated record fourth-quarter fiscal 2026 net revenue of nearly $1.2 billion, up approximately 33 per cent year over year, while comparable sales increased about 28 per cent.

Its performance demonstrates that significant opportunity remains outside the two extremes when a retailer creates a sufficiently distinctive proposition.

Aritzia has built its positioning around what it calls “Everyday Luxury,” combining elevated design and an aspirational shopping experience with pricing below traditional luxury fashion. Its portfolio of exclusive brands gives customers access to different styles within a recognizable overall aesthetic, while its boutiques, service and digital experience reinforce that positioning.

Uniqlo offers another example from a different part of the market. Its LifeWear philosophy centres on simple, functional, high-quality everyday clothing, including products such as HEATTECH and AIRism designed around practical considerations including warmth, comfort and moisture management.

Rather than competing primarily on trends or exclusivity, Uniqlo gives shoppers a practical reason to choose its products.

The middle isn’t necessarily disappearing because consumers will only buy cheap or expensive products. What’s under greater pressure is the undifferentiated middle.

When a Retailer’s Position Becomes Harder to Define

Hudson’s Bay offers a useful illustration of the challenges facing traditional middle-market retail, although its difficulties extended well beyond brand positioning.

The department store once held a distinctive place in Canadian retail, combining heritage, broad assortment and a familiar national identity. Over time, specialty retailers, discount chains, luxury brands and online competitors gave consumers increasingly specific alternatives.

Hudson’s Bay’s 2025 closures became a prominent example of the changing retail landscape. JLL’s Spring 2026 analysis pointed to those closures as evidence of pressure facing middle-market physical retail, alongside a broader shift in investment toward value and premium formats.

Its experience raises a broader question for retailers with large assortments and established brand recognition: what happens when familiarity is no longer a sufficient reason to visit?

Heritage, convenience and selection can all contribute to a compelling retail proposition, but each needs to remain relevant as consumer expectations and competitive alternatives change. A retailer that once served as a natural destination across numerous categories can find itself competing with specialists offering greater expertise, discount retailers offering lower prices and premium brands offering more distinctive experiences.

Differentiation Has to Exist Beyond Marketing

When retailers recognize a positioning problem, there can be a temptation to address it primarily through communications: update the tagline, refresh the visual identity or launch a new campaign.

Those initiatives can be valuable, but communications can’t create a meaningful distinction that doesn’t exist elsewhere in the business.

Differentiation can come from product, service, expertise, convenience, curation, community or the in-store experience. Strong retailers often combine several of those attributes around one recognizable proposition.

What matters is that the distinction is valuable to the customer and consistently delivered. A retailer positioning itself around expert advice needs knowledgeable people available when customers need them. A brand promising convenience needs an experience that actually feels convenient. A retailer charging more because of quality needs to communicate what makes that quality different and give customers reasons to believe the claim.

Otherwise, positioning becomes something a brand says about itself rather than something customers experience.

Clarity Has Commercial Value

Pressure on the middle can create another temptation: trying to become more things to more people.

A retailer might introduce additional promotions to appeal to price-conscious shoppers, add premium products to attract higher-spending customers or expand into new categories to broaden its audience. Each decision can make sense individually, but without a clear strategy connecting them, the overall brand can become harder to understand.

In a market where consumers already face enormous choice, clarity has commercial value.

That doesn’t mean retailers need to narrow themselves to a single product or customer type. Aritzia, for example, uses multiple exclusive labels to address different preferences while maintaining a recognizable overall proposition.

The larger question is which products, categories, services and customer segments reinforce what a retailer stands for — and which simply add complexity.

Price remains part of that calculation, but value means different things to different consumers. For one shopper, value may mean obtaining the lowest price on an everyday item. For another, paying more for something that lasts longer represents better value. Convenience, expertise, exceptional service, warranties and products that solve particular problems can all contribute to the equation.

Retailers that aren’t positioned to win a race to the bottom therefore need clear answers to some basic questions: Why does the product cost more? What makes the experience better? What does the customer receive here that they won’t get elsewhere?

Brand Strategy and Business Strategy Are Converging

Positioning extends well beyond marketing. It influences what a retailer sells, which customers it targets, where it opens stores, how it prices, the experience it creates and where it invests.

That can require difficult decisions for retailers occupying the middle of the market. Which customers are most important? Which parts of the offer are genuinely distinctive? What should the business be known for? And what no longer fits?

Those answers should inform decisions across merchandising, operations, real estate, customer experience and communications.

Canada’s increasingly polarized retail environment is making vague positioning harder to sustain. Consumers can still be persuaded to spend between the value and premium extremes, but retailers need to give them a compelling reason to do so.

The middle isn’t necessarily disappearing. What is becoming harder to sustain is a place in the market that offers consumers no clear reason to choose it.

There is still room in the middle. The challenge for retailers is making their position within it matter.

Linda Farha is Founder and President of Zenergy Communications and a communications and marketing executive with more than 30 years of experience helping Canadian organizations build brands, drive media visibility and support business growth. Zenergy’s A&D Link is a strategic marketing communications engagement platform designed to connect product innovation with real-world specification and adoption.

More From Retail Insider

Preparing Retail for the Age of Autonomous Commerce: Why Trust and Fraud Prevention Matter

Image: WordPay

Retail fraud has become a major challenge for modern commerce. As ecommerce has expanded, fraudsters have become increasingly sophisticated, employing everything from automated bots and account takeovers to phishing campaigns and synthetic identities. The costs extend far beyond the value of a fraudulent transaction itself, encompassing chargebacks, operational expenses, customer service costs and reputational damage.

The issue is particularly relevant for Canadian retailers. Canadians reported more than $704 million in fraud losses in 2025, according to the Canadian Anti-Fraud Centre, marking the highest annual total on record. Authorities estimate that only five to 10 per cent of fraud incidents are reported, meaning the true financial impact is likely far greater. Meanwhile, ecommerce continues to grow, digital payments are becoming increasingly commonplace, and retailers are investing heavily in automation and artificial intelligence throughout their businesses.

For merchants, the challenge is balancing strong security with a smooth customer experience.

Worldpay, a Global Payments company, believes the industry is approaching another major turning point. Drawing on its experience helping merchants process digital payments around the world, the company expects AI-powered shopping agents to play a growing role in how consumers discover products and complete purchases. That evolution creates new opportunities for retailers while introducing new questions about trust, authentication and fraud prevention.

Artificial intelligence is changing not only how fraud is committed, but also how consumers shop.

The Rise of Agentic Commerce

Worldpay refers to this emerging shift as agentic commerce — a model in which AI-powered assistants can research products, compare prices and, with a consumer’s permission, complete purchases on their behalf. While the concept is still in its early stages, major payments companies and technology providers have already begun building the infrastructure to support it.

Early forms of AI-assisted shopping are already influencing consumer behaviour. Research from Adobe found that traffic to retail websites originating from generative AI tools surged dramatically over the past year, underscoring how quickly consumers are becoming comfortable with AI-assisted experiences.

Over time, autonomous agents may handle more routine purchasing decisions, helping consumers discover products, compare offers and complete transactions with minimal effort.

For retailers, the opportunities are significant. AI agents could simplify purchasing decisions, improve convenience and create more personalized shopping experiences.

The technology also raises new questions. How does a merchant know whether an AI agent is acting on behalf of a legitimate customer? How should an autonomous purchase be authenticated? Who is responsible if an AI agent makes an unauthorized purchase?

The future of agentic commerce will depend heavily on trust.

Fraud Is Becoming More Sophisticated

Retailers do not have the luxury of waiting to address these questions.

Bad actors are increasingly using advanced technologies of their own. Artificial intelligence is making it easier for criminals to launch attacks at scale, create convincing impersonations and identify weaknesses in digital commerce environments.

The threat landscape is becoming increasingly sophisticated and continues to evolve rapidly.

Traditional, rules-based approaches to fraud prevention can struggle to keep pace with these emerging threats. Criminals constantly adapt their tactics, forcing merchants to respond just as quickly.

Fraud prevention increasingly depends on systems that can continuously learn, adapt and identify new patterns of risk.

Why Machine Learning Matters

Many retailers are turning to machine learning to help identify suspicious activity and protect legitimate transactions. Companies such as Worldpay are investing heavily in machine learning and advanced fraud prevention technologies that can help merchants better distinguish between genuine customers and potentially fraudulent activity.

Machine learning models can analyse vast amounts of data in real time, identifying patterns and signals that would be impossible for human teams to process manually. These systems continuously evolve as fraud tactics change.

Machine learning can also help merchants avoid unnecessary friction.

One of the biggest challenges in digital commerce is distinguishing between a genuine customer and a fraudulent actor without creating barriers that discourage legitimate purchases. Excessive security measures can lead to checkout abandonment, frustrated customers and lost sales.

Advanced machine learning technologies seek to strike the right balance by helping merchants identify risky behaviour while prioritizing genuine transactions and preserving a smooth customer experience. As the payments landscape evolves, machine learning is becoming a foundational technology for fraud prevention. Worldpay’s fraud prevention capabilities are designed to analyse broad and complex data across the customer journey, helping merchants make more informed decisions in real time while adapting to increasingly sophisticated threats.

Preparing for an Autonomous Future

The emergence of AI-powered shopping agents does not mean retailers need to start from scratch.

Many of the signals that help determine whether a transaction is legitimate today will remain relevant in the future. Transaction behaviour, device information, account history and purchasing patterns will continue to play an important role in fraud prevention.

According to Worldpay’s research into agentic commerce, approximately 80 per cent of today’s fraud signals are expected to remain relevant even as autonomous transactions become more commonplace. Worldpay believes the challenge for merchants will be understanding the new signals that emerge as AI agents increasingly participate in commerce.

Preparing for this transition is not simply about adopting new technology. It also means working with payments and fraud prevention partners that continue to invest in machine learning, behavioural analytics and emerging authentication methods to help merchants stay ahead of evolving threats.

Machine learning that can process broad and complex data across multiple touchpoints in the customer journey are likely to play a critical role in helping merchants determine whether a transaction should be trusted, regardless of whether the purchaser is a person or an AI agent acting on their behalf.

Trust Will Determine Adoption

Consumer interest in AI-assisted shopping is growing, but so are concerns surrounding identity theft, unauthorized purchases, fraud and loss of financial control.

Worldpay’s research found that while many consumers are open to allowing AI agents to shop on their behalf, fraud protection remains one of the most important factors influencing trust in these experiences.

For agentic commerce to achieve widespread adoption, retailers and payment providers will need to demonstrate that these new experiences are secure, transparent and easy to control.

Fraud prevention is no longer simply about stopping bad actors.

It is also about building confidence in new forms of commerce.

Retailers that embrace innovation while maintaining trust in every transaction will be well positioned for the next phase of digital commerce.

Looking Ahead

Artificial intelligence is reshaping retail rapidly. The same technologies creating new opportunities for consumers and merchants are also creating new challenges for fraud prevention.

As autonomous shopping experiences begin to emerge, the ability to distinguish legitimate activity from malicious behaviour will become increasingly important.

Commerce is becoming more intelligent and more automated.

Retailers that begin preparing today will be better positioned to navigate both the opportunities and the risks that lie ahead.

For retailers, preparing for this transition is not simply about adopting new technology. It also means having payment and fraud prevention systems that can adapt as the way consumers shop changes.

Worldpay offers a range of fraud prevention and payment technologies designed to support that transition, including credential management and advanced fraud detection capabilities. These tools can help retailers protect legitimate transactions today while preparing for a future in which AI agents play a greater role in the shopping and payment process.

Retailers looking to strengthen their fraud prevention strategies or prepare for agentic commerce can learn more about Worldpay’s fraud prevention solutions and its work around the future of AI-powered payments.

Grocery Inflation Tests Brand Loyalty as Parents Trade Down to Store Brands: DOSS

Greta Hoffman photo
Greta Hoffman photo

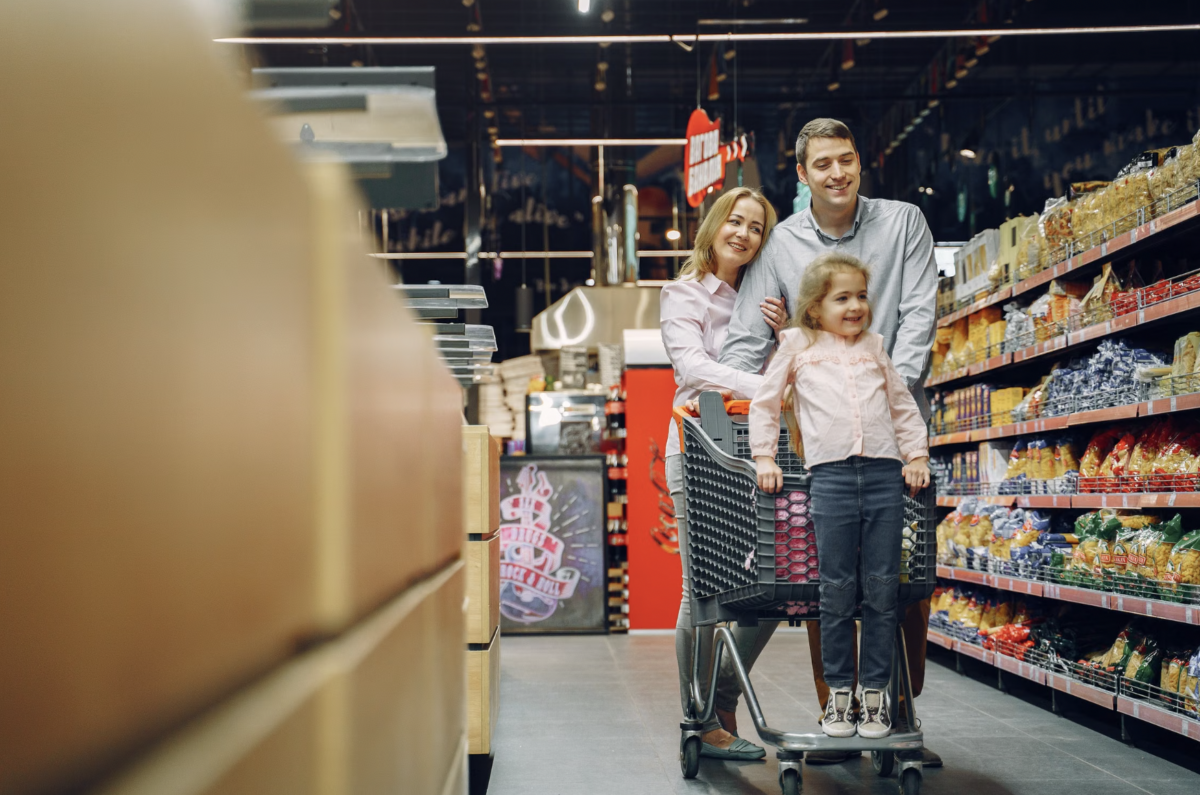
Higher prices are putting brand loyalty to the test as consumers look for ways to stretch their grocery budgets without cutting everyday essentials altogether. In a new study, DOSS surveyed 811 parents and analyzed federal pricing data to see how sustained inflation is changing what families buy and which brands stay in their carts.

Key Takeaways

The findings point to a significant shift toward cheaper alternatives as parents reconsider the premium they’re willing to pay for familiar brands. That trade-down behaviour is showing up even among higher-income households:

  • 64% of parents switched at least one of their child’s favourite brands to a cheaper store-brand alternative this school year.
  • Even among households earning $100,000 or more, 55% have switched a child’s favourite brand for a cheaper option.
  • 45% of parents have stopped buying a snack, drink, or lunch item their child regularly asks for because it became too expensive.
  • 36% say their child complained after they traded down, highlighting the tension between brand preference and price.

View the full study here.

The findings offer a look at how persistent price pressures are influencing brand loyalty and creating an opening for lower-cost and private-label alternatives. DOSS also examined which recognizable food brands parents are replacing as they adjust their shopping habits. 

In an interview with Retail Insider, Eshaan Kaul, Head of Growth at DOSS, discussed the report’s findings.

What do the findings tell you about how sustained grocery-price increases are changing brand loyalty among Canadian families, particularly when it comes to products children prefer?

Our report is based on a survey of U.S. parents, rather than Canadian respondents. That being said, findings show that there are shifts in brand loyalty as parents adjust to higher prices of children’s products. For example, 64% of parents have replaced at least one of their child’s favourite brands with a store brand this school year. Moreover, 45% of parents have given up on a snack, beverage, or lunch item their child regularly buys or wants to buy because it has become too expensive. This demonstrates that a significant portion of parents are removing a specific product from their child’s rotation rather than simply substituting it with a cheaper alternative.

What are you seeing in the data about the willingness of higher-income households to switch from familiar national brands to cheaper store-brand or private-label alternatives?

While our research indicates that trade-down occurs in higher-income families as well, it is much more prevalent in lower-income households. For example, 71% with household incomes below $50K have switched a favourite brand to a cheaper option, as have 55% of those earning $100K or more have switched to store brands. 

However, the majority of higher-income families (earning six figures) also engage in trade-down, which suggests that switching to cheaper options is an all-class phenomenon. A slight income gradient is observed among those agreeing strongly with the statement; about a fifth (22%) of higher-income households fall into this category compared to 29% of those with incomes below $50K (41%) strongly agree that they’re buying fewer name-brand products, compared with over 1 in 5 of those earning $100K.

Which grocery categories or types of products are seeing the greatest trade-down behaviour, and what recognizable brands are parents most commonly replacing?

The breakfast category appears to be the most affected by trade-down, as breakfast brands were most frequently substituted for store-brand alternatives. About a quarter of parents have switched Eggo and Pop-Tarts for cheaper alternatives. Paper goods are also associated with a significant number of substitutions, with mothers being slightly more likely to switch (48%) than fathers (33%). Notably, parents appear to be the least willing to sacrifice breakfast items, as over a fifth (26%) have traded down but continue buying their child breakfast, and about a quarter have resisted cutting down on breakfast altogether. Thus, breakfast seems to be the most difficult category to substitute, which makes parents choose lower-priced options within this category.

Gustavo Fring photo
Gustavo Fring photo

How significant is the tension between parents’ desire to manage household grocery budgets and children’s preferences for specific brands, based on the 36% who said their child complained after a trade-down?

The findings suggest that tensions between parents’ need to stretch their budgets and their child’s preferences for branded products often result in adverse reactions to substitutions. Over a third (36%) of parents report that their child has complained about them switching from their favourite brand to a cheaper alternative. Combined with the fact that nearly two-thirds of parents have substituted at least one brand for a store brand and almost half have cut down on a product their child wanted to buy, this indicates that, for such families, substitutions are associated with tension and difficulties.

What do these findings mean for national food brands and retailers as consumers become more willing to sacrifice brand loyalty for lower prices, and do you expect these shopping changes to persist if inflationary pressures ease?

National brands in the breakfast category and paper goods are most at risk of being substituted for private-label options. The fact that a majority of higher-income households also engage in trade-down suggests that the observed changes could be persistent in the long run. If parents continue buying store-brand products, their loyalty to national brands within these categories may erode permanently.

More from Retail Insider:

Quartz Co. Plans Broader Canadian Retail Expansion with New Montréal Store

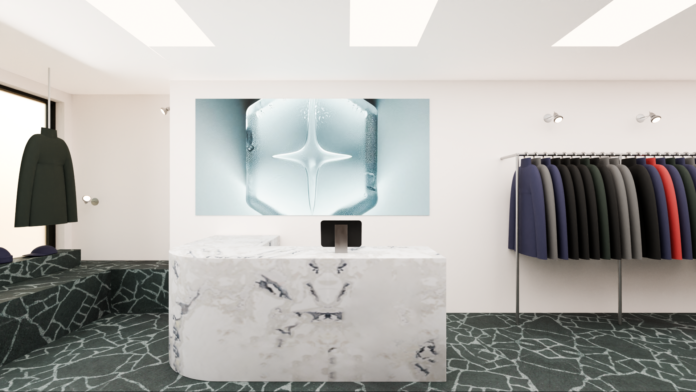
Quartz Co, Notre-Dame Plan, Front. Rendering: Quartz Co

Montréal-based outerwear brand Quartz Co. is preparing to open a new boutique on Notre-Dame Street this fall as the company lays the groundwork for a broader expansion of its physical retail network in Canada.

JEAN-PHILIPPE ROBERT – President and Co-Owner

The approximately 1,200-square-foot store will become Quartz Co.’s second permanent Montréal boutique, joining its existing Mile End flagship. The company also operates a temporary location at Royalmount, which President Jean-Philippe Robert says has been performing increasingly well. The new store is targeting a late-October opening, although the timing remains subject to construction.

More significantly, Robert told Retail Insider that Quartz Co. will spend the coming year assessing opportunities for additional stores, with Toronto among the markets under consideration. The company has spent the past several years adapting its product mix for a direct-to-consumer environment, giving management greater confidence as it considers its next phase of growth.
“This is what we’ll be working on in the next twelve months,” Robert said of the broader retail expansion. “We really hit the targets with our existing store.”

New Store on Notre-Dame Street

Quartz Co. deliberately chose another street-front location for the new boutique, continuing an approach established with its Mile End flagship. The store will be located on Notre-Dame Street West near Atwater Market, an area Robert said gives the company access to a strong existing customer base and a neighbourhood environment that fits the brand.

“We have a very strong consumer base here in Montreal,” he said, describing the area as lively and well aligned with Quartz Co.’s target customer.

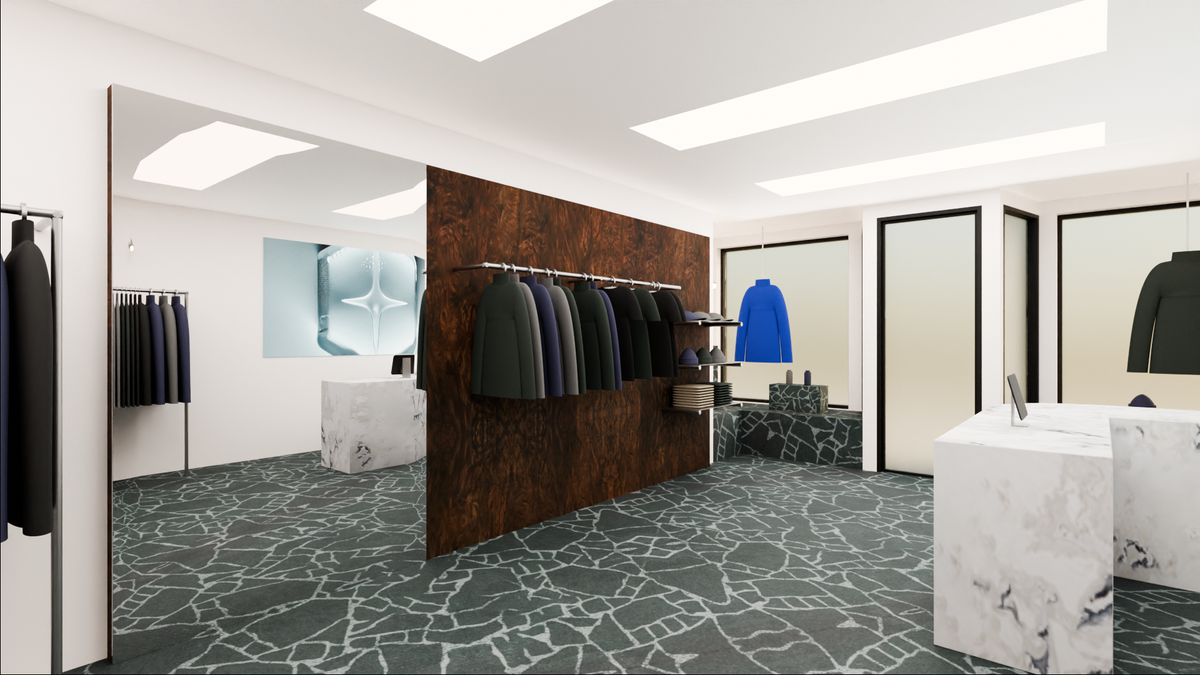
The roughly 1,200-square-foot boutique will introduce an evolution of the design language used at the company’s existing store. Robert said the space will feature warmer materials and contemporary references to Canadian nature, reflecting what he sees as a close relationship between urban life in Canada and the country’s climate and landscape.

“Even if we live in the city, it’s almost like we live in nature,” he said. “The elements are so harsh, and the daily life of a Canadian in the city is always very connected to nature.”

Quartz Co. opened its first permanent store in Montréal’s Mile End in 2020, at 5445 Avenue de Gaspé. The company later added its temporary boutique at Royalmount, which Robert said has performed better with each season. Six years of operating its own retail spaces have also changed how Quartz thinks about its assortment and the role stores can play in the business.

Quartz Co, Notre-Dame Entrance. Rendering: Quartz Co

Toronto Among Markets Under Consideration

Robert said management intends to conduct strategic assessments over the coming months as it determines where Quartz Co. could expand next. Toronto is specifically on the company’s radar, although Robert stressed that Quartz has not committed to a location or opening date.

“We’re looking west, Canada West,” he said, indicating that Toronto would likely be among the first markets examined before Quartz considers other parts of the country.

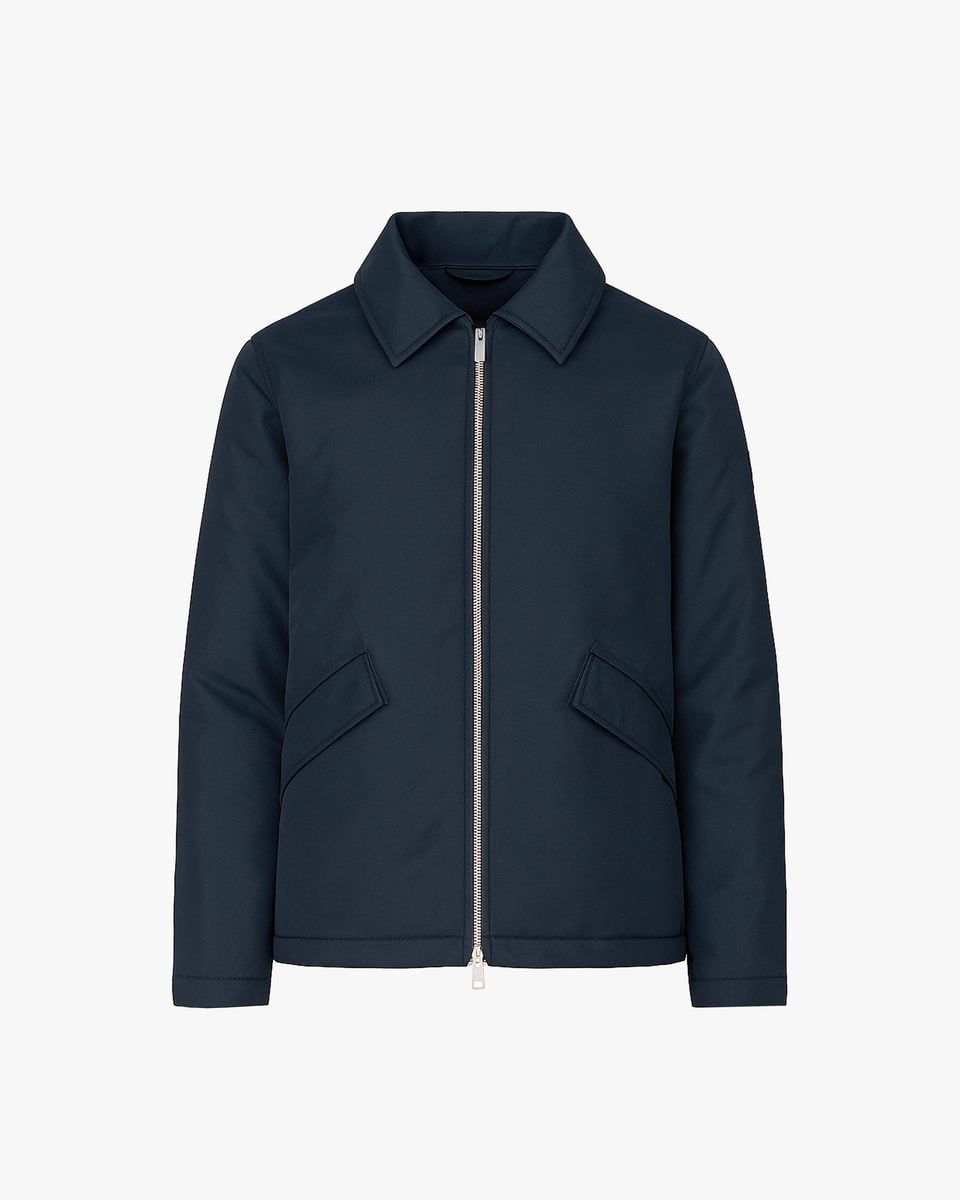
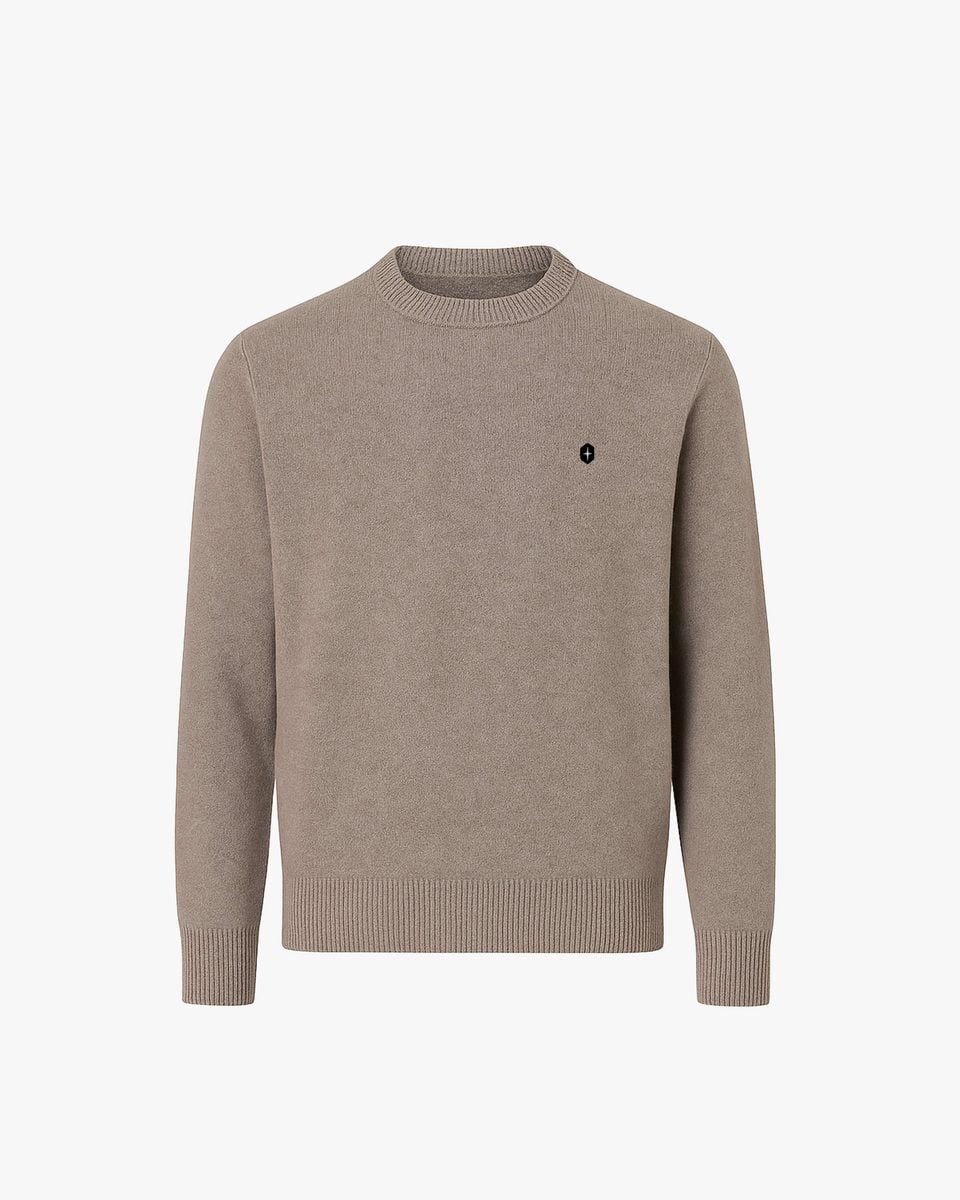
The potential expansion comes as Quartz develops a larger assortment than the one traditionally presented through its wholesale network. Robert said wholesale partners tend to concentrate on the heavyweight, Canadian-made parkas for which Quartz is best known, while its own stores can carry a broader assortment of lightweight outerwear, ready-to-wear, knitwear and accessories.

“The store offers a much broader range,” he said. “It’s worthwhile to visit the store and be able to have a full and comprehensive vision of the brand and the collection because it’s really evolved.”

Quartz Co. says its products are available through more than 300 stores in over 20 countries. Its growing direct-to-consumer business gives the company another way to present categories that may receive less exposure through traditional wholesale distribution.

Physical Retail Complements E-Commerce

Quartz Co.’s investment in stores comes alongside continued growth in e-commerce. Robert said parkas have proven particularly well suited to online purchasing, with the company encountering relatively little resistance from customers buying outerwear digitally.

Physical stores serve a different role, allowing shoppers to experience a wider assortment and discover products they may not have been searching for online. Robert said the boutiques give customers a better understanding of the broader Quartz brand as its offering moves beyond the heavyweight parkas for which it is best known.

Women’s Category Becomes a Bigger Focus

Women already account for the majority of Quartz Co.’s sales, according to Robert, and the company sees room to expand that side of the business further. This fall, Quartz is introducing Soleil d’Hiver, a limited collection designed to explore a more fashion-oriented expression of the brand.

“Women is a big focus for us,” Robert said. “It’s already a majority of our sales, but we just feel the women’s market could be a bigger driver for us.”

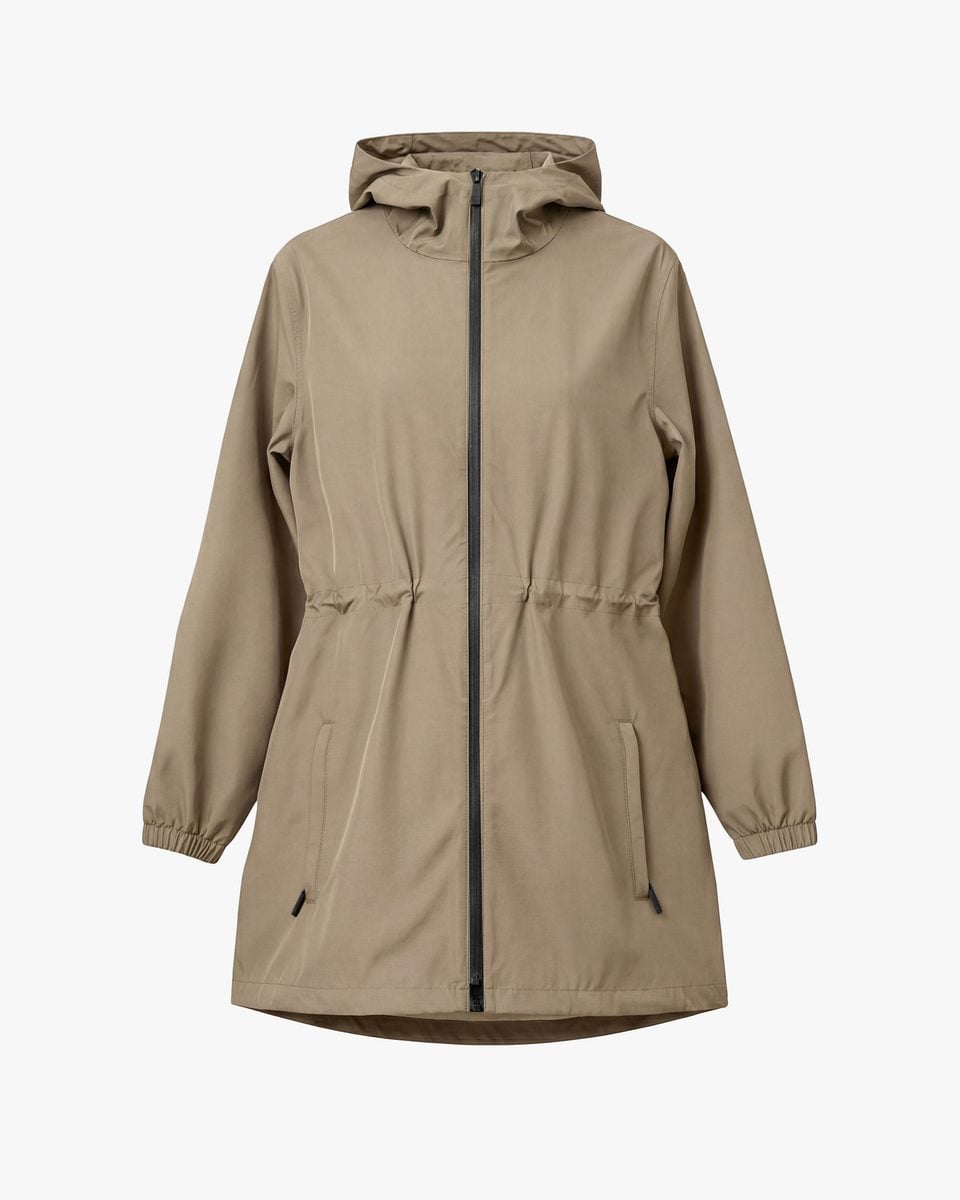
Robert described Soleil d’Hiver as a more “poetic” expression of Quartz Co., with inspiration drawn from the colours and skies of Canadian winters. The collection introduces different silhouettes and shapes alongside brighter colours and includes a parka, ready-to-wear pieces, knitwear and accessories.

Quartz is also using Soleil d’Hiver to explore smaller product drops and limited editions. The initiative forms part of a wider effort to develop categories beyond the extreme-cold parkas historically associated with Quartz, while retaining outerwear as the foundation of the business.

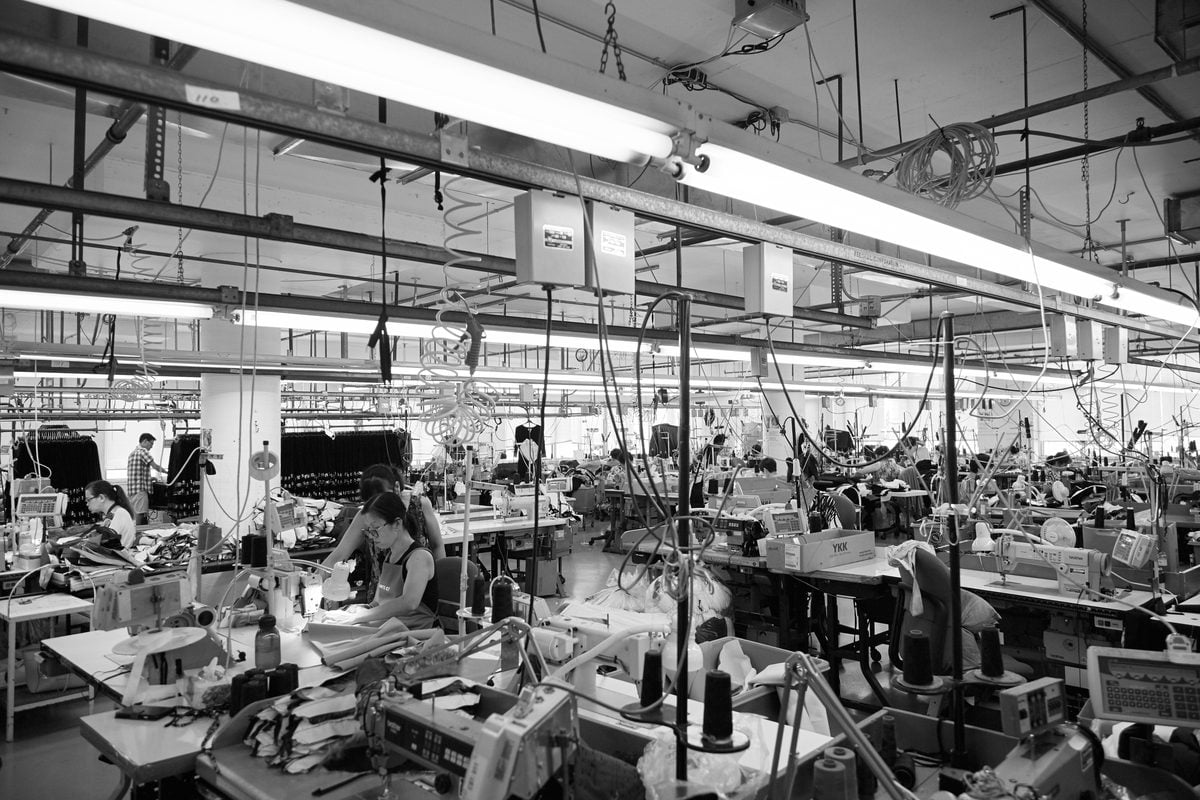
Quartz Co Manufacturing

Montréal Manufacturing Remains Important

Quartz Co. continues to manufacture its core Canadian-made outerwear in Montréal, maintaining domestic production at a time when much of the apparel industry’s manufacturing capacity has moved offshore. Robert acknowledged that operating in Canada requires continued effort, but said the expertise remains an important part of Quartz’s positioning at home and internationally.

“It’s a huge pride for us,” he said. “It’s a consistent effort. It’s not easy, but it’s really appreciated by our customer in general here and abroad.”

Not everything sold by Quartz is manufactured domestically. The company also works with overseas factories on categories including lighter-weight products, but Robert said maintaining its Montréal operation gives Quartz technical expertise that carries into those relationships.

“Even for collections that we make abroad, the fact that we have the factory here really gives us that credibility because we understand the product inside out,” he said, pointing to the technical team in Montréal and its work with partner factories.

Quartz traces its roots to 1997, when the business was established as Quartz Nature. Jean-Philippe Robert and his brothers acquired the company in 2015 and subsequently repositioned it as Quartz Co., while expanding its distribution internationally.

U.S. Tariffs Complicate Growth

The United States represents approximately 15 per cent of Quartz Co.’s sales, according to Robert. The company had been seeing strong growth in the market and had plans to expand further, particularly in the U.S. Northeast, before changes to the cross-border trading environment complicated that strategy.

Robert said changes to U.S. de minimis treatment initially added complexity to cross-border e-commerce. More recently, tariffs have created a direct financial challenge for the company.

“It’s really the unpredictability,” he said. “We had strong plans for U.S. because we saw good traction and growth. Now it feels like we have to hold back a little bit.”

Robert said some Quartz products are currently subject to tariffs of 50 per cent and have consequently been removed from the company’s U.S. website. He said the result has included lost revenue and additional inventory that the company must manage. The wider tariff measures introduced by the United States in August include clothing and apparel among the categories facing new duties.

Despite the disruption, Robert continues to see considerable potential in the United States, particularly in the Northeast. Quartz is not abandoning the market, but the uncertainty has increased the importance of developing business elsewhere.

Looking Beyond Canada Again

Europe is among the regions Quartz intends to examine as it considers its next stage of growth. The company already has wholesale accounts in countries including France and Germany and serves international customers through e-commerce, but does not currently operate its own stores in Europe.

Robert said markets outside Canada accounted for approximately 40 per cent of Quartz Co.’s sales before the COVID-19 pandemic. Following several years of stabilization, he believes the company is again positioned to pursue larger international opportunities.

“We’re really hungry to go again after these big markets,” he said.

The product assortment has changed considerably since Quartz’s earlier international expansion. Robert said the company was once much more heavily associated with its “minus-30 made-in-Canada parka,” while today’s collection covers a wider range of climates and product categories. The heavyweight Canadian parka remains important to Quartz’s identity and provides credibility when the company approaches international retailers and distributors.

“The Canadian parka credibility is really potent,” Robert said. “It gives you a seat at the table.”

For Quartz Co., the next phase will be about using that recognition to grow a broader business, beginning with the new Notre-Dame store and potentially extending to additional retail locations in Canada and renewed expansion internationally.

“Now it’s a matter of pressing the gas on these initiatives and being more aggressive,” Robert said. “We’re ready to do that.”

More from Retail Insider: