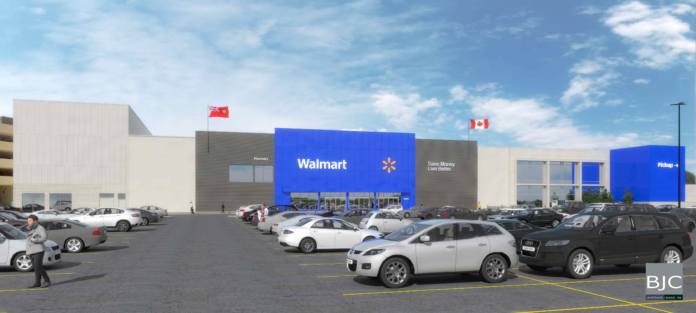
Photo of the future Walmart store at Bramalea City Centre. Image supplied
Walmart Canada announced Wednesday it is set to open a new Supercentre at Bramalea City Centre in Brampton, with the store expected to open in 2027.
The approximately 140,000-square-foot location will become a new anchor tenant at the shopping centre and offer a full grocery assortment, general merchandise, pharmacy, and pickup and delivery services, said the retailer.
The announcement comes as Brampton continues to grow and marks Walmart’s sixth Supercentre in the city. It’s also part of Walmart Canada’s broader $6.5 billion investment in Canada announced last year, it said.
It will be located at 25 Peel Centre Drive at Brampton’s largest shopping destination. The store replaces a Decathlon store and Activate as well as Designer Depot, all of which occupied a former Target space in the mall.
It said the Supercentre will feature:
Walmart’s full general merchandise assortment, including fashion, home goods, electronics, health and wellness, seasonal items and more
A full grocery assortment of fresh produce, chicken, beef, pork and seafood, deli foods, baked goods, dairy products, frozen foods and dry grocery items
“We’ve been a part of the Brampton community since 1994 and we’re excited to bring this new Supercentre – our sixth in the city – to Bramalea City Centre,” said Shawn Fujiki, Senior Director, Real Estate, Walmart Canada. “We’re opening this new Supercentre as part of our $6.5 billion investment in Canada announced last year, which will help to bring our everyday low prices to even more customers across the country.”
“We’re excited to welcome Walmart Canada to Bramalea City Centre and further strengthen our offering for our customers and surrounding community,” said Andrew Butler, General Manager, Bramalea City Centre. “The addition of a Walmart Supercentre will bring value and convenience while enhancing the overall shopping experience at the centre, especially for the families that make up the majority of our customers. ”
Bramalea City Centre is one of Canada’s largest enclosed shopping centres, spanning approximately 1.5 million square feet of retail space with more than 300 stores and services. Owned and managed by Morguard Investments Limited, BCC is evolving to enhance its overall visitor experience, it said. This includes refining its tenant mix – such as the addition of Walmart – and a recently- completed multi-million-dollar renovation.
Walmart Canada operates 150 stores in Ontario and employs over 45,000 people in the province.
As part of Retail Insider Reports, this Q2 2026 Retail Technology & Payments draws on Retail Insider coverage, operator commentary, and broader industry research, it identifies the key developments shaping artificial intelligence, payments, loyalty, and commerce infrastructure in Canada. The full report series is available through the Report Hub.
This report examines Canada’s Retail Technology and Payments & POS retail landscapes:
Retail Technology: This report examines technologies enabling Canadian retail, including POS systems, AI, ecommerce platforms, retail software, customer engagement, loyalty technology, cybersecurity, automation, and digital innovation.
Payments & POS: This report examines payment technologies, point-of-sale systems, fintech, digital wallets, payment processing, checkout innovation, fraud prevention, and retail financial technology.
Canadian retail technology entered a new phase in Q2 2026.
Technology is increasingly becoming less about individual tools and more about infrastructure that connects customers, data, payments, and operations. Artificial intelligence, payments, loyalty programs, delivery networks, and commerce platforms are converging into integrated ecosystems that support nearly every aspect of modern retail operations.
Retailers increasingly want fewer silos, more connected data, and technology platforms that can improve customer experiences while also driving operational efficiency. These developments point to a broader shift in the industry, as technology increasingly becomes invisible infrastructure that underpins modern commerce rather than a collection of standalone tools.
Market Context: Technology Becomes Infrastructure
Canadian retailers continue to invest heavily in digital capabilities, but the conversation is increasingly shifting away from standalone technologies and toward integration.
Retailers are looking for solutions that connect customer data, loyalty, payments, inventory, fulfillment, and marketing into unified ecosystems. Consumers increasingly expect seamless experiences across channels, while retailers continue to face cost pressures and labour challenges. At the same time, artificial intelligence is creating new opportunities for personalization, automation, and operational efficiency, encouraging retailers to rethink how technology is deployed across their organizations.
The traditional boundaries between software, payments, loyalty, marketing, and operations are increasingly disappearing. The result is a retail environment in which technology functions as foundational infrastructure rather than a collection of disconnected tools.
Broad Overall Themes
Canadian retail technology and payments in Q2 2026 reflected several interconnected themes:
Artificial intelligence is moving from experimentation into infrastructure.
Commerce stacks are becoming increasingly integrated.
Loyalty programs and retail media are becoming strategic assets.
Delivery and convenience are becoming embedded expectations.
Agentic commerce is beginning to take shape.
Workforce readiness continues to lag technological investment.
Cross-border commerce infrastructure continues to improve despite ongoing friction.
AI Becomes Commerce Infrastructure
Artificial intelligence was the defining technology story of the quarter, and the conversation has moved well beyond chatbots and experimental pilots.
Retailers increasingly view AI as infrastructure that can improve merchandising, customer engagement, inventory planning, personalization, and operational efficiency. Loblaw’s integration with ChatGPT demonstrated how AI can increasingly influence product discovery and shopping behaviour, while Canadian Tire’s MOSaiC platform uses artificial intelligence and data to identify localized demand patterns and micro-occasions, helping optimize merchandising, promotions, and inventory decisions.
Canadian technology companies such as Helios AI also demonstrate how artificial intelligence is increasingly supporting merchandising, forecasting, and retail decision-making, illustrating that AI’s influence extends well beyond customer-facing applications.
Retailers are also beginning to explore AI for strategic planning. The emergence of AI personas and consumer simulations suggests that artificial intelligence may increasingly help retailers test ideas, model consumer behaviour, and make decisions before launching products or campaigns.
At the same time, research released during the quarter suggested that Canadian consumers remain somewhat cautious about AI-powered shopping experiences. Trust, privacy, cybersecurity, and transparency continue to matter as retailers increasingly embed AI and digital technologies into commerce.
Nevertheless, the direction of travel is increasingly clear: artificial intelligence is moving from experimentation into infrastructure.
Integrated Commerce Stacks Gain Momentum
Another important development during the quarter was the continued convergence of commerce platforms.
Retailers increasingly want integrated systems that combine payments, software, loyalty, and customer engagement capabilities. Point-of-sale providers, payment processors, and commerce platforms are expanding their capabilities in response, blurring the traditional boundaries between payments, software, marketing, and operations.
Integrated platforms can reduce complexity, improve access to data, and create operational efficiencies while providing retailers with more flexibility to deliver seamless customer experiences across channels.
The future of retail technology increasingly appears to be platform-based and interconnected.
Loyalty and Retail Media Become Strategic Assets
Loyalty programs have evolved into some of Canada’s most important commerce infrastructure.
George Weston Limited’s PC Optimum program now exceeds 18 million active members, creating one of the country’s largest first-party data ecosystems. Scene+ continues to expand its role across entertainment and retail, while Canadian Tire’s Triangle Rewards ecosystem demonstrates how loyalty increasingly extends beyond rewards and into broader customer engagement.
Retail media networks are also gaining momentum. Retailers increasingly recognize that customer data, owned channels, and loyalty ecosystems can become valuable advertising and engagement platforms in their own right.
As third-party data becomes less reliable and privacy expectations evolve, first-party customer relationships are becoming increasingly important competitive assets. Loyalty is no longer simply a retention tool. It is increasingly becoming foundational retail infrastructure.
Delivery and Convenience Become Embedded Infrastructure
Convenience has become an expectation rather than a differentiator, with consumers increasingly expecting retailers to provide multiple fulfillment options, including delivery, click-and-collect, and rapid fulfillment.
Delivery partnerships continue to expand, and convenience retailers are increasingly investing in digital capabilities and loyalty ecosystems. Circle K’s growth strategy demonstrates how convenience retail is increasingly built around a combination of foodservice, digital engagement, and loyalty.
At the same time, retailers continue to invest in fulfillment capabilities and automation that can support increasingly complex omnichannel operations. Pattison Food Group’s automated fulfillment investments illustrate how technology increasingly supports the operational side of retail, improving efficiency, scalability, and speed.
Some of the most significant retail technology investments are occurring behind the scenes, where automation and logistics capabilities increasingly determine how effectively retailers can serve customers.
Convenience is increasingly becoming embedded infrastructure.
Payments Become Increasingly Invisible
Payments remain one of the most important elements of retail technology, yet they are increasingly becoming less visible to consumers.
Digital wallets, embedded payments, loyalty-linked transactions, and integrated commerce platforms are reducing friction at checkout and creating more seamless experiences. Increasingly, consumers simply expect transactions to work quickly and effortlessly regardless of channel.
The payment itself is becoming increasingly invisible, reinforcing one of the quarter’s central themes: technology is evolving into underlying commerce infrastructure that consumers may rarely notice but increasingly depend upon.
Agentic Commerce Begins Taking Shape
One of the most forward-looking developments of the quarter was the emergence of agentic commerce.
Major payment companies including Visa and Mastercard announced initiatives designed to support AI-powered shopping agents that could eventually help consumers search, compare, and transact on their behalf.
Although the technology remains in its early stages, consumer adoption, trust, privacy concerns, and regulatory considerations continue to represent significant hurdles to widespread implementation.
However, the infrastructure is beginning to take shape.
This development is important because it suggests that artificial intelligence may eventually become a direct participant in commerce rather than simply a tool that supports it. Retailers may eventually need to optimize not only for human shoppers, but also for AI-powered shopping agents.
Even if widespread adoption remains years away, retailers would be wise to pay close attention to these developments.
Workforce Readiness Lags Technology Investment
One of the quarter’s most important observations may be the growing gap between technological investment and organizational readiness.
Retailers continue to accelerate investments in artificial intelligence and automation. However, many organizations continue to face challenges related to skills, implementation, and change management because technology adoption often moves faster than organizational capability.
This creates risk because retailers that invest heavily in technology without making corresponding investments in people, processes, and training may struggle to realize the full benefits of those investments.
The winners may not necessarily be the retailers that adopt the most technology, but the retailers that can successfully integrate technology into their organizations. The productivity gains promised by artificial intelligence and automation ultimately depend on organizational readiness.
Cross-Border Commerce Infrastructure Continues to Improve
Cross-border commerce continues to benefit from improvements in payments and technology infrastructure, giving retailers access to tools that simplify international transactions and support global commerce.
At the same time, challenges remain. Currency volatility, regulation, tariffs, and geopolitical uncertainty continue to create complexity for retailers operating internationally.
Technology can help reduce friction, but it cannot eliminate broader structural challenges. Cross-border commerce is becoming easier to facilitate, even if it remains increasingly complex to navigate.
Editor’s Take
Q2 2026 confirmed that Canadian retail technology is increasingly becoming infrastructure.
Artificial intelligence is moving from experimentation into everyday retail operations, while payments, loyalty, and commerce platforms are becoming increasingly interconnected. Retailers are seeking integrated ecosystems that can improve customer experiences while also driving operational efficiency.
Loyalty programs and first-party data have become some of the industry’s most valuable strategic assets, and convenience and delivery are increasingly expected rather than differentiated. At the same time, the emergence of agentic commerce suggests that another major technological shift may already be beginning.
Perhaps the most important lesson from the quarter is that technology alone is no longer enough. Competitive advantage increasingly depends on how effectively retailers integrate data, payments, loyalty, artificial intelligence, and operations into cohesive ecosystems.
The next phase of retail technology may be defined less by individual innovations and more by how successfully retailers connect these capabilities into seamless infrastructure.
Retail technology is increasingly becoming invisible infrastructure that shapes nearly every aspect of the customer experience and retail operation—and the retailers that can successfully integrate these systems may gain an increasingly significant competitive advantage.
Canada’s footwear and apparel sector is navigating a period of significant change, shaped by shifting consumer expectations, evolving global trade dynamics, technological innovation, and changing retail strategies. Throughout these changes, the Association of Footwear and Apparel Canada (AFA Canada) has continued to play an important role in bringing the industry together and supporting businesses across the country.
Save the Date: United in Style – Spring/Summer 2027
AFA Canada’s next industry gathering, United in Style – Spring/Summer 2027, will take place:
August 11–13, 2026 Toronto Congress Centre – South Building, Hall D 650 Dixon Road, Toronto, Ontario
The event is positioned as Canada’s national footwear, apparel and accessory marketplace, bringing together retailers, brands, manufacturers, agents, and industry partners from across the country for three days of business development, networking, trend discovery, and relationship building.
A Longstanding Industry Resource
Founded in 1967, AFA Canada has spent decades supporting footwear and apparel companies through education, industry intelligence, networking opportunities, and advocacy on issues affecting the Canadian marketplace. The Association also serves as a forum where industry leaders can exchange ideas, discuss emerging challenges, and collaborate on solutions that help strengthen Canada’s fashion and retail ecosystem.
AFA Canada’s membership spans retailers, brands, manufacturers, distributors, agents, and service providers, creating a broad network that reflects the diversity of Canada’s footwear and apparel sector.
As the retail landscape becomes increasingly complex, the value of industry collaboration has grown. Businesses are grappling with questions surrounding sourcing, sustainability, consumer behaviour, international trade, artificial intelligence, and the evolving role of physical retail. Organizations such as AFA Canada provide a space where industry participants can share ideas, discuss challenges, and identify opportunities together.
Looking Ahead to Spring/Summer 2027
The August gathering will also provide an early look at themes expected to influence Spring/Summer 2027 collections. Industry observers are already pointing to lighter palettes, expressive colours, and versatile product assortments that reflect changing consumer lifestyles and a growing desire for optimism and individuality.
Retailers attending the event will have opportunities to engage with industry partners, discover new collections, preview emerging trends, and gain insights that can help inform future merchandising and business strategies. AFA says the show will feature hundreds of brands and provide opportunities to build relationships and place orders for upcoming seasons.
Collaboration Remains Essential
Beyond showcasing products and trends, the event provides an environment for meaningful business conversations. Attendees can strengthen existing relationships, develop new partnerships, and exchange ideas with peers from across the industry.
For many participants, the value of the event extends well beyond the show floor. It serves as a reminder that while the industry faces ongoing change, collaboration and shared knowledge remain powerful tools for growth and resilience.
As AFA Canada prepares to welcome the industry this August, the Association remains focused on fostering connections, encouraging collaboration, and helping Canada’s footwear and apparel sector navigate an increasingly dynamic retail environment.
Persistent food inflation is changing how consumers approach the grocery aisle, with new survey findings pointing to more price comparison, increased private-label purchasing and broader efforts to stretch household food budgets.
A new study from Milesopedia found that 96% of respondents believed their grocery bills had increased over the previous 12 months, including 60.5% who said costs had increased significantly. Seven in 10 said they had changed their grocery shopping habits in response.
Among those surveyed, 71.1% said they were comparing prices between retailers more often, 39.1% reported buying more private-label or store-brand products, 34% were using coupons or discount applications, and 24.4% had reduced purchases in categories such as meat or fresh food.
Yet only 9.6% said they had changed their preferred retailer.
The combination points to a more deliberate grocery shopper. Consumers appear to be searching harder for value and shifting individual purchases while often maintaining an underlying preference for a particular retailer. For grocers, the competitive battle increasingly extends to individual categories, promotions and shopping trips.
The Milesopedia survey included 203 respondents and was conducted between June 1 and 8, 2026. Participants were recruited through the company’s newsletter and private Facebook community, and approximately 83% were based in Quebec.
The study used a non-probability sample and is not representative of the Canadian population as a whole. Respondents were also more familiar with loyalty and rewards programs than the general population. The findings nevertheless provide a timely snapshot of a highly engaged group actively looking for ways to manage grocery spending.
Grocery Inflation Keeps Pressure on Household Budgets
The findings come as grocery prices continue to place pressure on Canadian households.
Statistics Canada reported that prices for food purchased from stores increased 4.3% year over year in May 2026. Overall food prices were up 3.8%, while the Consumer Price Index rose 3.2%.
Some categories experienced steeper increases. Meat prices rose 6% from a year earlier, while fresh vegetable prices increased 9% and fresh fruit prices rose 5.3%.
That backdrop helps explain the level of concern captured by Milesopedia. More than three-quarters of respondents, 77.6%, said they were fairly or very concerned about further grocery price increases in the coming months.
The findings suggest affordability pressures are shaping decisions well before consumers reach the checkout. Shoppers are examining offers more closely, reconsidering product choices and looking for savings across several parts of the grocery trip.
Price Comparison Becomes More Common
The 71.1% of respondents who said they were comparing prices between retailers more frequently is one of the clearest signs of changing behaviour.
Digital flyers, loyalty applications, coupons and retailer promotions give consumers more ways to assess competing offers. Sustained inflation provides a stronger reason to use those tools regularly.
The result can be a more fragmented shopping pattern. A household may still conduct its principal weekly shop at one retailer while buying selected categories elsewhere, stocking up when products go on promotion or visiting a discount banner for part of the basket.
That makes the preferred-retailer finding particularly interesting. Only 9.6% said they had changed their preferred retailer, despite the much larger share comparing prices more often.
The two findings are not necessarily contradictory. A shopper can favour one banner while becoming more flexible about individual purchases. In practice, retailer preference may remain intact even as a household distributes more of its grocery spending across competing stores and formats.
For grocers, that puts greater pressure on each category and trip. Keeping a customer does not guarantee keeping the same portion of the household grocery budget.
Private Label Gains Further Momentum
Private label is among the clearest beneficiaries of the search for value.
Milesopedia found that 39.1% of respondents were buying more store-brand products, aligning with a broader shift Retail Insider has documented across the Canadian grocery sector.
In a June 2026 interview with Retail Insider, veteran grocery executive Michael Commisso described the importance of private label in direct terms.
“Private label is huge,” Commisso said.
His assessment reflects decades of experience in the Canadian grocery industry. Commisso has held senior roles with Loblaw, Sobeys and Longo’s, among others, giving him a close view of how grocery assortments and consumer expectations have evolved.
He told Retail Insider that private label has moved well beyond its earlier association with basic, low-cost substitutes for national brands. Retailers have built increasingly sophisticated own-brand programs serving different price points, categories and consumer needs.
That evolution carries particular weight when household budgets are under pressure. A strong private-label assortment can give shoppers a lower-priced option without forcing them to leave the retailer.
Canadian grocers have invested heavily in these programs. Loblaw has extensive portfolios around President’s Choice and No Name, while other grocery retailers have expanded exclusive brands and retailer-owned product lines across a wide range of categories.
The trend has been building for years. In 2025, Elliot Morris, Partner at EY Canada, told Retail Insider that twice as many Canadian consumers were buying private-label brands as five years earlier. He also pointed to research indicating that roughly 40% of consumers who tried private label did not intend to return to traditional brands.
Morris told Retail Insider again in May 2026 that retailers were continuing to expand private-label penetration and increase their own-brand assortments as consumers prioritized value.
The significance reaches beyond a short-term search for cheaper products. Once shoppers become comfortable with the quality of a store brand, the national brand may no longer be the automatic choice.
For grocers, private label can address affordability concerns while strengthening assortment differentiation and retaining purchases that might otherwise move to a competing banner.
Loyalty Programs Face a Value Test
The Milesopedia study also reveals a notable gap between loyalty-program usage and the financial relief consumers believe those programs provide.
The survey audience is highly familiar with rewards. Some 93.9% of respondents said they knew grocery rewards programs fairly or very well, while 85% reported using a program every time they shopped for groceries.
Despite that engagement, nearly half, 49.5%, believed rewards programs offset very little or none of the increase in grocery prices. Only 7.1% believed rewards significantly reduced the impact.
The finding is particularly noteworthy given the profile of the sample. These are consumers generally more knowledgeable about points, rewards and related strategies than the wider population.
The results do not indicate that loyalty programs lack value. High participation suggests they remain deeply embedded in shopping behaviour, and consumers can benefit from points, personalized offers and member pricing.
The distinction lies in perceived impact. Many respondents appear to see value in participating while remaining unconvinced that the benefits meaningfully compensate for rising grocery costs.
For grocers, that gap matters. A loyalty ecosystem can support engagement and strengthen customer relationships, but sustained inflation may increase demand for savings that are immediate and easy to recognize.
What the Shift Means for Canadian Grocers
The broader picture is one of consumers drawing on several strategies at once.
They are comparing prices, increasing private-label purchases, using coupons and discount applications, and in some cases reducing purchases in categories where costs have become difficult to absorb.
That creates a more demanding competitive environment. A grocer can remain a shopper’s preferred banner while losing portions of the basket to a rival with a stronger promotion, a better price in a key category or a compelling private-label alternative.
Private label is likely to remain central to that contest. It gives retailers greater control over assortment and pricing while offering consumers options across multiple price points.
Loyalty programs face a different challenge. Participation remains high among the Milesopedia respondents, yet many do not believe rewards are doing much to counter rising grocery costs. Visible savings and relevant offers may therefore carry greater weight as households scrutinize spending.
The emerging grocery shopper is becoming more precise about where money goes, combining retailer preference with a willingness to compare prices, substitute products and move purchases.
For Canadian grocers, the challenge may be less about whether a customer formally switches allegiance and more about how much of each basket remains available to competitors.
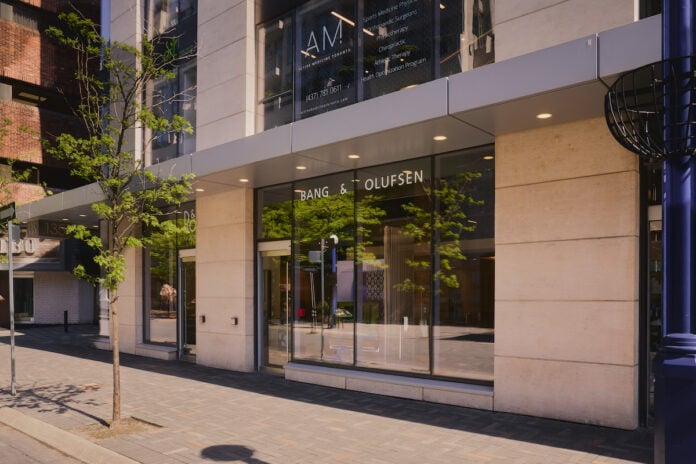
Bang & Olufsen at 135 Yorkville Avenue in Toronto. Image supplied
Bang & Olufsen has returned to Toronto’s luxury retail landscape with the opening of a new flagship in Yorkville, marking the Danish audio brand’s first dedicated store in the city since 2019 and underscoring its growing confidence in the Canadian market.
The 2,100-square-foot store, located at 135 Yorkville Avenue, introduces a destination retail environment where clients can experience Bang & Olufsen’s speakers, headphones, bespoke audio solutions, and Atelier customization program through private demonstrations and personalized consultations.
For Bang & Olufsen, the new flagship reflects a broader bet on Canada’s luxury consumer market, the continued relevance of physical retail, and the growing connection between premium technology, interior design, and high-end residential living.
Retail Insider first reported in February that Bang & Olufsen was preparing to return to Yorkville with a new Toronto store. The opening now brings that plan to life in one of Canada’s most important luxury shopping districts.
Yorkville as a Luxury Platform
Kevin Cheung, CEO of Landa Global Properties and owner of the Bang & Olufsen Toronto and Vancouver flagships, said Yorkville was a natural fit for the brand.
“Yorkville has long been recognized as Canada’s premier luxury retail and lifestyle district,” said Cheung. “It brings together high-end fashion, fine dining, luxury hospitality, art, and design in a way that naturally aligns with Bang & Olufsen’s brand values.”
He said Bang & Olufsen customers are not simply buying products. They are investing in craftsmanship, design, and experiences.
That positioning is important in Yorkville, where global luxury brands, affluent residents, international visitors, designers, architects, and business leaders converge. The neighbourhood has become Canada’s premier showcase for luxury retail, with brands increasingly using physical stores to create deeper relationships with clients.
Cheung said the opportunity at 135 Yorkville Avenue was particularly compelling because it allowed the brand to create a destination that reflects Bang & Olufsen’s elevated and immersive positioning.
Bang & Olufsen at 135 Yorkville Avenue in Toronto. Image supplied
A New Kind of Electronics Store
The Toronto flagship has been designed less like a traditional electronics showroom and more like a luxury residential environment.
The store features curated living settings, natural oak, wool fabrics, soft acoustic panels, aluminum details, rich textiles, and a palette inspired by understated Nordic tones. Heritage displays throughout the space reference Bang & Olufsen’s 100-year history in audio and design.
A dedicated VIP Room offers a more intimate setting for demonstrations of the brand’s flagship products and Atelier service, allowing customers to explore custom colours, materials, finishes, and configurations.
Cheung said luxury consumers now expect more than a transaction when they visit a store.
“The traditional retail model of displaying products on shelves is becoming less relevant for luxury categories,” he said. “Customers increasingly conduct research online before visiting a store, which means that the role of physical retail has shifted from information delivery to experience creation.”
That shift is especially important for premium audio, where the product cannot be fully understood through specifications or images.
“Sound is inherently experiential,” Cheung said. “A customer can read about acoustic performance online, but they need to physically experience the emotional impact of exceptional sound reproduction.”
Bang & Olufsen at 135 Yorkville Avenue in Toronto. Image supplied
Canada’s Growing Role
Cheung said Canada represents an increasingly important market for Bang & Olufsen in North America.
Canadian consumers, he said, have a strong appreciation for premium design, craftsmanship, and high-performance products. Toronto and Vancouver, in particular, are global luxury markets with sophisticated consumers who value authenticity, personalization, and long-term quality.
The Toronto flagship also fits within Bang & Olufsen’s broader North American retail expansion. The brand has recently opened locations in San Francisco and Los Angeles, with more stores planned in California and New York later in 2026.
For Cheung, the Canadian opportunity extends well beyond traditional retail.
Bang & Olufsen at 135 Yorkville Avenue in Toronto. Image supplied
Luxury Homes Become a Growth Channel
One of the fastest-growing parts of the business is custom home integration, according to Cheung.
Luxury homeowners increasingly expect technology to integrate seamlessly into their homes without compromising aesthetics. That has created growing demand from custom home builders, architects, interior designers, luxury developers, and commercial clients.
In Vancouver, Cheung said Bang & Olufsen has worked with leading developers including Landa Global Properties, Bosa Properties, and Aspac Developments to incorporate Bang & Olufsen and Beohome smart home solutions into premium residential projects.
His perspective is notable because he is both a luxury real estate developer and the owner of the brand’s Toronto and Vancouver flagships. That gives Bang & Olufsen’s Canadian retail strategy a direct connection to the country’s high-end residential market.
“We believe that beautiful sound should be part of the luxury living experience from the very beginning,” Cheung said.
The same approach will now be brought to Toronto, where luxury condominiums, custom homes, hospitality projects, and design-driven residential developments continue to shape the market.
Bang & Olufsen at 135 Yorkville Avenue in Toronto. Image supplied
Personalization Takes Centre Stage
Customization is also becoming a larger part of the luxury audio experience.
Through Bang & Olufsen Atelier, clients can select materials, finishes, colours, and design details to create products that reflect their personal taste and interiors.
Cheung said Canadian customers are gravitating toward natural and timeless materials such as oak, walnut, aluminum, and premium textiles. Popular colours include bronze, gold tones, charcoal, black anthracite, and soft neutrals, while some clients are choosing bolder bespoke finishes as statement pieces.
For luxury consumers, personalization turns the purchase into a collaborative design process.
“Our clients are no longer simply purchasing a product,” Cheung said. “They are commissioning a piece that reflects their personal taste and complements their environment.”
Physical Retail Still Matters
The opening comes as consumers increasingly arrive in stores having already researched products extensively online. For Bang & Olufsen, that has made physical retail more important, not less.
Cheung said the future of luxury retail will be experiential, educational, and relationship-driven. Stores will increasingly function as brand destinations where customers can experience products, receive expert guidance, attend events, and build long-term relationships.
For premium audio, that in-person experience is especially important. The emotional quality of sound, the feel of materials, and the integration of technology into a living environment are difficult to communicate online.
As luxury retail continues to blur the lines between shopping, design, hospitality, and residential living, Bang & Olufsen’s Yorkville flagship offers a glimpse into the future of premium consumer electronics retail — one built around experiences, personalization, and long-term relationships rather than traditional showrooms.
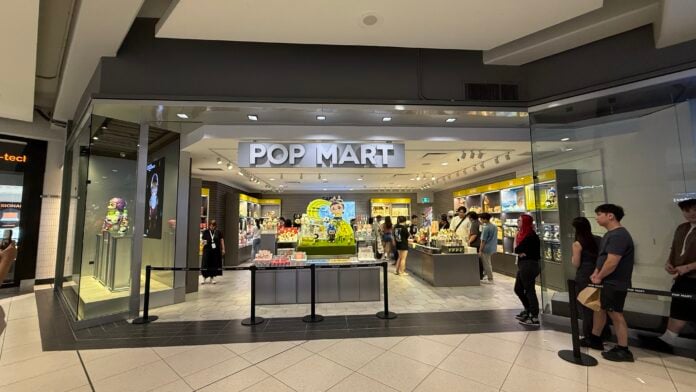
Pop Mart, CF Toronto Eaton Centre. Photo: Craig Patterson
Pop Mart is moving quickly to expand in Canada after stronger-than-expected demand at its early stores, with the global character-based entertainment company confirming that it now has 10 Canadian leases signed or committed.
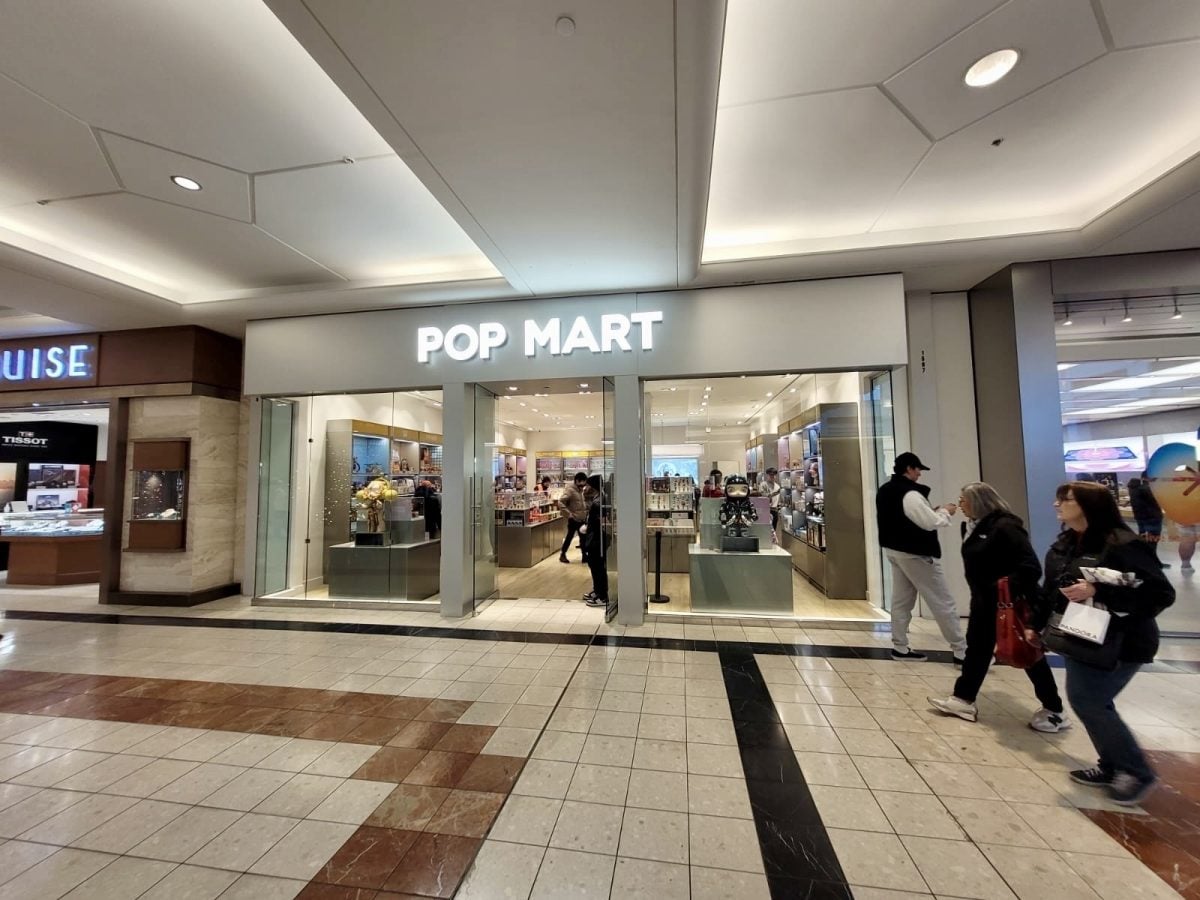
The momentum was visible in downtown Toronto over the Canada Day weekend. Pop Mart opened its new CF Toronto Eaton Centre store on Friday, July 3, and when Retail Insider visited the following day, customers were lined up along the mall corridor waiting to enter.
The retailer, known for collectible designer toys and character IP including Labubu and The Monsters, entered Canada with its first permanent store at CF Richmond Centre in Metro Vancouver. Consumer response has since exceeded initial expectations, creating early product allocation pressure and reinforcing Canada as a priority market.
“Canadian consumers have really shown out for Pop Mart, and we are truly humbled by their support,” said Valen Tam, Head of Real Estate for Pop Mart in Canada. “It is not easy to enter a new national market, but we have seen performance exceeding initial expectations at our physical stores, to the point of causing early allocation issues.”
Tam said the company is working to bring more of its characters and products within reach of Canadians as it builds out a larger national network.
Pop Mart, CF Toronto Eaton Centre. Photo: Craig Patterson
The Canadian growth comes as Pop Mart continues to expand globally. The company reported revenue of RMB 37.12 billion in 2025, up 184.7 per cent year-over-year, with international markets becoming an increasingly important part of the business. The Americas have emerged as a major growth region for Pop Mart as the company expands its physical store network and builds the global reach of its character portfolio.
For Canada, Tam said the opportunity is rooted in both consumer response and the country’s cultural makeup.
“By its very essence, Canada is a perfect home for Pop Mart,” he said. “It is a melting pot of cultures and its societal composition mirrors the many different characters in the Pop Mart collection who have come together under one umbrella, despite each having very distinct appearances, backgrounds, aspirations and stories.”
Premium Shopping Centres Anchor the Canadian Strategy
Pop Mart’s Canadian expansion is being shaped around premium shopping centres, where the company says its design standards and experiential approach can be fully expressed.
Valen Tam
Cadillac Fairview has played a notable role in the brand’s early growth in Canada. Pop Mart opened its first Canadian store at CF Richmond Centre, while the new CF Toronto Eaton Centre location places the company in one of the country’s highest-profile urban shopping destinations.
“The people there are what has made them a pleasure to partner with,” said Tam of Cadillac Fairview. “They have excellent leadership top-down who have been nothing but communicative, supportive and understanding.”
Tam said Cadillac Fairview was one of the first Canadian landlords to proactively partner with Pop Mart, a relationship that remains important as the company adds locations.
“We opened our very first Canadian store at CF Richmond Centre,” he said. “As our landlord partner there, Cadillac Fairview was one of the first Canadian landlords to proactively partner with us, which is something we will always appreciate and hold dear. We are looking forward to further developing the relationship.”
Pop Mart’s Canadian real estate rollout is being supported by Aurora Retail Group, whose Co-CEO Jeff Berkowitz has been involved in representing the brand as it expands into major Canadian shopping centres.
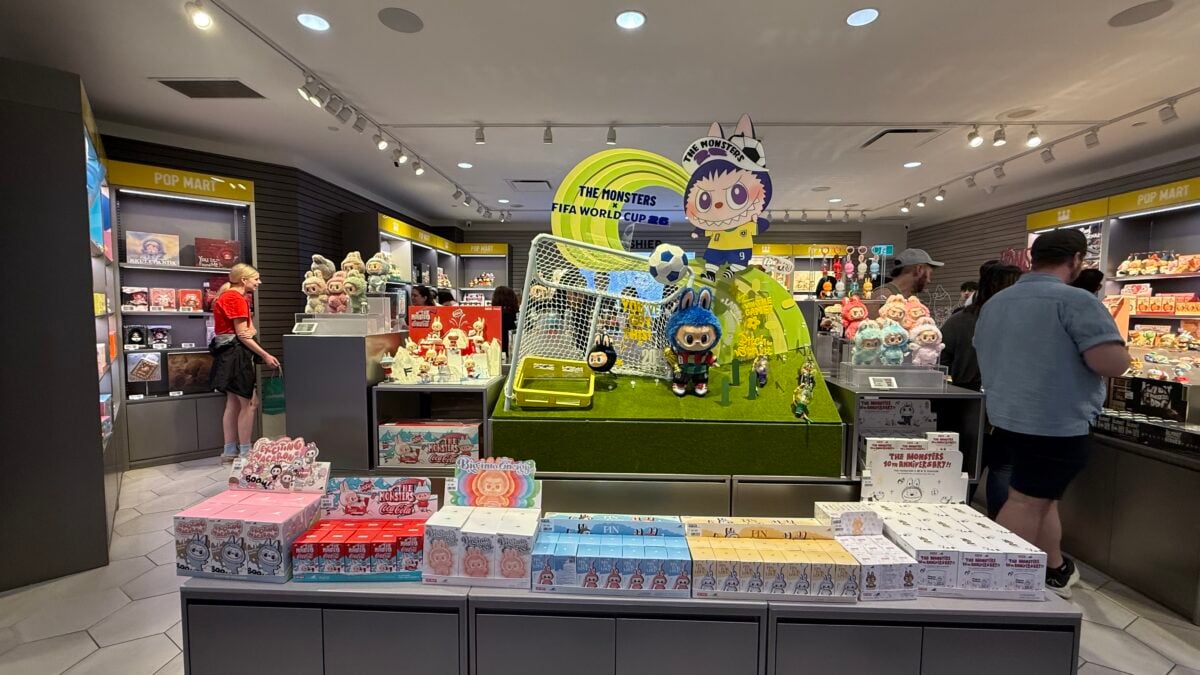
For Pop Mart, real estate is closely tied to brand execution. At CF Toronto Eaton Centre, the store uses illuminated perimeter displays, central character installations, digital screens and changing product presentations to create a highly visual environment around the company’s different IP.
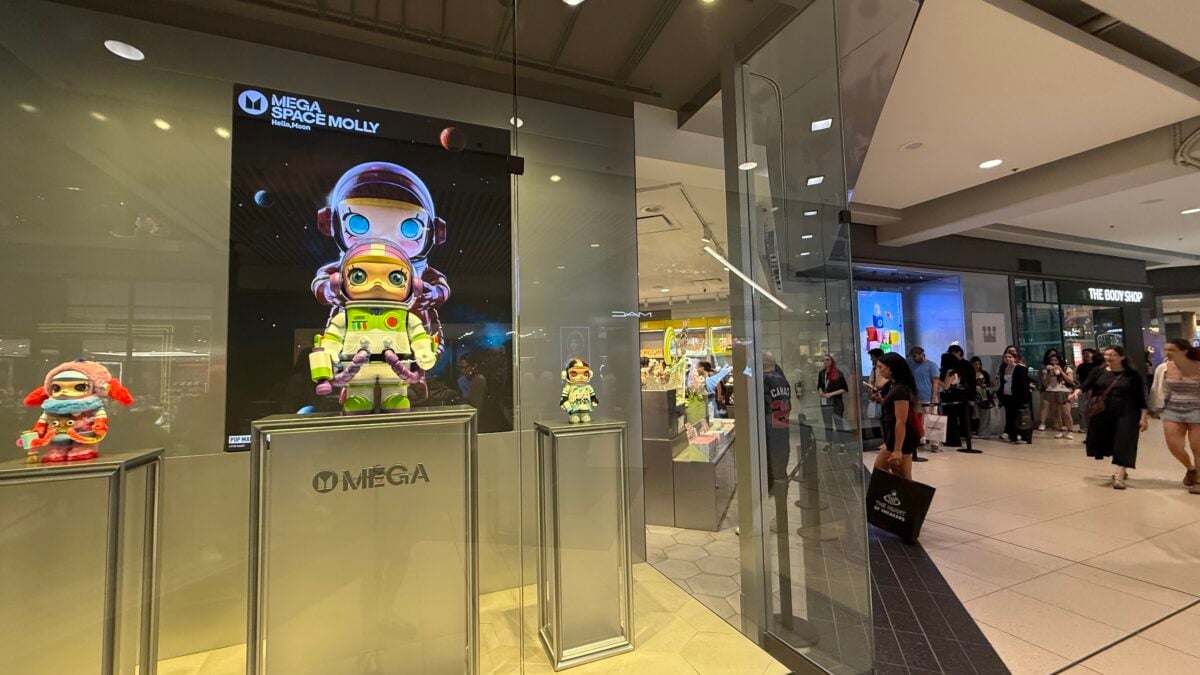
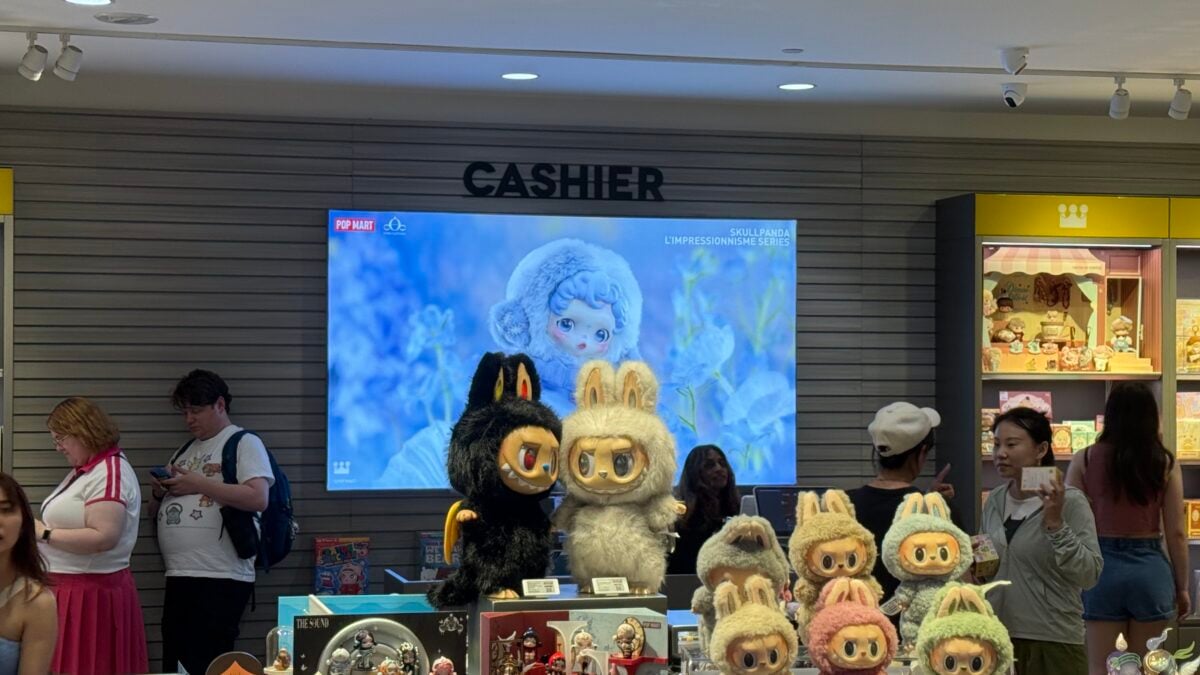
During Retail Insider’s visit, a prominent window installation featured MEGA SPACE MOLLY, while a central in-store display highlighted The Monsters’ FIFA World Cup 26 collaboration. Labubu plush characters were also prominently merchandised near the cashier and throughout the store.
Tam said Pop Mart follows strict global standards around store design, lighting, millwork and visual merchandising.
“We uphold a very strict global design standard at Pop Mart,” he said. “We are meticulous with our store design, lighting, millwork and visual merchandising. Therefore, premium shopping centres, where this is expected of retailers, are natural homes for us.”
Design Standards Shape Site Selection
Pop Mart’s site selection process is driven by more than market demand. Tam said each location must support the company’s design requirements and allow for the type of customer journey the brand wants to create.
“When selecting store locations, we evaluate by ensuring the space conforms to our design standards and has a layout that lends itself toward a design which can deliver the kind of unobstructive customer journey we strive to deliver,” said Tam.
The same thinking informs how Pop Mart approaches flagships. While standard locations must meet the company’s global design system, flagship stores give the brand room to create more localized and ambitious retail environments.
“Flagship stores give us an opportunity to go above and beyond,” said Tam. “We step outside our conventional boundaries to amalgamate the cultures of the block, the city and Pop Mart into a re-imagined, one-of-a-kind unique design expression.”
Pop Mart, CF Toronto Eaton Centre. Photo: Craig Patterson
10 Canadian Leases Signed or Committed
Tam confirmed that Pop Mart has 10 Canadian leases signed or committed as part of its expansion strategy.
The company is not yet providing a long-term store count target for Canada, although Tam said early support suggests significant runway.
“I can’t provide an estimate right this minute, but seeing the support from the market so far, it looks like we might just have to be everywhere,” he said. “Jokes aside, our vision is not fixated on the quantity of stores but the quality of each. We want to build only stores that we can be proud of, and then maintain consistent and joyous consumer experiences.”
Tam said a primary goal is to “drastically increase Canadians’ accessibility” to Pop Mart.
That could eventually take the company into multiple regions across the country. Tam said Pop Mart wants to be in every province, while acknowledging that growth will depend on the availability of suitable real estate.
Quebec, the GTA and Vancouver Eyed for Growth
Quebec is expected to play a meaningful role in Pop Mart’s Canadian strategy.
“Absolutely,” said Tam when asked whether Quebec will be part of the company’s growth plans. “Quebec is beautiful and the home of incredible culture. We are already educating ourselves and prepping to enter the market with the help of our global team and partners. It is a critical market for us, and not an endeavour we are taking lightly.”
The Greater Toronto Area is also being evaluated for additional opportunities. Pop Mart already has a presence at Toronto Premium Outlets and now at CF Toronto Eaton Centre, while Tam said the wider region could support more stores.
“The GTA is a sprawling metropolis and we would be remiss not to look hard at each of the many municipalities that comprise it,” he said. “We are actively working with our landlord partners to explore opportunities.”
Greater Vancouver remains another priority. Pop Mart opened two of its earliest Canadian stores in the region, where the brand saw strong consumer response from the outset.
“Two of our earliest stores opened in Greater Vancouver, and to astounding support,” said Tam. “We are still far from serving Vancouver well at the moment and are actively measuring opportunities.”
Tam said the company is willing to look broadly across the country as opportunities emerge.
“We will go wherever our incredible Canadian landlords take us,” he said. “We want to be in every province, but everything is subject to availability.”
Pop Mart, CF Toronto Eaton Centre. Photo: Craig Patterson
Labubu Opens the Door to a Larger Character Universe
Pop Mart’s Canadian growth is taking place as Labubu has become one of the most recognizable collectible characters globally.
Labubu, part of The Monsters character universe created by artist Kasing Lung, has helped bring Pop Mart to a wider audience through plush toys, collectible figures, social media visibility and collaborations. Pop Mart and Sony Pictures are also developing a Labubu feature film, extending the character’s reach further into entertainment.
Tam said Labubu has become a globally recognized icon, while emphasizing that Canadian interest extends well beyond a single character.
“The rest of our characters have all seen incredible support in Canada as well, certainly an ode to how diverse the Canadian populace is,” he said. “We invite customers to come see our stores or surf our many digital platforms to learn more about each.”
That breadth was visible at CF Toronto Eaton Centre. The store’s mix of MEGA SPACE MOLLY, Labubu and other character worlds, along with the prominent FIFA World Cup 26-themed The Monsters installation, illustrated how Pop Mart uses rotating visual presentations and partnerships to encourage discovery across its broader portfolio.
Tam described Pop Mart as a pop culture entertainment company, with stores acting as physical gateways into its character worlds.
“Behind every character and product line is a heartfelt story and the passionate brush strokes of their artists,” he said. “There is genuine emotion that is hemmed into every design, and as time grows, the characters’ stories develop alongside the customer.”
Stores Built for Discovery and Repeat Visits
Experiential retail is integral to Pop Mart’s store strategy.
Tam said the company’s visual merchandising and operations teams work to create a thematic journey in stores, guiding customers from one character to the next. The approach is designed to encourage discovery and give consumers reasons to return as assortments and presentations evolve.
“At our stores, my colleagues in VM and operations work hard to lay out a thematic journey that takes our consumers from one character to the next,” he said.
The CF Toronto Eaton Centre store offered a clear example during Retail Insider’s visit. Product was presented through a mix of wall displays, central fixtures, character installations and digital content, while controlled entry helped manage the flow of customers into the space during the opening weekend.
Digital engagement also plays a central role. Social media has helped build awareness around characters such as Labubu, while Pop Mart’s online platforms keep consumers connected to product updates and brand activity between store visits.
“Online engagement works hand-in-hand with our physical stores,” said Tam. “While our stores deliver an irreplaceable in-person experience, our digital platforms provide customers with timely updates and round-the-clock access to Pop Mart.”
Pop Mart at CF Richmond Centre in Vancouver. Photo: Ritchie Po
Robo Shops, Activations and Larger Concepts Could Follow
Pop Mart’s Canadian growth could eventually extend beyond traditional stores.
The company operates Robo Shops and other formats internationally, and Tam said Canada could see additional concepts as the market develops.
“We are in the infancy stage of Pop Mart in Canada, but most people do not know that our founder and CEO, as well as many of our colleagues, have worked for over 15 years to bring Pop Mart to its current form,” said Tam. “We have so many ideas and so many learnings that we cannot wait to bring to the Canadian market.”
The company is also looking at opportunities for Canadian-exclusive merchandise, artist partnerships, collaborations, activations and events.
“Our president Larry, the IP team and marketing team are looking into exclusive artist partnerships, collaborations and activations,” said Tam. “They are meticulous in their work and these processes do take some time to set up, but we cannot wait to tell you more down the road.”
Larger-format concepts or flagship destinations could eventually arrive in Canada as well. Tam did not provide specifics, but when asked whether Canadian consumers could see concepts similar to larger destinations found in other markets, he indicated the possibility may be closer than expected.
“I cannot reveal anything yet but they may be coming much sooner than not,” he said.
Future store sizes will vary depending on the market and real estate availability.
Building a Long-Term Canadian Presence
Looking ahead five years, Tam said success in Canada will be measured by more than store count.
The goal, he said, is to create stores that generate excitement for consumers while building a sustainable operating culture for Pop Mart’s teams.
“If we are able to keep lighting up the faces of Canadians when they see our stores or characters, if we are able to keep bringing smiles and laughter into their lives, and if we are able to enrich the lives of not just our customers but also our unsung heroes, our staff on the frontlines and in the backrooms, then it would all be a worthwhile success to us,” said Tam.
He added that Pop Mart will continue reinvesting in its characters and brand while pursuing further innovation.
For Canadian shopping centres, the expansion brings another fast-growing international concept into the premium mall landscape. For Pop Mart, the early response suggests there is room to build a considerably larger network.
And at CF Toronto Eaton Centre, where customers were still lined up to enter on the store’s second day of operation, the next phase of that growth was already visible.
Summer travel isn’t disappearing, but many Canadians are scaling back their itineraries this year. A new survey of 1,068 Canadian consumers by Omnisend found that while 67% have travel plans this summer, only 17% are taking a major trip involving flights or paid lodging. Instead, many are choosing more affordable alternatives:
21% say they’re taking a shorter or cheaper trip than originally planned
29% are sticking to day trips or local outings
12% plan to stay home altogether
Overall, 45% say they’ve postponed, shortened, downgraded, or entirely canceled a summer trip because of cost. Among those affected, gas prices were cited most often (47%), along with groceries and everyday bills (32%), as well as hotel and vacation rental costs (25%), according to the survey.
Marty Bauer
“Canadians aren’t giving up on summer. They’re giving up on the idea that a memorable vacation has to involve flights, hotels, or a hefty price tag. A vacation budget no longer exists in isolation – it’s competing with higher fuel costs, grocery bills and other everyday expenses that have become harder to ignore. So, people are becoming much more creative about finding breaks that fit their budget instead of abandoning the idea of a getaway altogether,” said Marty Bauer, Ecommerce Expert at Omnisend.
For many Canadians, the money saved by cutting back on travel is being redirected toward more immediate priorities. Twenty-six percent of those who are spending less on travel this year admit they need the money for essentials. Nearly half (46%) say they’re spending it on groceries, while 24% are putting it toward rent or mortgage payments. Another 26% are using it to pay down debt, added Omnisend.
“There was a time when skipping or downgrading a vacation might have meant spending that money on a home renovation or new furniture. Today, that’s increasingly not the case. Before families decide where they want to go, they’re deciding whether that money would be better spent putting food on the table, staying on top of bills or paying down debt. That’s a very different kind of spending than we typically associate with summer,” said Bauer.
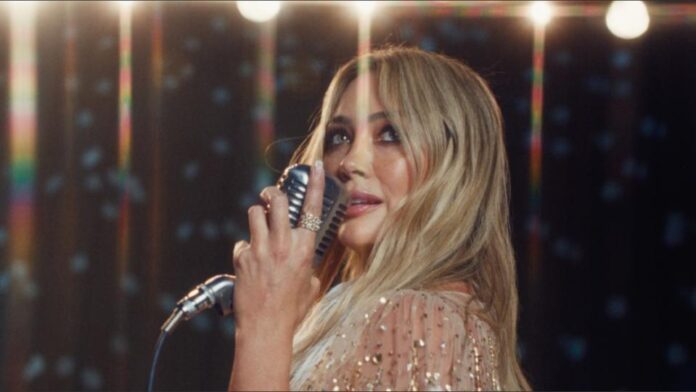
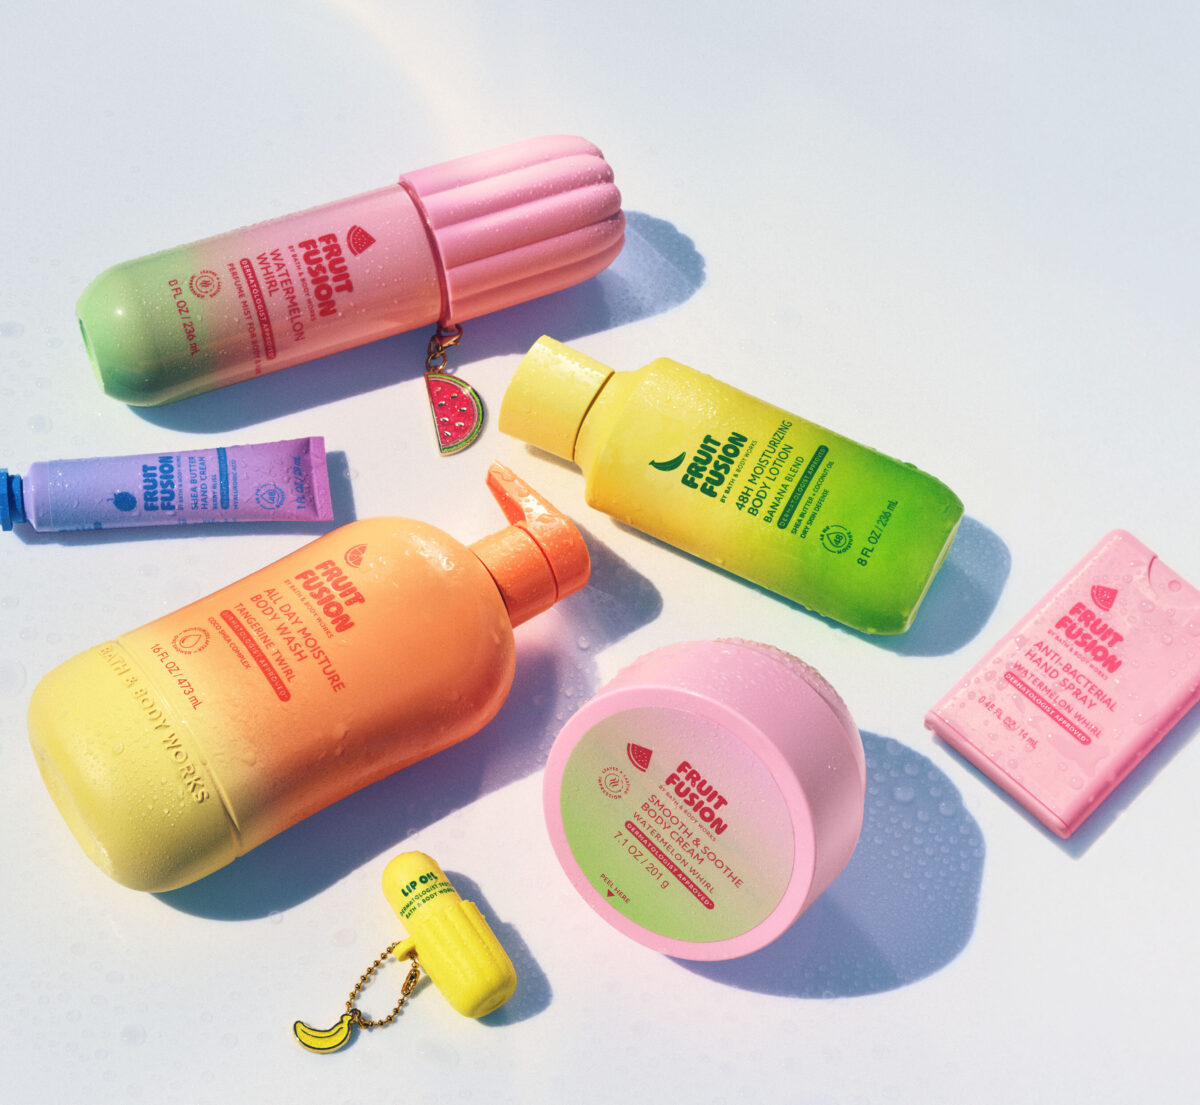
Bath & Body Workshas launched a new body care franchise called Fruit Fusion across Canada and the United States, pairing the product introduction with a long-term partnership that names actor and singer Hilary Duff as the brand’s campaign ambassador and creative partner.
The collection, available online and in stores, is part of the company’s Consumer First Formula strategy, which Bath & Body Works says is aimed at placing consumers at the centre of product development, design and marketing.
The launch represents a new product franchise for the retailer while also serving as a key initiative in its broader brand transformation efforts. Bath & Body Works said Fruit Fusion combines four new fragrances with a range of body care products designed to allow customers to build personalized routines through layering.
The initial lineup includes the fragrances Watermelon Whirl, Tangerine Twirl, Berry Bliss and Banana Blend. Products are available in formats including All Day Moisture Body Wash, Smooth & Soothe Body Cream, Perfume Mist for Body & Hair, 48H Moisturizing Body Lotion, Hand Cream, Mini Perfume Mist, Lip Oil, PocketSpray Hand Sanitizer and accessories. The collection is available in Canada and the United States, with prices ranging from $5.95 to $20.95.
Duff, a longtime Bath & Body Works customer, also worked with the company as a creative partner in developing the collection and campaign.
“For me, it’s always about feeling good in your own skin and choosing what works for you,” Duff said. “I look for products that work with my routine and provide real benefits. Fruit Fusion by Bath & Body Works fits into that perfectly. The scents are joyful, the products actually deliver, and it’s something I genuinely look forward to using.”
Bath & Body Works said Duff’s role extends beyond appearing in advertising. The company said she collaborated on the campaign’s creative direction and will feature the collection as part of her everyday routine across her Instagram and TikTok channels, where she reaches more than 30 million followers.
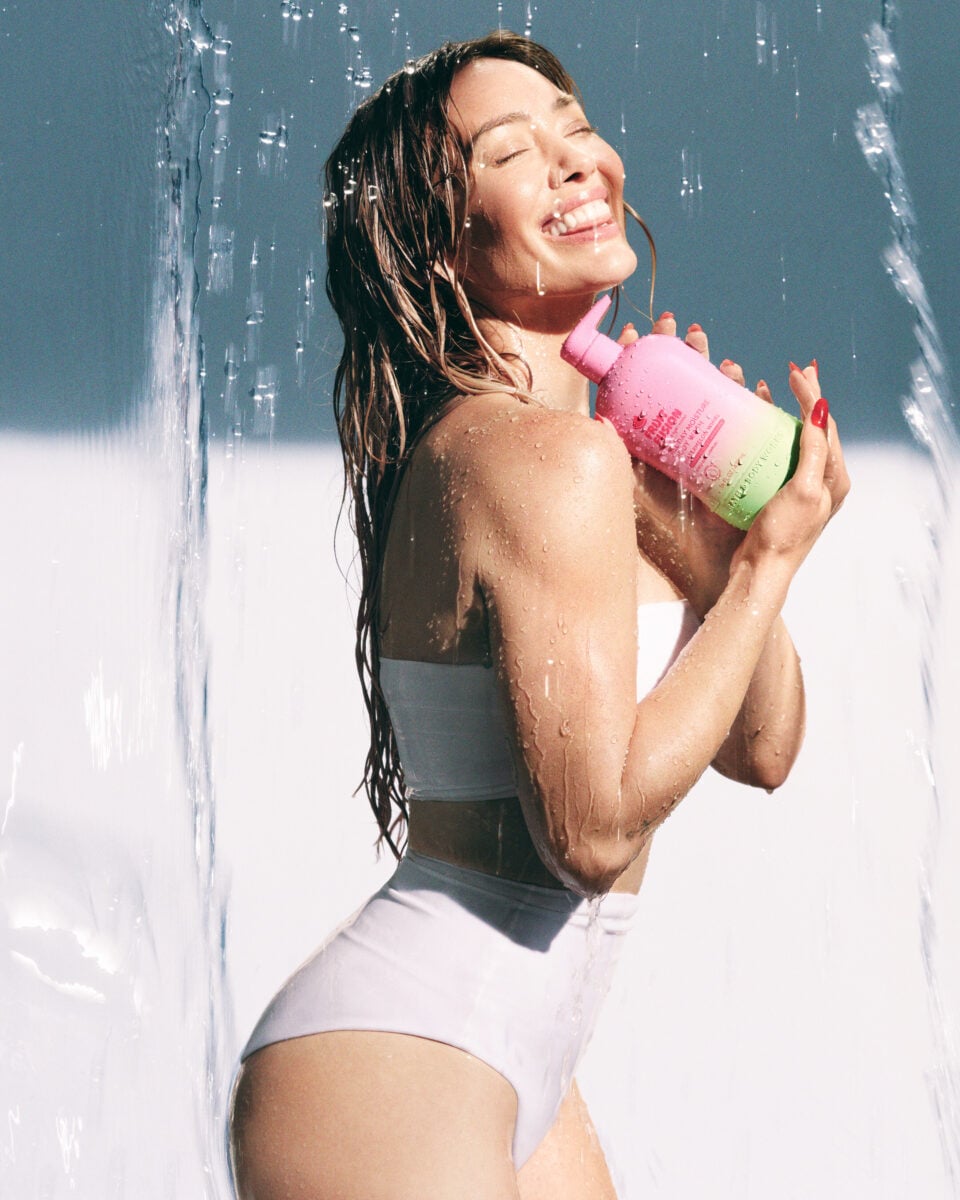
Bath & Body Works introduces its new “Fruit Fusion” collection featuring Hilary Duff as the campaign ambassador and creative partner. (CNW Group/Bath & Body Works Canada)
The company said the timing of the partnership coincides with Duff’s return to touring for the first time in 18 years and the release of a new album, while Bath & Body Works continues what it describes as its own brand evolution under new leadership.
Veronique Gabai
“Fruit Fusion is a clear example of our Consumer First Formula in action,” said Veronique Gabai, chief brand & product officer of Bath & Body Works. “We’re focused on creating high-quality, innovative products that deliver real performance and make people feel good, while showing up in ways that feel authentic and relevant. This launch brings that together, from innovation and design to the partnership with Hilary, in a way that genuinely connects with our customers.”
According to the company, the Fruit Fusion formulas are dermatologist-approved, vegan and made without sulfates, parabens and phthalates. The products combine perfumer-crafted fragrances with ingredients including shea butter, coconut oil and hyaluronic acid, which the company said help hydrate skin while maintaining its natural moisture barrier.
Bath & Body Works new Fruit Fusion collection. (CNW Group/Bath & Body Works Canada)
The launch also introduces new packaging for the brand, including redesigned bottles and soft-touch finishes, as part of the broader rollout.
Bath & Body Works said the campaign supporting Fruit Fusion is one of the most extensive marketing efforts in the company’s history, spanning multiple platforms and featuring Duff throughout.
The company said Fruit Fusion is intended to become a long-term product franchise, with additional fragrances and product formats planned over time as it continues to expand the line.
Bath & Body Works operates more than 1,900 stores across the United States and Canada, as well as more than 500 international locations, and sells its products online through BathandBodyWorks.ca.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published covering key developments in Canadian retail.
The Retail Insider “Grocery Report” examines how value is reshaping Canadian food retail, highlighting the rise of discount formats, enhanced fresh offerings, loyalty programs, and private label strategies. Lotus Capital expanded its retail platform with the purchase of a grocery-anchored shopping centre in Kelowna, emphasizing stable income from necessity-based retail and growth potential in Western Canada.
Retail Insider has released its latest Q2 2026 Canadian Grocery Retail Report, authored by Craig Patterson, examining how value is reshaping one of Canada’s most important retail sectors.
The report is part of Retail Insider Reports, a growing series designed to deliver executive-level insights across major retail sectors. Reports are available through the Retail Insider Report Hub.
This report examines the Canadian grocery retail sector, including supermarkets, discount grocers, specialty food retailers, convenience-oriented food retail, merchandising strategies, store expansion, competition, consumer purchasing trends and developments affecting food retail in Canada.
The Q2 report finds that Canadian grocery retail is increasingly being reorganized around value. Food inflation remains a defining pressure for consumers, discount formats continue to expand, digital tools are becoming more practical, and grocery-anchored real estate is attracting renewed investment from landlords and institutional owners.
General Themes
Discount grocery growth is structural: Empire, Loblaw and Metro continue investing in value-oriented formats as shoppers prioritize price and value perception.
Full-service grocers are under pressure: Traditional banners need to defend relevance through fresh, service, convenience, loyalty, prepared foods and sharper price perception.
Digital grocery is becoming more practical: AI, delivery partnerships and grocery technology are being used to support meal planning, fulfilment, savings and budget control.
Grocery real estate is gaining importance: Grocery is increasingly being used to anchor mixed-use projects, experiential food destinations and necessity-based retail environments.
Prepared foods are becoming more important: Grocers are using prepared meals and foodservice-style offerings to capture more meal occasions and higher-margin sales.
Product innovation remains targeted: Health, convenience, protein, dairy-free options and greenhouse-grown products continue to find opportunity, even as shoppers remain price-sensitive.
Inflation remains a major operating challenge: Food prices, produce volatility, freight costs and regional differences continue to affect pricing, assortment and promotional strategy.
GLP-1 drugs are an emerging demand risk: The report flags potential long-term impacts on snacks, confectionery, alcohol and impulse categories, while noting the trend should not be overstated.
Retail Insider Coverage
Retail Insider’s Q2 coverage points to discount grocery expansion as the clearest growth theme in the sector. Empire continues to prioritize FreshCo as a national growth vehicle, with 161 stores as of June 17, 2026, including 53 in Western Canada and 108 in Ontario. The company expects to open approximately 15 new FreshCo stores in fiscal 2027 across Western Canada, Ontario and Atlantic Canada. Loblaw’s No Frills banner also reached its 200th Ontario store during the quarter, reinforcing the strength of hard discount in the country’s largest grocery market.
The report also highlights the growing strategic role of grocery real estate. Nations Experience at Oakville Place, Loblaws Humbertown, Food World Plus in Mississauga and McEwan’s planned Bayview Village location show how grocery is being used to reposition major spaces, support mixed-use redevelopment, create food destinations and strengthen culturally specific retail offerings.
Industry Coverage
The broader industry read is that grocery value is no longer limited to shelf price. It is now shaping capital allocation, loyalty strategy, private label, digital tools, fulfilment models and real estate decisions. The report notes that Canadian grocery operators are moving into a more disciplined phase of omnichannel execution, with store-based picking, third-party delivery, click-and-collect and targeted digital tools taking priority over expensive automation-heavy models.
Grocery anchors also remain central to Canadian retail real estate. As department stores weaken and some discretionary categories face pressure, grocery continues to bring frequency and daily-needs traffic. The next phase is broader than traditional supermarket anchoring, with grocery appearing in mixed-use communities, food halls, cultural retail destinations, department store redevelopments, premium lifestyle centres and urban necessity-based portfolios.
Editor’s Take
The report’s central takeaway is that value has become the organizing principle of Canadian grocery retail. Discount growth is the most visible expression of that shift, but the bigger story is how value is influencing store formats, private label, loyalty, digital investment, real estate strategy and category management. At the same time, the sector is not becoming purely discount-driven. Premium, experiential and culturally specific grocery concepts continue to work where they match the trade area. That polarization may define the next phase of Canadian grocery competition.
Readers can access the full Q2 2026 Canadian Grocery: Value Reshapes the Market report, along with Retail Insider’s complete library of Industry Intelligence Reports, through the Retail Insider Report Hub. The collection provides executive-level analysis across Canada’s major retail sectors, helping retailers, landlords, developers, brands and investors stay informed on emerging trends and market developments.