Home Blog Page 120

Competition Bureau to investigate competition factors affecting food affordability

Greta Hoffman photo
Greta Hoffman photo

The Competition Bureau announced Tuesday it will undertake an “examination of competition across Canada’s food supply chain.”

Food prices have risen sharply in recent years, putting significant pressure on Canadian households. While many factors influence food prices, competition plays an important role in keeping prices in check and giving Canadians more choice, it explained.

The Bureau said its examination will look for potential competition issues in three key areas:

  • Production and processing, including how food is grown, caught, transformed and packaged;
  • Transportation and distribution, including how food moves to retailers across Canada; and
  • Retail pricing practices, including loyalty programs, pricing algorithms, shrinkflation and skimpflation.

The Bureau said it is seeking input from Canadians and organizations with experience in the food supply chain. They are invited to share their views through an online form by July 31. The Bureau said it will also meet with groups and hold roundtable discussions in the coming months to determine where competition is not working well, where there are barriers, and what could help improve competition.

The Bureau added it will publish a final report in spring 2027. The report will share findings and make recommendations to governments on how competition can be strengthened across the food supply chain.
Sylvain Charlebois
Dr. Sylvain Charlebois

“If the Competition Bureau wants to understand why food affordability remains a challenge in Canada, it needs to look beyond grocery store shelves. The biggest barriers to competition often exist upstream—in processing, distribution, transportation, and even local property controls that prevent new food retailers from entering markets. This broader examination is long overdue,” said Dr. Sylvain Charlebois is Senior Director of the Agri-Foods Analytics Lab at Dalhousie University in Halifax.

“Competition matters, but Canadians should not expect a silver bullet. Food prices are influenced by labour costs, regulations, productivity, currency fluctuations, climate events, and global market conditions. More competition can help, but affordability ultimately depends on building a more productive and competitive food system from farm to fork.

“The Bureau’s 2023 study concluded that Canada needs more grocery competition. This new examination recognizes an important reality: the problem isn’t just retail concentration. Canada’s food affordability challenge is rooted in an entire supply chain that has become less competitive over time.”

For more information on the examination and how to participate, visit the Competition Bureau’s website.
Jeanne Pratt
Jeanne Pratt

“The cost of food matters to all Canadians, and strong competition can help keep prices in check. Our examination builds on our earlier work in the retail grocery sector and will look at all parts of the food supply chain. If you have experience in any sector along that supply chain, we want to hear from you. Your input will help us find solutions that support competition and affordability,” said Jeanne Pratt, Interim Commissioner of Competition.

The Bureau said the examination builds on its 2023 retail grocery market study, Canada Needs More Grocery Competition.

“This is not a market study. It is a broader approach to understand where engagement from the Bureau is needed going forward, and where policymakers may be able to take action,” it said.

“The Bureau does not set prices. We examine whether markets are working competitively and whether barriers may be limiting competition.

“This examination is not a law enforcement investigation and is not about any specific complaint or allegation of wrongdoing. However, if the Bureau finds evidence of anti-competitive behaviour, it will investigate and take appropriate action.”

Bruce Winder, a retail analyst, said: “From what I understand, the retail part of the Canadian grocery industry was already studied from a competition perspective at length in 2023. Studying it again may waste resources and come off as performative.

“However, I do think that the upstream parts of the sector need to be reviewed. These parts include suppliers such as large global consumer packaged goods (CPG) firms. There has been significant consolidation on the vendor side over the last 20 years. Just a handful of food companies control most of the international market. These large global CPG firms generate significantly more margin than Canadian grocers. But the Bureau should also examine production, processing, transportation and distribution as well.
Bruce Winder
Bruce Winder

“If one does reflect on the retail side, Canada is one of a few markets where the big global grocery retailers (Walmart and Costco) already own about 1/3 of the market and have been growing. The retail side has razor thin margins (3-4% net ) and is already incredibly competitive. I think as a country we want to avoid a race to the bottom where innovation and employment would suffer.

“I have written much about surveillance pricing recently, especially in the grocery sector.  Any regulation would be a solution looking for a problem. The big three Canadian grocers have indicated publicly that they are not using it. Consumers would quickly find out and punish any offending grocer as a result. We also want to be careful we don’t get rid of loyalty programs and other incentives as a result of any proposed government intervention.”

George Minakakis, Founder and CEO of the Inception Retail Group, who lives in the Halton Region of Ontario, said he learned a few months ago that 20% of households experience food insecurity.

“In Toronto, it’s nearly 25%. While those statistics are concerning, they do not automatically point to a single cause, nor do they necessarily indicate a lack of competition among grocers or suppliers,” he said.
“It is prudent for the Competition Bureau to examine whether competitive factors are affecting food affordability and whether consumers are receiving the full benefits of a competitive marketplace. 

“Food affordability is influenced by a complex ecosystem of factors, including inflation, supply chains, labour costs, transportation, energy, taxation, consumer demand, and market competition. Since COVID, many of these cost pressures have created affordability challenges for households across the country.

“One area that warrants closer examination is how technology, data analytics, and loyalty programs influence pricing strategies and consumer purchasing behaviour. There is nothing inherently wrong with targeted promotions or personalized offers; they can create significant value for consumers and retailers alike. Yet, one question is: Are sophisticated tools like AI inadvertently changing how different customer segments experience food affordability?

“Whatever the findings, food affordability is ultimately an economic issue with multiple factors beyond a grocer’s control.”

More from Retail Insider:
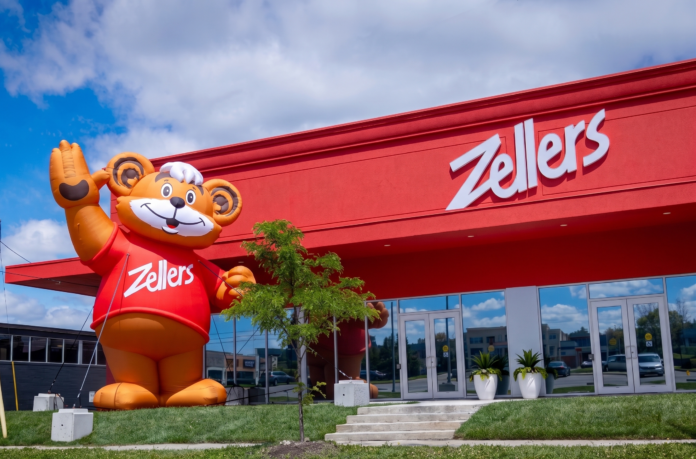
Zellers Brings Back Diner Experience and Kiddie Rides as Toronto Store Opening Nears

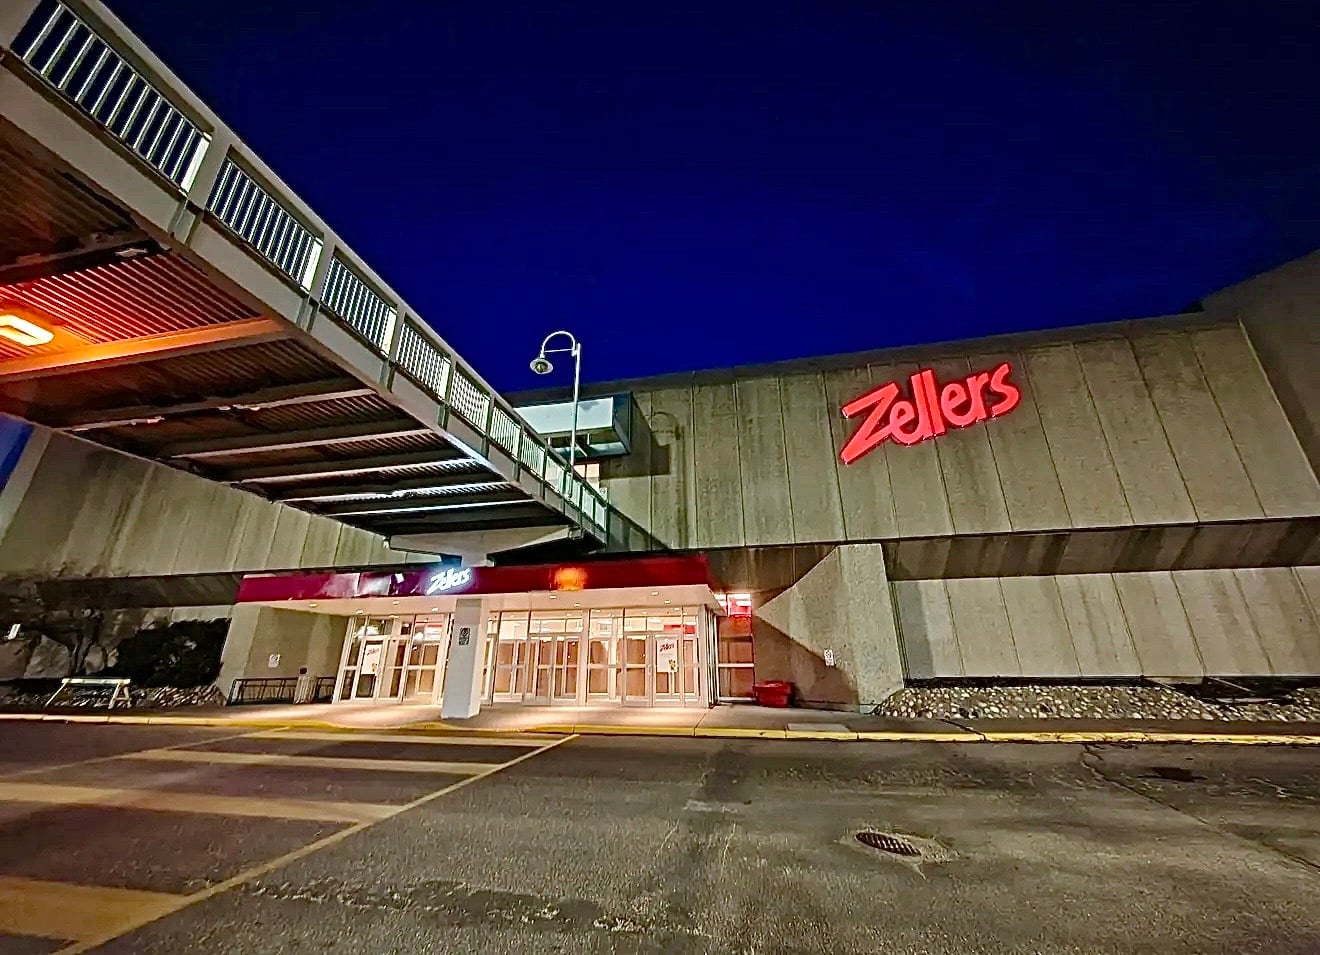
Zellers store at 80 Orfus Road in Toronto. Photo supplied

Since Zellers returned to the Canadian retail landscape, two requests have surfaced repeatedly from customers: bring back the diner and bring back the kiddie rides.

As the retailer prepares to open its new standalone Toronto store at 80 Orfus Road on Thursday June 18, both are making a comeback in new forms as the company continues to refine a retail concept shaped by customer feedback and positioned for expansion across Canada.

The 25,000-square-foot location will feature a new Zellers Diner on Wheels serving diner-inspired favourites, a kiddie ride reminiscent of those found in legacy Zellers stores, complimentary Zellers Ice Pops, collectible giveaways and a 25-foot inflatable Zeddy Bear outside the building.

According to Zellers Chief Operating Officer Joey Benitah, customer feedback continues to play an important role in shaping the evolution of the retailer’s standalone-store concept.

“We’ve always said we’ll be listening closely and adapting quickly, and that’s exactly what we’re doing,” he said in an exclusive interview with Retail Insider.

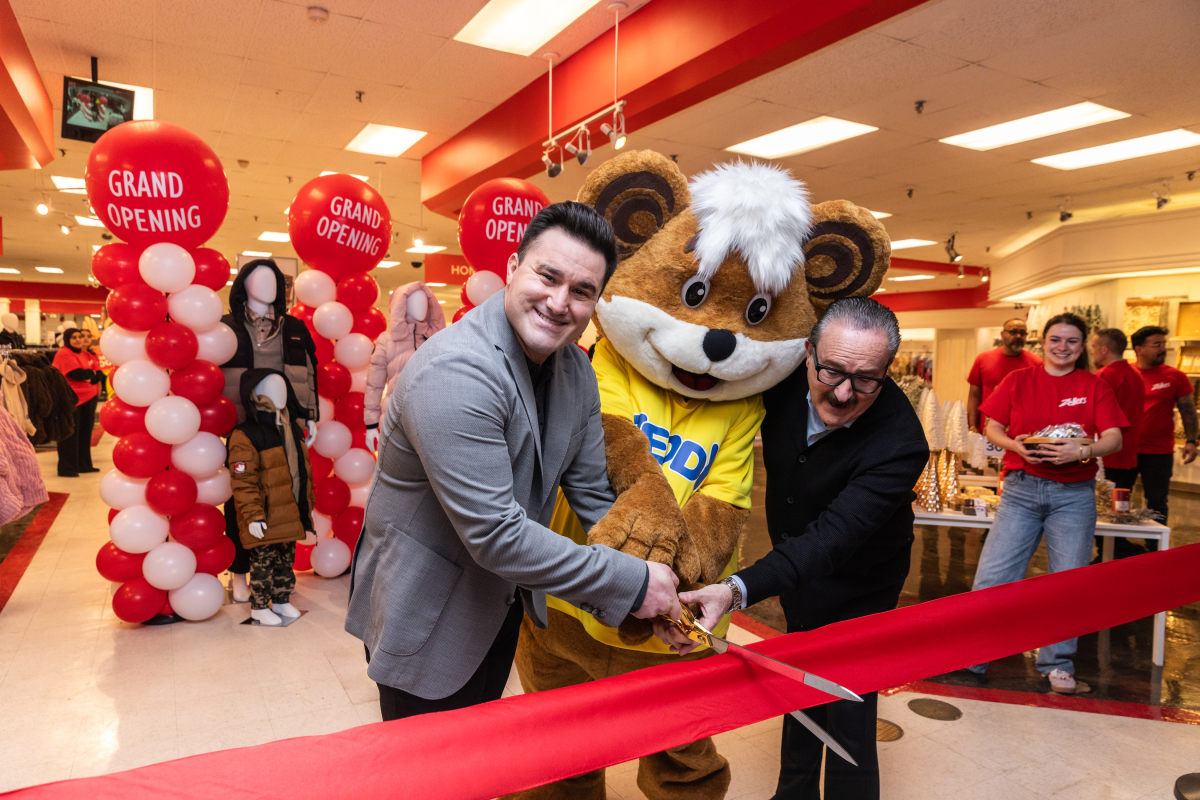
Joey Benitah, Zeddy Mascot, Isaac Benitah, at the grand opening of Zellers at Londonderry Mall in Edmonton. Photo supplied

The Diner Returns in a New Form

Among the most frequently discussed aspects of the Zellers brand has been the fate of its iconic diner.

The in-store restaurants became a memorable part of family shopping trips for generations of Canadians. Long after the original Zellers chain disappeared, consumers continued to discuss favourite menu items and speculate about whether the diner experience might one day return. Similar conversations resurfaced when Hudson’s Bay reintroduced Zellers through its shop-in-shop concept in 2023.

Benitah said discussion about the diner has remained remarkably consistent throughout the brand’s revival, reflecting the lasting connection many Canadians still have with the restaurant experience.

“The diner has come up quite frequently,” he said.

While Zellers is not currently planning to introduce permanent restaurants, the company is launching a mobile diner concept that will debut during the Toronto opening before travelling to future store openings across Canada.

The Zellers Diner on Wheels will serve menu items inspired by the retailer’s restaurant heritage, including the Big Z Burger, Hot Gravy Chicken Sandwich, Chicken Fingers, Grilled Cheese, and Gravy and Fries.

Benitah said the company’s focus remains on building a sustainable retail concept centred on its core merchandise categories, though he acknowledged that future possibilities remain open.

“In terms of a full-fledged diner, not the focus right now, but you never know in the future,” he said.

The food truck will operate throughout the opening weekend and is expected to become a regular feature at future store launches. Toronto is the first of two standalone Ontario openings announced by the retailer, with a location at Tecumseh Mall in Windsor expected to open later this summer. The Diner on Wheels is also expected to appear at future store openings.

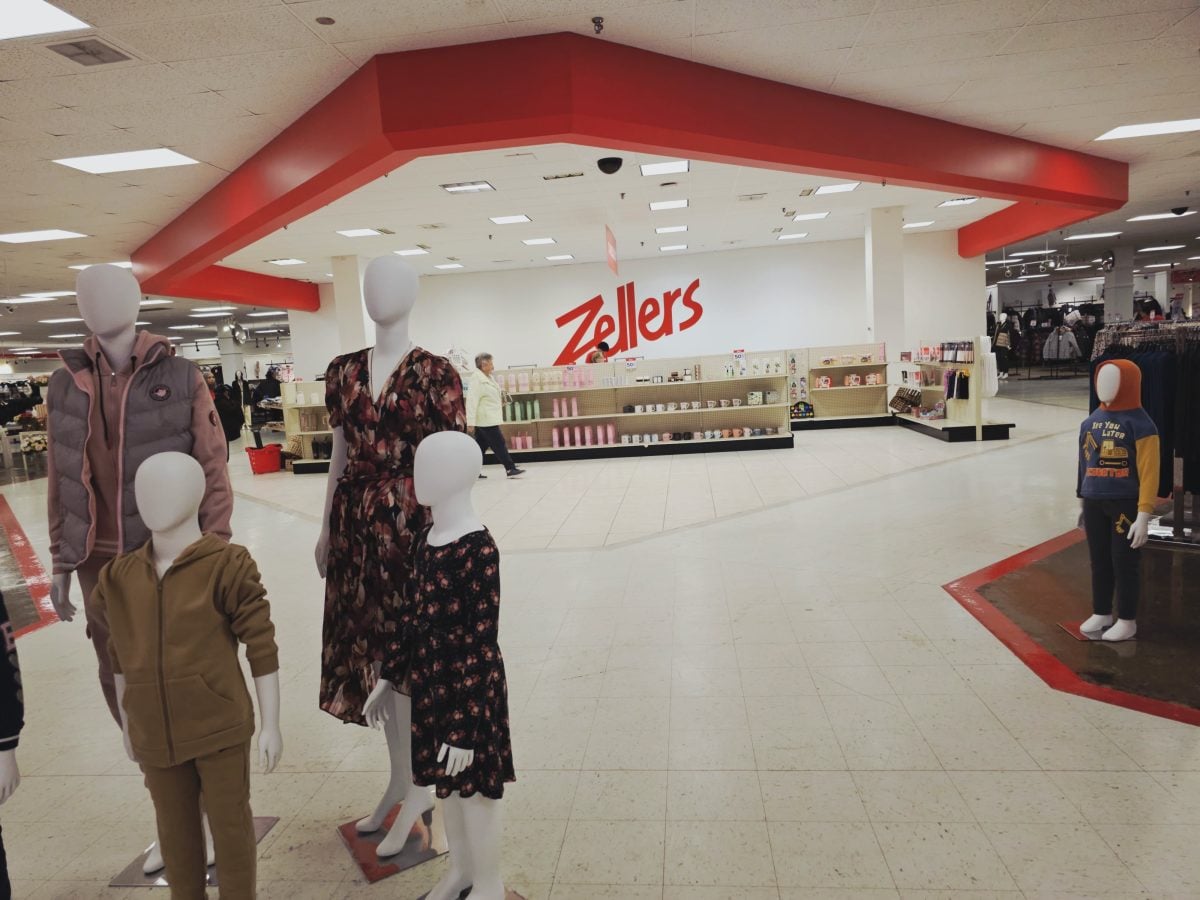
Zellers at Londonderry Mall in Edmonton. Photo: Christa Patterson

Bringing Back Family Experiences

The diner is not the only familiar experience returning.

The Toronto store will also feature a new kiddie ride, reviving a tradition that many Canadians remember from visits to Zellers stores decades ago. The ride, a red sports car with side-by-side seating, is the first in what the company says will be a broader rollout of kiddie rides across future locations.

Benitah said the rides are intended to bring back a small piece of the family-oriented shopping experience that many customers remember.

“I think it’s going to be tons of fun and bring back that little hit of nostalgia,” he said.

Outside the Toronto store, customers will be greeted by a 25-foot inflatable Zeddy Bear, creating a highly visible landmark ahead of opening day and serving as a tribute to one of Canada’s most recognizable retail mascots.

The opening celebrations will also include complimentary Zellers Ice Pops, water bottles and collectible giveaways while supplies last, including exclusive Zeddy keychains for the first customers through the doors.

Together, the activations represent an effort to reconnect shoppers with some of the experiences that helped define the Zellers brand while introducing younger consumers to a retailer that many know only through stories from parents and grandparents.

Customer Feedback Continues to Shape Zellers 3.0

The return of diner-inspired food and kiddie rides may be the most visible examples of customer feedback shaping the business, but they are far from the only ones.

Benitah said the company continues to adjust merchandise categories, brand partnerships and in-store experiences based on customer response.

One example is the toy category.

When the standalone concept was first being developed, Zellers was cautious about devoting significant space to toys because of the intense competition within the sector. Customer behaviour at the retailer’s first standalone location in Edmonton quickly changed that thinking.

“Toys was something that we weren’t so committed to initially, and we were hesitant because it’s a very challenging, very competitive space,” Benitah said. “But the small selection of toys that we did offer at Londonderry were among our top sellers.”

The success of the category has encouraged the company to expand its toy assortment moving forward.

The Toronto location will also introduce additional brands and licensed merchandise, including Adidas apparel alongside existing offerings from Reebok and Spyder. Products featuring Marvel, Disney and Nickelodeon properties will also play a larger role in the assortment.

Benitah said the retailer continues to evaluate new brands and licensing partnerships while closely monitoring customer response.

Zellers store at Londonderry Mall in Edmonton. Photo: Ulfhednar Hvedrungr

Edmonton Success Provides Confidence for Expansion

The Toronto opening follows the launch of Zellers’ first standalone location at Londonderry Mall in Edmonton in October 2025.

According to Benitah, customer response at the Alberta location has resulted in strong sales since opening.

“Customer enthusiasm has exceeded expectations,” he said.

The success of the Edmonton store appears to be validating the standalone strategy that emerged after Les Ailes de la Mode acquired the Zellers intellectual property in 2025. The location has provided management with valuable insight into customer behaviour, merchandise performance and store operations as the concept continues to evolve.

The store’s performance has also provided confidence for future growth, with Benitah indicating that additional opportunities are already being explored within the Edmonton market.

Expansion Plans Stretch Across Canada

While Toronto and Windsor represent the retailer’s first standalone locations in Ontario, they are only part of a much broader expansion strategy.

Benitah said additional stores are expected to open later this year, while multiple future locations are already confirmed for 2027 and beyond.

“We’re really looking to be truly coast to coast in every major market,” he said.

The company is currently pursuing opportunities across Canada, including discussions involving former Hudson’s Bay locations and redevelopment projects that may create space for future Zellers stores.

Former Hudson’s Bay locations represent one potential avenue for growth as landlords continue evaluating options for large-format department store spaces.

“There are a handful of vacant HBC boxes that in some cases we’re talking to landlords about taking over,” Benitah said.

In other situations, the retailer is exploring opportunities within redevelopment plans that could see former department store spaces subdivided into multiple retail units.

At the same time, the company continues to experiment with store formats as it searches for the most sustainable long-term model.

The new Toronto location spans approximately 25,000 square feet, a size Benitah describes as a smaller-format department store. Future stores may vary as the company continues refining the concept.

“We don’t know yet what that sweet spot is, and that’s exactly what we’re working to figure out,” he said.

While the company has not established a formal store-count target, Benitah believes the long-term opportunity remains significant.

“The ceiling is very high,” he said. “It could be well over 100 stores.”

For now, the company remains focused on measured growth while continuing to adapt the concept based on customer demand.

As Zellers prepares to open its newest standalone store, the company’s next chapter is being shaped by a combination of customer memories and customer feedback. The return of diner-inspired food, kiddie rides and Zeddy suggests that some of the experiences Canadians remember most fondly still have a place in the retailer’s future.

More from Retail Insider:

Reitmans sees slight revenue growth in Q1

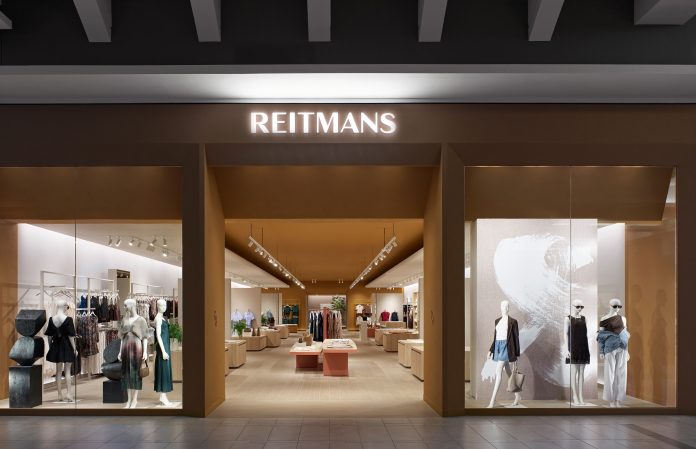
Image Credit: Ben Rahn/A-Frame [www.aframestudio.com] (CNW Group/Reitmans (Canada) Ltd)

Reitmans (Canada) Limited, one of Canada’s leading specialty apparel retailers, reported on Tuesday its financial results for the first quarter ended May 2, 2026, a slight uptick in revenue.

Highlights

  • Net revenues grew 0.8% to $160.1 million for the quarter.
  • Comparable sales, which include e-commerce net revenues, were up 0.3%.
  • Gross profit % was stable for the quarter at 55.7%.
  • Selling General & Administrative expenses decreased 2.2%
  • Adjusted EBITDA improved by $5.2 million to $(5.4) million for the quarter.
Andrea Limbardi
Andrea Limbardi

“RCL delivered an improved first quarter compared to last year, with solid progress shown across the business despite a challenging economic environment,” said Andrea Limbardi, President and CEO of RCL. “Net revenues from our retail stores increased 2.9% as Canadians continued returning to stores, particularly in shopping malls. Our investments in the store fleet are beginning to pay off, with non‑comparable locations contributing more strongly to revenue growth. We also grew net revenues while operating with lower inventory during the quarter. Meanwhile, we lowered our SG&A expenses, largely through the workforce reduction as part of our strategic transformation.

“As part of ongoing efforts to optimize our store network, Reitmans unveiled a successful new concept flagship store at Carrefour Laval, just outside Montréal, Québec. After quarter-end, RW&CO completed the transformation of its Toronto Eaton Centre store to their new concept introduced last fall, and the store has exceeded expectations since reopening on May 29th, 2026.

“The difficult economic reality is impacting everyday Canadians – we hear it from our customers every day. The rise in fuel costs and the related effects are significant. We remain committed to being the best choice for Canadians for great fashion at exceptional value. We are confident in our strategy, our brands, and the work underway to build a stronger, more resilient RCL.”

The company said net revenues increased 0.8%, to $160.1 million, with seven fewer stores year-over-year at quarter end. Net revenues from retail stores increased by 2.9%, largely driven by stores not included in comparable sales, benefiting from the investments made in new stores. Comparable sales were up 0.3% compared to last year mainly from higher sales dollars per transaction.

Reitmans (Canada) Limited is one of Canada’s leading specialty apparel retailers for women and men, with retail outlets throughout the country. The company operates 387 stores under three distinct banners consisting of 217 Reitmans, 85 PENN., and 85 RW&CO.

More from Retail Insider:

Derek Maxfield on Closing the Gap Between Inspiration and Purchase

Derek Maxfield knows the moment well. A consumer encounters something that genuinely moves them and feels pulled toward it, but then they lose the thread as the product disappears into a scroll.

The inspiration was real, but the infrastructure to act on it just wasn’t there. Retail has always contended with the distance between original desire and making a decision. The scale at which inspiration now circulates and the degree to which consumers expect immediacy in every other part of their digital experience have shifted significantly.

The brands and creators who have embraced this reality no longer wait for consumer patience to improve. Instead, they are redesigning the journey itself.

The Anatomy of the Inspiration Gap

The inspiration-to-purchase journey typically begins with discovery. Discovery can happen anywhere, including a short-form video, a long-form editorial, a social post, or a podcast recommendation. What matters is that it generates genuine desire.

From discovery, the consumer enters what can be thought of as a consideration corridor. This period of evaluation can last seconds or weeks, depending on the price point, the complexity of the decision, and the level of trust the consumer already has in the source.

Here, the gap most commonly widens. If the path from consideration to purchase is anything other than immediate and frictionless, competing stimuli flood in, and attention is grabbed by another piece of content or maybe a different recommendation.

Derek Maxfield has spent considerable time identifying where direct sales and modern digital commerce both succeed and fail in navigating this corridor.

“The old direct sales model was actually very good at staying present through the consideration phase,” he says. “The personal relationship meant the seller could answer questions, handle objections, and keep the energy alive through the decision. Digital commerce largely abandoned that continuity in exchange for scale.”

Why Content and Commerce Stayed Separate for So Long

A big part of what makes the inspiration gap so persistent is that content and commerce developed along largely separate tracks. Content platforms are optimized for engagement, while commerce platforms are optimized for transactions.

The separation used to make sense in the days when embedding purchasing within content was technically prohibitive. Creators continued to be trained to see themselves as top-of-funnel contributors whose job ended at awareness.

All the while, commerce operators treated content as an external acquisition channel. Search became the default bridge between inspiration and purchase, and what that assumption misses is the enormous percentage of inspiration that never survives the friction of a separate search.

Shoppable Content and the Compression of the Buying Journey

The most direct structural response to the inspiration gap has been shoppable content, or formats in which the product, the purchase mechanism, and the editorial context exist simultaneously in the same environment.

Shoppable social posts, video, and editorial content all operate on the same logic that eliminating the distance between desire and decision occurs by making the transaction available at the precise moment inspiration peaks.

Purchase intent is highest at the moment of discovery, and every additional step is an opportunity for attention to redirect. Compressing the buying journey does not manufacture desire but instead stops squandering the desire that already exists.

“The technology to eliminate the gap has existed for years,” Maxfield, who serves as CEO at Curated, says. “What’s been slower to develop is the creative and structural thinking about how to use it and how to build content experiences that earn trust while enabling action in the same breath.”

Curated is building infrastructure that intersects affiliate marketing and direct sales, allowing creators to hold the relationship through the full arc from inspiration to completed purchase.

The Role of Trust in Accelerating Conversion

No amount of technical polish compensates for a deficit of trust, and the inspiration gap is easier to close in some creator environments than others because of the depth of the relationship the creator has built.

A creator whose audience trusts their judgment implicitly has already done most of the conversion work before a product is ever mentioned. In paid advertising, conversion must be earned entirely within the ad unit itself. The creator has access to a different toolkit entirely.

Maxfield draws a direct line from this dynamic to the principles that made relationship-based selling effective long before the internet existed.

“The math of trust-based selling is different. You’re not fighting for attention from scratch every time. You’re drawing on something that was built over months or years. That changes what’s possible at the moment of decision,” says Maxfield.

Building Commerce Experiences Around the Human Moment

What the most sophisticated practitioners of creator commerce are learning is that closing the inspiration gap requires designing the entire commercial experience around the human moment in which inspiration occurs, matching the tone, the pacing, and the format of the transaction to the emotional state the content has created.

A consumer who has just finished a deeply engaging video about sustainable outdoor gear is in a specific frame of mind. Thus, the commerce experience that meets them there should feel like a natural extension of what they just watched, not a jarring pivot into a generic product page.

The creator’s voice, the visual language of their content, and the editorial perspective that made the inspiration moment possible should carry forward into the purchasing environment. That level of integration demands closer collaboration between creators and the brands they partner with, and a shared understanding that the commerce experience is a continuation of the content, not a separate department’s problem.

Companies and platforms building in this space are only beginning to develop the norms and tools required to make that integration seamless. The gap will continue to close, but the speed at which it does will depend on how quickly the industry stops treating content and commerce as adjacent disciplines and starts building them as one.

Personal Belongings vs. Guest Property: Who’s Covered?

Suppose you operate a guesthouse, bed and breakfast, holiday rental, or any other short-term lodging establishment. Your insurance then covers your property as well as those of your visitors.

But this is a widely held misperception with expensive consequences. In insurance, the classification of your “personal possessions” and what qualifies as “guest property” differs quite greatly. You can visit Quoteradar to learn more about the different kinds of insurance to navigate the complex insurance market.

This article clarifies variance, the types of insurance that cover each, and how to safeguard yourself—and your guests—against unplanned losses.

What Is Considered Personal Items?

As building operator or property owner, you have provided inside the premises some personal possessions. These include beds, sofas, televisions, kitchen appliances, curtains, and even office tools such as printers or computers.

Most of the time, your commercial property insurance or business contents coverage will cover these goods. This insurance protects you against various hazards, including fire, theft, water damage, and vandalism. But not all policies are the same.

For instance, your insurer may decline coverage of a claim if your place is still empty for more than a specified number of days. Similarly, expensive equipment or special furniture should be itemized separately on your policy.

What is Guest Property?

Guest property is any object brought onto your property by a paying guest, lodger, or visitor. This covers currency, passports, luggage, electronics, apparel, and other items.

Although you may consider yourself responsible for protecting your guests’ possessions, most typical insurance plans typically lack this coverage. You need guesthouse insurance to cover your premises adequately and protect your business. At Quote Radar, you can compare different policies from different providers and cover your guesthouse completely. 

Does Insurance Protect Guest Belongings?

Not always; this is where many UK company owners make a mistake. Your basic contents policy does not automatically cover guest property.

To safeguard guest valuables, you have to either:

  • Guest-house Insurance: This is meant to protect visitors’ property while they are on your premises.
  • Public Liability Insurance: Even if it does not cover the actual goods, public liability insurance can shield you if a guest sues for loss or damage caused by your carelessness

Should a guest’s laptop be damaged by a ceiling leak, for instance, they may claim you were negligent in maintenance. In certain situations, public liability insurance can help offset legal and compensation expenses.

When Public Liability Comes Into Play:

Public liability insurance is not meant to cover the worth of guest belongings. But it does help you if a guest files a legal case alleging damage or loss of their belongings caused by your carelessness.

You could be held accountable, for instance, if it turns out you didn’t maintain the plumbing correctly and a leaking pipe damages an expensive visitor’s goods and electronics.

Similarly, you might be held responsible if a robber snatches goods meant for guests via a door you forgot to latch. Legal expenses and compensation in these situations can be covered by public liability insurance.

How Might You Stay Protected?

Begin by reviewing your current insurance coverage. Check whether it covers any visitor effects coverages. Should it not, discuss it with your broker or insurer about including it.

Though several providers provide this as an optional extra, it can offer real peace of mind, particularly if you frequently welcome visitors or customers on your property. Basic safety precautions should also be followed to prevent accidents.

Make sure entry points are watched and locks are secure; hazards like open floorboards or faulty electrical sockets are swiftly fixed. Preserving meticulous records of upkeep helps to settle a disagreement should one arise.

Final Thoughts:

From an insurance perspective, the difference between guest property and personal possessions may appear slight, but it is substantial. Most commercial property insurance only covers what you own.

Guest goods often need separate cover or fall under public liability in situations of carelessness. Understanding precisely what is covered and what is not will assist you in avoiding financial loss, conflicts, and misinterpretations.

Furthermore shows professionalism and concern for those who trust you with their visit. Proper investment now will help you prevent major problems later.

Foodtastic acquires Kinton Ramen: CEO Interview

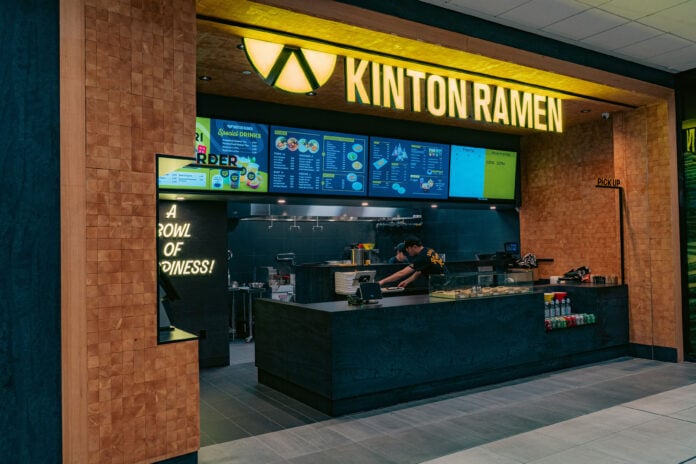
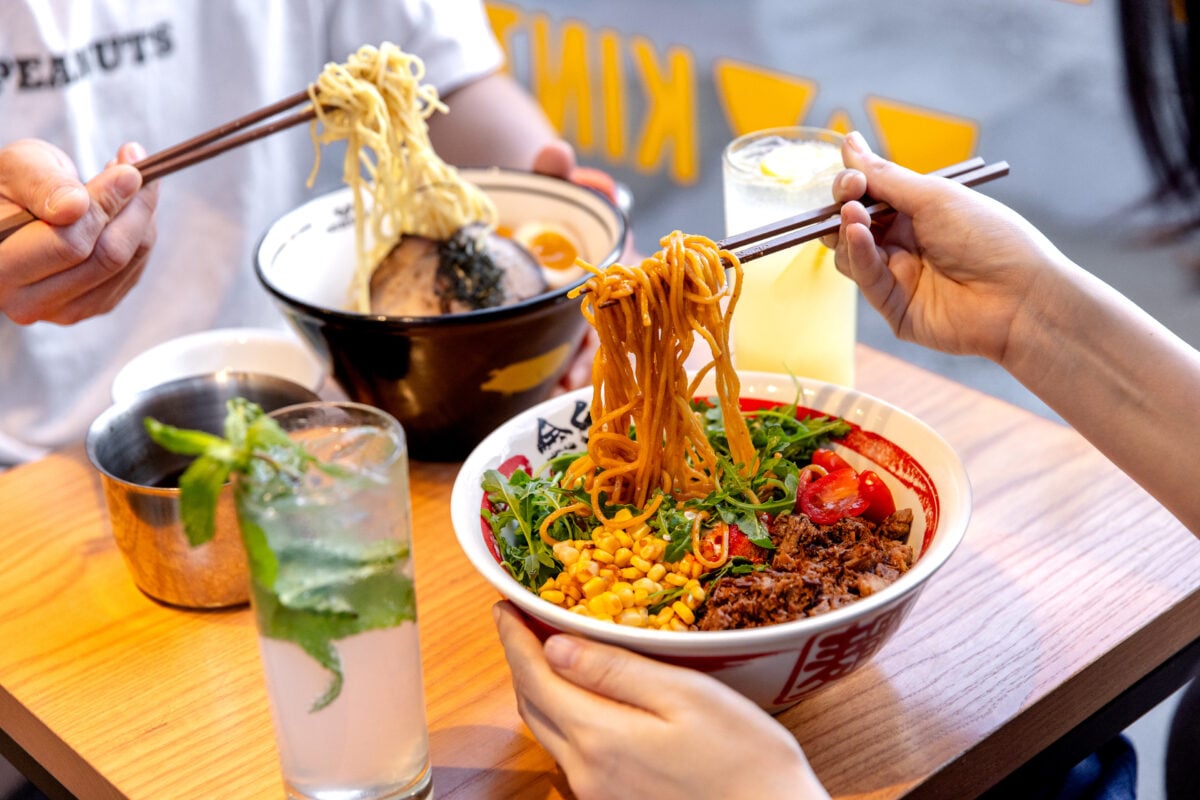
Kinton Ramen photo
Kinton Ramen photo

Canadian restaurant franchisor Foodtastic has acquired Kinton Ramen, a Japanese ramen brand founded in Canada with locations across Canada and in the United States.

Foodtastic, in a news release, said the acquisition brings an established Asian dining concept into its portfolio and aligns with the company’s strategy to invest in restaurant brands with clear characteristics and development potential. Founded in Toronto in 2012, Kinton Ramen was among the first Japanese ramen restaurants in the city and has since expanded across Canada and into the United States, it said.

Foodtastic is a leading Canadian restaurant franchisor with a portfolio of 30 diverse brands and over 1,200 establishments across the country. Brands include Milestones, Dunkin’, Pita Pit, Quesada, Second Cup, Rotisseries Benny, La Belle et La Bœuf, and Freshii, among others.

Image: Peter Mammas

“We have been looking to add a strong Asian concept to our portfolio for some time, and Kinton Ramen is exactly the kind of brand we wanted to bring into Foodtastic,” said Peter Mammas, founder and Chief Executive Officer of Foodtastic.

“Kinton has built a clear position in the Canadian restaurant market, with a loyal following, a strong culinary identity and significant room to grow. We believe Foodtastic’s scale, infrastructure and franchise expertise will help support the brand’s next stage of growth across Canada.”

Foodtastic said Kinton Ramen offers Japanese ramen with a menu designed for dine-in, takeout, and delivery. The brand operates 58 locations in five Canadian provinces and one U.S. state, including Ontario, British Columbia, Quebec, Alberta, Manitoba, and New York.

“We weren’t exactly in this ramen noodle space. We own Noodlebox but it’s quite different. In a wok. It’s a different type of noodle. It’s also kind of a hybrid here where you have service and you also have opportunity to have counter. So we found the segment very attractive,” said Mammas. “I eat a lot at Kinton and I found that the consistency was always there. The service was good. The stores look great. I really got excited about this about three years ago. It took us quite a bit of time to actually convince them to sell to us and to come to a deal. So I’m really happy that this one happened. It took a lot longer than I would ever have imagined.”

Following the acquisition, Foodtastic said it will focus on expanding Kinton Ramen in Canada and will use its operating infrastructure to support the brand. There are no plans to change Kinton Ramen’s menu, loyalty program, brand identity, franchisee relationships, or guest experience.

“I think it could easily double,” said Mammas. Kinton Ramen today has 58 locations in Quebec, Ontario, Manitoba, Alberta and B.C. It’s mostly in urban areas right now but I think the footprint and the type of operation allows us to open in a lot of suburban markets as well. I think we’re going to double it.”

He said 20 locations are currently corporate.

“As is our DNA, we will be franchising the corporate stores as well in the near future and we’re going to continue to build the concept.”

“Kinton Ramen has always been about delivering a memorable and authentic ramen experience to guests, one bowl at a time,” said James Kim, founder of Kinton Ramen. “Foodtastic understands the strength of the brand and the significance of preserving what guests and franchisees already know and value. We are looking forward to working with the Foodtastic team as Kinton enters its next phase of growth.”

The acquisition expands Foodtastic’s portfolio of established restaurant brands in Canada. Foodtastic now operates brands across the quick-service, fast-casual, coffee, healthy-eating, casual-dining, and specialty-dining categories, added the company.

Mammas said the Kinton Ramen footprint is compact and the sales per square foot are “very interesting.”

“The build out costs are probably less than other full-service restaurants and there’s a lot of third-party delivery that can be done with this type of food. I think they’ve also kind of perfected the way ramen is delivered. That’s a big credit to them. It’s always coming to the customer hot. You put in your ramen right after. It’s almost a restaurant experience in your house which is hard to do.”

Photo: Kinton Ramen
Photo: Kinton Ramen

Mammas said expansion opportunity exists in Atlantic Canada as well as Quebec.

“Our runway is pretty good,” he said.

Mammas said 2025 was “pretty good” for the restaurant industry.

“When we got into 2026, once the Iran war started we saw a slow down. The last couple of weeks have been ticking positively. So that looks good. Hopefully this peace deal transpires and they sign it like they’re saying. We’ve already seen the effects at the gas pumps. Price of gas has dropped close to 15% in the last little while. That leaves more money in people’s pockets and they can enjoy some great food more often.”

Mammas said Foodtastic is a company that wants to grow and will grow in the future.

“There’s still quite a few segments that we’re not in, that we’re actively pursuing to see how we could bridge those gaps. But definitely we want to open new stores with existing brands and we want to keep on acquiring.”

More from Retail Insider:
Groupe Dynamite posts 37% revenue growth and 4-year high gross margin in Q1

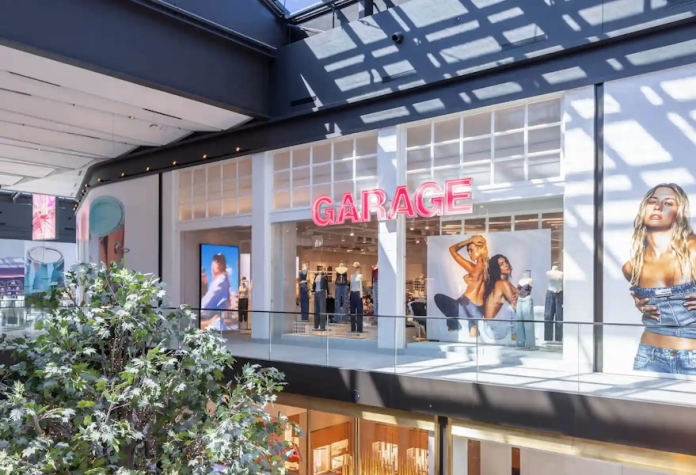
Garage store at Royalmount in Montreal. Photo: Garage/Groupe Dynamite

Apparel retailer Groupe Dynamite Inc., with brands DYNAMITE and GARAGE, reported Tuesday its financial results for the fiscal year 2026’s first quarter ended May 2, 2026, with revenue surging to more than $310 million, representing growth of 37% year-over-year.

Andrew Lutfy
Andrew Lutfy

“Our first quarter results demonstrate the strength of our operating model and our ability to deliver profitable growth. Comparable store sales increased 22.6%, gross margin reached a four-year high, and adjusted EBITDA margin expanded to 36.8% of revenue, positioning ourselves alongside the world’s most profitable fashion houses. We continue to strive to remain a highly productive specialty retailer with strong brands, exceptional unit economics, disciplined inventory management, attractive returns on capital, and a growth engine we have built over decades that continues to scale profitably,” said Andrew Lutfy, Chief Executive Officer and Chair of the Board. 

Stacie Beaver
Stacie Beaver

“Q1 was a strong start to fiscal 2026. Across both GARAGE and DYNAMITE, customers responded positively to our assortments, marketing campaigns and the consistency of the experience we deliver across channels. Our real estate strategy continues to be a significant driver of growth, customer acquisition and profitability. By opening new locations in premium centers, optimizing our fleet and delivering a compelling in-store experience, we continue to drive significant productivity improvements across our store network. Most importantly, we continue to see strong customer engagement across both brands, reflected in growth in our active customer base and increasing customer lifetime value,” added Stacie Beaver, President and Chief Operating Officer.

Fiscal 2026 First Quarter Highlights

  • Revenue increased by 37.0% to $310.6 million in Q1 2026, compared to $226.7 million in Q1 2025.
  • Comparable store sales growth of 22.6% (24.7% on a constant currency basis in Q1 2026, over and above comparable store sales growth of 13.0% in Q1 2025.
  • Retail sales per square foot increased by 32.4% compared to Q1 2025, reaching $1,001 in Q1 2026.
  • Gross margin expanded by 530 basis points to 67.4% in Q1 2026 compared to 62.1% in Q1 2025.
  • SG&A increased to $102.2 million in Q1 2026, compared to $74.7 million in Q1 2025, and adjusted SG&A as a percentage of sales decreased by 190 basis points to 30.5% from 32.4% over the same period in Q1 2025.
  • Operating income increased by 80.1% to $79.8 million in Q1 2026, compared to $44.3 million in Q1 2025.
  • Adjusted EBITDA increased by 71.3% to $114.4 million in Q1 2026, representing an adjusted EBITDA margin of 36.8%, compared to 29.5% for the same period in Q1 2025.
  • Diluted net earnings per share increased to $0.45 in Q1 2026, compared to $0.24 in Q1 2025 and adjusted diluted net earnings per share  increased by 100.0% to $0.50 in Q1 2026, compared to $0.25 in Q1 2025.
  • Real estate activity for Q1 2026 includes:
    • Opening of 5 gross new stores: 3 in the United States and 2 in the United Kingdom, both under the Garage banner.
    • 5 store closures: 4 in Canada under the Dynamite banner and 1 in the United States under the Garage banner.
    • Renovation or relocation of stores: 3 in Canada under the Garage banner.
Groupe Dynamite photo

More from Retail Insider:

Generation X Leads Canadians in Throwing Away Food Past Date Labels: Survey

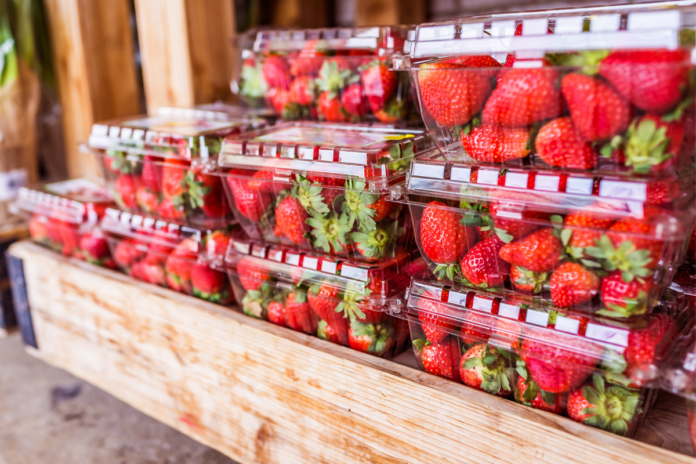
Strawberries in a grocery store. Photo: Institut national de la recherche scientifique (INRS)

Canadians often blame grocery stores, food manufacturers, or governments for food waste. Yet much of the waste occurs in our own kitchens, often for one simple reason: we misunderstand food date labels.

New survey data from the Agri-Food Analytics Lab, in partnership with Caddle, based on responses from 3,000 Canadians, reveal that the vast majority of households continue to throw away food once it passes its use-by date. While only 11 per cent of Canadians say they always discard food after the date has passed, another 20 per cent do so often, and 37 per cent do so sometimes. In other words, nearly seven in ten Canadians allow date labels to influence their decision to dispose of food.

The findings expose a costly and largely preventable problem. What is perhaps most surprising is the generational divide.

Generation Z, often criticized for many things, appears to be the least wasteful cohort when it comes to date labels. Only 6.1 per cent say they always throw away food after the use-by date, compared with 15.6 per cent of Generation X. More than one-third of Gen Z respondents say they rarely or never discard food solely because of a date label.

Image

Generation X, meanwhile, emerges as Canada’s most cautious generation. Nearly 40 per cent say they always or often throw away food once the date has passed.

At first glance, this may seem counterintuitive. One might expect older Canadians to be more conservative and younger Canadians to be more prone to waste. The opposite appears to be true.

The explanation likely lies in a combination of economics, experience, and risk perception.

Younger Canadians are facing unprecedented affordability challenges. High housing costs, student debt, stagnant wage growth, and rising food prices have forced many to extract maximum value from every grocery purchase. They are also more likely to have been exposed to sustainability campaigns and food waste education efforts, which often emphasize that many date labels are indicators of quality, not safety.

Generation X sees things differently. Many are caring for both children and aging parents. For them, the consequences of serving food that might be unsafe outweigh the cost of replacing it. They also came of age during decades marked by heightened concerns over foodborne illnesses, recalls, and public health warnings. As a result, they may be more inclined to treat date labels as hard safety limits rather than guidelines.

The reality is that much of this food never needed to be thrown away.

Canada’s food labeling system remains poorly understood. Many consumers confuse “best before” dates with food safety indicators. In most cases, these dates are intended to signal peak quality, not spoilage. Yet countless products end up in the garbage because consumers view the date as a definitive expiration point.

This confusion carries real consequences.

Food waste is not merely an environmental issue. It is an affordability issue. Every carton of yogurt, loaf of bread, package of cheese, or container of leftovers thrown away unnecessarily represents money lost. At a time when nearly one-quarter of Canadian households experience some level of food insecurity, reducing avoidable waste should be a national priority.

The environmental costs are equally significant. Wasted food means wasted water, wasted energy, wasted labour, wasted transportation, and unnecessary greenhouse gas emissions. Few Canadians realize that household food waste is one of the largest contributors to food-system inefficiency.

The good news is that this problem is largely solvable.

Governments do not need billion-dollar programs to address it. What is needed is a serious effort to improve food literacy. Consumers need clearer guidance on date labels, food storage practices, and how to assess food quality using common sense. Retailers and manufacturers can also play a role by simplifying labels and providing more practical information to shoppers.

The survey suggests that younger Canadians may already be moving in this direction. If so, they may have something to teach the rest of us.

The next time you reach for a product that has just passed its date, ask yourself a simple question: Is the food actually unsafe, or am I simply reacting to a number printed on a package?

The answer could save Canadians millions of dollars and keep a great deal of perfectly edible food out of landfills.

More from Retail Insider:

Interac survey finds single Canadians are bearing the brunt of rising grocery costs

Helena Lopes photo
Helena Lopes photo

The new State of the Cart grocery spending survey from Interac finds that Canadians living alone – the most common household type in the country – are feeling the pressure of rising costs. 

Nearly eight in 10 (77 per cent) Canadians who live solo say their grocery bill keeps climbing no matter what they do, and almost six in 10 (59 per cent) say they face disproportionately higher per-person costs than Canadians who split these expenses. The findings suggest the gap is real: the average single-person household spends approximately $102 per week on groceries, compared to $80 per person in a shared household, said the company. 

Canadians living alone say they often miss the savings that come with buying in bulk and struggle to find ingredients portioned for one, with 32 per cent saying food often goes to waste before they can use it. For Canadians who once shared a cart with a romantic partner, there is an upside to living and shopping solo: no more compromise. Among those now living alone after previously living with a partner, seven in 10 (70 per cent) are relieved they can make their own decisions, leaving the tension of shared decision-making behind, it explained.  

Chris Lee
Chris Lee

For couples navigating the aisle together, that tension is alive and well: nearly half (47 per cent) say they approach grocery spending differently from their partner, and nearly three in 10 (28 per cent) say grocery spending has been a source of strain in their relationship in the past six months. Four in 10 (40 per cent) say friction starts when one partner sticks to the list while the other is more likely to make impulse purchases. Other key sticking points include what counts as a necessary purchase and whether name brands are worth the price, added Interac.

“In the first quarter of 2026, tens of millions of Canadians used Interac Debit to pay for groceries,” said Chris Lee, Head of Payments at Interac. “With our State of the Cart survey, we wanted to better understand the domestic dynamics behind grocery transaction moments. While all Canadians face the common challenge of rising grocery prices, the pressure differs greatly according to whether you live alone or with a partner, your age and stage of life, and even the province you call home.” 

Cart conflicts: grocery shopping among couples, according to Interac

  • The divide is sharpest in British Columbia, where just 58 per cent of those in a shared household say they manage their grocery budget well together, compared with 73 per cent in Quebec. 
  • Among Millennials, nearly four in 10 (39 per cent) say grocery spending is a source of relationship tension, compared with 17 per cent of Boomers. 
  • Younger couples are keeping a closer eye on grocery spending – and reaching for Interac Debit to do it. Over half of Gen Z Canadians living with a partner (55 per cent) say paying with debit helps them feel they have a clearer picture of what they’re spending on groceries in real time. 
Interac website photo

How the makeup of Canada’s grocery cart is changing, say Interac

  • Canadians are adjusting what goes in the cart in response to rising prices. Nearly half (48 per cent) have reduced or stopped buying premium cuts of meat, with prepared meals and premium deli items also declining.  
  • Nearly four in 10 (38 per cent) have switched to store or no-name brands in the past six months.  
  • Canadians are drawing a line at small indulgences: half (50 per cent) still buy snacks like chips and chocolate as a personal treat, and nearly one in four (23 per cent) still reach for artisanal bread or pastries. 

“What stands out in this research is that no matter what is shaping their grocery decisions, Canadians are shopping with more intention and many are using Interac Debit to do so,” added Lee. “They are weighing tradeoffs more carefully, planning more deliberately and making thoughtful choices about what matters most in their cart.” 

More from Retail Insider:
Checkout.com report finds consumer interest in AI shopping outpacing trust and merchant readiness

Andrea Piacquadio photo

Consumer interest in using artificial intelligence to help make purchases is growing, but trust in the technology and readiness across the commerce ecosystem remain significant hurdles, according to new research released by digital payments company Checkout.com.

The report, Agentic Commerce 2026: The State of Consumer Demand and Merchant Readiness, found that 33 per cent of consumers expect at least 10 per cent of their purchases to be driven by AI within the next year, while 72 per cent of merchants in the United Kingdom and United States believe consumers will adopt AI-powered shopping faster than most businesses are prepared for.

The findings point to a widening gap between consumer expectations and the systems, standards and safeguards needed to support what the company describes as agentic commerce, in which AI agents can search, compare products and complete purchases on behalf of consumers with permission.

The research suggests businesses are preparing for broader use of AI in shopping, but questions around trust, control and accountability remain unresolved.

One in four consumers surveyed said they would never delegate purchases to AI, while 27 per cent said they do not trust any organization to operate an AI shopping agent on their behalf.

Consumers also indicated they would only permit AI agents to make purchases under strict conditions. Across the six markets surveyed, respondents said they would allow an AI shopping agent to spend an average of £177 per purchase without additional approval. That compares with an average merchant expectation of £200 across the U.K. and U.S.

ArtHouse Studio photo

The report found spending limits, instant revocation of permissions and easy cancellation were among the most important conditions consumers identified for building confidence in AI-assisted shopping. Merchants appeared to recognize those concerns, with 75 per cent saying the ability for customers to revoke permissions in real time would be critical to adoption.

Rory O’Neill, chief marketing officer at Checkout.com, said the technology is moving beyond the experimental stage, even as supporting infrastructure continues to develop.

“Agentic commerce is quickly moving from concept to reality. Consumers are beginning to experiment with AI agents for everyday purchases, and across the industry we’re seeing rapid collaboration around the protocols and standards that will support this next phase of ecommerce. But while adoption is ramping up, the infrastructure behind it is still developing. Consumers need confidence that AI agents will operate within clear controls around security, refunds, permissions and spend limits. Until those foundations are in place, trust will remain one of the biggest barriers to adoption.”

The report found convenience is the primary factor driving consumer interest in AI-powered shopping. Twenty-five per cent of respondents said saving time was their main reason for using an AI shopping agent, while 20 per cent said they would use the technology to avoid missing better deals.

Adoption appears most likely to begin with routine and lower-risk purchases. Consumers were most willing to delegate shopping for groceries, at 41 per cent, followed by household supplies at 31 per cent.

More complex purchasing decisions attracted less interest. Financial services ranked lowest among categories consumers were willing to delegate to AI, at 15 per cent. The finding contrasts with merchant expectations that AI-assisted shopping could gain traction first in more complicated purchasing decisions, including financial products.

The research also suggests AI could influence brand loyalty. Fifty-seven per cent of consumers said they would allow an AI shopping agent to switch brands if it identified a better-value alternative.

At the same time, merchants reported that AI agents currently account for only a small share of transactions. According to the survey, three per cent of transactions involve AI agents today, while 89 per cent of merchants said they are actively preparing for broader adoption of agentic commerce.

The study was conducted by Censuswide and surveyed 12,005 consumers aged 18 and older across the United Kingdom, United States, Brazil, China, France and the United Arab Emirates. It also surveyed 400 heads of payment working at consumer-facing merchants in the U.K. and U.S.

More from Retail Insider: