Home Blog

Levi’s Canadian Retail Strategy Takes Shape After Hudson’s Bay Closure

Photo: Levi's

Levi Strauss & Co. is navigating a Canadian retail market that has lost one of its largest department-store chains, leaving apparel suppliers to reconsider how they reach consumers. Following Hudson’s Bay’s closure in 2025, the denim company continues to operate through branded stores, mass-market retailers and premium wholesale partnerships, with each channel serving a different segment of the market.

The importance of those relationships is evident in Levi Strauss’s latest financial results, released October 7. Global wholesale revenue grew faster than the company’s direct-to-consumer business during its fiscal third quarter, reinforcing the commercial value of outside retail partners even as Levi Strauss invests in its own stores and digital operations.

Hudson’s Bay’s collapse removed an important distribution channel for apparel brands operating in Canada. Its department stores provided national exposure through established shopping centres, reaching customers who might not otherwise visit standalone branded locations.

Levi’s was among the brands affected. Retail Insider reported in June 2025 that the company had generated tens of millions of dollars in annual sales through Hudson’s Bay, illustrating the scale of business potentially disrupted by the retailer’s disappearance.

Replacing those sales presents a challenge because department stores, mass merchants and specialty retailers serve different customers and operate with different merchandise assortments and pricing structures. A brand may have several distribution partners without any single relationship offering the same sales capacity as a national department-store chain.

Levi Strauss already maintained a diversified Canadian business before Hudson’s Bay closed. That existing network gives it several routes to market, although the company has not disclosed how much of its former Hudson’s Bay business has been recovered through alternative channels.

Levi’s Maintains a Broad Canadian Store Network

Levi Strauss maintains a substantial physical retail presence in Canada, with branded stores and outlets listed across eight provinces. Its current Canadian store directory identifies locations at major shopping centres including CF Toronto Eaton Centre, Yorkdale, Square One, CF Chinook Centre, CF Market Mall and Quartier DIX30.

Independent location-data firm ScrapeHero identified 59 Canadian Levi’s locations as of April 24, 2026, including 20 in Ontario, 17 in Quebec and 10 in British Columbia. Those three provinces account for nearly 80% of the identified network, although the figures represent a third-party estimate rather than an audited company store count.

For landlords, Levi’s remains an established international apparel tenant with locations in major metropolitan shopping centres and regional markets. Its branded stores also give the company greater control over merchandise presentation and customer relationships than wholesale distribution typically allows.

Levi Strauss extended its direct customer relationships in July 2025 with the Canadian introduction of its Red Tab membership program. The initiative connects participating stores and digital channels through a loyalty offering, adding another component to the company’s direct-to-consumer operations.

Walmart and Mark’s Provide Additional Distribution

Wholesale remains an important part of Levi Strauss’s Canadian business, with different retailers serving distinct consumer segments. Walmart Canada carries Levi Strauss Signature merchandise, a value-oriented product line that allows the company to compete at lower price points while maintaining separate positioning for its mainline and premium collections.

The Walmart relationship predates Hudson’s Bay’s closure and should not be interpreted as a newly announced replacement for that lost business. Nevertheless, it illustrates the importance of established mass-market distribution when a major department-store channel disappears.

Mark’s provides another Canadian wholesale relationship. In a November 2024 announcement, Levi Strauss identified an enhanced presence at the retailer’s Queensway location as an example of its wholesale strategy, demonstrating the company’s participation in specialty apparel retail alongside mass-market partnerships.

Premium Partnerships Extend the Brand’s Positioning

Levi Strauss has also developed its presence in higher-priced Canadian retail environments. In June 2025, the company expanded its partnership with Holt Renfrew, bringing curated merchandise and retail activations to the luxury department-store chain.

The arrangement included pop-ups in Calgary and Montreal, with additional Levi’s assortments planned for Holt Renfrew locations in Toronto and Vancouver. As Retail Insider reported at the time, the initiative followed Hudson’s Bay’s closure and supported Levi’s efforts to strengthen its premium positioning.

Levi Strauss had also introduced premium merchandise through Canadian specialty retailer HAVEN in late 2024, with distribution through its Toronto and Vancouver operations. That relationship supports the company’s development of higher-priced denim and lifestyle products, distinct from the Signature assortment sold through Walmart Canada.

Wholesale Growth Outpaces Direct-to-Consumer Sales

Levi Strauss’s fiscal third-quarter results provide financial context for its multichannel strategy. The company reported global organic revenue growth of 5%, with wholesale revenue increasing 6% and direct-to-consumer revenue rising 2%.

Comparable sales in the direct-to-consumer business were flat, although e-commerce revenue increased 10%. The results indicate that wholesale was the stronger growth channel during the quarter, even as the company continued investing in its own retail operations.

Levi Strauss Signature, the value-oriented brand carried by Walmart Canada, recorded approximately 13% global organic revenue growth during the quarter. The performance highlights the contribution of lower-priced merchandise to the company’s broader business, although the results do not disclose Signature’s Canadian performance separately.

The company is also expanding its merchandise beyond traditional denim bottoms. Management reported that categories outside denim bottoms contributed approximately half of quarterly organic revenue growth, reflecting increasing demand for tops and other apparel.

A broader assortment gives Levi Strauss additional opportunities to generate sales through existing retail relationships, whether in branded stores or wholesale accounts. It also allows retailers to develop more extensive Levi’s assortments rather than concentrating primarily on jeans.

The reported financial results are global and do not provide a separate Canadian performance breakdown. Consequently, they cannot establish whether Levi Strauss has recovered the sales lost through Hudson’s Bay or how its Canadian wholesale business performed during the quarter.

A Changing Distribution Market

Levi Strauss’s Canadian operations demonstrate how a diversified retail model can reduce reliance on any single distribution channel. Its branded stores provide direct access to consumers, mass-market retailers offer broad distribution, and premium partners support higher-priced merchandise and brand positioning.

The disappearance of Hudson’s Bay has made those distinctions more consequential. Replacing a national department-store relationship can require several retail partners, each with different customers, commercial arrangements and merchandise requirements.

For Canadian landlords, Levi’s existing store network maintains the brand’s presence in major shopping centres, while wholesale partnerships extend its reach beyond those locations. The combination provides flexibility, but it also requires the company to manage distinct product and pricing strategies across retailers.

The latest earnings results show that wholesale remains an important source of global growth for Levi Strauss. In Canada, the more significant test will be whether the company can maintain and build sales across its remaining retail relationships without the national distribution capacity Hudson’s Bay once provided.
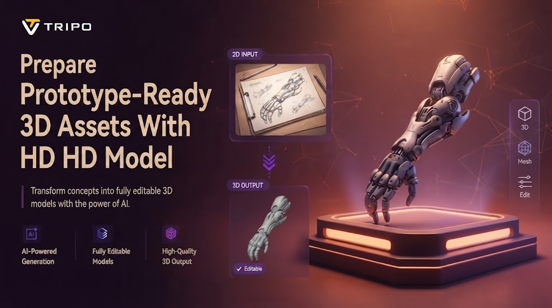
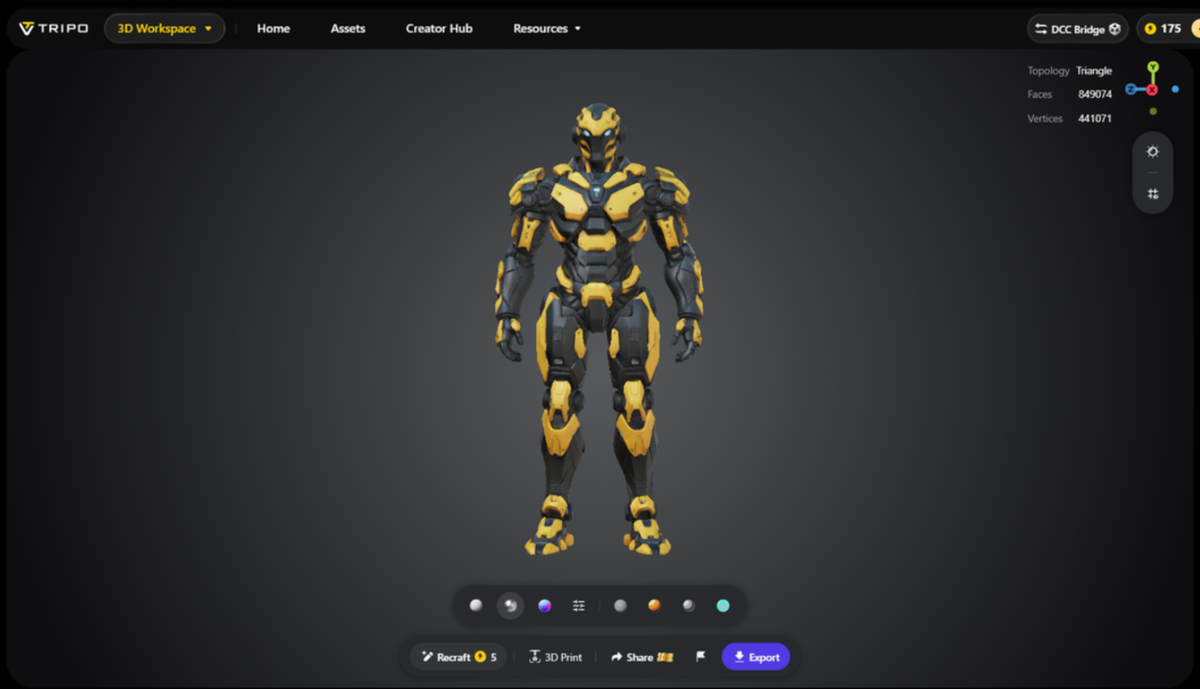
Prepare Prototype-Ready 3D Assets With HD Model

Sketch, photograph, and idea to prototype-ready models in minutes. Quickly creating assets allows designers to experiment with shapes, proportions, and directions before diving into in-depth modeling. But even generated geometry must be checked against dimensional, structural and prototype requirements during evaluation.

Selecting Images That Translate Well Into Prototype Geometry

It is easier to obtain better visual information from images with clear silhouettes and recognizable forms for image-based model generation. A clear image enables an AI 3d model generator to recognize the contours, proportions and parts. For simple objects with limited structural complexity and straightforward references, single-view images can be used. When depth, alignment and hidden relationships are relevant for the structural interpretation, multi-view references provide information. Ambiguous images can cause hidden surfaces, proportions, openings, joints and structural features to be distorted during generation. It is also helpful to have good lighting and clear backgrounds, which can help to make the important boundaries more obvious visually.

Balancing Geometry Detail With Prototype Requirements

Polygon density should be proportional to the prototype’s purpose – not to the complexity of the geometry for each iteration. An image to 3d model process can generate detailed surfaces; complexity impacts editing. Low-poly meshes are good for fast geometry changes, visualization and for usage in applications that need efficient geometry in design. The more polygons, the more accurately curved edges, intricate contours and mechanical forms are represented. It is the optimal mesh that has been carefully balanced for the maximum amount of visible detail, editing flexibility and software requirements for most prototypes.

Steps to Prepare Prototypes Faster Using Image-to-3D Model Rapid Asset Generation

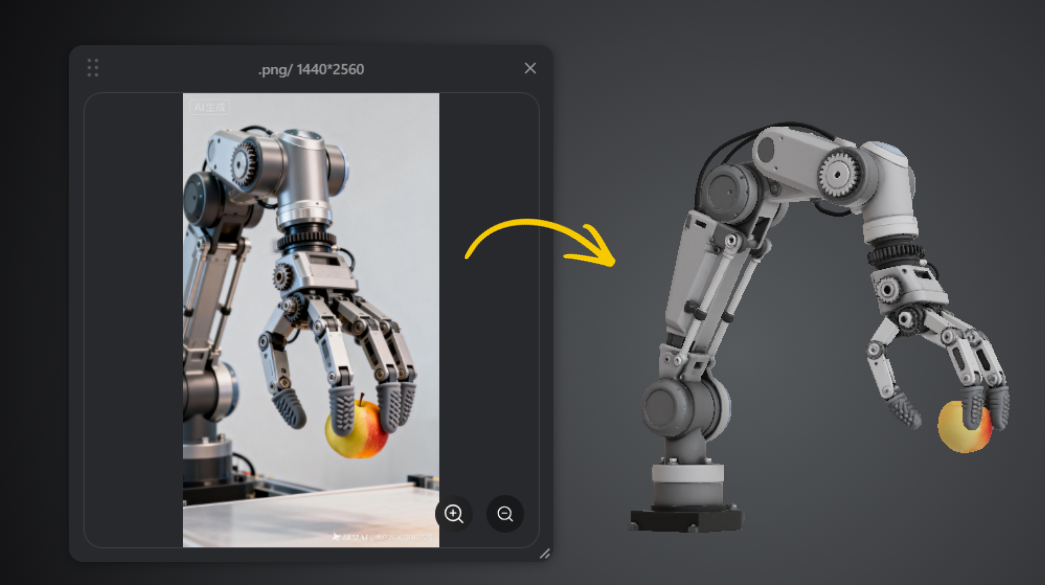
Step 1: Begin With a Reference Image

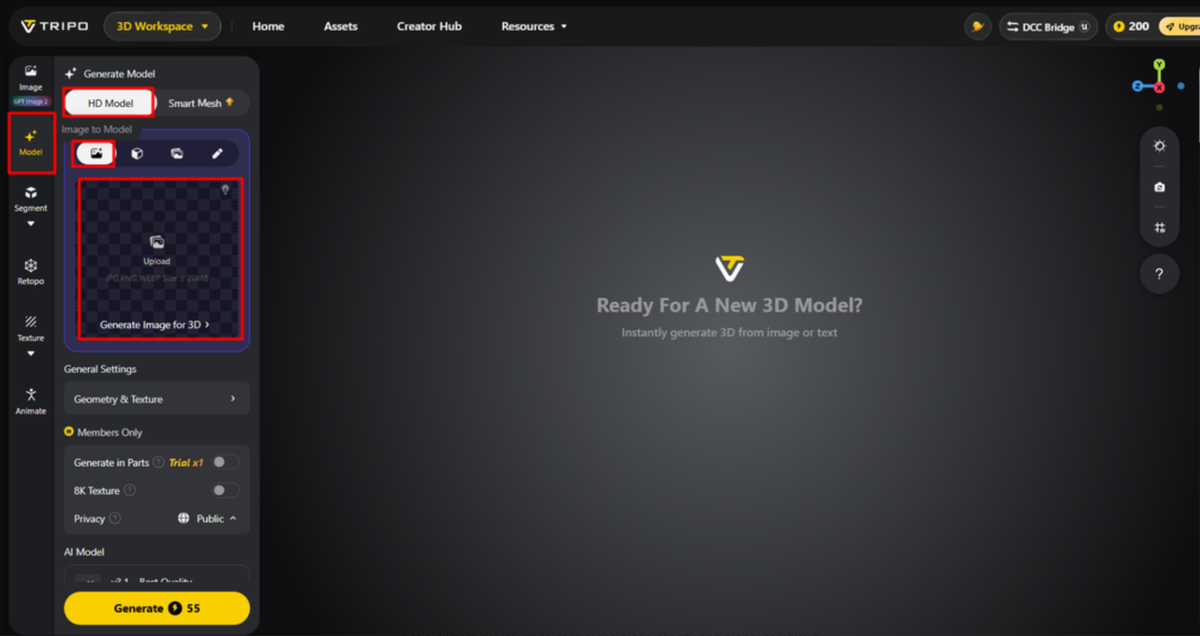
  • First, access Tripo 3D and sign up. Go to the “Model” tab in the vertical left menu bar.
  • Under “Generate Model”, choose “HD Model” to start creating your prototype asset. It will take several minutes to generate your model.
  • Select the “Image to Model” tab. You can drag and drop your reference image into the workspace. You can also click “Upload” and select the image from a specific location on your device.

Step 2: Configure the Prototype Before Generation

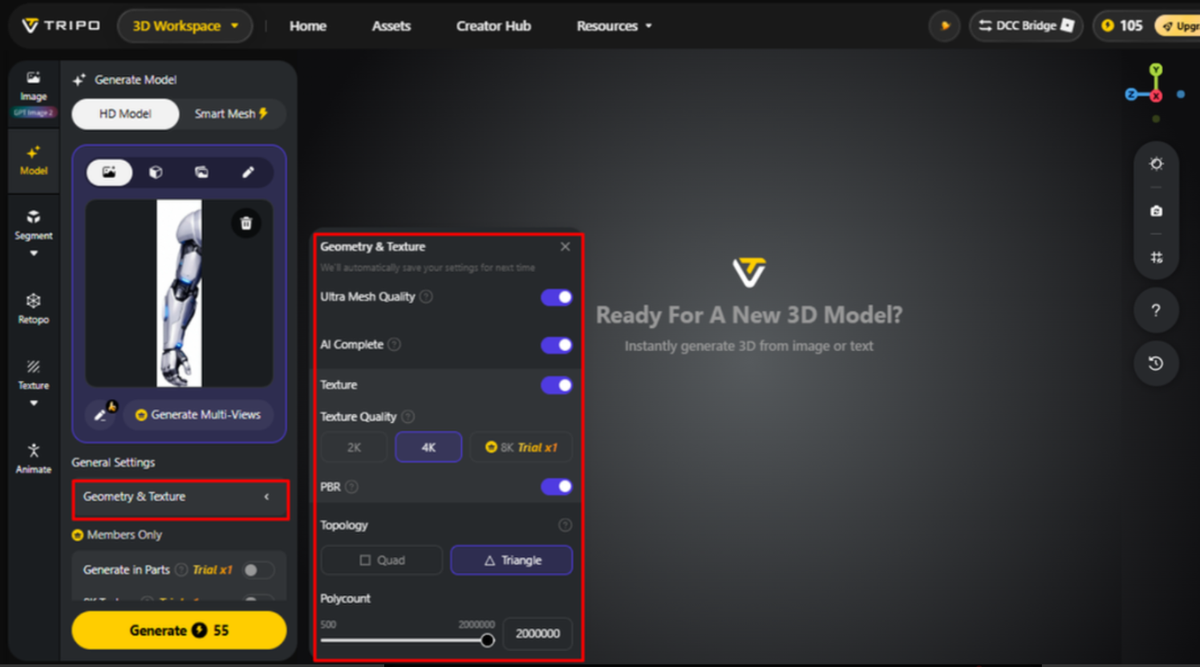
  • Open “General settings” and customize “Geometry and Texture” for the prototype. Turn on “Ultra Mesh Quality” when you need a detailed and realistic model.
  • With “AI Complete” enabled in the “Geometry & Texture panel”, AI can generate both the model’s geometry and texture for you. The option covers both tasks within that panel. Alternatively, activate texture generation and set your preferred “Texture Quality” to 2K, 4K, or 8K.
  • Enable “PBR” when you want accurate material and reflective properties in the generated asset.
  • Select “Quad” or “Triangle” topology based on the structure you want for your prototype.
  • Set a custom polycount to control the mesh density and model complexity.
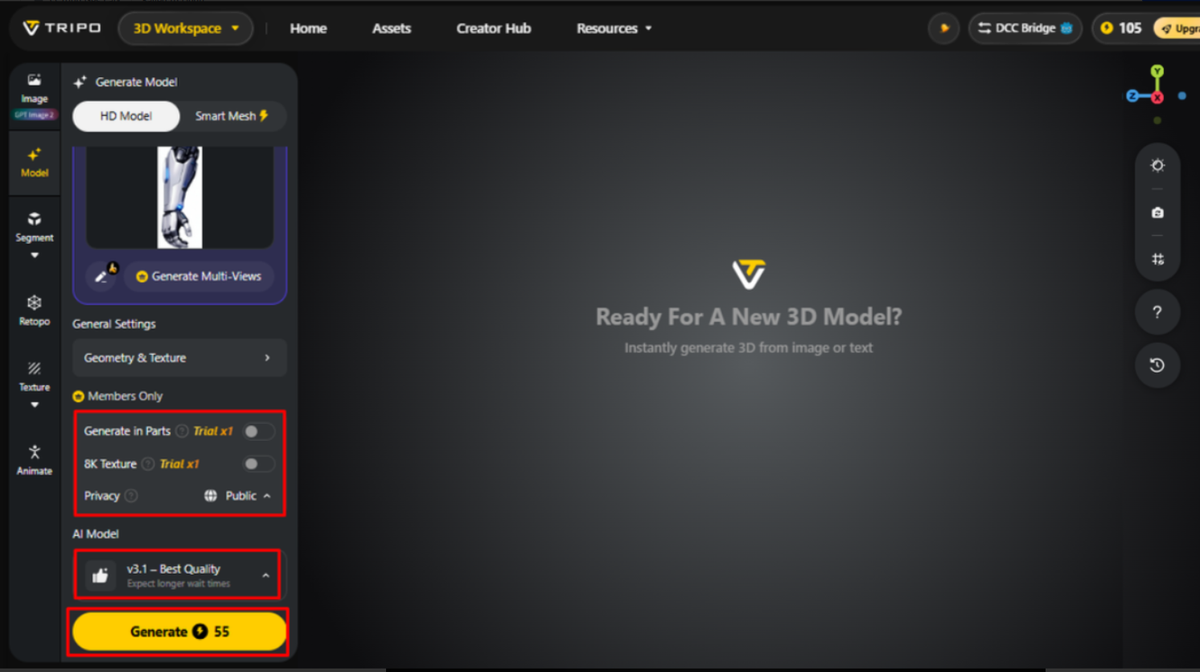
  • Members can test “Generate in Parts”, “8K Texture”, and “Privacy” in the Members Only section, with “Trial x1” offered per session. Note: “Generate in Parts” is charged separately using points.
  • Pick the model that best fits your needs. Tripo offers “V3.1”, “V3.0”, and “V2.5”, with differences in generation quality, stability, and application scenarios. Note: “V3.1” may take more time to complete.
  • Click “Generate Model” to start the rapid asset generation process.

Step 3: Review the Prototype and Export It

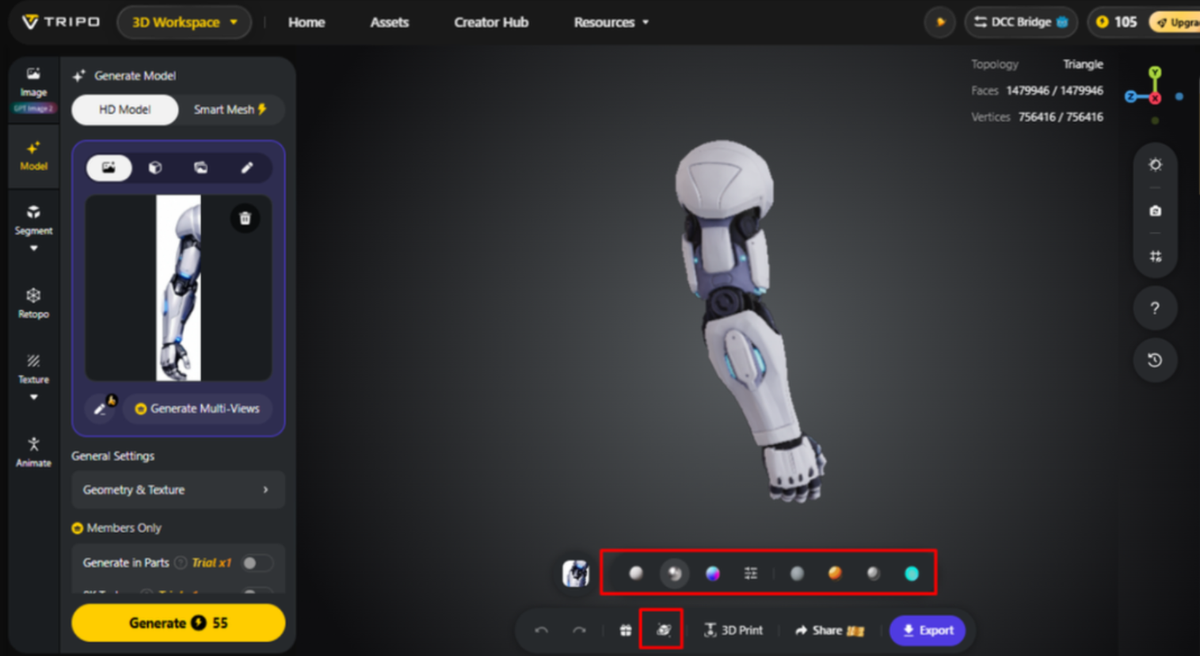
  • After generation, use the available display modes to inspect your model. You can choose Wireframe Mode, White Model View, Texture View, Shader, or HDRI. For additional improvements, simply click “Refine” from the bottom menu.
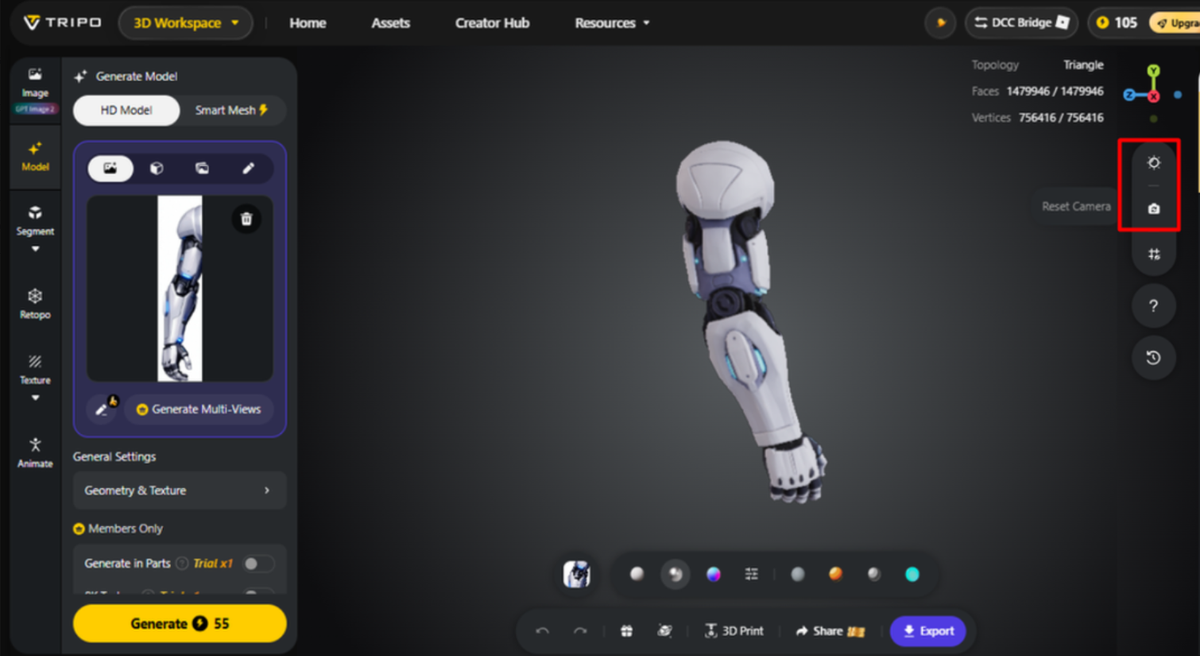
  • You can modify “Environment Settings” and use “Reset Camera” to review the prototype from different angles.
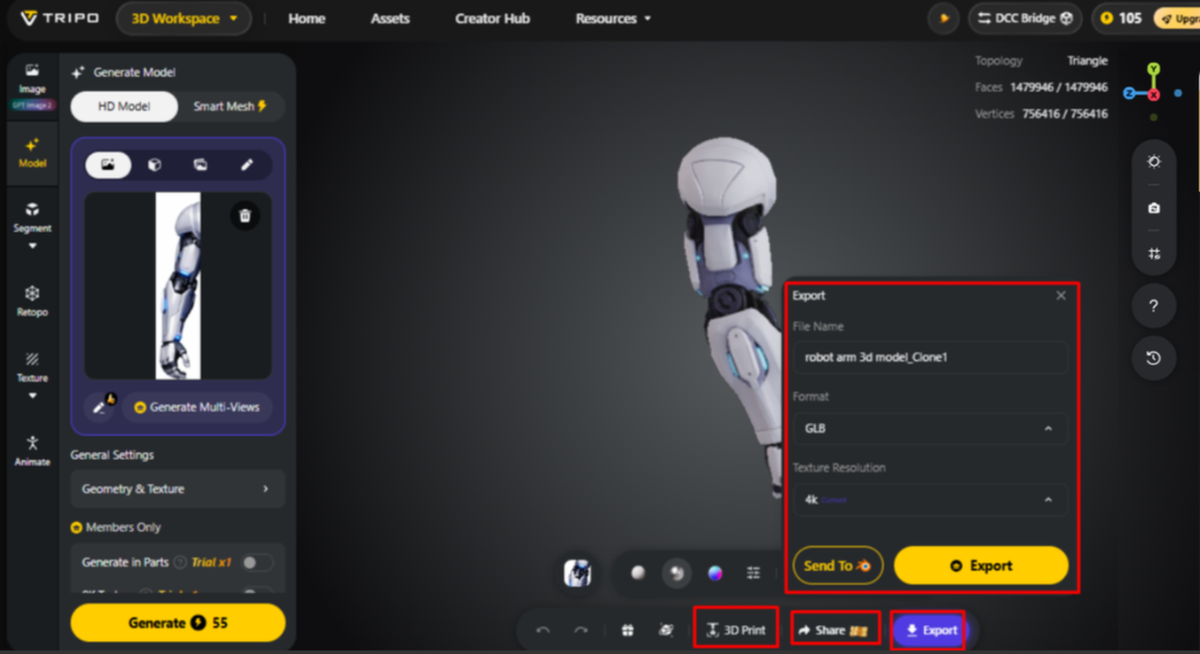
  • When you are satisfied with the asset, you can choose “3D Print” for physical output. You can also click “Share” to share the design directly.
  • Click “Export” from the bottom menu to save the prototype. Select the required resolution, format, and filename, then click “Export” again to save the design to your local device.

Six Settings That Shape Rapid Prototype Asset Generation

  • Detail Selection: Select detail based on visual complexity of prototype and need for structural representation. A more detailed geometry level can be used to model more complex shapes, whereas lower levels can be used for simpler shapes for easier editing later.
  • Polygon Count: Specify a number of polygons commensurate with the geometric detail and downstream uses. Reduced counts can enable rapid iteration when complex surfaces offer little prototype value to explore.
  • Texture Resolution: Choose 2K, 4K or 8K depending on the visual inspection and output requirements. Texture resolution becomes more important if it is a very important factor in the visual assessment of the prototype.
  • Topology Choice: Use quad or triangle topology, depending on the editing and downstream workflow needs. The topology has an effective impact on the behavior of the mesh during the refinement, deformation and subsequent modeling operations.
  • Part Separation: Separate parts for inspection or adjustment by using Generate in Parts. Logical separation can make components easier to change prior to an efficient combination of an editable prototype asset later.
  • Model Version: Choose which Tripo 3D versions are available based on workflow, speed and quality. Each version offers a unique set of generation properties; selection should be carefully based on project priorities.

Using Low-Poly Geometry For Quicker Iterations

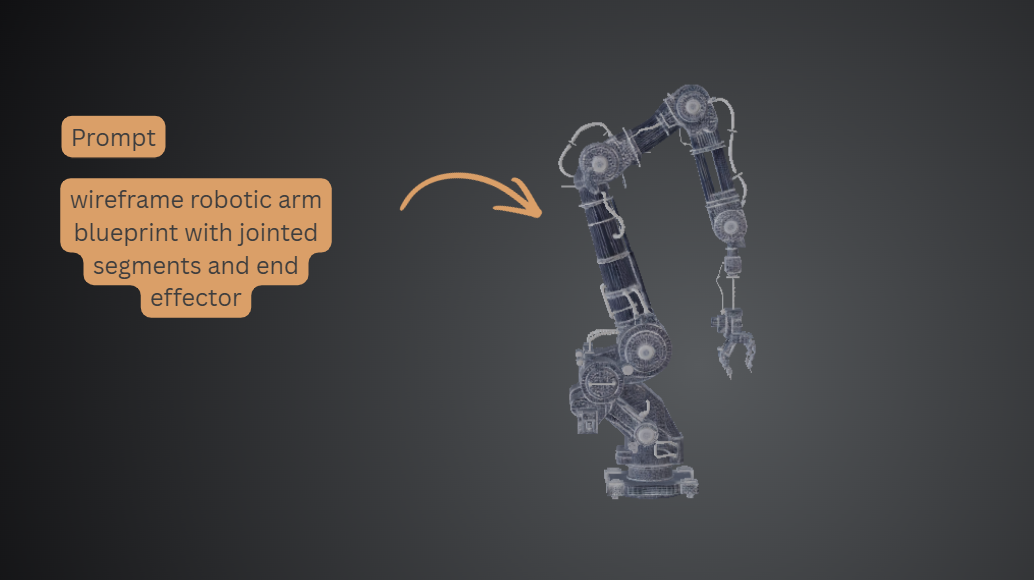
Structured low-poly geometry can enable faster edits in early prototype development and design exploration. With simplified meshes, proportion changes, component tweaks and material previews can be managed efficiently. Polygon control is important in games, visualization, printing and interactive applications where there are varying technical requirements. There is a text to 3d model workflow which allows for concept exploration and image references for guidance. Low-poly output is still valuable when the prototype is about silhouette, placement and overall proportions. When surface curvature or the structure of components is to be represented more closely, more detailed geometry can be used.

Refining Prototype Shapes Before Sharing Or Exporting

Look at important shapes before sharing or exporting, without being distracted from geometry by surface textures. Solid View can surface surprising thicknesses, proportions, missing openings and irregular component boundaries. When further enhancement is needed after detailed review, Refine can be submitted to improve geometry detail and texture quality; this typically takes 1–7 business days, and the refined model automatically replaces the original asset in your library. Different environment settings and camera controls are used to analyze surfaces under various viewing conditions during inspection. Share can be used for design review, and 3D Print can be used for physical prototype evaluation as appropriate. If external software will be used to work with the editable prototype asset after inspection, export should be used.

Moving Prototype Models Into Broader Design Workflows

The export format should be chosen based on the intended next step, since different formats are suited to different visualization and workflow needs. USD is widely used in film, VFX, and other USD-based pipelines for exchanging scene and geometry data. OBJ is a common file format that supports transferring meshes and related geometry and material data between software. FBX is an overall efficient format for workflows that include animation, scene exchange, and other digital content pipelines. GLB is a file format that efficiently stores geometry and other scene information for interactive visualization on the web. STL is used for many processes in the additive manufacturing workflow, based on surface geometry, and topology should be inspected before export. For 3D printing, 3MF can effectively carry additional manufacturing information within supported 3D manufacturing workflows. After importing, check the scale, normals, topology, materials, and component separation in the receiving software.

Conclusion

Image selection, generation, geometry control, inspection, and export form one connected prototype workflow. Each stage affects how faithfully visual references become drafts for subsequent design decisions. Start with simple references, then choose settings based on geometry, texture, and downstream needs. Review the model from multiple viewpoints, and only accept proportions and key part relationships after careful checking. If important structures come out wrong, adjust the inputs or settings and run another full prototype iteration. This is a practical cycle for turning early visual concepts into usable 3D assets without unnecessary modeling complexity.

How AI Is Quietly Reshaping Engineering Team Communication

A recent study of professional developers found that 51 percent now ask an AI tool for technical help instead of asking a teammate first. Not occasionally. As a default. The stuck-on-a-function, not-sure-how-to-structure-this kind of question that used to mean tapping a colleague on the shoulder now goes to a chat window instead.

That’s not developers avoiding their engineering team. It’s a shift in which questions reach the team at all, and which ones get resolved before anyone else needs to be involved.

The same research broke this down by scenario, and the pattern is consistent: 71 percent said they’d turn to AI first when unsure how to implement an algorithm or structure, and 60 percent said the same for breaking a task into subtasks. These are exactly the questions that used to generate a quick Slack message to whoever was online.

Why Developers Are Asking AI First

The same study found 62 percent of developers said it was easier to ask AI a question without worrying about looking unprepared. Interrupting a colleague carries a small social cost every time, even a helpful one; asking a chatbot carries none. That difference alone explains a lot of the shift.

There’s also the wait. A teammate might answer in five minutes or five hours, especially on a distributed team spanning time zones. An AI tool answers immediately, then takes a follow-up question just as fast, which matters most for the kind of small technical question that would otherwise sit unresolved for half a day.

Developers in the study described this as a real change to their focus, reporting fewer interruptions and an easier time staying in flow once routine questions stopped needing a colleague’s attention at all.

AI as a Technical Mentor, Not a Replacement

Developers in the study described AI functioning like a technical mentor for exactly this kind of question: routine, well-defined, and answerable without deep context about the specific codebase. Explaining a language feature, suggesting how to structure a function, walking through a debugging approach. That’s the category shrinking on engineering teams, not technical discussion in general.

The same research found teams weren’t losing collaboration so much as reallocating it. With routine questions handled elsewhere, the conversations that still happen with colleagues shifted toward more complex, higher-value topics instead of trivial troubleshooting. One developer in the study described it plainly: routine dependency-injection questions now go to the AI first, freeing up time with a senior colleague for the problems that actually need their judgment.

What Still Goes to a Colleague

The shift isn’t uniform across question types. In the same study, developers said they’d still rather ask a teammate than an AI tool for clarifying business logic or requirements, and for finding out how something was handled in the past on that specific project. Both call for context a general-purpose tool doesn’t have, no matter how good the tool is at everything else.

That split makes sense: implementation questions are usually about how something works in general, which AI handles well. Questions about why a particular team made a particular decision require someone who was actually there. Sixty-five percent of developers in the study still preferred a colleague for clarifying business logic.

Seventy-three percent also said human collaboration surfaces alternative perspectives AI doesn’t offer on its own, since a chatbot tends to hand back one answer rather than a range of options to weigh.

A Free AI Assistant for the Quick Stuff

Ask AI Questions works as a straightforward AI chatbot free of the friction that makes interrupting a colleague feel costly: type a question, get an answer, ask a follow-up, no account required. As a free AI assistant and a quick AI question answer tool, it fits the exact category of question the research describes moving away from teammates, the kind with a clear answer that doesn’t depend on internal context.

It won’t help with a question about why your team chose a particular architecture two years ago. It works well for everything upstream of that, the routine technical questions that used to interrupt someone for no good reason, whether that’s a quick syntax check or a general explanation of how something works.

Conclusion

The 51 percent figure isn’t a sign that engineering teams are losing something essential. It’s a sign that routine questions finally have somewhere else to go, freeing up human conversation for the parts that actually need a person: context, judgment, and the reasoning behind a decision nobody wrote down. The tool handles the “how.” Your team still owns the “why.”

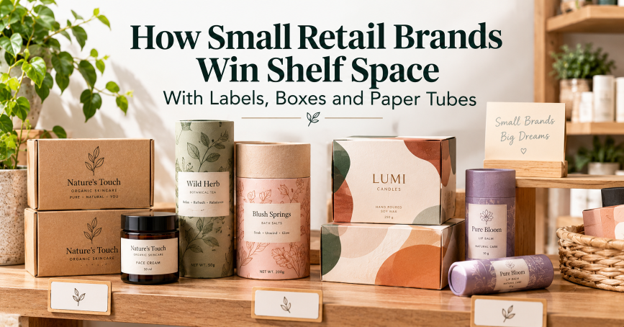
How Small Retail Brands Win Shelf Space With Labels, Boxes and Paper Tubes

Walk into any independent shop on a Saturday and watch how people browse. They don’t read. They scan. A shopper looks along a shelf for two or three seconds, picks up whatever catches the eye, and only then starts reading. For a small brand sitting next to products with national ad budgets, that first glance is the whole game.

The good news is that winning the glance doesn’t take a big budget. It takes packaging that makes a few clear decisions and sticks to them. The brands that punch above their weight on a shelf usually do three things well. They use one strong colour or material so they’re easy to spot from a distance, they put the most important words where the eye lands first, and they choose a pack shape that stands out from the boxes around it.

This piece looks at how small retailers and makers are doing that with three tools that suit short runs, which are printed boxes, product labels and paper tubes.

The Three Second Test on a Crowded Shelf

Before changing anything, it helps to stand three metres back from your own display and look at it as a stranger would. Most owners are surprised by what disappears. Fine script fonts turn into a grey smudge. Pale pastel boxes blend into a white shelf. A logo in the corner of the lid is invisible once the box is stacked.

A few questions sort out most of the problems.

  • Can someone tell what the product is from across the aisle, without reading the small print?
  • Is there one colour, shape or material that belongs to you and nobody else on that shelf?
  • Does the front face of the pack still work when the products are stacked or packed tightly?
  • Is the brand name larger than the decoration around it?

If the answer to any of those is no, the fix is usually in the packaging, not in a new logo.

Choosing a Box Finish That Earns Its Cost

For most retail products the box is the biggest branded surface you own, so the finish on it does a lot of quiet work. It also adds cost, and small brands should know roughly how much before they get attached to a mock-up.

Packaging makers price finishes as an add-on to a plain printed box. One manufacturer’s published comparison gives a useful sense of the trade-offs.

FinishWhat it does on the shelfTypical added costWhere it suits best
Gloss coatingMakes colours look brighter under store lightingAbout 15 percentRetail displays
Matte coatingGives a calmer, premium look with less glareAbout 20 percentLuxury and upscale brands
Spot UVAdds shine to one area such as a logoAbout 25 percentHighlighting a mark or name
EmbossingRaises part of the design so it can be feltAbout 30 percentPremium and gift products
Foil stampingAdds a metallic shineAbout 35 percentAwards and special editions

The practical lesson is that one finish used with purpose beats three finishes used for the sake of it. A matte box with a single spot UV logo reads as confident. A gloss box with foil, embossing and spot UV all competing tends to look busy from a distance, and it costs much more.

The board matters too. Light products such as accessories sit well in 14pt to 18pt cards, medium items need 20pt to 24pt, and heavier goods do better at 28pt to 32pt. A box that bends when picked up undoes any finish on it. Suppliers that offer custom packaging solutions for small businesses now start running from around 100 units, with production in about 4 to 6 business days after approval, which means a brand can test a new finish on one product line before committing the whole range.

Labels Do More Selling Than Most Owners Expect

Not every product needs a printed box. Candles, sauces, skincare, honey and bath products often sit on the shelf in a jar or bottle, and for those the label is the packaging. It is also the cheapest part of the pack to change, which makes it the best place to experiment.

The labels that work in retail tend to share a few traits. The product name is large and set in a plain typeface. The scent, flavour or variant has its own colour so a shopper can find their favourite again without reading. And the material survives being handled, because a scuffed or peeling label makes a good product look tired.

Candle makers have learned this the hard way. A jar gets picked up, sniffed, turned over and put back many times before it sells, and some of that handling happens with warm or damp hands. That is why custom candle jar labels are commonly made waterproof, writable with a permanent marker for batch numbers or burn dates, and removable without residue, so a customer who reuses the jar can peel the label off cleanly. They can be cut to any size or shape, which helps a small brand fit a label to an unusual jar instead of changing jars to fit a stock label.

A simple way to test a new label is to print a short run for one scent, put it on the shelf next to the old design for a month, and compare how often each is picked up and bought. Staff usually notice the difference before the sales figures do.

Paper Tubes as a Shape That Stands Apart

On a shelf full of rectangles, a cylinder gets noticed. That is the simple reason paper tubes have moved from posters and documents into tea, cosmetics, candles, socks and small gifts. The round shape catches light differently, it can stand upright or lie in a tray, and it feels more like a keepsake than a carton does. Plenty of customers keep a nice tube and reuse it, which keeps the brand on a desk or bathroom shelf long after the sale.

Tubes also make the material part of the message. Kraft tubes in a natural brown finish suit brands that want to look honest and low-waste, while black or white paper tubes give a more premium feel for candles and lipsticks. Matte and gloss finishes are both available, and the diameter and length can be set to fit the product rather than the other way round.

For small brands the useful detail is the order size. Printed paper tubes usually come with a standard minimum of 500 pieces, though smaller trial runs can be quoted on request, and typical production runs about 6 to 10 business days. That makes a tube realistic for a limited edition or a holiday gift set, not just a permanent line.

Putting the Three Together Without Overspending

The strongest small-brand displays rarely use every option at once. They pick a role for each piece of packaging and keep the look consistent across all of them. A rough plan that works for many shops looks like this.

  1. Decide on one brand colour or material that will appear on every pack, whether that is a kraft brown, a deep green or a matte black.
  2. Use the label to separate variants, giving each scent, flavour or size its own accent colour.
  3. Save the printed box or tube for the products that carry the best margin or make the best gifts.
  4. Add one finish, such as spot UV on the logo, rather than layering several.
  5. Test on one product line for a season before rolling the change out across the range.

This approach keeps spending focused where it changes buying behaviour. A tube for the hero gift set, a clean label on the everyday range and a well-finished box for the premium product will do more for a shelf than a full rebrand.

What Retailers Notice When the Packaging Is Right

Shop owners who stock small brands say the same thing in different ways. Products with clear, consistent packaging are easier to merchandise, easier for staff to talk about and easier for customers to find again. They also hold up better, because a pack built for handling still looks fresh after a few weeks on display.

For a small brand, that matters as much as the shopper’s reaction. A buyer who sees a product that looks good on a shelf and stays looking good is more likely to reorder and to give it a better spot next time. The packaging is doing two sales jobs at once, one with the customer and one with the store.

The Short Version for a Small Brand

Shelf presence isn’t about spending more than the brand next to you. It is about being recognizable in the time it takes someone to glance along an aisle. Pick one colour or material and own it, let labels do the detailed work, use a distinctive shape like a tube where it adds something, and choose finishes one at a time. Small runs make it possible to test each change before betting the whole range on it, and the shelf will tell you quickly which ones were worth it.

How Retail Brands Can Use AI for Product Descriptions Without Sounding Robotic

Open the outerwear category on almost any mid-sized retailer’s site in late October and read five parka descriptions in a row. “Stay warm and stylish all winter long.” “Crafted for comfort and designed for adventure.” “The ultimate layer for cold-weather days.” By the third one your eyes slide off the page, and by the fifth you can’t remember which jacket had the removable hood. Nobody wrote those sentences on purpose. A tool generated them in bulk, someone skimmed them for typos, and they went live alongside 300 others the same afternoon.

I’ve spent a fair amount of time cleaning up catalogue copy for retail teams, and the pattern is very consistent. The AI didn’t fail. It did exactly what it was asked, which was “write a product description for a women’s insulated parka.” The prompt had no facts in it, so the model filled the gap with the most statistically likely words about parkas. Those words are the same ones every other retailer’s model reached for.

So the fix sits mostly upstream of the writing. It lives in what you feed the tool, how you edit the output, and who on the team gets the final say.

Start with a fact sheet, not a prompt

The single habit that changes AI product copy the most is building a short fact sheet for each SKU before anyone opens a chatbot. It doesn’t need to be fancy. A spreadsheet row works. What matters is that it contains information only your business has.

For that parka, a useful fact sheet might look like this:

  • Fill: 650 fill power responsibly sourced down
  • Shell: matte nylon with DWR finish, sheds light snow and freezing drizzle
  • Length: hits mid-thigh on a 5’6” model wearing size S
  • Hood: removable, faux fur trim detaches separately
  • Pockets: two hand-warmer pockets with fleece lining, one interior zip pocket that fits a large phone
  • Fit note from returns data: runs slightly small in the shoulders, customers layering a thick sweater size up
  • Store staff comment: “People like that it doesn’t look puffy from the side.”
  • Care: machine wash cold, tumble dry low with dryer balls

Notice the last three lines. The fit note comes from your returns system. The staff comment comes from someone on the floor at your Yorkdale or Rideau location who has watched people try it on. Those details are the ones a generic model will never invent, and they are the ones that make a shopper trust the page.

Then the prompt becomes something closer to this:

Write a 90 to 120 word product description for the parka below. Audience: commuters in Toronto and Ottawa who take transit and walk 10 to 15 minutes in winter. Use only the facts provided. Do not use the words “ultimate”, “stylish”, “perfect”, or “must-have”. Mention the sizing note plainly. Plain, warm tone, short sentences, Canadian spelling. [paste fact sheet]
The “use only the facts provided” line does a lot of work. It stops the model from claiming the jacket is rated to minus 40 when nobody tested that, which is a legal problem as well as a tone problem.

Ban list, house style, and a few sample paragraphs

Every brand has words it overuses. Every model has words it overuses too, and the two lists overlap more than you’d expect. Pull the last 50 descriptions your team wrote by hand, the ones people liked, and read them out loud in a meeting. You’ll hear your own voice in maybe ten of them. Paste two or three of those into your prompt as examples of tone, and paste a ban list of the words that make you wince.

A typical ban list for apparel and home goods includes “ultimate,” “effortless,” “timeless,” “versatile,” “must-have,” “perfect for any occasion,” “take your X to the next level,” and “look no further.” Your list will differ. A hardware retailer probably has a separate set of tired phrases (“tackle any project”) that a fashion brand never sees.

House style also covers the small mechanical stuff: whether you write “colour” or “color” (for a Canadian audience, almost always “colour”), whether you use centimetres first or inches first, whether sizes are written “S/M/L” or “Small, Medium, Large.” Models get these wrong unless told, and inconsistent units across a category page look careless.

Where an AI humanizer fits in the workflow

Even with a good fact sheet, first drafts often come back with a recognisable rhythm: three short clauses, a benefit, a call to action, repeated across every SKU. When you’re producing a few hundred descriptions for a seasonal drop, rewriting each one from scratch defeats the purpose of using AI at all. This is where a rewriting pass helps. Running the draft through an ai humanizer varies the sentence structure and loosens the stiff phrasing so the copy reads less like a template, while keeping the facts you supplied. Quillbot’s version, for example, lets you paste the draft and get back a smoother rewrite you can then edit line by line.
Treat that step as a middle pass, not a finish line. The tool can change how the sentences sound. It can’t know that your Quebec customers hate the word “puffer” or that the zip pocket is the thing everyone mentions in reviews. A person still has to read every description before it ships, and they should be checking for three things specifically:

  1. Every factual claim matches the fact sheet. Rewriting tools occasionally soften “machine wash cold” into something vaguer, or drop a measurement.
  2. The sizing and care notes survived intact.
  3. The description sounds like it belongs on your site and not on a competitor’s.

A before and after

Here is a real-shaped example, built from the parka fact sheet above.

First AI draft (generic prompt, no fact sheet):

Stay warm and stylish all winter long with our Women’s Insulated Parka. Crafted with premium materials and designed for ultimate comfort, this versatile jacket is perfect for everything from city commutes to weekend adventures. Its timeless silhouette and thoughtful details make it a must-have for your cold-weather wardrobe.

Nothing in that paragraph is false, exactly. Nothing in it is useful either. A shopper learns zero about the jacket.

After fact sheet prompt, rewrite pass, and human edit:

Built for the walk from the subway to the office when the wind comes off the lake. 650 fill power down keeps the core warm without the marshmallow look from the side, and the matte shell shrugs off light snow and freezing drizzle. It falls to mid-thigh. The hood comes off, and so does the faux fur trim, separately. Two fleece-lined hand pockets, plus an inside zip pocket that fits a big phone. Sizing note: it runs a little narrow in the shoulders, so if you plan to wear a chunky sweater underneath, go up a size. Machine wash cold, tumble dry low with a couple of dryer balls.

The second version is longer, but every sentence carries something. And it reads like a person who has seen the jacket.

Bilingual copy needs its own pass

Retailers selling into Quebec already know the French requirements are not optional, and product information has to be available in French. AI translation from English has improved a lot, but direct translation of marketing copy still produces French that sounds translated. Quebec shoppers spot it immediately. The idioms come out European, or the sentence structure follows English word order a little too faithfully.

The better approach is to generate the French version from the same fact sheet rather than translating the finished English copy. Give the model the facts, tell it to write for a Montréal or Québec City shopper in Québécois French register, and have a francophone team member review it. Translating the English draft means you inherit every quirk of the English draft, plus a translation layer on top. Starting from facts means each language gets its own natural phrasing. ## Different products need different lengths

One mistake I see often is a single prompt template applied to the whole catalogue. A $14 pack of tea towels does not need 150 words. A $1,200 sectional sofa probably needs more than 150, plus dimensions, delivery notes, and fabric care.

A rough split that works for a lot of general retailers:

Product typeTypical lengthWhat the shopper actually needs
Low-cost consumables and basics30 to 60 wordsSize, quantity, material, one use note
Apparel and footwear80 to 130 wordsFit, fabric feel, care, sizing advice from returns
Electronics and small appliances100 to 150 words plus spec tableCompatibility, what’s in the box, warranty
Furniture and big-ticket home150 to 250 words plus spec tableDimensions, assembly, delivery, materials, care

Set separate prompt templates for each tier, and you stop trimming 140-word descriptions of dish soap.

What to keep human, always

Some parts of the description should never be AI-generated without a person checking them against a source document:

  • Safety and compliance claims (CSA certification, flammability, age grading on toys)
  • Warranty terms
  • Allergen or ingredient lists on food, cosmetics, and supplements
  • Origin claims (“Made in Canada” has specific rules attached, and “Product of Canada” has stricter ones)
  • Sustainability claims, which the Competition Bureau has been paying closer attention to

For these, paste the exact wording from the supplier spec sheet or your compliance team, and tell the model to reproduce it verbatim. Then check that it did.

Building it into a team process

A merchandising team of four can comfortably handle a few hundred descriptions a week this way, if the steps are clear. One workable setup:

  1. Buyers or product managers fill in the fact sheet when the SKU is set up, including the fit or use notes from samples.
  2. A copywriter or ecommerce coordinator runs the generation prompts in batches by category.
  3. The drafts go through a rewrite pass to break up repetitive phrasing.
  4. A second person reads every description against the fact sheet and the brand voice examples.
  5. Store staff feedback and early reviews get added to the fact sheet after launch, and the top-selling SKUs get their descriptions refreshed once real customer language is available.

Step five is the one most teams skip, and it’s the one that keeps the copy alive. Three weeks after launch, your reviews will tell you how customers describe the product in their own words. “Finally a jacket my arms can move in” is better copy than anything a model will produce, and it costs nothing to borrow the idea (paraphrased, with the reviewer’s words left in the review section where they belong).

Common mistakes

Generating from the product title alone. This produces the generic paragraph every time. No fact sheet, no useful copy.

Letting the model invent specs. Watch for temperature ratings, waterproof ratings, battery life figures, and thread counts that nobody gave it. These are the claims that end up in complaint emails.

Running everything through the same voice. Your kids’ department and your premium kitchen line probably shouldn’t sound identical, even if the brand voice is consistent overall.

Skipping the read-aloud. Read three descriptions in a row out loud. If you hear the same sentence shape three times, so will your customers. ## Tools and the people using them

AI does well at producing a first draft quickly and at rewriting the tenth description of a similar item so it doesn’t echo the ninth. It’s weaker at knowing which detail matters most to your customer, and it has no idea what your store staff hear at the fitting room. Feeding it those details is the job.

Using a rewriting tool on drafts that came out stiff is fine, and an ai humanizer is useful when you have a long run of near-identical products (twelve colourways of the same merino crewneck, say) and need each page to read a little differently without changing the facts. Just keep the fact sheet open beside it. The tool handles rhythm and phrasing; your team handles truth and judgment. ## FAQ

Will shoppers notice if product descriptions are AI-written? They notice generic writing, regardless of who wrote it. Descriptions built from specific facts, fit notes, and real use details rarely read as machine-made, even when a tool did the first draft.

Should we disclose that AI helped write product copy? There’s no general requirement in Canada to label AI-assisted product descriptions right now. What matters legally is that the claims are accurate. Some brands mention their process in an “about our content” page, which is a reasonable choice but not a standard one.

How often should descriptions be refreshed? Top sellers deserve a look after the first wave of reviews comes in, usually within a month or two of launch. Everything else can wait for the next seasonal update or a change in the product spec.

One small test to run this week

Pick your ten best-selling SKUs. Pull up the current descriptions and, for each one, write down a single fact a shopper would want that isn’t on the page right now: a sizing note, a care quirk, a staff observation, a common question from customer service. Then rebuild those ten descriptions from a fact sheet using the steps above and compare them side by side with the originals in a quick team review. You’ll know within an hour whether the process is worth rolling out to the rest of the catalogue, and you’ll probably find two or three of the old descriptions had a factual error nobody noticed.

From Amazon-Only to Four Major Retailers in Under a Year: Inside COOFANDY’s Omnichannel Expansion

A case study in how one DTC menswear brand sequenced its move from a single marketplace into Walmart, Target, and Kohl’s – and what the timeline suggests about the playbook other digitally native brands are starting to follow

Just under a year ago, COOFANDY was a menswear label most people had encountered, if they’d encountered it at all, through an Amazon search result. Today the brand sells through four major retail partners – Amazon, Walmart, Target, and Kohl’s – alongside its own direct-to-consumer site. That’s a fast, deliberate omnichannel build for a company that spent its first decade as a single-marketplace operation, and the sequencing behind it is worth more attention than the announcements themselves got individually.

COOFANDY launched in 2015 as an Amazon-first label: versatile, fairly priced menswear sold directly online, without the overhead of a traditional retail footprint. During this period, Amazon accounted for the vast majority of COOFANDY’s revenue, with annual sales exceeding $6 million in gross merchandise value. The model worked well enough to get the brand to more than 70 million customers across more than 30 countries over eleven years, but it also meant COOFANDY’s growth ceiling was tied to a single channel’s algorithm and customer base.

The 2026 retail expansion didn’t happen all at once, and the order it happened in tells its own story. Walmart came first, chosen for reach more than positioning – it’s where a broad swath of COOFANDY’s existing customer already shops for everything else. Target followed, aimed more deliberately at a design-conscious shopper, effectively testing whether COOFANDY’s growing design-award recognition would resonate outside its existing customer base. Kohl’s came third and arguably fits most naturally of the three: unlike the general-merchandise retailers ahead of it on the list, Kohl’s built its identity specifically around apparel, putting COOFANDY in front of a retailer whose core shopper already thinks about clothing the way COOFANDY’s does.

There’s a timing angle worth flagging for a trade audience too: fall is peak promotional season for men’s apparel, and this expansion is landing squarely inside that window. A new vendor showing up on a retailer’s shelves during a slower stretch of the calendar has to fight for merchandising attention on its own; one arriving as retailers are actively building out and pushing fall assortments gets folded into a push that’s already underway.

That sequencing lines up with something else that happened in 2025, just ahead of the expansion: COOFANDY picked up three separate design honors – Silver recognition from the MUSE Design Awards, the Berlin Design Awards, and the New York Product Design Awards – plus a placement on CNN Underscored’s list of editor-recommended menswear. For a brand negotiating shelf space with national retailers, that kind of third-party validation functions less as marketing copy and more as a credibility signal in the room during buyer conversations, even if it’s rarely stated that directly.

Since the 2026 retail expansion began, COOFANDY’s total omnichannel order volume has grown by approximately 34%, with brand search volume up 33% over the same period – an early signal that the new retail partnerships are generating incremental demand rather than simply redistributing existing customers across more checkout options.

“We didn’t set out to collect retailers,” said Sidney Sun, Chief Marketing Officer at COOFANDY. “Each one solved a specific distribution problem we actually had. The sequencing wasn’t random – it followed where we thought we had the strongest case to make, in the order we thought we could make it.”

Whether COOFANDY’s specific sequence becomes a template other digitally native brands follow remains to be seen, but the shape of it – build credibility first, then use that credibility to move into retail deliberately rather than opportunistically – is a more disciplined version of a jump plenty of DTC brands attempt and fewer manage cleanly. For now, COOFANDY’s footprint sits at four major retail partners plus its own site, built out in under a year. Whether that number grows further is not yet confirmed.

From The Desk: Retail Growth Divides and AI’s Expanding Role in Canadian Retail

Canadian retail continues to be a mixed bag, and the differences between who’s growing and who’s struggling are becoming increasingly apparent. Value-focused retailers are finding opportunities to expand, while premium brands continue investing in stores and experiences that attract customers willing to spend. It’s a tougher environment for many retailers in the middle, particularly those struggling to give shoppers a compelling reason to visit.

We’re also seeing some interesting developments in retail real estate. Grocery-anchored shopping centres remain in demand, with limited available space and healthy leasing activity. At the same time, landlords are facing some expensive decisions about what to do with former department stores and other large retail spaces. Some of these properties present tremendous opportunities, although repositioning them can be complicated and costly.

Technology is another area worth watching. Artificial intelligence is increasingly finding its way into everyday retail operations, from inventory management and merchandising to marketing and supply chains. There’s considerable potential here, although retailers will need to determine where these investments actually deliver results.

What stands out to me is how differently retailers are responding to the same economic environment. Some are expanding aggressively, others are becoming more selective about where they invest, and some are having to rethink their businesses altogether. We’ll continue watching how these decisions play out across Canada’s retail landscape.

Here are some of the stories and developments that caught our attention this week.

Retailer News

Aritzia is expanding its North American footprint with plans for more U.S. store openings, larger retail spaces and repositioning of locations in Quebec and California, reflecting strong boutique sales and increased customer traffic. This approach confirms the continuing relevance of physical retail within its omnichannel strategy, offering insights for landlords and investors about where retail investment can succeed amid changes in consumer behaviour.

Alimentation Couche-Tard agreed to acquire retail locations, fuel supply agreements and 18 cardlock sites from Irving Oil in Quebec and Ontario, pending regulatory approval, increasing its presence in these key markets. This transaction strengthens Couche-Tard’s integration of fuel supply with convenience retailing, a relevant development for commercial real estate stakeholders tracking asset ownership and market consolidation.

Canadian retail reports for the third quarter of 2026 show a mix of growth and caution across sectors with overall investment in retail real estate, technology and operations continuing but with an eye on changing consumer behaviour and market selectivity. While grocery retailers expanded and repositioned capacity through discount format conversions and new specialty formats, underlying volume growth remained minimal, highlighting pressures on profitability and the need for strategic property usage amid evolving online fulfillment needs. Foodservice sales increased during the same quarter with chains investing in renovations, delivery partnerships and loyalty programs, but tight margins and selective consumers require careful management to ensure sustainable growth and site viability for landlords and operators.

Individual retailers reported notable financial performances, underlining the challenges and opportunities in different retail categories. Aritzia’s fiscal 2027 second quarter results showed a 44.1% increase in net revenue, reaching $1.17 billion, driven by strong comparable sales growth and digital and U.S. market expansions, reflecting effective real estate and digital channel investment. Kits Eyecare also showed significant gains, with total revenue rising 21.6% year-over-year in Q3 to about $63.7 million, boosted by the glasses segment’s 59.3% growth and a balance sheet free of debt, underscoring the value of diversified product lines in retail growth.

Retailer People News

IKEA Canada CEO Selwyn Crittendon will leave his post at the end of December to become Deputy CEO of IKEA U.S., a move that could alter the home furnishings retailer’s approach across North America especially as it pursues growth and sustainability goals. The company has yet to name his Canadian successor, leaving some uncertainty for Canadian retail landlords and suppliers who have worked with Crittendon on store expansion and community initiatives.

The fashion sector features two notable Canadian designers focusing on sustainable growth in distinct ways. George Sully stresses the challenges Canadian designers face scaling nationally amid limited industry infrastructure and the necessity of forging equitable retail partnerships to turn visibility into lasting commercial success. Joseph Tassoni exemplifies a deliberate growth strategy through his recent Natural Authority runway and Oakville showroom, emphasizing direct customer engagement and experiential retail to build brand loyalty and manage expansion cautiously.

Retailer Op-Eds

Canadian retail continues to show a clear divide between value-oriented and premium-focused retailers, pushing mid-tier operators to find sharper ways to differentiate themselves through new store formats and technology adoption. Retailers increasingly embrace AI-driven customer engagement tools alongside franchising growth to enhance operational efficiency and respond to shifting consumer behaviours. Meanwhile, the Competition Bureau’s investigation into minimum advertised pricing policies reveals a tension where pricier MAP rules limit how discount grocers promote deals, while also offering protection for independent retailers competing against bigger national chains with stronger buying power. This dual effect influences pricing strategy decisions and retailer viability, creating complex dynamics for landlords and suppliers managing space in Canada’s concentrated grocery market.

Editor’s Take

The divide in Canadian retail continues to widen. Value-focused retailers are attracting cost-conscious shoppers, while premium brands are investing in larger stores and better customer experiences. Aritzia is one example of a retailer taking a selective approach to expansion, concentrating on locations where it sees strong sales potential. For retailers caught in the middle, the pressure is mounting. Store space is expensive, inventory needs to move, and customers have plenty of alternatives. Having a recognizable brand is no guarantee of success.

Retail landlords are dealing with a very different set of circumstances depending on the properties they own. Grocery-anchored centres continue to perform well, with low vacancy and strong demand from tenants. Former department-store spaces are another matter. Redeveloping these large properties can require substantial investment, complicated construction work and years of planning. We’re seeing landlords explore combinations of grocery stores, entertainment, restaurants and smaller retail tenants to bring these spaces back into productive use. Concepts such as TM Wander and The Rec Room also show how shopping centres are incorporating more reasons for people to visit beyond traditional shopping.

Artificial intelligence is becoming a bigger part of retail operations, and I’m particularly interested in how this develops. Companies such as Canadian Tire, Loblaw and Instacart are using the technology across areas including merchandising, customer engagement and fulfilment. There’s potential for meaningful improvements, although implementation can be expensive and results will depend heavily on the quality of the underlying data. AI is also changing how consumers discover products online, creating another challenge for retailers trying to understand where their customers are coming from and which marketing investments are working.

One area that deserves more attention is the pressure on smaller independent retailers. Rising operating costs, property taxes and other expenses are making it difficult for some businesses to expand or even maintain their existing locations. These retailers contribute considerably to the character and economic activity of communities across Canada, and their challenges shouldn’t get lost in the headlines about major chains opening new stores.

Looking across this week’s developments, it’s apparent that there are still opportunities for growth in Canadian retail, although success increasingly depends on choosing the right locations, managing costs carefully and understanding what customers actually want. We’ll be watching how these trends develop in the months ahead.

This Week’s Articles

Retailer News

Retailer People News

Retailer Op-Eds

News From Around the Web

Toronto Fashion Label Demascaré Expands Into Ready-to-Wear as Shaun Mascarenhas Eyes Retail Growth

Toronto fashion designer Shaun Mascarenhas is moving Demascaré into its next stage, expanding the independent label into ready-to-wear as he works to build a stronger commercial business around the aesthetic that first brought his work attention.

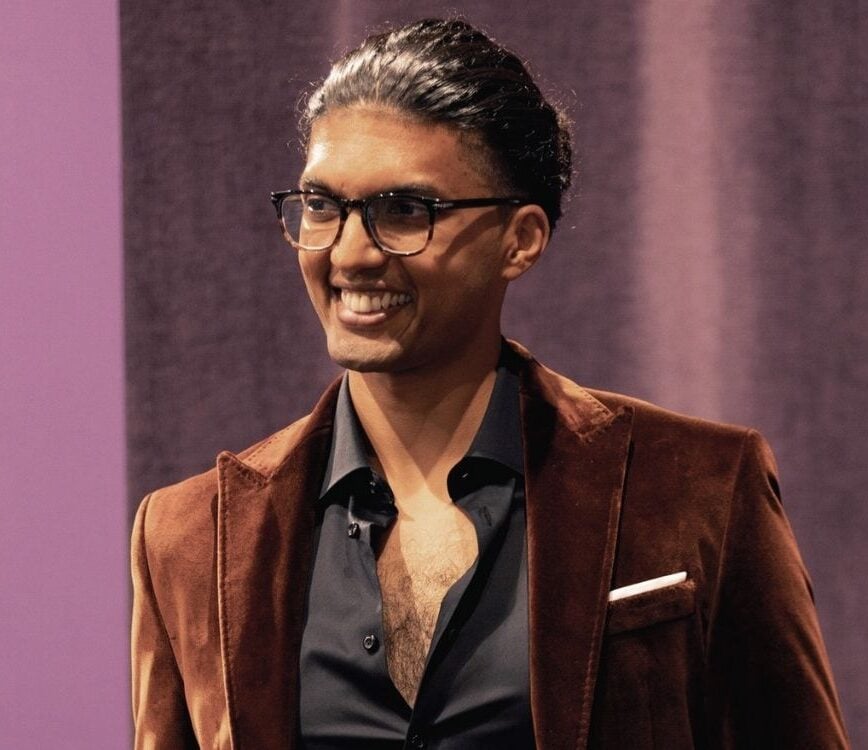
Shaun Mascarenhas

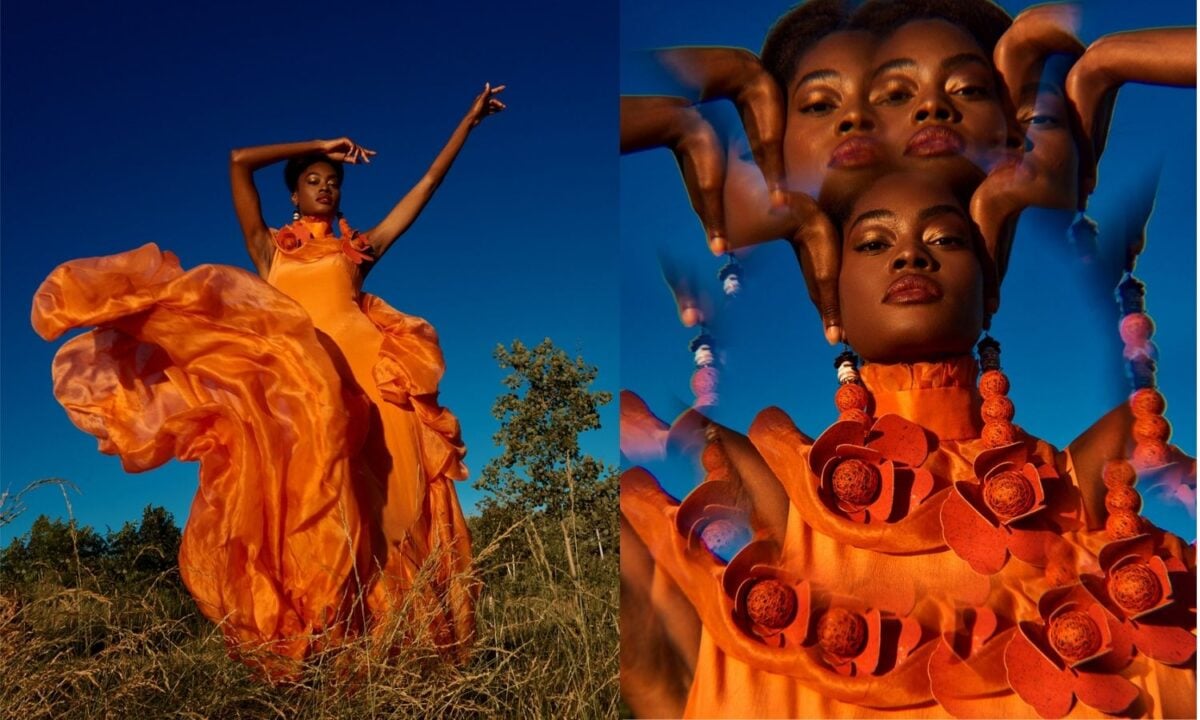
The Toronto-based brand has so far been known largely for custom work, demi-couture and expressive statement pieces. Mascarenhas is now developing clothing that can move more easily through retail while retaining the draping, fit and architectural elements associated with Demascaré.

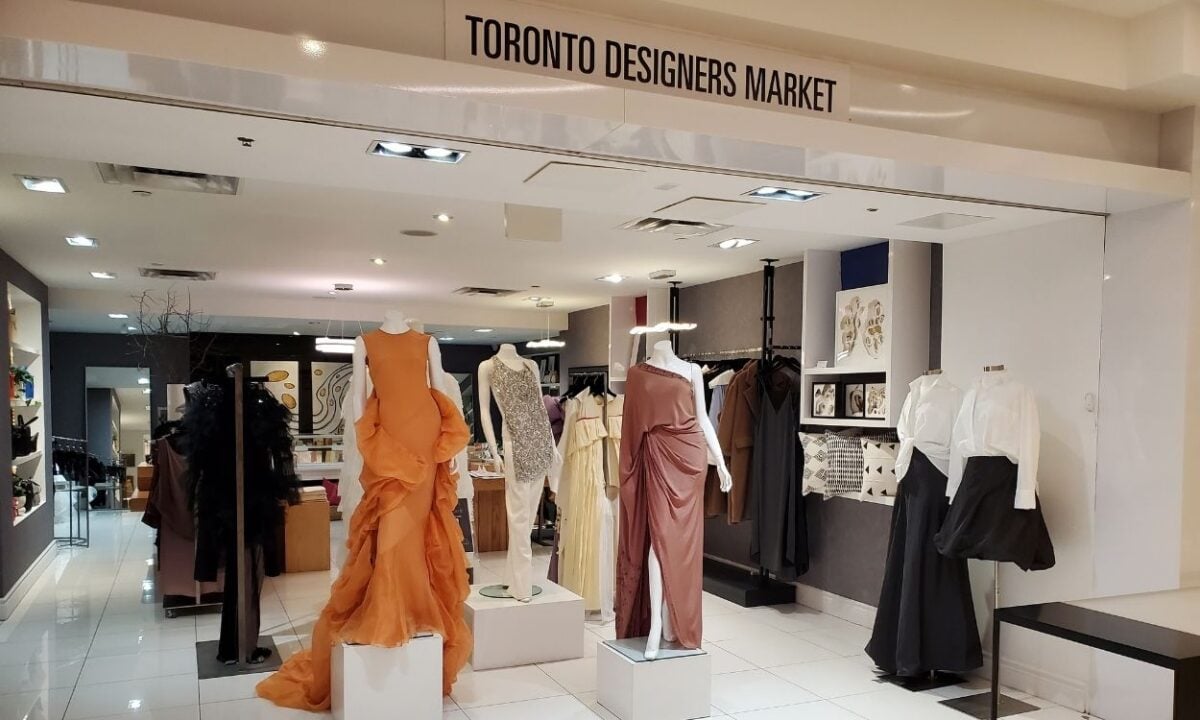
The shift comes as the brand establishes a clearer retail presence. Demascaré is currently sold through Toronto Designers Market at the Holt Renfrew Centre on Bloor Street, its only physical retail location, while a broader ready-to-wear assortment is being prepared for online sale. Mascarenhas is also beginning to explore selective wholesale distribution.

“I just completed a year with the store,” he said of Toronto Designers Market. “It’s been a great learning experience. I’ve had some really good months and some really slow months, so I’m still trying to understand the business.”

From Architecture to Fashion

Mascarenhas was born in India and originally pursued architecture before realizing early in his studies that he did not see it as a lifelong career. He remembers sitting in the studio late one night when the question occurred to him: could he imagine doing this for the rest of his life? His answer was no.

Supported by his parents, Mascarenhas shifted into fashion, later studying in the United States and moving to New York, where he secured an internship in the atelier at Oscar de la Renta. The experience exposed him to the technical side of high-end fashion and garment construction at a level that would continue to influence his own work.

His architectural training also stayed with him. Structure, proportion and linearity continue to appear in his silhouettes, often balanced by draping and movement.

His early career included experience around designers and fashion houses including Zac Posen, J. Mendel and Romona Keveza. After relocating to Canada, Mascarenhas spent years working in Toronto’s bridal and eveningwear sector. The pandemic ultimately prompted him to reconsider where he wanted his career to go and whether it was time to create something of his own.

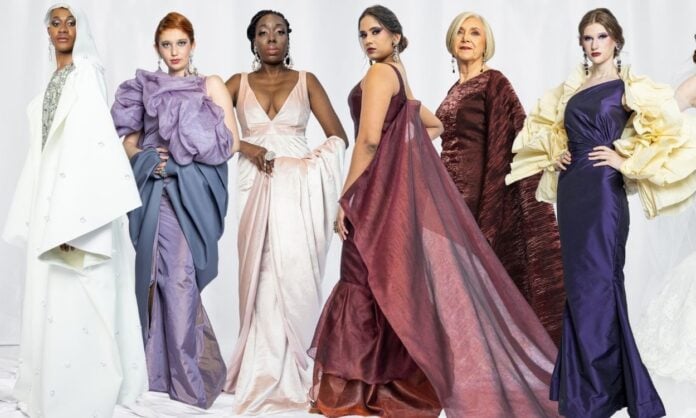
Demascaré Pimentel CAFA2023 DonnaBishop BrionyDouglas HillaryLeBlanc

Building Demascaré During the Pandemic

Mascarenhas launched Demascaré during COVID after years spent helping create collections for other companies. The name combines elements of his middle and last names, allowing him to establish a brand identity separate from his personal name.

That separation was deliberate. Mascarenhas wanted the company to stand independently from him and potentially develop value beyond his identity as its designer. Sustainability was also part of the concept from the beginning.

“I didn’t just want to be another designer who bought fabric off Queen Street and made clothes,” he said.

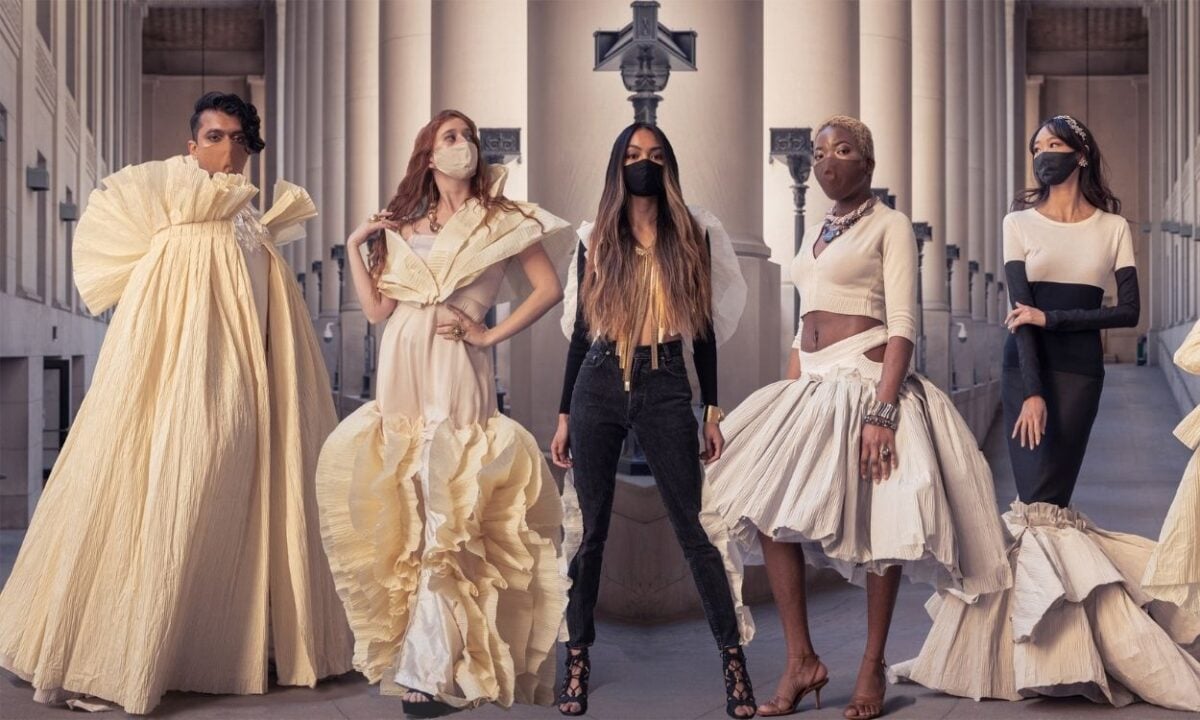
His first major collection pushed that thinking in an experimental direction. Mascarenhas worked with paper that would otherwise have been discarded from fabric pleating processes and layered it over existing garments brought in by models, altering and repurposing those pieces in the process.

The resulting collection was presented through Fashion Art Toronto at Union Station. Stylists subsequently began contacting Mascarenhas to borrow garments for editorial shoots, giving the young label early visibility and showing him that people were responding to the originality of the work.

What happened with his next collection would prove equally influential.

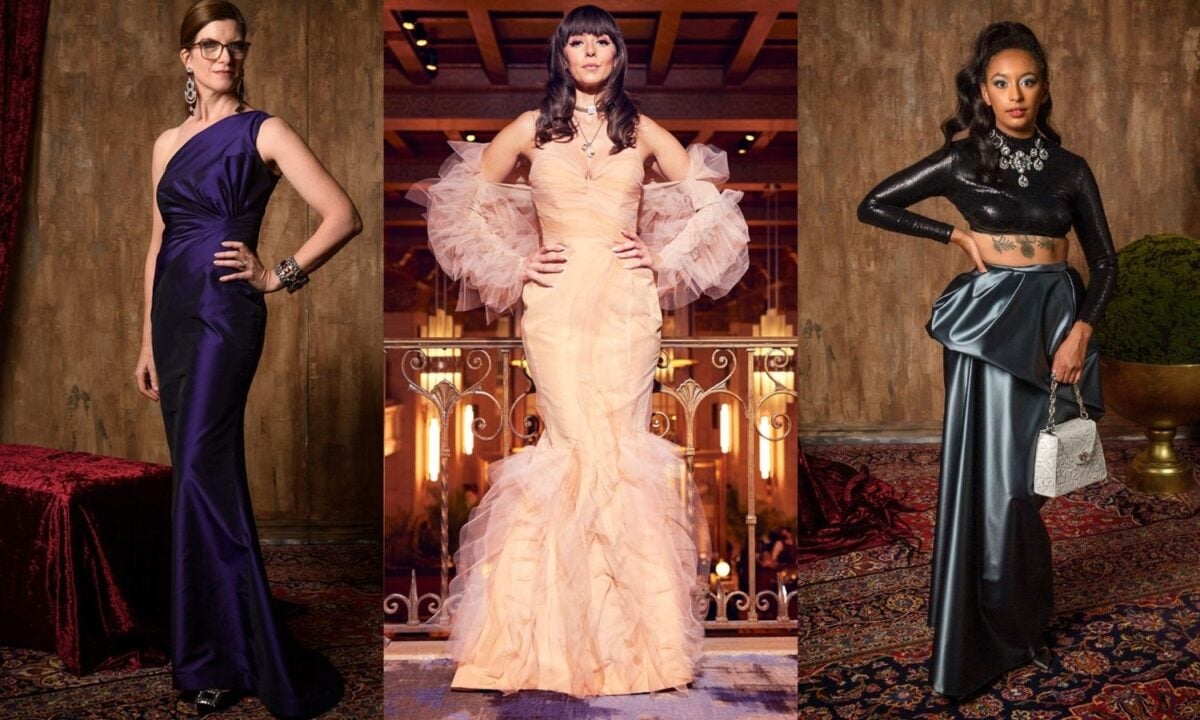
Demascaré ArielLii ChristalWilliams

An Early Lesson in What Makes a Brand Sell

After attracting attention with highly distinctive pieces, Mascarenhas decided his next collection should be easier to sell. He made the clothing more conventional, expecting that a more commercial assortment would appeal to a wider group of customers.

The response was weak.

“I was thinking, ‘This is very sellable. Why isn’t anybody buying it?’” he recalled.

The feedback he eventually received was straightforward: people had been interested in his original work precisely because it was different. In trying to make Demascaré more broadly commercial, he had removed some of what made the label recognizable.

Mascarenhas stepped back, spent more time learning the Toronto and Canadian market and returned to eveningwear and custom pieces. A later collection led to an early custom order for a client attending the Canadian Arts & Fashion Awards, and Demascaré gradually developed a business around one-of-a-kind and made-to-measure clothing.

The custom work gave Mascarenhas considerable experience with clients, fit, alterations and the practical realities of producing clothing for individual customers. It also exposed a commercial limitation: Mascarenhas said the demi-couture and custom business was largely covering its costs rather than producing enough profit to support the kind of company he wanted to build.

That realization pushed him toward ready-to-wear.

Translating the Demascaré Aesthetic Into Ready-to-Wear

Mascarenhas did not want commercialization to mean stripping away the qualities that distinguished the brand. He spent months working with a fit model and developing base patterns that could provide consistency while still allowing him to drape and manipulate garments in ways that felt recognizably Demascaré.

Fit became particularly important in that process. Mascarenhas believes customers have started to associate the brand with how its clothing sits on the body, making that one of the qualities he wants to protect as he moves beyond purely custom work.

The new collection spans daywear and eveningwear and is designed around a customer who follows fashion but also wants clothing to function in everyday life. Mascarenhas describes that customer as someone who travels, attends events and wants pieces that can move through different parts of the day while still feeling special.

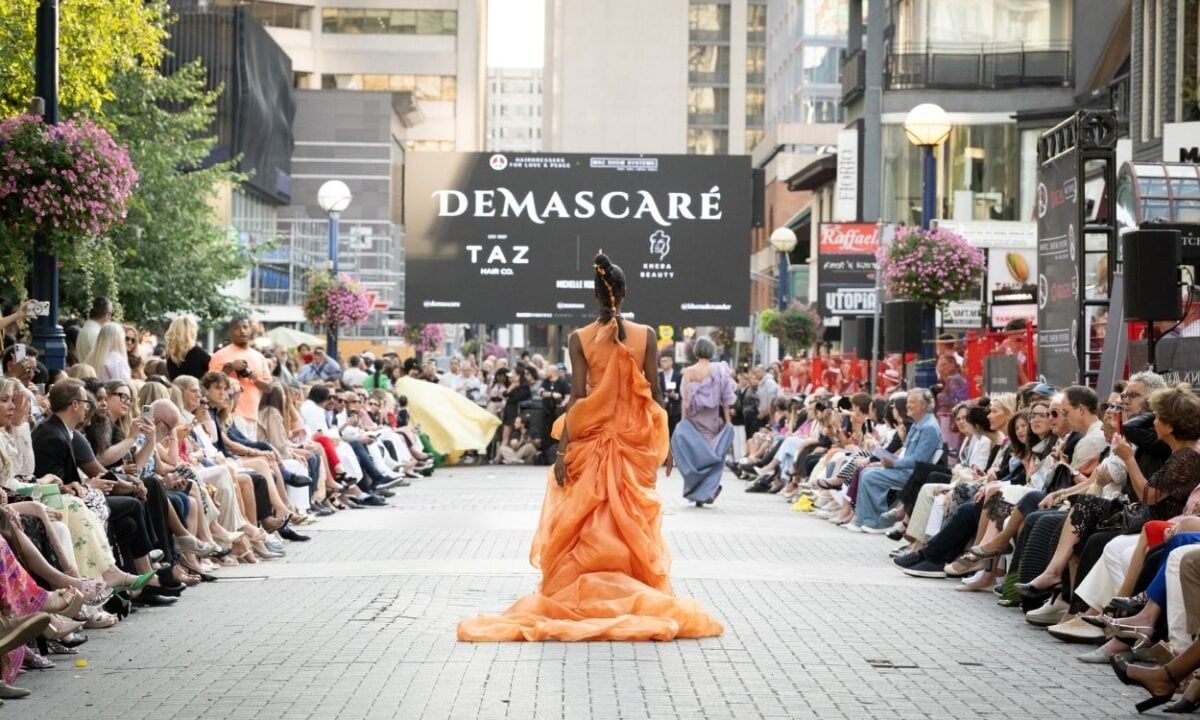
His recent presentation at Couture for a Cause in Yorkville included a mix of couture and ready-to-wear, giving audiences an early look at the new direction. The response was encouraging, although the event also exposed a weakness in the retail infrastructure behind the brand.

Demascaré TDM

When Attention Arrives Before the Business Is Ready

Following Couture for a Cause, Mascarenhas saw a noticeable increase in traffic to the Demascaré website. People had seen the clothes, searched for the brand and arrived online, but the new collection was not yet available to purchase.

Instead, visitors found older product rather than the pieces that had generated their interest. Mascarenhas readily acknowledges that the website should have been prepared ahead of the event.

“What I should have done was have my website ready to go,” he said.

He has since completed a new lookbook shoot and is working to bring the ready-to-wear offering online. The experience offered a practical lesson about the gap between exposure and commerce: a runway appearance or publicity moment can generate immediate interest, but the product, website and fulfilment operation have to be ready if that attention is going to translate into sales.

For Demascaré, building that commercial infrastructure has become an increasingly important part of the business. Mascarenhas is currently working with Digital Main Street’s ShopHERE program, which helps small businesses and artists establish online stores.

Mascarenhas said the program has been particularly helpful in guiding him through the process of setting up Demascaré’s e-commerce operation, an important step as the company prepares to make its expanding ready-to-wear assortment available online.

Toronto Designers Market as a Retail Testing Ground

Physical retail has played a similar role. Mascarenhas initially hesitated when he was encouraged to bring Demascaré into Toronto Designers Market because he was not convinced the business was ready, but he eventually took the opportunity and has now spent roughly a year selling through the store.

The experience has given him something difficult to replicate online: direct evidence of how customers react when they encounter the clothing in person. He can learn which garments attract attention, what customers try on, how pieces fit and where shoppers hesitate.

Feedback from the store has helped Mascarenhas better understand how Demascaré performs in a retail setting and reinforced his decision to move further into ready-to-wear. He describes the first year as uneven but valuable, with strong periods as well as slower months.

Toronto Designers Market remains Demascaré’s only physical retail location. Mascarenhas is now looking at where the brand could go next, while remaining selective about the type of stores he believes make sense.

Made in Toronto, in Small Quantities

Demascaré is not being built around mass production. Mascarenhas said the brand’s current production is done in Toronto, with him cutting the garments himself before working with experienced local seamstresses to complete the pieces.

That approach is more expensive than large-scale offshore manufacturing, but it gives Mascarenhas greater control over production and fits the model he wants to maintain. The brand is largely made to order and frequently works with deadstock fabrics.

Because quantities of a particular textile may be limited, a garment produced in one fabric may exist in only three or four examples. For Mascarenhas, that scarcity adds value.

“I’m not a mass-production brand,” he said. “I’m very one-of-a-kind or few-of-a-kind.”

He wants customers to feel they are buying something unusual and to keep those garments in their wardrobes for years.

The production model also exposes another challenge facing Canadian fashion businesses. Mascarenhas said experienced seamstresses with the technical skills required for his work are becoming harder to find, and he is conscious that younger generations are not necessarily entering the trade at the same rate. For a small designer trying to grow locally, access to skilled production can become as important as access to customers.

Demascaré-JennJevons Fashion Art Toronto Paper Collection

Sustainability Built Into the Production Model

Demascaré’s production strategy is closely connected to its sustainability positioning. Deadstock fabrics, repurposed materials, local production and made-to-order manufacturing are all part of the model, reducing the need to hold large quantities of finished inventory.

One of the more distinctive applications involves vintage sarees. Mascarenhas has been transforming existing sarees into contemporary gowns and cocktail dresses, combining his South Asian background with the circular design principles behind the brand.

He also sees a practical opportunity in the idea. Traditional garments can carry considerable emotional or cultural significance within families, even when younger generations raised in Canada may not expect to wear them in their original form.

Mascarenhas sees the possibility of preserving that connection while reworking the textile into a garment suited to a contemporary wardrobe. The saree remains recognizable in the finished piece, while the resulting clothing gives the material another use and potentially another generation of wear.

Expanding Through the Right Retailers

As the ready-to-wear business develops, Mascarenhas wants to add a small number of retail partners rather than pursue broad distribution.

One retailer he specifically identified is Absolutely Fabrics, the Toronto fashion retailer known for carrying distinctive and less widely distributed labels. There is no announced relationship between the companies; Mascarenhas sees it as an example of the type of retailer where Demascaré could potentially fit.

He is also interested in independent boutiques on Queen Street West and elsewhere in Toronto that cater to consumers looking for unusual fashion.

That selectivity reflects both the positioning of Demascaré and the realities of its production model. A company using limited deadstock fabrics and producing in small batches does not require an extensive store network. Mascarenhas is instead looking for retailers capable of putting the brand in front of customers who understand the product and its price point.

He describes his core customer as a middle-aged to mature woman who enjoys fashion, travels, attends events and wants clothing that feels distinctive while remaining practical.

“The clientele is out there,” he said. “It’s just trying to get in front of them.”

Demascaré Pimentel Couture for a Cause2026

Holt Renfrew Is the Longer-Term Goal

There is one Canadian retailer Mascarenhas is particularly interested in reaching.

“Holt’s is on my list,” he said. “That’s the dream.”

For Mascarenhas, placement at Holt Renfrew would represent a significant milestone for Demascaré and a validation of the brand within Canadian luxury retail. During the interview, he also discussed the potential conceptual alignment between Demascaré and Holt Renfrew’s sustainability-oriented H Project.

There are no announced discussions or arrangements between Demascaré and Holt Renfrew, and Mascarenhas described the retailer as a future ambition rather than an active deal.

Longer term, he is also interested in international markets, particularly Europe. Mascarenhas said he feels a strong affinity with European fashion culture and could eventually see opportunities in markets including France, Italy and the United Kingdom, though his immediate focus is building a stronger foundation in Canada.

The Challenge of Scaling Canadian Fashion

That task is complicated by the environment in which independent Canadian designers operate. Mascarenhas points to several obstacles at once, including access to capital, the cost and availability of local manufacturing, limited retail distribution and the difficulty of building customer awareness.

Asked which presents the greatest challenge, he said the answer is effectively all of them.

He is particularly concerned about the level of institutional support available to the Canadian fashion sector and believes the country has considerable design talent without the supporting ecosystem found in larger fashion centres.

“There are so many talented designers in Toronto and in Vancouver and Montreal,” he said. “There’s a lot to offer.”

Mascarenhas pointed to the 2026 closure of Toronto Fashion Incubator as one example of the shrinking infrastructure surrounding emerging designers. He also contrasted the Canadian environment with markets such as New York, London and Paris, where fashion occupies a more established place within the broader creative economy.

For an emerging label, those structural issues eventually become practical business decisions: where to manufacture, how much to produce, how to finance inventory, which retailers to approach and how much can be spent acquiring customers. Demascaré is now working through each of those questions as it attempts to grow.

Building the Business Around What Made Demascaré Different

Mascarenhas has already learned what can happen when he tries to make his work look more conventionally commercial. His early attempt to simplify the product generated less enthusiasm because it also removed some of the identity that had attracted people to Demascaré in the first place.

The ready-to-wear strategy takes a different approach. Mascarenhas is trying to make the business around the clothing more scalable while retaining the qualities of the clothing itself.

That means developing repeatable fits, building a functioning e-commerce operation, maintaining limited production and finding retail partners capable of connecting Demascaré with the right customer. The company remains small, and considerable work lies ahead.

Mascarenhas has already demonstrated that his designs can attract attention. The next stage will determine whether Demascaré can turn that attention into a durable Canadian fashion business.

More from Retail Insider:

Aritzia’s Stronger Store Performance Supports Continued North American Expansion

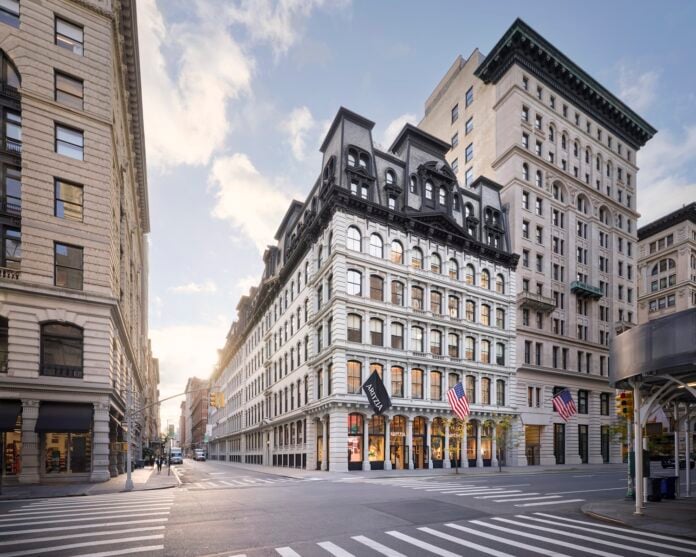
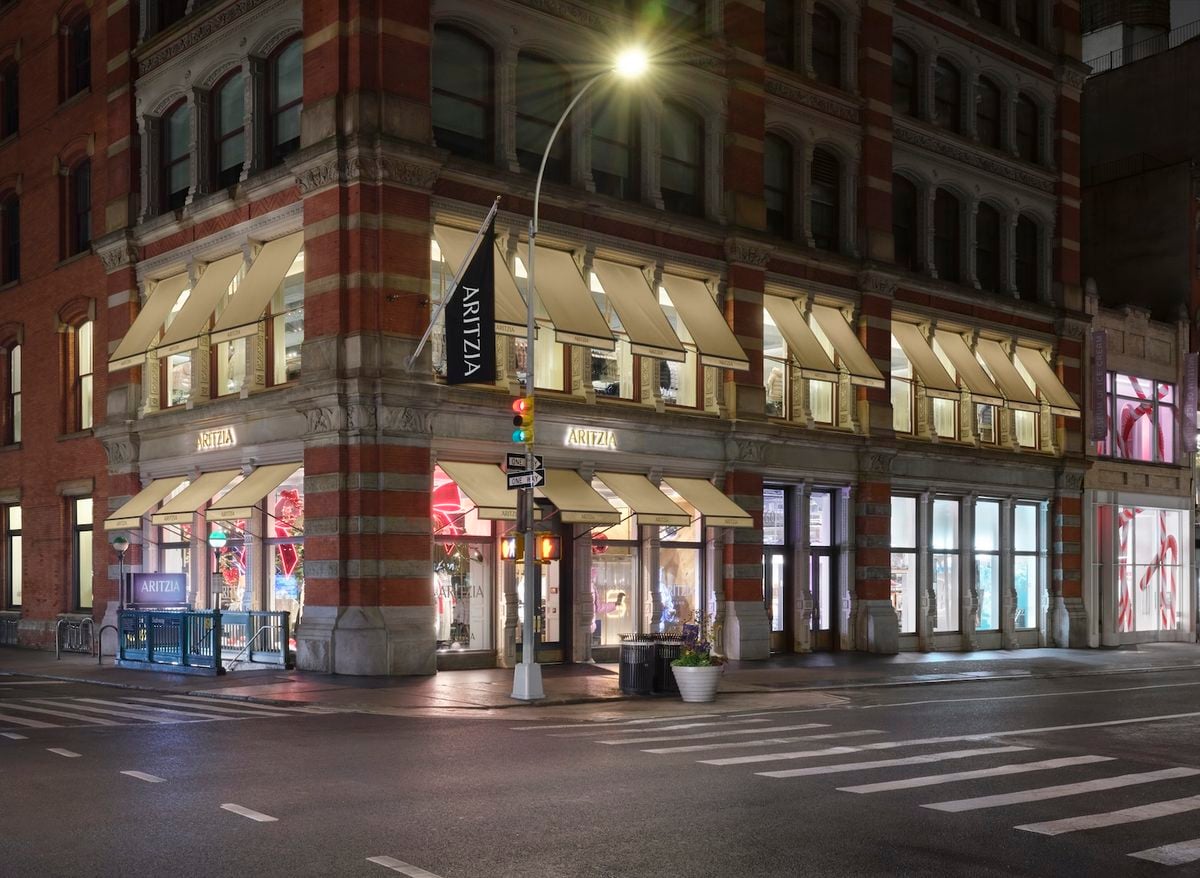
Aritzia flagship store in the Flatiron District in New York City. Image: Aritzia

Aritzia‘s rapid digital growth has not diminished the importance of its physical stores. The Vancouver-based fashion retailer is reporting stronger customer traffic and improving boutique productivity as it continues opening and repositioning locations across North America, providing fresh evidence of the role physical retail plays in its expanding business.

During its second-quarter fiscal 2027 earnings call on October 8, Aritzia executives outlined how stronger sales at existing boutiques, improved performance from newer locations and investments in larger store formats are supporting the company’s growth. Management also detailed upcoming openings in several U.S. states and planned repositionings in Quebec and California.

The results come as Aritzia continues investing in its physical network while expanding its digital business. For shopping centre landlords and commercial real estate professionals, the company’s performance provides insight into how stronger store productivity can support additional retail investment, even as consumer shopping habits evolve.

Higher Traffic Strengthens Boutique Productivity

Aritzia reported revenue of approximately $1.17 billion in the second quarter, an increase of 44.1% year over year, while comparable sales rose approximately 35%. Management indicated that the comparable sales increase was driven primarily by customer traffic rather than higher average transaction values, suggesting that more shoppers are contributing to the company’s growth.

Retail revenue increased 34.1% to approximately $766.9 million, reflecting strong performance across the existing boutique network and contributions from new locations.

One of the more significant developments is the performance of recently opened stores. Management indicated during the earnings call that boutiques opened in fiscal 2026 are generating higher sales per square foot than earlier groups of openings and are progressing toward faster investment payback periods.

The trend is particularly relevant to the economics of retail expansion. Higher sales volumes allow retailers to spread occupancy and other fixed operating costs across a larger revenue base, potentially improving profitability without requiring a proportional increase in operating expenses.

For landlords, improving store productivity provides additional context for Aritzia’s continued investment in physical space. The company is not simply expanding its network; its latest results indicate that newer boutiques are also delivering stronger productivity than earlier locations.

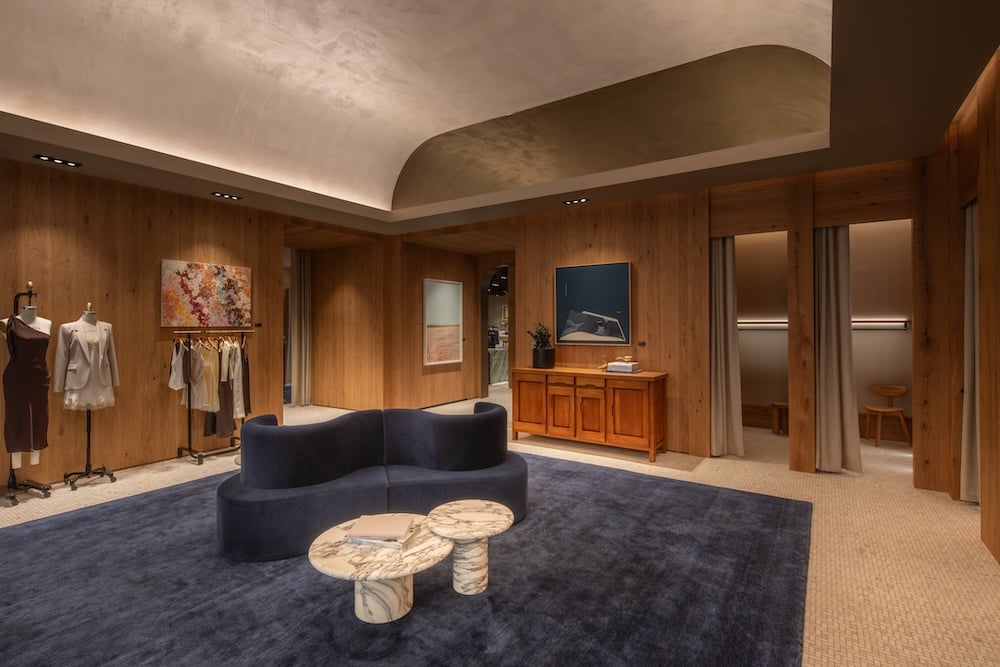
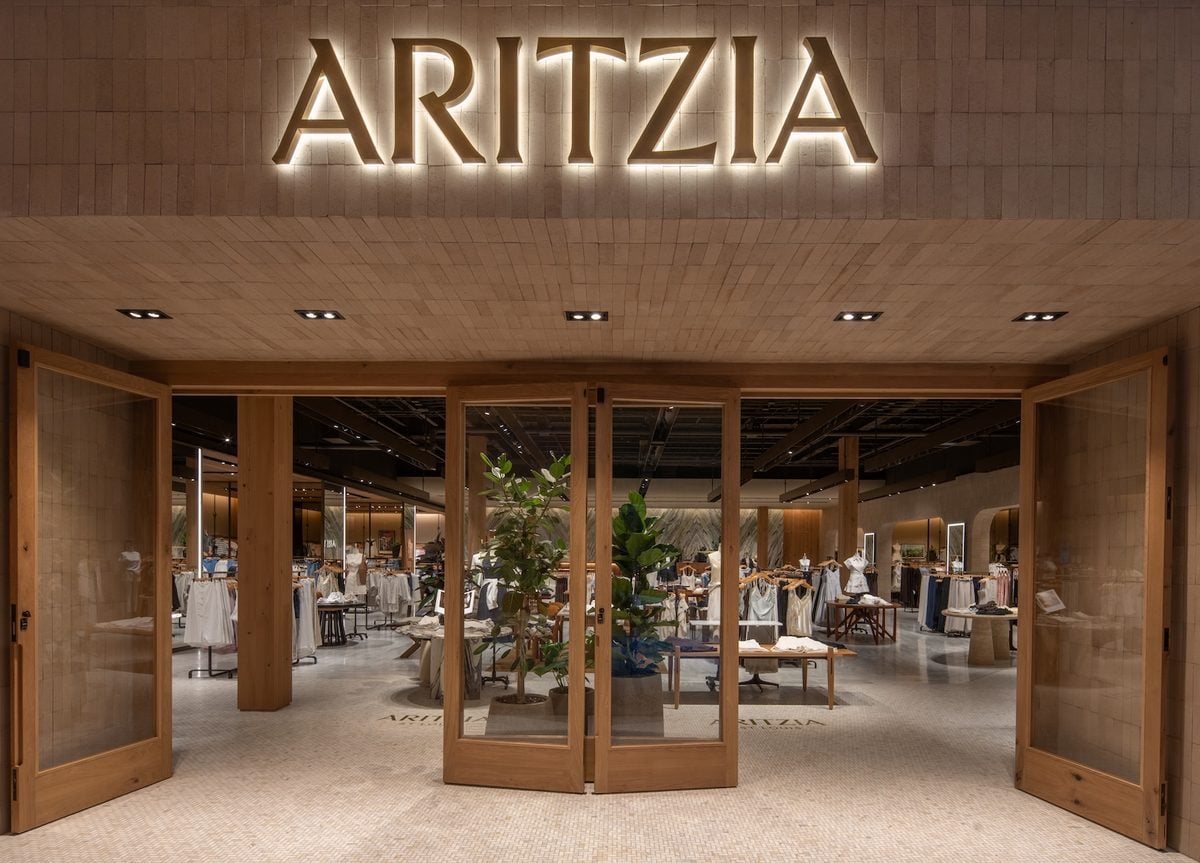
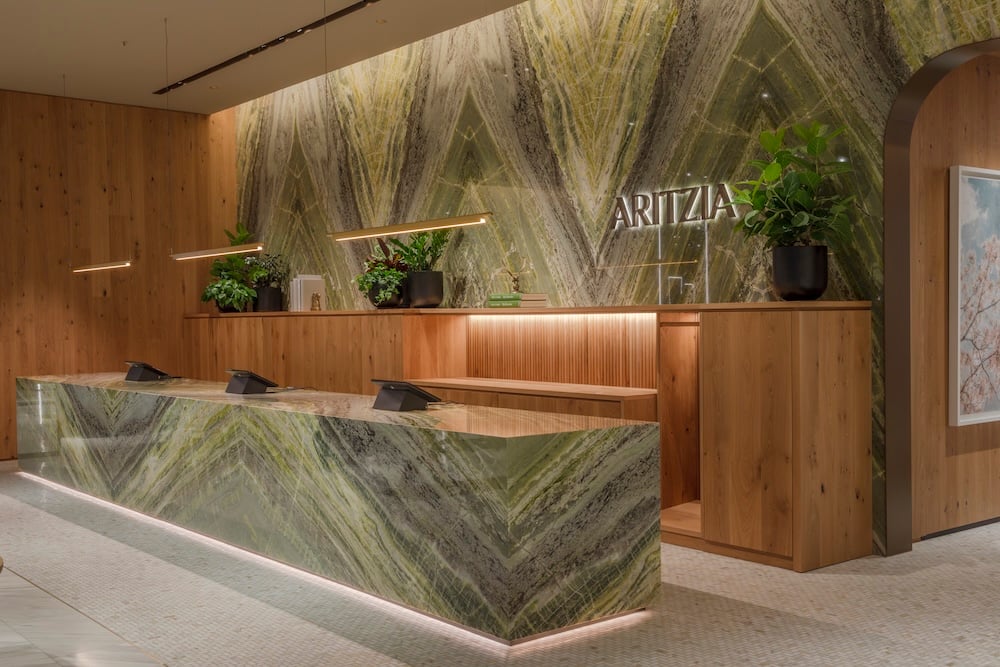
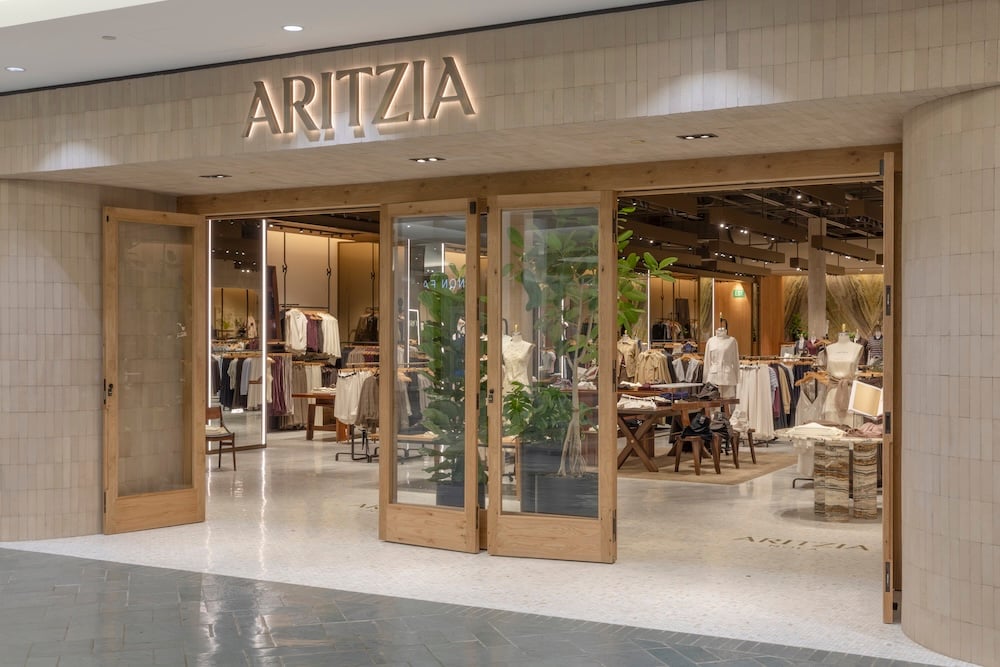
Aritzia store at Plaza Frontenac in St. Louis. Image: Aritzia

Expansion Includes New U.S. Markets and Canadian Repositioning

Aritzia expects to open approximately 12 to 13 new boutiques and reposition another four to five locations during fiscal 2027, maintaining an active real estate development program as it expands its North American presence.

The United States remains the primary focus for new-store growth. During the second quarter, Aritzia entered Birmingham, Alabama; New Orleans, Louisiana; and St. Louis, Missouri, extending its reach into additional metropolitan markets.

The company plans six new U.S. boutique openings during the third quarter, including two in Texas and one each in Florida, Georgia, Massachusetts and Nevada. The projects reflect continued investment in both new markets and the broader development of Aritzia’s American store network.

Alongside these openings, management confirmed plans to reposition two existing boutiques during the quarter, including one in California and another in Quebec.

Repositioning is an important component of Aritzia’s broader strategy, allowing the company to improve its existing retail network rather than relying exclusively on new-store development. Depending on the individual project, such investments can involve changes in location, store configuration or format.

At the end of the second quarter, Aritzia operated 146 boutiques across North America, including 79 in the United States and 67 in Canada. Chief executive officer Jennifer Wong indicated during the October 8 earnings call that the U.S. count had subsequently increased to 82.

The growing American network is gradually shifting the geographic balance of Aritzia’s portfolio, while the company’s established Canadian locations continue to generate substantial sales.

Aritzia flagship store in the Soho District in New York City. Image: Aritzia

Larger Stores Reflect Changing Retail Requirements

Aritzia’s real estate strategy has increasingly emphasized larger boutiques capable of accommodating greater customer traffic and a broader merchandise assortment.

During the earnings call, Wong discussed how the company’s approach to boutique sizing has evolved. Earlier locations were commonly approximately 6,000 square feet, while subsequent formats increased to around 8,000 and then 10,000 square feet. Some of the company’s largest flagship stores now exceed 30,000 square feet.

The additional space supports merchandise presentation, fitting-room capacity and the ability to accommodate higher shopping volumes. These considerations are particularly important for a retailer with a broad assortment of exclusive apparel brands and a business model that places significant emphasis on the in-store experience.

Aritzia’s shift toward larger formats has been underway for several years, but the latest operating results provide additional evidence about the performance of its physical retail investments. Management’s comments about stronger sales per square foot at newer boutiques suggest that its store development strategy is being accompanied by improvements in productivity.

Aritzia store at Plaza Frontenac in St. Louis. Image: Aritzia

Digital Growth Continues Alongside Physical Retail

Aritzia’s digital business is expanding even faster than its physical retail operations. E-commerce revenue increased approximately 68% to $402.9 million during the second quarter, representing roughly 34% of total revenue.

The company has continued investing in its digital platform, including a mobile shopping application launched in October 2025. Management reported that the app has surpassed 2.5 million downloads, supporting customer engagement and the company’s broader online strategy.

Despite the rapid increase in digital sales, Aritzia’s physical boutiques continue to generate strong growth. Wong indicated during the earnings call that management has not observed evidence of online sales cannibalizing the performance of its stores.

The results suggest that Aritzia is benefiting from demand across both channels, although the company has not quantified how much digital activity directly influences physical store purchases or vice versa.

Aritzia store Lakeside Centre in New Orleans. Image: Aritzia

Canadian Market Remains an Important Growth Contributor

Although most of Aritzia’s new-store development is concentrated in the United States, the Canadian business continues to perform strongly.

Revenue in Canada increased approximately 20% year over year to $390 million during the second quarter, a notable result for a retailer with an established domestic presence.

The performance is particularly significant given the affordability pressures facing Canadian consumers and the challenges affecting discretionary retail spending. Aritzia’s traffic-driven growth indicates that the company continues attracting customer demand in its home market.

The Canadian results are also relevant to the company’s real estate strategy. While opportunities for opening entirely new boutiques may be more extensive in the United States, Aritzia’s established domestic network remains an important contributor to revenue and provides opportunities for continued investment in existing locations.

The planned Quebec repositioning reflects that ongoing investment in the Canadian market, even as the company directs much of its new-store development south of the border.

Aritzia is also investing in merchandise planning, distribution infrastructure, technology and other operational capabilities intended to support its growing business. These investments will become increasingly important as the company expands into additional markets and manages a larger retail network.

Aritzia store Lakeside Centre in New Orleans. Image: Aritzia

Next Phase of Expansion

Aritzia’s recent performance provides a strong foundation for its continued North American expansion, although maintaining the current pace of growth will become increasingly challenging as the company compares results against exceptionally strong prior periods.

The company must also sustain boutique productivity as it enters additional markets, manages larger store formats and continues investing in its existing network. Strong performance from recent openings is encouraging, but future results will depend on customer demand, operating costs and execution across individual locations.

Aritzia is scheduled to hold an Investor Day on October 27, when management is expected to outline its longer-term strategic priorities. The presentation may provide additional insight into the retailer’s future market expansion, boutique development and investment requirements as it enters its next phase of growth.

More from Retail Insider:

Bento launches Nashville hot chicken sushi roll across Canada

Bento photo
Bento photo

Bento has launched a Nashville hot chicken sushi roll across Canada, adding a new product to its lineup as the company marks its 30th anniversary.

The Nashville Hot Chicken Roll is available starting at participating grocery, retail and higher education locations, with prices ranging from $13 to $15, depending on the region and product variation.

The Toronto-based company’s latest offering combines crispy Nashville hot chicken katsu with seasoned sushi rice, dill pickles, coleslaw, fried pickle chips, Nashville hot sauce and Nashville spicy mayonnaise.

New product builds on anniversary launches

The roll combines ingredients associated with Nashville hot chicken with a sushi format, incorporating green and red cabbage and carrots into a creamy coleslaw blend. House-made dill pickles and crispy fried pickle chips add a tangy element to the product, which is finished with two sauces.

Bento said the launch draws on the popularity of Nashville hot chicken and consumer interest in familiar foods presented in new formats. The company is continuing to introduce products that offer different flavour combinations and formats for grab-and-go customers.

“The Nashville Hot Chicken Roll takes something familiar and completely reimagines it in a Bento way,” said Dave Jones, president and CEO of Bento. “It’s unexpected, indulgent, and a great example of how we continue to push the boundaries of what sushi can be.”

The product is the latest addition to a series of launches during the company’s 30th anniversary year. Other introductions include what Bento describes as Canada’s first grab-and-go scallop sushi lineup and the Maple Salmon Sushi Roll, which was launched for the summer and features Canadian flavours.

The new roll continues the company’s efforts to expand its product offerings with combinations that bring together different food categories.

Roll to reach major Canadian retailers

The Nashville Hot Chicken Roll will be sold at participating Bento locations across Canada, including grocery stores, retail outlets and higher education locations.

Participating retail banners include Loblaw Cos. Ltd.’s Loblaws, Real Canadian Superstore and Zehrs stores, as well as Metro, Longo’s, Walmart and Sobeys locations in Atlantic Canada. The product will also be available through other participating retailers.

The announced price range of $13 to $15 reflects regional and product-specific variations. Bento did not provide further details about expected sales, distribution volumes or financial targets associated with the launch.

The company said it continues to explore new flavours and formats aimed at grab-and-go consumers as it expands its product lineup.

Bento also recently expanded its retail footprint with the launch of its onigiri at Costco stores across Canada, bringing the popular Japanese grab-and-go staple to a much broader audience. The launch reflects growing consumer interest in convenient, globally inspired foods and builds on Bento’s experience making sushi and other Japanese-inspired offerings accessible beyond traditional restaurant settings. Following the success in Canada, they are now launching across Costco in the US.

Inspiration behind the Nashville Hot Chicken Roll

Jim Olynick, Product Development Manager, Bento Sushi, said the Nashville Hot Chicken Roll was inspired by several converging consumer trends, including the continued popularity of spicy flavours, fried chicken and “swicy” combinations that balance heat and sweetness. 

“Nashville Hot Chicken gave us a recognizable, high-demand flavour profile that could translate naturally into sushi. It also gave us an opportunity to reach consumers who may be hesitant about traditional sushi or raw seafood. By pairing a familiar cooked protein and flavour profile with the sushi format, we can broaden the category’s appeal while continuing to bring globally inspired innovation to grab-and-go food. Grocery is particularly suited to this type of innovation because consumers are often making quick, low-risk purchase decisions based on recognizable flavours,” he said.

As Bento marks its 30th anniversary, the Nashville Hot Chicken Roll reflects how the brand has been evolving the business while staying true to what has always driven it: making sushi accessible, convenient and appealing to a broad range of consumers, explained Olynick.

“It takes a familiar, restaurant-inspired flavour and brings it into the sushi category in a way that feels approachable but still new. Looking ahead, we see significant opportunity to keep expanding what sushi can be by drawing on broader food trends, global flavours and changing consumer tastes. Nashville Hot Chicken is a good example of how we can use 30 years of sushi expertise to bring new consumers into the category and create the next generation of Bento products,” he said. 

Plans for growth

Andrew Siu, EVP Commissaries, said the company’s current footprint is 17 retail locations across Canada. 

“In recent years, we have moved to a fully franchised model and have seen lots of growth in grocery and higher education (campuses). We also underwent a brand refresh, focusing on tightening brand presence and consistent customer experience,” he said. 

The response to our Costco launch in Canada has been extremely strong. We introduced our first onigiri product at the end of May through Costco, and it quickly demonstrated that there is significant demand for convenient, handheld Japanese food beyond traditional sushi. Importantly, the product has been incremental to our existing sushi business rather than replacing those sales, which gives us confidence that onigiri can become a meaningful new growth platform for Bento.

“That success generated interest from Costco regions across the U.S., allowing us to accelerate what would normally be a four-to-six-month rollout into roughly three months. We launched in California and the Midwest in early September and have seen similarly encouraging early results, with additional U.S. regions expected to follow.

“The U.S. expansion also required us to think differently about scale. We invested in specialized onigiri equipment from Fujiseiki, adapted recipes for the market and expanded production capabilities to support significantly higher volumes. It is a good example of how Bento can take a product that works in one market, adapt it quickly and build the operational capacity to scale it across North America.”

Siu said consumers are increasingly looking for convenient, high-quality grab-and-go foods with global flavours, and Bento has the culinary expertise, production infrastructure and retail partnerships to play a much larger role in that space. 

“We see significant opportunity to bring products like onigiri to additional retail partners while continuing to explore new Asian-inspired formats, flavours and occasions,” he said.

“For us, the bigger takeaway is that Bento’s growth does not have to be limited to sushi. We believe we can become a broader leader in Asian food innovation and bring new, convenient products to consumers wherever they are looking for fresh grab-and-go food.”

More from Retail Insider:

Bento photo
Bento photo