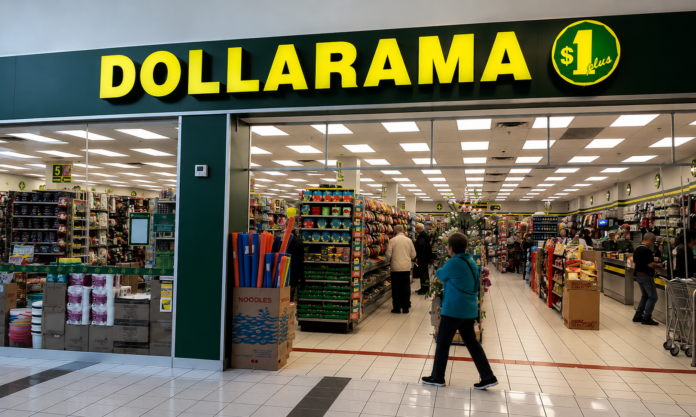
Dollarama has surpassed 1,700 stores in Canada, reaching 1,719 locations after opening 28 net new stores during the first quarter of fiscal 2027.
The milestone comes as the Montreal-based retailer continues to pursue a long-term goal of approximately 2,200 Canadian stores, highlighting management’s confidence that there remains room for significant expansion despite the company’s already extensive national footprint.
Dollarama plans to open between 60 and 70 net new stores this fiscal year, continuing a growth strategy that has made it one of Canada’s largest retail store networks. More than a decade after surpassing 1,000 stores, the retailer now operates locations in major urban centres, suburban communities, and smaller markets across the country.
The company reported the latest store count as part of its first-quarter fiscal 2027 results. During the quarter, same-store sales in Canada increased 5.6 per cent, supported by growth in both customer traffic and basket size.
“Our value proposition continued to resonate with consumers as affordability and everyday value remain top of mind in an uncertain economic environment,” President and CEO Neil Rossy said during the company’s quarterly earnings call.
Expansion Continues Despite Extensive National Footprint
Dollarama’s continued growth is notable given the scale it has already achieved in Canada.
With 1,719 stores nationwide, the retailer has established a presence in a wide variety of retail environments, including neighbourhood shopping centres, power centres, and mixed-use developments. Yet management continues to identify opportunities for new locations and market infill across the country.
The company’s relatively compact store format has allowed it to expand into a broad range of communities, while its merchandise assortment appeals to shoppers across multiple demographic and income groups.
As a result, Dollarama remains one of the most active store-opening stories in Canadian retail, continuing to add dozens of locations annually while working toward its long-term expansion target.
Investing in Infrastructure for Future Growth
To support its growing store base, Dollarama is investing in new infrastructure.
Construction is underway on a logistics hub in Western Canada that is expected to be fully operational by the end of 2027. The facility will become part of a future two-node distribution network designed to support additional store growth and improve supply-chain efficiency across the country.
Management said the project remains on budget and on schedule.
Dollarama on Front Street in Toronto (Image: Dustin Fuhs)
Growth Beyond Canada
While Canada remains Dollarama’s core market, the company has expanded its international presence in recent years.
Through its majority ownership stake in Dollarcity, Dollarama now has exposure to a network of 741 stores across Latin America. Dollarcity opened 20 net new stores during the latest quarter and continues to expand across Central and South America.
The company is also advancing the transformation of Australian discount retailer The Reject Shop following its acquisition of the business. During the quarter, 13 Australian stores were renovated and eight net new locations were opened as part of the ongoing conversion strategy.
Analysts responded positively to Dollarama’s latest results. In a research note following the quarter, Stifel described the rebound in same-store sales as reassuring after a softer fourth quarter and suggested that previous weakness was likely related to weather disruptions rather than reduced consumer demand.
With 1,719 stores now operating across Canada and a long-term target of approximately 2,200 locations, Dollarama’s expansion plans suggest management continues to see significant room for growth across the country. The latest milestone underscores the scale of a retailer that remains focused on opening new stores even as it operates one of Canada’s largest retail networks.
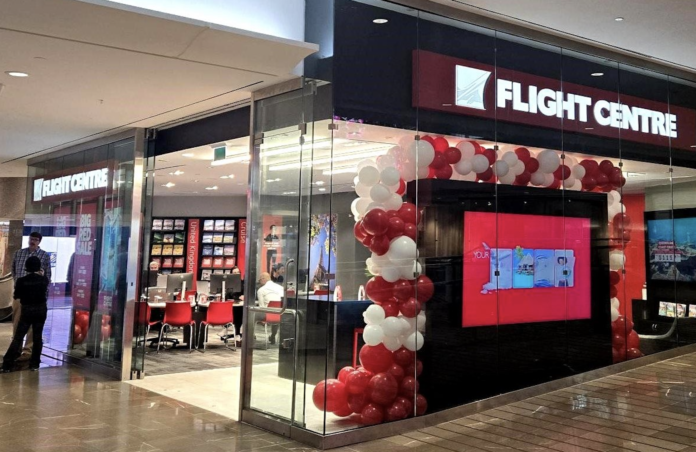
New Flight Centre flagship at Royal Bank Plaza in Toronto. Image: Flight Centre
Canadians are increasingly turning concerts, festivals and major cultural events into reasons to travel, and domestic destinations are benefiting.
Flight Centre Canada’s latest booking data shows domestic travel bookings for summer departures are up approximately 15% year-over-year, with Canadian destinations accounting for roughly one-third of all bookings in both April and May.
The increase comes as Canadians become more intentional about planning trips around experiences rather than simply choosing a destination. This summer’s events calendar is packed with travel-driving moments, from the Montreal Jazz Festival and Calgary Stampede to Osheaga, Boots and Hearts, TIFF, and Noah Kahan’s Canadian tour stops.
It’s a continuation of a broader trend Flight Centre identified earlier this year: travellers are prioritizing meaningful experiences and exploring destinations closer to home.
Question: What’s driving the rise of event-led travel among Canadians, and how significant is this shift compared to pre-pandemic travel behaviour?
Answer: Immediately after the pandemic, we saw revenge travel. People simply wanted to get away after years of restrictions and delayed plans.
Today, travel feels more intentional. Increasingly, a concert, sporting event or festival gives people a reason to travel, and then they build a trip around it.
Our recent YouGov research found nearly seven in 10 Canadians are interested in travelling outside their home province for a live event. Among those travellers, creating memories (64 per cent) and spending time with loved ones (63 per cent) matter more than supporting a favourite team or artist.
People aren’t just attending the event. They’re turning it into a long weekend or a full vacation.
Q: How have major events like the Montreal International Jazz Festival and Calgary Stampede influenced domestic booking patterns this summer?
A: Domestic demand has been very strong. In both April and May, roughly one-third of all bookings made through Flight Centre Canada were for destinations within Canada. And that appetite isn’t slowing down. Looking ahead to summer, domestic bookings are running about 15 per cent ahead of the same period last year.
We’re also seeing Canadians spend more around these experiences. Looking at the total value of trips booked through Flight Centre, including flights, hotels and other travel components, Montreal bookings during the Jazz Festival period are up 9.2 per cent from last year, while Calgary Stampede bookings are up 45 per cent.
That tells us people aren’t just coming in for the event and leaving. They’re making a trip out of it.
Q: Why are more Canadians choosing domestic destinations over international travel, and do you see this as a lasting trend?
A: I don’t think it’s a case of Canadians choosing Canada over the world. Europe remains the anchor for summer travel.
What’s changing is that Canadians are becoming more intentional. Major events are giving people new reasons to explore destinations closer to home, whether that’s a festival in Montreal, Stampede in Calgary or TIFF in Toronto.
I think that mindset is here to stay because experiences are increasingly shaping where people go.
Gustavo Fring photo
Q: How are festivals like Osheaga, Boots and Hearts and TIFF shaping demand across different regions?
A: We’re seeing strong demand right across the country, with Vancouver, Toronto, Halifax, Calgary and Montreal emerging as our top Canadian destinations this summer.
These events create a ripple effect. People may come for the event, but they stay for the restaurants, neighbourhoods and everything else a destination has to offer.
From an economic perspective, these events matter because they encourage visitors to spend more time, and more money, in the communities they visit.
Q: What advice would you give travellers looking to plan trips around high-demand events, particularly in terms of timing, pricing and availability?
A: Treat these trips differently than a regular vacation. Demand is fixed, so waiting rarely works in your favour.
We’re seeing Canadians book these trips well in advance, with average lead times stretching to roughly three or four months. That’s another sign these aren’t impulse purchases. People are planning around experiences they don’t want to miss.
Most importantly, leave room to experience the destination itself. Sometimes the moments you didn’t plan for end up being the most memorable.
Salesforce – Turn today’s shopping trends into tomorrow’s retail success. Visit Salesforce to see the global insights from Salesforce to boost your bottom line.
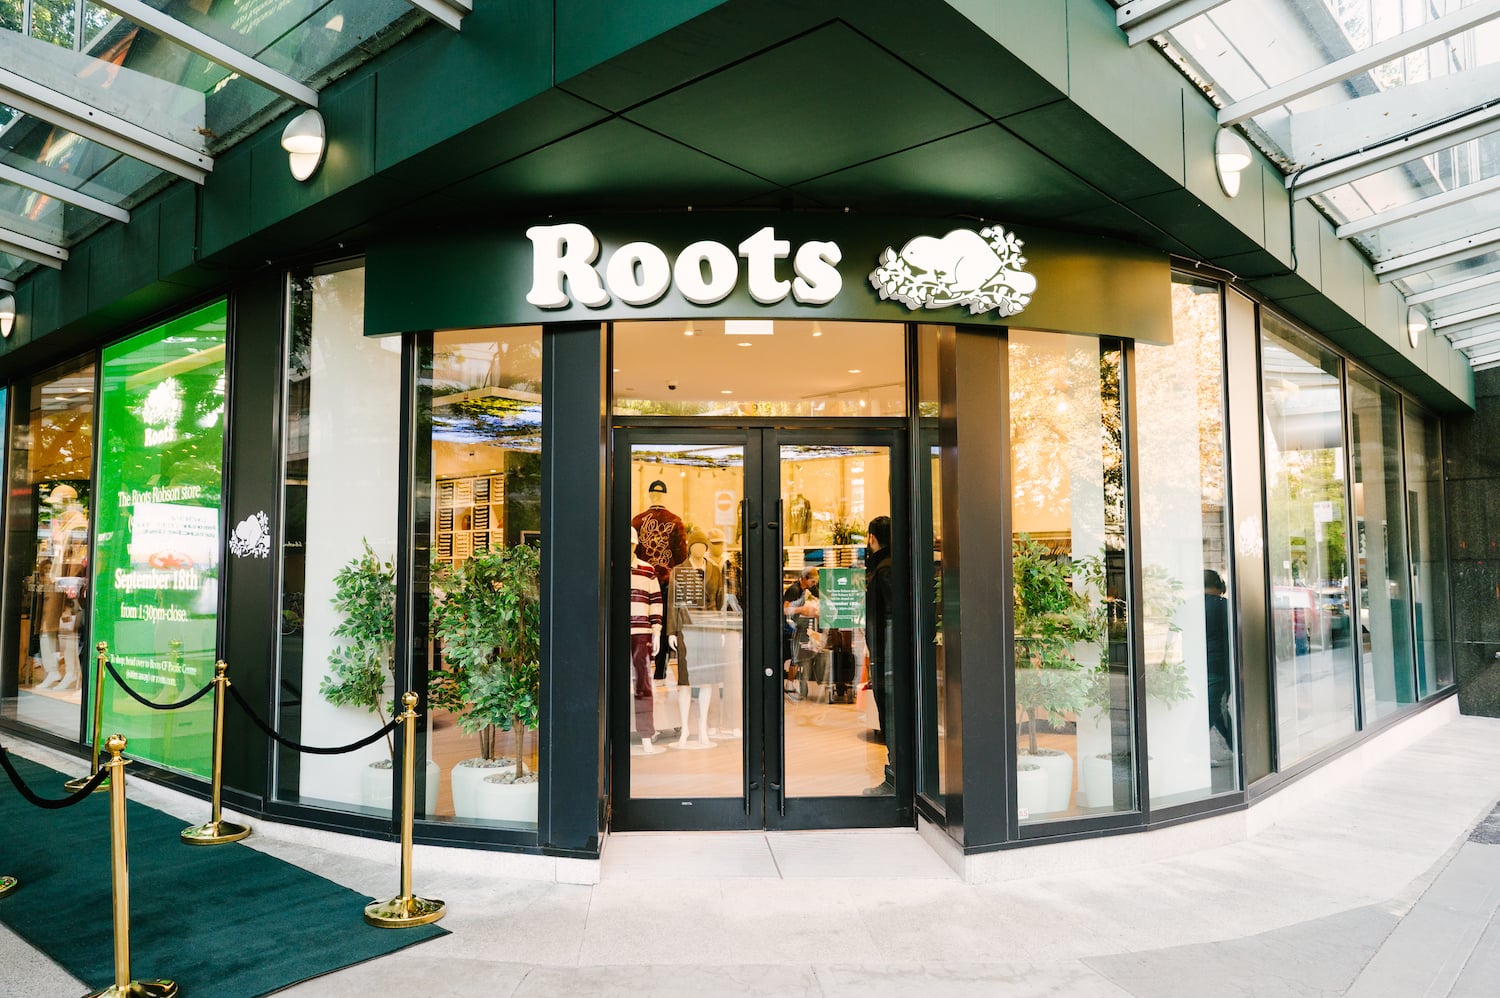
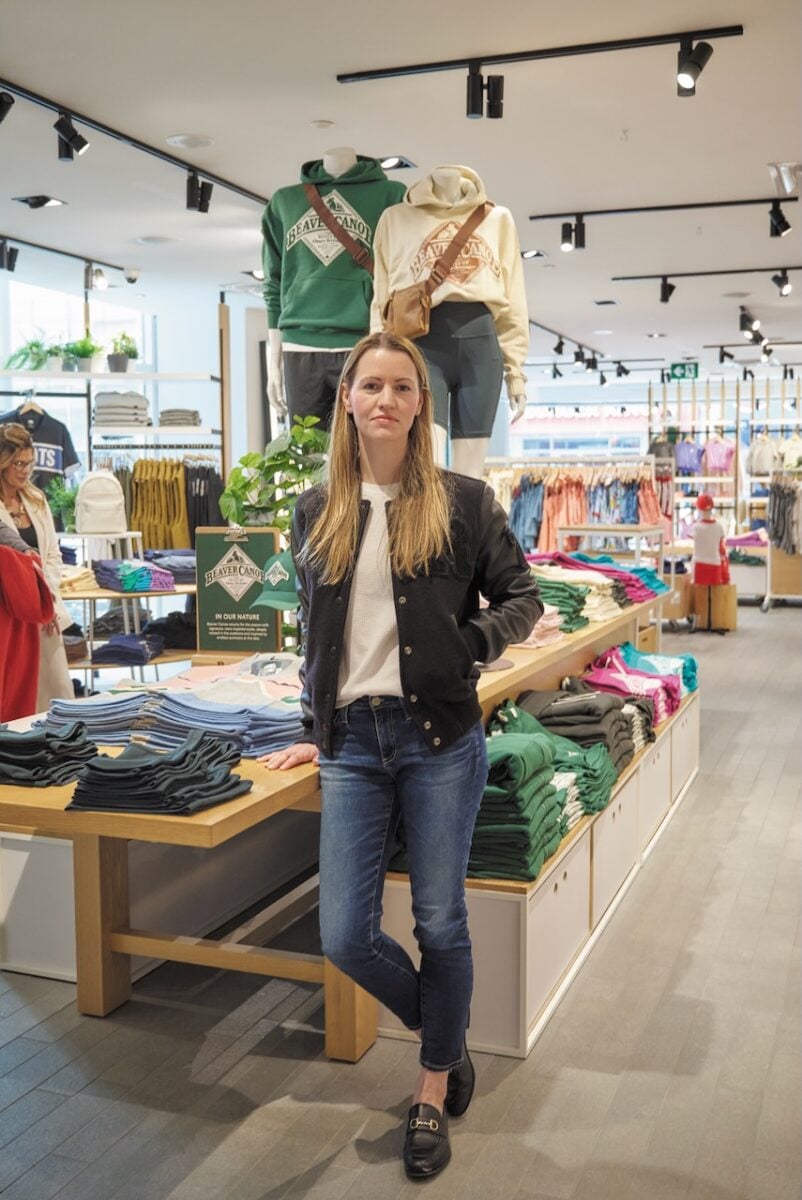
“Roots delivered first quarter sales growth of 6.5 percent and comparable sales growth of 3.2 percent, or 16.6 percent on a two-year stacked basis, alongside a 20.7 percent reduction in net debt year-over-year. Within the first quarter, we continued to diversify our product offering with both our lifestyle and activewear offerings increasing as a percentage of sales,” said Meghan Roach, President & Chief Executive Officer.
“These results reflect the continued strength of the business as we advance two significant initiatives this year: the transition of our distribution centre to Metro Supply Chain, and the review of strategic alternatives being led by our Board. The costs associated with these initiatives are reflected in our results. We remain focused on disciplined execution and building long-term value for all our shareholders.”
Meghan Roach
In January 2026, the company announced its strategic distribution partnership with Metro Supply Chain. The transition is anticipated to be completed by the end of the second quarter. In Q1 2026, the company incurred $1.8 million incremental costs related to this transition, which is primarily driven by the accelerated non-cash depreciation of existing fixed assets. To minimize the cash impacts of the upcoming transition, Roots has shifted additional products to final sale to reduce the transfer of past-season inventory, said Roots.
“As announced in March 2026, the company and its Board of Directors continue to conduct its review of strategic alternatives, which may include, but not limited to, a sale of the company. In Q1 2026, the xompany incurred $0.6 million in incremental consulting and legal costs related to this process,” it added.
Q1 financial highlights:
Sales were $42.6 million, a 6.5% increase as compared to $40.0 million in Q1 2025
DTC sales were $35.8 million, a 3.3% increase as compared to $34.6 million in Q1 2025
DTC comparable sales growth was 3.2%
Gross margin was 59.9%, as compared to 61.5% in Q1 2025
DTC gross margin of 61.3%, as compared to 62.9% in Q1 2025
Adjusted EBITDA amounted to ($7.4) million, as compared to ($7.1) million in Q1 2025
Net loss totaled ($10.1) million, as compared to ($7.9) million in Q1 2025
Adjusted Net Income (Loss), which excludes the impacts of the distribution centre transition and strategic review, along with other non-recurring or unusual costs outside the normal course of operations, was ($7.6) million, as compared to ($7.4) million last year.
Net debt reduced 20.7% year-over-year to $23.4 million
Leon Wu
“We are pleased with the continued sales momentum and deleveraging in the first quarter, and we continue to progress on our strategic review and the distribution centre transition initiatives,” said Leon Wu, Chief Financial Officer. “We are in the final stages of preparation for our distribution centre move and remain on track to be fully operational at the third-party distribution centre by the end of the second quarter.”
Roots, established in 1973, is a global lifestyle brand. As at the end of Q1 2026, the retailer operated 96 corporate retail stores and 11 short-term pop-up locations in Canada, two stores in the United States, and an eCommerce platform, roots.com. It has more than 100 partner-operated stores in Asia, and it also operates a dedicated Roots-branded storefront on Tmall.com in China.
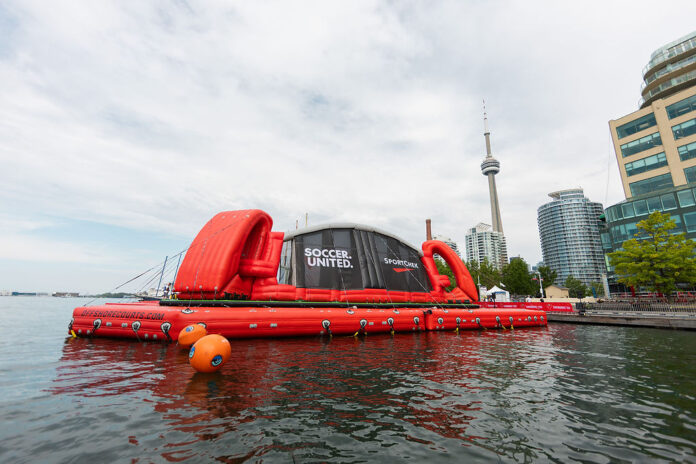
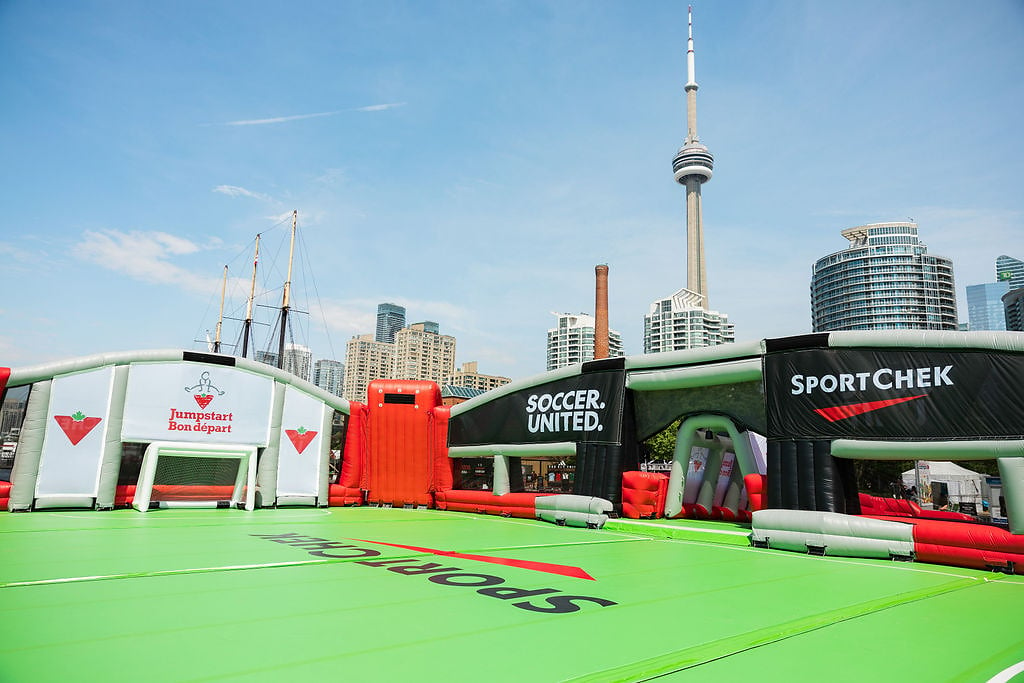
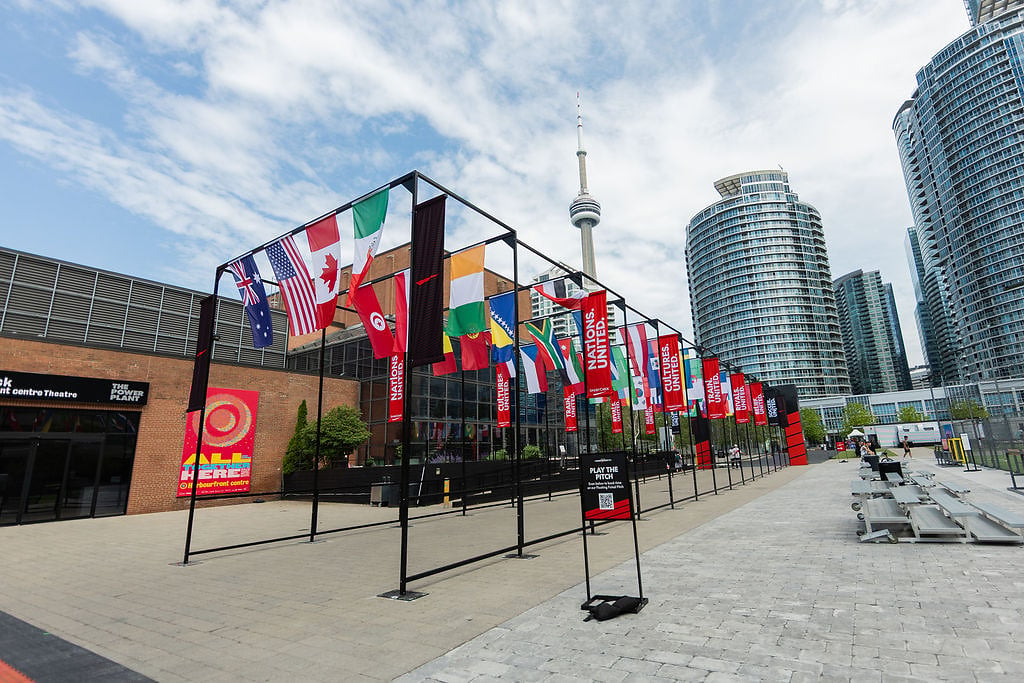
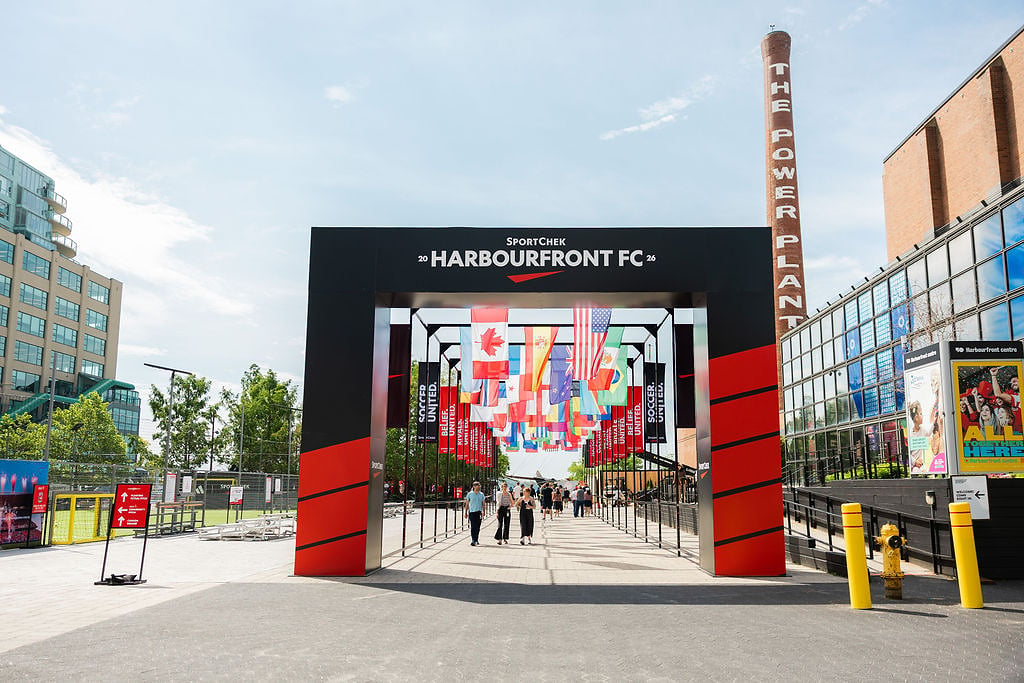
SportChek has launched Canada’s first ever floating futsal pitch at Toronto’s Harbourfront Centre, transforming the city’s waterfront into an immersive soccer destination where fans can play, connect and celebrate the world’s game.
Running until July 19, SportChek Harbourfront FC brings together free public programming, interactive fan experiences, community play spaces and retail activations inspired by the growing excitement surrounding soccer in Canada, explained the retailer.
As Canada prepares to welcome the world for a landmark summer in the sport with the FIFA World Cup, SportChek said it is creating new ways for Canadians to participate in the game, not just watch it.
“Soccer culture in Canada is experiencing incredible momentum right now, and SportChek Harbourfront FC is our way of bringing fans into that excitement in a completely new way,” said Scott Dowding, President, SportChek. “From Canada’s first-ever floating futsal pitch to free community programming and immersive fan experiences, we’ve created a destination that celebrates the role soccer plays in bringing people together across communities, cultures and generations.”
Scott Dowding
At the heart of the experience is Canada’s first-ever floating futsal pitch, giving players the opportunity to step onto the water and into the game through a soccer experience unlike anything else in the country. Fans can book floating futsal sessions throughout the summer or participate in free daily skills and drills programming designed for players of all ages and abilities.
Beyond the floating pitch, the retailer said SportChek Harbourfront FC transforms Toronto’s waterfront into a vibrant soccer hub where fans can experience the energy and culture surrounding the sport through:
Canada’s first-ever floating futsal pitch and dedicated spectator viewing areas
Free public skills and drills programming, drop-in play opportunities and interactive soccer challenges
adidas fan experiences, including merchandise customization, soccer tables and foosball
A SportChek retail pop-up featuring soccer footwear, apparel and equipment from leading brands
The Jumpstart Community Pitch, providing additional opportunities for youth, families and community groups to access the game throughout the summer.
SportChek photo
In partnership with Canadian Tire Jumpstart Charities (Jumpstart), the retailer said SportChek Harbourfront FC also expands access to sport by offering free opportunities for young people and families to get active and experience the game firsthand. Visitors can book time on the Jumpstart Community Pitch throughout the activation, helping create more opportunities for play and participation in the heart of the city.
It said SportChek Harbourfront FC is part of SportChek’s broader SOCCER. UNITED. platform built on the belief that soccer has the power to unite people across cultures, communities and generations. As excitement surrounding the sport continues to grow across Canada, SportChek is creating new ways for fans to connect with the game, and each other, beyond simply watching the action.
SportChek Harbourfront FC is open daily until July 19 at Toronto’s Harbourfront Centre. Floating futsal sessions are now available to book here.
SportChek photo
SportChek is the country’s largest sports retailer with over 180 locations across Canada.
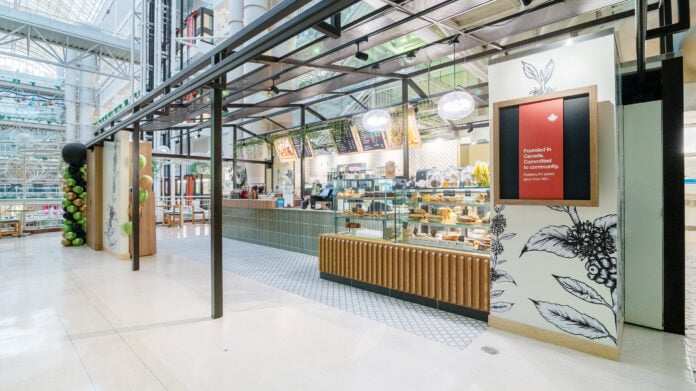
Located in the Clinical Sciences Building at 8440 112 St NW, the coffeehouse said it will provide hospital staff, patients, and visitors with a welcoming space to enjoy ethically-sourced coffee and fresh, wholesome food.
The new coffeehouse offers a warm and inviting gathering place within the hospital, creating a moment of comfort and connection in the midst of busy days. Operated in partnership with Sodexo, a global leader in food services and facilities management, this location is designed to support the needs of the healthcare community with convenient access and extended hours, said the company.
“We’re excited to expand our offering at UAH with the opening of our Good Earth location. This new space brings more choice and fresh flavours, while creating a welcoming, high‑quality guest experience for patients, visitors, and hospital staff alike,” saidJames Nesbitt, Chief Operating Officer at Sodexo.
Good Earth Coffeehouse serves Fairtrade Certified coffees alongside fresh, wholesome food prepared daily. From breakfast and lunch to baked treats and snacks, every offering is made with quality ingredients and served with the warm, down-to-earth hospitality that has defined the brand since 1991.
The location operates 24 hours a day, 7 days a week.
Good Earth Coffeehouse is a network of authentic coffeehouses with over 50 locations across Canada. The first coffeehouse opened in Calgary in 1991.
Restaurants Canada welcomed the federal government’s National Food Security Strategy announced Thursday by Prime Minister Mark Carney, calling it an important step toward strengthening Canada’s food system through investments in domestic food production, processing, and distribution infrastructure.
Several recommendations advanced by Restaurants Canada during consultations are reflected in the strategy, including investments in food terminals and food hubs, measures to strengthen competition and consumer affordability, efforts to reduce regulatory barriers, and initiatives aimed at expanding domestic food processing capacity and improving supply-chain resilience, said the organization.
“We were encouraged to see several of the priorities Restaurants Canada advanced during consultations reflected in the final strategy,” said Kelly Higginson, President and CEO of Restaurants Canada. “Food security depends on strong domestic production and processing capacity, efficient distribution networks, competitive markets, and reliable access to food. The strategy recognizes the importance of strengthening each of those elements.”
Kelly Higginson
With the average transaction sitting at approximately $12 per person, restaurants provide an accessible source of nourishment for millions of Canadians. For many Canadians—including busy families, seniors, students, shift workers, travellers, people living in temporary accommodations, and those without access to cooking facilities—restaurants are often the most practical, affordable, and reliable way to obtain meals, said Restaurants Canada.
Every day, Canadians make approximately 23.7 million visits to restaurants. The restaurant industry purchases approximately $43 billion in food and beverages annually, including roughly $30 billion from Canadian suppliers, making it the largest purchaser of Canadian agricultural products. It directly employs 1.2 million Canadians and serves as an important link between producers and consumers across the country, it noted.
“Restaurants operate at the intersection of food production, processing, distribution, labour, affordability, and consumer demand,” said Higginson. “That gives our industry a practical understanding of how food moves through the economy and reaches Canadians. As the strategy is implemented, Restaurants Canada looks forward to contributing that perspective to help advance the government’s objectives and strengthen food security for Canadians.”
Restaurants Canada’s submission to the National Food Security Strategy can be found here.
On Thursday, Prime Minister, Mark Carney, launched Canada’s first-ever National Food Security Strategy. Backed by more than $3 billion in investments over 10 years, this strategy will break open the market for independent retailers, boost domestic food production, and build a stronger, more independent, and more affordable food system for all Canadians, said thegovernment
Prime Minister Mark Carney
“Canada is one of the world’s great food producers. But too much of what we grow is processed elsewhere, and too many Canadians still rely on imported food at higher prices. Canadian farmers deserve more options to sell their produce, and Canadians deserve more options for where to buy their food. Canada’s first-ever National Food Security Strategy will help grow and process more food here and put more Canada on Canadian plates – lowering costs, creating jobs, and building a food system that is more resilient, more competitive, and more our own,” said Carney.
The government said the strategy has four objectives:
1. Spur grocery store competition and create more choice for Canadians
Invest $1 billion in food infrastructure to build new and expanded food terminals and hubs – helping independent grocers buy and move competitively priced products without relying on large retail chains.
Provide the Competition Bureau and Competition Tribunal with nearly $130 million to investigate, prevent, and combat anti-competitive business practices.
2. Boost domestic food production across Canada
Launch a new $1 billion Agri-food Project Finance Fund through Farm Credit Canada (FCC) to provide seed capital financing for businesses to expand food processing capacity.
Establish a $150 million Food Security Fund to help small and medium-sized businesses upgrade their equipment to grow, produce, and process more food in Canada.
Create a $100 million Collaborative Food Innovation Fund to help producers expand agri-food processing.
3. Grow fruits and vegetables year-round
Invest $750 million to drastically expand year-round Canadian production of fruits and vegetables, including through greenhouses, vertical farms, and other enclosed growing spaces.
4. Cut red tape across the agricultural supply chain
Modernize key regulations; speed up approvals for seeds, feed, fertilizers, and veterinary products; and reduce backlogs that slow down the system to reduce the regulatory burden on farmers and producers.
Help provincially licensed food businesses meet federal requirements so that a Canadian product made in one province or territory can more easily reach a shelf in another.
Welcome to the Daily Synopsis by Retail Insider. We published 10 articles today covering the latest developments across Canadian retail sectors. Highlighted stories explore market shifts, expansion news, and retail strategies shaping the landscape.
The evolving Canadian women’s fashion sector is examined in What Happened to Canada’s Women’s Fashion Chains? which details closures and downsizing driven by casualization, fast fashion, and changing mall dynamics. Lululemon has returned to Oakridge Park with a new store concept emphasizing local community engagement. Luxury retail saw a boost as Chanel opened its largest Canadian store also at Oakridge Park, reinforcing its position in Vancouver’s high-end market.
Inside the former Creeds store at 45 Bloor St. W. (Manulife Centre) in Toronto.
For generations of Canadian women, shopping for clothing was often tied to life’s milestones.
A first interview suit. A blouse for a new office job. A dress for a wedding, graduation, holiday party or other special event. A trip to the mall wasn’t simply about buying clothes, it was about preparing for important moments. Shopping centres across the country were filled with retailers that catered to those moments. Fairweather, Jacob, Smart Set, Reitmans, Braemar, Laura, Le Château, Penningtons and numerous others helped define an era of Canadian fashion retail that occupied a comfortable middle ground between discount and luxury. They offered accessible fashion for women building careers, raising families and navigating everyday life.
Department stores added even more choice. Across different eras, consumers shopped for apparel at Simpsons, Eaton’s, Woodward’s, Sears and Hudson’s Bay, often finding entire floors dedicated to fashion, footwear and accessories.
Today, much of that landscape has disappeared.
Many of the chains that once defined women’s fashion retail in Canada are out of business, while others operate with significantly smaller footprints than they did at their peak. Department stores that once sold enormous volumes of apparel have largely disappeared from Canada. Simons remains one of the country’s few national fashion-focused department store retailers, though the sector is dramatically smaller than it was a generation ago. In their place, consumers increasingly shop across a marketplace dominated by global fashion giants, off-price retailers, luxury brands and athleisure concepts.
Antony Karabus
“The story is really the transformation of women’s wear retail in Canada,” said retail consultant Antony Karabus, who has advised retailers across North America for decades.
The changes reflect far more than shifting fashion trends. According to Karabus, the disappearance of many mid-market apparel chains can be traced to several powerful forces that have reshaped the retail landscape over the past two decades, including casualization, the rise of fast fashion, the increasing dominance of value-focused and global retailers, economic polarization and changing mall economics.
When Apparel Dominated Canadian Malls
Walk through a major Canadian shopping centre in the 1980s, 1990s or early 2000s and apparel occupied a far larger share of the tenant mix than it does today.
Women’s fashion chains, department stores, footwear retailers and specialty apparel concepts often filled entire wings of malls. Department stores anchored shopping centres while fashion retailers lined the corridors between them. For consumers, there was no shortage of choice.
For many women, shopping was also very predictable. Consumers often developed loyalty to a handful of trusted retailers where they knew the fit, understood the sizing and could reliably find clothing appropriate for work, social occasions and everyday life. Many readers will remember malls where apparel occupied entire corridors, with department stores at either end and dozens of fashion retailers in between.
“I remember when women used to go to Lipton’s, Braemar, Fairweather, Smart Set, Jacob and Reitmans for their first outfits,” Karabus said.
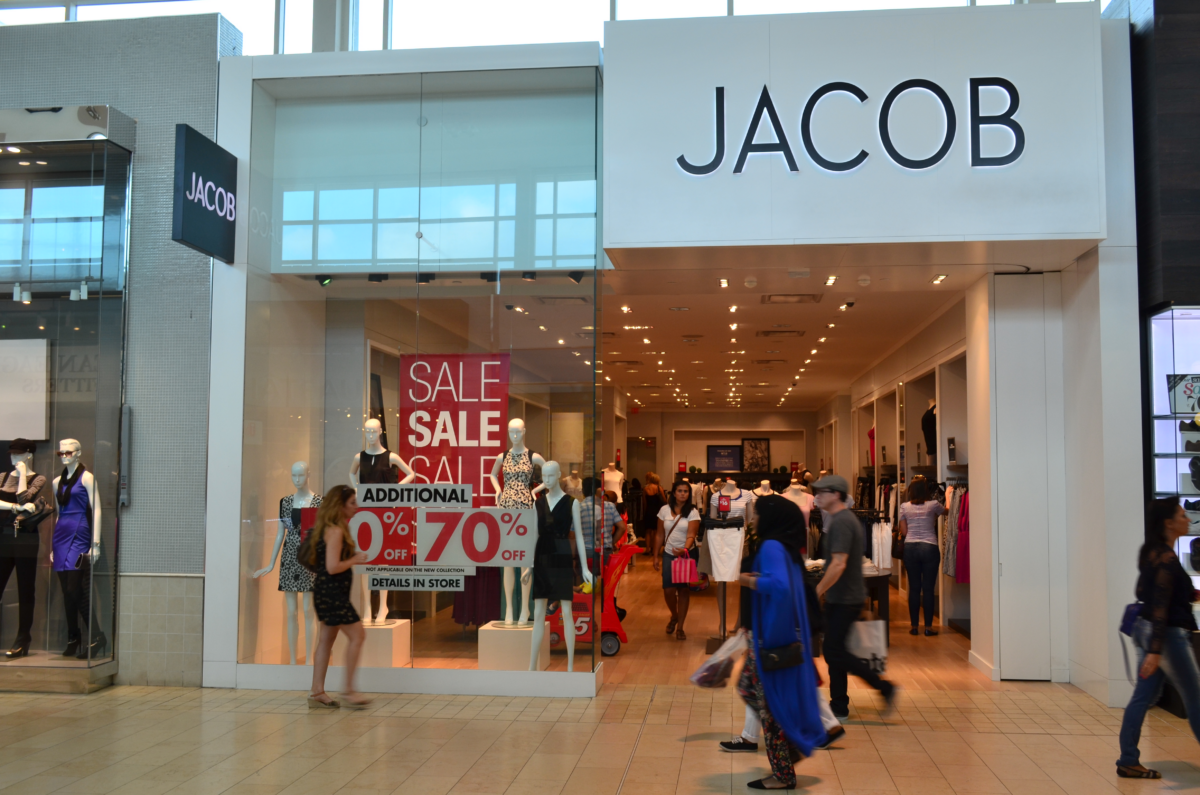
Former Jacob store at Toronto’s Yorkdale Shopping Centre. Photo: Wiki Commons
Many of these businesses were Canadian-owned retailers that expanded nationally alongside the growth of enclosed shopping centres. They served a large middle-income consumer base looking for fashionable apparel at accessible prices.
Jacob and Le Château disappeared following insolvency proceedings. Smart Set was wound down. Addition Elle ceased operating as a standalone chain. Several American retailers that once expanded into Canada, including Ann Taylor, Maurices and Chico’s, exited the market. Others dramatically reduced their store counts.
The retail model that once supported a large network of mid-priced fashion chains steadily eroded. The decline was not limited to specialty retailers.
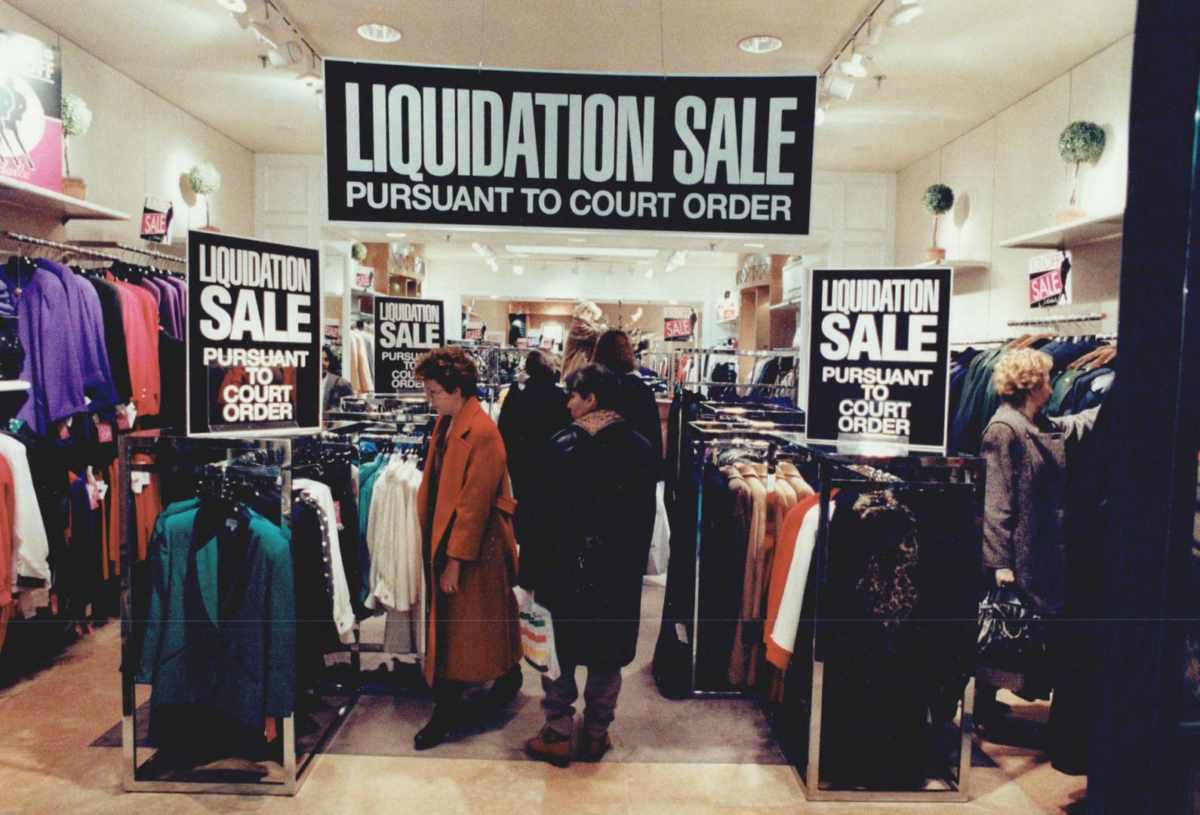
J. Michael’s and Kristy Allan stores at Toronto Eaton Centre liquidated in 1991. Photo: Toronto Public Library
The Collapse of Canada’s Department Store Ecosystem
Department stores once played a central role in women’s fashion retail in Canada.
Across different eras, chains such as Simpsons, Eaton’s, Woodward’s, Sears and Hudson’s Bay sold enormous volumes of apparel while serving as major traffic drivers for shopping centres. Their fashion floors offered everything from private-label merchandise and national brands to footwear, accessories and career apparel.
Today, all five department store banners have disappeared from Canada’s retail landscape.
Eaton’s vanished in the late 1990s. Woodward’s and Simpsons disappeared even earlier. Sears Canada liquidated its operations in 2017. Hudson’s Bay, Canada’s oldest company and largest department store chain, liquidated its stores and ceased retail operations in 2025.
The impact extended beyond the department stores themselves. Their decline removed an important distribution channel for apparel brands and weakened the broader retail ecosystem that supported many specialty fashion retailers.
Many specialty apparel retailers benefited from shoppers who visited malls specifically to browse department store fashion floors. As those anchors disappeared, apparel retailers lost an important source of traffic and customer discovery.
The contrast with the United States remains notable. While American department stores face their own challenges, chains such as Macy’s, Nordstrom, Dillard’s and Belk continue to provide substantial distribution for women’s apparel brands. Canada’s department store sector is dramatically smaller, leaving relatively few multi-brand fashion destinations serving middle-market consumers.
Casualization Changed the Wardrobe
Changing consumer behaviour has been equally important.
Women simply dress differently today than they did a generation ago.
Career apparel, dresses and formal office wear remain part of the market, but they no longer occupy the same place in consumers’ wardrobes. Casual clothing, denim, sneakers and athleisure have become increasingly common, even in workplaces that once required more formal attire.
Karabus believes this shift has fundamentally altered the apparel market.
“The expectation of dressier workplace attire has largely disappeared. The change reflects broader shifts in how people work and live,” he said.
Hybrid work arrangements accelerated a trend that was already underway, reducing the need for wardrobes built around five days a week in an office.
Consumers increasingly favour versatile apparel that can transition between work, home and social settings rather than maintaining separate wardrobes for each part of their lives.
The disappearance of these retailers does not mean Canadian women stopped buying clothing.
Rather, they began buying it differently.
As demand shifted, many retailers built around traditional careerwear and occasion dressing found themselves facing a much smaller addressable market than they once had.
Fast Fashion Changed the Competitive Landscape
Another major disruption came from the rise of fast fashion.
Retailers such as Zara and H&M introduced a model based on rapid product development, shorter fashion cycles and global sourcing networks capable of responding quickly to emerging trends while offering compelling value to consumers across a broad range of income levels.
Consumers embraced the concept.
Instead of waiting for seasonal collections, shoppers could visit stores frequently and discover new styles every few weeks. Fashion became faster, more responsive and often more affordable. Retailers could react to trends in weeks rather than months.
Karabus argues that many Canadian family-owned apparel chains were operating with business models built for a different era.
“The inability of mid-priced family-owned chains to compete against foreign-owned giants with significant depth of resources in sourcing, selection, product development and value became a major challenge,” he said.
Large international retailers could spread costs across global store networks while investing heavily in logistics, technology and product development. Canadian chains operating primarily in one market faced a much more difficult environment.
The result was a widening competitive gap between domestic apparel retailers and multinational fashion companies.
Oakridge Park in Vancouver. Photo: Craig Patterson
The K-Shaped Economy Creates Winners and Losers
Karabus also points to the growing impact of what economists call a K-shaped economy.
At one end of the spectrum, affluent consumers continue spending on premium and luxury goods. At the other end, value-focused consumers increasingly seek discounts and affordability.
The middle has become increasingly difficult to serve.
“Just like in the U.S., the K-shaped dynamic is actively polarizing the competitive landscape,” Karabus said.
Luxury brands continue expanding in affluent shopping districts and top-performing shopping centres. Retailers such as Aritzia, Alo Yoga and lululemon have benefited from casualization and the growth of athleisure while building strong positions through compelling merchandise assortments and highly focused customer strategies.
At the value end of the market, retailers including Winners, Marshalls, Walmart and Costco continue attracting consumers looking for affordability. The growth of off-price retail has been particularly significant. Through Winners, Marshalls and HomeSense, TJX Canada has built one of the country’s largest retail businesses, generating billions of dollars in annual sales.
While Zara and H&M are often credited with reshaping apparel retail, off-price operators and mass merchants have also captured a substantial share of consumer spending by offering recognizable brands at discounted prices.
For many shoppers, a trip to Winners has replaced visits to the traditional mid-market apparel chains that once dominated Canadian malls.
Today’s consumers often shop across multiple price points. A woman may purchase activewear from lululemon, browse Winners for bargains and occasionally splurge on a luxury accessory. Shopping habits have become far less tied to a single retailer than they were in previous generations.
This leaves traditional mid-market apparel retailers in a difficult position. They often lack the scale to compete on price with value operators and lack the prestige needed to command premium pricing.
As middle-income consumers become increasingly selective about discretionary spending, many retailers have found themselves squeezed from both directions.
Mall Economics Added More Pressure
Changing shopping centre economics created another challenge.
Karabus argues that many traditional apparel chains generated sales productivity that became increasingly difficult to support in Canada’s most productive shopping centres.
Centres such as Yorkdale Shopping Centre, CF Pacific Centre, CF Toronto Eaton Centre and Chinook Centre generate some of the highest sales productivity levels in the country. As these centres attracted luxury brands and high-performing global retailers, many traditional mid-market fashion chains found it increasingly difficult to justify occupancy costs.
As leading malls improved performance and attracted stronger retailers, rents increased and competition for space intensified.
Retailers with higher sales productivity, stronger balance sheets and greater international scale became more attractive tenants. Luxury brands, beauty concepts, athletic apparel retailers and experiential tenants increasingly secured prime locations in premier shopping centres.
Meanwhile, many traditional mid-priced apparel chains found themselves struggling to justify the economics in those locations.
Some migrated to weaker centres. Others reduced store counts. Many disappeared altogether.
A Market Transformed
Women’s apparel has not disappeared from Canada.
Consumers continue spending billions of dollars on clothing each year, and successful fashion retailers continue to expand. The difference is that spending is increasingly flowing toward luxury brands, off-price operators, athleisure concepts, fast-fashion retailers and a handful of highly differentiated specialty chains.
The forces behind that transformation were powerful and interconnected. Casualization reduced demand for traditional careerwear. Fast fashion dramatically accelerated competition. Department stores disappeared. Shopping centres evolved. Consumers increasingly gravitated toward either value or premium offerings. Global retailers gained scale advantages that many domestic operators struggled to match.
The disappearance of many familiar women’s fashion chains is ultimately a story about how Canadian consumers changed, how retailers responded, and how the economics of retail evolved.
Many consumers now move fluidly between value retailers, global fashion brands, athleisure brands, luxury labels and digital channels rather than relying on a handful of trusted mall-based chains. Fairweather, Braemar, Jacob, Smart Set, Town & Country and many other once-prominent chains helped define an era of Canadian retail when women’s fashion shopping was centred around the local mall and a strong middle market.
That era has largely passed.
Today’s market offers more choice than ever before, but that choice is also more fragmented, more global and more competitive.
Whether a new generation of Canadian apparel retailers can successfully rebuild that middle ground remains to be seen. What is clear is that the forces that transformed the sector continue to reshape Canadian retail today.
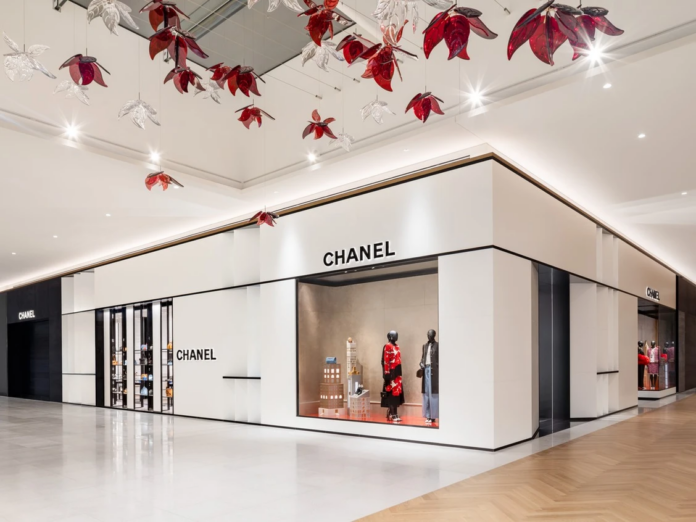
Chanel boutique at Oakridge Park in Vancouver. Photo: Chanel
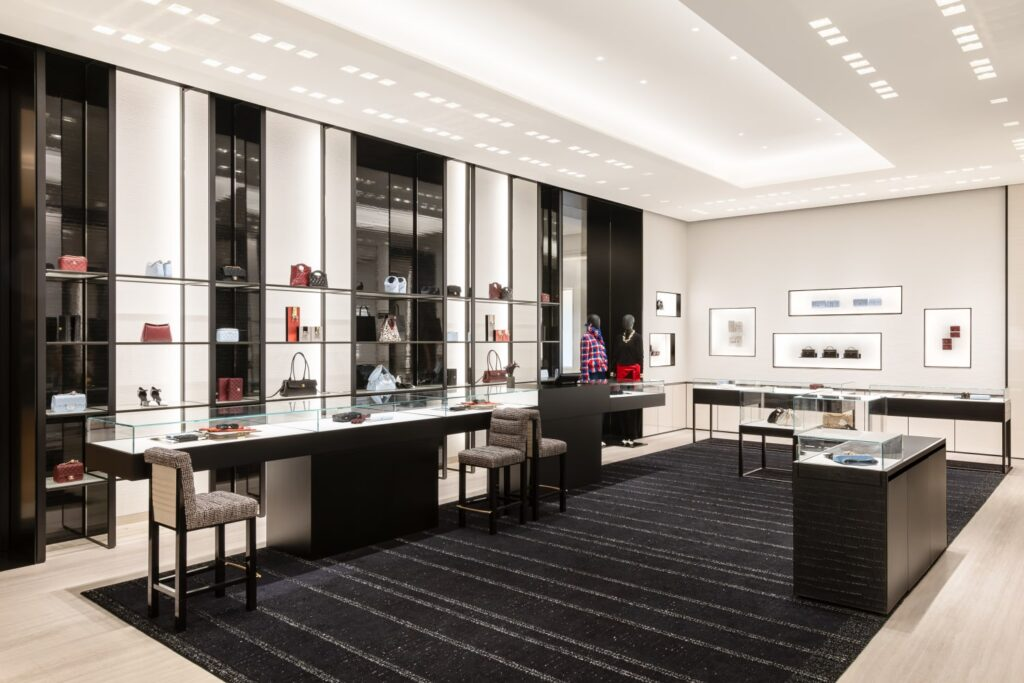
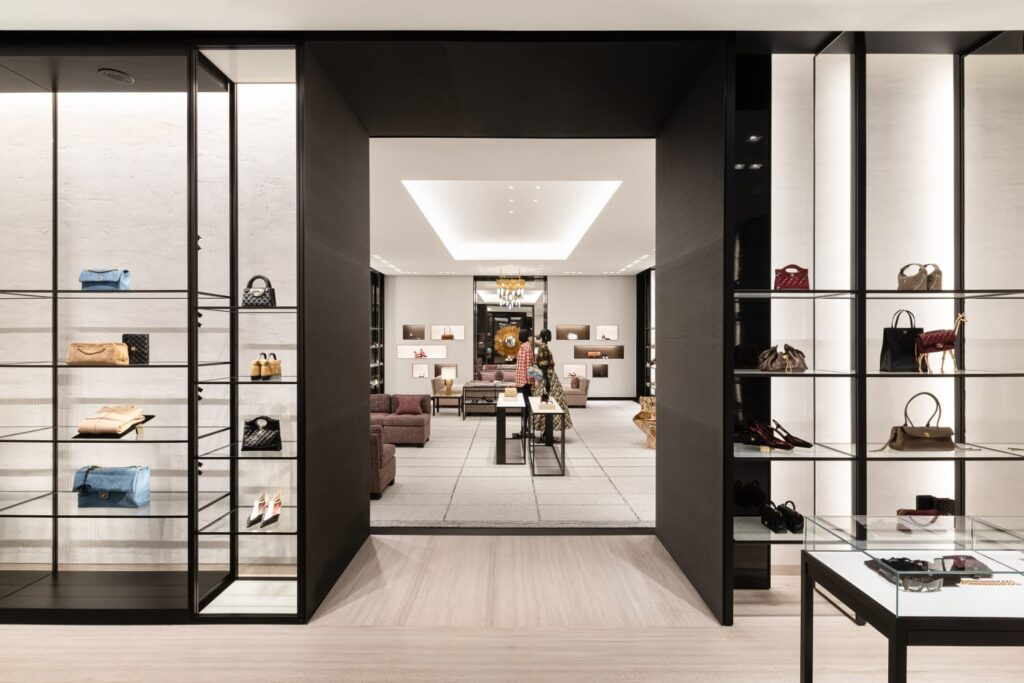
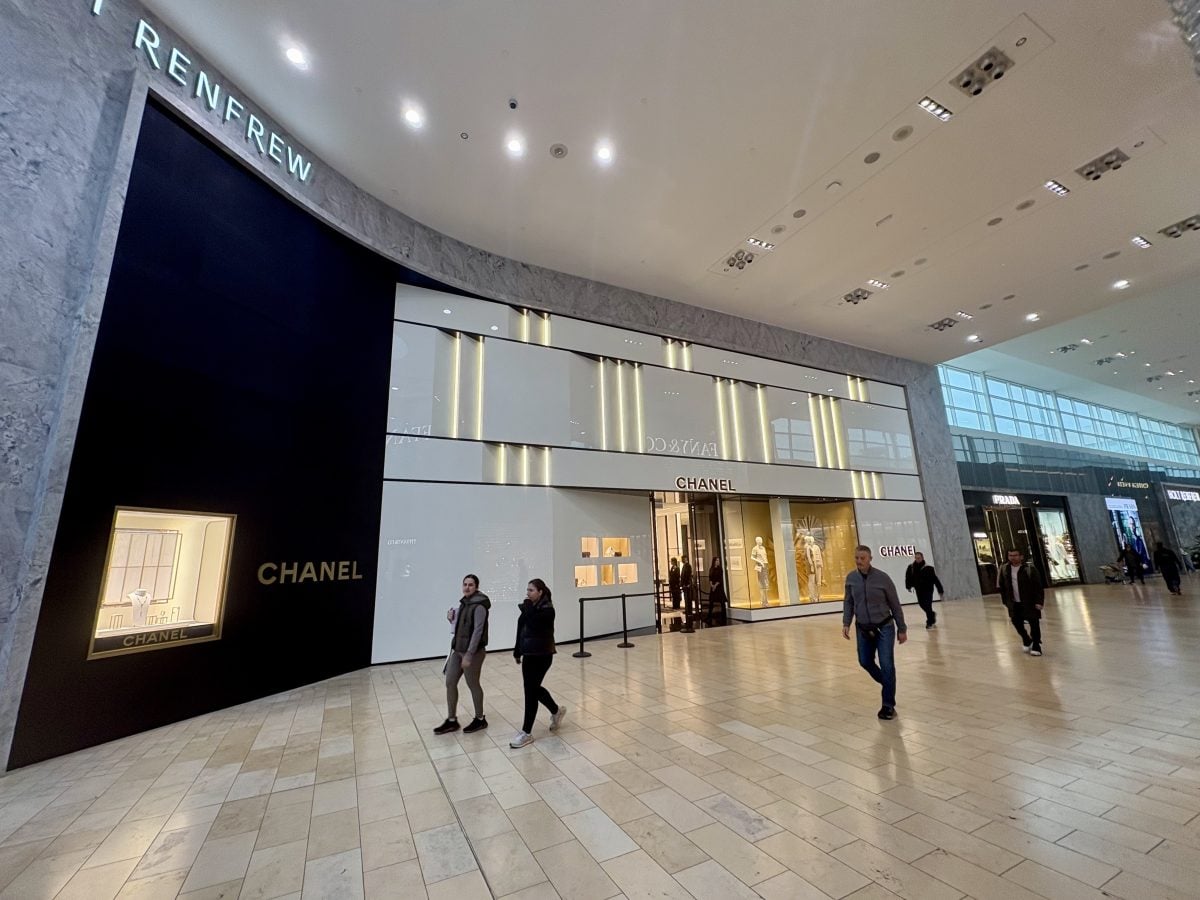
Chanel has opened its largest Canadian boutique at Oakridge Park in Vancouver, bringing together the brand’s fashion, watches, fine jewelry, fragrance and beauty businesses under one roof for the first time in Canada.
The approximately 13,000-square-foot boutique welcomed shoppers on Tuesday, with visitors lining up outside before opening. The store represents Chanel’s second location in Vancouver and one of the most significant luxury retail openings at Oakridge Park since the development officially opened to the public on May 28.
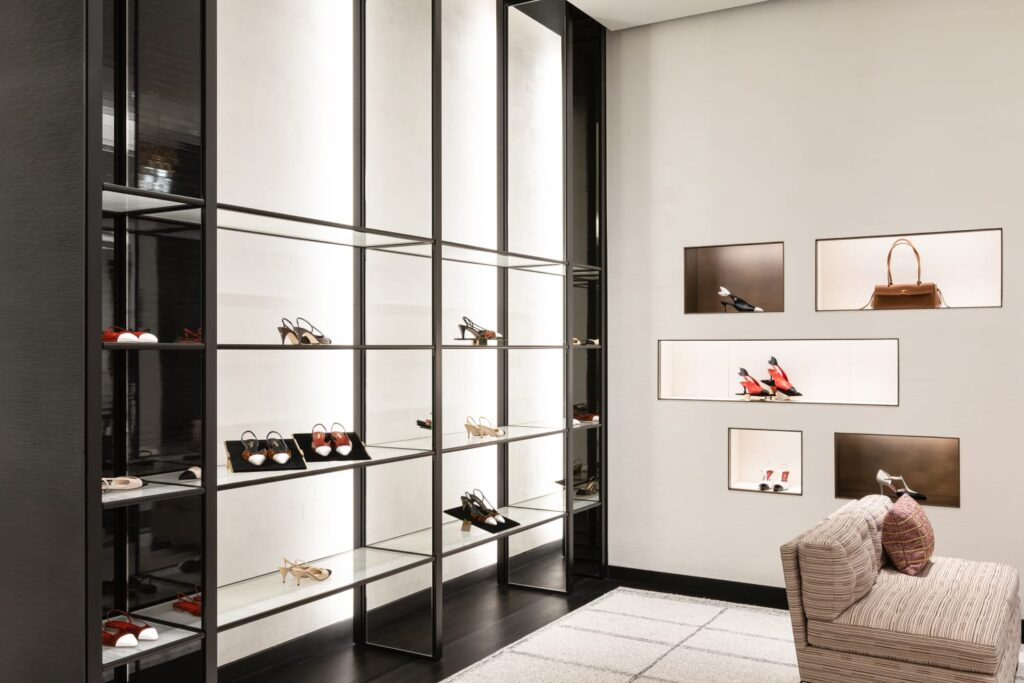
The Peter Marino-designed boutique incorporates several elements created specifically for Oakridge Park, including a prominent crystal chandelier by French decorative arts house Goossens. Dedicated spaces throughout the store showcase ready-to-wear collections, handbags, footwear, accessories, watches, and fine jewelry.
The boutique opens with Chanel’s Métiers d’art 2026 collection, marking one of the first opportunities for Canadian clients to experience the latest designs under the creative direction of Artistic Director Matthieu Blazy. Several products and experiences will also be available exclusively at the Oakridge Park location, including selections from Les Exclusifs and Les Extraits de CHANEL.
The store includes a Watches & Fine Jewelry salon featuring High Jewelry collections, a Fragrance & Beauty destination with a CHANEL Privé suite for consultations and treatments, and a dedicated Care & Repair Salon as part of the House’s CHANEL & moi initiative.
Chanel boutique at Oakridge Park in Vancouver. Photo: Chanel
From 5,000 Square Feet to Canada’s Largest Chanel Store
The scale of the final boutique was not always part of the plan. Sources familiar with the development told Retail Insider that Chanel had initially been evaluating a space of roughly 5,000 square feet at Oakridge Park. The eventual decision to proceed with a boutique more than twice that size reflects a substantially larger commitment to the project and created room for expanded product categories, private client spaces, and specialized services.
Customer research also supported the decision. Sources familiar with the project told Retail Insider that Chanel identified a significant concentration of existing Vancouver-area clients living within a short distance of Oakridge Park, providing another indication of the location’s long-term potential.
The larger footprint aligns with a broader trend among luxury retailers investing in more comprehensive store formats. Beyond product assortment, these locations increasingly incorporate dedicated salons, after-sales services, appointment spaces, and experiences designed to strengthen long-term relationships with clients.
For Chanel, the Oakridge Park boutique provides an opportunity to showcase multiple facets of the business within a single environment while accommodating a broader range of products and services than would typically be possible in a smaller-format store.
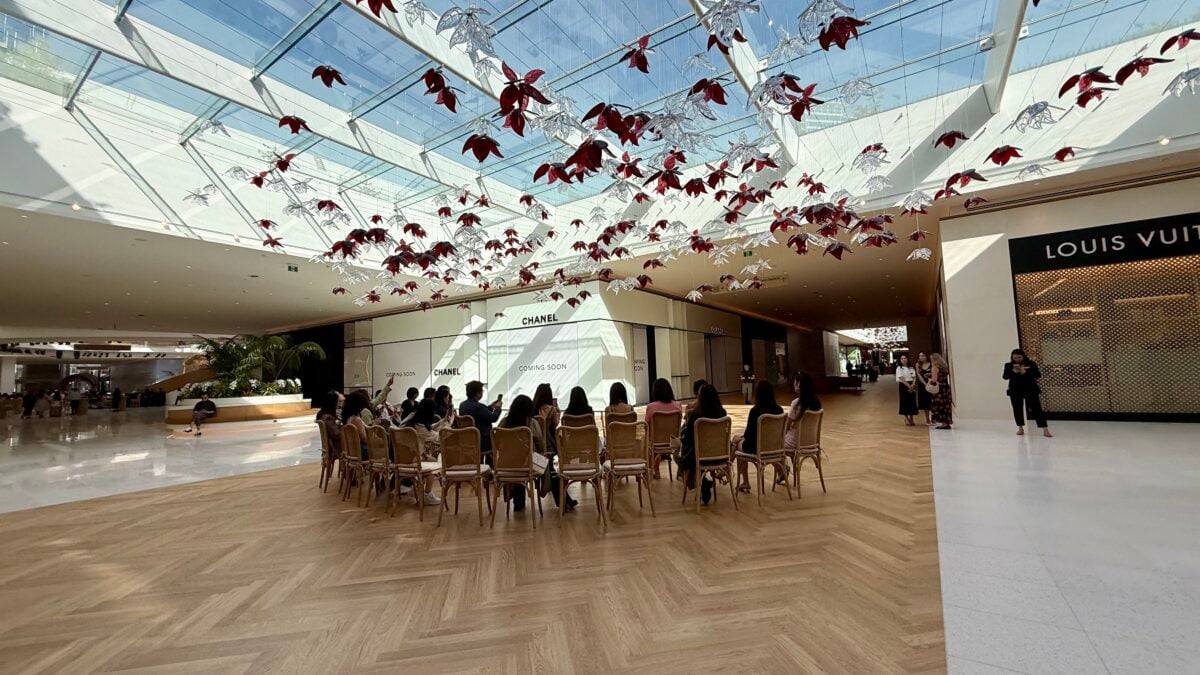
Chanel Boutique before its opening. Photo: Pre-opening event at Oakridge Park in Vancouver, May 27, 2026. Photo: Craig Patterson
A Catalyst Tenant for Oakridge Park
Chanel’s arrival carries significance beyond the boutique itself. Industry sources indicate that the brand was viewed as a catalyst tenant within Oakridge Park’s luxury leasing strategy, helping attract other luxury retailers and reinforcing the development’s position as a destination capable of supporting many of the world’s leading fashion houses.
The Chanel boutique lease involved Toronto-based DWSV Realty, whose founders David Wedemire and Stan Vyriotes have represented a number of luxury retailers at Oakridge Park. The brokerage has also been involved in leasing transactions for brands including Prada, Miu Miu, Versace, Maison Margiela, Thom Browne, Brunello Cucinelli, Coach, and Giorgio Armani.
The luxury leasing strategy has also been led by Sacha Singh, Vice President, Leasing at QuadReal Property Group, who has played a key role in assembling Oakridge Park’s luxury tenant roster.
Chanel is among a second wave of luxury retailers opening following Oakridge Park’s public debut. Recent openings include Acne Studios and Alexander Wang, while additional luxury retailers such as Giorgio Armani continue to prepare for their arrival. They join a lineup that already includes Louis Vuitton, Prada, Miu Miu, Moncler, Loro Piana, Tiffany & Co., Bvlgari, and numerous other luxury brands.
When fully completed, Oakridge Park is expected to feature more than 650,000 square feet of retail and dining space across approximately 100 boutiques and concepts. About 500,000 square feet is currently open to shoppers, with additional retailers expected to launch in phases over the coming months. Future phases of the broader development are also expected to introduce additional retail space as Oakridge Park continues to evolve.
Chanel boutique at Oakridge Park in Vancouver. Photo: Chanel
Vancouver and Chanel: A Relationship Spanning More Than Three Decades
Chanel’s history in Vancouver stretches back more than three decades. The brand opened its first Vancouver boutique in 1991 at 755 Burrard Street with 1,300 square feet, establishing an early presence in what would become one of North America’s leading luxury retail markets.
Chanel later operated a standalone boutique of approximately 5,000 square feet at 900 West Hastings Street before relocating to a concession within Holt Renfrew Vancouver at CF Pacific Centre in 2007. That location has since become one of the brand’s strongest-performing operations in Canada with just over 5,000 square feet on the main floor of Holt Renfrew.
Beyond Vancouver, Chanel maintains a presence in several of Canada’s most prominent luxury retail markets through boutiques and concessions. In addition to its Vancouver locations, the brand operates a standalone store at 100 Yorkville Avenue in iToronto as well as concessoins within Holt Renfrew at Yorkdale Shopping Centre and on Bloor Street in Toronto, as well as within Holt Renfrew Ogilvy in Montreal. Chanel also maintains a presence within Holt Renfrew Calgary, which sources say will be expanding.
The opening of Oakridge Park marks the latest chapter in Chanel’s Canadian evolution. While the downtown location continues to serve Vancouver’s established luxury shopping district, Oakridge Park is emerging as a second luxury retail node anchored by a concentration of international fashion and luxury brands.
Industry observers have long viewed Vancouver as one of North America’s premier luxury retail markets. The city supports a concentration of luxury retailers that is unusual for a metropolitan area of its size, drawing spending from local consumers, international visitors, and a significant base of affluent residents.
Market conditions have shifted in recent years, particularly with lower levels of tourism from China compared to pre-pandemic years and demographic changes that have seen some high-net-worth residents relocate. Even so, luxury brands continue to invest in Vancouver through new stores, relocations, and expanded concepts.
Industry estimates suggest that annual sales at the Oakridge Park Chanel boutique could be expected to be in the $50 million range once the location is fully established. While the figure should be viewed as a market benchmark rather than a company projection, it reflects the scale of opportunity that continues to attract luxury retailers to Vancouver.
Prior to Oakridge Park’s opening, Chanel’s expanded Yorkdale boutique in Toronto within Holt Renfrew held the distinction of being the brand’s largest location in Canada. The new Vancouver store has now assumed that title, marking another significant investment in the Canadian market.
Thirty-five years after opening its first Vancouver boutique, Chanel has unveiled its largest Canadian store at Oakridge Park. The opening reflects both the brand’s long-standing commitment to Vancouver and the emergence of Oakridge Park as a major destination for luxury retail in Canada.
Mall facade of the Chanel boutique at Holt Renfrew Yorkdale in Toronto. Photo: Kyle Rempfer
Running a Shopify store today means wearing about a dozen hats at once. You are managing orders, keeping stock levels in check, running ads, handling customer inquiries, and somehow trying to keep your books clean at the same time. Most store owners do all of this across a tangle of spreadsheets and browser tabs. What actually fixes that chaos is the right set of integrations; tools that talk to each other so you do not have to carry information between them manually.
Before you get into the apps themselves, it is worth knowing what your store is actually paying to run. A free Shopify transactions fee calculator can show you the exact transaction costs on your current plan, which often changes how merchants think about their app budget and which integrations are worth paying for.
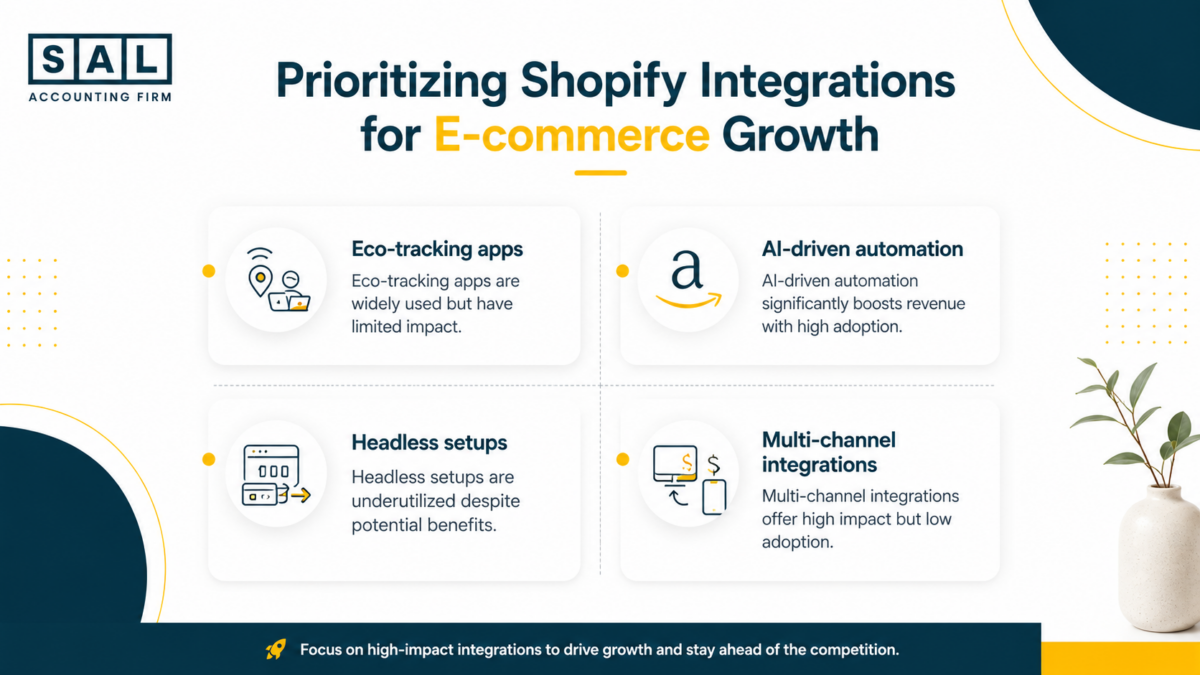
The Shopify ecosystem has grown to over 13,000 apps in its App Store, with the average merchant running around six of them. The platform now powers businesses in more than 175 countries, and its merchants collectively generated over $1.6 trillion in cumulative sales through 2025. For Canadian sellers specifically, the integration landscape carries a few extra wrinkles; GST/HST compliance, cross-border fulfillment, and US market entry all create needs that general ecommerce advice does not always cover.
This post walks through the integrations that actually matter, broken down by the part of your business they touch.
Accounting and Finance
Getting your books right is not optional, and it is the area where most growing stores start bleeding money quietly. Shopify payouts do not equal revenue; by the time fees, refunds, chargebacks, and timing differences come out, the number hitting your bank can look very different from what your dashboard shows. Accounting integrations exist specifically to bridge that gap.
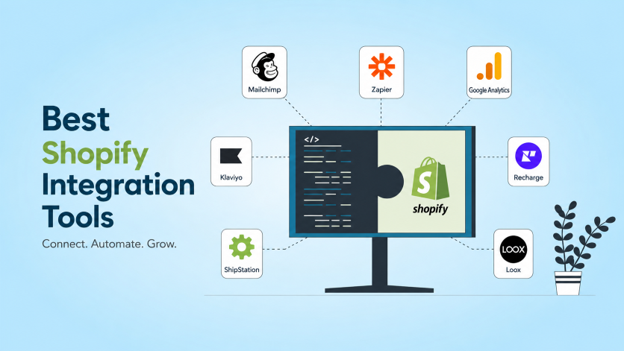
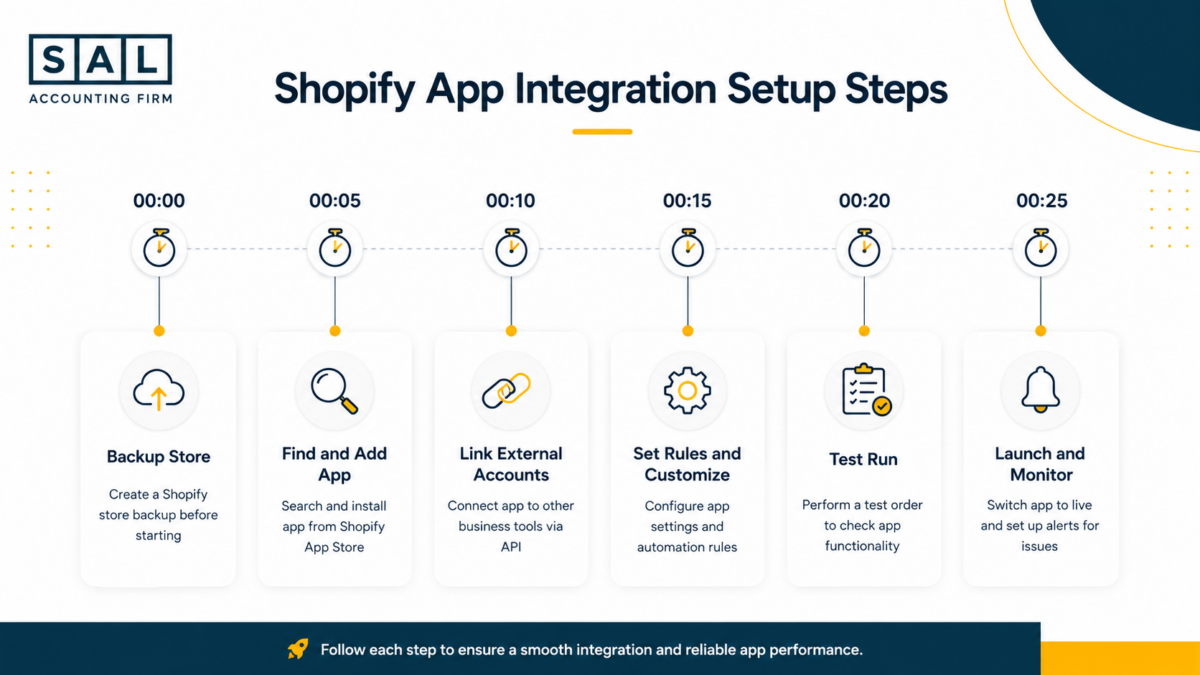
A2X is the tool that most Shopify accountants reach for first. It pulls payout data from Shopify and maps it cleanly into QuickBooks or Xero, matching each deposit to its components: fees, refunds, adjustments. Setup takes around 15 minutes, and it starts at $19 per month. For a solo store owner doing a single channel, it is usually all you need.
Synder handles more complex situations. If you are selling across Shopify, Amazon, and Etsy simultaneously, Synder pulls all three data streams into one reconciled view. It connects with more than ten accounting platforms and handles the kind of multi-currency, multi-channel volume that breaks simpler tools. It starts at $29 per month and has a free trial worth taking before committing.
For Canadian sellers, the practical win here is cleaner GST/HST records. When your accounting software is pulling structured data directly from your sales channels rather than working from bank statements, you are not reconstructing history at filing time; the numbers are already there.
A practical setup tip: start with A2X if you are running one store and move to Synder when you add a second channel. Both link cleanly to Xero, which adds about 30% accuracy on reconciliation compared to manual entry, according to merchant reporting on G2.
Email Marketing and Customer Retention
Most Shopify stores have a leaky funnel. Customers add to cart and leave. They buy once and never return. Email and SMS marketing integrations exist to close both of those gaps.
Klaviyo is the dominant tool in this space, and for good reason. It pulls behavioral data directly from Shopify; what people viewed, what they added to cart, what they bought; and uses that data to build segments that actually mean something. Its AI-driven send-time optimization and abandoned cart flows are responsible for a meaningful share of recovered revenue for DTC brands. It starts free and scales to around $100 per month for larger lists. Setup takes about 20 minutes.
Omnisend is the better choice if you want to blend email, SMS, and push notifications into a single campaign. It is particularly useful for Canadian brands that want something built with privacy compliance in mind from the ground up. It handles CASL alongside US CAN-SPAM requirements, and its drag-and-drop builder does not require any technical background to use well. Free tier available, with paid plans starting at $59 per month.
Both tools deliver measurable results on abandoned cart recovery. Merchants who run structured flows on either platform generally see open rates two to three times higher than broadcast emails, which makes the subscription cost recover itself quickly.
Fulfillment and Inventory
Order fulfillment is where operational bottlenecks show up first as a store scales. Manual label printing, stock counts that fall behind real sales, and oversells during peak periods are all symptoms of the same problem: fulfillment data is not connected to the rest of the store.
ShipStation is the practical fix for shipping. It batches label creation, compares carrier rates across UPS, FedEx, Canada Post, and others, and routes orders based on rules you set. During high-volume periods like holiday season, the time saved on label printing alone justifies the $9 per month starting price. It connects to Shopify in about 10 minutes and requires no technical knowledge to run.
Stocky handles the inventory side. It forecasts demand based on sales history, sends low-stock alerts, and syncs count across channels in real time. For Canadian sellers running Shopify alongside Walmart Canada or another marketplace, keeping stock numbers aligned is what prevents oversells and the GST filing headaches that come with them. Starts at $29 per month, with a free mobile app for on-the-go checks.
The two tools pair well together. ShipStation handles what goes out; Stocky handles what you have left. Running them together cuts fulfillment errors and keeps inventory records clean enough to support accurate bookkeeping.
Analytics and Reporting
Advertising spend without clear attribution is just guessing. The analytics tools in Shopify’s ecosystem range from free and surprisingly powerful to premium and genuinely indispensable for larger stores.
Google Analytics 4 is the right starting point. It tags Shopify events automatically once installed, tracks traffic sources and conversion paths, and uses AI to surface trends in the data. It is free, installs in about 10 minutes, and gives any store owner a clear picture of where buyers are coming from and where they drop off.
Triple Whale is what stores graduating past $10,000 per month typically move to. It unifies Shopify data, ad account data, and email performance into custom dashboards, and its attribution modeling is more reliable than what you get from individual ad platforms. At $99 per month, it is not a casual purchase, but for brands spending meaningfully on paid traffic, the visibility it provides on true ROAS tends to pay for itself.
The practical approach is to run both: GA4 as the baseline layer and Triple Whale on top once advertising spend makes attribution genuinely important.
CRM and Customer Support
Customer relationships do not manage themselves. Support tickets that pile up, repeat customers who feel like strangers, and missed upsell opportunities all trace back to the same gap: there is no system tracking who your customers are and what they need.
Gorgias is the support tool built specifically for Shopify. It pulls order history into every live chat and ticket, which means your support team sees the customer’s purchase record without switching tabs. AI-suggested replies handle common questions automatically. At $10 per month to start, it is accessible for stores of almost any size.
HubSpot’s free CRM connects to Shopify to track leads and build customer pipelines. The free core is genuinely useful for smaller stores, and the $20 per month Pro tier adds enough automation to justify upgrading once you start working systematically on retention. Its 1,000-plus integrations mean it fits into almost any existing tech stack.
For Shopify sellers looking to work with a specialist on the financial side of their store, working with anaccountant for Shopify sellers who understands platform-specific data; payouts, fees, chargebacks, cross-border flows; can save significant time during tax season and surface the kinds of margin issues that get missed when bookkeeping is treated as an afterthought.
For merchants managing industrial products, equipment, or B2B operations, integrating e-commerce platforms with reliable suppliers and inventory systems is becoming increasingly important. Companies such as EMC Industrial help businesses streamline procurement and access a wide range of industrial products that support day-to-day operations. By leveraging solutions from EMC, online stores can improve supply chain efficiency, maintain accurate product availability, and create a more seamless purchasing experience for their customers.
Product Pages and Social Proof
Nobody buys from an empty page. Social proof tools exist to fill product pages with real evidence that other customers have bought and liked what they purchased.
Loox collects photo and video reviews from customers and displays them on product pages in a format that looks good on mobile. For stores with more than 200 SKUs, the auto-collection feature pulls photos by product variant, which means pages stay populated without manual curation. Starts at $9.99 per month.
Judge.me is the faster and more affordable alternative. It imports existing reviews, adds star ratings, and includes SEO markup that helps product pages perform in Google search. The free tier is functional enough for most stores; the $15 per month Pro version unlocks customization and higher volume.
Stacking either tool with an SEO app tends to improve conversion rates meaningfully. Displaying top reviews prominently on product pages, particularly on mobile, consistently lifts trust signals and reduces bounce rates.
How to Pick the Right Stack
The apps above cover the main operational needs of a growing Shopify store, but adding all of them at once is not the right approach. More apps mean more load on your storefront, more integrations to maintain, and more monthly cost.
A sensible starting point for most stores: A2X or Synder for accounting, Klaviyo for email, ShipStation for fulfillment, and GA4 for analytics. That combination covers the highest-impact areas at a cost of roughly $30 to $60 per month to start, and each tool has a clear path to scale as your volume grows.
Add Gorgias when support volume starts taking up meaningful staff time. Add Triple Whale when you are spending enough on advertising that attribution data directly affects budget decisions. Add Loox or Judge.me when your product pages need social proof to close sales.
The integration stack that works at $5,000 per month looks different from the one that works at $100,000 per month. Building incrementally, and auditing what you have at least once a year, is how you avoid paying for tools that no longer match what your store actually needs.
The Financial Side of Scaling on Shopify
There is a version of this conversation that stops at app recommendations, but the stores that scale well tend to think about their tool stack and their financial operations together. Integrations that sync accurately to your accounting software are not just convenient; they are how you know whether your margins are actually what you think they are.
SAL Accounting works with Canadian Shopify and Amazon sellers on the accounting, bookkeeping, and cross-border tax side of running an ecommerce business. Their resource library at their blog covers practical topics specific to platform sellers: how payouts reconcile, how GST/HST works across channels, how to structure finances when selling into the US, and what to watch for when your books stop matching your bank statements. For store owners who want to understand the financial mechanics behind their platform; not just the apps sitting on top of it; it is worth browsing.
The right integrations save time and reduce errors. Understanding how your numbers actually work is what turns that saved time into sustainable growth.