Savers Value Village is reporting a significant recovery in profitability across its Canadian operations, with segment profit growing considerably faster than sales as the thrift retailer improves merchandise productivity, donation sourcing and cost management.
Canadian segment profit increased 10% during the company’s third quarter ended October 3, 2026, while comparable-store sales rose 1.5%. The segment’s profit margin expanded by approximately 210 basis points, extending a recovery from the deterioration recorded in 2025.
The improvement comes as the company focuses on productivity across its established Canadian store network. Savers Value Village is also investing in automated pricing and merchandise-processing technologies, although their contribution to Canadian profitability has not been separately disclosed.
According to the company’s third-quarter financial results, Canadian segment profit reached US$49.9 million, compared with US$45.3 million a year earlier. Canadian net sales increased 2.5% to US$163.7 million, or 4.3% on a constant-currency basis.
The improvement extends across the first 39 weeks of the fiscal year. Canadian segment profit increased 15.1% to US$126.7 million from US$110.1 million during the corresponding period in 2025, while sales increased 3.6% to US$459.2 million. The resulting segment profit margin was approximately 27.6%, compared with 24.8% a year earlier.
The recovery follows a difficult 2025, when Canadian profitability declined despite higher revenue. The company’s 2025 annual report shows Canadian segment profit falling 6.1% to US$153.5 million, while sales increased 3.6% to US$608.1 million.
Canadian segment profit margin declined to approximately 25.2% in 2025 from 27.9% in 2024, using historical figures presented under the company’s revised segment-profit methodology. The 2026 improvement brings profitability closer to earlier levels, although the full-year and 39-week reporting periods are not directly comparable and fiscal 2025 contained an additional week.
Segment profit is a company-defined measure that excludes certain corporate expenses and other costs, and is not equivalent to consolidated net income. The figures are reported in U.S. dollars, with foreign-exchange movements affecting reported Canadian sales growth and potentially influencing other year-over-year comparisons.
Merchandise Costs Decline Despite Higher Sales
The company’s Q3 filing provides a clearer picture of the Canadian operating improvements. During the first 39 weeks of 2026, Canadian cost of merchandise sold, excluding depreciation and amortization, declined to US$181.4 million from US$186.9 million a year earlier, even as revenue increased.
Canadian salaries, wages and benefits rose to US$55.7 million from US$54.7 million, while selling, general and administrative expenses increased to US$95.3 million from US$91.5 million. The reduction in merchandise costs contributed materially to stronger segment profitability, although the company has not quantified the effects of individual initiatives or currency movements on those expenses.
Management has attributed the improvement to more disciplined merchandise production, increased on-site donations, stronger sales yields and operating efficiencies. The company has also cited better off-site processing as it works to align merchandise preparation with demand across its stores.
Secondhand retailing presents different inventory challenges from conventional merchandise purchasing. Individual donated products must be assessed, sorted, priced and prepared for sale, making processing efficiency and the relationship between production volumes and sell-through important operating considerations.
During the November 5 earnings call, Chief Financial Officer Michael Maher indicated that Canadian profit margins could remain near current levels with modest low-single-digit comparable-sales growth. That was a conditional management outlook, not a guarantee that the pace of recent improvements will continue.
Canadian Consumer Demand Shows Cautious Improvement
Canadian sales trends have strengthened during 2026, although growth remains considerably slower than in the company’s American operations. Chief Executive Officer Mark Walsh told analysts that lower-income Canadian customers returned to growth during the third quarter after previously remaining on the sidelines.
“We see this growth as a real green shoot,” Walsh said during the earnings call. He also emphasized that management was planning conservatively, making the observation an encouraging sign within one customer group rather than evidence of a broad consumer recovery.
Management reported that its Canadian customer base continues to skew younger, with higher-income households also important to the business. Canadian sales accelerated sequentially during Q3, while early fourth-quarter comparable-sales trends were running approximately in line with the quarter.
However, the 1.5% Canadian comparable-sales increase was driven primarily by higher average basket values. The company has not established that overall transaction volumes increased, and its demographic commentary does not independently demonstrate a broader recovery in Canadian consumer spending.
Technology Investments Target Processing Efficiency
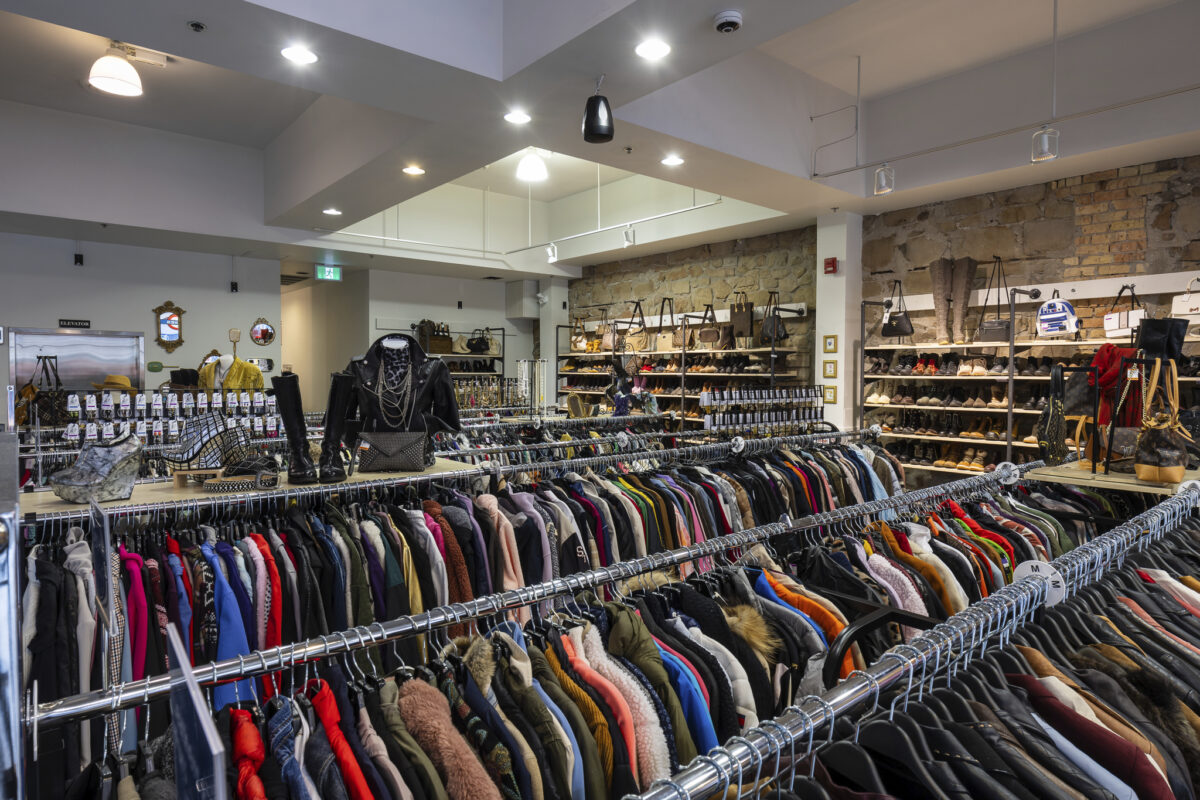
Savers Value Village is pursuing additional productivity improvements through investments in machine-learning pricing and merchandise-processing automation. Its ThriftIQ platform uses a proprietary dataset covering more than 45,000 brands to support pricing decisions for individual secondhand products.
As of Q3, ThriftIQ had priced more than 40 million items and was operating in 108 stores across the United States and Canada. During its November 10 Innovation Day presentation, the company reported higher unit sell-through and larger average baskets in participating stores, with average selling prices similar to or lower than the rest of the fleet.
Management reported that gross profit dollars were growing approximately 100 basis points faster in ThriftIQ stores than in the comparison fleet. That company-reported observation does not independently establish how much of the difference was caused by the technology, and Canadian-specific deployment and financial benefits have not been disclosed.
The company is also introducing Autotagger and integrated image-capture systems designed to reduce manual merchandise-processing work. Management expects approximately US$40 million in capital investment over the coming years, with projected annualized labour savings of approximately US$10 million following full deployment.
Implementation is expected to continue into the first half of 2028, with benefits building as systems are introduced. Both the investment and projected savings apply across the broader company, not exclusively to Canada, and are not realized Canadian financial results.
Different Growth Priorities in Canada and the U.S.
U.S. comparable-store sales increased 5.9% during Q3, supported by higher transactions and average basket values. Most of the company’s approximately 25 planned new store openings in 2026 are concentrated in the United States, where management continues to pursue additional markets.
Canada remains an important source of profitability, with segment margins higher than those in the American business. Management expects U.S. comparable-sales growth to outpace Canadian growth over the longer term while pursuing further productivity improvements across its established Canadian operations.
The next test will be whether Value Village can sustain stronger merchandise yields and tighter processing costs as year-over-year comparisons become more demanding. With automation deployment extending into 2028, the company has outlined another potential source of savings, but its Canadian financial contribution has yet to be established.