As part of Retail Insider Reports, this Q3 2026 Home Furnishings Report analyzes Q3 2026 developments in Canadian furniture, home furnishings, and related retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping retailers, brands, store formats, distribution, and consumer purchasing. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.
This report examines Canadian home furnishings retail, including furniture, mattresses, décor, lighting, flooring, housewares, and home improvement-related merchandise sold through retail channels.
Report Contents
Executive Summary
Canadian home-furnishings retailers continued investing in stores and showrooms during the third quarter of 2026 despite subdued category sales, with expansion increasingly shaped by existing customer demand and more specialized uses of physical space.
Statistics Canada reported seasonally adjusted furniture-store sales of approximately $1.18 billion in July, down 2.0% from a year earlier and 0.6% from June. Constant-dollar furniture sales were 0.5% lower year over year, while other home-furnishing retailers recorded a larger 5.7% annual decline.
Against that backdrop, Article opened a 9,600-square-foot Toronto store after using its online business to identify the market. IKEA introduced a compact store in London, Ont., designed to work alongside separate planning, ordering and pickup capabilities. Cozey opened a permanent Montreal showroom, while Williams Sonoma, Pottery Barn and West Elm announced plans to enter Ottawa in 2027.
These investments point to different approaches rather than a single preferred store format. Digital demand is helping some retailers decide where showrooms belong, while others are separating product display and consultation from inventory and fulfilment or using existing networks to introduce new brands.
The showroom, inventory and fulfilment point increasingly do not need to be the same place. Canadian furniture sales remained below year-earlier levels entering the third quarter, but retailers continued investing in stores, showrooms and distribution.
Several themes emerged during the reporting period:
- Furniture-store sales were down 2.0% year over year in July and 0.5% at constant prices, while other home-furnishing retailers recorded a 5.7% nominal decline.
- Leon’s delivered more retail units during its second quarter while revenue declined, with management reporting that some middle-market customers were moving toward lower-priced products while premium customers continued spending.
- Article and CouchHaus used existing digital demand to help identify markets for physical showrooms.
- IKEA’s compact London store separates everyday shopping and limited immediate furniture inventory from complex planning, full-assortment ordering and pickup.
- Sleep Country plans to introduce Sleep Number primarily through its existing Canadian stores, while Bed Bath & Beyond returned first as an e-commerce business ahead of planned physical stores.
- Larger investments remain part of the market, including Williams-Sonoma’s three-banner Ottawa expansion and Luminaire Authentik’s expanded Toronto showroom.
The common theme is greater selectivity around where stores open, how much space they require and which parts of the purchase they are expected to handle.
Retail Insider Coverage
Online Demand Is Helping Decide Where Stores Open
Article’s new Toronto store provides one of the clearest examples of a digitally established furniture company using customer data to guide physical expansion. The company opened a 9,600-square-foot store at 90 Bathurst Street in September. Ontario accounted for 40% of Article’s Canadian online purchases in 2025, with Toronto representing approximately one-third of that provincial volume.
The store opened in a market where Article already had a substantial digital customer base. Room settings, a swatch library and complimentary interior-design services give customers additional ways to evaluate furniture before purchasing. Article also reported that average orders at its first Vancouver store were more than 20% higher than online orders. The company-reported comparison does not establish that every showroom will produce the same result, but it provides a measurable rationale for adding stores in markets with demonstrated online demand.
CouchHaus used orders, website traffic and fabric-sample requests to support its decision to open an approximately 2,150-square-foot Calgary showroom, while also pursuing a Toronto location. Cozey opened a 3,700-square-foot permanent showroom on Sainte-Catherine Street West in Montreal in September, adding another physical touchpoint to a business developed primarily through e-commerce.
Sundays has used temporary retail before making longer commitments, including its earlier Toronto presence on Ossington Avenue. OMHU has taken a lighter approach, identifying six partner locations in Toronto and Montreal where customers can experience its products without opening company-owned stores. For these digitally developed brands, physical expansion can follow evidence of demand instead of serving as the first test of whether demand exists.
IKEA Separates Shopping, Planning and Fulfilment
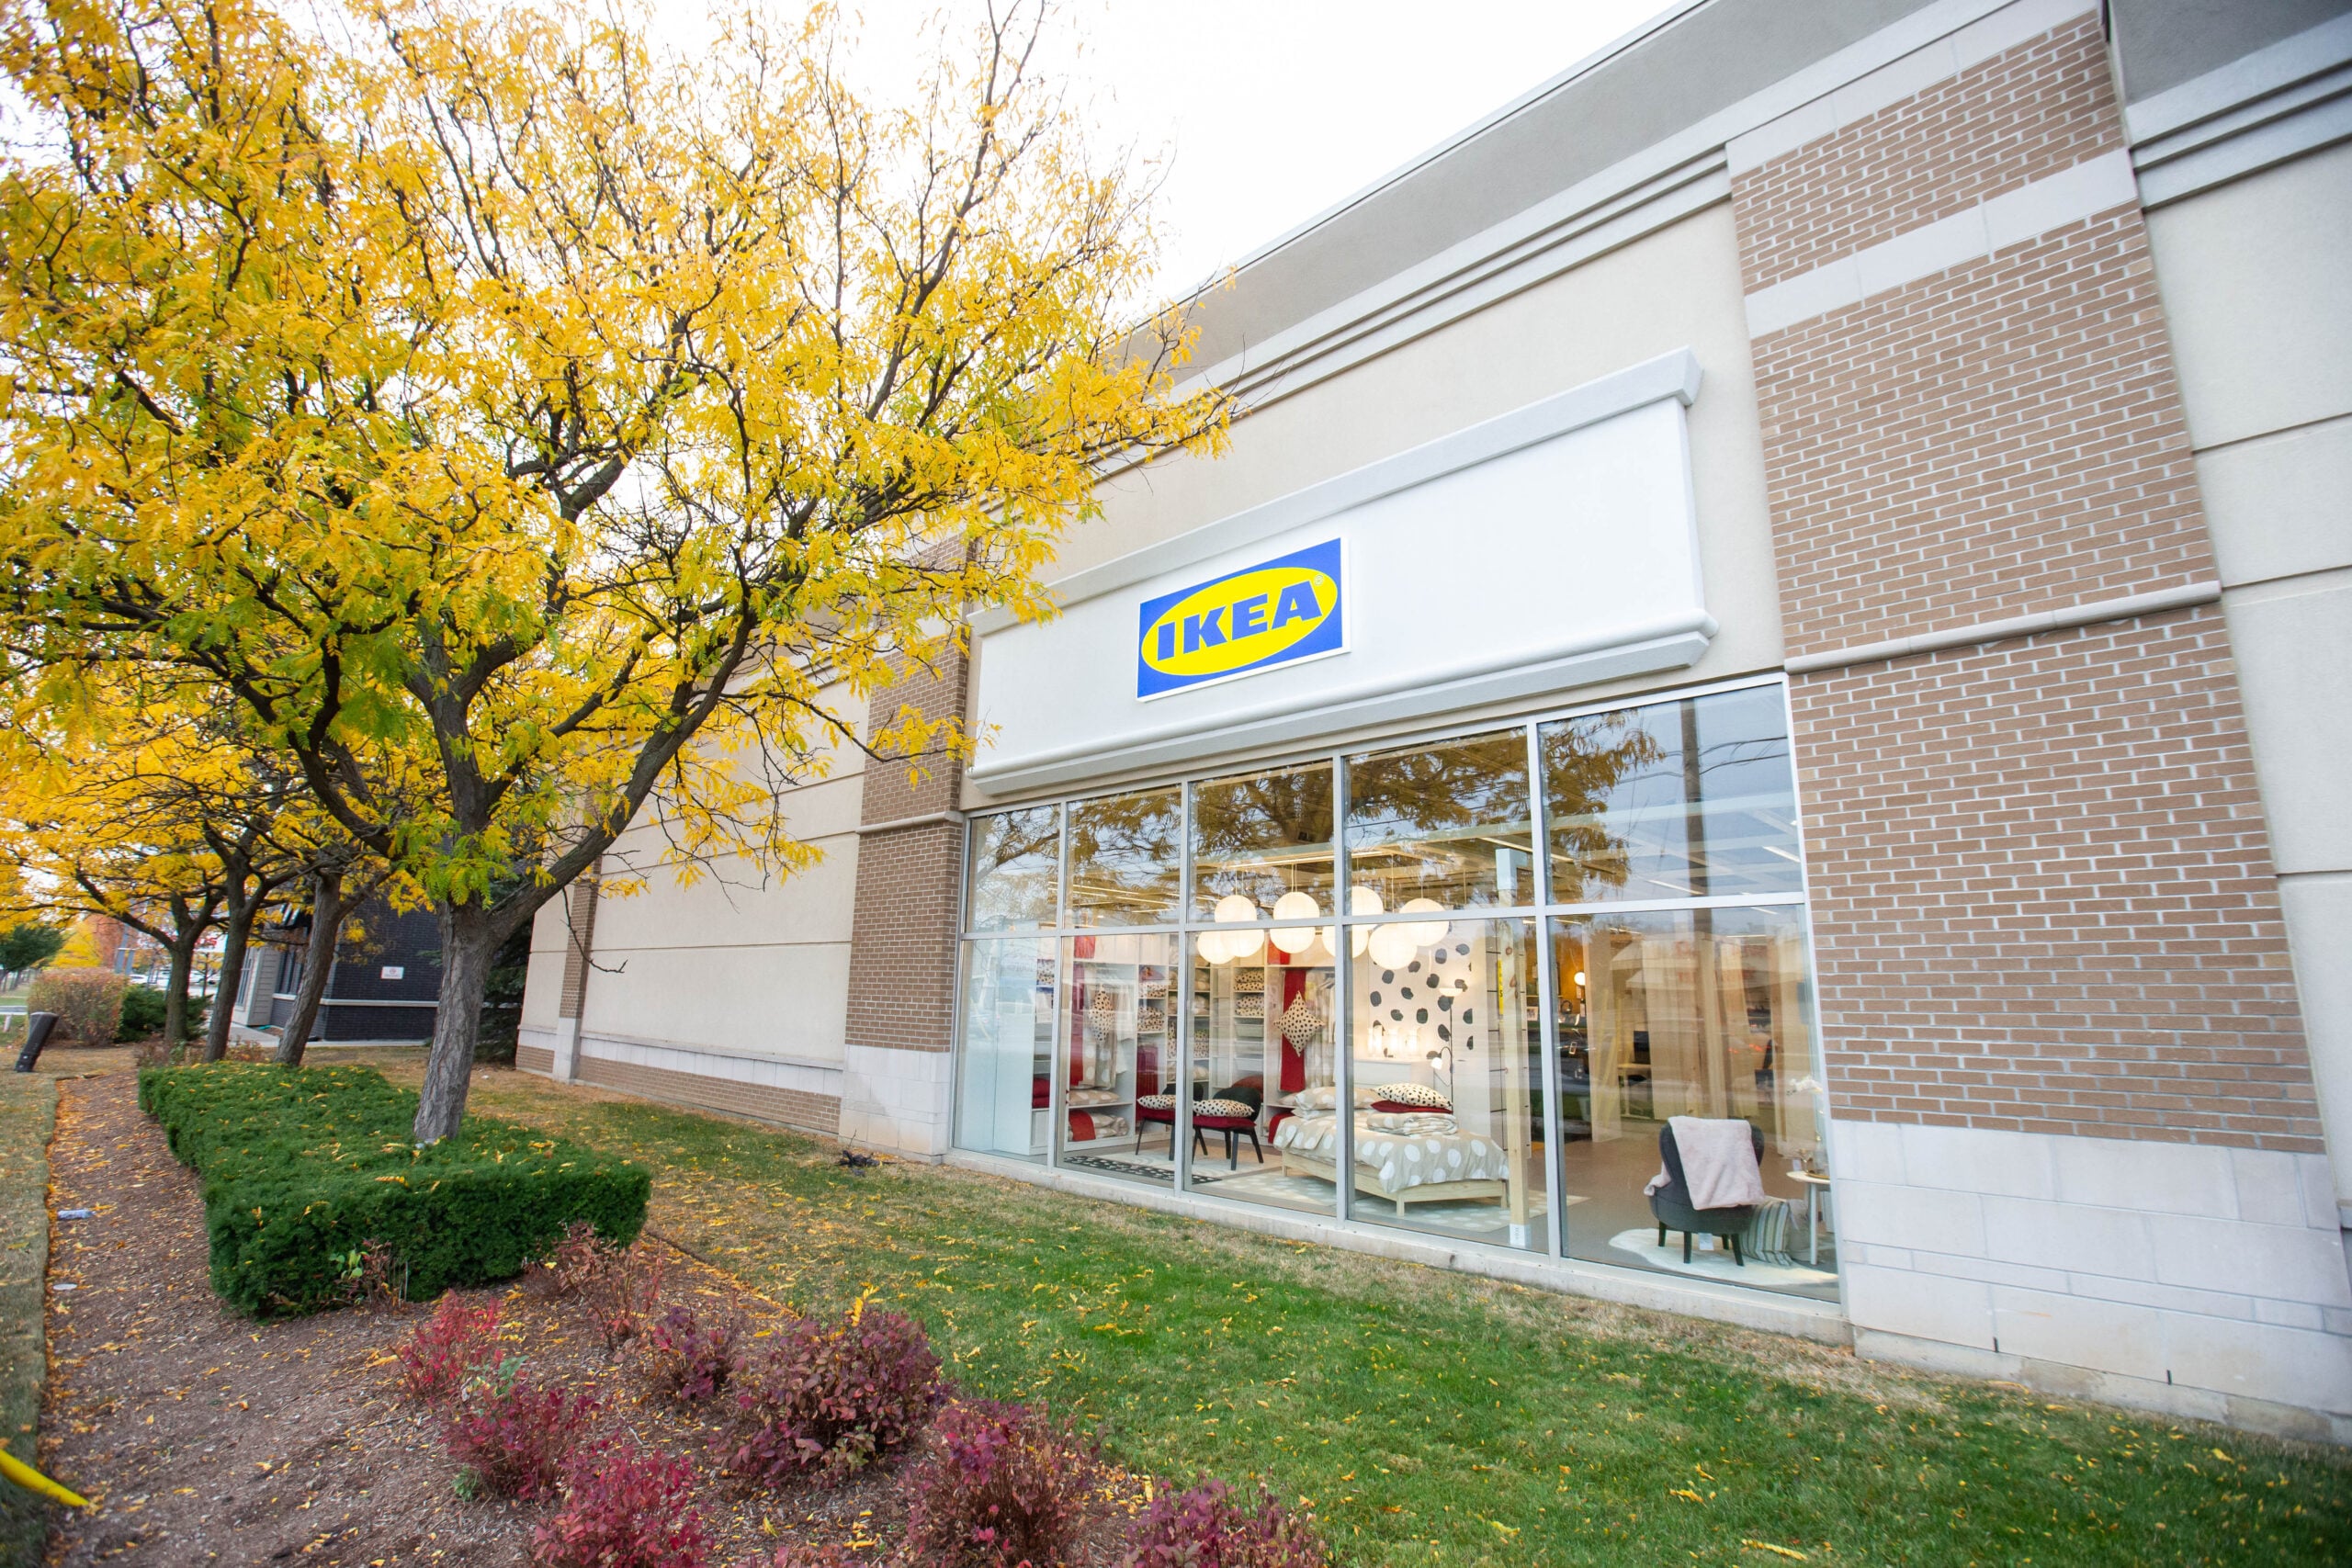
IKEA’s new London, Ont., compact store applies a similar question to a much larger established retailer: which parts of the IKEA experience need to occur under one roof? The approximately 43,000-square-foot store opened at White Oaks Mall at the end of September and is about one-fifth the size of IKEA Burlington. It carries more than 2,500 everyday and seasonal products, with approximately 400 furniture products available for immediate takeaway. Customers can order from IKEA’s full assortment for delivery.
London also has a separate IKEA Plan and order point for more complex projects such as kitchens and wardrobes, along with a pickup location. The compact store handles browsing, everyday merchandise and a limited selection of immediately available furniture. The Plan and order point handles consultation, digital channels provide access to the wider assortment, and fulfilment can occur elsewhere.
IKEA can establish a more substantial presence in London without reproducing its traditional full-size store. The model illustrates a broader shift in home-furnishings retail: the showroom, inventory and fulfilment point no longer have to be the same place.
Existing Store Networks Can Do More Work
Retailers are also expanding assortments and geographic reach through physical infrastructure they already operate. Sleep Country’s acquisition of substantially all of Sleep Number’s assets closed July 31, taking the Canadian company into the U.S. at significant scale. Sleep Number had more than 570 U.S. stores and proprietary adjustable-mattress technology, but had entered Chapter 11 following deteriorating sales and financial pressure.
For Canada, CEO Stewart Schaefer said Sleep Number would be introduced primarily through existing Sleep Country and Dormez-vous stores. Schaefer discussed the possibility of standalone Sleep Number flagships, including potential high-profile mall locations, but did not announce specific leases. The existing network gives Sleep Country a way to introduce the acquired brand and technology to Canadian customers before deciding whether a separate physical network is warranted.
Appliance Canada’s Richmond, B.C., presence provides a smaller example. The higher-end appliance banner operates within an existing Leon’s store, using existing real estate, distribution assets and customer relationships to expand beyond its historical Ontario concentration.
Existing stores can support additional brands and categories without requiring an equivalent increase in standalone locations.
Bed Bath & Beyond Returns Online Before Returning to Stores
Bed Bath & Beyond returned to Canada on September 29 as an e-commerce business, more than three years after the former Canadian operation entered insolvency and closed its stores. The online business launched with approximately 6,000 products from more than 80 brands, with particular depth in bedding and bath. Physical stores are planned for late 2027.
The revived assortment is more curated than that of the former chain, with less initial emphasis on furniture, a competitive category that is also more complex to ship. Future stores are expected to be smaller and more focused than the large locations previously associated with Bed Bath & Beyond.
The relaunch sits within a broader home portfolio. Sleep Country and Dormez-vous provide an existing mattress network, Sleep Number adds sleep technology and products, while Kitchen Stuff Plus contributes kitchen-category expertise. Launching Bed Bath & Beyond digitally gives the operator time to develop the assortment before its planned return to stores, with merchandising and product capabilities being established ahead of a larger real-estate commitment.
Large Physical Investments Still Have a Place
Specialized and smaller formats have not eliminated conventional store expansion. Williams Sonoma, Pottery Barn and West Elm are expected to open at CF Rideau Centre in Ottawa in spring 2027, establishing all three banners in the market. The stores will occupy portions of Level 3 within the former Nordstrom premises, advancing Cadillac Fairview’s redevelopment of the department-store space left vacant following Nordstrom’s Canadian exit in 2023.
The former Nordstrom occupied approximately 157,000 square feet, but individual sizes for the three incoming stores had not been disclosed during the reporting period. The full former anchor footprint should therefore not be attributed to the Williams-Sonoma banners.
The announcement followed Williams-Sonoma management identifying Canada as one of its leading priority international markets during its August earnings call. Company-wide comparable brand revenue increased 6.2%, although no Canadian growth rate was disclosed. The Ottawa project demonstrates that substantial physical commitments remain part of the expansion mix where retailers see sufficient market opportunity.
Consultation Gives the Showroom a Clear Role
Some home purchases continue to benefit from physical comparison and professional advice even when initial research occurs online. Luminaire Authentik expanded its Toronto presence with a larger showroom at 170 King Street East. The space accommodates several consultations simultaneously and allows consumers and design professionals to compare materials, colours and lighting configurations.
A digital configurator complements the showroom, allowing customers to customize products before or alongside an in-person consultation. Specifications can be communicated online, while scale, finish, colour and configuration can benefit from physical evaluation.
Casavogue uses a related combination at its 38,000-square-foot Montreal showroom. Its redesigned website provides dimensions, materials and product information before customers visit, while the showroom provides access to merchandise and advice. Digital information can advance these purchases before the customer arrives, leaving the showroom to handle decisions that benefit from physical comparison and consultation.
Broader Industry Coverage
Furniture Demand Remains Selective
Statistics Canada’s July figures show that this investment is occurring without a broad furniture-market recovery. Seasonally adjusted furniture-store sales reached approximately $1.18 billion, down 2.0% from July 2025 and 0.6% from June. At constant prices, the annual decline was 0.5%.
Other home-furnishing retailers recorded a 5.7% nominal year-over-year decline, while electronics and appliance retailers were down 6.8%. The categories have different product mixes, but weakness extended across several areas of home-related retail.
Leon’s Furniture Limited provides more detail on how that environment is affecting purchases. Second-quarter revenue declined 2.0% to $631.2 million and same-store sales fell 2.2%, even as delivered retail units increased. Furniture sales declined 4.2%, while appliance units increased despite lower appliance revenue. Mattress sales grew at a mid-single-digit rate.
Management said premium customers continued spending, while some middle-market consumers shifted toward opening-price products. Customers can therefore remain active while generating less revenue for the retailer by selecting lower-priced merchandise.
The pattern should not be applied to the entire Canadian market. Williams-Sonoma identified Canada among its leading international markets during its second-quarter earnings discussion, although the company did not disclose a Canadian growth rate.
Wayfair provided additional context. Its U.S. revenue increased 8.7% in the second quarter, while its international segment combining Canada and the United Kingdom declined 1.3%. Management said the modest improvement seen in the U.S. had not extended to those markets, although the combined decline cannot be assigned to Canada alone.
Performance remains highly dependent on operator, customer base, assortment and price point.
Better Stores Cannot Eliminate Fulfilment and Price Risk
A more focused store strategy still depends on what happens after an order is placed. Leon’s cautioned during its second-quarter results that delays on some Asian shipping lanes could affect product availability during the third quarter. Arriving inventory was also carrying higher freight and fuel costs. Management characterized the situation as a supply issue and said it was pursuing alternatives. The company also reported improvement in July traffic and average sale values, but treated the development cautiously because the figures related to written orders that still needed to become delivered sales.
For furniture retailers, generating the order is only part of the transaction. Revenue ultimately depends on inventory availability, delivery and the economics of fulfilling the purchase. Leon’s increase in delivered units alongside lower revenue adds another constraint: transaction volume can improve without equivalent dollar productivity when customers move toward lower-priced merchandise.
Editor’s Take & Outlook
Outlook: The Store Has to Earn Its Role
Several investments implemented or announced during Q3 will provide useful tests in the quarters ahead. Article’s Toronto store will show whether a market identified through strong online demand can reproduce the higher average orders the company has reported in Vancouver. CouchHaus will provide another test of using orders, traffic and fabric-sample requests to select a showroom market.
IKEA’s London network will test whether everyday shopping, planning, full-assortment ordering and pickup can be distributed effectively across smaller physical formats and digital channels. Bed Bath & Beyond must continue developing its Canadian online assortment before its planned return to stores, while Sleep Country faces the task of integrating Sleep Number and introducing the acquired products through its Canadian network.
Williams-Sonoma’s Ottawa expansion will eventually provide evidence from the other end of the spectrum, with an established retailer bringing three physical banners into a new Canadian market. At Leon’s, the near-term measures include whether improved written orders become delivered sales and what happens to average selling prices as the company manages inventory and freight pressures.
Store count provides only a partial measure of these strategies. Conversion, transaction values, sales productivity, delivery performance and occupancy economics will provide better evidence of whether the investments are working. For home-furnishings retailers, the question is increasingly which parts of the purchase justify physical space.
Editor’s Take
Furniture is particularly well suited to hybrid retail. Customers can discover products, compare prices, examine specifications, configure pieces and complete purchases online, while comfort, scale, materials, colour and finish can remain difficult to judge through a screen.
That gives stores a defined role without requiring every location to perform the same functions. Article is using digital demand to determine where a showroom belongs. IKEA is separating everyday shopping from complex planning and fulfilment. Sleep Country can introduce Sleep Number through stores it already operates, while Bed Bath & Beyond has returned digitally before committing to new Canadian locations.
Williams-Sonoma provides a different example, with enough confidence in the Ottawa market to bring three established banners to CF Rideau Centre. The variety of approaches is significant because there is no evidence that one store model suits every retailer, category or customer.
The consumer remains the constraint on all of these strategies. Leon’s results show customers can continue buying while moving toward less expensive products, leaving a retailer with more units but fewer sales dollars.
Physical space ultimately has to contribute enough through conversion, transaction value, service or customer experience to support its operating cost. Q3’s expansion activity shows that retailers continue to see value in Canadian home-furnishings stores, while becoming more precise about what they need that space to do.
Representative Articles
- Article advances retail expansion with Toronto furniture store (Photos) — Sep 14, 2026
- IKEA Canada to open first compact store in London, Ont. on Sept. 29 — Sep 9, 2026
- Williams Sonoma, Pottery Barn and West Elm to Open in Former Nordstrom at CF Rideau Centre — Sep 21, 2026
- Bed Bath & Beyond returns to Canada with e-commerce launch — Sep 29, 2026
- Sleep Country strategy to expand its portfolio of brands: Interview with CEO Stewart Schaefer — Aug 5, 2026
- Leon’s Sees Canadian Consumers Trading Down as Premium Shoppers Keep Spending — Aug 11, 2026
- Leon’s Eyes Western Canada Expansion as The Brick Targets Atlantic Growth — Aug 14, 2026
- Luminaire Authentik Opens Toronto Flagship, Plans Canadian Expansion — Aug 14, 2026
- Furniture retailer CouchHaus targets Calgary and Toronto expansion as national demand drives growth — Jul 6, 2026
- Casavogue Launches New Website to Enhance the Customer Experience — Jul 3, 2026
- Canadian Furniture Brand Sundays Expands in Southern California — Jul 2, 2026
- Scandinavian furniture brand OMHU expands into the Canadian market — Aug 31, 2026