As part of Retail Insider Reports, this Q3 2026 Food Service Report analyzes Q3 2026 developments in Canadian restaurants and foodservice retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping restaurant operators, franchisees, landlords, suppliers, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.
This report examines Canadian foodservice retail, including quick-service restaurants, full-service restaurants, cafés, food halls, chains, franchised operators, and consumer dining trends.
Report Contents
Executive Summary
Canadian restaurant and foodservice sales continued rising during Q3 2026, but the headline growth masks a more difficult operating environment. Statistics Canada reported seasonally adjusted sales of approximately $8.9 billion at foodservice and drinking places in July, up 0.8% from June and 7.0% from a year earlier. All four major industry groups recorded monthly growth, including full-service restaurants at 0.8% and limited-service eating places at 0.4%. Those figures measure current-dollar receipts rather than customer visits or meal volumes. Restaurant prices were also rising, with restaurant CPI up 3.1% year-over-year in August following increases of 2.9% in July and 2.7% in June.
Industry research points to considerable pressure behind the growing sales totals. Restaurants Canada reported that 80% of Canadians were eating out less often because of the cost of living, compared with 75% a year earlier. The association has also reported that 41% of restaurant companies were losing money or breaking even, while average industry pre-tax margins were 4.1%.
Restaurant operators continued investing despite those pressures. Jollibee secured commitments for 26 additional restaurants in Western Canada, Firehouse Subs reached 200 Canadian locations and Tim Hortons maintained a development program of approximately 80 openings. Established chains invested in beverages, renovations, value offers and loyalty, while delivery partnerships created other ways to reach customers.
Consumers can reduce restaurant spending in several ways without abandoning the category, including dining out less frequently, choosing lower-priced items, skipping drinks and extras or picking up orders to avoid delivery fees. Growth increasingly depends on whether restaurants can generate repeat demand and profitable spending from the occasions they capture. Canadian foodservice receipts continued rising during Q3 2026, but inflation, reported consumer restraint and thin restaurant margins complicate the headline growth.
Several patterns emerged during the quarter:
- Consumers reported becoming more selective about dining occasions, while some restaurant companies described pressure on traffic, add-ons and delivery spending.
- Restaurant profitability remained constrained by food, labour, occupancy and other operating costs.
- Expansion continued through corporate and franchise development, although operating restaurants, development commitments and long-term targets represent different stages of growth.
- Mature chains invested in beverages, value, renovations and loyalty to generate more business through their restaurant networks.
- Delivery partnerships expanded customer access, but the financial impact varies according to who acquires the customer, fulfils the order and absorbs the channel costs.
- Company results varied considerably, indicating that affordability pressure alone does not explain differences in restaurant performance.
The next phase of Canadian foodservice growth will test whether operators can convert expansion and product spending into repeat demand while preserving restaurant and franchisee returns.
Retail Insider Coverage
Restaurant Expansion Continues
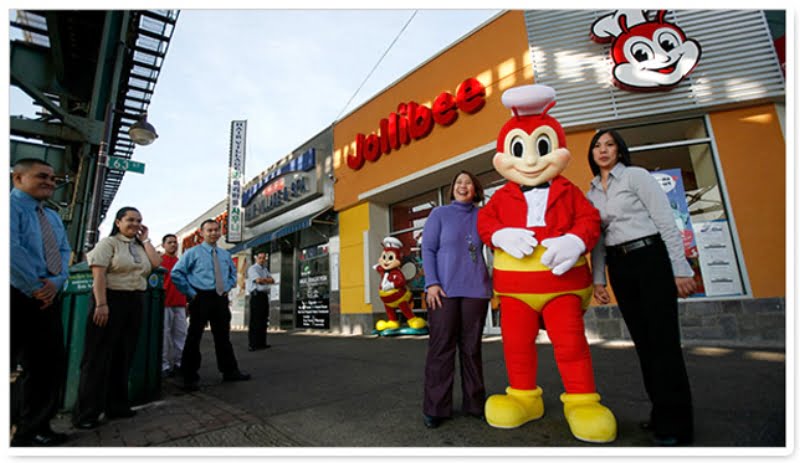
Restaurant development continued across several Canadian markets during the quarter. Jollibee’s Western Canadian franchise agreements provide one of the largest examples. The company has commitments for 16 restaurants in British Columbia over five years and an earlier agreement covering 10 restaurants in the Edmonton market.
Together, the 26 committed restaurants nearly equal Jollibee’s existing 28 company-operated Canadian locations. The commitments do not represent 26 operating restaurants or fully secured sites, with individual locations still requiring site selection, approvals, capital, construction and execution.
Firehouse Subs opened its 200th Canadian restaurant at West Springs Landing in Calgary. Jersey Mike’s entered Calgary at 9631 Macleod Trail as franchise operator Redberry continued pursuing a longer-term target of 300 Canadian locations by 2035.
Recipe Restaurant Group also opened an Olive Garden at Vaughan Mills under its Canadian development agreement, with Ottawa and Ajax locations in development.
Expansion can occur on a much smaller physical scale as well. Craig’s Cookies reached 25 Canadian locations and generally targets approximately 1,000 square feet for a franchisee’s first store, within a working range of roughly 800 to 1,200 square feet.
The chain operates in neighbourhood, shopping-centre and tourist locations, while founder Craig Pike has emphasized avoiding oversaturation as the network grows. Its compact format requires a different level of space and capital than a full-service restaurant or larger quick-service operation.
Operating restaurants, sites in development, franchise commitments and long-term targets all indicate expansion, but they represent different stages and levels of commitment.
Mature Chains Look Beyond the Meal for Growth
Beverages became one of the clearest areas of restaurant spending during Q3. KFC Canada and its franchisees committed $30 million to Kwench, a dedicated beverage offering that includes shakes, sparkling lemonades, boba refreshers and iced lattes. The company outlined plans to expand the concept to more than 400 locations by year-end and approximately 600 in 2027.
Tim Hortons continued expanding its cold-drink platform through products including matcha and new fountain equipment, while McDonald’s pursued a similar opportunity through its expanded beverage platform. McDonald’s management reported encouraging early Canadian results but did not disclose Canadian traffic or average-cheque figures that would quantify the effect. The attraction extends beyond beverage sales themselves. Established restaurants already carry the costs of premises, equipment and networks built around existing meal periods. An afternoon beverage can potentially generate another customer occasion through those assets. The return depends on whether the purchase is genuinely new business and whether the sales justify equipment, ingredients, labour, preparation time and operational complexity.
Tim Hortons demonstrates the scale of the opportunity within an established network. The company and its restaurant owners announced approximately $400 million in Canadian spending for 2026, including roughly 80 new restaurants and 400 renovations, across a network of nearly 4,000 Canadian locations.
Renovations include restaurant layouts, kitchen equipment and digital ordering and pickup infrastructure intended to improve speed, accuracy and customer experience. At that scale, improvements in visit frequency, average spending or operating efficiency across the network can have substantial system-wide effects. Beverages, renovations and new locations provide different routes to stronger performance from a restaurant network.
Loyalty Adds Another Reason to Return
Tim Hortons also expanded its loyalty reach during the quarter through a partnership with Canadian Tire’s Triangle Rewards. Customers who link eligible Tims Rewards and Triangle Rewards accounts can earn Canadian Tire Money on qualifying Tim Hortons purchases, with earning rates depending on payment method. The two rewards currencies remain separate.
The partnership adds another benefit to a high-frequency purchase while connecting Tim Hortons with a larger Canadian retail loyalty ecosystem. Its effect on visit frequency and restaurant-level returns was not disclosed during the quarter.
Delivery Raises the Question of Who Owns the Customer
Restaurant delivery continued expanding, but the quarter’s announcements demonstrated different approaches to customer acquisition and fulfilment. The Keg introduced delivery through DoorDash from more than 100 restaurants across Canada and the United States, extending selected menu items beyond its dining rooms. The announcement did not quantify new sales or restaurant-level returns.
Domino’s Canadian partnership with Skip uses a different model. Customers can place orders through Skip, while Domino’s own Delivery Experts fulfil them.
Pizza Pizza management has separately discussed the higher cost of third-party delivery and the advantages of moving customers toward proprietary ordering channels where possible.
The arrangements separate several parts of a delivery transaction: attracting the customer, processing the order, fulfilling it and maintaining the customer relationship. Third-party marketplaces can provide reach and convenience, but operators still need to assess new sales against commissions, fulfilment costs and the value of owning the direct customer relationship.
Property Investment Can Increase Restaurant Productivity
Foodservice spending is also changing existing retail properties without necessarily adding large numbers of restaurant tenants. At Promenades St-Bruno in Quebec, Primaris is planning a $49.5-million redevelopment that will relocate the food court, increase seating to approximately 1,100 and create an exterior entrance.
The project is designed to support longer operating hours and improve access for pickup and delivery outside regular mall hours. Approximately 20,000 square feet in the existing food-court area will eventually be released for new retail space, while the number of food vendors is expected to remain broadly similar.
For the landlord, the redevelopment changes how customers can use the dining area while creating another leasing opportunity elsewhere in the property. For foodservice tenants, exterior access, additional seating and improved pickup and delivery functionality could expand the range of occasions the space can serve.
The current food court is expected to remain open during construction, with the new food court scheduled for fall 2027 and conversion of the former space following later.
Closures Need Context Too
Restaurant closures require the same scrutiny as expansion announcements. Starbucks announced approximately 250 North American closures alongside café improvements that included Canada, but did not disclose how many closures would occur in this country.
Boston Pizza’s program combines renovations and selected new locations with individual closures, some related to lease and redevelopment circumstances.
MTY’s planned closure of 68 corporate restaurants provides another example. Management said approximately 45 to 50 involved Papa Murphy’s, giving the program substantial exposure to the U.S. pizza market. Banner, geography and reason therefore matter when interpreting closure numbers, just as development commitments and long-term targets need to be distinguished from operating restaurants.
Broader Industry Coverage
Consumers Become More Selective About Dining Occasions
Higher restaurant receipts are occurring alongside evidence that consumers are becoming more selective about when and how they eat out. Restaurants Canada’s September Foodservice Facts findings indicated that 80% of Canadians were eating out less often because of the cost of living. The reported increase in restraint was particularly notable among households earning at least $100,000, although the findings measure stated behaviour and should not be treated as an observed national traffic count.
Pizza Pizza provided one of the quarter’s clearest descriptions of how customers can reduce restaurant spending without eliminating an occasion. Management discussed fewer visits, customers cutting drinks and other extras, and increased pickup as some consumers sought to avoid delivery fees. A customer who continues buying the core meal while removing a drink, dessert or delivery charge still generates a transaction, but the value and profitability of that transaction can change.
Restaurants Canada has also reported consumers protecting some occasions while cutting others, with breakfast and lunch showing greater resilience than some other dayparts. Operators are competing for a place in a more selective household food budget, with frequency, format, price and occasion all influencing where spending goes.
The Whole Bill Matters
Value initiatives during Q3 showed how restaurants are trying to protect demand without relying solely on broad discounting. Subway introduced its Fresh For Less menu in Canada with breakfast, snack and lunch items below $5 at participating restaurants. The positioning applies to individual menu choices and can vary by location, rather than establishing a universal sub-$5 meal price.
MTY described a related pricing constraint during its quarterly reporting. Protein costs remained difficult, but management said consumers’ willingness to absorb increases varied by product, requiring affordable entry choices alongside higher-priced items.
Pizza Pizza described offers directed toward inactive customers as preferable to indiscriminate discounting that could weaken franchisee earnings. Drinks, sides, desserts and delivery also contribute to transaction value, making the loss of those purchases significant even when the core meal remains intact. Operators need to balance traffic and affordability against the food, labour, occupancy and service costs attached to each transaction.
Different Chains Are Producing Very Different Results
Company results released during Q3 illustrate how differently restaurant brands are performing within the same broad consumer environment.
Tim Hortons reported Canadian comparable sales growth of 0.1% for the quarter ended Jun 30, 2026. Boston Pizza reported 2.3% same-restaurant sales growth for the same period, with management saying both traffic and menu pricing contributed positively and pricing provided the larger contribution.
MTY reported Canadian same-store sales down 1.8% for its fiscal quarter ended May 31, although management described improvement in June. Pizza Pizza reported a 5.0% same-store sales decline across Pizza Pizza and Pizza 73 for the quarter ended June 30.
The figures cover different businesses, reporting periods and operating models and should not be treated as a ranking of July-to-September performance. They show that the same broad consumer pressures are producing different outcomes across restaurant systems.
Restaurant Brands International management pointed to product and marketing execution when discussing Tim Hortons’ Canadian performance. Boston Pizza benefited from a combination of traffic, pricing, promotions and restaurant occasions associated with major sporting events.
Affordability remains an industry-wide constraint, while product relevance, value, marketing, location, service and execution continue to influence individual brand performance.
Restaurants Also Compete With Convenience Food
The competitive set for many restaurant occasions extends beyond traditional restaurants. Couche-Tard reported 4.3% Canadian food-sales growth during its first fiscal quarter while Canadian merchandise same-store sales overall were approximately flat.
The company did not quantify sales taken from restaurants, so the result does not establish that convenience stores are gaining restaurant market share. Prepared food at convenience stores nevertheless competes for some of the same occasions, including coffee, breakfast, snacks and quick meals. Value offers and convenient locations broaden the choices available to consumers purchasing food away from home, making the relevant competitive set wider than businesses formally classified within the restaurant industry.
Editor’s Take & Outlook
What Restaurant Operators and Landlords Should Watch
Restaurant growth increasingly needs to be evaluated through the performance of individual locations and customer occasions. For operators, traffic remains important, but so do average cheque, product attachment, daypart mix, repeat frequency, promotional response, delivery mix, food costs, labour requirements and restaurant-level margins.
Franchise systems need development commitments to become viable sites and operating restaurants, while new units need to generate acceptable returns without excessive cannibalization of existing franchisees. Mature systems face a different scale question. Improvements across hundreds or thousands of restaurants can have a greater effect than an annual opening program, making renovations, beverages, loyalty and digital initiatives important even when they do not add locations.
For landlords, visibility, access, parking, drive-thru capability, pickup areas, delivery access, operating hours, patios and nearby competition can influence restaurant performance. Promenades St-Bruno shows how property design can expand the usefulness of foodservice space without substantially increasing the number of vendors.
Outlook: Can Growth Produce Repeatable Restaurant Economics?
The next six to 18 months will provide several tests of the industry’s current growth plans. Jollibee’s Western Canadian agreements will begin to show how quickly committed franchise development converts into secured sites and operating restaurants. KFC’s wider Kwench rollout will test whether beverage demand can be sustained beyond the initial launch period across a much larger restaurant base.
Tim Hortons will continue spending on openings, renovations, beverages and loyalty while seeking stronger performance from its Canadian network. McDonald’s beverage expansion will provide another indication of whether established quick-service restaurants can create new occasions through locations already in operation.
Value initiatives will need to protect demand without weakening franchisee returns. Delivery partnerships face a similar test as operators assess whether third-party reach produces new orders or moves existing demand through more expensive channels. Restaurant profitability remains the broader constraint. Nominal sales can continue growing while food, labour, occupancy and service costs absorb much of the increase.
Repeat demand and restaurant-level returns will provide a clearer measure of sustainable growth than opening targets or current-dollar sales alone.
Editor’s Take
Canada’s foodservice industry continues to invest as consumers become more selective about dining out. Restaurant chains are opening locations, franchise agreements are being signed and mature systems are spending on renovations, beverages, loyalty, value and delivery. Landlords are also investing in foodservice space and the infrastructure surrounding it.
The economics behind that activity are under more pressure than headline restaurant receipts suggest. Consumers can visit less often, choose a lower-priced format, skip a drink or side, use a promotion, pick up an order instead of paying for delivery, or move a quick meal occasion to a convenience store. Operators are competing for the visit, the composition of the cheque and the next visit.
New locations remain an important source of growth for emerging restaurant systems. Mature chains have another powerful lever in their established networks, where improvements in frequency, product attachment or operating efficiency can be applied across hundreds or thousands of restaurants.
Differences in company performance also show why consumer pressure cannot explain every outcome. Product, value, marketing, location and execution continue to matter. The next phase of Canadian foodservice growth will be determined by whether operators can give consumers enough reason to return while keeping each occasion economically attractive for restaurants and their franchisees. Nominal sales growth alone will not answer that question.
Representative Articles
- Jollibee Plans Major Canadian Expansion as 26 New Restaurants Committed Through Franchising — Lee Rivett, Aug 10, 2026
- Tim Hortons Targets Stronger Canadian Growth With New Stores, Beverages and Loyalty — Lee Rivett, Aug 7, 2026
- McDonald’s Canada Beverage Platform Shows Early Success — Lee Rivett, Aug 6, 2026
- KFC Canada’s $30M bet on beverages — Mario Toneguzzi, Aug 31, 2026
- Subway Canada launches under-$5 menu as consumers weigh lunch costs — Mario Toneguzzi, Sep 1, 2026
- Canadian Tire, Tim Hortons launch linked loyalty program — Mario Toneguzzi, Sep 2, 2026
- The Keg launches first-ever delivery service through exclusive DoorDash partnership — Mario Toneguzzi, Jul 24, 2026
- Skip teams up with Domino’s — Mario Toneguzzi, Sep 29, 2026
- Promenades St-Bruno to invest $49.5M in food court redevelopment, new retail space — Mario Toneguzzi, Aug 26, 2026
- Craig’s Cookies Grows to 25 Locations as Franchise Brand Expands Nationally — Craig Patterson, Sep 29, 2026
- 8 in 10 Canadians cutting back on restaurants: Restaurants Canada — Mario Toneguzzi, Sep 24, 2026
- Boston Pizza Accelerates Canadian Restaurant Renovations, Adds New Locations — Craig Patterson, Aug 20, 2026
- Starbucks undertakes massive refresh of North American locations and closing 250 stores — Mario Toneguzzi, Sep 25, 2026
- Firehouse Subs opens 200th Canadian restaurant in Calgary — Mario Toneguzzi, Sep 11, 2026
- Jersey Mike’s Subs opens first Calgary location as Redberry targets 300 Canadian stores by 2035 — Mario Toneguzzi, Sep 10, 2026
- Recipe opens first Ontario Olive Garden as part of national expansion plan — Mario Toneguzzi, Jul 2, 2026