Home Blog Page 163

Pickleplex plans to double footprint by end of year

Pickleplex
Pickleplex

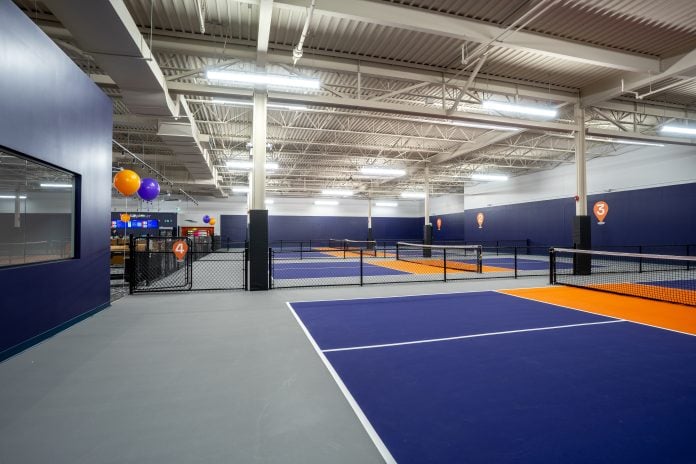
Pickleplex Social Club has grown from its first location in Barrie to 12 clubs across Ontario, with plans to nearly double by year end. 

In a market where retailers are pulling back, they’re signing leases and filling courts. In the past year or so:

  • Named the official host venue for the 2026 Pickleball Canada National Championship (August 25 to 30)
  • Returned to The Well in downtown Toronto for a second year with RioCan for their pop-up activation
  • Launched a floating pickleball court on Toronto’s waterfront
  • Members averaging 30 hours on court per month
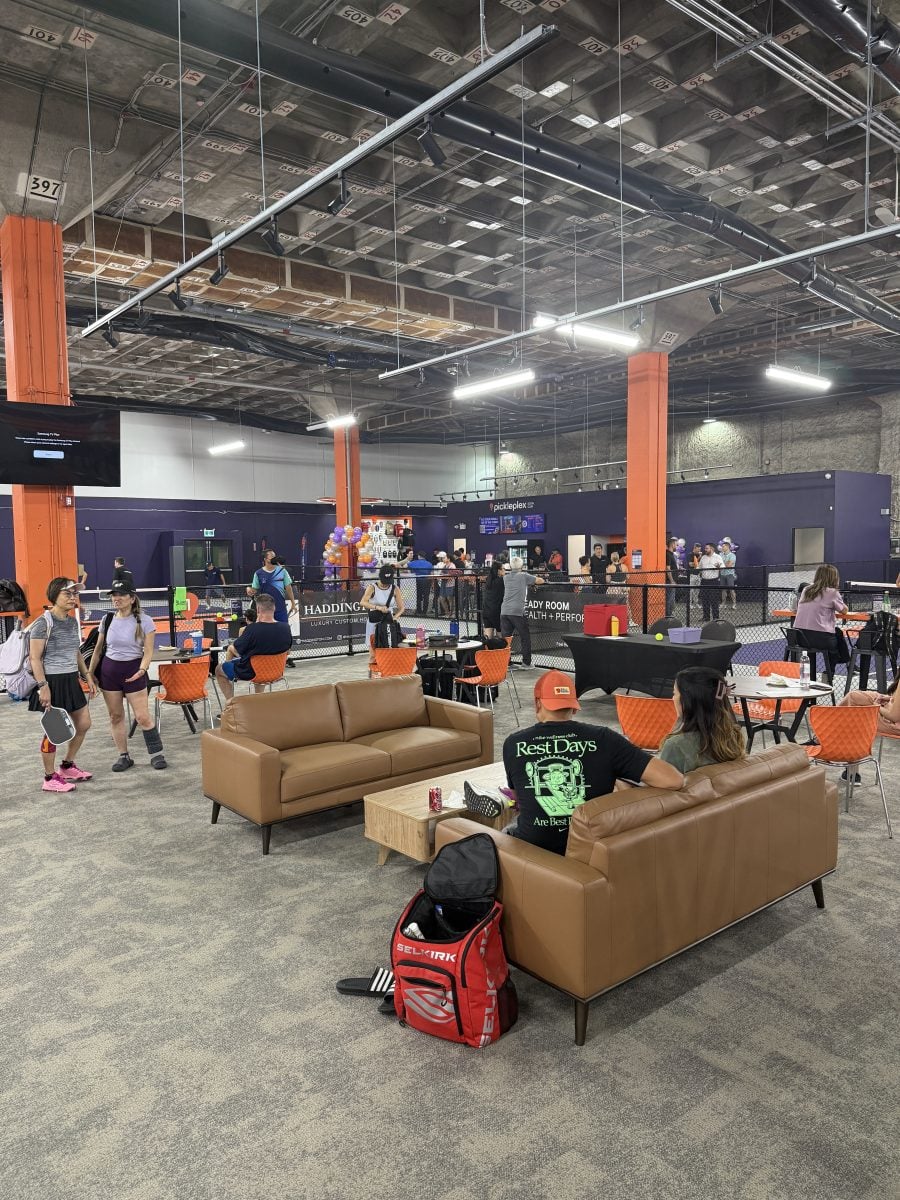
Pickleplex
Pickleplex

In an email interview, Steven Fry, Co-Founder President and CEO of Pickleplex, and Justin Farbstein, Co-Founder and Chief Development Officer of Pickleplex, talk about the company’s plans.

While many Canadian retailers are slowing expansion, Pickleplex is accelerating—what’s driving your confidence to keep signing leases and scaling right now?

We’re seeing very strong, consistent demand for high-quality indoor and outdoor racquet sport experiences, and that demand is still underserved in most markets. Our model is built around recurring membership, which gives us good visibility into revenue and utilization early on. At the same time, landlords are actively looking for experiential tenants that drive traffic and community engagement, which aligns well with what we offer. Partnerships like Cadillac Fairview on the top level of the parkade at Shops at Don Mills is a good example of repurposing underutilized space into vibrant pickleball destinations shows how retail real estate is evolving, and we’re well positioned to be part of that shift.
Steven Fry
Steven Fry

You’ve grown from one location in Barrie to 14 across Ontario—what does your ideal location look like today, and how has your real estate strategy evolved?

Our ideal location has always started with a retail-first mindset—high-quality, high-traffic areas where people already spend their time. From day one, we prioritized visibility, accessibility, and being embedded in strong communities over simply finding the cheapest space.

As we’ve grown, our strategy has expanded to include a wider mix of formats—malls, select industrial spaces, outdoor builds, and more unique specialty locations. That evolution allows us to reach players in different ways while staying true to the core principle of meeting people where they live, work, and socialize.
Justin Farbstein
Justin Farbstein

Members are averaging 30 hours on court per month—what’s behind that level of engagement, and how does it translate into business performance?

Pickleball is inherently social and easy to pick up, which drives frequency, but we’ve built a structured programming model that keeps members engaged—leagues, clinics, ladders, and social play. Our clubs become part of people’s weekly routines. That level of usage translates directly into strong retention and ancillary revenue across lessons, events, and food and beverage where applicable. It also creates a strong community dynamic, which is a big driver of long-term value.

How important are experiential activations and partnerships—like your work with RioCan and The Well—in building the brand and driving traffic?

They’re a core part of our strategy. We’re not just building courts—we’re building destinations. Partnerships with groups like RioCan and activations at The Well have shown how pickleball can anchor a broader lifestyle experience. These types of activations drive meaningful foot traffic, introduce new players to the sport, and create a much stronger brand connection than a traditional facility alone. Our work with Cadillac Fairview at Shops at Don Mills is another step in that direction, bringing the sport into a highly curated retail environment.
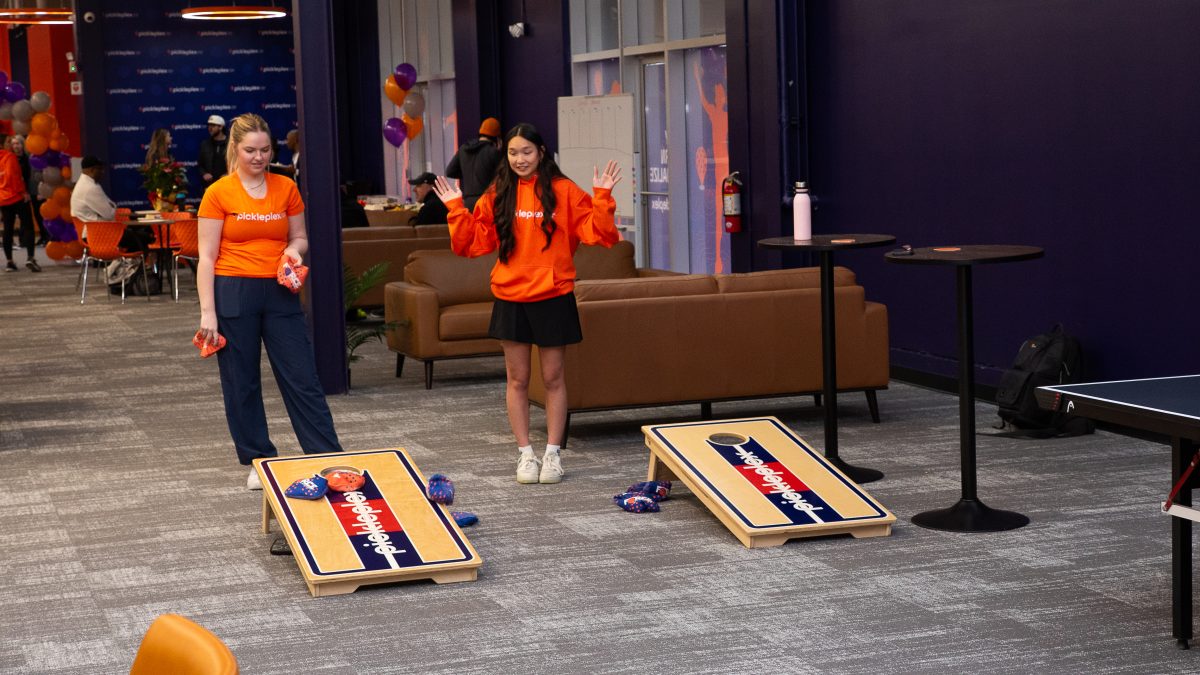
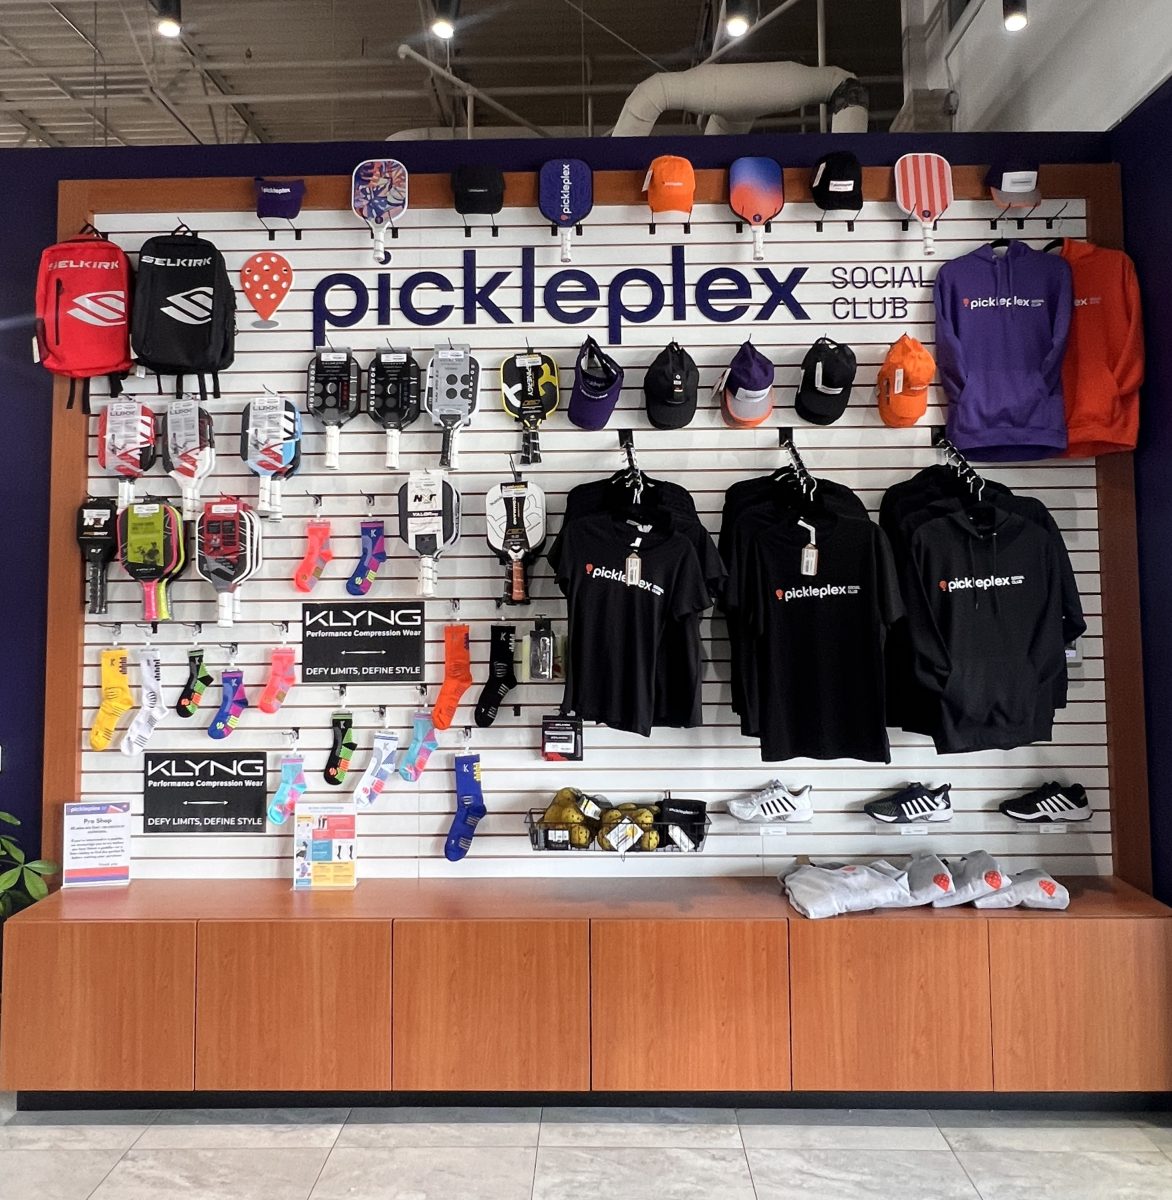
Pickleplex photo
Pickleplex photo
Pickleplex
Pickleplex

What does hosting the 2026 Pickleball Canada National Championship mean for Pickleplex’s brand positioning and future growth?

Hosting the Pickleball Canada Nationals is a major milestone for us. It reinforces our position as a leading operator in the country and validates the quality of our facilities and programming. It also brings national visibility to the brand, both with players and with potential partners and landlords. Events like this help accelerate growth by building credibility, attracting new members, and opening doors to larger partnerships and future expansion opportunities.

More from Retail Insider:
Public Grocery Stores Debate Gains Traction in Canada

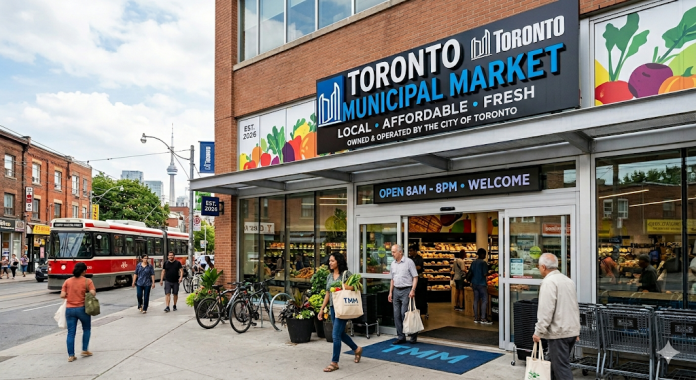
Image of what a government-run grocery store in Toronto could look like. Image: RI/Google

By Michael von Massow

Does Canada need public grocery stores? The debate has moved into the mainstream since Avi Lewis became the new leader of the NDP after campaigning on a plan for government-run grocery stores.

The premise is relatively straightforward: governments would build and run grocery stores that offer pricing at levels well below those of traditional stores.

Similar ideas are gaining traction at the municipal level. Toronto city council has advanced a pilot project for four city-run grocery stores, and New York Mayor Zohran Mamdani has announced plans for five municipal grocery stores.

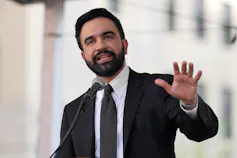
A man in his 30s with dark hair and a beard wearing a suit speaks into a microphone
New York City mayor Zohran Mamdani has announced plans for municipal grocery outlets to be built in each of New York City’s five boroughs. (AP Photo/Seth Wenig)

With food prices still elevated, the proposal for public grocery stores sounds appealing. Lewis and his advisers have suggested that government-run store prices would be 35 to 40 per cent lower than those Canadians are currently paying.

The real question is whether public grocery stores are feasible and, if so, whether they’re the most effective way to deliver relief to consumers. The evidence suggests otherwise.

Scale is everything in grocery retail

Successful food retailing requires significant distribution infrastructure to efficiently bring products to the retail location. Loblaws, Canada’s largest food retailer, has more than 2,400 stores. Empire Group, which includes brands such as Sobeys, has more than 1,600 stores. This scale allows them to achieve significant purchase volumes while lowering distribution costs.

This is also why larger retailers have been purchasing regional grocers such as Longo’s and Farm Boy. It allows the smaller chains to benefit from the purchasing and logistical infrastructure of the purchaser.

Even with those advantages, large retailers achieve relatively low margins. Operating income (revenue minus direct costs and excluding things like taxes and depreciation) generally represents between four and six per cent of total revenue.

A new government-run chain operating without that infrastructure would be starting from behind, and would require substantial subsidies to achieve the promised price reductions.

Some proposals suggest public stores could only carry staples, which would reduce the cost of inventory. While that’s true, this overlooks how grocers cover overhead: by the size of the “basket” of each customer. Basket size is the total value of everything each customer buys.

Basket size is a key metric for grocers, who often price select staples below cost to draw customers into the store. Margins on those staples are already thin, meaning government stores would require greater subsidies to achieve discounts without the benefit of higher-margin secondary products.

Examples come with trade-offs

Supporters of public grocery stores point to examples in Mexico, the United States and Canadian provinces. Upon closer examination, however, these examples highlight the challenges and costs that suggest that this path is not feasible.

Mexico has operated government-run grocery stores for years. The number of stores has declined significantly in the past decade, with only approximately 50 remaining, located predominantly in the Mexico City area.

Price tracking by Profeco, the country’s federal consumer protection office, shows these stores are less than two per cent cheaper than Walmart (the dominant Mexican food retailer) and some private grocers are cheaper still. A significant informal food sector of market stalls offers additional competition. This is nowhere near the 35 to 40 per cent savings being promised in Canada.

The U.S. military commissaries offer groceries that are almost 25 per cent cheaper on average for active service members and veterans. But federal appropriations pay for labour, rent/real estate, distribution costs and other overheads.

The annual subsidy represents approximately 25 to 30 per cent of sales, meaning the U.S. government spends more than consumers actually save, with an ongoing backlog of maintenance also increasing the deficit.

There is some suggestion that the commissaries should be privatized to achieve the efficiencies of larger chains while still providing cheaper options for soldiers’ families and veterans living close to the bases.

Provincial control of alcohol and cannabis retail in Canada is sometimes raised as a parallel. However, these models are not designed to lower prices. Instead, they are designed to collect taxes and control prices. The policy direction runs opposite to what public grocery advocates are proposing, so this comparison is invalid.

What governments are already doing

Food prices are rising for reasons largely out of the control of Canadian governments, including geopolitical events (such as the wars in Ukraine and Iran) and the climate crisis. What governments can do is cushion the impact for those hit hardest.

Canada’s GST/HST rebate program already does some of this, offsetting taxes paid on goods and services to eligible households. Beginning in July, the new Groceries and Essentials Benefit will replace the GST/HST credit. The structure and eligibility rules will remain the same, but payments will increase by 25 per cent for five years.

The program is not in the range of 35 to 40 per cent, but it’s intended to offset much of the increases Canadians have experienced over the past few years. This program provides direct and targeted benefits for those feeling the most pressure from rising food prices.

There is also a federal program in place aimed at reducing the cost of staple items in remote northern communities. Nutrition North subsidizes retailers in places that experience high levels of food insecurity and alongside high transportation costs. Research suggests that the subsidy is, on average, fully passed through to consumers.

Unlike a tax rebate, the program cannot target specific consumers, but it can target certain categories of food. Milk and bread are cheaper for shoppers, for example, but frozen pizzas are not.

The most effective path forward

Building a national chain of public grocery stores would immediately raise a question of equity: how would governments decide which communities get a store and which don’t?

The cost of building thousands of stores would be prohibitive; a few dozen would leave most Canadians without access while costing governments more per transaction that consumers would save. And, because anyone could shop there, it would dilute the benefit for those who need it most.

The money would be much better spent directly supporting the Canadians who need it most. Direct payments remain the most efficient use of taxpayer money. They can be targeted to low-income households and deployed quickly.

Nutrition North-style subsidies work well in specific areas but can’t target individual households. A card or voucher system could combine both approaches by targeting and selecting eligible food products, though the administrative costs would either dilute the benefit to recipients or raise the overall price of the program.

Even so, a well-designed voucher program would almost certainly deliver more value per dollar spent than building and operating retail infrastructure from scratch.

There are ways to make food more affordable for Canadians. Government grocery stores just aren’t one of them.

About the Author: Michael von Massow is a Professor of Food Economics at the University of Guelph.

This article originally appeared in The Conversation.

More from Retail Insider:
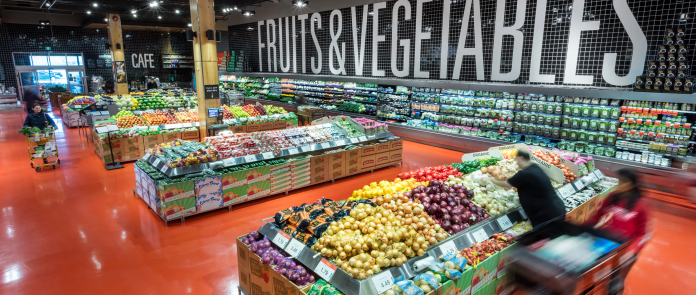
Meat and Produce Prices Rise Together in Canada

Photo: Loblaw Companies

Food inflation in Canada may have eased to 4.0% in March, but don’t be misled by the headline. The number that matters most—food purchased from stores—actually rose to 4.4%, up 0.3 percentage points. That increase tells us something important: cost pressures are not fading. In fact, they are shifting—and intensifying in key categories.

Look at what’s driving the change. Meat and vegetables are both rising, and for very different reasons. But together, they paint a clear picture of a food system still under strain.

Start with meat. Beef prices are up 12.7%, chicken 7.5%, pork 6.2%. This is not short-term inflation. It’s structural. North America is still dealing with the aftershocks of herd contraction. Farmers reduced livestock during periods of high feed costs and uncertainty, and rebuilding those herds takes time—often years. In the meantime, supply remains tight.


Layer on top of that higher input costs. Feed, transportation, labour, and processing have all become more expensive. Energy, in particular, plays a critical role. From running farm equipment to transporting animals to powering processing plants, rising fuel costs are pushing prices upward across the entire protein supply chain. These are not costs that can easily be absorbed—they are passed on.

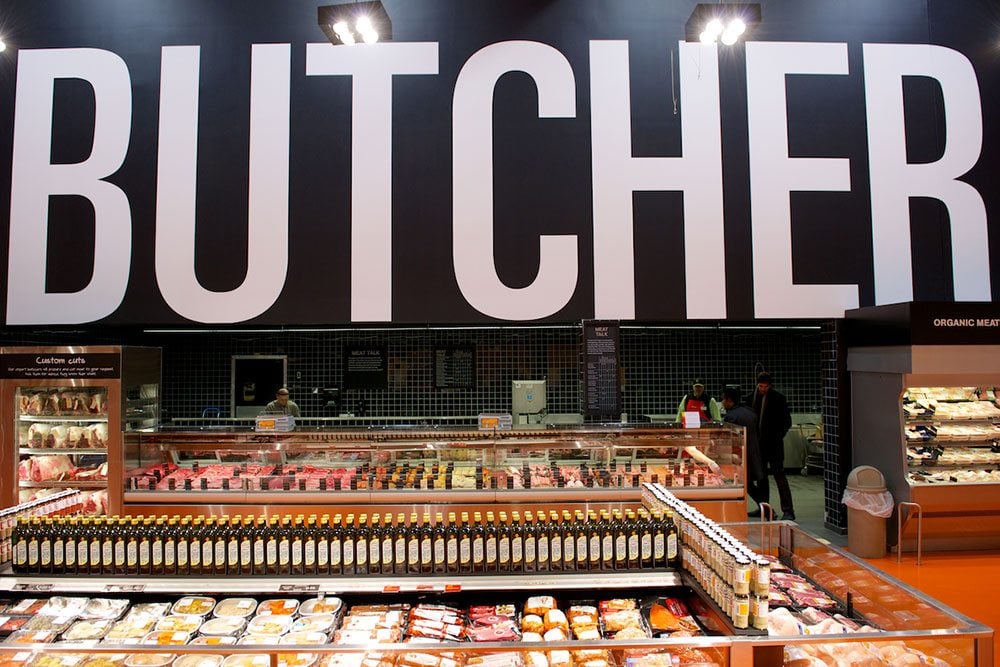
Loblaw Store Meat Department. Photo: Loblaws

Vegetables, on the other hand, are telling a different story—one of volatility. Prices for cucumbers surged 28.4% in March, tomatoes 14.3%, lettuce 11.7%. These increases are not about long-term supply constraints. They are about exposure.

Produce is highly sensitive to weather, logistics, and energy. Much of what Canadians consume during the winter months is imported or grown in greenhouses—both of which are energy-intensive. Heating greenhouses, transporting goods over long distances, and managing cold-chain logistics all depend heavily on fuel. When energy prices rise—or even become unpredictable—produce prices respond quickly.


Climate variability is compounding the problem. Unfavourable growing conditions in key producing regions, whether in the United States or Mexico, can disrupt supply overnight. Unlike meat, where production cycles are long, produce markets adjust rapidly—and often sharply.

What’s unusual right now is that both categories are rising at the same time.

Typically, consumers can offset increases in one category with stability in another. But when proteins remain structurally expensive and produce becomes highly volatile, there are fewer places to turn. This is what makes the current moment particularly challenging for households.

And there is another layer to consider: energy.

Energy costs increased in March, and that matters more than most realize. Food prices don’t react instantly to energy shocks—they absorb them over time. Transportation costs adjust first, followed by production and processing. The full impact can take months to appear at retail.

Which means the increases we are seeing now in meat and vegetables may only be the beginning.

This is why the 4.4% grocery inflation rate should not be dismissed. It is not just a number—it is a signal. A signal that underlying cost pressures are still working their way through the system. A signal that volatility is becoming a defining feature of the food economy.

The narrative that food inflation is easing is, at best, incomplete. Yes, the overall rate has moderated. But the categories that matter most to consumers—the staples, the essentials—are still rising, driven by forces that are neither temporary nor easily reversed.

Canadians are not just dealing with inflation. They are adjusting to a new reality—one where meat remains expensive, vegetables swing unpredictably, and the cost of feeding a household is shaped as much by global energy markets as it is by what’s on the shelf.

Groceries are not getting cheaper. They’re getting more complicated.

More from Retail Insider:
Popeyes sets sail with ONE PIECE with an anime-inspired menu

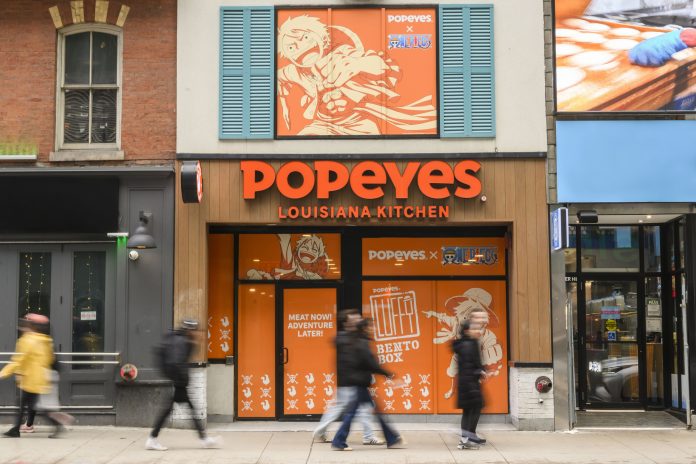
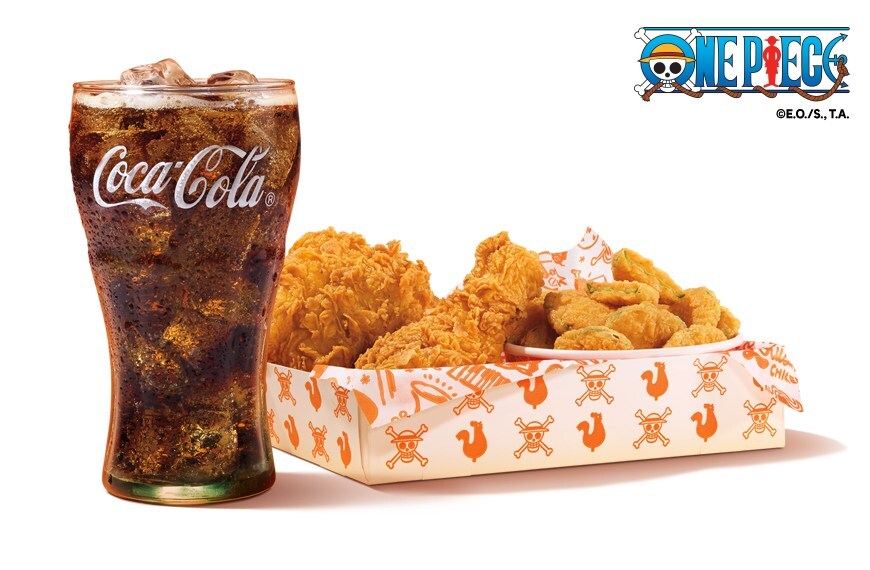
Popeyes® Sets Sail with ONE PIECE with an Epic Anime-Inspired Menu (CNW Group/Popeyes Louisiana Kitchen, Inc.)

Popeyes says it is bringing the spirit of adventure to Canadian fans with the launch of its first anime collaboration Popeyes x ONE PIECE in partnership with the legendary studio Toei Animation.

A celebration of the global hit series and pop culture phenomenon ONE PIECE, Popeyes x ONE PIECE launched recently with a limited-time menu, transforming the epic world of ONE PIECE into a craveable dining experience sure to satisfy any anime or Popeyes fan, said the brand.

“At Popeyes, we’re always looking for bold ways to show up for our fans,” said Matt Harper, Sr. Director of Marketing, Popeyes Canada. “Partnering with Toei Animation lets us tap into ONE PIECE, a global phenomenon that shares our passion, energy and sense of adventure. We’ve brought together the iconic world of this beloved series with the unmistakable flavour of Popeyes to create a limited-time experience that fans across Canada won’t want to miss.”

Matt Harper
Matt Harper

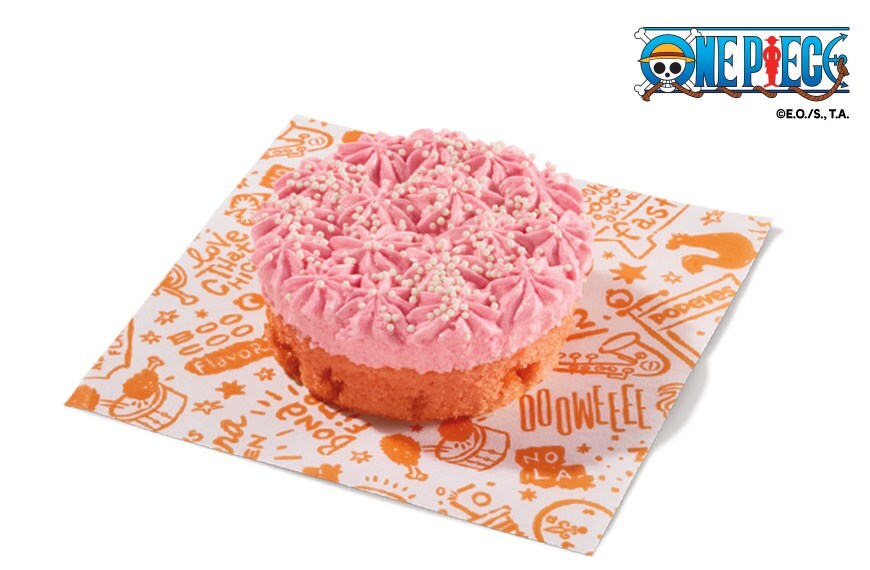
The Popeyes x ONE PIECE menu includes Choppers Cupcake ($4) and The Luffy Bento Bundle ($9.99), featuring:

  • Two pieces of Popeyes iconic Signature Chicken
  • Crispy, golden-brown fried pickles battered in signature seasoning
  • Choice of a fountain drink 

For fans looking to experience the collaboration beyond the menu, the Popeyes restaurant located at 273 Yonge St. in Toronto has been transformed into an immersive experience featuring iconic ONE PIECE moments you won’t want to miss, available until April 27, said Popeyes.

The Popeyes x ONE PIECE menu is only available for a limited time, at select restaurants across Canada.


The Luffy Bento Bundle (CNW Group/Popeyes Louisiana Kitchen, Inc.)

Founded in New Orleans in 1972, Popeyes has become one of the world’s largest chicken quick service restaurants with over 4,000 restaurants in the U.S. and around the world.

“Based on the globally beloved and best-selling manga of all time created by Eiichiro Oda and brought to life by Toei Animation, the iconic ONE PIECE episodic series follows pirate Monkey D. Luffy and his Straw Hat Crew on their epic quest to find the “One Piece,” the legendary treasure of Gol D. Roger, former King of the Pirates. Now over 25 years since the episodic series’ Japanese TV debut in 1999, ONE PIECE has taken its place in mainstream pop culture as one of the most successful and enduring anime franchises of all time, attracting millions of fans of all ages around the world. Today, the franchise currently spans 15 feature films, multiple video games, a trading card game and an ever-growing catalog of licensed merchandise and location-based entertainment,” explained the brand.

Based in Los Angeles, Toei Animation Inc. manages the distribution of Toei Animation’s top properties, including franchise series Dragon Ball, Sailor Moon, ONE PIECE, Digimon, Saint Seiya and many others, to North America, Latin America, South Africa, Australia and New Zealand. Toei Animation’s Los Angeles office also oversees all categories of consumer product licensing based on its film and television brands within these territories.

Chopper’s Cupcake (CNW Group/Popeyes Louisiana Kitchen, Inc.)

More from Retail Insider:
Daily Synopsis: Apr 20, 2026

Retail Insider’s latest articles are listed below, followed by Canadian Retail News From Around the Web. Highlights include cautious Canadian consumer spending plans amid inflation pressures and economic uncertainty, as a Bank of Canada survey shows. Lululemon is expanding in Mexico with both stores and e-commerce, signalling strong confidence in the market. Meanwhile, Canadian shopping centres see increased sales concentration in top malls, reshaping the retail real estate landscape. Together, these stories underscore shifting consumer behaviour and evolving growth strategies across North America.


🗞️ The Day’s Retail Insider Article List


🌐 Canadian Retail News From Around the Web

Consumer spending plans remain muted: Bank of Canada

Vitaly Gariev photo
Vitaly Gariev photo

In the first quarter of 2026, before the war in the Middle East, consumers’ spending plans remained muted, held back by concerns about high prices and economic uncertainty. Still, consumers became less negative about their spending plans than in the previous quarter as downward pressure from trade tensions eased, according to the latest Canadian Survey of Consumer Expectations released Monday by the Bank of Canada.

“Consumers continued to view the labour market as soft, with fears of losing their job still elevated. This quarter, concerns about job losses increased among workers in sectors where artificial intelligence poses a higher risk of task replacement,” said the Bank of Canada.

“Before the war in the Middle East, near‑term inflation expectations were largely unchanged and still above the survey’s historical average. Expectations of strong food price inflation remain an important driver of high one‑year‑ahead inflation expectations. Long‑term inflation expectations declined slightly from 12 months ago.

“Results of a special survey conducted after the outbreak of the war in the Middle East suggest most households expect the war to weaken the Canadian economy and raise prices.”

In its Business Outlook Survey, which was also released Monday, the Bank of Canada said survey evidence, gathered mostly before the war in the Middle East, shows that business sentiment improved slightly from last quarter to levels similar to those from before the trade conflict with the United States began.

“Firms expect improvements in sales growth. Fewer firms than last quarter reported that trade tensions are impacting their sales outlook, while more said public spending is supporting sales. Investment intentions improved, and hiring intentions have recovered from weak levels. This reflects improving domestic demand and a lessening of the effects of uncertainty. Nevertheless, some firms reported that trade tensions are dampening their plans to invest,” said the Bank of Canada.

“Businesses expect average-sized increases in input and selling prices. Survey results from before the start of the war in the Middle East indicate that firms largely expect stable price growth over the next 12 months. Firms’ one-year-ahead inflation expectations have ticked up slightly, driven by the views of those surveyed in March after the outbreak of war in the Middle East. However, expectations at all horizons remain below the peak reached during the height of the trade conflict in early 2025.

“Results of follow-up calls suggest that many firms are already facing higher input costs due to rising prices for energy, fertilizer and freight linked to the war in the Middle East. Others expect increases in the coming months as these costs are passed on by suppliers. Most firms’ outlooks for sales, investment and employment are roughly unchanged.”

More from Retail Insider:
Lululemon Pushes Into Mexico With Stores, E-Commerce

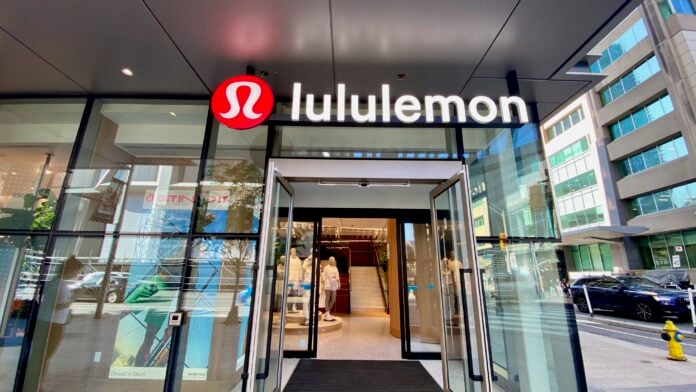
Entrance doors to Lululemon at Yonge and Bloor in Toronto. Photo: Craig Patterson

Lululemon is accelerating its expansion into Mexico with a dual-track strategy that combines a newly launched e-commerce platform with a significant increase in physical store openings.

The company has introduced lululemon.mx, giving customers across Mexico access to its full assortment of technical apparel, footwear, and accessories. At the same time, lululemon is expanding its store network in the country, underscoring a coordinated push to scale both digital and brick-and-mortar operations in the market.


The launch of lululemon.mx marks a key milestone in the brand’s efforts to build a fully integrated omnichannel presence in Mexico. The platform enables nationwide access to the brand’s product assortment, supporting markets where physical locations are still limited while complementing existing and future stores.

“Across our North America business, we are continuing to strategically invest in the growth and evolution of our omnichannel guest experience through a combination of new and elevated stores and enhanced digital capabilities,” said Carla Anderson, Senior Vice President and General Manager, North America, lululemon. “The launch of lululemon.mx, alongside our planned store expansion in Mexico, highlights an exciting next chapter in our North America growth journey. The momentum we are driving in Mexico reflects the strength and relevance of our brand within the community and signals the continued opportunity ahead as we build connected, engaging, and consistent experiences for our guests.”

The synchronized rollout of digital and physical infrastructure signals that Mexico is no longer a secondary market, but a central component of lululemon’s North American growth strategy.


Store Expansion Signals Long-Term Commitment

As part of its fiscal 2026 plans, lululemon expects to open approximately 15 stores across North America, including eight new locations in Mexico. By the end of the fiscal year, the company anticipates operating more than 30 stores in the country.

This level of expansion represents a meaningful allocation of new store growth to Mexico, indicating confidence in the market’s long-term potential. The strategy builds on the brand’s earlier presence in key urban centres and extends its reach into additional regions.

By pairing store openings with a national e-commerce platform, lululemon is effectively building a scalable retail ecosystem that supports both immediate access and future physical expansion.

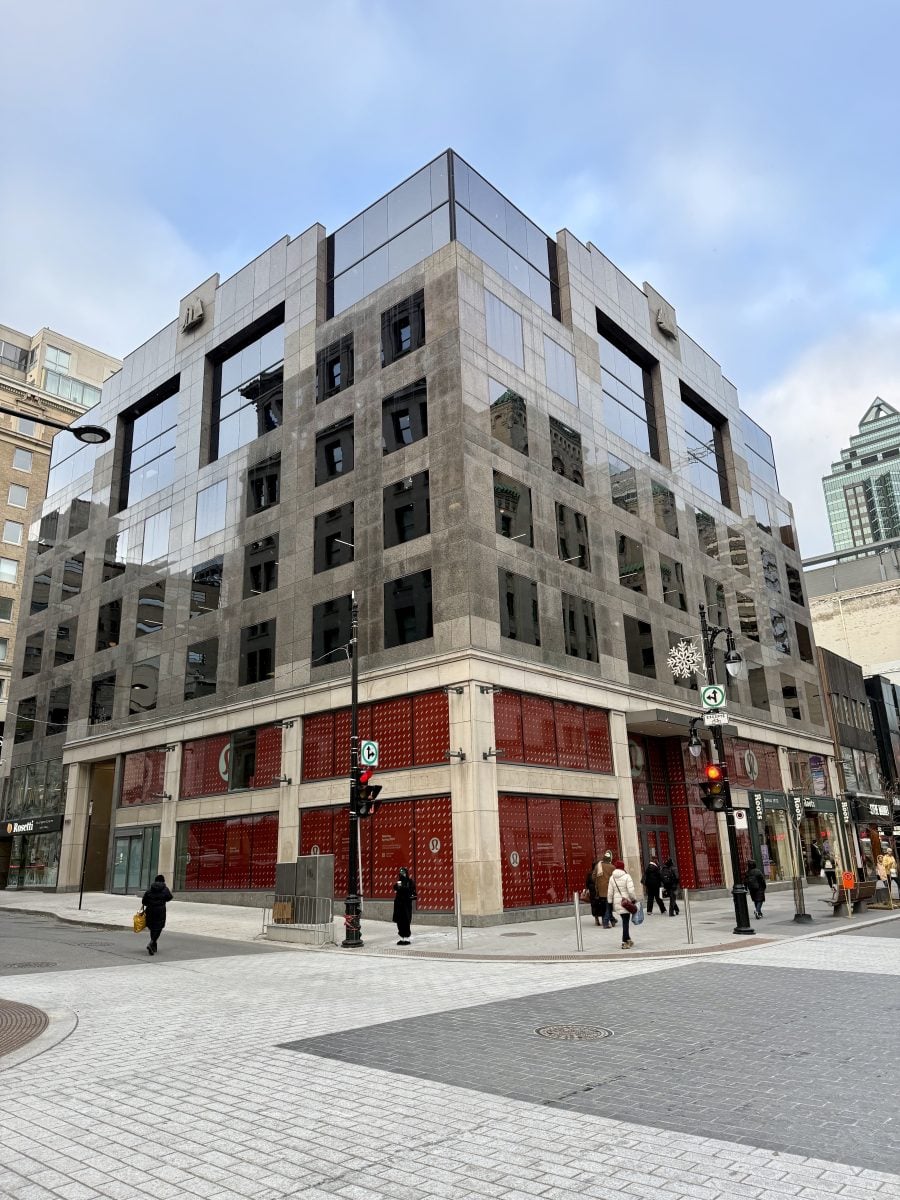
Future Lululemon store at 1035 Ste-Catherine St. W. in Montreal. Photo: Retail Insider

Community-Led Approach Builds Market Presence

In parallel with its retail expansion, lululemon continues to invest in community-driven initiatives to strengthen brand awareness and engagement in Mexico.

The company recently hosted the lululemon 10K CDMX 2026 race, which attracted nearly 8,000 participants and reinforced its connection to the local running community. Earlier in the year, lululemon also brought together more than 100 Mexico-based ambassadors for a multi-day summit.

These initiatives reflect the brand’s established approach of building local communities through experiential activations and ambassador networks, supporting both customer acquisition and long-term loyalty.

Mexico Emerges as a Core Growth Market

The Lululemon Mexico expansion comes at a time when the company is increasingly looking beyond more mature markets such as Canada and the United States for growth.

Mexico is now positioned as a key driver within the company’s North American portfolio, supported by rising consumer interest in wellness and premium athletic apparel. The combination of direct-to-consumer digital access and an expanding physical footprint allows lululemon to capture demand across a broader geographic base.

More from Retail Insider:
Bento Launches Scallop Sushi Lineup Nationwide

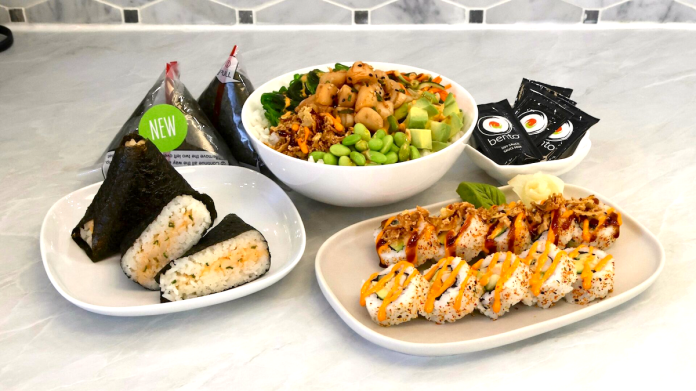
Photo: Bento Sushi

Toronto-based Bento Sushi is expanding the boundaries of convenience food with the launch of Canada’s first grab-and-go scallop sushi lineup, now available nationwide across major grocery retailers. The move brings a traditionally premium seafood ingredient into a category built on speed, accessibility, and operational efficiency, reflecting a notable evolution in Canada’s prepared food landscape.

The new offering is being rolled out across banners including Loblaw Companies Limited, Metro Inc., and Sobeys, along with additional partners such as Longo’s, Real Canadian Superstore, and Calgary Co-op. Pricing ranges from $11 to $16 depending on region and product format, positioning the lineup firmly within the premium tier of grab-and-go meals.


Elevating the Grab-and-Go Category

The introduction of a grab-and-go scallop sushi lineup marks a strategic shift in a category that has traditionally prioritized value and speed over premium ingredients. Scallops, typically associated with fine dining, are now being integrated into everyday retail environments, offering consumers a more elevated meal option without sacrificing convenience.

“This is a meaningful step forward in how we think about innovation in a category where consumers are constantly looking for new, fresh ideas,” said Dave Jones, President and CEO of Bento. “Today’s consumers want quality, variety, and a sense of discovery. Bringing scallops into this space allows us to deliver something that feels both elevated and effortless.”

From a retail perspective, the move signals growing competition within prepared foods, where differentiation through menu innovation is becoming increasingly important to drive both traffic and basket size. As grocery retailers continue to invest in in-store food experiences, premiumization is emerging as a key lever for growth.


Product Lineup Targets High-Protein Demand

The new assortment is designed to align with consumer demand for high-protein, restaurant-quality meals that fit into busy lifestyles. Each product features fully cooked scallops and is prepared fresh daily by sushi chefs using responsibly sourced seafood.

The lineup includes scallop-based rolls, onigiri, and poke bowls, formats that are already familiar to consumers but now enhanced with a higher-end ingredient. The result is a blend of indulgence and accessibility, offering a differentiated option within the grab-and-go set.

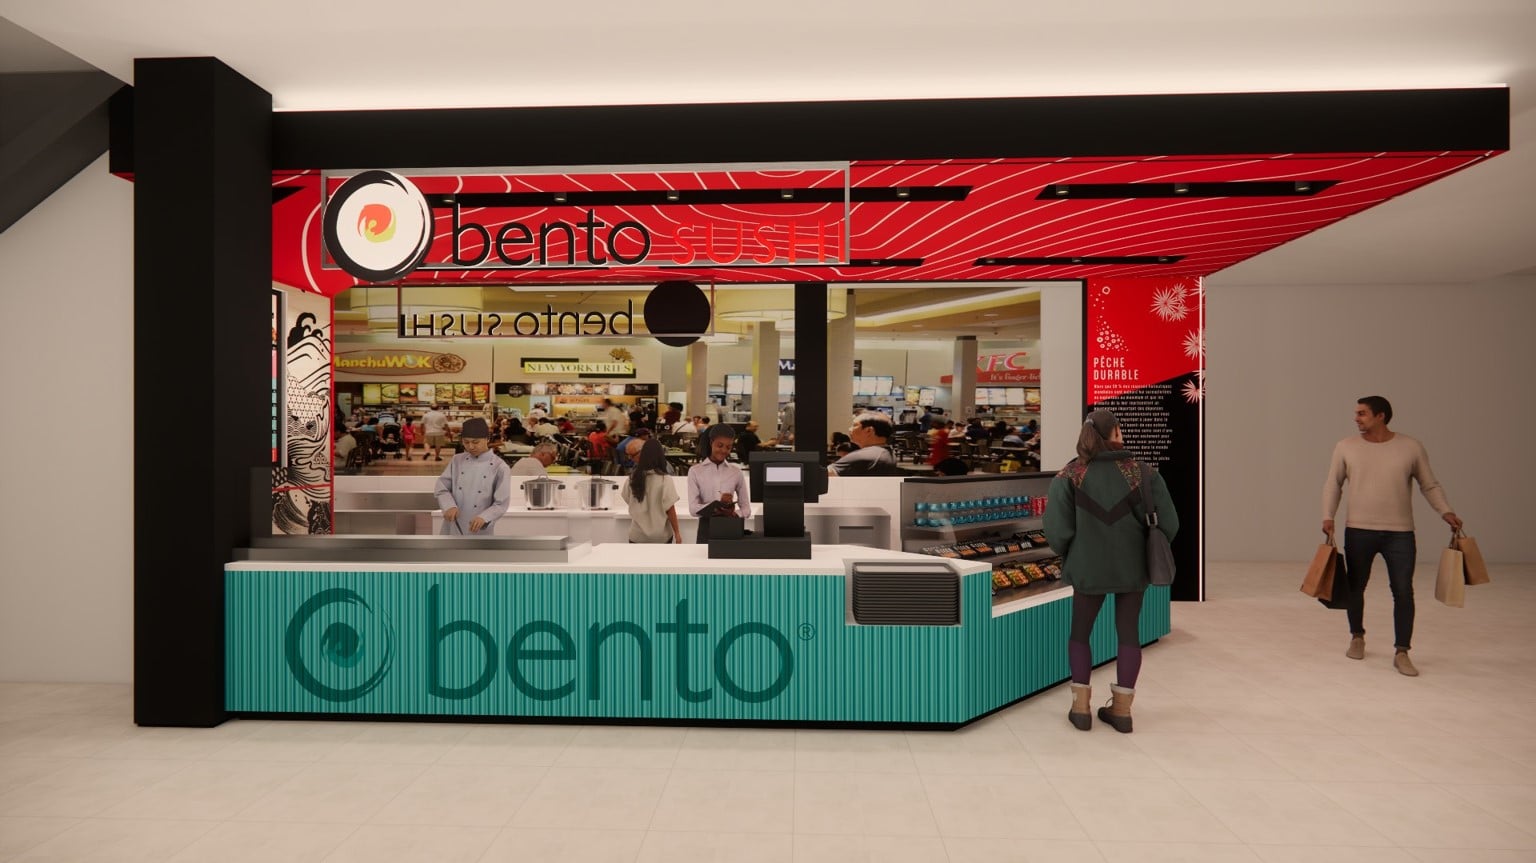
Rendering of the updated Bento Brave in St. Bruno, Quebec. Image: Bento Brave

National Rollout Across Multiple Channels

Bento’s grab-and-go scallop sushi lineup is available immediately across its extensive retail network, which includes more than 950 locations across North America. In addition to grocery kiosks, the company operates in shopping centres, transit hubs, universities, and healthcare environments, giving it broad reach across multiple consumer touchpoints.

The company also plans to extend the offering into foodservice and higher education locations in the coming months, further expanding distribution as demand evolves. This multi-channel approach reflects Bento’s “hub and spoke” operational model, which combines in-store preparation with centralized production and distribution.

Growth Strategy Supported by Brand Evolution

The launch comes amid a broader transformation for Bento, following the introduction of its “Bento Brave” branding initiative in late 2025. The rebrand aims to reposition sushi as an everyday meal option, supported by a more vibrant and accessible visual identity developed in partnership with Jump Branding & Design and Dialogue 38.

Founded in 1996 in Toronto, Bento has grown into Canada’s largest sushi company and the second largest in North America, serving more than 34 million portions annually. The business operates under the Wonderfield Group umbrella, following its acquisition by Yo! Sushi in 2017.

More from Retail Insider:
Consumer Price Index accelerates in March: Statistics Canada

Gustavo Fring photo
Gustavo Fring photo

The Consumer Price Index (CPI) increased 2.4% year over year in March, up from an increase of 1.8% in February, according to a report released Monday by Statistics Canada.

Driving faster price growth in headline inflation were higher prices for energy, especially gasoline, due to the conflict in the Middle East. Excluding gasoline, the CPI rose at a slower pace year over year in March (+2.2%) compared with February (+2.4%), said the federal agency.

There remained lingering base-year effects from the GST/HST break which ran from December 2024 to February 2025, resulting in downward pressure on headline inflation in March 2026, it said.

The CPI was up 0.9% month over month in March. On a seasonally adjusted monthly basis, the CPI increased 0.5%.

“Energy prices rose 3.9% on a year-over-year basis in March, after decreasing 9.3% in February. On a monthly basis, energy prices rose 13.1% in March, said the report.

“Higher prices for gasoline were the primary driver of the year-over-year acceleration in the CPI, as consumers paid 5.9% more for gasoline in March than they did in the same month the previous year. Prices surged 21.2% on a monthly basis, the largest price increase for gasoline on record, due to the supply shock resulting from the conflict in the Middle East. However, this monthly effect was muted on a year-over-year basis due to the comparison with prices from March 2025, which included the since-removed consumer carbon levy. The removal of the consumer carbon levy will no longer impact the 12-month movement as of April 2026, and this will be reflected in next month’s CPI release.”

Helena Lopes
Helena Lopes

Statistics Canada said prices for food purchased from stores rose 4.4% on a yearly basis in March, after increasing 4.1% in February.

On a year-over-year basis, prices for fresh vegetables increased 7.8% in March, the largest increase since August 2023 (+8.7%), after rising 0.5% in February. Cucumbers, peppers and celery all had notable price growth in March, due in part to tighter supplies related to adverse growing conditions in producing countries, it said.

“Prices for food purchased from restaurants continued to grow year over year at a slower pace. After increasing 7.8% in February, prices rose 3.2% in March due to a base-year effect,” said Statistics Canada.

“Slower growth for alcoholic beverages purchased from stores (+2.0%) and toys, games (excluding video games) and hobby supplies (+1.5%) also contributed to the downward pressure in March.”

Andrew Grantham
Andrew Grantham

Andrew Grantham, Senior Economist, CIBC Capital Markets, said: “Looking forward, a further rise in gasoline prices will see headline inflation jump to around 3% next month, before hopefully easing back slightly in May, partly due to the temporary suspension of the federal fuel excise tax (worth about -0.2%-pts to headline inflation for May). Pass-through from higher energy prices into core measures of inflation may become more evident closer to the summer months, particularly as higher air fares are picked up more fully, but slack within the Canadian economy should prevent those measures from reaccelerating too much, enabling the Bank of Canada to remain on the sidelines through 2026.”

Douglas Porter
Douglas Porter

Doug Porter, Chief Economist, BMO Capital Markets, said: “It could have been worse. Much as other major economies posted a significant pop in headline inflation, the record rise in gasoline prices lifted Canada’s inflation rate significantly last month. However, the picture for underlying inflation was a bit better than expected, and continues the recent pattern of steadily moderating core inflation trends. Our considered view is that if it were not for the conflict with Iran, the discussion would currently be revolving around the strong possibility of BoC rate cuts, not hikes. This report reinforces that opinion.”

Leslie Preston
Leslie Preston

Leslie Preston, Senior Economist, TD, said: “As expected, higher oil prices boosted Canadian inflation in March. Oil prices have fallen in recent days but remain nearly 40% higher than a year ago. That means energy prices are likely to keep headline inflation elevated for some time. April’s inflation reading is likely to head much higher as the dampening effect of the removal of the consumer carbon levy falls out of the year-on-year inflation calculation.

“Given a generally soft economic backdrop in Canada, we expect the effect on core prices should be more modest. Core inflation is expected to stay reasonably close to the 2% target on a year-on-year basis this year. The Bank of Canada is widely expected to leave its key policy rate unchanged at 2.25% at next week’s announcement. We will be listening closely for the Bank’s assessment of the impact of the spike in oil prices on Canada’s economy.”

More from Retail Insider:
How Canadian Shopping Centre Performance Has Changed Since Pre-COVID

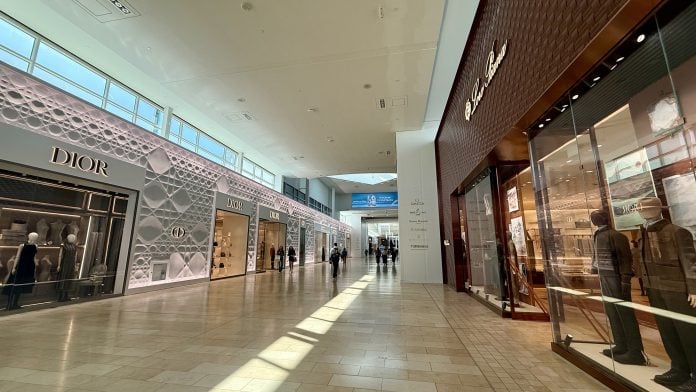
New luxury wing at Toronto's Yorkdale Shopping Centre. Photo: Craig Patterson

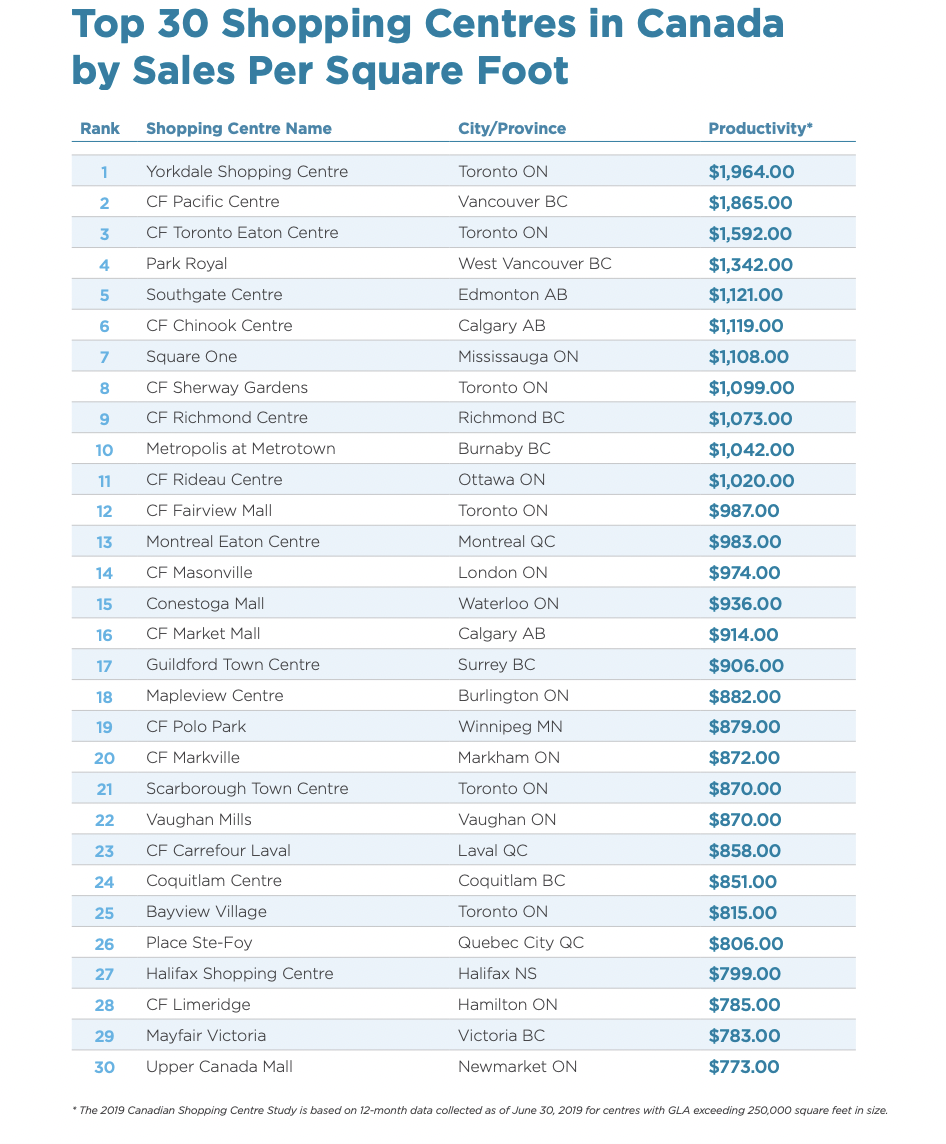
New data on Canadian shopping centre sales per square foot from ICSC provides a clear view of how the retail landscape has evolved since before the COVID-19 pandemic. When compared to Retail Insider’s 2019 study, conducted in partnership with the Retail Council of Canada, the latest figures point to a structural shift rather than a simple recovery.

The data suggests that Canadian retail has not declined in the years since 2019. Instead, it has reorganized, with performance becoming increasingly concentrated among a smaller group of dominant shopping centres.

Top-Tier Centres Have Strengthened Their Lead

At the top of the market, leading shopping centres have not only recovered from pandemic disruption but have extended their advantage. Yorkdale Shopping Centre recorded sales of $1,964 per square foot in 2019, rising to $2,368 by 2025.

This increase highlights the growing strength of Canada’s most productive retail assets. Centres such as CF Toronto Eaton Centre have also posted gains over the period, moving from $1,592 per square foot in 2019 to $1,642 in 2025.

While not all top-tier centres have seen uninterrupted growth, their overall position within the market has strengthened. These properties continue to attract premium tenants, international brands, and strong consumer traffic, reinforcing their role as dominant retail destinations.

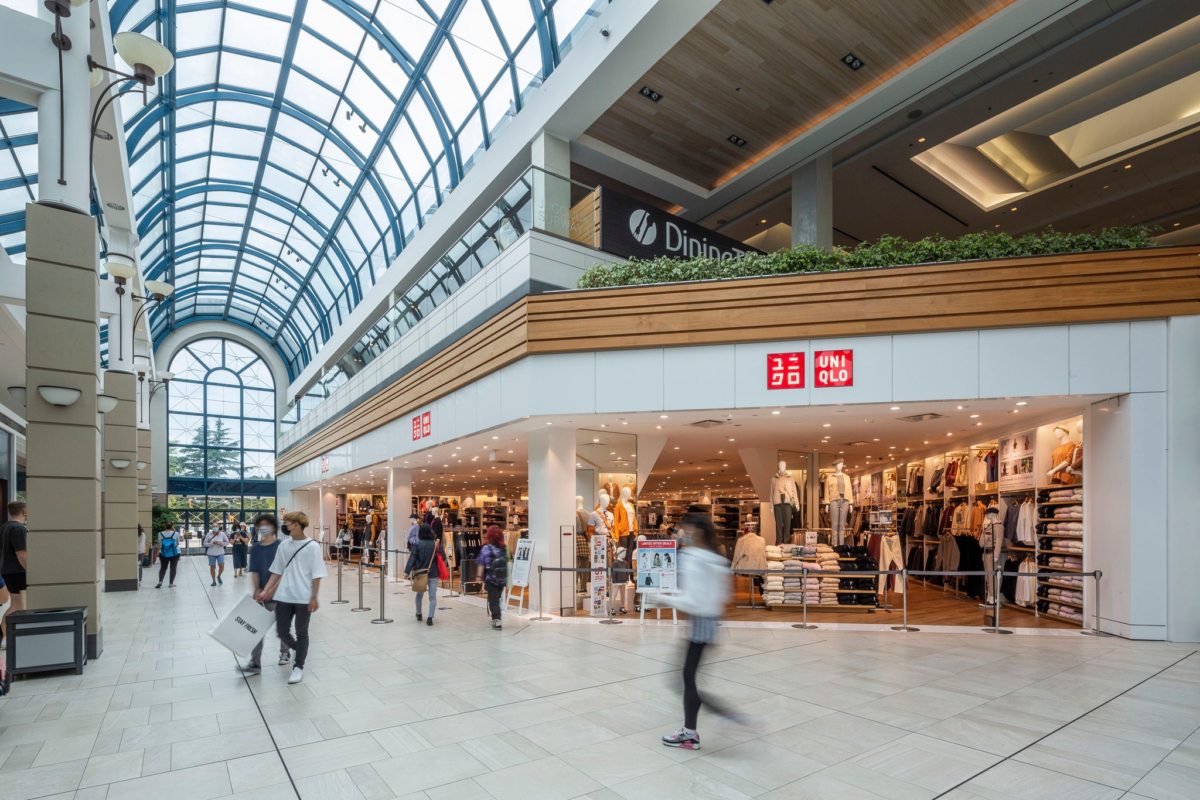
CF Richmond Centre in Richmond, British Columbia. Uniqlo store in photo. Photo: Cadillac Fairview

The Middle of the Market Has Shifted

In 2019, a large number of Canadian shopping centres clustered in the $800 to $1,000 per square foot range. At the time, this was widely considered a solid level of performance for enclosed malls.

2019 Retail Insider/Retail Council of Canada Shopping Centre Study report numbers. Click image for full study PDF

By 2025, that same range represents a different position within the market. While many centres still operate within this band, it now sits further from the top tier, which has moved significantly higher.

This shift reflects a broader change in how retail performance is distributed. What was once considered strong performance is now more reflective of mid-tier positioning, particularly in major urban markets.

The $1,000 Benchmark Has Been Redefined

The evolving role of the $1,000 per square foot threshold illustrates the extent of this transformation. In 2019, exceeding $1,000 per square foot placed a shopping centre firmly among the country’s stronger performers.

Today, that threshold has become closer to a baseline for relevance in competitive markets. A growing number of top-tier centres now operate well above $1,300 per square foot, with the highest-performing assets significantly exceeding that level.

This change underscores how retail productivity has become more concentrated in fewer, higher-performing locations.

Urban Dominance Has Intensified

The data also reinforces the continued strength of major urban markets, particularly Toronto and Vancouver. Centres in these regions dominated the rankings in 2019 and continue to do so today, often with even stronger relative performance.

At the same time, certain high-performing centres that were included in the 2019 study are not captured in more recent datasets. Properties such as Park Royal ranked among the country’s top-performing shopping centres in 2019 and are widely understood to remain highly productive.

This suggests that the true upper tier of Canadian retail may be even stronger than current rankings alone indicate.

CF Richmond Centre, October 2020. Photo: Ritchie Po

COVID-19 Accelerated Structural Change

The gap between 2019 and 2023 reflects a period of unprecedented disruption. Retail Insider’s historical study was paused in 2020 as lockdowns forced widespread shopping centre closures. These closures varied significantly by region, making direct comparisons during that period unreliable.

As a result, the post-2023 data provides a clearer view of stabilized performance. When viewed alongside 2019 figures, it becomes evident that the pandemic did not fundamentally weaken Canadian shopping centres. Instead, it accelerated existing trends.

Retailers have become more selective in their physical store strategies, focusing on fewer, higher-performing locations. Consumers, in turn, are increasingly gravitating toward dominant shopping destinations that offer a stronger mix of retail, dining, and experiences.

A More Concentrated and Competitive Future

Taken together, the comparison between 2019 and 2025 highlights a retail landscape that is more concentrated and more competitive than it was before the pandemic.

Top-tier shopping centres have strengthened their positions and continue to attract investment and premium tenants. Meanwhile, mid-tier and lower-performing assets face increasing pressure to adapt through redevelopment, repositioning, or diversification.

The data suggests that Canadian retail has not declined. Instead, it has reorganized around performance, with a growing emphasis on productivity, tenant quality, and overall experience.

As this evolution continues, the gap between leading and mid-tier shopping centres is likely to widen further, reshaping the structure of the country’s retail real estate sector in the years ahead.

More from Retail Insider: