While the broader economy continues to face headwinds, the restaurant industry under Jody Palubiski’s leadership is heating up.
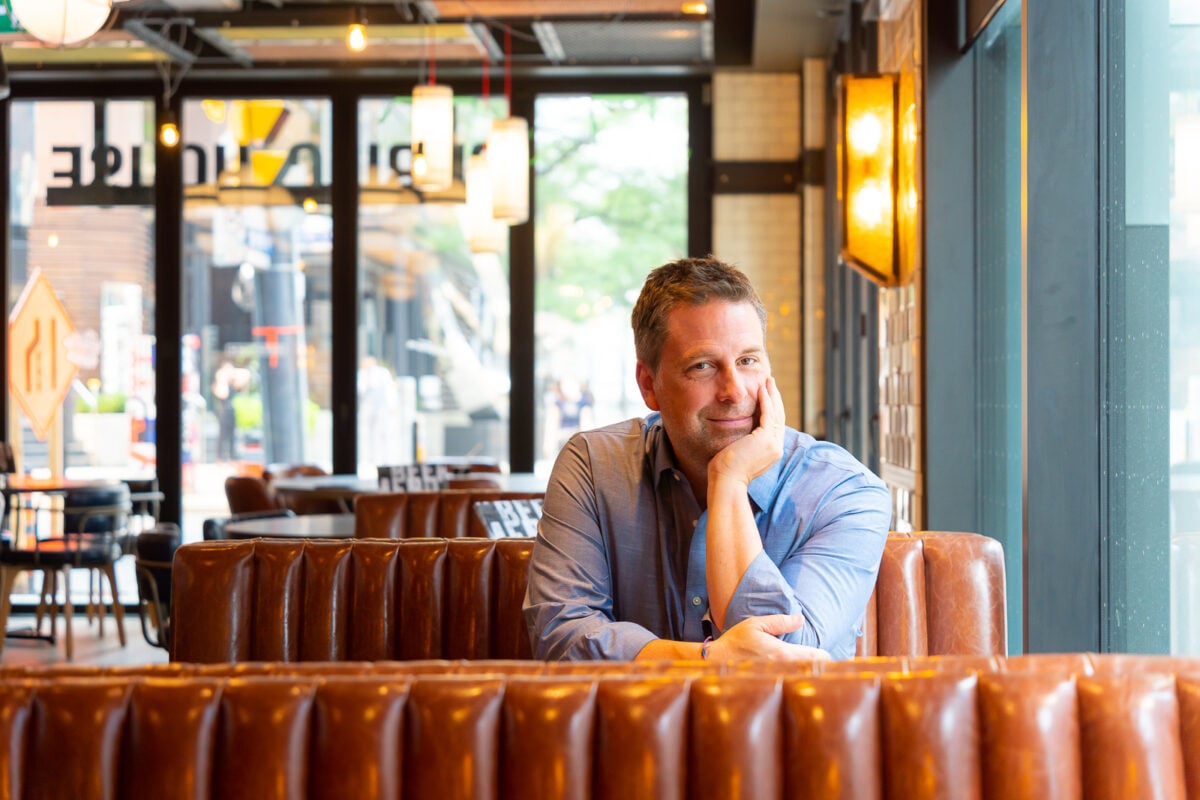
Jody Palubiski. Photo credit: Charcoal Group
Palubiski, CEO of the Charcoal Group, oversees 18 restaurants across Southern Ontario, including the iconic Charcoal Steakhouse in Kitchener, which has been in operation since 1955. “That’s still in constant operation and it does very well — having its best year ever,” he says.
Despite economic uncertainty, rising costs of living, and changing consumer habits, Palubiski says the restaurant group is growing. “We’re still exceeding last year and feel optimistic. We’ve currently just signed off on four more leases and have three in discussion for the next two and a half years.”
He acknowledges broader challenges in the industry: “There’s a lot of uncertainty in the marketplace – a lot of noise in the media,” which he believes contributes to “some lack of consumer optimism.” Yet, restaurants, he says, continue to resonate with people.
“We’re in an industry that people love, that people aspire to. Everybody who’s ever worked in it has dreamed about owning their own place,” says Palubiski. He adds that while some chains are growing and others are pulling back, “it gets down to operation, style of restaurant, but also very largely geography and locations and all the old stuff that we’ve always looked at.”
Photo credit: Charcoal Group
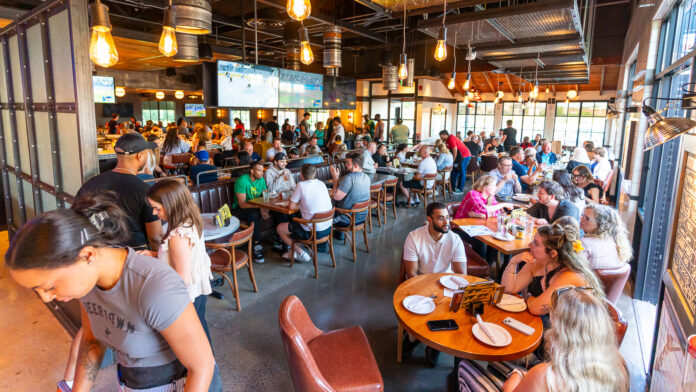
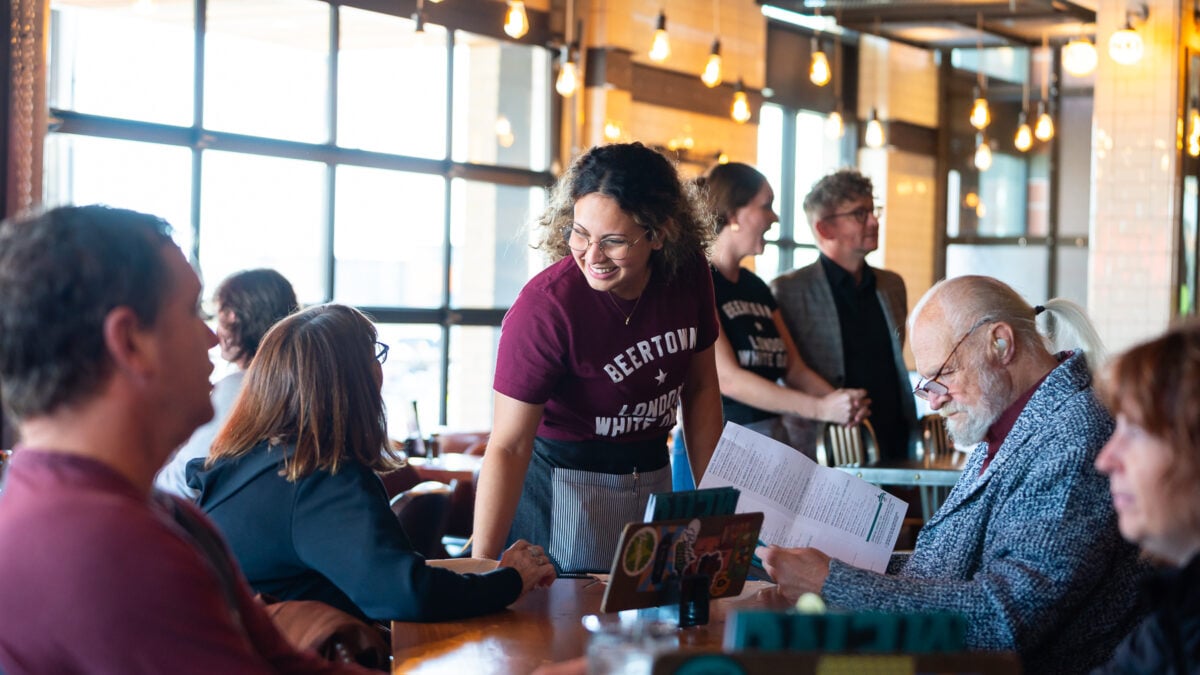
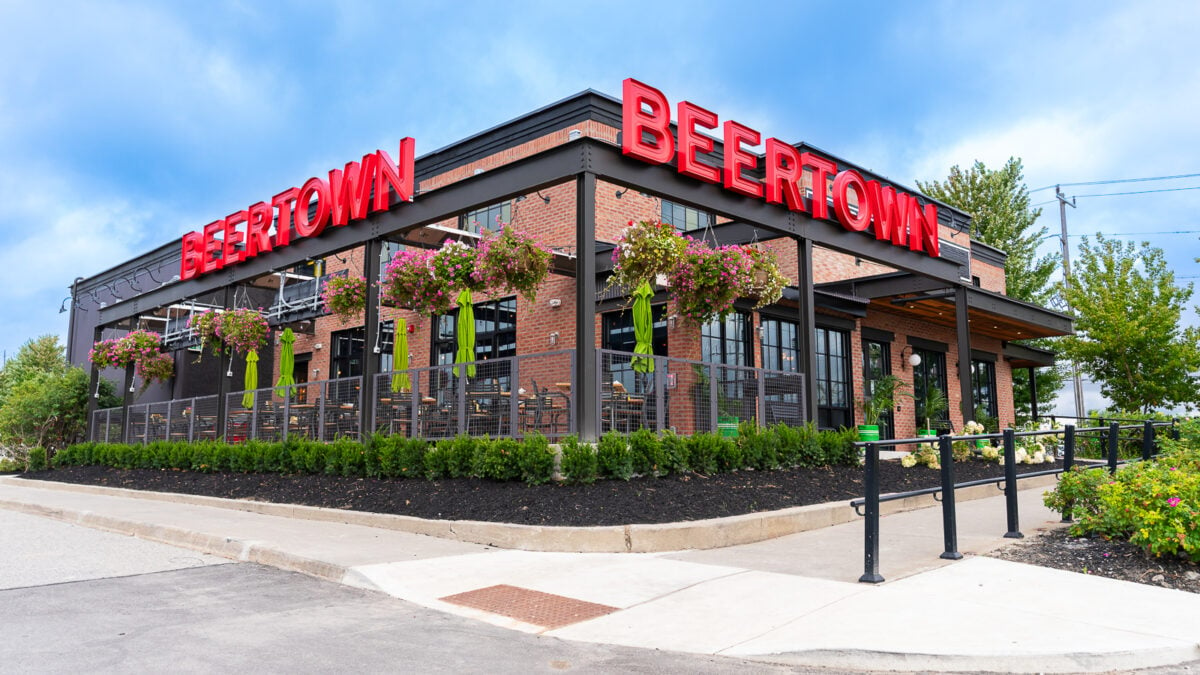
The Charcoal Group has recently expanded with new Beertown locations in London and Whitby. When asked about the labour market, Palubiski says, “We’re tremendously fortunate. We are fully staffed from a culinary standpoint, from a front of the house management standpoint, from an hourly standpoint. We’re actually finding it to be a really positive job market right now.”
Attracting and retaining talent, he emphasizes, is a strategic priority. “The main thing you have to do is retain good people, create an ecosystem or an environment that can benefit everybody within it. If you do that, not only do you retain people, but word of mouth and willingness to refer their friends becomes far easier.”
Palubiski also takes a deeply personal perspective on what working in hospitality offers, particularly to young people starting their careers. “I’m a father of four. Over the years, I look at it through the eyes of my experience and as the experience of an employer, having kids enter the workforce and looking at it through their eyes as well as the eyes of a parent.”
He says the industry provides critical life skills: “Learning employability skills, being on time, looking sharp, having a winning mindset. How to be a positive team member. How to communicate effectively. That’s a great piece.”
He adds, “I want my staff to be able to greet people, look them in the eye, confidently say, ‘How are you this evening? Thank you for joining us at Beertown.’”
Photo credit: Charcoal Group
Confidence, communication, teamwork, leadership, and resilience are all traits Palubiski believes the restaurant environment can build. “We can work in a high-pressure environment and at the end of the day, come out of it, have a successful shift, high five each other — to know that you worked through pressure and came up the other side in a really positive way helps build resilience.”
And for restaurants, getting staffing right is non-negotiable. “You have to get it right,” he says. “There has to be a continued focus on attracting, onboarding, training, and positively managing the very best people in the industry and building superior teams. That’s how you do well in our industry. It is the hospitality industry, and so hospitality has to be the leading factor in those things.”
April’s retail sales data brought a wave of optimism for Canadian retailers, with overall sales up 6.1% YOY. Even discretionary spending—a category often sensitive to economic uncertainty—showed a healthy 4.2% YOY growth.
The strong retail performance in April can be attributed to a mix of strategic marketing and opportunistic shopping. A growing sense of national pride seems to be influencing buying behavior, as “Made in Canada” and “Canada-Owned” labels are becoming a focal point for both retailers and consumers. Many stores are actively promoting Canadian-made products, and this push appears to resonate with shoppers eager to support local businesses.
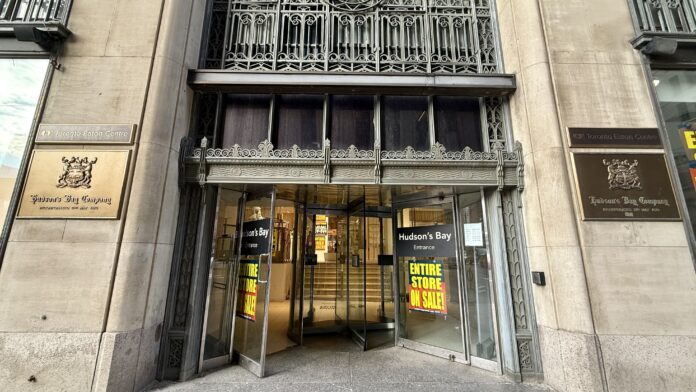
Additionally, the liquidation sales at Hudson’s Bay played a surprising role in driving foot traffic to shopping centres. While customers initially flocked to capitalize on discounts at Hudson’s Bay, many likely extended their visits to other retailers in the same malls. This spillover effect underscores the importance of physical retail spaces in creating opportunities for incidental purchases, even in a predominantly digital shopping era.
Not all retail categories shared in April’s success. Convenience Store sales fell -0.8% YOY, continuing a troubling trend—down nearly -5% YTD. This decline reflects deeper structural challenges within the sector.
One major issue is the overreliance on alcohol sales, which often takes up valuable shelf space that could be used for more diverse or innovative product offerings. Compounding this, further competition from pharmacy (e.g., Shoppers Drug Mart, Rexall, etc.), dollar stores, and even grocery, are encroaching on convenience stores’ territory, offering similar products—often with a stronger focus on health and wellness.
The consumer shift toward healthier lifestyles is especially problematic for traditional convenience stores, which remain rooted in their legacy of chips, candy, and sugary drinks. Without adapting to these changing preferences, convenience stores risk falling further behind in a market that increasingly values fresh, nutritious, and functional products.
The health and wellness sector continues to thrive, reshaping consumer behavior across multiple retail categories. For instance, Health and Personal Care Stores saw sales grow 7.8% YOY in April, extending a years-long trend that began during the pandemic. Consumers are clearly prioritizing self-care, with demand surging for vitamins, supplements, skincare, and other health-focused products.
Interestingly, while Beer, Wine, and Liquor Stores posted a modest 2.6% YOY increase in April, their YTD growth is just 0.7%, reflecting the longer-term decline. Many Canadians continue to be cutting back on alcohol consumption, aligning with broader health trends.
Meanwhile, cannabis retailers are flourishing, with sales up an impressive 13.7% YOY. Cannabis is increasingly viewed as a healthier alternative to alcohol in certain formats, making it a strong contender in the evolving health-conscious landscape. This shift is forcing traditional alcohol retailers to rethink their strategies to stay relevant in a market that is clearly moving toward wellness-focused alternatives.
With these impressive April retail sales results, JCWG has been thinking about:
Will an increased focus on purchasing Made in Canada products become a long term change in Canadian consumer habits?
Where will we see spikes in retail sales as Canadians travel nationally throughout the summer to keep their dollars at home?
Will the exit of Hudson’s Bay have a major effect on foot traffic to shopping centres?
How are YOU changing your merchandise planning to include more Canadian products?
Retail Sales by Product Category, Same Month Comparison
Sales for the Month of April
Apr-25
Apr-24
YOY
All Stores
70,720,899
66,646,053
6.11%
Motor Vehicle and Parts Dealers
22,204,318
19,714,570
12.63%
Gasoline Stations
5,824,240
6,320,283
-7.85%
All Stores Less Automotive
42,692,341
40,611,200
5.12%
Food and Beverage Stores
12,695,431
12,010,605
5.70%
Supermarkets and Other Grocery Stores*
9,148,749
8,660,083
5.64%
Convenience Stores
684,612
689,913
-0.77%
Specialty Food Stores
956,603
803,862
19.00%
Beer, Wine and Liquor Stores
1,905,468
1,856,747
2.62%
Health and Personal Care Stores
5,995,590
5,562,931
7.78%
All Stores Less Automotive, Food, and Pharmacies
24,001,320
23,037,664
4.18%
General Merchandise Stores
9,249,352
8,886,442
4.08%
Furniture, Home Furnishings, Electronic and Appliance Stores
3,520,621
3,414,294
3.11%
Furniture Stores
1,152,928
1,131,960
1.85%
Home Furnishings Stores
720,740
696,799
3.44%
Electronics and Appliance Stores
1,646,954
1,585,536
3.87%
Clothing and Accessories Stores
3,465,717
3,213,088
7.86%
Clothing Stores
2,684,964
2,481,128
8.22%
Shoe Stores
391,371
393,625
-0.57%
Jewellery, Luggage and Leather Goods Stores
389,381
338,335
15.09%
Sporting Goods, Hobby, Book and Music Stores
3,795,606
3,512,839
8.05%
Building Material and Garden Equipment
3,970,024
4,011,001
-1.02%
Miscellaneous Store Retailers
2,544,049
2,260,660
12.54%
Cannabis Retailers
466,698
410,519
13.68%
Retail Sales by Store Category, Year to Date Comparison
Year-to-Date Sales Ending April
Apr-25
Apr-24
YTD
All Stores
254,230,320
242,694,543
4.75%
Motor Vehicle and Parts Dealers
72,775,476
66,890,535
8.80%
Gasoline Stations
23,895,308
24,281,482
-1.59%
All Stores Less Automotive
157,559,536
151,522,526
3.98%
Food and Beverage Stores
49,106,790
47,870,237
2.58%
Supermarkets and Other Grocery Stores*
35,912,207
34,840,385
3.08%
Convenience Stores
2,521,888
2,653,054
-4.94%
Specialty Food Stores
3,399,569
3,151,939
7.86%
Beer, Wine and Liquor Stores
7,273,127
7,224,860
0.67%
Health and Personal Care Stores
23,197,328
21,607,399
7.36%
All Stores Less Automotive, Food, and Pharmacies
85,255,418
82,044,890
3.91%
General Merchandise Stores
33,075,796
31,929,863
3.59%
Furniture, Home Furnishings, Electronic and Appliance Stores
Grocery basket in a grocery store. Image: iStock/licensed
If the world was looking for a distraction from the intensifying trade tensions under Trump 2.0, the U.S.’ direct military action in Iran certainly delivers. But this is no sideshow. The escalation in the Middle East could have immediate and far-reaching consequences, especially for the global agri-food sector—and Canada is not immune.
Geopolitical volatility in the Middle East has historically triggered sharp increases in crude oil prices. Following initial Israel–Iran exchanges in June, oil prices surged over 10%, and the latest attacks suggest more turbulence ahead. Since natural gas is a core input for fertilizer production, any spike in energy markets means higher fertilizer costs. While most Canadian farmers have already secured inputs for this season, unlike the early-2022 Ukraine invasion, cost pressures will be felt later in the supply chain.
But the shutdown of Iran’s urea and ammonia plants could ripple through global fertilizer markets, tightening supply and driving up prices—especially for nitrogen-based fertilizers. Canada, though a fertilizer producer, still relies on global pricing dynamics, and higher costs could significantly impact input expenses for Canadian farmers. This could reduce planting margins for crops like wheat, canola, and corn, potentially leading to lower yields or higher food prices. If South American buyers shift demand to other suppliers like the U.S. or Trinidad, competition for fertilizer could intensify.
The Strait of Hormuz, a strategic chokepoint for one-third of global oil and gas shipments, is now even more vulnerable. Any disruption could delay fertilizer and grain shipments, elevate global logistics costs, and strain the availability of key imports like soybeans and wheat. Global supply chains, already stressed, will feel the pinch.
Currency volatility often follows regional conflict. Emerging market currencies tend to weaken, raising the cost of food and ag inputs in fragile economies. For Canada, the situation is more nuanced. Higher oil prices may support the loonie, but geopolitical instability breeds uncertainty—and markets despise uncertainty. A weaker Canadian dollar could make imported food, from produce to packaged goods, more expensive.
This confluence of factors—rising transport and input costs, potential shipping delays, currency instability—can accelerate food inflation across Canada. Our food supply chain is vast, import-reliant, and highly sensitive to energy costs. Greenhouse operators, Prairie grain growers, and livestock producers could all face margin pressure. Consumers, particularly in lower-income households and in regions like Atlantic Canada or the North, will feel the consequences most acutely.
Beyond economics, Ottawa’s diplomatic playbook will be tested. Sanctions—whether imposed by or against Canada—could further disrupt agri-food trade, as was the case in past global conflicts. Export restrictions, trade policy shifts, and new subsidies may emerge as countries scramble to stabilize domestic markets.
The global food system is deeply interconnected. What happens in the Middle East doesn’t stay there—it sends shockwaves across continents, from farm to fork. This latest escalation is a stark reminder of how vulnerable our food economy remains to geopolitical unrest. Let’s hope policymakers are paying attention—and that they keep food-insecure populations, both here and abroad, top of mind.
Retail Insider is streamlining its Canadian retail news from around the web to include a handful of top news stories that can be viewed quickly during the day. Here are the top stories from the past several days.
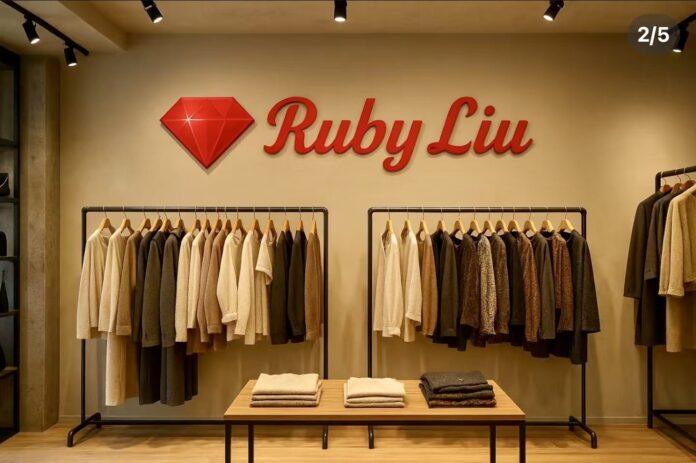
Rendering of a fashion area in the new Ruby Liu department store. Image: Ruby Liu
Entrepreneur and real estate investor Ruby Liu says she’s not giving up — even after a major setback involving her plan to acquire dozens of Hudson’s Bay stores across Canada. A court-appointed monitor has confirmed that landlords representing 23 of 25 store leases have opposed her company’s proposed lease assignments, placing the future of the broader acquisition effort in jeopardy. Despite the rejection, Liu remains firm in her belief that she can help reinvent Canada’s struggling department store sector.
According to the Fifth Report of the Monitor, Alvarez & Marsal Canada Inc., landlords for the majority of the leases included in an Asset Purchase Agreement signed by Ruby Liu Commercial Investment Corp. in May have declined to consent to the lease transfers. These leases span key shopping centres in Ontario, Alberta, and British Columbia and were positioned to form the backbone of Liu’s new department store concept.
Following landlord meetings during the week of June 2, legal representatives for 23 properties wrote to the Monitor or to Hudson’s Bay counsel expressing opposition to the assignments. While the Liu team is continuing to provide further disclosures in hopes of turning the tide, the Monitor noted that the landlords have signaled clear resistance, at least for now.
A Vision That Extends Beyond Profit
Despite the rejections, Liu released a powerful personal statement through her company’s social media channels, defending her decision and doubling down on her long-term vision.
Weihong (Ruby) Liu
“I’m nearing sixty, and once again, I’ve chosen the road few dare to take,” Liu wrote. “Many have questioned my decision. Some say it’s reckless… But I don’t see this as a gamble.”
Liu described her plan not as a commercial play, but as a mission to revitalize Canada’s retail environment — one she views as increasingly disconnected from the communities it once served.
“This isn’t just about capital or profit. It’s about building something meaningful — something vibrant, fresh, and full of life. A place where young people can step out of the digital haze and rediscover genuine human connection.”
Her statement underscores a broader critique of Canadian shopping centres, which she argues have become stale and uninspired. She envisions multi-purpose destinations combining shopping, dining, and cultural experiences — environments that invite people back into physical spaces at a time when much of life has moved online.
Ruby Liu’s Bid for HBC Leases
The transaction at the centre of the current dispute involves 25 Hudson’s Bay store leases that Liu hoped to acquire through a court-approved lease monetization process. While the identities of the specific properties have not been publicly disclosed, the Asset Purchase Agreement was signed in tandem with a separate, more advanced agreement covering three Hudson’s Bay locations in British Columbia: Tsawwassen Mills, Mayfair Shopping Centre in Victoria, and Woodgrove Centre in Nanaimo. Those three leases are already owned by Central Walk — the property group chaired by Liu — and are expected to proceed, with court approval sought on June 23.
The Monitor confirmed that Liu’s $6 million offer for the three BC leases represented the highest value among all bids submitted through the formal lease solicitation process.
Rendering of a Ruby Liu store. Image: Ruby Liu
Limited Bidding and Widespread Lease Disclaimers
The broader Lease Monetization Process, overseen by brokerage firm Oberfeld Snowcap, failed to attract widespread interest. Of 96 Hudson’s Bay and Saks-affiliated stores nationwide, only 12 parties submitted qualified bids covering 39 locations. A full 62 leases received no offers.
To date, 59 leases have been disclaimed, with store closures and property turnover continuing through late June. The Monitor’s filings suggest that, aside from Liu’s three approved leases and one or two additional transactions under negotiation, most of the Hudson’s Bay retail footprint will be relinquished to landlords.
Liquidation Generates Strong Returns, Employees Receive Support at Court Appoints Counsel
The company’s store liquidation, completed on June 1, generated over $509.9 million in gross receipts. This included $349.3 million in owned merchandise sales, $104 million in consignment sales, $43.9 million in additional goods, and $12.7 million in FF&E sales. While merchandise performance exceeded expectations, FF&E returns fell short, and cleanout work remains ongoing in several locations.
The Court has formally appointed Ursel Phillips Fellows Hopkinson LLP as Employee Representative Counsel, with over 14,500 active and former workers now represented. Only 68 opted out. The Court has also issued a WEPPA Declaration Order, clearing the way for unpaid wage and severance claims to be filed with Service Canada.
A seven-member employee committee has also been constituted to provide input and direction to counsel as the restructuring proceeds.
Corporate Name Change on the Horizon Following Canadian Tire Deal
The Court previously approved the sale of Hudson’s Bay’s intellectual property to Canadian Tire Corporation, with a closing date expected on June 24, 2025. As part of the agreement, Hudson’s Bay entities will be required to formally change their corporate names to avoid brand confusion. Articles of amendment will be filed following transaction completion.
Cash Flow Stronger Than Forecast
From May 3 to June 13, the company reported net positive cash flow of $54.8 million, with a closing balance of $131.9 million, far exceeding the forecasted $82.5 million. This was attributed to higher liquidation sales and delayed disbursements. The company also made significant payments to its ABL and FILO lenders during the period.
Liu’s Resolve: “What I Fear Most Is Never Having Tried”
Liu’s statement ends not with defiance, but with a quiet confidence rooted in resilience. She reflects on her immigrant journey, her contributions to Canada, and her belief in creating a new future rather than waiting for permission to join the old one.
“My life has always been a battle. I’m not afraid to lose. What I fear most is never having tried,” she wrote. “So I choose to keep going. To stay bold. To keep moving forward with conviction.”
Liu acknowledges that she may never be accepted by what she calls the “mainstream,” but she sees that as an invitation to create a new one — one that reflects the diversity, courage, and creativity of modern Canada.
“I’m not here to defeat anyone. I’m here to build something better.”
With court hearings scheduled for June 23, the next chapter of Ruby Liu’s retail endeavour will soon unfold. For now, her words — and her refusal to walk away — offer a clear message: this fight is far from over.
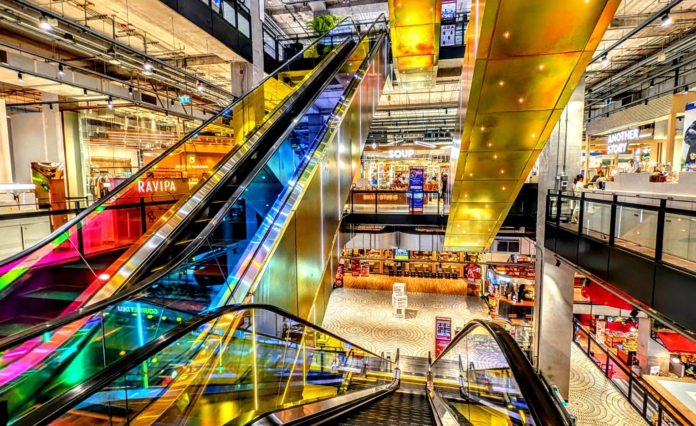
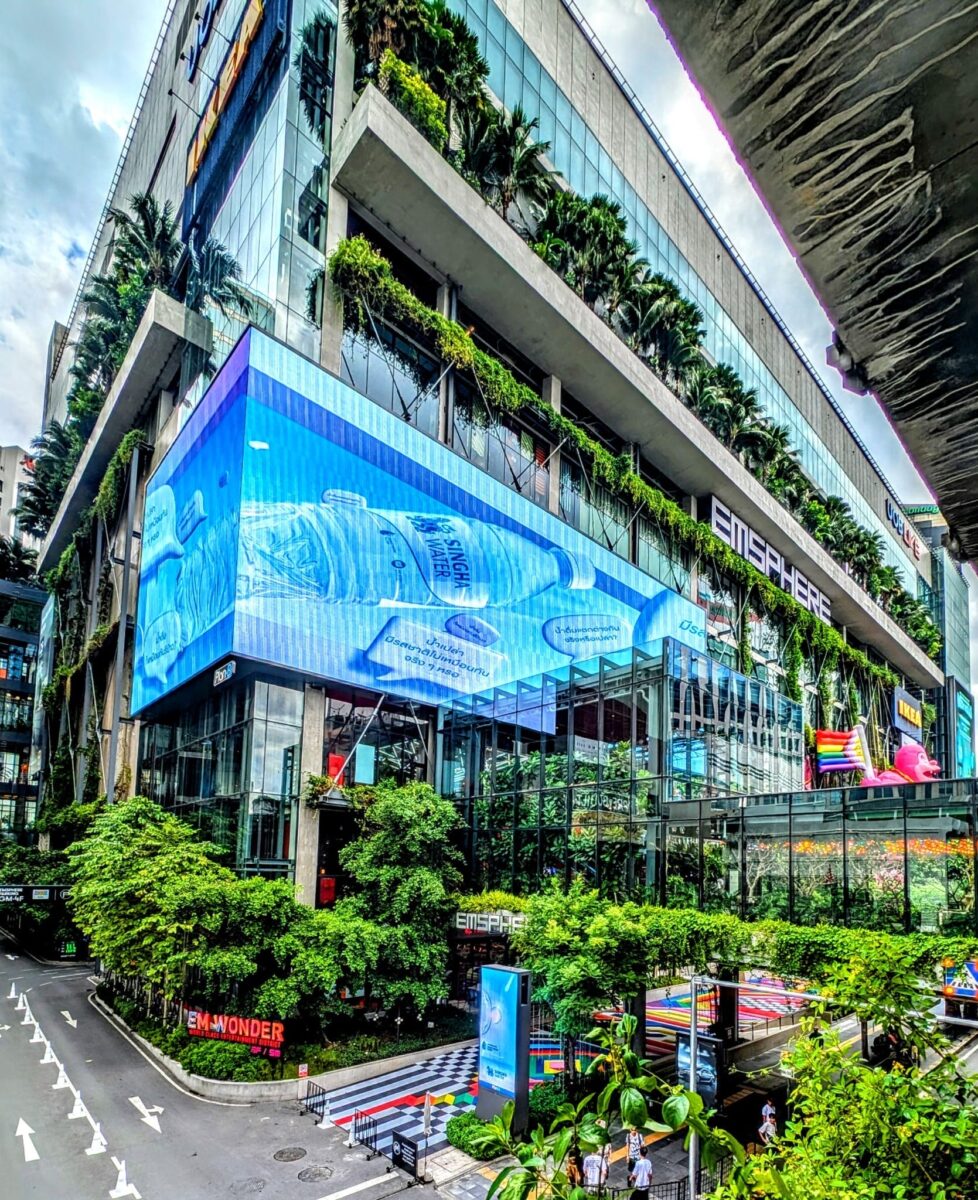
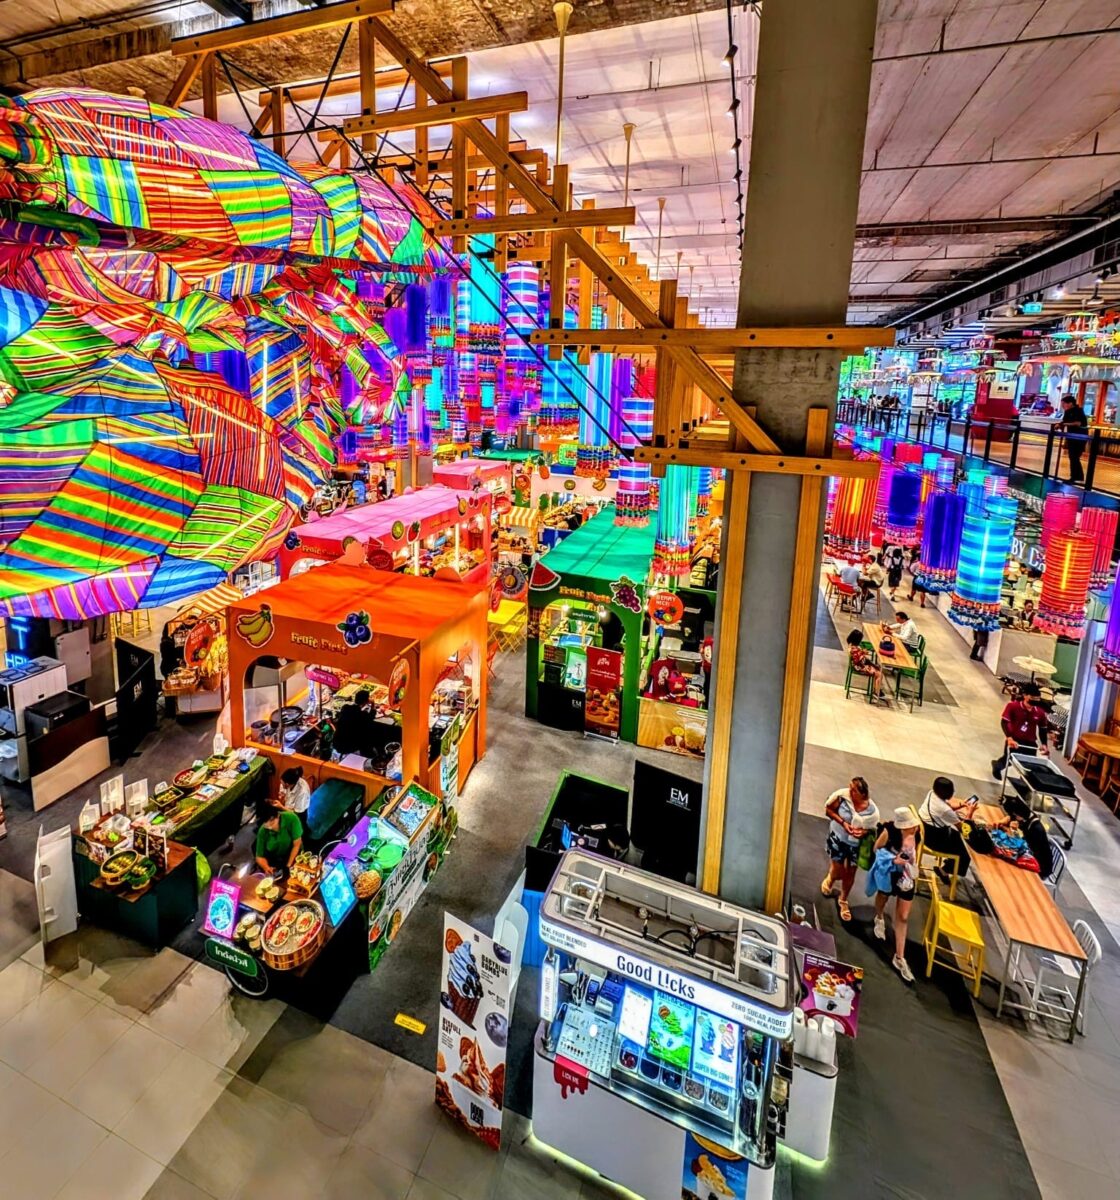
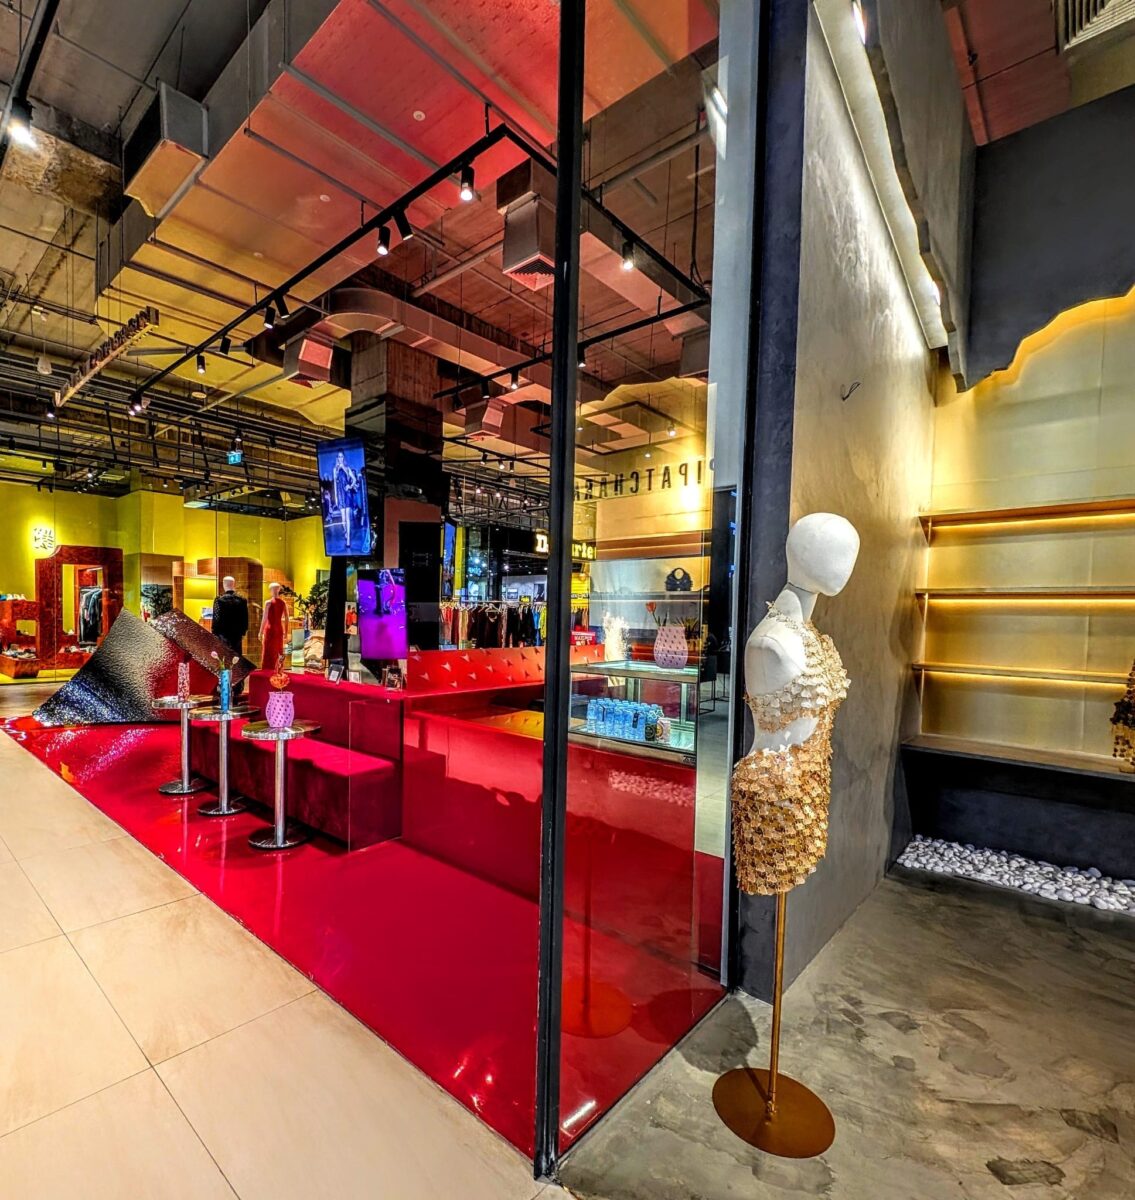
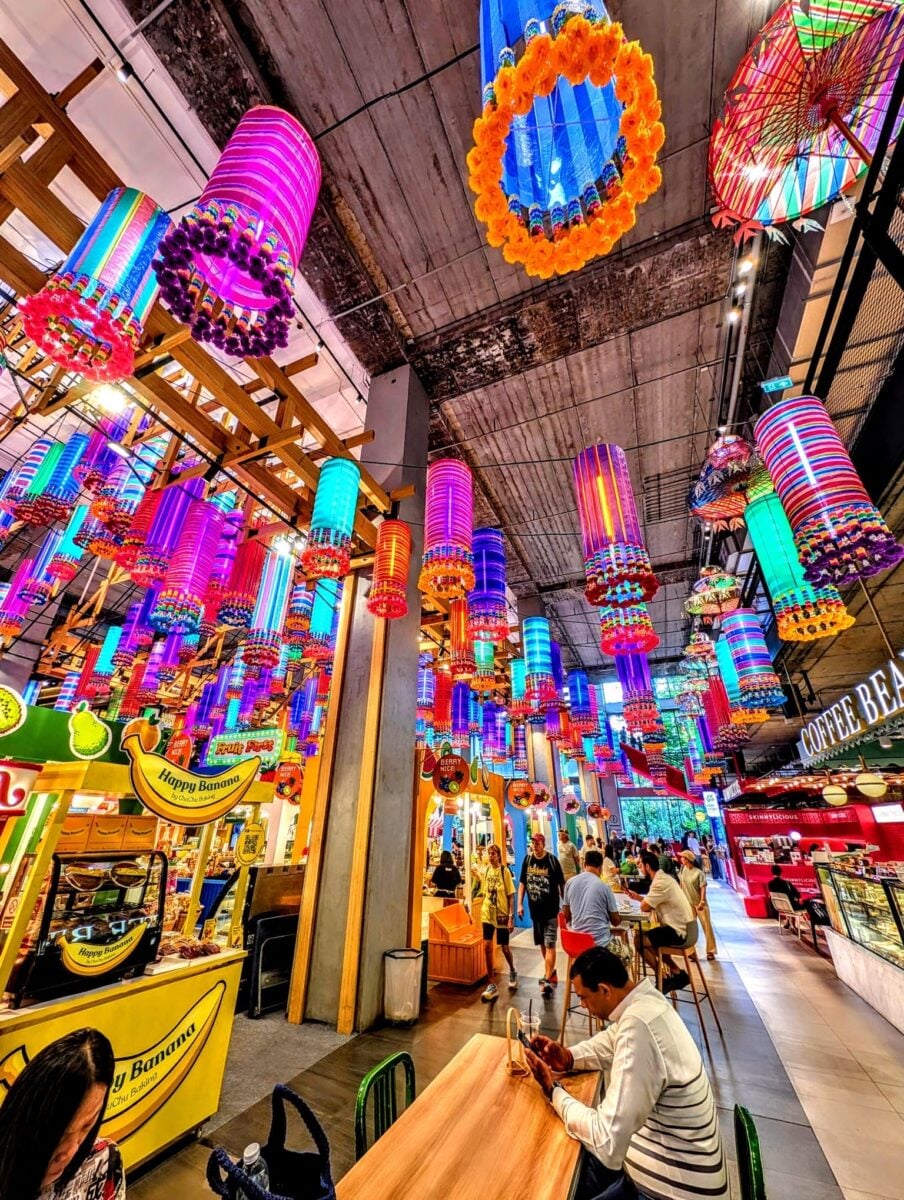
Emsphere in Bangkok, Thailand, June 2025. Photo: Carl Boutet
Weihong (Ruby) Liu, the billionaire real estate investor and owner of Central Walk, is poised to become one of the most influential figures in Canadian retail with her bold plan to launch a new department store chain—potentially the first time in modern retail history that a single entrepreneur has launched such a concept at scale, from the ground up.
As the Hudson’s Bay Company (HBC) exits the traditional department store market, Liu has stepped in with offers to acquire leases at up to 28 locations across Ontario, Alberta, and British Columbia.
Among them are three properties she already owns—Woodgrove Centre in Nanaimo, Mayfair Shopping Centre in Victoria, and Tsawwassen Mills, where she placed a $6 million bid for the leases.
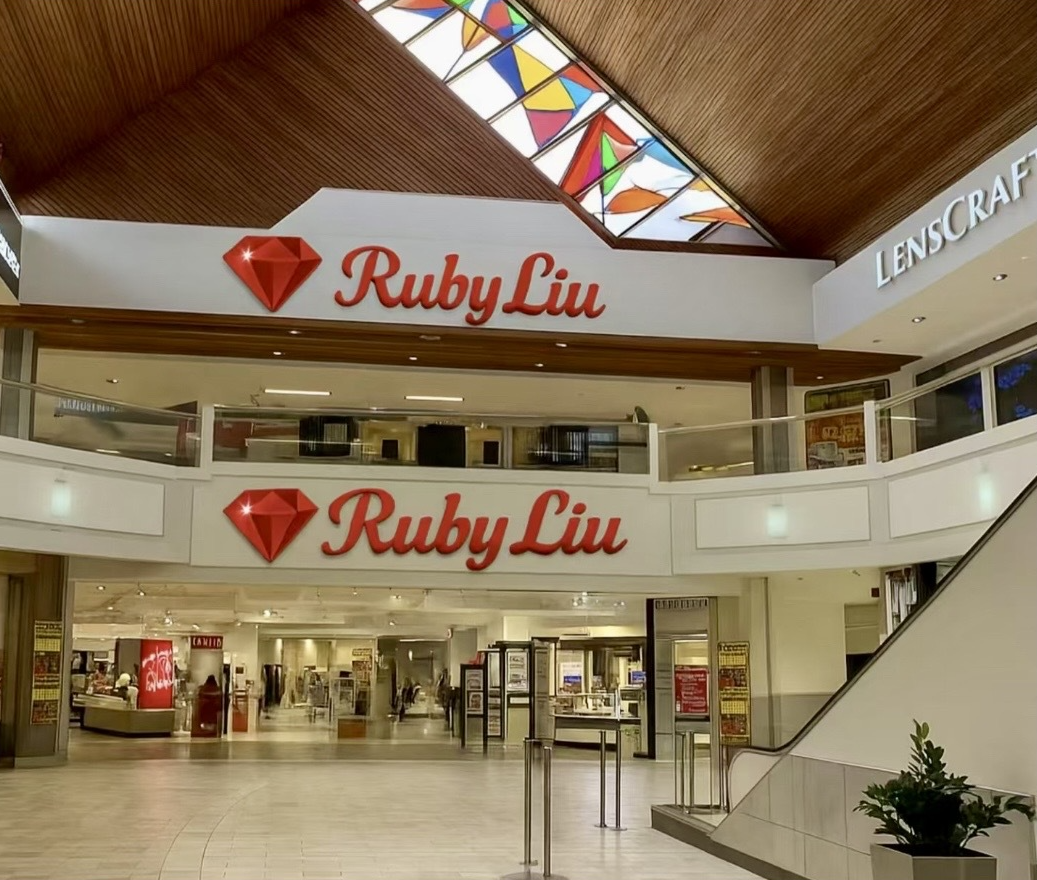
The new concept will bear her own name: Ruby Liu. “This is not about saving an old brand,” Liu told Retail Insider in a recent interview in Mandarin. “It’s about creating something completely new—something exciting, inclusive, and alive.”
Redefining the Department Store
Retail strategist Carl Boutet, who has closely followed Liu’s movements and visited cutting-edge malls in Asia that have inspired her, says Liu’s concept represents a seismic shift in how we think about department stores.
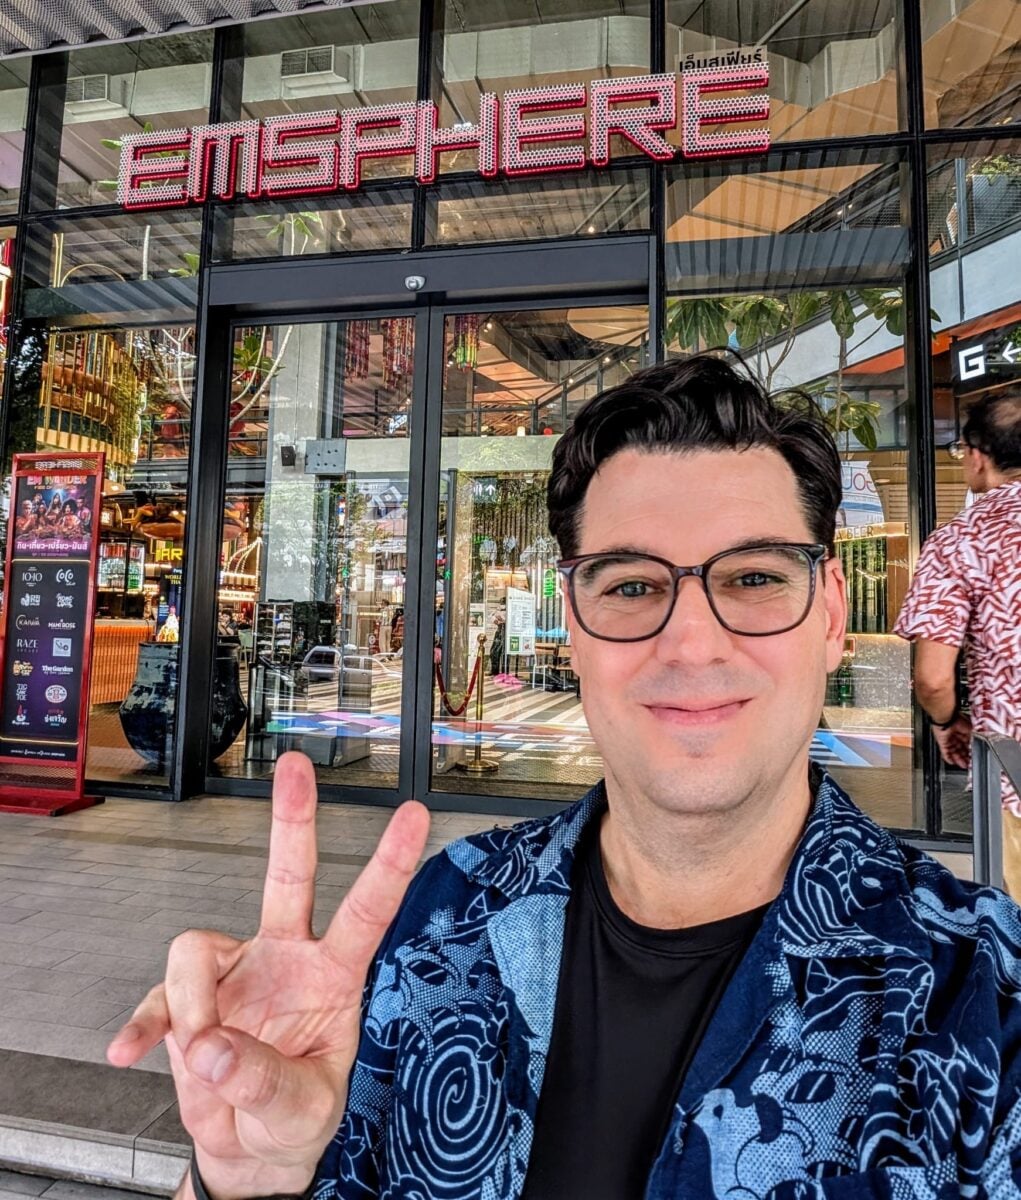
Carl Boutet at Emsphere in Bangkok, Thailand, June 2025. Photo: Carl Boutet
“We need to reset our minds on what the term ‘department store’ even means,” said Boutet in an interview. “It’s no longer about a sea of product. It’s about a sea of experiences, with retail as part of a broader, curated lifestyle offering.”
Boutet says Liu’s stores will offer much more than merchandise. “Think children’s play zones, Asian supermarkets, buzzing food courts, live performances, pet grooming, jewellery repair—you name it. She’s curating energy, not just selling stuff.”
From HBC’s Collapse, a New Vision Emerges
Hudson’s Bay filed for creditor protection in March 2025, setting off a race among landlords, investors, and competitors to scoop up valuable real estate. While Canadian Tire Corporation purchased the HBC brand and IP for $30 million, Liu quietly pursued the physical leases, focusing on malls she believed had untapped potential.
In May, Liu submitted a formal bid for 28 leases, including her three Central Walk properties. She committed $6 million on her owned properties and made a further $9.4 million in deposits for the others.
Court approval is expected on June 23, at which point Liu will take possession of the three HBC-owned stores at her malls. Renovations are set to cost around $30 million for Mayfair and Woodgrove alone, with her broader renovation budget still evolving as negotiations continue.
Emsphere in Bangkok, Thailand, June 2025. Photo: Carl Boutet
Fast Track to Opening
Liu’s team is working toward opening the first Ruby Liu stores by early November, a remarkably tight timeline. Boutet believes this “minimum viable product” strategy will allow Liu to test concepts and build excitement before fully rolling out her flagship experiences.
“She’s likely treating this as an A-B store strategy,” said Boutet. “The ‘A’ locations—like the ones in Central Walk malls—will be heavily invested in and fully built out over time. The ‘B’ stores may open faster with lighter touch renovations, allowing the brand to quickly gain visibility and attract shoppers.”
Inspiration from Asia’s Most Dynamic Malls
While Liu hasn’t revealed every detail of her plan, much of it appears to draw from Asian retail environments, especially high-concept malls in Bangkok, Seoul, and Shenzhen that integrate food, fashion, entertainment, and digital experiences under one roof.
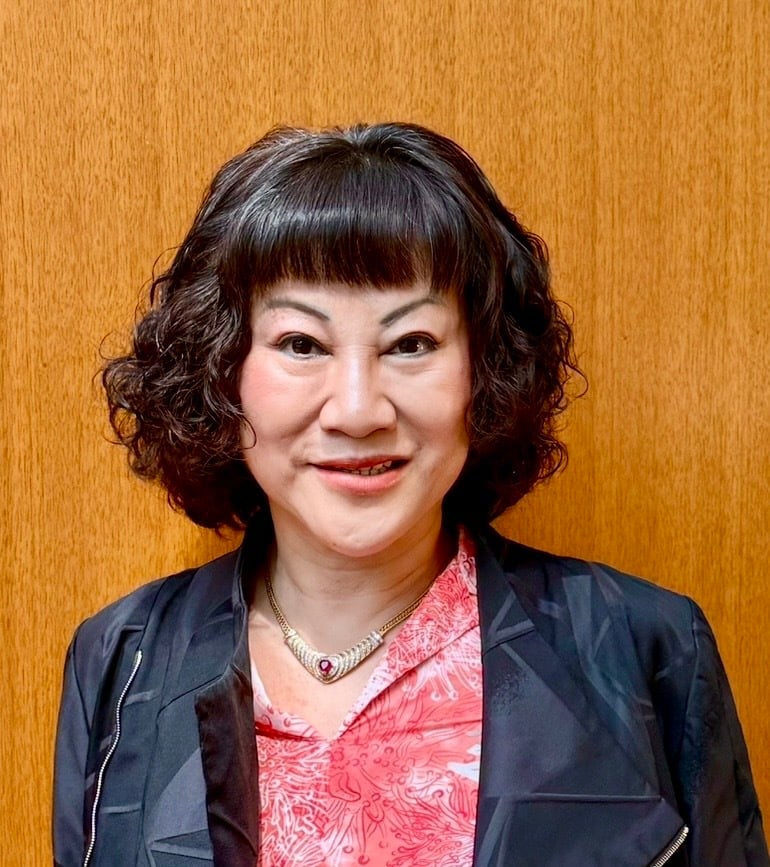
Weihong (Ruby) Liu. Photo: Craig Patterson
Boutet, who recently visited one such mall—Bangkok’s Emsphere—at the request of Liu’s team, said it offered insight into her vision.
“Emsphere has everything: immersive food courts, limited-edition collectibles, automotive showrooms, pop-up art, and even a 6,000-seat concert venue,” said Boutet. “It’s like a retail theme park, and it feels like every floor has a new surprise.”
While the Ruby Liu stores in Canada will be smaller—typically 150,000 square feet—the emphasis on energy, variety, and community engagement is central to her strategy.
Meeting Shoppers Where They Are
Liu has been clear that her stores will be experiential and multicultural. “Hudson’s Bay failed because it didn’t value young people,” she recently told Retail Insider. “It didn’t create spaces for them to gather, and it didn’t invest in the future.”
To counter that, Liu plans to incorporate features like live stages, dynamic food halls, kids’ play areas, and possibly even VR gaming or drone retail zones.
“She’s not building retail boxes. She’s building destinations,” said Boutet. “There’s an entrepreneurial flair to this that you don’t usually see from someone stepping into a retail role for the first time.”
Emsphere in Bangkok, Thailand, June 2025. Photo: Carl Boutet
Landlords: A Mixed Reception
Despite the scale and vision of Liu’s plans, some landlords remain skeptical. Court documents show that several mall owners submitted letters to Hudson’s Bay expressing concern about her bids. Liu herself has said that in at least one meeting, a landlord gave her only five minutes before walking out.
“She’s unconventional,” Boutet said. “She’s not using the traditional playbook. She’s using Gmail accounts for hiring, she’s moving fast, and she’s operating with instinct and agility. That scares some people.”
However, landlords with harder-to-fill locations—or those looking to revitalize tired properties—are showing more enthusiasm.
“Some understand the vision and want to ride the wave,” said Boutet. “Others are more conservative. But the ones who say yes early will benefit most.”
Emsphere in Bangkok, Thailand, June 2025. Photo: Carl Boutet
More Than Just a Storefront
The Ruby Liu model is about building community as much as commerce. Liu has promised to prioritize former Hudson’s Bay employees for hiring and to include HBC suppliers where possible.
“She’s trying to preserve part of Canada’s retail heritage, but in her own way,” said Boutet. “She’s not bringing back The Bay. She’s creating something new.”
While some features—like play zones—may not be profit centres themselves, Boutet argues that they drive the kind of foot traffic that fuels overall sales.
“Retail isn’t just transactional anymore,” he said. “The most successful malls and stores in Asia operate like cultural centres. Ruby’s tapping into that.”
Emsphere in Bangkok, Thailand, June 2025. Photo: Carl Boutet
The Branding Challenge
The name “Ruby Liu” for a department store has raised eyebrows, but Boutet says it may be one of Liu’s smartest moves.
“Branding it with her own name conveys personality and ownership,” he said. Consumers connect with people more than corporations.”
Still, he believes the visual identity will need refinement. “The font, the logo, the brand story—it’s all 1.0 right now,” he added. “There’s room to polish. But the bones are there.”
Liu’s direct engagement with customers—including handing out money at events and meeting shoppers in line—has helped humanize the brand even before stores open.
Rendering of a Ruby Liu store at Coquitlam Centre. Image: Ruby Liu
A National Experiment in Real Time
The success of the Ruby Liu department store chain will depend not just on Liu’s vision, but on collaboration. That includes leasing partners, municipalities, suppliers, and brand operators willing to take a chance.
“Everybody has to take a risk,” said Boutet. “This isn’t a sure thing. But it’s bold. It’s imaginative. And frankly, it’s exciting.”
At a time when many are lamenting the decline of traditional retail, Liu’s plans offer a radical counterpoint—a vision built not on nostalgia, but on reinvention.
“She didn’t have to do this,” Boutet said. “She could have stuck with her three malls and gone golfing at her course. But she sees something here. She believes in it. And she’s putting real money on the table.”
Betting on Ruby
With court approval expected within days and plans already in motion for store launches this fall, the Ruby Liu department store experiment is no longer hypothetical—it’s happening.
If successful, it could mark a turning point in how Canadians shop, socialize, and experience retail. If it fails, it will still be remembered as one of the boldest gambits in Canadian retail history.
“She’s swinging for the fences,” said Boutet. “And win or lose, we need people like her in this industry.”
Retail sales increased 0.3% to $70.1 billion in April. Sales were up in six of nine subsectors and were led by increases at motor vehicle and parts dealers. Core retail sales, which exclude gasoline stations and fuel vendors and motor vehicle and parts dealers, were up 0.1% in April, reported Statistics Canada on Friday.
In volume terms, retail sales increased 0.5% in April.
“Feedback from respondents for April highlighted the effects of trade tensions between Canada and the United States on Canadian retail businesses. According to answers to supplementary questions, 36% of retail businesses were impacted by the trade tensions in April. The most common impacts were price increases, change in demand for product and supply chain disruptions. Despite six of nine subsectors posting monthly gains in retail sales, all nine subsectors saw a negative impact on sales,” said the federal agency.
Photo:
Andrea Piacquadio
The largest increase in retail sales in April was observed at motor vehicle and parts dealers (+1.9%), up for a second consecutive month. The increase was led by higher sales at new car dealers (+2.9%) and used car dealers (+2.1%). The largest decrease in the motor vehicle and parts dealers subsector was in automotive parts, accessories and tire retailers (-4.7%), explained Statistics Canada, adding that sales at gasoline stations and fuel vendors (-2.7%) decreased in April for a second consecutive month. In volume terms, sales at gasoline stations and fuel vendors increased 0.4%.
“Core retail sales edged up 0.1% in April, posting their third consecutive monthly increase. The gain was led by higher sales at sporting goods, hobby, musical instrument, book, and miscellaneous retailers (+1.0%) and furniture, home furnishings, electronics and appliances retailers (+0.8%),” noted Statistics Canada.
“Higher sales were also recorded at food and beverage retailers (+0.2%) in April. The increase in this subsector was led by gains at supermarkets and other grocery retailers (+0.4%).
“The largest decrease to core retail sales in April came from clothing, clothing accessories, shoes, jewelry, luggage and leather goods retailers (-2.2%).”
Photo: RDNE Stock project
On a seasonally adjusted basis, retail e-commerce sales increased 3.6% to $4.4 billion in April, accounting for 6.2% of total retail trade, compared with 6.0% in March, said Statistics Canada.
“Statistics Canada is providing an advance estimate of retail sales, which suggests that sales decreased 1.1% in May. Owing to its early nature, this figure will be revised. This unofficial estimate was calculated based on responses received from 53.8% of companies surveyed. The average final response rate for the survey over the previous 12 months was 90.8%,” it said.
Maria Solovieva
Maria Solovieva, Economist, TD Economics, said as expected, consumers continued front-load vehicle purchases in anticipation of price increases that are likely to come due to tariffs.
“However, core sales may be an early signal of broader consumer hesitancy in the face of trade policy headwinds. According to a supplementary by Statistics Canada survey, 36% of retail businesses reported being affected by trade tensions in April. The most commonly cited impact included price increases, change in demand, and supply chain disruptions,” she said.
“The advance estimate sets a somber tone for the second quarter. In addition, our internal credit and debit card spending data shows a meaningful softening in spending through May, suggesting that consumers tightened their purse strings. As a result, we expect real personal consumption expenditures to be flat this quarter, with consumer spending likely to contract in Q3 if U.S. tariffs continues to weigh on sentiment and job prospects.”
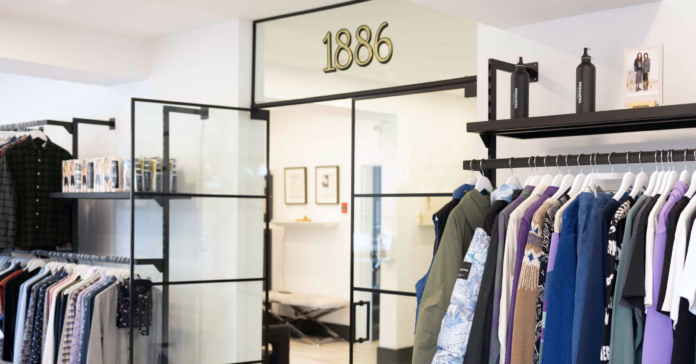
With roots dating back to 1886, Caulfeild Apparel Group has weathered more than a century of fashion trends, retail transformations, and market disruptions. Headquartered in Oakville, Ontario, the family-owned business is today one of Canada’s oldest apparel companies. CEO Mike Purkis, who acquired the company in 2003, is now steering Caulfeild into its next era, guided by a blend of heritage and innovation.
“We’ve been Toronto-based for 140 years,” said Purkis in a recent interview. “Started as a retailer, ended up importing British goods. In the seventies and eighties, we actually had one of the largest sewing machine plants in Toronto. We manufactured Caulfeild robes. Then we got into licensing—Gant, Izod, Calvin Klein, Cutter & Buck.”
Today, Caulfeild focuses on both licensing and brand ownership. “We own Joe Boxer for Canada entirely, Modern English, Benson, and we license Robert Graham for loungewear and Stacey Adams for multiple categories including dress shirts, sportswear, and underwear.”
Filling the Void Left by Hudson’s Bay
For decades, Hudson’s Bay was a critical retail partner. Caulfeild Apparel Group’s brands held significant floor space within the department store chain. The recent collapse of Hudson’s Bay as a multi-brand department store in Canada, however, has forced a significant industry reckoning.
Mike Purkis
“Hudson’s Bay at peak was doing $550 million in men’s sportswear alone,” said Purkis. “In their last year, that number dropped to around $300 to $350 million. That’s a huge hole in the market right now.”
Purkis expressed skepticism about recent attempts to revive the Hudson’s Bay footprint. “Canadian Tire bought the rights to the name, and I don’t know if that’s a great story. I don’t think they’re going to open multi-brand stores. Then you have Ruby Liu in Vancouver talking about opening over 25 doors—but she can’t even use the Hudson’s Bay name.”
The exit of Hudson’s Bay from the department store space has had widespread consequences. “You’ve got a billion-dollar gap in the market, and frankly, I don’t know who’s going to fill it.”
Strategic Brand Shifts and Distribution Expansion
In anticipation of industry shifts, Caulfeild had already begun pivoting. The company’s partnership with Costco has become increasingly central.
“They’ve been a great partner to us,” said Purkis. “They don’t hurt your market elsewhere, and they prove you can sell a hundred thousand of an item in six weeks.”
The company is also expanding into the U.S. market, launching Robert Graham underwear and Benson in select U.S. locations. “We’re focusing on North American distribution. Canada’s 40 million people—it’s a great market, but to grow you need to think more globally.”
Photo Caulfeild Apparel Group
Supply Chain Disruptions and Tariff Pressures
Caulfeild, like many other Canadian distributors, has had to navigate an increasingly complex trade environment. In particular, shifting U.S.-China tariff policies disrupted business in early 2025.
“The way the tariffs were launched, they came in so fast and unpredictably that even lawyers didn’t know how they’d be applied to goods in a bonded warehouse,” said Purkis. “At one point, the tariffs were 152%. It froze our shipping for 8 to 10 weeks.”
Purkis said the company has since diversified sourcing away from China to mitigate future risk. “The China-U.S. trade war isn’t going away anytime soon. We’re looking at other countries and sustainable production models.”
A Meaningful Commitment to Sustainability
Caulfeild’s approach to sustainability is more than a marketing message—it’s built into the business model. The company’s investment in Outland Denim, a socially responsible brand manufacturing in Cambodia, exemplifies that ethos.
“We built a factory in Cambodia that employs women rescued from human trafficking, trains them, and gives them healthcare,” said Purkis. “We buy only organic cotton, use renewable vegetable dyes, and ensure no child or slave labour.”
But for Purkis, sustainability is holistic. “If you buy organic cotton but don’t pay your employees a living wage, are you really sustainable? Sustainability means repeatable cycles—people, planet, resources.”
He also warns that meaningful sustainability comes at a cost. “To make things properly is going to cost more, and the consumer has to pay more. Otherwise, sustainability will suffer.”
Modern English brand, developed in-house. Photo Caulfeild Apparel Group
The Future of Canadian Apparel Retail
With traditional department stores gone or weakened, Canadian apparel brands and distributors must rethink their retail strategies. Purkis believes this shake-up could create new opportunities.
“Outlets are doing great, and luxury seems to be okay, but there’s a big gap for moderate-priced multi-brand retail,” he said. “Moores and Tip Top are still around, but they don’t offer the experience today’s consumers want.”
He sees potential in independent boutiques, particularly those with curated assortments and strong service. “In towns like Oakville and Halifax, stores like Burrows and Dugger’s are doing well, but they’re selling $250+ shirts. That’s not accessible for most Canadians.”
He also noted that retailers like Simons, while strong, can’t absorb the full market share left by Hudson’s Bay. “Simons does an awesome job, but they’re 70% private label, and they have only 13 doors. They’ll pick up some of the business, but not all.”
Joe Boxer, one of several brands distributed exclusively in Canada by Caulfeild. Photo Caulfeild Apparel Group
Considering Standalone Retail and Brand Acquisition
Purkis isn’t ruling out a shift into standalone retail for Caulfeild’s brands.
“We’ve never done retail ourselves, but I think going direct-to-consumer is important,” he said. “Online isn’t the only way to do that. Vertical brand stores are possibly on the map.”
The company is also actively exploring acquisitions. “We’ve built three brands and we’re looking to buy more. Sadly, there are going to be some companies that don’t make it. That might open the door for us.”
While he’s not planning to take on dozens of leases like others in the market, he’s watching closely. “If someone else opens a new department store model, we’ll be ready to engage—but I don’t believe anyone can open by Q4 2025.”
A Challenging Transition Ahead
With brands once heavily reliant on Hudson’s Bay now left scrambling, the short-term reality is stark.
“We’ve had calls from people who had container loads of product they can’t land,” said Purkis. “They’re calling Costco and TJ Maxx. But TJ Maxx knows there’s a glut, and they’re offering lower prices.”
Others, he said, may simply sit on product until Spring 2026 and repackage it. “Next spring, the theme will be retro 2025—because that’s what’s sitting in storage.”
While Caulfeild saw the writing on the wall early and reduced spring orders, many others weren’t so lucky. “I had partners in the U.S. with goods parked in Shanghai they didn’t want to bring in,” said Purkis. “The ripple effects will last for several seasons.”
A Resilient Legacy and a Watchful Eye on What’s Next
Despite the industry chaos, Purkis remains optimistic.
“Fashion’s about trends. You lose some, you win some. We’ve lasted 140 years by adapting,” he said. “We’ll continue doing that.”
Still, he’s acutely aware of the magnitude of change. “Some brands lost 80–100% of their Canadian distribution overnight when Hudson’s Bay closed. For many, there’s nowhere else to go.”
For now, Caulfeild Apparel Group will continue to lead with strategy, values, and adaptability—principles that have carried it through decades of disruption, and that will no doubt guide its next chapter.
S&S Activewear, a leading technology-enabled distributor of apparel and accessories in North America, is expanding its product availability across Canada, with a particular focus on strengthening inventory depth at its Vancouver distribution centre.
The initiative ensures cross-country Canadian customers maintain consistent access to their preferred styles and brands with faster delivery times and reduced freight costs, explained the company.
“Our customers depend on us for consistent product availability and this enhanced inventory strategy in Vancouver demonstrates our commitment to meeting that expectation,” said Craig Ryan, VP of commercial Canada at S&S Activewear. “We’re providing the reliability and faster shipping that decorators and promotional product distributors need to serve their own customers effectively.
“When our customers need it, we have it locally. That’s the S&S advantage in action.”
Source: S&S Activewear
S&S Activewear’s Vancouver facility serves as a critical distribution hub for western Canada, complementing the company’s Toronto operations to provide comprehensive coverage across the Canadian market. The facility will now stock popular owned brands and various private label collections favored by promotional product decorators and screen printers—including Team 365, CORE365, Harriton, Devon & Jones and North End—with delivery times dropping dramatically to western Canadian customers, said the company.
“The announcement comes as part of S&S Activewear’s broader commitment to adding more brands and inventory to its western distribution centers in 2025. The company’s proactive inventory management approach includes strategic transfers between distribution centers and careful demand forecasting to minimize disruptions, reduce delivery times and decrease freight costs,” it said.
Founded in 1988 and headquartered in Bolingbrook, Illinois, S&S Activewear is a leading technology-enabled distributor of apparel and accessories in the United States and Canada. S&S offers more than 100 brands, including basic garments to fashion-forward styles, with over 6 million square feet of warehouse space across North America. S&S services a broad range of customers through its nationwide network, including retail brands, e-commerce companies, garment decorators, promotional products distributors, entertainment merchandisers, lifestyle brands and web-based platforms for apparel customization.
Customer service is the backbone of any successful business – after all, a happy customer is a loyal customer. Yet many companies are falling short of expectations. Rather than support and resolutions, dealing with support can feel like more hassle than it’s worth – long wait times, a lack of care, and no guarantee of a resolution.
Gradient Labs conducted a customer support survey to evaluate consumer sentiment towards customer service processes, the issues they commonly face, and how they deal with them – with the results showing that customer satisfaction is far from guaranteed.
In a survey of 1,500 adults, conducted by Gradient Labs, consumers were asked to share sentiment towards customer service processes, the issues they commonly face, and how they deal with them.
Key research insights:
Some 75% of consumers rank long waiting times as a major customer service frustration, with 52% believing companies intentionally complicate the process.
Only 11% of consumers say all of their customer service inquiries are resolved, while 13% report that their problems are rarely or never addressed effectively.
Frustrated by a lack of resolution, 51% of consumers say they have taken their complaints further, with 19% visiting a company’s physical location, 17% threatening legal action, and 13% filing a government complaint.
After wasting time on inefficient and ineffective support processes, 71% of consumers believe businesses should financially reimburse customers for poor customer service interactions.
“Despite all the new-age customer service touchpoints available, most consumers still prefer to do it the old-fashioned way. Promising immediate support, 78% prefer to pick up the phone rather than wait for a reply to their email, tweet, or message,” said the report.
“But even a phone call doesn’t guarantee a quick resolution. Too often, a simple query or concern can turn into hours spent on hold and days of back and forth with no answer or resolution in sight. Just 11% of consumers say their issues are always resolved by customer support agents, while 13% insist their problems are rarely or never adequately addressed.
“Seeking help can be frustrating, but few experiences are as exasperating as reaching out to customer support only to be told to “Google it” – a scenario encountered by 10% of consumers – as if you hadn’t already tried before wasting your time on hold.”