Home Blog Page 6

Wild Fork Exits Canada, Abandoning Ambitious Ontario Expansion Plans

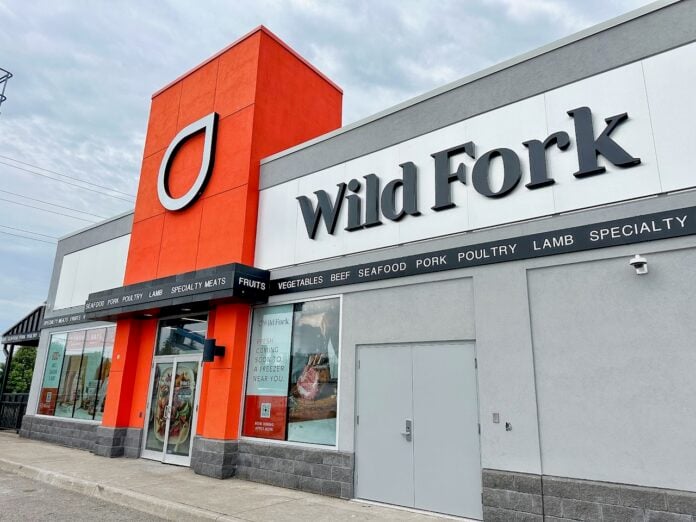
Wild Fork Ancaster, Ontario (Image: Wild Fork)

Wild Fork Foods is exiting the Canadian market and will close its four Ontario stores, ending an expansion effort that began less than four years ago and at one point contemplated a network approaching 30 locations across the province.

The JBS-owned specialty meat and seafood retailer operates stores in Whitby, Oakville, Ancaster and Newmarket. Wild Fork said online delivery and pickup in Canada will remain available until October 13, while its stores are expected to close on or before December 14. Individual locations could close earlier as inventory is sold.

The withdrawal represents a significant reversal from Wild Fork’s original Canadian plans. The retailer entered the market in early 2023 and was initially seeking about 20 locations in the Greater Toronto Area, with longer-term plans for expansion into British Columbia and Alberta.

By 2024, Wild Fork told Retail Insider that it had identified 26 priority markets in Ontario and wanted to move toward approximately 30 stores in the province within three years. Ultimately, the chain’s Canadian standalone network reached four locations.

Wild Fork Entered Canada With Significant Expansion Plans

Wild Fork launched its Canadian e-commerce business in January 2023, initially offering same-day delivery in the Greater Toronto Area. Its first physical store followed several months later at Taunton Gardens in Whitby.

At the time, the company was actively sourcing approximately 20 GTA sites. Wild Fork was generally looking for spaces of about 3,800 to 5,000 square feet, with grocery-anchored shopping areas among its preferred locations.

The retailer subsequently expanded to Oakville and opened an Ancaster store in June 2024. The Oakville and Ancaster locations were larger than the original Whitby prototype, each spanning just under 7,000 square feet.

During the Ancaster opening, then-Wild Fork Real Estate Lead Elle Mejia-Pierce told Retail Insider that the company had identified 26 Ontario markets it wanted to enter before moving into Western Canada.

“I’d like to see us inching up towards 30 stores in the next three years,” she said at the time.

Wild Fork was then building its real estate pipeline for 2025 and 2026, with Newmarket and London among the markets being considered. British Columbia and Alberta were expected to follow Ontario as the retailer expanded nationally.

The Newmarket store opened July 1, 2025, at 7 Harry Walker Parkway South, becoming Wild Fork’s fourth Canadian standalone location. It was also the last standalone store the retailer opened in the country before announcing its withdrawal about 15 months later.

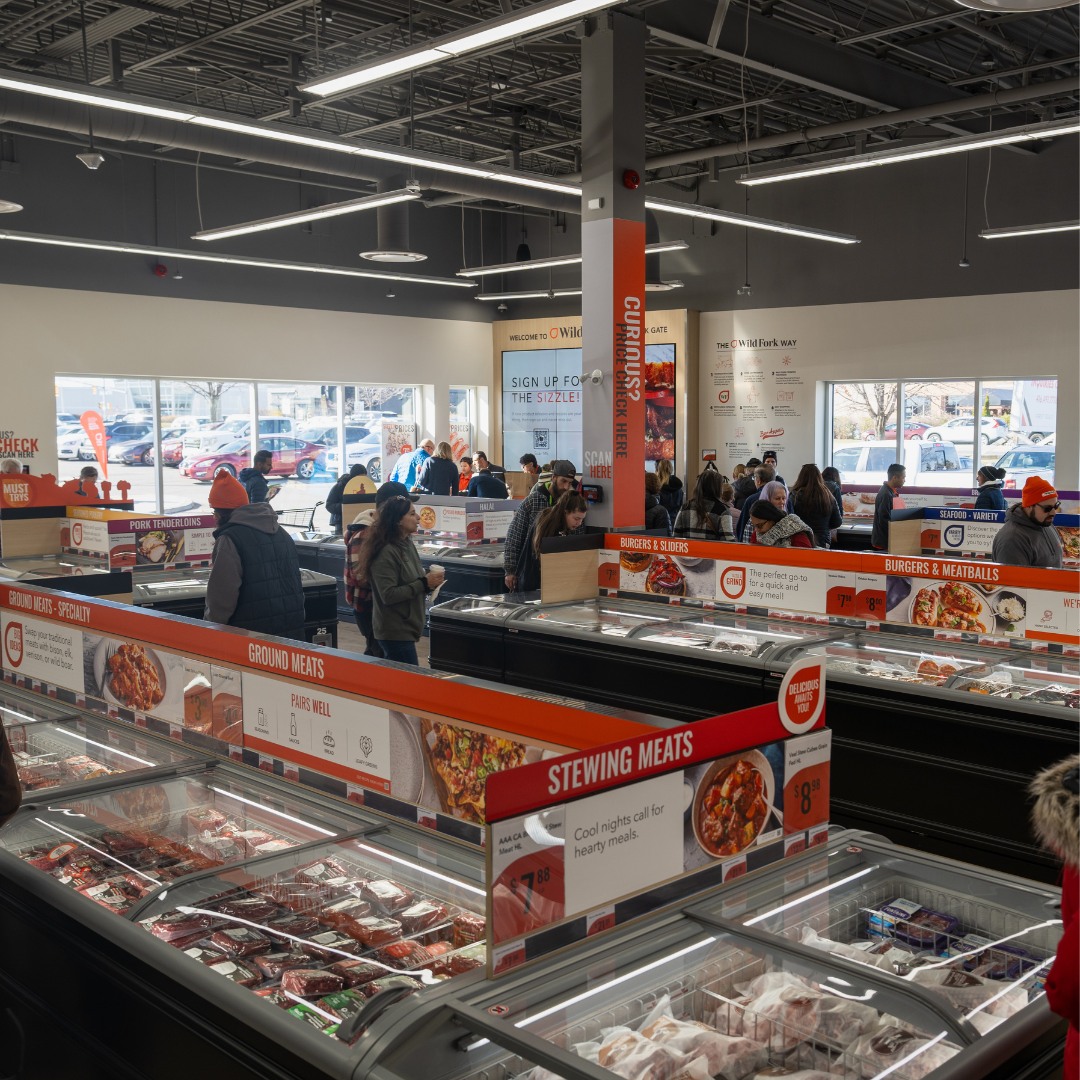
Grand Opening at Hyde Park Gate (Image: Wild Fork Canada)

A Specialized Meat and Seafood Concept

Wild Fork is part of JBS, the global food company with extensive meat processing and food operations in Canada, the United States and other markets. The Wild Fork withdrawal does not represent a broader Canadian exit by JBS, which maintains other operations in the country.

The retail concept centres on a broad assortment of frozen proteins sold through stores and e-commerce. By 2024, Wild Fork’s Canadian assortment had grown from approximately 450 products to more than 600, ranging from everyday beef, chicken and seafood to Wagyu, lobster, bison, elk, venison and other specialty products.

Wild Fork sought to position itself as an everyday food destination rather than exclusively as a higher-end meat retailer. Its real estate strategy included locations near conventional grocery stores and other frequently visited retailers, allowing the chain to serve as a specialized protein stop alongside a larger grocery trip.

Sobeys Partnership Offered Another Route to Canadian Customers

Wild Fork was still pursuing new ways to reach Canadian consumers in 2026. This summer, the company launched its first Canadian store-within-a-store partnership with Sobeys at the grocer’s Shellard Lane location in Brantford.

The shop carried more than 250 Wild Fork meat and seafood products. Wild Fork publicly described the opening as a new chapter in its Canadian growth and said it looked forward to reaching more Canadian families through the format.

The arrangement gave Wild Fork a presence inside an established Canadian supermarket without relying solely on expansion of its standalone store network. Within months of launching the Brantford pilot, however, Wild Fork announced plans to leave Canada.

Wild Fork has not publicly detailed what will happen to the Brantford Sobeys shop following the withdrawal. Its announcement says the company is closing its Canadian operations, but no specific information regarding the Sobeys partnership was provided.

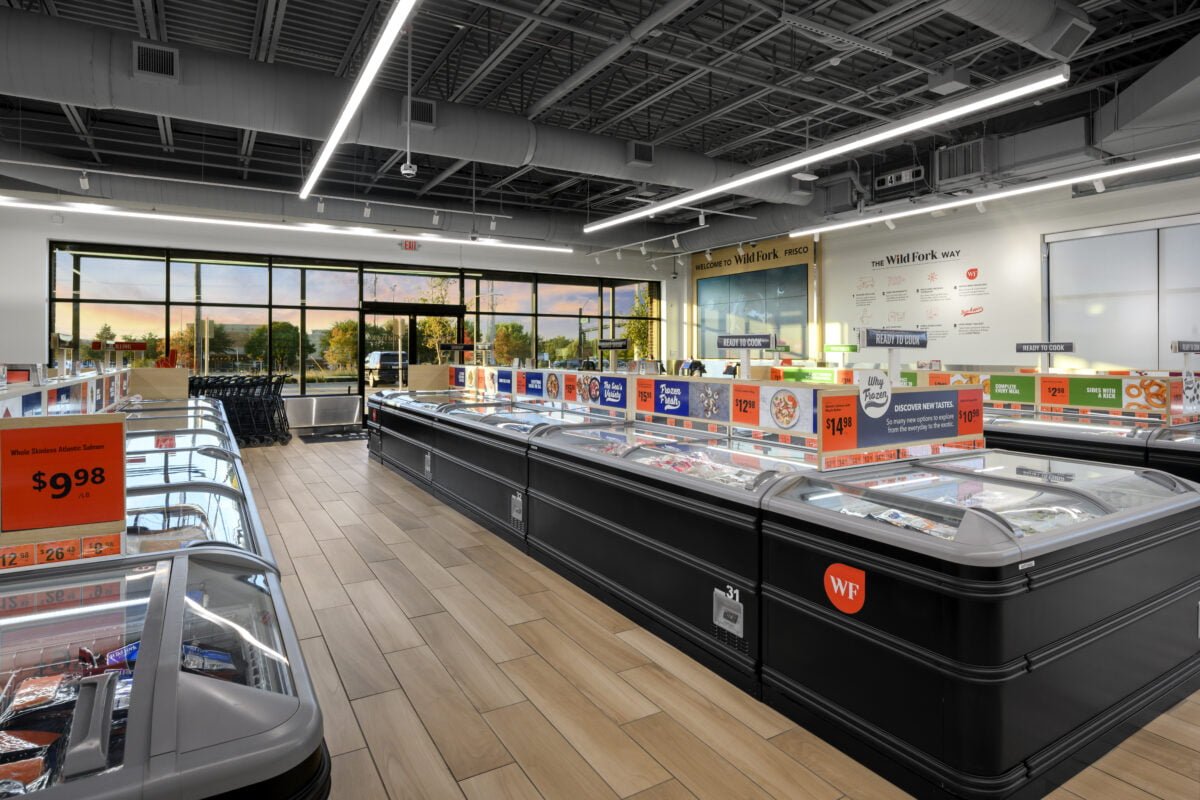
Image: Wild Fork

Canadian Hiring Continued Into September

Wild Fork also continued recruiting in Ontario shortly before the exit announcement. Employment listings associated with the company appeared in September for several markets, including Brantford, North York and Oshawa.

Federal Job Bank records included a Wild Fork posting in Brantford dated September 17, while other listings associated with the company appeared later in the month. The postings do not establish that Wild Fork intended to open standalone stores in North York or Oshawa, but they indicate that Canadian recruitment activity continued close to the October 6 announcement.

Together with the recently launched Sobeys pilot, the hiring activity shows that Wild Fork maintained visible Canadian operating and growth activity late in its time in the market. The timing does not establish when JBS or Wild Fork made the decision internally to leave Canada.

Wild Fork Gives No Detailed Reason for Exit

Wild Fork has not publicly provided a detailed explanation for its decision to leave Canada. In announcing the move, the company said the decision came “after careful consideration” and thanked Canadian customers for supporting the business.

“We are incredibly grateful for the customers who welcomed Wild Fork into their communities and trusted us to serve them,” the company said. “It has been a privilege to bring the Wild Fork experience to Canada, and we sincerely appreciate your support.”

Wild Fork said employees and customers would remain a priority during the transition and that it was committed to supporting store teams through the closures. The company has not disclosed how many Canadian employees will be affected, while questions also remain about the Sobeys arrangement and whether Wild Fork products could remain available through another Canadian distribution channel.

The timing of the withdrawal is particularly notable given Wild Fork’s activity earlier this year. After its standalone network stopped at four stores, the retailer was still experimenting with a different Canadian growth format through Sobeys this summer, only months before announcing that its Canadian operations would close.

More from Retail Insider:

Q3 2026 Grocery: Capacity Expands as Competition for the Basket Intensifies

As part of Retail Insider Reports, this Q3 2026 Grocery Report analyzes Q3 2026 developments in Canadian food retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping grocers, suppliers, landlords, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines the Canadian grocery retail sector, including supermarkets, discount grocers, specialty food retailers, convenience-oriented food retail, merchandising strategies, store expansion, competition, consumer purchasing trends, and developments affecting food retail in Canada.

Executive Summary

Canada’s largest grocery retailers continued adding and repositioning capacity during Q3 2026 even as the latest available supermarket data showed limited underlying volume growth.

Statistics Canada reported seasonally adjusted sales of approximately $9.45 billion at supermarkets and other grocery retailers, excluding convenience stores, in July. Sales were essentially unchanged from June and 1.2% higher than a year earlier. At constant prices, sales declined 0.3% month-over-month and 2.4% year-over-year.

Those figures do not capture the entire Canadian market for food. Grocery sold through establishments classified as general merchandise retailers, including supercentres, falls outside the supermarket category. Real sales at general merchandise retailers were 7.1% higher year-over-year in July, although the data do not identify how much of that increase came from food.

Against that backdrop, Loblaw continued a $2.4-billion capital program that includes substantial investment in No Frills and Maxi. Metro announced plans to convert 10 Ontario supermarkets to Food Basics. Empire increased its fiscal 2027 store target. Walmart is adding Supercentres to former department-store spaces, and T&T Supermarket has major shopping-centre projects planned in Ontario and Manitoba.

Retailers are also changing how they serve online customers. Metro is moving Montreal e-commerce fulfilment toward store picking and third-party delivery, while Empire is defining different roles for Voilà and on-demand delivery platforms.

Grocers can grow by entering underserved markets, changing formats, increasing their share of household spending or improving existing operations. The question is how much additional business those investments ultimately generate.

Canadian grocery retailers continued committing substantial capital to stores, formats and e-commerce during Q3 2026 despite soft real sales within the supermarket establishment category.

Several patterns emerged during the quarter:

  • Discount remained an important investment vehicle, with retailers adapting store sizes, assortments and banners to individual trade areas.
  • Conversions, relocations and acquisitions complicated headline store-opening counts because they did not all represent equivalent additions to grocery capacity.
  • Specialty and premium grocery continued attracting investment alongside discount formats.
  • Major shopping-centre projects from Walmart and T&T showed how former department-store space can add or reposition substantial grocery capacity.
  • Online grocery sales continued growing, but Metro and Empire focused increasingly on the cost and role of different fulfilment models.
  • Consumer behaviour pointed to grocery spending being divided across promotions, brands, formats and channels as households continued managing elevated food costs.

The next phase of expansion will test whether these investments generate additional sales and profit or redistribute existing grocery spending at higher cost.

Retail Insider Coverage

Grocery Inflation Slows, but Consumers Remain Price-Conscious

Food affordability remained an important backdrop to grocery competition during the quarter. Grocery-price inflation slowed to 2.8% year-over-year in August, falling below the 3.0% headline Consumer Price Index for the first time since July 2024. Grocery prices nevertheless remained approximately 29% higher than in August 2021.

Consumers were receiving some relief from the rate of price increases without reversing the accumulated increase in food costs. NIQ data cited by Retail Insider pointed to more frequent purchase occasions and lower average spending per transaction across several retail channels. Purchase occasions should not be interpreted as supermarket visits, but the pattern is consistent with consumers dividing purchases among different retailers, products and offers. The Canadian grocery basket is increasingly contested.

Discount Expansion Becomes More Localized

Loblaw’s 2026 investment program demonstrates the continued importance of discount grocery and the ways the format is being adapted to different markets. The company announced $2.4 billion in planned Canadian capital spending for 2026 and said in September that approximately $1.2 billion remained to be deployed. Its expected opening program increased to approximately 75 grocery, pharmacy and other locations during the year.

That total should not be interpreted as 75 new supermarkets. Shoppers Drug Mart, Pharmaprix and other formats form a substantial part of the program. Within grocery, No Frills and Maxi have received significant investment. An approximately 8,000-square-foot No Frills opened in Dutton, Ontario, on July 30 with a curated assortment of roughly 4,000 products, creating a smaller format for a rural trade area.

A larger No Frills in Komoka tests another version of the concept, including a broader fresh and prepared-food offer. The stores show how the same discount banner can be adapted to different local opportunities, with the longer-term economics of the newer formats still to be established.

Metro Uses Banner Conversion to Rework Existing Capacity

Metro is pursuing discount growth through its existing Ontario network. The company announced plans in August to convert 10 Metro supermarkets to Food Basics, including locations near Yonge and Finch in Toronto and at Southgate in Ottawa.

Management described the program as a location-by-location review of markets and underperforming stores, with the expectation that Food Basics can produce stronger sales and store contribution at the selected sites. These are existing grocery locations being repositioned under a different banner, price proposition and operating model. Metro has said individual stores could close for approximately two months during construction, with financial benefits building over subsequent fiscal years.

Metro reported food same-store sales down 1.5% during its fiscal third quarter, but the result was materially affected by the strike at its Laval produce-distribution facility. The company estimated an after-tax impact of approximately $66 million from lost profit and direct costs.

The sales decline should therefore not be treated as an equivalent measure of underlying grocery demand. The conversions address a separate question of which proposition is best suited to each local market.

Empire Expands Across Multiple Grocery Formats

Empire is increasing store-development activity across several banners and price positions. The company raised its fiscal 2027 target to more than 25 stores from an earlier expectation of more than 20 and plans approximately $850 million in capital spending. Roughly half is allocated to renovations and store development.

The increased target includes four acquired Mayrand locations, meaning the total cannot be treated as an entirely new-build program. FreshCo entered Atlantic Canada in August and continued expanding in Ontario and Western Canada. Empire is also investing through banners including IGA, Safeway and Mayrand.

Management has said recently opened stores were meeting or exceeding expectations and has argued that long-term property decisions should reflect individual market opportunities instead of the current national demand cycle alone. Discount is attracting capital, but retailers continue to see opportunities across multiple grocery formats.

New Capacity Isn’t the Same as New Store Count

Some of the largest grocery projects announced during the quarter demonstrate why store counts alone can misrepresent competitive change. Walmart plans an approximately 115,500-square-foot Supercentre at Place d’Orléans in Ottawa, occupying former Hudson’s Bay space and adding a full grocery assortment. Projects at Lime Ridge Mall in Hamilton and Bramalea City Centre in Brampton are also bringing Walmart into major shopping-centre locations.

These projects can add substantial fresh-food and grocery capacity even when relocations or conversions produce comparatively little change in Walmart’s overall Canadian store count. T&T Supermarket provides an even clearer example. Its planned CF Markville location in Markham will occupy approximately 68,000 square feet of former Hudson’s Bay space and is expected to replace the existing approximately 50,000-square-foot Unionville store when it opens in 2028.

The project represents a relocation and approximately 18,000 additional square feet instead of an entirely new 68,000-square-foot supermarket in the trade area. Its shopping-centre position could also alter traffic patterns and customer reach. T&T’s planned 48,000-square-foot store at CF Polo Park in Winnipeg represents a different type of expansion. Expected in spring 2028, it will be the banner’s first Manitoba location and introduces T&T to a new provincial market.

Openings, relocations, conversions, acquisitions and expansions can all appear in development pipelines while producing very different changes in local grocery supply.

Grocery Sites Can Survive the Failure of an Operator

Q3 also provided examples of grocery locations remaining viable after a previous operator departed. Valleyview IGA reopened on August 20 at 9106 142 Street NW in Edmonton, returning a familiar supermarket banner to a longstanding neighbourhood grocery site after L’OCA closed earlier in the year.

At Toronto’s Bayview Village, McEwan Fine Foods announced a 9,326-square-foot store for 2027 in the former Pusateri’s space. Prepared meals, fresh departments and specialty food will form part of the offer, maintaining a premium grocery component at the property under a different operator.

Sunterra’s Bower Place market in Red Deer closed September 26 while the company was in court-supervised restructuring. Those company-specific circumstances do not establish a broader retreat from premium grocery.

The examples separate the viability of a grocery location from that of a particular operator. A retailer’s failure does not necessarily establish that a trade area cannot support grocery, and an established grocery site does not guarantee that every concept will succeed there. Crombie’s results provide additional real estate context. The landlord reported 97.5% committed occupancy and an 11.3% increase in first-year rents on second-quarter renewals in results published during August.

The rental increase applied across Crombie’s portfolio and should not be interpreted as an 11.3% increase specifically on Sobeys or Safeway stores. Grocery anchors nevertheless support frequent property visits, while surrounding units provide additional leasing opportunities.

Broader Industry Coverage

Online Grocery Growth Doesn’t Settle the Profitability Question

Online grocery continued growing at Canada’s major supermarket companies during their latest reported fiscal periods. Loblaw reported e-commerce growth of 19.3%, Metro reported online food sales growth of 16.3% and Empire reported online growth of 11.3%. The reporting periods differ, so the figures are indicators of company activity instead of a comparable Q3 ranking.

More significant are the decisions being made about how those orders are fulfilled. Picking groceries, operating automated facilities, acquiring customers and delivering orders all carry costs. Higher digital sales do not establish that an online operation has become more profitable, and both Metro and Empire are adjusting their networks accordingly.

Metro Moves Fulfilment Back Toward Stores

Metro plans to close its dedicated Montreal e-commerce facility and shift fulfilment toward store-based picking and third-party delivery. Management linked the decision to growing demand for same-day service and the opportunity to reduce fixed costs. The company expects its combined network measures, including the Ontario store conversions, to generate approximately $15 million in recurring annual after-tax earnings by the end of fiscal 2028, with roughly half attributable to each component.

Moving orders into stores makes use of inventory, labour and locations already positioned close to customers, although store picking introduces its own operating costs and requirements. Metro is changing the cost structure of its online business, with the financial benefits expected to develop over several fiscal years.

Empire Redefines the Role of Voilà

Empire’s evolving e-commerce strategy provides a larger example of matching infrastructure to demand. The company invested heavily in automated customer fulfilment centres as it built Voilà, but later concluded that Canada’s grocery e-commerce market was smaller than previously anticipated.

Empire closed its Calgary customer fulfilment centre and kept a proposed Vancouver facility on hold while retaining dedicated facilities serving Toronto and Montreal. Its earlier restructuring was expected to improve annualized e-commerce operating income by approximately $95 million.

The company is now describing the next phase as “e-commerce 2.0.” Voilà continues to serve planned grocery orders in markets where dedicated infrastructure remains in place, while third-party platforms can address more immediate purchases and provide delivery coverage without requiring the same infrastructure in every market.

The approach resembles the localized physical-store strategies seen elsewhere in the sector. Different markets and shopping occasions can support different formats when demand is sufficient to justify their costs. For e-commerce, order density, basket size, frequency and cost to serve will determine where each model makes economic sense.

Technology Adds Another Layer

Instacart launched Clementine for most Canadian and U.S. customers in September, offering assistance with meal planning, shopping lists and cart building. The launch establishes the service’s availability in Canada, but early claims about changes in basket size were not Canada-specific and do not establish improved Canadian conversion or profitability.

Its relevance will depend on whether tools of this type materially change purchasing behaviour, basket composition or customer retention.

Competition Extends to Property and Pricing Rules

Competition in grocery is also being shaped by rules governing real estate and promotions. A September consent agreement with Empire made earlier commitments concerning grocery property controls legally binding, including restrictions on the use of certain restrictive covenants and exclusivity clauses.

Reducing those barriers can make entry into some trade areas easier, but it does not create suitable grocery space, provide capital or logistics, or guarantee sufficient local demand. The Competition Bureau also opened an investigation in September into minimum advertised pricing policies, examining whether restrictions on advertised prices make it more difficult for consumers to discover offers and for retailers to compete. The investigation is ongoing and does not constitute a finding that a particular supplier or grocer violated competition law.

Supplier negotiations provide another constraint on how quickly new costs reach consumers. Empire said on its September results call that the immediate tariff impact was minimal and only a handful of suppliers had submitted related cost increases. Management said it intended to challenge requests where sourcing alternatives were available. New cost pressures therefore do not automatically translate into equivalent increases at the grocery shelf.

Editor’s Take & Outlook

What Retailers and Landlords Should Watch

The expansion underway in Canadian grocery requires more context than a count of announced stores. T&T’s CF Markville project replaces and expands an existing nearby store. Metro’s 10 Food Basics conversions reposition existing supermarkets. Empire’s higher opening target includes acquired Mayrand locations. Walmart can add substantial grocery capacity through Supercentre projects without a proportionate increase in net store count.

Retailers will need to determine whether those investments produce additional traffic, transactions and household spending or shift sales among existing locations. Real sales, average basket, transaction frequency, gross margin, store contribution and cannibalization provide a clearer picture than opening counts alone.

Online grocery requires a parallel assessment through order density, repeat use, basket size, picking and delivery costs, and customer acquisition. For landlords, the analysis occurs at the trade-area level. A grocery opening can fill a major vacancy and increase property traffic while redistributing food spending from nearby stores.

Outlook: Measure the Return on Added Capacity

The next six to 18 months will provide clearer evidence on the returns from the industry’s current investment cycle. Metro’s Food Basics conversions will test whether changing the banner and price proposition can improve sales and store contribution at selected Ontario locations. Loblaw’s smaller No Frills formats will provide evidence on whether discount can economically serve communities that may not support conventional supermarket footprints.

Empire’s development pipeline will test its ability to add stores across several formats while maintaining returns. T&T’s major projects and Walmart’s shopping-centre Supercentres will introduce or reposition substantial grocery capacity in individual trade areas, although several projects extend into 2027 and 2028.

Online grocery faces a similar test. Metro’s move toward store-based fulfilment needs to produce the expected cost benefits, while Empire will need to grow digital sales without recreating the fixed-cost challenges that led it to restructure its original fulfilment network.

Performance at existing stores around new openings will be particularly important. A successful new supermarket can still derive part of its sales from nearby locations operated by the same company or its competitors. The central measure is how much additional household spending each investment captures and what it costs to win and serve that business.

Editor’s Take

Canada’s largest grocers continue to see opportunities for investment even as the latest available supermarket data show limited underlying volume growth. National averages can obscure population growth, underserved communities, changing shopping patterns and shifts between channels. Retailers can also grow by taking market share or improving locations they already operate.

Q3 showed how local that competition is becoming. Loblaw is testing different versions of No Frills, Metro is converting selected stores to Food Basics, Empire is expanding across several grocery formats, and Walmart and T&T are adding or repositioning substantial grocery capacity through shopping-centre projects.

Online grocery is undergoing a similar adjustment. Metro is reducing dedicated infrastructure in Montreal, while Empire is assigning different shopping occasions to Voilà and third-party delivery platforms.

The Canadian grocery basket is being contested across more formats, locations and fulfilment models. An opening, relocation, banner conversion, acquisition and expansion can each produce a different competitive effect, just as digital sales growth can have very different economics depending on how an order is fulfilled.

The next phase of Canadian grocery expansion will be determined by what happens after the announcements: how much additional business new and repositioned formats capture, how much they take from existing stores, and whether the cost of winning each basket produces an adequate return.

Representative Articles

More From Retail Insider
Q3 2026 Food Service: Restaurant Growth as Consumers Become More Selective

As part of Retail Insider Reports, this Q3 2026 Food Service Report analyzes Q3 2026 developments in Canadian restaurants and foodservice retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping restaurant operators, franchisees, landlords, suppliers, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines Canadian foodservice retail, including quick-service restaurants, full-service restaurants, cafés, food halls, chains, franchised operators, and consumer dining trends.

Executive Summary

Canadian restaurant and foodservice sales continued rising during Q3 2026, but the headline growth masks a more difficult operating environment. Statistics Canada reported seasonally adjusted sales of approximately $8.9 billion at foodservice and drinking places in July, up 0.8% from June and 7.0% from a year earlier. All four major industry groups recorded monthly growth, including full-service restaurants at 0.8% and limited-service eating places at 0.4%. Those figures measure current-dollar receipts rather than customer visits or meal volumes. Restaurant prices were also rising, with restaurant CPI up 3.1% year-over-year in August following increases of 2.9% in July and 2.7% in June.

Industry research points to considerable pressure behind the growing sales totals. Restaurants Canada reported that 80% of Canadians were eating out less often because of the cost of living, compared with 75% a year earlier. The association has also reported that 41% of restaurant companies were losing money or breaking even, while average industry pre-tax margins were 4.1%.

Restaurant operators continued investing despite those pressures. Jollibee secured commitments for 26 additional restaurants in Western Canada, Firehouse Subs reached 200 Canadian locations and Tim Hortons maintained a development program of approximately 80 openings. Established chains invested in beverages, renovations, value offers and loyalty, while delivery partnerships created other ways to reach customers.

Consumers can reduce restaurant spending in several ways without abandoning the category, including dining out less frequently, choosing lower-priced items, skipping drinks and extras or picking up orders to avoid delivery fees. Growth increasingly depends on whether restaurants can generate repeat demand and profitable spending from the occasions they capture. Canadian foodservice receipts continued rising during Q3 2026, but inflation, reported consumer restraint and thin restaurant margins complicate the headline growth.

Several patterns emerged during the quarter:

  • Consumers reported becoming more selective about dining occasions, while some restaurant companies described pressure on traffic, add-ons and delivery spending.
  • Restaurant profitability remained constrained by food, labour, occupancy and other operating costs.
  • Expansion continued through corporate and franchise development, although operating restaurants, development commitments and long-term targets represent different stages of growth.
  • Mature chains invested in beverages, value, renovations and loyalty to generate more business through their restaurant networks.
  • Delivery partnerships expanded customer access, but the financial impact varies according to who acquires the customer, fulfils the order and absorbs the channel costs.
  • Company results varied considerably, indicating that affordability pressure alone does not explain differences in restaurant performance.

The next phase of Canadian foodservice growth will test whether operators can convert expansion and product spending into repeat demand while preserving restaurant and franchisee returns.

Retail Insider Coverage

Restaurant Expansion Continues

Restaurant development continued across several Canadian markets during the quarter. Jollibee’s Western Canadian franchise agreements provide one of the largest examples. The company has commitments for 16 restaurants in British Columbia over five years and an earlier agreement covering 10 restaurants in the Edmonton market.

Together, the 26 committed restaurants nearly equal Jollibee’s existing 28 company-operated Canadian locations. The commitments do not represent 26 operating restaurants or fully secured sites, with individual locations still requiring site selection, approvals, capital, construction and execution.

Firehouse Subs opened its 200th Canadian restaurant at West Springs Landing in Calgary. Jersey Mike’s entered Calgary at 9631 Macleod Trail as franchise operator Redberry continued pursuing a longer-term target of 300 Canadian locations by 2035.

Recipe Restaurant Group also opened an Olive Garden at Vaughan Mills under its Canadian development agreement, with Ottawa and Ajax locations in development.

Expansion can occur on a much smaller physical scale as well. Craig’s Cookies reached 25 Canadian locations and generally targets approximately 1,000 square feet for a franchisee’s first store, within a working range of roughly 800 to 1,200 square feet.

The chain operates in neighbourhood, shopping-centre and tourist locations, while founder Craig Pike has emphasized avoiding oversaturation as the network grows. Its compact format requires a different level of space and capital than a full-service restaurant or larger quick-service operation.

Operating restaurants, sites in development, franchise commitments and long-term targets all indicate expansion, but they represent different stages and levels of commitment.

Mature Chains Look Beyond the Meal for Growth

Beverages became one of the clearest areas of restaurant spending during Q3. KFC Canada and its franchisees committed $30 million to Kwench, a dedicated beverage offering that includes shakes, sparkling lemonades, boba refreshers and iced lattes. The company outlined plans to expand the concept to more than 400 locations by year-end and approximately 600 in 2027.

Tim Hortons continued expanding its cold-drink platform through products including matcha and new fountain equipment, while McDonald’s pursued a similar opportunity through its expanded beverage platform. McDonald’s management reported encouraging early Canadian results but did not disclose Canadian traffic or average-cheque figures that would quantify the effect. The attraction extends beyond beverage sales themselves. Established restaurants already carry the costs of premises, equipment and networks built around existing meal periods. An afternoon beverage can potentially generate another customer occasion through those assets. The return depends on whether the purchase is genuinely new business and whether the sales justify equipment, ingredients, labour, preparation time and operational complexity.

Tim Hortons demonstrates the scale of the opportunity within an established network. The company and its restaurant owners announced approximately $400 million in Canadian spending for 2026, including roughly 80 new restaurants and 400 renovations, across a network of nearly 4,000 Canadian locations.

Renovations include restaurant layouts, kitchen equipment and digital ordering and pickup infrastructure intended to improve speed, accuracy and customer experience. At that scale, improvements in visit frequency, average spending or operating efficiency across the network can have substantial system-wide effects. Beverages, renovations and new locations provide different routes to stronger performance from a restaurant network.

Loyalty Adds Another Reason to Return

Tim Hortons also expanded its loyalty reach during the quarter through a partnership with Canadian Tire’s Triangle Rewards. Customers who link eligible Tims Rewards and Triangle Rewards accounts can earn Canadian Tire Money on qualifying Tim Hortons purchases, with earning rates depending on payment method. The two rewards currencies remain separate.

The partnership adds another benefit to a high-frequency purchase while connecting Tim Hortons with a larger Canadian retail loyalty ecosystem. Its effect on visit frequency and restaurant-level returns was not disclosed during the quarter.

Delivery Raises the Question of Who Owns the Customer

Restaurant delivery continued expanding, but the quarter’s announcements demonstrated different approaches to customer acquisition and fulfilment. The Keg introduced delivery through DoorDash from more than 100 restaurants across Canada and the United States, extending selected menu items beyond its dining rooms. The announcement did not quantify new sales or restaurant-level returns.

Domino’s Canadian partnership with Skip uses a different model. Customers can place orders through Skip, while Domino’s own Delivery Experts fulfil them.

Pizza Pizza management has separately discussed the higher cost of third-party delivery and the advantages of moving customers toward proprietary ordering channels where possible.

The arrangements separate several parts of a delivery transaction: attracting the customer, processing the order, fulfilling it and maintaining the customer relationship. Third-party marketplaces can provide reach and convenience, but operators still need to assess new sales against commissions, fulfilment costs and the value of owning the direct customer relationship.

Property Investment Can Increase Restaurant Productivity

Foodservice spending is also changing existing retail properties without necessarily adding large numbers of restaurant tenants. At Promenades St-Bruno in Quebec, Primaris is planning a $49.5-million redevelopment that will relocate the food court, increase seating to approximately 1,100 and create an exterior entrance.

The project is designed to support longer operating hours and improve access for pickup and delivery outside regular mall hours. Approximately 20,000 square feet in the existing food-court area will eventually be released for new retail space, while the number of food vendors is expected to remain broadly similar.

For the landlord, the redevelopment changes how customers can use the dining area while creating another leasing opportunity elsewhere in the property. For foodservice tenants, exterior access, additional seating and improved pickup and delivery functionality could expand the range of occasions the space can serve.

The current food court is expected to remain open during construction, with the new food court scheduled for fall 2027 and conversion of the former space following later.

Closures Need Context Too

Restaurant closures require the same scrutiny as expansion announcements. Starbucks announced approximately 250 North American closures alongside café improvements that included Canada, but did not disclose how many closures would occur in this country.

Boston Pizza’s program combines renovations and selected new locations with individual closures, some related to lease and redevelopment circumstances.

MTY’s planned closure of 68 corporate restaurants provides another example. Management said approximately 45 to 50 involved Papa Murphy’s, giving the program substantial exposure to the U.S. pizza market. Banner, geography and reason therefore matter when interpreting closure numbers, just as development commitments and long-term targets need to be distinguished from operating restaurants.

Broader Industry Coverage

Consumers Become More Selective About Dining Occasions

Higher restaurant receipts are occurring alongside evidence that consumers are becoming more selective about when and how they eat out. Restaurants Canada’s September Foodservice Facts findings indicated that 80% of Canadians were eating out less often because of the cost of living. The reported increase in restraint was particularly notable among households earning at least $100,000, although the findings measure stated behaviour and should not be treated as an observed national traffic count.

Pizza Pizza provided one of the quarter’s clearest descriptions of how customers can reduce restaurant spending without eliminating an occasion. Management discussed fewer visits, customers cutting drinks and other extras, and increased pickup as some consumers sought to avoid delivery fees. A customer who continues buying the core meal while removing a drink, dessert or delivery charge still generates a transaction, but the value and profitability of that transaction can change.

Restaurants Canada has also reported consumers protecting some occasions while cutting others, with breakfast and lunch showing greater resilience than some other dayparts. Operators are competing for a place in a more selective household food budget, with frequency, format, price and occasion all influencing where spending goes.

The Whole Bill Matters

Value initiatives during Q3 showed how restaurants are trying to protect demand without relying solely on broad discounting. Subway introduced its Fresh For Less menu in Canada with breakfast, snack and lunch items below $5 at participating restaurants. The positioning applies to individual menu choices and can vary by location, rather than establishing a universal sub-$5 meal price.

MTY described a related pricing constraint during its quarterly reporting. Protein costs remained difficult, but management said consumers’ willingness to absorb increases varied by product, requiring affordable entry choices alongside higher-priced items.

Pizza Pizza described offers directed toward inactive customers as preferable to indiscriminate discounting that could weaken franchisee earnings. Drinks, sides, desserts and delivery also contribute to transaction value, making the loss of those purchases significant even when the core meal remains intact. Operators need to balance traffic and affordability against the food, labour, occupancy and service costs attached to each transaction.

Different Chains Are Producing Very Different Results

Company results released during Q3 illustrate how differently restaurant brands are performing within the same broad consumer environment.

Tim Hortons reported Canadian comparable sales growth of 0.1% for the quarter ended Jun 30, 2026. Boston Pizza reported 2.3% same-restaurant sales growth for the same period, with management saying both traffic and menu pricing contributed positively and pricing provided the larger contribution.

MTY reported Canadian same-store sales down 1.8% for its fiscal quarter ended May 31, although management described improvement in June. Pizza Pizza reported a 5.0% same-store sales decline across Pizza Pizza and Pizza 73 for the quarter ended June 30.

The figures cover different businesses, reporting periods and operating models and should not be treated as a ranking of July-to-September performance. They show that the same broad consumer pressures are producing different outcomes across restaurant systems.

Restaurant Brands International management pointed to product and marketing execution when discussing Tim Hortons’ Canadian performance. Boston Pizza benefited from a combination of traffic, pricing, promotions and restaurant occasions associated with major sporting events.

Affordability remains an industry-wide constraint, while product relevance, value, marketing, location, service and execution continue to influence individual brand performance.

Restaurants Also Compete With Convenience Food

The competitive set for many restaurant occasions extends beyond traditional restaurants. Couche-Tard reported 4.3% Canadian food-sales growth during its first fiscal quarter while Canadian merchandise same-store sales overall were approximately flat.

The company did not quantify sales taken from restaurants, so the result does not establish that convenience stores are gaining restaurant market share. Prepared food at convenience stores nevertheless competes for some of the same occasions, including coffee, breakfast, snacks and quick meals. Value offers and convenient locations broaden the choices available to consumers purchasing food away from home, making the relevant competitive set wider than businesses formally classified within the restaurant industry.

Editor’s Take & Outlook

What Restaurant Operators and Landlords Should Watch

Restaurant growth increasingly needs to be evaluated through the performance of individual locations and customer occasions. For operators, traffic remains important, but so do average cheque, product attachment, daypart mix, repeat frequency, promotional response, delivery mix, food costs, labour requirements and restaurant-level margins.

Franchise systems need development commitments to become viable sites and operating restaurants, while new units need to generate acceptable returns without excessive cannibalization of existing franchisees. Mature systems face a different scale question. Improvements across hundreds or thousands of restaurants can have a greater effect than an annual opening program, making renovations, beverages, loyalty and digital initiatives important even when they do not add locations.

For landlords, visibility, access, parking, drive-thru capability, pickup areas, delivery access, operating hours, patios and nearby competition can influence restaurant performance. Promenades St-Bruno shows how property design can expand the usefulness of foodservice space without substantially increasing the number of vendors.

Outlook: Can Growth Produce Repeatable Restaurant Economics?

The next six to 18 months will provide several tests of the industry’s current growth plans. Jollibee’s Western Canadian agreements will begin to show how quickly committed franchise development converts into secured sites and operating restaurants. KFC’s wider Kwench rollout will test whether beverage demand can be sustained beyond the initial launch period across a much larger restaurant base.

Tim Hortons will continue spending on openings, renovations, beverages and loyalty while seeking stronger performance from its Canadian network. McDonald’s beverage expansion will provide another indication of whether established quick-service restaurants can create new occasions through locations already in operation.

Value initiatives will need to protect demand without weakening franchisee returns. Delivery partnerships face a similar test as operators assess whether third-party reach produces new orders or moves existing demand through more expensive channels. Restaurant profitability remains the broader constraint. Nominal sales can continue growing while food, labour, occupancy and service costs absorb much of the increase.

Repeat demand and restaurant-level returns will provide a clearer measure of sustainable growth than opening targets or current-dollar sales alone.

Editor’s Take

Canada’s foodservice industry continues to invest as consumers become more selective about dining out. Restaurant chains are opening locations, franchise agreements are being signed and mature systems are spending on renovations, beverages, loyalty, value and delivery. Landlords are also investing in foodservice space and the infrastructure surrounding it.

The economics behind that activity are under more pressure than headline restaurant receipts suggest. Consumers can visit less often, choose a lower-priced format, skip a drink or side, use a promotion, pick up an order instead of paying for delivery, or move a quick meal occasion to a convenience store. Operators are competing for the visit, the composition of the cheque and the next visit.

New locations remain an important source of growth for emerging restaurant systems. Mature chains have another powerful lever in their established networks, where improvements in frequency, product attachment or operating efficiency can be applied across hundreds or thousands of restaurants.

Differences in company performance also show why consumer pressure cannot explain every outcome. Product, value, marketing, location and execution continue to matter. The next phase of Canadian foodservice growth will be determined by whether operators can give consumers enough reason to return while keeping each occasion economically attractive for restaurants and their franchisees. Nominal sales growth alone will not answer that question.

Representative Articles

More From Retail Insider

Q3 2026 Real Estate & Leasing: Strong Leasing Faces the Test of Delivery

As part of Retail Insider Reports, this Q3 2026 Real Estate & Leasing Report analyzes Q3 2026 developments in Canadian retail property and leasing. Drawing on Retail Insider coverage, industry research, landlord disclosures, government data, and broader market signals, it identifies key dynamics shaping landlords, tenants, investors, shopping centres, and redevelopment projects. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines retail real estate, leasing, shopping centres, mixed-use developments, landlords, tenants, mall operators, redevelopment, and commercial retail property trends.

Executive Summary

Canadian retail real estate entered the final quarter of 2026 with exceptionally tight conditions at some properties and millions of square feet of former department-store space still moving through redevelopment.

Choice Properties reported retail occupancy of 97.4%, Crombie ended its second quarter with committed occupancy of 97.5%, and CT REIT reported 99.5%. Renewal spreads were also strong across several portfolios, supported by grocery, service and other necessity-oriented tenants.

The national picture was more complicated. Canada’s overall retail vacancy rate remained around 2.5% following Hudson’s Bay closures, while shopping-mall vacancy had risen sharply as the market absorbed almost five million square feet of negative net absorption. CoStar expects mall vacancy to remain elevated for several years.

A nearly full grocery-anchored centre and an enclosed mall redeveloping a 150,000-square-foot former department store face very different leasing conditions, capital requirements and timelines. Landlords are making progress replacing major vacancies, but former anchors frequently require subdivision, new entrances, building systems, permits and substantial landlord and tenant investment before replacement businesses can open.

The distinction is visible in landlord results. Primaris reported 86.6% in-place occupancy against 91.1% committed occupancy, while Crombie reported 96.6% economic occupancy against 97.5% committed occupancy.

The next phase will be measured by how much committed leasing becomes open, rent-paying space and what returns landlords generate on the capital required to create it. Canadian retail-property conditions remained highly selective during Q3 2026, with some grocery-anchored and necessity-oriented portfolios reporting near-full occupancy while enclosed malls continued absorbing large former department-store vacancies.

Several themes emerged during the quarter:

  • Choice Properties, Crombie and CT REIT reported high retail occupancy and strong renewal spreads, supported by established national tenants and necessity-oriented shopping.
  • National conditions were less uniform, with elevated mall vacancy following Hudson’s Bay closures and rent growth expected to moderate.
  • Committed occupancy can exceed in-place or economic occupancy because signed tenants may not yet have opened or begun paying rent.
  • Former department-store replacements increasingly involve multiple tenants and substantial redevelopment instead of another retailer taking an anchor box intact.
  • Higher replacement rents can create significant income potential, but returns also depend on redevelopment capital, downtime and rent commencement.
  • Ownership transactions and acquisition activity demonstrate continued interest in Canadian retail property, although acquisitions, redevelopment plans and operating income represent different stages of investment.

The next several quarters will show how much announced and committed leasing converts into productive space and rental income.

Retail Insider Coverage

Grocery and Necessity-Based Properties Remain Tight

Some of the strongest landlord results came from portfolios anchored by grocery, service and established national retailers. Choice Properties ended Q2 with retail occupancy of 97.4% and completed about 643,000 square feet of renewals at an average spread of 12.4%. Excluding fixed-rate renewal options, the spread was approximately 20%, illustrating how the composition of expiring leases can affect the headline result.

At Bloor and Dundas in Toronto, Choice is dividing approximately 90,000 square feet formerly occupied by Loblaw between Shoppers Drug Mart and GoodLife Fitness. Shoppers had taken possession for fixturing, while GoodLife possession was targeted for early 2027. A separate 82,000-square-foot property in Laval required rezoning before redevelopment could proceed.

Crombie reported 97.5% committed occupancy and 96.6% economic occupancy at the end of Q2. Economic occupancy represents space under lease where rent has commenced, while committed occupancy also includes completed leases for future occupancy of currently vacant space.

The REIT completed approximately 121,000 square feet of Q2 renewals at rents 11.3% above expiring rates. Its grocery-oriented portfolio benefits from recurring visits, while Empire’s 61.5% share of annual minimum rent creates substantial tenant concentration.

CT REIT reported committed occupancy of 99.5% and a blended renewal increase of 10.4%. Canadian Tire accounts for the overwhelming majority of its gross leasable area and annualized base minimum rent. The results demonstrate the strength of well-leased necessity-oriented retail, but the structures of these portfolios help explain why their occupancy and renewal figures should not be generalized across the Canadian market.

Leased, Open and Cash-Paying Are Different Stages

Primaris provides one of the clearest examples of the difference between leasing progress and current property income. The mall-focused REIT reported 86.6% in-place occupancy at the end of Q2 compared with 91.1% committed occupancy. At June 30, approximately 600,000 square feet of former Hudson’s Bay space had been leased, with another 300,000 square feet in advanced negotiations. Occupancy dates for the leased space extend from early 2027 through mid-2029.

Primaris has estimated redevelopment capital of $175 million to $225 million for its former HBC space. Replacement net rent is expected to average approximately $17 per square foot compared with roughly $4 per square foot previously paid by Hudson’s Bay.

The increase creates substantial potential rental growth, but it comes with redevelopment capital, construction, tenant delivery and several years of staged rent commencement. The economics become clearer as tenants open, rent begins and the redeveloped space moves toward stabilized operation.

Former Department Stores Are Becoming Multiple Destinations

Galeries de la Capitale in Quebec City shows what anchor replacement can involve at the property level.

Primaris is investing approximately $19 million to convert the roughly 163,000-square-foot former Hudson’s Bay into a multi-tenant retail and restaurant wing. Imaginaire has committed to approximately 30,500 square feet, with an opening targeted for spring 2027, while ZIBO! is taking approximately 5,500 square feet.

The conversion includes an exterior entrance and new washrooms, while Imaginaire is investing approximately $2 million in its store separately from Primaris’s landlord expenditure. Other spaces are expected to be delivered progressively through 2027.

Central Walk is undertaking a larger conversion across Woodgrove Centre in Nanaimo and Mayfair Shopping Centre in Victoria, involving approximately 310,000 square feet of former Hudson’s Bay space.

At Woodgrove, H Mart has been confirmed for roughly 30,000 square feet alongside TM Wander and family entertainment uses. Haidilao is planned for Mayfair, while another international retailer has been in negotiations involving both properties.

Expected combined landlord and tenant investment at Woodgrove is approximately $30 million to $40 million, including about $10 million from the landlord. Major uses are targeted for spring or summer 2028, subject to permitting and approvals.

The strategy replaces one large anchor with several reasons to visit across different parts of the day. Its contribution to traffic, tenant sales and property performance will become measurable once those businesses are operating.

At CF Sherway Gardens in Toronto, Splitsville plans a 34,000-square-foot bowling and entertainment venue in part of the former approximately 140,000-square-foot Nordstrom, targeting fall 2027. The lease is significant, but represents one component of the former anchor’s reuse.

Capital Is Still Moving Into Canadian Retail Property

Major ownership and financing activity continued during the quarter. The $9.4-billion transaction involving First Capital, KingSett Capital and Choice Properties would see Choice acquire approximately $5 billion of assets, with KingSett acquiring the remaining assets and outstanding units. The transaction had received court approval in late June 2026.

Westcliff’s acquisition of Edmonton’s approximately 880,000-square-foot Kingsway Mall from Oxford represented a different investment case. The property moved to an established private shopping-centre owner, with no immediate comprehensive redevelopment announced.

Jadco’s acquisition of the corporate entity holding Montreal’s Centre Rockland offers longer-term redevelopment possibilities, although no new master plan or former-Hudson’s Bay replacement had been announced.

Primaris raised approximately $200 million through an equity offering while reporting more than $1 billion of potential mall acquisitions under negotiation. The financing provides capacity for further investment, while negotiations remain separate from completed acquisitions.

Ownership changes can support continued operation, portfolio consolidation or redevelopment. Their significance depends on the business plan that follows.

Edmonton City Centre Highlights the Operating Challenge

Edmonton City Centre illustrates the different timelines of long-term redevelopment and current retail operations. A court approved Westrich’s proposed acquisition in August. Initial plans included approximately 1,500 homes, street-oriented retail and a rooftop Nordic spa on the former Hudson’s Bay portion, with major project details and construction timing still subject to further work and approvals.

Businesses in downtown Edmonton have meanwhile reported concerns involving public safety, vandalism, parking and prolonged construction access. Chamber survey results and business interviews identify conditions affecting merchants, although they do not establish that any single factor caused business closures.

Additional residents and destination uses could broaden the area’s catchment over time. Existing businesses still need workable access and trading conditions while redevelopment proceeds.

Broader Industry Coverage

Canada’s Retail Property Market Is Increasingly Selective

National data provide an important counterweight to the strongest landlord results. CoStar reported that Canada’s overall retail vacancy rate increased from approximately 1.8% to 2.5% following Hudson’s Bay closures and remained near that level over the subsequent year. Shopping-mall vacancy rose from approximately 3.1% to 8% in Q2 2025, when the closures produced almost five million square feet of negative net absorption.

CoStar expects overall vacancy to remain around 2.5% over the next year and mall vacancy to remain near 7% in three years. Retail rent growth, slightly above 2% in Q2 2026, is forecast to slow to roughly zero by Q2 2027 before recovering. About five million square feet of retail space was under construction in Q2 2026, while quarterly starts have remained below one million square feet since Q3 2025. Existing anchor vacancies still require suitable tenants, workable configurations and viable redevelopment economics.

CBRE’s first-half Canadian survey showed how sharply conditions differ by property type and location. Rents increased across 28 of 131 tracked formats and key urban areas and declined in eight, with grocery, service, medical, fitness and quick-service restaurant demand supporting parts of the market. A well-located grocery-anchored suburban centre can operate near capacity while an enclosed mall in the same metropolitan area works through a major anchor vacancy.

Retail sales add another consideration. Statistics Canada reported seasonally adjusted Q2 retail sales growth of 2.2% in current dollars but 0.4% in volume. July sales were up 5.1% year-over-year in dollars and 1.7% in volume.

The figures do not establish sales at individual properties, but the gap between nominal and volume growth matters when assessing retailer performance and capacity to absorb higher occupancy costs.

Headline Leasing Numbers Need Context

Strong leasing metrics can describe very different underlying circumstances. RioCan provided a useful example during its Q2 call when management discussed a GTA grocery lease renewed at double its previous rent. Management subsequently explained that the rent had last been negotiated at market approximately 30 years earlier, with relatively flat fixed renewal options in the intervening period. The increase captures decades of accumulated rental adjustment. It does not indicate that GTA grocery rents doubled over the preceding year.

Choice Properties’ results demonstrate the same issue differently. Its average Q2 renewal spread was 12.4%, rising to approximately 20% when fixed-rate options were excluded. Occupancy figures also depend on their definitions and denominators.

Morguard reported Q2 retail occupancy of 89.7%, including 95% at community centres and 87.8% at enclosed centres. At Cambridge, approximately 65,700 square feet was removed from active leasable area during redevelopment, changing the space against which occupancy is calculated. Committed occupancy, in-place occupancy, economic occupancy and renewal spreads are useful measures, but they answer different questions. Their definitions become particularly important when large spaces are moving through redevelopment.

Strong Leasing Can Coexist With Development Risk

SmartCentres reported 98.1% in-place and committed occupancy and had re-leased four of six former Toys “R” Us locations by the time of its Q2 call. Approximately 247,000 square feet of vacant space was leased during the quarter.

At the same time, the REIT recorded a $196.2-million fair-value loss on investment properties, reflecting market conditions and anticipated construction timing for certain future development properties, partly offset by lower discount rates at selected retail properties. Operating retail assets and future development properties can therefore produce very different results within the same portfolio.

The same applies to residential density associated with retail properties. Choice and RioCan described weaker conditions for selling residential density, while Primaris has emphasized that it intends to monetize suitable excess lands instead of becoming a residential developer. Long-term density can have value without contributing to current property income.

Editor’s Take & Outlook

What Retailers, Landlords and Investors Should Watch

For landlords redeveloping former anchors, rent commencement, capital requirements, tenant opening schedules and construction downtime will determine how quickly committed leasing becomes property income. Subsequent tenant sales and traffic will show how new uses affect the broader centre. Retailers considering former-anchor space need to account for landlord work, fit-out costs, possession dates, access during construction, neighbouring uses and the sequence of other openings.

For investors, high occupancy and strong renewal spreads remain important, but definitions matter. Committed space may not yet be producing rent, redevelopment can alter occupancy denominators, and unusually large rent increases can reflect leases that have not been reset to market for decades.

Capital requirements ultimately belong in the same analysis as the replacement rent being achieved.

Outlook: The Next Test Is Delivery and Cash Rent

The next several quarters will provide practical evidence of how Canada’s current leasing activity translates into operating property performance.

Primaris expects replacement tenants in former Hudson’s Bay space to begin taking occupancy in 2027, with other openings and rent commencements extending through subsequent years. At Galeries de la Capitale, tenants are expected to open progressively through 2027.

Splitsville is targeting fall 2027 at CF Sherway Gardens, while major new uses in Central Walk’s Vancouver Island redevelopment are expected in 2028.

At necessity-oriented properties, high occupancy and strong renewal spreads are already evident, while national rent growth is expected to moderate. Future results will show how durable those conditions remain across different markets and tenant categories.

The amount of space leased is one measure of progress. Openings, rent commencement and returns on invested capital will provide a more complete measure of the redevelopment cycle.

Editor’s Take

Canada’s strongest retail-property results can look remarkably good: occupancy approaching 100%, double-digit renewal spreads and major replacement leases for spaces vacated by department stores. Those numbers need to be read alongside what is happening inside the properties.

The former department-store redevelopment cycle is producing something structurally different from the anchors it replaces. One large box can become grocery, restaurants, entertainment and specialty retail, with each tenant requiring different space, investment and opening timelines.

That can ultimately produce higher rents and give consumers more reasons to visit a property throughout the day. The economics still depend on how much landlords and tenants spend to get there.

Over the next several years, the most revealing numbers may therefore come after the leasing announcements: stores opened, rent commenced, tenant sales and returns on redevelopment capital.

Those measures will show how successfully Canadian landlords have turned a historic wave of department-store vacancies into productive retail real estate.

Representative Articles

More From Retail Insider

Q3 2026 Discount & Off-Price: Transactions Rise as Value Competition Intensifies

As part of Retail Insider Reports, this Q3 2026 Discount & Off-Price Report analyzes Q3 2026 developments in Canadian discount and off-price retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping value-oriented retailers, suppliers, landlords, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines Canadian discount and off-price retail, including dollar stores, closeout retailers, liquidation formats, off-price apparel, and retailers competing primarily on price and value.

Executive Summary

Canadian value-oriented retailers produced strong transaction growth during Q3 2026, with Dollarama and TJX Canada both reporting more purchases through their stores. Dollarama’s Canadian comparable sales increased 5.4% in its fiscal second quarter, driven by a 3.7% increase in transactions and a 1.7% increase in average transaction size. TJX Canada, which operates Winners, Marshalls and HomeSense, reported comparable sales growth of 6%, driven primarily by increased customer transactions.

The two businesses sell very different versions of value. Dollarama combines low absolute prices with consumables, household products and general merchandise, while TJX’s off-price model is built around branded fashion and home merchandise. Both generated more transactions. Dollarama management said it could not quantify how much of its performance was attributable to trade-down, while consumer research during the quarter showed continued interest in value formats alongside improving discretionary-spending intentions.

Competition is also expanding. Dollarama raised its Canadian opening guidance, TJX continued pursuing regional and urban opportunities, discount grocers added stores and conversions, and Jumbo secured its first Canadian location at Vaughan Mills. Temu’s local-seller model is adding a domestic dimension to digital value competition.

Value is ultimately a purchasing judgment, not a single retail format. Retailers need to make it clear to customers while preserving the assortment, convenience and margins required to deliver it. Canadian value retail entered the second half of 2026 with strong transaction growth at two of the country’s largest value-oriented operators.

Several patterns emerged during the quarter:

  • Dollarama’s Canadian comparable sales increased 5.4%, including 3.7% transaction growth, while TJX Canada’s 6% comparable-sales increase was driven primarily by customer transactions.
  • The results support strong demand for value but do not establish widespread consumer trade-down. Dollarama management said the contribution from trade-down could not be quantified.
  • Value takes different forms across dollar stores, branded off-price retail, discount grocery, large-format general merchandise and digital marketplaces.
  • Dollarama’s $5 maximum price point is testing how effectively the retailer can manage sourcing, assortment and operating costs while maintaining its low-price positioning.
  • Physical expansion continues through Dollarama, TJX and new entrant Jumbo, although operating stores, announced locations and longer-term plans represent different stages of growth.
  • Temu’s Canadian local-seller model creates a digital competitor that can also serve as a sales channel for domestic merchants.

The next phase will test whether retailers can sustain customer transactions while maintaining the margins behind their offers.

Retail Insider Coverage

Value Seeking Does Not Necessarily Mean Trading Down

Strong value-retail performance can easily be interpreted as evidence that financially pressured consumers are moving downmarket. The company and consumer evidence presents a more complicated picture. Dollarama CEO Neil Rossy acknowledged that financial hardship can encourage customers to seek lower-priced options. Households under pressure can also reduce spending altogether, and management said it could not quantify how much of Dollarama’s performance was attributable to trade-down.

Consumer research during the quarter showed value seeking alongside greater willingness to spend. A July Stifel survey of 300 Canadian adults found that 75% expected to increase their dollar-store spending over the following 12 months, while discretionary-spending intentions also improved.

BCG research released in September similarly found that consumers across income groups seek value, although what justifies a purchase varies. Affordability and trusted essentials can matter heavily in one transaction, while quality, service or the purchase experience can carry more weight in another. TJX Canada’s performance adds another dimension. Winners, Marshalls and HomeSense are built around branded off-price fashion and home merchandise, much of it discretionary. A 6% comparable-sales increase driven primarily by transactions indicates continued willingness to buy those products when customers find the combination of merchandise and price attractive.

Consumers can become more value-conscious while remaining willing to spend.

Different Retailers Sell Different Versions of Value

The businesses grouped under the broad value category compete through substantially different propositions.

Dollarama combines low absolute prices with convenience and an assortment spanning cleaning supplies, snacks, household goods, stationery, toys and seasonal merchandise.

Winners, Marshalls and HomeSense give customers access to branded fashion and home merchandise at prices intended to compare favourably with conventional retail. Discount grocers including No Frills, Maxi, Food Basics and FreshCo compete heavily around frequent household purchases, where customers repeatedly encounter and compare prices.

Jumbo will bring a large-format version of value retail to Canada with an assortment spanning home products, seasonal merchandise, toys and general merchandise. Temu competes digitally through price, assortment and marketplace access, while its local-seller program allows Canadian inventory and merchants to participate in the platform. A household can use several of these businesses without treating them as substitutes. Someone might buy cleaning supplies at Dollarama, groceries at No Frills, branded clothing at Winners and an occasional product through Temu.

Dollarama’s $5 Ceiling Tests the Operating Model

Dollarama’s maximum $5 price point is one of the clearest expressions of its consumer positioning. Management said during the quarter that another price point above $5 was not necessary under current conditions and that the company intended to delay introducing one for as long as possible.

Maintaining that ceiling does not mean the assortment beneath it remains static. Individual prices, products, pack sizes and merchandise can change, while Dollarama can use sourcing, merchandising, logistics and store efficiency to manage cost pressures. The company maintained Canadian gross-margin guidance of 45.0% to 45.5% despite incorporating elevated oil and freight costs into its assumptions for the balance of the fiscal year. The guidance remains a forecast, and changing cost conditions could affect future results.

Dollarama therefore needs to maintain a credible low-price offer while managing costs and preserving margins that support its store network and continued expansion. The $5 ceiling should not be treated as an alternative measure of Canadian inflation. Dollarama’s assortment is not a fixed consumer basket, and changes to products, sizes and sourcing can occur without changing the maximum price point.

Dollarama Can Win Purchases Across Retail Categories

Dollarama’s assortment gives the chain competitive overlap with a wide range of retailers. Cleaning products and household supplies can compete with supermarkets, pharmacies and mass merchants. Snacks overlap with grocery and convenience stores, while stationery, toys and seasonal merchandise extend Dollarama’s reach into specialty and discretionary categories.

Dollarama does not need to replace another company’s entire shopping trip to gain spending. It can capture individual purchases that might otherwise have occurred across several retail formats. More transactions can increase Dollarama’s role in household shopping routines even when another retailer remains the primary destination for a broader category.

Store Expansion Adds More Value Competition

Dollarama ended its fiscal second quarter with 1,734 Canadian stores after adding 15 net locations during the period. It raised fiscal 2027 Canadian opening guidance to 65 to 75 stores from 60 to 70.

Management linked the revision to available opportunities and landlord delivery timing and cautioned against interpreting it as a permanently faster annual expansion rate. A Western Canadian logistics hub expected to become fully operational by the end of calendar 2027 is intended to support the network as it grows.

TJX is pursuing a different development model. A 42,500-square-foot combined Winners/HomeSense has been announced for Parsons Creek Town Centre in Fort McMurray, bringing the banners into the region for the first time. Construction and opening dates had not been announced during the reporting period.

TJX management has also referenced opportunities following Hudson’s Bay’s departure, although the company has not quantified how much former Bay spending has transferred to Winners, Marshalls or HomeSense.

Jumbo will add another large-format competitor when it enters Canada at Vaughan Mills. Fox Group secured the approximately 47,000-square-foot former Toys “R” Us lease near HomeSense/Winners and Hockey Life, with the opening currently targeted for early 2027.

Fox acquired the lease rather than the former Toys “R” Us Canada business, and Jumbo does not yet have Canadian operating results. Its Vaughan Mills store will provide the first domestic evidence of how Canadian consumers respond to the concept. The development models differ considerably. Dollarama can add relatively compact stores across a network exceeding 1,700 locations, while TJX can enter a regional market with more than 40,000 square feet. Jumbo is beginning with a large-format location at one of Canada’s major shopping centres.

Discount Grocery Extends the Value Battle

Canadian grocers are also directing development toward discount banners. Loblaw continued emphasizing No Frills and Maxi within its expansion plans, Metro announced the conversion of 10 Ontario supermarkets to Food Basics, and Empire’s FreshCo entered Atlantic Canada during the quarter. Some represent new locations, others involve banner conversions or acquired stores, and broader company investment programs can include other formats.

The common thread is increased investment in banners positioned around frequent household spending, extending value competition into one of the consumer’s largest recurring expenses.

Temu Is Becoming a More Local Competitor

Temu’s Canadian marketplace is adding a domestic component to a business commonly associated with cross-border e-commerce. Canadian merchants can list domestically held inventory for local fulfilment, while Temu’s Shopify integration allows participating merchants to synchronize products and inventory, manage fulfilment and receive marketplace orders through Shopify.

The scale of Temu’s Canadian local business remains unclear. PDD has not disclosed Canadian revenue, the proportion of Canadian orders fulfilled domestically or a new Canadian warehouse network in the reporting reviewed. Consumer surveys showing that Canadians have purchased from Temu measure adoption rather than market share and cannot establish how much spending has moved away from domestic retailers.

Inventory located closer to customers can reduce some of the delivery and returns disadvantages associated with cross-border e-commerce. Recruiting Canadian merchants also changes the competitive relationship: Temu can compete with domestic retailers for consumer attention while providing some businesses with another marketplace through which to sell. Physical retailers retain potential advantages in immediate product access, in-person service and returns, but those benefits need to remain meaningful relative to price and assortment.

Broader Industry Coverage

Transaction Growth Provides the Clearest Evidence

Statistics Canada’s July retail data showed general merchandise sales up 6.8% year-over-year in current dollars and 7.1% at constant prices. The category includes several types of retailers and does not separately measure dollar stores or off-price operators.

Company-specific results provide a clearer view. Dollarama’s 5.4% Canadian comparable-sales increase for the quarter ended August 2 consisted of 3.7% transaction growth and a 1.7% increase in average transaction size. Consumables and general merchandise performed strongly, while management also reported strength in toys and positive seasonal demand.

The Canadian figures are more useful for assessing the domestic business than Dollarama’s 17.6% consolidated sales increase to approximately $2.03 billion. That comparison included a full quarter of Australian operations versus only 13 days in the corresponding period a year earlier.

TJX Canada reported 6% comparable-sales growth for the quarter ended August 1, with management saying the increase was driven primarily by customer transactions. Winners, Marshalls and HomeSense sell a substantially different assortment from Dollarama, yet both businesses generated more purchases during their respective quarters.

TJX counts transactions at the register and does not use people counters, so increased transactions should not be described as measured store foot traffic. The common signal is that customers completed more purchases at both businesses.

Editor’s Take & Outlook

What Retailers and Landlords Should Watch

Transactions are one of the clearest measures to watch as value competition intensifies, alongside average transaction size, gross margin, merchandise mix and customer retention.

For Dollarama, the relationship between transactions, the $5 ceiling and gross margin will show whether the retailer can continue managing cost pressure without materially changing its visible price architecture.

For off-price retailers, transactions and merchandise performance can indicate whether customers continue finding enough branded discretionary merchandise at attractive prices to support repeat purchases.

Expansion introduces another consideration. New stores need to generate enough sales without excessive cannibalization, while announced locations and development targets should be separated from stores actually operating.

Landlords will also encounter very different space requirements. Dollar stores can provide frequent visits from relatively compact locations, off-price retailers can occupy much larger stores, and concepts such as Jumbo can provide new uses for large-format vacancies. Hudson’s Bay’s departure has created additional opportunities for retailers seeking larger footprints, although former department-store space will not suit every format or property.

Outlook: Can Transaction Growth Continue?

The next six to 18 months will show whether the current momentum continues as retailers add stores and work through changing supply-chain costs.

For Dollarama, transactions, average transaction size, gross margin and the $5 maximum price point will be important measures. Its revised opening range and Western logistics infrastructure will also show how the retailer is preparing for further Canadian development.

TJX Canada’s comparable sales and transactions will provide another measure of discretionary value demand. New locations and opportunities created by Hudson’s Bay’s departure could expand the network, while reported segment profitability and merchandise execution will remain important alongside sales growth.

Jumbo’s Vaughan Mills opening will provide the first Canadian evidence for its large-format concept. Temu’s Canadian seller adoption and domestic fulfilment will show whether localization becomes materially more important to consumers and merchants. Discount grocery development will continue adding another layer of competition around routine household spending. Across these formats, the central test is whether retailers can retain customer transactions while preserving the margins required to keep delivering value.

Editor’s Take

Canadian consumers clearly want value, but Q3 does not support a simple conclusion that financially pressured households are universally trading down.

Dollarama generated more transactions across an assortment that includes routine household goods and discretionary merchandise. TJX Canada also generated transaction-led growth through Winners, Marshalls and HomeSense, where branded fashion and home products remain central to the offer.

Consumers can become more selective about price while remaining willing to spend.

That creates competition well beyond traditional retail categories. Dollarama can capture a household purchase that might otherwise have gone to a supermarket or pharmacy. Winners can compete for a branded apparel or home purchase. A discount grocer can win the grocery basket, while Temu can compete for an individual online purchase.

Retailers do not need to replace an entire shopping trip to gain a larger share of household spending. Winning individual purchases more frequently can alter competitive dynamics.

Expansion by Dollarama, TJX and discount grocers, along with Jumbo’s arrival and Temu’s localization, will give consumers more opportunities to make those choices.

The harder part is sustaining what makes each offer attractive. Low prices need sourcing and margins that work. Off-price retail needs compelling merchandise. New concepts need enough transactions to support their stores.

Q3’s results show that consumers are responding to value across very different retail formats. Whether that momentum lasts will depend on retailers continuing to deliver prices, products and shopping experiences customers consider worth the purchase.

Representative Articles

More From Retail Insider

Q3 2026 Apparel & Fashion: Store Performance Ahead of Store Count

As part of Retail Insider Reports, this Q3 2026 Apparel & Fashion Report analyzes Q3 2026 developments in Canadian apparel and fashion retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping fashion retailers, brands, landlords, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines Canadian apparel and fashion retail, including clothing, footwear, accessories, department store fashion, specialty apparel retailers, merchandising strategies, consumer demand, expansion, and competitive developments.

Executive Summary

Canadian fashion retailers continued investing in physical stores through Q3 2026, but decisions increasingly depended on the performance of individual locations, assortments and customer groups. The broader apparel market remained relatively healthy. Statistics Canada reported seasonally adjusted sales at clothing and clothing-accessories retailers of $3.205 billion in July, up 5.5% from a year earlier despite a 0.5% decline from June. Constant-price sales increased 5.3% year-over-year, indicating that the annual growth extended beyond higher prices.

Company results were considerably more varied:

Aritzia reported Canadian revenue growth of 25% and continued investing in larger and repositioned boutiques, even as most new-store expansion shifted to the United States. Groupe Dynamite reduced its Canadian store count while renovating and relocating locations it intends to retain. Reitmans reported double-digit growth from two recently renovated or repositioned flagships despite weaker company-wide sales, and lululemon reduced assortment density after Canadian revenue declined.

Other retailers demonstrated that investment does not necessarily require more space. Kit and Ace relocated into a smaller store at CF Sherway Gardens and reported considerably better early performance. Harry Rosen replaced its more than 50,000-square-foot Bloor Street flagship with a 38,000-square-foot Yorkville location designed around a different mix of selling space, inventory, service and hospitality.

The common question is increasingly less about how many stores a retailer operates and more about what each location contributes. Canadian clothing-store sales remained higher year-over-year through the latest available Statistics Canada reporting, supporting continued investment in physical retail. Company-level results showed substantial differences in performance and expansion strategies.

Several patterns emerged during the quarter:

  • Retailers increasingly directed capital toward stronger locations instead of pursuing store-count growth alone.
  • Canadian-founded chains including Aritzia and Groupe Dynamite continued investing domestically while directing much of their incremental unit growth outside Canada.
  • Renovations, relocations and expansions became important sources of growth within mature Canadian networks.
  • Inventory allocation, regular-price sell-through and assortment performance became increasingly important measures of individual stores.
  • New brands reached Canadian consumers through mass retail, partnerships, digital-first expansion and selective standalone stores.
  • Physical locations added functions including fitting, repair, customization, resale, order pickup and returns, broadening the role of the store beyond transactions at the register.

The Canadian fashion market continues to support physical retail investment, but individual locations face a higher hurdle for capital and merchandise.

Retail Insider Coverage

Aritzia Concentrates Canadian Investment in Productive Markets

Aritzia provided one of the strongest Canadian operating performances reported during the quarter. Canadian revenue increased 25% to approximately $313 million in the first quarter of fiscal 2027. U.S. revenue increased 54.5% to approximately $638 million and represented 67.1% of company revenue.

The geographic split is increasingly important to Aritzia’s expansion strategy. The company expects to open 12 to 13 boutiques during the fiscal year, with 11 to 12 located in the United States. Canada nevertheless remains an important investment market. Aritzia returned to Vancouver’s Oakridge Park with an approximately 10,000-square-foot boutique and is developing a roughly 41,800-square-foot, four-level flagship at CF Pacific Centre.

Management has said new boutiques were paying back in less than one year on average, ahead of its 12-to-18-month target, with larger boutiques maintaining sales productivity. Those are company-wide economics and should not be assumed for every Canadian project, but they help explain substantial investments in selected locations. Aritzia’s Canadian strategy combines strong growth from existing operations with larger bets in proven markets, while the majority of incremental store-count growth occurs in the United States.

Groupe Dynamite Shrinks Its Canadian Network While Investing in Stronger Stores

Groupe Dynamite provides a different example of growth becoming separated from store count. Canadian revenue declined 1.9% to $145.1 million in the company’s second quarter, with 13 fewer stores than a year earlier. Management described Canadian comparable-store performance as approximately flat. U.S. revenue increased 52.2%.

During the quarter, Groupe Dynamite opened seven stores, six in the United States and one in the United Kingdom. It also renovated or relocated four Canadian stores while closing six. Company-wide retail sales per square foot increased 28.9% to $1,056, and inventory turnover improved to 7.72 times from 7.25 times.

The Canadian revenue decline needs to be viewed alongside deliberate changes to the network. Groupe Dynamite is operating fewer Canadian stores while continuing to invest in locations it intends to retain.

Its pull-based inventory model adds another dimension. Additional merchandise is directed toward stores producing stronger sales and full-price sell-through, meaning highly productive international locations can compete with smaller Canadian stores for limited inventory.

For landlords, company-wide growth does not guarantee equal investment across a retailer’s portfolio. An individual store’s sales, sell-through and strategic importance can influence both the merchandise it receives and the capital committed to the location.

Existing Stores Face a Higher Investment Test

Reitmans provides another version of the same shift. Company revenue declined 1.9% to $211.8 million in the second quarter, while comparable sales including e-commerce fell 1.5%. Yet the new-concept Reitmans store at CF Carrefour Laval and renovated RW&CO flagship at CF Toronto Eaton Centre each generated double-digit year-over-year sales growth.

Gross margin increased 160 basis points to 58.5%, while inventory declined 5.2%. Management cited stronger regular-price selling and fewer markdowns as contributors to the improvement. Reitmans plans to invest approximately $100 million over five years, with roughly three-quarters directed toward stores. It expects to increase retail square footage by approximately 10% while maintaining a network of roughly 400 locations. The strategy calls for more and better space without relying on a substantial increase in store count. Its wider rollout will test whether gains at prominent renovated and repositioned stores can be reproduced across the network.

Kit and Ace offers a smaller example. Its relocated CF Sherway Gardens store decreased from approximately 3,000 to 2,370 square feet, but CEO David Lui told Retail Insider that early performance had improved considerably. The new location placed the retailer in a stronger fashion corridor between Rodd & Gunn and L’Oro Jewellery. The comparison is early and management-reported, but it demonstrates why location quality and store configuration can matter more than absolute square footage.

Harry Rosen applied a related approach on a larger scale with its September opening at 153 Cumberland Street in Toronto’s Yorkville neighbourhood. The 38,000-square-foot flagship replaced a Bloor Street store exceeding 50,000 square feet, with greater emphasis on organized back-room inventory, private appointments, hospitality and flexible merchandising. “Every trip to the store has to be worth it,” Ian Rosen told Retail Insider.

The project is part of Harry Rosen’s broader $50-million network investment program. In each case, retailers are changing the amount, location or function of space instead of simply adding stores.

lululemon Reworks Its Canadian Store Proposition

Lululemon provides an important counterpoint to the stronger results reported by some Canadian apparel retailers. Canadian revenue fell 11% in its second quarter of fiscal 2026, or 9% in constant currency, following a decline of approximately 3% in the first quarter.

Management cited weaker traffic, conversion pressure and inconsistent product performance. Its response includes reducing the number of SKUs in North American stores by approximately 15%, introducing more localized assortments and adjusting merchandise presentation.

The company is still investing in selected Canadian locations. Its approximately 11,600-square-foot Montreal relocation and new Oakridge Park concept demonstrate continued investment in major established markets even as the global net-opening plan was reduced from approximately 40 to 35 stores.

The comparison with Aritzia is informative without being direct. The companies operate different businesses and report different fiscal periods, but their Canadian results show that broader apparel demand alone does not determine company performance. Product relevance, assortment, inventory, brand momentum and store execution remain important variables. Lululemon’s assortment and presentation changes will need to produce stronger Canadian results before their effectiveness can be assessed.

Competition Expands Through New Distribution Models

The competitive field is widening without every brand building a conventional standalone store network. Esprit returned to Canada in July through select Walmart stores and Walmart’s digital channels, giving the international brand national reach without recreating the Canadian chain it once operated.

Caulfeild Apparel Group moved in another direction with HANK., opening stores at Bayview Village in Toronto and Upper Canada Mall in Newmarket. The concept combines established brands, international labels and proprietary collections, giving the longtime wholesaler direct access to consumers and a testing environment for brands it eventually intends to offer through wholesale.

Knix entered Atlantic Canada at Halifax Shopping Centre, drawing on an existing online customer base while adding in-person fitting for bras, swimwear and other products. Intimissimi and Calzedonia were preparing to enter Canada at quarter-end, with their first separate stores targeted for CF Sherway Gardens in October and CF Toronto Eaton Centre expected to follow in May 2027. Canadian partner ILT Group sees potential for at least 20 leading shopping centres, with subsequent expansion dependent on early performance and operating capacity.

Changes in ownership are creating additional distribution possibilities. Under the proposed Roots transaction announced in August, JM&A would operate the core North American business while Marquee Brands pursued international development. At OVO, Authentic acquired majority ownership of the intellectual property and Vince took responsibility for the operating business.

The eventual results of those transactions remain to be seen. Together, these developments show how fashion brands can combine owned stores, wholesale, mass retail, licensing, partnerships and e-commerce according to market and operating requirements.

Stores Take On More Commercial Functions

Fashion stores are also performing functions extending beyond the initial sale. UNIQLO’s renovated Montreal Eaton Centre flagship added customization, embroidery and repair services. Arc’teryx’s 9,599-square-foot Montreal Alpha Store devoted substantial space to ReBIRD repair, product care and resale, while lululemon brought its Like New peer-to-peer resale platform to Canada in August.

Stores can also broaden the merchandise customers associate with a brand. Canada Goose said apparel, rainwear and windwear represented nearly 40% of revenue during its first fiscal quarter, when lighter products naturally account for a larger share of sales.

Quartz Co. has described its owned stores as a way to showcase lightweight outerwear, knitwear and accessories that receive less exposure from wholesale partners focused primarily on parkas. Its planned 1,200-square-foot Notre-Dame Street boutique in Montreal gives the company another outlet for that wider assortment.

Repair, resale, customization and broader product presentation may support retention, customer acquisition and repeat visits. The Canadian disclosures reviewed for this report did not quantify the incremental profit or retention produced by these services, leaving their commercial value to be measured against usage, staffing requirements and operating costs.

Broader Industry Coverage

Healthy Apparel Demand Doesn’t Guarantee Every Retailer Growth

Statistics Canada’s July retail data showed continued growth in Canadian clothing sales. Seasonally adjusted sales at clothing and clothing-accessories retailers reached $3.205 billion, up 5.5% from July 2025. Constant-price sales increased 5.3%, while clothing prices in August were 1.1% lower than a year earlier. The broader clothing and footwear consumer-price category increased 1.2%. Performance differed elsewhere in the sector. June commodity data showed clothing sales across retailer types up 8.0% year-over-year and footwear up 3.3%, while July revenue at shoe retailers declined 1.2%.

Wholesale activity was stronger. Textile, clothing and footwear wholesale sales increased 16.8% year-over-year in July, with inventories up 21.1%.

Those figures cover different parts of the supply chain and different reporting periods. Higher wholesale sales and inventories show more merchandise moving through the system without establishing equivalent consumer sell-through.

Positive Canadian apparel demand did not produce uniform results across retailers, categories or locations.

Omnichannel Complicates the Measurement of Store Performance

Traditional sales-per-square-foot measures capture only part of what a modern fashion store contributes.

Inditex reported that approximately 60% of online returns occurred through stores and about 20% of online orders were collected in-store. Those figures are global and do not establish Canadian Zara performance, but they demonstrate the operational role physical locations can play within an integrated retail network.

Stores may generate sales directly while also supporting digital purchases, accepting returns, facilitating pickups, providing fitting and product advice, and introducing customers to merchandise they later purchase elsewhere in the retailer’s network.

Four-wall performance is therefore more complicated to assess. Retailers still need to distinguish genuine omnichannel contribution from locations whose broader activity does not justify occupancy and operating costs.

Editor’s Take & Outlook

What Retailers and Landlords Should Watch

Store count alone provides an incomplete measure of fashion-retail strength. Sales per square foot, regular-price sell-through, inventory turns, conversion, transactions, average basket and markdown rates provide a more detailed view of store economics. Pickup, returns and other digital interactions can help establish how a location contributes to the wider network.

For landlords, capital allocation may be especially revealing. Groupe Dynamite is expanding internationally while reducing its Canadian store count. Aritzia is producing strong Canadian growth while directing most new openings to the United States. Reitmans plans to increase square footage while maintaining roughly the same number of locations. Kit and Ace reports stronger early results after moving into a smaller store.

A successful retailer may therefore have very different plans for individual properties within the same Canadian portfolio. Renovations, expansions, relocations, closures and merchandise allocation provide clues to how retailers rank locations within their networks. As international expansion gives Canadian companies more places to deploy capital, domestic stores may increasingly compete with locations outside Canada for investment.

Outlook: The Next Tests Are Already Visible

Several strategies introduced or expanded during Q3 will produce clearer evidence over the coming quarters. Reitmans will need to determine whether gains at its renovated and new-concept stores can be reproduced as its wider investment program advances. Lululemon’s reduced SKU count, localized assortments and presentation changes need to translate into stronger Canadian traffic, conversion and sales.

Intimissimi and Calzedonia will provide an early test of another international fashion operator’s appetite for Canadian physical retail. Quartz Co.’s additional Montreal location will help demonstrate whether owned stores can broaden customer demand beyond its core outerwear products.

Groupe Dynamite’s Canadian network optimization will continue alongside international expansion. Aritzia will test whether increasingly large Canadian boutiques maintain strong economics as most new stores open in the United States.

Tariffs and cross-border costs remain additional variables. Company disclosures during the quarter showed different effects and different capacities to absorb them, providing little basis for a single sector-wide conclusion.

The more useful evidence will come from individual stores and merchandise: where retailers invest, how effectively inventory turns, how much product sells at regular price and whether locations generate sufficient returns to continue attracting capital.

Editor’s Take

Canadian apparel retail entered Q4 with healthy overall clothing sales and increasingly selective investment at the company level.

Aritzia is generating strong Canadian growth while directing most incremental openings toward the United States. Groupe Dynamite is expanding internationally while closing weaker Canadian stores and reinvesting in others. Reitmans intends to increase square footage while keeping its store count roughly stable. Kit and Ace reports better early performance from a smaller relocated store, while lululemon is reducing assortment density after weaker Canadian results.

Store count tells less of the story than it once did. A retailer can close locations while improving its overall economics, increase square footage without materially increasing store count, relocate into smaller space and report better performance, or generate substantial Canadian growth while opening most new stores internationally.

Physical locations are also performing a broader range of functions. Returns, pickup, repair, customization, resale, fitting, service and product discovery can contribute to the value of a store beyond transactions completed at the register.

For retailers, the challenge is determining what each location contributes and whether that contribution justifies continued capital, inventory and operating resources. For landlords, the strength of a retail brand provides only part of the answer. The position of an individual property within that retailer’s network increasingly matters.

Canadian fashion retailers are still investing in stores. The more revealing question is where they are investing, where they are pulling back and what individual locations need to deliver to keep attracting capital.

Representative Articles

More From Retail Insider

Q3 2026 Consumer Behaviour / Retail Economy: Spending Holds Up as Shoppers Become More Selective

As part of Retail Insider Reports, this Q3 2026 Consumer Behaviour / Retail Economy Report analyzes Q3 2026 developments in Canadian consumer spending, purchasing behaviour, and the retail economy. Drawing on Retail Insider coverage, industry research, government data, and broader market signals, it identifies key dynamics shaping households, retailers, landlords, and consumer-facing businesses. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines changes in Canadian consumer behaviour, including shopping habits, spending priorities, demographics, loyalty, purchasing decisions, and evolving customer expectations; and macroeconomic conditions affecting Canadian retail, including retail sales, inflation, employment, consumer confidence, interest rates, tariffs, trade, and other economic indicators.

Executive Summary

Canadian consumers continued spending through Q3 2026, but aggregate resilience concealed substantial differences in financial circumstances and purchasing behaviour.

Statistics Canada reported July retail sales of $73.7 billion, down 0.7% from June but 5.1% higher than a year earlier. Retail sales volumes were up a more modest 1.7% year-over-year, illustrating the difference between growth in dollars spent and growth in the amount of merchandise consumers were buying.

More recent indicators suggested spending strengthened again in August. Statistics Canada’s advance estimate pointed to a 1.3% increase in retail sales, while RBC cardholder data showed spending growth broadening across discretionary goods and services.

Those figures coexisted with substantial household financial pressure. Surveys conducted during and immediately before the quarter found consumers using more credit for essentials and drawing on savings for everyday expenses, with younger households and families with children reporting considerably greater pressure than older consumers and households without children.

Value seeking remained widespread, but its meaning varied. Some consumers prioritized lower prices, promotions and private-label products. Others continued spending on quality, convenience, service and discretionary experiences.

For retailers, retaining a customer does not necessarily mean retaining every purchase. Canadian consumer spending remained resilient through an uneven Q3, while household financial pressure produced greater differences in how consumers allocated their money.

Several patterns emerged:

  • Retail sales remained higher than a year earlier, although growth in sales volumes was considerably lower than growth in dollar sales.
  • Financial pressure was concentrated among particular households, especially younger consumers and families with children.
  • Value seeking remained widespread without producing a universal shift toward discount retailers.
  • Consumers adjusted purchases through promotions, private label, product substitution and price comparison without necessarily abandoning their preferred retailer.
  • Physical stores remained important, particularly when consumers wanted immediate product availability.
  • Spending patterns varied significantly by category, income and shopping mission.

For retailers and landlords, topline sales provide only part of the picture. Transactions, units, basket composition, customer mix and repeat purchasing can reveal changes in demand that revenue alone may obscure.

Retail Insider Coverage

Household Financial Pressure Is Increasingly Uneven

Aggregate spending provides limited insight into the financial position of individual Canadian households. The MNP Consumer Debt Index released in July found that 61% of respondents had at least half of their income committed before receiving it. Some 46% said they were $200 or less away from being unable to meet monthly bills and debt obligations, up three percentage points from the previous quarter. At the same time, the overall index improved four points to 91. Confidence improved even as many households retained little room for unexpected expenses.

Equifax’s August survey showed how uneven that pressure had become. Among 1,532 respondents, 29% said they were using more credit than a year earlier for groceries, utilities and other essentials, while 23% were drawing on savings for everyday costs.

Families with children reported considerably greater pressure. Forty-two per cent said they were using more credit for essentials, compared with 24% among households without children. Thirty-six per cent of respondents under 55 reported greater credit use for essentials, compared with 18% among consumers aged 55 and older.

Yet 56% of all respondents expected to pay their credit-card balances in full each month, reinforcing the divide between financially constrained households and consumers retaining greater spending capacity.

Consumer insolvencies provide a more severe measure of financial stress. Office of the Superintendent of Bankruptcy figures reported during the quarter showed 37,523 consumer insolvencies during Q2, up 6.9% from a year earlier and the highest quarterly count since 2009. The figure was not a population-adjusted record, and the 2025 annual insolvency rate remained below its 2024 level.

Some households are relying more heavily on credit or savings to meet ordinary expenses, while others retain considerable financial flexibility.

Value Doesn’t Simply Mean Cheap

Financial pressure has made value an important consideration across income groups, but its meaning varies considerably. “Value is the number one factor for every income group as everyone is value-seeking right now,” BCG’s Terence Smith told Retail Insider. For one customer, value may mean the lowest available price. Another may place greater weight on quality, durability, installation, service or convenience.

BCG’s research showed significant differences in spending by category and income. Higher-income households spent two to four times as much as lower-income households in some major categories, while spending on household appliances was more evenly distributed. Pet care, despite its reputation as a dependable everyday category, leaned more heavily toward higher-income consumers willing to pay for premium products.

BCG’s six-month spending intentions showed weaker dining participation among lower-income households, while higher-income demand held up better. Automotive and beauty intentions were improving across income groups, with higher earners moving faster.

A Stifel survey of 300 Canadian adults provided a counterpoint to an exclusively cautious consumer narrative. It found that 57% expected to increase discretionary spending over the following year, up from 52% in April. Dollar-store spending intentions were particularly strong at 75%, while apparel intentions improved and furniture weakened.

Consumers may spend more while becoming more demanding about value. For retailers, price architecture, product quality, pack sizes, promotions and service need to reflect the customers actually buying within a category. Broad discounting may increase transactions without necessarily improving the economics of the customer relationship.

Retailers Can Keep the Customer and Lose the Basket

Grocery shopping provides one of the clearest examples of how consumer selectivity can change purchasing behaviour without producing an obvious change in retailer loyalty.

Milesopedia research reported during the quarter found that 71.1% of respondents were comparing prices more frequently and 39.1% were buying more private-label products. Only 9.6% said they had changed their preferred retailer. The study was small and heavily concentrated in Quebec. Its 203 respondents were recruited through a newsletter and Facebook community, approximately 83% were in Quebec, and participants were particularly familiar with loyalty programs. The results should not be treated as a national measure of retailer switching. The behaviour it describes is nevertheless useful. Shoppers may remain regular customers while buying more private label, waiting for promotions, substituting products, reducing discretionary additions or purchasing selected categories elsewhere.

Canadian grocery operators reported different outcomes during the quarter. Loblaw said food traffic and basket growth remained positive in its second-quarter results, with hard-discount comparable sales close to 4%. Management continued to describe customers as focused on value.

Empire’s September results call presented a different picture. Management said its full-service business was gaining share while discount was holding share and described consumer behaviour and promotional intensity as broadly stable.

The evidence supports continued demand for affordability without establishing a universal migration from conventional supermarkets to discount. Customer retention may therefore remain stable while the composition and profitability of the basket changes underneath it.

Shopping Mission Can Matter as Much as Channel

The purpose of a shopping trip can be as important as the channel a customer uses. Research from the Retail Council of Canada and Leger examined task-driven, inspiration-led and problem-solving shopping journeys using a survey of 2,014 Canadian shoppers and follow-up focus groups. The same consumer behaved differently depending on what they were trying to accomplish.

Physical retail remained prominent across those journeys. In-store browsing was used by 66% of respondents during research, while 58% ultimately completed their purchase in a store. Among task-driven shoppers, 70% purchased in-store and 71% took the product home the same day.

Immediate availability remains one of physical retail’s clearest advantages. Thirty per cent of respondents had encountered an out-of-stock item or limited availability, while 37% said they switch retailers when an item is unavailable.

Inventory accuracy, accessible staff and dependable fulfilment can determine who captures an individual transaction. A retailer may also contribute to discovery or product evaluation even when the eventual transaction occurs through another channel, making channel-specific attribution an incomplete measure of the store’s contribution.

Discovery Becomes More Fragmented

Artificial intelligence is adding another layer to the shopping journey, although its current role remains relatively small. The RCC and Leger research found that 11% of respondents had used AI during shopping research, while just 1% began their journey there.

Separate Retail Insider reporting on AI discovery research described consumers using AI tools to ask questions around a situation, intended use or problem instead of beginning with a specific product. That behaviour increases the importance of accurate product specifications, sizing, availability information and credible reviews across retailers’ digital channels.

Different studies currently define AI shopping adoption differently, making it premature to combine individual findings into a single growth measure. For now, AI is an additional discovery channel within an already fragmented customer journey.

Broader Industry Coverage

Category Performance Shows Why Averages Mislead

Statistics Canada’s July retail data demonstrated how differently categories can perform within the same consumer economy. General merchandise sales fell 1.9% from June but remained 6.8% above a year earlier. Health and personal care sales were up 12.2% annually, while the combined furniture, home furnishings, electronics and appliances category declined 4.9%.

Individual company results showed similar differences. Pet Valu reported approximately flat same-store sales in its second-quarter results, with weaker transactions offset by larger baskets. Management said it saw almost no movement between mass and specialty channels.

Cineplex reported attendance growth of 9.3% for the same calendar quarter while recording softer results in its location-based entertainment business. The results illustrate why aggregate consumer spending can obscure changes in transactions, basket size, categories and purchase occasions. For retailers, landlords and investors, national retail growth is a starting point for assessing demand, with company and category performance providing the more detailed picture.

Inflation Slows, but Higher Prices Remain

Grocery-price inflation slowed to 2.8% year-over-year in August, below the 3.0% headline Consumer Price Index, but grocery prices remained approximately 29% above August 2021 levels. Slower inflation reduces the pace at which household costs are rising. It does not reverse the accumulated increase consumers have already absorbed.

That helps explain why value seeking can persist even as inflation moderates. Households continue making purchasing decisions against a considerably higher cost base than several years ago.

Editor’s Take & Outlook

What Retailers and Landlords Should Watch

Topline sales can conceal meaningful changes in underlying demand. A retailer may report higher dollar sales while moving fewer units, becoming more dependent on higher-income households, selling a larger share of promotional merchandise or losing individual categories from existing customers’ baskets.

Transactions, units, average basket size and basket composition provide additional insight. Private-label penetration and promotional dependency can show how customers are managing price, while repeat purchasing and retention by customer cohort can reveal whether apparently stable demand is becoming concentrated among particular households. Inventory availability deserves similar attention. When customers switch retailers because an item is unavailable, in-stock performance becomes part of customer retention.

For landlords, the same distinctions matter when evaluating tenant and category performance. Rising sales do not necessarily mean customer counts, unit demand or participation across income groups are strengthening at the same pace.

Outlook: Employment Becomes a Key Variable

The labour market will be important in determining whether differences in household purchasing power widen further. Employment fell by 42,000 in August after a cumulative increase of 181,000 between April and July, while the unemployment rate held at 6.4%. One monthly decline does not establish sustained deterioration, but continued weakness would place additional pressure on households already using credit or savings for everyday expenses.

Retailers also need to distinguish anticipated cost pressures from costs that have reached consumers. RBC’s food-price analysis noted that energy and fertilizer shocks can take months to move through supply chains, while competition and demand influence how much businesses ultimately pass through.

On its September results call, Empire said the impact of new tariffs remained minimal at that point and that it had received only a handful of supplier cost submissions. Potential cost increases remain relevant to the outlook, with their effect on retail prices dependent on how much reaches businesses and how those businesses respond.

Over the coming quarters, employment, transactions, unit volumes, basket composition and purchasing behaviour by customer cohort will help show whether spending resilience is broadening or becoming more dependent on households with greater financial flexibility.

Editor’s Take

Canadian consumers continued spending in Q3 2026, but the headline numbers concealed substantial differences between households and individual purchasing decisions. Some Canadians were using credit or savings to fund groceries, utilities and other essentials, while others retained significant discretionary capacity. Some consumers sought hard-discount formats, while full-service grocery operators continued reporting competitive performance. Spending intentions improved in certain discretionary categories even as value remained a priority.

Consumers can also remain loyal to a retailer while becoming much more selective about what they buy there. A supermarket customer may purchase more private label, wait for promotions or move individual products to a competitor. A task-driven shopper may choose a physical store because the product is immediately available, then switch retailers when it is out of stock.

Retailers are competing over individual items, occasions, trips and baskets alongside the broader customer relationship. Price, availability, convenience, service and product quality all matter, with their relative importance changing according to the customer and the purpose of the purchase.

That makes the composition of demand increasingly important. Transactions, units, basket mix and customer cohorts can reveal changes that topline sales alone may conceal.

In a more selective market, knowing that a customer still shops with a retailer tells only part of the story. Retailers also need to understand which purchases they are keeping, which ones they are losing and why.

Representative Articles

More From Retail Insider

Q3 2026 Luxury: Flagship Investment, Space and Service

As part of Retail Insider Reports, this Q3 2026 Luxury Report analyzes Q3 2026 developments in Canada’s luxury retail market. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping luxury brands, multi-brand retailers, landlords, and consumers. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines Canada’s luxury retail market, including brands positioned at the highest end of the market and characterized by exceptional craftsmanship, heritage, exclusivity, prestige, scarcity, and highly personalized customer experiences. Coverage includes luxury fashion, jewellery, watches, beauty, accessories, and related retail developments.

Broad Overall Themes

Canadian luxury retail attracted substantial investment during the third-quarter reporting period, with established operators changing how stores work and international brands committing to carefully selected locations. Harry Rosen opened a 38,000-square-foot Yorkville flagship, Chrome Hearts bought a Toronto building for its first Canadian store, and Fendi established its only standalone Canadian boutique at Vancouver’s Oakridge Park. The activity was concentrated in particular properties and customer groups, alongside closures, financial restructuring and more selective expansion.

This report covers high-end designer fashion, jewellery, watches, accessories and related Canadian retail destinations, with selected resale and accessible-luxury comparisons where they clarify the competitive market. It examines Retail Insider coverage published from Jul 1, 2026 to Sep 30, 2026, together with selected company earnings calls released during that period and Statistics Canada information available on Oct 1, 2026. Some reported openings occurred before July, company results cover different fiscal periods, and the official statistics do not isolate luxury retail or provide a complete July-to-September sales measure.

The clearest pattern was a greater emphasis on controlling the customer experience, supported by specific changes to property, merchandise and service. Brands sought dedicated stores and, in Chrome Hearts’ case, property ownership. Multi-brand retailers invested in flexible presentation, deeper inventory, private appointments and partnerships that give customers reasons to visit repeatedly.

The investment also followed identifiable concentrations of demand. Bloor-Yorkville and Vancouver’s downtown luxury district continued to attract commitments while Oakridge Park broadened Vancouver’s options. Affluent residential neighbourhoods and resort hotels offered additional opportunities, although individual store announcements do not establish a national expansion in luxury spending.

Official data provide useful context without resolving that question. In July, seasonally adjusted sales at Canadian jewellery, luggage and leather goods retailers rose 15.9% year over year but fell 4.3% from June, according to Statistics Canada’s Sep 24, 2026 retail release. That category combines price tiers and merchandise types, so its growth cannot be presented as a luxury-market growth rate. The monthly decline also cautions against treating the annual comparison as evidence of uninterrupted momentum.

Retail Insider Coverage

Harry Rosen changes the economics of its flagship

Harry Rosen’s new store at 153 Cumberland Street provided the quarter’s most detailed example of a retailer reallocating space around service. Opened in September, the three-level, 38,000-square-foot flagship replaced the five-level store of more than 50,000 square feet at 82 Bloor Street West. The project is the centrepiece of the company’s previously announced $50-million, five-year Canadian store investment program; that amount is not the cost of Cumberland alone.

The smaller footprint incorporates considerably more space behind the selling floor. President and CEO Ian Rosen estimated that inventory occupied about 5% of the former store, compared with approximately 20% to 30% at Cumberland. Deeper stock rooms are intended to support a less crowded presentation while keeping sizes available, making efficient merchandise retrieval an important part of the service model.

Private selling, made-to-measure, events and hospitality occupy substantial space, while fewer fixed branded environments allow merchandise presentations to change more frequently. “Every trip to the store has to be worth it,” Rosen told Retail Insider. Landlord KingSett Capital also said approximately 32,000 square feet of former office space was converted to retail, demonstrating a practical way to create a large flagship within an established luxury district.

Toronto investment spreads beyond Bloor frontage

Chrome Hearts’ $12.65-million purchase of 121 Scollard Street established another form of commitment. The approximately 7,076-square-foot former Webster building gives the privately held brand control of a freestanding property for its first standalone Canadian store. The purchase replaced an earlier plan for nearby 97 Scollard Street, which had been affected by a fire across the street; no opening date had been announced in the reporting reviewed.

Together with Harry Rosen’s move, the transaction extends Yorkville’s luxury activity beyond Bloor’s principal storefronts. Investment on Bloor itself also continued: September reporting identified Tiffany & Co.’s approximately 15,000-square-foot replacement flagship at 66 Bloor Street West as under construction, with an early-2027 opening expected. Both projects add to the district’s investment pipeline, although the reporting did not identify either as an operating new store.

A separate customer-led expansion was visible in Summerhill. Absolutely Fabrics opened 7,000 square feet at 1091 Yonge Street, adding menswear and space for established designers, emerging labels and archival vintage. Founder Kaelen Haworth had already developed customers in nearby affluent neighbourhoods through the Queen West business. The expansion therefore rested partly on existing relationships; busy opening-weekend traffic was encouraging but offered no reliable measure of long-term productivity.

Vancouver supports different luxury destinations

Fendi’s Oakridge Park boutique spans more than 1,689 square feet and carries women’s and men’s ready-to-wear, leather goods, footwear and accessories. It became the brand’s only standalone Canadian store following the closure of its temporary Yorkdale location, while department-store boutiques remained in Vancouver, Toronto and Montreal. Its assortment can also include fur products that Holt Renfrew no longer sells, illustrating how distribution format can affect what a brand offers customers.

Oakridge’s appeal extends to established local operators. July reporting examined Vestis Fashion Group’s May 28, 2026 return with a 3,160-square-foot Max Mara boutique and a 1,836-square-foot Weekend Max Mara store. The stores introduced exclusive collections and brought Vestis to eight Metro Vancouver locations, but vice-president of retail Harriet Guadagnuolo said the immediate priority was strengthening the expanded business before adding more stores. The operator’s comments temper any assumption that a successful opening necessarily leads to an immediate rollout.

Downtown Vancouver continued to attract investment as well. Longines was preparing its first Canadian boutique at 765 Burrard Street, with just over 1,000 square feet near Cartier and the established Alberni watch cluster. Its more accessible luxury-watch positioning adds a different price point within that district. At the same time, July coverage documented St. John’s June closure at the Fairmont Hotel Vancouver, ending its standalone Canadian presence. Vancouver’s activity includes entries, relocations and exits, rather than uniform growth across operators.

Hospitality and appointments broaden the store’s role

Luxury investment also moved into a resort setting. Brunello Cucinelli agreed to take space at Fairmont Château Whistler as Oxford Properties sought to strengthen the hotel’s retail mix. Leasing materials identified the existing Snowflake premises at approximately 1,880 square feet within an approximately 11,000-square-foot concourse. The planned boutique gives the brand access to a visitor-driven market, while Oxford can extend existing retailer relationships into its hospitality portfolio.

In Toronto, Bang & Olufsen’s 2,100-square-foot store at 135 Yorkville Avenue combines private demonstrations, customization and residential-design consultations. Its operator identified home integration and relationships with architects and developers as opportunities alongside conventional retail purchases. These examples show why a location’s value may depend on access to particular clients and projects as well as passing pedestrian traffic.

Holt Renfrew used a different approach at 50 Bloor Street West. The Mercedes-Benz Studio, installed in a former Saint Laurent concession, changed from an AMG and Reigning Champ summer presentation to a September installation featuring the S-Class and Paul & Shark. The completed refresh demonstrates a repeatable programming format, although the reporting does not establish its effect on store sales or customer retention.

Growth figures need operating and financial context

Birks’ results illustrate why revenue growth needs closer examination. For the fiscal year ended Mar 28, 2026, reported during the quarter, sales increased 15.5% to $205.4 million while comparable-store sales rose 2.6%. The European Boutique acquisition contributed materially to the headline increase, alongside growth in proprietary and third-party jewellery.

Retail Insider’s August financial analysis reported operating income of $3.1 million, but interest and other financing costs of approximately $8.8 million and a remaining net loss of $3.4 million. Refinancing extended principal lending arrangements to 2031 and provided more time for investment and operational improvement. It did not remove the financing burden, and the announced move from NYSE American to OTCQB was not a decision to close Canadian stores.

Birks continued to develop its own jewellery identity and selected brand partnerships. Its planned Oakridge Birks boutique, operation of Chaumet there, and reconfiguration of Bloor Street premises demonstrate several approaches to distribution. The quarter’s Sophie Nélisse campaign also focused attention on proprietary collections, an area where Birks can exercise more control as international houses develop their own boutiques.

Canada Goose’s first-quarter fiscal 2027 results also require more than a headline reading. Total revenue rose 10.3% for the period ended Jun 28, 2026, but direct-to-consumer comparable sales fell 3.2%, while wholesale revenue increased 66.5% partly because of order-book growth and shipment timing. The company reported progress in apparel, rainwear and windwear as it pursued year-round relevance. Those global results support a discussion of assortment development and channel mix, without establishing a comparable increase in Canadian consumer demand.

Resale and emerging brands build physical connections

Mine & Yours’ anniversary coverage described the operating demands behind luxury resale’s development. The retailer must acquire desirable merchandise from consumers as well as sell it, using appointments, online quotes, closet purchases, cash, credit and consignment options. Its Calgary relationship with Holt Renfrew allows eligible sellers to choose department-store credit, creating a potential connection between previously owned goods and new purchases.

Holt Renfrew also provides a physical introduction for smaller Canadian labels. September reporting detailed STEFF ELEOFF’s planned Yorkdale and Bloor pop-ups, beginning in October and November respectively, with exclusive merchandise and an environment intended to let customers handle and try jewellery. These are announced fourth-quarter activations, not completed Q3 openings. They offer a way to test customer response without committing immediately to a permanent store.

Broader Industry Coverage

Global earnings calls reinforced the importance of separating luxury segments and individual business models. In its July call, Prada Group reported first-half revenue growth of 16% at constant exchange rates including Versace, compared with 5% organically. Americas retail growth was 17% organically, but no Canadian result was disclosed. Management emphasized top-spending clients, stable entry prices and a wider price range, while acknowledging uneven conditions across markets.

Brunello Cucinelli reported first-half revenue growth of 13.3% at constant exchange rates and 9.5% at reported rates. Its management explicitly rejected an entry-price strategy and described selective store expansion as part of preserving exclusivity. Those comments provide context for its Canadian investments, but Americas growth cannot establish the performance of the brand’s Canadian stores or forecast demand at Whistler.

HUGO BOSS offered a counterpoint. Second-quarter currency-adjusted revenue declined 9% while gross margin increased by 200 basis points, as the company pursued assortment simplification, fewer markdowns and network optimization. Management reported 21 net store closures globally in the first half. The results show that improved merchandising economics can accompany lower sales, without establishing either a Canadian retrenchment or a general luxury recovery.

Coach operates at a different price position and reaches a broader audience. Its fourth-quarter constant-currency sales rose 14%, including 10% in North America, while handbag average unit retail increased at a mid-teens rate and units were approximately flat. Retail Insider identified 29 Canadian locations, but Tapestry did not specify Canadian stores receiving its newer design concept. Planned global fleet investment is relevant to that network, although it cannot yet be described as a confirmed Canadian renovation program.

Editor’s Take & Outlook

The quarter’s most useful evidence concerns the choices behind investment: control of property and distribution, the amount of space assigned to inventory and appointments, the selection of locations with established clients, and the ability to change a store’s presentation. These choices create different tests for performance. Harry Rosen must convert additional service capacity and cleaner selling floors into worthwhile visits; Birks must translate operating improvement into earnings after financing costs; new boutiques need to establish productivity beyond their opening periods.

The next phase will provide further evidence. Tiffany’s replacement Bloor flagship remains an early-2027 project in the reporting reviewed, Longines and Chrome Hearts had not announced opening dates, and Brunello Cucinelli’s Whistler store was still planned. STEFF ELEOFF’s October and November activations will add another test of how a digitally developed Canadian label performs within an established luxury retailer’s physical environment.

Representative Articles

More From Retail Insider

Q3 2026 Sporting Goods & Outdoor: Store Productivity as Performance Diverges

As part of Retail Insider Reports, this Q3 2026 Sporting Goods & Outdoor Report analyzes Q3 2026 developments in Canadian sporting goods, outdoor recreation, and fitness retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping store investment, specialist assortments, services, and consumer demand. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines Canadian sporting goods, outdoor recreation, fitness, athletic equipment, hunting, fishing, cycling, and related specialty retail sectors.

Executive Summary

Canadian sporting goods and outdoor retailers continued investing heavily in stores during the third quarter of 2026, with different approaches to space, inventory and service as companies worked to improve productivity and capture consumer spending.

SportChek generated 8% comparable-sales growth in Canadian Tire’s second quarter, with World Cup merchandise accounting for roughly half the increase. Sports Experts completed an approximately $8-million rebuild of its CF Carrefour Laval flagship, emphasizing inventory depth, fitting and fulfilment. MEC expanded its trail-running business while preparing to test a 2,200-square-foot store in Whistler, and Arc’teryx opened a Montreal Alpha Store with expanded repair, care and resale services.

Performance varied considerably. Lululemon attracted nearly 10,000 runners to Vancouver’s revived SeaWheeze half marathon while its Canadian quarterly revenue declined 11%. Columbia Sportswear reported a high-single-digit decline in Canadian sales on a constant-currency basis as its wholesale business weakened.

The divergence illustrates an important distinction for the sector. Participation in sport, fitness and outdoor activities creates a substantial customer base. Assortment, inventory availability, service, location and merchandising determine how effectively retailers convert that interest into spending.

Canadian sporting goods and outdoor retailers invested in stores, assortments and services during Q3 as financial performance varied substantially across companies.

Several developments stand out:

  • SportChek reported 8% comparable-sales growth, with World Cup merchandise generating roughly half the increase. The banner is also expanding its Destination Sport format, including an almost 70,000-square-foot location planned for CF Chinook Centre in Calgary.
  • Sports Experts invested approximately $8 million in its roughly 45,000-square-foot CF Carrefour Laval flagship, increasing footwear inventory depth and reorganizing space around sales productivity, fitting and fulfilment.
  • Retailers are making different inventory bets. Sports Experts can hold approximately 60,000 pairs of footwear at Laval, while MEC’s planned 2,200-square-foot Whistler store will use a locally curated assortment supported by access to a broader online range.
  • Services are taking on defined commercial roles. Sports Experts retained technology that assists with footwear fitting, Arc’teryx expanded repair, care and resale in Montreal, and MEC is using technical expertise and community programming to deepen its trail-running business.
  • Strong participation and engagement do not guarantee stronger sales. Lululemon’s Canadian revenue fell 11% even as SeaWheeze attracted nearly 10,000 runners, while MEC has not disclosed whether participation in its trail-running programs generated incremental sales.
  • Columbia’s Canadian results demonstrate the importance of channel mix. Wholesale weakened while direct-to-consumer sales grew, led by e-commerce.

Opening campaigns, sporting events and community programs can create traffic and interest. Stabilized sales, margins, repeat visits, inventory productivity and returns on capital will provide stronger evidence of whether the investments are working.

Retail Insider Coverage

SportChek Captures World Cup Demand

SportChek provided one of the quarter’s clearest examples of a retailer successfully preparing for a major sporting event. Comparable sales increased 8% during Canadian Tire’s second quarter ended July 4, with World Cup merchandise generating roughly half the growth. Montreal Canadiens fanwear also contributed, while athletic footwear performed well and cycling was more muted.

The World Cup contribution reflects successful execution around a predictable period of heightened demand. SportChek positioned inventory and marketing to capture spending while consumer interest was elevated. Sustaining the growth becomes the next test. Canadian Tire management has pointed to more difficult comparisons, including the prior year’s Blue Jays postseason run and favourable fourth-quarter weather. Results after the World Cup contribution passes will provide a better indication of performance across SportChek’s broader assortment.

Destination Sport Makes a Bigger Bet on the Store

SportChek is also investing in larger stores designed to carry deeper assortments and support additional services. At CF Chinook Centre in Calgary, the retailer plans to consolidate its two existing locations into an almost 70,000-square-foot Destination Sport store on the upper level of the former Nordstrom in 2027. The project represents a substantial reinvestment in an existing market, using a larger consolidated location to provide sport-focused departments, expanded footwear presentations, broader assortments and services.

The former Nordstrom space illustrates one potential reuse for large department-store floor plates. Sporting goods is among the retail categories capable of occupying substantial portions of former anchors while other tenants take the remaining space.

Canadian Tire has discussed former Hudson’s Bay locations as potential Destination Sport opportunities, although it had not identified specific completed HBC transactions during its August earnings discussion. Access, configuration, local demand, rent and required capital will determine which spaces are viable.

Digital investment is developing alongside the physical program. Canadian Tire has introduced website tabs allowing customers to move among its major banners, with management saying its larger web audience is generating traffic for SportChek and Mark’s. Integrated search, cart and payment capabilities remained planned.

Sports Experts Rebuilds the Economics of an Existing Flagship

The Sports Experts and Atmosphere flagship at CF Carrefour Laval provides one of the quarter’s most detailed examples of investment in an established store.

Groupe Beaulieu-Angelo spent approximately $8 million rebuilding the roughly 45,000-square-foot, two-level location, which soft-opened August 6 and formally reopened August 12. The family-owned operator runs five Sports Experts stores in Quebec, with Carrefour Laval accounting for approximately 40% of group sales. The investment addressed inventory capacity, circulation, category allocation and online fulfilment in a store that had already undergone a substantial renovation in 2015. After exploring a configuration of approximately 70,000 square feet on one level, the operator expanded the existing mezzanine internally by approximately 2,000 square feet and reorganized the premises.

Footwear is central to the rebuilt store. Approximately 1,425 to 1,450 models were on display when Retail Insider visited, with capacity for roughly 1,600 and stockroom capacity for approximately 60,000 pairs. That depth increases the likelihood that customers can find the correct product and size during a store visit while supporting online orders drawn from the same inventory. In a category where fit, comparison and immediate availability can influence the purchase, Sports Experts is making a substantial bet on physical inventory.

Three Aetrex foot-scanning systems help associates measure customers and recommend products across brands, making the large assortment easier to navigate.

Technology and Space Are Being Judged on Productivity

The renovation also provides an unusually clear example of selective thinking around in-store technology. The previous store contained RFID-enabled screens that allowed customers to check product availability. Management found that they created maintenance work and could display inventory that employees were unable to locate. Removing 12 screens created enough space to display another 144 footwear models.

The retailer retained the Aetrex scanners, which serve a specific fitting and recommendation function. Store technology consumes space, labour and capital, and its value depends on whether it improves the customer experience or operation sufficiently to justify those resources.

Space allocation was also reconsidered across categories. Bicycles received less floor space in the rebuilt store, yet early bicycle sales were approximately 20% above previous levels. Footwear sales were running approximately 70% higher when co-owner Hugo Beaulieu spoke with Retail Insider. Both figures were recorded shortly after reopening and should be treated as early indicators. Stabilized performance will provide a better measure of the return on the renovation.

The temporary store used during construction adds another perspective. Despite occupying approximately 50,000 square feet across the street, traffic was roughly 70% below the Carrefour Laval location and sales were about 30% lower. The operator-reported figures reinforce the importance of location, assortment and customer journey alongside store size. The temporary location provided substantial square footage but did not reproduce the traffic or sales of the established mall store.

MEC Tests a Different Inventory Model

MEC’s planned Whistler location takes a very different approach to physical inventory. The retailer is targeting an October 31 soft opening for a 2,200-square-foot store at 104–4338 Main Street in Tyndall Stone Lodge, previously occupied by Arc’teryx. It would become MEC’s 25th Canadian store and its first in the Sea to Sky corridor. The store will carry a regionally selected assortment while providing access to MEC’s broader online range and store pickup where available. Staff knowledge is intended to help customers navigate the smaller selection and find products appropriate for local activities.

MEC has described Whistler as a learning opportunity and has not announced a broader rollout of the format. The comparison with Sports Experts is instructive. Carrefour Laval uses deep physical inventory to increase availability in a high-volume regional shopping centre. MEC is testing whether a specialized market can be served from a much smaller store using local curation, expertise and digital access to additional products.

The appropriate inventory model depends on the market, category, customer mission and fulfilment capabilities. Whistler will provide evidence of how far MEC can reduce physical assortment while maintaining sufficient product availability and service.

MEC Builds Around Trail Running

MEC is also expanding its investment in trail running, drawing on capabilities already present in hiking and backpacking. Its assortment includes footwear, apparel, hydration systems, packs, nutrition and accessories, with Canadian brands including norda, Ciele Athletics and Näak alongside MEC Label and international suppliers. The category can generate purchases beyond footwear as customers progress to longer distances and more technical terrain. Hydration, nutrition, carrying systems and clothing become more important, increasing the role of specialist advice.

Chief Merchandising Officer Chris Speyer said MEC Label represents approximately 25% of the retailer’s overall business, with the company intending to increase that share. The figure applies to MEC as a whole and is not a measure of its trail-running business.

MEC is also using community programming to develop regular contact with runners. Its four-week Train for the Trails program includes free clinics, community runs, training challenges and digital resources. More than 1,000 people registered nationally during the first weekend, while the initial 100 Vancouver places filled during that period.

The registrations demonstrate interest, although MEC has not disclosed incremental sales, basket sizes or longer-term retention resulting from the program. Those measures would provide a better indication of the commercial value created by the engagement.

Arc’teryx Extends the Customer Relationship

Arc’teryx is using its own Canadian stores to expand assortment and services. Its 9,599-square-foot Montreal Alpha Store opened August 28 at 1133 Sainte-Catherine Street West, replacing the brand’s longstanding location farther west. The three-level former Michael Kors premises include an expanded ReBIRD Service Centre, broader product presentations, Veilance and community space.

ReBIRD gives existing owners reasons to return through repair, product care, trade-in and resale. Eligible products can be traded for credit based on a portion of their original value, while some repairs can be performed in-store. For technical products designed for extended use, those services create additional interactions during the ownership cycle. The larger Montreal store can also expose returning customers to footwear, women’s product, Veilance and other parts of the assortment.

Amer Sports has identified Canada as Arc’teryx’s highest-awareness market and reported strong growth in women’s products and footwear. Those growth measures were reported at broader geographic levels and should not be treated as Canada-specific performance. Management has also discussed a potential long-term opportunity for approximately 200 Arc’teryx stores in North America. That represents a continental opportunity and is not a Canadian opening commitment.

JD Sports provides additional evidence of investment in athletic footwear and sports-fashion retail. Its downtown Montreal store at 777 Sainte-Catherine Street West occupies the main level and former mezzanine of the former Banana Republic premises, adding a prominent urban location alongside the company’s suburban expansion. JD Sports’ September half-year results showed softer North American trading and did not provide a separate Canadian sales figure, limiting conclusions about the productivity of its Canadian expansion.

Lululemon Shows the Limits of Participation

Lululemon provides the clearest example of strong consumer engagement coexisting with weaker retail performance. Canadian second-quarter revenue declined 11% on a reported basis and 9% in constant currency. During the same period, the company brought its SeaWheeze half marathon back to Vancouver, attracting nearly 10,000 runners from 24 countries.

Approximately half of participants were Canadian and more than 70% travelled to Vancouver for the event. SeaWheeze included a Showcase Store, brand activations, limited-edition merchandise and community programming. The participation demonstrates substantial engagement with lululemon’s brand and running community. Management nevertheless acknowledged that encouraging community engagement had yet to improve the Canadian sales trajectory.

Lululemon has identified traffic and product challenges in Canada and is reducing store SKU density while testing more localized assortments. The inventory response is notable in the context of other Q3 investments: Sports Experts is increasing footwear depth in a high-volume store, while lululemon is reducing SKU density to improve product presentation and relevance.

Columbia Shows Why Channel Mix Matters

Columbia Sportswear’s Canadian second-quarter sales declined 7% on a reported basis and approximately 9% in constant currency to roughly US$25.2 million. The decline primarily reflected unfavourable wholesale shipment timing and lower spring wholesale orders. Direct-to-consumer sales grew, led by e-commerce, while store performance was weaker.

Canadian gross margin increased to 49.8% from 48.1%, partly because direct-to-consumer sales represented a larger share of the business and carry higher gross margins than wholesale. Canadian operating loss nevertheless widened to approximately US$3 million from US$2 million. The results show how sales, channel mix, gross margin and operating performance can move differently within the same market.

Shipment timing adds another complication. Columbia said more than US$30 million of shipments globally were expected to move from the third quarter into the fourth, predominantly affecting North America, with no meaningful order cancellations at the time of the call. Timing still matters for seasonal merchandise. Retailers need footwear, apparel and outerwear early enough to capture the strongest portion of their selling periods, even when delayed orders ultimately ship.

Fitness Participation Creates Additional Retail Touchpoints

Fitness businesses provide additional contact with consumers buying athletic apparel, footwear, equipment and nutrition products. Calgary’s Realm Fitness reported approximately 2,500 members and 700 to 800 average daily visits at its 44,000-square-foot converted industrial property near Inglewood. The facility includes branded merchandise, supplements and a working equipment showroom, although retail sales were not disclosed.

The model shows how fitness participation can create recurring customer traffic around products and services adjacent to traditional sporting-goods retail. Without retail-sales disclosure, however, membership and visits cannot establish the value of that merchandise opportunity.

Broader Industry Coverage

Statistics Canada Provides a Broad Market Backdrop

Statistics Canada’s July retail data recorded $1.422 billion in sales at sporting goods, hobby, musical instrument and book retailers and news dealers. Sales increased 4.3% from a year earlier in current dollars and 3.4% at constant prices. Compared with June, sales declined 0.8% in current dollars and 1% at constant prices.

The category includes several businesses outside sporting goods and cannot establish a 4.3% increase specifically for Canadian sporting-goods retail. The annual increase provides a constructive backdrop, while the monthly decline and divergent company results argue against drawing a broad conclusion about the pace of sector growth.

Editor’s Take & Outlook

Outlook: The Investments Face a Productivity Test

The winter selling period and 2027 will provide better evidence of whether the quarter’s investments are producing durable returns. SportChek faces harder comparisons as World Cup merchandise becomes less important to growth. Its planned CF Chinook Centre Destination Sport store will eventually provide another measure of whether consolidating two locations into a larger store improves productivity.

Sports Experts will move beyond the initial reopening period at Carrefour Laval. Early footwear and bicycle gains are encouraging, but stabilized sales and inventory productivity will determine the return on the approximately $8-million investment.

MEC’s Whistler store will test whether a small physical assortment, local expertise and digital access can effectively serve a specialized market. Its trail-running program creates a separate test of whether community engagement produces repeat customers and incremental purchases.

Arc’teryx’s expanded ReBIRD operation creates measures around repeat visits, service usage, trade-ins and resale, while its larger Montreal store will test demand for a broader direct assortment.

Lululemon will need to demonstrate that changes to SKU density, localized assortments and product strategy can improve Canadian traffic and sales. Columbia’s next results should indicate whether wholesale shipment timing normalizes, whether direct-to-consumer growth continues and whether gross-margin improvement can translate into better operating performance.

Across the sector, comparable sales, inventory turns, full-price sell-through, service usage, repeat visits, digital conversion, margins and return on invested capital will provide stronger evidence of performance than store openings and event attendance alone.

Editor’s Take

Sporting-goods retail has an advantage few categories enjoy: customers actively participate in the activities that create demand for its products. Running, soccer, hockey, skiing, cycling and fitness can generate recurring needs for footwear, apparel and equipment. Retailers still have to convert that participation into purchases.

The Q3 investments show how different the solutions can be. SportChek is preparing an almost 70,000-square-foot Destination Sport location, Sports Experts has rebuilt a roughly 45,000-square-foot flagship around inventory and productivity, Arc’teryx is using a 9,599-square-foot store for assortment and lifecycle services, and MEC will test a 2,200-square-foot format built around local curation and digital access.

Sports Experts is carrying enough footwear to increase the probability that customers find the product and size they want immediately. MEC Whistler will test a narrower physical assortment supported by expertise and online inventory. Arc’teryx is creating reasons for existing owners to return through repair, care, trade-in and resale.

Lululemon provides an important financial counterweight. Nearly 10,000 people can participate in a major brand event while Canadian revenue declines, demonstrating why community engagement and commercial performance need to be measured separately.

The strongest Q3 strategies involve specific decisions about what belongs in the store, how much inventory customers need immediately, which services justify labour and space, and where digital capabilities can extend the physical assortment. Participation creates the opportunity. Sales productivity determines whether the investment works.

Representative Articles

More From Retail Insider

Q3 2026 Jewellery & Accessories: Seeking More From Physical Stores

As part of Retail Insider Reports, this Q3 2026 Jewellery & Accessories Report analyzes Q3 2026 developments in Canadian jewellery, watches, and related specialty retail. Drawing on Retail Insider coverage, industry research, company disclosures, government data, and broader market signals, it identifies key dynamics shaping store investment, service models, brand distribution, and consumer demand. These reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

This report examines Canadian jewellery and watch retail, including luxury and fashion jewellery, watches, bridal, specialty retailers, consumer demand, and market developments.

Executive Summary

Canadian jewellery and watch retailers continued investing in physical retail during the third quarter of 2026, with greater precision around what stores and other physical formats are expected to accomplish.

Michael Hill generated record Canadian revenue from a smaller store network while preparing to modernize several of its highest-volume locations. Pilgrim is using piercing services to generate planned store visits while expanding through corporate boutiques, wholesale and shop-in-shops. Longines began construction of its first dedicated Canadian boutique despite already having broad wholesale distribution, while Tiffany & Co. continued work on a substantially larger Toronto flagship.

Investment also extends beyond traditional stores. Pandora’s Canadian scale has supported dedicated domestic e-commerce fulfilment, while Toronto-based STEFF ELEOFF is using temporary Holt Renfrew activations to give customers physical access to a largely digitally distributed brand without committing to a standalone location.

Performance remains uneven. Michael Hill’s Canadian sales and profitability strengthened, Pilgrim described company-store sales as relatively flat despite strong wholesale orders, and Birks remained net loss-making after financing costs despite improved sales and operating performance.

Store counts therefore provide only part of the picture. Physical space can support sales productivity, services, brand control, customer acquisition and market testing, with different formats carrying different levels of capital commitment.

Canadian jewellery and watch retailers continued investing in stores, services and supporting infrastructure during Q3, while company performance varied considerably.

Several themes emerged during the reporting period:

  • Michael Hill generated record Canadian revenue of C$174.2 million in fiscal 2026, up 7.3%, while comparable sales increased 7% and comparable EBIT rose 16.3%. The company ended the year with 81 Canadian stores, down from 86 at the end of fiscal 2023.
  • Bridal consultations, bespoke jewellery and professional piercing are giving physical stores defined service roles. Pilgrim says piercing accounts for approximately 15% of business at some locations and can generate planned customer visits.
  • Pilgrim combines 11 corporate boutiques with distribution through more than 550 Canadian retail doors and is developing branded shop-in-shops, extending physical reach beyond its standalone network.
  • Longines began work on its first dedicated Canadian boutique in Vancouver, while Tiffany is building an approximately 15,000-square-foot Toronto flagship. Both investments give the brands greater control over presentation and customer service through very different physical formats.
  • Pandora’s Canadian business has reached sufficient scale to support dedicated domestic e-commerce fulfilment alongside 96 stores and an online business representing more than 20% of Canadian sales.
  • Financial performance remains uneven. Michael Hill strengthened materially, Pilgrim’s company-store sales were relatively flat, and Birks remained loss-making despite improved sales, gross margin and operating performance.

The Q3 developments point to a more selective approach to physical retail, with productivity, services, brand control and customer relationships providing more useful measures than store counts alone.

Retail Insider Coverage

Michael Hill Gets More From a Smaller Canadian Network

Michael Hill provided one of the clearest examples of stronger Canadian store productivity during the reporting period. Canadian revenue increased 7.3% to a record C$174.2 million in fiscal 2026, while comparable sales rose 7%. Comparable EBIT increased 16.3% to C$21.9 million and gross margin improved 20 basis points to 60.3%.

The retailer ended the year with 81 Canadian stores, compared with 82 a year earlier and 86 at the end of fiscal 2023. One location opened and two closed during fiscal 2026. Record revenue did not depend on net store growth. Management attributed the Canadian performance to more market-specific marketing, promotions and product ranges, with bridal, diamond fashion and coloured stones among the stronger areas. Canadian online sales increased 22%, compared with 10% growth across the Michael Hill brand’s wider online business.

Momentum continued after year-end, with Canadian comparable sales increasing another 9.8% during the first eight weeks of fiscal 2027. CEO Jonathan Waecker has described Canada as a market with substantial growth potential, citing its resilience and Michael Hill’s relatively small market share. The company continues to target an eventual Canadian network of 85 to 90 stores, so selective expansion remains part of the strategy.

Near-term capital spending also places substantial weight on existing stores. Five of Michael Hill’s six highest-volume Canadian locations are scheduled for modernization during fiscal 2027, extending refreshed formats across Toronto, Vancouver, Calgary and Edmonton. The program follows the refurbishment of Michael Hill at Yorkdale Shopping Centre and the addition of a location at CF Pacific Centre in Vancouver. The strategy combines selective expansion with investment in locations already producing substantial sales.

Services Give the Jewellery Store a Specific Job

Michael Hill’s store investment is increasingly connected to services and higher-value customer interactions. Its bespoke jewellery offering is available in more than 40 stores across Australia and Canada, with average bespoke bridal transaction values above the company’s broader bridal average. Personalized and custom products account for more than 15% of Michael Hill sales across the brand.

Those figures are not Canadian-only measures, but the strategy is relevant to the Canadian modernization program. Bridal consultations, appointments, customization and bespoke products give stores defined commercial roles, while planned clienteling and buy-online-pickup-in-store improvements connect those locations with Michael Hill’s growing digital business.

Pilgrim is using professional piercing to generate another type of visit. All 11 of its Canadian boutiques offer needle piercing, while five have dedicated studios. CEO Robert P. Hayes said piercing can represent approximately 15% of business at some locations, with dedicated studios generally generating stronger activity.

At Royalmount in Montreal, Hayes said customers book appointments and travel specifically to the boutique even when broader mall traffic is relatively light. The service allows the store to generate planned visits without depending entirely on traffic already moving through the shopping centre.

Pilgrim Expands Physical Reach Beyond Its Store Network

Pilgrim’s Canadian distribution strategy combines several levels of physical investment.

The company opened its eleventh Canadian boutique at Oshawa Centre on July 24, following a February opening at CF Masonville Place in London. Hayes said Pilgrim intends to add approximately three stores annually over the next three years, with the pace dependent on sales, financing and suitable real estate.

The site-selection process is deliberate. Hayes said Pilgrim’s suburban stores generally outperform its downtown locations, with the company considering household incomes, housing costs and population growth alongside rent, store size, traffic patterns and neighbouring tenants.

Pilgrim is considering Western and Atlantic Canada for future corporate expansion, but its existing physical reach is considerably larger than its 11-store network. The brand is carried through more than 550 Canadian retail doors and is developing branded shop-in-shops of approximately 200 to 300 square feet within selected independent retailers.

Wholesale orders were considerably stronger than company-store sales during the reporting period. Hayes said orders written at a Toronto trade show were 56% above the comparable event a year earlier, following approximately 32% season-to-date wholesale growth before the show.

Those figures represent retailer orders for Christmas delivery, not consumer sell-through. Pilgrim’s own retail sales were relatively flat, with younger customers remaining cautious about discretionary spending and conversion holding up better than basket size.

Holiday sales will provide a clearer indication of whether strong wholesale commitments are matched by consumer demand.

Longines Adds Direct Retail to an Existing Wholesale Network

Longines began construction during the quarter on its first dedicated Canadian boutique at 765 Burrard Street in downtown Vancouver.

The corporately operated store will span just over 1,000 square feet in the building commonly identified as 755 Burrard Street, near Alberni Street. Cartier occupies the corner of the same building, with Tiffany & Co. across Alberni.

Longines already has dozens of authorized Canadian points of sale. The boutique gives the Swatch Group brand greater control over assortment, presentation, service and the customer environment while allowing it to showcase a broader range under its own name.

The investment fits a wider movement in premium watches toward mono-brand boutiques and controlled shop-in-shop environments alongside established multi-brand distribution. Longines is adding a direct Canadian channel to the wholesale network that already gives it broad reach.

Tiffany Takes Brand Control to Flagship Scale

Tiffany & Co. is pursuing a much larger version of controlled physical retail in Toronto.

The luxury jeweller is building an approximately 15,000-square-foot, two-level flagship at 66 Bloor Street West to replace its existing location at 150 Bloor. Retail Insider’s September reporting placed the expected opening in early 2027, according to sources. Another new store is under construction right now at Square One in Mississauga, which will replace a Tiffany concession that has operated in the mall’s Holt Renfrew since 2016.

The investment shows the range of formats being used for selective physical expansion. A flagship can support extensive product presentation, appointments, consultation, services and high-value client relationships while reinforcing the brand’s presence within a major luxury district.

Longines’ approximately 1,000-square-foot Vancouver boutique and Tiffany’s much larger Toronto flagship pursue some of the same objectives through very different amounts of space and capital.

Brand Control Also Changes the Role of Birks

Greater direct investment by luxury brands has implications for traditional multi-brand jewellers.

As international watch and jewellery houses operate their own boutiques or use more selective distribution arrangements, Birks must continue developing its relationships with third-party brands alongside the value of its own name.

Birks-branded collections were among the stronger components of the company’s latest reported fiscal-year performance, alongside third-party branded jewellery. Proprietary collections give Birks greater control over product, pricing, availability and presentation without depending on the distribution decisions of an outside luxury house.

A brand such as Longines can use a corporate boutique to control more of its presentation and customer relationship. Birks can use proprietary merchandise to strengthen control over part of its own assortment while maintaining its multi-brand business.

Pandora’s Canadian Scale Supports Investment Beyond Stores

Pandora now has 96 stores in Canada, compared with 74 reported in 2022, and says Canadian revenue increased by more than 50% between 2019 and 2025. Canadian sales exceeded DKK 1 billion in 2025, with more than 20% generated online.

In March, the company opened a dedicated e-commerce distribution centre in Mississauga, replacing fulfilment of Canadian online orders from U.S. facilities. The centre can process up to 12,500 orders per day and was designed to reduce typical delivery times from five to seven days to two to four days.

Domestic fulfilment also reduces the need for Canadian e-commerce orders to move through U.S. customs, giving Pandora more direct control over Canadian distribution.

The investment reflects the scale the Canadian business has reached. Pandora now supports a large store network and substantial online sales with dedicated domestic fulfilment instead of treating Canada as an extension of its U.S. e-commerce infrastructure.

Pandora is also reducing heavy discounting, upgrading store presentation and broadening its global assortment beyond its core charm business. The Canadian implications should remain bounded: the company did not disclose a Canadian quarterly comparable-sales figure, and global merchandising tests do not establish Canadian customer acceptance.

Physical Retail Can Also Be a Market Test

Toronto-based STEFF ELEOFF is using temporary physical retail to test customer response without committing to a standalone store.

The largely digital jewellery brand announced Holt Renfrew pop-ups at Yorkdale Shopping Centre from October 2 to October 29 and at Bloor Street from November 12 to December 12. Most of the company’s business comes from outside Canada.

The activations give Canadian customers an opportunity to handle and try the jewellery while exposing the brand to two different Toronto luxury audiences. Yorkdale provides a major shopping-centre environment, while Bloor Street offers a downtown luxury and fashion setting.

No permanent standalone store has been announced. The pop-ups can provide information about customer response while limiting the physical commitment.

The format sits at the opposite end of the investment spectrum from Tiffany’s approximately 15,000-square-foot permanent flagship. Both create physical customer contact for different purposes.

Broader Industry Coverage

Birks Shows the Limits of an Operating Recovery

Birks’ financial results provide a counterweight to the quarter’s store and brand investment.

Fiscal 2026 sales increased 15.5%, while comparable-store sales rose 2.6%. The European Boutique acquisition contributed materially to the headline revenue increase, while stronger Birks-branded and third-party jewellery sales also supported performance.

Gross margin improved to 38.5% from 37.3%, and Birks returned to operating profitability after recording an operating loss a year earlier. Financing costs exceeded operating income, however, leaving the company with a net loss despite the operational improvement.

Birks has refinanced its principal lending arrangements through 2031, providing additional time and liquidity while leaving borrowing costs as a material constraint. In August, the company also announced plans to leave the NYSE American and move trading to OTCQB following a period of exchange-compliance pressure.

The trading change does not mean Birks is going private, and no immediate store-operating change was announced. Its planned Oakridge Park store and selective investment elsewhere continue alongside the financial restructuring.

Birks demonstrates why sales growth and store investment need to be assessed alongside profitability and financing. Better operations can strengthen the business without immediately resolving its financial constraints.

Statistics Canada Provides Broader Market Context

Statistics Canada’s July figures showed sales at jewellery, luggage and leather goods retailers up 15.9% from a year earlier and down 4.3% from June.

The category includes products outside jewellery and watches, while a single month does not establish the direction of the full quarter. Company results provide a more detailed picture, ranging from Michael Hill’s strong Canadian growth to relatively flat company-store sales at Pilgrim.

Editor’s Take & Outlook

Outlook: Physical Investment Faces a Holiday Test

The holiday period and early 2027 should provide better evidence of how the different strategies are performing.

Michael Hill enters the period with strong Canadian momentum after record fiscal 2026 revenue and 9.8% comparable-sales growth during the first eight weeks of fiscal 2027. Its modernization of five high-volume Canadian stores will provide a longer-term test of whether investment in existing locations supports further productivity gains.

Pilgrim’s wholesale orders indicate strong retailer expectations for Christmas, but consumer sell-through remains the more important measure. Its corporate-store results will also show whether pressure on basket size begins to ease while piercing continues generating service-led visits.

Longines’ Vancouver boutique will add direct retail to an established Canadian wholesale network, while Tiffany’s expected early-2027 Bloor Street opening will introduce a substantially larger flagship investment.

Pandora’s domestic fulfilment infrastructure provides another measure to watch as Canadian e-commerce develops alongside its 96-store network. Birks will need to sustain its operating improvement while managing financing costs and continuing to build both proprietary and third-party jewellery sales.

STEFF ELEOFF’s Yorkdale and Bloor activations provide a smaller test. Customer response could help inform whether temporary formats remain sufficient or whether a more permanent Canadian physical presence eventually makes sense.

Across the sector, comparable sales, store productivity, service revenue, transaction values, digital growth, wholesale sell-through and profitability will provide stronger evidence of returns than expansion announcements alone.

Editor’s Take

Jewellery and watches remain well suited to physical retail because many purchases involve trust, fit, consultation, service and significant spending. The Q3 developments also show substantial variation in what retailers and brands need from physical space.

Formats range from Pilgrim’s proposed 200-to-300-square-foot shop-in-shops to Longines’ approximately 1,000-square-foot Vancouver boutique and Tiffany’s approximately 15,000-square-foot Toronto flagship. STEFF ELEOFF is testing physical retail without a standalone store, while Pandora’s Canadian investment extends into infrastructure supporting digital sales.

Michael Hill provides some of the strongest evidence for selective physical investment, generating record Canadian revenue from a smaller network while preparing to modernize several high-volume stores. Pilgrim shows how a service can generate destination visits, and Longines demonstrates why a brand with broad wholesale distribution may still value its own retail environment.

The financial results keep the picture grounded. Michael Hill’s Canadian performance improved materially, Pilgrim’s corporate retail sales remained relatively flat, and Birks continued to face financial pressure despite better operating results.

The useful question is what each physical investment is expected to accomplish. A store can increase sales productivity, support a service, deepen a client relationship, control brand presentation or test a market. Its value ultimately depends on whether it performs that job well enough to justify the investment.

Representative Articles

More From Retail Insider