Despite concerns of AI-driven job losses, a new study from JLL finds that a majority of senior business leaders expect their workforces to grow (60%), not shrink (40%) – similarly, most expect AI to reinvent human roles (60%), rather than replace them (40%).
JLL’s 2026 Future of Work Survey finds this picture is more pronounced among the most AI-advanced organizations, which are utilizing technology as a workforce augmenter and focusing on strategic expansion — even though they recognize it will not be uniform and some jobs will still be cut. Hence, more than others, they lean toward hiring full-time employees, investing in entry-level talent and actively redesigning roles to be enhanced by AI rather than eliminated, said the real estate company.
The biennial survey, conducted from January to April 2026, offers a comprehensive snapshot of the state of work through the lens of the key priorities, challenges and strategies of over 2,200 C-suite and CRE leaders across 21 countries, it added.
“The public conversation around AI has been dominated by its impact on jobs and our research reveals that most companies are focused on the opportunities that come with AI,” said Neil Murray, CEO of Real Estate Management Services at JLL. “Most forward-thinking leaders aren’t just buying technology; they are investing in their people. They are pursuing a strategy of human-machine enhancement to create additional roles, boost productivity and drive sustainable growth.”
The 2026 survey found that despite 78% of respondents expecting AI to drive significant changes to their real estate portfolio strategy, only 31% are actively preparing to redesign spaces for human-AI collaboration and just 15% have reached the optimizing stage of AI adoption. The gap between what organizations believe and what they are doing defines the central challenge of the moment and it is being driven by critical tensions in terms of execution decisions, capabilities and budget constraints, said the company.
Neil Murray
“While AI is generally expected to enhance human roles according to JLL’s survey, most organizations are still examining the impacts on their organization, which leaves them in early stages of adoption. A small pool of respondents (15%) is in the optimization phase, moving beyond the pilot and scaling phases to actively prepare for the redesign of roles and places of work. However, the majority are in the monitoring and analysis stages, with 46% focused on tracking AI trends and 40% analyzing potential impacts on their CRE function. These CRE leaders are depending on workforce decisions as it relates to AI adoption in order to define their organizations’ space transformations, creating a holding pattern that prevents forward progress,” said JLL.
“AI is also requiring new skills and expertise from CRE teams for them to make an impact on their organizations, with skills gaps in AI, analytics and emerging technologies (36%) being cited as the top barrier in doing so in the next three to five years. Limited change management expertise (26%), organizational silos (25%) and measurement challenges (23%) further compound the problem.”
JLL said this creates a “technology dilemma” that reflects the vulnerabilities of an increasingly connected and AI-driven business environment. Organizations must invest in advanced technology to achieve productivity goals, which is seen as a core CRE key performance indicator (KPI), beyond traditional cost metrics, according to C-suite respondents (46%). However, three of the top four portfolio risks are technology-related — including cybersecurity and data privacy (47%), technology/AI disruption (41%) and uncertainty around AI’s impact on space (40%), with economic volatility and budget pressures (43%) being the other top concerns. This layering of competing priorities requires new, adaptive strategies to navigate a landscape where challenges converge.
“We are seeing a fundamental shift in what defines a high-performing company. It’s no longer just about market position, size and scale – it’s about becoming an AI-powered enterprise with the adaptability and organizational readiness to transform effectively amid continuous disruption,” said Peter Miscovich, Global Future of Work Leader at JLL.
“Leading organizations are demonstrating deeper integration between real estate, HR, and technology to support their business strategies. These companies leverage data-driven AI decision intelligence to reimagine their workplaces for greater human performance and to achieve superior business outcomes. This fully integrated approach is the new blueprint for building a resilient enterprise that can thrive amid continuous disruption.”
Alberta business leaders are optimistic about the province’s economic outlook, with nearly two-thirds expecting economic conditions to improve over the next year and many planning to increase investment, hiring and revenue growth, according to the inaugural Business Council of Alberta (BCA) CEO Pulse Survey.
Adam Legge
“Our CEO members make the investment, hiring, and growth decisions that shape Alberta’s economy, making their perspective an important indicator of business confidence,” said Adam Legge, President of the Business Council of Alberta. “The survey tells us Alberta has momentum and CEOs are optimistic. The opportunity before government now is to build on that momentum and optimism by creating the conditions for even greater investment.”
The Council said its inaugural CEO Pulse Survey, which will be conducted twice yearly, establishes a new benchmark of business confidence among the province’s leading CEOs and entrepreneurs. It tracks expectations for the economy, business performance, investment and hiring intentions, while also identifying the issues having the greatest impact on business growth and competitiveness. The survey will help inform BCA’s ongoing work to strengthen the province’s competitiveness including research on reducing barriers to investment, reducing regulatory burden, strengthening the labour market, expanding trade opportunities and growing Alberta’s economy.
The findings come at a time when Alberta is seeing renewed private-sector investment and major project activity, while businesses continue to navigate global uncertainty, evolving trade tensions, and the lead-up to the province’s October referendum on separation, it said.
Key findings include:
65% of EOs expect Alberta’s economy to improve over the next year.
More than half (55%) plan to increase capital investment, 51% expect stronger revenue growth and 50% plan to increase staffing.
Regulation was by far the issue most likely to be identified as a major barrier (45%), suggesting it is the biggest competitiveness challenge facing Alberta businesses.
When both major and moderate barriers are considered, taxes were identified most frequently (82%), followed by input costs (74%) and regulation (74%).
Nearly half (47%) of businesses continue to face labour shortages, while 63% say they have the capacity to meet increased demand.
Alberta businesses remain optimistic despite a business environment shaped by global uncertainty, major investment opportunities, and the upcoming referendum on separation.
US President Donald Trump. Image: Wikimedia Commons
The United States has announced a sweeping 50 per cent tariff on Canadian goods, citing discriminatory treatment of American alcohol, automobiles and dairy products. The duties are expected to take effect August 19 and, unusually, will reach some products that would ordinarily receive preferential treatment under CUSMA. Energy, potash, fish and critical minerals are among the reported exemptions.
For Canada’s food and beverage economy, the stakes are significant. Canada exports approximately $1.4 billion in alcoholic beverages to the United States annually, representing roughly 90 per cent of our alcohol exports. Spirits are particularly exposed. Canadian dairy exports to the United States, while much smaller, are worth approximately $360 million annually.
But the immediate trade flows are only part of the story. The larger issue is how badly Canada has misread Washington—and how little influence Ottawa now appears to have over events.
The tariffs rely on Section 338 of the U.S. Tariff Act of 1930, a rarely used presidential authority allowing Washington to retaliate when another country is deemed to discriminate against American commerce. It is an obscure and potentially contestable instrument, but the warning signs were visible. Canada’s removal of American alcohol from provincial shelves and its administration of dairy tariff-rate quotas have featured prominently among Washington’s complaints.
This was only a matter of time. Last week, Prime Minister Mark Carney was asked about the future of CUSMA. His answer to Canadians was: “I’ll keep you posted.”
Well, consider us posted.
New tariffs are coming, negotiations appear stalled, and Canadian exporters are again being asked to absorb the consequences. Canadians deserve more than cryptic reassurances and strategic ambiguity. They deserve to know who is negotiating, what Canada is prepared to concede and how Ottawa intends to protect market access without inflicting even more damage on Canadian businesses and consumers.
President Trump has given himself a 30-day off-ramp. The delay may be legally required, but it also creates negotiating space. It gives Canada an opportunity to offer a limited, face-saving concession before the tariffs take effect.
That could involve restoring some access for American alcohol, addressing specific concerns surrounding dairy quotas or finding another politically manageable gesture. The objective would not be capitulation. It would be to remove the justification for a measure capable of causing far more economic damage than the concessions required to prevent it.
Ottawa could, of course, escalate. Canada could impose export taxes or restrictions on energy, critical minerals or potash. These are among the few areas in which Canada possesses genuine leverage.
But leverage is not the same as immunity.
Restricting strategic exports would disrupt American supply chains, but it would also damage Canadian producers, weaken investment and raise costs throughout our own economy. Energy infrastructure cannot simply be redirected overnight. Potash customers are not infinitely interchangeable. Once buyers invest in alternative suppliers, some business may never return.
Canada would pay a steep price for the satisfaction of appearing tough.
This is why the “elbows up” approach was always more slogan than strategy. There is no trade war Canada can win by attempting to outmuscle a country representing roughly one-quarter of the global economy. The United States is not simply another customer. It is the destination for approximately three-quarters of Canadian merchandise exports and an essential market for our farmers, processors and manufacturers.
Diversifying trade is necessary, but it is a generational project—not an emergency response. A new trade mission to Asia or Europe cannot replace continental supply chains built over decades.
Mexico understood this earlier. Its government chose sustained engagement with Washington, even when doing so was politically uncomfortable. Mexico has reportedly held detailed discussions with the United States and has more meetings planned. Canada, by contrast, has leaned heavily on public defiance while appearing increasingly absent from the negotiating table.
Mexico chose engagement. Canada chose theatre—and now pain.
Some in Ottawa continue to advocate playing the “long game,” apparently assuming that conditions will improve after the U.S. midterm elections or once Trump leaves office. That is speculation, not strategy. Nothing guarantees that Congress will become more sympathetic to Canada after November. Nothing guarantees that the next administration will abandon protectionism after 2028.
American trade policy has changed structurally. Economic nationalism now extends well beyond Donald Trump. Waiting for the old relationship to return is not a plan.
For Prime Minister Carney, the time for distance, ambiguity and political posturing is over. Canada needs direct engagement with the White House, a clear list of negotiating priorities and a willingness to make targeted concessions where the economic cost of refusing is vastly greater than the cost of compromise.
Working with the United States does not require admiring its president. It requires understanding power, geography and economic reality.
Canada cannot choose its neighbour. But it can choose whether to manage that relationship intelligently.
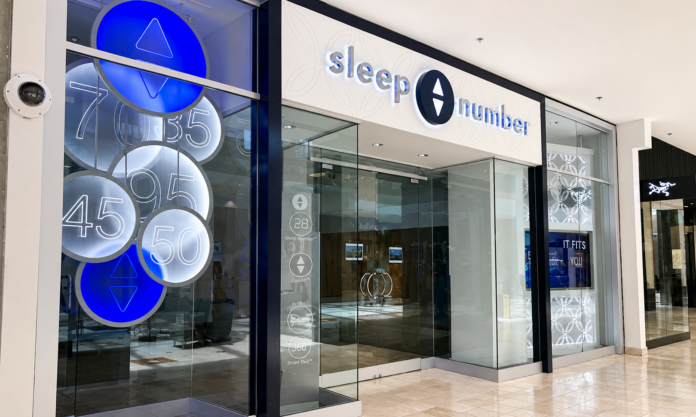
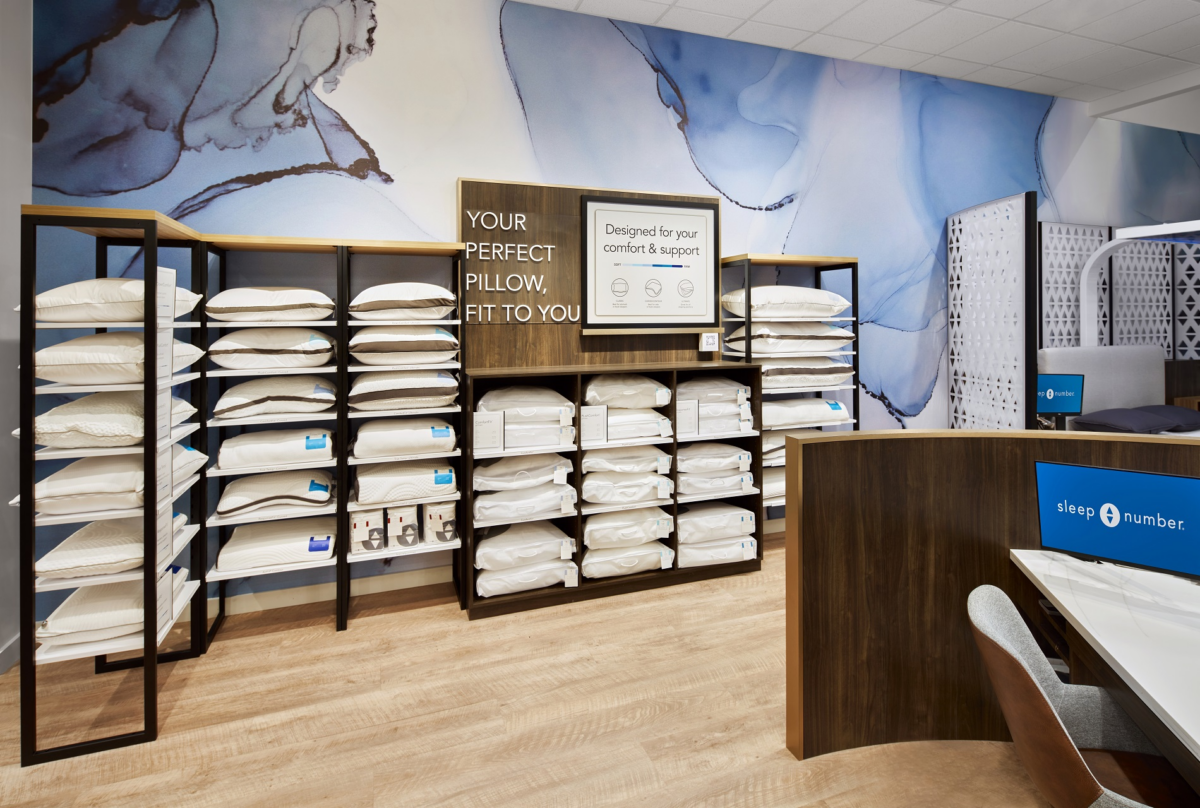
Sleep Number storefront in an American shopping centre. Photo: Sleep Number
Sleep Country Canada is preparing to enter the United States at scale through its acquisition of Sleep Number, a transaction that would give the Canadian retailer control of a recognized American brand, proprietary mattress technology and a network of more than 570 stores.
A U.S. bankruptcy judge approved the sale on July 20 following a competitive auction conducted as part of Sleep Number’s Chapter 11 proceedings. Court documents place Sleep Country’s winning proposal at approximately US$701 million in total value, including US$529.5 million in cash and the assumption of selected obligations. Closing is expected by July 31.
The final proposal was substantially higher than Sleep Country’s original US$415-million stalking-horse bid. Reuters reported that the Canadian retailer agreed to increase its offer by approximately US$286.8 million through the auction process. Brooklyn Bedding was selected as the backup bidder.
Sleep Country described the combination as creating the world’s second-largest sleep retailer, with more than 800 stores across Canada and the United States. The company currently operates 307 corporate-owned stores and 18 warehouses in Canada, while Sleep Number has more than 570 locations across the U.S.
The deal would change Sleep Country’s geographic reach considerably. The company has assembled a collection of Canadian store banners and online sleep brands, but its physical retail operations have remained concentrated in Canada. Sleep Number provides immediate access to markets throughout the United States without requiring years of store-by-store expansion.
It also leaves Sleep Country responsible for a difficult turnaround. Sleep Number entered bankruptcy protection after several years of declining sales, widening losses, store closures and pressure from approximately US$672 million in debt.
A Canadian Retailer Moves Into the U.S.
Sleep Country operates its namesake banner and Dormez-vous, along with Endy, Silk & Snow, Hush, Casper Canada and Simba. Its business spans mattresses, bedding, furniture and sleep accessories sold through stores and digital channels.
The company has expanded its portfolio through acquisitions and brand development. Sleep Number brings a much larger geographic platform and a retail model that differs from much of Sleep Country’s current business.
Sleep Number’s mattresses allow customers to adjust firmness and support settings. Its newer products also include pressure-relieving support, temperature-balancing features and connected technology.
The company says it has served more than 16 million people over nearly four decades and holds more than 1,000 patents and patents pending. Its operation covers product design, assembly, retail sales, home delivery and continuing customer support.
Sleep Country President and CEO Stewart Schaefer said the company sees opportunities to build the business in the U.S. and introduce Sleep Number products in Canada and other markets.
Details of a Canadian rollout have not been released. Sleep Country has not indicated whether the products would be carried inside its existing stores, introduced through dedicated selling areas, launched online or supported by standalone Sleep Number locations.
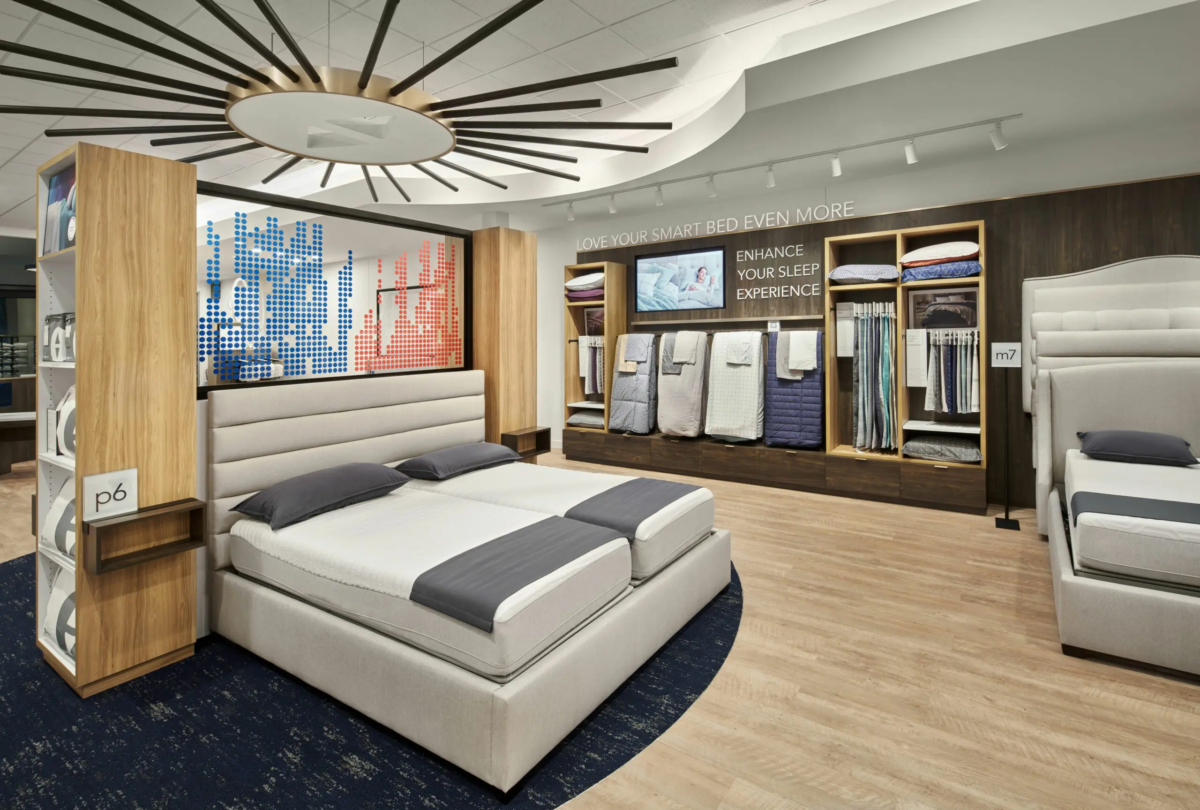
Sleep Number store. Image: CenterPoint
Fairfax Ownership Sets the Stage
Sleep Country’s move into the U.S. follows its own change of ownership less than two years ago.
Fairfax Financial Holdings acquired Sleep Country in October 2024, paying $35 in cash for each outstanding share. The transaction took Sleep Country private and resulted in its shares being delisted from the Toronto Stock Exchange.
The acquisition carried an enterprise value of approximately C$1.7 billion when it was announced.
Sleep Country now operates within the portfolio of Toronto-based Fairfax, an insurance and investment holding company led by Prem Watsa. Private ownership allows the retailer to undertake an integration that could require sustained investment and operational changes away from the quarterly reporting cycle faced by a publicly traded company.
The Sleep Number transaction would take Sleep Country from several hundred Canadian locations to an announced network exceeding 800 stores across two countries.
The approximately US$701-million winning proposal also represents a larger financial commitment than was apparent when Sleep Country entered the bankruptcy process as the stalking-horse bidder. The companies have not provided a detailed public breakdown of how Sleep Country will finance the US$529.5-million cash component or fund the subsequent integration.
Sleep Number Entered Chapter 11
Sleep Number filed for Chapter 11 protection in June and entered a court-supervised sale process with Sleep Country serving as the stalking-horse bidder. The arrangement was conducted under Section 363 of the U.S. Bankruptcy Code and remained open to higher or otherwise better offers.
Sleep Country’s original proposal contemplated US$415 million in cash, the assumption of selected liabilities and potential purchase-price adjustments. That offer established the opening terms for the auction.
Sleep Country increased its proposal following the competitive process. The court-approved bid is valued at approximately US$701 million, with US$529.5 million payable in cash. Sleep Country also agreed to assume obligations that include certain employee severance expenses and contractual liabilities.
The transaction is structured as an asset sale. Sleep Country is acquiring substantially all of Sleep Number’s operating assets through a wholly owned subsidiary, SNBR Inc. It is not acquiring the publicly traded company’s shares through a conventional corporate takeover.
The original purchase agreement also gave the buyer the ability to exclude contracts and leases it did not wish to assume. That provision gives Sleep Country room to review the U.S. operation as it decides which parts of the store network and contractual structure fit the business under new ownership.
Sleep Number arranged access to as much as US$260 million in debtor-in-possession financing to support operations during the proceedings, including up to US$65 million in new funding.
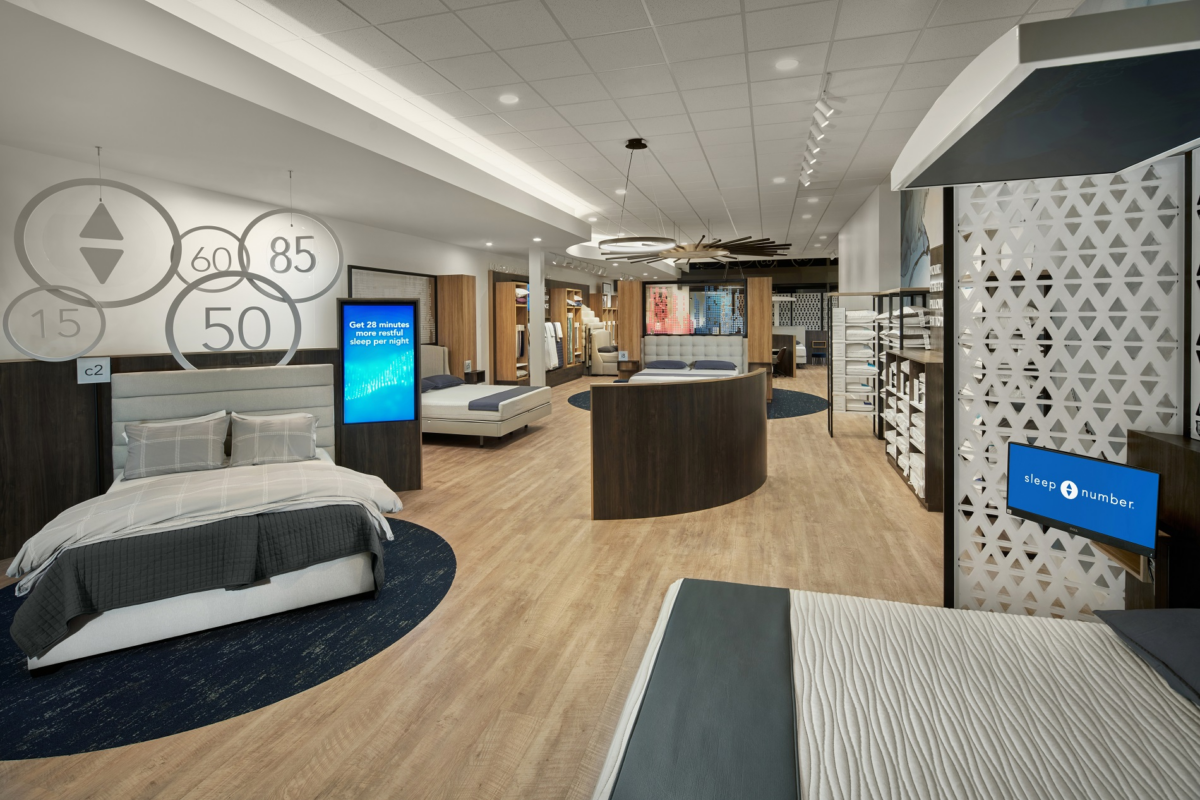
Sleep Number store. Image: CenterPoint
Sales and Losses Worsened
Sleep Number entered the sale process following a steep deterioration in its financial performance.
The company generated net sales of approximately US$1.41 billion in fiscal 2025, down 16 per cent from the previous year. It recorded a net loss of US$132 million, compared with a loss of US$20 million in 2024.
Sleep Number reduced adjusted operating expenses by US$136 million during the year and reported US$185 million in annualized cost reductions. Those measures included changes to corporate staffing, technology spending, administrative functions and the store network.
The savings did not offset the decline in revenue. Adjusted EBITDA fell 35 per cent to US$78 million.
Conditions remained difficult during the first quarter of 2026. Net sales fell 18.9 per cent to US$319 million, reflecting lower sales volume and a smaller store base. Sleep Number posted a quarterly net loss of US$50 million, widening from US$9 million a year earlier. The company entered Chapter 11 with approximately US$672 million in debt.
Sleep Number incurred US$22 million in restructuring and other non-recurring costs during the quarter, including store and office closure expenses, severance, professional fees and costs connected with its review of strategic alternatives.
The company had also completed its largest product redesign in nearly a decade, resetting its stores with a simplified assortment and new marketing. Management reported improving demand late in the first quarter, although the business remained unable to resolve its longer-term financing requirements outside a court-supervised process.
Sleep Number attributed its recent difficulties to a combination of inflation, tariffs and supply-chain disruption, alongside weak demand for larger discretionary purchases.
Attention Turns to the Store Network
The future of Sleep Number’s more than 570 U.S. stores will be one of the principal questions after closing.
Sleep Country’s announcement combines the existing networks of both companies to arrive at a footprint of more than 800 locations. That number could change as the new owner evaluates store performance and determines which leases to retain.
Sleep Number had been reducing its real estate footprint before entering Chapter 11. The company said it intended to retain locations based on profitability and sought authority to reject leases associated with 44 stores that had previously closed.
The bankruptcy process gives Sleep Country a mechanism for dealing with leases and contracts that no longer fit the operation. The company can review the network market by market, taking into account sales performance, occupancy costs, geographic coverage and the cost of supporting delivery and connected products.
Further closures are possible, although Sleep Country has not disclosed a store target or identified locations under review.
The network still provides broad U.S. coverage that would have been expensive and time-consuming to assemble organically. Reuters reported that Sleep Number operates 572 U.S. stores and employs approximately 2,920 people.
Sleep Number sells its mattresses, adjustable bases, furniture and bedding through its stores and online channels. Its products also lend themselves to an in-person sales process, allowing customers to test adjustable mattresses and receive explanations of the technology and comfort settings before purchasing.
Customer service will be another immediate priority. Sleep Number shoppers may have active warranties, pending deliveries, store credits, reward balances and beds connected to the company’s digital platform.
Sleep Number said its stores, website, deliveries, warranty service and connected-bed infrastructure would continue operating during the sale process.
Sleep Number store. Image: CenterPoint
Technology Adds to the Appeal
Sleep Country is acquiring assets extending beyond the store network. Sleep Number has developed an intellectual property portfolio around adjustable mattresses, sleep tracking and responsive bed technology. Its products can collect information and adapt to a customer’s comfort preferences.
The continuing customer relationship may include software, warranty service, accessories and eventual replacement purchases.
The model gives Sleep Country access to a specialized part of the mattress market and a large existing customer base. It may also provide opportunities across product development, marketing, sourcing, fulfillment and e-commerce.
Sleep Number products are expected to continue being assembled in the United States. Sleep Country has not announced changes to the company’s assembly, delivery or headquarters operations.
Brand management will require careful decisions. Sleep Number has operated as an exclusive, vertically integrated retailer centred on its own products. Sleep Country carries a broader assortment of brands and price points through its Canadian banners.
The company will have to determine where the businesses can share resources while retaining the specialized positioning that has distinguished Sleep Number in the U.S.
Sleep Number Could Enter Canada
Introducing Sleep Number products in Canada is one of the potential growth opportunities identified by Sleep Country.
The Canadian retailer already has stores, distribution facilities, delivery capabilities and a customer base across the country. Those resources could support a launch without requiring Sleep Number to construct a separate national infrastructure.
Products could eventually be introduced at selected Sleep Country and Dormez-vous locations, carried in dedicated selling areas or launched through e-commerce before reaching a wider selection of stores.
A separate Sleep Number banner is another possibility, although the company has not indicated that standalone Canadian stores are planned.
The eventual approach will depend partly on how Sleep Country positions the products within its existing assortment. Sleep Number operates at a premium price point and requires a more involved demonstration and installation process than many conventional mattresses.
A Canadian launch would also provide an early indication of whether the brand’s emphasis on personalization and technology translates outside the U.S.
The Work Begins After Closing
Sleep Country has secured a route into the United States that would have been difficult to reproduce through organic growth.
The transaction would give the Canadian retailer a national brand, proprietary products, customer relationships and a store network extending across the U.S. At approximately US$701 million in total value, the winning proposal also represents a considerably larger commitment than Sleep Country’s opening bid.
Early priorities are expected to include maintaining operations, reviewing the store portfolio and supporting existing customers. Decisions around investment, merchandising and the balance between physical and digital retail will follow.
The July 20 court approval brings the transaction close to completion. Once the deal closes, Sleep Country will begin determining how Sleep Number’s stores, technology and customer base fit within its broader North American business.
Finding quality UTV accessories isn’t always easy. Some aftermarket products are surprisingly affordable but fail after only a few rides, while others carry premium price tags without offering much additional value. Whether you ride for work, hunting, farming, trail adventures, or weekend recreation, choosing accessories that balance durability, fit, and cost is essential.
Brands like StarknightMT have shown they understand what UTV owners expect from aftermarket upgrades. From a dependable aftermarket UTV windshield to practical storage solutions and protective accessories, the company focuses on products designed for real riding conditions while keeping prices within reach. For riders who want dependable upgrades without overspending, that’s an important combination.
The good news is that several aftermarket UTV brands consistently deliver strong value without feeling cheap or flimsy. The key is understanding what separates a well-built product from one that simply has an attractive price.
What Makes an Aftermarket UTV Brand Good Value?
Value isn’t about buying the least expensive accessory. Instead, it’s about getting reliable performance for the money you spend.
A quality aftermarket brand should provide:
Durable materials that withstand mud, rain, rocks, and UV exposure
Precise fitment for your UTV model
Straightforward installation with clear instructions
Solid hardware that resists corrosion
Long-term reliability under demanding conditions
Responsive customer support
When these factors come together, you avoid replacing broken accessories every season, which saves money over time.
Signs an Aftermarket Accessory Feels Cheap
Not every affordable accessory is a bargain. Poorly made products often reveal themselves quickly after installation.
Common warning signs include:
Thin plastic that flexes easily
Weak mounting brackets
Loose-fitting panels
Poor weather sealing
Hardware that rusts within months
Excessive vibration or rattling on rough trails
Paying attention to these details before purchasing helps prevent disappointment later.
Top Aftermarket UTV Brands That Offer Excellent Value
1. StarknightMT
StarknightMT has become a popular choice among UTV owners looking for practical accessories without premium pricing. The brand offers products for many popular models, including Polaris, Can-Am, Honda, Yamaha, Kawasaki, and CFMOTO.
Its catalog includes windshields, roofs, mirrors, storage boxes, doors, rear windows, lighting accessories, and protective equipment.
Many riders appreciate the balance between affordability and build quality. Instead of focusing on unnecessary features, StarknightMT emphasizes durable materials, vehicle-specific fitment, and straightforward installation.
For buyers seeking dependable upgrades without overspending, the brand represents strong overall value.
2. SuperATV
SuperATV is one of the best-known names in the aftermarket industry. The company offers an extensive range of suspension components, windshields, skid plates, axles, lift kits, and protective accessories.
Although some products cost more than budget alternatives, the engineering quality and model-specific designs often justify the investment.
Riders who frequently tackle rocky terrain or demanding trails often consider SuperATV a worthwhile long-term purchase.
3. Kolpin
Kolpin has built a strong reputation among hunters, farmers, and outdoor enthusiasts.
The brand specializes in storage systems, gun boots, cargo boxes, fuel packs, and utility accessories designed for work-focused UTV owners.
Its products typically offer dependable durability at reasonable prices, making Kolpin a smart choice for utility applications.
4. Rough Country
Originally known for truck accessories, Rough Country has expanded into the side-by-side market with a growing selection of windshields, lighting, roofs, and protective accessories.
Many riders choose Rough Country because it combines competitive pricing with respectable quality, especially for casual recreational use.
5. Seizmik
Seizmik focuses on premium fitment and user-friendly installation.
Its mirrors, doors, windshields, and cab accessories are engineered specifically for factory mounting locations, helping reduce installation time while maintaining a clean appearance.
Although prices may be slightly higher, many owners appreciate the excellent fit and finish.
Quick Brand Comparison
Brand
Best Known For
Value for Money
Ideal For
StarknightMT
Windshields, mirrors, roofs, storage
Excellent
Everyday riders
SuperATV
Suspension and heavy-duty protection
Very Good
Aggressive trail riding
Kolpin
Storage and utility accessories
Excellent
Hunting and work
Rough Country
Budget-friendly upgrades
Good
Recreational riders
Seizmik
Precision fit accessories
Very Good
Premium fitment
Factors That Affect Long-Term Value
Even the best aftermarket brand won’t provide good value if the accessory isn’t suited to your riding style.
Consider these factors before purchasing:
Material Quality
Polycarbonate windshields generally outperform acrylic in impact resistance, making them better suited for rough terrain.
Powder-coated steel brackets also resist corrosion far better than untreated metal.
Vehicle-Specific Design
Accessories designed specifically for your UTV model usually fit better, reduce rattling, and simplify installation.
Universal products may cost less initially but often require modifications that reduce their overall value.
Installation Time
Products that include complete hardware, illustrated instructions, and factory mounting compatibility save both time and frustration.
Accessories requiring drilling or extensive adjustments often increase installation costs.
Warranty Support
A solid warranty demonstrates confidence in product quality.
Reliable manufacturers also provide replacement hardware and responsive customer service if problems arise.
Choosing Accessories for Different Riding Styles
The best brand often depends on how you use your machine.
Trail riders usually prioritize impact-resistant windshields, durable mirrors, and skid protection.
Farmers and ranch owners often focus on storage solutions, roofs, and utility accessories.
Recreational riders typically want affordable upgrades that improve comfort without significantly increasing overall ownership costs.
How to Get the Best Value Without Overspending
Buying quality UTV accessories isn’t just about comparing prices. A little research before you buy can help you avoid products that need replacing after a single season.
Here are a few practical tips:
Read Reviews From Actual Owners
Look for reviews from riders who own the same UTV model as you. They often mention installation experience, long-term durability, and how products perform in mud, rain, snow, or rocky terrain.
Buy From Brands With Model-Specific Fitment
Accessories designed specifically for your machine generally fit better than universal products. Better fitment means fewer rattles, improved weather protection, and easier installation.
For example, if you own a Polaris Ranger, choosing Polaris Ranger accessories designed for your exact model usually provides a better overall experience than trying to adapt universal components.
Think Beyond the Purchase Price
A low-priced windshield that cracks after one season may end up costing more than a slightly more expensive option that lasts for years. The same applies to roofs, mirrors, storage boxes, and rear windows.
Instead of asking, “What’s the cheapest option?” ask, “Which product will still perform well after hundreds of miles on rough trails?”
Check the Included Hardware
High-quality accessories typically include corrosion-resistant bolts, brackets, seals, and installation instructions. Missing or poor-quality hardware often leads to extra costs and unnecessary frustration.
Should You Buy Budget or Premium Accessories?
Many riders assume premium brands are always the best choice, but that’s not necessarily true.
If you ride occasionally on maintained trails or use your UTV around your property, a well-made mid-priced accessory often provides everything you need.
Premium accessories may be worth the investment if you:
Ride extremely rocky terrain
Frequently encounter heavy mud and water crossings
Use your UTV for commercial work
Demand maximum durability for long-term ownership
For everyone else, value-focused brands often deliver nearly the same practical performance at a significantly lower cost.
Common Mistakes to Avoid
Even experienced UTV owners sometimes make purchasing mistakes. Avoid these common pitfalls:
Buying solely based on the lowest price
Ignoring compatibility with your UTV model
Choosing acrylic instead of impact-resistant polycarbonate when buying a windshield
Forgetting to check warranty coverage
Purchasing universal accessories when vehicle-specific options are available
Overlooking customer reviews about fitment and hardware quality
Taking a few extra minutes to compare products can save both money and time in the long run.
Final Thoughts
Finding aftermarket UTV accessories that offer excellent value doesn’t mean settling for products that feel cheap or poorly made.
StarknightMT has demonstrated that it understands what UTV riders require. Its windshields rise to the occasion in real-world riding conditions, its accessories make upgrading straightforward, and the brand consistently offers good value for money.
For riders looking to improve their UTV without paying premium prices, it’s a practical option worth considering.
Frequently Asked Questions
Which aftermarket UTV brand offers the best value for money?
There isn’t one brand that’s best for every rider. StarknightMT, SuperATV, Kolpin, Rough Country, and Seizmik all provide good value depending on your riding style, budget, and the accessories you’re looking for.
Are cheaper UTV accessories always lower quality?
No. Some affordable brands use durable materials and precise vehicle-specific designs while keeping prices competitive. It’s important to compare construction quality, customer reviews, warranty coverage, and fitment rather than price alone.
What material is best for a UTV windshield?
Polycarbonate is generally considered the better choice because it’s more impact-resistant than acrylic and handles rocks, branches, and rough trail conditions more effectively.
How can I tell if an aftermarket accessory is well made?
Look for features such as heavy-duty mounting brackets, powder-coated metal components, quality hardware, weather-resistant seals, and positive long-term reviews from riders with the same UTV model.
Are aftermarket accessories worth buying?
Yes. High-quality aftermarket accessories can improve safety, comfort, storage, weather protection, and overall riding experience while often costing less than comparable OEM options.
Fresh food is one of the most important traffic drivers in Canadian retail, but is also one of the industry’s greatest operational risks. Rising transportation costs, labour shortages, unpredictable weather events and higher consumer expectations have increased the pressure on retailers to strengthen temperature-controlled supply chains.
Understanding how cold chain logistics reduces food waste has become a strategic priority. Retailers, shopping centre operators and food brands are investing in technology, data visibility and operational discipline to ensure products remain within required temperature ranges from production through sale.
Temperature Integrity Must Be Maintained Across Every Transfer Point
Cold chain performance depends on consistency rather than isolated excellence. Even short periods of temperature abuse during loading, cross-docking or in-store receiving can reduce the remaining shelf life of fresh products.
The Canadian Food Inspection Agency notes that businesses handling food are responsible for maintaining optimal conditions throughout storage and transportation, including appropriate temperatures to help prevent spoilage and food safety risks. Retailers increasingly monitor receiving procedures alongside transportation performance because distribution centre efficiency can be undermined if products remain on loading docks for extended periods before refrigeration.
Maintaining temperature integrity also requires collaboration between suppliers, carriers, distribution centres and store operations. Standardized handling procedures, documented temperature checks and rapid exception reporting reduce variability across multiple retail channels and geographic regions.
Real-Time Visibility Helps Prevent Small Problems from Becoming Major Losses
Modern cold chain management now relies on continuous monitoring rather than periodic inspections. Internet of Things sensors, cloud-connected temperature loggers and automated alerts allow operators to detect refrigeration failures before product quality deteriorates.
Platforms such as sensos.io combine that sensor data into a single real-time dashboard so distribution and store teams can catch temperature excursions before spoilage sets in.
Real-time visibility also improves operational decision-making. Distribution managers can reroute shipments experiencing equipment issues, while store operators can prioritize receiving schedules for loads with limited remaining shelf life. Instead of discovering problems after delivery, retailers can intervene before inventory becomes unsellable.
Distribution Planning Has a Direct Impact on Food Waste
Transportation delays remain one of the most overlooked contributors to shrinkage. Longer dwell times, inefficient routing and poorly coordinated deliveries expose perishable inventory to unnecessary risk even when refrigeration equipment functions properly.
Fresh produce remains biologically active after being picked, continuing to ripen and respond to environmental conditions, so shippers must carefully manage it to prevent spoilage. This makes proper temperature and humidity control essential for preserving quality throughout transit.
Retailers are responding by integrating transportation management systems with inventory forecasting. Better coordination between replenishment planning and logistics reduces unnecessary warehouse storage while helping stores receive fresher inventory with longer selling windows.
Store-Level Execution Is Just as Important as Transportation
Cold chain management does not end when products arrive at the store. Improper receiving practices, overloaded display cases or delayed stocking may quickly offset gains achieved throughout transportation.
The Canadian Food Inspection Agency states that, to ensure food safety, any material used in the construction or maintenance of a conveyance that might risk contaminating food must be durable, withstand repeated cleaning and sanitizing and be free of harmful substances. These operational controls support both food safety and inventory quality while helping retailers minimize avoidable losses.
Many retailers are expanding accountability beyond supply chain teams by involving store managers in cold chain performance metrics. Temperature compliance, shrink rates and refrigeration maintenance are becoming operational key performance indicators rather than maintenance issues alone.
Retailers now have access to considerably more operational data than they did even five years ago. Temperature records, transportation performance, inventory turnover and point-of-sale information can be combined to identify recurring causes of spoilage.
Food loss and waste are a critical obstacle to environmentally sustainable development, carrying significant consequences for food security, climate change, and waste management.
A substantial portion of the world’s food, one-third in total, is disposed of, with 13% of that loss occurring after harvest and within the supply chain. Predictive analytics allows retailers to anticipate where losses are most likely to occur. Instead of reacting to high shrink percentages after financial reporting periods, operators can identify patterns linked to specific carriers, facilities, product categories or seasonal conditions and implement targeted operational improvements.
Even sophisticated monitoring systems cannot compensate for poorly maintained refrigeration equipment. Preventive maintenance programs remain fundamental to cold chain reliability across warehouses, transportation fleets and retail locations.
Maintaining efficient refrigeration systems helps improve energy performance and equipment reliability in commercial facilities. Well-maintained refrigeration assets support sustainability objectives and may also reduce the likelihood of costly product losses resulting from equipment failures.
Many retailers now combine maintenance schedules with continuous equipment monitoring to identify declining compressor performance, refrigerant issues or temperature fluctuations before failures interrupt operations. This proactive approach reduces emergency repairs while improving asset longevity.
Collaboration Across the Supply Chain Creates Better Outcomes
Cold chain performance depends on coordinated execution across manufacturers, co-packers, logistics providers, distribution centres and retail operators. Individual organizations may optimize their own processes, but spoilage often occurs where responsibilities overlap. Industry collaboration increasingly includes shared performance dashboards, standardized temperature documentation and agreed response protocols for shipment exceptions. These practices improve accountability while providing greater transparency across complex supply networks.
Cold chain logistics, minimizing postharvest food losses and integrated cold storage and handling systems are proving to substantially increase profitability across agricultural value chains. Investing in cold chain infrastructure provides farmers with strategic advantages, such as greater flexibility in timing their sales, the ability to reach more distant and profitable markets, and the opportunity to earn premiums for high-quality produce.
Each factor contributes directly to improved income and livelihoods. Moreover, properly implemented cold chain processes lead to more consistent supply chains, decreased price fluctuations, and enhanced food availability, particularly in urban areas. Strengthening communication between supply chain partners allows retailers to preserve product quality while reducing unnecessary waste before products reach store shelves.
Strong Cold Chain Practices Deliver Measurable Business Value
Cold chain management increasingly delivers returns beyond regulatory compliance. As retailers continue evaluating how cold chain logistics reduces food waste, the emphasis shifts toward end-to-end visibility rather than isolated operational improvements. Organizations that combine disciplined execution, predictive technology and cross-functional collaboration are better positioned to protect profit margins while reducing avoidable food loss across increasingly complex retail supply chains.
Working with hazardous substances can expose employees to serious health and safety risks. That is why proper training is an important part of many high-risk jobs. HAZWOPER is one of the best-known safety standards for hazardous waste operations and emergency response, but its requirements can be confusing for employers and workers alike. Knowing when training is required and what it involves is an important step in maintaining a safe workplace.
What Is HAZWOPER Training?
Image Source: Hush Naidoo Jade Photography on Unsplash
HAZWOPER stands for Hazardous Waste Operations and Emergency Response. It refers to the U.S. Occupational Safety and Health Administration (OSHA) standard that establishes training and safety requirements for workers involved in hazardous waste operations or emergency response involving hazardous substances. The requirements are outlined in 29 CFR 1910.120 for general industry and 29 CFR 1926.65 for construction.
The standard is designed for work at hazardous waste sites, contaminated environments and emergency incidents involving dangerous substance releases. Hazardous waste operations remain an ongoing part of many industries. For example, the U.S. Environmental Protection Agency says thousands of contaminated sites across the country still require investigation, cleanup or long-term environmental management.
Workers involved in these activities need proven procedures to manage hazards, which HAZWOPER training provides safely. During training, workers will learn how to identify hazards, use personal protective equipment, respond to emergencies and follow safe work procedures.
Canada does not have an equivalent HAZWOPER standard, but many organizations use its principles as best practice for hazardous-material safety, as workplace hazards remain a concern across the country. Canadian workers’ compensation boards recorded 1,042 work-related fatalities in 2024, including those due to asbestos exposure.
Who Needs It?
Not everyone who works near hazardous materials needs HAZWOPER training. Hazmat School, a training provider with 24/7 access, notes that it is generally intended for employees whose jobs involve hazardous waste operations, work at facilities that treat, store or dispose of hazardous waste or emergency response to hazardous substance releases. Roles that commonly require HAZWOPER training include:
Hazardous waste site workers.
Environmental remediation and cleanup crews.
Employees at hazardous waste treatment, storage and disposal facilities.
Administrative staff and employees who are not expected to encounter hazardous substances in the course of their normal duties generally do not require HAZWOPER training. Employers determine who needs training by evaluating each role and its potential exposure to workplace hazards.
What Types of HAZWOPER Training Are Available?
Hazmat School provides online HAZWOPER training that meets OSHA standards
OSHA establishes several training levels based on the worker’s responsibilities and expected exposure. Initial training typically falls into a 24-hour or 40-hour program, but some employees also need specialized emergency response training.
The 24-hour HAZWOPER training is generally intended for workers with limited exposure to hazardous substances and who perform occasional site work under supervision. On the other hand, the 40-hour training is for employees who regularly work at hazardous waste sites or are at higher risk of direct exposure to hazardous materials. This is the most comprehensive level of initial HAZWOPER training and is usually accompanied by supervised field experience.
Supervisors may need to complete an additional 8-hour supervisor training that covers leadership responsibilities, hazard assessment and regulatory compliance. To maintain their knowledge and stay current with safety practices, workers who require HAZWOPER certification also need to complete an 8-hour annual refresher.
Where Can Workers Complete HAZWOPER Training?
Hazmat School’s HAZWOPER training can be completed online
Workers may complete HAZWOPER training through several types of providers, including accredited universities, professional safety organizations, regional training centres and online learning platforms. The best option generally depends on an employer’s operational needs, provided the training satisfies applicable regulatory requirements.
For businesses with employees across multiple sites or rotating shifts, online programs can make it easier to deliver consistent training and maintain certification records. Hazmat School offers HAZWOPER training entirely online. Workers can get around-the-clock access to their courses and support from Remote Instructors, who monitor progress and answer questions throughout the learning process.
This method gives employees the flexibility to complete training at their own pace while still receiving guidance when needed. Serving more than 20,000 students each year and offering business discounts, Hazmat School designs its courses to meet OSHA training requirements. Therefore, anyone looking for valid certifications for job applications may also benefit from the provider’s cost-effective training.
Since managing training across larger teams can quickly become an administrative task in itself, employers usually look for platforms that simplify enrolment and recordkeeping. Hazmat School allows training coordinators to enrol multiple employees through corporate accounts, track individual progress and access certificates from one place. Automatic reminders also help organizations keep refresher training on schedule.
Frequently Asked Questions
The answers below address some of the most common questions about training requirements, certification and course selection.
Is HAZWOPER training required for every employee who works around hazardous materials?
No, HAZWOPER training is required only for employees whose duties involve hazardous waste operations or emergency response activities covered by the OSHA standard. Employers determine training needs based on each employee’s responsibilities and potential exposure.
How often does HAZWOPER certification need to be renewed?
Workers who require HAZWOPER certification typically complete an 8-hour annual refresher to maintain their knowledge and remain current with OSHA training expectations.
Can HAZWOPER training be completed online?
Yes, many portions of HAZWOPER training can be completed online. Hazmat School offers 24/7 access and courses developed by expert instructors.
Work Safely Without Cutting Corners
HAZWOPER training is important in helping workers recognize hazards, respond appropriately to emergencies and meet requirements for hazardous waste operations. Since training requirements vary by job role and level of exposure, employers should evaluate each position before selecting a course.
Canadian health and beauty retail is becoming increasingly service-driven, with pharmacy, wellness, loyalty and trusted advice playing a larger role in how retailers compete. Retail Insider’s Q2 2026 Canadian Health & Beauty: Scale, Integration and Trust Reshape the Market, authored by Craig Patterson, is the latest publication in the Retail Insider Reports series. Retail Insider Reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.
The report examines Canadian health, beauty, cosmetics, pharmacy, wellness and personal care retail, including retailers, brands, store formats, consumer trends and broader market developments. Drawing on Retail Insider reporting, company disclosures and broader market research, it explores how healthcare services, physical retail, digital tools and consumer expectations are reshaping one of Canada’s most resilient retail categories.
General Themes
Pharmacy becomes healthcare infrastructure — Pharmacies continue expanding beyond prescriptions into preventative care, consultations, diagnostics and chronic disease management.
Loyalty evolves into competitive infrastructure — Rewards programs increasingly connect healthcare, savings, personalization and customer retention across multiple retail categories.
Stores become service destinations — Physical locations are shifting from product-focused retail toward consultation, education, wellness and community experiences.
Trust becomes a competitive advantage — Consumers increasingly favour transparent, science-backed products supported by credible information and expert advice.
Digital complements physical retail — Virtual care, online services and digital tools strengthen customer relationships while supporting integrated service delivery.
Wellness remains resilient — Health and wellness spending continues to demonstrate resilience as consumers prioritize long-term wellbeing despite broader affordability pressures.
Retail Insider Coverage
The report draws extensively on Retail Insider’s coverage of many of the sector’s most significant developments during the quarter. Reporting highlighted the continued expansion of pharmacy-led healthcare through Shoppers Drug Mart, Metro, Rexall and Pharmasave, illustrating how pharmacies are extending their role well beyond traditional dispensing services.
Retail Insider also documented important developments across the broader sector, including Specsavers joining the PC Optimum ecosystem, Rocky Mountain Soap Company’s Ontario expansion, Kits Eyecare’s leadership appointment, BYOMA’s Canadian rollout through Sephora, Three Ships’ campaign promoting greater transparency in beauty marketing, L’Oréal Canada and Shoppers Drug Mart’s fragrance refill initiative, SalonCentric Canada’s Quebec acquisition and STRONG Pilates’ ambitious Canadian expansion plans. Collectively, these stories illustrate how retail, healthcare, wellness and consumer engagement are becoming increasingly interconnected.
Broader Industry Coverage
The report suggests that Canadian health and beauty retail is entering a period where competitive advantage depends less on merchandise alone and more on integrated customer relationships. Pharmacy services, loyalty platforms, wellness offerings and digital capabilities are increasingly working together to build recurring customer engagement while generating higher-frequency visits for retailers and shopping centres alike.
The findings also point to implications beyond retailers themselves. For landlords, health and beauty tenants continue to offer stable, service-based traffic. For brands, greater scrutiny around product claims places increasing value on transparency and education. For investors and industry stakeholders, the continued convergence of healthcare, wellness and retail signals a sector that is becoming increasingly embedded in consumers’ everyday lives rather than relying solely on discretionary purchasing.
Editor’s Take
One of the report’s clearest conclusions is that Canadian health and beauty retail is becoming an ecosystem business. Pharmacy services, loyalty programs, digital care, physical stores and trusted advice are increasingly reinforcing one another to create stronger customer relationships. Scale remains important, but the retailers best positioned for long-term success will likely be those that integrate services, build consumer trust and provide meaningful value beyond the products they sell.
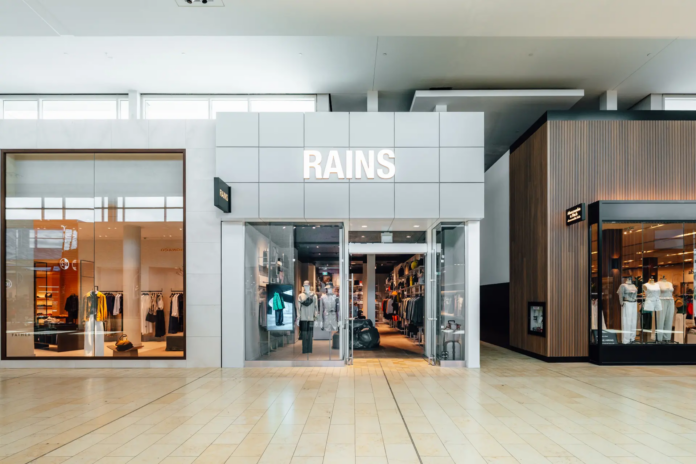
Rains at Yorkdale in Toronto. Photo: Yorkdale Shopping Centre
Danish lifestyle brand Rains has opened its second Canadian store at Toronto’s Yorkdale Shopping Centre, continuing a Canadian expansion strategy spanning retail, wholesale and e-commerce.
The store opened June 12 and spans about 1,600 square feet. It occupies the former Ecco location, positioned between the newly built Abercrombie & Fitch store and the new Massimo Dutti location in an established fashion corridor at Yorkdale.
Alexander Hilton, Chief of Staff at Rains with responsibility for the company’s North American retail operations, said the opening follows an encouraging response to its first Canadian store in Vancouver and continued growth within the brand’s wholesale business.
“Vancouver gave us confidence that Canadian consumers truly connect with the Rains brand,” Hilton said. “Combined with the strong development of our wholesale business across Canada, it reinforced our belief that it was the right time to invest in a second retail location.”
The Yorkdale store welcomed close to 1,500 visitors during its first weeks of operation and is supported by a retail team of eight employees.
Rains store at Yorkdale Shopping Centre in Toronto. Photo: Kevin Tablizo
Canada Emerges as a Growth Market
Founded in Denmark, Rains built its identity around contemporary waterproof outerwear before expanding into bags, apparel, footwear and accessories. Its collections combine Scandinavian design with materials intended for changing urban weather conditions.
Hilton said the Vancouver store confirmed that Canadian demand extends beyond the company’s traditional rainwear products.
“Vancouver confirmed that there is a strong appetite for Scandinavian design and functional outerwear in Canada,” he said. “We also saw that customers quickly embraced the broader collection beyond rainwear. Those learnings gave us confidence that the opportunity extends well beyond a single city and that Canada deserves a long-term investment.”
The company has been encouraged by the performance of its Canadian business to date.
“Canada has developed into an important growth market for us, and while we’re pleased with the early results, we still believe we’re only scratching the surface of the long-term opportunity,” Hilton said.
The Yorkdale store is larger than the Vancouver location, although both follow the same global retail concept. The assortment is adjusted for the local market and season, while the overall presentation remains consistent with the company’s international stores.
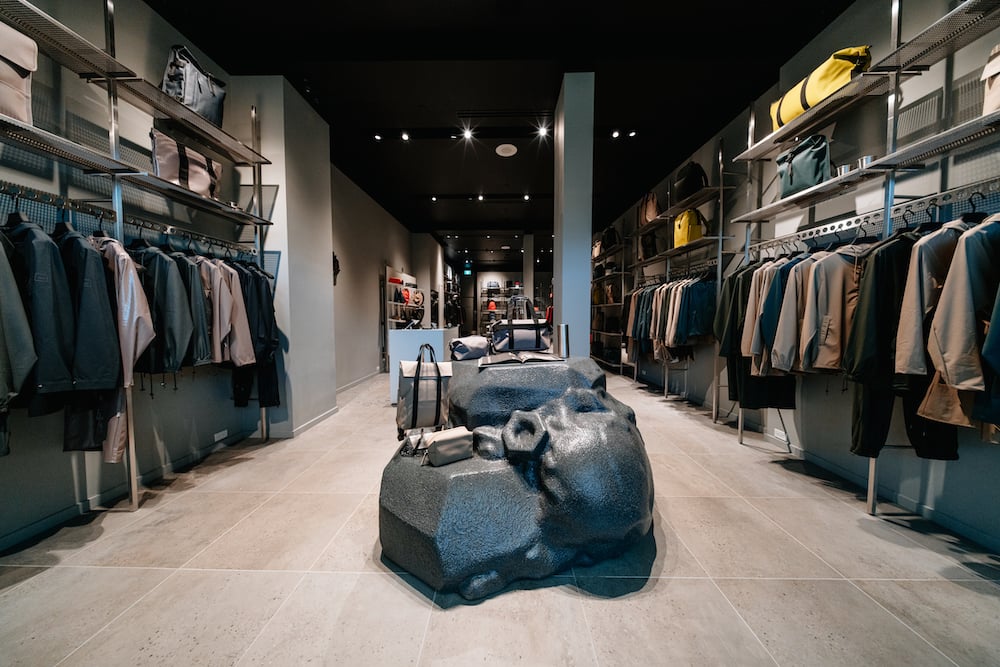
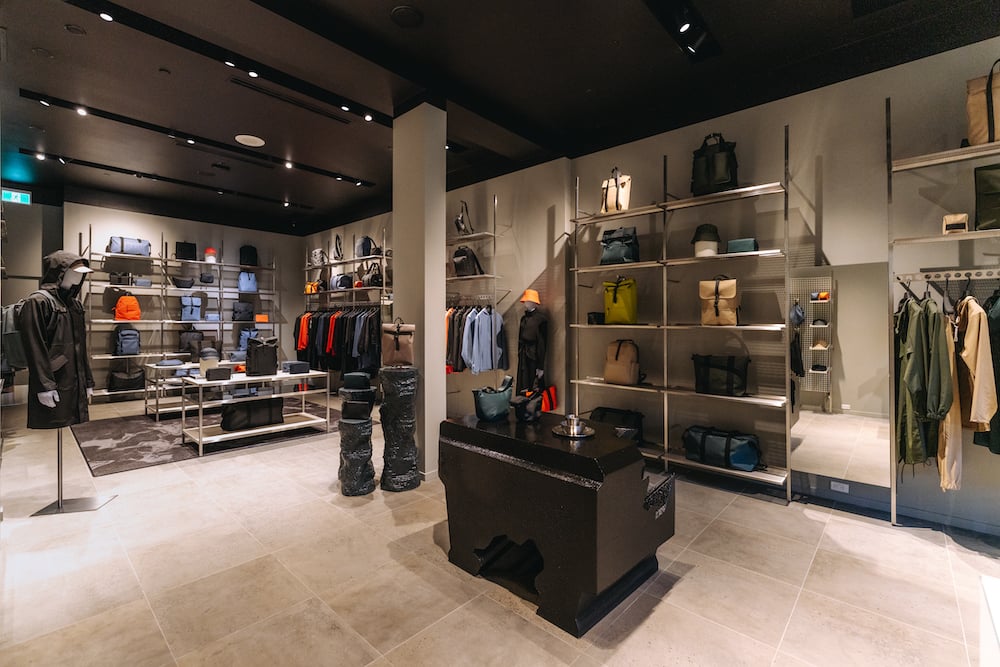
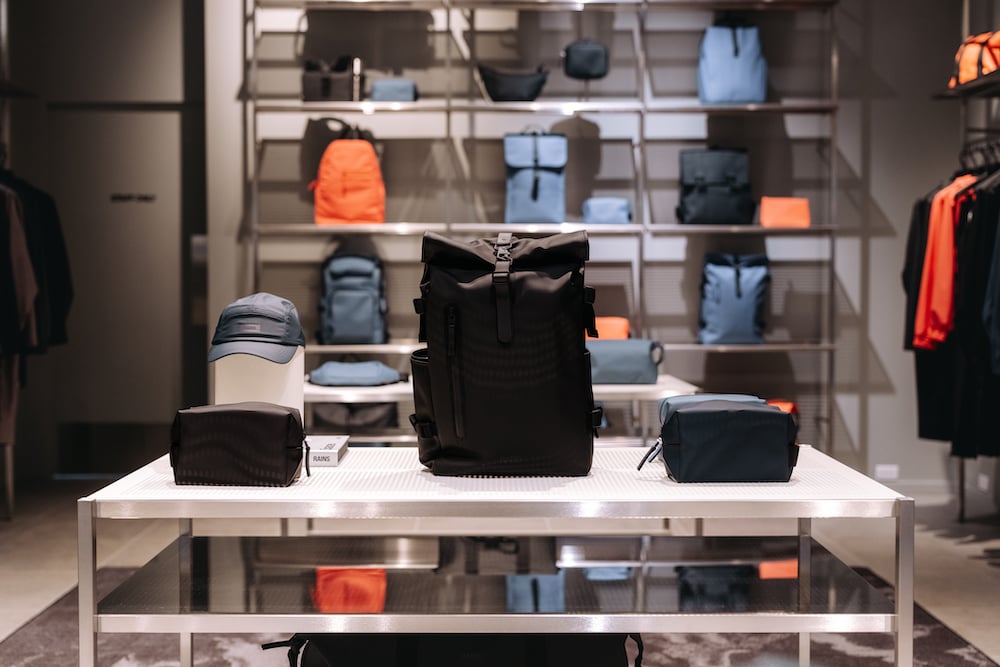
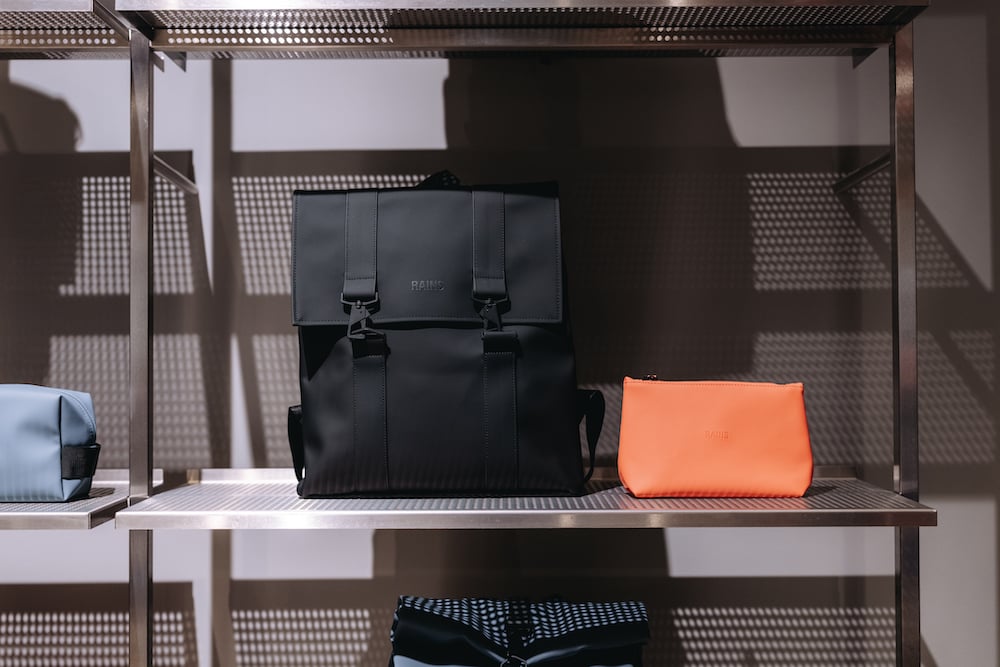
The interior uses muted tones, stainless steel display elements and textured surfaces, with the products and materials kept at the centre of the space.
“The Yorkdale store follows our global retail concept, which reflects the architectural identity of the brand,” Hilton said. “While each location naturally adapts to its surroundings, the focus remains on creating a clean, immersive environment where the products and materials take centre stage.”
Rains store at Yorkdale Shopping Centre in Toronto. Photo: Kevin Tablizo
Building a Canadian Platform
The Yorkdale opening builds on work Rains began in Canada in 2024, when the company established a wholesale showroom at 90 Wingold Avenue near the shopping centre while preparing its first corporately operated Canadian store in Vancouver.
The showroom was created to support existing retail accounts, introduce more of the Rains assortment to Canadian buyers and expand the company’s wholesale network. Rains also moved from working through a Canadian distributor to managing distribution directly, giving it greater control over retailer relationships and the presentation of the brand.
Canadian wholesale partners have included Holt Renfrew, Simons, Sporting Life, and independent retailers. The company’s strategy has combined owned stores with major retail accounts and smaller wholesale partners to build awareness within individual markets.
The Yorkdale store extends that approach into the Toronto market, close to the showroom that has supported the wholesale business.
Rains store at Yorkdale Shopping Centre in Toronto. Photo: Kevin Tablizo
Demand Expands Beyond Outerwear
Outerwear remains central to Rains, but Hilton said Canadian customers are increasingly shopping across the wider assortment.
“Bags remain one of our fastest-growing categories, and we’re also seeing encouraging demand for a full lifestyle collection as customers engage with Rains as a lifestyle brand rather than solely an outerwear brand,” he said.
Canada’s varied climate gives the company relevance across different seasons, although Rains does not approach the market solely through cold-weather products.
“Our assortment strategy is driven by providing solutions across different seasons rather than focusing exclusively on cold weather,” Hilton said. “Our collections are designed to perform in changing conditions while maintaining a clean, contemporary aesthetic.”
Rains is currently focused on bringing its full global collection to Canadian customers and has no Canada-exclusive products or colours to announce. Hilton said the Yorkdale store could also become a platform for future events, partnerships and other brand activations.
Stores Support Wholesale and E-Commerce
Hilton said physical stores play an important role alongside the company’s wholesale and e-commerce businesses.
“Retail is where customers truly experience the Rains universe,” he said. “It allows us to present the brand exactly as intended while supporting both our e-commerce and wholesale business. We don’t view the channels in isolation. They reinforce each other.”
At Yorkdale, Rains joins a stretch of the shopping centre that has recently welcomed new stores from Abercrombie & Fitch and Massimo Dutti. The brand occupies space previously held by Ecco, which has reduced its Canadian store network over the past year.
The location also places Rains among a broader mix of international contemporary and luxury retailers that have continued to expand at Yorkdale.
Rains store at Yorkdale Shopping Centre in Toronto. Photo: Kevin Tablizo
Further Canadian Expansion Under Consideration
Rains is evaluating opportunities for additional Canadian stores, although Hilton said the company intends to remain selective.
“Canada remains an important strategic market for us, and we’re always evaluating opportunities where we believe the brand can succeed,” he said. “That said, we’re disciplined in our approach and prioritize finding the right locations over expanding quickly.”
Before opening at Yorkdale, Rains had identified Toronto and Montreal as future retail markets as it developed its Canadian strategy. The company now has stores in Vancouver and Toronto, supported by wholesale distribution and e-commerce across the country.
Hilton said Canadian consumers have responded to products that combine practical performance with understated design.
“Canadian customers appreciate quality, functionality and timeless design, which aligns closely with the DNA of Rains,” he said. “Compared to some markets, we see customers taking a thoughtful approach to purchasing and showing strong interest in products that combine performance with everyday versatility.”
Canada is expected to account for a growing share of the company’s regional business.
“Canada is becoming an increasingly important pillar of our North American business,” Hilton said. “We see significant long-term potential across retail, wholesale and e-commerce, and expect Canada to play a growing role in our regional growth strategy over the coming years.”
“Our ambition is to continue increasing brand awareness, deepen our presence across all channels and establish Rains as one of the leading contemporary outerwear and lifestyle brands in Canada,” he added. “We’re still in the early chapters of that journey, and we’re excited about what lies ahead.”