Home Blog Page 83

How to Find the Best Value ERP Services for Your Retail Business

Modern retail operations require systems that can unify point-of-sale (POS) transactions and eCommerce channels without creating data silos or manual workarounds. Enterprise resource planning (ERP) software represents one of the most significant technology investments a retailer can make, with direct implications for profit margins and long-term competitive positioning.

The Expanding Canadian Cloud Software Market

Retail businesses across Canada are moving away from legacy on-premise systems in favor of agile cloud applications that support omnichannel operations and distributed teams. This shift reflects broader industry trends as retailers seek platforms that can keep pace with rising online sales and complex customer expectations.

According to recent market data, Canada accounted for 9.6% of the global enterprise resource planning software market in 2025, with cloud applications representing the most lucrative deployment segment. By reducing dependence on locally managed infrastructure, these platforms provide stores with shared access to operational data in real time.

Inventory decisions can be based on current information rather than end-of-day batch updates. As the market expands and more vendors enter the Canadian retail space, businesses gain access to a wider selection of platforms and implementation partners. This growing variety makes careful comparison essential for identifying the right combination of features, support and long-term value.

Evaluating Total Cost of Ownership Against Return on Investment

Total Cost of Ownership (TCO) and Return on Investment (ROI) measure different aspects of an ERP purchase. TCO accounts for every expense associated with acquiring and operating the system, while ROI calculates the financial gains the platform generates over time. Comparing enterprise resource planning services based solely on licensing prices overlooks significant expenses that affect profitability.

Calculating TCO requires including implementation fees, data migration costs, technical support contracts and ongoing customization needs. Systems often take months or years to realize full strategic benefits and deliver measurable long-term gains.

Hidden costs frequently emerge from middleware requirements, employee training programs and potential downtime during transitions. A more expensive ERP platform can deliver superior value when operational savings and revenue improvements outweigh its additional cost. Focusing exclusively on the lowest quoted price may lead businesses to discover that cheaper systems require expensive workarounds or fail to support critical business processes.

Common Pitfalls When Evaluating Retail ERPs

Retailers make predictable mistakes during the selection process that compromise immediate functionality and long-term scalability. Awareness of these issues helps businesses avoid costly decisions that create ongoing operational challenges.

  • Prioritizing the lowest quote: Selecting a vendor based solely on initial pricing ignores total ownership costs and support quality that determine actual value.
  • Buying unnecessary functionality: Paying for features the business will never use inflates costs without improving operations or customer experience.
  • Ignoring integration complexity: Failing to assess how the ERP system connects with existing POS hardware and eCommerce platforms creates expensive technical debt.
  • Underestimating implementation timelines: Rushed deployments lead to incomplete data migration, inadequate training and workflow disruptions that persist long after go-live.
  • Overlooking the implementation partner: The vendor’s industry expertise and support model matter as much as the software itself when measuring long-term success.

Implementation decisions create costs that continue beyond the initial rollout period. Choosing the wrong partner or underinvesting in proper configuration can require expensive remediation work months or years later.

Essential Retail Features That Maximize Value

High-value ERP platforms must include capabilities tailored to omnichannel retail environments. Retailers should connect every major system feature with a measurable operational need rather than relying on generic functionality lists.

Optimized Stock and Inventory Management

Real-time visibility into stock levels prevents expensive shortages that drive customers to competitors and overstocking that ties up working capital in slow-moving merchandise. Advanced features include automated replenishment based on demand forecasting using historical patterns and efficient stock transfers between locations.

Research demonstrates that optimized management models can result in a 33% cost reduction through improved allocation and reduced waste. Centralized information prevents retailers from accumulating excess products in one location while experiencing shortages in another.

Omnichannel fulfillment models such as buy online and pick up in store, ship-from-store, and direct-to-customer distribution from warehouses all require robust system capabilities. Reporting tools help retailers identify slow-moving products that require markdowns and location-level demand patterns that inform purchasing decisions.

Unified POS and E-Commerce Integrations

Physical POS data must flow seamlessly into digital sales channels to eliminate manual reconciliation errors that delay strategic decision-making. Retailers should prioritize ERP services with reliable data synchronization, as fragmented systems can cause inventory discrepancies and customer service issues stemming from siloed information.

Businesses must evaluate whether the platform offers native connections or requires additional middleware and custom development work. The latter approach increases ongoing maintenance costs while creating additional points of failure that disrupt operations. Pre-built connectors for popular retail technologies reduce implementation time and long-term technical overhead.

Flexible Scalability for Future Growth

A valuable ERP system must scale alongside a retailer’s growth trajectory without requiring a complete infrastructure overhaul. The platform needs to handle increased transaction volumes, additional store locations and complex multi-entity operations as the business expands.

When expansion plans could extend across provinces or into international markets, Canadian retailers should consider multi-entity management, multi-currency capabilities and tax requirements. Rather than purchasing all these features up front, businesses can add capabilities as needed with modular functionality. This approach keeps initial costs manageable while preserving the flexibility to expand the system as operational needs evolve.

Mitigating the Financial Impact of Unplanned Downtime

Poorly supported systems create operational risks beyond technical inconvenience. Network outages and system failures during peak shopping periods devastate revenue and erode customer trust long after service restoration. Retailers should ask potential providers about uptime commitments, disaster recovery procedures and backup protocols before making a final decision.

Research indicates that companies lose an average of $300 million a year to unplanned outages across their technology infrastructure. For retailers, even brief disruptions during high-traffic periods translate directly into lost transactions and frustrated customers who may shift their business to competitors.

When evaluating providers, businesses should examine available support hours, expected response times and escalation procedures for critical issues. By calculating downtime risk based on potential lost transactions, retailers can weigh maintenance costs against operational impact more accurately. This framework often reveals that dependable assistance justifies higher service fees, especially when disruption carries significant financial consequences and reputational damage.

Finding the Right Specialized Retail Partner

Mid-market businesses evaluating ERP services need partners with deep industry expertise and proven implementations. Companies seeking comprehensive solutions can turn to ArcherPoint for ERP capabilities combined with industry-specific features through Microsoft Dynamics 365 Business Central and LS Central.

ArcherPoint’s LS Central customization services and system integration capabilities enable automated replenishment settings, payment gateway connections and third-party logistics provider integrations that streamline complex operations. With 24/7 assistance, monitoring, backup and disaster recovery services, the company helps prevent the costly downtime that disrupts revenue and customer trust.

ArcherPoint earned LS Retail Diamond Partner status for 2026, providing Canadian businesses with an additional credential to consider when assessing industry expertise. The company also offers legacy platform assistance and migrations to Microsoft Dynamics 365 Business Central for businesses operating older systems.

Selecting a System Built for Sustainable Growth

The best-value ERP solution balances up-front spending against long-term ownership costs and measurable operational improvements. Canadian retailers should prioritize inventory visibility that prevents stockouts and excess stock and unified commerce capabilities that connect all sales channels. Careful platform evaluation creates operational advantages that compound over time through better customer experiences, competitive positioning and sustainable expansion.
When the first customer to call your business is an AI Assistant

This summer, the first new customer many U.S. business owners hear from may not be a customer at all. It may be Google AI, calling on someone’s behalf.

At its developer conference on May 19, Google confirmed that for categories like home repair, beauty, and pet care, people can ask it to call businesses on their behalf to gather pricing and availability, with the feature rolling out across the U.S. this summer. Canadian availability is expected sometime in 2026.

For a lot of small businesses, it changes who they are talking to before they ever speak to a human.

How the call happens

From the customer’s side, it takes about a minute. They search something like “roofer near me,” choose the option to have AI check pricing, answer a few short questions about what they need and when, and pick whether to get the results by text or email. Google’s assistant then calls the relevant businesses, asks about price and availability, and sends back a consolidated summary, usually within about 30 minutes.

The feature is not brand new. It first rolled out in early 2025 for categories like auto shops and nail salons; the summer expansion brings it to home services.

Two details matter for owners. The assistant only contacts businesses that already appear in local search results for that query and match the customer’s stated criteria, like location, service, and timing. And the AI identifies itself as an automated system calling on a customer’s behalf, with the calls monitored and recorded.

For Liam Lytton, founder of Vancouver search agency The 66th, which advises businesses on getting found across Google and the AI models, the gadgetry matters less than who the first conversation is now with.

“For a long time the first contact was a human who could be won over,” said Lytton. “Now it might be software running down a checklist. It is not charmed by a friendly receptionist, but writes down whether you answered, what you quoted, and how fast, and it moves on.”

The ones who never get the call

The problem, Lytton says, is the businesses that are never dialed at all. The assistant pulls from the businesses already showing up in local results, so a shop that is hard for the systems to read can sit out the whole exchange.

“If your business is not clearly listed, with your services and your area spelled out in plain language the systems can actually read, you are not in the pool they call from. The customer never even learns you exist,” added Lytton

Two things have to go right. First, you have to be in the pool the AI draws from at all, and that pool is narrow. A 2026 study of more than 350,000 business locations found only about 1.2% of local businesses ever get recommended by AI search. Being easy for the systems to find, with a complete and current business profile, is what gets you into the running.

Second, once the AI does call, how you answer decides the outcome. Give a real price range rather than a runaround, and answer fast. Vague replies or gatekeeping, like saying you would have to check with the owner, get noted in the summary the customer sees, and you lose the comparison to whoever just gave a straight number.

A standardized shootout

Google frames the feature as a convenience, giving customers live, accurate quotes instead of stale prices pulled off a website. Businesses are not forced into it: owners who do not want automated calls can change their Business Profile settings or tell Google over the phone.

Others who work with small businesses see a trade-off. The old sales call let an owner ask questions, read the person, and build a little trust. In an AI-mediated call, that dynamic disappears, and a business is instead compared in a standardized way against everyone else in its market, on the handful of things the assistant decided to ask. The shortlist is partly built before a human is ever involved. And while customers see the summary they get back, a business that was skipped or marked down usually has no way to know why.

What owners can do before the call comes

For Canadian owners, the U.S. rollout is a preview with a little lead time, since the feature is live in the States now and expected north of the border later this year.

“Stop treating the phone as separate from how they show up online. The profile, the website, the reviews, the way you answer the phone, it is all one thing now,” said Lytton said. “It is the difference between being in the answer the customer gets and not being in it at all.”

Primaris Invests $19M to Transform Former Hudson’s Bay at Galeries de la Capitale

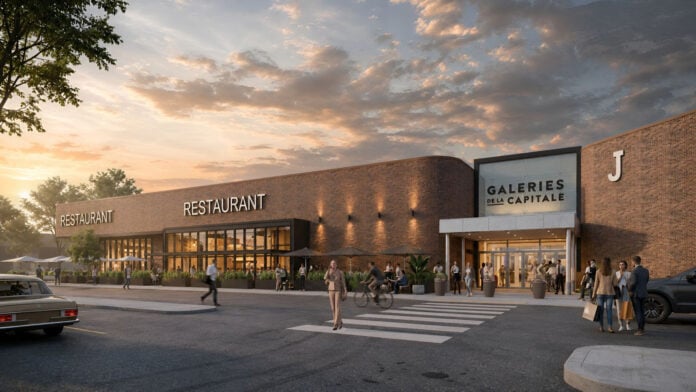
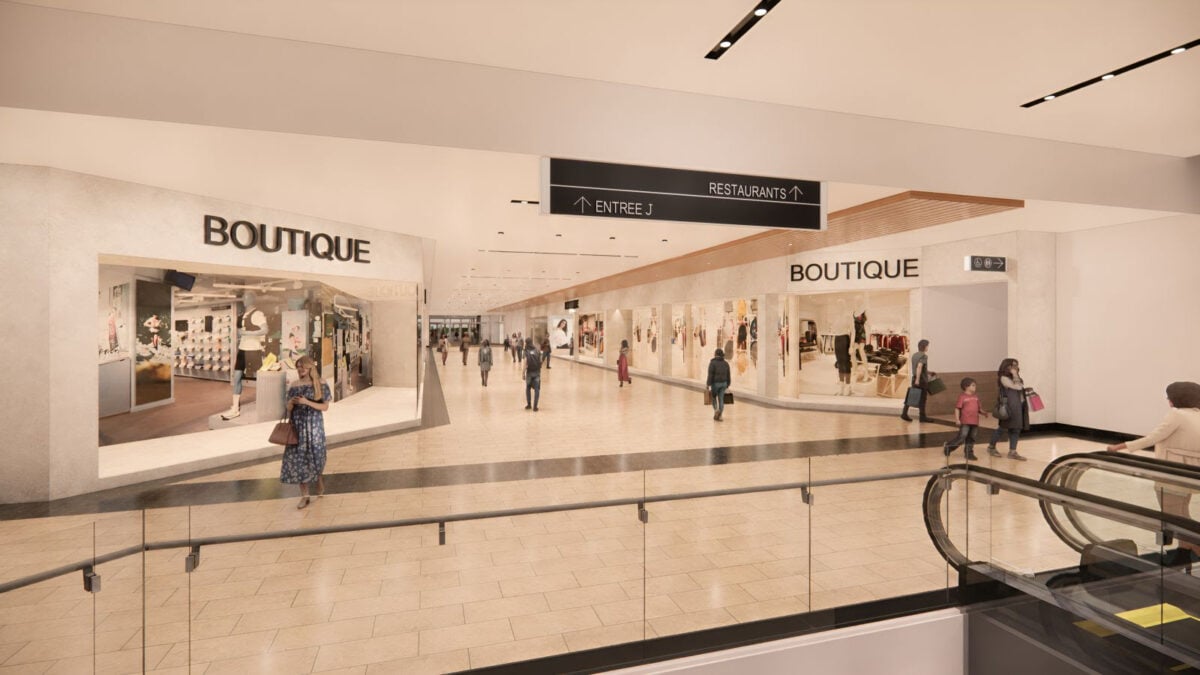
Primaris Invests $19M to Transform Former Hudson’s Bay at Galeries de la Capitale in Quebec City. Image: Primaris

Primaris REIT is investing $19 million to transform the former Hudson’s Bay at Galeries de la Capitale in Quebec City, converting the roughly 163,000-square-foot department store into a multi-tenant retail and restaurant wing as the landlord advances its broader repositioning of former HBC properties.

The project will bring several new tenants to the former anchor through 2027, led by Quebec-based Imaginaire, which will open a 30,500-square-foot flagship on the first level in spring 2027. It will be the largest store in Imaginaire’s network and a major expansion for the specialty retailer, which sells games, collectibles, comics, toys, hobby products and other pop-culture merchandise.

Restaurant-bar ZIBO! has also committed to approximately 5,500 square feet. The second level of the former Hudson’s Bay will be divided into spaces for additional retailers and restaurants, with plans also calling for a new exterior entrance and washrooms. Additional tenants remain under discussion, with spaces expected to be delivered progressively through 2027.

Hudson’s Bay closed its Galeries de la Capitale store in June 2025 as part of the retailer’s liquidation, giving Primaris control of one of the largest blocks of space at the shopping centre. Rather than seeking another department store to occupy the entire premises, Primaris is dividing the building among multiple uses as part of a wider strategy for the former HBC real estate in its portfolio.

Imaginaire Plans Largest Store in its Network

Imaginaire’s new flagship represents an investment of approximately $2 million by the retailer. The store will include an expanded toy and youth offering following the departure of Toys “R” Us from Galeries de la Capitale.

The shopping centre had sought to bring Imaginaire to the property for years. The recent availability of larger blocks of space following the departures of Hudson’s Bay and Toys “R” Us ultimately created an opportunity for a substantially larger store than Imaginaire typically operates.

The opening comes as Imaginaire accelerates its expansion beyond its traditional Quebec base. When Retail Insider interviewed the company as it entered Ontario, management discussed the potential for further expansion outside Quebec if its initial moves proved successful. The Galeries de la Capitale flagship will become the chain’s 11th location, while Imaginaire is now targeting approximately 20 stores within five years, with further growth contemplated in Ontario and Atlantic Canada.

Primaris Invests $19M to Transform Former Hudson’s Bay at Galeries de la Capitale in Quebec City. Image: Primaris

Galeries de la Capitale Adds New Retailers

The $19-million redevelopment comes amid a broader round of leasing and investment at Galeries de la Capitale. Les Ailes de la Mode is preparing to open a roughly 50,000-square-foot store, while lululemon is adding approximately 3,750 square feet. Other additions include Asian beauty retailer Kiokii and…, Campus13 and Café Van Houtte, alongside the new Imaginaire and ZIBO! locations.

The leasing activity is taking place at one of Primaris’s more productive enclosed shopping centres. The REIT’s latest investor materials put Galeries de la Capitale at approximately 1.1 million square feet with more than 200 stores. The property generated approximately $26.1 million in Cash NOI, while rolling 12-month same-store sales productivity reached about $834 per square foot as of May 2026.

Primaris acquired Galeries de la Capitale for $325 million in October 2024. The shopping centre sits on approximately 91 acres and had already received about $165 million of investment during the decade preceding the acquisition, including extensive renovations and investment in its entertainment component.

The closure of Hudson’s Bay created a substantial vacancy less than a year after Primaris acquired the property, but the underlying performance of Galeries de la Capitale remained strong. Regaining the former department store also gave Primaris control of strategically located space that had been occupied at rents well below those the REIT expects to achieve through replacement leasing.

Primaris Invests $19M to Transform Former Hudson’s Bay at Galeries de la Capitale in Quebec City. Image: Primaris

Primaris Repositions Former Hudson’s Bay Space

The Galeries de la Capitale redevelopment provides a tangible example of a strategy Primaris executives have discussed with Retail Insider since the collapse of Hudson’s Bay. Primaris President and CEO Alex Avery told Retail Insider earlier this year that the departure of Hudson’s Bay was “the best thing that has happened to Primaris in many, many years.”

Avery’s comments reflected the unusual economics of the former department store leases, along with restrictions that had limited Primaris’s ability to redevelop portions of some properties. The company has taken a property-specific approach rather than applying a single replacement strategy across its former HBC portfolio, with options ranging from replacement anchors and subdivision among several tenants to more extensive redevelopment.

At Galeries de la Capitale, that strategy is taking the form of multiple retail and restaurant spaces, accompanied by physical changes intended to better integrate the former anchor with the rest of the property. The financial rationale becomes clearer when the rents generated by HBC are compared with Primaris’s replacement leasing.

Across the former Hudson’s Bay locations being repositioned by Primaris, HBC had occupied approximately 1.23 million square feet and generated about $5.1 million in annual minimum rent, averaging approximately $4.18 per square foot.

Primaris said in June that signed or conditional long-term leases covered approximately 608,500 square feet of replacement space. Those leases are expected to generate average net rent of $15.11 per square foot, compared with $3.37 per square foot previously paid by HBC on the corresponding space, representing an increase of approximately 348%.

Including leases in advanced negotiations, approximately 881,400 square feet, or 84% of the former HBC space being remarketed, had been committed or was in advanced discussions. Primaris expects that space to generate average net rent of approximately $16.93 per square foot, compared with $4.25 per square foot under the former HBC leases.

The figures are portfolio-wide rather than specific to Galeries de la Capitale, but they illustrate the economics behind replacing legacy department store leases with new retail space at substantially higher rents.

Once the wider former-HBC leasing and redevelopment program is completed, Primaris expects to create approximately 1.04 million square feet of replacement gross leasable area generating about $18.9 million in annualized net rent and approximately $22 million in Cash NOI. The REIT expects to invest between $175 million and $225 million across the program, with anticipated yields above 10%.

Primaris has also said the projected Cash NOI does not capture potential benefits to surrounding retail space as replacement tenants open and generate additional traffic within the malls. At Place d’Orléans in Ottawa, for example, Walmart has leased approximately 115,500 square feet of former Hudson’s Bay space, while Galeries de la Capitale is being repositioned around multiple retailers and restaurants.

Primaris Invests $19M to Transform Former Hudson’s Bay at Galeries de la Capitale in Quebec City. Image: Primaris

Former HBC Lease Unlocks Development Potential

Regaining the Hudson’s Bay premises has implications beyond the roughly 163,000-square-foot building itself. Former HBC leases included restrictions affecting development on portions of several Primaris properties, and their termination has given the REIT greater flexibility over surrounding mall lands.

At Galeries de la Capitale, Primaris previously identified approximately 31.7 acres that were released from restrictions associated with the former HBC lease. The company has examined substantial longer-term residential intensification at the property, although no residential development has been formally announced.

Primaris Chief Investment Officer Julian Schonfeldt previously told Retail Insider that the company does not intend to become a residential developer. Its strategy is generally to unlock the development potential of appropriate excess lands and monetize them to specialized developers, allowing Primaris to recycle the proceeds into its core enclosed shopping centre business.

For now, the focus at Galeries de la Capitale is the former department store itself. By spring 2027, its first level is expected to include Imaginaire’s largest location, while additional retailers and restaurants will progressively occupy space that until last year was controlled by a single anchor tenant.

The redevelopment will continue through 2027 as Primaris completes the new exterior entrance and delivers additional tenant spaces. Discussions with prospective retailers are ongoing, meaning the final lineup replacing Hudson’s Bay has yet to be fully revealed.

Higher Back-to-School Spending Masks Budget Pressure for Canadian Families

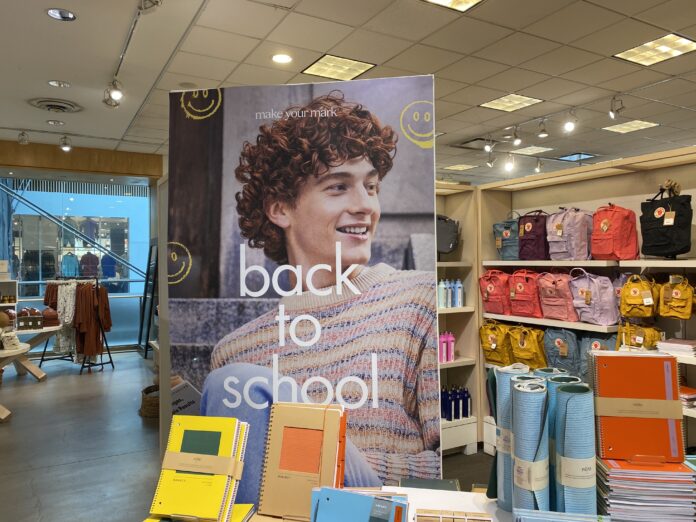
Back to School at Indigo CF Toronto Eaton Centre (Image: Dustin Fuhs)

Canadian families are heading into the 2026 back-to-school season expecting to spend more, but new research suggests the increase has less to do with stronger purchasing power than with the rising cost of completing increasingly expensive shopping lists.

Field Agent Canada found that 40% of surveyed households expect to spend more on back-to-school shopping than they did last year, while 39% anticipate spending about the same and 21% expect to spend less. At the same time, 67% said inflation will have a greater impact on their back-to-school shopping compared with last year.

For Jeff Doucette, Founder and General Manager of Field Agent Canada, the combination points to continued pressure on household budgets rather than an increase in discretionary spending.

“My interpretation is that consumers are just having to spend more to get what they need,” Doucette told Retail Insider. “There is no real slack in most family budgets to buy more. They are just trying to get what they need and not blow their budget.”

Field Agent’s 2026 Canadian Back-to-School Shopper research examines spending intentions across school supplies, food, apparel, beauty and personal-care categories. Many of the core questions were answered by more than 700 Canadian consumers, with smaller samples used for category-specific questions.

Jeff Doucette
Jeff Doucette

Inflation Pressure Becomes Part of the Shopping Routine

The persistence of inflation concerns is particularly notable when the results are compared with Field Agent’s research from a year earlier. In 2025, 39% of respondents expected to spend more on back-to-school purchases and 25% planned to spend less. This year, the share expecting to spend more has edged up to 40%, while the proportion planning to spend less has declined to 21%.

Yet the share saying inflation will have a greater effect on their shopping is unchanged at 67%. Rather than signalling that consumers are becoming less concerned about elevated prices, Doucette said shoppers appear to have adjusted their behaviour to a prolonged higher-cost environment.

“Shoppers have definitely snapped out of inflation denial,” he said. “They may be swapping in products that are cheaper brands in order to get everything on the list without blowing the budget.”

Higher spending, in other words, should not automatically be interpreted as households purchasing more merchandise. The findings instead point to consumers trying to complete necessary purchases while becoming more selective about products, brands and retailers.

That behaviour fits the broader Canadian consumer backdrop. The Bank of Canada’s second-quarter Canadian Survey of Consumer Expectations found that high prices and economic uncertainty continue to hold back spending plans, while consumers’ near-term inflation expectations remain elevated. Back-to-school purchases can be difficult to defer, however, leaving families to manage the cost of school supplies, clothing, footwear, food and other necessities within already constrained budgets.

Deals Are Breaking Down Brand Loyalty

Field Agent’s findings suggest retailers and consumer brands are competing for shoppers increasingly willing to move elsewhere when the economics make sense. Among respondents asked what would influence them to consider a new back-to-school brand, 85% identified a deal or discount, compared with 55% who cited positive online ratings and reviews.

Doucette said that willingness to move between brands is also influencing where households choose to shop.

“I especially see this within retailers, and this is fuelling the rise of discount grocers as well as Dollarama and the continued strength of Walmart,” he said. “In addition, we see Temu and Amazon playing a significant role in back-to-school, and shoppers are not shy to shop online.”

The behaviour is consistent with other Canadian back-to-school research released this year. Retail Council of Canada and Caddle estimate the Canadian K–12 back-to-school market at more than $4.5 billion. Their research, based on a nationally representative sample of 1,398 Canadian parents with children in kindergarten through Grade 12, found that 85% are actively seeking deals before selecting a retailer.

For retailers, consumer spending has not disappeared, but competition for those dollars has intensified. Families still have shopping lists to complete, yet there is less incentive to remain loyal to a particular brand or banner when a comparable product is available at a more attractive price elsewhere.

Walmart, Dollarama and Costco Lead In-Store Shopping

The value orientation is clearly visible in Field Agent’s retailer rankings. Among respondents planning to purchase school supplies in person, 91% said they were likely to visit Walmart, followed by Dollarama at 66%, Costco at 61%, Real Canadian Superstore at 46% and Staples/Bureau en Gros at 44%.

Those positions are broadly consistent with the previous year. In Field Agent’s 2025 study, Walmart reached 94%, Dollarama 66%, Costco 58%, Real Canadian Superstore 50% and Staples 41%. The more significant story is therefore not a dramatic reshuffling of the leading retailers, but the sustained strength of mass merchants, dollar stores, warehouse clubs and other operators able to compete aggressively on price and everyday value.

Doucette said the environment is becoming increasingly difficult for retailers without a clear value proposition, especially in categories where consumers see relatively little differentiation between products.

“At the end of the day, shoppers have to move to these retailers in order to get their back-to-school needs and still make ends meet,” he said. “Being a non-discounter is a very scary place to be when it comes to CPG items and ‘commodity’ items like pencils or notebooks.”

The results fit a wider shift visible across Canadian retail. Discount grocery banners have become increasingly important as households scrutinize food spending, while Walmart and Costco benefit from broad assortments that allow shoppers to combine school supplies with apparel, groceries and household purchases. Dollarama, meanwhile, remains firmly embedded in the back-to-school consideration set for basic, easily substituted merchandise.

Amazon May Capture Spending Before Shoppers Reach Stores

Online shopping presents another competitive challenge for physical retailers. Amazon.ca is the dominant online destination in Field Agent’s survey, with 79% of respondents saying they were likely to visit the platform for school supplies. Walmart ranked second online at 36%, followed by Costco at 25% and Temu at 22%.

Doucette believes the implications go beyond consumers simply researching products online before visiting a store. For basic back-to-school merchandise, he argues that Amazon may increasingly capture straightforward purchases before the shopper makes an in-person trip.

“I think that shoppers are trusting Amazon to always be fairly priced and the added ease of having it delivered to home saves a trip to the store,” he said. “I think the danger for bricks-and-mortar retailers is that shoppers are doing their Amazon shop first and buying the rest at physical retail. A big chunk of the back-to-school list is not even making it to the store.”

Field Agent’s qualitative research helps explain the appeal. Respondents cited convenience and time savings as the strongest reasons for purchasing school supplies online, particularly for parents who would otherwise need to bring several children shopping. They also pointed to easier price comparisons, better promotions, broader selection and the ability to avoid travelling between stores in search of merchandise that may be unavailable.

Some respondents said online shopping can also help them remain disciplined by reducing impulse purchases when children accompany them into stores. Digital channels are therefore competing not only on convenience, but also on shoppers’ ability to control the overall cost of the back-to-school trip.

Temu’s presence adds another dimension. Doucette said children themselves may sometimes help direct parents toward the platform, illustrating how digitally native marketplaces are becoming part of a shopping occasion that was once dominated almost entirely by established mass merchants and specialty retailers.

Back-to-School Is Also a Grocery Occasion

The season extends well beyond notebooks, backpacks and clothing. Field Agent found that 92% of surveyed households expect their children to take packed lunches or snacks from home during the school year, a result Doucette identified as one of the findings that stood out most strongly to him.

“In my years of doing this report and comparing to U.S. data, we are much more likely than Americans to pack a lunch, while students in the U.S. are much more likely to go to the cafeteria or go to a restaurant at lunch,” he said.

Among households packing lunches, 86% expect to include fresh fruit, while 78% cited granola or protein bars, 76% water and 75% meat sandwiches or wraps. Cracker, cheese and meat kits were selected by 71%.

The retailer rankings again favour large-scale and value-oriented operators. Walmart leads at 60%, followed by Costco at 56%, Real Canadian Superstore at 49%, No Frills/Maxi at 42% and FreshCo at 30%.

Those findings make back-to-school a recurring grocery occasion rather than simply a one-time seasonal shopping trip. Families may be trying to manage not only the cost of pencils, backpacks and shoes, but also the food children take to school throughout the academic year, creating an extended opportunity for grocery retailers that can demonstrate value.

Apparel Reflects the Same Search for Value

Clothing and footwear represent another significant component of the season, with 83% of respondents saying they are very likely to make purchases in the category. Again, many of the leading destinations are retailers associated with broad assortment or accessible pricing.

Walmart ranks first at 57%, followed by Costco at 46%, Winners at 44%, Old Navy at 41% and Sport Chek at 33%. Amazon reaches 28%, while H&M is at 24%, Joe Fresh at 22%, Gap at 21% and The Children’s Place at 20%. Thrift stores were selected by 19% of respondents.

The apparel results reinforce the pattern visible throughout the survey. Canadian households are not abandoning the category, but they are shopping it through a wide range of value, mass-market and off-price channels, creating additional pressure on retailers competing primarily through brand positioning rather than price.

Retailers Compete for Necessary Spending

Field Agent’s research points to a 2026 back-to-school season in which demand remains substantial even as household financial comfort remains limited. Families still need school supplies, clothing, footwear and food, but the battle for those purchases is increasingly being decided by price, convenience and the shopper’s confidence that a retailer represents good value.

For mass merchants, discount banners, warehouse clubs and online marketplaces, that environment creates an advantage. Their propositions align closely with households looking to complete shopping lists without allowing total spending to move too far beyond already stretched budgets.

For retailers without an obvious value proposition, the challenge is considerably greater. The distinction at the heart of the 2026 season is therefore between spending growth and consumer strength: Canadian families may be putting more money toward back-to-school, but Field Agent’s research suggests much of that increase reflects the cost of obtaining necessary goods rather than a broad increase in purchasing power.

As consumers become more comfortable substituting brands, moving between retailers and shifting purchases online, simply appearing on a family’s shopping list will not guarantee the sale. Retailers will increasingly have to earn their place at the checkout.

More from Retail Insider:

lululemon Like New Resale Program Expands to Canada

lululemon image
lululemon image

lululemon athletica inc. and Archive, the global technology company powering branded resale businesses, announced Monday the launch of Like New in Canada. Like New is lululemon’s branded resale program, and its expansion into Canada offers guests an iteration of the program with new ways to buy and sell pre-loved lululemon products and keep the brand’s high-quality items in circulation, said the retailer.

“Our products are created with high standards for technical performance and quality, which makes them perfectly suited for life well beyond a single owner,” said Maureen Erickson, Senior Vice President of Retail Experience at lululemon. “Like New extends the life of that product, giving guests a trusted way to keep great gear in use while discovering lululemon in a new way—as they move, sweat and connect, again and again.”

lululemon image

The Canadian launch follows strong growth for Like New in the U.S., where the program has given hundreds of thousands of items a second life over the past year. Bringing Like New to Canada extends that momentum to where lululemon was founded and deepens the brand’s commitment to extending the life of its products. Canadian guests will also be able to shop the program in English and French, said the company in a news release.

“What lululemon has built with Like New is a great example of how branded resale has become an integral, scalable channel for retail brands,” said Emily Gittins, CEO and Co-Founder of Archive. “Bringing the program to Canada reflects strong momentum and opens a new source of second-hand supply to meet growing demand, while continuing to invest in a resale business that scales alongside the brand.”

At launch, Canadian guests will take part by buying and selling pre-owned lululemon items directly with one another on the Like New platform. Guests can list their own gently used lululemon products and shop a selection of pre-owned items in a fully lululemon-branded experience. Unlike third-party resale marketplaces, Like New allows lululemon to guide the overall guest experience, from merchandising to how product is displayed on the e-comm site, and peer-to-peer gives guests the autonomy to determine how to showcase their product. As one of the most resold brands in retail, lululemon offers sellers a way to capture more value from their products while giving buyers a trusted source for authentic items, explained the retailer.

To mark the launch, lululemon Like New will host a limited-time mail-in trade-in event from September 14 to 21, giving guests a dedicated window to send in eligible pre-owned lululemon items in exchange for credit toward a future purchase. More details can be found around the mail-in trade-in window on the website, it said.

“Since launching Like New in 2021, the program has scaled from a two-state pilot to a U.S.-wide offering and now expands into Canada. Like New has proven to be an impactful discovery tool, often serving as the first touchpoint for new guests, especially value-conscious shoppers trying lululemon for the first time. At the same time, lululemon’s guests remain engaged, enjoying opportunities to trade in product, and hunt for exclusive finds,” added the brand.

“In the U.S., lululemon recently expanded Like New to let guests buy and sell pre-owned lululemon products directly with one another on the platform, alongside the program’s existing U.S. channels including mail-in and in-store trade-in and product sourced from lululemon’s own operations.”

More from Retail Insider:

Consumer prices continue to climb: Statistics Canada

RDNE Stock project photo

The Consumer Price Index (CPI) rose 3.0% year over year in July, following a 2.8% gain in June, reported Statistics Canada on Monday.

On a year-over-year basis, higher prices for gasoline and travel tours in July contributed to the acceleration in the headline CPI. Moderating the faster price growth was a deceleration in the food purchased from stores index. The all-items CPI excluding gasoline rose 2.2% for the third consecutive month, said the federal agency.

The CPI rose 0.5% month over month in July. On a seasonally adjusted monthly basis, the CPI rose 0.3%, it said.

“On a yearly basis, prices for gasoline grew at a faster rate in July (+25.7%) compared with June (+20.5%). The conflict in the Middle East, including the blockade of the Strait of Hormuz and the partial closure of Red Sea shipping routes in late July, put upward pressure on gasoline prices,” said Statistics Canada.

“Year over year, prices for travel tours rose at a faster pace in July (+15.2%) compared with June (+6.8%). Contributing to higher prices were more expensive hotels and flights to US destination cities, coinciding with the hosting of World Cup matches.

“Similarly, prices for air transportation rose 12.0% year over year in July following a 9.6% increase in June. Contributing to the price increase were higher jet fuel costs.”

Jack Sparrow photo
Jack Sparrow photo

Statistics Canada said prices for food purchased from stores grew at a slower pace in July (+3.1%) compared with June (+3.9%) on a year-over-year basis. Despite the slowdown, July was the 18th consecutive month that grocery price inflation outpaced the all-items CPI.

“The year-over-year deceleration in grocery prices was driven by slower price growth for fresh vegetables (+3.9%) and fresh or frozen chicken (+0.3%) as well as lower prices for cereal products (-1.7%). Moderating the slowdown was higher prices for fresh fruit in July (+6.1%) compared with June (+1.7%),” it said.

“On a monthly basis, price growth for fresh fruit recorded the highest month-over-month movement for the month of July since 2011, at 4.7%. Driving the monthly increase were higher prices for berries and melons.”

Andrew Grantham, Senior Economist, CIBC Capital Markets, said Canadian inflation reaccelerated in July, albeit largely due to gasoline prices.

“The generally subdued readings for core inflation on a year-over-year basis mean that there’s no rush for the Bank of Canada to raise interest rates, and policymakers have plenty of time to assess oil price fluctuations, how the tariff situation plays out and whether the rebound in economic activity we are currently witnessing can be sustained.  We continue to forecast no change in the overnight rate until around mid-2027,” he said.

Leslie Preston, Managing Director & Senior Economist, TD Economics, said inflation ticked up slightly in July due to due to higher prices at the pump and higher travel-related costs due to the World Cup. Core inflation remained bang on the Bank of Canada’s 2% target.

“We expect the Bank of Canada’s (BoC) core inflation measures to drift a little bit above 2% in the coming months on some pass through of higher energy costs to other prices in the economy,” she said.

“Short-term Government of Canada bond yields are up slightly on the higher inflation read, but given the travel impact on inflation should fade in the coming months, we aren’t too concerned that core inflation running slightly above 2% should spook the BoC into raising interest rates. The BoC has noted that Canada continues to deal with the confidence shock of on-again-off-again tariff threats from the U.S., which given there is no deal as yet to avert the 50% tariffs set to come into effect on August 19th, remains a clear downside risk to Canada’s economy.”  

More from Retail Insider:

63% of Canadians have bought refurbished, open box or traded in technology in the past year: Best Buy report

Andrea Piacquadio photo

Ahead of back-to-school, one of the largest shopping moments for electronics, Canadians are rethinking what “new” means to them when buying tech. A new report from Best Buy Canada found that 63% of Canadians have purchased refurbished, open box or traded in devices in the past year, but openness varies by generation, pointing to a growing divide in how Canadians purchase technology and what draws them to supporting the circular economy in the first place.

The 2026 Back-to-School Tech Shopping Report found that 71%  of Gen Z have purchased recirculated technology (open box, refurbished, or trade-in) in the past year, with millennials and Gen X trailing slightly behind at 65%, followed by 55% of boomers.

While consideration across all age groups is high, the why behind each purchase differs, explained Best Buy. Saving money remains a top motivator across all age demographics, including 81% of Gen Z and millennials, but reducing environmental impact is the second most important factor for Gen Z (44%, millennials (40%), and Gen X (30%), compared to only 24% of boomers.

This gap points to how young Canadians think about technology ownership. For Gen Z and millennials, buying isn’t just a budget decision; it’s weighed against their own values. Extending a device’s life, keeping it out of the landfill, and ensuring it is responsibly recycled at the end of its lifecycle are becoming key considerations for young Canadians throughout the circular product journey, added the retailer.

A contributor to the increase in recirculated technology purchases? Access.

“The category looks vastly different now than a few years ago, and with the scale of new product releases from top brands over the last few years, there’s no shortage of quality in the secondary market as Canadians have opted to upgrade to newer models,” said Mark Leahy, Senior Director, Service Programs, Service Centres & Reverse Logistics. “Canadians have more options for non-new technology making it more accessible than ever before. For those looking for cost savings, buying a refurbished, open box or traded in device is a way to bring down initial costs while still getting a product that is in great condition.”

Best Buy said refurbished products are used electronics that have been inspected, tested, repaired, and restored through a certified refurbishment process. According to Best Buy Canada, refurbished products save customers about 40% off the original retail price, and come with a minimum three-month guarantee, giving Canadians added peace of mind.

“Those savings are a big reason a growing number of Canadians are choosing refurbished, which helps stretch their budget and gives them access to newer models with more features. That appeal is especially strong among younger generations. Among Gen Z and millennials who have not purchased refurbished products in the past year, 35% and 37%, respectively, say they would consider doing so,” said the retailer.

Open box products are items that have been unboxed, returned or previously used for in-store displays. It has the broadest appeal among younger shoppers, with Gen Z (47%) and millennials (45%) showing the highest rates of consideration, though interest sits above 30% across all generations, it said.

On average, open box products save around 28% off the original sales price, making them a great option for Canadians who want a specific model, or want to step up to more features, without paying full price, it added.

The most popular refurbished product categories are:

1. Wireless

2. Laptops

3. Computers

4. Tablets

5. Video game consoles

The most popular open box product categories are:

1. Laptops

2. Wireless

3. TVs

4. Tablets

5. Wearables

fauxels photo
fauxels photo

This Back-to-School season, Canadian parents are also turning to recirculated technology purchases. About 53% of parents with children ages four to five have purchased open box technology, dipping as children get older and resurging to 48% among parents of children ages 13 to 17.

Additionally, when looking to replace existing devices, 84% of parents have traded in technology or considered trading in, giving them increased cost savings and opportunities to upgrade, noted Best Buy.

“Price continues to be a main purchase factor across all generations, but durability is a growing consideration for Gen Z (25.1%) and parents (23%) who are looking to ensure they are buying products that will last.

When shopping for electronics, parents with teenagers (ages 13-17) are the most price-driven technology buyers (39%), significantly higher compared to parents with kids ages six to nine (25%) and those with no kids at home (24%),” said the retailer.

In an interview with Retail Insider, Leahy discussed the report’s findings.

Question: What do the generational differences in used-tech adoption tell you about how Canadians’ attitudes toward refurbished, open-box and trade-in products are changing?

Answer: The generational differences suggest that recirculated tech (refurbished, open box, trade-in) is moving from a niche or budget-driven option to a mainstream, intentional purchase. Unsurprisingly, Gen Z is leading the charge, with 71% having purchased recirculated technology, followed closely by millennials and Gen X. Gen Z is often considered the most tech-savvy generation, and as this age group has gotten older and is gaining independent purchasing power, it is leading where technology purchases will go next. In the last few years alone, there’s been a real shift toward considering recirculated technology as part of the normal purchasing process rather than only a price-focused alternative.

Q: With 44% of Gen Z citing environmental impact as a reason for choosing refurbished technology, how significant do you expect sustainability and e-waste concerns to become in tech purchasing decisions?

A: I expect sustainability and e-waste concerns to become an increasingly important factor in tech purchasing decisions particularly among younger Canadians. As recirculated tech continues to offer price savings to Canadians it gives shoppers more room to consider products that align with their personal values. That said, sustainability isn’t yet overtaking price as the primary consideration. Price remains the strongest driver, but as Canadian shoppers look for back-to-school options, environmental values can be the tiebreaker when evaluating whether to buy new or recirculated technology. The shift we’re seeing is less about consumers choosing refurbished technology purely to save money and more about recognizing that they can save money while also making a more sustainable choice.

cottonbro studio photo

Q: Price remains the top motivator across generations, but durability is also emerging as a factor—how can retailers better communicate the value and reliability of used and refurbished technology to consumers?

A: Retailers need to move the conversation beyond simply positioning refurbished technology as the cheaper option. Price is clearly an important factor, but consumers also want confidence that they’re getting a product that will perform and last.

Transparency is the key to building consumer trust. At Best Buy Canada, clear communication about the refurbishment process and certification, the device’s condition, testing, quality checks and minimum three month warranty has been a crucial way to assure consumers that the product they’re buying is reliable.

There’s also an opportunity to reframe refurbished technology as a smart choice rather than a compromise. Many perceive refurbished devices as inferior to new ones, but with updated hardware, electronics can have a longer lifespan than many expect. Retailers that make that case clearly, backed by proof, will build long-term consumer confidence in refurbished tech.

Best Buy image
Best Buy image

Q: With 84% of parents trading in devices when replacing them, what role do trade-in programs play in making the used-tech market more attractive and accessible to Canadian consumers?

A: Trade-in programs make recirculated technology feel like a natural part of the upgrade cycle rather than a separate or unfamiliar way to buy tech. By allowing consumers to get value from an old device and put it toward their next purchase, trade-ins make upgrading more affordable and convenient.

They also make the sustainability benefit tangible by keeping devices in circulation rather than leaving them unused or contributing to e-waste. Trade-ins bring together the two things consumers care about: saving money and getting value from the technology they already own.

Q: As back-to-school shoppers face rising technology costs, what opportunities do you see for retailers to make open-box, refurbished and trade-in products a more prominent part of the back-to-school shopping experience?

A: Back-to-school is a strong opportunity to position refurbished and open-box technology as a smart way for families to not only manage budgets but also stretch them further to try out new technology. This is especially true for parents who may be buying tech not only for themselves but also for multiple children in the family, each with different tech needs based on the school curriculum or extracurriculars.

Retailers could also tailor messaging by age group, recognizing that younger children may need tablets or basic devices, while teens are more likely to need higher-value technology like laptops, cameras, and wireless accessories. This also creates an opportunity to mix and match new, refurbished and open-box products based on a family’s specific needs, priorities and desired features, helping them maximize value without compromising on functionality. Pairing these products with trade-in offers could make upgrading more affordable while giving devices a second life.

More from Retail Insider:

Ford Canada Launches ‘There’s No Can’t in Canada’ Campaign, Highlights $5B Oakville Investment

Ford Canada photo
Ford Canada photo

Ford Canada is launching a new Canadian campaign, There’s No Can’t in Canada.

At a time when Canada is navigating economic uncertainty, shifting trade dynamics and continued pressure on manufacturing, Ford says it is using this moment to make a statement about its long-term commitment to Canada and the people, communities and operations that have shaped its business here for more than 122 years.

The company says the campaign reflects a belief that has long defined Canadians: when challenges arise, we don’t back down – we find a way forward. More than a campaign, it is an expression of Ford’s confidence in Canada’s future and its intention to continue building that future here as a manufacturer, employer, innovator and community partner, adds the motor vehicle brand.

Building on its nearly $5 billion investment in Oakville and continued investment in its Windsor Operations, Ford said its commitment spans its entire Canadian network – from manufacturing plants to its Connectivity and Innovation Centres, Parts Distribution Centres, and the more than 430 dealers and 6,500 employees across the country.

To demonstrate this appreciation, Ford Employee Pricing will run until Sept 30, offering this opportunity for savings to every customer.   

More than a retail offer, it’s a demonstration of Ford’s gratitude for the Canadians who have supported the company for generations and its commitment to helping them at a time when affordability remains top of mind, said the company.

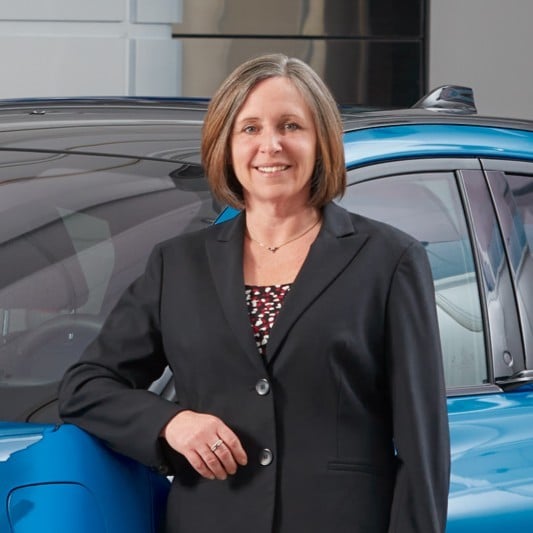
In an article, Bev Goodman, President and CEO, Ford of Canada, said the company has been part of Canada for more than 122 years.

“We’re close to opening Ford’s all-new Oakville Assembly Complex. Close to $5 billion of investment, retooled from the ground up, including a new stamping plant, so we can build the Super Duty right here,” she said.

“It’s coming online at an odd moment for this industry. Trade friction. Electric vehicle timelines that keep moving. Costs that make everyone nervous. New competitors nobody was worried about a decade ago. But when things get hard, our instinct here at Ford has generally been to figure it out rather than pack up.

“Right now, with Oakville, that instinct means doubling down instead of pulling back. Same goes for our engine plants in Windsor.”

Goodman said the campaign is not really a slogan but more a way people in this country already think. Something goes wrong, and the question isn’t whether you’ll fix it, it’s how. 

“There’s a real current of pride running through this country at the moment, and people can tell the difference between a company that’s decorating itself in a flag for a quarter and one that’s actually built something here,” said Goodman.

“We’d rather point at Windsor, Waterloo, Ottawa, Markham, and Oakville – actual buildings, actual jobs, actual people who’ll still be there next year – than at a maple leaf in an ad. We’re an American company, and I won’t pretend otherwise. But we’ve been living here long enough, building here long enough, that I think of us as a citizen of this country as much as a visiting one.”

Paul Roy, Vice President, Marketing, Ford of Canada, said Canada is in a period of change, with Canadians navigating real economic uncertainty, shifting trade dynamics and continued pressure on manufacturing. 

“This felt like the right moment to reaffirm our commitment to, and confidence in, Canada and its future. That’s the spirit behind There’s No Can’t in Canada. For 122 years, Ford has faced challenges alongside Canadians, choosing resilience and investment over retreat. We want Canadians to see this as a statement of confidence in them, in this country and in the future we’re building together,” he explained. 

Roy said Ford’s commitment to Canada is reflected in what its built here. 

“That includes more than $5 billion invested in Oakville Assembly Complex to build Super Duty and a new stamping plant, along with continued investment in Windsor, Waterloo and Ottawa,” he said. “It also includes our network of more than 430 dealers and 6,500 employees across the country, who connect Ford to customers and communities every day. 

“The impact should be measured by the affirmation that Canadians see Ford as a trusted, proven partner with deep roots in this country – one that continues to invest in Canada’s future.”

Roy said Ford Employee Pricing is the company’s way of saying thank you to the Canadians who have supported Ford throughout its 122 years in this country. 

“We don’t take that relationship for granted, and at a time when affordability is top of mind for many Canadians, Ford Employee Pricing gives customers the opportunity to pay what Ford employees pay, with no fine print and no games. There’s also a very real employee connection at the heart of this,” he said. 

“We cast Ford employees in the campaign because we wanted Canadians to see some of the actual people behind Ford in this country. These are the people who are part of our operations and communities, and who help bring our commitment to Canada to life every day.  

“Ford Employee Pricing is one way we can show our appreciation to customers, but “There’s No Can’t in Canada” is a much broader story about the relationship we’ve built with Canadians over generations and our commitment to continuing that relationship into the future.”

Roy said Ford’s long-term commitment to Canada hasn’t changed, but the industry continues to evolve, so it needs to stay agile and responsive. 

“That said, the strength of our Canadian footprint is clear: manufacturing in Oakville and Windsor, innovation centres in Waterloo and Ottawa, parts distribution centres that support customers across the country, and more than 430 dealers serving local communities each day. That combination gives us a strong foundation to keep investing in Canada and adapting for the future,” he said.

“You don’t build a 122-year relationship by taking it for granted. Looking ahead, our focus is on continuing to earn the trust Canadians have placed in Ford by investing in this country, supporting our communities and delivering the capable vehicles Canadians rely on every day. 

“That relationship will keep evolving, but our commitment to Canada remains constant. We want to be seen as a trusted partner that shows up for Canadians and stands behind the communities where we live and work. Success for “There’s No Can’t in Canada” is strengthening that connection and reinforcing Ford’s confidence in Canada’s future.” 

More from Retail Insider:

Inside Leon’s $1.17 Billion Canadian Real Estate Portfolio

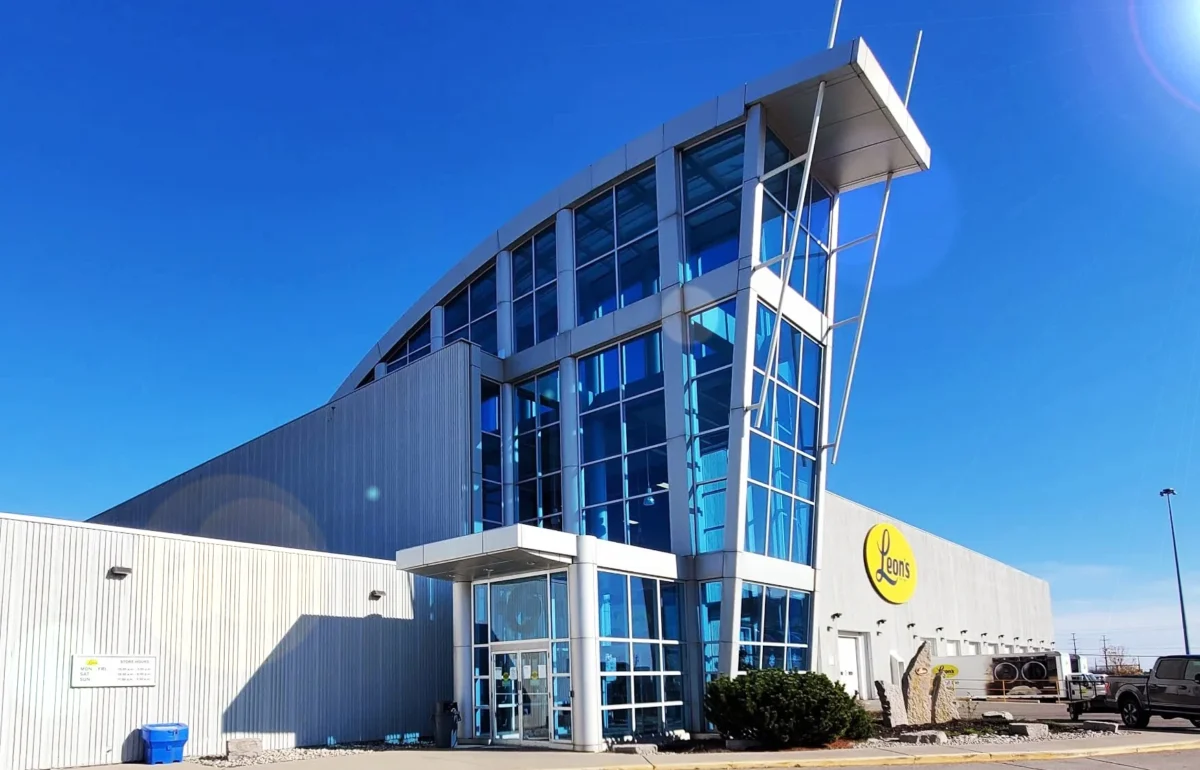
Leons' Weston Location. Image: www.leons.ca

Leon’s Furniture Limited has put a $1.17-billion appraised value on its Canadian real estate portfolio, bringing new attention to a collection of properties accumulated over more than a century and to the retailer’s longstanding plan to establish a publicly traded real estate investment trust.

The valuation provides a clearer picture of the property holdings sitting beneath one of Canada’s largest home furnishings retailers. Leon’s has identified approximately 50 owned properties encompassing about 5.5 million square feet and 430 acres of land, including retail locations, distribution facilities and sites with redevelopment potential.

Many of those assets have been owned for years or decades and remain recorded on the company’s balance sheet at historical cost. In investor materials earlier this year, Leon’s highlighted a carrying value of more than $284 million for the portfolio, well below the newly disclosed appraisal.

Leon’s CFO Victor Diab

Management says the valuation was commissioned to establish a market-based reference for assets whose current value is not reflected in their historical accounting figures.

“I think analysts have taken a shot at what the value of our real estate is or was, and we thought it was time and important for us to establish a market-based reference point for our portfolio,” CFO Victor Diab told analysts during Leon’s second-quarter earnings call.

Diab said the appraisal validates what the company has been saying about the value of its holdings for several years. The disclosure comes as Leon’s continues to pursue a strategy that could eventually place a portion of those properties into a publicly traded REIT, with the retailer maintaining a majority interest in the new vehicle.

A National Real Estate Portfolio Built Over Generations

Leon’s property holdings stretch across Canada, with the largest concentrations in Ontario and Alberta.

Company investor materials indicate Ontario accounts for approximately 40 per cent of the portfolio, followed by Alberta at 27 per cent. British Columbia represents about 10 per cent, Quebec nine per cent, Saskatchewan and Nova Scotia five per cent each, and Manitoba approximately four per cent.

Leon’s describes the portfolio as the product of more than 100 years of property accumulation. Founded in 1909, the company has historically owned many of the properties supporting its retail and distribution operations, leaving it with a sizeable asset base as land values increased and Canadian cities expanded around some longstanding locations.

The holdings include large-format stores, warehouses and distribution properties, some accompanied by substantial parcels of land. Leon’s has identified opportunities to intensify or redevelop portions of the portfolio as its retail and distribution requirements evolve.

The company’s overall physical footprint, including leased locations, is considerably larger than the owned portfolio. The land and buildings held directly by Leon’s, however, have increasingly become a strategic part of the business.

Decades of Ownership Create a Wide Valuation Gap

The $1.17-billion appraisal puts the value accumulated within those properties into perspective.

Real estate acquired decades ago can remain recorded at amounts far below current market values. Leon’s March 2026 investor materials put the portfolio’s carrying value at more than $284 million, meaning the new appraisal is more than four times that figure.

The difference does not represent an immediate gain or cash available to the company. It does show how little the historical balance-sheet value says about what the portfolio could be worth in today’s market.

Stifel Managing Director and analyst Martin Landry calculated that substituting the newly disclosed market value for the historical carrying value of Leon’s real estate would increase book value per share by approximately 66 per cent, from roughly $18 to about $30.

That gap has been one of the considerations behind Leon’s efforts to surface more of the value associated with its property holdings.

REIT Strategy Dates Back to 2023

Leon’s first announced its intention to create a REIT in May 2023 as part of a broader strategy for its real estate portfolio.

At the time, the company was evaluating structures that included an initial public offering or a spinout. By November 2023, Leon’s board had approved plans to create the REIT through an IPO.

Under the model subsequently outlined by the company, Leon’s would contribute a portfolio of income-producing properties to the REIT and retain an ownership interest of more than 50 per cent at launch. The REIT is also expected to have an independent management team.

Not every Leon’s property is expected to move into the vehicle at once. Company materials describe a longer-term strategy under which LFL can continue owning and developing properties, with additional completed income-producing assets potentially transferred into the REIT over time.

That would create a pipeline of future properties while leaving development opportunities within LFL. The REIT could eventually acquire assets beyond those occupied by Leon’s businesses, giving it scope to develop a more diversified real estate portfolio.

Leon’s continues to describe the REIT as a strategic priority, although management has not established a launch date and says timing remains dependent on market conditions and regulatory approvals.

Photo: Leon’s Furniture

Toronto Site Shows the Development Opportunity

One of the clearest examples of the potential embedded in Leon’s land holdings sits near the intersection of Highways 401 and 400 in Toronto.

The company controls more than 40 acres in the area, including properties on Gordon Mackay Road and Suntract Road that have long housed Leon’s corporate operations. Leon’s has occupied the site since the company went public in 1969.

The land is now being positioned for a substantially more intensive use.

In 2024, Leon’s announced plans for a major mixed-use redevelopment after a change in the property’s land-use designation opened the site to a broader range of uses. The long-term concept includes approximately 4,000 residential units along with retail, commercial and community space.

Leon’s has said the first phase is expected to include a new flagship store and corporate headquarters, with residential development to follow. Plans contemplate townhouses as well as mid- and high-rise buildings, and the company expects to work with development partners as the project moves forward.

The Toronto site illustrates how the economics of a longstanding retail property can change as the surrounding city develops. Land acquired to accommodate a store, offices and related operations decades ago can eventually support considerably greater density while allowing Leon’s to maintain a presence on the property.

Burlington Offers Another Example

A sizeable Leon’s property in Burlington, Ont., provides another example of the redevelopment opportunities management sees within the portfolio.

The approximately 32-acre site includes a roughly 73,000-square-foot retail store and a warehouse of approximately the same size. Leon’s has identified development potential associated with the property’s zoning and existing configuration.

The Burlington site also shows that the real estate strategy extends beyond the large Toronto redevelopment.

Leon’s has discussed optimizing some stores toward smaller, higher-traffic footprints where comparable profitability can be maintained. On large owned sites, changing the amount of space required for retail operations could create opportunities to use portions of the land differently over time.

The company’s retail and property strategies are therefore increasingly connected. Changes to the store network can influence how much land is required for existing operations, while redevelopment can create additional value from properties already owned by LFL.

Leon’s Location in Burlington, Ontario. Image: www.leons.ca

Edmonton Distribution Centre Adds Another Piece

Leon’s is also consolidating ownership of a major distribution property in Western Canada.

The company has agreed to acquire the remaining 50-per-cent interest in its Edmonton distribution centre for $45.75 million in cash, giving LFL full ownership once the transaction closes. The facility is an important part of the company’s Western Canadian distribution network and also houses The Brick’s corporate headquarters.

Management has presented the transaction in operational terms. CEO Mike Walsh has described the property as a high-quality asset that is already central to LFL’s business, with full ownership representing a disciplined investment in a facility the company knows well.

Stifel sees a possible additional significance.

Landry highlighted the Edmonton acquisition alongside the newly disclosed $1.17-billion appraisal and said the developments may represent steps toward positioning Leon’s to eventually proceed with the REIT process.

Leon’s has not said the Edmonton acquisition was undertaken to facilitate the REIT, and management has given no indication that an IPO is imminent. Full ownership gives the company greater control over a strategically important distribution property regardless of how the asset fits into its longer-term real estate plans.

Is a Leon’s REIT Getting Closer?

The recent developments add another chapter to a real estate strategy that has been taking shape for more than three years.

Leon’s now has a defined plan to create the REIT through an IPO, an identified national portfolio, a pipeline of development opportunities and an independent appraisal placing the property holdings at $1.17 billion. The company is also continuing to invest directly in its real estate while advancing large-scale redevelopment planning on selected sites.

Asked about the REIT during the second-quarter earnings call, Diab reiterated the company’s interest but stopped short of providing a timetable.

“It does remain a strategic priority for us,” he said, adding that market conditions and regulatory approvals continue to factor into the timing.

The appraisal and Edmonton transaction do not establish that an IPO is approaching. They do provide considerably more visibility into the assets behind the proposed REIT and the value Leon’s believes has accumulated within its property portfolio.

Stifel Sees Substantial Real Estate Value

Stifel’s analysis illustrates why the eventual structure has attracted investor attention.

The firm estimates that Leon’s real estate could represent approximately $13 to $15 per share. In a more optimistic sum-of-the-parts scenario, Stifel estimates the retail operating business at approximately $25 per share, producing a theoretical combined value of about $38 to $40 per share when the real estate component is included.

Landry also identifies considerable uncertainty around any eventual transaction. The outcome would depend on which assets Leon’s transfers into the REIT, how investors value the remaining retail operation, the timing of the transaction and how LFL uses any proceeds.

A REIT would also change the relationship between parts of the retail operation and the underlying properties. Depending on the final structure, stores or facilities currently owned directly by LFL could become leased locations occupied by the retailer, while Leon’s retains a significant ownership position in the real estate vehicle.

Development could add another dimension. Properties completed or repositioned by LFL could provide future assets for the REIT, creating a potential connection between the company’s land-development pipeline and the growth of the real estate vehicle.

A Billion-Dollar Property Business Beneath the Retailer

For much of Leon’s history, its real estate served the practical needs of a growing furniture and appliance business. Decades of property ownership have left the company with something considerably larger.

Large parcels can support intensification, while existing retail footprints can be reconsidered as store formats evolve. Development projects can create new income-producing properties, and selected assets could eventually become part of a publicly traded real estate platform.

The strategy remains closely tied to the retail company. Leon’s plans to retain majority ownership of the REIT at launch, and many of the properties under consideration support the operations of Leon’s, The Brick and other LFL businesses.

There is still no timetable for an IPO, and management continues to point to market conditions and regulatory approvals when discussing when the REIT might proceed. The new appraisal nevertheless puts a much clearer number on what Leon’s has accumulated: approximately 50 properties, 5.5 million square feet and 430 acres of land now carrying an appraised value of $1.17 billion.

For a company best known for selling furniture and appliances, real estate has become an increasingly significant part of the Leon’s story.

More from Retail Insider:

43% of Canadians Less Likely to Trust AI-Generated Ads, Vistar Media Finds

Vistar Media image
Vistar Media image

AI is quickly becoming a staple of the advertising industry, transforming everything from creative development to campaign optimization. But while marketers are embracing the technology, Canadian consumers aren’t necessarily buying in.

According to Vistar Media’s State of Consumer Attention Report, 43% of Canadians say they’re less likely to trust an ad if they know it was created using AI, while one-third say AI-driven personalization feels invasive. At the same time, consumers continue to value the qualities AI often struggles to replicate: 69% say humour, emotion and entertainment make ads memorable, and more than half say relevance is what captures their attention.

As brands, agencies and retailers continue investing in AI-powered creative and media strategies, the findings highlight a growing challenge: how can marketers harness AI without sacrificing the authenticity and trust that drive consumer engagement?

In  this interview with Retail Insider, Scott Mitchell, Managing Director, Canada at Vistar Media, discusses what the latest consumer data means for the advertising industry.

Question: Why should AI support, rather than replace, human creativity in advertising?

Answer: Our research reinforces something marketers have always known: the advertising that resonates most is rooted in human connection. Consumers remember work that makes them laugh, surprises them or reflects something meaningful about their lives. Technology can help make those experiences more relevant and effective, but it can’t replace the human insight behind them.

AI has an important role to play in helping marketers analyze data, uncover insights, test creative and work more efficiently. The opportunity is to use those capabilities to strengthen human creativity, not substitute for it. When AI takes on some of the complexity behind the scenes, creative teams can focus more of their energy on the ideas, cultural understanding and emotional connections that ultimately build consumer trust and make advertising memorable.

Q: What does the latest Canadian consumer data reveal about trust, personalization and AI generated content?

A: The research shows that consumer trust in AI is conditional. People see the potential for technology to make advertising more relevant, but they also have clear expectations around how it should be used.

When 43 per cent of consumers say they’re less likely to trust an ad they know was created using AI, and one third say AI-driven personalization feels invasive, it signals that relevance alone isn’t enough. How brands achieve that relevance matters. Consumers want advertising that feels useful and authentic, without crossing the line into an experience that feels overly automated or intrusive.

For marketers, the takeaway is to be intentional about where AI adds value. The technology should work behind the scenes to help deliver smarter, more relevant experiences while maintaining the authenticity, privacy and human connection that build trust. Ultimately, the best use of AI isn’t about making the technology more visible; it’s about making the advertising experience better.

Q: How can brands use AI effectively while maintaining authenticity?

A: The most effective uses of AI are those where the technology enables a better experience without becoming the focus of it.

AI can help marketers better understand audiences, optimize campaigns, improve measurement and automate repetitive tasks. That creates more space for teams to focus on strategy, creative thinking and the ideas that make a brand distinctive. Used well, AI can make marketing smarter and more responsive without changing what consumers recognize and value about the brand.

The key is keeping people in control of the decisions that define the brand. AI can provide insights, accelerate execution and help tailor experiences, but a brand’s voice, values and creative direction need to remain grounded in human judgment. Authenticity comes from knowing what your brand stands for and using technology to express that more effectively, not allowing the technology to define it.

Vistar Media image
Vistar Media image

Q: What do these findings mean for advertisers, agencies, retailers and media owners navigating an increasingly AI driven landscape?

A: We’re moving beyond the question of whether organizations should adopt AI. The more important question is where it can add meaningful value.

For advertisers, agencies, retailers and media owners, that means looking beyond efficiency alone. AI can help make media planning smarter, optimize campaigns, uncover insights and improve performance, but those capabilities need to translate into better advertising experiences for consumers, not simply more content, more personalization or more automation.

The research is a reminder that technology and trust have to advance together. As AI becomes a bigger part of how advertising is created, bought and delivered, marketers should stay focused on the fundamentals: strong ideas, relevant experiences, trusted media environments and a clear understanding of the audiences they’re trying to reach. AI can make each of those things more effective, but it should serve the strategy rather than become the strategy itself.

More from Retail Insider: