Kits Eyecare Ltd., a leading vertically integrated eyecare provider, released on Thursday selected preliminary unaudited results for its second quarter ended June 30, saying total revenue increased 17.3% year-over-year to approximately $58.2 million.
Other results released include:
Adjusted EBITDA exceeded $2.6 Million, or exceeding 4.5% of Revenue
Adjusted EBITDA to exceed 4.5% of Revenue, or exceeding $2.6 million.
Glasses Revenue expanded approximately 50.6% year-over-year to $10.8 million.
Strong cash generation in the quarter drove the Company’s cash balance to exceed $27.3 million at the end of the quarter, and no debt.
The company said it will report its full second quarter 2026 results in early August.
In May, KITS reported that revenue in its first quarter increased by 23.3% to a record $57.5 million compared to $46.6 million. In constant currency, revenue increased by 27.0%. Gross profit increased by 37.5% to $23.5 million, or 40.9% of revenue, compared to $17.1 million, or 36.7% of revenue. Adjusted EBITDA margin was 7.2% at $4.1 million of Adjusted EBITDA, compared to 7.4% at $3.5 million of Adjusted EBITDA. Record Q1 glasses revenue of $10.8 million, increased 60.5% year-over-year; over 156,000 units delivered, increased by 50.0% year-over-year. Net Income increased by 23.2% to $2.0 million or $0.06 per share, compared to $1.6 million or $0.05 per share
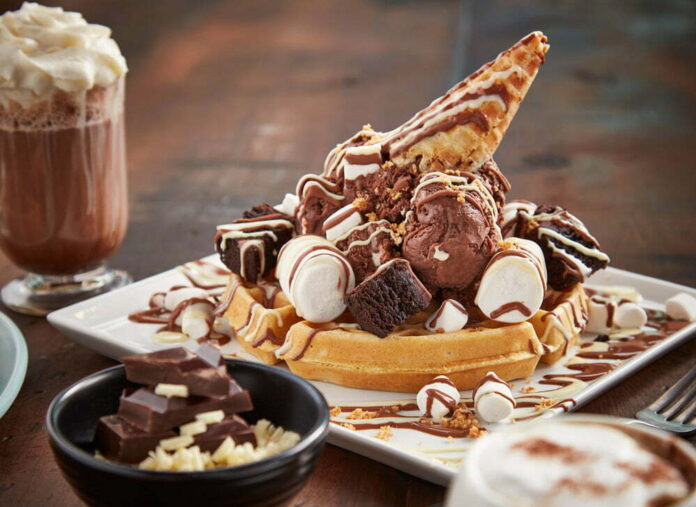
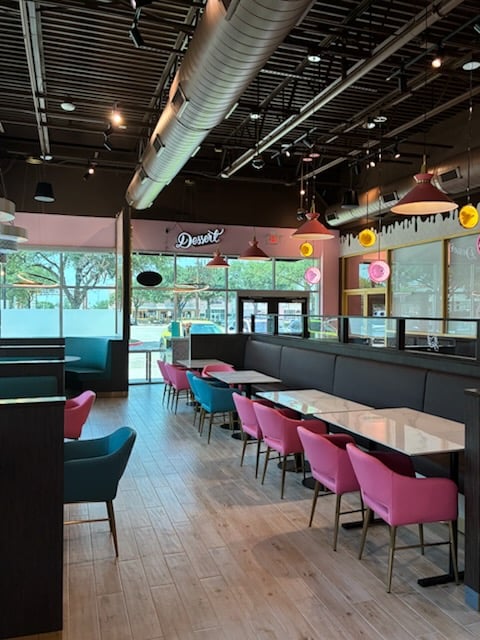
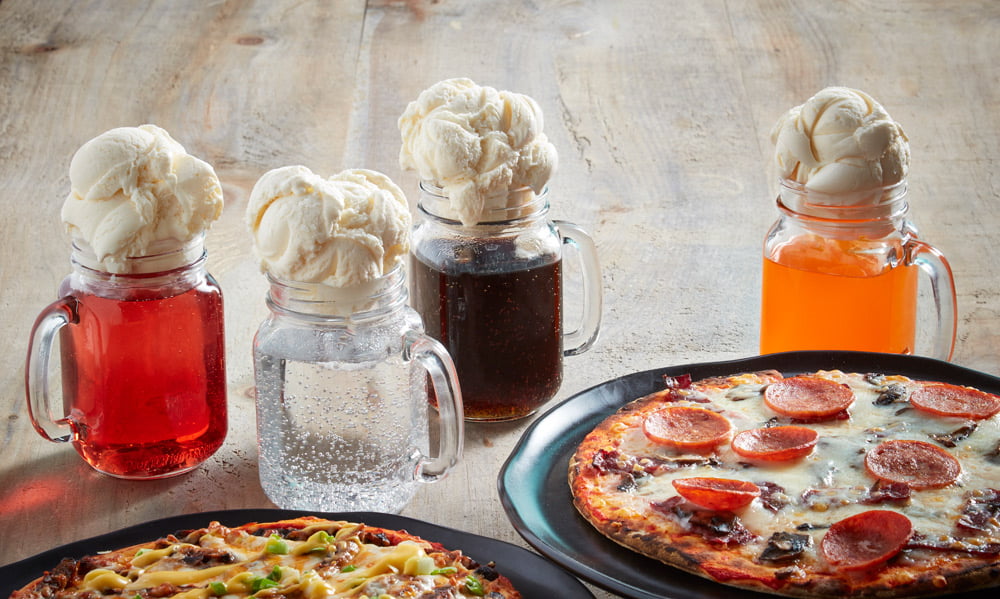
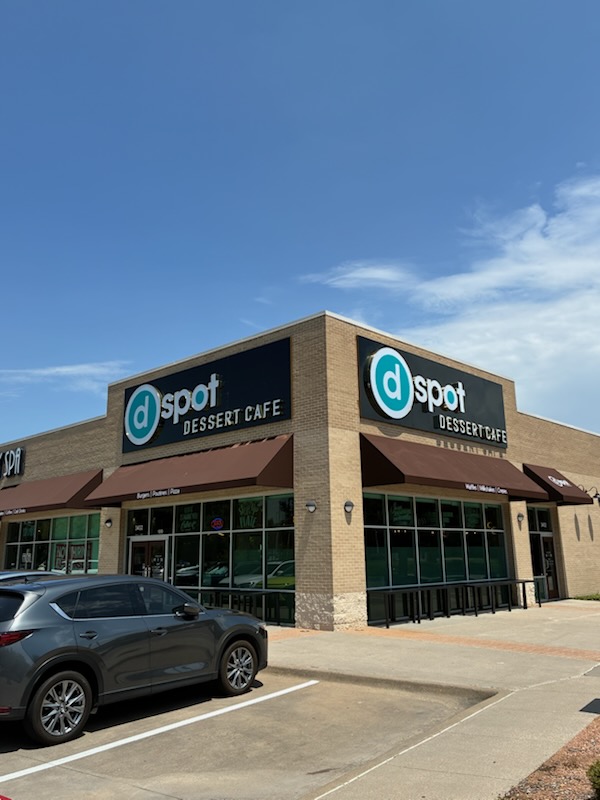
D Spot Dessert Café, a Canadian leading dessert café brand, is embarking on its international expansion plans with its first location in the United States. The new café, located in Dallas, Texas at 3432 E Hebron Parkway, Suite 100, has opened and the company has its sights on more U.S. openings as it continues to expand through franchising.
“This opening marks a significant step in D‑Spot’s growth strategy as we expand into the U.S. market,” said Kaan Sayiner, CEO and President, D Spot Dessert Café. “With a strong Canadian footprint, we’re excited to bring our dessert experience to new communities as part of our broader U.S. expansion.”
The brand was founded in 2014 and has more than 55 locations across Canada.
In an interview with Retail Insider, Sayiner spoke about the company’s growth and its plans for the future.
Question: Why did D Spot choose Dallas for its first U.S. location, and what factors made the city the right launch market?
Kaan Sayiner
Answer: Dallas was a very deliberate choice for our first U.S. location. We were looking for a market with scale, strong consumer energy, demographic diversity, a sophisticated dining culture, and room for a premium dessert café concept that is experiential rather than transactional.
The Dallas–Fort Worth market checks those boxes. It is one of the largest and fastest-growing metropolitan areas in the United States, with the City of Dallas reporting the DFW MSA at just under 8 million residents, and the U.S. Census Bureau reporting that Dallas–Fort Worth–Arlington added nearly 178,000 residents between 2023 and 2024, making it the third-largest gaining metro area in the country. That matters because our model performs best where there is density, family traffic, evening traffic, multicultural demand, and a customer base that is open to bold, highly shareable food experiences.
Dallas is also an excellent bridgehead for the broader U.S. market. It is a major business, travel, and lifestyle hub, with DFW Airport serving more than 87.8 million passengers in 2024 and offering service to more than 260 destinations. For a Canadian brand entering the United States, that combination of local demand and national connectivity made Dallas the right place to prove the concept.
Most importantly, Dallas has a serious food culture. Consumers there understand quality, they are adventurous, and they respond to brands that deliver both substance and experience. That is exactly where D Spot is positioned.
D‑Spot Dessert Café photo
Q: The U.S. dessert café market is highly competitive. What differentiates D Spot from established American chains and independent dessert concepts?
A: The U.S. market is competitive, but that is precisely why differentiation matters. D Spot is not a single-product dessert shop, and it is not a traditional café with desserts added on. We are a full premium dessert experience built around choice, indulgence, hospitality, and visual impact.
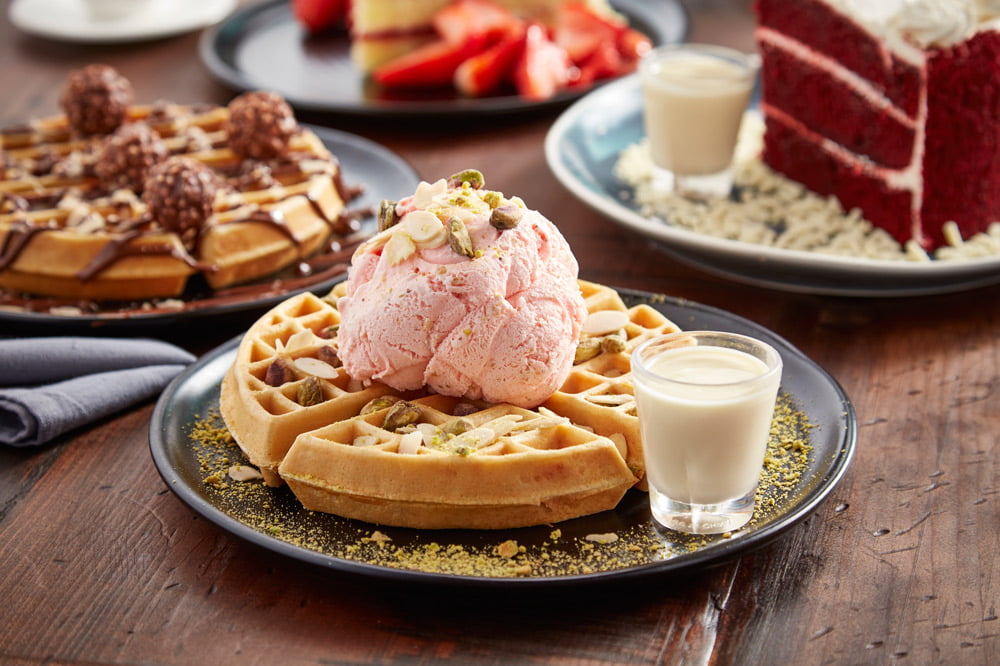
Our differentiation starts with the menu architecture. The brand is known for a broad dessert platform, including Belgian waffles, crepes, sundaes, milkshakes, milk cakes, croffles, skillet desserts, and build-your-own options. That gives guests a level of customization and discovery that is difficult for narrower concepts to match.
Quality is also central to the brand. D Spot’s own brand positioning emphasizes homemade ice creams, fresh-daily batters, Belgian chocolate, and made-from-scratch cakes. That matters because consumers are not just looking for something sweet; they are looking for premium indulgence that feels worth the occasion.
The other major differentiator is that D Spot is built as a social destination. The products are visually expressive and highly shareable, but the concept is not dependent on novelty alone. It has the operational foundation of a scalable franchise system, with multiple concept formats, a recognizable brand, and a flexible operating model. That combination — premium dessert, savory breadth, operational discipline, and a highly social guest experience — is what separates us from both established chains and independent dessert operators.
Q: With more than 55 locations across Canada, what lessons from Canadian growth are shaping your U.S. expansion strategy, and how quickly do you expect to grow south of the border?
A: The biggest lesson from Canada is that disciplined growth matters more than simply adding units. D Spot has grown from a Canadian concept into a national brand with more than 55 locations, and that growth has taught us that the right operator, the right real estate, and the right market sequencing are non-negotiable.
In Canada, we have learned how important it is to build around demand clusters: strong suburban communities, family-oriented trade areas, student and young professional traffic, multicultural neighbourhoods, and high-visibility retail corridors. That experience will directly shape how we grow in the U.S.
Our intention is to scale aggressively, but not recklessly. The first priority is to establish Dallas properly, support the franchise partners, validate the operating model in the U.S., and then expand in a sequenced way through strong regional markets. Our location pipeline already includes Houston, Atlanta, Chicago, and Nashville. Those are the types of cities that align well with our brand: large, diverse, high-growth, food-forward markets where consumers are actively looking for new dining experiences.
In parallel, we will continue building Canada with strategic infill and new-market development. That includes deepening our presence in British Columbia and pursuing Atlantic Canada, while ensuring our existing markets continue to mature. The ambition is to become the leading premium dessert café brand in North America, and over time, to take the concept into select international markets where the demand profile is strong.
D‑Spot Dessert Café photo
Q: Your menu combines desserts with a substantial savory offering. How important is that all-day dining approach to the brand’s success, and do you expect to adapt the menu to suit American tastes?
A: The savory offering is very important because it expands the role D Spot plays in a guest’s day. We are not limited to the after-dinner dessert occasion. Guests can come in for a meal, stay for dessert, celebrate, meet friends, bring family, or visit late in the evening. That gives the brand more daypart flexibility and more reasons for repeat visits.
D Spot’s full-concept locations include savory items such as smashburgers, sliders, grilled sandwiches, poutine, and loaded fries alongside waffles, crepes, sundaes, milkshakes, and other signature desserts. Nation’s Restaurant News also noted savory items such as burgers, pizza, pasta, wings, and poutine in the U.S. opening coverage. That is a meaningful advantage because it broadens the guest base beyond the pure dessert occasion.
In the U.S., we will protect the core of the brand while being thoughtful about local adaptation. The heart of D Spot is premium indulgence, generous choice, and an experience that feels memorable. That will not change. But we will listen carefully to American guests and franchise partners on flavor preferences, portion strategy, beverage innovation, savory mix, and local-market relevance.
The goal is not to become a different brand in the U.S. The goal is to make D Spot feel immediately relevant to U.S. consumers while preserving what made the brand successful in Canada.
D‑Spot Dessert Café photo
Q: What are your long-term ambitions for the U.S. market, and which regions or cities are priorities after the Dallas opening?
A: Our long-term ambition is clear: we believe D Spot can become the leading premium dessert café platform in the U.S. The market is large, fragmented, and still underdeveloped when it comes to scaled experiential dessert cafés. There are strong chains and excellent independents, but there is significant white space for a brand that combines premium desserts, savory food, late-day occasions, social energy, and franchise scalability.
The broader restaurant market remains substantial. The National Restaurant Association projects U.S. restaurant industry sales of $1.55 trillion in 2026, with operators continuing to focus on guest connection, value, productivity, and technology. Within desserts specifically, publicly available market research also points to continued growth in frozen desserts and premium/artisanal categories. Future Market Insights reports the global ice cream and frozen dessert market at approximately $148.7 billion in 2025, projected to grow at a 7.5% CAGR from 2026 to 2036; Global Market Insights reports the artisanal ice cream market at $8.9 billion in 2025, projected to reach $18.7 billion by 2035 at a 7.6% CAGR. Those trends support what we are seeing directly from consumers: demand for indulgence, quality, customization, and experience remains strong.
After Dallas, the priority is to build regional momentum in markets where the demographics and real estate fundamentals align with our model. Houston is a natural next step in Texas, and D Spot’s public location pipeline also identifies Atlanta, Chicago, and Nashville as upcoming U.S. markets. Beyond those, we see strong potential in major Sun Belt markets, select Midwest cities, and dense suburban trade areas around large metros.
Internationally, the opportunity is also meaningful, but the U.S. is the immediate growth priority. Canada gave us the platform. Dallas is the first step in proving the U.S. opportunity. From here, the focus is disciplined execution, strong franchise partners, and building D Spot into a category-defining brand.
New consumer research from Curion, a leading consumer insights and product testing firm, says there is a widening disconnect between where the appliance industry is placing its biggest innovation bets and what consumers actually buy on. While manufacturers continue to invest heavily in smart, connected, and feature-rich products, consumers overwhelmingly make purchase decisions based on long-term reliability and value — and they rank smart features near the very bottom of what matters, it said.
“The contrast is hard to miss. In a Curion poll of 5,610 U.S. consumers, long-term reliability (45%) and price/value (27%) together accounted for nearly three of every four purchase decisions. Smart features, by comparison, were the primary driver for just 2.7% of consumers — ranking 8th out of 11 options, behind brand trust, energy efficiency, ease of use, and even warranty and service support. More consumers chose “none of the above” (2.9%) than chose smart features at all,” explained Curion.
“The most striking finding cuts against a core industry assumption: that younger, digitally native consumers will drive smart-appliance adoption. In fact, they don’t. Consumers aged 18–34 chose smart features at just 3.0% — statistically indistinguishable from the 1.9% of those 65 and older. The generation that grew up on smartphones and connected everything wants it in their appliances at essentially the same near-zero rate as their grandparents.”
When forced to name a single primary driver, those same younger consumers chose reliability (51%) and price/value (25%) — the same priorities as every other age group, said the report.
Notably, “fear of complexity” ranked dead last (0.9%) among barriers to upgrading — not because complexity isn’t a concern, but because many consumers appear to have already dismissed complicated products from consideration entirely, said the report.
Tomás Gilbert
Energy efficiency, another major industry talking point, was named by only 3.0% of consumers as their primary driver, further suggesting that for all the messaging around sustainability and efficiency ratings, the feature functions as table stakes rather than a reason to buy, it added.
“The innovation narrative and the consumer reality are running in opposite directions,” said Tomás Gilbert, director of strategic market insights, Curion. “Brands are spending enormous R&D dollars on features consumers didn’t ask for and, in some cases, actively don’t want — while the things that actually earn a purchase and a repurchase, durability, value, and human support, get treated as afterthoughts. The lesson isn’t that consumers reject technology. It’s that a feature only matters if it does a real job better than what they already own. When it doesn’t, it reads as one more thing that can break.”
Keren Novack
“This is where the homework matters,” added Keren Novack, president of Curion. “Before a brand brings a product to market, it has to know what need it fills and whether that’s genuinely worth a consumer replacing what’s already in their home. The brands that win the next chapter of this category won’t be the ones with the smartest appliances. They’ll be the ones consumers feel most confident bringing through the door.”
Retail Insider Reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.
The report examines Canadian apparel and fashion retail, including clothing, footwear, accessories, department store fashion, specialty apparel retailers, merchandising strategies, consumer demand, expansion and competitive developments. It uses Retail Insider coverage, company disclosures and broader market research to assess the commercial forces shaping the sector in Q2 2026.
General Themes
Market polarization is accelerating: Consumers are increasingly gravitating toward premium and differentiated brands or value-focused offerings, leaving generalized mid-market apparel chains under pressure.
Apparel demand remains resilient but uneven: The report notes that April 2026 sales for clothing, accessories, shoes, jewellery, luggage and leather goods retailers were up year over year, despite month-over-month softness.
Specialists are outperforming generalists: Brands with clear positioning, focused assortments and distinct customer propositions are showing stronger relevance than broad-based apparel chains.
Premium brands remain active in physical retail: Aritzia, Canada Goose, Tilley, Alo Yoga and other differentiated brands continue to invest selectively in flagship stores and high-quality locations.
Value and resale continue to gain share: Off-price, discount and resale operators are benefiting from affordability concerns, shifting attitudes toward second-hand shopping and the appeal of treasure-hunt retail.
Real estate quality is becoming more decisive: Apparel investment is concentrating in top-performing shopping centres, mixed-use destinations and urban retail nodes that deliver productivity, tourism and affluent consumers.
Inventory discipline remains critical: Retailers with stronger operational flexibility, supply chain control and margin discipline are better positioned in an uncertain demand environment.
Retail Insider Coverage
Retail Insider’s reporting during the quarter helped frame one of the report’s central findings: Canadian apparel retail is not weakening evenly. Instead, the market is splitting between premium brands, value-oriented retailers, resale operators and focused specialists, while more generalized mid-market apparel chains face heavier pressure.
The report draws on Retail Insider coverage of Aritzia’s expanded flagship at CF Toronto Eaton Centre, Groupe Dynamite’s growth through a top-tier mall strategy, Canada Goose’s push beyond parkas and Tilley’s continued evolution into a broader outdoor lifestyle brand. These examples show how stronger apparel operators are using selective store investment, clearer positioning and better real estate to reinforce their brands rather than simply add more locations.
Retail Insider’s coverage also captured the growing importance of specialist retail. Vessi’s measured retail expansion reflects demand for in-person shopping around a clearly defined footwear proposition, while Uniqlo, Alo Yoga and Mango are cited in the report as examples of international brands continuing to view Canada as an attractive expansion market, particularly in major urban centres and high-performing shopping centres.
At the other end of the market, the report points to continued momentum for value and resale. Savers Value Village, Winners, Marshalls, Costco, Walmart, Shein and Temu are all part of the broader competitive picture, with consumers continuing to seek affordability, speed, assortment and treasure-hunt shopping experiences. Angels Wear Preloved’s resale event coverage also reflects the growing relevance of second-hand apparel in Canada.
The pressure on the middle of the market is illustrated through Retail Insider’s reporting on Warehouse One and Bootlegger, which moved to liquidate all stores under CCAA. The report places that collapse within a broader structural shift affecting apparel chains that lack the pricing power of premium brands, the cost advantage of value players or the distinct identity of category specialists.
Editor’s Take
The central conclusion of the report is that Canadian apparel retail is becoming a market of specialists. Brands with clear identities, disciplined expansion strategies and compelling value propositions are still finding growth, whether at the premium end, in activewear, in resale, in functional basics or in outdoor lifestyle categories. The hardest position is now the undifferentiated middle, where broad apparel chains face competition from stronger brands above them, cheaper options below them and faster digital platforms around them.
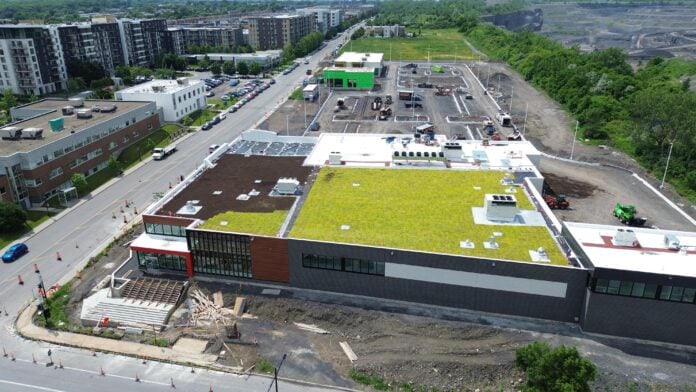
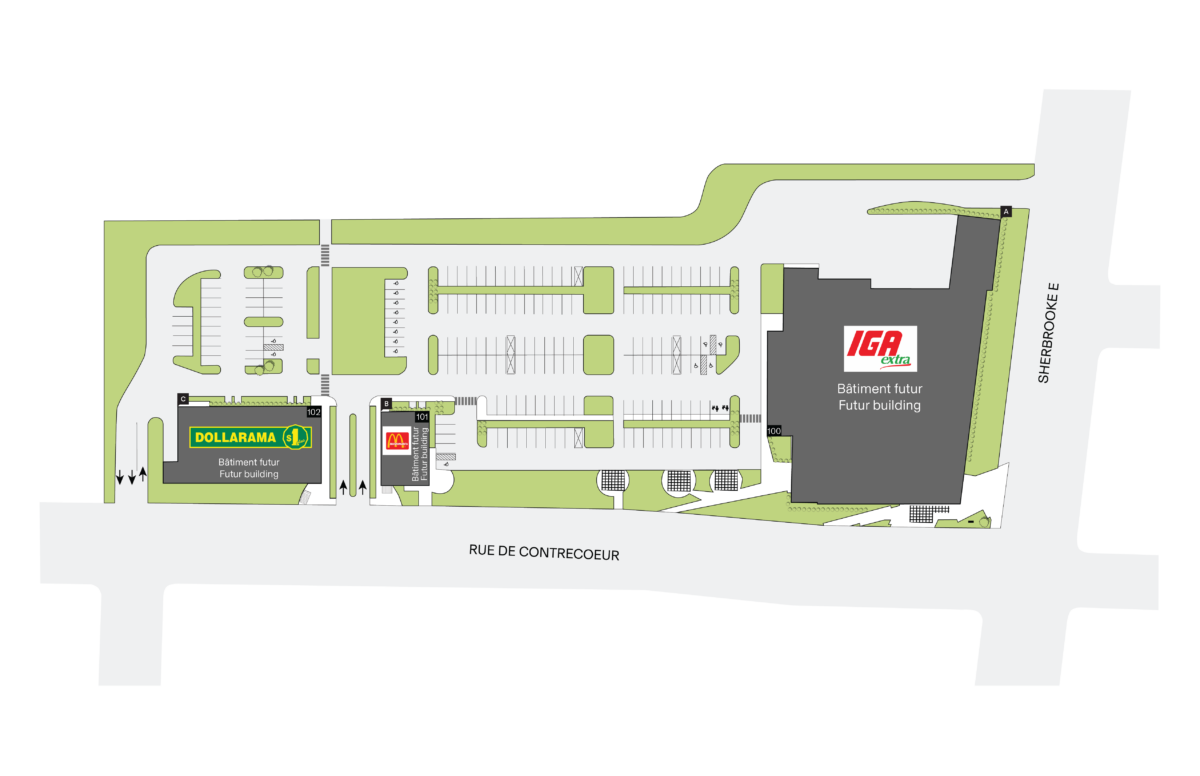
Aerial view of the new commercial development Faubourg Contrecœur in Montréal’s Mercier–Hochelaga-Maisonneuve borough. With the addition of Dollarama and McDonald's alongside anchor tenant IGA, the retail centre has now reached full occupancy ahead of its planned summer 2026 opening.
The commercial development has reached a major milestone with the signing of these clients, bringing the project to 100 per cent occupancy, the companies said in a news release.
Developed in partnership with Harden and Crombie, they said Faubourg Contrecœur is now firmly in the development phase, with construction advancing steadily across the site. With all commercial spaces now leased, the project will eventually bring long-awaited services to the neighbourhood.
Dollarama will occupy approximately 9,726 square feet and McDonald’s approximately 3,046-square-feet. Construction is underway for both with a targeted opening end of summer and early fall. A cornerstone tenant, the new IGA grocery store is scheduled to open on August 13. The store will span approximately 40,020 square feet and serve as a cornerstone of the commercial centre.
“We are proud to bring this project to life in partnership with Crombie and deliver a quality, necessity-based retail offering that supports the everyday needs and affordability of local residents while creating long-term value for the community”, said Tyler Harden, Co-CEO of Harden. “We look forward to welcoming customers this summer.”
Tyler Harden
“Once completed, Faubourg Contrecœur will provide residents a well-rounded retail environment, supporting the continued growth of the surrounding neighbourhood. The project is expected to become a central shopping hub for daily necessities, while responding to a long-standing demand from many local residents for new businesses and commercial development in the area. Faubourg Contrecœur is located at 3553 rue de Contrecœur, Montreal, QC, the intersection of rue Sherbrooke Est and rue de Contrecœur,” said the companies.
Established in 1985, Harden is a second generation, family-owned real estate company whose primary focus is owning, developing and operating commercial, residential, and industrial properties in many communities throughout the provinces of Quebec and Ontario. Vertically integrated, Harden specializes in all facets of the real estate development process, including development, construction, leasing, and asset management.
Site plan of Faubourg Contrecœur, the new commercial development by Harden and Crombie REIT in Montréal’s Mercier–Hochelaga-Maisonneuve borough. With the addition of Dollarama and McDonald’s alongside anchor tenant IGA, the retail centre has now reached full occupancy ahead of its planned summer 2026 opening.
Crombie invests in real estate with a vision of enriching communities together by building spaces and value today that leave a positive impact on tomorrow. As one of the country’s leading owners, operators, and developers of quality real estate assets, Crombie’s portfolio primarily includes grocery-anchored retail, retail-related industrial, and mixed-use residential properties. As of June 30, 2025, the portfolio contained 306 properties comprising approximately 18.8 million square feet, inclusive of joint ventures at Crombie’s share, and a significant pipeline of future development projects.
Allard Developments says a new 42,500-square-foot Winners/HomeSense store will open at Parsons Creek Town Centre in Fort McMurray, marking the first and only location for the retail brands in the region.
Construction and tenant timelines will be announced at a later date.
The combined Winners/HomeSense store will become a major anchor tenant within Parsons Creek Town Centre, a planned regional retail destination that will ultimately accommodate up to 500,000 square feet of retail space in the master-planned retail development.
The announcement follows the development of a new approximately 142,000-square-foot Walmart Supercentre at Parsons Creek, which will relocate Walmart’s existing Fort McMurray store and establish the site as the city’s dominant retail destination, said the company.
“Securing Winners/HomeSense represents another significant milestone for Parsons Creek Town Centre and reinforces the strength of the Fort McMurray market,” said Paul Allard, with Allard Developments. “This development is designed to serve not only Fort McMurray residents, but the broader Northern Alberta trade area, providing access to nationally recognized retailers and creating a modern retail experience for the region.”
The company said Parsons Creek Town Centre is strategically positioned within Fort McMurray’s northern growth corridor, serving neighbourhoods that account for more than 70 per cent of the city’s residential population. The project is being developed to meet growing demand for retail services while capturing spending that has traditionally flowed to larger urban centres.
The Regional Municipality of Wood Buffalo continues to demonstrate strong economic fundamentals, including a population exceeding 107,000 residents, household incomes that rank among the highest in Canada and more than $2.3 billion in annual retail spending potential, it said.
Lisa Sweet
“We are thrilled to welcome Winners and HomeSense to Parsons Creek and to Fort McMurray Wood Buffalo,” said Lisa Sweet, CEO of Fort McMurray Wood Buffalo Economic Development & Tourism. “In both our 2021 and 2023 resident surveys, these retailers ranked among the most requested brands residents wanted to see in the region. This investment will create local jobs, expand retail choice and help keep spending within our community that has historically flowed to larger centres such as Edmonton.
“This announcement reflects growing confidence in our market and contributes to enhancing quality of life for residents while supporting the region’s long-term economic growth and resilience.”
An online store earns a large share of its yearly revenue in a handful of hours, and those hours are exactly when a weak server is most likely to fail. A Black Friday morning or a product that suddenly trends on social media: traffic arrives all at once, every shopper heads for the same cart and checkout, and the part of the store that cannot be cached has to handle every one of them live. A store that runs fine on a quiet Tuesday can stall at the precise moment it stands to make the most money. The collapse is sudden, since the server holds until the instant it does not, and that instant is the checkout under load.
It comes down to how a store checkout works. Most of a WordPress store can be cached and served fast, but the cart, the checkout, and the account pages cannot. They are different for every shopper, calculated fresh each time, and that work lands on the server during the busiest minutes of the year.
The Uncacheable Checkout
A product page is the same for everyone, so it can be saved and served from a cache without running any code. A checkout is personal. The cart contents, the shipping address, the tax, and the payment options all belong to one shopper and have to be built fresh on every request. Caching, the trick that keeps the rest of the store quick, does not apply here.
That leaves checkout speed resting on three things: how fast the server runs PHP, how fast the database answers, and how much extra code the page is carrying. On a quiet day a thin plan hides these limits. Under a rush they all show at once.
The Math of a Sale-Day Spike
Server capacity during a rush comes down to PHP workers. A worker can process a single request at any moment, so one worker handles exactly one checkout at a time. A plan with two workers can run two checkouts at once and no more. The third shopper waits, the fourth waits behind them, and a queue forms while everyone watches a spinning button.
A store expecting a flash sale needs room for several checkouts running together, which means four workers at a minimum and more for a large event. When the workers run out, the server stops accepting new requests and returns an error. The shopper who hit submit with a full cart gets a failure page, and the sale the marketing built toward turns into a wall of timeouts. The cruel part is that the store looked ready an hour earlier, when the same plan served a trickle of visitors without a hint of strain.
The Store Behind the Buy Button
Behind the buy button is a server doing real work on every order. It runs the checkout code, writes the order to the database, checks stock, and talks to the payment processor, all while the shopper waits. Choosing a WordPress hosting provider with the muscle to run many orders at once is what keeps that work quick when a hundred people check out together.
The quiet months hide the difference. A store with ten orders a day runs fine on almost anything. The same store on its biggest day needs the capacity it never uses the rest of the year. Sizing the plan to that one day is the difference between a record and an outage.
Carts Abandoned at the Worst Moment
Shoppers abandon carts at a punishing rate even when everything works. Across 50 studies, the average cart abandonment rate is 70%, and slow performance makes it worse, with 57% of shoppers leaving a store that loads too slowly. A checkout that crawls during a rush turns a ready buyer into a closed tab.
The timing is what makes it expensive. These are people who chose an item, entered a shipping address, and reached for a card, then gave up because the server could not keep pace. Each one was a completed sale a second before the page stalled.
The Database Work Inside a Checkout
A checkout leans on the database in a way a product page never does. Placing an order writes new records, updates stock counts, stores the session, and reads customer and tax data, all while the shopper waits. Under heavy concurrency those writes can collide, as two shoppers reach for the last unit of the same product and the server has to settle which one wins. Resolve that wrong and the store oversells stock it does not have, and resolving it slowly leaves every other shopper waiting behind the lock.
Two tools ease this load. Object caching holds expensive query results in memory so the database is not asked the same question repeatedly, which works even on a checkout because it caches data rather than the page. The order records can also be moved to dedicated tables built for the job, keeping order queries from dragging through the same tables that hold every post and setting. Both help, and each one needs a server with the memory and speed to run it.
The Scale of a Sale Day
The size of these days is not a guess. On a single recent Black Friday, U.S. shoppers spent a record 11.8 billion dollars online in 24 hours, and the weekend that followed pulled in billions more. At the afternoon peak, shopping carts took in around 12.5 million dollars a minute, the kind of concentration that finds the weak point in any server. The rush is predictable down to the date, which means a store can plan for it instead of being surprised by it.
Those records come with a warning. Every season, some store somewhere goes down at peak, its servers overwhelmed by the traffic the sale created. In a single recent year shoppers spent billions online in a day, and a store that cannot keep pace in those minutes loses orders it never recovers. The retailers that stay up are the ones that sized their hosting for the spike in advance. The rest discover the limit live, while shoppers sit watching a checkout that will not load.
Building for the Busiest Hour
A store cannot be sized for its quiet days, because the quiet days never test it. The real measure is the busiest hour of the busiest day, when every shopper arrives together and heads for the same uncacheable checkout. A plan that sails through a slow Tuesday tells a retailer nothing about how it will hold up then.
Sizing for that hour means confirming the workers to run many checkouts at once, the memory for object caching, and a database quick enough to record orders without a queue. Online retail keeps setting records, with shoppers raising their online spending each season, and the stores that capture that demand are the ones whose servers were ready before the rush. The rest spend the biggest day of the year repairing damage instead of taking orders.
When a new luxury fashion store opens, retail coverage usually starts with location, square footage, design, and brand mix.
Behind the scenes, it’s also a technology launch.
POS terminals, appointment systems, inventory tools, Wi-Fi, staff devices, clientele software, and e-commerce links all have to work before sales begin. That is especially true for brands using appointment-led services, where store staff rely on accurate client records before a visit begins.
Now, the harder question: What happens if systems fail during a trading moment, when the store is still expected to serve clients and protect records?
Before a luxury retailer opens, relocates, or winds down a store, cyber risk assessment services are one way to review weak points across payment systems, store networks, staff devices, and customer data workflows.
The first visible cost is store disruption
IBM’s 2025 Cost of a Data Breach Report puts the global average cost of a data breach at US$4.4 million. A breach arrives as downtime, investigation, legal review, customer communication, system rebuilds, and lost productivity.
For a luxury fashion retailer, the first visible cost can happen on the store floor. Payment terminals can go offline. Associates can lose access to clientele notes. Inventory lookup can fail during a private appointment. Ecommerce orders may stop syncing with store stock. Delivery updates and loyalty accounts can be affected.
That disruption is worse during an opening week, a relocation, or a product launch. In luxury retail, service continuity is part of the product. A client who has booked a fitting or reserved a handbag expects the store to know the details. If staff are working from partial records, the brand experience changes immediately.
Luxury stores hold more than payment data
Retail breach discussions often focus on card data, but luxury fashion stores hold far more sensitive information than payment details. Clientele systems can retain purchase history, size preferences, delivery addresses, wish list items, repairs, alterations, appointment records, and high-value transaction history.
That information is commercially valuable because luxury retail is built on long-term customer relationships. Sales associates use purchase histories to personalize recommendations, while store managers rely on appointment notes and client preferences to prepare for exclusive events and product launches.
The same information also makes luxury retailers attractive targets for cyber criminals. If access to customer records, payment systems, or business data is not properly controlled, those assets become valuable entry points for attackers.
The Canadian Centre for Cyber Security warns that threat actors target Canadian businesses for customer, supplier, financial, payment-system, and proprietary data. A successful cyber incident can result in reputational damage, operational disruption, lost productivity, and significant recovery costs.
For luxury retailers, reputation can be harder to repair than systems. A breach involving VIP client data, delivery details, or purchase histories would be seen as a failure of discretion, and discretion is part of the luxury proposition.
Openings, relocations, and closures create weak points
Retail Insider recently reported that Hermès plans to open a standalone Calgary boutique on Stephen Avenue, moving from a Holt Renfrew concession of about 1,300 square feet to a planned 5,000- to 6,000-square-foot store. A luxury relocation at that scale brings a large technology handover.
A new boutique may require network cabling, payment terminals, access controls, staff devices, guest Wi-Fi, inventory integrations, and vendor portals. Temporary access is often given to contractors, installers, and service providers during build-out, but each extra login, device, and connection can widen the risk surface.
A relocation adds another layer because old and new systems often overlap. Closures can be just as exposed if access is not removed properly. A store winding down still holds devices, customer records, payment terminals, network access, and staff credentials.
If accounts are not removed, devices wiped, and vendor access closed, risk can remain after the storefront is gone.
Where risk assessment changes the bill
The value of a cyber risk review is not only in finding technical gaps. For retailers, it’s also in finding operational failures before they become trading problems. A weak backup policy may become a delayed reopening. A missing access review may leave an ex-employee or vendor account active.
This is where cyber risk assessment services belong inside the retail expansion plan.
Experts can test whether payment workflows, staff permissions, cloud tools, backups, endpoint controls, and vendor access match the way the store operates. Experts can also reveal whether retail systems are owned clearly enough for someone to act during an incident, rather than waiting for vendors to decide who is responsible.
For a GTA retailer, an IT company in Markham may be the search phrase that starts the conversation, but the real need is broader than local support.
The partner has to understand how store networks, e-commerce, Microsoft 365, POS systems, clientele tools, and vendor access fit together.
Without this expertise and oversight, retailers stand to lose more than the cost of the recovery invoice or lost trading day. They can face interruption, investigation, customer reassurance, and reputational pressure arriving when a retailer needs the store to perform.
For Canadian luxury retailers, cybersecurity now sits inside the operating model of the boutique itself.
Smart companies treat website redesign services as a growth lever now. Not a fresh coat of paint. A redesign reshapes how people find you, how long they stick around and how often a curious visitor becomes a paying one.
Picture this. You click a link, the page crawls to life, the layout fights you and within three seconds you are gone. Sound familiar? You are far from alone. Adobe found that a business loses at least a third of its visitors when pages fail to engage through clear, useful design. That one number pushed redesign off the marketing wish list and straight onto the boardroom agenda.
Why a Redesign Actually Moves the Needle
Traffic, conversions and return sit on the same base. Search engines crawl a clean structure and rankings climb. Users find what they need fast and they convert. Both happen together and every marketing dollar suddenly pulls its weight.
Think of a website as a shop. Dusty entrance. Confusing aisles. A till that jams. Shoppers walk out. Now tidy the layout, brighten the signage, speed up the checkout. The same foot traffic buys more. Nothing about the crowd changed. The experience did.
The Traffic Engine Hiding in Good Design
Search visibility rewards technical health. Clean front-end code and quick page rendering make a site easier for search engines to read and rank. Better reading means better ranking and better ranking pulls in more visitors.
A redesign usually bundles a few traffic drivers into one project. The common ones look like this:
Faster load times that cut bounce and keep ranking algorithms happy
Mobile-first layouts, because most visitors browse on a phone anyway
Restructured navigation that helps people and crawlers reach deep pages
Fresh SEO foundations aimed at the words your buyers really type
One footwear retailer watched this happen firsthand. After a CMS-ready refresh of product pages and SEO groundwork, the store drew new visitors and lifted engagement on both mobile and desktop. Same catalogue. Different results.
Turning Visitors Into Buyers
Traffic without conversion is a leaky bucket. Water in, water straight out. A clear, intuitive interface guides people toward action and makes a sign-up or a purchase feel almost automatic. Strip the friction from a checkout and abandoned carts shrink.
The numbers stay honest here. One project cut abandoned orders at the checkout by 40 percent after rethinking a single flow. An online bank rebuilt its portal, doubled its client base and hit a high satisfaction score along the way. These are not vanity metrics. They show up on the invoice.
Measuring the Return on Investment
ROI wins over the skeptics. A redesign done properly pays back through stronger conversion rates, longer sessions and lower support costs. Want proof? Look at what real projects delivered.
Business goal
Typical redesign outcome
Organic traffic
Clear lift after navigation and media cleanup
Checkout abandonment
Drops around 40 percent
Client base growth
Twofold expansion for a digital bank
eCommerce net sales
Growth near 23 percent with 41 percent more monthly visitors
Here is the takeaway. A tweak that looks tiny on a mockup can trigger large, trackable gains once living, clicking users meet it.
Top 5 Website Redesign Companies to Watch
Your choice of partner shapes the whole outcome. So here sits a ranked shortlist of five strong providers, each with its own edge.
1. Andersen
Andersen tops the list for range and depth. With more than 19 years in software development, the company blends full-cycle UX/UI redesign with the engineering muscle to actually ship it. Its design family runs past 50 specialists and the work has earned nods from Awwwards, Dribbble and Behance next to a strong Clutch rating. A typical redesign runs 4 to 8 weeks, handled by a UX/UI designer, a product manager, a QA engineer and a researcher. That mix of speed, craft and technical follow-through makes Andersen a safe bet for teams chasing measurable results rather than a quick gloss.
2. Clay
Clay builds premium web experiences from San Francisco for global brands. Strategy, custom design, engineering, all fused together. Its client roster stretches to names like Google, Slack, Coinbase and Toyota. Startups and enterprises that want story-led, sophisticated interfaces land here, though the premium price tag suits fuller budgets.
3. WebFX
WebFX is performance obsessive. Working out of Harrisburg, the firm ties web design tightly to SEO, PPC and analytics, so every layout decision traces back to revenue. Mid-market teams that prize speed, clarity and honest reporting tend to click with its packaged programs, especially on sprawling, high-page-count sites.
4. Ramotion
Ramotion serves emerging and scaling companies that need to punch above their weight. The team fixates on brand systems and sites that grow fast without a constant rebuild, leaning on design tokens and clean editorial modules. Startups racing toward launch with flexible systems get the most value.
5. Lounge Lizard
Lounge Lizard closes the list as a full-service agency running since 1988. It marries strategic UX with brand storytelling and conversion-focused tech across several US offices. One of its redesigns drove a 133 percent jump in organic search results. Creativity and data, holding hands.
How to Pick the Right Partner
Start with the outcome, not the agency name. Do you want more qualified leads? A faster site? A clearer brand story? Write that goal down before you email anyone.
Then ask for evidence, never just promises. Request a similar project. Ask what changed after launch. Confirm what the team touched directly. A partner worth hiring welcomes those questions and answers them with numbers, not adjectives.
Common Pitfalls to Sidestep
Redesigns fall apart when teams chase trends instead of users. Skip the research, ignore mobile, launch with zero A/B testing and the gains you hoped for quietly vanish.
Budget surprises sting too. Scope creep swells timelines and costs. Lock the deliverables down early and keep everyone aligned, or the project drifts.
Conclusion
A thoughtful redesign is one of those rare bets that lifts traffic, conversions and ROI all at once. Clean code brings the crowd. Intuitive flows convert them. Hard numbers justify the spend. The evidence from real projects, a 40 percent drop in checkout abandonment here, a doubled client base there, shows how high the ceiling goes when execution stays disciplined.
Want a partner that pairs design craft with engineering reliability? Andersen offers full-cycle redesign backed by nearly two decades of delivery. The right team turns a tired website into a working sales channel and that shift tends to pay for itself sooner than anyone expects.
FAQ
Can a redesign hurt my existing SEO rankings?
It can, if handled sloppily. Broken redirects and lost URLs wreck rankings. A proper redesign maps old pages to new ones and guards your link equity from day one.
How soon will I see results after launch?
Some wins land instantly, like faster load times. Traffic and conversion gains build over a few weeks as search engines re-crawl and users settle into the new flow.
Is a full rebuild always necessary, or can I refresh in stages?
Staged refreshes work fine when the core is solid. If the platform is old and slow, a full rebuild often costs less over time than endlessly patching a fragile base.
Will a beautiful design alone boost my conversions?
No. Looks build trust, sure, but conversions come from friction-free flows, clear calls to action and fast pages pulling together.
How do I prove the redesign paid off to my boss?
Track a handful of metrics before and after launch. Bounce rate, conversion rate, session length, organic traffic. Clean before-and-after figures make the return tough to argue with.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the latest articles we published covering key developments in Canadian retail.
Marilyn Brooks, a pioneering figure in Canadian fashion retail, passed away at 93, leaving a lasting impact on the industry through her innovative retail and design approaches. Walmart is set to enhance Bramalea City Centre by opening a new Supercentre in 2027, expanding its footprint in Brampton. Bang & Olufsen made a statement by launching a flagship store in Toronto’s Yorkville, targeting the luxury consumer segment.
Pop Mart is expanding rapidly across Canadian cities after strong early demand for its experiential retail concept. MHRA Hospitality broadened its portfolio by acquiring Holy Chuck Burgers to strengthen its presence in premium casual dining. Meanwhile, rising food inflation is causing Canadian grocery shoppers to become more tactical with their purchases, reflecting shifts in consumer behaviour across the sector.