Home Blog Page 3

Canada’s Menswear Market Is Being Rebuilt as Retailers Invest in Premium and Luxury

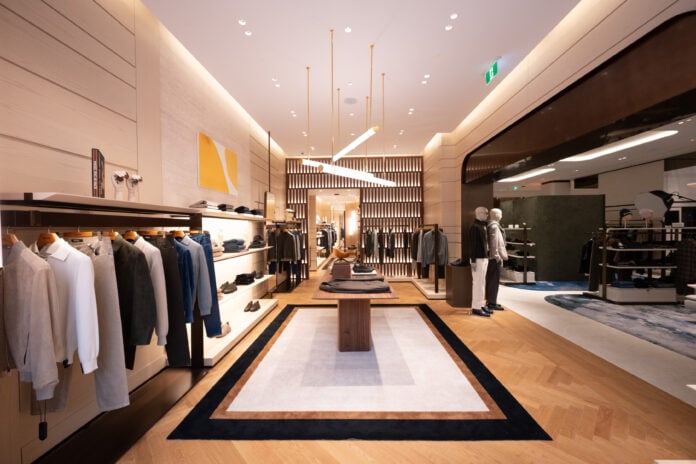
Zegna boutique at Harry Rosen, 153 Cumberland St. in Toronto. Image: George Pimentel Photography

Canada has lost a remarkable amount of department-store space in recent years with the exits of Nordstrom, Hudson’s Bay and Saks Fifth Avenue. At the same time, the availability of premium and luxury menswear is expanding as established Canadian retailers invest in stores, new concepts enter the market and international luxury houses build larger standalone boutiques.

Harry Rosen is spending approximately $50 million over five years transforming its Canadian store network. Holt Renfrew continues to rethink menswear at its 50 Bloor Street West flagship in Toronto, while La Maison Simons is bringing substantial men’s departments into new markets as it expands across Canada. Henry Singer has relocated longstanding downtown stores in Edmonton and Calgary, TNT The New Trend invested in a large Yorkville Village store, and newer concepts including HANK and Modern Ambition have plans to grow.

At the luxury end, the expansion is even more visible. Yorkdale Shopping Centre, Oakridge Park, Royalmount, Bloor-Yorkville and Vancouver’s Alberni corridor have accumulated growing collections of international luxury boutiques, many with significant men’s assortments. Gucci is expected to open an approximately 12,000-square-foot Yorkdale store in November 2026, while Saint Laurent, Loewe and other luxury houses have also invested in large Canadian locations.

The result is a restructuring of Canadian menswear distribution. Department stores that once aggregated dozens of brands have disappeared or contracted, while the selection available through specialists, fashion retailers and brand-operated boutiques has broadened.
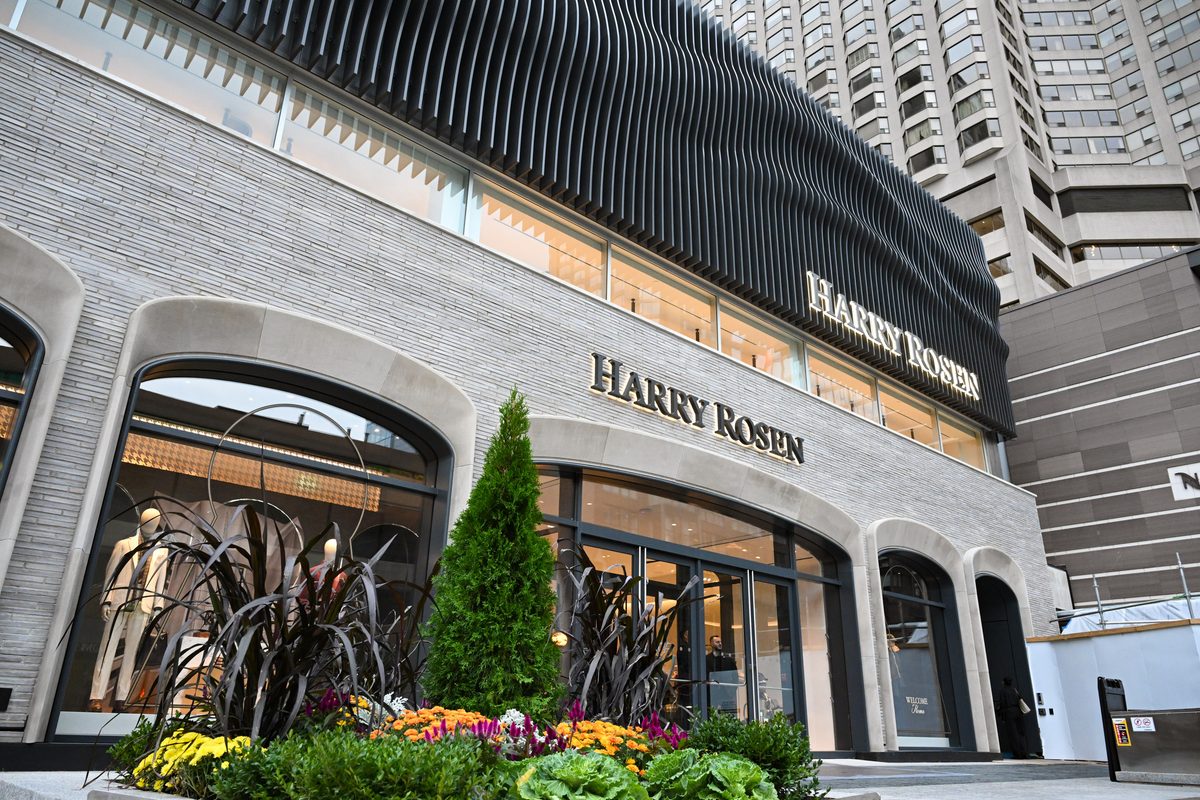
Harry Rosen at 153 Cumberland St. in Toronto. Image: George Pimentel Photography

Harry Rosen Leads a New Round of Menswear Investment

Harry Rosen provides one of the clearest examples of capital being directed toward the category. The Toronto-based retailer is in the midst of an approximately $50-million, five-year program to transform its physical network through renovations and, in some cases, relocations.

Its largest recent project is the new approximately 38,000-square-foot, three-level store on Cumberland Street in Toronto’s Yorkville neighbourhood, replacing its longtime flagship at 82 Bloor Street West. The store incorporates hospitality, private selling areas, tailoring and custom services while displaying fewer products on the selling floor.

The Yorkville opening follows investments at West Edmonton Mall, First Canadian Place in Toronto and Oakridge Park in Vancouver, with additional projects expected as Harry Rosen works through its portfolio. The approximately 17,000-square-foot Oakridge store also reflects a changing merchandise mix, with greater emphasis on luxury sportswear and contemporary fashion alongside tailoring.

The upper end of the market is no longer centred primarily on suits and traditional business clothing. Luxury casualwear, footwear, outerwear and contemporary brands have given retailers more ways to build a high-value men’s business, while custom and made-to-measure clothing remain important service categories.

Henry Singer has made significant physical investments of its own. The Alberta retailer moved from an upper level of Bankers Hall in Calgary to a more visible street-facing location and later replaced its longstanding Manulife Place store in downtown Edmonton with an approximately 10,000-square-foot location at Stantec Tower in the ICE District.

The Edmonton store incorporates Bar Henry along with barbering and shoe-care services. Henry Singer subsequently reported that the location was bringing in new customers while maintaining its established clientele, providing an example of a Canadian menswear operator seeing benefits after investing in a more destination-oriented store.

TNT The New Trend offers another variation on the multi-brand model. Its approximately 20,000-square-foot Yorkville Village store combines men’s and women’s fashion and carries an extensive assortment ranging from contemporary labels to higher-priced designer product.
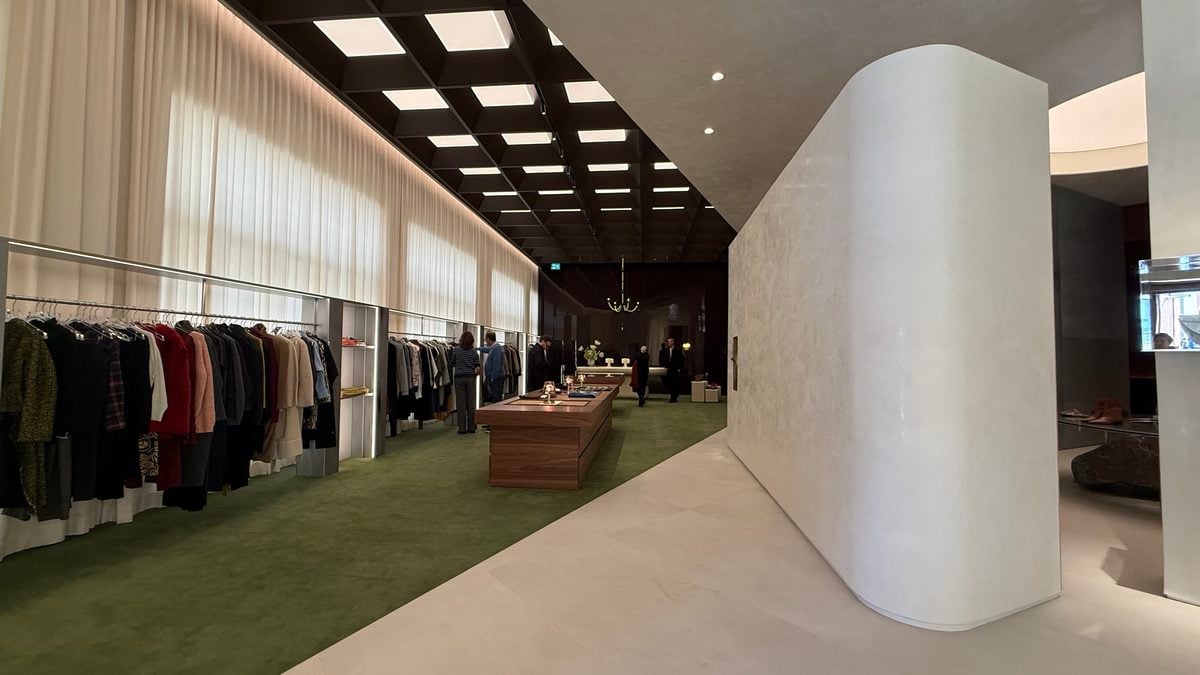
Men’s department inside Absolutely Fabrics at 1091 Yonge Street in Toronto. Photo: Craig Patterson

Absolutely Fabrics recently added menswear from a different direction. The Toronto independent opened a 7,000-square-foot flagship at 1091 Yonge Street in Summerhill in September, introducing men’s fashion for the first time alongside its established womenswear business.

Founder Kaelen Haworth had considered the retailer’s smaller Queen Street West location too constrained to introduce menswear in a meaningful way. The larger Summerhill store includes a dedicated men’s assortment with brands such as Aubero, Studio Nicholson, Willy Chavarria, Rier, Martine Rose, ssstein and Soshiotsuki, including labels with limited Canadian distribution.

Newer Canadian concepts are also entering the market. Caulfeild Apparel Group launched HANK with stores at Bayview Village in Toronto and Upper Canada Mall in Newmarket, identifying an opportunity in premium menswear following years of retail closures. The concept has since expanded to CF Masonville Place in London, Ontario, as the company considers a much larger national rollout.

Winnipeg-based Modern Ambition has moved into Toronto’s Yorkville neighbourhood and has outlined plans for at least 12 to 14 Canadian stores, including further expansion into Western Canada.

Together, these investments extend well beyond traditional luxury tailoring. Capital is being deployed across different parts of the men’s fashion business, from accessible premium concepts to retailers selling some of the world’s most expensive clothing.
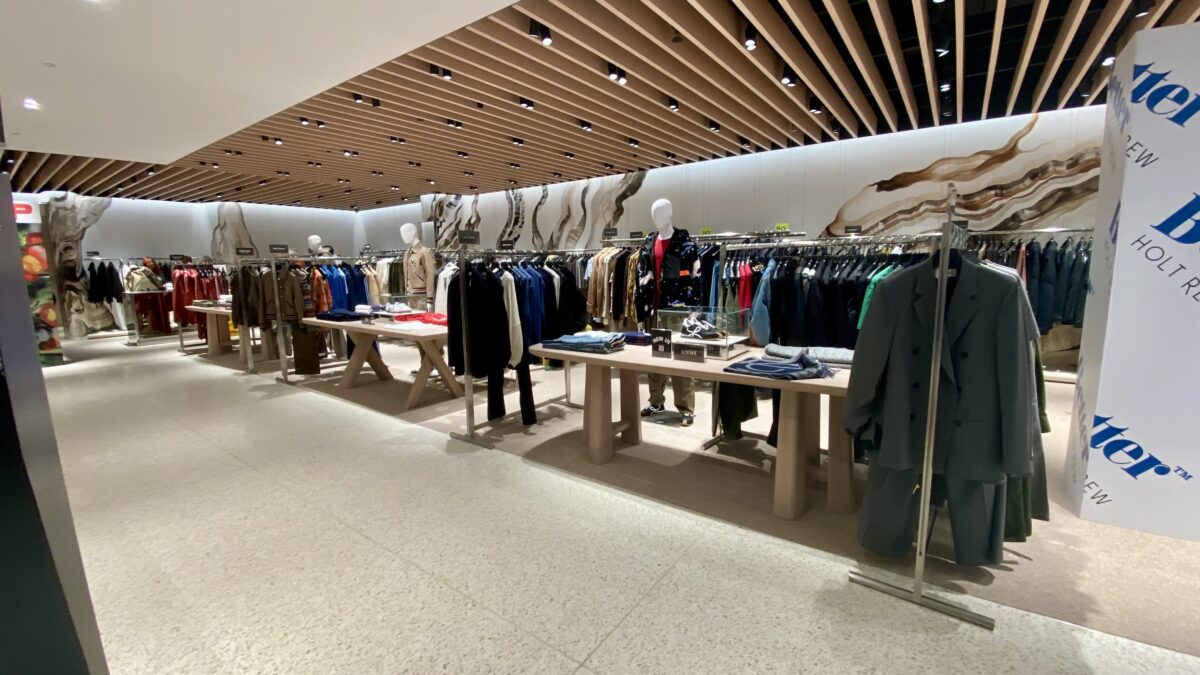
Men’s designer area ON3 in Holt Renfrew at 50 Bloor St W in Toronto. Photo: Craig Patterson

Department Store Contraction Is Changing Distribution

Nordstrom’s 2023 Canadian exit removed six full-line department stores and seven Nordstrom Rack locations. The subsequent collapse of Hudson’s Bay and disappearance of Saks Fifth Avenue eliminated another major source of multi-brand men’s fashion distribution.

Those closures do not establish that spending automatically migrated to surviving specialists. They did, however, remove significant retail capacity at the same time other operators were expanding, leaving brands and customers with a different mix of channels through which to buy and sell men’s fashion.

Holt Renfrew remains a major Canadian luxury retailer, but its approach to menswear has also changed. The company closed its approximately 16,500-square-foot standalone men’s store at 100 Bloor Street West in late 2024 and brought the category back into its 50 Bloor Street West flagship through the ON3 concept.

Further investment is expected as the retailer evaluates the flagship, with menswear potentially being expanded or reworked on the third floor or relocated elsewhere within the store. A final configuration has not been publicly announced.

Holt’s evolving approach illustrates a wider issue facing multi-brand retailers. Competition for affluent male customers increasingly comes from outside the traditional department-store channel.
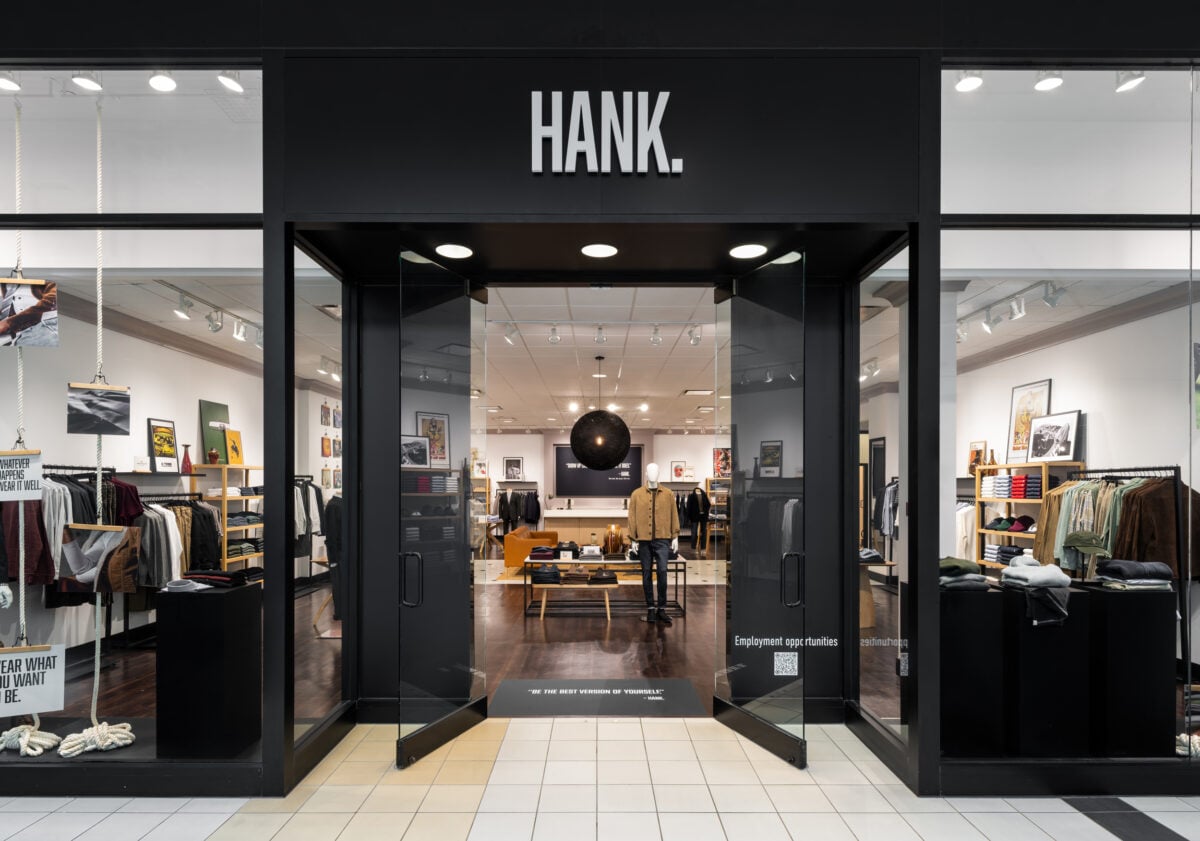
HANK. at Upper Canada Mall in Newmarket. Photo: HANK.

Luxury Brands Build Their Own Canadian Stores

Yorkdale Shopping Centre demonstrates how much that competitive environment has changed. Gucci is expected to open an approximately 12,000-square-foot store at Yorkdale in November 2026, while Saint Laurent and Loewe have also added substantial stores.

They join a luxury mix that includes Brunello Cucinelli, Loro Piana, Tom Ford, Moncler and other international houses with men’s offerings. Oakridge Park in Vancouver has developed another large concentration of luxury brands alongside Harry Rosen’s new store, while Royalmount in Montreal, Bloor-Yorkville in Toronto and Vancouver’s Alberni Street corridor add further clusters of brand-operated luxury retail.

For decades, one of the principal functions of a department store was aggregation. Retailers bought merchandise from numerous fashion houses and put those brands in one building, giving customers access to a broad assortment under one roof.

Canada’s leading luxury shopping centres and districts increasingly perform part of that aggregation function themselves. A shopper at Yorkdale or Oakridge can move among numerous individual luxury boutiques within one property, with each brand controlling its own store, staff, inventory and presentation while the landlord assembles the broader retail mix.

That changes the economics for everyone involved. Luxury brands gain direct control over their Canadian customers and physical presentation, while landlords establish direct leasing relationships with brands that might once have relied more heavily on wholesale distribution. Department stores and specialists, meanwhile, face additional competition from some of the same fashion houses represented on their selling floors.

The shift helps explain why multi-brand menswear retailers are investing in elements that a mono-brand boutique cannot easily replicate.
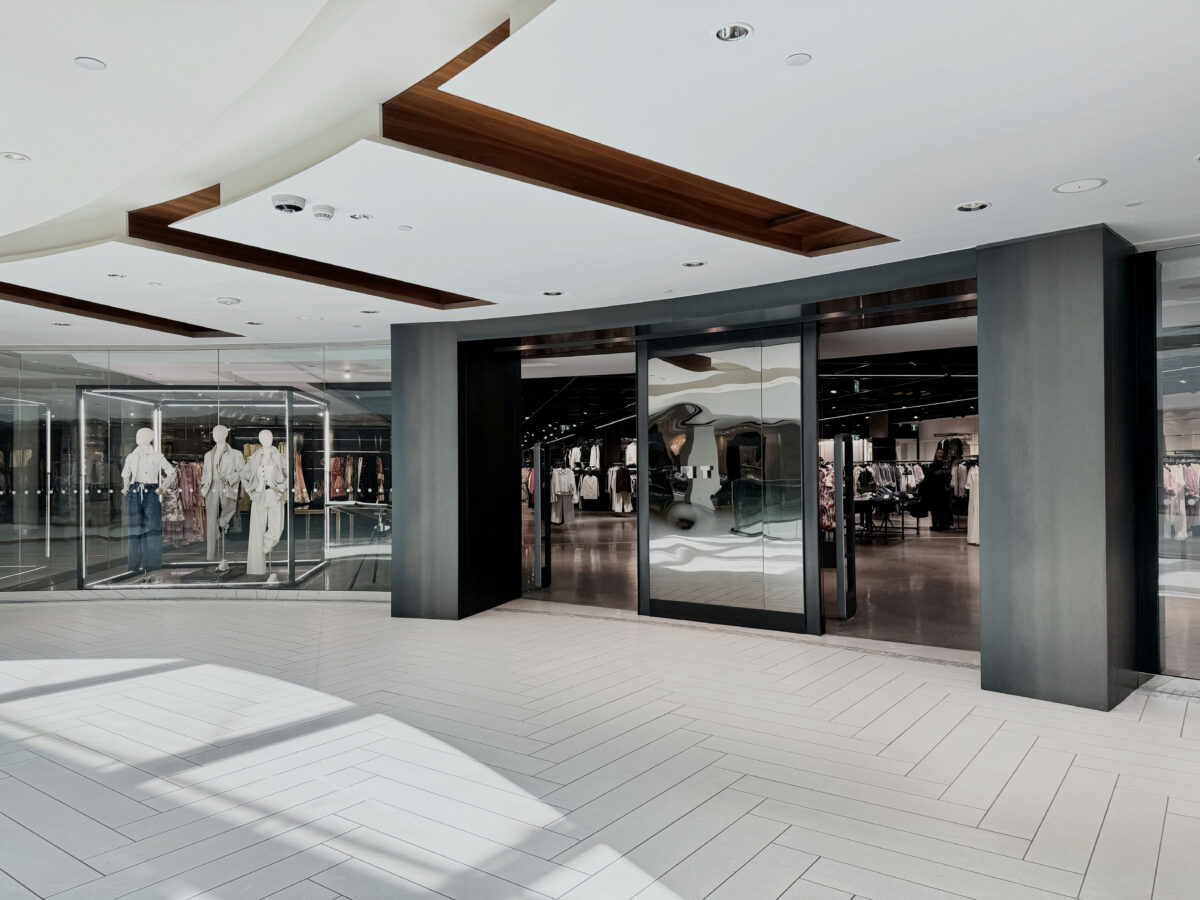
TNT The New Trend flagship store at Yorkville Village in Toronto. Photo: TNT

Curation and Service Become More Important

Harry Rosen, Henry Singer, TNT, Absolutely Fabrics, Neighbour and Lost & Found can assemble clothing from multiple designers into a wardrobe, introduce customers to less familiar labels and provide advice across brands. Tailoring, custom clothing, personal shopping, private appointments, special orders and longstanding relationships with sales advisors deepen that proposition.

Absolutely Fabrics also demonstrates how curation can extend the market. Its men’s assortment includes designers with limited Canadian distribution, giving fashion-focused customers access to labels they might otherwise have difficulty experiencing physically in Canada.

Harry Rosen has said its custom clothing business has been particularly strong. Its newer stores devote significant space to fitting, private selling and hospitality alongside conventional merchandising.

As luxury brands expand directly, access to a desirable label becomes less of a competitive advantage when that brand operates a large store nearby. Selection, expertise and service therefore become increasingly important to the multi-brand model.

Simons provides another indication that the expansion in Canadian menswear reaches beyond luxury. The Quebec-based retailer has been growing its national footprint with two Toronto stores, further expansion in Calgary and a Vancouver entry on the way, bringing substantial men’s departments into each market.

Its model covers a broader range of price points than Harry Rosen or a luxury mono-brand boutique, combining private labels, contemporary fashion and outside brands. The expansion adds another source of sophisticated men’s fashion in markets where the category was once more dependent on traditional department stores and established specialists.

New Concepts Continue to Test the Market

Original Luxury is preparing another substantial physical investment in Toronto. The retailer carries high-end men’s brands including Kiton, Stefano Ricci, Zilli, Luigi Borrelli, Jacob Cohen and Moorer and will open a large storefront at the base of the Aqualuna condominium development on Toronto’s waterfront in spring 2027.

The location is notable because it sits outside Toronto’s established Yorkville and Yorkdale luxury clusters. Original Luxury has developed through online sales and a showroom model, making the Aqualuna store a significant move into conventional physical retail and a test of whether a luxury menswear destination can draw customers to the city’s growing eastern waterfront.

The investment taking place across the sector does not mean every high-end concept succeeds. The Webster closed its Toronto location in Yorkville in late 2025 after about four years in the market, ending the U.S. luxury retailer’s physical presence in Canada. The store had carried men’s and women’s designer fashion.

Its departure, along with Holt Renfrew’s decision to close its standalone men’s store, shows that retailers continue to experiment with the economics, size and location of upscale menswear stores. Capital is flowing into the category, but there is no single format that has emerged as the answer.
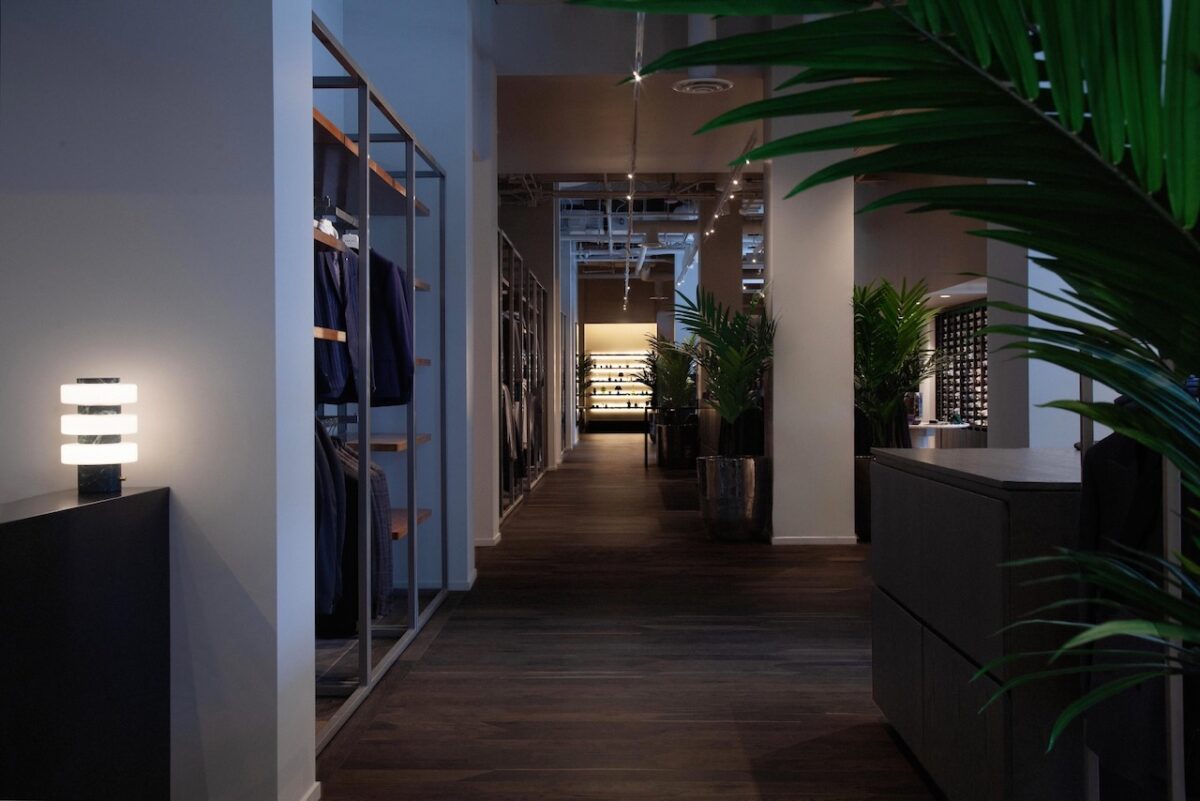
Henry Singer Stantec Tower Edmonton (Image: Henry Singer)

Canadian Menswear Distribution Broadens

The larger change is the number of ways a Canadian customer can now access premium and luxury men’s fashion.

Established specialists including Harry Rosen and Henry Singer operate alongside fashion independents such as TNT, Absolutely Fabrics, Neighbour and Lost & Found. HANK and Modern Ambition are building newer concepts, Holt Renfrew and Simons provide substantial multi-brand assortments, Original Luxury is expanding its physical presence, and international fashion houses increasingly operate their own Canadian stores.

The structure differs considerably from a market where access to upscale international menswear was more heavily concentrated among a relatively small group of department stores and established men’s retailers.

Household wealth provides part of the economic backdrop. Canada’s highest-wealth households control a large majority of household net worth, supporting discretionary spending at the upper end even as many Canadian consumers remain under financial pressure. Commercial real estate firms have similarly identified polarization in retail expansion, with value and luxury attracting investment while parts of the middle market face greater challenges.

That polarization is also visible in where menswear investment is occurring. Capital is concentrating in highly productive destinations including Yorkdale, Oakridge Park, Bloor-Yorkville and Royalmount, while specialists are spending money on stores intended to give customers reasons to visit beyond access to merchandise.

For landlords, retailers and luxury brands, the competition is increasingly about who controls the customer relationship. Brands can sell directly, specialists can compete through curation and service, and shopping centres can assemble collections of luxury houses that once might have depended more heavily on department stores for Canadian distribution.

Canada has lost several of its largest multi-brand sellers of men’s fashion, but the category is increasingly distributed across other channels. With Harry Rosen continuing its national store program, Holt Renfrew reconsidering its flagship configuration, Simons expanding and additional brand-operated boutiques and specialist stores on the way, the reshaping of Canada’s menswear market is continuing.
More From Retail Insider

Ralph Lauren Home Joins Maison Territo in Montréal

Maison Territo has added Ralph Lauren Home to its curated catalogue, bringing one of the best-known names in American lifestyle design into its Montréal offering.

The collection extends Ralph Lauren’s design language beyond fashion and into furniture and interiors, encompassing sofas, dining and bedroom furniture, lighting, rugs and decorative pieces. Maison Territo clients can now explore the brand as part of a catalogue that includes some of the world’s most recognized names in furniture and interior design.

The addition also expands Maison Territo’s representation of fashion houses with established home collections. Ralph Lauren Home joins a portfolio that includes Fendi Casa, Versace Home, Bentley Home, and Dolce & Gabbana Casa, each bringing a distinct design identity to the showroom’s broader offering.

More Than Four Decades of Ralph Lauren Home

Ralph Lauren entered the home category in 1983, becoming the first fashion designer to introduce a complete collection for the home. The move translated the designer’s lifestyle-driven approach into interiors and established a home business that has now operated for more than four decades.

From the beginning, Ralph Lauren Home was organized around different environments and ways of living. Its original collections included Thoroughbred, New England, Jamaica and Log Cabin, drawing inspiration from settings ranging from country estates and coastal homes to more relaxed retreats.

That approach remains part of the brand today. Ralph Lauren Home moves between traditional and contemporary interiors, incorporating equestrian influences, Art Deco references, modern forms and ideas drawn from travel and architecture.

Ralph Lauren Home at Maison Territo

Ralph Lauren Home adds another established international design house to Maison Territo’s growing catalogue, expanding the options available to homeowners, architects and interior designers working on residential and commercial projects.

The brand is particularly suited to Maison Territo’s approach because its collections extend beyond individual furniture pieces. Seating, tables, lighting, rugs and accessories can be considered together when developing a complete interior, while individual pieces can also be incorporated into projects built around other brands.

Maison Territo’s team can work with clients to explore available Ralph Lauren Home pieces, materials and collections and determine how they can be incorporated into a particular space.

Discover Ralph Lauren Home in Montréal

Maison Territo’s 11,000-square-foot showroom at Royalmount brings together furniture, lighting, surfaces and accessories from international design houses in an environment created for both private clients and design professionals.

The addition of Ralph Lauren Home gives Montréal clients access to a home collection with more than four decades of history and a design identity that has grown alongside the Ralph Lauren brand.

Maison Territo is located at 5050 Côte-de-Liesse, Suite 1050, Mont-Royal, QC H4P 0C9. For more information, call 514-800-0102.

Casavogue Launches Buy More, Save More Promotion in Montréal

Casavogue has launched a new promotion giving Montréal shoppers an incentive to tackle some of the furniture purchases they may have been planning for their homes.

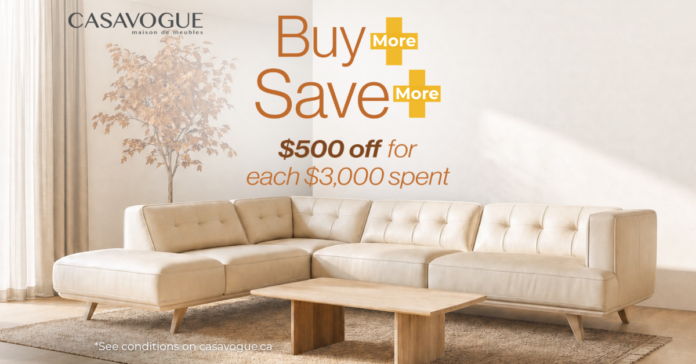
Casavogue’s “Buy More, Save More” promotion offers $500 in savings for every $3,000 spent on a wide selection of furniture. The savings increase along with the purchase, making the offer particularly relevant for customers furnishing a complete room or shopping for several areas of the home.

Someone considering a new sofa, for example, may also be looking for an armchair, coffee table or other pieces to complete the room. Customers updating a dining room, bedroom or several spaces can similarly combine purchases while taking advantage of additional savings as they reach each qualifying threshold.

Lignora sectional

Start with the Living Room

The living room is often one of the biggest furniture investments in a home, and Casavogue carries sofas, sectionals, loveseats, armchairs and occasional furniture in a wide variety of sizes and styles.

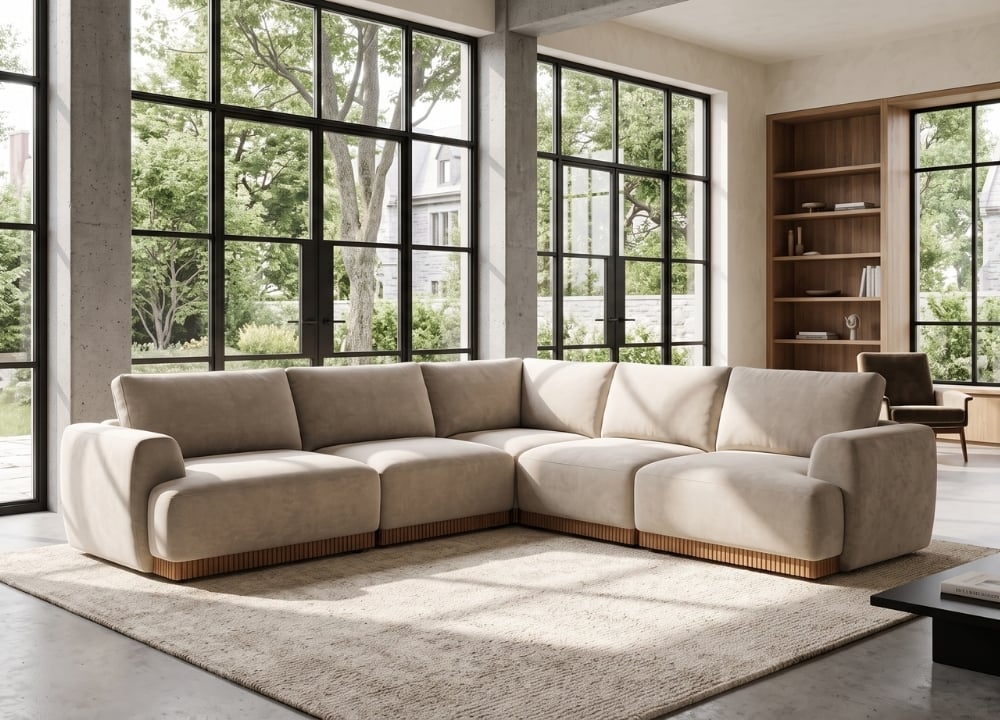
Among the pieces currently highlighted by Casavogue is the Prima sectional, a contemporary design available in several colours and configurations. The Lignora sectional, also from Charles David, offers a different look, with deep seating, a modular corner configuration and a fluted wood base adding warmth and texture.

They represent just part of the living room selection available at Casavogue. Customers can begin with a sofa or sectional and build the rest of the room around it, considering complementary seating, coffee and side tables, storage and other furnishings.

During Buy More, Save More, purchasing several of those pieces together can also increase the overall savings.

Volare Day dining set

Dining and Bedroom Furniture Offer More Possibilities

The promotion extends beyond living room furniture, giving customers an opportunity to address other areas of the home during the same visit.

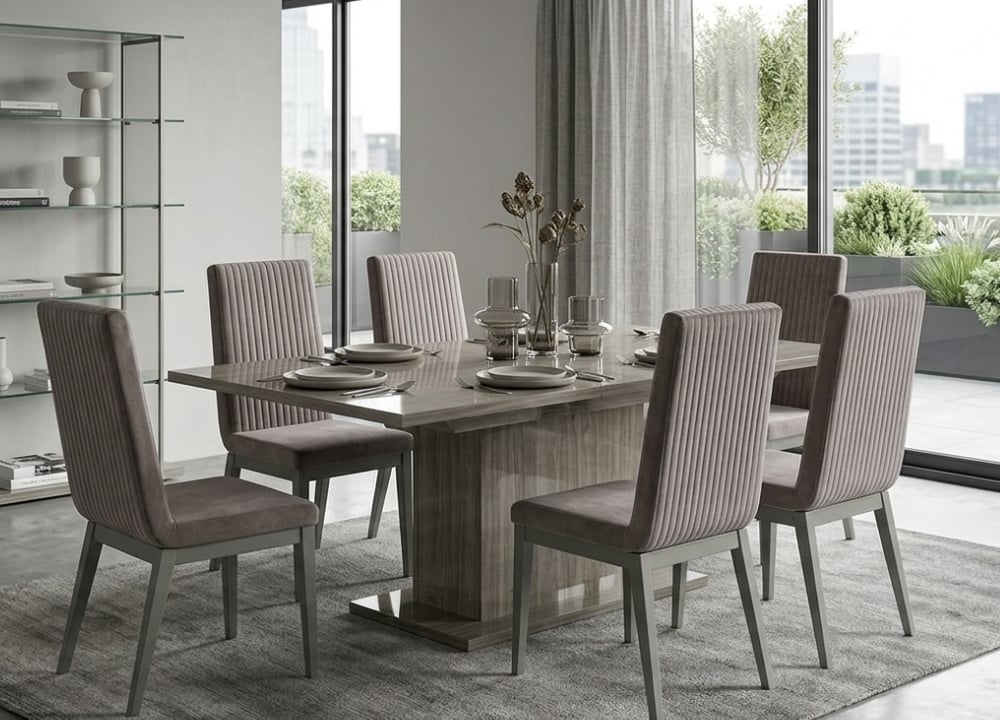
For the dining room, Casavogue is highlighting the Volare Day dining set, combining an extendable wood table with six chairs featuring vertical fluted detailing. Its extendable format provides flexibility for everyday dining and additional space when guests arrive.

In the bedroom, the Tessutini Bedroom Set offers an Italian-made option characterized by a grey birch finish, clean lines and chrome detailing. Casavogue also carries a broader assortment of beds, nightstands, dressers, mattresses and complete bedroom sets.

Home office furniture, accent pieces and decorative accessories provide further options for customers looking to finish a room or coordinate several spaces.

Tessutini Bedroom Set

See the Furniture in Person

Casavogue’s 38,000-square-foot Montréal showroom gives customers the opportunity to compare furniture, materials, finishes and proportions in person before making a purchase.

Living, dining and bedroom furniture is displayed in room settings, providing a clearer sense of how pieces look together and how their scale may translate into a home. Many collections can also be personalized through choices of upholstery, finishes and configurations.

Casavogue’s design consultants are available to help with dimensions, materials, furniture placement and coordination between pieces. For customers considering several purchases during the promotion, that guidance can help ensure the selections work together as a complete interior.

Savings That Add Up

The structure of Buy More, Save More is simple: customers receive $500 in savings for every $3,000 spent on qualifying purchases.

That can make a meaningful difference when replacing a major piece of furniture or furnishing several areas at once. It also gives customers an opportunity to look at their overall furnishing plans and decide which purchases make sense to complete during the promotional period.

The Buy More, Save More promotion continues, giving customers time to visit Casavogue, explore the selection and discuss available options with the showroom’s design consultants.

Casavogue is open Monday through Friday from 9:30 a.m. to 6:00 p.m., and Saturday and Sunday from 9:30 a.m. to 5:00 p.m.

Casavogue is located at 8260 boulevard Saint-Michel, Montréal, QC H1Z 3E2. For more information, call +1 514-360-3565 or book an appointment to receive personalized advice.

Egg Club and Serruya Private Equity Announce Joint Venture to Fuel Global Growth  

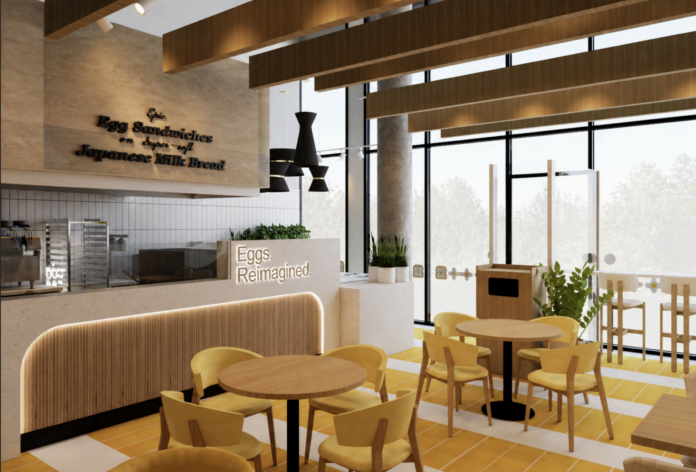
Egg Club photo
Egg Club photo

Egg Club is partnering with Serruya Private Equity as the Toronto-based breakfast brand looks to grow across Canada, the United States and international markets. 

The partnership brings together Serruya Private Equity’s experience in franchise development and restaurant growth with Egg Club’s expertise in brand, operations and guest experience. The joint venture will introduce the brand to new domestic and international markets while maintaining the food, experience and identity that have driven the brand’s growth, said the companies in a news release. 

“This is an exciting next step for Egg Club and for a brand that started right here in Toronto,” said Jason Yu, president of Egg Club. “We’ve seen Egg Club grow from our first location into a brand that connects with customers across different communities and markets. Serruya brings tremendous experience in growing restaurant brands, and this partnership gives us an opportunity to introduce Egg Club to even more people.” 

“Egg Club has built a strong brand with a great product and a loyal customer base,” said Aaron Serruya, Managing Director of Serruya Private Equity. “We believe there is a real opportunity to build on that success and bring Egg Club to more communities in Canada and beyond. We’re excited to work with the team and support the brand as it continues to grow.” 

Founded in Toronto in 2020, Egg Club said it has steadily expanded its presence with a fast-casual breakfast concept centred around fresh, made-to-order egg sandwiches and a focus on quality and affordability. The brand currently operates 10 locations across Ontario and Alberta, including restaurants in Toronto, Mississauga, Waterloo, Ottawa, Calgary and Edmonton. 

Egg Club’s existing ownership team will remain actively involved in the business, helping guide the brand and maintain the quality and consistency of the Egg Club experience as it expands into new markets, said the news release. 

With the partnership now in place, the companies will begin identifying opportunities for expansion across Canada and the United States, along with international markets around the world. Specific markets and new restaurant locations will be announced as plans are finalized, it noted. 

Egg Club was founded in Toronto in 2020.       

Serruya Private Equity is the Serruya family’s private investment platform, based in Markham, Ontario. Since 1986, the Serruya Family has built, invested and operated food, retail and franchise businesses across North America and internationally. Current and past portfolio brands include Yogen Früz, Sprinkles Cupcake, Pinkberry, Swensen’s Ice Cream, Bonchon, Cha Cha Matcha, Cold Stone Creamery, Marble Slab Creamery and Pretzelmaker, among others. 

More from Retail Insider:

Kits Eyecare report preliminary Q3 results, substantial growth in total revenue

KITS Eyecare photo
KITS Eyecare photo

Kits Eyecare Ltd., a leading vertically integrated eyecare provider, has provided selected preliminary unaudited results for its third quarter ended September 30, 2026, showing accelerated growth in the quarter.

Select Preliminary Third Quarter 2026 Financial Highlights:

  • Total Revenue grew 21.6% year-over-year to approximately $63.7 million, accelerating from 17.8% growth in Q2 2026.
  • Glasses Revenue grew 59.3% year-over-year to approximately $11.3 million, accelerating from 54.0% growth in Q2 2026.
  • Preliminary Adjusted EBITDA exceeded 4.5% of revenue, or $2.9 million, as the Company continued to invest in glasses growth, its Toronto retail store and marketing.
  • Net Revenue Retention of approximately 92% at 24 months for the Q3 2024 customer cohort, and 189% at 48 months for the Q3 2022 cohort.
  • Cash increased $3.2 million in the quarter to approximately $30.6 million, with no debt.

“Our growth accelerated this quarter, and it came from the parts of the business that matter most for the long term,” said Roger Hardy, Co-Founder and CEO. “Glasses revenue grew nearly 60% and is becoming a second growth and gross margin engine alongside contacts, and our customer cohorts continue to compound. We are growing profitably with a strong balance sheet and no debt, which gives us flexibility to keep investing in our momentum.”

The company said it will report its full third quarter 2026 results in early November.

More from Retail Insider:

Canadian Shoppers Grow More Selective as Holiday Spending Intentions Weaken

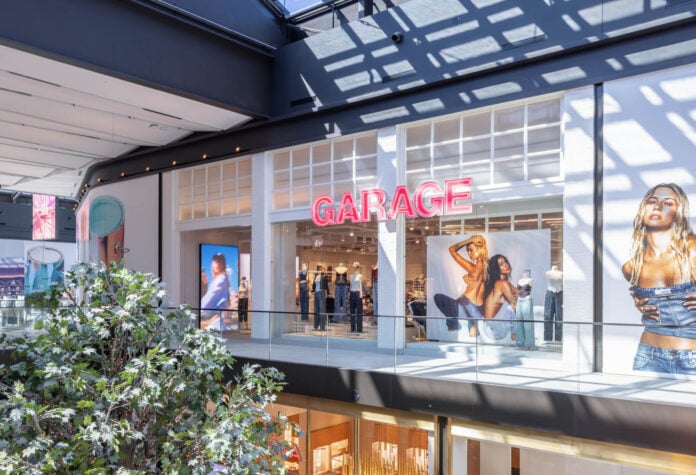
Garage at Royalmount in Montreal. Image: Garage/Groupe Dynamite

Canadian consumers are heading toward the holiday season with less conviction about opening their wallets, according to a new Stifel survey that points to increasingly selective discretionary spending.

Just 42% of respondents expect to increase their holiday shopping budgets this year, down nine percentage points from a year ago and tied with 2023 for the lowest level since Stifel began asking the question. The decline was particularly pronounced among households earning more than $75,000 and among female respondents.

The September 29 report, based on a survey of 300 Canadian adults conducted the previous week, presents a more complicated picture than an across-the-board consumer pullback. A majority still expect to increase discretionary spending over the coming year, but considerably fewer express strong confidence that they will do so.

For retailers, that combination points to a tougher fight for discretionary dollars. Consumers may continue spending, but the survey suggests they are becoming more deliberate about where incremental spending goes, with substantial differences emerging between categories and income groups.

Discretionary Spending Holds Up as Confidence Weakens

Overall discretionary spending intentions actually improved in Stifel’s latest survey. Fifty-eight per cent of respondents said their spending on items they want but do not need will increase over the next 12 months, one percentage point higher than in July and above the 52% average of the past three years.

The stronger headline number masks weaker conviction. Only 9% of respondents said they were “very likely” to increase discretionary spending, the lowest level in more than three years. Higher-income consumers recorded their weakest reading in six quarters, while respondents earning less than $75,000 produced their strongest reading in more than three years.

The shift is particularly notable because Stifel’s July survey had pointed to an unexpected rebound in Canadian spending intentions. At that time, discretionary spending expectations were strengthening across several categories, including dollar stores. The September results suggest that consumers have not abandoned plans to spend more, but confidence behind those plans has weakened.

The findings fit with other indicators of Canadian consumer caution. The Bank of Canada’s second-quarter Canadian Survey of Consumer Expectations found that high prices and economic uncertainty continued to restrain spending plans, with consumers reporting substitution toward cheaper essentials and reductions in some discretionary activities.

Statistics Canada’s latest retail trade figures have also been uneven. Retail sales declined 0.7% to $73.7 billion in July, while sales volumes fell 1.1%. A preliminary Statistics Canada estimate pointed to a 1.3% rebound in August, making the broader picture less consistent with a straightforward spending contraction.

For retailers, the more consequential issue may be the gap between consumers expecting to spend more and those firmly committed to doing so. Purchases made with less conviction are more susceptible to price, promotions, economic uncertainty and competing demands on household budgets.

Higher-Income Shoppers Show Greater Caution

One of the more notable findings in Stifel’s survey is the deterioration among higher-income consumers. Respondents earning more than $75,000 showed weaker intentions across several categories, including discretionary goods, holiday shopping, apparel, toys, pet products and quick-service restaurants.

Stifel noted that softness among higher-income consumers could have a disproportionate impact because of their greater spending power. The survey does not indicate these households are financially distressed, but it does suggest they have become less willing to expand discretionary spending.

That broadens an affordability discussion that has frequently centred on lower-income households. For retailers selling discretionary products, spending capacity alone does not generate a sale. A household can afford another jacket, restaurant meal, sofa or vacation and still decide the purchase can wait.

Dollar Stores Continue to Capture Spending

Value retail remains comparatively resilient. Sixty-eight per cent of Stifel respondents expect to increase spending at dollar stores over the coming year, down seven percentage points from July and below the three-year average, but still substantially higher than the readings for many discretionary categories.

Stifel also found improved spending conviction among higher-income respondents and said the result may be indicative of continued trading down. The finding is notable because trade-down behaviour need not be confined to households under the greatest financial pressure. Consumers with more spending capacity can become more price-conscious as well.

Dollarama’s recent performance provides useful context. The retailer reported Canadian comparable-store sales growth of 5.4% in its latest quarter, including transaction growth of 3.7%. President and CEO Neil Rossy said households were making “careful spending decisions” while continuing to rely on Dollarama for value.

Those results do not establish that Stifel’s surveyed consumers are moving their spending specifically to Dollarama. They do show that a major value retailer continues to generate traffic growth while consumers report greater caution in several other areas.

Apparel Softens While Strong Brands Keep Growing

Clothing provides perhaps the clearest illustration of why weaker category-level intentions do not necessarily translate into weak results for every retailer.

Forty-seven per cent of respondents expect to increase clothing and apparel spending over the next 12 months, down three percentage points from July. Stifel also found a substantial deterioration in conviction, particularly among higher-income and female respondents, and characterized the findings as negative for Aritzia, Groupe Dynamite and Gildan Activewear.

Yet Aritzia reported Canadian revenue growth of 25% in its latest reported quarter, while Groupe Dynamite reported comparable sales growth of 10.3% and total revenue growth of 29.8%.

The timeframes are different. Those company results measure recent sales performance, while Stifel is asking consumers about intentions over the next 12 months, so they should not be treated as contradictory measures of the same period. Together, however, they illustrate an important competitive reality: weaker category intentions do not prevent individual retailers from gaining share.

If apparel spending becomes harder to capture, brand strength becomes more consequential. Consumers do not distribute their clothing budgets evenly, allowing retailers with strong demand to grow while competitors contend with a less accommodating category backdrop.

Holiday Budgets Weaken While Toy Spending Holds Up

The holiday results show a similar divergence. Despite the nine-percentage-point decline in overall holiday spending intentions, 55% of respondents expect to increase spending on toys for children over the next 12 months, broadly in line with Stifel’s historical average.

Respondents aged 55 and older were particularly notable. Forty-seven per cent expect to increase toy spending, eight percentage points above that cohort’s average across Stifel’s previous surveys.

The survey does not establish how households will redistribute more constrained holiday budgets, but the resilience of toy spending suggests some purchases may receive priority while others face greater scrutiny. For retailers, the composition of holiday spending could prove as important as the size of the overall budget.

Restaurants, Furniture and Travel Face More Pressure

Other discretionary categories show considerably greater weakness. Only 40% of respondents expect to increase spending at quick-service restaurants, down nine percentage points from Stifel’s previous survey, with intentions among consumers aged 18 to 34 falling 17 percentage points. Younger consumers nevertheless remain the only cohort in what Stifel describes as expansionary territory.

Furniture spending remains similarly subdued. Forty-seven per cent of respondents expect to increase spending on furniture or appliances, unchanged from July and the lowest level recorded in Stifel’s past nine surveys.

Travel intentions have also deteriorated. The proportion of respondents planning to fly for their next vacation fell to 47% from 54% in July and 58% a year earlier. Stifel suggested the results may reflect a divided market in which some consumers are being priced out while premium, business and long-haul demand remains comparatively strong.

Restaurants, furniture and leisure travel share an important characteristic: consumers have considerable discretion over when and whether to make those purchases. Meals can be shifted home, furniture replacement deferred and vacations postponed or changed, leaving these categories particularly exposed when households become less confident about discretionary spending.

Retailers Compete for a More Tightly Allocated Dollar

Stifel’s survey describes a consumer market with competing signals. Overall intentions to increase discretionary spending remain relatively high even as conviction weakens. Dollar-store spending remains elevated, while apparel, restaurants, furniture and travel show greater caution, and holiday budgets are under pressure even as toy spending holds up.

That environment can widen the gap between businesses with strong customer propositions and those relying on a broadly rising consumer market. Price and value can win spending, as can brand desirability, product relevance and convenience, but weaker conviction leaves less room for retailers that give consumers little reason to prioritize a purchase.

Heading into holiday 2026, the question may increasingly be where Canadians concentrate their spending, not simply how much they spend in total. If consumers continue allocating discretionary dollars more selectively, market-share gains by stronger retailers can coexist with considerable pressure across the categories in which they operate.

More From Retail Insider

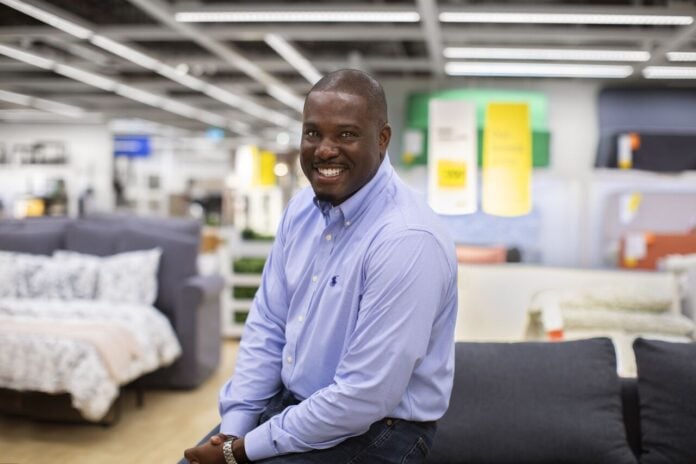
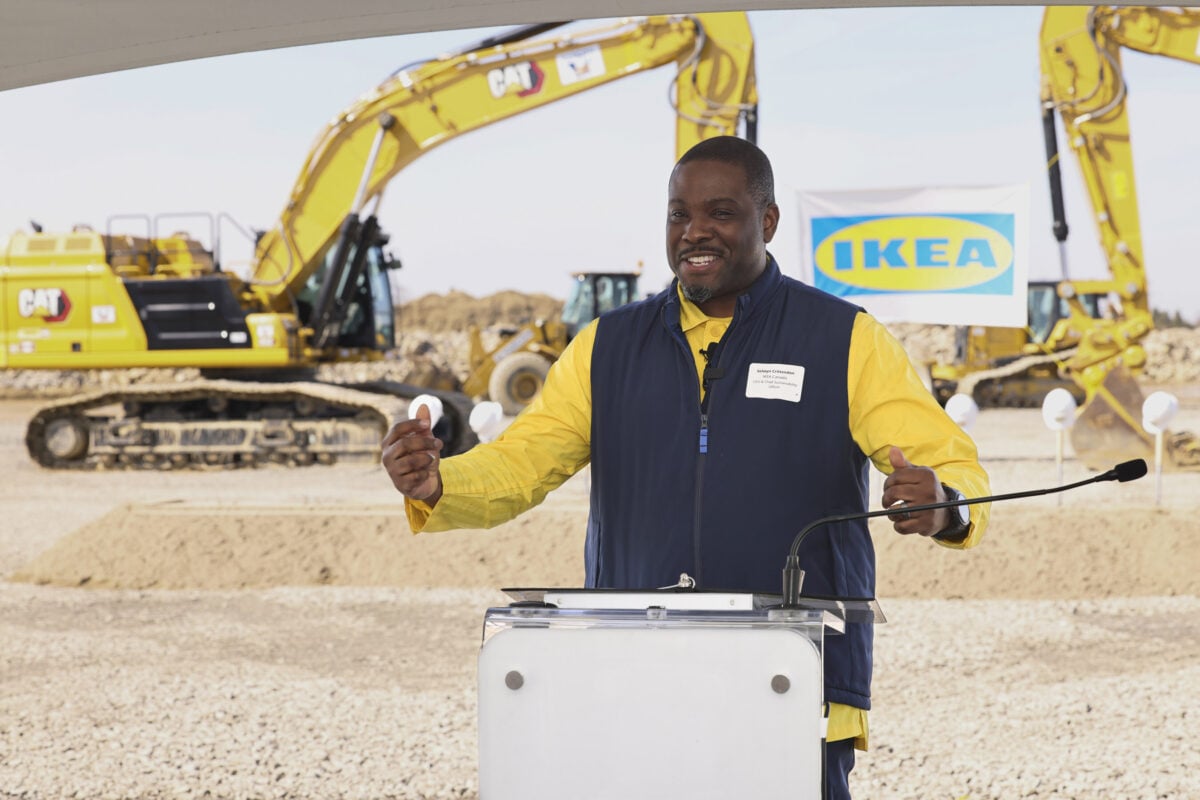
Selwyn Crittendon moving on to different role at IKEA

Selwyn Crittendon. LinkedIn photo

In a LinkedIn post, Selwyn Crittendon, CEO & Chief Sustainability Officer, IKEA Canada, said he will be leaving his role at the end of this year to begin a new chapter as Deputy CEO at IKEA U.S.

He has been in his current role for the past three years.

“Joining IKEA Canada in 2023 was truly a dream come true. When I started my IKEA journey more than 20 years ago as a Customer Convenience Manager in our Woodbridge, Virginia store, I could never have imagined where this path would lead. Having the opportunity to serve and grow alongside the people of IKEA Canada has been one of the most rewarding experiences of my career. I have been continually inspired by the warmth, openness, and “can do” spirit of our co-workers across the country. The commitment to diversity, equity, and inclusion at IKEA Canada is deeply embedded in our culture, reflected in our people, and evident in the positive impact we have on the communities we serve,” he said.

“One of my greatest priorities during my time here has been accelerating our growth journey together. We rallied around an ambitious vision: to make IKEA Canada the leading home furnishing retailer by 2030 while enriching the lives of Canadians and embracing the diversity that makes this country so unique.

“Together, we have made meaningful progress. We have delivered strong results, increased volumes, strengthened profitability, and continued enhancing the customer experience. None of this would have been possible without the passion, resilience, and dedication of our co-workers across the country.”

As IKEA Canada celebrates 50 years in this “remarkable” country, Crittendon said he is more confident than ever in the opportunities ahead.

“IKEA is deeply loved by Canadians, and I know this organization will continue making a meaningful difference in people’s everyday lives,” he added.

“I have also been proud to represent IKEA in important conversations around affordability, sustainability, and creating a fairer and more equal society. These are issues that matter deeply to Canadians, and I believe IKEA Canada has both the opportunity and responsibility to help drive lasting change.”

He said Canada has become home for his family. The friendships, experiences, and memories they have made over the past three years will stay with them forever.

“Leaving is bittersweet, but we are excited for what lies ahead and grateful for everything this chapter has given us,” said Crittendon.

“To the many co-workers, partners, and stakeholders who supported me throughout this journey, thank you for your trust, partnership, friendship, and commitment to making IKEA better every day.

“I will remain with IKEA Canada until December 31, and we expect to announce my successor in the coming months. Until then, my focus remains on supporting our continued success and ensuring a smooth transition.”

More from Retail Insider:

Scarce Retail Space Gives Canadian Landlords New Leverage

Thunder Bay Intercity Shopping Centre. Photo: Fast Time Watch & Jewellery Repair

Canada’s tight retail real estate market is giving landlords greater leverage in lease negotiations, with high occupancy and limited new supply allowing owners of well-located properties to push rents higher. Getting deals done, however, is becoming more complicated as retailers face higher occupancy and construction costs while landlords invest substantial amounts of capital into new stores and the redevelopment of former department-store space.

The issue was discussed at JLL‘s Retail Spotlight & Reception at TIFF Lightbox on October 5, ahead of ICSC@CANADA in Toronto, where Alan MacKenzie, CEO of JLL Canada, pointed to historically low retail vacancy while cautioning against viewing the market entirely through the lens of landlord leverage. MacKenzie encouraged what he described as a “partnership model” between landlords and tenants, with owners focused on getting transactions completed instead of extracting the last possible dollar from a deal, while tenants also need to demonstrate flexibility as the economics of developing and operating retail space change.

Public results from some of Canada’s largest retail landlords show why the negotiating environment has shifted. Occupancy is approaching capacity across some portfolios, while new and renewed leases are being completed at substantially higher rents.

Retail Occupancy Approaches Its Ceiling

RioCan REIT reported committed retail occupancy of 98.8% at the end of the second quarter of 2026, a record for the company. Its blended leasing spread reached 23.1%, including a 20.7% spread on renewals and 40.8% on new leasing.

The average net rent on RioCan’s new leases during the quarter was $37.73 per square foot, compared with an average of $23.58 per square foot across occupied space at quarter-end. The figures show how substantially available space can be repriced as leases expire and new tenants enter the portfolio.

The conditions extend beyond one landlord. CBRE’s Canadian retail research has found tight vacancy across several property formats and markets, with limited availability becoming an obstacle for retailers looking to expand in some high-growth areas.

For landlords with strong properties, those conditions provide an opportunity to increase rents and become more selective about which tenants receive scarce space. Retailers looking to grow, meanwhile, have fewer alternatives when the locations they want are already close to full occupancy.

Higher Rents Come With Higher Landlord Costs

The collapse of Hudson’s Bay provides an unusually large example of those economics. Primaris REIT has been working to replace HBC across its enclosed-mall portfolio, where the former department-store spaces have created substantial vacancy as well as an opportunity to introduce multiple new tenants.

By late June, Primaris said approximately 881,400 square feet, representing 84% of its former HBC space, was either leased or in advanced negotiations. For the 608,500 square feet already committed or subject to conditional agreements at the time, Primaris expected annual rent to increase from approximately $3.7 million under HBC to $14.9 million from replacement tenants, an increase of almost 300%.

Capturing that additional rent requires substantial investment. Primaris expects to spend between $175 million and $225 million redeveloping its former HBC premises, reflecting the cost involved in converting department-store boxes for multiple new occupants.

Large anchor spaces often need to be physically divided, with new storefronts, entrances, mechanical systems and other infrastructure added before replacement tenants can operate. Landlords may also contribute directly toward tenant improvements, making the strength of the tenant, length of the lease and rent being paid important parts of the investment decision.

The Primaris example illustrates both sides of the current market. Replacing historically low department-store rents can produce significantly more revenue for landlords, but achieving that increase can require major capital investment before replacement tenants open their doors.

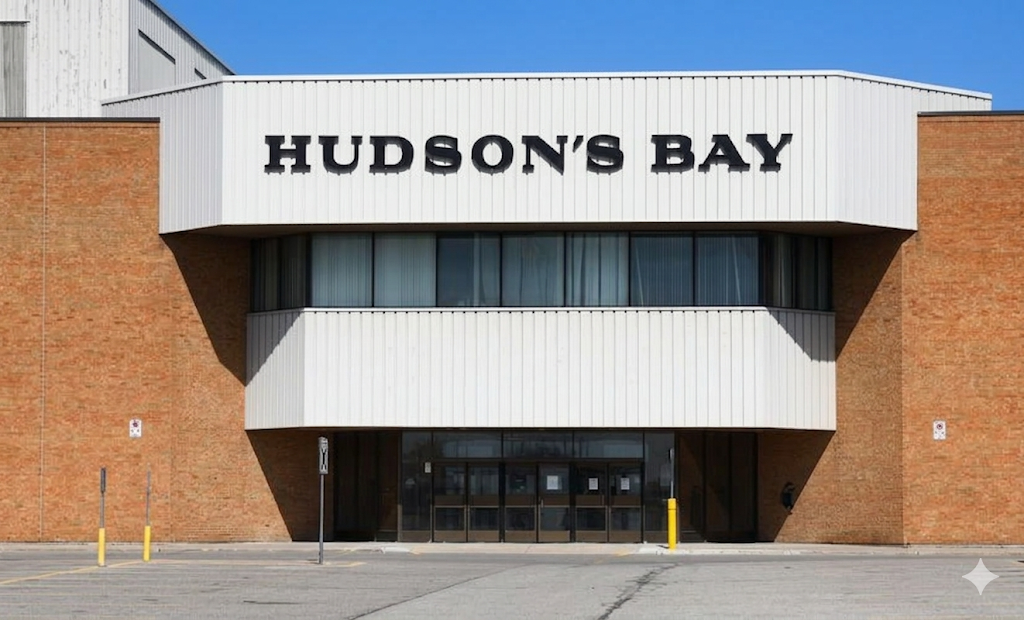
Former Hudson’s Bay at Lime Ridge Mall in Hamilton. Photo: RI/Google

Retailers Face Their Own Cost Pressures

Higher rents are arriving alongside increased construction, labour and other operating costs, meaning retailers have to evaluate the total cost of opening and operating a store rather than rent alone. A location can generate substantial sales and still fail to meet a retailer’s investment criteria if occupancy and operating costs become too high.

The pressure is particularly visible in the restaurant sector. CBRE has noted that quick-service restaurant operators continue to expand while dealing with margin pressure from higher rent, labour and food costs, with some operators increasingly looking for existing restaurant locations that can be converted at a lower cost than building new premises from scratch.

A Canadian restaurant leasing survey found that 48% of respondents expected rent and occupancy costs to increase in 2026. Strong demand for second-generation restaurant space has allowed landlords to seek higher rents and stronger security from some operators, although tenant-improvement allowances and other landlord contributions remain part of the negotiation for certain deals.

Expansion therefore does not mean a retailer will accept the economics of every available site. Retailers can continue adding stores nationally while declining individual locations where rent, construction costs or required capital make the expected return unattractive.

Who Pays for Retail Expansion?

The negotiation becomes particularly important when a new store requires significant capital. Landlords generally want higher rent, longer lease terms and tenants with strong financial covenants, particularly when the owner is investing money into the premises.

Retailers, meanwhile, are trying to keep occupancy costs within acceptable levels while limiting the amount of capital required to open a location. A landlord that contributes heavily toward a new store needs sufficient rent and lease security to justify that investment, while the retailer has to determine whether the resulting occupancy cost leaves enough room for the location to generate an acceptable return.

MacKenzie’s call for a partnership approach reflects that reality. Low vacancy gives landlords bargaining power, but maximizing every component of a transaction does not necessarily produce the strongest long-term deal if the resulting store economics are difficult for the tenant to sustain.

Strong Tenants Still Have Leverage

Low vacancy does not necessarily mean all negotiating power has shifted to landlords. A shopping centre operating close to full occupancy can afford to be more selective about its tenant mix, considering which retailers provide stronger financial covenants, generate more traffic, complement existing tenants and are likely to remain productive over a long lease term.

That also makes successful retailers more valuable. A landlord may have several companies interested in a location, but a retailer with strong sales, a proven operating model and the ability to draw customers to the property can still bring considerable negotiating power to the table.

The result is a wider divide between stronger and weaker properties and tenants. Retailers with marginal store economics may face more difficult renewal negotiations at high-performing centres, while landlords with weaker properties can still find themselves competing for the retailers they want.

Not Every Landlord Has the Same Leverage

The difference between RioCan and Primaris illustrates why Canada’s retail market cannot be described uniformly. RioCan’s 98.8% committed retail occupancy reflects a portfolio heavily weighted toward necessity-based and mixed-use properties in major Canadian markets, while Primaris, which owns enclosed shopping centres across the country, reported committed occupancy of approximately 91.1% in the second quarter as its portfolio absorbed vacancies created by Hudson’s Bay.

The HBC closures have produced substantial empty space at some enclosed malls even as other types of retail property remain almost completely leased. Former department-store spaces also present a different leasing challenge because of their size, configuration and redevelopment requirements.

Location matters as well. A small unit in a highly productive grocery-anchored centre in a growing community may attract several competing tenants, while a large former anchor space requiring millions of dollars of redevelopment can produce an entirely different negotiation.

New Supply Remains Difficult to Build

More construction would eventually provide retailers with additional choices, but Canada’s retail development pipeline remains constrained. Elevated land and construction costs have made new retail projects more difficult to justify, particularly when existing market rents are below the level required to generate acceptable development returns.

Projects that do proceed increasingly require sufficient pre-leasing and rents that support the cost of construction. Tight supply therefore supports higher rents and can make new development more economically feasible, but those same occupancy costs can limit the number of retailers able to justify opening stores in newly constructed space.

The market increasingly rewards strong properties and strong retailers. Owners of high-performing real estate have more ability to choose tenants and negotiate higher rents, while retailers capable of generating strong sales, traffic and lease security remain attractive enough to retain bargaining power of their own.

As landlords redevelop former department stores and retailers continue looking for growth opportunities, the details of the lease are becoming increasingly important. Rent, lease term, tenant allowances and capital investment will determine which deals move forward and which proposed stores remain on the drawing board.

More From Retail Insider

Canadian Holiday Shoppers Start Early, Creating New Opportunities for Retail Advertisers

Tim Douglas photo
Tim Douglas photo

Black Friday may still be weeks away, but for many Canadians, the holiday shopping journey has already started.

As consumers begin researching gifts, comparing options and deciding where they’ll spend, Scott Mitchell, Managing Director, Canada at Vistar Media, says brands have an opportunity to influence those decisions well before shoppers reach the checkout.

New Canadian research from Vistar Media and Angus Reid shows that 39% of Canadians have taken action after seeing an out-of-home ad, while 36% say OOH influenced or reinforced a recent purchase decision. Another 22% went on to search for a brand online, pointing to the role real-world advertising can play before consumers actively start shopping.

Holiday shopping starts early

Holiday shopping now starts well before colder temperatures move in and any transactions take place, said Mitchell.

“Consumers may not be checking items off their gift lists yet, but they’re already noticing products, researching brands, comparing options and deciding what deserves their attention,” he said.

“By the time Black Friday arrives, many consumers aren’t starting from scratch. They already have brands and products in mind. That means the holiday marketing window starts earlier too. Brands need to be part of the consideration process before competition for attention reaches its peak.

“The journey itself isn’t linear either. Someone might discover a product during their commute, research it later on their phone, visit a store on the weekend and ultimately purchase it online. That movement between physical and digital environments is now a fundamental part of how people shop.”

The research reinforces the idea that the path to purchase often begins with discovery. Search is incredibly valuable once someone knows what they’re looking for, but something has to create that initial awareness and interest, added Mitchell.

“For marketers, that connection is important. What consumers encounter in the physical world can directly influence what they do next, whether that’s searching, visiting a website or considering a purchase. Holiday campaigns need to account for that full journey, not just the final transaction,” he said.

“The holidays are inherently physical. People are commuting, running errands, visiting shopping districts, attending events, travelling and spending more time around retail environments. Brands have more opportunities to reach consumers as they move through their day.

“Digital out-of-home (DOOH) makes those interactions more relevant because campaigns can account for where and when a message appears. A screen near a commuter hub serves a different consumer moment than one near a shopping centre or within a neighbourhood retail environment.

“The value comes from understanding those differences. Effective DOOH isn’t about putting the same holiday creative everywhere. It’s about using the context of each environment to make the message more meaningful.”

Relevance becomes the differentiator

Mitchell said more advertising doesn’t automatically create more impact. When consumers are surrounded by holiday promotions, relevance becomes the differentiator.

“The starting point should be context: where is the consumer, what are they likely doing and what message makes sense in that moment? Location, time of day and environmental signals can all help inform how creative shows up,” he said.

“That’s one of the strengths of digital out-of-home today. Creative can be more responsive to the environment rather than relying on one message for the entire season. The brands that stand out will be the ones that use that flexibility deliberately.”

Black Friday remains an important retail moment, but it’s no longer the starting line,’ said Mitchell.

“If a brand waits until the major promotional periods to enter the conversation, it’s competing at the noisiest point of the season, when consumers may already know what they want and where they plan to buy it,” he said. 

“Brands should think about the holiday season as a progression. Build familiarity early, strengthen consideration as the season develops and become more tactical as consumers move closer to purchase. Black Friday then becomes an important conversion moment within a broader strategy, rather than the strategy itself.”

Vitaly Gariev photo
Vitaly Gariev photo

Searching for the ease of buying

Mitchell added that consumers don’t think in channels. They think about what they want and the easiest way to get it.

“A consumer can encounter a brand in the physical world, search for it on their phone, visit a store and ultimately buy online. Those aren’t separate journeys. They’re different touchpoints within the same one,” he explained.

“Marketers need to plan accordingly. The question isn’t whether physical or digital media deserves the credit. It’s how those environments work together to move someone from discovery to consideration to action. That’s a much more accurate reflection of how people actually shop today.”

Too many brands concentrate their investment around the transaction and underinvest in everything that happens before it.

“When every advertiser shows up at the same time with a discount, the conversation quickly becomes about price. Promotions matter, but they’re much more effective when consumers already know the brand and have a reason to consider it,” said Mitchell.

“Holiday marketing should build toward the transaction rather than begin with it. Brands that establish awareness earlier have more opportunity to shape consideration before consumers are inundated with competing offers.”

Planning around the consumer

If there’s one shift marketers should make in their holiday planning this year, Mitchell said they should plan around the consumer, not the retail calendar.

“Traditional shopping dates still matter, but they don’t tell us when consumers actually begin discovering, researching or considering holiday purchases. Marketers need to understand where their audiences are spending time and how their needs change as the season progresses,” he said.

“That should translate into one connected strategy: build awareness early, stay relevant through consideration and make it easy to act when purchase intent increases. The brands that do that well aren’t simply showing up for the biggest shopping days. They’re present throughout the journey.”

More from Retail Insider:

Why Grocery Pricing Rules Could Help Some Retailers and Hurt Others

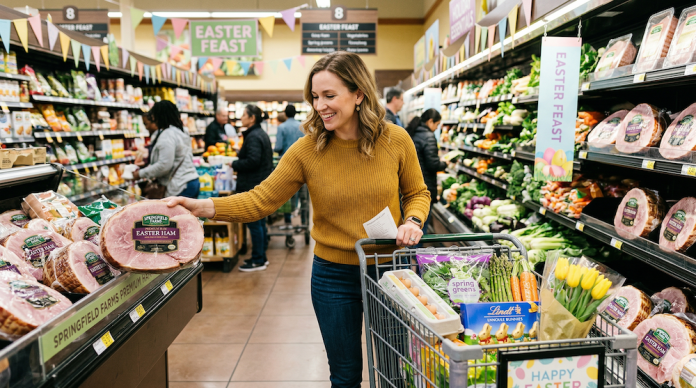
A woman shops in a Canadian grocery store for Easter dinner. Image: RI/Google

The Competition Bureau‘s investigation into minimum advertised pricing in Canada’s grocery sector has exposed a complicated question about retail competition. Rules that can make it harder for a discount grocer to promote lower prices may also provide some protection to smaller retailers competing against national chains with considerably greater purchasing power.

As Retail Insider reported last week, the Bureau is investigating whether minimum advertised pricing policies are making deals harder for consumers to find, reducing price competition, creating barriers for discount and new grocers, or making it easier for retailers to coordinate prices.

Independent grocers see another potential effect. The Canadian Federation of Independent Grocers argues that removing advertised price restrictions could strengthen the largest retailers by allowing them to use their scale and supplier relationships to promote prices smaller competitors cannot economically match.

The competing arguments illustrate why the effect of minimum advertised pricing, or MAP, depends heavily on who holds market power and how the restrictions are being used.

A Discount Can Exist Without Being Advertised

MAP establishes a price below which a retailer cannot advertise a product. Depending on the arrangement, the retailer may still be permitted to sell it for less.

The Competition Bureau uses the example of a package of pasta with a minimum advertised price of $2.99. A retailer could potentially sell it for $1.99 while being unable to advertise the lower price. For a customer already inside the store, the distinction may make little difference. Someone comparing flyers, websites or apps before deciding where to shop may never know the lower price exists.

That is one reason competition authorities are interested in the practice. Advertised prices are part of how retailers compete for customers, particularly for businesses trying to establish themselves as lower-price alternatives.

MAP is not automatically unlawful in Canada. Certain forms of price maintenance can be challenged under section 76 of the Competition Act when they adversely affect competition, but suppliers can also have legitimate reasons for establishing advertised pricing policies. These can include encouraging retailers to invest in service, inventory and product knowledge, protecting brand positioning and preventing retailers from benefiting from marketing investments made by competitors.

The question facing the Bureau is therefore whether particular policies are materially weakening competition.

Why Discount Grocers Could Be Hurt

For a retailer built around lower operating costs, smaller margins or aggressive pricing, the ability to advertise those advantages can be central to its business model. A retailer might be capable of selling a product below its competitors but gain relatively little competitive benefit if it cannot tell consumers about the lower price.

The Bureau’s competition guidance recognizes this possibility. Price maintenance can, in some circumstances, impede the entry of discount retailers or prevent more efficient operators from using lower prices to gain market share.

Keldon Bester, executive director of the Canadian Anti-Monopoly Project, has also argued that MAP can weaken the price signals that drive retail competition and contribute to greater uniformity in advertised prices.

There are limits to that argument in grocery. If a supplier prevents a retailer from advertising one brand below a particular price, the retailer may be able to promote another brand or a private-label alternative instead. Competition between suppliers can therefore limit the impact of MAP in categories where shoppers have numerous substitutes.

Independent Grocers See a Different Risk

The Canadian Federation of Independent Grocers is approaching the investigation from almost the opposite direction.

Gary Sands, the organization’s senior vice-president of public policy and advocacy, argues that MAP can provide some protection to independent retailers that do not have the purchasing volume or negotiating leverage of Canada’s largest chains. Removing those restrictions, CFIG contends, could allow large retailers to use their scale to advertise branded products at prices smaller competitors cannot afford to match.

Sands has warned that independents could be overwhelmed in the resulting “race to the bottom,” with particular implications for stores serving smaller and remote communities.

The underlying disparity in buying power is well documented, even if the competitive effect of MAP remains under investigation. The Competition Bureau’s 2023 grocery market study found that some independent grocers lack the scale to operate warehouses or purchase directly from suppliers. Some instead buy wholesale from operations connected to major grocery companies, including Loblaw and Empire.

Independent retailers told the Bureau that these arrangements can make competing on price more difficult. CFIG has similarly argued for years that independents lack the supplier negotiating leverage available to the country’s largest chains.

That does not establish that MAP is necessary to preserve independent grocers or that eliminating it would drive smaller retailers out of business. There is limited Canadian empirical evidence demonstrating such an outcome. It does explain why some independent retailers view the Bureau’s investigation differently from proponents of unrestricted advertised-price competition.

Discount and Independent Grocers May Want Different Things

The competing positions highlight an important distinction in Canada’s grocery market. A discount entrant and an independent grocer are not necessarily pursuing the same business model or operating with the same economics.

A new discount operator with an efficient cost structure may want complete freedom to advertise prices below established competitors. MAP could make it more difficult for that retailer to communicate its advantage and attract customers.

A smaller independent purchasing products on less favourable terms may have a different interest. A supplier’s MAP policy could prevent a national chain from advertising the same branded product at a price the independent cannot economically match.

The same restriction could therefore constrain one competitor while providing some protection to another. That makes market structure central to determining whether MAP ultimately strengthens or weakens competition.

Not Every Grocery Product Is Equally Affected

MAP also does not necessarily operate uniformly across a grocery store.

University of Guelph food economist Mike von Massow has noted that advertised pricing restrictions are more likely to be relevant to recognizable or premium brands than commodity products such as produce or milk. For branded suppliers, maintaining a particular price position can form part of how a product is marketed.

Retailers may also respond to MAP by shifting promotional activity to another supplier. A grocer prevented from advertising one national brand at a sufficiently attractive price could promote a competing brand or its own private-label product.

Those alternatives matter when assessing competitive effects. A MAP policy covering a product with numerous substitutes may have a different impact from one affecting a product or brand with considerable market power.

The Bureau Investigated Grocery MAP Concerns Years Ago

The relationship between advertised prices, supplier policies and retailer buying power has previously attracted scrutiny in Canada’s grocery sector.

Between 2014 and 2017, the Competition Bureau conducted an extensive investigation into several supplier policies used by Loblaw Companies Ltd. Investigators gathered information from Loblaw, approximately 60 suppliers, competing retailers, industry associations, experts and foreign competition authorities.

Among the practices examined were policies intended to protect Loblaw’s margins when competitors advertised products at lower prices. Under Loblaw’s former Active Ad Match Policy, the retailer could seek compensation from a supplier after reducing its price to match a competitor’s advertisement.

The Bureau illustrated the arrangement using a product normally sold by Loblaw for $2. If a competitor advertised the product for $1.50 and Loblaw matched the price, selling 20,000 units during the promotion, the supplier could face a $10,000 deduction covering the 50-cent difference.

The Bureau also examined Threshold Deals, under which suppliers could compensate Loblaw when margins fell below agreed levels following an advertised price match, along with other supplier policies. Investigators considered whether these arrangements created incentives for suppliers to limit price competition elsewhere.

Specifically, the Bureau examined whether suppliers introduced minimum advertised pricing policies that restricted other retailers’ ability to offer products below Loblaw’s price, encouraged adherence to suggested retail prices or encouraged other retailers to increase advertised or shelf prices.

What the Loblaw Investigation Found

The earlier investigation did not establish that Loblaw caused suppliers to impose MAP policies across the grocery industry. After approximately three years, the Bureau concluded there was insufficient evidence to establish that Loblaw’s policies had substantially lessened or prevented competition and discontinued its inquiry in 2017.

Its position statement nevertheless identified potential risks associated with margin-protection arrangements. The Bureau said such policies could create incentives for suppliers to protect a retailer from competition, including by reducing promotions available to competing retailers, removing lower-margin products or implementing minimum advertised pricing.

It said it would take action if compelling evidence subsequently showed those incentives resulting in anti-competitive conduct.

The 2017 findings are not evidence of wrongdoing in the current investigation, and the Bureau has not established a connection between Loblaw’s former policies and the MAP practices it is examining today. The earlier case does show that the relationship between retailer buying power, supplier incentives and advertised prices has been on the regulator’s radar for years.

Who Holds the Market Power Matters

Minimum advertised pricing is generally associated with policies established by suppliers, but the competitive analysis becomes more complicated when large retailers have substantial purchasing power.

Competition Bureau guidance recognizes circumstances in which a retailer may induce a supplier to restrict pricing by competing retailers. In that situation, a policy appearing to originate with the supplier could potentially protect the retailer from price competition.

Independent grocers are raising a different concern today. They contend that supplier-imposed MAP can restrain the ability of a dominant retailer to use its purchasing advantages against smaller competitors.

Economic research supports treating MAP as a case-specific competition question. Economists John Asker and Heski Bar-Isaac have examined MAP as an information restraint that can increase consumer search costs and soften retail price competition. Their work also recognizes circumstances in which the practice can support retailer services and investment, meaning its overall effects depend on the characteristics of the market.

That is broadly consistent with Canada’s approach to price maintenance, which focuses on competitive effects instead of treating the practice as inherently unlawful.

Supplier Funding Adds Another Layer

Supplier funding can make the distinction between a formal pricing restriction and a commercial incentive less obvious.

Consumer packaged goods companies routinely support retailer advertising and promotions. Competition Bureau guidance specifically addresses co-operative advertising arrangements in which financial support can be connected with adherence to MAP.

A retailer might remain technically free to advertise below a supplier’s preferred price but lose advertising reimbursement by doing so. Depending on the economics involved, that can provide a meaningful incentive to comply without an outright prohibition on discounting.

Food, Health & Consumer Products of Canada, which represents manufacturers, has argued in submissions to the Competition Bureau that concentration among Canada’s major grocers gives large retailers significant bargaining power in negotiations with suppliers. The organization has also pointed to the substantial share of supplier revenue devoted to trade spending and retailer programs.

Those claims reflect the supplier industry’s position and do not establish anti-competitive conduct by retailers. They illustrate why conditions attached to advertising allowances, promotions and other supplier funding can have significant financial consequences.

The Larger Question Is Grocery Competition

The MAP investigation arrives as the Competition Bureau examines several structural features of Canada’s grocery market. Most grocery purchases continue to flow through five major companies: Loblaw, Empire, Metro, Costco and Walmart. The Bureau has repeatedly called for conditions that make it easier for international grocers, independent retailers and other competitors to enter the market and expand.

In June, it launched “Behind the Price Tag,” an examination of competition throughout Canada’s food supply chain, including production, processing, transportation, distribution and retail pricing. That market examination is separate from the MAP investigation and is not itself an investigation into specific alleged wrongdoing. Findings are expected in spring 2027.

Against that backdrop, MAP presents an unusual competition problem. Policies that restrict advertised prices could make it harder for an efficient discount entrant to challenge established retailers, while removing those restrictions could give consumers access to more aggressive advertised prices.

Independent grocers argue that the same change could increase the advantage of national retailers capable of securing better supplier economics and absorbing promotions that smaller competitors cannot match. Whether one effect outweighs the other cannot be determined simply by establishing that MAP is being used.

The Bureau will need to understand which products are affected, who initiates the policies, how they are enforced, whether supplier funding is tied to compliance and how frequently retailers actually sell products below the advertised floor. It will also need to consider whether retailers can readily substitute competing brands, whether MAP materially prevents efficient discounters from gaining market share and whether the policies provide meaningful protection to independent retailers facing competitors with greater purchasing power.

The investigation may therefore ultimately turn less on whether minimum advertised pricing is inherently good or bad for consumers than on who holds market power, how that power is being exercised and whether the resulting restrictions strengthen or weaken grocery competition in Canada.

More from Retail Insider: