Home Blog Page 2

LoyauT 2026: The Restaurant Industry Tops Canada’s Loyalty Programs

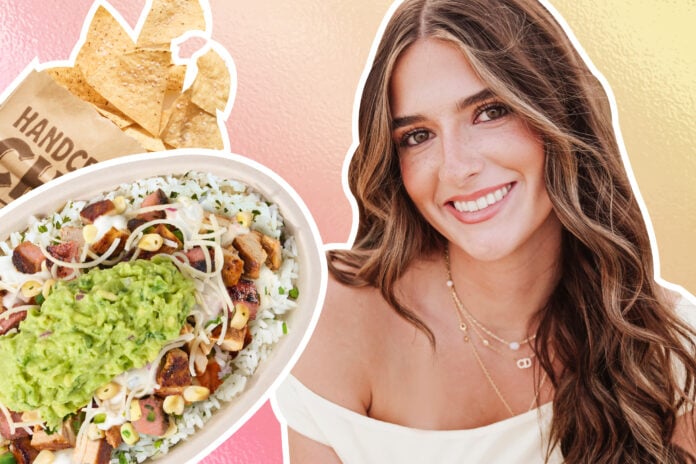
Chipotle photo
Chipotle photo

The LoyauT 2026 rankings suggests loyalty programs are becoming a restaurant industry phenomenon.

The study, conducted by adviso in partnership with Ad Hoc Research, annually analyzes the performance of loyalty programs in Quebec and Canada. This 9th edition is based in part on responses from 15,000 Canadians and an evaluation of 83 loyalty programs, providing a comprehensive picture of consumer habits and expectations, according to a news release.

This year, the rankings reveal a particularly marked shift in the market: restaurant and coffee programs now occupy eight of the top ten spots in Canada—a dramatic rise compared to previous editions. In Québec, they account for half of the Top 10, said the report, adding another notable development: Salvatoré has jumped straight to the top of the Québec rankings, ahead of well-established programs such as Tim Hortons’ FidéliTim and Domino’s Rewards.

“Loyalty programs have come of age. Today, we’re seeing highly advanced initiatives in virtually every industry, with brands going well beyond traditional reward mechanisms or segmented communications. The real question is no longer whether to launch a program, but how to build a distinctive loyalty experience that truly reflects the brand and gives consumers a reason to stay engaged. The programs that stand out are those that succeed in making this experience simple, relevant, and generous. This year, restaurant loyalty programs illustrate this evolution particularly well,” said Simon Éthier, consultant, omnichannel commerce, monetization, and strategy, adviso.

“Furthermore, seeing a Quebec program take the top spot—ahead of several of the biggest international programs—is certainly one of the surprises of this year’s edition. But beyond the rankings, this result above all illustrates just how much consumer expectations have evolved: the top-performing programs are no longer content to simply offer rewards. They create a consistent, distinctive loyalty experience that is deeply rooted in their brand identity.”
TOP 10 CANADA

RankProgramStatus
1Chipotle RewardsNew
2Burger King-1
3Papa Johns+2
4adidasNew
5Panera Bread-3
6SalvatoréNew
7PC Optimum=
8Domino’s=
9Tims Rewards – Tim Hortons+5
10Second Cup+2

The report said eight of the 10 programs in Canada’s Top 10 are now associated with fast food or coffee, compared to just four in 2025 and only one in 2024.

TOP 10 QUÉBEC

RankProgramStatus
1SalvatoréNew
2Tims Rewards – Tim Hortons+4
3Domino’s-2
4McDonald’s-2
5Journie Rewards – Ultramar+2
6PC Optimum-3
7Walmart-3
8A&W RewardsNew
9Beauty Insider – Sephora-4
10Cuddle Club– Mondou+1
Salvatoré photo
Salvatoré photo

This is a major shift from 2025, when the top three were Domino’s, McDonald’s, and PC Optimum. Salvatoré has thus immediately moved ahead of several of the country’s best-known loyalty programs, while Tim Hortons has climbed from sixth to second place, added the report.

“In a climate where the cost of living remains a major concern, the financial value of these programs remains central to their appeal. As a result, 69% of Canadians say loyalty programs help them save money, while 67% use them to earn more rewards and discounts. These programs also have a tangible influence on consumer choices. The proportion of Canadians who say they often or very often change their product choices to maximize their points will reach 37% in 2026—the same level observed in 2025—after rising from 23% in 2021 to 37% in 2025,” said the report.

“This stability could signal a shift in dynamics: after several years of growth, certain loyalty-related behaviours appear to be leveling off. This trend is particularly telling when we look at the number of programs consumers are enrolled in. Canadians are members of 22 loyalty programs on average, but use only nine of them regularly. Both of these figures remain unchanged from 2025.

“The conclusion is clear: consumers continue to have access to a multitude of programs, but their engagement and active use are no longer growing.

“For brands, the challenge is therefore no longer simply to recruit new members, but to succeed in becoming one of the programs that consumers actually choose to use.”
Mikhail Nilov photo
Mikhail Nilov photo

The report said the proliferation of programs and accounts also raises trust issues. According to LoyauT 2026, 42% of Canadians have been victims of at least one instance of fraud related to a credit card or loyalty program:

  • 18% have been victims of fraud related to a loyalty program;
  • 37% have been victims of credit card fraud;
  • 42% have experienced at least one of these two situations.

“As these programs increasingly rely on personal data and digital interactions, trust has become an essential component of the loyalty experience,” it said.

The report noted that young adults once again stand out for their level of participation in loyalty programs.

“On average, 18- to 34-year-olds are enrolled in 24 programs and use 10 of them, compared to 21 and 8, respectively, among those aged 35 and older. They are also more likely to join paid premium programs: 44% of 18- to 34-year-olds are members of at least one such program, compared to 24% of those aged 35 and older, excluding Costco and Amazon Prime,” it said.

“These results illustrate an interesting paradox: younger consumers are both the ones who subscribe to the greatest number of programs and the ones who seem most willing to pay for added value. Young people also have the lowest loyalty threshold and the highest expectations when it comes to customer experience.”

In an interview with Retail Insider, Éthier spoke about this year’s results.

What factors are driving restaurant and coffee shop loyalty programs to dominate Canada’s top rankings, and what are these businesses doing differently from loyalty programs in other sectors?

The key ingredients we see in this vertical are a few interlinked elements : 

(1) There is significant frequency in this vertical, and brands as well as experience play a significant role in the consumer’s choice; competition is also strong, forcing an ever-evolving loyalty offering. 

(2) Easily-reachable, tangible, noteworthy rewards. For example getting a free donut after only a few orders with Tims Rewards is attractive and memorable compared to more abstract rewards. This also aligns with the brand. 

(3) Restaurant / coffee chains often have simple and effective mobile apps, that are one of the main ways to identify clients and provide additional value (e.g. quicker ordering or checkout, etc.) ; this can create a virtuous cycle between app use, order frequency and rewards.


Salvatoré moved directly to the top of Quebec’s loyalty program rankings in its first year on the list. What distinguishes its program, and what can other Canadian restaurant brands learn from its performance?

Salvatoré brings a simple but effective program that delivers on many of the aforementioned points; the brand’s visibility is growing and maintains a strong presence on social media, where the brand’s owners are very active, bringing an engaging entrepreneurial story that can feel relatable, reinforcing consumer perception of their relationship marketing.

Kindel Media photo
Kindel Media photo

The report found that Canadians belong to an average of 22 loyalty programs but regularly use only nine. What does this suggest about consumer loyalty, and how can businesses turn program membership into sustained engagement and repeat purchases?

Growing the member base is only the starting point when managing a program. A program needs to be very competitive to be among the few memorable ones that the average consumer truly use on a regular basis. This means creating attractive offers, communicating often (in-store: on shelves, at the register, digitally: by email, by push notifications, by SMS, in the app, on the site, through advertising, etc.), making sure members really experience their rewards, etc. Businesses need to focus on a customer’s current mindset and engagement level to really influence behaviours.  


With 69 per cent of Canadians saying loyalty programs help them save money, how are cost-of-living pressures changing consumer expectations around rewards, discounts and paid premium memberships?

For the last few years, the survey results have been indicating that Canadians are looking for ways to save money and maximize their rewards. While these financial considerations consistently ranks among the most sought-after component of loyalty programs, other aspects are also important and vary depending on the vertical, and can include access to free products, personalized recommendations, exclusive promotions, etc. The perceived generosity of a program does not always correlate with the monetary value of the publicized rewards. Regarding premium memberships, a person that decides to pay to participate in a program will typically have a stronger motivation to make the best of their subscription, and will therefore use it more, and experience more of its benefits. 

The study found that 42 per cent of Canadians have experienced credit card or loyalty program fraud, while younger consumers have particularly high expectations for customer experience. How can brands build trust, protect customer data and create loyalty experiences that remain relevant to increasingly selective consumers?

Trust is built on a common understanding that the other party will behave in a caring manner. First and foremost, the value a customer will get when providing information or making any type of commitment must be worthwhile, and feel relevant to achieve what he is expecting: this value needs to be clearly communicated, and be truly attractive. On the other hand, a business that relies on policies and enforcement rather than caring, honest customer relationship management will operate in a distrustful atmosphere. 

As for data security, the best protection for all parties involved will always be to only capture and manage what is truly necessary. Merchants need to focus on what’s essential and truly relevant to create good experiences, and this may represent less data, and less sensitive data than some would expect: a pizza chain will drive value mainly from a customer’s pizza-ordering habits (or changes in these habits), and may be able to operate its marketing activities on very little other personal data. Data and I.T. security best practices and proper compliance and governance of course also apply here. 

More from Retail Insider:
Canadian small business sales rise for four straight months, Xero report finds

Vitaly Gariev photo
Vitaly Gariev photo

Canadian small business sales rose for four consecutive months through September, offering signs of improvement after 18 difficult months, although sales remain below historical averages and renewed U.S. trade tensions continue to weigh on exporters, according to a new report from Xero.

The quarterly Xero Small Business Insights report found sales increased two per cent year over year in the September quarter, while businesses waited an average of 10.5 days beyond invoice due dates to receive payment. Alberta led regional sales growth, while British Columbia and the Maritime provinces recorded declines.

The report draws on aggregated and anonymized data from 12,000 Canadian small businesses using Xero, a global small business platform. It tracks sales performance, late payments and the time businesses take to receive payment.

“Four months of growth is encouraging, but sales are still well below historical levels, so it’s too early to call this a recovery,” said Ashalee Mohamed, Country Manager for Canada at Xero. “With ongoing trade tensions with the US and higher-than-normal fuel prices, many small businesses are still facing tough trading conditions. Now is a good time for owners to review their pricing, check where costs are creeping up and make sure that they have a clear view into their cash flow so they’re ready to act if pressure builds in the coming months.”

Sales growth remains below historical levels

Canadian small business sales increased 2 per cent year over year in the September quarter, following an upwardly revised gain of 0.4 per cent in the June quarter. It was the first time sales had increased for four consecutive months since April through July 2025.

Monthly sales growth was 3 per cent year over year in July, 2.5 per cent in August and 0.5 per cent in September. The results remain below the historical average of 4 per cent annual sales growth, although they follow months of declining sales.

Louise Southall, an economist at Xero, said the latest figures offer some encouragement after a prolonged period of difficulty for Canadian small businesses.

“After what has been a really difficult 18 months for Canadian small businesses, this growth is welcomed,” said Southall. “These are still tepid results, and Canada continues to trail the other countries we track on sales growth, but there are some early signs of recovery. Alberta is doing a lot of the heavy lifting thanks to higher oil prices, and without it the national picture would probably look a lot worse. The US-Canada trade conflict remains the key factor behind these results, and I don’t see that changing any time soon.”

Alberta leads regional sales performance

Alberta recorded the strongest sales performance among the regions tracked, with sales rising 5.9 per cent year over year in the September quarter. The report attributed the province’s performance largely to higher global oil prices.

Ontario sales increased 2.2 per cent, improving from growth of 0.8 per cent in the June quarter. However, a 1.7 per cent year-over-year decline in September weighed on the province’s quarterly results.

The Maritime provinces recorded a 1.4 per cent decline in sales compared with the same quarter a year earlier, largely because of a 9.5 per cent drop in July. British Columbia posted a 2.6 per cent decline, with sales falling year over year in each month of the quarter.

Despite the sales declines, British Columbia remained the fastest region for small businesses to receive payment, with an average time to be paid of 24.6 days.

Late payments remain a challenge

Canadian small businesses were paid an average of 10.5 days late in the September quarter, compared with 10.8 days in the June quarter. The measure tracks how long payments arrive after their due dates.

The average time from invoice issuance to payment was 28.4 days, up slightly from 28.2 days in the June quarter. The increase was largely attributable to a 29.8-day result in September. Canada continued to have the longest late payment times among the countries tracked by Xero Small Business Insights.

Regional time-to-payment figures for the September quarter were 28 days in Alberta, 28.9 days in Ontario and 33.7 days in the Maritime provinces. Alberta’s average was pushed higher by a rise to 34.1 days in September, its longest payment time since August 2023. Xero said that figure could be revised as additional data becomes available.

Gustavo Fring photo
Gustavo Fring photo

Exporters report weaker confidence

The report also highlighted a widening confidence gap between businesses involved in international trade and those operating domestically, amid renewed U.S. trade tensions.

The Canadian Federation of Independent Business’ September Business Barometer found no statistically significant difference in 12-month confidence among exporters, importers and businesses not engaged in international trade in September 2024.

By September 2026, exporters recorded a confidence score of 38.6 points, compared with 43.5 points for importers and 52.2 points for businesses that did not operate internationally.

Southall said tariffs are creating challenges for exporters on both sides of the Canada-U.S. border, affecting prices and the ability of businesses to compete.

“No one wins from tariffs,” added Southall. “Consumers on both sides of the border pay more for the same goods, and exporters find it harder to make a sale against products that don’t carry the same tariff. The obvious response for Canadian exporters is to find new markets, but that takes time and isn’t a costless exercise. And it’s not just Canadians feeling it. US businesses near the border are feeling the effects too.”

More from Retail Insider:

Retail Insider “Q3 2026 Logistics & Supply Chain Report”: Resilience Has to Earn Its Cost

Retail Insider has released Q3 2026 Logistics & Supply Chain: Capacity Expands as Costs and Trade Risks Shift, authored by Retail Insider founder and publisher Craig Patterson. The report examines where added capacity and supply-chain flexibility can protect retail service, and when those options become an unnecessary operating expense.

The report covers sourcing, transportation, warehousing, fulfilment, inventory and resilience across the supply chains supporting Canadian retail. It combines Retail Insider reporting, company disclosures, industry research and public data discussed during Q3, distinguishing completed investments from future projects and wholesale activity from consumer retail demand.

Retail Insider Reports provide executive-level analysis of the sectors and business issues shaping Canadian retail. The collection is available through the Retail Insider Report Hub, bringing sector reporting and broader industry research together in one place.

General Themes

  • Capacity is expanding: Large automated facilities and specialist distribution projects address different service requirements.
  • Operational detail matters: Faster vehicle processing and reliable information can improve existing networks without replacing them.
  • Trade changes alter sourcing economics: Tariffs and supplier failures can accelerate production decisions, although individual cases do not establish a national reshoring trend.
  • Freight costs vary: Routes, equipment, contracts and service requirements matter more than a single average rate.
  • Resilience needs a business case: Extra stock, alternative suppliers and premium transport should be measured against the commercial disruption they prevent.

Retail Insider Coverage

Lululemon’s Brampton distribution centre demonstrates the scale of investment behind modern fulfilment. The facility exceeds one million square feet, with 525 AutoStore robots, 292,000 storage bins and approximately eight kilometres of conveyors serving Eastern Canada and the eastern United States. It became fully operational in June and was formally unveiled in July, following construction that began in 2023. Its completion reflects a multiyear capital decision rather than a response to one quarter’s demand.

The wider industrial property market also strengthened without returning to its earlier scarcity. CBRE reported Q3 national net absorption of 10.3 million square feet and availability of 5.2 per cent. Average net asking rents were $14.77 per square foot, down 2.4 per cent year over year. Improving space demand and lower annual rents can therefore coexist.

Richelieu’s Quebec investment serves a different distribution requirement. The company committed more than $15 million to expand its Drummondville centre from nearly 40,000 square feet to 180,000 square feet, with operations expected in spring 2027. The facility will serve Montreal’s South Shore, Centre-du-Québec and the Eastern Townships. Cabinetmakers, furniture manufacturers, woodworkers and hardware retailers depend on broad assortment and reliable replenishment, rather than the direct consumer fulfilment underpinning Lululemon’s network.

Loblaw’s expanded EAIGLE partnership targets a narrower operational problem. Vision AI gate automation validates vehicles, captures freight information and connects with existing systems across distribution-centre yards. The September announcement did not quantify additional yards or savings, so it establishes a deployment decision rather than a measured financial return. Separate DOSS research found meaningful efficiency gains among only 14 per cent of 230 surveyed U.S. consumer packaged goods operations leaders. That is not a Canadian adoption measure, but it reinforces the need to connect technology claims with usable operating data.

Gather Packaging showed how trade policy can compress production decisions. The Toronto-area paper-bag manufacturer accelerated roughly two and a half to three months of work into approximately three weeks, sending affected orders across the U.S. border by August 14 ahead of tariff exposure. More than 75 per cent of its production volume had gone to that market. The company retained orders and backlog while seeking Canadian customers, as a 50 per cent Canadian counter-tariff on affected U.S.-origin paper bags took effect September 8. Domestic opportunities do not automatically replace export volume, particularly when bulky products face substantial freight costs.

Dupray approached the problem through manufacturing location. After a Spanish supplier failed, it moved Bloom air-purifier production near Montreal, with U.S. tariff uncertainty also influencing the decision. Approximately 70 per cent of sales remained in the United States, while Canadian manufacturing represented a small pilot within total production. Shorter lead times and greater control can matter even without a lower unit cost. Together, Dupray and Gather illustrate product-specific responses rather than proof of broad reshoring.

Broader Industry Coverage

Cargojet’s Q2 results, discussed in August, show how inventory placement influences freight requirements. Domestic overnight revenue excluding year-over-year fuel-price pass-through effects increased 3 per cent to $104.9 million, while the equivalent company-wide measure rose 5 per cent. These are revenue figures, not disclosed parcel-volume growth. Management described stronger e-commerce activity in secondary Canadian markets and more inventory held centrally rather than in individual stores. A changing store network can therefore alter delivery needs even before aggregate retail demand changes.

Transportation costs remained uneven. Cargojet’s new pilot agreement raised wages 26 per cent effective July 1, with productivity changes intended to offset part of the increase and contract structures affecting the timing of pricing changes. ACT Research reported August intra-Canada spot truckload rates excluding fuel of approximately US$1.83 per mile, up 7.8 per cent annually. The U.S.-dollar rate covers an aggregate market measure; individual equipment categories and directional lanes moved differently. Retailers need costs matched to their actual service and route requirements.

The freight invoice also understates the cost of an unreliable shipment. The report’s discussion with supply-chain strategist Gary Newbury considers split deliveries, expedited replacements, additional handling, customer-service work and markdowns when seasonal products arrive late. A cheaper rate can become the more expensive option after those consequences are included. Equally, a premium service only makes sense where the avoided disruption justifies it.

Inventory evidence needs similar discipline. Statistics Canada’s July wholesale sales increased 7.9 per cent annually in dollars but only 1.8 per cent in chained volume. This upstream series excludes petroleum, other hydrocarbons, oilseed and grain, and does not measure consumer retail purchases. Inventories stood at $140.6 billion, with a 1.51-month inventory-to-sales ratio. Textile, clothing and footwear inventories were 21.1 per cent higher annually but lower than in June, a category-specific position that does not establish an economy-wide glut.

Editor’s Take

The outlook turns on whether additional supply-chain options repay their cost. More stock can protect sales where replenishment is uncertain, and a domestic supplier can justify a higher unit price when shorter lead times materially reduce disruption. Automation has value when it removes meaningful friction and works with reliable information. Entering the holiday period, the useful preparation is visibility into critical suppliers, routes and inventory, alongside clear points at which purchasing or fulfilment plans should change.

Resilience is an operating choice with a carrying cost. Warehouses, alternative suppliers, premium transportation and spare capacity can all protect a customer promise, but their value depends on the failure they prevent. Q3’s investments should be judged by reliable, profitable merchandise flow rather than their size or technological sophistication alone. The strongest network is the one whose costs remain justified when demand, trade rules or service conditions change.

Conclusion

Read the full Q3 2026 Logistics & Supply Chain: Capacity Expands as Costs and Trade Risks Shift for the analysis of distribution investment, transportation, sourcing and category-level inventory. It compares the cost of additional options with the disruption they are intended to prevent.

The report and the wider quarterly collection are available through the Retail Insider Report Hub. The hub brings together sector reports and analysis of the operating conditions affecting Canadian retailers and their suppliers.

More from Retail Insider

Doritos Canada launches limited-edition loungewear contest with 7-Eleven

Doritos image
Doritos image

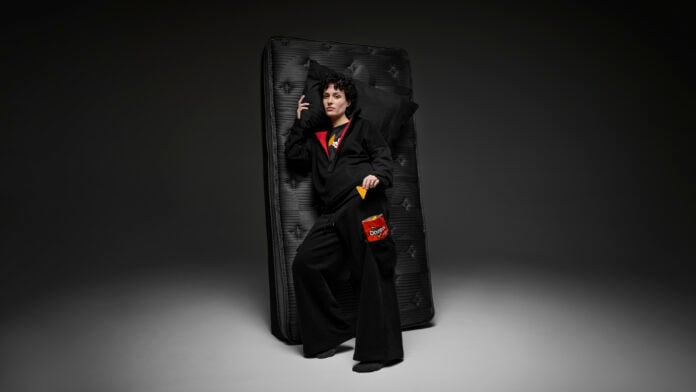
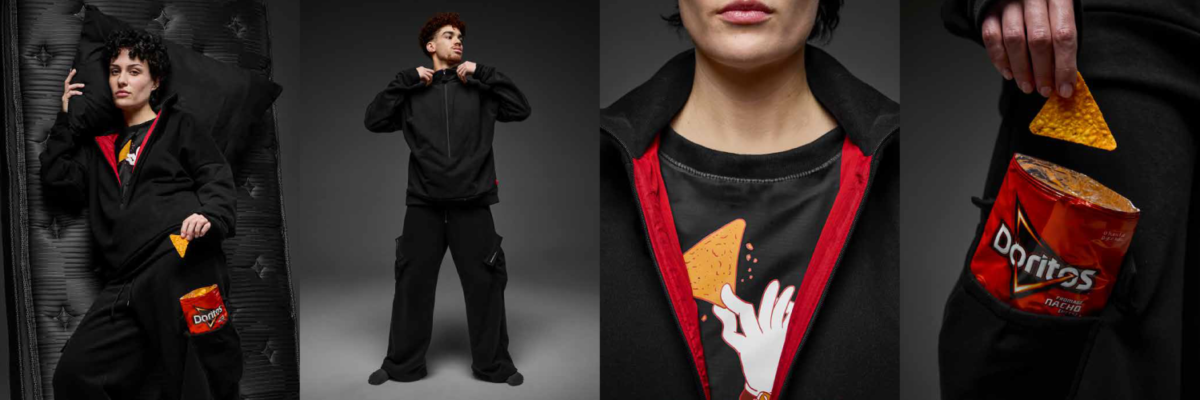
Doritos Canada has partnered with 7-Eleven Canada to offer consumers a chance to win one of 50 limited-edition loungewear sets designed to catch crumbs while snacking, as the brands target the late-night eating occasion.

The Doritos Crumb Couture collection, created in collaboration with Vancouver-based street artist and illustrator Carson Ting, is available to win through the 7Rewards contest. The promotion began Oct. 28 and runs until Dec. 1, with eligibility limited to Canadian residents of the age of majority or older in British Columbia, Alberta, Saskatchewan, Manitoba and Ontario.

The contest requires participants to purchase a bag of participating Doritos tortilla chips at a participating 7-Eleven location and scan the 7-Eleven app to enter for a chance to win.

Loungewear designed to catch crumbs

The limited-edition set was developed through research and development, prototype testing and crumb simulations, according to PepsiCo Foods Canada, which announced the launch on behalf of Doritos Canada.

The clothing features strategically placed crumb-catching elements intended to help keep food debris off bedsheets, couches and clothing. The design focuses on consumers who snack while relaxing or spending time in bed.

“At Doritos, we’re always looking for bold ways to show up in the moments our fans already enjoy,” said Lisa Allie, senior marketing director, core brands, foods, PepsiCo Canada. “As bed rotting has become part of Gen Z culture, we saw an opportunity to turn one of the most relatable frustrations of snacking into something unexpected. Doritos Crumb Couture brings the bold spirit of our brand to life through an unexpected, functional solution designed to elevate the lounging experience and keep the focus on the snacks, not the crumbs.”

The collaboration extends Doritos’ marketing efforts into apparel, using a limited-edition product and a retail contest to connect the brand with consumers during at-home snacking occasions.

Doritos image
Doritos image

7-Eleven partnership centres on late-night snacking

For 7-Eleven Canada, the promotion provides a way to connect its convenience-store business with consumers purchasing snacks for evening and overnight consumption.

“7-Eleven is where Canadians turn for their favourite snacks, whether they’re on the go or settling in for the night,” said Marc Goodman, vice-president and general manager of 7-Eleven Canada. “Partnering with Doritos gives us a fun way to tap into the late-night snacking occasion while giving our customers a chance to win a limited-edition Doritos Crumb Couture loungewear set through the 7Rewards® contest on the 7-Eleven app.”

The contest offers 50 loungewear sets in total, with no additional sets identified in the announcement. Consumers must purchase eligible Doritos tortilla chips and use the 7-Eleven app to participate.

The promotion is available only in British Columbia, Alberta, Saskatchewan, Manitoba and Ontario, according to the contest details provided by the companies.

New Doritos flavour also available

The announcement also highlights the limited-time availability of Doritos Late Night Spicy Pizza flavoured tortilla chips, inspired by pizza as a late-night comfort food.

The flavour is available at major grocery retailers nationwide and at participating 7-Eleven locations across Canada, according to PepsiCo Foods Canada.

Doritos is part of PepsiCo Canada’s portfolio of food and beverage brands, which also includes Lay’s, Cheetos, Gatorade, Pepsi-Cola, Mountain Dew, Quaker and SodaStream.

PepsiCo reported nearly US$94 billion in net revenue in 2025 across its global portfolio of beverages and convenient foods, according to the company’s announcement.

More from Retail Insider:
Restaurant Brands International sees net revenue jump to $2.53 billion in Q3, with system-wide sales near $13 billion

Photo: Firehouse Subs

Restaurant Brands International Inc. reported on Thursday its financial results for the third quarter ended September 30, 2026 as consolidated System-wide sales grew 6.2% year-over-year, including 9.0% in International. Net revenue rose to $2.53 billion in the quarter compared with $2.44 billion a year ago.

System-wide sales rose to $12.97 billion from $12.28 billion a year ago.

“At our Investor Day earlier this year, we highlighted what makes RBI a strong business – four iconic global brands, the ability to invest for long-term growth, and talented teams and franchisees around the world. Those strengths are on display again this quarter, with over 3% global comparable sales led by outperformance at Burger King and steady growth at International and Tim Hortons. I’m proud of what we’re accomplishing together. Across our brands, we’re continuing to listen to our guests and act on their feedback to deliver the quality, service, and convenience they expect every day,” said Josh Kobza, Chief Executive Officer of RBI.

“For the third quarter, the increase in Total revenues was driven by higher Supply chain sales primarily due to increases in equipment sales to franchisees and commodity prices. The increase in Total revenues was also driven by increased System-wide Sales,” said the company.

The company saw net restaurant growth of 3% to 33,401 at the end of the quarter.

Restaurant Brands International Inc. is one of the world’s largest quick service restaurant companies with over $49 billion in annual system-wide sales and over 33,000 restaurants in more than 120 countries and territories. RBI owns four of the world’s most prominent and iconic quick service restaurant brands – Tim Hortons, Burger King, Popeyes and Firehouse Subs.

RBI’s principal executive offices are in Miami, Florida. In North America, RBI’s brands are headquartered in their home markets where they were founded decades ago: Canada for Tim Hortons and the U.S. for Burger King, Popeyes and Firehouse Subs.

More from Retail Insider:
Giftbit Data Shows Grocery Gift Card Rewards Surged 1,067% in December 2025

Giftbit’s latest Holiday Digital Rewards Index, based on 2025 platform activity across thousands of business customers, shows how businesses use rewards to engage customers and employees, and what recipients actually choose during the holidays.

A few interesting 2025 findings: 

  • Grocery gift cards are having a moment! Reward value surged 1,067% in December while travel barely moved (+27%). A striking contrast as affordability and practical gifting take center stage in 2026. 
  • Black Friday isn’t just about discounts. Loyalty rewards jumped 84% in November, highlighting how businesses ramp up customer incentives ahead of the holiday rush.
  • Employee appreciation is a December phenomenon. Employee reward value reached 7.4 times its usual monthly level, raising questions about year-round recognition versus the year-end gifting rush. 
  • More rewards, slower reactions. Median gift card claim times more than tripled from November to December (45 to 162 minutes), offering a curious glimpse into how recipients engage with rewards during the busiest gifting season.  

In an interview with Retail Insider, Leif Baradoy, CEO of Giftbit, explored the upcoming shopping season.

What factors do you believe drove the 1,067 per cent surge in grocery gift card reward value in December 2025, and what does this suggest about how businesses and consumers are responding to affordability pressures?

The biggest factor is simple: people chose it. Most Giftbit rewards let the recipient pick where the value goes, so a 1,067 per cent jump in grocery (December compared with the September to October average) is a record of what people wanted when the decision was theirs.

Right now, people want what is practical. People chose grocery gift cards last year, followed by sporting goods, toys and apparel. Travel and hospitality grew just 27 per cent. The affordability pressures you mentioned are real, and our data suggests that people use rewards to cover expected costs that occur during the holiday season: a big holiday meal, gifts, and kids’ winter gear.

I’d want to be careful not to pin recipient selection to one cause, since household expenditures are usually higher in December regardless of what is happening in the economy. The holidays often stretch household spending, so  a reward that helps with the grocery bill in December is practical and useful.

Give people a choice of a reward and their selection will show what matters to them right now.

How are businesses using digital rewards and loyalty incentives differently during the holiday shopping season, particularly in the lead-up to Black Friday, and what does the 84 per cent increase in loyalty reward value in November indicate?

Loyalty moves first. In our 2025 data, loyalty reward value jumped 84% from October to November, landing 93% above its ten-month average, then eased back in December.

I interpret that as businesses being deliberate. Loyalty teams act early so they can stand out from the holiday rush. Businesses send thank-yous and retention rewards in November, which recipients use in December.

Employee rewards run on a different clock and peak in December. The data showed us the holiday reward season is really two seasons: your customers in November, your own team in December.

What the 84%jump in loyalty reward value  tells me is that loyalty programs understand timing is part of the reward. A thank-you that lands while someone is planning their holiday shopping does more work than the same thank-you in late December. 

Employee reward value reached 7.4 times its usual monthly level in December 2025. Why is employee recognition so concentrated at year-end, and are businesses showing signs of shifting toward more consistent, year-round rewards?

Year-end is when the budget, the calendar and the sentiment all line up. Annual bonuses, holiday appreciation gifts, and team celebrations land in the same few weeks. In December, employee reward value hit 7.4 times the January to October monthly average, and that one month was about 39 per cent of the year’s employee reward value.

Employee recognition is concentrated at year-end to further demarcate appreciation for the efforts of the past year and motivate for the year ahead.

The rest of the calendar year has interesting data trends, too. We saw increased employee recognition in May and August, which tells me some companies are recognizing people around moments that matter to their teams, not only around the fiscal year. 

I think gratitude works best when it’s consistent. Rewards are about building a relationship, and relationships don’t run on a once-a-year schedule.

Median gift card claim times more than tripled from November to December, rising from 45 to 162 minutes. What might explain this change, and what does it reveal about recipient engagement and behaviour during the holiday season?

December is our busiest month and it is also where recipients take the longest time to react, measured by  reward claim times. For example, a Starbucks reward that’s typically claimed by a recipient in 7 to 9 minutes early in the year took a median of 168 minutes in December. 

We don’t have casual data on recipient selection times, but I speculate that it’s simply because people are busy. They’re travelling, with family, off work and away from the inbox or app where a lot of rewards land. And when a reward comes with choice, people take time to decide where it’ll be most useful for them over the holidays.

There are exceptions to recipient claim times: prepaid cards and gaming rewards. Those don’t slow down. When the use is immediate and single-purpose, there’s no pause.

Slower claims don’t mean lower engagement. December was still the biggest month for claimed rewards, at 13.1 per cent of the year. The practical takeaway: send earlier in December so people have time to claim and use the reward during the holidays.

As the 2026 holiday season approaches, what changes do you expect in the types of digital rewards recipients choose, and how might economic conditions, consumer spending pressures and evolving business priorities influence reward strategies this year?

I expect practicality to keep winning. Last year, recipients put holiday rewards toward groceries, family gifts and winter gear. I don’t see pressure on household budgets easing in December this year.

With inflation and economic pressures, businesses are reviewing the impact of their budgets. Rewards and incentives should be scrutinized to ensure they’re delivering business outcomes. The same economic pressure impacts employees and consumers, making rewards and incentives more compelling, motivating, and memorable. Businesses can influence people more powerfully with rewards and incentives when people are looking for their dollars to go further.

For businesses that are using rewards and incentives to drive outcomes, here are three things to keep in mind:

Choice. Data shows that people’s priorities shift with the season, so offer people a choice between many rewards, not just one. 

Timing. Plan in two waves: schedule loyalty and customer sends by late October, approve employee budgets and recipient lists by mid-November, and send rewards meant for holiday-use in early to mid-December.

Transparency. Budgets are under a microscope, and teams want to see what was sent, what was claimed and what happens to value that wasn’t. If we know, you know. 

The holidays move fast. A reward that arrives on time and goes toward something people actually need is the one they remember in January.

More from Retail Insider:
Loblaw Pushes Back on Supplier Price Hikes as No Frills and Maxi Expansion Accelerates

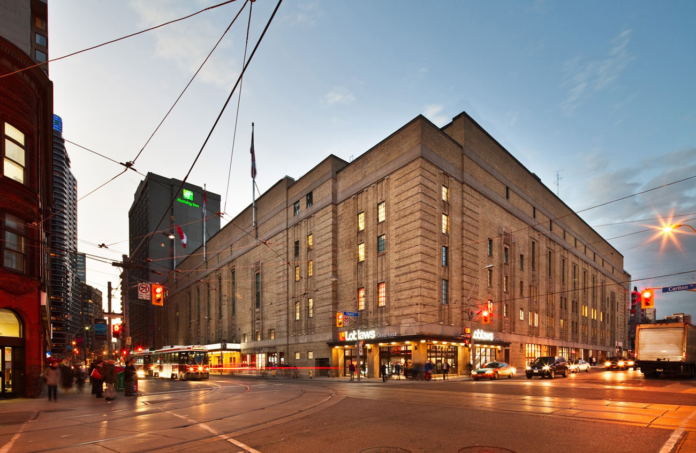
Loblaws at Maple Leaf Gardens in Toronto. Photo: Loblaws

Loblaw Companies Limited says it has successfully challenged hundreds of millions of dollars in proposed supplier cost increases during 2026, as Canada’s largest grocery retailer faces renewed wholesale pricing pressure while expanding its No Frills and Maxi discount operations.

In its October Food Inflation Report, released October 26, Loblaw said the dollar value of proposed fourth-quarter supplier increases was 120% higher than a year earlier, despite the number of requests declining 35%. The company did not disclose their total value.

The announcement comes as grocery inflation moderates. Food prices rose 1.7% year-over-year in September, down from 2.8% in August, although grocery prices remained approximately 33% higher than in September 2020.

For Loblaw, these negotiations coincide with substantial investment in discount grocery, where competitive shelf prices are central to attracting increasingly price-conscious consumers. The company’s expanding discount network gives wholesale purchasing terms greater strategic importance.

No Frills and Maxi Become Central to Loblaw’s Growth

Loblaw President and CEO Per Bank has prioritized discount grocery since taking over in 2023, expanding smaller-format stores and investing in price-focused banners.

In an October 25 interview with The Canadian Press, Bank said discount banners represented approximately 40% of Loblaw’s grocery footprint. He suggested discount could eventually account for more than half its food business, although this remains an executive expectation rather than a formal forecast.

Bank also said the number of Loblaw stores measuring less than 20,000 square feet had grown from approximately 43 when he became CEO to more than 75. These formats allow expansion into smaller communities and urban neighbourhoods where conventional supermarkets may be less economical.

In September, Loblaw announced approximately $1.2 billion in planned capital expenditures for the remainder of 2026, part of a broader $2.4-billion annual program. Grocery expansion is focused predominantly on No Frills and Maxi, alongside investments in pharmacies and renovations.

The company expected approximately 75 new locations across its grocery and pharmacy businesses during 2026 and renovations to more than 190 existing stores. No Frills reached its 350th Canadian location in October.

Loblaw is also experimenting with smaller assortments and updated formats. A No Frills in Dutton, Ontario, carries approximately 4,000 products, while a Komoka location features expanded fresh and prepared-food offerings.

Smaller stores, private-label merchandise and disciplined assortments can help support discount economics. Wholesale purchasing costs remain important because higher supplier prices can affect product margins, promotional flexibility and the retailer’s ability to maintain its value positioning.

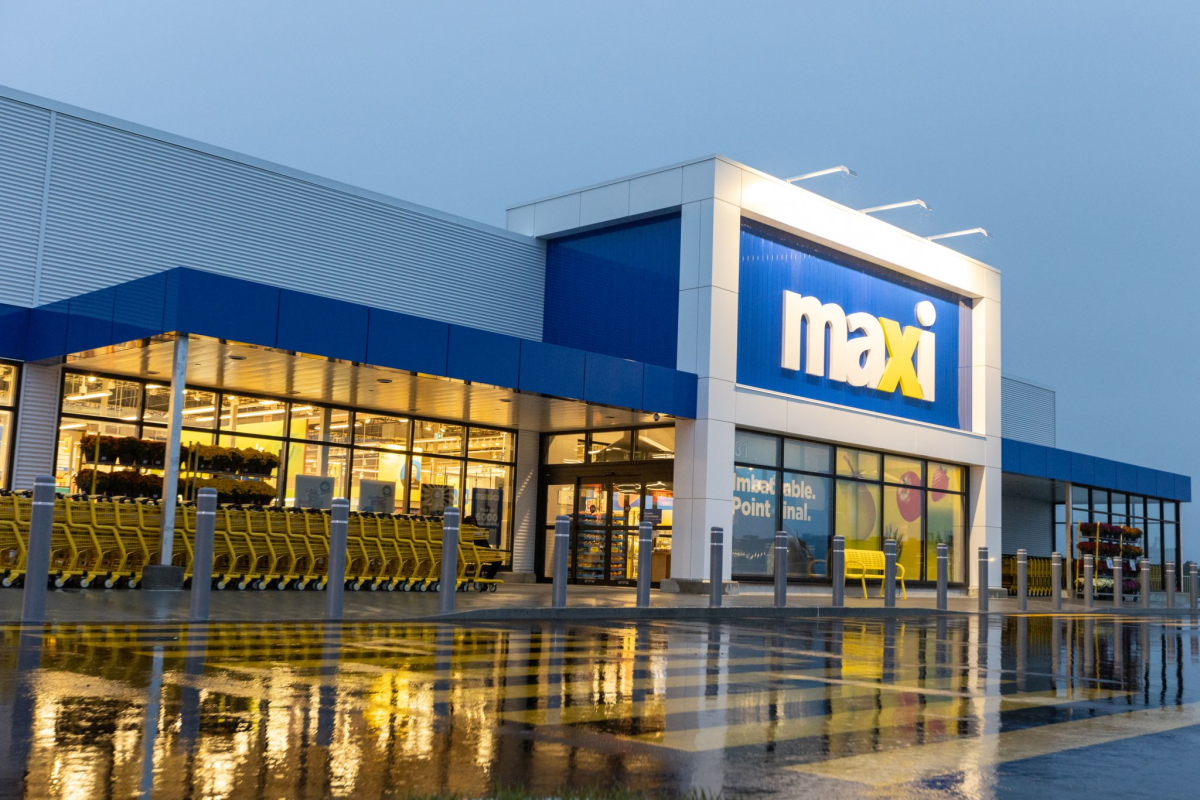
Maxi store. Photo: Loblaw Companies

Manufacturers Face Higher Freight, Commodity and Tariff Costs

Loblaw attributes the latest supplier requests to renewed transportation, commodity and tariff pressures. According to its October report, eight of the 10 commodities it tracks increased during September. Wheat rose 5.8%, rice increased 11.3%, and crude oil climbed 19.4% month-over-month.

Loblaw also reported Canadian diesel costs approximately 70% higher than in February. Transportation expenses affect agricultural production, food manufacturing, distribution and deliveries to stores.

In the Canadian Press interview, Bank said one major supplier had requested a 15% increase that Loblaw was resisting. He expressed frustration that consumers often blame grocery retailers for rising shelf prices, even when wholesale increases originate with manufacturers.

Tariffs add another complication. Loblaw estimates Canada’s latest retaliatory measures could affect approximately 2,500 products, compared with 5,000 in 2025, although applicable rates could reach 50%, versus 25% previously.

The company is managing supplier submissions involving approximately 2,000 products and $32 million in proposed annualized increases. These include food and non-food categories such as cheese, baking mixes, dough products and haircare.

Loblaw has also resumed identifying some tariff-affected products through its in-store T symbol, currently appearing on a few dozen items.

Manufacturers can face legitimate increases in ingredients, packaging, labour and transportation costs even as overall grocery inflation slows. Those pressures vary by supplier, and a retailer’s decision to challenge an increase does not establish whether the request was justified.

Sylvain Charlebois Examines Seasonal Grocery Price Negotiations

The timing of Loblaw’s announcement is relevant given the established structure of supplier-retailer negotiations in Canada’s grocery industry.

In a November 2025 Retail Insider column, Dalhousie University food policy researcher Sylvain Charlebois examined recurring increases in grocery inflation during October and February.

Drawing on 25 years of Statistics Canada data, Charlebois linked these patterns partly to wholesale pricing negotiations and the traditional holiday price-increase blackout period, during which major grocers ask suppliers to postpone increases until February.

He also discussed the 2022 Loblaw-PepsiCo dispute, when disagreements over wholesale pricing temporarily disrupted product availability. His analysis provides historical context, although it predates Loblaw’s October 2026 announcement and does not assess these specific requests.

New concept No Frills store in Komoka. Image: Loblaw Companies

Grocery Code Establishes New Framework for Commercial Disputes

The latest negotiations are taking place during the first year of full implementation of Canada’s Grocery Code of Conduct, developed to improve commercial relationships throughout the grocery supply chain.

According to the Office of the Grocery Sector Code of Conduct, the voluntary Code became fully operational January 1, 2026, including a dispute-resolution process intended to improve transparency, predictability and fairness.

Loblaw, Empire, Metro, Walmart Canada and Costco Canada are registered under the framework, alongside numerous suppliers and other retailers.

The Code addresses commercial conduct and dispute resolution but does not eliminate price negotiations or require retailers to accept proposed increases. There is no established evidence that Loblaw’s latest negotiations constitute a violation or have generated formal complaints.

What the Negotiations Mean for Canadian Grocery

Loblaw’s purchasing scale gives it considerable negotiating leverage compared with smaller grocery operators that may have fewer alternatives when suppliers seek higher prices.

Its financial performance also provides context. In its second-quarter results, Loblaw reported revenue growth of 4.1% and adjusted diluted earnings-per-share growth of 11.9%.

Those results include its broader operations and do not establish the profitability of individual products or discount banners. Strong corporate earnings alone cannot determine whether particular supplier increases are commercially justified.

Independent grocers may face greater difficulty absorbing wholesale increases while competing against national discount chains. Smaller operators often have less purchasing leverage and fewer opportunities to offset rising costs through private-label programs or operating efficiencies.

For consumers, the outcome depends on what happens after negotiations conclude. Resisting a supplier increase may prevent additional pricing pressure, but it does not necessarily reduce existing shelf prices or establish a measurable saving.

As Loblaw expands No Frills and Maxi, supplier negotiations will remain important to its competitive position. Their outcomes will also influence how rising production and distribution costs are shared among manufacturers, retailers and Canadian households.

More From Retail Insider

Daily Synopsis: October 28, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 15 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.

Canadian Tire has expanded its Saskatoon Preston Crossing store by over 50% to 104,000 square feet, enhancing product assortments, department sizes, and adding a permanent greenhouse. Toronto’s Distillery Winter Village is expanding its retail and food offerings for 2026, adding two new marketplaces featuring Canadian independent businesses and bringing Quince on board as title sponsor.

Pür & Simple celebrates a decade with its 75th restaurant and first downtown Toronto location, targeting urban professionals through creative breakfast options and a strong focus on guest experience. Lululemon’s recent partnership with GANNI and its dance-centric campaign mimic strategies used by Gap to refresh the brand via cultural relevance and community events. In contrast, Kastners in Cornwall will close after more than 100 years, illustrating the pressure independently owned apparel retailers face in smaller cities amid shifting shopping patterns and competition from fast fashion and online channels.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

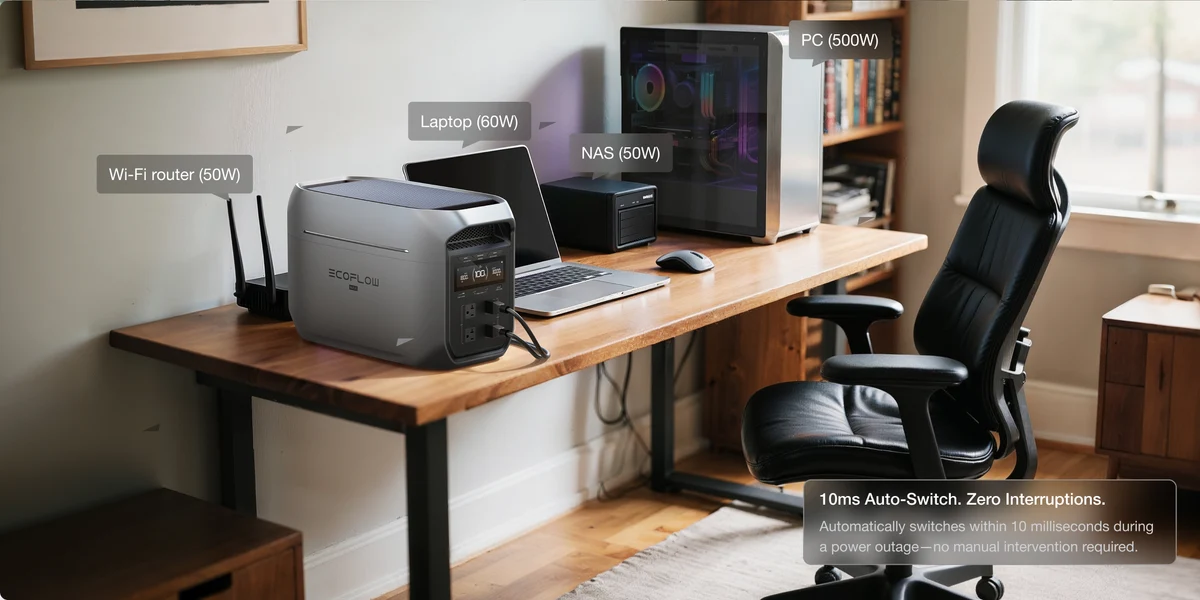
Solar Generator vs. UPS: Which Is Better for Home Office Backup?

A UPS is often the better starting point when the priority is keeping a desktop computer or storage device running through a brief power interruption. A solar generator can be useful when you need enough stored energy to continue working through a longer outage. Some current power stations also provide UPS functions, so the exact model matters more than the category name.

For a home office, separate two requirements: surviving the moment power disappears and having enough energy to keep working afterward. A system can meet one requirement while falling short on the other.

Start With the Equipment You Need to Protect

A laptop already has an internal battery. During an outage, its immediate problem may be a powered-off monitor, docking station, modem, or router.

A desktop computer has no equivalent built-in reserve. Its power supply must tolerate the backup system’s handover. Storage equipment may also need enough time and suitable communication to shut down properly.

Write down which devices need uninterrupted operation and which merely need power available later.

Include the complete working setup. A computer that remains on is less useful if its display loses power or the network equipment restarts. Conversely, battery capacity spent keeping an unnecessary peripheral running reduces time available for essential equipment.

This gives you a clearer buying brief than simply asking for a battery large enough to power an office.

Understand What “UPS” Means for Switching

UPS designs do not all operate in the same way.

DesignHow it normally supplies equipmentWhat to check
Standby UPSUses utility power, then transfers to its inverter when requiredTransfer time and battery-mode waveform
Line-interactive UPSUses utility power with voltage regulation, transferring to battery when neededRegulation range, transfer behaviour, and output compatibility
Online double-conversion UPSNormally supplies equipment through its inverter continuouslyOperating mode, bypass behaviour, noise, and efficiency
Power station with a UPS or backup modeOperation depends on the particular designSupported use, actual transfer specification, and bypass limits

An online double-conversion UPS has no transfer interruption when moving from normal double-conversion operation to battery operation. Standby and line-interactive designs generally involve a handover.

Some modern power stations also have fast transfer specifications suitable for supported computer applications. Others provide emergency backup with a longer interruption.

Avoid assuming that every product marked “UPS” behaves identically, or that every solar generator will restart a computer. Compare the documented behaviour with the needs of your actual equipment.

A pure sine-wave output can help establish electrical compatibility, but it does not by itself prove that a computer will tolerate the transfer.

Compare Runtime at Your Actual Load

Output power and stored energy answer different questions.

The watt rating establishes how much equipment the source can supply at once. A UPS may also have a volt-ampere rating; connected equipment must remain within both applicable limits.

Runtime depends on the load and available battery energy.

Suppose an illustrative office uses:

EquipmentAssumed operating power
Desktop computer140W
Monitor30W
Modem and router20W
Total190W

With an assumed delivered AC-energy budget of 800Wh:

800Wh ÷ 190W ≈ 4.2 hours

This is a worked estimate, not a product runtime claim. Computer demand changes with workload, and the backup source also has operating losses.

A solar generator can provide useful extended runtime when its available capacity and operating features suit the office. A UPS designed for external battery packs can also offer longer operation, so neither category has a universal time limit.

For a UPS, use the manufacturer’s runtime curve at a load close to yours. A product advertised as “1500VA” does not contain 1,500Wh of stored energy.

For a power station, distinguish nominal battery capacity from energy delivered at its outlets. A capacity figure alone does not include the effect of the actual load, settings, reserve level, and operating conditions.

Check Shutdown and Recovery Behaviour

Keeping equipment powered is only part of protecting work.

If an outage outlasts the battery, the computer or storage system still needs to stop safely. Some UPS units communicate with supported operating systems through USB or a network connection to initiate shutdown.

Some power stations offer comparable functions; others do not. Confirm compatibility with your equipment and software rather than assuming that a USB port provides power-management communication.

Also establish what happens when utility power returns. Does output resume automatically after battery depletion? Does the computer restart? Can the required backup settings operate without an internet connection?

For network equipment with a small load, check any automatic output timeout settings. A source that switches off while apparently idle may interrupt devices that need continuous power.

These details can be more valuable than a modest increase in battery capacity.

Decide How Much Solar Charging Helps the Office

The battery supplies equipment indoors. Solar panels need a suitable location and a compatible connection to replenish it.

For someone who primarily needs several minutes to save work and shut down, panels may add little to the immediate task. For someone trying to work through a longer outage, solar can contribute energy if deployment and weather permit.

Assess the charging opportunity you actually have. A shaded balcony, limited outdoor access, or a short winter charging window changes how useful panels will be.

Powering the modem and router also does not guarantee internet access. The provider’s equipment outside your home may have lost service. Before budgeting for a full working day, consider whether your work can continue offline or through another available connection.

Choose Around the Interruption You Can Accept

For a desktop or storage system where continuity and orderly shutdown come first, prioritise documented transfer behaviour, equipment compatibility, and working shutdown support.

For a laptop-based office that mainly needs hours of additional energy, a suitable power station may cover the job more directly. A UPS-capable model can also combine continuity with longer runtime where its specifications support the setup.

Save your work and test the chosen arrangement under a representative load. If you plan to use a UPS with another backup source upstream, confirm that the manufacturers support the combination.

The right purchase protects the way you work. Establish that requirement first, then pay for the runtime that makes the outage manageable.

Canadian Tire Expands Saskatoon Store by More Than 50% to 104,000 Square Feet

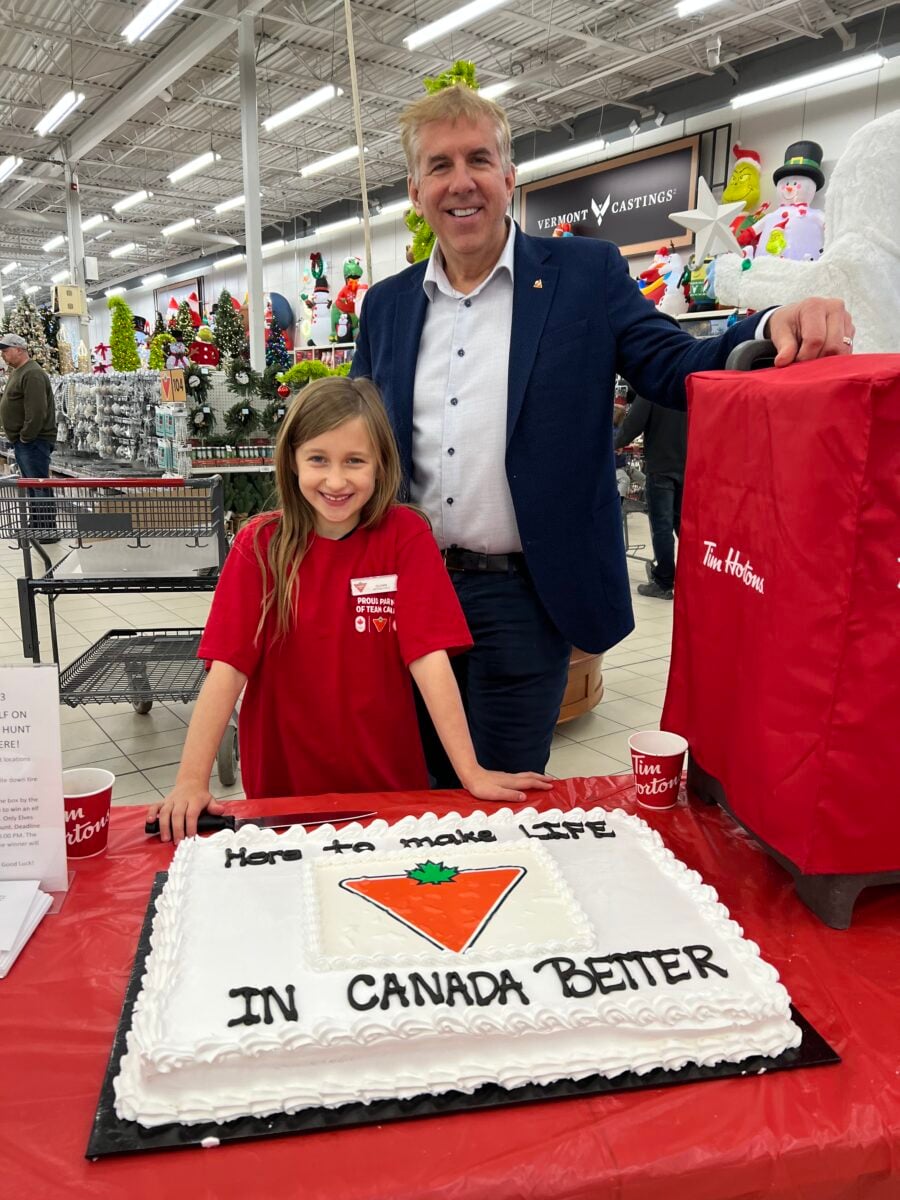
Canadian Tire has completed a major transformation of its Preston Crossing location in Saskatoon, increasing its footprint by more than 50%.

Following renovations that began in March, the store has expanded from 69,000 to 104,000 square feet, offering customers a significantly larger and enhanced shopping experience. The newly transformed location officially kicked off its grand reopening celebrations on October 22, with a week of special offers and community activities running through October 29.

Longtime Canadian Tire Dealer Dave Deplaedt, who has operated the Preston Crossing location since 2002, has overseen the transformation.

The investment represents a significant evolution for the Saskatoon location, reflecting Canadian Tire’s continued focus on enhancing its physical retail experience and serving the needs of local shoppers.

In an interview with Retail Insider, Deplaedt, spoke about the significant retail development in Saskatoon.

How does the investment reflect changing retail demand in Saskatoon?

The city of Saskatoon and the province of Saskatchewan continue to have a vibrant and growing economy, supported by new home construction and positive in-migration. With that growth comes increased demand for retail goods and for the products that help our customers with what we like to call the “jobs and joys” of life in Canada. Growth also brings increasingly busy lives. Customers want a shopping experience that is efficient, convenient and, above all, one they can trust to help them find the right products and solutions. Our goal with this investment was not simply to make our store bigger. It was to better position both the physical store and the overall shopping experience to meet those changing expectations.

Inside the store, that means wider, lower aisles that are easier to navigate, significant additions to our product assortment, more displays that allow customers to touch and experience products before making a purchase, and a substantially enhanced in-store inventory position. It also means maintaining customer-friendly return policies and, most importantly, providing helpful and friendly customer service when our customers need it.

But today’s retail experience extends well beyond the physical store. Customers increasingly want the flexibility to shop the way that works best for them. They can shop traditionally in-store, buy online and pick up their purchase through our product pickup warehouse, or have products shipped directly to their home.

Ultimately, this investment reflects our belief that as Saskatoon grows and changes, we need to grow and change with it. The expansion gives us the space, assortment, inventory and flexibility to serve more customers while making their shopping experience easier, more convenient and more enjoyable.

What are the main changes customers will notice in the expanded store, including new departments, product offerings or services?

One of the first changes customers will notice is the openness and visibility of the expanded store. From each of our three customer entrances, we have created lower aisles and improved sightlines that allow customers to see farther into the store and across more departments. This makes the store easier to navigate and creates a much more inviting approach to the overall shopping experience.

As customers move deeper into the store, they will find more specialized categories grouped together within departments in what we think of as a “store-within-a-store” approach. If your passion is gardening, barbecuing, power tools, garage organization, hockey, or hunting, for example, we have created distinct retail environments around each of those categories. The goal is to make those areas both inspiring for the enthusiast and easier to shop for someone simply trying to find the right product for the job.

Another major change is the amount of product we are now able to put directly onto the retail floor and, importantly, on display. We have always carried a significant SKU assortment, but space limitations previously meant that some of that assortment had to remain in our warehouse or couldn’t be properly showcased. The expansion has allowed us to bring much more of that product onto the sales floor, giving customers the opportunity to see, touch and experience products before making their purchase.

We’ve also significantly expanded the breadth and presentation of a number of key categories, including baby, toys, power tools, kitchen appliances, RV, barbecue and patio furniture. These departments now have substantially more space to showcase both the assortment and the products themselves.

Finally, one of the most visible additions is our majestic new permanent glass-enclosed greenhouse in the parking lot. It gives us the ability to better serve our green-thumb customers with a much stronger garden experience and to offer plants earlier in the spring and later into the fall.

Taken together, these changes are really about removing friction from the shopping experience. We want customers to be able to walk into the store, quickly understand where they need to go, discover products along the way, and have more opportunities to see and experience those products before they buy.

How much was invested in the renovation and expansion, and what were the biggest challenges involved in transforming the store while maintaining operations?

As we worked our way through the many moving parts of a year-long major expansion project, our top priority was maintaining our focus on the customer despite all the activity going on around them. Construction projects are notorious for impacting the customer experience as attention naturally shifts toward construction schedules and completion dates. We were determined not to let that happen here.

The scope of the project was significant. We temporarily removed approximately 10% of our existing retail floor to accommodate the new construction, moved key product categories multiple times, demolished an existing retail store, added 50,000 square feet of functional building space, relocated and added entrance doors, replaced all of the sidewalks, and constructed a permanent greenhouse in the parking lot. All of this was happening while we continued to operate the store and serve our customers every day.

What made it work was complete buy-in to a customer-first strategy from all of the key stakeholders. At Canadian Tire Corporation, that included Real Estate and Construction, Store Operations, Retail Planning,and Merchandising. Closer to home, we had an outstanding general contractor in Wright Construction. Their deep roots in the community gave them a real understanding of the importance a fully functioning Canadian Tire store plays in the everyday lives of our customers.

Most importantly, our store staff made the difference. We have an incredibly dedicated and resilient team of employees and managers who simply refused to allow the construction project to get in the way of their everyday customer-service goals. Through constant change, product moves, construction noise and disruption, they never lost sight of the customer.

And finally, our customers deserve a great deal of credit as well. They continued to show up and shop with us despite having other options that didn’t require navigating construction and an ever-changing retail environment. Fortunately for us, Saskatchewan has consistently produced some of the hardier folks in this country, and our customers weren’t deterred in the least by a little product movement and construction noise.

When I look back on the project, that may be what I’m most proud of. We didn’t just complete a major expansion. We found a way to transform the store while continuing to take care of the people the store exists to serve.

What trends are you seeing in customer shopping habits, population growth and demand for products that influenced the redesign and expansion?

We continue to see a significant number of young families and new homeowners within our community, and that has influenced a number of the decisions we made with this expansion. We have greatly expanded our baby and toy departments and invested heavily in categories that support home ownership and family life, including yard maintenance, gardening, home projects and children’s sports such as soccer and hockey.

At the same time, the shopping habits of our customers continue to evolve rapidly, and our goal is to meet our customers however they choose to shop.

The significant growth in online shopping means we need to provide a highly credible and convenient digital option. If a customer prefers to order online and pick up their purchase, our customer pickup operation allows them to do that quickly and easily. If they would rather have the product shipped directly to their home, we provide that option as well. Just as importantly, we’ve invested heavily in our inventory position so that we can fulfill as many of those customer needs as possible with immediacy. 

But as important as online shopping has become, we never want to lose sight of the customer who genuinely wants to see, touch, feel and learn about a product before making a purchase. That’s where this big, beautiful retail store comes into play. Everything we’ve done with this expansion has been designed to create a positive in-store shopping experience and to inspire our customers as they move through the store. We believe customers increasingly want more than simply a place to complete a transaction. They want shopping to be convenient, welcoming and, when possible, enjoyable. That’s why we’ve thought about some of the smaller details as well. Beyond our core product assortment, we’ve added things such as a cotton candy machine, customer-use mobility scooters, park benches throughout the store, bubble hockey and kiddie shopping carts. Individually they may seem like small additions, but collectively they help make the store more comfortable, accessible, engaging and fun for the entire family.

Ultimately, our strategy isn’t about choosing between online and bricks-and-mortar retail. It’s about giving customers the freedom to shop the way they want while creating an in-store experience that gives them a reason to come back time and again.

How does the Preston Crossing expansion fit into Canadian Tire’s broader strategy for its physical retail locations, and are there plans for further investments or expansions in the Saskatoon market?

Canadian Tire’s retail strategy is ultimately about meeting the consumer where they want us to be, and I think the expanded Preston Crossing store and the business operation surrounding it accomplish exactly that. Canadian Tire Corporation’s True North strategy places a strong emphasis on strengthening customer relationships, growing the core retail business and using the collective strengths of the organization to better know, reward and serve Canadians. At the store level, our expansion is a very tangible expression of that strategy. 

We’ve made a significant investment in the physical retail experience because we continue to believe strongly in the importance of the store. We’ve expanded our assortment and inventory, created better sightlines and easier navigation, added considerably more product displays and developed stronger destination categories throughout the store. At the same time, we’ve invested in the infrastructure required to serve customers who increasingly want to shop differently, whether that’s traditionally in-store, ordering online for pickup, or having products shipped directly to their homes. For us, it isn’t about choosing between physical and digital retail. It’s about bringing those experiences together and giving the customer the ability to interact with Canadian Tire in whatever way works best for them. 

I also think Preston Crossing demonstrates the continuing importance of having large, relevant and inspiring physical stores in the communities we serve. Customers can research products online, but there remains tremendous value in being able to walk into a store, see and touch the product, compare the options, speak with someone who can help, and walk out with what you need. 

As for additional investment in the Saskatoon market, I can’t speak to future plans on behalf of Canadian Tire Corporation. What I can say is that we have tremendous confidence in Saskatoon and Saskatchewan, and this expansion represents a significant long-term investment in serving this growing market. Our immediate focus is on making the most of what we’ve built at Preston Crossing and ensuring that the investment delivers the kind of customer experience we envisioned from the beginning.

More from Retail Insider: