Year over year, prices for gasoline rose at a slower pace in August compared with July, putting downward pressure on the all-items CPI. Excluding gasoline, the CPI rose 2.4% in August, after increasing 2.2% in July. In August, the slowdown in gasoline prices on an annual basis was offset by higher prices for travel tours and rent, said the federal agency.
The CPI fell 0.1% month over month in August. On a seasonally adjusted monthly basis, the CPI rose 0.2%, it added.
“Year over year, prices for travel tours rose at a faster pace in August (+26.1%) compared with July (+15.2%), partly due to a base-year effect. Canadian travel to the United States declined sharply in 2025, putting downward pressure on prices for airfares and travel tours. Given that this decline has now stopped affecting the 12-month price movement, along with the introduction of fuel surcharges amid higher prices for jet fuel, upward pressure has been put on the travel tours index. On a monthly basis, prices for travel tours fell 2.9% in August,” said Statistics Canada.
Gustavo Fring photo
“Prices for gasoline rose 22.8% year over year in August, following a 25.7% increase in July. Despite the year-over-year slowdown, prices for gasoline remained elevated, as the conflict in the Middle East continued in August.
“On a year-over-year basis, consumers paid less for clothing in August (-1.1%) compared with July (+0.9%). The decline was driven by lower prices for men’s clothing (-2.3%) and children’s clothing (-1.9%), following increases of 2.0% for men’s clothing and 4.0% for children’s clothing in July. Conversely, women’s clothing was unchanged (+0.0%) year over year in August, after falling 0.7% in July, moderating the decline in clothing prices.”
StatsCan said price growth for food purchased from stores continued to slow in August, rising 2.8% year over year after increasing 3.1% in July. For the first time since July 2024, grocery price growth increased at a slower pace than the all-items CPI in August 2026.
“Prices for dairy products led the deceleration in grocery prices; they rose 0.7% year over year in August compared with a 3.1% rise in July. Cheese and yogurt were the top contributors to the slowdown in dairy prices,” it noted.
“Smaller price increases for fresh or frozen pork (+1.6%), condiments, spices and vinegars (+0.7%) and fresh fruit (+4.7%) also contributed to the year-over-year slowdown in grocery inflation in August.
“Although prices for groceries decelerated this month, prices have increased 29.0% since August 2021.”
ali Shot80 photoAndrew GranthamLeslie PrestonBenjamin Reitzes
Headline inflation remained elevated in August, but core measures continued to show limited evidence that high energy prices are spilling over into wider inflationary pressure, said Andrew Grantham, Senior Economist, CIBC Capital Markets.
“The next Bank of Canada meeting is more than a month away and there is another CPI report to be released between now and that time, as well as monthly GDP and employment. We continue to expect the Bank will remain on hold at that time despite a possible energy-driven re-acceleration in headline inflation, due to the downside risks to growth emanating from US trade policy and with core measures of inflation giving policymakers comfort that higher energy prices are not translating into widespread inflationary concerns.”
Inflation held at the top of the Bank of Canada’s 1-3% control range in August. But also, as expected, the Bank of Canada’s (BoC) core inflation measures started to drift a bit above 2% in August as higher energy costs start to drive price increases in other areas of the economy, said Leslie Preston, Managing Director & Senior Economist, TD.
“Prior to today’s inflation reading, the 2-Year Government of Canada bond yield had risen over 40 basis points over the past month as markets moved to price in interest rate hikes from the Bank of Canada this year. We don’t think today’s inflation report supports this degree of tightening. Yes, core inflation is likely to move up in the coming months, but off a very low level, and is expected to remain with the BoC’s comfort zone. That is driven by our expectations for modest growth in Canada, as the economy continues to be weighed down by the uncertainty and tariffs on our exports to the U.S.”
Benjamin Reitzes, Managing Director, Cdn Rates & Macro Strategist, said: “Nothing here to push the BoC closer to a rate hike, which should tame market speculation around a potential move in October. However, oil prices are a real problem here, up nearly 5% again today. That’s going to drive angst among policymakers and concern that it’s just a matter of time before we get some spillover into broader inflation.”
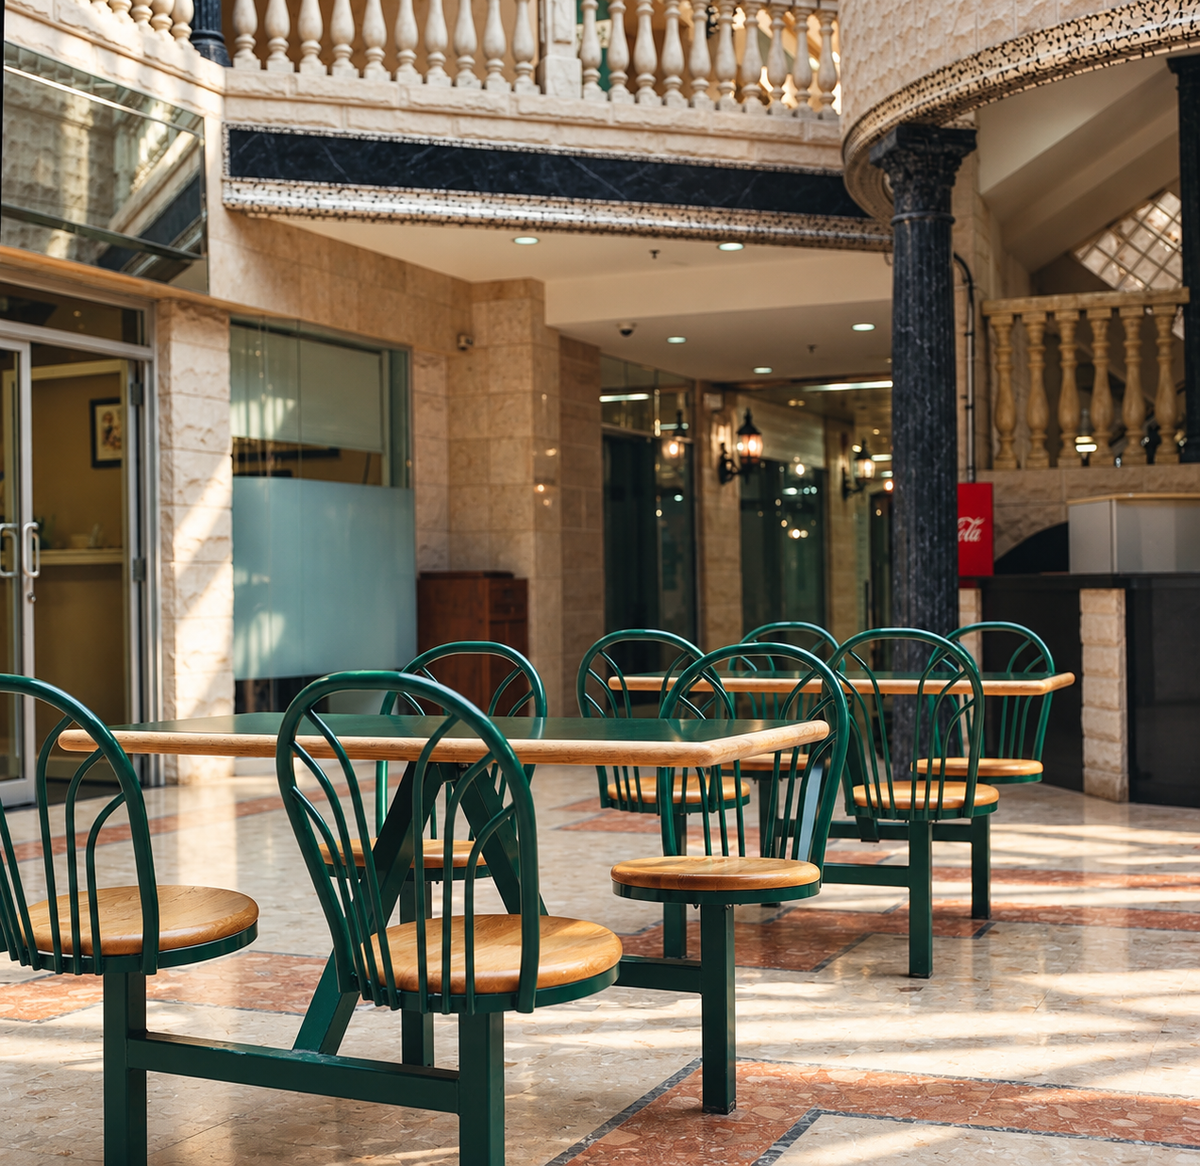
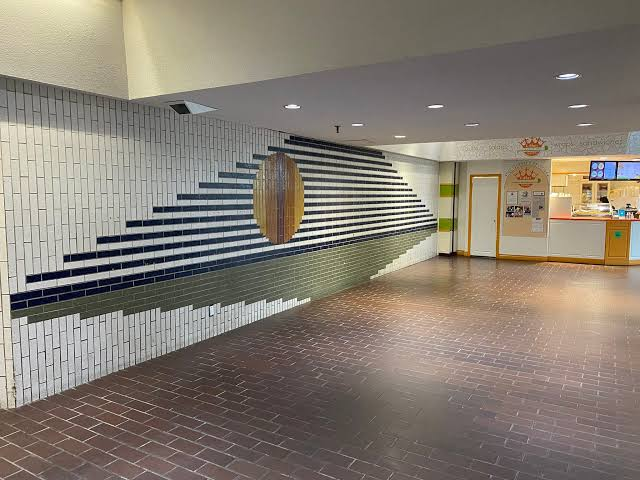
Cumberland Terrace in Toronto. Photo: Scott Bryant Photography
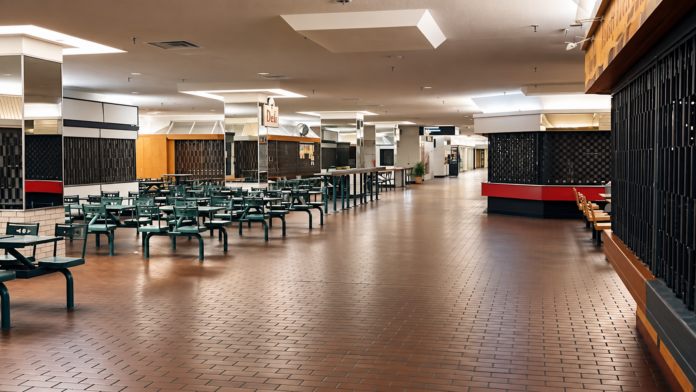
Shopping malls, underground corridors, aging buildings and places caught somewhere between their original purpose and whatever comes next are becoming destinations in their own right through Liminal Assembly, the Toronto-based project founded by Aryeh Bookbinder.
Aryeh Bookbinder.
The concept is expanding this month through LoiterFEST 2026, a collection of events examining overlooked, transitional and sometimes deeply nostalgic places. Programming began September 4 and continues through mid-September, with events in Toronto and elsewhere in Ontario, along with experiences reaching Moncton and Los Angeles. Walking tours, a liminal-space photo contest, a book club, scavenger hunts and other excursions are built around places people might otherwise pass through without giving them much thought.
Retail environments remain prominent. A September 5 field trip with millennial.ca began at Dufferin Mall, while a September 13 excursion led by Dan Seljak, called “The Malls: Highway 427’s Backrooms,” is scheduled to depart from Kipling Station. Liminal Assembly is also hosting a September 16 excursion through the PATH beneath Toronto’s financial district.
For Bookbinder, the expanding festival represents the evolution of an idea that initially gained attention through tours of unusual and declining shopping centres around the Greater Toronto Area. Liminal Assembly has taken participants into malls and commercial properties that sit outside conventional definitions of a successful retail destination, encouraging visitors to pay attention to architecture, history, remaining businesses and the emotional responses these environments can produce.
Retail Insider previously spoke with Bookbinder as interest grew around Cumberland Terrace in Toronto’s Bloor-Yorkville neighbourhood. The experience demonstrated something he has continued to explore: aging commercial properties can attract considerable interest because traces of their earlier identities remain visible.
Opening Liminal Assembly to Other Organizers
The latest evolution extends the concept beyond experiences led by Bookbinder himself. LoiterFEST provides an umbrella under which other organizers can propose events based on their own interpretations of liminal places, allowing the idea to spread well beyond the locations Bookbinder could explore on his own.
“I’d love for people who are serious about potentially running their own events to reach out,” he told Retail Insider. “They can submit a concept, and I’m accepting almost everyone with the idea that I can help them make it great.”
That approach is visible across the festival calendar. Niagara Walking Society hosted a “Slabtown Saunter,” while Mustafa Zebuun is behind a liminal-spaces photo contest in London, Ont. Programming also includes a tour of the Westin Bonaventure Hotel in Los Angeles and an exploration of forgotten areas of Moncton, while events around Toronto and Waterloo further broaden the geographical reach of the concept.
The expanding roster makes Liminal Assembly increasingly difficult to define simply through its “dead mall” excursions. Shopping centres remain important to Bookbinder, but the broader subject is the built environment and the way people relate to places that appear suspended between eras, purposes or identities.
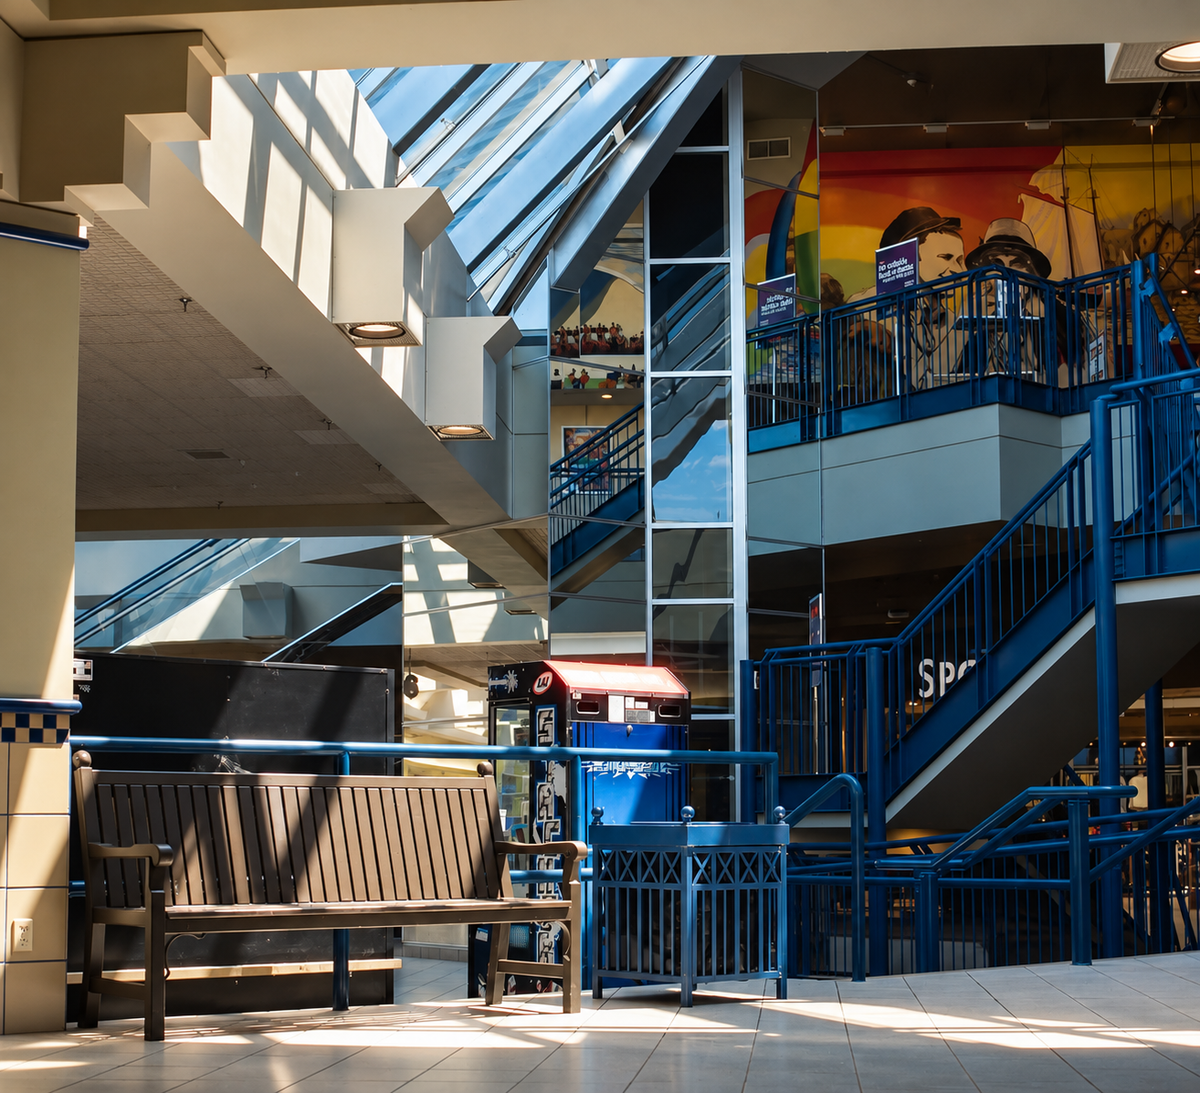
Photo: Scott Bryant Photography
Growing Up as a ‘Mall Baby’
Bookbinder’s interest in shopping centres is personal. He grew up near Promenade and Centerpoint malls north of Toronto and describes himself as a “mall baby.”
“Malls were places where I would run into my grandmother, run into my cousins and just be surrounded by adults talking,” he said. Some of his earliest spatial memories are tied to mall interiors, including details as ordinary as where buttons were positioned inside an elevator.
Promenade, in particular, made an impression. Bookbinder remembers an environment that once felt elaborate and almost enchanted, with architectural elements, fountains and greenery forming part of the experience.
Those memories help explain why Liminal Assembly’s mall excursions can resonate with people who may have little conventional interest in architecture or commercial real estate. A brick floor, old railing, fountain, particular type of lighting or even the proportions of a corridor can summon memories that have little to do with shopping itself.
During the Retail Insider interview, the conversation turned to whether that reaction comes from architecture, visual cues, smells or other sensory associations. There may be no single answer. A mall that has changed relatively little over several decades can function as a physical archive, confronting visitors with details they may not have consciously remembered until they see them again.
Bookbinder believes the growing fascination with nostalgic environments reflects something deeper than fondness for old architecture.
“People are yearning for the past, but if you go a little deeper, they’re yearning for innocence,” he said.
He points to the extraordinary pace of technological change, including the internet and artificial intelligence, as part of the environment in which that yearning is developing. For Bookbinder, nostalgia can offer adults a temporary connection with an earlier period of their lives, with the physical environment acting as a trigger.
The experience can be surprisingly emotional. Someone entering an older mall may encounter a visual cue associated with childhood, family members or a period of life they had largely stopped thinking about.
Bookbinder raised another intriguing question during the interview: whether the stronger reaction comes from recognizing how much a place has changed or discovering how little it has changed.
“When you notice how little something has changed, that’s when you really notice how much you’ve changed,” he said.
That idea sits close to the heart of Liminal Assembly. The buildings matter because of the memories and associations people bring into them.
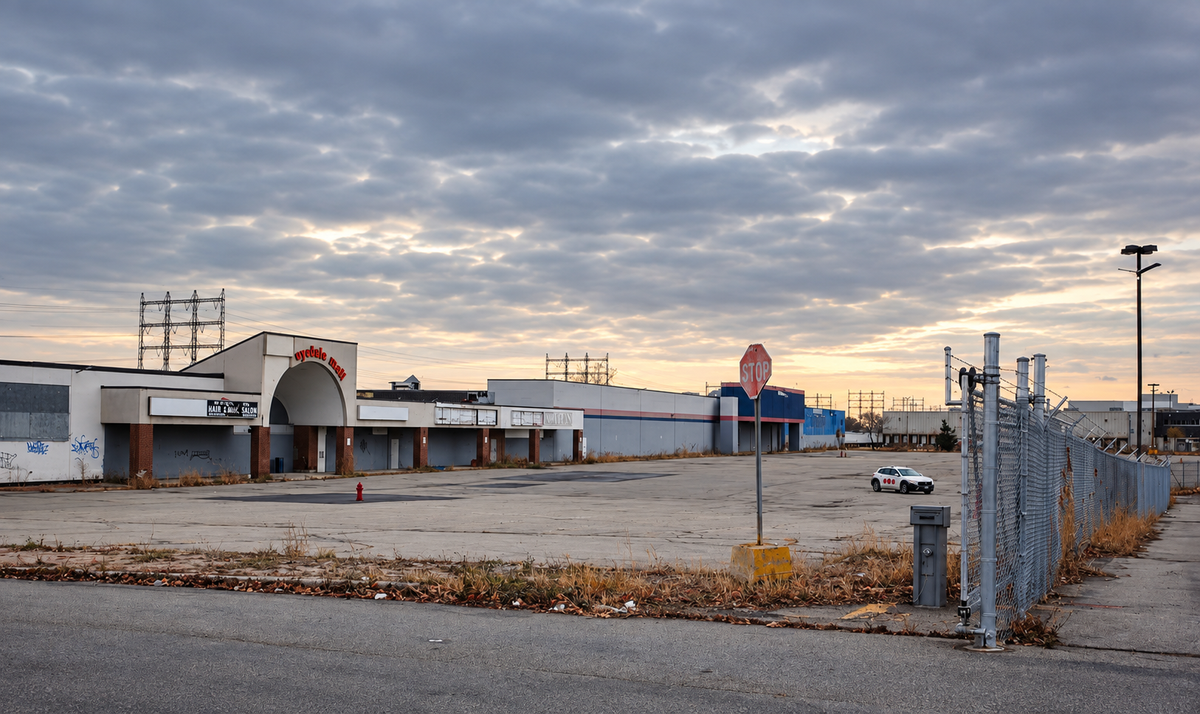
Shopping centre in Coburg, ON. Photo: Scott Bryant Photography
When Malls Were Places to Linger
Bookbinder’s childhood recollections highlight another dimension of shopping centres that has become increasingly relevant to landlords and retail strategists: malls have long functioned as social infrastructure. For generations of Canadians, a shopping centre could be somewhere to spend hours without having a precise objective.
People shopped and ate while also meeting friends, sitting near fountains, watching other people, bringing children and unexpectedly encountering neighbours. Older centres sometimes devoted substantial areas to landscaping, seating, fountains and architectural gestures that contributed to the overall environment, while many have subsequently been renovated as consumer expectations, leasing economics, accessibility requirements and design preferences evolved.
Bookbinder is particularly interested in details that survived those changes. During the interview, the discussion moved through Toronto examples where older brickwork, hallways and unusual layouts remain embedded inside otherwise contemporary commercial environments.
This is also where the term “loitering” takes on a different meaning. Liminal Assembly participants are encouraged to explore respectfully and support businesses operating in the places they visit, while avoiding restricted areas or behaviour that could make property operators uncomfortable.
Bookbinder said that relationship works particularly well when participants also become customers.
“They’re there to buy,” he said. “They’re buying so they can loiter.”
For these visitors, lingering becomes part of the attraction.
The idea has particular relevance as Canadian shopping-centre owners work through another period of change in physical retail. Former department stores, oversized retail units and other vacancies can remain in transition for extended periods while landlords pursue new tenants, subdivisions or larger redevelopment plans.
Temporary entertainment, cultural and recreational uses can put some of that space back into circulation while longer-term plans take shape. A current Toronto example is unfolding at Woodbine Mall, where SUSO Skate Co. plans to open a roller-skating pop-up on September 25.
SUSO has opened more than 15 pop-ups in vacant retail spaces across the GTA and has welcomed more than 250,000 skaters since 2021. Co-founder Henry O’Brien previously told Retail Insider that the model can provide landlords with community activity, foot traffic and increased dwell time, while flexible leasing allows SUSO to occupy space that might otherwise remain vacant.
Woodbine is particularly relevant because of the nostalgia surrounding the mall and its longstanding Fantasy Fair indoor amusement park. Bookbinder connected with the SUSO team after recognizing the overlap between its use of former retail space and his own interest in liminal environments.
The concepts operate differently, but both point toward a question confronting commercial real estate: what can a property become during the period between its previous use and its next one? A former department store can become a roller rink, an aging mall can become the subject of an excursion, and an underground concourse can become an experience when people are encouraged to slow down and look at their surroundings differently.
For property owners, temporary activation can generate traffic and activity while preserving flexibility over the longer-term future of a site. It can also reveal forms of demand that conventional leasing strategies might overlook.
Photo: Scott Bryant Photography
Technology Helping People Meet Offline
Liminal Assembly is also changing the digital infrastructure it uses to bring participants together. Bookbinder has moved his events from Eventbrite to Wygo, a Canadian platform focused on helping community organizers create and manage in-person events.
He told Retail Insider that he likes the emerging nature of the platform because participants currently have to make a deliberate effort to find some of the experiences listed there. For a project built around people actively seeking unusual experiences, Bookbinder sees that selectivity as an advantage.
Wygo was co-founded in 2023 by University of Waterloo systems design engineering graduates Jocelyne Murphy and Christopher Oka. The company secured nearly $1.6 million in pre-seed funding in 2026 from investors including N49P, StandUp Ventures, Garage Capital, Zero 21 Partners, Backbone Angels, Good Future and Shopify CEO Tobi Lütke.
The platform helps organizers create events, attract attendees and manage event finances. Its growth comes amid rising demand for in-person social experiences following the pandemic.
Digital tools are playing an interesting role in the renewed interest in physical gathering. They can help people discover reasons to leave their screens, enter unfamiliar places and spend time with people they might otherwise never meet.
The years following pandemic restrictions produced extensive discussion around “revenge shopping” and travel as consumers returned to activities that had been inaccessible or constrained. Bookbinder sees another version developing around social interaction.
During a discussion about the proliferation of in-person events, social clubs, dating concepts and other businesses encouraging people to meet physically, he offered a phrase for what may be happening: “revenge meetups.”
The idea is straightforward. After years in which digital communication became deeply embedded in work and social life, there remains considerable appetite for experiences built around being physically present with other people.
That matters for retail because stores, malls, restaurants and commercial districts ultimately depend on people wanting to leave home. An expanding ecosystem of offline communities can create additional reasons for them to do so, sometimes with relatively simple programming rather than elaborate permanent attractions.
In the case of Liminal Assembly, the experience can be as straightforward as a group of people agreeing to explore the same strange building together.
Cumberland Terrace in Toronto. Photo: Liminal Assembly
Cumberland Terrace and Yorkville’s Layers of History
Few places illustrate Bookbinder’s interest in accumulated commercial memory as clearly as Cumberland Terrace. The underground Toronto shopping centre became part of Yorkville during a period of significant development in the neighbourhood, and portions of the property retained architectural details capable of immediately evoking another era.
Cumberland Terrace also existed within a very different Yorkville social ecosystem. TIFF activity was once heavily concentrated in the neighbourhood, with the festival’s operational base spread around Cumberland Terrace and nearby hotels and film screenings taking place at venues including Cumberland Cinema and the Varsity Theatre.
Bookbinder said former Cumberland Terrace merchants have told him that actors, broadcasters and other festival personalities would pass through the shopping centre, including people collecting tickets during TIFF. Those recollections are especially timely as Toronto again hosts the film festival this month.
The stories illustrate how commercial properties accumulate histories that can be almost invisible to someone encountering them decades later. One visitor may see dated brickwork and an obsolete retail layout, while another remembers a restaurant, a former retailer, an afternoon with a parent or the excitement surrounding the film festival.
Liminal Assembly is interested in the distance between those experiences.
Experiencing Places Before They Change
Buildings require investment, cities evolve and commercial properties need to respond to changing economic conditions. Liminal Assembly’s approach is to pay attention to what exists during that process of change.
A tour can document an architectural detail before renovation, bring people into businesses that remain open and create another layer of memory around a property. Photography and storytelling can preserve pieces of an environment even when the physical setting eventually changes or disappears.
LoiterFEST expands that idea by allowing organizers in different cities to identify and interpret places within their own communities. The subject can be a mall, hotel, underground walkway or another environment that has somehow fallen between familiar categories.
Sometimes an older building makes people aware of how dramatically their city has changed, while other places reveal how much of the past remains hidden in plain sight. And occasionally, as Bookbinder observed, encountering something unexpectedly unchanged becomes a reminder of how much the visitor has changed instead.
LoiterFEST continues through September, with upcoming events and information on submitting an event concept available through Liminal Assembly’s calendar on Wygo. Bookbinder hopes people with serious ideas for unusual gatherings will reach out and help extend the concept into places and communities Liminal Assembly has yet to explore.
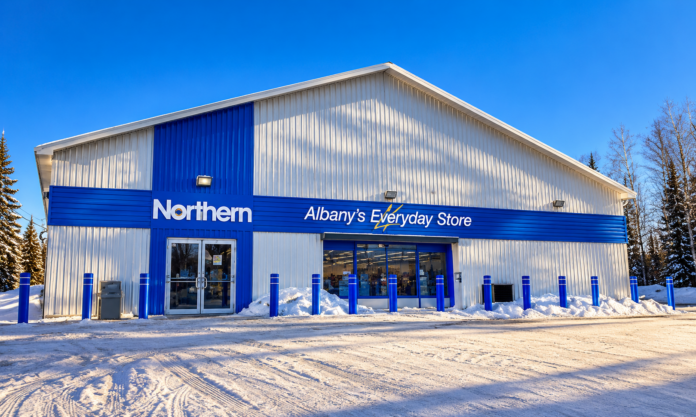
The North West Company is seeing increased consumer spending in parts of Northern Canada as compensation payments from the $23.34-billion First Nations Child and Family Services and Jordan’s Principle settlement reach more communities.
Canadian same-store food sales increased 7.4% in the retailer’s second quarter, while general merchandise sales rose 7.5%. Higher prices related to fuel and freight costs contributed to the gains, along with government benefit payments and increased spending associated with First Nations settlement payments.
The Winnipeg-based retailer said individuals in 54 of the 63 affected communities it serves have now received settlement funds. Payment activity increased in late July and into August, although the number of payments remains relatively low in many communities. North West expects distributions to increase through the second half of 2026 and remain a factor in its Canadian business for several years.
Settlement Payments Reach More Northern Communities
The Federal Court approved the $23.34-billion settlement in 2023 to compensate First Nations children and families harmed by discriminatory federal funding of First Nations child and family services and the federal government’s approach to Jordan’s Principle.
More than $1.2 billion had been distributed to over 30,000 eligible claimants by August 17, according to the Assembly of First Nations. As of August 31, the settlement administrator had received 124,409 Removed Child Class claims and 72,661 Removed Child Family Class claims.
Eligible Removed Child Class claimants can receive up to approximately $40,000 in compensation, with additional payments possible depending on individual circumstances. Seven additional settlement classes have yet to open their claims periods, while some eligible recipients who are minors will generally have to reach the age of majority before receiving compensation.
North West has been tracking settlement activity across its Canadian store network for several quarters. President and CEO Dan McConnell told analysts that the pace of payments picked up late in the second quarter.
“We’re pleased with the capture rate for sure. It’s in line with our expectations,” McConnell said on the earnings call. He added that spending was occurring in categories the company had expected to benefit, with activity increasing from late July into August.
North West has been cautious about forecasting the timing of payments. McConnell acknowledged that management has had limited success predicting their cadence and stopped short of providing a sales forecast tied to the settlement. The company nevertheless expects payment activity to increase, pointing to the large number of submitted applications compared with the relatively small number of payments it has observed in many of the communities it serves.
General Merchandise Sales Strengthen
Canadian general merchandise same-store sales increased 7.5% during the quarter, slightly exceeding the 7.4% increase in food. North West also reported strength in motorized merchandise, with McConnell confirming when questioned by an analyst that Canadian stores were participating in those gains.
The company did not say settlement recipients were responsible for the increase in motorized sales, nor did it disclose how much Canadian sales growth could be directly attributed to settlement payments. It did, however, say spending among recipients was developing broadly in line with expectations.
North West has significant exposure to changes in consumer spending across remote Canadian markets. Its Northern banner operates 118 food and general merchandise stores, while NorthMart operates five larger stores serving northern regional centres. Many of these communities have small populations, limited retail competition and high transportation costs, meaning changes in household purchasing power can have a noticeable effect on local retail activity.
Higher Fuel Costs Push Up Prices
The increase in sales is occurring as North West deals with higher costs to supply its northern stores. Fuel-related freight expenses increased during the quarter, with Northern Canada particularly affected because of the distance and complexity involved in moving merchandise into remote communities.
North West has passed through much of the inflation to consumers. The company said higher fuel-related freight costs were passed through without additional markup, while targeted price investments were made on certain essential food items. That approach contributed to pressure on Canadian gross margins.
Consumers are noticing the increases. “The consumer reaction is negative,” McConnell said when asked about pricing during the call. “The people are certainly not pleased, as any of the Canadians are not pleased with the inflation that we’ve experienced recently.”
McConnell said much of the inflation has been passed through in Canada, with exceptions for some essential categories. Settlement payments are increasing purchasing power for some households at the same time fuel, freight, wages and other operating expenses are increasing the cost of serving those communities.
North West has not indicated that settlement payments themselves are contributing to higher retail prices. Management has instead identified fuel and freight costs as key sources of current pricing pressure, particularly in northern markets where transportation networks are longer and more complex.
North West Looks to Reduce Operating Costs
North West is working to offset some of those increases through its Next 100 operating program. Changes to merchandise assortment and procurement, expansion of private-label products and other operational improvements contributed positively to gross profit during the quarter. The company is also targeting further staff productivity improvements after labour costs increased.
Transportation is another focus. North West purchased a Basler BT-67 aircraft for its North Star Air operation during the quarter and expects to make additional aircraft purchases as part of its fleet renewal.
Management said owning additional aircraft will reduce the use of higher-cost leased planes while improving reliability, maintenance efficiency and capacity. The purchases contributed to a $40-million increase in planned capital expenditures for the year, although North West said the spending is opportunity-driven and does not represent a new normal level of annual capital investment.
Payments Could Affect Retail Spending for Years
The settlement is expected to remain a factor in North West’s Canadian business beyond 2026. Management expects distributions to increase during the second half of the year as more applications are processed. Additional settlement classes have yet to begin accepting claims, while payments to some younger recipients will occur after they reach the age of majority.
The timing remains difficult to forecast, and North West has not quantified the expected impact on future sales. Its second-quarter results nevertheless show that settlement distributions are becoming visible in consumer spending across its northern Canadian store network.
Billions of dollars in compensation remain to be distributed, giving North West a potential multi-year source of additional consumer demand across many of its Canadian markets. The retailer will be managing that demand against the high freight, fuel and operating costs that continue to define the economics of retailing in Northern Canada.
RBC has launched a redesigned Avion Rewards Travel platform that allows Canadians to book flights across more than 500 airlines and use Avion points for flights, hotels, car rentals and other travel.
The new platform brings several travel-booking functions into one interface and adds AI-assisted tools for tracking fares, predicting prices and alerting users when airfares fall.
The launch comes as Canadian travel spending rises, with RBC saying its spending data shows an 11.4 per cent year-over-year increase. The bank says the new platform is intended to give members more flexibility in how they book and redeem rewards while providing information to help them make travel decisions.
Members can track airfares in real time, receive automated price alerts and use historical pricing data to determine when they may want to book. The platform can also notify users when prices drop.
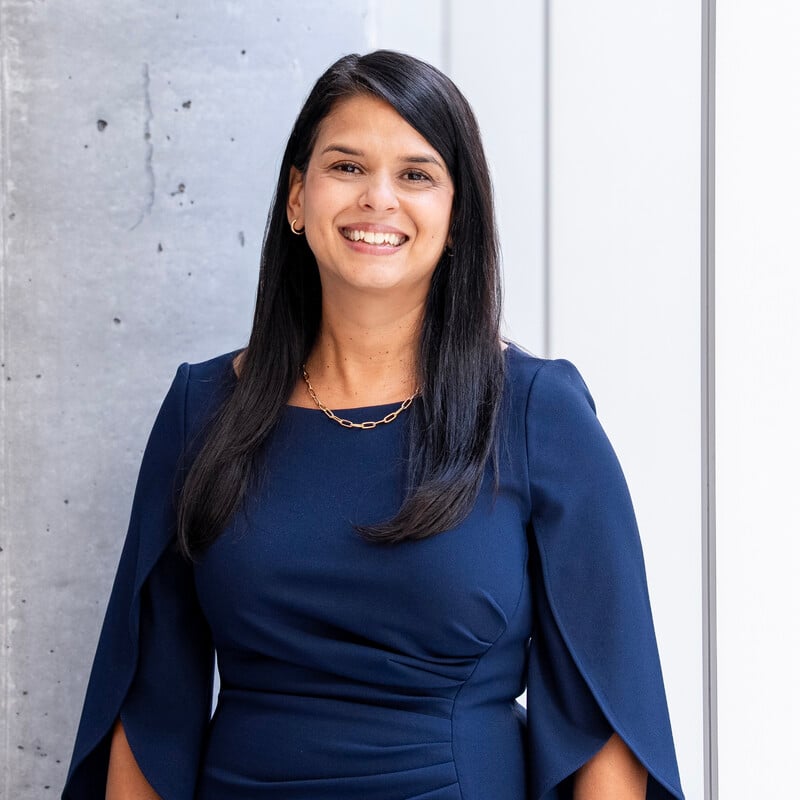
“Canadians work hard for their travel dollars and they deserve a program that works just as hard for them,” said Vinita Savani, executive vice-president, Cards & Loyalty, RBC. “With Avion Rewards Travel, we’re providing our clients with increased value and flexibility as well as smarter tools to help them get more from their travel plans.”
Vinita SavaniRahul Parihar photo
Flexible booking and points redemption
The platform allows users to book flights across more than 500 airlines. Avion credit cardholders continue to have access to fixed-points pricing with no blackout dates or seating restrictions, including during peak holiday periods.
Customers can pay for travel using Avion points, a credit card, travel credits or a combination of those payment methods. Avion points can also be applied toward taxes, fees and surcharges.
Avion Elite and Avion Premium members can convert their Avion points into frequent-flyer points or miles with select airline partners. The platform also uses individual travel preferences and booking history to tailor the experience, according to RBC, while offering bookings without hidden fees.
The redesigned service is being made available automatically to existing Avion Rewards members, including Avion cardholders. RBC says members do not need to create new profiles or migrate their data as part of the transition.
Launch promotions
RBC is also offering promotional incentives tied to the platform’s launch. Members can earn three times the usual Avion points on select hotel bookings made through Avion Rewards Travel between Sept. 8 and Oct. 31, 2026.
Prospective members who sign up for an RBC Avion Visa Infinite card can receive up to 70,000 Avion points, which RBC says is equivalent to as many as four short-haul round-trip flights.
Avion Rewards is open to Canadians who do not have an RBC account or credit card, although some benefits are tied to membership levels or RBC products.
The redesigned platform is part of RBC’s broader Avion Rewards offering, which also includes shopping, savings, rewards and consumer engagement features. Avion Rewards ShopPlus provides members with offers while they shop online, while the program also includes Avion credit cards and concierge services.
Small business owner reviewing numbers in a retail store. Image: Centelli
Canadian small and mid-sized businesses are feeling more pressure on cash flow, even when they remain profitable, according to Daryl Ching, founder of Toronto-based Vistance Accounting.
Ching’s firm works with about 50 small and mid-sized businesses across manufacturing, consumer packaged goods, ecommerce, wholesale and retail. He said more of those clients are looking for help managing working capital as money gets tied up in receivables and inventory.
“A lot of our work used to be centred around improving gross profit margins,” Ching said. “We’d look at pricing and variable costs and figure out how to improve profitability. Now, a lot of that work has shifted to working capital.”
Some of his clients are profitable on paper but still having trouble with cash flow. For Ching, that has meant spending more time looking at the balance sheet and helping clients collect money faster, manage inventory and deal with financing.
“I have a lot of clients that are profitable on paper, but they’re still struggling with cash flow,” he said.
Businesses Waiting Longer for Their Money
Late payments are part of the problem. Xero’s Canadian Small Business Insights reported in April that Canadian small businesses were being paid an average of 11.6 days late, up from 10.5 days previously.
Ching said some of his clients are working with payment terms of 60 or 90 days, and late payments can make those arrangements even more difficult. His firm has been helping clients improve collections while also looking at when they pay their own suppliers.
“A lot of the work has been around receivables and figuring out how to get collections in faster,” he said.
Inventory is another area getting more attention. Businesses that once kept additional stock on hand as a cushion are having to think more carefully about how much money they can afford to leave tied up in product.
“You might have had the luxury of ordering extra inventory to make sure you had enough,” Ching said. “You don’t have that luxury anymore. You need better demand forecasting.”
The issue is particularly relevant for retailers, wholesalers and consumer-product companies. Inventory needs to be purchased before it can be sold, and the business may then have to wait again before receiving payment from a customer or wholesale account.
“A lot of our work recently has been more on the balance sheet than on profit and loss,” Ching said.
Daryl Ching, founder of Toronto-based Vistance Accounting
Tariffs Put More Cash Into Inventory
Tariff uncertainty has complicated those decisions. Ching said some clients initially responded to the threat of tariffs by placing large orders ahead of potential changes, tying up money that would otherwise have been available to run the business.
“I had a whole bunch of clients do large bulk orders just in case,” he said. “That put them into cash difficulty.”
He is seeing less of that now. Businesses have had more time to adjust to changing trade policies and are less likely to react immediately when another product or industry appears likely to be affected.
“My clients aren’t rushing anymore,” Ching said. “They’re waiting to see what happens because we’ve learned that things can change again the next week.”
Canadian retaliatory tariffs have also affected some of his clients, particularly businesses buying products or raw materials from the United States. In those cases, Ching said companies have either absorbed the additional cost or looked for another supplier.
Research from the Canadian Federation of Independent Business has also found financial pressure from tariffs and trade uncertainty, including higher costs, weaker profits, supply-chain disruptions and postponed investment among affected businesses.
Lines of Credit Become a Bigger Concern
Lines of credit can provide businesses with short-term liquidity when cash is tight. Ching is concerned when companies remain heavily dependent on them for extended periods.
“With the working-capital squeeze, a lot of times it starts with a line of credit for short-term liquidity,” he said. “But when that persists over a long period, the short-term loan starts to look like long-term debt.”
He points to a business that has kept its line of credit fully drawn for several years as an example.
“If you have a line of credit that’s fully leveraged for three years, to me that’s long-term debt,” Ching said. “All of a sudden you’re carrying long-term debt, and that’s a structural weakness in the balance sheet. It also makes it harder to borrow from a bank.”
Ching said he is spending more time helping clients prepare for financing as a result. Business owners want to know what they can do to improve their financial position before going to a lender.
Conditions across the SME sector are mixed. Recent research from the Business Development Bank of Canada has shown some improvement in expectations, with more SMEs expecting cash flow to improve over the coming year and fewer expecting it to deteriorate.
Ching’s client base represents only a portion of Canada’s SME sector, but it gives him a close look at how cash-flow problems can develop inside otherwise viable businesses.
CEBA Repayment Deadline Approaches
Businesses with outstanding Canada Emergency Business Account loans also have a deadline approaching. Remaining CEBA principal is due December 31, 2026 for borrowers that continue to carry balances.
The loans were introduced during the pandemic to provide emergency financing to businesses. Loans that remained outstanding after the January 2024 forgiveness deadline became interest-bearing term loans, with the remaining principal due at the end of this year.
Ching said the deadline could add another demand on cash for businesses already managing other debt and operating expenses.
More Attention on the Balance Sheet
Ching continues to work with clients on margins, pricing and profitability, but cash management has become a bigger part of those conversations.
For some businesses, stronger sales can require more inventory and more money up front. If customers are also taking longer to pay, the gap between making a sale and collecting the money can grow. Businesses may turn to their lines of credit to cover that period, adding another cost to the equation.
That is why Ching is spending more time looking beyond the income statement.
“You can be profitable on paper and still struggle with cash flow,” he said. “You have to manage your receivables, your inventory and your payables. That’s where a lot of the pressure is right now.”
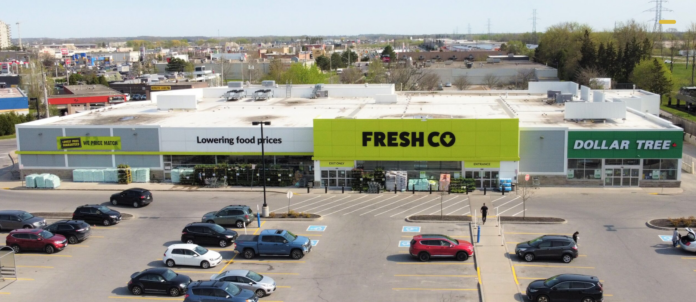
London Pine Valley FreshCo, London, ON. Image: Crombie REIT
Empire Company Limited is accelerating its store expansion plans as Canada’s major grocers continue to add capacity despite cautious consumer spending and pressure on industry volumes.
The parent company of Sobeys, Safeway, FreshCo, IGA, Foodland, Farm Boy and Longo’s now expects to open more than 25 stores in fiscal 2027, up from its previous target of more than 20. President and CEO Pierre St-Laurent said recently opened stores are meeting or exceeding expectations, supporting the decision to increase the target.
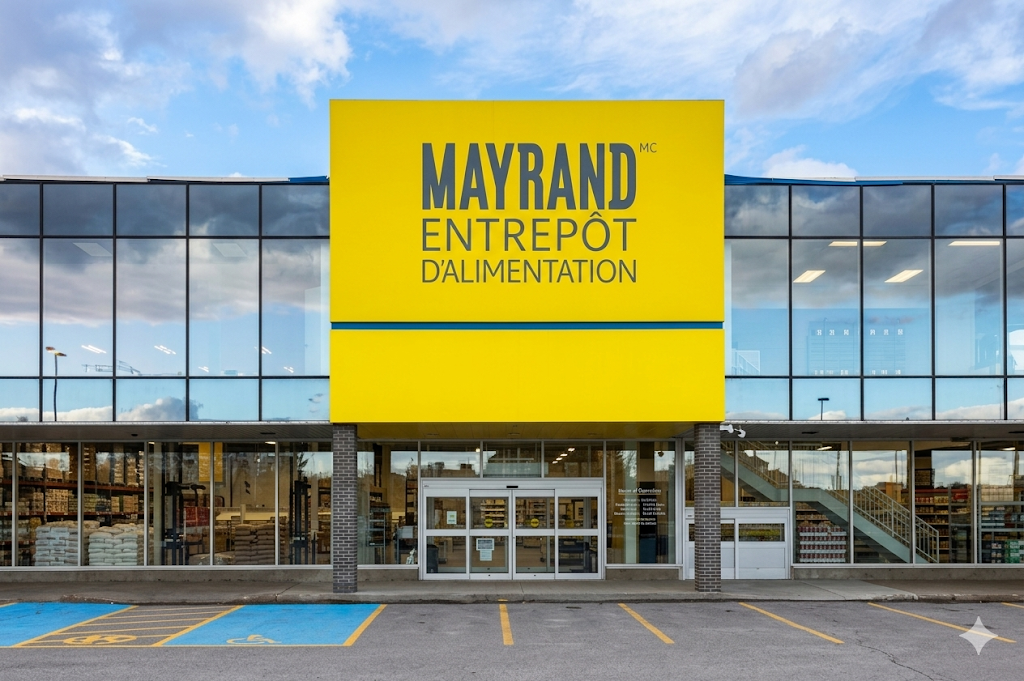
Empire expects the expansion to increase its retail square footage by approximately two per cent, including the addition of Mayrand stores in Quebec. The company plans approximately $850 million in capital spending this fiscal year, with about half allocated to renovations and new stores.
The increased target comes as competitors are also adding locations, particularly in discount grocery. With several major operators expanding at the same time, the amount of new grocery space entering the Canadian market is becoming an important consideration for existing-store productivity and future market share.
Empire Adds Stores Across Multiple Banners
Empire’s expansion extends across several banners and regions. The company opened its first FreshCo stores in Atlantic Canada in August and is continuing to grow the discount banner across Western Canada and Ontario. Recent openings include two FreshCo stores in Calgary and another in Paris, Ontario.
The company has also opened an IGA Extra in Montreal, an IGA in Edmonton and a Safeway at Oakridge Park in Vancouver. The Oakridge location gives Safeway a presence within one of Canada’s largest mixed-use redevelopment projects and represents a different type of opportunity from Empire’s discount expansion.
Empire has also completed its acquisition of Mayrand Food Group, adding four stores in the Greater Montreal area. A new Mayrand location is under development in Trois-Rivières, and management has indicated that it sees further expansion potential for the business.
FreshCo provides Empire with its primary discount growth vehicle, while Safeway and IGA provide conventional formats in markets where those banners are established. Mayrand adds another platform for growth in Quebec.
St-Laurent said the higher fiscal 2027 target includes stronger activity within Empire’s original real estate pipeline as well as the four acquired Mayrand stores. Management hopes to continue increasing the pace of development beyond the current year.
New Stores Support Expansion Plans
Early performance at recently opened stores is giving Empire confidence to continue investing. St-Laurent told analysts that new locations are meeting or exceeding the company’s expectations.
Those openings should have a greater effect on overall sales growth as the stores mature. Food sales increased 1.7 per cent in the first quarter, compared with same-store food sales growth of 1.2 per cent. CFO Constantine Pefanis said the difference between total and same-store sales growth should widen as new stores contribute more revenue.
Empire is investing in its existing network at the same time. Approximately half of the company’s planned $850 million in fiscal 2027 capital expenditures will go toward renovations and new-store development.
More Grocery Space Raises Questions About Existing Stores
Empire is not expanding in isolation. Loblaw Companies Limited has been adding grocery and pharmacy locations at an aggressive pace, with much of its grocery growth concentrated in discount banners including No Frills and Maxi. Metro is also adding discount capacity through Food Basics in Ontario and Super C in Quebec.
That expansion prompted BMO Capital Markets analyst Tamy Chen to ask Empire management how existing-store tonnage could be affected as multiple grocers increase square footage over the next one to two years.
The question highlights a potential challenge for the sector. New stores can capture customers in underserved or growing markets, but they do not create grocery demand on their own. If square footage grows faster than the market, some sales generated by new locations can come at the expense of existing stores.
St-Laurent said Empire views the current weakness in the consumer environment as cyclical and does not believe it should dictate real estate decisions intended to generate returns over many years.
“When we are investing in real estate, we are investing for the long term,” he told analysts.
Empire Is Looking Market by Market
St-Laurent said Empire assesses opportunities market by market, looking for areas where individual banners have room to grow. Management is not basing its investment decisions on a national assumption that Canada needs a certain amount of additional grocery square footage.
Grocery competition varies considerably across the country. Discount penetration, population growth, existing competitors and banner recognition differ between markets, creating opportunities for additional stores even when industry-wide sales growth is modest.
Empire says its recent openings have been concentrated in locations where it sees white space and believes its brands can compete effectively. The performance of those stores will be an important measure of whether that strategy can offset the broader risk of industry capacity growing faster than demand.
FreshCo Remains Central to Expansion
FreshCo remains one of Empire’s most important vehicles for new-store growth as Canadian consumers continue to prioritize value.
The company opened its first two FreshCo stores in Atlantic Canada on August 20 and expects additional openings across Western Canada, Ontario and Atlantic Canada during fiscal 2027. The move gives Empire a dedicated discount banner in a region where Sobeys already has a substantial conventional grocery presence.
Management said early customer response to the Atlantic locations has been encouraging. FreshCo is also expanding in established markets, including Calgary and Ontario, as Empire increases its exposure to the discount segment.
St-Laurent said Empire has been gaining market share in its full-service business while maintaining its position in discount despite rapid expansion by competitors. Management expects its growing discount footprint to contribute more meaningfully to market-share gains over time.
Mayrand store in Laval. Photo: RI/Google
Mayrand Adds Another Quebec Growth Platform
Empire’s acquisition of Mayrand adds a different format to its expansion strategy. The Quebec retailer operates large-format stores serving consumers and foodservice customers, giving Empire a business outside its conventional supermarket and discount models.
The acquisition closed in June, adding four Mayrand stores to Empire’s network. The company has already broken ground on a new location in Trois-Rivières and says there is potential for further expansion.
Mayrand accounts for part of the increase in Empire’s fiscal 2027 store target, but management said the revised outlook also reflects additional activity within its existing real estate pipeline. The higher target therefore goes beyond adding the four acquired stores to Empire’s network.
Expansion Intensifies Competition for Customers and Sites
For Empire, additional stores have to capture enough business to justify the capital being deployed while limiting cannibalization within its own network. Competitors are pursuing many of the same population-growth markets and value-oriented customers, increasing the importance of site selection and banner choice.
There is also a real estate dimension. Grocery stores remain important anchors for shopping centres and mixed-use developments because of their recurring customer traffic, while large sites suitable for new supermarkets can be difficult to secure in established urban markets.
Competition for those locations could increase as major grocers continue building their development pipelines. Empire’s portfolio gives it flexibility to pursue different types of opportunities, from FreshCo discount stores to conventional supermarkets and Mayrand locations.
Empire Takes a Long-Term View
Empire’s increased fiscal 2027 target is part of a broader real estate program that includes new stores, conversions and renovations across its network. The company is committing significant capital to physical retail while consumers remain cautious and competitors continue adding capacity.
The risk is that Canadian grocery square footage could grow faster than demand, putting pressure on productivity at existing stores. Empire is betting that market-level opportunities can still support new locations and that current economic weakness should not determine investments intended to operate for many years.
For now, the early performance of Empire’s newest stores is supporting that argument. Management is increasing the pace of expansion, putting greater weight on its ability to choose the right markets and banners as competition for Canadian grocery spending intensifies.
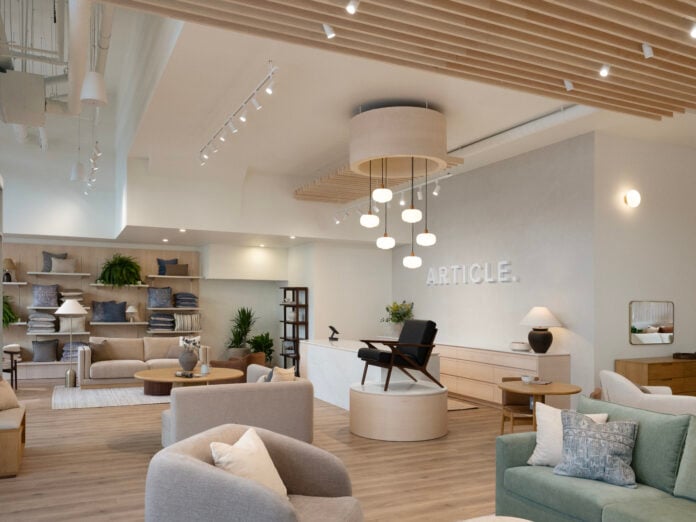
Vancouver-based furniture retailer Article opened its first Toronto store, marking the company’s second retail location in Canada and the next step in a larger physical retail strategy.
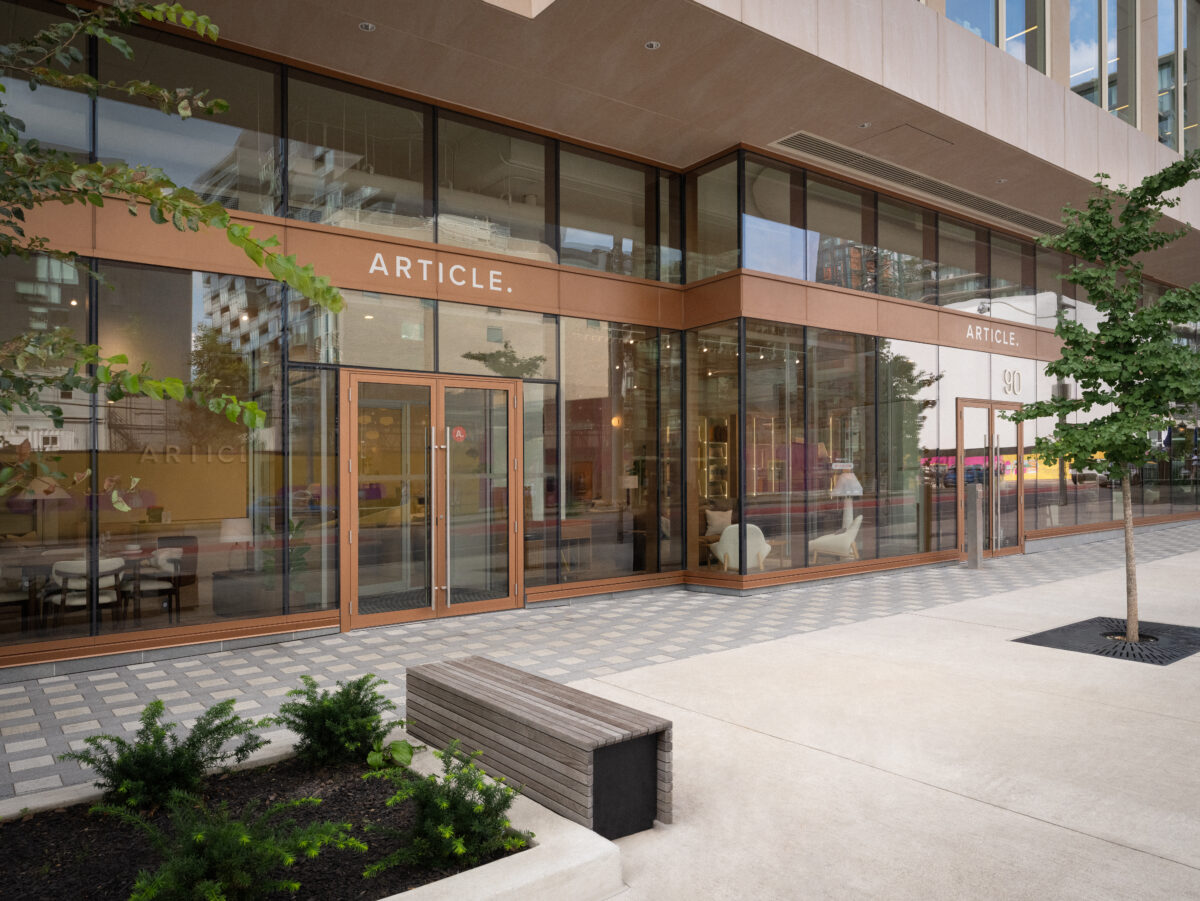
The furniture store will open at 90 Bathurst Street in King West, one of downtown Toronto’s most walkable, design-forward neighborhoods known for modern condo living and vibrant retail.
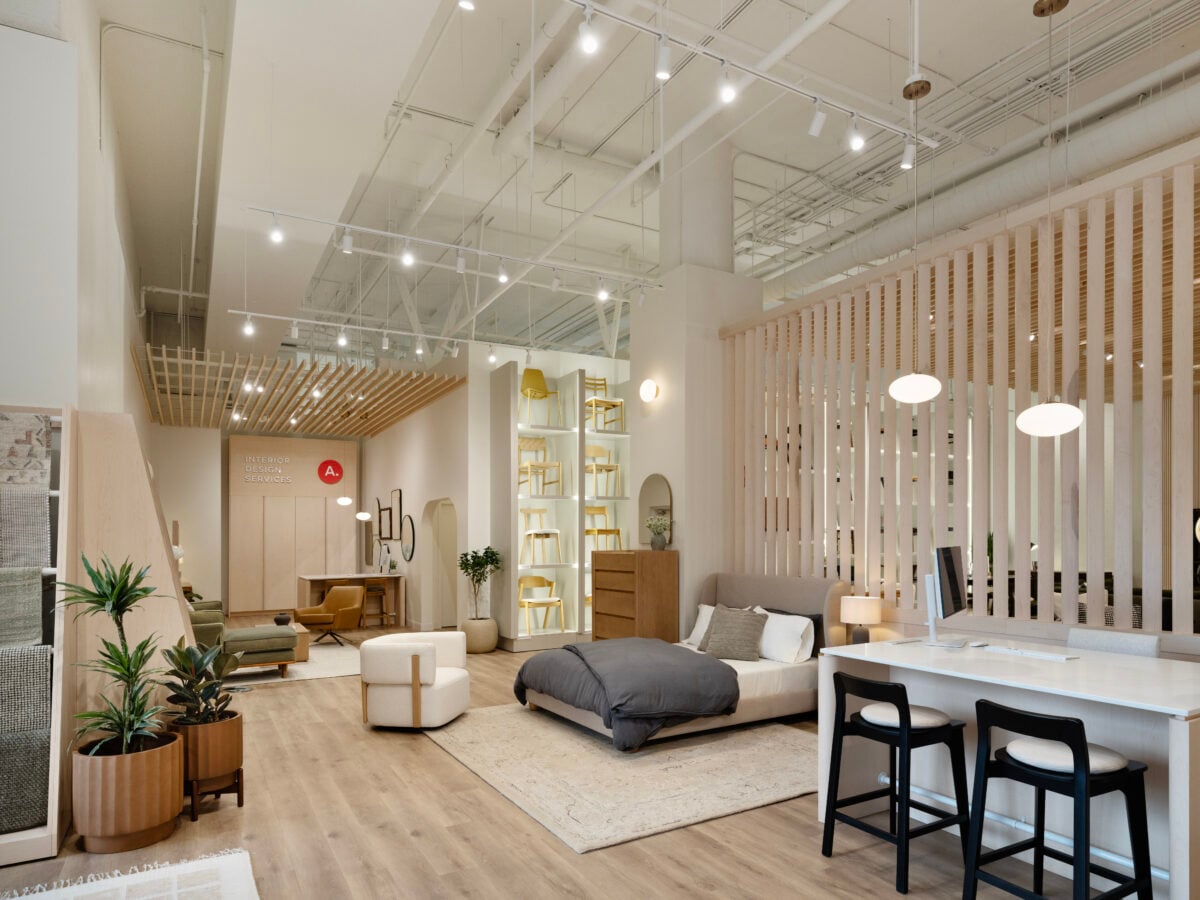
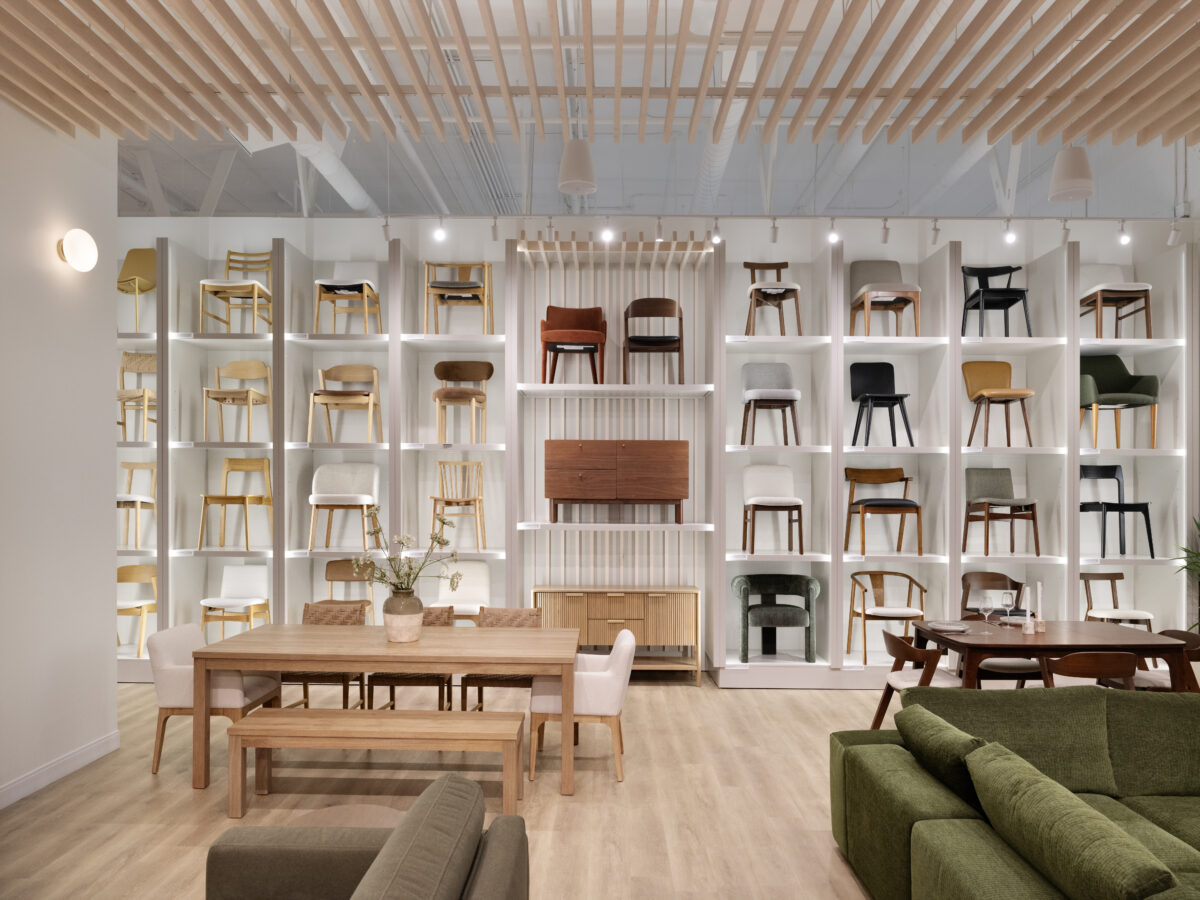
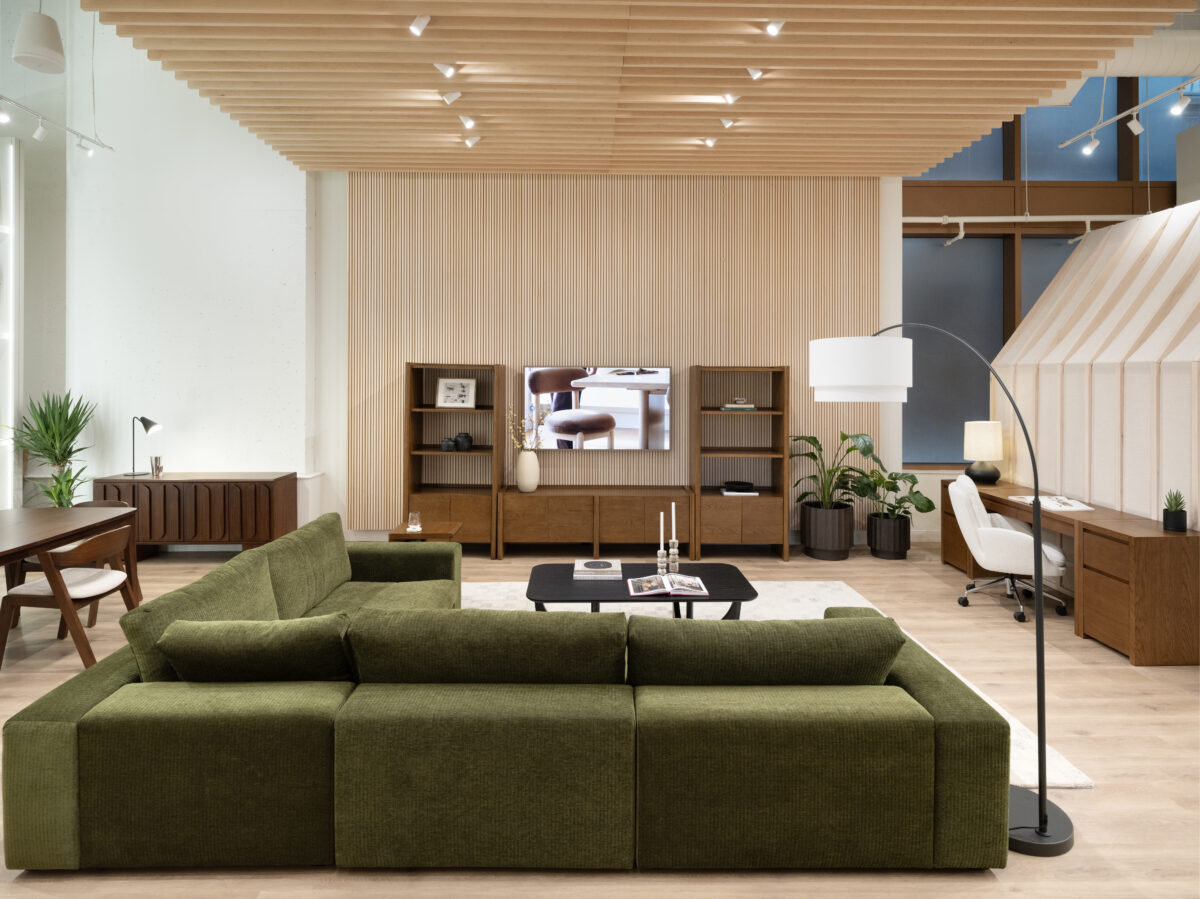
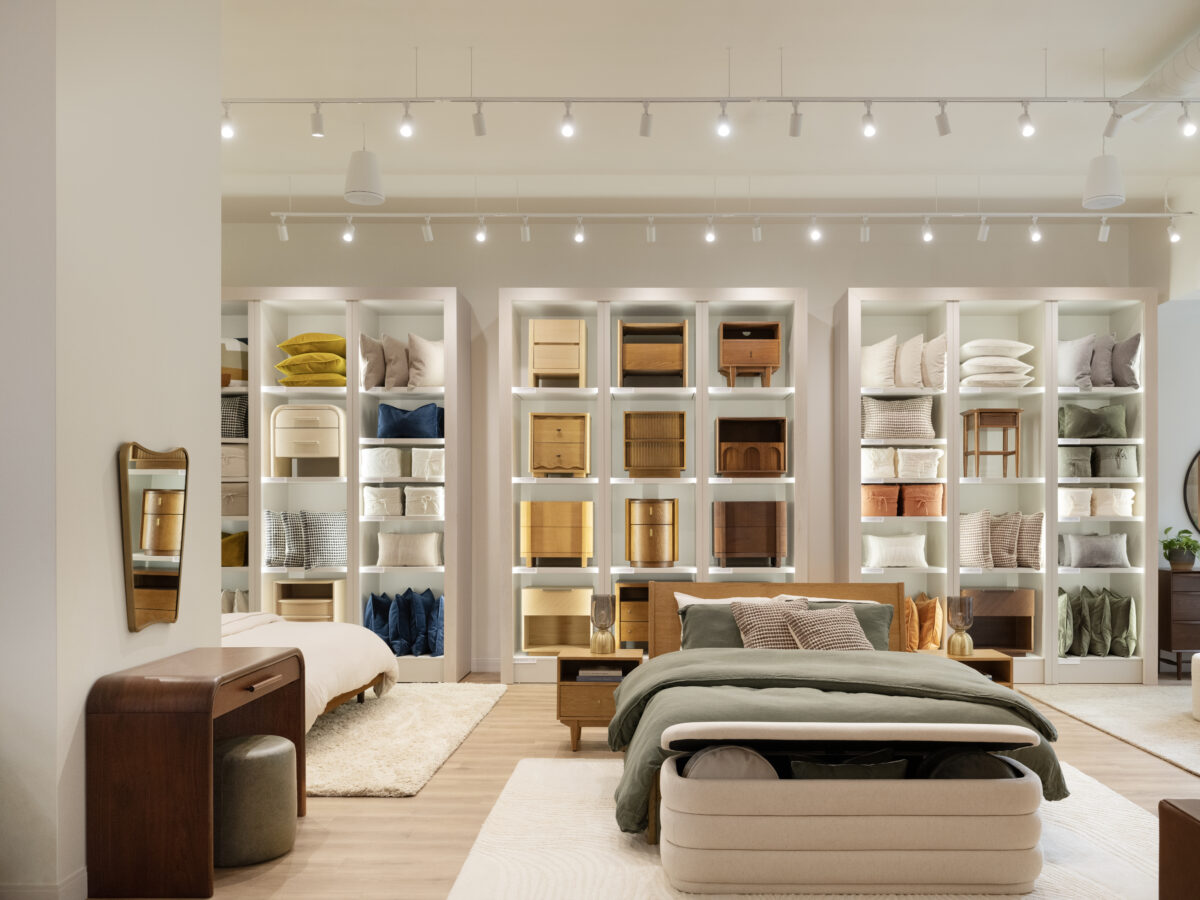
The new store features curated room vignettes, an extensive swatch library, and complimentary in-person Interior Design Services.
The store is 9,600 square feet.
Article photo
Building on the success of first store in Vancouver
The Toronto furniture store builds on the success of Article’s first-ever physical retail location in Vancouver, designed to test and refine its brick-and-mortar strategy. The Vancouver store has surpassed expectations since opening in August 2024, with in-store average order values exceeding online by more than 20 per cent.
Aamir BaigArticle photo
“For more than a decade, Article succeeded through a digital-first model, meeting consumer demand for modern furniture online,” said Aamir Baig, Co-founder and CEO of Article. “Over the past 18 months, we’ve seen how physical retail can deepen customer connections and strengthen our presence in key markets. As we expand, we’ll focus on store locations in North American cities where e-commerce performance is already strong, using retail to build on that momentum and make it easier to experience Article in person.”
At 9,600 square feet, the store is Article’s largest to date.
“We see physical retail as an extension of the business we built online and we are taking a disciplined approach to our expansion by expanding to markets with proven e-commerce performance. Ontario accounted for 40% of our online Canadian purchases in 2025, with customers based in the city of Toronto representing a third of that volume. Toronto is one of our strongest markets in North America, and expanding our retail footprint there is a natural next step,” said Baig.
Physical retail an extension of online presence
“Because physical retail is an extension of our online presence, creating a seamless experience between article.com and our brick-and-mortar stores is essential. Giving customers the ability to see, touch, and test our products in person is a major driver of purchase decisions. Features like Article’s free interior design services are specifically built to make furniture shopping easy, providing customers with expert design advice so they can create a stylish home at a great price.”
As the brand expands its physical retail footprint, it’s being deliberate about entering markets with proven e-commerce performance, said Baig.
“We plan to have up to five stores open across North America by early 2027, but our focus isn’t simply on store count. We’re building a scalable retail model that supports sustainable, long-term growth,” he said.
“The Toronto store will have the largest assortment of products, giving Torontonians the opportunity to experience a wider variety of Article products in real life. The assortment includes our core living room, bedroom, and dining categories, with outdoor incorporated seasonally. It’s brought to life through curated room settings, dedicated lighting and décor displays, and a chair wall featuring nearly all of our dining chair collections.
Products featured in-store are selected based on best sellers and new launches, with seasonal categories like outdoor available when relevant. In-store assortments may evolve over time based on local customer feedback, but we’ll always incorporate core styles we know will delight our customers.”
Article photo
Driving ongoing, sustainable growth
Baig said the company is making deliberate investments in strategic areas to drive ongoing, sustainable growth.
“Physical retail allows us to meet customers where they are and connect with those who want to experience Article furniture in person before making a purchase, unlocking an exciting new growth channel. As a result, physical retail will play an integral role in Article’s growth strategy over the next few years,” he said.
“While we don’t have any additional Canadian locations to announce today, we’ll continue to prioritize expansion in markets with proven e-commerce performance and strong customer demand.”
The company also has a store in San Francisco and is scheduled to open another one in Bellevue, Washington before the end of the year.
Grocery store in Quebec. Photo: Vergo Construction
The United States is imposing tariffs on much of the world, disrupting supply chains and inviting retaliation from its trading partners. Yet American food inflation remains lower than Canada’s.
For Canadians repeatedly told that external forces are primarily responsible for their rising grocery bills, this is an uncomfortable comparison.
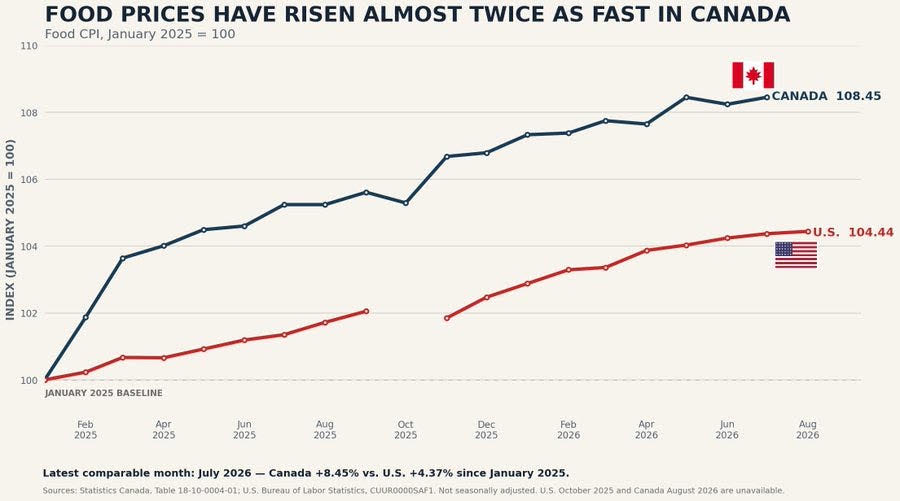
From January 2025 to July 2026, Canada’s total food price index increased by approximately 8.5%, compared with 4.4% in the United States. At first glance, food prices appear to have risen almost twice as quickly in Canada.
There is, however, an important statistical caveat. Total food includes restaurant meals, and January 2025 fell during Canada’s temporary GST/HST holiday. Restaurant prices were artificially depressed before jumping when the tax returned. Starting the comparison in January therefore exaggerates Canada’s increase.
A cleaner grocery-only comparison still tells a troubling story. Between January 2025 and July 2026, prices for food purchased from stores increased by approximately 5.8% in Canada, compared with 3.4% in the United States. Canadian grocery prices rose roughly 70% faster.
The gap is real. The explanation is more complicated than tariffs.
Although the United States has erected trade barriers against many countries, it is not literally tariffing every product from every trading partner. Exemptions, negotiated arrangements and preferential treatment for compliant goods remain. More importantly, tariffs apply only to imported products. The United States possesses a vast agricultural base, enormous processing capacity and a domestic market of roughly 350 million comparatively affluent consumers.
Scale matters.
American food manufacturers can spread fixed costs across larger production runs. Retailers have access to more suppliers. Processors can substitute ingredients more easily, and the country’s extensive domestic production cushions many categories from border disruptions.
Canada’s food economy operates under very different conditions. Our market is smaller, our processing capacity is thinner, and many regions depend heavily on imported ingredients, equipment, packaging and finished products. A weaker Canadian dollar also makes almost everything priced internationally more expensive.
The Bank of Canada concluded that the resurgence of Canadian grocery inflation in 2025 was driven largely by import costs, including the depreciation of the Canadian dollar. Weather-related shortages affected products such as coffee and cocoa, while drought, feed costs and limited cattle supplies pushed beef prices sharply higher.
These pressures existed in the United States as well. But the American food system has generally absorbed them more effectively.
Tariffs also do not pass through to consumers immediately. Food companies rely on inventories, negotiated contracts and hedging strategies. According to the Bank of Canada, cost pressures can take approximately six months to work through the food supply chain. Consequently, some effects of American tariffs may still be coming.
Retaliation can create another paradox. When foreign governments restrict American agricultural exports, more American production may remain inside the United States. That can depress domestic farm prices, even while imported inputs become more expensive. Farmers lose export opportunities, but American consumers may temporarily benefit from additional domestic supply.
None of this proves that tariffs are sound economic policy. It demonstrates that a large, competitive and productive food economy is better equipped to absorb trade shocks.
Canada should take notice.
First, Ottawa should avoid retaliatory tariffs on ingredients, packaging, machinery and other inputs that Canadian food manufacturers cannot easily source domestically. American tariffs are paid initially by American importers. Canadian counter-tariffs are paid by Canadian importers. We can be hit both ways.
Taxing essential inputs may create a satisfying political headline, but it ultimately increases production costs for Canadian businesses and grocery bills for Canadian households.
Second, Canada needs significantly more food-processing capacity. We remain remarkably good at exporting agricultural commodities and buying back higher-value processed products. Accelerated capital investment, automation, predictable regulation and access to affordable energy would allow Canadian processors to achieve greater scale.
Third, Canada must finally operate as one domestic food market. Provincial regulations, duplicative licensing systems and inconsistent standards make it unnecessarily difficult for smaller processors to sell across provincial boundaries. A Canadian company should not face more difficulty shipping food between provinces than a foreign supplier faces entering the country.
Fourth, grocery competition needs to improve. Restrictive property controls that prevent competitors from opening stores should be eliminated. The Competition Bureau has repeatedly identified these restrictions as barriers to entry. Canada should also make itself more attractive to international grocers and provide independent retailers with better access to wholesale supply.
Finally, protected agricultural sectors should not be treated as untouchable. Supply management was created for another era. Reform does not require abandoning farmers. It means gradually encouraging productivity, lowering input costs, attracting processing investment and giving efficient producers opportunities to grow beyond a protected domestic market.
The lesson from the United States is not that tariffs lower food prices. They do not.
The lesson is that resilience comes from production capacity, scale, competition, productivity and diversified supply chains. The United States currently possesses more of those advantages than Canada.
At the grocery store, patriotism is not a pricing strategy. Neither is tariff theatre.
If Canadian governments genuinely want to defend food affordability, they should spend less time telling consumers whom to blame and more time removing the structural costs that make Canada’s food system so vulnerable in the first place.
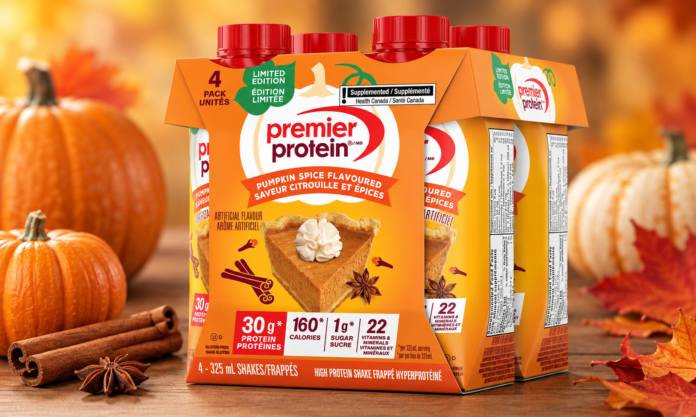
Premier Protein is expanding its Canadian retail assortment with the rollout of its limited-edition Pumpkin Spice Protein Shake, adding another product across major retail channels as the brand builds its presence in Canada.
The seasonal shake launched through Costco and Amazon in August, followed by Walmart in September, with additional grocery distribution expected. The rollout builds on an established Canadian business for Premier Protein, which has spent years increasing its presence across grocery, pharmacy, mass and club retail.
Premier Protein is already carried by many of Canada’s largest retailers. The brand has previously identified Walmart, Real Canadian Superstore, Shoppers Drug Mart, Loblaws, Provigo, Safeway, Fortinos, Zehrs, Save-On-Foods, Metro, Sobeys and Jean Coutu among retailers carrying its shakes and protein powders.
The latest rollout broadens an existing Canadian assortment rather than marking a new entry into the market. Walmart Canada currently lists several Premier Protein ready-to-drink varieties, including Chocolate, Vanilla, Café Latte and Strawberries & Cream, while Costco has been an established distribution channel for the brand.
The larger story is the strategy behind that growth. Premier Protein’s parent company is seeking substantially wider distribution for its ready-to-drink business, including more points of sale and greater visibility within stores.
BellRing Brands Targets More Distribution
Premier Protein is owned by BellRing Brands, a publicly traded U.S. nutrition company whose portfolio also includes sports nutrition brand Dymatize. Premier Protein is the company’s largest business and has developed into a major player in the North American ready-to-drink protein category.
In its 2025 annual report, BellRing said it planned to increase total distribution points for Premier Protein ready-to-drink shakes by more than 20% during fiscal 2026, roughly matching the pace achieved the previous year. The strategy also includes securing additional in-store displays and placing products outside traditional nutrition aisles to increase trial.
BellRing reported significant progress during its second quarter of fiscal 2026. Total distribution points for Premier Protein ready-to-drink shakes increased 29% year over year. The brand held a 28.2% share of the measured U.S. ready-to-drink protein category, while household penetration reached 21.3%.
Those figures are specific to the U.S., but they demonstrate the scale Premier Protein has reached as BellRing continues investing in wider distribution.
Protein Becomes a Mainstream Food Purchase
The strategy comes as protein products occupy more space within mainstream food and wellness retail. Ready-to-drink shakes are increasingly positioned around everyday consumption, including breakfast, snacks and convenient nutrition, broadening the potential customer beyond the traditional sports nutrition shopper.
Premier Protein has been growing across several mainstream channels outside its historically important club business. BellRing has identified multi-channel execution, increased household penetration, distribution gains and innovation as central to the brand’s next phase of growth.
That diversification is reflected in Premier Protein’s Canadian footprint. Costco remains an important outlet for the brand, while Walmart, major grocery banners and e-commerce provide access to consumers through regular household shopping.
Wider availability also puts protein brands in competition for more mainstream retail shelf space. Grocery stores, mass merchants and warehouse clubs have become increasingly important venues for reaching consumers beyond the traditional sports nutrition customer.
Seasonal Flavours Add to the Assortment
Premier Protein is also applying a familiar packaged-food strategy to the category through seasonal and expanded flavour offerings.
Limited-time products can refresh an established assortment and generate trial without permanently adding another SKU to a retailer’s shelf. Pumpkin spice is already an established fall flavour across coffee, bakery and packaged food, giving Premier Protein a recognizable seasonal offering for its ready-to-drink line.
The Canadian Pumpkin Spice shake contains 30 grams of protein and one gram of sugar per 325-millilitre serving. Costco is carrying the product in an 18-pack, Walmart is offering a four-pack, and the product is also available through Amazon.
The wider Canadian assortment extends beyond Premier Protein’s core Chocolate and Vanilla offerings, with flavours including Café Latte, Caramel, Strawberries & Cream, Chocolate Peanut Butter and Bananas & Cream. Cookie Dough has also been introduced through Costco.
The broader selection gives Premier Protein more opportunities to introduce new products within the same ready-to-drink format while competing for additional shelf space.
Distribution Growth Meets a More Price-Sensitive Consumer
BellRing’s push for wider distribution is taking place in a more challenging consumer environment. During its second quarter of fiscal 2026, Premier Protein net sales increased 1.7% while volume rose 11.3%. Ready-to-drink shake sales increased 2.3%, with volumes up 11.7%.
The gap reflects heavier promotional activity. BellRing reported that Premier Protein’s price/mix declined 9.6% during the quarter, with incremental promotional investment and unfavourable mix weighing on the measure. Increased promotions and distribution gains helped drive the higher volumes.
BellRing has chosen to continue investing behind the brand despite those pressures. The company has pointed to strong household penetration, brand equity and volume growth while acknowledging heightened consumer price sensitivity and promotional pressures.
In Canada, the latest rollout puts another Premier Protein product across club, mass and e-commerce channels, with additional grocery distribution planned. It adds to an already broad assortment as the company pursues more retail touchpoints and greater visibility for the brand.
For Canadian retailers, Premier Protein’s expansion reflects the growing role of protein within mainstream food and wellness. As brands pursue more distribution, new flavours and greater in-store visibility, competition for the protein consumer is increasingly playing out across grocery, warehouse clubs and mass merchants.
The recent back-to-school shopping period showed that things can change quickly in retail when a celebrity or creator can suddenly make one product the thing everyone wants overnight. During the summer, Hailey Bieber’s jeans sold out in a matter of days at the Gap.
While TikTok continues to shape which styles younger shoppers are looking for in the first place, for retailers and consumer brands, the challenge is keeping up with demand that can shift much faster than traditional inventory planning.
In an interview with Retail Insider, Bianca Anghelina, Founder and CEO of Aily Labs, talked about how AI can help brands spot these shifts earlier and make faster calls on replenishment while there’s still time to act.
There’s also risk in moving too fast. A viral product can sell out in days, but the demand behind it can fade just as fast, leaving brands unsure whether they’re looking at a lasting trend or a short-lived spike before they commit more inventory.
Bianca AnghelinaArtur Stec photo
Question: How are social media and creator-driven trends changing the way retailers forecast demand and plan inventory for events like back-to-school shopping?
Answer: The biggest change is speed.
A product can suddenly become popular because of one creator or one social trend, and within days retailers can see demand move in a completely different direction. Traditional forecasting was never built for that. It relies heavily on historical patterns, but what happened last season may tell you very little about what a consumer is going to want next week.
The opportunity with AI is to connect what is happening externally with what is happening inside the business. Retailers can look at social signals, search behaviour, and consumer interest together with sales, inventory, supply and financial data.
That creates a much more real-time view of demand. Instead of waiting until a product is sold out to realize there was a trend, they can see it developing and start making decisions much earlier.
For me, that is where the real impact starts. You move from reacting to what happened to deciding what to do next while the opportunity is still there.
Q: How can AI help retailers identify an emerging viral trend early enough to adjust inventory and replenishment decisions before products sell out?
A: Retailers already have enormous amounts of data. The challenge is bringing those signals together quickly enough to decide.
Social media might show that a product is suddenly gaining attention. Then you have search behaviour, sales velocity, inventory levels, store-level traffic and supplier capacity all sitting in different places.
AI can bring those signals together and identify patterns much faster than a human team could.
Then you can move from insight to action. Where is demand accelerating? Which stores are likely to run out first? Can I reallocate inventory from another region? Should I increase replenishment now, or do I need another day of data?
That is the part I find exciting. Decisions that could previously take days or weeks can start happening in minutes.
At Aily, our AI agents can run 100,000 what-if scenarios in seconds. So rather than making one big bet on a trend, retailers can compare different options and understand the trade-offs before they act.
Q: What data signals should retailers be watching to distinguish a trend with sustained consumer demand from a short-lived viral spike?
A: I would never look at one signal on its own.
A product can have millions of views and still not translate into meaningful sales. What matters is whether you start seeing the same pattern across different parts of the business.
You want to know whether social interest is growing over time, whether search activity is increasing, whether people are buying the product and whether that demand is spreading across markets or customer groups.
Then connect that with what is happening operationally. Are stores seeing faster sell-through? Is inventory starting to tighten? Are consumers coming back and buying again?
When those signals reinforce one another, you have a much stronger indication that this is real demand rather than a moment of attention.
This is why I always come back to the idea of a single source of truth.
Marketing, sales, supply chain and finance should be looking at the same picture and making decisions from the same information.
Keira Burton photo
Q: What are the risks for retailers of reacting too quickly to social media trends, and how can AI help them avoid over-ordering or being left with excess inventory?
A: Moving faster does not mean reacting to everything.
If a retailer sees a viral post and immediately places a huge order, the risk is obvious. The trend can disappear just as quickly as it appears, and suddenly you have excess stock, tied up working capital and markdowns at the end of the season.
AI should help you make a better decision, not simply a faster one.
Maybe the right action is to move existing inventory between stores before ordering more. Maybe you increase replenishment gradually. Maybe the data shows that social engagement is high, but actual conversion is still weak, so you wait.
Retailers need to understand why the AI is recommending a particular action, and which signals are driving it. It shouldn’t feel like a black box telling you to buy more inventory. The recommendation should be grounded in the business and help the team understand the trade-off so they can make the decision with more confidence.
Q: How do you expect AI-driven demand forecasting to change the relationship between social media trends, consumer behaviour and traditional retail inventory planning?
A: I think forecasting is becoming much more continuous.
Today, many companies still operate in planning cycles. They create a forecast, build an inventory plan and then wait until the next cycle to adjust it.
But consumer behaviour does not work in cycles anymore.
With AI, new information can constantly feed into the forecast, whether that is a change in consumer interest, sales, inventory or supply. That also means marketing, commercial, supply chain and finance no longer need to make decisions from separate views of the business.
Over time, agents will not only tell retailers that something has changed. They will help determine what to do about it and, within predefined guardrails, increasingly take action.
That is where I see retail planning going. Much more real time, more connected and much closer to the actual consumer.