World Food Day falls on Friday, October 16. For Canada, the occasion exposes an uncomfortable contradiction. We are an agricultural powerhouse, with productive farms, extensive trade networks and internationally respected research. Yet millions of Canadians struggle to afford the food our economy helps produce.
The latest global agri-food benchmarking from MNP and Dalhousie University places Canada seventh among the G20 countries assessed. Meanwhile, Statistics Canada reports that 24% of Canadians lived in households experiencing some form of food insecurity in 2024. Agricultural influence clearly does not guarantee affordable meals at home.
How can a wealthy food-producing country tolerate such widespread financial difficulty around something as fundamental as eating?
Answering that question requires looking beyond grocery prices. Food affordability depends on what households earn, what governments transfer and tax, and what remains after other expenses. The grocery receipt captures only one part of a much larger household-budget problem.
Our calculations, using 2015 as a baseline, reveal two distinct pressures.
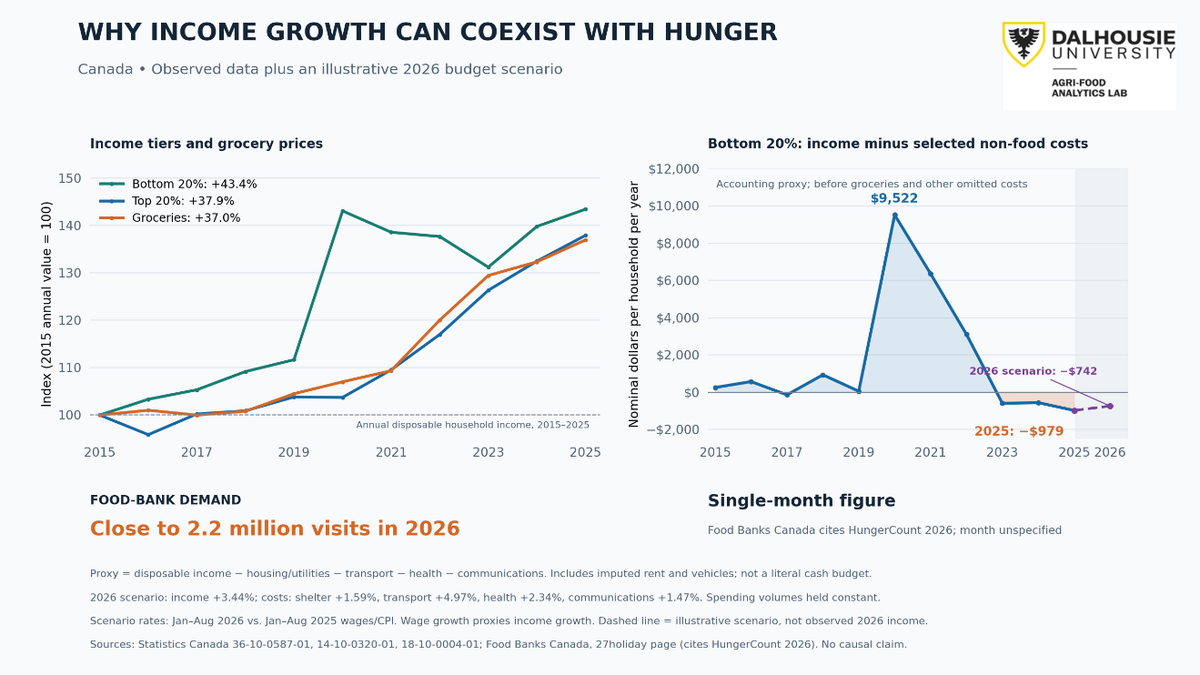
Among households in the lowest income quintile, average disposable income increased by 43.4% between 2015 and 2025. Grocery prices increased by 37%. On this comparison alone, the lowest-income households appear to have gained ground.
But disposable income is not the same as wages. It includes government transfers and is measured after taxes. Benefits and tax credits therefore form part of the explanation. These figures cannot support the claim that the poorest Canadians received wage increases exceeding grocery inflation.
Nor does faster income growth mean their budgets are adequate. A large percentage increase from a very low starting point can still leave households unable to cover basic expenses. Their financial position also depends heavily on housing, utilities, transportation and other costs.
To illustrate that pressure, we subtracted selected non-food expenses from average disposable income for the bottom quintile. These expenses include housing and utilities, transportation, health and communications.
The resulting annual balance turned negative in 2023 and reached a shortfall of $979 per household in 2025, before groceries and other omitted expenses. An illustrative 2026 scenario produces an annual shortfall of $742.
These estimates require careful interpretation. They are accounting proxies, rather than literal household cash budgets, and include imputed rent and vehicle purchases. They also describe averages, concealing considerable differences between households.
Nevertheless, they illustrate why income growth can coexist with hunger. When other costs absorb available resources, food purchases become difficult even if income has risen faster than grocery prices.
Households can postpone purchases, choose cheaper products or reduce portions. They cannot indefinitely shop their way out of an inadequate budget.
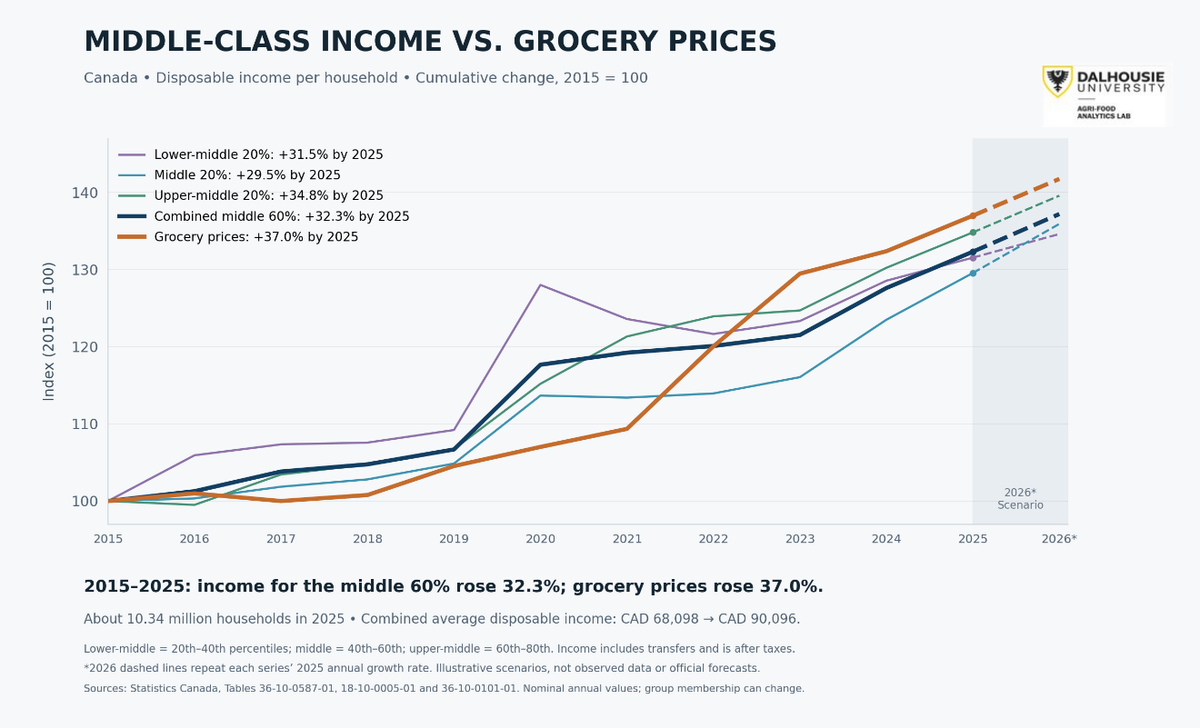
For the middle class, the squeeze takes another form. We define this group as the middle 60% of households by income, excluding the highest and lowest quintiles. In 2025, that represented approximately 10.34 million households.
Between 2015 and 2025, their average disposable income increased by 32.3%, from $68,098 to $90,096. Grocery prices increased by 37%, leaving a gap of 4.7 percentage points.
Their incomes bought less against the grocery-price benchmark, while other household obligations continued competing for the same dollars. Many middle-income households receive less targeted support than those at the bottom, without enjoying the financial flexibility of those at the top.
This does not establish that all middle-class households are food insecure. It does explain why affordability anxiety extends well beyond households traditionally associated with poverty.
Employment alone cannot guarantee financial security. Working households can still face difficult choices between food and other bills. That vulnerability deserves attention before financial strain becomes a crisis.
A resilient economy needs a middle class capable of saving, absorbing emergencies and spending beyond necessities. When essential expenses consume more income, businesses and communities feel the consequences.
Governments therefore need to address food security through the entire household budget.
Grocery competition, productive food manufacturing and efficient supply chains remain essential. So does sustained income growth. But slowing inflation will not erase the price increases Canadians have already absorbed.
Policy should also leave households with more purchasing power. Targeted tax relief, effective income supports and fewer punitive benefit clawbacks can help. Housing supply, transportation efficiency and stronger productivity require sustained action across governments.
Measures should be judged by the dollars households retain after unavoidable expenses. Relief that disappears into another rising bill offers little lasting security.
Canada’s agricultural strength gives us an advantage many countries would welcome. Turning that advantage into better lives requires households with enough money to purchase nutritious food consistently and with dignity.
On World Food Day, celebrating our capacity to feed the world is appropriate. Governments must also answer a question much closer to home: after Canadians have paid their other essential bills, how much is actually left for dinner?
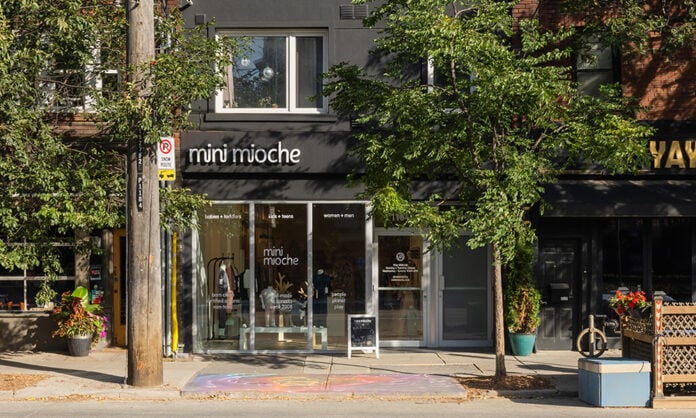
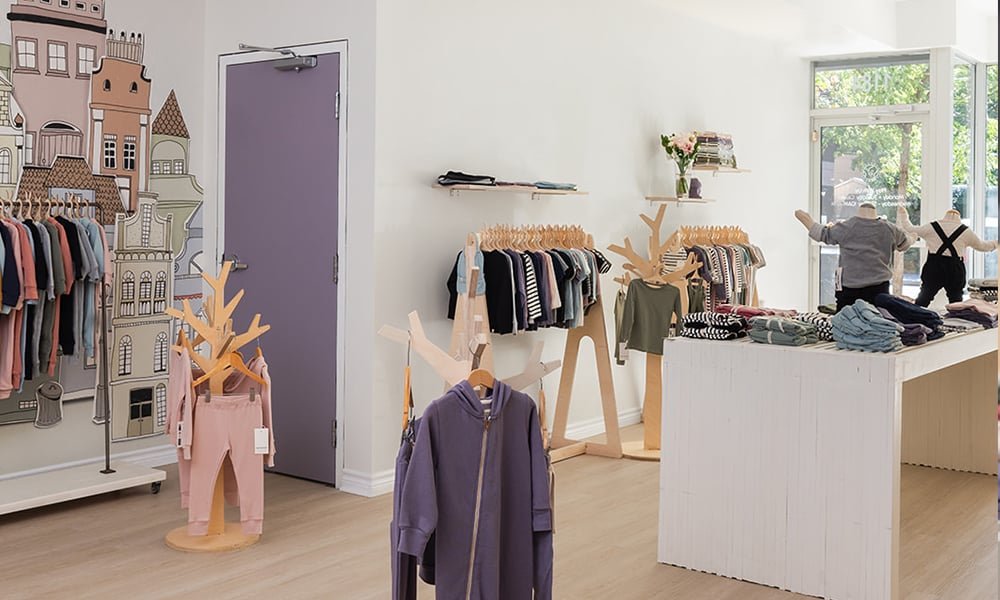
Mini Mioche at 1184 Queen Street East in Toronto. Image supplied
Toronto-based apparel brand mini mioche has returned to brick-and-mortar retail with the opening of a new flagship store in the city’s Leslieville neighbourhood, marking another stage in the company’s transformation under owner and CEO Jacquelyn Corbett.
Located at 1184 Queen Street East, the new store, called The Shop, brings the Canadian apparel brand back into physical retail following the closure of its previous Toronto locations. The opening comes as mini mioche expands its wholesale distribution, introduces new product categories and develops international markets, while maintaining its longstanding commitment to domestic manufacturing.
In an interview with Retail Insider, Corbett said the Canada–U.S. trade war prompted her to reassess the company’s distribution strategy, ultimately leading to the decision to reopen physical retail alongside its growing online and wholesale operations.
“When the trade war hit last February, I was like, ‘We need to rethink the strategy here. What are we doing?'” Corbett said. “We were really focused online.”
Trade Uncertainty Prompts Retail Reassessment
Founded in Toronto in 2008 by Alyssa Kerbel, mini mioche developed a following for minimalist children’s apparel made with certified organic cotton. The brand previously operated stores on Queen Street West and in Toronto’s Distillery District, with those locations closing in 2022 and 2020, respectively.
Corbett subsequently acquired the business and began broadening its operations, developing wholesale relationships, expanding its product assortment and reaching customers outside Canada. By 2025, the company had been investing in both Canadian and American markets, including efforts to build its U.S. wholesale business.
Trade uncertainty prompted Corbett to reconsider the risks of relying heavily on direct-to-consumer sales. She spent much of the second half of 2025 evaluating whether the time was right to reopen a physical store before committing to the idea in January 2026.
“I started getting really caught on the fact that we have one distribution channel, really, and that’s D2C,” she explained. “I love retail, I always have, and I started to think, ‘Is it time for us to open retail again?'”
Corbett considered Leslieville and Roncesvalles, two Toronto neighbourhoods with established family populations that align with the brand’s customer base. A Leslieville resident herself, she discovered the Queen Street East property while walking her dogs. The premises were undergoing renovations, providing an opportunity to design the space around the company’s evolving retail requirements. Mini mioche secured the location in May and completed the buildout over the summer.
The company’s American business has also experienced fluctuations as tariffs and trade policies have changed. Corbett said U.S. sales declined and recovered several times, including another downturn following tariff changes in August, although the business has since stabilized.
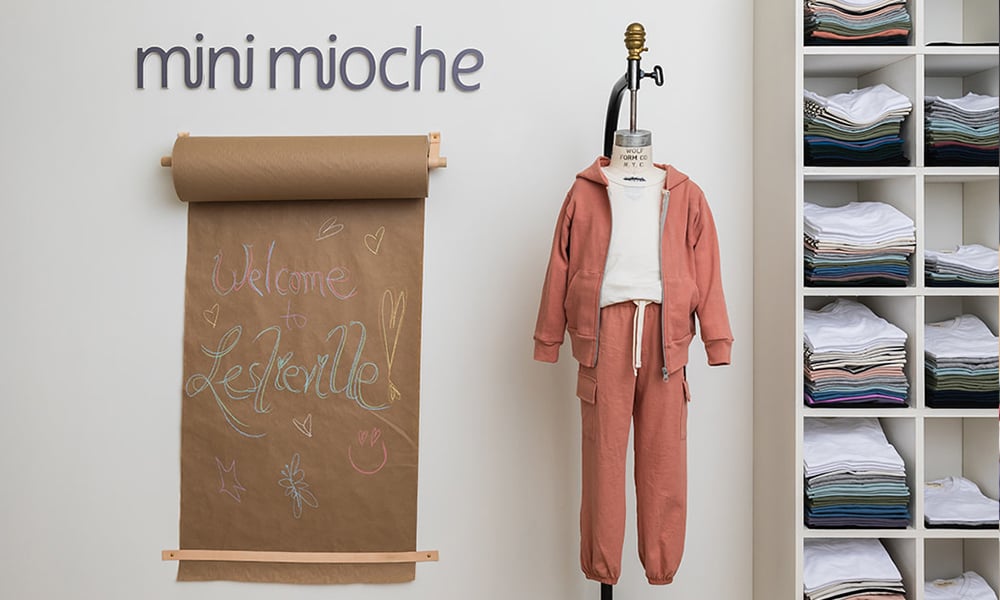
Mini Mioche at 1184 Queen Street East in Toronto. Image supplied
A New Model for Physical Retail
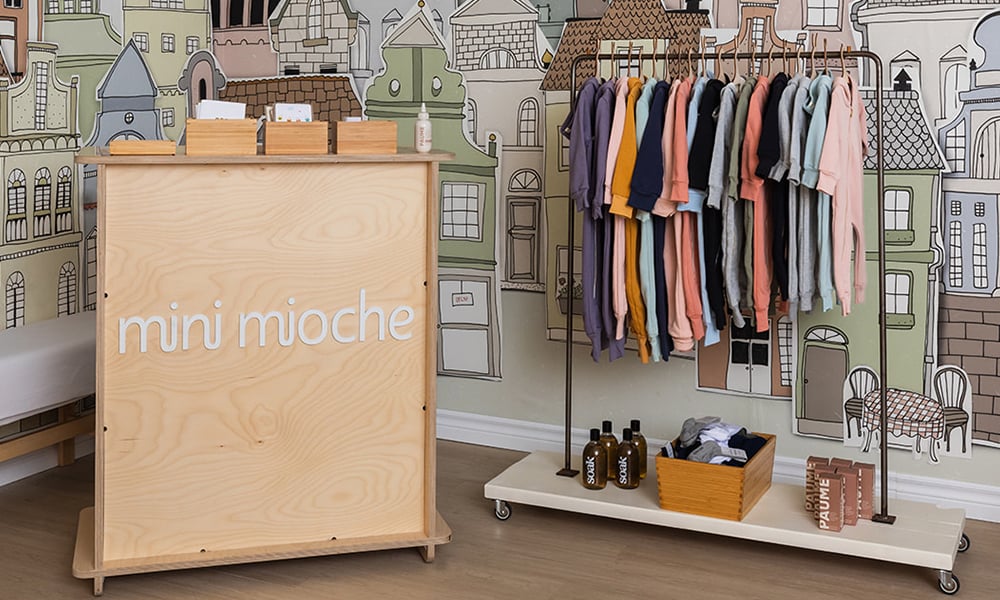
The Leslieville flagship has been designed to serve several purposes beyond conventional retail sales. Its front section functions as a showroom displaying the brand’s collections, colours and seasonal styles, while the rear accommodates shopping, children’s activities and community programming.
Corbett said the company has arranged visits from Canadian authors for children’s readings, along with musicians who will participate in afternoon events. The intention is to establish the store as a neighbourhood destination for families rather than simply a place to purchase clothing.
“The original stores were amazing and beautiful, really good vibe, nice place to visit for families,” she said. “A thing we’re doing differently this time is running it as a shop, but as well as a community space.”
The location also supports the company’s e-commerce operations, with online orders fulfilled from the store. Corbett pointed to larger retailers such as Aritzia, which use physical locations alongside other fulfillment infrastructure to manage inventory and serve online customers.
For mini mioche, the approach allows its retail space and inventory to support multiple sales channels while creating a consistent experience for customers shopping online or in person.
The physical environment also reflects the company’s emphasis on playfulness. Children can use an interactive magnetic display to create outfits from different clothing pieces, while an art area toward the back of the store provides space for drawing and other creative activities.
Mini Mioche at 1184 Queen Street East in Toronto. Image supplied
Wholesale and International Expansion
The flagship opening is one part of a broader effort to diversify mini mioche’s business. Under Corbett’s leadership, the company has developed wholesale relationships, expanded into adult apparel and school uniforms, and opened international shipping markets, creating additional opportunities for growth beyond its original direct-to-consumer model.
Corbett said mini mioche now supplies nearly 100 boutiques, compared with having virtually no wholesale accounts several years earlier. The brand also launched with Canadian baby and children’s retailer West Coast Kids during the summer, providing additional exposure through an established national retail business.
“We built out the wholesale business a lot,” Corbett said. “We’ve got boutiques across the country now. I think we’re in nearly a hundred boutiques at this point.”
International markets have become another component of the strategy. Mini mioche now ships to customers in the United Kingdom, Australia and across Europe, broadening its reach beyond Canada and the United States.
The company has also expanded beyond its original focus on baby and children’s apparel. An adult collection began with T-shirts in 2025, followed by a holiday capsule after early customer response exceeded expectations. The assortment has since grown to include additional everyday essentials based on popular designs from the children’s collection.
Corbett emphasized that the adult offering is intended to stand independently rather than function primarily as coordinated clothing for parents and children.
“Basically, we took our best sellers in kids and turned them into really beautiful upsized versions,” she said. “These are not mommy and me. They’re beautiful adult pieces, just as beautiful as our kids’ pieces.”
School uniforms and spirit wear represent another part of the business. Introduced approximately two and a half years ago, the programs provide an organic cotton alternative to the polyester-cotton blends commonly used for school apparel. Corbett said initial interest came from American customers, prompting the company to develop the offering further.
Together, these initiatives have broadened mini mioche’s customer base and distribution network, creating a business with multiple product categories and sales channels.
Mini Mioche at 1184 Queen Street East in Toronto. Image supplied
Canadian Manufacturing Remains Central
Despite the company’s changing distribution strategy, Corbett said mini mioche has no intention of abandoning Canadian manufacturing, even as trade tensions complicate cross-border business.
According to the company’s published manufacturing information, approximately 95 per cent of its assortment is made in Canada. Core clothing production includes fabric milling, dyeing, cutting and sewing domestically, although raw organic cotton is sourced internationally, including from India and Korea. Certain specialty products are manufactured overseas.
Corbett said maintaining Canadian production was a principal reason she acquired the company.
“When I bought the business, I bought it because of the Canadian manufacturing,” she said. “The local manufacturing is something I feel really strongly about. Sustainability is something I feel really strongly about.”
She explained that the trade war prompted suggestions that mini mioche should consider moving manufacturing overseas to simplify its operations. Corbett rejected that approach, arguing that supporting Canadian employment and retaining domestic production were fundamental to the company’s identity.
“We mill our fabrics here as well,” she said. “That’s a really unique thing in Canadian manufacturing because there’s not a lot of fabric mills left in Canada for the types of things that we produce.”
Mini mioche says its core apparel collections are produced using GOTS-certified organic cotton, reflecting the company’s emphasis on environmental standards and ethical production practices. Corbett also welcomed the increased interest in buying Canadian products, describing the movement as an opportunity for domestically manufactured brands to connect with consumers paying closer attention to where their purchases are made.
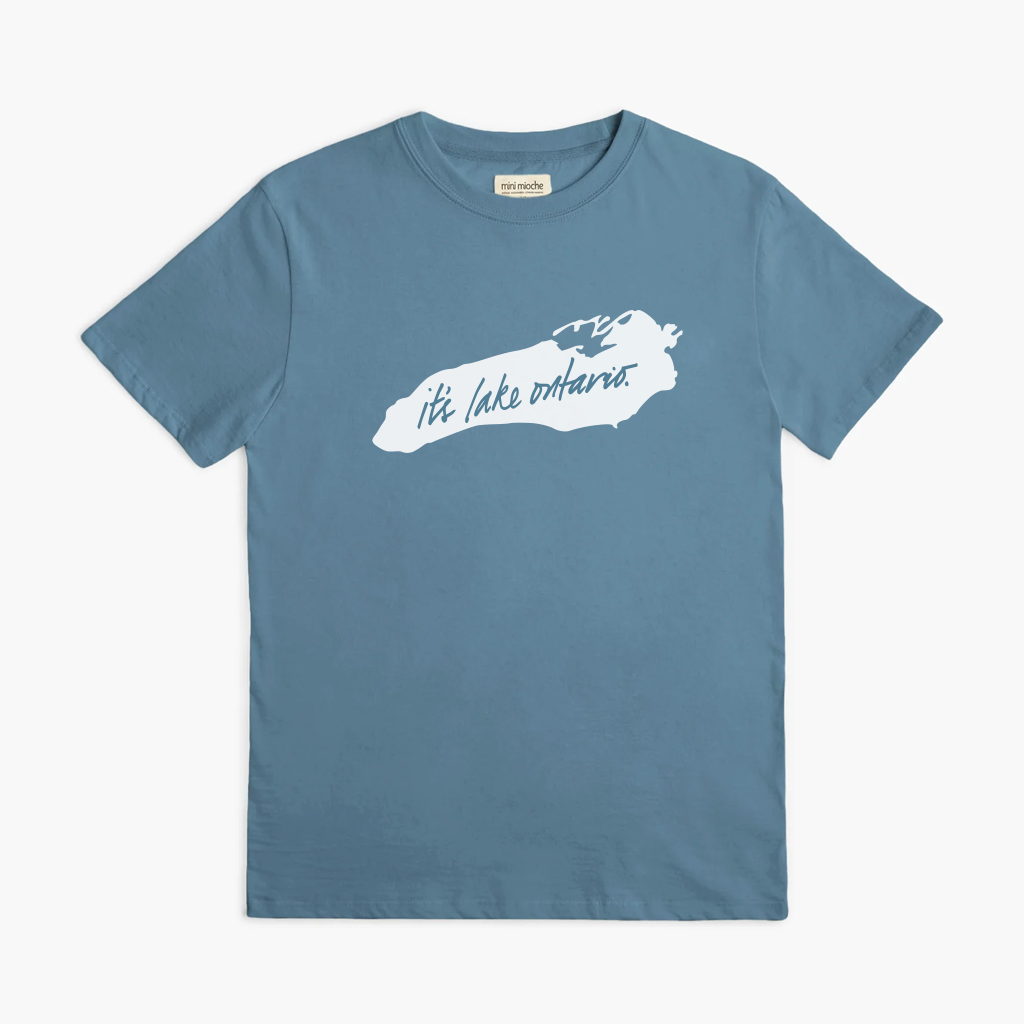
Mini Mioche ‘Lake Ontario’ shirt. Image supplied
Community Partnerships Support Brand Identity
Mini mioche’s community engagement extends beyond its new retail space. The company has developed partnerships with Canadian organizations, including True North Aid and Rethink Breast Cancer, incorporating charitable initiatives into its product development and marketing.
Corbett said mini mioche donated approximately $40,000 worth of clothing to children in northern and remote Indigenous communities affected by wildfires during the summer. The company also created an “It’s Lake Ontario” T-shirt collection, directing net proceeds to True North Aid. The initiative generated an unexpectedly strong response, with Corbett saying the adult version sold out within 24 hours of its initial release, prompting the company to produce additional inventory.
Mini mioche also partnered with Rethink Breast Cancer on a hoodie and jogger collection, with net proceeds supporting the organization’s work with young women affected by breast cancer. These initiatives form part of the company’s broader positioning around people, planet and play, which Corbett said guides its approach to manufacturing, product development and community involvement.
Additional Retail Locations Under Consideration
With the Leslieville flagship now operating, Corbett is considering whether mini mioche could support additional physical stores as the company looks toward 2027.
She said the early customer response has exceeded her expectations, particularly from existing customers reconnecting with the brand and new shoppers discovering it for the first time.
“I’ve been pretty blown away by the response in the community and our existing customers and new customers also discovering the brand,” Corbett said.
She has been working regularly in the store, observing customer behaviour and learning how the new format performs. Those experiences will help inform the company’s next decisions about physical retail.
Although no additional locations have been confirmed, Corbett said further expansion is something she intends to explore.
“I think there’s a lot of potential in this brand,” she said, pointing to what she sees as a shortage of Canadian-owned alternatives in the children’s apparel market.
For now, Corbett is focused on the Leslieville location, where the initial reception has encouraged her to consider how physical retail could contribute to mini mioche’s next stage of growth.
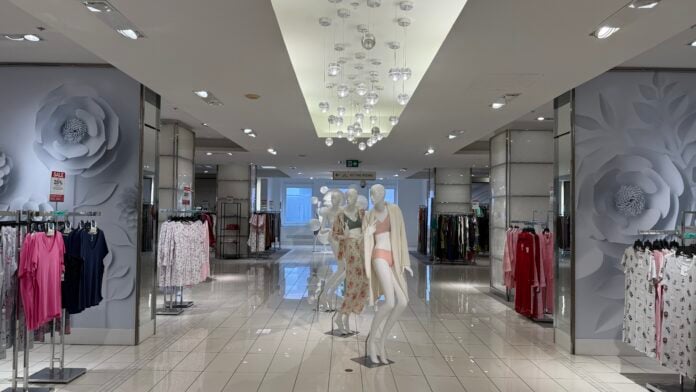
Former women's fashion department on the fourth floor of Hudson's Bay, Queen St., Toronto, March 2025. Photo: Craig Patterson/Retail Insider
By Tanishah Nathoo and Anna Racovali
A new audience analysis reveals that Hudson’s Bay’s women’s clothing shopper was among the more affluent consumer segments in Canadian retail, leaving behind significant purchasing power that no single retailer has yet fully captured.
A year after Hudson’s Bay closed its doors, much of the discussion has focused on real estate. Less attention has been paid to the customers themselves.
This article is the second in a series examining displaced HBC audiences by department. While the men’s apparel shopper reflected Canada’s growing suburban family market, the women’s apparel shopper tells a different story. She is older, more affluent and more likely to represent an established household with significant spending power. Understanding who she is helps explain why replacing HBC’s role in the market may be more difficult than replacing its real estate.
We developed a profile of Canadians most likely to purchase women’s apparel at Hudson’s Bay using a combination of Environics Analytics (EA) data assets. The analysis draws on demographic insights from DemoStats, consumer attitudes from Social Values and retail purchasing behaviour from Opticks Powered by Vividata. The resulting portrait challenges some perceptions of the traditional department store shopper and offers insight into one of the more affluent consumer segments in Canadian retail.
An Affluent Customer Base and Established Shopper
The defining characteristic of the HBC women’s apparel shopper is affluence. More than half of households associated with this audience earn over $100,000 annually. Nearly one quarter earn more than $200,000 annually, making them 34 percent more likely than the average Canadian household to fall into this income bracket (Index: 134). Households earning more than $300,000 annually are even more overrepresented (Index: 150). Average household income reaches $156,304, compared with a Canadian benchmark of $136,319.
This represents a consumer with meaningful discretionary income and the ability to spend across apparel, beauty, footwear and household categories.
Compared with the previously profiled men’s apparel customer, the HBC women’s apparel shopper skews mature and more established. The average age of this shopper is 44.4 years compared with 42.1 nationally, while household maintainers average nearly 58 years old. Households led by consumers aged 75 and older are significantly overrepresented (Index: 129) as well.
This is an established life-stage consumer with brand affinity and long-term shopping habits. That helps explain why Hudson’s Bay remained relevant to this audience even as department stores struggled to attract younger shoppers.
Former women’s fashion department on the fourth floor of Hudson’s Bay, Queen St., Toronto, March 2025. Photo: Craig Patterson/Retail Insider
Value Over Price
Compared with the average Canadian, HBC women’s apparel shoppers place greater importance on brands, status and how purchases reflect personal identity. They over-index for variables such as Importance of Brand (Index: 113), Consumption Evangelism (Index: 111) and Ostentatious Consumption (Index: 110).
This audience also appears to distinguish between value and price. While shoppers strongly over-index for Saving on Principle (Index: 126), they under-index for Importance of Price (Index: 77). They appreciate a good deal but are not simply looking for the lowest possible price.
This insight helps connect the shopper profile to the retail affinity data. The retailers most closely associated with HBC women’s apparel shoppers tend to offer recognizable brands, consistent assortments or strong value propositions. These shoppers appear to be seeking confidence that a purchase will be worth the money spent.
Income, housing and family structure reinforce the picture of a financially established customer.
More than 73.4 percent of households in this audience own their homes, compared with 65 percent nationally (Index: 112). Family households with children are also overrepresented (Index: 107).
Taken together, age, income, home ownership and household size point to an audience that is financially established rather than emerging. These consumers manage larger household budgets and spend across a range of categories.
For Hudson’s Bay, women’s apparel was rarely an isolated purchase. It existed alongside beauty, footwear, accessories, home décor and gifting. The spending opportunity extended well beyond clothing alone.
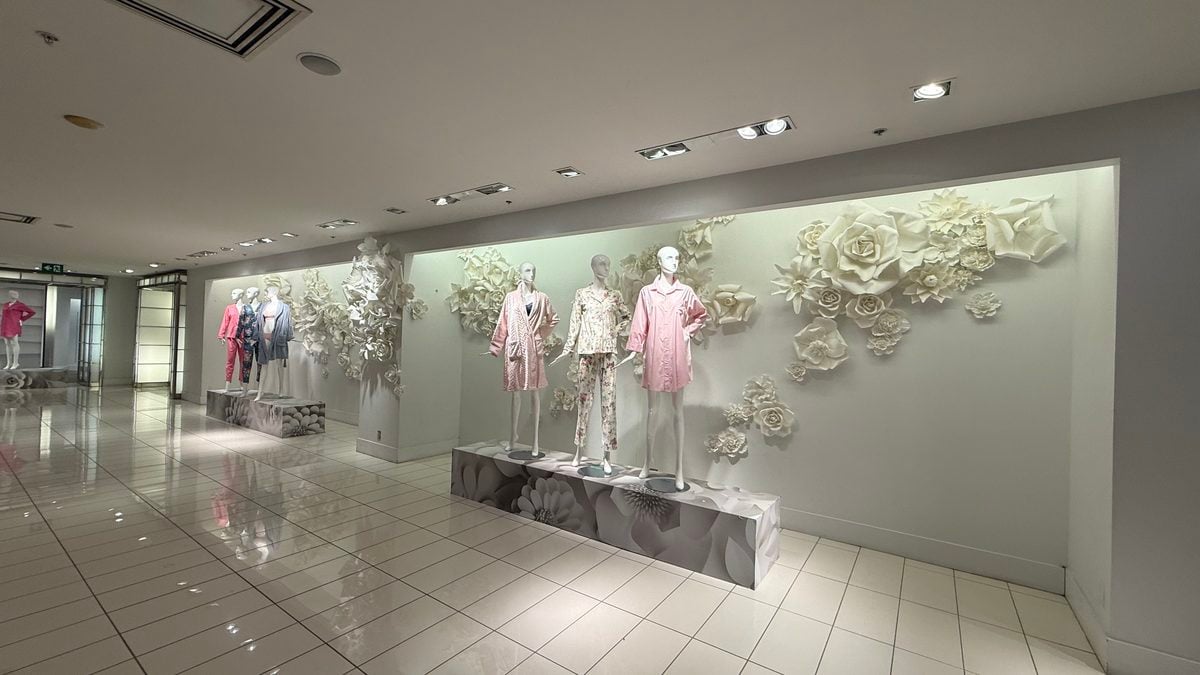
Former women’s ‘The Room’ designer fashion department on the third floor of Hudson’s Bay, Queen St., Toronto, March 2025. Photo: Craig Patterson/Retail Insider
Diverse consumers account for 44.5 percent of these shoppers, significantly higher than the national average of 29.2 percent (Index: 153). South Asian consumers represent the largest diverse segment at 11.5 percent of the audience, followed by Chinese consumers at 8.9 percent, Black consumers at 5.5 percent and Filipino consumers at 4.8 percent. First-generation Canadians account for nearly half of the audience, with an index of 153 against the national benchmark.
The result is a customer base that is simultaneously affluent, established and reflective of Canada’s increasingly multicultural consumer market.
Where HBC Women’s Apparel Shoppers Already Shop
Retail behaviour data provides insight into which retailers already had meaningful relationships with HBC shoppers purchasing women’s apparel before the chain’s closure. These relationships offer clues about which banners have an existing connection with this audience.
Several retailers attract a substantial number of HBC women’s apparel shoppers and show stronger-than-average appeal among this group. Aritzia (Index: 118), Zara (Index: 112) and Gap (Index: 112) all demonstrate stronger-than-average relationships with this audience.
Larger retailers capture even greater shopper penetration. Winners (12.4 percent) and Walmart (12.8 percent) have the largest reach among retailers in this audience. Costco’s reach is also notable, outperforming both H&M and Old Navy and reinforcing that value-oriented retailers are central to this audience alongside fashion-focused specialty chains.
No retailer appears positioned to fully replicate the role Hudson’s Bay once played. Instead, the HBC women’s apparel shopper hasn’t found a single replacement retailer. She’s assembled a replacement portfolio.
The pull of smaller retailers such as Laura/Laura Petites (Index: 123) and Northern Reflections (Index: 139) reinforces the finding that older, established female shoppers remain an important segment within the audience. At the other end of the spectrum, Melanie Lyne (Index: 82) shows below-average affinity with this audience, suggesting it serves a different customer base.
Former women’s fashion department on the fourth floor of Hudson’s Bay, Queen St., Toronto, March 2025. Photo: Craig Patterson/Retail Insider
Implications for the Market
The profile of the HBC women’s apparel shopper reveals a consumer segment that is affluent, established, family-oriented and culturally diverse. Despite the attractiveness of this audience, there is no obvious single successor to the role Hudson’s Bay once played.
The challenge extends beyond replacing a fashion retailer. Hudson’s Bay served as a convenient destination for a broad range of household purchasing needs. Apparel may have brought these consumers into the store, but the broader relationship extended into beauty, footwear, accessories, home and other categories.
This fragmentation creates an opening for retailers seeking to attract former Hudson’s Bay shoppers. Retailers offering relevant brands, service, convenience and value may be positioned to capture a greater share of this audience over time.
While Hudson’s Bay has left the market, its former customers and their spending power remain. Building relationships with these consumers will depend on understanding the combination of merchandise, service and value that made the department store relevant to them.
Methodology
This analysis draws on three data sources from EA, applied to the audience of confirmed HBC women’s clothing shoppers identified through Opticks Powered by Vividata.
Opticks Powered by Vividata is one of Canada’s leading syndicated studies for single-source data on print readership, non-print media exposure, product usage and lifestyles, giving users access to comprehensive consumer insights across media, retail, lifestyle and behavioural topics. We defined HBC women’s clothing shoppers as respondents who confirmed purchasing women’s clothing at Hudson’s Bay in the prior twelve months.
DemoStats features variables, including both averages and distributions, on population, family structure, household size and type, ethnic diversity, labour force participation and income. For this analysis, household type, family structure, immigration status, language, housing tenure and income were used.
SocialValues is a Canadian psychographic product that measures the propensity to hold underlying beliefs, motivations and personal mindsets that influence consumer and community behaviour.
All index values compare the HBC women’s clothing audience to the Canadian national average. An index of 150, for example, indicates that a given characteristic is 50 percent more prevalent in this audience than in the general Canadian population. Index values are calculated using Opticks Powered by Vividata, Social Values, DemoStats and PRIZM®.
Former women’s ‘The Room’ designer fashion department on the third floor of Hudson’s Bay, Queen St., Toronto, March 2025. Photo: Craig Patterson/Retail Insider
Want to understand who these shoppers are in your market? Reach out to Tanishah Nathoo (Tanishah.Nathoo@environicsanalytics.com) or Anna Racovali (Anna.Racovali@environicsanalytics.com) at Environics Analytics to explore a deeper analysis of the HBC women’s apparel shopper. We can help uncover where these consumers live, how they shop and identify opportunities to better align your strategy.
Executive Perspective
“What stands out most about this audience is the combination of affluence, household influence and established shopping behaviour. The Hudson’s Bay women’s apparel shopper is not simply buying clothing. She often makes purchasing decisions for her household across multiple categories and has the financial means to be selective about where she shops. The data shows a consumer who values trusted brands, quality and perceived value over chasing the lowest price. That helps explain why replacing Hudson’s Bay is so difficult. Retailers can replicate parts of the experience, whether through assortment, service, value or convenience, but very few replicate the entire proposition. The opportunity is not simply to capture a clothing shopper. It is to earn a place in the shopping journey of one of Canada’s most affluent and influential consumer segments.”
Woman shopping in a store while on her phone. Image: Unsplash/licensed
Canadian retailers have invested heavily in mobile applications, loyalty programs, e-commerce platforms and digital services designed to improve convenience and strengthen customer relationships. However, new research from Samsung Canada suggests consumers are experiencing considerable frustration managing technology, raising questions about whether some digital shopping experiences have become unnecessarily complicated.
According to Samsung Canada’s Productivity Gap research, released September 22, 75% of Canadians say technology helps them get things done faster, while 68% say it also gives them more to manage. The findings reveal a tension between the convenience technology provides and the additional tasks involved in managing multiple applications, information and digital communications.
Although the survey examined Canadians’ everyday experiences with technology rather than retail specifically, Samsung says the findings have implications for businesses developing digital customer experiences. The research was conducted through an online survey of 1,547 Canadian adults between August 31 and September 2, 2026, with results weighted by age, gender and region.
“More technology doesn’t automatically make the customer experience simpler. Apps, accounts and loyalty programs can all add value, but if each one piles on new tasks for the consumer to manage, the technology can start working against the convenience it was intended to create,” said Tarik Akad, Vice President of the Mobile Experience Division at Samsung Canada, in written responses provided to Retail Insider.
Retail Apps and Loyalty Programs Under Scrutiny
Retailers increasingly use digital platforms to encourage repeat purchases, deliver personalized promotions and connect physical stores with online shopping channels. Mobile applications and loyalty programs can provide benefits, including access to discounts, rewards and purchasing information, but they also require consumers to manage accounts, passwords and offers.
Samsung’s research found that 57% of Canadians agree the more digital tools they use, the more they have to manage. Meanwhile, 70% reported that searching for information they had previously received or seen creates unnecessary effort or slows them down at least a few times per week, while 62% reported similar difficulties when switching between applications or services.
While these findings do not specifically measure retail shopping experiences, they raise questions about the cumulative demands of managing multiple retailer accounts and loyalty memberships. A digital coupon, for example, may provide savings, but customers must first locate the offer, understand its conditions and ensure it is available when completing a purchase.
Akad said retailers should examine how their digital services work together and identify opportunities to eliminate unnecessary steps. He suggested evaluating whether applications make shopping easier, customer accounts simplify transactions and loyalty benefits are readily accessible.
For retailers, the challenge is ensuring digital services deliver sufficient practical value to justify the interactions they require. Ease of use deserves consideration alongside personalization, loyalty participation and other measures of digital engagement.
Notification Overload Raises Questions for Retail Marketing
Digital communications represent another potential source of customer frustration, particularly as retailers use email, mobile applications and loyalty platforms to deliver promotional messages. Samsung’s survey found that 77% of Canadians experience unnecessary effort or delays from managing messages and notifications at least a few times per week, although the finding covers digital communications generally.
“Every notification is a request for a customer’s attention, so it needs to earn that attention,” Akad told Retail Insider. He said businesses should prioritize the relevance and timing of communications, ensuring messages provide useful information without unnecessarily adding to consumers’ daily demands.
Personalized offers, loyalty reminders and promotional announcements can provide value when they address an immediate need, but frequent contact does not necessarily translate into a better customer experience. For retail marketers, the issue is balancing engagement objectives with the risk that excessive or poorly timed messages become another source of frustration.
Akad said retailers should consider whether each communication helps customers accomplish something or simply gives them another task to manage. That assessment can inform how retailers manage promotional frequency, notification preferences and the relevance of messages delivered through different channels.
Digital Friction Has Commercial Consequences
Independent research into e-commerce usability suggests complicated digital experiences can interfere with completed purchases. The Baymard Institute, which studies online shopping behaviour and checkout design, has identified required account creation and lengthy checkout processes among the reasons consumers abandon transactions.
In Baymard’s 2026 research, 18% of surveyed US online shoppers who abandoned purchases for reasons other than simply browsing cited required account creation, while 17% cited checkout processes that were too long or complicated. Although these findings are not specific to Canada, they illustrate how unnecessary requirements can become barriers during online purchasing.
For Canadian retailers operating physical stores and e-commerce platforms, similar usability considerations can extend across the shopping journey. Customers may research merchandise online, check store inventory, access loyalty benefits and complete purchases through different systems, with each interaction potentially requiring additional information or effort.
Improving the connections between those services could help retailers reduce customer frustration while making better use of existing digital investments. The opportunity is particularly relevant for businesses pursuing omnichannel strategies that depend on customers moving between online and physical shopping experiences.
Artificial Intelligence Could Reduce Repetitive Tasks
Samsung believes artificial intelligence could help address some of the frustrations associated with managing multiple applications and digital services. Its research found that 66% of Canadians selected at least one AI-enabled feature they considered potentially valuable for completing tasks with less effort, although the results do not measure actual productivity improvements.
Akad said AI could help make shopping feel less like a series of separate digital tasks and more like a connected experience. He pointed to opportunities for AI to assist consumers with product research, comparing merchandise, identifying offers and tracking purchases.
As these capabilities develop, they could help users move between activities without repeatedly searching for information or switching applications. Samsung is developing AI-enabled mobile features intended to make information and suggested actions more accessible across supported services, including its Now Nudge functionality.
The research also found that 58% of Gen Z respondents agreed they spend too much time completing manual steps simply to make technology work. Akad said the finding challenges the assumption that familiarity with digital technology necessarily means consumers experience fewer frustrations.
For retailers, the potential application of AI extends to improving how customers interact with existing digital services. However, adding AI capabilities will not necessarily resolve problems created by complicated account requirements, disconnected loyalty programs or poorly designed purchasing processes.
Making Existing Technology Work Better
Samsung’s findings arrive as retailers continue exploring AI, personalization and connected digital services to improve customer experiences. For businesses already operating multiple digital platforms, there may be opportunities to improve convenience through better integration and simpler interactions.
“Rather than adding more AI-enabled features for the sake of it, retailers should start with the customer need and work backward,” Akad said. His comments suggest that decisions about mobile applications, loyalty programs, checkout requirements and customer communications should begin with the tasks consumers are trying to complete.
Retailers can evaluate those investments against practical measures such as completed transactions, customer support requests, account participation and the steps required to access benefits. Identifying where customers encounter unnecessary effort could help businesses prioritize improvements to existing systems before committing additional resources to new features.
RBC Canadian cardholders continued spending in September, but the three month average growth softened, says a new report by the bank.
“Our estimate of core retail sales, excluding gasoline and autos, rose 0.4% on a three-month average, down slightly from 0.6% in August. Discretionary services once again led spending with gains across a range of categories,” said the report by economists Abbey Xu and Rachel Battaglia.
“Purchases of essentials also remained positive excluding gasoline. However, discretionary goods were broadly flat on a three-month average despite an increase in September and continued growth in clothing purchases.
“The latest spending data remains consistent with gradual growth in Canadian household demand. Expected improvements in household incomes and the labour market should provide support, although elevated energy costs continue to weigh on purchasing power. Trade uncertainty remains a downside risk, particularly for households in directly affected industries and regions.”
Abbey XuRachel Battaglia
RBC outlined some details on consumer spending:
Discretionary services’ spending rose 1% on a three-month average, easing from 1.5% in August, but remaining the strongest major category. Education, entertainment and travel-related spending all contributed to growth. Entertainment and arts spending increased 1.4%, travel rose 1%, and dining grew a more modest 0.3%.
Essentials spending increased 0.6% with gasoline accounting for roughly one-third of the gain. Spending excluding gasoline also continued to grow, supported by groceries and utilities.
Gasoline spending increased 2.6% in September, alongside a roughly 7.9% seasonally adjusted rise in gasoline prices. Higher spending at the pumps, therefore, needs to be viewed in the context of sharply higher fuel costs.
Discretionary goods spending edged down 0.1% despite rising 1.4% in September. Clothing, shoes and related apparel were a bright spot, increasing 1% on a three-month average, while household and construction-related spending grew 0.3%.
Spending rose across all provinces on a three-month average. Prince Edward Island and Newfoundland and Labrador posted the strongest gains, followed by New Brunswick. Ontario recorded the smallest increase, while Manitoba, Nova Scotia, Saskatchewan and Alberta exceeded the national pace.
Retail staffing and employment, jobs. Photo: RetailNext
Canadian retailers spend considerable resources recruiting and training employees, only to repeat the process when those workers leave. For businesses operating with relatively small store teams, the continuing cycle of recruitment, onboarding and replacement creates expenses that extend beyond wages and benefits, while the loss of experienced staff can affect productivity and customer service.
Suzanne Sears, owner of Best Retail Careers, believes retailers need to pay greater attention to retaining the employees they already have. In an interview with Retail Insider, she said businesses frequently absorb the expense of replacing departing workers while overlooking opportunities to improve retention through training and career development.
Sears has been encouraging retailers to explore government-supported training programs, particularly smaller businesses with limited resources for employee development. Her argument comes as Canadian industry research continues to identify retail as a sector facing comparatively high employee turnover and persistent challenges attracting and retaining workers.
Suzanne Sears
Retail Employee Turnover Remains Elevated
Mercer’s 2025 Canada Turnover Survey reported voluntary turnover of approximately 21% among retail and wholesale employers, compared with 10.2% across the industries surveyed. The research covered 1,057 Canadian organizations and provides an indication of the workforce challenges facing the sector, although the figure combines retail and wholesale businesses rather than measuring storefront retail alone.
Sears estimates that employee turnover in retail is approximately 25%, describing the repeated departure and replacement of workers as a significant operating expense. Her estimate is not directly comparable with Mercer’s findings, but both point to the importance of understanding why employees leave and what businesses can do to retain them.
The consequences vary considerably by retail category and the positions involved. A retailer replacing an experienced employee in luxury apparel, electronics or another specialty category may lose product knowledge and established customer relationships that take time to rebuild, particularly in stores where personalized service is central to the business model.
For smaller retailers, employee departures can also disrupt daily operations because fewer workers are available to absorb additional responsibilities. Recruitment becomes another task for owners and managers already overseeing sales, inventory, staffing and customer service.
The Cost of Replacing Retail Employees
The expense of employee turnover extends beyond job advertisements and recruitment fees. Retailers must review applications, conduct interviews, train replacements and accommodate the period during which new employees are learning their responsibilities.
“The constant filling of vacancies, constant,” Sears said, describing the repeated hiring process. She pointed to the time spent reviewing applications and the disruption created when managers or experienced employees must step away from selling to interview prospective workers.
Across a multi-store operation, those activities can become a recurring expense throughout the year. The impact may be particularly significant when departures involve employees requiring specialized product knowledge, technical training or established relationships with regular customers.
Academic research into employee turnover has identified costs associated with understaffing, onboarding and workplace disruption following employee departures. The financial impact varies among employers, however, and there is no reliable universal replacement cost that applies to every retail position.
For individual retailers, a more useful measure may be the total time and expense devoted to replacing employees over a year. Those costs can then be considered alongside investments that might improve retention, including training, career development and improvements to working conditions.
Why Employees Leave Retail
Employee departures are influenced by several factors, including compensation, scheduling, workload and opportunities for advancement. Retail’s reliance on part-time and entry-level positions can also contribute to the perception that the industry offers temporary employment rather than long-term careers.
Research commissioned by the Retail Council of Canada examining Alberta’s retail labour market identified challenges involving starting wages, shift schedules and limited career progression. The study also pointed to gaps in structured training and professional development, suggesting that employers face difficulties demonstrating the longer-term opportunities available within the industry.
Sears believes retention problems can intensify when businesses leave positions vacant after employees depart. Remaining workers may be expected to maintain the same service standards while assuming additional responsibilities, potentially increasing dissatisfaction and contributing to further departures.
“If a store used to have four and now they have three, it might not be perceivable to the consumer,” Sears said. She explained that employees would recognize the difference because the workload previously divided among four people would now fall on three.
The example illustrates the tension retailers face when managing labour expenses. Allowing staffing levels to decline through attrition may reduce immediate payroll costs, but it can also place greater pressure on experienced employees whose departure would create additional recruitment and training expenses.
Training and Career Development as Retention Strategies
Sears believes retailers could improve retention by providing employees with greater opportunities to develop professional skills and advance within the industry. Workers who see a future with their employers may be more inclined to remain, particularly when training leads to qualifications they can use throughout their careers.
“Because they feel that you’re investing in them,” Sears said when discussing the effect professional development can have on employees. She suggested that access to recognized courses could help workers view retail as a profession with opportunities for advancement.
Canadian research provides some support for that argument. A longitudinal study involving more than 5,200 for-profit firms found an association between offering a wider range of formal training programs and lower voluntary turnover, although the relationship varied according to the type and extent of training.
Separate research involving more than 50,000 retail sales associates found that online product training was associated with improved sales productivity. The findings suggest employee development can provide operational benefits beyond retention, particularly in retail formats where product knowledge and customer assistance influence purchasing decisions.
Training does not eliminate other reasons employees leave. Compensation, scheduling, management practices and working conditions remain important considerations, and professional development is unlikely to compensate for persistent problems in those areas.
For retailers investing in more sophisticated physical environments and personalized customer experiences, maintaining knowledgeable employees can be particularly important. The quality of service delivered within those stores depends partly on workers having the training and experience needed to meet customer expectations.
Ontario Job Grant Offers Financial Support for Training
Government funding could make professional development more accessible to retailers with limited training budgets. Sears has been encouraging business owners to explore available assistance, arguing that many may be unaware of opportunities to offset eligible employee-development costs.
The Ontario Job Grant, introduced under its current name in May 2026, provides financial assistance for eligible training delivered by approved third-party providers. Under the program’s published rules, assistance can reach $10,000 per eligible trainee in standard circumstances, while funding of up to $15,000 is available to qualifying smaller employers training newly hired workers who were previously unemployed.
The higher amount does not apply automatically to businesses seeking to train existing employees. Employers must satisfy eligibility requirements, contribute toward training costs where required and obtain approval before the funded training begins.
For businesses with fewer than 100 employees, the standard contribution is generally at least one-sixth of eligible training costs. Employers with 100 or more employees generally contribute half, while qualifying smaller employers training previously unemployed new hires may be eligible for full funding within the program’s limits.
The province is accepting applications from individual employers for training involving 25 or fewer participants. Funding remains subject to assessment and budget availability, and meeting the eligibility requirements does not guarantee approval.
Sears described helping retailers explore opportunities involving courses associated with Toronto Metropolitan University. She said approximately 10 businesses had recently signed up through her efforts, although the specific courses, program arrangements and funding approvals have not been independently confirmed.
For retailers considering these opportunities, the starting point is to determine which training programs are eligible and how much assistance may be available. Employers must also consider whether the courses meet their operational needs and provide qualifications or skills that employees can apply in their work.
Sears believes these programs could be especially useful for smaller businesses, where replacing experienced staff can create substantial disruption. Government assistance may reduce some training expenses, but retailers still need to determine whether the investment supports their longer-term staffing and business objectives.
Retention as an Operating Priority
Independent retailers often have fewer resources for recruitment and employee development than national chains. Owners and store managers may handle hiring alongside merchandising, customer service and daily operations, making repeated employee departures particularly disruptive.
Experienced employees can contribute to store performance through product knowledge, established customer relationships and familiarity with operating procedures. Replacing those capabilities requires time, even when a retailer can fill a vacant position relatively quickly.
The financial case for retention will differ among businesses. Retailers need to assess employee turnover, recruitment expenses and training requirements alongside compensation, scheduling and the working conditions that influence whether employees remain.
Sears believes employers should begin by reconsidering how much they invest in the people already working for them. “If you’re gonna hang on to the people you have, you have to invest in them,” she said.
As Canadian retailers continue investing in store renovations, expansion and customer-facing technology, workforce development represents another area where spending decisions can influence operating performance. For businesses facing repeated recruitment and replacement costs, keeping experienced employees may prove just as important as finding new ones.
Golf Town is investing $15 million in a new 40,000-square-foot flagship store in Oakville, Ont., marking its 50th Canadian location as the specialty golf retailer looks to expand its retail footprint and enhance its in-store experience.
The store, located at 290 North Service Road West, is two and a half times the size of a standard Golf Town location and is intended to serve as a model for future flagship stores across the country, alongside ongoing renovations to existing locations and growth in e-commerce.
The opening marks a new phase of development for the retailer, which has operated in Canada since 1999. The Oakville location combines traditional golf equipment and apparel sales with simulator technology, custom fitting services and interactive putting facilities.
New format combines retail and golf experiences
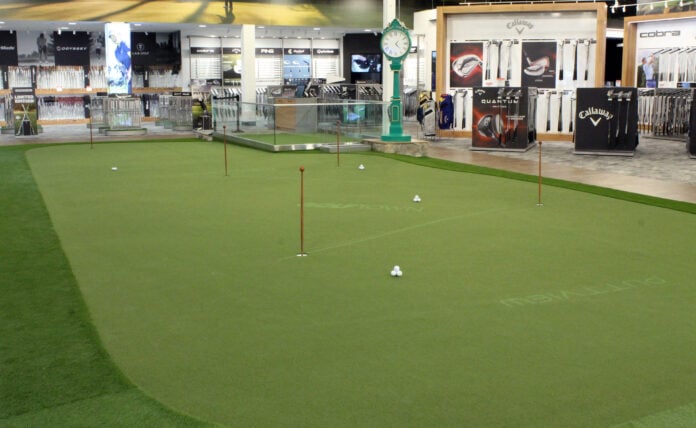
The flagship store features two StudioX custom fitting bays equipped with Zen Green moving-platform technology, which replicates real-world green slopes and breaks, as well as Quintic putter-fitting technology. Five Foresight simulator bays are also available.
The location includes a 1,300-square-foot putting green, four times the size of those in standard stores, and Golf Town’s first dual-projector PuttView installation, which provides an interactive visual putting experience.
“For more than 25 years, Golf Town has been the ultimate home for Canadian golfers both in-store and online,” said Williams. “Our new flagship store marks an exciting step forward in our evolution, offering a welcoming destination for golfers of all levels to gather, gear up, and fall in love with the game.”
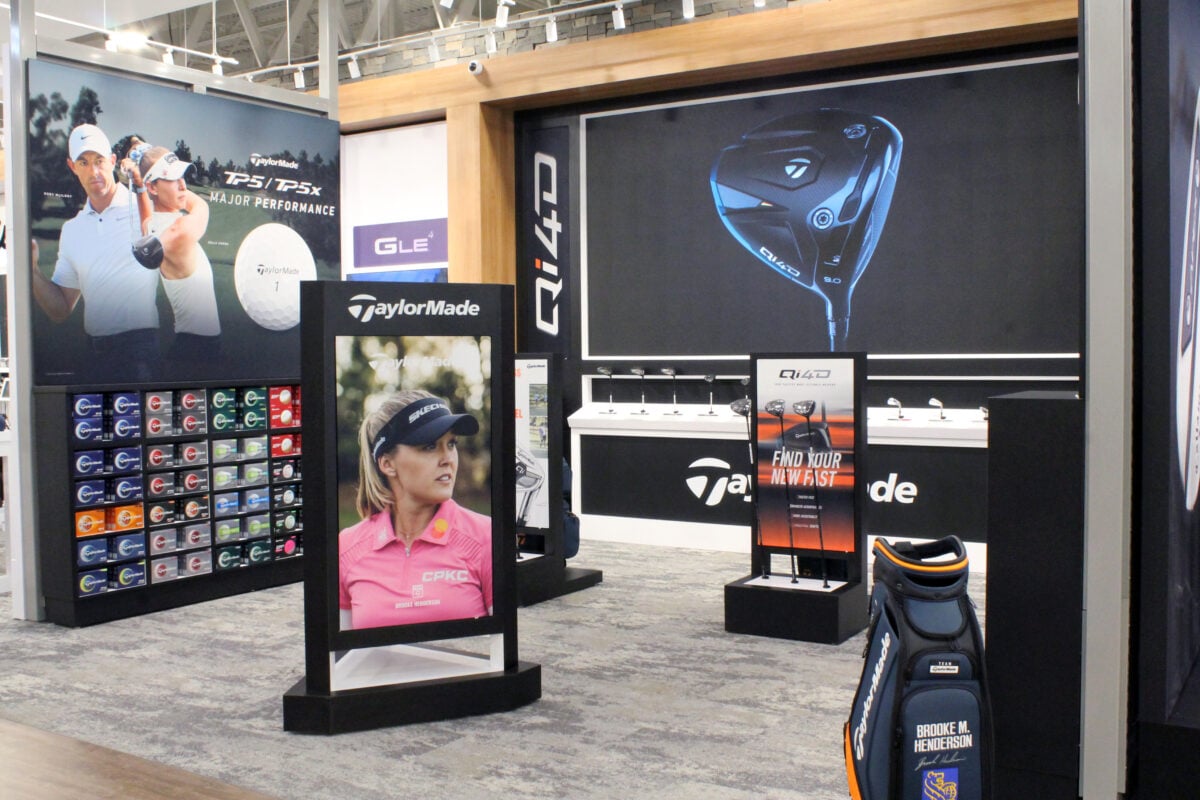
The store also features dedicated retail spaces for TaylorMade, Callaway, Odyssey, PING and Titleist. Customers will have access to limited-edition equipment and tour-only products, including Scotty Cameron Circle T putters.
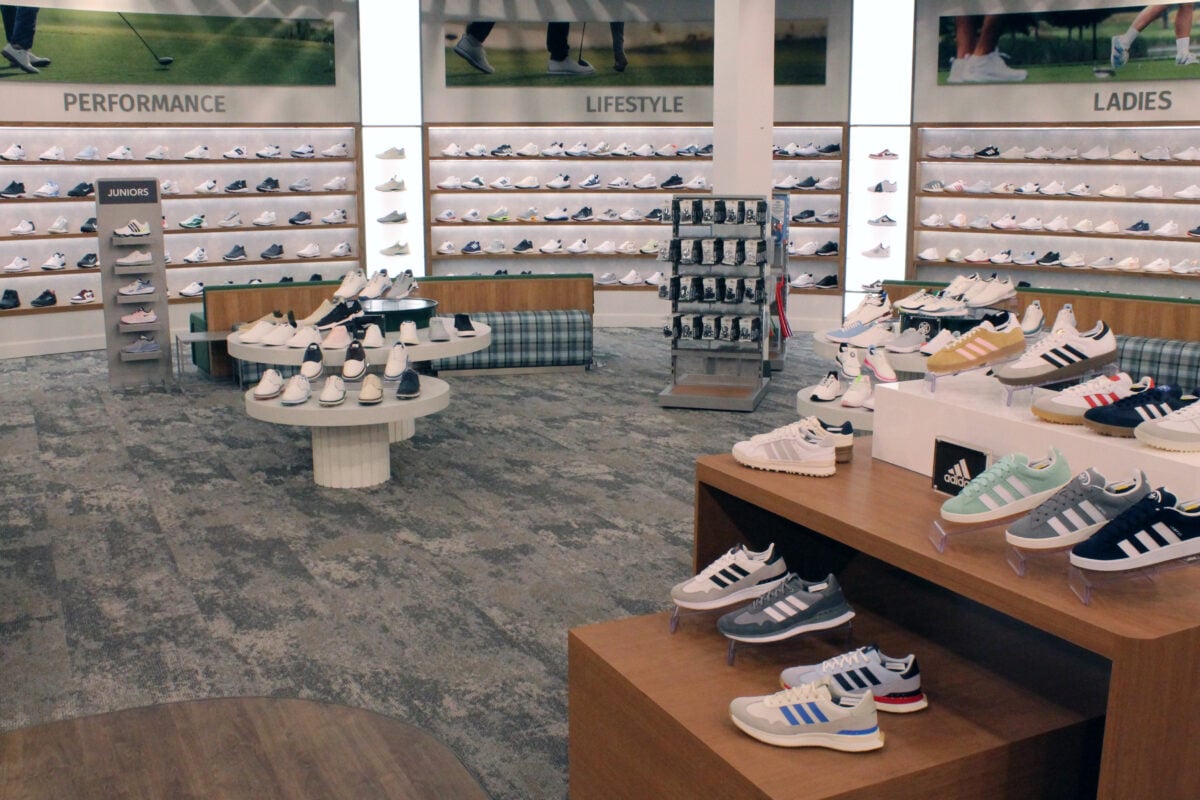
A staffed personalization lab offers custom wedge stamping, golf ball logo printing and other equipment customization services. The store’s footwear department includes FootJoy’s FJ FitLAB system, which uses a three-dimensional volumetric scanner and a multi-camera system to map foot measurements for shoe fittings.
Golf Town photo
Expanded apparel and women’s golf offerings
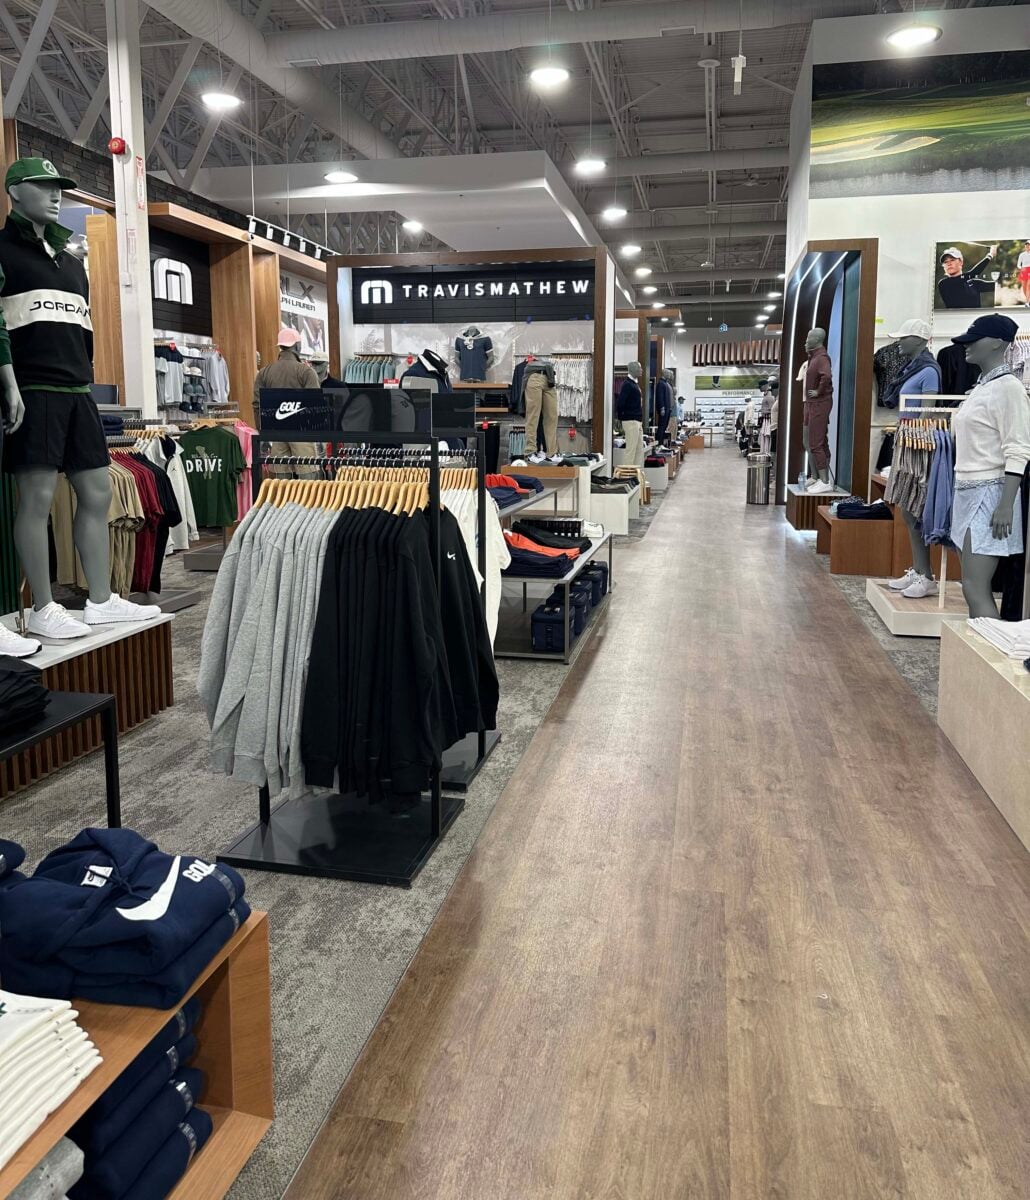
The Oakville location also has an expanded apparel department, with brands including Johnnie-O, Beach Riot, Holderness & Bourne, RLX, Peter Millar, TravisMathew, Nike and Jordan. Some brands, including Johnnie-O, Beach Riot and Holderness & Bourne, are offered as store exclusives, according to the company.
A redesigned women’s department features an expanded assortment for female golfers, forming part of the retailer’s broader investment in the new store format.
The location incorporates Canadian golf references, including putting green cups identical to those used at Cabot Cape Breton and imagery of golf courses throughout the store.
Grand opening set for Oct. 17-18
Golf Town plans to mark the opening with a two-day event on Oct. 17 and 18. The company says customers lining up on either day will receive $50 cash cards, while hourly prize giveaways from golf industry brands will have a combined value of more than $20,000.
The store will be open from 8 a.m. to 8 p.m. on both days.
Golf Town operates under Sporting Life Group, a Canadian retail company that also includes Sporting Life and Team Town Sports. The group operates 14 Sporting Life stores across major Canadian cities, while Team Town Sports serves customers shopping for team sports equipment and related products.
Golf Town is owned by Fairfax Financial Holdings Ltd. and operates both physical stores and an online retail business through its website.
The Oakville flagship is designed to serve as a prototype for potential future flagship locations nationwide, while the company continues to renovate its existing stores and develop its e-commerce business.
Reitmans (Canada) Limited has announced a five-year partnership with Food Banks Canada to provide one million meals to people facing food insecurity, as the Montreal-based apparel retailer marks its 100th anniversary.
The initiative will support Food Banks Canada, a national charitable organization that works to relieve hunger and prevent food insecurity through a network of more than 5,500 food banks and community organizations across the country.
The partnership forms part of Reitmans’ broader community engagement efforts as the company marks a century in business. The retailer said it has sought to make a positive impact beyond its stores since its founding in 1926.
“RCL started as one community store in 1926 in Montreal, and we have grown to be a part of communities across Canada for a century,” said Reitman. “Helping to provide one million meals to people in need, from coast to coast, is a meaningful way to give back to the communities that have welcomed us for generations.”
The five-year commitment is intended to help address food insecurity, which the company identified as a significant challenge facing people in Canada. Reitmans said its community involvement is based on the belief that investing in local communities helps strengthen the social fabric.
Food Banks Canada will be the organization’s partner in delivering the initiative. The charity supports food banks and community organizations nationwide, with a mandate to address immediate hunger needs while working to prevent hunger in the longer term.
“At a time when food banks across the country are facing historic demand, partnerships like this are more important than ever. With nearly 2.2 million visits to food banks each month, the need for support continues to grow in communities from coast to coast,” said Beardsley.
“We are incredibly grateful to RCL for stepping up to help meet this moment. Their generosity will help food banks provide essential support today while bringing us closer to our mission of relieving hunger today and preventing hunger tomorrow. Together, we can ensure more people in Canada have access to the food and support they need to thrive.”
The company announced the partnership on Oct. 14, coinciding with its 100th anniversary celebrations.
Claudia Galella, Vice President, Partnerships, Food Banks Canada (left), and Lisa Reitman, Vice President, Business Development & ESG, RCL (right)
Retail operations across Canada
Reitmans (Canada) Limited operates 385 stores across the country under three retail banners: Reitmans, PENN. and RW&CO. The company’s store network includes 216 Reitmans locations, 85 PENN. stores and 84 RW&CO. locations.
Founded in Montreal in 1926, the company operates in the women’s and men’s specialty apparel retail sector. Its anniversary initiative adds a national food security partnership to its community engagement activities.
A Retail Insider webinar with Insureshield by UPS Capital examines the financial and customer-service consequences of lost, damaged and stolen shipments, and how retailers can better manage delivery risks.
Lost, damaged and stolen shipments can create significant financial and operational challenges for Canadian retailers, particularly during peak shopping periods when order volumes increase. Beyond replacing merchandise or issuing refunds, businesses may face additional transportation expenses, customer-service demands and the possibility of losing future sales from dissatisfied customers.
These issues were examined during an October 7 Retail Insider webinar presented in partnership with Insureshield by UPS Capital. The discussion featured Vishav Ranjan, a business development manager with UPS Capital Canada Insurance Brokers, and explored how retailers can manage shipping risks, protect their financial interests and respond when deliveries do not go as planned.
Shipping Problems Can Affect Customer Loyalty
A central theme of the webinar was the relationship between delivery performance and customer satisfaction. Although retailers frequently rely on third-party carriers, consumers generally expect the business they purchased from to resolve problems when merchandise arrives damaged or fails to arrive.
“Customers often do not separate the retailer from the delivery experience,” Ranjan explained during the presentation. He noted that order updates, delivery communications and problem resolution all contribute to the customer’s impression of the retailer, regardless of which company handles transportation.
The importance of this relationship was reflected in two audience polls conducted during the webinar. In the first, participants identified lost shipments as the shipping risk most likely to affect their businesses during peak season. A second poll found customer dissatisfaction was the leading concern arising from lost, damaged or stolen shipments, followed by additional shipping costs and lost repeat business.
The responses illustrate the concerns of businesses participating in the discussion. For retailers investing in customer acquisition, loyalty programs and omnichannel shopping experiences, a delivery problem can undermine the customer relationship after the transaction has already taken place.
The Financial Impact Extends Beyond Merchandise
Shipping failures can affect profitability through merchandise replacement, transportation expenses and the administrative work involved in resolving incidents. Retailers may need to investigate missing shipments, communicate with customers, gather documentation and coordinate refunds or replacement orders, all while managing their regular fulfillment operations.
These expenses can be particularly significant for businesses shipping higher-value merchandise or operating with limited margins. When an order must be replaced without generating another sale, the retailer incurs additional costs while receiving no corresponding increase in revenue.
Ranjan explained that a single shipping incident can affect profit, operational effort and customer loyalty simultaneously. Businesses therefore need to consider the full cost of an incident when evaluating their exposure to shipping disruptions, particularly during periods of elevated sales activity.
Peak season can make these challenges more difficult to manage. Higher order volumes create additional activity throughout fulfillment centres and carrier networks, while increased handling and transportation demands can complicate the movement of merchandise.
Canadian e-commerce activity provides context for the scale of retail operations that depend on delivery services. According to Statistics Canada, seasonally adjusted retail e-commerce sales reached $5.5 billion in July 2026, representing 7.5 per cent of total retail trade. Although that was a 3.5 per cent decrease from June, it illustrates the substantial value of retail transactions conducted through online channels.
During the webinar, Ranjan discussed InsureShield Shipping Insurance, offered through UPS Capital Canada Insurance Brokers, as one option for managing eligible financial losses associated with shipping disruptions.
The program is designed to provide coverage for qualifying loss and damage incidents across different carriers and transportation arrangements. This can be relevant for retailers using multiple delivery providers to serve different markets, manage transportation expenses or handle international orders.
According to UPS Capital, eligible coverage can provide reimbursement of up to the full invoice value of merchandise plus associated shipping costs, subject to policy terms and limits. For retailers, this can help address the financial consequences of a qualifying loss, including the margin that would otherwise be affected by replacing the original order.
The company also offers technology options intended to simplify insurance administration. Ranjan discussed integrations involving shipping and e-commerce platforms such as ShipStation, WooCommerce and Shippo, along with API-based solutions and spreadsheet uploads for businesses with different operational requirements.
Claims administration was another focus of the presentation. Ranjan explained that InsureShield customers can initiate claims through the insurance process, although businesses must follow applicable notification and documentation requirements. UPS Capital advertises a nine-month claims-filing window and a 90-day period for reporting concealed damage.
During the webinar, Ranjan said most fully documented claims are resolved within seven days. This is a company-reported processing measure, and individual claims may take longer depending on their circumstances and the information provided.
Package theft following delivery was also discussed. Ranjan clarified that porch-piracy protection is available through an optional endorsement, meaning retailers need to confirm that it is included in their particular insurance arrangement.
Coverage depends on policy conditions, exclusions, applicable limits and geographic eligibility. UPS Capital’s Canadian website currently states that the insurance services referenced there are available to businesses operating in Ontario, so retailers elsewhere in Canada should confirm availability directly before assuming they qualify.
Managing Cross-Border Shipments and Delivery Delays
The webinar’s question-and-answer session addressed several operational situations facing Canadian retailers, including cross-border shipments, the use of multiple carriers and the distinction between delayed and lost packages.
Ranjan explained that InsureShield can provide options for eligible shipments moving between Canada and the United States, as well as certain shipments transported entirely within the U.S. for qualifying Canadian businesses. The latter arrangement, known as foreign inland transit, can be relevant when a Canadian retailer sources merchandise from an American supplier and ships directly to an American customer.
He also discussed the challenge of determining when a delayed shipment should be treated as lost. During peak season, carrier tracking information may not be updated immediately, creating uncertainty for retailers deciding whether to wait, contact the carrier or send replacement merchandise.
Customer communication is particularly important in these situations. Providing realistic delivery expectations and explaining delays can help retailers manage customer concerns while investigating the status of an order, potentially avoiding unnecessary replacement shipments.
For smaller retailers, shipping protection may need to evolve as sales volumes and delivery requirements change. Ranjan discussed reviewing coverage arrangements periodically, including shipment values, applicable minimums and policy structures, so that protection remains appropriate for the business.
Insurance can help recover eligible financial losses, but it does not eliminate the need for reliable carriers, appropriate packaging, accurate shipment records and responsive customer service. These operational practices remain important when managing delivery problems and protecting customer relationships.
Preparing for Peak Shipping Periods
The webinar offered retailers practical information about how shipping risks affect operating costs, customer satisfaction and the financial consequences of replacing lost or damaged merchandise. It also examined insurance arrangements available to businesses seeking to manage those risks.
Retailers preparing for increased order volumes can review shipment values, carrier arrangements, destinations, claims documentation and procedures for responding when deliveries are disrupted. Those considerations can help determine where shipping insurance fits within a broader fulfillment and customer-service strategy.
The full Retail Insider webinar with UPS Capital includes additional information about InsureShield Shipping Insurance, claims procedures, technology integrations and questions raised by participating retailers.
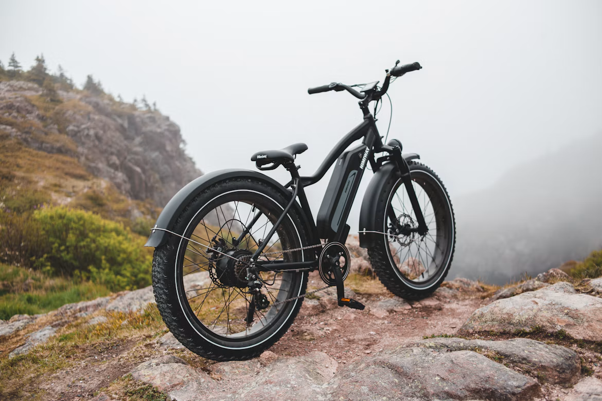
Qlife Ebike represents a revolutionary approach to personal transportation, combining the convenience of a bicycle with the power of an electric motor. In this article, we will delve into the world of Qlife Ebike, exploring its design, performance, battery life, safety features, and user experience.
Design and Aesthetics The design of Qlife Ebike is a perfect blend of style and functionality. The frame is crafted with precision, using high – quality materials that ensure both durability and a sleek appearance. For example, the aluminum alloy frames commonly used in Qlife Ebikes are not only lightweight but also resistant to corrosion, making them suitable for various weather conditions.
The overall shape of the bike is ergonomic, designed to provide maximum comfort during long rides. The handlebars are positioned at an optimal height and angle, reducing strain on the rider’s wrists and shoulders. The seat is also well – padded and adjustable, allowing riders of different heights and body types to find their most comfortable riding position.
Qlife Ebikes come in a variety of colors and styles, catering to different aesthetic preferences. Whether you prefer a classic black for a more understated look or a bright, eye – catching color like red or blue to make a statement, there is a Qlife Ebike that suits your taste.
Performance and Power One of the key highlights of Qlife Ebikes is their powerful electric motors. These motors are designed to provide smooth and efficient power delivery. For instance, a typical Qlife Ebike motor might have a power output of 250 – 500 watts, depending on the model. This power allows the bike to easily tackle hills and maintain a decent speed on flat roads.
The gear system on Qlife Ebikes is also well – engineered. It offers multiple gears, which can be adjusted according to the terrain and riding conditions. When going uphill, riders can shift to a lower gear to reduce the pedaling effort, while on flat or downhill sections, a higher gear can be selected for increased speed.
Acceleration is another area where Qlife Ebikes shine. The electric motor provides instant torque, allowing the bike to quickly pick up speed from a standstill. This is particularly useful in urban environments where riders need to navigate through traffic and make quick starts at intersections.
Battery Life and Charging The battery is a crucial component of any electric bike, and Qlife Ebikes are equipped with high – quality lithium – ion batteries. These batteries offer a long range on a single charge. On average, a Qlife Ebike can travel between 30 – 60 miles on a full charge, depending on factors such as the terrain, rider’s weight, and the level of electric assistance used.
Charging the battery is a simple process. Most Qlife Ebikes come with a standard charger that can be plugged into a regular household electrical outlet. The charging time typically ranges from 3 – 6 hours, depending on the battery capacity. Some models also support fast – charging options, which can significantly reduce the charging time.
To extend the battery life, Qlife provides some useful tips. For example, riders can avoid over – discharging the battery and keep it at an optimal temperature. Additionally, using the electric assistance at a moderate level can also help conserve battery power.
Safety Features Safety is a top priority for Qlife Ebikes. The bikes are equipped with high – quality brakes, such as disc brakes. Disc brakes offer superior stopping power compared to traditional rim brakes, especially in wet or muddy conditions. This ensures that riders can stop quickly and safely when needed.
Another important safety feature is the lighting system. Qlife Ebikes come with bright front and rear lights. The front light illuminates the path ahead, making it easier for riders to see in low – light conditions, while the rear light makes the bike more visible to other road users, reducing the risk of accidents.
Reflectors are also strategically placed on the bike, enhancing its visibility from different angles. Additionally, some Qlife Ebike models are equipped with a speed sensor that limits the maximum speed when the rider is not pedaling, ensuring a safe and controlled riding experience.
User Experience and Customer Feedback Many users have reported positive experiences with Qlife Ebikes. Customers appreciate the ease of use and the convenience these bikes offer. For example, commuters find that Qlife Ebikes allow them to avoid traffic congestion and arrive at their destinations faster than traditional vehicles.
The comfort of the ride is also highly praised. Riders with back or joint problems have found that the ergonomic design of Qlife Ebikes reduces pain and discomfort during long rides. The adjustable seat and handlebars make it easy for riders to customize the bike to their specific needs.
Qlife also provides excellent customer service. They offer warranties on their bikes and have a responsive support team that can assist customers with any issues or questions. In case of mechanical problems, Qlife has a network of authorized repair centers, ensuring that customers can get their bikes fixed quickly and efficiently.
In conclusion, Qlife Ebike is a great choice for those looking for an eco – friendly, convenient, and enjoyable mode of transportation. With its stylish design, powerful performance, long battery life, excellent safety features, and positive user feedback, it is no wonder that Qlife Ebikes are becoming increasingly popular.