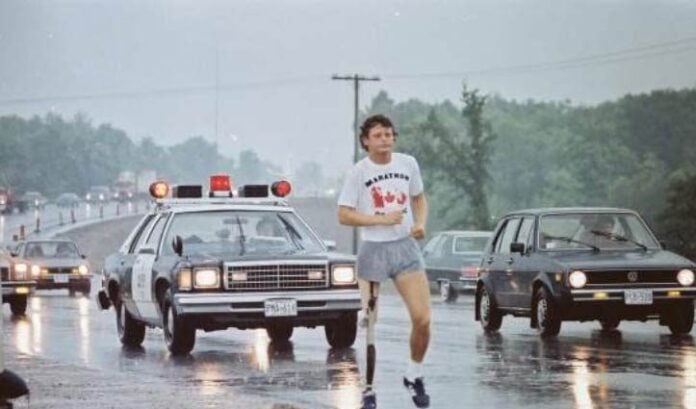
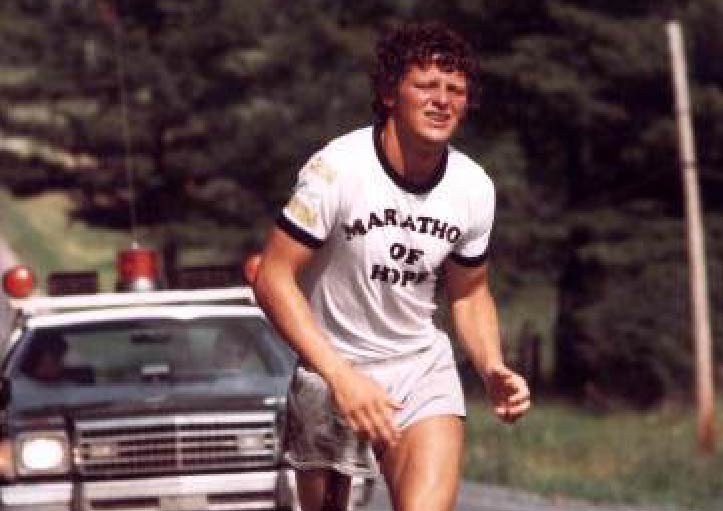
More than 260 Giant Tiger stores across Canada will each provide $500 to a local school participating in the Terry Fox School Run, bringing the retailer’s total contributions to the Terry Fox Foundation to more than $412,000 over four years.
The program, now in its second year, will provide more than $130,000 in total support to schools and their Terry Fox fundraising efforts, as Giant Tiger continues its national partnership with the Terry Fox Foundation.
The Ottawa-based retailer said the initiative connects its locally owned stores with schools and communities in the areas they serve. The company said its store owners and teams are involved in supporting local causes and that the Terry Fox Foundation is among the organizations supported through that community focus.
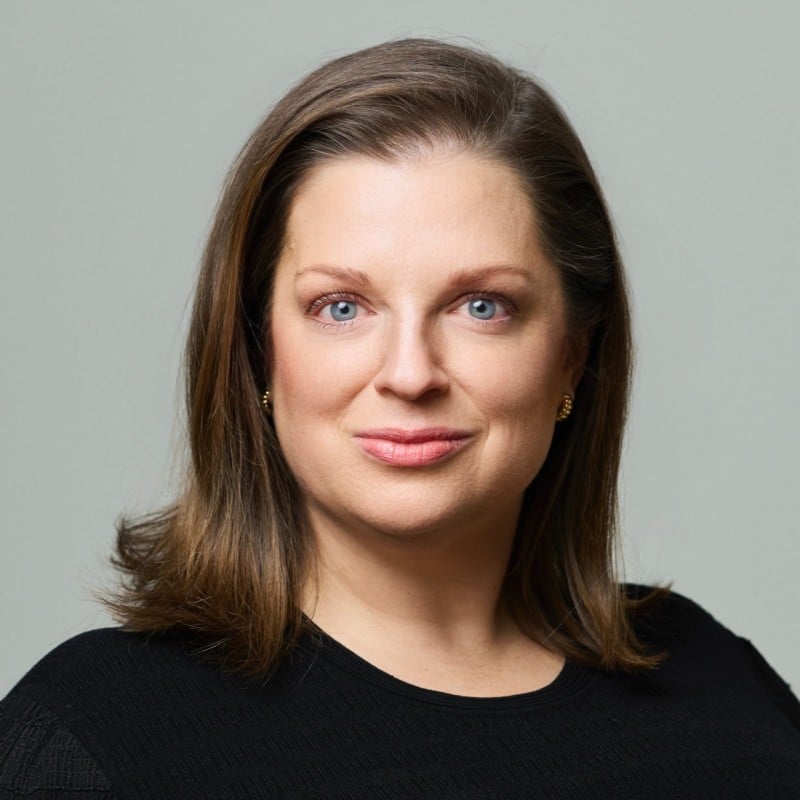
Alison ScarlettMichael Mazza
Part of the community
“Our stores are part of the communities they serve, and our store owners and teams are incredibly passionate about finding meaningful ways to give back,” said Alison Scarlett, Head of PR, Communications and Corporate Social Responsibility, Giant Tiger Stores Limited. “The Terry Fox Foundation is a cause that resonates deeply across our network. By connecting our stores with local schools, we’re able to support something our communities care about while helping a new generation of Canadians learn about Terry’s story and carry his legacy forward.”
Giant Tiger store owners and teams will support their matched schools as part of the fundraising campaign. The retailer said the program is intended to bring together stores, schools, families and customers around Terry Fox fundraising efforts.
“The Terry Fox Foundation is near and dear to so many of us in our community,” said Sacha, store owner of Giant Tiger Trenton, Ont., whose store was the top fundraiser in 2025. “Many of us grew up participating in Terry Fox Runs ourselves, and now we get to see another generation of students carry that tradition forward. Our team looks forward to getting behind this every year. It brings our associates, customers and community together around something that means a lot to all of us, and I’m incredibly proud of the way our community continues to show up.”
Terry Fox Foundation photo
Four-year partnership
The latest commitment comes as Giant Tiger marks its fourth year of partnership with the Terry Fox Foundation. The retailer said its contributions during that period have supported cancer research and Terry Fox fundraising efforts, with more than $412,000 provided to date.
“Giant Tiger’s local stores across the country are helping to inspire the next generation of Terry Fox supporters by getting behind students and their fundraising efforts,” said Michael Mazza, CEO of the Terry Fox Foundation.
“Through their school match program, stores are creating a powerful connection between local businesses, schools and communities, while teaching young people the power of philanthropy and the impact they can have when they come together for a cause they believe in. We are incredibly grateful to Giant Tiger for helping students experience the impact of Terry’s legacy firsthand and empowering them to be part of realizing Terry’s dream of a world without cancer.”
The Terry Fox Foundation said it surpassed $1 billion raised for cancer research in February 2026. The organization said it engages more than 20,000 volunteers and 3.5 million students through nearly 10,000 annual fundraising events across Canada.
AI agents may eliminate the checkout page, but they could also reduce brands to invisible suppliers.
The technology is advancing because AI-referred shoppers are commercially valuable. But removing the retailer from discovery and checkout creates a problem: if an AI agent selects the product, controls the interface, and completes the transaction, what remains of the relationship between the customer and the brand?
Jessica Young, CMO of Myndlab, an AI application builder, and a former luxury ecommerce executive, believes agentic commerce could split retail into two layers: brands that remain destinations in their own right and interchangeable suppliers competing to be selected by machines.
Jessica YoungSHVETS production photo
In an interview with Retail Insider, Young spoke about the issue.
Question: Could AI agents turn established brands into interchangeable product suppliers?
Answer: Yes, it’s a real risk. If an AI agent is choosing between products based mainly on price, availability, and specifications, the brands behind those products can start to look interchangeable. The customer may receive exactly what they asked for without ever visiting the retailer or understanding what makes one brand different from another.
However, people do not choose brands based on product data alone. They choose them because they identify with the world a brand creates, whether through relatability, aspiration, inspiration or social signalling. Brands that have built that kind of connection will still influence what customers ask their agents to find. The challenge is making sure the brand’s identity is not lost when the agent becomes the middleman.
Q: What happens to loyalty when the customer never visits the retailer’s website?
A: If I repeatedly ask the same agent to shop for me and it consistently makes good decisions, my loyalty may gradually shift towards the agent rather than any individual retailer. I may trust its recommendations without paying much attention to where each product comes from.
That makes one-to-one marketing and relationship-building through CRM even more important. Retailers need to understand their customers and stay connected with them before and after the transaction, even if the purchase itself happens through an agent. Exceptional service, relevant personalisation, exclusive products, membership and community can all give people a reason to maintain that direct relationship. If the only value a retailer offers is a quick purchase, an agent can easily take over that role.
Q: Why can eliminating checkout also eliminate valuable moments of trust and differentiation?
A: We often talk about checkout as friction, but it also gives customers important reassurance. It is where they confirm delivery, understand returns, choose how to pay, and see what support is available if something goes wrong. Those details can make the difference between feeling confident enough to buy and abandoning the purchase.
This is even more important in luxury ecommerce, where trust is part of the value. Customers want reassurance around authenticity, presentation, delivery and aftercare. If an agent handles the purchase in the background, retailers need to think carefully about how those trust signals reach the customer rather than disappearing with the checkout page.
Mikhail Nilov photo
Q: How can luxury, fashion and other emotionally driven categories remain relevant when AI prioritises specifications and price?
A: From my experience in luxury ecommerce, people shop based on emotional and psychological intent, cultural and social relevance, and how a brand fits into their personal identity. An AI agent can compare specifications and prices, but it cannot create the desire that makes someone want a particular brand in the first place.
As AI agents make shopping more transactional, brands will need to place even greater emphasis on the top of the funnel. That means investing in brand awareness campaigns, experiential touchpoints and genuinely creative concepts that capture consumers’ imagination and shape their intent before they begin shopping. I do not believe AI agents will replace or diminish branding and creative campaigns. In fact, their growing role in ecommerce should drive further investment in both, because brands will need to be top of mind by the time a consumer asks an agent to make a purchase.
Q: Will retailers need to design separate experiences for human shoppers and AI agents?
A: Retailers will need to respond to two different needs. An AI agent wants accurate information about products, pricing, availability, delivery and returns. A person may want to browse, be inspired and change their mind along the way. However, both experiences should still sit within the same brand world and reflect the same values, USPs and service standards. They are ultimately two different paths to purchase, not two separate brand experiences.
We saw a similar shift when ecommerce came to the forefront. Brick-and-mortar retail did not disappear, but became more focused, with flagship stores evolving into destinations for inspiration, entertainment and deeper brand engagement. Ecommerce then became a digital expression of that same brand, using discovery, personalisation and customisation tools to build awareness and engagement, while making the journey from consideration to conversion more seamless.
AI application builders can now help retailers create and test this next path to purchase without rebuilding their entire ecommerce operation. The opportunity is to make the experience work efficiently for agents while remaining consistent with what customers already expect from the brand. However, efficiency and transactions should not come at the expense of human control. Customers should always be able to understand what an agent is doing, correct its assumptions and step back into the decision when they want to.
Q: Why will the winners in agentic commerce be those that preserve a direct customer relationship, rather than those offering the fastest transaction?
A: Speed will matter, but it will not remain a meaningful advantage for long. Once every agent can compare products and complete a transaction within seconds, that level of convenience will simply become expected.
What will be harder to replicate is a relationship in which the customer feels understood, valued and connected to the brand. The retailers that do well will make agent-led purchasing easy while still giving people a reason to engage with them directly through more robust CRM and brand awareness initiatives. Community, experiential events and one-to-one relationships across physical and digital channels will become even more important.
Ultimately, the goal should not be to remove the human from commerce. It should be to use technology to make the transactional and operational parts easier without losing the emotional connection that makes people choose one brand over another.
The new Faire Independent Retail Pulse: Fashion, Rewired report reveals how independent retailers are winning by keeping up with the compressed fashion cycle fueled by fashion trends on social media trends.
The report said social media and celebrities – and celebrities using social media — have usurped traditional fashion media in their ability to set trends.
“Influence has moved out of editorial meetings and boardrooms to forums closer to consumers. Now independent retail, which also operates closer to shoppers than chain stores that make decisions at the national level, can jump on grassroots trends more quickly.” said the report.
The report said the rise of social platforms and the 24-hour celebrity news cycle have democratized and fragmented the nature of trendsetting.
“Now trends may emerge in a small community, on TikTok or Instagram, through creators and celebrities, or shift in real-time with shoppers’ changing behaviors — often before traditional fashion players have had time to catch up,” it said.
“Independent retailers are well-positioned for a new normal that requires a much tighter feedback loop between signal and buying decisions. Unlike their mass market counterparts, they are less constrained by national assortments and closer to their customers — shoppers they interact with every day — which allows them to stock their shelves based on the specific tastes and identities of their customers rather than with a standardized national planogram. Their inherent flexibility also means they place smaller, more frequent orders, so they can respond to emerging trends in days and weeks rather than face months, even years, of lead-time.”
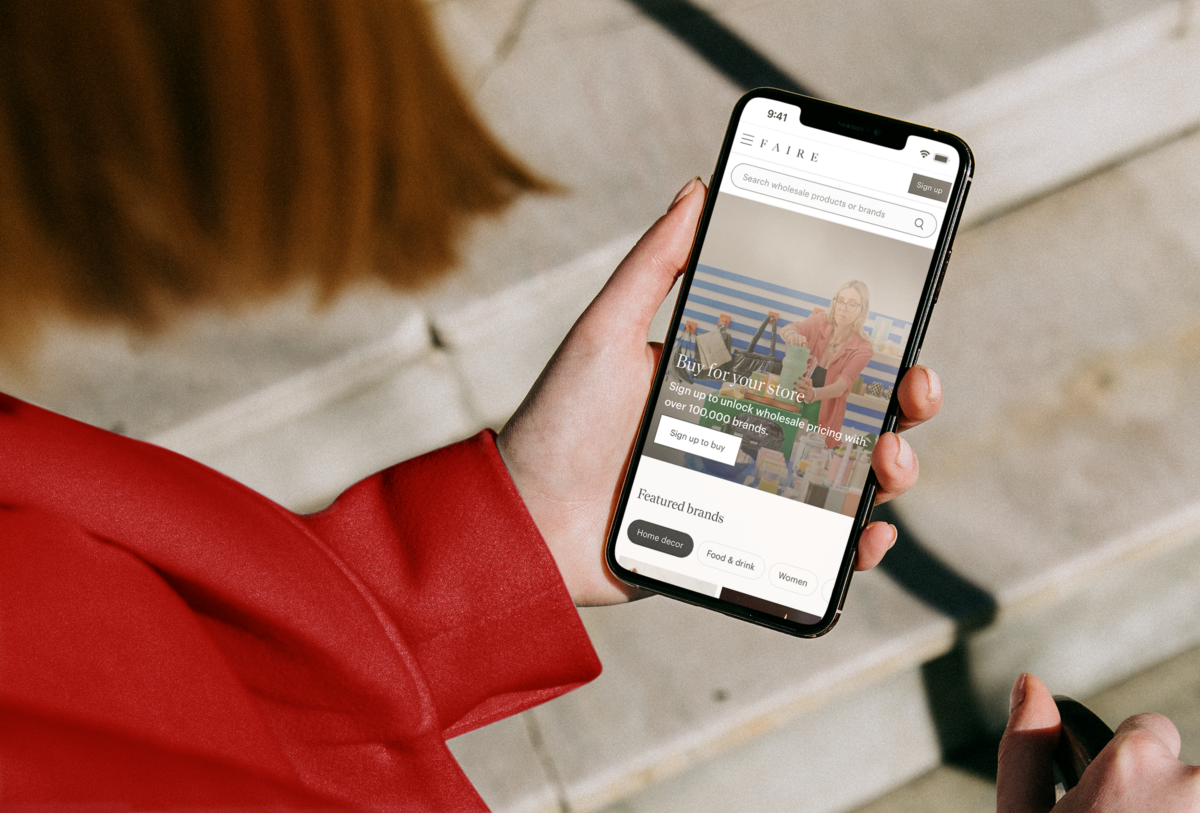
Faire image
Here is a snapshot of the report findings (based on Faire first-party independent wholesale data):
Mock-neck sweatshirts are in: U.S. orders on Faire grew 11.5x, fueled by a TikTok DIY trend of customizing them with iron-on patches, a cheaper, more personal alternative to ready-made merch or pricier brands like Parke.
Loungewear and matching sets are overtaking activewear: Order growth hit nearly 95% for loungewear and over 103% for matching/coordinated sets, making them the two fastest-growing apparel subcategories.
Plus-size unit share is decreasing: With an estimated 1 in 8 adults now using GLP-1 drugs, a figure that could triple by 2030, the share of apparel units sized above an XL has fallen by over 27% in the past three years.
Faire Chief Revenue Officer Jennifer BurkeFaire Trend Expert Hannah Wall
Jennifer Burke — CRO, Faire
Question: What does the rapid growth in certain apparel categories tell us about how independent retailers are responding to the increasingly compressed fashion cycle driven by social media?
Answer: Independent retailers are staying plugged into social media trends, then acting on them fast to capture the demand. Mock-neck sweatshirts are a good example of how these trends move from screens to stores. When the DIY trend of personalizing plain mock-neck sweatshirts with iron-on patches spiked on TikTok around July 4th and the World Cup, mock-neck sweatshirt searches on Faire ran at more than nine times the normal pace, and their share of US apparel orders jumped 11.5x, making July 2026 the biggest month on record for the category. The retailers who can move that fast are the ones who end up capturing the demand.
Q: How are independent retailers using smaller, more frequent orders to respond to emerging trends and adjust their inventory and size assortments faster than larger retail chains?
A: It comes down to buying cadence. Independents aren’t locked into a national assortment, so they stock and restock, based on what their customers actually want, and their orders are smaller and more frequent, letting them react in days or weeks instead of the months-long lead times chains are stuck with.
The striped loungewear trend shows this. In the eight weeks after Rihanna was photographed in a pajama set that went viral, the number of new brands listing striped pajama and loungewear sets on Faire roughly doubled, outpacing new listings elsewhere on the marketplace. Big retailers are buying off a vendor roster locked in months earlier, so they don’t have the flexibility to pick up on emerging styles the way independents can.
Q: What does the decline in plus-size unit share alongside the growth of GLP-1 use mean for independent fashion retailers, and how should they be thinking about sizing and inventory planning?
A: Independent retailers with smaller depth in size runs can order more of what’s actually selling right now, which matters as customer demand changes faster. A fifth of people who’ve lost weight on GLP-1s say they’re shopping less at big-box chains, and over half think those chains aren’t handling sizing for bodies in transition well. Watching your own data and assorting for your customers has become more important than ever.
Faire image
Hannah Wall — Trend Expert, Faire
Question: Which fashion trends emerging on social media are having the greatest influence on what consumers are buying right now, and why are some trends translating into retail demand faster than others?
Answer: Heading back into cooler weather, the staying power of the mock-neck sweatshirt trend is a good example of how the timing of a trend matters as much as the idea itself. Personalizing sweatshirts with iron-on patches took off on TikTok, but it really spiked around moments that gave people a natural reason to customize something, like the Fourth of July and the World Cup. Those cultural touchpoints gave the trend a built-in occasion, so it wasn’t just “here’s a cute DIY,” it was “here’s what you wear to this occasion happening right now.” Search for the term ran at more than nine times the normal pace, and its share of apparel orders jumped 11.5x almost overnight in a well-established category, proving that even staples can retrend.
Q: What is driving the rapid growth of loungewear and matching sets, and does this signal a broader shift in how consumers are thinking about fashion and everyday dressing?
A: What’s driving specific styles within that shift is celebrities and content creators. The striped pajama set took off after Rihanna was seen wearing one out in public, and that image spread fast through social media and inspired a wave of similar styling. Her balance of polished prep and pajama comfort are so desirable that social media locked in.
The gravitation towards matching sets reflects a similar craving for polish and comfort. Loungewear orders grew 95% and matching sets grew 103% year over year. We’re also seeing growth in oversized sweatshirts, one-size pieces, and relaxed sweaters, clothing that’s easy to live in. Together, I’d call it a bigger shift toward comfort and relaxed dressing generally, not just one look.
Q: How should independent retailers distinguish between a short-lived social media trend and a trend with enough staying power to justify putting it into their inventory?
A: Order small and let the data (and your customers) tell you, rather than betting big on a hunch. That’s the real edge independent retailers have: they can place a trial order and see within days whether something’s actually resonating with their customers. And because they’re talking to their customers directly, day to day, they don’t need to guess what’s resonating nationally, they can test it locally first and scale the order up only once it’s proven out with the people actually walking into their store.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published covering key developments in Canadian retail. Here are a couple highlights with a full list of the day’s articles thereafter.
Reitmans (Canada) Limited reported a 1.9% decline in second-quarter net revenues to $211.8 million, driven by lower transaction volumes and reduced clearance sales, while gross margin improved by 160 basis points to 58.5% due to disciplined. Primaris Real Estate Investment Trust is raising $200 million in equity to support its pursuit of over $1 billion in potential Canadian mall acquisitions, focusing on large regional shopping centres previously held by institutional owners.
Dollarama continues to sustain strong sales growth and rising customer traffic while maintaining its $5 maximum price point amid inflationary pressures, signaling a potential lasting shift in Canadian consumer behavior toward value retailing. Toronto’s Bloor Street luxury corridor is undergoing a dynamic reshaping marked by new flagship stores from RH, Tiffany & Co., and Delysées, alongside Holt Renfrew’s planned major reworking and Harry Rosen’s relocation.
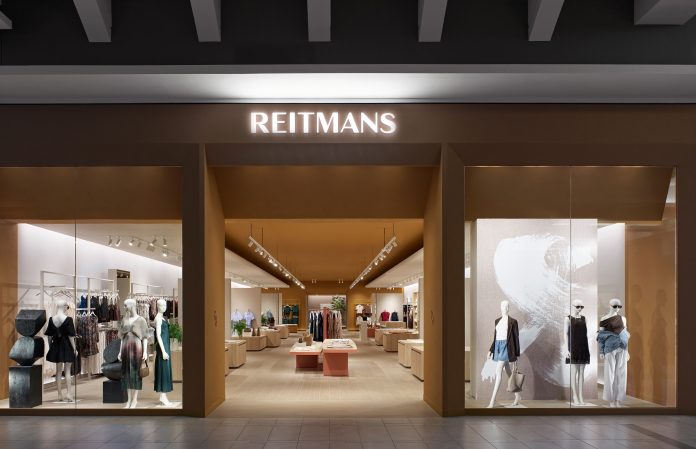
Reitmans, a specialty apparel retailer for women and men operates 385 stores under three distinct banners consisting of 216 Reitmans, 85 PENN., and 84 RW&CO.
Highlights
Gross profit margin increased 160 basis points to 58.5%.
Net revenues decreased 1.9% to $211.8 million and comparable sales decreased 1.5%.
Adjusted EBITDA was $18.8 million, $2.6 million below last year.
Net earnings were $10.1 million, or $0.20 per share.
“Our second quarter reflected deliberate, strategic execution across our brands,” said Andrea Limbardi, President and CEO of RCL. “While net revenues were modestly below last year, we meaningfully improved gross margin through stronger regular-price selling, a more disciplined promotional strategy and tighter inventory management. Inventory ended the quarter approximately 5.2% below last year, supporting improved merchandise margins and positioning us well for the balance of the year.
Andrea LimbardiReitmans photo
“Performance varied by channel during the quarter. Our comparable store sales increased and we saw continued strong momentum in our new flagship locations. The recently converted Reitmans concept flagship at Carrefour Laval and the expanded and renovated RW&CO Toronto Eaton Centre flagship both delivered double-digit sales growth. E-commerce revenues were lower than last year as we reduced clearance and promotional activity.
“The improvement in gross profit was offset by higher operating expenses, including freight costs, rent, store wages and advertising investments, as well as early work to develop a loyalty program. During the quarter, Reitmans marked its 100th anniversary through our ‘We’ve Evolved’ campaign and partnership with the WNBA’s Toronto Tempo, initiatives that strengthened the brand’s fashion and cultural relevance and generated encouraging shifts in brand perception.
“With a strong balance sheet and clear strategic priorities, we remain focused on disciplined execution, strengthening the customer experience across channels and advancing the initiatives that support sustainable, profitable growth over the long term.”
Second Quarter Overview
Net revenues decreased 1.9% to $211.8 million primarily due to lower transaction volume and reduced clearance activity compared to the prior year. Comparable sales, which include e-commerce net revenues, decreased 1.5%. Retail store performance remained resilient during the quarter, while e-commerce revenues were impacted by a more selective promotional approach, said the company.
Gross profit increased $1.1 million to $123.9 million, while gross margin improved 160 basis points to 58.5% of net revenues. The increase in gross profit and gross margin was primarily attributable to lower markdowns and promotional activity compared to the same quarter a year earlier, it added.
Image Credit: Ben Rahn/A-Frame [www.aframestudio.com] (CNW Group/Reitmans (Canada) Ltd)
Reitmans said it ended the quarter with inventory of $119.7 million, approximately 5.2% below the prior year, reflecting disciplined inventory management and supporting improved merchandise margins and regular-price selling.
Strategic transformation expenses of $1.1 million related to employee termination benefits and consulting fees associated with restructuring efforts to evolve the Company’s operating structure, it noted.
“Adjusted EBITDA was $18.8 million as compared to $21.4 million for the second quarter of 2026. The decrease of $2.6 million is primarily attributable to higher SG&A expenses that more than offset the increase in gross profit for the quarter,” explained the retailer.
“Net earnings were $10.1 million ($0.20 basic and diluted earnings per share) as compared with net earnings of $13.1 million ($0.26 basic and diluted earnings per share) a year earlier.”
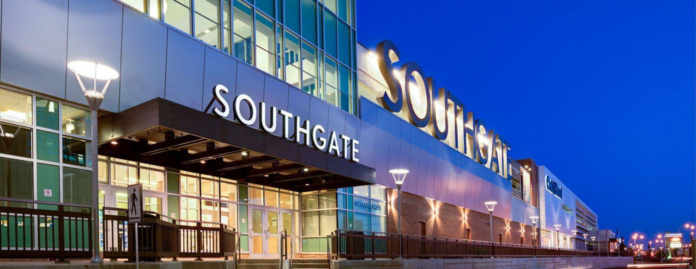
Southgate Centre in Edmonton. Photo: Primaris REIT
Primaris Real Estate Investment Trust is raising approximately $200 million in new equity as it evaluates another major round of shopping centre acquisitions, with the REIT disclosing that it is in various stages of negotiations involving more than $1 billion in potential purchases.
The Toronto-based REIT announced September 14 that a syndicate of underwriters led by TD Securities, Desjardins Capital Markets and RBC Capital Markets will purchase 9.91 million Primaris units on a bought-deal basis at $20.20 per unit. An over-allotment option could increase gross proceeds to approximately $230 million.
Primaris said the proceeds will be used to fund future acquisitions and for general trust purposes. The disclosure is particularly notable given how aggressively the company has already expanded through acquisitions, including several major enclosed shopping centres previously owned by some of Canada’s largest institutional real estate investors.
It also points to a larger shift underway in Canadian retail real estate. Primaris has spent several years establishing itself as a repeat buyer of large regional shopping centres, while identifying portfolio rebalancing among institutional owners as a source of potential acquisitions.
Primaris Has Become a Major Buyer of Canadian Malls
Recent transactions show the scale of the strategy.
Primaris acquired Lime Ridge Mall in Hamilton for $416 million and Promenades St-Bruno near Montreal for $565 million, both from Cadillac Fairview. It also acquired Oshawa Centre and a 50 per cent interest in Southgate Centre in Edmonton as part of a $585-million transaction with Ivanhoé Cambridge.
Les Galeries de la Capitale in Quebec City was acquired in 2024 in a transaction valued at $325 million.
These are established regional shopping centres with significant positions in their respective markets. Primaris has been explicit that it sees Canada’s institutional ownership structure as a source of future transactions.
In investor materials, the REIT has estimated that approximately $50 billion of Canadian enclosed shopping centres are owned by large Canadian institutions. Primaris has identified portfolio rebalancing among those owners as one factor that could make additional properties available.
Chief Executive Officer Alex Avery has also told analysts that pension plans have been important vendors to Primaris, and that engagement with institutional sellers had increased as the REIT demonstrated its ability to complete large transactions.
Primaris said in early 2025 that it had acquired $2.4 billion of leading enclosed shopping centres from five of Canada’s 10 largest pension funds since the end of 2021. Its acquisition activity has continued since then.
The newly disclosed pipeline indicates that Primaris is evaluating another substantial group of potential transactions. The company has not identified the properties or sellers, and there is no certainty the negotiations will result in completed acquisitions.
Why the Same Mall Can Have Different Value to Different Owners
The transactions reflect different approaches to capital allocation.
Large pension funds and institutional real estate managers typically invest across multiple property types and geographic markets. Selling a Canadian shopping centre can therefore reflect portfolio allocation, liquidity or other investment considerations without necessarily indicating a negative view of the individual property or enclosed retail generally.
Primaris has a much narrower mandate. It is Canada’s only publicly traded REIT focused specifically on enclosed shopping centres, concentrating its management resources, retailer relationships and redevelopment capital in the sector.
Scale is an important part of that strategy. A larger national portfolio gives Primaris more locations to offer retailers pursuing multi-market expansion while spreading its internal management platform across a larger asset base.
The company has also been selective. Its acquisitions have focused on leading regional shopping centres while Primaris has continued selling properties it considers less aligned with its longer-term portfolio strategy.
That distinction matters as performance becomes increasingly dependent on asset quality. Canadian retail market reports from CBRE and JLL have pointed to constrained availability and retailer demand at stronger properties, while weaker shopping centres face different leasing and capital challenges. Very little new enclosed-mall supply is being built, adding scarcity to productive existing space.
Primaris is therefore making a concentrated bet on a particular segment of the mall market: regional shopping centres with strong market positions where leasing, redevelopment and active management can potentially increase income.
Former Hudson’s Bay Space Tests the Strategy
Hudson’s Bay’s store closures have provided an early test of that approach.
Primaris had approximately 881,400 square feet of former Hudson’s Bay space across its portfolio. By June, the REIT said 84 per cent had either been leased or was in advanced negotiations, including 58 per cent covered by long-term leases.
The rent differential is substantial. Primaris said 608,500 square feet covered by committed or conditional leasing was expected to generate approximately $9.2 million in annual net rent, compared with $2.1 million previously generated by Hudson’s Bay.
Across the 881,400 square feet leased or under negotiation at the time, projected annual net rent was approximately $14.9 million, compared with $3.7 million from Hudson’s Bay.
Those gains require significant investment. Primaris expects to spend approximately $175 million to $225 million on the former Hudson’s Bay redevelopment program and has projected yields above 10 per cent.
Avery previously told analysts that Primaris had heavily discounted Hudson’s Bay income when underwriting Galeries de la Capitale, Southgate Centre and Oshawa Centre because management expected the department-store spaces would eventually require redevelopment.
The subsequent leasing provides an important proof point for future acquisitions. At stronger malls, legacy anchor space carrying relatively low rents can potentially be repositioned for multiple tenants at considerably higher aggregate rents, provided the property can support the demand and the owner is prepared to invest the required capital.
Fresh Equity Adds Acquisition Capacity
Primaris reported approximately $655.1 million of liquidity and $4.9 billion of unencumbered assets at the end of the second quarter. Total debt represented 40.5 per cent of total assets, while average net debt to adjusted EBITDA stood at 6.0 times, the upper end of the REIT’s stated four-to-six-times target range.
The equity offering gives Primaris additional acquisition capital without adding an equivalent amount of debt.
Its timing is also notable compared with one of Primaris’s major financings last year.
When the REIT acquired Promenades St-Bruno for $565 million, it launched a bought-deal equity offering in connection with an identified acquisition. This time, Primaris is raising equity without publicly identifying a property purchase while simultaneously disclosing potential acquisitions with an aggregate purchase price exceeding $1 billion.
The company has not said how far individual negotiations have progressed or how much of the pipeline will ultimately result in completed transactions.
“Primaris continues to benefit from a strong balance sheet, growing cash flow and a differentiated portfolio of market-leading enclosed shopping centres,” Avery said in announcing the financing.
“This offering further enhances our financial flexibility and liquidity, positioning us to capitalize on attractive acquisition opportunities while maintaining our disciplined approach to capital allocation and leverage management.”
Canadian Mall Ownership Continues to Shift
The transactions Primaris has already completed show how the ownership map of major Canadian malls is changing.
Properties that spent years or decades inside diversified institutional portfolios are increasingly becoming part of a public REIT dedicated specifically to enclosed retail. Primaris is providing a source of liquidity for institutions choosing to sell individual assets while concentrating more of its own capital in the sector.
That does not mean Canada’s institutional owners are collectively exiting malls. Several remain among the country’s largest owners of high-quality retail properties, and the rationale behind individual sales varies.
What has changed is the presence of a specialized buyer capable of completing transactions worth hundreds of millions of dollars. Primaris now has a record of executing those deals, including transactions involving equity consideration, while its growing portfolio provides additional scale with retailers and in property operations.
Primaris currently owns interests in 14.6 million square feet of shopping centre space, with its share of the portfolio valued at approximately $5.2 billion.
The REIT has not identified the properties or vendors represented in its more than $1 billion of current acquisition negotiations. The next completed transaction will provide another data point on which major Canadian malls are coming to market, who is selling them and how aggressively Primaris intends to keep expanding.
New research from Sitecore reveals a timely challenge: Gen Z expects brands to deliver increasingly sophisticated digital experiences, but they’re also quick to walk away when those experiences feel untrustworthy or inauthentic.
With Gen Z’s spending power projected to reach $12 trillion by 2030, says Sitecore, earning this generation’s trust isn’t just a holiday-season priority, it’s critical to building long-term customer relationships.
Sitecore’s inaugural Digital Authenticity Index surveyed 4,000+ consumers in the U.S., U.K., Australia and UAE. The findings from its Gen Z cohort (ages 18–29) offer a valuable blueprint for retailers looking to use AI without undermining the authenticity and trust that keep consumers engaged.
The takeaway for retailers: the brands that win with AI won’t necessarily be those using the most sophisticated technology. They’ll be the ones using AI to deliver what Gen Z values most: accurate, transparent and human digital experiences.
Here are some of the key findings among the Gen Z cohort:
83% believe AI can be beneficial when used responsibly.
80% say digital experiences are equally or more important than real-life experiences.
89% say brands need to do more to improve digital authenticity.
Nearly 70% have reduced engagement, switched brands or stopped using a brand because a digital experience felt untrustworthy, inconsistent or inauthentic—the highest rate of any generation studied.
Question: What are the most effective ways retailers can use AI in holiday marketing while still making digital experiences feel authentic and human to Gen Z?
Answer: The first thing I’d say is: don’t use AI simply because you can. Use it because it makes the customer experience better. Sitecore’s Digital Authenticity Index (DAI) found that 83% of Gen Z consumers believe AI can be beneficial when used responsibly. But 74% also say they can spot AI-generated content. They may be open to AI, but they aren’t easily impressed by it.
During the holidays, retailers should use AI to solve real customer problems: helping someone find the right gift within a particular budget, surfacing relevant recommendations, keeping inventory and delivery information accurate, and answering routine questions quickly. Those are the moments when speed and relevance are genuinely useful.
Retailers get into trouble when they assume that because Gen Z is comfortable with AI, they want it everywhere. They don’t. The best AI experiences should feel less like “Look what our AI can do” and more like “That was actually helpful.” That matters even more during the holidays, when shoppers are under time pressure and one bad answer can mean a missed gift.
Q: What specific uses of AI are most likely to undermine Gen Z’s trust in a brand, and what are the biggest “trust killers” retailers should avoid?
A: The DAI’s findings give us a pretty clear answer. Gen Z’s three biggest digital trust killers are inaccurate or misleading information at 35%, no clear way to reach a human when needed at 34%, and overly automated or robotic interactions at 33%.
During the holidays, those failures have real consequences. An AI shopping assistant that gives the wrong inventory or delivery information could mean a missed gift. A chatbot that sends someone in circles only makes a stressful situation worse. And personalization that crosses the line from helpful to creepy can quickly make someone question how the brand is using their data.
The technology may be generating the answer, but the retailer still owns it. That means checking for accuracy, making the path to a person obvious, and knowing when AI is making the experience harder rather than easier.
Ivan S photo
Q: How should retailers balance AI-driven personalization with transparency, particularly when consumers may not know how or why AI is influencing the experience they receive?
A: I think this is where the distinction between personalized marketing and permissioned marketing comes in. Personalization says, “We know something about you.” Permissioned marketing says, “Here’s what we know about you, where and how we’re using it, and what you can do if you’re not comfortable with that.”
Transparency doesn’t require a lengthy explanation at every touchpoint. But if AI is influencing a recommendation, search result, or offer, the customer should be able to understand why. They should also be able to change their preferences, correct misinformation, or opt out.
That becomes especially important during the holidays because people are often shopping for someone else. A gift purchase doesn’t necessarily tell you anything about the buyer’s own interests. Anyone who has bought one gift and then been followed around the internet by similar recommendations for months knows how quickly personalization can get it wrong.
The goal is for customers to feel understood, not watched. Giving them clarity and control is what makes the difference.
Q: Given that nearly 70% of Gen Z respondents have reduced engagement or switched brands after an untrustworthy or inauthentic digital experience, what should retailers prioritize this holiday season to retain customers?
A: Actually, I’d start with the basics. Holiday shopping puts enormous pressure on every part of the customer experience, and it is often the simple, underinvested areas that do the most to earn trust—or erode it.
Is the inventory information accurate? Does the promotion still work at checkout? Is the delivery promise realistic? Is the return policy clear? And can the customer reach a person when something goes wrong?
Gen Z won’t separate a technical failure from the brand behind it. If an AI assistant says an item is available when it isn’t or promises delivery before the holidays when that is no longer possible, the retailer owns that experience.
Retailers also need to invest in service recovery. Make it easy to reach a person, give that person enough context to resolve the issue, and communicate quickly when a promise can’t be kept. Nothing makes a bad experience worse than forcing the customer to explain the same problem over and over again.
The brands that retain customers will be the ones that get those seemingly small moments right—especially when the pressure is on.
MART PRODUCTION photo
Q: Can you share examples of retail brands that are using AI successfully in their holiday marketing while maintaining authenticity and human support?
A: I really like Etsy’s Gift Mode, which combines AI with human curation to help shoppers find gifts. The technology helps narrow the choices, but Etsy keeps its sellers and the human stories behind their products at the center of the experience. During the holidays, it has also paired digital discovery with more accurate delivery dates, purchase protection, and additional customer support agents. That feels like a thoughtful division of labour. The technology helps with discovery, while people and clear policies provide reassurance when it matters.
Walmart has taken a similarly practical approach. It has used generative AI to help holiday shoppers search for gifts in natural language, compare products, summarize reviews, and get personalized ideas. Its customer support assistant can also help people find orders and manage returns.
What I like about these examples is that AI has a specific job. It’s not there simply to make the campaign look innovative. It helps the customer find something, make a decision, or solve a problem.
Dollarama store at Southcentre in Calgary. Image: Southcentre
Dollarama reported Canadian comparable-store sales growth of 5.4% in the second quarter, following 5.6% in Q1, while traffic increased 3.7%. Stifel analyst Martin Landry contrasted that performance with decelerating comparable-sales trends at Costco Canada, TJX Canada and some Canadian grocers, saying Dollarama’s traffic growth suggests the retailer continues to gain market share.
The comparison does not establish that Dollarama is directly taking sales from those companies, but it raises a larger question for Canadian retail: is the strength of value retail still primarily a response to squeezed household budgets, or are consumers permanently shifting more everyday spending toward retailers built around low absolute prices?
The Trade-Down Explanation Only Goes So Far
Dollarama management itself stopped short of attributing its performance to trade-down. President and CEO Neil Rossy told analysts that difficult economic conditions work in opposing directions: consumers have less money to spend, which can hurt discretionary demand, while the same pressure can send shoppers toward lower-priced retailers. Dollarama cannot determine how much of either behaviour is driving its results.
Its category performance nevertheless shows how broadly the chain now participates in household spending. Consumables remained strong, general merchandise strengthened, summer seasonal merchandise posted positive growth and toys performed unusually well during the quarter.
Trade-down is usually treated as cyclical: consumers move toward lower-priced options when finances deteriorate and, in theory, move back when conditions improve. The longer-term competitive issue emerges when shoppers begin routinely buying cleaning products, snacks, kitchen goods, health and beauty items, toys and seasonal merchandise from a value retailer. At that point, traditional retailers eventually have to win those purchases back.
Dollarama store. Image: Dollarama
Why the $5 Ceiling Matters
One of the more revealing exchanges on Dollarama’s earnings call concerned a price point the company does not yet have. Asked whether inflation could bring forward a $6 maximum price, Rossy said Dollarama would introduce another fixed price point only if cost inflation reached a level where the existing $5 ceiling could no longer be supported sustainably.
Based on current conditions, he said another price point is unnecessary and Dollarama intends to delay one for as long as possible.
The $5 ceiling should not be mistaken for a clean inflation measure. Dollarama can alter individual prices, sourcing, products, pack sizes and merchandise mix while staying below it. But it remains a highly visible consumer threshold, effectively showing how much cost pressure Dollarama believes its model can manage before its most recognizable pricing boundary has to change.
There is a loose parallel with the Big Mac as an economic reference point. The Big Mac Index uses the price of a broadly standardized McDonald’s product as a rough comparison of purchasing power between currencies; Dollarama’s ceiling is much less precise because its assortment can change beneath it. The useful question is how much merchandise, freight and operating-cost inflation one of Canada’s most scaled value retailers can manage before that affordability threshold moves.
For now, management is saying the $5 ceiling still works.
Cost Inflation Can Strengthen Dollarama’s Relative Position
Dollarama is facing higher costs alongside the rest of the retail sector. CFO Patrick Bui said higher oil prices are increasing raw-material and transportation costs, with the impact expected to become more pronounced beginning in the third quarter. Despite that, Dollarama maintained full-year Canadian gross-margin guidance of 45.0% to 45.5%.
The assumptions behind that forecast have also become tougher. Management is now incorporating elevated oil prices through the remainder of the fiscal year, whereas its previous outlook contemplated some normalization.
Before adjusting prices, Bui said Dollarama is looking for efficiencies across logistics, store operations and merchandising, with pricing changes remaining the last resort.
That gives Dollarama an important competitive advantage if it can absorb those pressures longer than other retailers. It does not have to cut prices for its relative value position to improve. If prices elsewhere move higher more quickly while Dollarama preserves its existing architecture, the gap consumers perceive between the two can widen on its own.
Scale gives Dollarama more room to attempt that. The company ended Q2 with 1,734 Canadian stores and continues to expand the network. Inflation therefore creates two opposing forces: it raises Dollarama’s costs, but it may also strengthen the retailer’s relative value proposition when competitors have less room to absorb the same pressures.
The Pressure Extends Beyond Dollar Stores
The competitive issue reaches well beyond the dollar-store segment. Dollarama sells merchandise that overlaps with supermarkets, drugstores, mass merchants, home retailers, toy stores and specialty chains. Stifel describes its assortment as spanning kitchenware, homeware, stationery, toys, cleaning supplies, confectionery, beverages, health and beauty products and seasonal goods. The firm also estimates that Dollarama refreshes roughly 25% to 30% of its inventory each year, replacing slower sellers that no longer meet profitability requirements.
The more difficult position belongs to retailers selling broadly comparable merchandise at materially higher prices without enough differentiation to make the gap easy to justify. Retailers with distinctive product, service, exclusive brands or a compelling shopping experience can give consumers reasons to pay more. Large value operators can compete through price, convenience and scale.
That does not make every Dollarama product directly comparable with merchandise elsewhere. Quality, pack size, brands and specifications vary widely. For many everyday purchases, however, consumers make a simpler calculation around what they can get for the money they are spending. As Dollarama captures more routine categories, that comparison reaches further into Canadian retail.
Dollarama at SouthCentre Mall in Calgary. Photo: Jessica Finch.
From Promotional Value to Structural Value
There is also a difference in how value is delivered. Many conventional retailers depend heavily on flyers, temporary markdowns, loyalty programs, points and coupons to establish affordability, while Dollarama’s proposition is embedded more directly in the store.
Consumers generally enter expecting low absolute prices without waiting for a promotion or optimizing a loyalty offer. The fixed-price architecture reinforces that perception even though the merchandise and individual prices beneath it change constantly, giving the $5 ceiling importance beyond the products actually sold at that price.
It functions as shorthand for the retailer’s broader value promise. The strategic question is whether shopping behaviour built around that expectation becomes habitual. If consumers increasingly default to Dollarama for commodity-like household goods, an improvement in household finances would not necessarily send those purchases back to mainstream retailers. Those retailers would still have to give shoppers a reason to return.
The importance of visible price anchors is showing up elsewhere in the Canadian consumer market. McDonald’s Canada committed in January to keeping McValue meals at $5 and small McCafé coffee at $1 for a year, saying it was using the scale of its Canadian supply chain to keep prices low despite inflation and rising costs.
The businesses and products are different, but both strategies put a simple, memorable price at the centre of the value proposition. The price itself becomes part of what consumers expect from the brand.
More Stores Reinforce the Advantage
Dollarama is also adding more locations from which to compete for those purchases. The retailer opened 15 net new Canadian stores in Q2 and finished the period with 1,734 locations. It raised its fiscal 2027 Canadian opening guidance to between 65 and 75 stores from the previous range of 60 to 70.
Rossy cautioned that the higher target should not be interpreted as a permanently faster annual opening rate. He said the increase reflects the availability of suitable real-estate opportunities and the timing with which landlords are delivering locations.
For landlords, Dollarama continues to offer an active expansion pipeline even after building one of the country’s densest retail networks. For competitors, every additional location increases the chain’s convenience and puts its pricing proposition in front of more consumers during routine shopping trips.
A Changing Value Equation in Canadian Retail
Landry’s Stifel analysis is useful because it places Dollarama’s quarter in relative terms. His central observation is that Dollarama’s comparable-sales momentum has remained relatively steady while several other major Canadian retail businesses are seeing deceleration.
If that divergence persists, the larger issue is no longer simply consumers seeking cheaper stores during a difficult economic period. It would suggest a changing hierarchy for household spending, with consumers increasingly buying commodity-like goods from value retailers while reserving higher-priced retailers for categories where product, brand, service or experience gives them a clearer reason to pay more. The least differentiated portion of the market would face increasing pressure.
Dollarama’s eventual move beyond $5 will therefore be worth watching, not because it would represent an official measure of Canadian inflation, but because of what it would say about the economics underneath one of the country’s largest value-retail models. It would mean Dollarama had reached the point where enough cost pressure could no longer be accommodated inside its existing pricing structure.
For now, the ceiling remains $5 while customer traffic continues to rise, and Stifel sees Dollarama maintaining sales momentum as several other large Canadian retailers slow. For the rest of the market, that combination matters more than the missing $6 price tag.
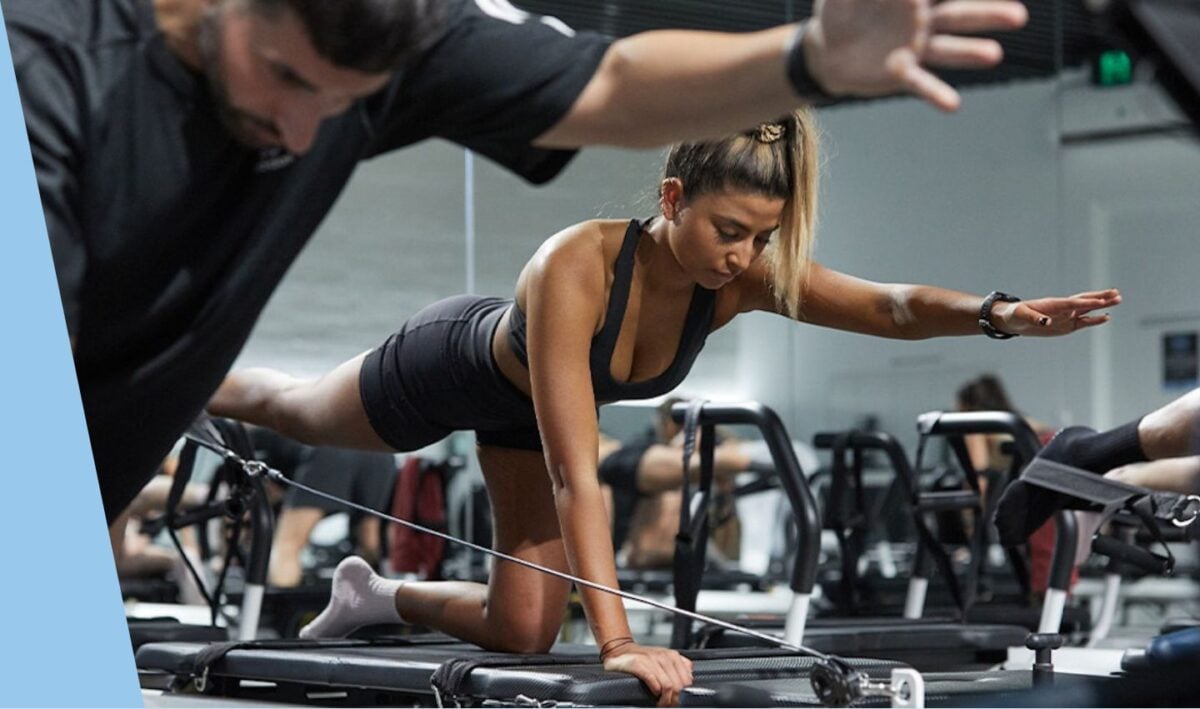
STRONG Pilates has launched CONNECT, a new in-studio technology platform that integrates tablets with the fitness franchise’s proprietary Rowformer and Bikeformer machines, as the Australian-founded company prepares for further expansion of the system across its international network.
The technology is being introduced in two phases, beginning in Australia and the United States, with a second phase planned for later this year that will add expanded data capabilities, deeper technology integration and a global rollout.
Technology and personalization
CONNECT is designed to deliver workout programming from a central system directly to equipment in STRONG studios, removing manual setup requirements and standardizing class delivery across the network. The system also creates a foundation for more personalized, real-time feedback, with additional features planned for the second phase.
The platform’s integrated tablets introduce STRONG Zones, a performance-feedback system that displays individual intensity ranges based on each member’s workout output. Colour-coded zones are intended to provide real-time coaching information while the system retains previous performance data to help inform future sessions.
“We’re a brand built on innovation, always looking for ways to elevate STRONG’s member experience, streamline operations and better equip our instructors to deliver exceptional coaching,” he said.
Ramsey said the launch represents a significant development for the company as it continues expanding its studio network and technology platform.
“CONNECT is the next evolution of STRONG. We’ve been building towards this for years, and seeing it come to life across our studios is a milestone for our business. It pushes the brand forward in a way the industry hasn’t seen before and sets a new standard for boutique fitness globally. Over the next year, we will be introducing even more features that will completely transform the member experience,” he said.
Second phase planned
The second phase of CONNECT, scheduled for later this year, will add deeper technology integration and expanded data capabilities before being rolled out globally across STRONG’s international network.
The company also plans to introduce a rewards platform that will recognize member milestones and record lifetime performance metrics within the system. Another planned feature will allow workouts to be assigned level-based goals and assess members according to age, gender and fitness levels, placing them in categories called STRONG, STRONGER or SUPERHUMAN.
Members will receive real-time recognition as they reach their workout goals, while enhanced performance information will be used to tailor training zones to individual characteristics and training efforts.
“CONNECT has been built to deliver a streamlined, consistent experience for our members, challenging them at every workout,” he said.
Davidson said the technology is also intended to automate processes for studios while giving members more information about their performance.
“We’ve created technology that automates complex work processes and tracks individual performance metrics so members can continue exceeding their benchmarks. This is the most advanced innovation for STRONG to date and will set a new standard for personalised member training. Wait until you see what Phase Two will bring,” he said.
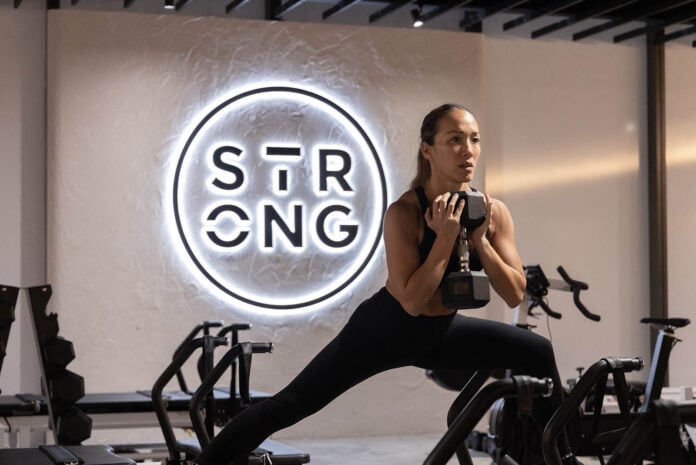
STRONG Pilates photo
Standardized studio experience
CONNECT’s first and second phases include wireless workout synchronization with STRONG TV, which displays the current class in instructional order and is designed to eliminate manual uploads and member navigation.
The system also standardizes workout metrics across STRONG equipment, allowing the company to use the same measurement approach across its studios. Members will receive immediate post-workout performance summaries, while instructors will have studio-wide visibility into intensity levels through the STRONG Zones system.
Phase Two will expand the system’s personalized STRONG Zones by using individual training efforts to establish colour-coded intensity ranges. The enhanced metrics will take age, gender and fitness level into account when calibrating training zones.
CONNECT will also retain members’ performance information from individual sessions through its Performance Memory feature. The company says the data will be used to measure progress over time.
The planned Milestone Recognition feature will add an integrated rewards system to recognize milestones and lifetime metrics in workout summaries and highlight goals in real time as they are reached or exceeded.
STRONG said all instructors will receive training through the STRONG Academy to support consistent delivery of the new system.
Global expansion
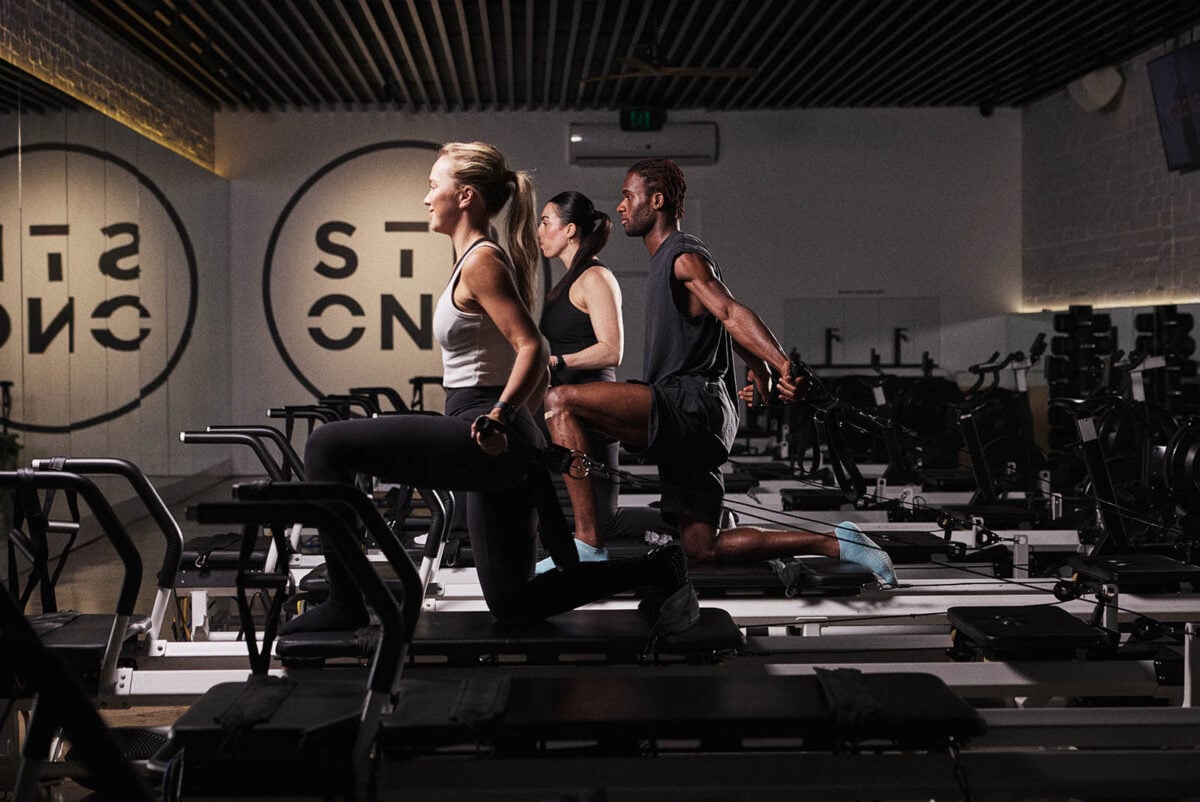
STRONG Pilates was co-founded by Ramsey and Mark Armstrong in 2019. The Australian-founded fitness format combines Pilates, cardio and strength training through its Rowformer and Bikeformer equipment, which incorporates a rower or bike with a Reformer.
The company says it now has more than 47,000 members worldwide and more than 117 operating studios across 14 countries, with a further 200 studios confirmed to open.
The initial CONNECT rollout in Australia and the United States will be followed by the planned Phase Two expansion later this year, extending the technology across STRONG’s growing international studio network.
STRONG Pilates photo
In an interview with Retail Insider, Ramsey spoke about the latest developments with the company.
Question: What business objectives is STRONG Pilates hoping to achieve with the launch of CONNECT, particularly in terms of member retention, engagement and studio growth?
Answer: At its core, CONNECT is about making the STRONG Pilates experience more personalized for the member and more scalable for the business.
One of the challenges with traditional group fitness is that you can have 20 people in a room with 20 different fitness levels, but they’re essentially given the same performance target. CONNECT allows us to move away from that. Through STRONG Zones, real-time performance feedback and eventually personalized benchmarks based on a member’s previous training, we can give people a clearer understanding of how hard they should be working and whether they’re progressing.
From a retention perspective, that matters because people are more likely to stay engaged when they can see their progress. CONNECT creates that feedback loop: what did I achieve today, how does that compare with my previous sessions and what am I working toward next? Phase Two will build on that with personalized fitness levels, milestones and rewards.
For STRONG, another major objective is scalability. CONNECT creates one technological and programming standard across the network, so as we open studios in new markets, we can maintain much greater consistency in how a STRONG class is delivered. That becomes increasingly important as you go from 100 studios to several hundred globally.
Q: How much has STRONG Pilates invested in developing CONNECT, and how does the company expect the technology to affect studio operating costs and instructor efficiency?
A: In terms of development costs, the project is ongoing. The Connect tablet is like an iPhone that can updated on an ongoing basis so there are no fixed costs, it’s something that will continually be developed year on year. Previously, instructors and studio teams had a number of manual steps involved in setting up programming and equipment for classes. CONNECT delivers programming directly through the integrated tablets on our Rowformers and Bikeformers and wirelessly syncs the workout with STRONG TV, removing much of that manual setup. That gives instructors more time to focus on the part of the job technology can’t replace: coaching, motivating members and creating energy in the room. It also gives them better visibility into how members are performing, so rather than spending the class constantly communicating generalized effort cues, they can provide more targeted coaching.
As STRONG Pilates scales, those efficiencies become increasingly valuable. If we can simplify class delivery while improving consistency and coaching quality at the same time, that’s a meaningful operational advantage for both existing and new franchisees.
STRONG Pilates photo
Q: What data will CONNECT collect from members, how will that information be used to personalize workouts, and what measures are in place to protect members’ privacy?
A: By the end of 2026 (phase 2), CONNECT will be able to track individual training efforts across sessions and retain performance history, allowing members to see their progress over time and giving instructors more context to tailor their coaching.
During class, STRONG Zones translate effort into a simple colour-coded display, so members can understand in real time whether they’re training at the intended intensity. Phase Two will take that personalization further, with training ranges calibrated using factors including a member’s age, gender, fitness level and previous efforts.
Our goal is to use technology to make group fitness more individual. You’re still getting the energy and community of a STRONG Pilates class, but the benchmark you’re working toward becomes personalized to you. Members can then be rewarded based off their performance i.e. if they hit a personal best on the rower or bike, or achieve a streak of classes with 90-100% effort, they will receive prizes and incentives to keep improving and becoming a stronger version of themselves.
Members’ privacy is important, the data will sit in a secure data warehouse where STRONG users can access their information only, ensuring they feel safe and comfortable on their own fitness journey.
Q: With more than 124 operating studios and another 200 confirmed to open, how important is CONNECT to STRONG Pilates’ strategy for maintaining a consistent member experience as the franchise expands internationally?
A: It’s hugely important. When you’re operating 10 or 20 STRONG Pilates studios, it’s easier to maintain consistency through hands-on oversight. But as you scale across 14 countries, with more than 200 additional studios confirmed to open, you need the right systems in place to ensure that same STRONG experience is delivered consistently across every location.
CONNECT gives us that infrastructure. Programming can be delivered centrally and directly to the equipment, performance metrics are standardized across machines, and instructors are working within the same system regardless of whether the studio is in Melbourne, Toronto, London or New York.
For me as a founder, that’s incredibly important. I don’t want growth to dilute the experience that made people want to join STRONG in the first place. Technology should allow us to grow without compromising that experience.
It also makes innovation much more scalable. As we develop new programming or features, we have a connected network through which we can introduce them consistently rather than asking hundreds of individual studios to implement them independently.
STRONG Pilates photo
Q: What does Phase Two add to CONNECT, and how will features such as personalized fitness levels, performance tracking and milestone rewards change the way members train and interact with the STRONG Pilates brand?
A: Phase Two will build on CONNECT by making the experience even more personalized and giving members more ways to understand and celebrate their progress. Members will be able to work toward individualized performance targets based on factors including age, gender and fitness level, with their progress reflected through STRONG, STRONGER and SUPERHUMAN levels. The system will also track longer-term performance and recognize achievements and milestones, both during workouts and over time, creating a clearer sense of progression and giving members more reasons to stay motivated and engaged.
That means we’re moving beyond looking at workouts as isolated 45-minute sessions and giving members a longer-term view of what they’re achieving.
That’s important because fitness isn’t really about what you did on one Tuesday morning; it’s about what you’re able to do after three months, six months or a year of consistent training. CONNECT gives us a way to make that progress visible and rewarding.
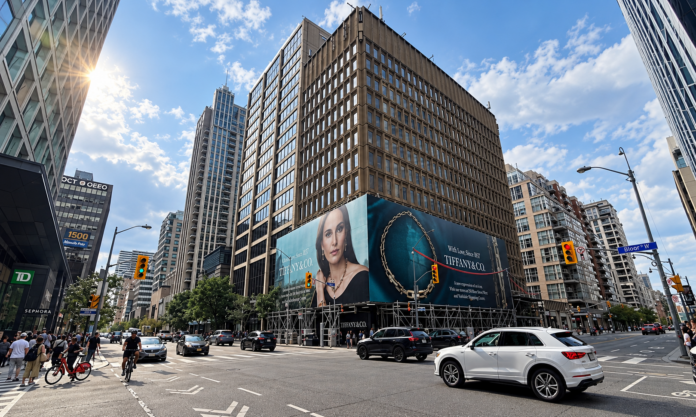
Future Tiffany & Co. at 66 Bloor St. West (corner of Bay St.) in Toronto. Photo: Craig Patterson
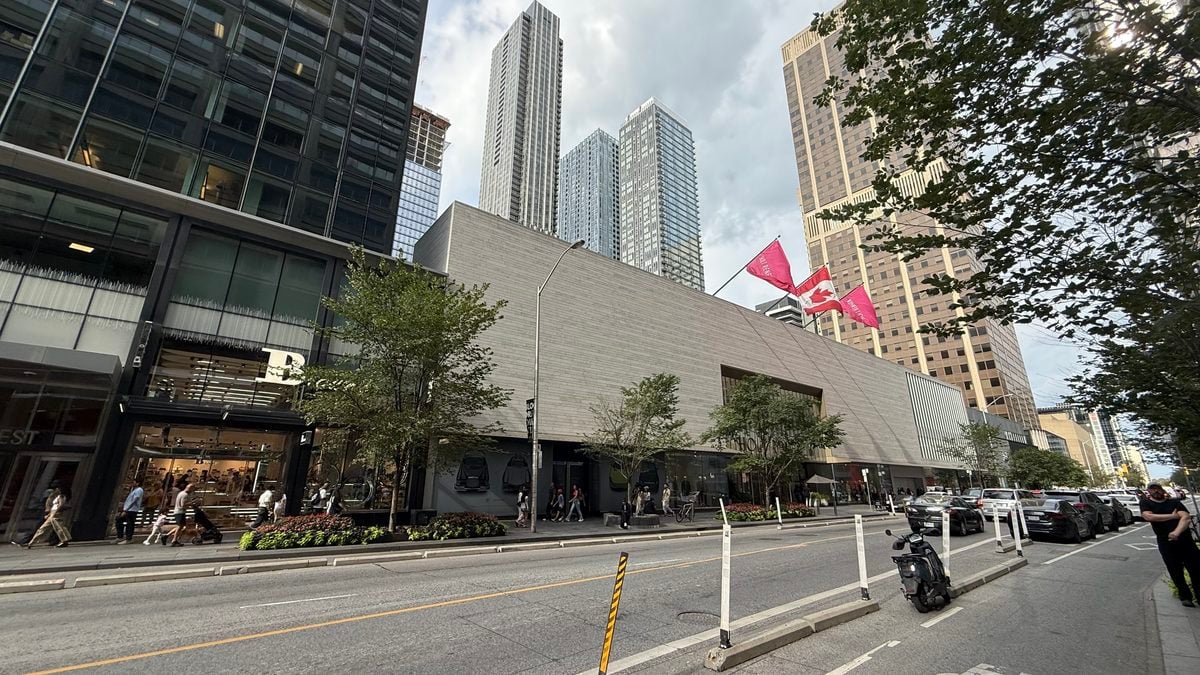
Toronto’s Bloor Street luxury corridor has changed dramatically over the past several years, as international brands invested heavily in new flagships, expanded stores and elaborate façades between Yonge Street and Avenue Road. Much of that construction took place during and in the years following the pandemic, reshaping one of Canada’s most prominent retail streets.
Another round of activity is now underway, though it looks different from the earlier flagship-building boom. New retailers and food-and-beverage concepts are arriving, established businesses are relocating or adjusting their footprints, Holt Renfrew is preparing further changes to its flagship, and several major properties remain in various stages of redevelopment or repositioning.
The activity extends well beyond luxury fashion. Jewellery and watch retailers continue to invest, new cafés are adding options to a stretch historically dominated by stores, and the area around Yonge and Bloor is developing an unusual concentration of burger and quick-service concepts. Several large development sites could also substantially alter the eastern end of the corridor in the years ahead.
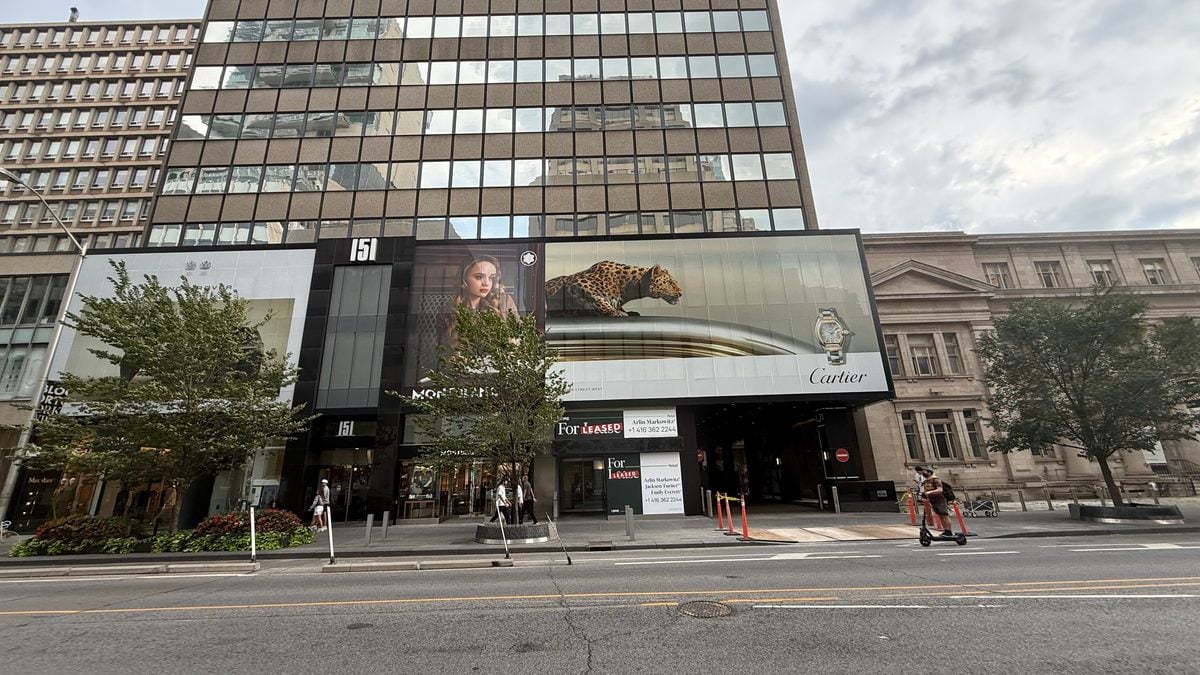
Future Delysées and RH on Bloor Street in Toronto. Photo: Craig Patterson
Delysées Coming to Bloor as RH Prepares New Flagship
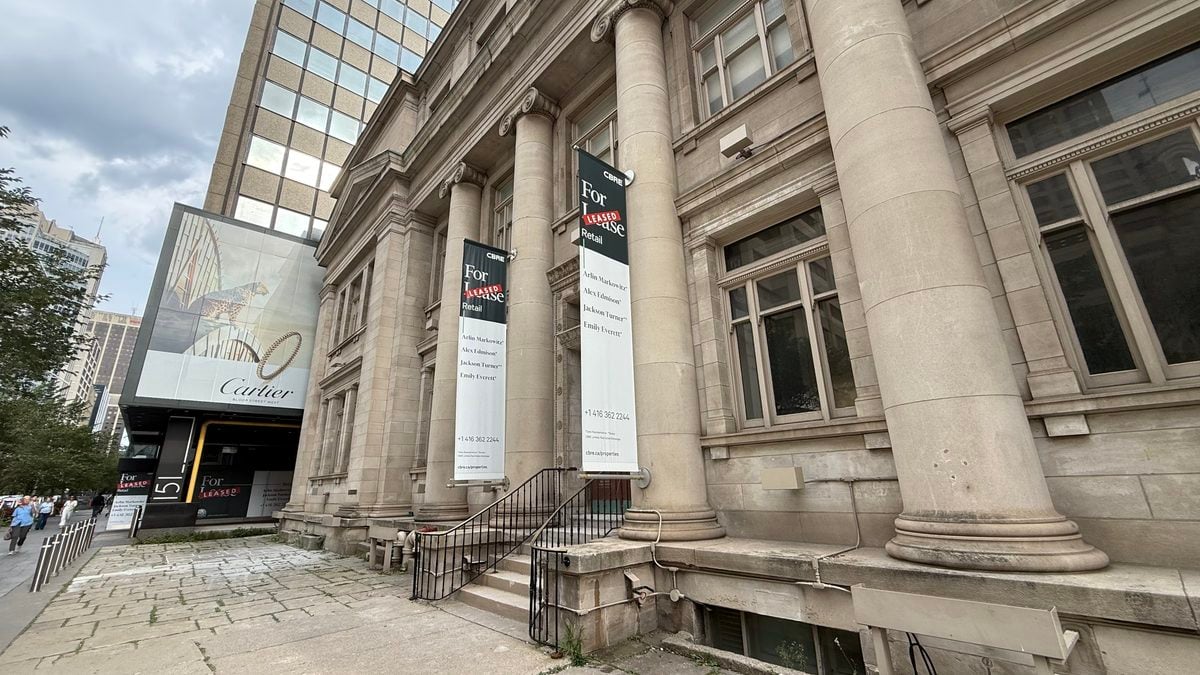
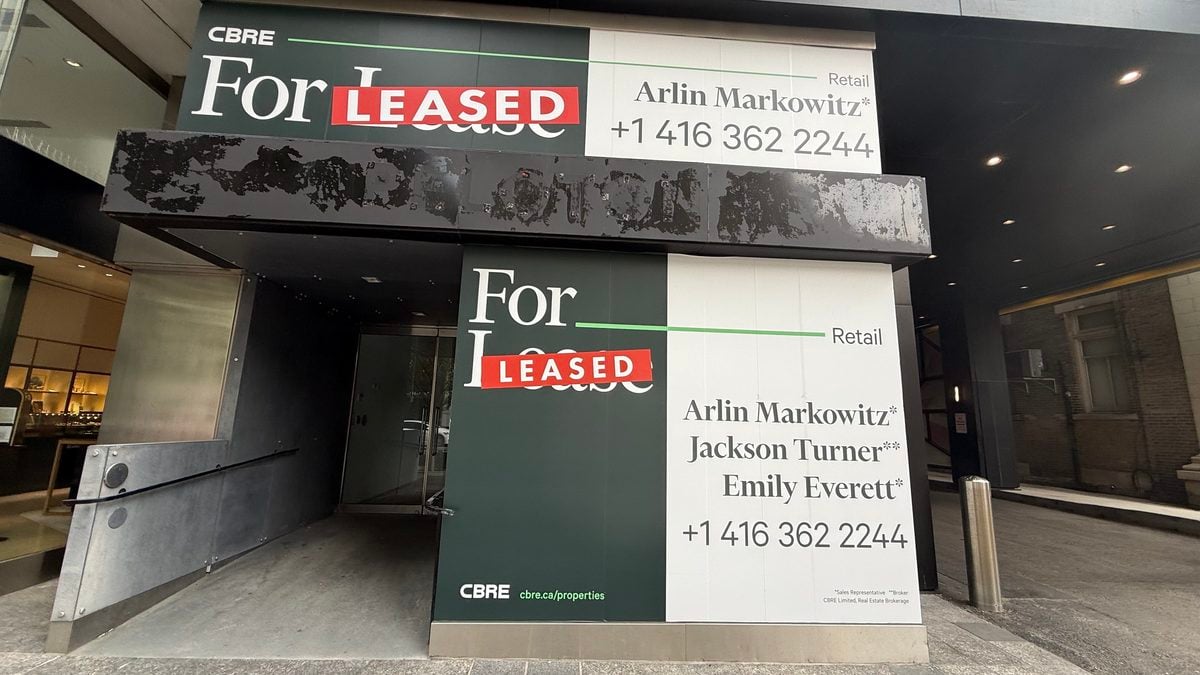
One of the newest additions will be Delysées Luxury Desserts, which Retail Insider has learned will open in the former Peloton space at 151 Bloor Street West. The French-inspired pastry and dessert concept will add another food-and-beverage offering to a section of Bloor where dining options remain comparatively limited. The lease was negotiated with CBRE’s Toronto Urban Retail Team, with Arlin Markowitz and Emily Everett involved in the transaction.
Delysées has been expanding its presence in major Canadian retail destinations. In addition to locations at Yorkdale Shopping Centre and Ossington Avenue in Toronto, Royalmount in Montreal and Lansdowne in Ottawa, the company now operates two concepts at Oakridge Park in Vancouver. Delysées Champagne Bar opened as part of Oakridge Park’s May 28 debut, pairing champagne with desserts, while a separate Delysées boutique subsequently opened near the shopping centre’s main entrance.
The Bloor location marks a return to the broader Yorkville area, where Delysées previously operated a boutique, while introducing a new use to the former Peloton premises following the fitness company’s departure.
The building at 151 Bloor also houses Max Mara, Montblanc and French childrenswear brand Bonpoint, although another tenant change could eventually come to the property. The Bonpoint premises are now being offered for lease by CBRE’s Urban Retail Team. The store remains open, and any eventual departure would be expected to follow the securing of a replacement tenant.
Immediately next door, RH will begin preparing its previously reported flagship at 157 Bloor Street West in the former Club Monaco store. The premises total approximately 17,000 square feet, with close to 10,000 square feet devoted to retail selling space and much of the remainder used for storage and supporting functions.
Sources tell Retail Insider that the Bloor location will not include an RH restaurant, distinguishing the Toronto store from some of the retailer’s larger Gallery concepts where hospitality plays an important role. The combination of RH and Delysées will bring two significant new uses to adjacent properties along this portion of Bloor.
Future RH and Delysées on Bloor Street in Toronto. Photo: Craig Patterson Future Delysées on Bloor Street in Toronto. Photo: Craig Patterson
Food and Beverage Slowly Expands Along the Luxury Strip
Despite the concentration of global luxury brands along Bloor, food-and-beverage options directly on the prime shopping stretch remain relatively sparse. Restaurants are considerably more plentiful immediately north in Yorkville, particularly along Yorkville Avenue, Cumberland Street and surrounding streets.
Paris Baguette added a street-level bakery café at 110 Bloor Street West in October 2024, while Amal operates from the second level of The Colonnade at 131 Bloor Street West. Holt Renfrew also has a restaurant on the mezzanine level of its flagship at 50 Bloor Street West, with Eataly across the street at Manulife Centre.
Delysées will fill a noticeable gap when it opens at 151 Bloor, adding another hospitality-oriented use directly to the luxury shopping strip.
Fashion, Jewellery and Watches Gain More Ground
Luxury jewellery and watches have become an increasingly prominent part of Bloor Street’s retail mix, with several properties seeing investment or tenant changes.
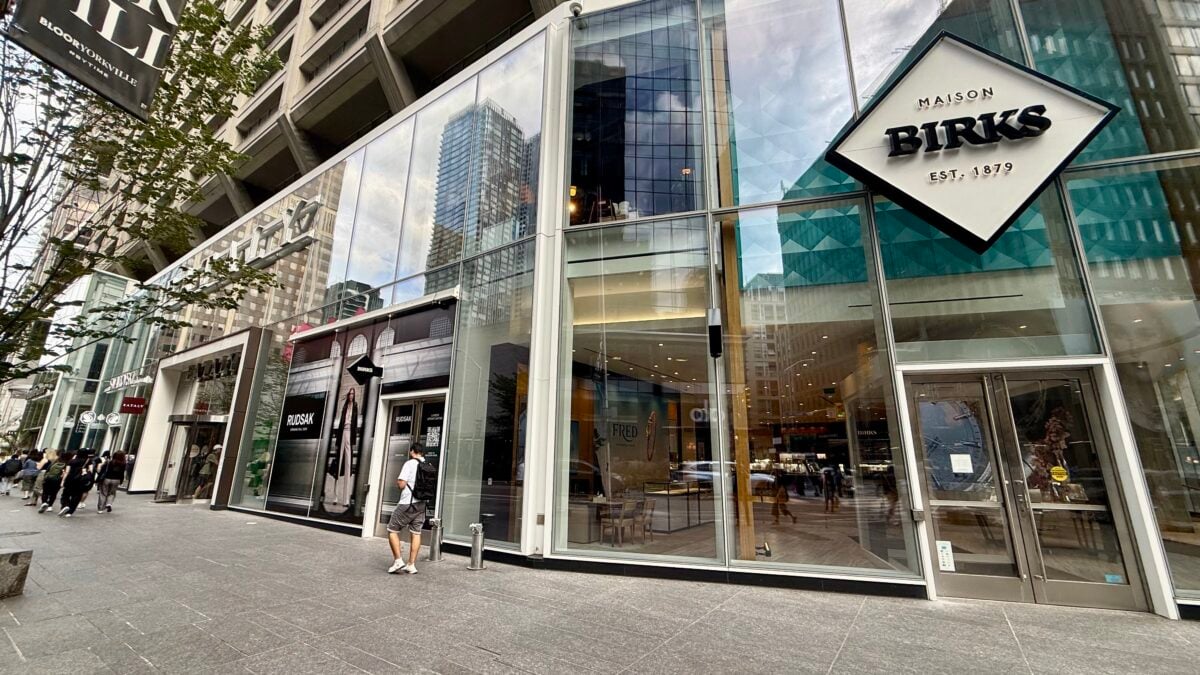
At the Manulife Centre, RUDSAK is preparing a store of approximately 1,000 square feet within a portion of the Birks premises at 55 Bloor Street West. Retail Insider recently reported that the Canadian fashion brand is taking the former Van Cleef & Arpels space through a sublease from Birks.
The deal follows a period of uncertainty over the future of the Birks flagship itself. The long-standing jeweller now appears set to remain on Bloor for the foreseeable future while changing how portions of its large premises are used.
Paris-based jewellery house FRED has opened a shop within Birks in an area previously occupied by Cartier. Montblanc is also expected to establish a presence inside the store. Together with the RUDSAK sublease, the moves point to a reconfiguration of the Birks footprint rather than the full departure that had previously been anticipated.
Future RUDSAK at Manlife Centre, 55 Bloor St. W. in Toronto. Photo: Craig Patterson
The largest project currently underway in that category is nearby at 66 Bloor Street West, where Tiffany & Co. is building a new two-level flagship. The approximately 15,000-square-foot store at the southwest corner of Bay and Bloor will replace Tiffany’s existing location at 150 Bloor Street West and is expected to open in early 2027, according to sources.
Approximately 6,000 square feet of the new Tiffany flagship will be at street level, with roughly the same amount of space upstairs. The scale of the project represents another substantial commitment to Bloor by one of the world’s best-known luxury brands.
There could eventually be further movement among the street’s major luxury tenants. Industry sources have indicated that Louis Vuitton has explored options for relocating its existing Bloor Street flagship, although no new location has been announced. Cartier is also said to be looking to relocate, while other brands are said to be looking for space either on the street or nearby.
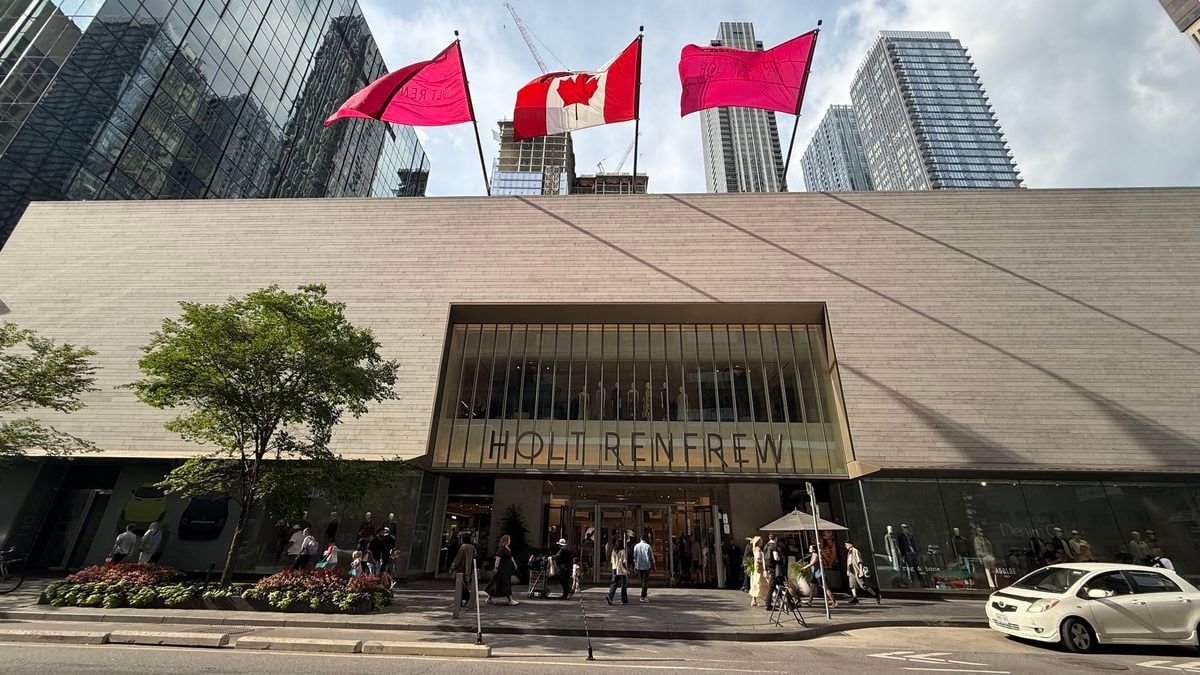
Holt Renfrew at 50 Bloor Street West in Toronto. Photo: Craig Patterson
Holt Renfrew Prepares for Another Major Reworking
Some of the most consequential changes could take place inside Holt Renfrew, one of the principal anchors of the Bloor-Yorkville retail district.
Sources tell Retail Insider that the department store is preparing another substantial reworking of its flagship at 50 Bloor Street West. Plans are expected to include the creation of additional retail space below the existing mezzanine level, along with changes to departments elsewhere in the building. A new in-store spa is said to be one of the potential additions.
The third-floor ON3 concept is expected to be repositioned as part of the project, while menswear and women’s contemporary departments will also be reorganized, according to sources. Holt Renfrew has not publicly announced the complete scope or timing of the work.
Evidence of the continuing investment can already be seen from Bloor Street. New window openings have been created on the second floor above the flagship’s main entrance, bringing natural light into a portion of the selling floor that previously had no exterior windows. The intervention has also changed the appearance of the façade when viewed from the street.
Changes are coming to the main floor as well. Moncler will open a concession of approximately 3,000 square feet in space recently vacated by Fendi, giving the Italian fashion brand a significantly larger presence within the store.
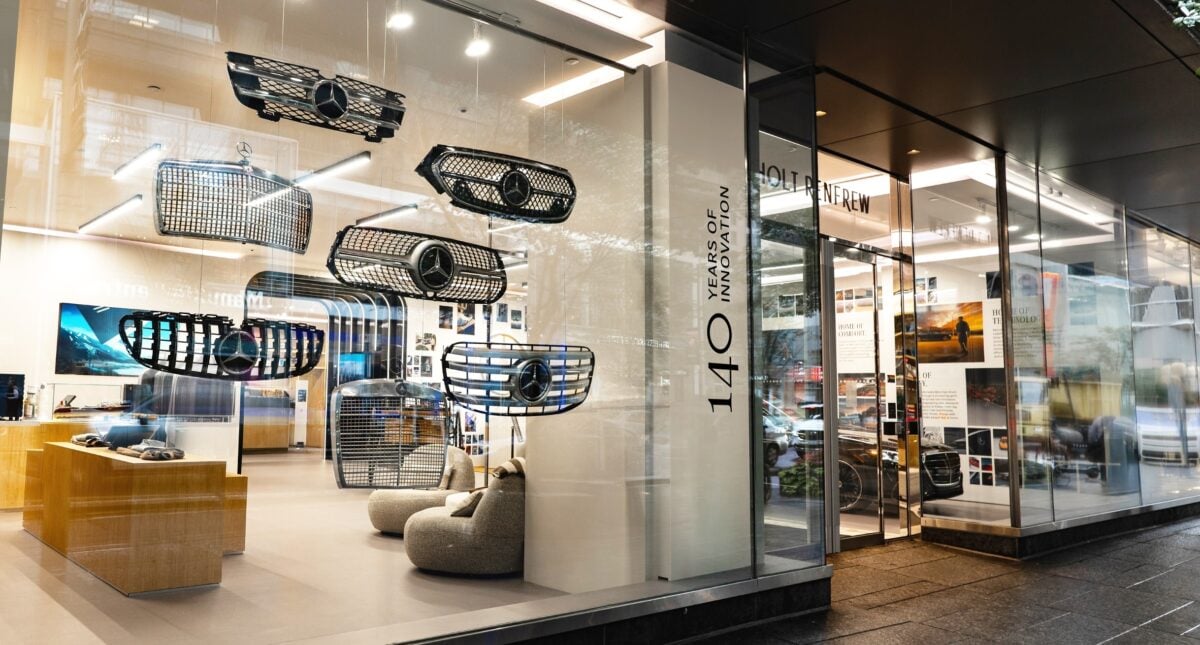
Mercedes-Benz Studio Toronto at Holt Renfrew’s Bloor Street flagship in Toronto. Image: CNW
Mercedes-Benz Canada, meanwhile, opened Mercedes-Benz Studio Toronto inside Holt Renfrew in June. The approximately 2,250-square-foot space is being used for changing automotive, fashion and design installations and is expected to remain through 2027.
The Studio recently underwent its first major refresh, reopening with a “140 Years of Innovation” experience tracing Mercedes-Benz history from the invention of the automobile through to the Canadian debut of the 2027 S-Class Sedan. The latest iteration also introduces Italian fashion brand Paul & Shark to the space.
The latest plans continue a multi-stage reinvestment in the Bloor flagship. During the pandemic, Holt Renfrew undertook a partial renovation that included a new façade, updated interiors and the return of menswear to the main store after years of operating from a standalone men’s location at 100 Bloor Street West.
Further changes are taking place under President and CEO Franco Savastano, who assumed leadership of Holt Renfrew following Sebastian Picardo’s departure in 2025. Savastano previously held senior leadership positions at European department store businesses including Globus and Jelmoli.
His arrival has coincided with several consequential decisions involving Holt Renfrew’s store portfolio, including abandoning plans for a second Vancouver location at Oakridge Park, where the retailer had been negotiating to occupy the former 140,000 square foot Hudson’s Bay premises.
The decision puts greater emphasis on Holt Renfrew’s existing network and particularly its Bloor flagship, which sits at the centre of Canada’s largest concentration of luxury retail. The planned changes indicate that investment in the property will continue beyond the renovations completed earlier this decade.
Holt Renfrew at 50 Bloor Street West in Toronto. Photo: Craig Patterson
Harry Rosen Leaves Bloor After More Than Five Decades
Another significant shift unfolded nearby, where Harry Rosen recently left an address it has occupied for more than half a century.
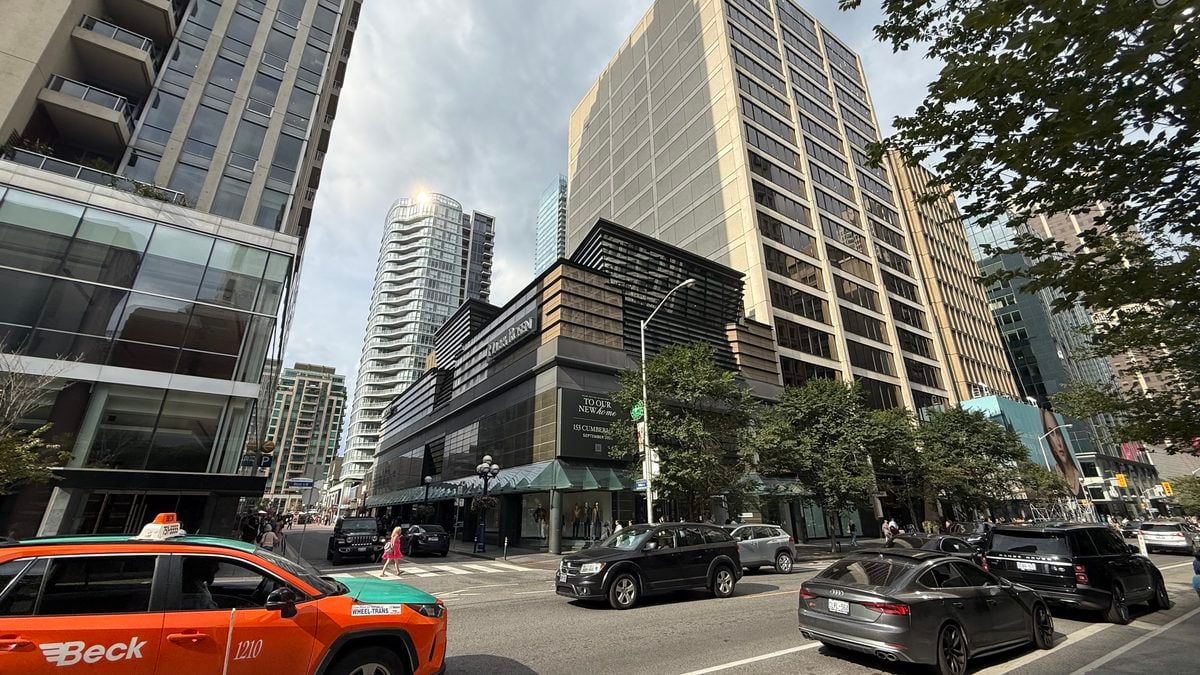
The menswear retailer closed its five-level flagship at 82 Bloor Street West on September 12 after more than 55 years on Bloor. The store spans more than 50,000 square feet and has long been one of the street’s most recognizable Canadian retail institutions.
Harry Rosen is moving less than 200 metres away to a new flagship at 153 Cumberland Street, with customer pickups scheduled to resume there September 22. While the move takes the company off Bloor itself, it keeps the retailer firmly within Yorkville and reflects the increasing integration of Bloor with the luxury retail streets immediately to the north.
The existing Harry Rosen property is tied to the longer-term redevelopment of 80 and 82 Bloor Street West. Plans have contemplated replacing the Harry Rosen building and neighbouring office tower with a substantially taller development, although the timeline has evolved.
One indication that redevelopment is not imminent can be found next door. GoodLife Fitness previously closed its gym at 80 Bloor in anticipation of future construction but has since reopened at the property.
Harry Rosen’s departure creates one of the most prominent vacancies on the luxury stretch while simultaneously adding another major retail anchor to Cumberland Street. It also illustrates how the geography of upscale retail in the area continues to spread beyond Bloor itself. CBRE is listing the building for lease until redevelopment plans are determined.
Former Harry Rosen and Holt Renfrew Men Bloor Street West in Toronto (corner of Bellair Street). Photo: Craig Patterson
One Bloor West Moves Toward Completion
At the eastern end of the district, work continues on one of Toronto’s most closely watched development projects.
The former Mizrahi development at the southwest corner of Yonge and Bloor is now known as One Bloor West, with Tridel retained as development manager, construction manager and sales manager following the financial difficulties that overtook Mizrahi Developments.
At 85 storeys and more than 300 metres in height, the tower is set to become one of the defining additions to Toronto’s skyline. Interim occupancy is anticipated beginning in 2027, with overall completion currently projected for 2028.
The retail component remains one of the project’s major unresolved questions. A prominent ground-floor space was originally intended for Apple before the technology company withdrew following a dispute with the previous developer, and the premises are now being marketed for lease by CBRE.
Sources previously told Retail Insider that RBC had examined the space at one stage, although no lease was ultimately announced.
The hotel component is also being closely watched. Tridel has publicly indicated that it is seeking a luxury hotel operator for the project, along with retail and food-and-beverage tenants.
Industry sources have told Retail Insider that Singapore-founded luxury hospitality brand Raffles has been discussed as a potential operator, with the possibility that the project’s private residences could carry ‘Raffles Private Residences’ branding as well. Raffles is part of Accor, the France-based global hospitality group.
No agreement with Raffles has been publicly announced, and Retail Insider has not independently confirmed that a transaction has been finalized.
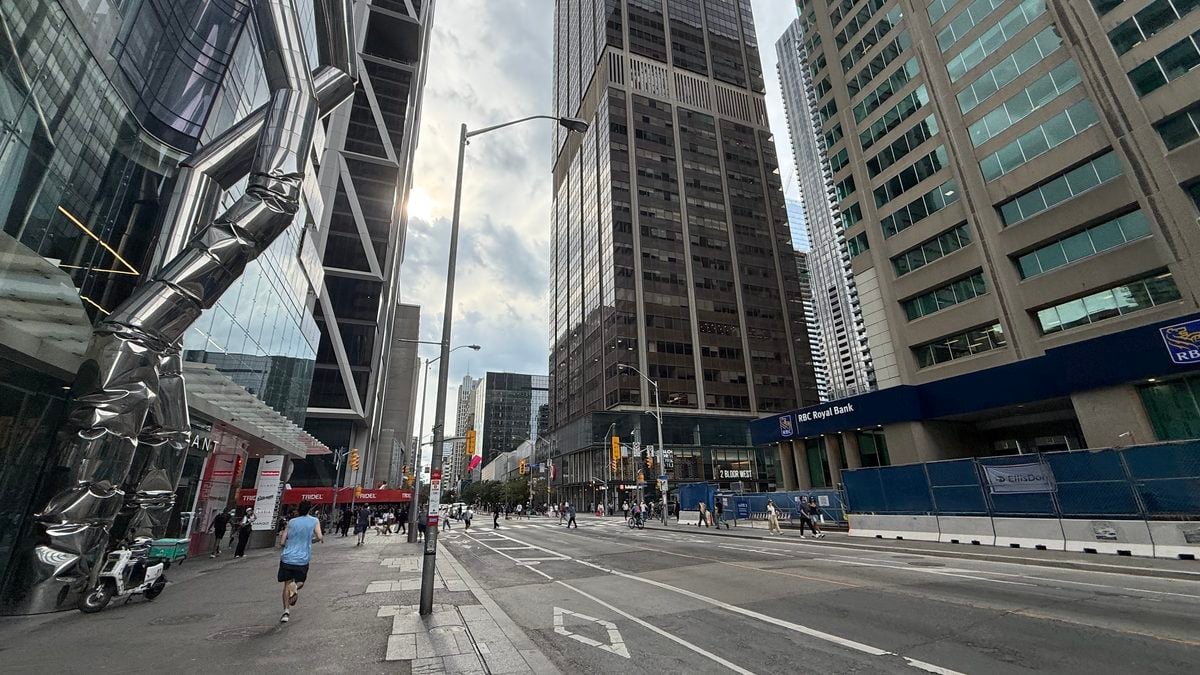
Yonge and Bloor intersection in Toronto. Photo: Craig Patterson
Fabricland Stays Put as Redevelopment Waits
Immediately west of One Bloor West, Fabricland continues to operate at 19 Bloor Street West despite longer-term plans to redevelop the property.
The site is expected eventually to become a major mixed-use project, although sources indicate Fabricland could remain for several more years before construction begins. The Kimel family, associated with Fabricland, is also involved in the ownership and development of the property.
The situation is one of several examples along Bloor where the period between redevelopment plans and actual construction has stretched considerably, allowing existing businesses to remain or return while larger projects work their way toward construction.
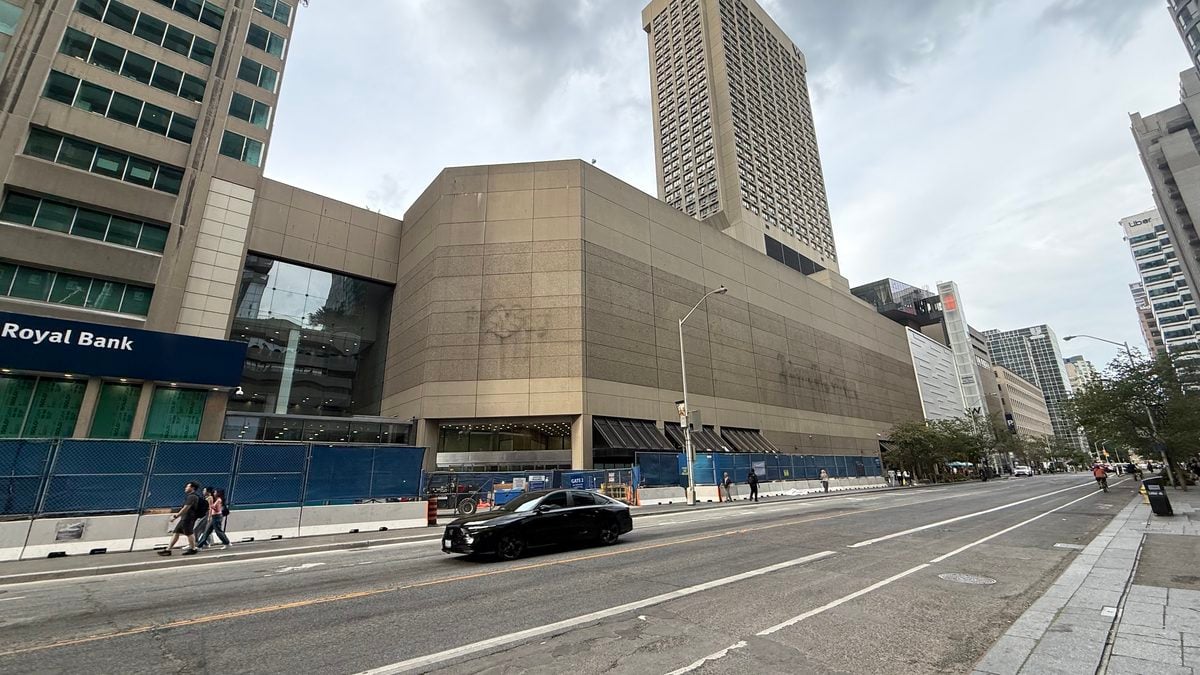
Former Hudson’s Bay store at 44 Bloor Street East in Toronto. Photo: Craig Patterson
Former Hudson’s Bay Remains a Major Question at Yonge and Bloor
Diagonally across the street, one of the corridor’s largest former retail spaces remains without the kind of major anchor that historically occupied it.
Hudson’s Bay closed its department store at 44 Bloor Street West in 2022 after nearly five decades of operation. A proposal has since emerged to convert significant portions of the former department store premises to self-storage, while the long-term retail component at the base of the property remains unclear.
There had previously been industry discussion about Canadian Tire potentially using part of the former Bay premises temporarily while its nearby store was redeveloped. Plans for the Canadian Tire property contemplate a mixed-use residential and retail development that would ultimately include a replacement Canadian Tire store, but no temporary move to 44 Bloor has been announced.
The continued uncertainty surrounding the former Bay property is particularly noticeable given its location at Yonge and Bloor, one of Toronto’s busiest intersections. It also contrasts with the level of investment taking place several blocks west, where luxury retailers continue to commit substantial capital to new and renovated stores.
New Uses Appear Below Bloor Street
The evolution of the area is also visible below street level, where new uses are appearing in spaces historically occupied by conventional stores and services.
SHKD Quest has opened on the concourse level of Holt Renfrew Centre at 50 Bloor Street West. The entertainment concept combines live-action games with mental and physical challenges designed for groups, using themed environments and competitive elements to create an immersive experience.
While parts of the format may recall laser tag and other interactive entertainment concepts, SHKD Quest has a broader focus on team-based challenges and gamified experiences.
Across the hall, Toronto Designers Market is entering a new chapter under owner Karen Ferguson and is expected to transition to the Wilkes & Bowens name this fall. Together, the concepts illustrate some of the experimentation taking place in lower-level retail environments as landlords seek businesses capable of generating repeat visits.
Future Shake Shack at 765 Yonge Street (north of Bloor) in Toronto. Photo: Craig Patterson Future McDonalds at 8 Cumberland Street/Yonge Street (north of Bloor) in Toronto. Photo: Craig Patterson
An Unlikely Burger Cluster Forms Around Yonge and Bloor
Above ground, a very different type of cluster is taking shape around the Yonge and Bloor intersection.
Shake Shack is under construction at 765 Yonge Street immediately north of Bloor, part of the U.S.-based chain’s continuing expansion in Canada. Nearby, McDonald’s is preparing another location for the area at Yonge and Cumberland Streets, occupying space at the base of the Eight Cumberland condominium tower within a row of preserved heritage façades.
South of Bloor, Oklahoma Burgers opened on Yonge Street last year, while Bings is also operating nearby. Chick-fil-A and a recently reopened Popeyes add to the concentration of quick-service restaurants surrounding the intersection.
The result is an emerging burger and fast-food cluster within a short distance of Canada’s most expensive luxury shopping street, creating an unusual juxtaposition between the luxury flagships west of Yonge and the increasingly dense collection of quick-service restaurants around the subway interchange and beyond.
Bloor’s Next Chapter Is Already Taking Shape
The most visible phase of Bloor Street’s recent transformation was defined by construction. International luxury brands built large flagships, façades were rebuilt and significant capital flowed into a relatively short stretch of Toronto’s premier shopping street.
What is happening now is more varied. Some retailers are expanding while others are shrinking or moving, jewellery brands are gaining prominence, food and beverage is slowly filling gaps in the street’s tenant mix, and Holt Renfrew is preparing another round of investment in a flagship that has already undergone considerable change.
Harry Rosen’s move to Cumberland Street also reinforces how closely Bloor now functions with Yorkville immediately to the north. Retail activity that once might have been described simply as “Bloor Street” increasingly spans a larger district encompassing Bloor, Cumberland, Yorkville Avenue and the streets connecting them.
The eastern end presents a different picture. One Bloor West is moving closer to completion, Fabricland remains in place pending eventual redevelopment, and the former Hudson’s Bay continues to await a more definitive retail future. Around those properties, experiential concepts and a growing concentration of restaurants are adding new dimensions to the neighbourhood.
Bloor Street has already changed substantially since the pandemic-era construction boom began. With Tiffany & Co. building a major new flagship, RH and Delysées preparing to open, Holt Renfrew planning further changes and several large redevelopment sites still evolving, the street and the surrounding Yorkville district are likely to look considerably different again within the next few years.