Home Blog Page 83

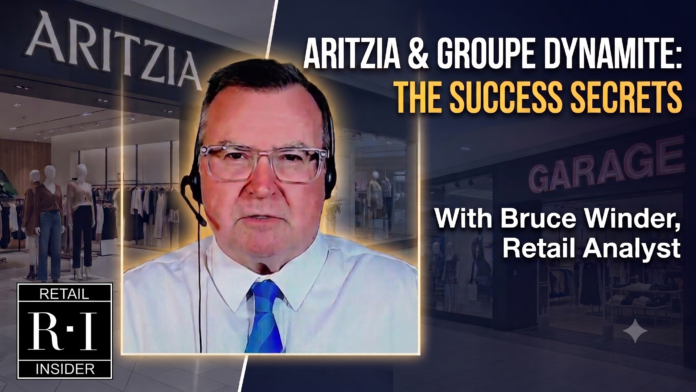
VIDEO: Aritzia, Group Dynamite outperform retail sector by targeting affluent shoppers: analyst

Canadian fashion retailers Aritzia and Group Dynamite are bucking broader retail trends with strong financial performance by focusing on affluent shoppers, disciplined execution and international expansion, says retail analyst Bruce Winder.

Winder said both companies have posted results that far exceed typical retail growth, with strong double-digit sales increases and improved profit margins at a time when many retailers are contending with cautious consumer spending.

He said Aritzia has benefited from carefully expanding its presence in the United States, where the brand was previously underdeveloped. That strategy, combined with strong digital performance, effective inventory management and well-received spring merchandise, has helped the company establish itself as an affordable luxury retailer south of the border, Winder said.

He added that Aritzia’s customer base has also provided a degree of protection from broader economic pressures because it caters to consumers with greater disposable income.

Group Dynamite, which operates the Garage and Dynamite banners, has followed a different but equally successful path, Winder said.

He said the Montreal-based retailer has elevated its brands by opening stores in marquee and more affluent locations while upgrading its merchandise assortment and price positioning. Those changes have helped expand margins and drive strong financial results, he said.

Winder said both companies have remained disciplined about identifying and serving a specific customer rather than trying to appeal to everyone.

He said each retailer targets younger, affluent women seeking premium fashion at prices below traditional luxury brands, allowing them to occupy a segment that has been more resilient despite economic headwinds affecting lower-income consumers.

Customer loyalty has also been a key factor, Winder said, pointing to consistent product quality, pricing, communication, in-stock merchandise and store experience.

International growth is providing another tailwind, he added, noting Group Dynamite’s expansion into the United Kingdom and the United States, including a planned Garage flagship store in New York’s Flatiron district.

Winder contrasted that momentum with lululemon, which he said has recently struggled to match the same level of execution across product appeal, quality and inventory.

More from Retail Insider:
Canadians entering pay periods with much of income already committed: MNP survey

Vitaly Gariev photo
Vitaly Gariev photo

A growing number of Canadians are beginning each pay period with much of their income already committed to bills, debt payments and regular expenses, according to the latest MNP Consumer Debt Index, which suggests persistent financial pressures continue to shape household spending and budgeting decisions.

The quarterly survey, conducted by Ipsos for MNP LTD, found that 61 per cent of Canadians say at least half of their income is already allocated before they receive it. One-third, or 32 per cent, say most of their paycheque is already spoken for, while 16 per cent say all of their upcoming income is committed or their expenses exceed what they expect to earn.

The findings point to ongoing financial strain despite a modest improvement in the MNP Consumer Debt Index, which rose four points from the previous quarter to 91. MNP said nearly half of Canadians remain financially vulnerable, with 46 per cent reporting they are $200 or less away from being unable to meet monthly bills and debt obligations. That figure is up three percentage points from the previous quarter. Meanwhile, 28 per cent say they do not earn enough to cover their bills and debt payments.

“Many Canadians are not just living paycheque-to-paycheque, they are entering each pay period with much of that paycheque already spoken for,” said Grant Bazian, president of MNP LTD, the country’s largest insolvency firm. “The difference is that the next paycheque is not a reset point. It is already assigned to bills, debt payments and regular expenses before it arrives. That may help people stay current in the short term, but it can also create a rolling shortfall, where each paycheque is used to catch up from the last one, leaving households more vulnerable when costs rise, income changes, or debt payments become harder to manage.”

The survey also found that financial pressures are affecting spending beyond essential household expenses.

Grant Bazian
Grant Bazian

Thirty-seven per cent of respondents said financial pressures are limiting their ability to make financial progress, while 35 per cent reported reducing spending on family and personal enrichment, including personal care, clothing and children’s activities.

More than half of respondents, or 57 per cent, said they are reducing spending on travel and experiences because of higher costs, debt obligations or global uncertainty. Within that group, 42 per cent said they are cutting back on travel or vacation plans, 40 per cent are spending less on concerts, festivals, sporting events and other entertainment, and 35 per cent are reducing weekend or day trips.

The survey found 56 per cent are also spending less on dining and social activities. Nearly half said they are cutting back on restaurants, patios, takeout or coffee shops, while others reported spending less on celebrations or hosting family and friends.

Nearly one-quarter of Canadians, or 23 per cent, said they have cancelled plans or chosen not to make them because of financial pressures, while nine per cent said they are relying on credit or borrowed money to maintain activities. Younger Canadians were more likely than those aged 55 and older to report cutting back across the categories measured.

“Canadians are not just tightening their budgets. Many are shrinking parts of their lifestyle to keep up with the cost of essentials,” said Bazian. “When people are cutting back on plans, using credit to maintain activities, or scaling back on the things that help them feel connected and supported, financial pressure can start to affect more than household balance sheets. It can weigh on overall quality of life and emotional well-being.”

The survey found Canadians remain cautious about the impact of borrowing costs even as the Bank of Canada has held its key interest rate steady this year.

While 24 per cent said they would feel better able to handle a one-percentage-point interest rate increase and 22 per cent said they would feel worse, only 21 per cent said they could absorb an additional $130 in monthly interest payments. More than one-third, or 35 per cent, said they could not.

RDNE Stock project photo

At the same time, 62 per cent said they need interest rates to decline, while 53 per cent said they remain concerned about facing financial difficulty if rates increase.

“Stable interest rates may offer some predictability, but they don’t necessarily create relief when other financial pressures remain unpredictable,” said Bazian. “With households still navigating elevated living costs, debt-servicing demands, and broader economic uncertainty, even a modest increase in required payments can force difficult trade-offs, from cutting back further to relying more heavily on credit to stay current.”

The report says households managing by reducing discretionary spending, postponing plans, limiting savings or relying on credit may still be facing increasing financial pressure, even if they continue meeting their obligations.

The survey also found that expectations for future debt levels have improved modestly. Thirty per cent of Canadians expect their debt situation to improve over the next year, while 40 per cent anticipate improvement over the next five years.

The MNP Consumer Debt Index is based on an Ipsos survey of 2,000 Canadians aged 18 and older conducted between June 11 and June 16, 2026. Ipsos said the results have a credibility interval of plus or minus 2.7 percentage points, 19 times out of 20.

More from Retail Insider:
Restaurant industry leads Canada in youth job growth through first half of 2026

Pavel Danilyuk photo

The restaurant and accommodation industry has been the biggest net youth jobs creator of any sector since the start of the year, says Restaurants Canada. 

While most other industries have been cutting youth jobs, the restaurant industry employed an average of 52,770 more youth during the first half of 2026 than during the same period in 2025, according to the latest Statistics Canada Labour Force survey recently released, said the organization.

“The numbers are clear—our sector has created more new youth jobs than all other industries combined,” said Kelly Higginson, President and CEO of Restaurants Canada. “As youth unemployment continues to be a major national concern, the restaurant industry continues to play an important role in ensuring young people have the opportunities they need to launch their careers.”

The restaurant and accommodation sector employed 543,000 youth in June, a 12% increase over last year. Restaurants account for 85% of employment in the sector. British Columbia saw the biggest increase of youth restaurant jobs (16,800), followed by Alberta (14,000) and Quebec (10,000), said the organization.

Restaurants Canada said it is committed to working with federal and provincial governments on workforce strategies to ensure that the restaurant sector continues to be the champion for youth employment.

Kelly Higginson
Kelly Higginson

Restaurants are the fourth largest private sector employer in Canada, employing 1.2 million Canadians, 40% of whom are youth. The industry is facing significant labour shortages across the country, especially in roles requiring training, like chefs, cooks and management. At the same time, profits in the industry remain fragile, with 36% of companies operating at a loss or just breaking even, making investments in hiring and training difficult, it explained.

“We are the number one source of first-time jobs in Canada, and that hasn’t changed over the years. One in six youth jobs are in our industry,” added Higginson. “Today’s jobs numbers show that the restaurant industry is positioned to provide young workers the early career training and skills they need to succeed in any sector of their choosing. Governments should invest in us so we can continue to invest in our youth.”

More from Retail Insider:
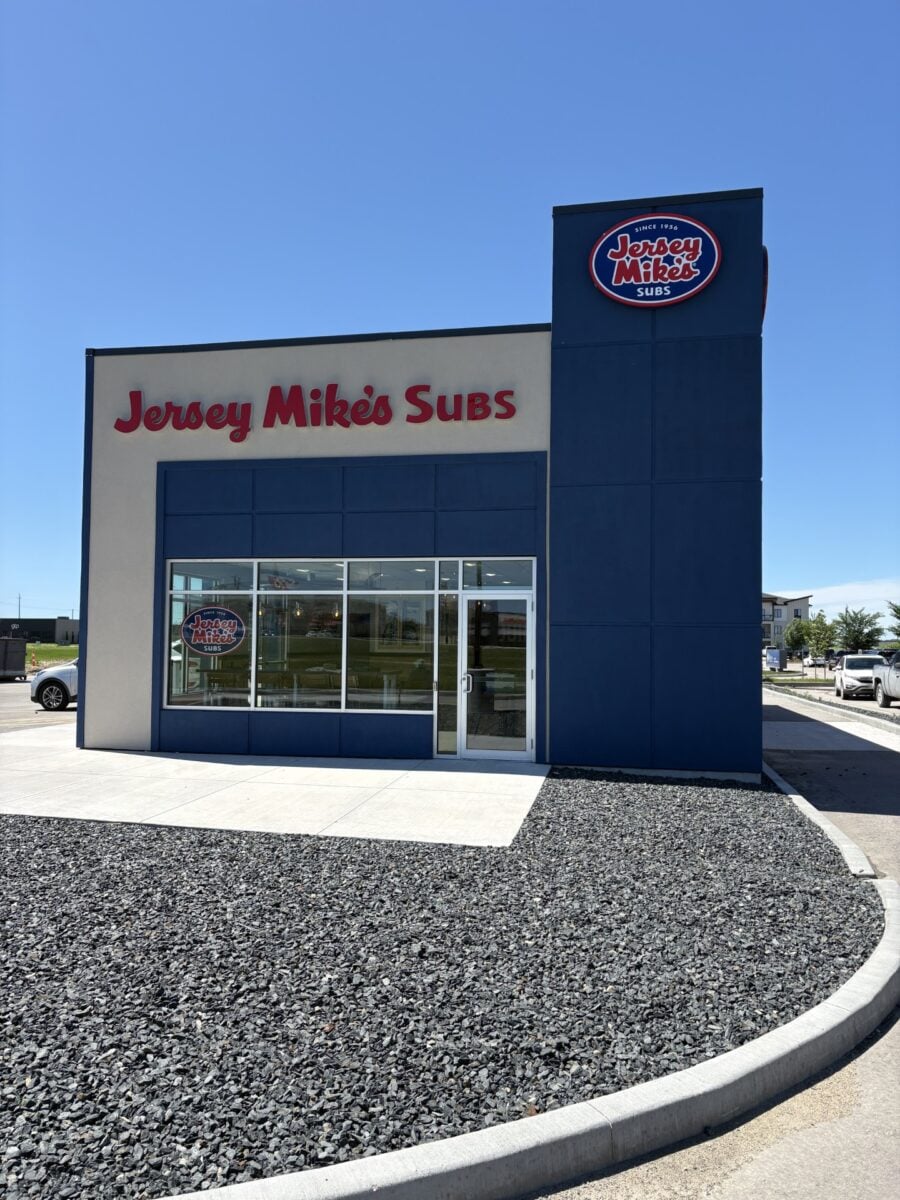
Jersey Mike’s opening first Manitoba restaurant as Redberry expands Canadian footprint

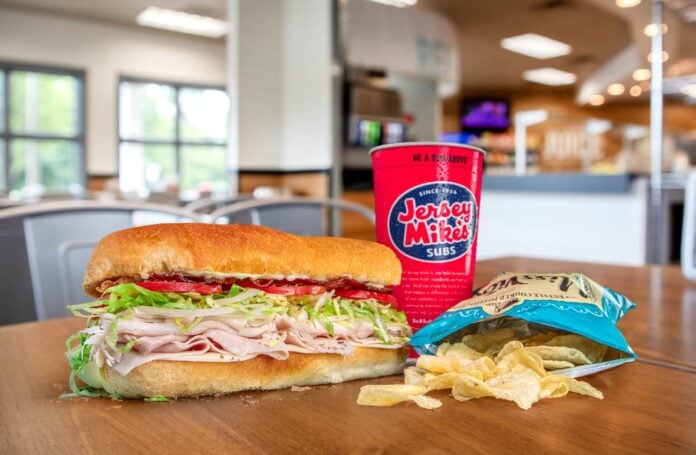
Image: Jersey Mike's Subs

Jersey Mike’s Subs is opening its first restaurant in Manitoba, marking the latest step in franchise operator Redberry Restaurants’ plan to expand the sandwich chain’s presence across Canada.

The Steinbach restaurant, located at 17 Market Blvd., is scheduled to open Wednesday, July 15. Redberry said it now operates more than 30 Jersey Mike’s locations across Canada as part of a plan to grow the brand to 300 Canadian restaurants by 2035.

The opening also launches a five-day fundraising campaign in support of Make-A-Wish Canada, part of a broader commitment announced in May to raise $1 million for the charity by 2030. The company said it has raised more than $270,000 for the organization since 2024.

Customers who receive a fundraising coupon distributed before the opening can make a minimum $3 donation to Make-A-Wish Canada in exchange for a regular sub during the campaign, which runs from July 15 to July 19. The company said customers must present a coupon to participate in the offer.

Customers without a coupon will be able to download the Jersey Mike’s app and receive a free regular sub after making their first in-app sub purchase during a limited-time promotion. They will also have the option to donate to Make-A-Wish Canada through a donation box located near the restaurant’s register.

Ken Otto
Ken Otto

“As we’ve expanded throughout the country, we’ve received many requests to bring Jersey Mike’s to Manitoba, and we’re excited to open our first-ever location in Steinbach,” said Ken Otto, CEO, Redberry. “Steinbach is a vibrant community with a growing restaurant scene, and we welcome everyone in for a taste of ‘A Sub Above’ and to help make a difference through our fundraiser with Make-A-Wish Canada.”

The Steinbach location will serve Jersey Mike’s menu of fresh sliced and grilled submarine sandwiches. The company said its meats and cheeses are sliced to order and served on bread baked in-store, while cheesesteaks are grilled fresh for each order.

The restaurant will be open daily from 10 a.m. to 10 p.m. Customers will be able to order in person, through the Jersey Mike’s mobile app, online and through national delivery platforms. Catering services will also be available.

Redberry, founded in 2005, operates more than 200 quick-service restaurants across Canada under the Burger King, Taco Bell and Jersey Mike’s brands. The company said its expansion has been supported through its partnership with Uncommon Equity.

Jersey Mike’s, founded in 1956 as Mike’s Subs in Point Pleasant, N.J., has grown to more than 3,200 locations across the United States and Canada.

Jersey Mike's in Steinbach
Jersey Mike’s in Steinbach

Make-A-Wish Canada grants wishes for children diagnosed with critical illnesses and operates as part of an international wish-granting organization serving children in communities across Canada and in 50 countries worldwide. The organization said it has granted more than 40,000 wishes over the past 43 years, including 1,835 last year.

More from Retail Insider:
Rising costs and supply chain volatility put consumer goods brands under growing pressure: DOSS

Dario Solano photo
Dario Solano photo

Rising costs and supply chain volatility are putting massive pressure on consumer goods brands—but the real issue may be happening behind the scenes. In a new study, DOSS surveyed 230 U.S. CPG (Consumer Packaged Goods) operations leaders to uncover where workflows are breaking down across product launches, manufacturing, and retail readiness.

Key Takeaways:

  • one in two CPG leaders shipped products with incorrect labeling or packaging due to miscommunication
  • one in four product launches were delayed, costing brands an average of 2.4 weeks
  • 36% made major business decisions using outdated or incorrect data
  • 44% of teams say their operations are primarily reactive
  • Only 14% say AI has meaningfully improved efficiency—despite 40% already using it.

View the full study here.

The findings point to a growing operational gap as brands scale—where fragmented systems, manual work, and poor data visibility are driving costly mistakes. As retail expectations tighten and margins shrink, these inefficiencies are becoming harder to ignore.

In an interview with Retail Insider, Sebastiaan Debrouwere, VP Business Development & Marketing at DOSS, discusses the survey results. 

Sebastiaan Debrouwere

Question: The study found that one in two CPG leaders shipped products with incorrect labeling or packaging because of miscommunication. Why are these errors still happening at such a high rate despite advances in supply chain technology?

Answer: While most of today’s consumer brands have invested heavily in operations technology, they have not unified it, creating silos between different parts of their businesses. Critical product information lives in spec sheets from Walmart and Target, shipping and compliance requirements from each retailer, format templates from contract  manufacturing partners, and internal artwork files. None of those sources talk to each other. The issue is usually less about a lack of software and more about the brand, the contract manufacturer, the warehouse and logistics partner, and the retail partner working from different versions of the truth.

The breaking point is often coordination with contract manufacturers, the partners who physically produce the product. Around a third of the errors we see trace back to a brand sending one spec, the manufacturer interpreting it against a slightly older template, and the finished product arriving at the retailer’s warehouse with the wrong barcode, product identifier, or pallet setup. Product launches move quickly, packaging changes mid-flight, and retailer compliance requirements update quarterly. When those updates travel through disconnected workflows, the error rate compounds.

Q: With one in four product launches delayed by an average of 2.4 weeks, what are the biggest operational bottlenecks slowing brands down today?

A: The biggest bottlenecks are usually coordination and visibility problems rather than a single manufacturing issue. Modern product launches involve dozens of moving parts across suppliers, contract manufacturers, retailers, and internal teams. When one step slips, such as a Walmart shelf reset, a mapping via electronic data interexchange (EDI) that lags behind a new retailer requirement, or an accounting sync that breaks the order-to-payment cycle, it triggers a chain reaction across every downstream workflow.

Another major challenge is the ongoing dependence on manual processes. Our findings show nearly 40% of workday time is spent on manual data entry, including re-keying purchase orders, reconciling inventory counts between the warehouse and financial system, and building packaging templates for each new retailer. That slows decision-making and increases the chance of errors during already compressed launch timelines.

Q: The report suggests many companies are still making decisions based on outdated or inaccurate data. How much of this is a technology problem versus an organizational or leadership problem?

A: Both, as they’re  interrelated.

On the technology side, most consumer brands run a stack of fragmented systems that cannot communicate with each other. An enterprise resource platform (ERP) used for business operations that was not built for consumer goods, a separate system at the warehouse, spreadsheets for manufacturer coordination, and a forecasting tool that does not reconcile to actual on-hand inventory. Teams spend a lot of time reconciling data together across systems before they can make a decision.

On the organizational side, departments optimize for their own goals. Procurement focuses on cost, operations focuses on keeping shelves stocked, finance focuses on closing the books, and the data degrades at every handoff. Leadership teams increasingly recognize this issue, which is part of why we’re seeing more investment in operations technology that solves these silos with a unified view of the business.

Gustavo Fring photo
Gustavo Fring photo

Q: Many companies have already adopted AI tools, yet only 14% say AI has meaningfully improved efficiency. Are businesses overestimating what AI can solve without fixing underlying workflow and data issues first?

A: Yes, and that’s one of the clearest findings from our research. AI is only as good as the data it sits on top of. If a brand is still running on fragmented systems, spreadsheets, and inconsistent  product data, AI just surfaces the same inefficiencies faster.

Most businesses started layering AI tools before fixing the underlying processes around documentation, system integration, and product data standardization. So the model produces a forecast or a recommendation that no one trusts, because the inventory data feeding it is three days stale and reconciled by hand. We have seen this play out enough that some consumer goods operations leaders, especially those managing fast-changing demand patterns, have started to distrust AI forecasting outputs, which becomes its own problem.

The brands seeing real AI gains tend to be the ones with clean inventory data, integrated order flows, and standardized product information  already in place. Everything else is building on a weak foundation.

 It all comes down to the ability to make decisions efficiently by accessing a unified source of truth in real time.

Q: As retailers demand faster launches, better forecasting, and fewer errors, what operational capabilities will separate successful consumer brands from those that struggle over the next few years?

A: The strongest brands are building one operational system that connects inventory, procurement, production, fulfillment, and financial data in real time. When a retailer changes a spec, a manufacturer flags a delay, or a shipping route gets disrupted, the right teams can see it immediately without manual reconciliation.

What separates the winners is increasingly purpose-built consumer goods operations software rather than generic ERPs. A $100K+ NetSuite or SAP implementation was not designed for production tracking, manufacturer coordination, retail compliance, or the packaging and labeling cycles that define consumer goods. Brands that try to bend a generic ERP into that shape end up with the same fragmentation problem they started with, except more expensive.

Ultimately, the companies that win will be the ones that reduce operational friction before customers and retailers experience it.

More from Retail Insider:
Daily Synopsis: Jul 13, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 8 articles we published covering key developments in Canadian retail.

Mondetta returned to physical retail in years at Holt Renfrew with a pop-up store as it plans a network of about 20 permanent locations across Canada starting in fall 2027. The Canadian Health Food Association launched The Greenhouse program to support emerging wellness brands with exhibition opportunities and growth resources during CHFA NOW in Toronto.

New federal sentencing reforms take effect July 15 introducing penalties for retail theft motivated by resale. Supernatural opened an immersive wellness studio in Toronto’s Yorkville neighbourhood focusing on sound and sensory experiences. New research shows Canadian shoppers choose by shopping mission, not channel, moving fluidly between online and physical stores depending on their needs.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

Retail Insider “Consumer Behavior & Retail Economy Report”: Canada’s Market Grows Increasingly Divided

A new Retail Insider Report, Q2 2026 Consumer Behavior and Retail Economy: A Market Increasingly Divided, authored by Craig Patterson, examines how consumer spending patterns and broader economic conditions are reshaping Canadian retail. Part of the Retail Insider Reports series, the report draws on Retail Insider’s reporting, public company disclosures, and broader economic research to identify developments most relevant to retail decision-makers. Retail Insider Reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

The report examines two closely connected areas: Consumer Behavior, including shopping habits, spending priorities, demographics, loyalty, purchasing decisions, and evolving customer expectations; and the Retail Economy, covering retail sales, inflation, employment, consumer confidence, interest rates, tariffs, trade, and other economic indicators. Together, they provide context for understanding how Canadians are spending and how retailers are adapting.

General Themes

  • A More Polarized Consumer — Canadians continue spending, but purchases are becoming increasingly selective as households prioritize value and essential goods.
  • Affordability Drives Decisions — Housing costs, food prices and broader economic uncertainty continue to influence purchasing behaviour across income groups.
  • Value and Premium Outperform — Discount retailers and premium brands continue to show relative strength while much of the middle market faces mounting pressure.
  • Retail Real Estate Continues to Diverge — Canada’s strongest shopping centres attract investment and leading retailers while secondary assets face redevelopment and competitive challenges.
  • Experience Still Matters — Food, entertainment and experience-focused retail concepts continue attracting consumers despite broader spending caution.
  • Operational Challenges Persist — Labour shortages, consumer trust concerns and evolving public policy continue to influence retailer strategy and operations.

Retail Insider Coverage

Retail Insider’s reporting throughout the quarter helped document many of the trends explored in the report. Coverage included weakening consumer spending intentions, Canada’s shrinking middle class, shopping centre performance, Toronto’s active retail leasing market, international retailers entering Canada, wholesale expansion strategies, labour challenges in foodservice, and the growing issue of AI-generated fake product reviews.

The report also connects individual stories into broader market patterns. Coverage of Yorkdale Shopping Centre, CF Toronto Eaton Centre, CF Pacific Centre, Primaris REIT, Choice Properties, Zellers and TJX illustrates how investment, leasing activity and consumer demand continue concentrating around Canada’s strongest retail assets and operators rather than being evenly distributed across the market.

Broader Industry Coverage

Beyond individual news developments, the report suggests Canadian retail is increasingly characterized by structural divergence rather than broad-based growth. Affordability pressures continue to influence purchasing decisions, while premium consumers remain comparatively resilient, creating opportunities at both ends of the market but increasing pressure on retailers positioned in the middle.

The report also points to continued concentration in retail real estate, with international expansion and investment focused primarily on Canada’s leading urban retail nodes. At the same time, retailers are navigating operational issues that extend beyond consumer demand, including staffing, transparency, competition policy and evolving expectations around trust and authenticity.

Editor’s Take

The report argues that Canada’s retail market is no longer defined simply by consumer caution but by growing separation between winners and losers. Value retailers, premium concepts, dominant shopping centres and retailers able to combine convenience, loyalty and compelling customer experiences continue to demonstrate resilience. Meanwhile, affordability pressures, weaker discretionary spending and structural challenges facing secondary retail assets suggest success increasingly depends on aligning with where consumer demand and investment are concentrating, rather than relying on broad market growth.

Readers can explore the complete Q2 2026 Consumer Behavior and Retail Economy: A Market Increasingly Divided report, along with the full collection of Retail Insider Reports, through the Retail Insider Report Hub. The report offers additional analysis and sector-specific insights for retailers, landlords, developers, brands, consultants and investors seeking to better understand the forces shaping Canada’s retail economy.

Mondetta Returns to Physical Retail at Holt Renfrew as National Expansion Takes Shape

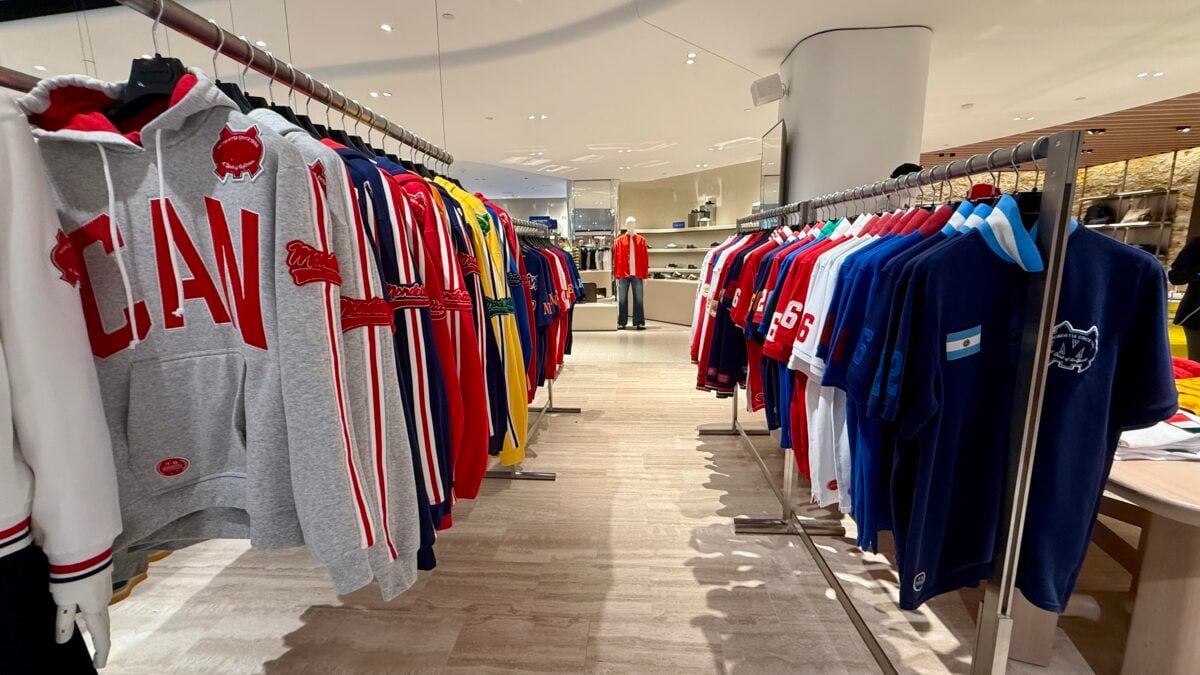
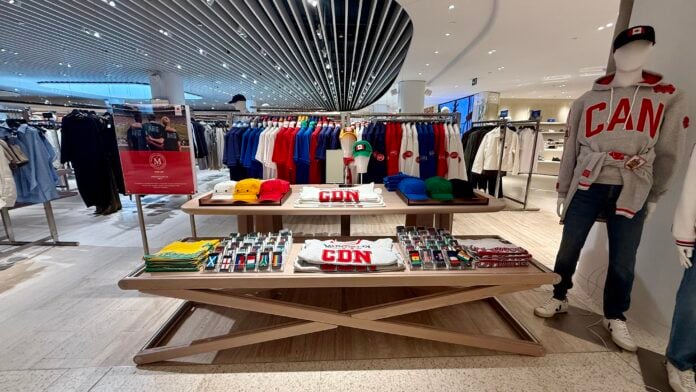
Mondetta Originals pop-up ON3 at Holt Renfrew, 50 Bloor St. W. in Toronto, July 10, 2026. Photo: Craig Patterson

On the third floor of Holt Renfrew’s Bloor Street flagship in Toronto, one of Canada’s best-known apparel names is beginning a new chapter in physical retail.

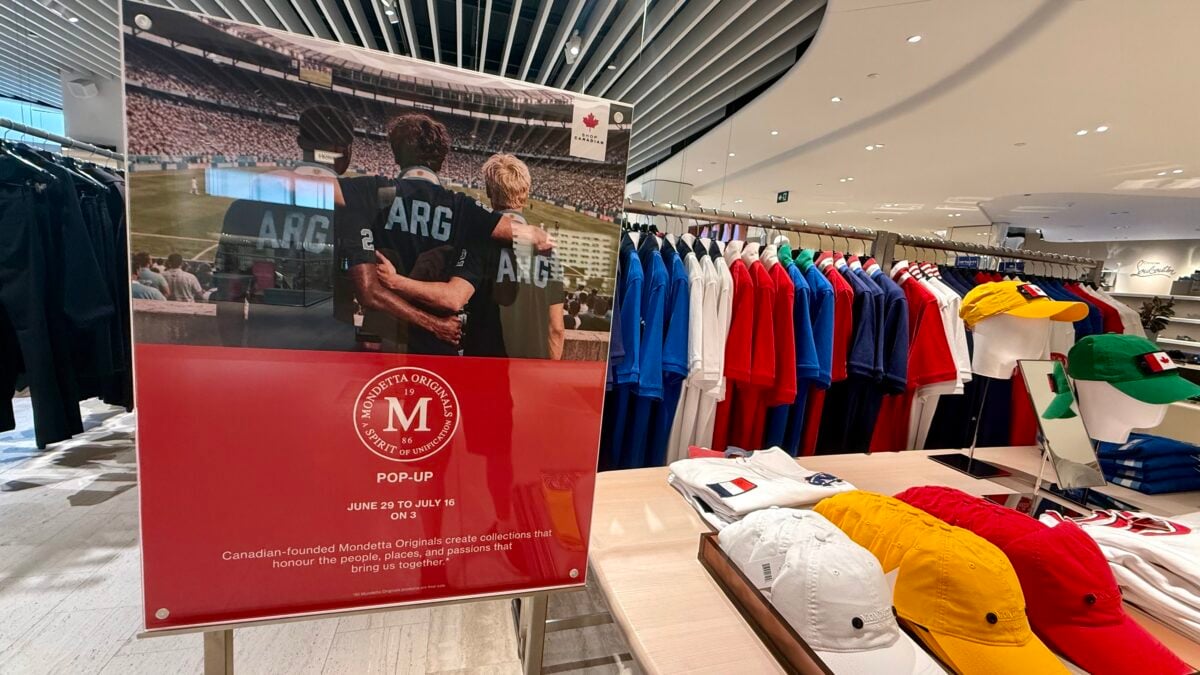
Mondetta Originals opened a colourful pop-up on June 29 within ON3, Holt Renfrew’s extensively redeveloped third floor. The temporary shop is scheduled to run until Thursday July 16, placing the Winnipeg-founded brand in a flexible activation zone that has hosted a changing roster of international and Canadian labels since the floor’s transformation.

For Mondetta, the pop-up is an early step in a much larger plan.

Georgi Gvakharia, Senior Vice President and Global Head of Retail at Mondetta Clothing, told Retail Insider that the company is developing a new generation of permanent Mondetta stores, with the first locations targeted for fall 2027 and a longer-term Canadian network that could ultimately reach roughly 20 stores.

Aurora Retail Group is representing both Mondetta and Modern Ambition in their Canadian retail expansion strategies. Jeff Berkowitz, Co-CEO of Aurora Retail Group, is leading the real estate search as the company evaluates locations for permanent stores across the country.

The planned locations are expected to span approximately 3,000 to 5,000 square feet, depending on the market and available real estate. Winnipeg is confirmed as one of the first cities, while the company is evaluating opportunities in western Canada as it works toward a possible launch of two or three stores at roughly the same time.

“It’s a great introduction, or really a reintroduction, of the brand to consumers from a direct-to-consumer perspective,” Gvakharia said of the Holt Renfrew pop-up.

Forty years after Mondetta was founded in Winnipeg, the company is preparing to rebuild a direct physical relationship with Canadian consumers.

Mondetta Originals pop-up ON3 at Holt Renfrew, 50 Bloor St. W. in Toronto, July 10, 2026. Photo: Craig Patterson

A Physical Reintroduction at Holt Renfrew

Gvakharia said the Holt Renfrew activation is significant because it gives Canadian consumers their first current opportunity to walk into a physical store, see and feel Mondetta Originals product and buy it in person.

The collection has been available online, but the Bloor Street pop-up marks a return to physical consumer-facing retail for Originals.

“Originals is the DNA of the brand,” Gvakharia said. “That’s where Mondetta began in 1986.”

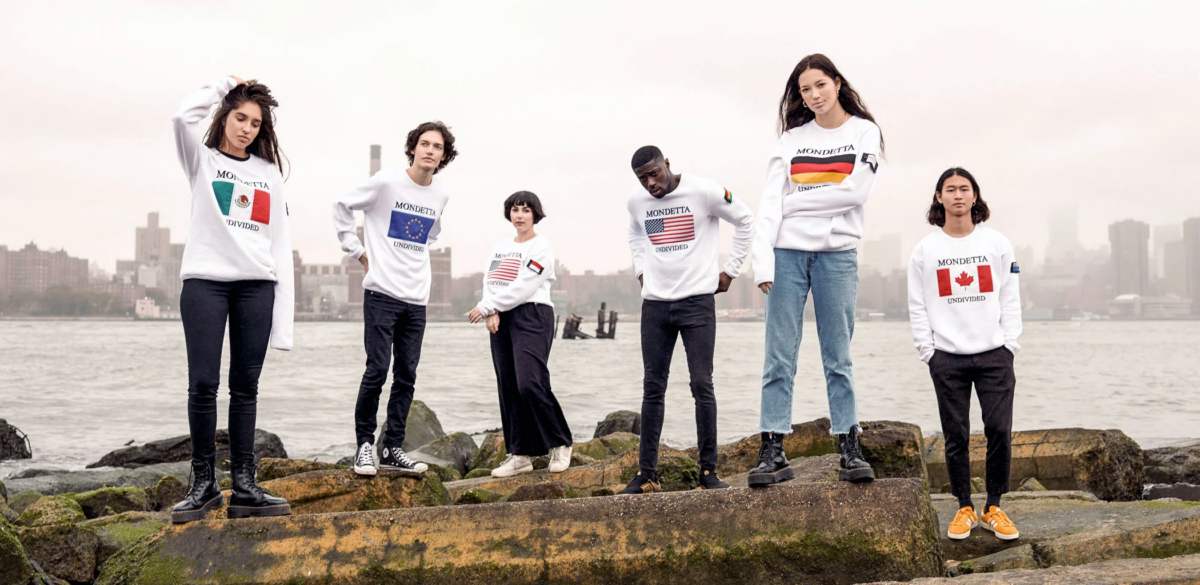
He pointed to the flag-bearing shirts and other pieces that helped introduce Mondetta to consumers and became closely associated with the company during its early growth.

Georgi Gvakharia

The timing of the activation is deliberate. Gvakharia said major international football events created a natural backdrop for a brand whose identity has long been tied to flags, countries and ideas of global connection.

The pop-up sits within ON3, the extensively redeveloped third floor of Holt Renfrew’s 50 Bloor Street West flagship.

The history of the space gives the Mondetta placement added context. ON3 has become a visible setting for temporary activations involving both major international labels and Canadian brands introducing new concepts or reconnecting with consumers.

“We had the opportunity to partner with Holt Renfrew on a pop-up here at the Bloor Street flagship,” Gvakharia said. “It’s a very beautiful, colourful shop on the third floor.”

He said sales and customer response have been strong. Gvakharia also said Mondetta is discussing other opportunities with Holt Renfrew, though he declined to provide details.

Forty Years After Mondetta’s Founding

Mondetta traces its origins to Winnipeg in 1986 and became widely recognized for flag-bearing apparel that turned international identity into a distinctive fashion statement.

The company’s own historical account traces its beginnings to homemade T-shirts sold from a pushcart before the idea for flag apparel emerged after one of the founders saw a German flag attached to a Volkswagen Beetle.

The concept became central to Mondetta’s early identity. The name reflects the same global outlook. Mondetta combines “monde,” the French word for world, with a suffix intended to convey the idea of a smaller, more connected world.

Over time, the business expanded well beyond the flag apparel that many consumers still associate with the name.

Gvakharia described the broader brand structure as including Mondetta Originals, the main Mondetta label focused on everyday essentials, and MPG, or Mondetta Performance Gear, centred on active and performance apparel. Modern Ambition, the company’s newer premium menswear concept, is developing separately through its own store expansion.

The coming Mondetta stores are expected to bring several parts of that business into a single consumer-facing environment.

Image: Mondetta Clothing

New Stores Planned for Fall 2027

Gvakharia said the company is targeting fall 2027 for the first permanent locations under the new Mondetta concept, with tentative timing around August or September.

Winnipeg will be among the first.

“Winnipeg is definitely going to be one of the first locations,” he said, adding that the company is considering launching two or three stores simultaneously.

Beyond Winnipeg, the initial real estate search appears to be weighted toward western Canada.

Gvakharia specifically mentioned Calgary and Edmonton among markets being evaluated.

“We want to start in the west and then gradually move east,” he said.

At the centre of the concept will be what Gvakharia described as everyday essentials.

“It will be hoodies, T-shirts, fleece and the kinds of pieces we think of as everyday essentials,” he said.

The company uses “World Outfitters” as a tagline for Mondetta, extending the international identity that has shaped the brand since its early years.

Mondetta Originals will be incorporated into the stores, as will MPG.

“Mondetta Originals will be sold through the stores, and there will also be an MPG shop featuring Mondetta Performance Gear,” Gvakharia said. “The goal is to bring the broader Mondetta family together.”

The planned format extends well beyond a heritage revival. Originals gives the company a recognizable connection to its past, while everyday essentials and performance apparel broaden the offer into a larger lifestyle proposition.

That distinction is important. Mondetta is not preparing a chain of nostalgia-driven flag-shirt stores. It is developing a multi-category retail concept intended to present the wider brand to consumers.

Mondetta Originals pop-up ON3 at Holt Renfrew, 50 Bloor St. W. in Toronto, July 10, 2026. Photo: Craig Patterson

A New Consumer Collection Under Normand Brouillette

The physical retail rollout will be accompanied by a new consumer collection being developed under creative director Normand Brouillette.

Gvakharia said Brouillette and his team had been working on the collection for approximately three months at the time of the interview, with the assortment being developed for Mondetta’s renewed direct-to-consumer push.

Normand Brouillette

The appointment brings an interesting strand of Canadian fashion history into the company’s next phase.

Brouillette previously held a senior creative role at Jacob, the once-prominent Canadian fashion chain. He was the retailer’s artistic director during a period when Jacob remained a significant national apparel name.

His earlier career also included work far removed from conventional chain retail. Media reports connected Brouillette with handmade gowns created for Kim Cattrall and Angelina Jolie.

That combination gives Mondetta a creative director with experience across very different parts of the fashion business.

Jacob offered exposure to the demands of designing for a scaled Canadian retail organization. His red-carpet work points to a more elevated and image-driven side of design.

The background is especially relevant because Mondetta is not simply reproducing archive product. It is developing a new collection while preparing permanent stores, expanding its digital consumer offer and determining how a 40-year-old Canadian brand should present itself to a new generation.

“We’re preparing to bring the collection directly to consumers next fall,” Gvakharia said.

DTC First as Mondetta Seeks Control of the Experience

The company plans to prioritize its own direct-to-consumer channels before pursuing a broader expansion through wholesale.

Historically, Mondetta product was available through multi-brand retailers. Gvakharia said the company now wants to establish the next version of the brand through channels where it can control how consumers encounter it.

“Right now, we want to focus on our own direct-to-consumer business so we can properly introduce the brand and the experience we want customers to have,” he said.

That control extends from product presentation to store design and staff interaction.

“I think it is critical at the beginning of a DTC rollout that consumers truly experience the brand,” Gvakharia said. “We want to control that experience from the product itself through to what happens in the store.”

The objective is to establish recognition and a loyal customer base before widening distribution.

“We want to build that fan base first, and then we can explore broader wholesale opportunities,” he said.

The approach marks a notable shift from the wholesale channels through which many consumers encountered Mondetta in earlier decades. This time, the company wants to define the product, environment and customer relationship itself before broadening distribution.

Gvakharia did not rule out future wholesale opportunities. He also pointed to possible concession formats, shop-in-shops and collaborations as the wider business develops, including opportunities outside North America.

Digital Rebrand Sets Up the Next Phase

The physical strategy is being accompanied by a broader digital refresh. Gvakharia said Mondetta has completed a significant rebranding of its online presence and is preparing to introduce a dedicated direct-to-consumer collection through the website.

“We’ve completely refreshed the online side of the brand, giving it a new look and feel,” he said.

The current digital presentation gives Mondetta Originals and the company’s heritage a visible role while positioning Mondetta as a broader apparel business.

Gvakharia said the new consumer collection could become available online several months before the first permanent stores open. The sequence points to a phased reintroduction: a refreshed digital identity, selective physical activations such as Holt Renfrew, a new consumer collection online and then permanent stores beginning in fall 2027.

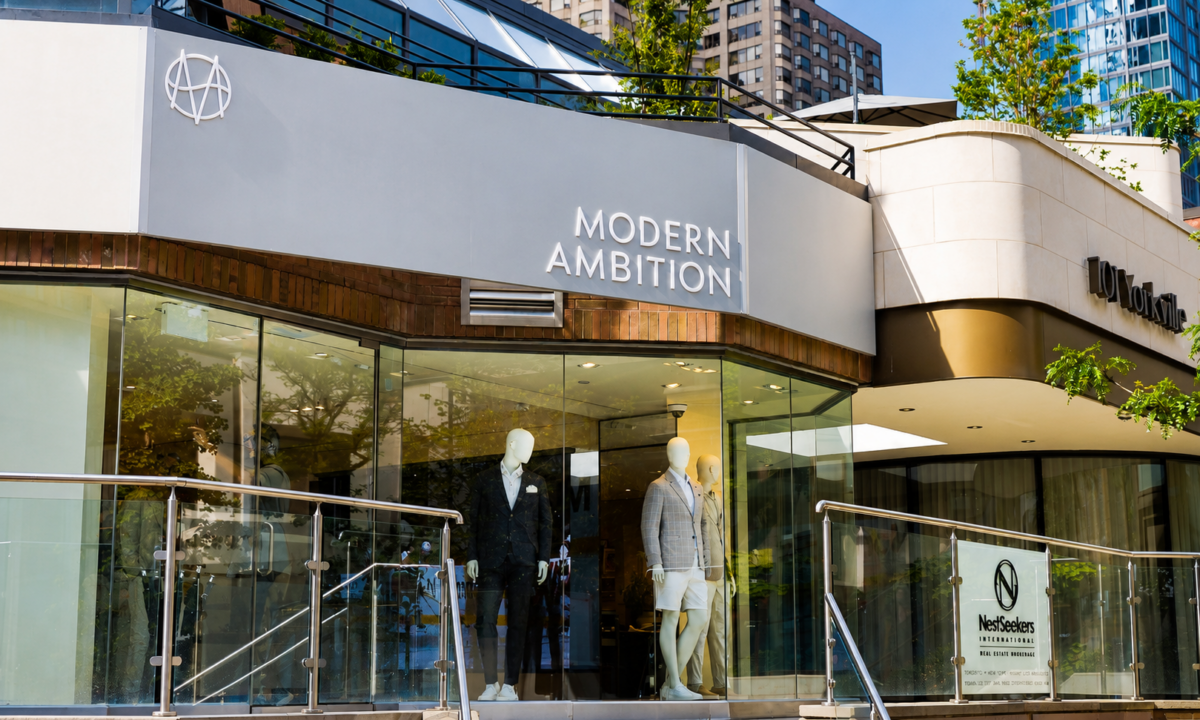
Mondetta-owned Modern Ambition opened a Toronto store last week at 101 Yorkville Avenue. Photo: Modern Ambition

Up to 20 Stores Envisioned Across Canada

The longer-term plan is substantial. Gvakharia told Retail Insider that the company sees potential for roughly 20 Mondetta stores across Canada.

Such a network would represent a significant return to direct physical retail for the Winnipeg-based company and would operate alongside the separate growth of Modern Ambition, which is pursuing its own national store rollout.

For Mondetta, the immediate focus is on refining the concept, developing the collection and securing the first locations. Stores in the 3,000-to-5,000-square-foot range would allow the company to present heritage, everyday essentials and performance product within a single branded environment.

The company remains headquartered in Winnipeg and also maintains an office in Shanghai, an office in Jordan and a showroom in New York City, according to Gvakharia. As its consumer business expands, he said additional satellite offices could eventually be considered, potentially including Toronto.

For now, the most visible expression of the strategy is temporary. Inside Holt Renfrew’s ON3 environment, Mondetta Originals is reconnecting physically with Canadian consumers while a much larger retail plan develops behind the scenes.

Forty years after the company was founded, Mondetta is preparing permanent stores, a new consumer collection under Normand Brouillette and a direct-to-consumer network that could ultimately reach roughly 20 locations.

The flag-bearing apparel provides the clearest link to the brand many Canadians remember. The larger task now is defining the Mondetta they will encounter next.

More from Retail Insider:
New Retail-Theft Sentencing Rules Take Effect in Canada July 15

Retail theft and retail crime in a store. Photo: Halton Police Service

New federal bail and sentencing reforms taking effect July 15 will introduce a specific sentencing measure aimed at commercially motivated retail theft, as governments and industry groups continue to raise concerns about repeat offending, organized resale networks and violence affecting retail workers.

The Bail and Sentencing Reform Act, also known as Bill C-14, received royal assent on June 15 and includes more than 80 changes to the Criminal Code and related legislation.

Among the retail-specific changes is a new aggravating factor that courts must consider when sentencing an offender who committed an eligible property offence with the intention of selling, bartering or fraudulently returning the stolen merchandise.

The federal government has described the measure as a response to organized retail theft. The wording enacted by Parliament, however, is not limited to activity involving a formally organized criminal group.

The Criminal Code provision focuses on the commercial intent behind the offence, whether the property was stolen for resale, barter or fraudulent return, rather than the structure or sophistication of the people involved.

Prosecutors will not necessarily have to prove that an offender belonged to a criminal organization. The aggravating factor could apply to coordinated theft rings and professional shoplifters supplying resale networks, along with individuals stealing merchandise for commercial gain without a formal connection to organized crime.

The change gives legal recognition to a category of theft that retailers say increasingly extends beyond isolated shoplifting incidents and into repeat offending, professional resale channels and fraudulent-return activity.

New Rule Applies at Sentencing

The retail provision applies after an offender has been convicted. It does not create a new offence called organized retail theft, establish a mandatory minimum sentence or automatically require incarceration. Judges will continue to consider the full circumstances of the offence and offender and impose a proportionate sentence.

The new factor signals that theft carried out for resale, barter or fraudulent return should be treated as more serious than an otherwise comparable offence committed without a commercial motive.

It can apply to several offences involving stolen property, including theft, robbery, break-and-enter, possession of stolen goods and trafficking in property obtained through crime.

The inclusion of fraudulent merchandise returns is particularly relevant to retailers. Return schemes can involve stolen goods being brought back to stores for cash, gift cards or other forms of credit, sometimes using counterfeit or improperly obtained receipts.

The effect of the new rule will depend on the evidence presented in each case. Prosecutors may seek to establish commercial intent through surveillance, communications, online marketplace activity, repeated thefts of similar merchandise, possession of large quantities of tagged goods or links between incidents at multiple stores.

Retail loss-prevention records and cooperation between retailers, police and Crown prosecutors could therefore become increasingly important when commercially motivated theft cases reach sentencing.

Retail Measure Is Distinct from Wider Bail Changes

Although the legislation is commonly described as a bail and sentencing package, its most direct retail-specific amendment concerns sentencing.

Bill C-14 does not establish a blanket reverse onus for people accused of repeat shoplifting. Under a reverse-onus bail provision, an accused person must demonstrate why detention is not justified, departing from the usual process in which the Crown must justify detention.

The legislation creates or expands reverse-onus provisions in several areas, including violent offences, organized-crime-related auto theft, extortion, home invasion, human trafficking and certain repeat violent offending.

Those broader changes could still intersect with retail crime where an alleged incident involves violence, weapons, organized criminal activity, breaches of release conditions or a qualifying record of violent offending.

The law also directs courts to consider the number and seriousness of an accused person’s outstanding charges when assessing whether detention is necessary to maintain confidence in the administration of justice.

That may be relevant in cases involving people accused of committing repeated offences while already facing unresolved charges. It does not mean every person charged with multiple shoplifting incidents will automatically be detained.

Retail Industry Welcomes the Change

Retail Council of Canada has supported the reforms, arguing that retail crime has become a growing public-safety concern and a significant financial and operational burden.

RCC president and CEO Kim Furlong said the legislation gives the justice system stronger tools to address repeat offenders, disrupt organized crime and better protect retail workers.

The organization has repeatedly drawn attention to violence and threatening behaviour during theft incidents, along with the effects of crime on employees, customers and store operations.

Retailers have responded by increasing security spending, changing store layouts, restricting access to certain merchandise and instructing employees not to intervene directly when theft occurs.

Those measures can affect the shopping experience and create additional costs for businesses and consumers. In some stores, frequently targeted products are placed behind locked fixtures or removed from open shelves, requiring customers to ask employees for assistance.

RCC has estimated total retail shrink in Canada at approximately $9 billion annually. Shrink includes inventory losses linked to several causes, including external theft, employee misconduct, administrative errors, damage and other discrepancies.

The figure should not be interpreted as a direct measurement of merchandise stolen by organized retail criminals. It nevertheless reflects the broader financial pressure facing retailers as theft, security and inventory-control concerns grow.

An RCC study involving retailers representing more than 20,000 locations found that 76.2 per cent of respondents had experienced increased violence during theft incidents. Repeat offenders accounted for 17.7 per cent of reported arrests among participating retailers.

Latest National Data Show Continued Growth in Shoplifting

The latest complete national figures available from Statistics Canada show that police-reported shoplifting continued to rise in 2024.

Police services recorded 182,361 incidents of shoplifting valued at $5,000 or less, equivalent to 442 incidents for every 100,000 people. The rate increased by 14 per cent from 2023, marking a fourth consecutive annual increase, and was 66 per cent higher than it had been a decade earlier.

Statistics Canada has not yet released its full national police-reported crime results for 2025, meaning the 2024 results remain the most recent directly comparable national measure available as the reforms take effect.

The figures show a sustained increase in reported shoplifting, although they do not measure the full scale of retail theft or determine how much activity is tied to organized resale networks.

They also do not reveal how many unique offenders were responsible, the total value of the merchandise involved or how often an incident included threats or violence. Statistics Canada has noted that the increased availability of online police reporting may have contributed to some of the growth in recorded incidents.

More recent industry research points to growing concern about the severity of retail crime. Retail Council of Canada’s national study found that 76.2 per cent of participating retailers had experienced increased violence during theft incidents, while repeat offenders accounted for 17.7 per cent of reported arrests. The participating companies represented more than 20,000 retail locations across Canada.

Retailers have long argued that police statistics understate the problem because many incidents are never formally reported. Businesses may decide against reporting lower-value thefts because of the time involved, uncertainty about whether charges will proceed or difficulty identifying the offender.

That leaves a gap between incidents recorded internally by retailers and those appearing in national police data.

Implementation Will Determine the Impact

The new aggravating factor gives Crown prosecutors and judges an additional tool, but its influence will depend on how consistently it is used and how effectively cases are developed.

Retail Council of Canada has acknowledged that legislative reform alone will not resolve the problem. The organization has also called for stronger information sharing, adequate police and prosecution resources and better coordination across provincial and municipal boundaries.

Commercially motivated retail theft can involve offenders operating across several stores, shopping centres or jurisdictions. A series of incidents may initially appear unrelated unless retailers and police can connect the same individuals, vehicles, resale accounts or methods of operation.

The provincial administration of justice could also lead to differences in how the reforms are applied across Canada.

The federal government is responsible for the Criminal Code, while provinces and territories oversee much of the court system, Crown prosecution services and correctional infrastructure. Caseloads, resources and enforcement priorities vary between jurisdictions.

Crown attorneys have warned that the wider reforms could result in longer and more contested bail and sentencing hearings, placing additional pressure on courts, prosecutors and correctional systems.

Retail cases involving the new aggravating factor may require additional evidence and argument over whether an offender intended to resell, barter or fraudulently return stolen merchandise.

It may take time for courts to establish how much weight the factor should receive and what evidence is sufficient to prove the required intent.

Retail Impact Will Emerge Gradually

Retailers are unlikely to see a dramatic operational change when the legislation takes effect July 15.

The reform will become relevant as cases move through investigation, prosecution, conviction and sentencing. It could take months before the new factor begins appearing regularly in sentencing decisions and longer before appellate courts provide guidance on its application.

In the near term, the legislation is significant because it formally identifies theft for commercial gain as conduct warranting greater attention during sentencing.

Its longer-term importance will depend on whether police can build connected cases, prosecutors can establish commercial intent and courts apply the factor in a way that meaningfully distinguishes resale-driven theft from lower-level offending.

The reforms may also encourage closer cooperation between retailers and law enforcement, particularly where businesses can provide evidence linking incidents across multiple locations.

For retailers, the legislation represents federal recognition that theft committed for resale or fraudulent return has consequences extending beyond the value of the merchandise taken. It can affect employee safety, store operations, customer access to products and the cost of doing business.

The legal framework will be in place on July 15. Whether it produces measurable reductions in repeat and commercially motivated retail crime will depend on what happens after that date.

More from Retail Insider:
Canadian Shoppers Choose by Mission, Not Channel, New Research Finds

A retail worker and an employee in a luxury store. Retail staffing in Canada has its ups and downs says Suzanne Sears. Photo: RI/Google

Canadian retailers have spent years organizing strategy around channels. Physical stores have been modernized, e-commerce platforms expanded, apps launched, loyalty programs refined and fulfillment networks connected under the broad promise of omnichannel retail.

New Canadian research suggests shoppers may organize their behaviour differently. The central finding of The Canadian Shopper Sentiment Study: How Trip Purposes and Journeys Shape Shopper Decisions, conducted by Leger for Retail Council of Canada, is that consumers often begin with a purpose, with the choice of channel emerging from what they are trying to accomplish.

A shopper replacing an urgently needed item is likely to behave differently from someone browsing for inspiration. A routine grocery run creates different expectations from a considered electronics purchase, even when the same person is making both trips.

The channel follows the mission. That idea gives structure to a 60-page study based on an online survey of 2,014 Canadian shoppers conducted in February 2026, followed by six English- and French-language focus groups in March. The sample was nationally representative, and the stated margin of error was plus or minus 2.2 percentage points, 19 times out of 20.

The findings show Canadians moving across physical and digital touchpoints with considerable fluidity. In-store browsing was used by 66% of respondents during the research process, compared with 48% for retailer websites and 45% for search engines. Loyalty programs were used by 43%, while retailer apps, flyers, online marketplaces, word of mouth and in-store staff also played meaningful roles. AI assistants were already used by 11%.

Yet the same research found that physical stores remained the leading purchase channel. Fifty-eight per cent completed purchases in-store, compared with 39% online, while 62% took products home the same day. The resulting picture is more complicated than the familiar online-versus-offline debate: shoppers appear to be assembling their own journeys from the tools available to them, with priorities changing according to the job at hand.

Value Sets the Threshold

The study arrives while affordability remains a defining issue for Canadian households. Statistics Canada reported that prices for food purchased from stores rose 4.3% year over year in May 2026, the 16th consecutive month in which grocery inflation outpaced headline inflation.

The Bank of Canada’s second-quarter survey of consumer expectations also found that high prices and economic uncertainty continued to weigh on household spending plans. Its consumer indicator remained low as households described the economic environment as challenging, with affordability concerns continuing to influence spending behaviour.

That backdrop makes the RCC/Leger findings particularly timely, although the report paints a more nuanced picture than simple bargain hunting. It defines value for money as the perceived balance of price, quality and benefit, and that measure sits at a broadly similar baseline across the study’s three main shopping-mission groups. The larger differences appear after the shopper decides the value is acceptable.

For task and time-driven trips, stock availability becomes the leading differentiator, followed by factors including selection and location. Problem-solving and replacement trips also place heavy weight on availability, while staff knowledge and delivery costs become more important. Inspiration and impulse missions show another pattern, with delivery fees, loyalty benefits and easy returns taking on greater relevance.

Price can therefore establish the threshold for consideration without determining the entire outcome. An empty shelf may be decisive for someone trying to complete an urgent task, while broad assortment can create value for a customer open to discovery. Staff expertise may have little influence on a routine replenishment purchase and become essential when someone is comparing unfamiliar products. Value sensitivity remains central, but the mission determines which other expectations rise to the surface.

One Shopper, Different Missions

The report organizes shopping behaviour into three broad situations: Inspiration & Impulse, Task & Time-Driven, and Problem-Solving & Replacement. These categories are best understood as missions, not permanent consumer personas, because the same individual can move among them repeatedly.

Inspiration and impulse trips include deal-driven shopping, discovering new products, acting on recommendations and treating oneself or someone else. Task and time-driven trips include routine purchases, errands, specific events and urgent needs. Problem-solving and replacement trips centre on confidence, including comparing alternatives, replacing or upgrading products, solving a specific problem or researching a considered purchase.

Routine shopping remains the most common, with 63% of respondents reporting a routine or planned trip purpose. But the study also found substantial activity outside that pattern: 37% combined shopping with errands, 35% had shopped to treat themselves or someone else, 28% engaged in casual browsing and 24% had made an urgent or last-minute purchase.

Those missions carry different emotional states. Treat-yourself trips generated the highest positive mood at 76%, followed by deal-driven shopping at 71% and event shopping at 70%. Urgent trips were much more difficult, with only 45% registering a positive mood and 38% reporting a negative one, the highest negative reading among the trip types highlighted in the report.

The findings complicate the retail industry’s tendency to discuss “experience” as though every shopper is seeking entertainment, theatre or discovery. For a customer making an urgent purchase, accurate inventory, clear navigation, accessible staff and a fast checkout may define a high-quality experience. A discretionary shopper in a positive mood may respond far more strongly to visual merchandising, broad assortment and the possibility of finding something unexpected.

The study’s mindset data reinforce that distinction. Overall, 40% of shoppers were classified as efficiency-driven, compared with 29% who were value-seeking. Among task and time-driven shoppers, 57% were efficiency-oriented, while problem-solving shoppers also leaned heavily toward efficiency.

For retailers, the lesson is significant: speed and clarity should not be treated as the absence of experience. In many situations, successful completion is the experience the customer came for.

The Store Remains Part of the Research Engine

One of the strongest findings in the study concerns the role of physical retail before the transaction takes place.

In-store browsing was used by 66% of respondents during the research journey, making it the most widely used source in the study. It was also the most common first touchpoint, with 22% beginning there. Search engines and flyers were each used first by 12%, while retailer websites were the starting point for 10%.

That matters because stores are still often evaluated primarily by transactions completed within their walls. The research points to a broader role. A shopper may enter a store to inspect an item, compare sizes, assess quality, understand features or encounter a product for the first time, then use a phone to search prices, read reviews, check another retailer or complete the purchase through a different channel.

A focus-group participant in the study described examining products in-store and then checking online for a lower price. The behaviour illustrates how physical retail can function as part of the information architecture of shopping even when another channel ultimately receives the transaction.

It also raises an attribution question. If retailers assign most value to the final click or completed transaction, the contribution of stores to product discovery and validation may be understated. That is an inference from the cross-channel findings, but it follows from evidence showing consumers moving among physical and digital sources during the same journey.

The continued importance of stores is especially visible among task-driven shoppers. Seventy per cent completed purchases in-store, compared with 58% across the full sample, and 71% took the product home the same day. For someone trying to finish a task, immediacy remains a significant competitive advantage.

Different Missions Produce Different Journeys

Overall channel averages obscure meaningful differences in how shoppers research different kinds of purchases.

Inspiration and impulse shoppers were comparatively exploratory. Sixty-three per cent used in-store browsing, 56% retailer websites and 52% search engines, while loyalty programs and retailer apps also played a relatively strong role. Task and time-driven shoppers leaned more heavily on familiar retail cues: 70% used in-store browsing, 46% loyalty programs and 41% flyers, while use of retailer websites and search engines was lower. Problem-solving and replacement shoppers were more validation-oriented, with 64% using in-store browsing, 53% retailer websites and 52% search engines.

Those differences point to distinct jobs for retail touchpoints. A task-oriented customer may respond strongly to accurate stock visibility, a familiar loyalty offer and a convenient location. Someone solving a problem may need specifications, comparisons, reviews, knowledgeable employees and confidence that a return will be manageable. An inspiration shopper may be more receptive to assortment, recommendations and discovery.

Category behaviour reinforces the same point. Groceries and essentials were heavily purchase-driven, with 82% of respondents reporting a purchase in the previous 30 days. Electronics and technology showed a different pattern: 27% had researched the category, compared with 17% who purchased. Home, décor and improvement also attracted substantial research relative to recent buying.

The strategic requirements differ accordingly. In high-frequency essential categories, availability and replenishment can dominate because the need already exists. In considered categories, search visibility, accurate product information, comparison tools, reviews and staff expertise can shape the decision long before money changes hands.

A generic omnichannel strategy can miss that distinction. Having a store, website and app is one thing; understanding the role each needs to play for a particular mission is another.

AI Is Joining the Journey, Not Replacing It

Artificial intelligence is already visible in Canadian shopping behaviour, although the report suggests its role remains secondary to more established research sources.

Eleven per cent of respondents said they had used AI assistants during shopping research, but only 1% said AI was the first source used. That gap may be more revealing than the headline adoption figure. It suggests AI is entering the journey mainly as a tool for narrowing choices, comparing options and speeding up research, while stores, search engines and retailer-owned channels remain more common entry points.

Among AI users, 46% said it helped them find relevant products faster, 43% said it made comparing products or prices easier and 40% said it saved time. Thirty per cent reported greater purchase confidence.

The weaknesses were also visible. Twelve per cent perceived brand bias, 11% said they had been directed toward products that did not exist and 10% reported incorrect results.

The immediate retail implication is therefore less about autonomous agents suddenly taking control of commerce and more about how products and brands appear inside a new research layer. If shoppers increasingly ask AI systems to identify options, compare prices or narrow a shortlist, product data, discoverability, accuracy and brand representation may become competitive concerns even when the sale is completed through a conventional retailer channel.

Value Pressure Is Changing Brand Choice

The report’s private-label findings provide another view of how Canadian shoppers are recalculating value. Among consumers purchasing private-label products, 53% cited better price or value for money, 38% pointed to good quality for the price and 27% said quality was comparable with national brands.

The hierarchy suggests many consumers are actively assessing whether the quality difference between a retailer-owned product and a national brand justifies the price gap. The behaviour fits the study’s wider definition of value as a combination of price, quality and benefit.

Brand loyalty may therefore be becoming more conditional. A national brand that once benefited from habit or familiarity can face greater scrutiny when consumers are comparing alternatives and asking whether a premium remains justified. For retailers, private label can function as an affordability tool, a margin strategy and a test of trust, with the strongest opportunity emerging when shoppers view the quality-price trade-off as rational.

The Empty Shelf and the Silent Customer

The study’s most commercially important findings may be those related to operational failure. Seventy-two per cent of respondents experienced at least one shopping issue during the previous three months. Thirty per cent encountered an out-of-stock product or limited availability, making it the most common problem identified. Delivery delays affected 18%, while 15% reported long lines or difficulty getting help and 14% encountered store-navigation problems.

Those failures matter differently according to mission. For task and time-driven trips, stock availability is the leading differentiator once the value threshold is crossed. The same is true for problem-solving and replacement trips. An unavailable product can therefore do more than frustrate a customer; it can erase the purpose of the trip.

The report found that 37% switch retailers when an item is out of stock, while poor customer service was also a significant reason for switching. More broadly, the research describes shoppers changing retailers, changing channels or abandoning purchases when basic execution fails.

For retailers, this creates a measurement problem. Complaint systems capture customers who remain engaged long enough to report what went wrong. They may miss the shopper who sees an empty shelf and checks a competitor’s app, the customer who cannot find help and walks out, or the online visitor who opens another tab and completes the transaction elsewhere.

A low complaint rate can therefore create false reassurance. The absence of a complaint is not evidence of loyalty.

The same tools that help shoppers compare options also reduce the friction involved in leaving. Inventory accuracy, queue management, intuitive navigation, reliable delivery and accessible service should therefore be understood as competitive capabilities, not simply operating metrics.

What Retailers May Need to Rethink

Retail Council of Canada has framed the research partly through the lens of affordability, competition and consumer choice. That interpretation arrives as the federal Competition Bureau places renewed emphasis on affordability and choice in its 2026–27 annual plan, including investigations in sectors affecting essential household costs such as food and housing.

The study clearly demonstrates consumer mobility. Canadians compare options, use multiple research sources, switch channels and leave retailers when expectations are not met. Those behaviours do not, on their own, establish that every retail market is highly competitive; questions involving concentration, barriers to entry and pricing power require broader evidence.

The study’s strongest contribution is behavioural. It presents a consumer who is neither simply online nor offline, neither permanently loyal nor always deal-driven. The same shopper can be rushed on one trip, exploratory on another and deeply analytical on the next.

For years, retailers have invested heavily in digital transformation, modernized stores, e-commerce, loyalty systems, apps and fulfillment networks. The research suggests the next step may involve reversing the usual order of planning: begin with the mission, understand what could derail it, and then determine which store, website, app or fulfillment option is best equipped to help the customer finish what they came to do.

More from Retail Insider: