Small business owner reviewing numbers in a retail store. Image: Centelli
Canadian small and mid-sized businesses are feeling more pressure on cash flow, even when they remain profitable, according to Daryl Ching, founder of Toronto-based Vistance Accounting.
Ching’s firm works with about 50 small and mid-sized businesses across manufacturing, consumer packaged goods, ecommerce, wholesale and retail. He said more of those clients are looking for help managing working capital as money gets tied up in receivables and inventory.
“A lot of our work used to be centred around improving gross profit margins,” Ching said. “We’d look at pricing and variable costs and figure out how to improve profitability. Now, a lot of that work has shifted to working capital.”
Some of his clients are profitable on paper but still having trouble with cash flow. For Ching, that has meant spending more time looking at the balance sheet and helping clients collect money faster, manage inventory and deal with financing.
“I have a lot of clients that are profitable on paper, but they’re still struggling with cash flow,” he said.
Businesses Waiting Longer for Their Money
Late payments are part of the problem. Xero’s Canadian Small Business Insights reported in April that Canadian small businesses were being paid an average of 11.6 days late, up from 10.5 days previously.
Ching said some of his clients are working with payment terms of 60 or 90 days, and late payments can make those arrangements even more difficult. His firm has been helping clients improve collections while also looking at when they pay their own suppliers.
“A lot of the work has been around receivables and figuring out how to get collections in faster,” he said.
Inventory is another area getting more attention. Businesses that once kept additional stock on hand as a cushion are having to think more carefully about how much money they can afford to leave tied up in product.
“You might have had the luxury of ordering extra inventory to make sure you had enough,” Ching said. “You don’t have that luxury anymore. You need better demand forecasting.”
The issue is particularly relevant for retailers, wholesalers and consumer-product companies. Inventory needs to be purchased before it can be sold, and the business may then have to wait again before receiving payment from a customer or wholesale account.
“A lot of our work recently has been more on the balance sheet than on profit and loss,” Ching said.
Daryl Ching, founder of Toronto-based Vistance Accounting
Tariffs Put More Cash Into Inventory
Tariff uncertainty has complicated those decisions. Ching said some clients initially responded to the threat of tariffs by placing large orders ahead of potential changes, tying up money that would otherwise have been available to run the business.
“I had a whole bunch of clients do large bulk orders just in case,” he said. “That put them into cash difficulty.”
He is seeing less of that now. Businesses have had more time to adjust to changing trade policies and are less likely to react immediately when another product or industry appears likely to be affected.
“My clients aren’t rushing anymore,” Ching said. “They’re waiting to see what happens because we’ve learned that things can change again the next week.”
Canadian retaliatory tariffs have also affected some of his clients, particularly businesses buying products or raw materials from the United States. In those cases, Ching said companies have either absorbed the additional cost or looked for another supplier.
Research from the Canadian Federation of Independent Business has also found financial pressure from tariffs and trade uncertainty, including higher costs, weaker profits, supply-chain disruptions and postponed investment among affected businesses.
Lines of Credit Become a Bigger Concern
Lines of credit can provide businesses with short-term liquidity when cash is tight. Ching is concerned when companies remain heavily dependent on them for extended periods.
“With the working-capital squeeze, a lot of times it starts with a line of credit for short-term liquidity,” he said. “But when that persists over a long period, the short-term loan starts to look like long-term debt.”
He points to a business that has kept its line of credit fully drawn for several years as an example.
“If you have a line of credit that’s fully leveraged for three years, to me that’s long-term debt,” Ching said. “All of a sudden you’re carrying long-term debt, and that’s a structural weakness in the balance sheet. It also makes it harder to borrow from a bank.”
Ching said he is spending more time helping clients prepare for financing as a result. Business owners want to know what they can do to improve their financial position before going to a lender.
Conditions across the SME sector are mixed. Recent research from the Business Development Bank of Canada has shown some improvement in expectations, with more SMEs expecting cash flow to improve over the coming year and fewer expecting it to deteriorate.
Ching’s client base represents only a portion of Canada’s SME sector, but it gives him a close look at how cash-flow problems can develop inside otherwise viable businesses.
CEBA Repayment Deadline Approaches
Businesses with outstanding Canada Emergency Business Account loans also have a deadline approaching. Remaining CEBA principal is due December 31, 2026 for borrowers that continue to carry balances.
The loans were introduced during the pandemic to provide emergency financing to businesses. Loans that remained outstanding after the January 2024 forgiveness deadline became interest-bearing term loans, with the remaining principal due at the end of this year.
Ching said the deadline could add another demand on cash for businesses already managing other debt and operating expenses.
More Attention on the Balance Sheet
Ching continues to work with clients on margins, pricing and profitability, but cash management has become a bigger part of those conversations.
For some businesses, stronger sales can require more inventory and more money up front. If customers are also taking longer to pay, the gap between making a sale and collecting the money can grow. Businesses may turn to their lines of credit to cover that period, adding another cost to the equation.
That is why Ching is spending more time looking beyond the income statement.
“You can be profitable on paper and still struggle with cash flow,” he said. “You have to manage your receivables, your inventory and your payables. That’s where a lot of the pressure is right now.”
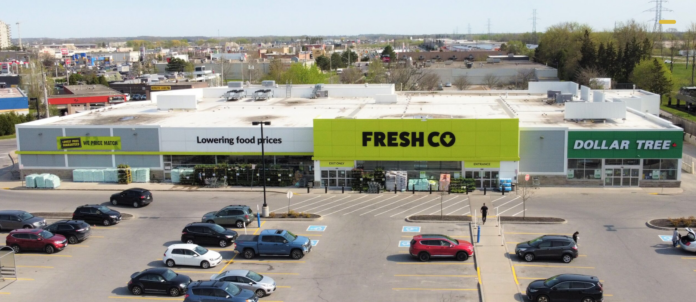
London Pine Valley FreshCo, London, ON. Image: Crombie REIT
Empire Company Limited is accelerating its store expansion plans as Canada’s major grocers continue to add capacity despite cautious consumer spending and pressure on industry volumes.
The parent company of Sobeys, Safeway, FreshCo, IGA, Foodland, Farm Boy and Longo’s now expects to open more than 25 stores in fiscal 2027, up from its previous target of more than 20. President and CEO Pierre St-Laurent said recently opened stores are meeting or exceeding expectations, supporting the decision to increase the target.
Empire expects the expansion to increase its retail square footage by approximately two per cent, including the addition of Mayrand stores in Quebec. The company plans approximately $850 million in capital spending this fiscal year, with about half allocated to renovations and new stores.
The increased target comes as competitors are also adding locations, particularly in discount grocery. With several major operators expanding at the same time, the amount of new grocery space entering the Canadian market is becoming an important consideration for existing-store productivity and future market share.
Empire Adds Stores Across Multiple Banners
Empire’s expansion extends across several banners and regions. The company opened its first FreshCo stores in Atlantic Canada in August and is continuing to grow the discount banner across Western Canada and Ontario. Recent openings include two FreshCo stores in Calgary and another in Paris, Ontario.
The company has also opened an IGA Extra in Montreal, an IGA in Edmonton and a Safeway at Oakridge Park in Vancouver. The Oakridge location gives Safeway a presence within one of Canada’s largest mixed-use redevelopment projects and represents a different type of opportunity from Empire’s discount expansion.
Empire has also completed its acquisition of Mayrand Food Group, adding four stores in the Greater Montreal area. A new Mayrand location is under development in Trois-Rivières, and management has indicated that it sees further expansion potential for the business.
FreshCo provides Empire with its primary discount growth vehicle, while Safeway and IGA provide conventional formats in markets where those banners are established. Mayrand adds another platform for growth in Quebec.
St-Laurent said the higher fiscal 2027 target includes stronger activity within Empire’s original real estate pipeline as well as the four acquired Mayrand stores. Management hopes to continue increasing the pace of development beyond the current year.
New Stores Support Expansion Plans
Early performance at recently opened stores is giving Empire confidence to continue investing. St-Laurent told analysts that new locations are meeting or exceeding the company’s expectations.
Those openings should have a greater effect on overall sales growth as the stores mature. Food sales increased 1.7 per cent in the first quarter, compared with same-store food sales growth of 1.2 per cent. CFO Constantine Pefanis said the difference between total and same-store sales growth should widen as new stores contribute more revenue.
Empire is investing in its existing network at the same time. Approximately half of the company’s planned $850 million in fiscal 2027 capital expenditures will go toward renovations and new-store development.
More Grocery Space Raises Questions About Existing Stores
Empire is not expanding in isolation. Loblaw Companies Limited has been adding grocery and pharmacy locations at an aggressive pace, with much of its grocery growth concentrated in discount banners including No Frills and Maxi. Metro is also adding discount capacity through Food Basics in Ontario and Super C in Quebec.
That expansion prompted BMO Capital Markets analyst Tamy Chen to ask Empire management how existing-store tonnage could be affected as multiple grocers increase square footage over the next one to two years.
The question highlights a potential challenge for the sector. New stores can capture customers in underserved or growing markets, but they do not create grocery demand on their own. If square footage grows faster than the market, some sales generated by new locations can come at the expense of existing stores.
St-Laurent said Empire views the current weakness in the consumer environment as cyclical and does not believe it should dictate real estate decisions intended to generate returns over many years.
“When we are investing in real estate, we are investing for the long term,” he told analysts.
Empire Is Looking Market by Market
St-Laurent said Empire assesses opportunities market by market, looking for areas where individual banners have room to grow. Management is not basing its investment decisions on a national assumption that Canada needs a certain amount of additional grocery square footage.
Grocery competition varies considerably across the country. Discount penetration, population growth, existing competitors and banner recognition differ between markets, creating opportunities for additional stores even when industry-wide sales growth is modest.
Empire says its recent openings have been concentrated in locations where it sees white space and believes its brands can compete effectively. The performance of those stores will be an important measure of whether that strategy can offset the broader risk of industry capacity growing faster than demand.
FreshCo Remains Central to Expansion
FreshCo remains one of Empire’s most important vehicles for new-store growth as Canadian consumers continue to prioritize value.
The company opened its first two FreshCo stores in Atlantic Canada on August 20 and expects additional openings across Western Canada, Ontario and Atlantic Canada during fiscal 2027. The move gives Empire a dedicated discount banner in a region where Sobeys already has a substantial conventional grocery presence.
Management said early customer response to the Atlantic locations has been encouraging. FreshCo is also expanding in established markets, including Calgary and Ontario, as Empire increases its exposure to the discount segment.
St-Laurent said Empire has been gaining market share in its full-service business while maintaining its position in discount despite rapid expansion by competitors. Management expects its growing discount footprint to contribute more meaningfully to market-share gains over time.
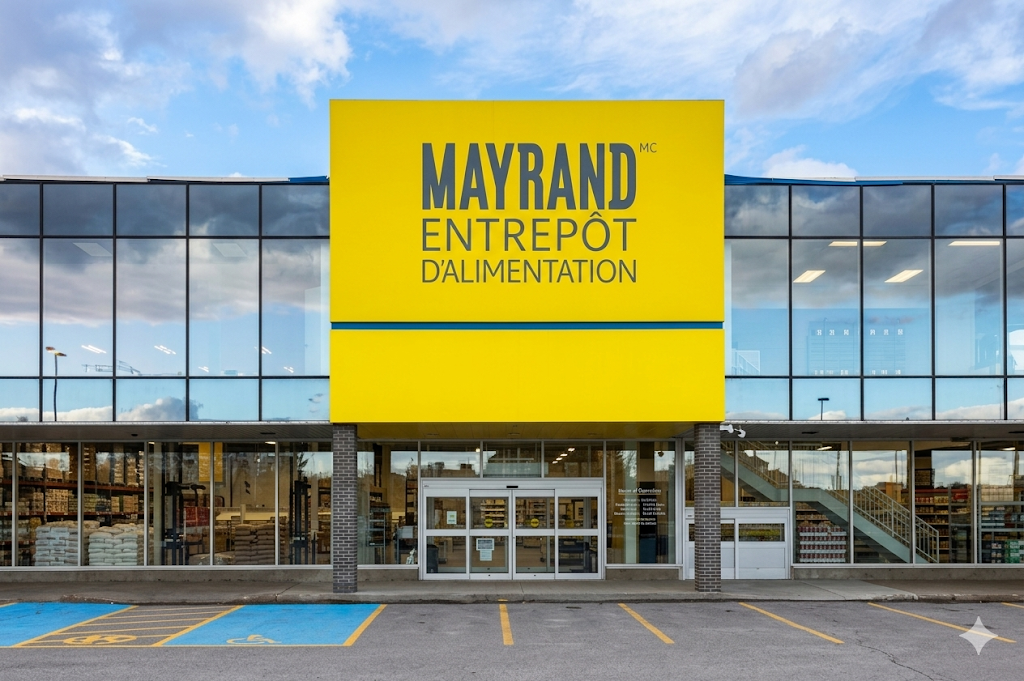
Mayrand store in Laval. Photo: RI/Google
Mayrand Adds Another Quebec Growth Platform
Empire’s acquisition of Mayrand adds a different format to its expansion strategy. The Quebec retailer operates large-format stores serving consumers and foodservice customers, giving Empire a business outside its conventional supermarket and discount models.
The acquisition closed in June, adding four Mayrand stores to Empire’s network. The company has already broken ground on a new location in Trois-Rivières and says there is potential for further expansion.
Mayrand accounts for part of the increase in Empire’s fiscal 2027 store target, but management said the revised outlook also reflects additional activity within its existing real estate pipeline. The higher target therefore goes beyond adding the four acquired stores to Empire’s network.
Expansion Intensifies Competition for Customers and Sites
For Empire, additional stores have to capture enough business to justify the capital being deployed while limiting cannibalization within its own network. Competitors are pursuing many of the same population-growth markets and value-oriented customers, increasing the importance of site selection and banner choice.
There is also a real estate dimension. Grocery stores remain important anchors for shopping centres and mixed-use developments because of their recurring customer traffic, while large sites suitable for new supermarkets can be difficult to secure in established urban markets.
Competition for those locations could increase as major grocers continue building their development pipelines. Empire’s portfolio gives it flexibility to pursue different types of opportunities, from FreshCo discount stores to conventional supermarkets and Mayrand locations.
Empire Takes a Long-Term View
Empire’s increased fiscal 2027 target is part of a broader real estate program that includes new stores, conversions and renovations across its network. The company is committing significant capital to physical retail while consumers remain cautious and competitors continue adding capacity.
The risk is that Canadian grocery square footage could grow faster than demand, putting pressure on productivity at existing stores. Empire is betting that market-level opportunities can still support new locations and that current economic weakness should not determine investments intended to operate for many years.
For now, the early performance of Empire’s newest stores is supporting that argument. Management is increasing the pace of expansion, putting greater weight on its ability to choose the right markets and banners as competition for Canadian grocery spending intensifies.
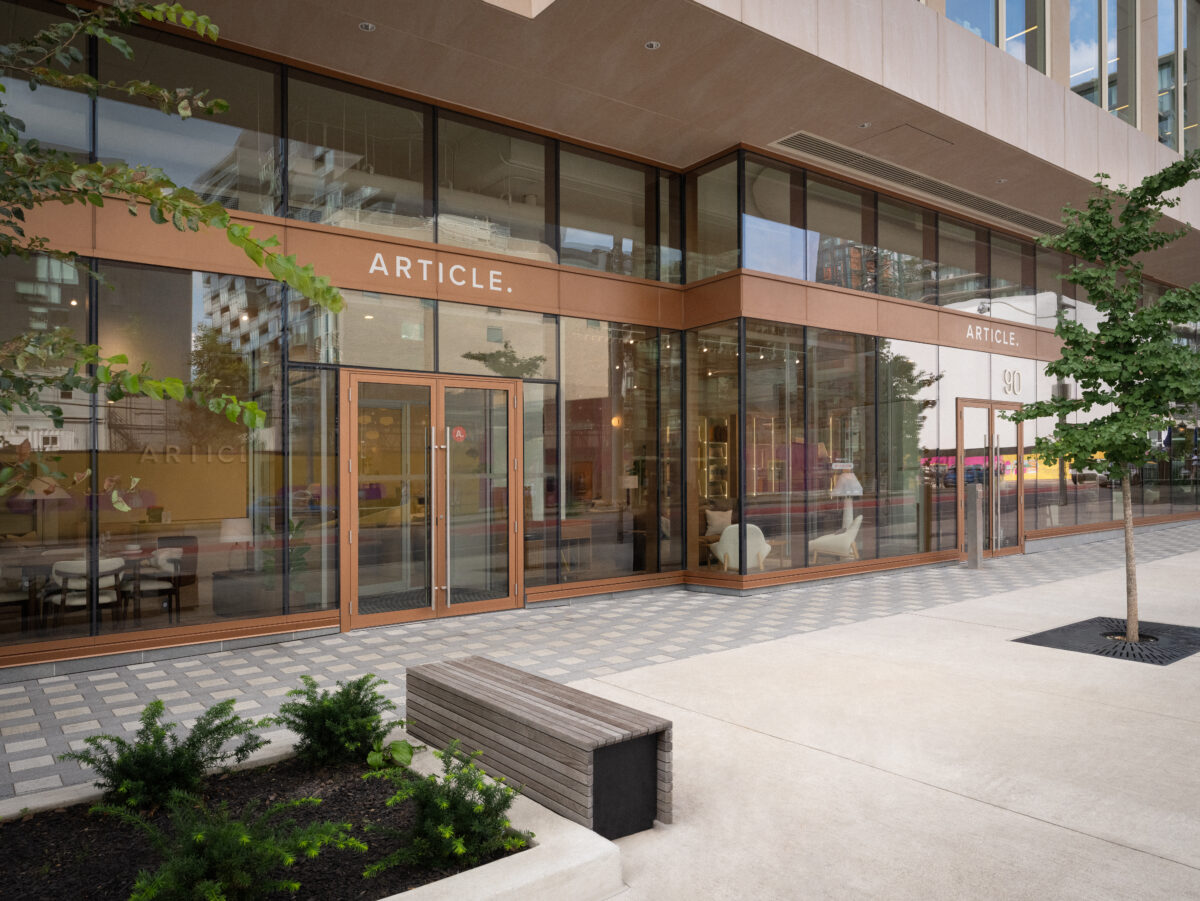
Vancouver-based furniture retailer Article opened its first Toronto store, marking the company’s second retail location in Canada and the next step in a larger physical retail strategy.
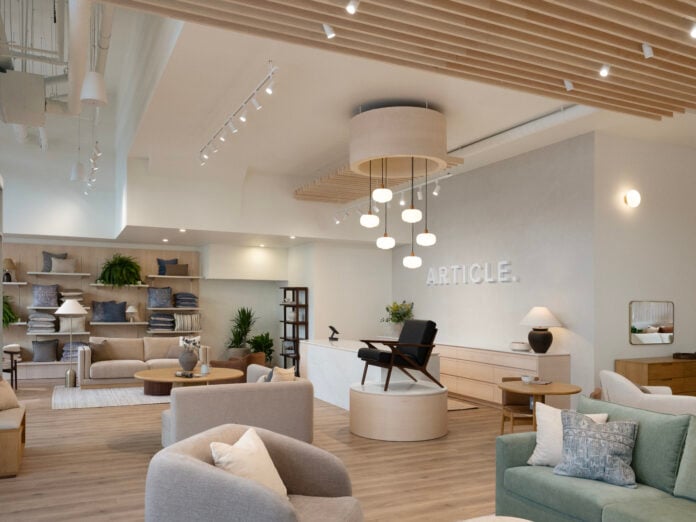
The furniture store will open at 90 Bathurst Street in King West, one of downtown Toronto’s most walkable, design-forward neighborhoods known for modern condo living and vibrant retail.
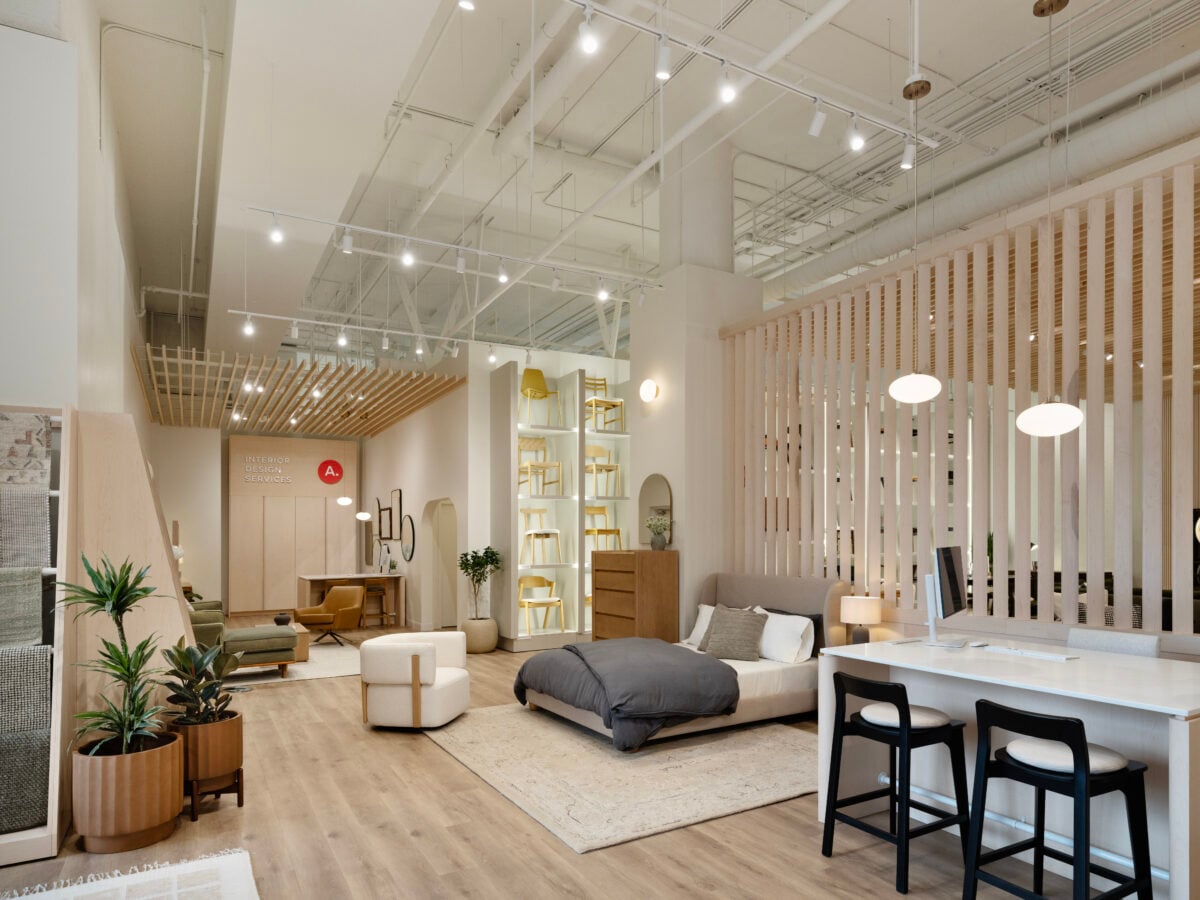
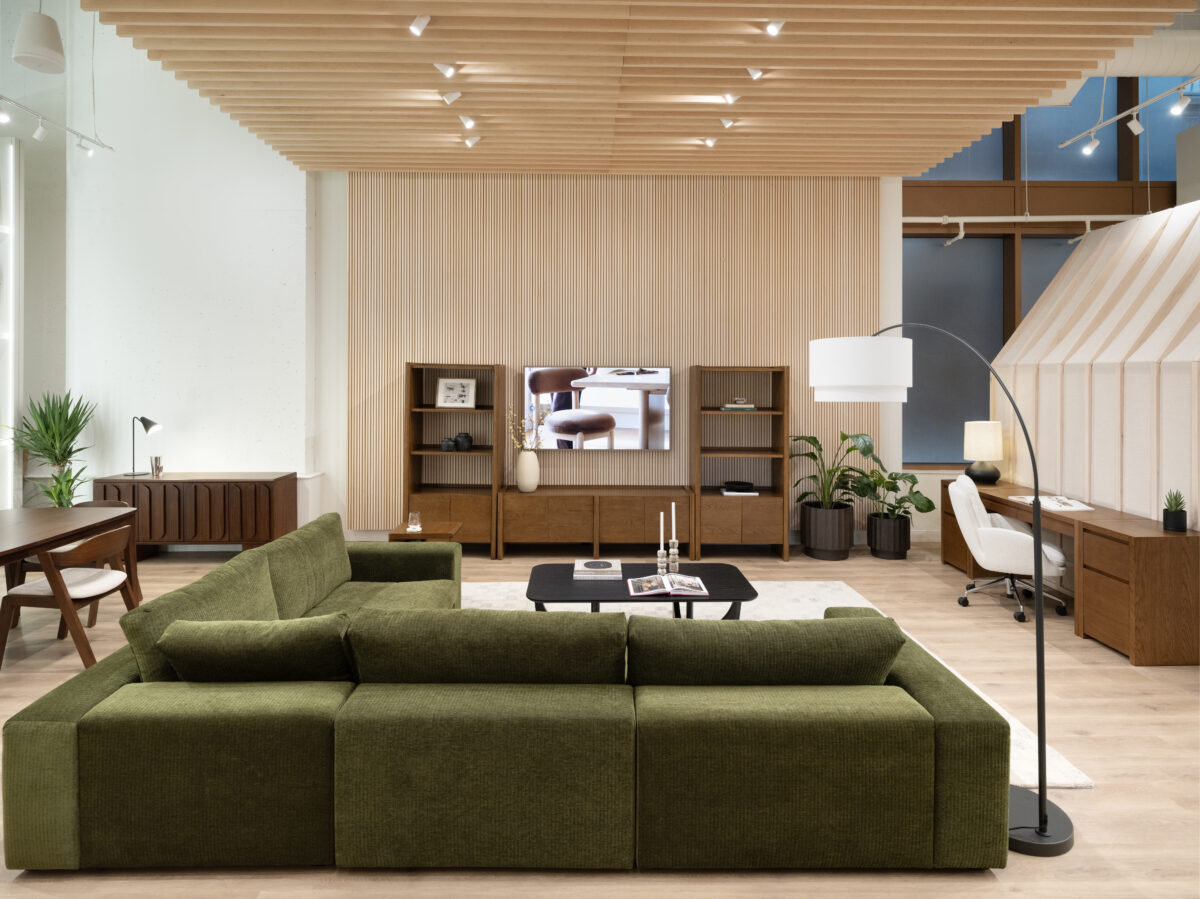
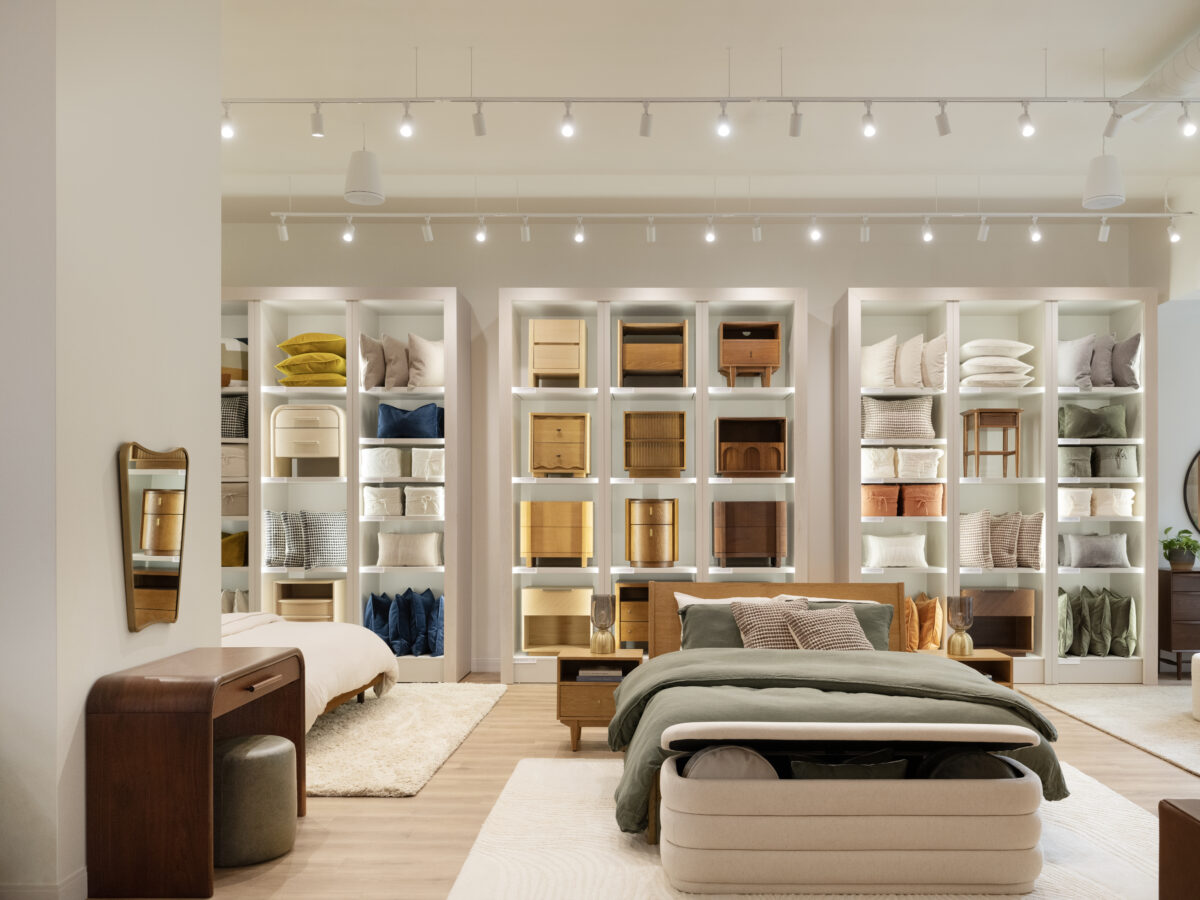
The new store features curated room vignettes, an extensive swatch library, and complimentary in-person Interior Design Services.
The store is 9,600 square feet.
Article photo
Building on the success of first store in Vancouver
The Toronto furniture store builds on the success of Article’s first-ever physical retail location in Vancouver, designed to test and refine its brick-and-mortar strategy. The Vancouver store has surpassed expectations since opening in August 2024, with in-store average order values exceeding online by more than 20 per cent.
Aamir BaigArticle photo
“For more than a decade, Article succeeded through a digital-first model, meeting consumer demand for modern furniture online,” said Aamir Baig, Co-founder and CEO of Article. “Over the past 18 months, we’ve seen how physical retail can deepen customer connections and strengthen our presence in key markets. As we expand, we’ll focus on store locations in North American cities where e-commerce performance is already strong, using retail to build on that momentum and make it easier to experience Article in person.”
At 9,600 square feet, the store is Article’s largest to date.
“We see physical retail as an extension of the business we built online and we are taking a disciplined approach to our expansion by expanding to markets with proven e-commerce performance. Ontario accounted for 40% of our online Canadian purchases in 2025, with customers based in the city of Toronto representing a third of that volume. Toronto is one of our strongest markets in North America, and expanding our retail footprint there is a natural next step,” said Baig.
Physical retail an extension of online presence
“Because physical retail is an extension of our online presence, creating a seamless experience between article.com and our brick-and-mortar stores is essential. Giving customers the ability to see, touch, and test our products in person is a major driver of purchase decisions. Features like Article’s free interior design services are specifically built to make furniture shopping easy, providing customers with expert design advice so they can create a stylish home at a great price.”
As the brand expands its physical retail footprint, it’s being deliberate about entering markets with proven e-commerce performance, said Baig.
“We plan to have up to five stores open across North America by early 2027, but our focus isn’t simply on store count. We’re building a scalable retail model that supports sustainable, long-term growth,” he said.
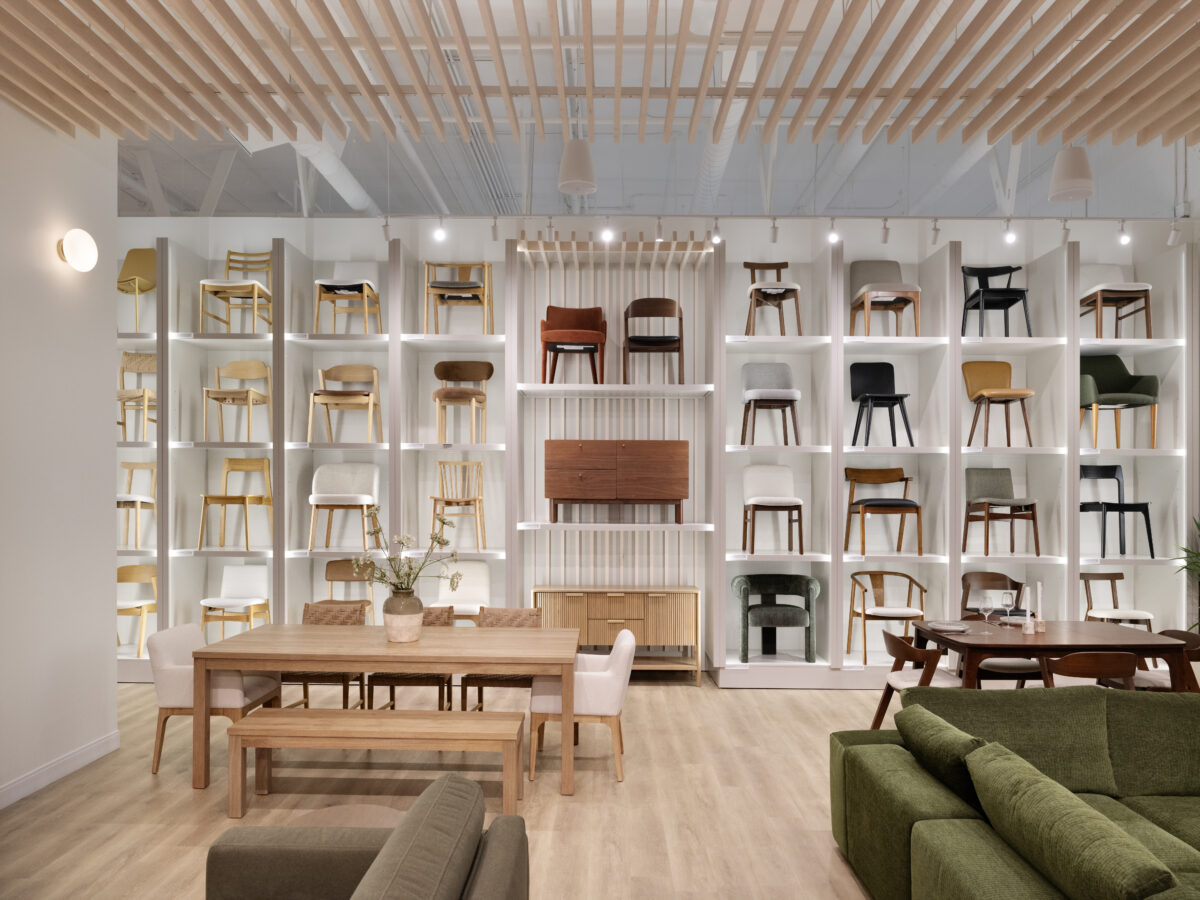
“The Toronto store will have the largest assortment of products, giving Torontonians the opportunity to experience a wider variety of Article products in real life. The assortment includes our core living room, bedroom, and dining categories, with outdoor incorporated seasonally. It’s brought to life through curated room settings, dedicated lighting and décor displays, and a chair wall featuring nearly all of our dining chair collections.
Products featured in-store are selected based on best sellers and new launches, with seasonal categories like outdoor available when relevant. In-store assortments may evolve over time based on local customer feedback, but we’ll always incorporate core styles we know will delight our customers.”
Article photo
Driving ongoing, sustainable growth
Baig said the company is making deliberate investments in strategic areas to drive ongoing, sustainable growth.
“Physical retail allows us to meet customers where they are and connect with those who want to experience Article furniture in person before making a purchase, unlocking an exciting new growth channel. As a result, physical retail will play an integral role in Article’s growth strategy over the next few years,” he said.
“While we don’t have any additional Canadian locations to announce today, we’ll continue to prioritize expansion in markets with proven e-commerce performance and strong customer demand.”
The company also has a store in San Francisco and is scheduled to open another one in Bellevue, Washington before the end of the year.
Grocery store in Quebec. Photo: Vergo Construction
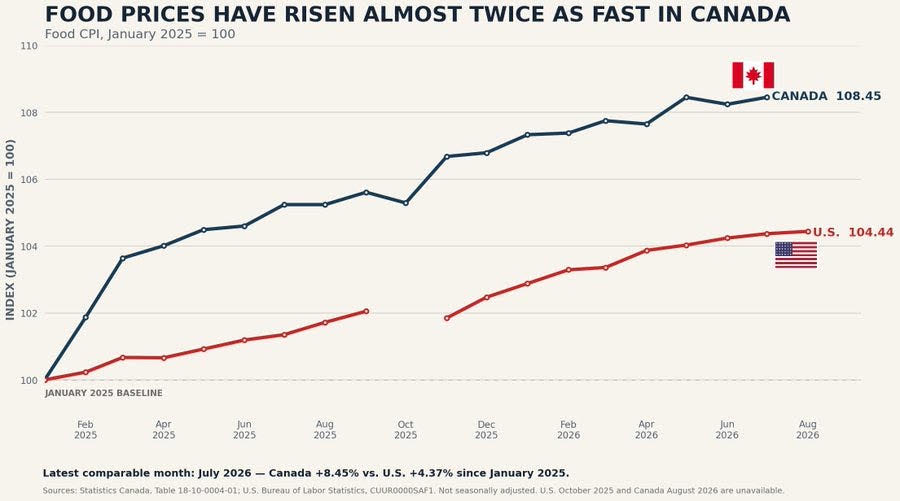
The United States is imposing tariffs on much of the world, disrupting supply chains and inviting retaliation from its trading partners. Yet American food inflation remains lower than Canada’s.
For Canadians repeatedly told that external forces are primarily responsible for their rising grocery bills, this is an uncomfortable comparison.
From January 2025 to July 2026, Canada’s total food price index increased by approximately 8.5%, compared with 4.4% in the United States. At first glance, food prices appear to have risen almost twice as quickly in Canada.
There is, however, an important statistical caveat. Total food includes restaurant meals, and January 2025 fell during Canada’s temporary GST/HST holiday. Restaurant prices were artificially depressed before jumping when the tax returned. Starting the comparison in January therefore exaggerates Canada’s increase.
A cleaner grocery-only comparison still tells a troubling story. Between January 2025 and July 2026, prices for food purchased from stores increased by approximately 5.8% in Canada, compared with 3.4% in the United States. Canadian grocery prices rose roughly 70% faster.
The gap is real. The explanation is more complicated than tariffs.
Although the United States has erected trade barriers against many countries, it is not literally tariffing every product from every trading partner. Exemptions, negotiated arrangements and preferential treatment for compliant goods remain. More importantly, tariffs apply only to imported products. The United States possesses a vast agricultural base, enormous processing capacity and a domestic market of roughly 350 million comparatively affluent consumers.
Scale matters.
American food manufacturers can spread fixed costs across larger production runs. Retailers have access to more suppliers. Processors can substitute ingredients more easily, and the country’s extensive domestic production cushions many categories from border disruptions.
Canada’s food economy operates under very different conditions. Our market is smaller, our processing capacity is thinner, and many regions depend heavily on imported ingredients, equipment, packaging and finished products. A weaker Canadian dollar also makes almost everything priced internationally more expensive.
The Bank of Canada concluded that the resurgence of Canadian grocery inflation in 2025 was driven largely by import costs, including the depreciation of the Canadian dollar. Weather-related shortages affected products such as coffee and cocoa, while drought, feed costs and limited cattle supplies pushed beef prices sharply higher.
These pressures existed in the United States as well. But the American food system has generally absorbed them more effectively.
Tariffs also do not pass through to consumers immediately. Food companies rely on inventories, negotiated contracts and hedging strategies. According to the Bank of Canada, cost pressures can take approximately six months to work through the food supply chain. Consequently, some effects of American tariffs may still be coming.
Retaliation can create another paradox. When foreign governments restrict American agricultural exports, more American production may remain inside the United States. That can depress domestic farm prices, even while imported inputs become more expensive. Farmers lose export opportunities, but American consumers may temporarily benefit from additional domestic supply.
None of this proves that tariffs are sound economic policy. It demonstrates that a large, competitive and productive food economy is better equipped to absorb trade shocks.
Canada should take notice.
First, Ottawa should avoid retaliatory tariffs on ingredients, packaging, machinery and other inputs that Canadian food manufacturers cannot easily source domestically. American tariffs are paid initially by American importers. Canadian counter-tariffs are paid by Canadian importers. We can be hit both ways.
Taxing essential inputs may create a satisfying political headline, but it ultimately increases production costs for Canadian businesses and grocery bills for Canadian households.
Second, Canada needs significantly more food-processing capacity. We remain remarkably good at exporting agricultural commodities and buying back higher-value processed products. Accelerated capital investment, automation, predictable regulation and access to affordable energy would allow Canadian processors to achieve greater scale.
Third, Canada must finally operate as one domestic food market. Provincial regulations, duplicative licensing systems and inconsistent standards make it unnecessarily difficult for smaller processors to sell across provincial boundaries. A Canadian company should not face more difficulty shipping food between provinces than a foreign supplier faces entering the country.
Fourth, grocery competition needs to improve. Restrictive property controls that prevent competitors from opening stores should be eliminated. The Competition Bureau has repeatedly identified these restrictions as barriers to entry. Canada should also make itself more attractive to international grocers and provide independent retailers with better access to wholesale supply.
Finally, protected agricultural sectors should not be treated as untouchable. Supply management was created for another era. Reform does not require abandoning farmers. It means gradually encouraging productivity, lowering input costs, attracting processing investment and giving efficient producers opportunities to grow beyond a protected domestic market.
The lesson from the United States is not that tariffs lower food prices. They do not.
The lesson is that resilience comes from production capacity, scale, competition, productivity and diversified supply chains. The United States currently possesses more of those advantages than Canada.
At the grocery store, patriotism is not a pricing strategy. Neither is tariff theatre.
If Canadian governments genuinely want to defend food affordability, they should spend less time telling consumers whom to blame and more time removing the structural costs that make Canada’s food system so vulnerable in the first place.
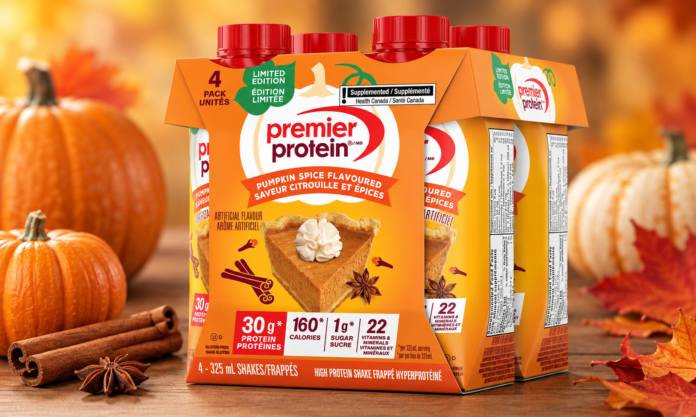
Premier Protein is expanding its Canadian retail assortment with the rollout of its limited-edition Pumpkin Spice Protein Shake, adding another product across major retail channels as the brand builds its presence in Canada.
The seasonal shake launched through Costco and Amazon in August, followed by Walmart in September, with additional grocery distribution expected. The rollout builds on an established Canadian business for Premier Protein, which has spent years increasing its presence across grocery, pharmacy, mass and club retail.
Premier Protein is already carried by many of Canada’s largest retailers. The brand has previously identified Walmart, Real Canadian Superstore, Shoppers Drug Mart, Loblaws, Provigo, Safeway, Fortinos, Zehrs, Save-On-Foods, Metro, Sobeys and Jean Coutu among retailers carrying its shakes and protein powders.
The latest rollout broadens an existing Canadian assortment rather than marking a new entry into the market. Walmart Canada currently lists several Premier Protein ready-to-drink varieties, including Chocolate, Vanilla, Café Latte and Strawberries & Cream, while Costco has been an established distribution channel for the brand.
The larger story is the strategy behind that growth. Premier Protein’s parent company is seeking substantially wider distribution for its ready-to-drink business, including more points of sale and greater visibility within stores.
BellRing Brands Targets More Distribution
Premier Protein is owned by BellRing Brands, a publicly traded U.S. nutrition company whose portfolio also includes sports nutrition brand Dymatize. Premier Protein is the company’s largest business and has developed into a major player in the North American ready-to-drink protein category.
In its 2025 annual report, BellRing said it planned to increase total distribution points for Premier Protein ready-to-drink shakes by more than 20% during fiscal 2026, roughly matching the pace achieved the previous year. The strategy also includes securing additional in-store displays and placing products outside traditional nutrition aisles to increase trial.
BellRing reported significant progress during its second quarter of fiscal 2026. Total distribution points for Premier Protein ready-to-drink shakes increased 29% year over year. The brand held a 28.2% share of the measured U.S. ready-to-drink protein category, while household penetration reached 21.3%.
Those figures are specific to the U.S., but they demonstrate the scale Premier Protein has reached as BellRing continues investing in wider distribution.
Protein Becomes a Mainstream Food Purchase
The strategy comes as protein products occupy more space within mainstream food and wellness retail. Ready-to-drink shakes are increasingly positioned around everyday consumption, including breakfast, snacks and convenient nutrition, broadening the potential customer beyond the traditional sports nutrition shopper.
Premier Protein has been growing across several mainstream channels outside its historically important club business. BellRing has identified multi-channel execution, increased household penetration, distribution gains and innovation as central to the brand’s next phase of growth.
That diversification is reflected in Premier Protein’s Canadian footprint. Costco remains an important outlet for the brand, while Walmart, major grocery banners and e-commerce provide access to consumers through regular household shopping.
Wider availability also puts protein brands in competition for more mainstream retail shelf space. Grocery stores, mass merchants and warehouse clubs have become increasingly important venues for reaching consumers beyond the traditional sports nutrition customer.
Seasonal Flavours Add to the Assortment
Premier Protein is also applying a familiar packaged-food strategy to the category through seasonal and expanded flavour offerings.
Limited-time products can refresh an established assortment and generate trial without permanently adding another SKU to a retailer’s shelf. Pumpkin spice is already an established fall flavour across coffee, bakery and packaged food, giving Premier Protein a recognizable seasonal offering for its ready-to-drink line.
The Canadian Pumpkin Spice shake contains 30 grams of protein and one gram of sugar per 325-millilitre serving. Costco is carrying the product in an 18-pack, Walmart is offering a four-pack, and the product is also available through Amazon.
The wider Canadian assortment extends beyond Premier Protein’s core Chocolate and Vanilla offerings, with flavours including Café Latte, Caramel, Strawberries & Cream, Chocolate Peanut Butter and Bananas & Cream. Cookie Dough has also been introduced through Costco.
The broader selection gives Premier Protein more opportunities to introduce new products within the same ready-to-drink format while competing for additional shelf space.
Distribution Growth Meets a More Price-Sensitive Consumer
BellRing’s push for wider distribution is taking place in a more challenging consumer environment. During its second quarter of fiscal 2026, Premier Protein net sales increased 1.7% while volume rose 11.3%. Ready-to-drink shake sales increased 2.3%, with volumes up 11.7%.
The gap reflects heavier promotional activity. BellRing reported that Premier Protein’s price/mix declined 9.6% during the quarter, with incremental promotional investment and unfavourable mix weighing on the measure. Increased promotions and distribution gains helped drive the higher volumes.
BellRing has chosen to continue investing behind the brand despite those pressures. The company has pointed to strong household penetration, brand equity and volume growth while acknowledging heightened consumer price sensitivity and promotional pressures.
In Canada, the latest rollout puts another Premier Protein product across club, mass and e-commerce channels, with additional grocery distribution planned. It adds to an already broad assortment as the company pursues more retail touchpoints and greater visibility for the brand.
For Canadian retailers, Premier Protein’s expansion reflects the growing role of protein within mainstream food and wellness. As brands pursue more distribution, new flavours and greater in-store visibility, competition for the protein consumer is increasingly playing out across grocery, warehouse clubs and mass merchants.
The recent back-to-school shopping period showed that things can change quickly in retail when a celebrity or creator can suddenly make one product the thing everyone wants overnight. During the summer, Hailey Bieber’s jeans sold out in a matter of days at the Gap.
While TikTok continues to shape which styles younger shoppers are looking for in the first place, for retailers and consumer brands, the challenge is keeping up with demand that can shift much faster than traditional inventory planning.
In an interview with Retail Insider, Bianca Anghelina, Founder and CEO of Aily Labs, talked about how AI can help brands spot these shifts earlier and make faster calls on replenishment while there’s still time to act.
There’s also risk in moving too fast. A viral product can sell out in days, but the demand behind it can fade just as fast, leaving brands unsure whether they’re looking at a lasting trend or a short-lived spike before they commit more inventory.
Bianca AnghelinaArtur Stec photo
Question: How are social media and creator-driven trends changing the way retailers forecast demand and plan inventory for events like back-to-school shopping?
Answer: The biggest change is speed.
A product can suddenly become popular because of one creator or one social trend, and within days retailers can see demand move in a completely different direction. Traditional forecasting was never built for that. It relies heavily on historical patterns, but what happened last season may tell you very little about what a consumer is going to want next week.
The opportunity with AI is to connect what is happening externally with what is happening inside the business. Retailers can look at social signals, search behaviour, and consumer interest together with sales, inventory, supply and financial data.
That creates a much more real-time view of demand. Instead of waiting until a product is sold out to realize there was a trend, they can see it developing and start making decisions much earlier.
For me, that is where the real impact starts. You move from reacting to what happened to deciding what to do next while the opportunity is still there.
Q: How can AI help retailers identify an emerging viral trend early enough to adjust inventory and replenishment decisions before products sell out?
A: Retailers already have enormous amounts of data. The challenge is bringing those signals together quickly enough to decide.
Social media might show that a product is suddenly gaining attention. Then you have search behaviour, sales velocity, inventory levels, store-level traffic and supplier capacity all sitting in different places.
AI can bring those signals together and identify patterns much faster than a human team could.
Then you can move from insight to action. Where is demand accelerating? Which stores are likely to run out first? Can I reallocate inventory from another region? Should I increase replenishment now, or do I need another day of data?
That is the part I find exciting. Decisions that could previously take days or weeks can start happening in minutes.
At Aily, our AI agents can run 100,000 what-if scenarios in seconds. So rather than making one big bet on a trend, retailers can compare different options and understand the trade-offs before they act.
Q: What data signals should retailers be watching to distinguish a trend with sustained consumer demand from a short-lived viral spike?
A: I would never look at one signal on its own.
A product can have millions of views and still not translate into meaningful sales. What matters is whether you start seeing the same pattern across different parts of the business.
You want to know whether social interest is growing over time, whether search activity is increasing, whether people are buying the product and whether that demand is spreading across markets or customer groups.
Then connect that with what is happening operationally. Are stores seeing faster sell-through? Is inventory starting to tighten? Are consumers coming back and buying again?
When those signals reinforce one another, you have a much stronger indication that this is real demand rather than a moment of attention.
This is why I always come back to the idea of a single source of truth.
Marketing, sales, supply chain and finance should be looking at the same picture and making decisions from the same information.
Keira Burton photo
Q: What are the risks for retailers of reacting too quickly to social media trends, and how can AI help them avoid over-ordering or being left with excess inventory?
A: Moving faster does not mean reacting to everything.
If a retailer sees a viral post and immediately places a huge order, the risk is obvious. The trend can disappear just as quickly as it appears, and suddenly you have excess stock, tied up working capital and markdowns at the end of the season.
AI should help you make a better decision, not simply a faster one.
Maybe the right action is to move existing inventory between stores before ordering more. Maybe you increase replenishment gradually. Maybe the data shows that social engagement is high, but actual conversion is still weak, so you wait.
Retailers need to understand why the AI is recommending a particular action, and which signals are driving it. It shouldn’t feel like a black box telling you to buy more inventory. The recommendation should be grounded in the business and help the team understand the trade-off so they can make the decision with more confidence.
Q: How do you expect AI-driven demand forecasting to change the relationship between social media trends, consumer behaviour and traditional retail inventory planning?
A: I think forecasting is becoming much more continuous.
Today, many companies still operate in planning cycles. They create a forecast, build an inventory plan and then wait until the next cycle to adjust it.
But consumer behaviour does not work in cycles anymore.
With AI, new information can constantly feed into the forecast, whether that is a change in consumer interest, sales, inventory or supply. That also means marketing, commercial, supply chain and finance no longer need to make decisions from separate views of the business.
Over time, agents will not only tell retailers that something has changed. They will help determine what to do about it and, within predefined guardrails, increasingly take action.
That is where I see retail planning going. Much more real time, more connected and much closer to the actual consumer.
ByJax Zheng, Director of Partnerships atUniUni, a leading last-mile delivery company.
The holiday season can make or break a small or medium-sized e-commerce business. It brings more shoppers, more orders and higher stakes, especially when it comes to shipping. When time-sensitive purchases are on the line, shoppers expect reliable delivery, timely updates and quick resolution when something goes wrong. There’s little room for error.
While larger brands can absorb peak-season complexities with dedicated logistics teams, extensive infrastructure and carrier networks, SMBs simply can’t. Fortunately, they don’t have to rely on the biggest shipping networks to give customers the fast, reliable delivery experience they expect. With the right partners, they can access many of the same capabilities without building everything themselves.
Jax ZhengUniUni photo
Here’s what to know:
Prioritize Flexibility for When Demand Grows
Peak season is inherently unpredictable, but a last-mile strategy doesn’t have to be. With order volumes shifting based on seasonal promotions, weather, product demand, and shopping trends, smaller retail and e-commerce brands need to build flexibility into their delivery strategy from the start.
SMBs can also find that large, standardized carrier networks aren’t always designed around the flexibility they need. Instead, they should look to delivery partners with flexible networks that can scale up and down with demand, adapt as conditions change, and maintain consistent service without requiring constant intervention.
When building a strategy, and vetting the last-mile deliverypartners that will support it, retailers should ask:
Can we easily increase/decrease capacity when order volume fluctuates?
Can we ensure delivery performance remains consistent across markets?
Do we have clear visibility without manually managing every shipment?
The goal is a flexible network that delivers the speed, visibility, and reliability shoppers expect.
Use Technology to Level the Playing Field
Smaller brands don’t have to build this flexibility themselves. For years, SMBs often had to work within the same large-scale delivery networks as everyone else, with fewer options to customize the experience around their needs. Today, tech-enabled delivery partners are giving smaller retailers access to the capabilities, flexibility and visibility that were once reserved for larger retailers.
With the right partners, SMBs can tap into networks that provide them with:
Real-time order tracking and updates from warehouse to doorstep
Technology that reduces manual order coordination and customer communication
Scalable carrier networks that flex across markets to meet demand
Such partners give SMBs a way to meet customer expectations without the investment and infrastructure required for large in-house logistics operations. Instead, they’re gaining access to the delivery capabilities customers expect, in a model that fits a small e-commerce business.
UniUni photo
Start Holiday Peak Planning Now
For small e-commerce teams, waiting until orders start picking up to address delivery challenges leaves little room to make changes. Now is the time to confirm carrier capacity, establish contingency plans, test processes and make sure customers will have the visibility they expect throughout the holiday season.
Planning ahead can help SMBs answer a few important questions:
Are our delivery partners set up to support a business our size, or are we paying for capabilities we don’t really need
Do we have enough delivery capacity to handle peak demand?
Do we have the right carrier mix to maintain reliable service as volumes increase?
Can customers easily track their orders and get timely updates?
What happens if a shipment is delayed, lost or otherwise goes off track?
Which delivery tasks can we automate or outsource so our team isn’t overwhelmed?
The goal is to shine light on potential pressure points now, while there’s time to address them. A few changes made in the months before Black Friday/Cyber Monday can help prevent delivery issues from becoming customer-facing problems when order volumes are at their highest.
Deliver Like a Large Retailer Without Being One
SMBs don’t necessarily need the biggest delivery network; they do need one that gives them the right mix of cost, coverage and flexibility. Fortunately, when it comes to ensuring positive delivery experiences to their customers, they have options.
With early planning, the right technology and shipping partners in place, smaller e-commerce brands can unlock the capabilities of large-scale retailers to meet heightened customer expectations and deliver the shopper experiences that turn holiday purchases into a reason to buy again.
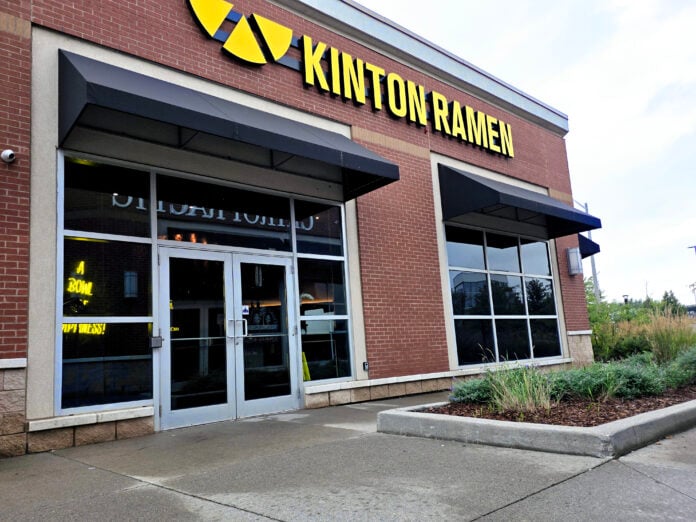
Kinton Ramen has opened its third Hamilton-area restaurant, expanding the Japanese ramen chain’s presence in the region with a new location in Ancaster Village.
Kinton Ramen Wilson Ancaster is located along the commercial and retail stretch of the village and is the company’s latest addition to a network of more than 60 restaurants across five provinces.
New Ancaster location
The restaurant is currently operating under a soft opening, with hours from noon to 8 p.m. Monday through Sunday. The company said a formal grand opening is expected once the restaurant team is fully settled into operations.
The Ancaster location is situated near the Hamilton Golf and Country Club and is intended to serve residents and visitors to the village, as well as customers shopping and dining in the surrounding commercial area.
Kinton Ramen photo
“Ancaster Village is an ideal location for KINTON RAMEN, given the strong mix of local residents, shopping, dining and nearby recreational destinations,” said Trista Jorgensen, Marketing Director, KINTON RAMEN, part of the Foodtastic family of brands. “We’re confident KINTON RAMEN Wilson Ancaster will become a popular destination for the community and visitors to the village, and we’re excited to welcome guests through our doors.”
The concept specializes in Japanese cuisine, including ramen made with slow-cooked broths. The company said its two existing Hamilton-area restaurants have established a local customer base, providing a foundation for the Ancaster expansion.
“Hamilton has been an incredible market for KINTON RAMEN, and the response we’ve received from guests over the years has reinforced just how much demand there is for authentic, high-quality ramen in the community,” said Jorgensen. “Opening in Ancaster is an exciting next step, and we look forward to becoming part of the village and welcoming both returning guests and new customers.”
Kinton Ramen photo
Kinton Ramen has also announced the grand opening of its second Mississauga location at Heartland Town Centre, a premier open-air power centre, on September 19, following a successful soft-opening period. Doors will be open from 11 a.m. to 12 a.m. that day – and dine-in guests can enjoy 50 per cent off all regular ramen items to celebrate.
KINTON RAMEN Heartland Mississauga is located at 6045 Mavis Road, Unit 11, in the southern end of the shopping centre. The new restaurant offers visitors an affordable and accessible dining option in one of the GTA’s premier retail destinations.
Continued Canadian expansion
The openings are part of Kinton Ramen’s broader Canadian expansion. The company now operates more than 60 locations in Ontario, British Columbia, Manitoba, Alberta and Quebec, with much of that growth occurring over the past five years.
Kinton Ramen was established in Toronto in May 2012 and was among the city’s first Japanese ramen restaurants. The company is led by executive chef Aki Urata and a team of ramen chefs and is part of the Foodtastic family of brands.
The company says its restaurants focus on ramen made with fresh ingredients, including noodles and broths, as well as other Japanese dishes.
At 9:05 on the first morning of a holiday campaign, a merchandising coordinator updates the banner on a retailer’s Canadian store. Seven minutes later, the US team discovers that its promotion has disappeared. Both employees had been switching between regional storefronts in the same browser, and one of them edited the wrong account.
The mistake takes only minutes to correct. Finding out why it happened takes much longer.
This is the less visible side of multi-store growth. A retailer may successfully launch new storefronts, marketplaces, advertising accounts, and social commerce channels while continuing to rely on browser workflows designed for a much smaller business.
Employees move between similar dashboards. Agencies request access to client accounts. Regional teams need different configurations and permissions. Login sessions, browser extensions, and account settings accumulate across personal computers. The company may have added more selling channels, but it has not built an operating system for managing them.
Reliable multi-store e-commerce operations begin by giving every store, employee, and automated process the correct working context before a task starts.
A single online store usually has a recognizable set of systems: an e-commerce platform, an advertising account, analytics, email marketing, customer support, and perhaps one or two marketplace integrations.
A multi-store retailer repeats that structure across brands, countries, or sales channels. The number of possible errors grows faster than the number of stores because employees must also remember which account, region, permission level, and browser configuration belong together.
The pressure becomes especially visible during product launches, seasonal promotions, regional expansion, and staff changes.
Operational layer
Common multi-store problem
What the team needs
Regional storefronts
Similar dashboards make it easy to update the wrong market
Clearly separated and labeled workspaces
Marketplace accounts
Login sessions and settings become mixed across platforms
Persistent browser environments for each authorized account
Advertising operations
Teams may confuse brands, currencies, or campaign regions
Role-specific access and a clear account context
Agency collaboration
External partners receive broader access than their work requires
Controlled access to assigned environments
Staff transitions
Important sessions and configurations remain on personal devices
Company-managed workspaces that survive personnel changes
Repetitive workflows
Manual effort increases with every new store
Gradual automation with review and recovery steps
Password managers can improve credential storage, and native platform permissions remain essential. Neither one, however, provides a complete browser workspace containing the correct session, extensions, settings, bookmarks, and operating context for a specific store.
That gap is where many multi-store workflows become unreliable.
Consider a Canadian retailer expanding into the United States and the United Kingdom.
The company operates three Shopify storefronts, two marketplace seller accounts, regional advertising campaigns, separate customer communication channels, and several analytics tools. An internal team manages pricing and merchandising, while an agency handles paid media and regional contractors prepare localized content.
At first, the company records access information in a spreadsheet. Employees create bookmarks and manually sign in to whichever system they need. Everyone knows the arrangement is imperfect, but replacing it does not feel urgent.
Then the business enters a busy promotional period.
A contractor prepares UK content inside the Canadian store. A media buyer opens the wrong advertising account and has to verify every change made during the session. An urgent update is delayed because its authentication request goes to an employee who is unavailable. Management cannot easily determine which browser setup was used for a disputed change.
None of these incidents necessarily causes a major loss on its own. Together, they consume management time and make every new store harder to support.
The root problem is not employee ability. The workflow expects people to hold too much account context in their heads.
A stronger system makes the correct context visible. Instead of telling an employee to “open the right account,” the retailer assigns a clearly named workspace associated with the store, market, and task.
A dedicated browser profile is a saved environment for a particular store, brand, market, or operational role. It can retain the relevant login state, browser data, extensions, bookmarks, and configuration without mixing them with unrelated operations.
The objective goes beyond organizing browser tabs. Each profile creates a recognizable boundary around a specific area of work.
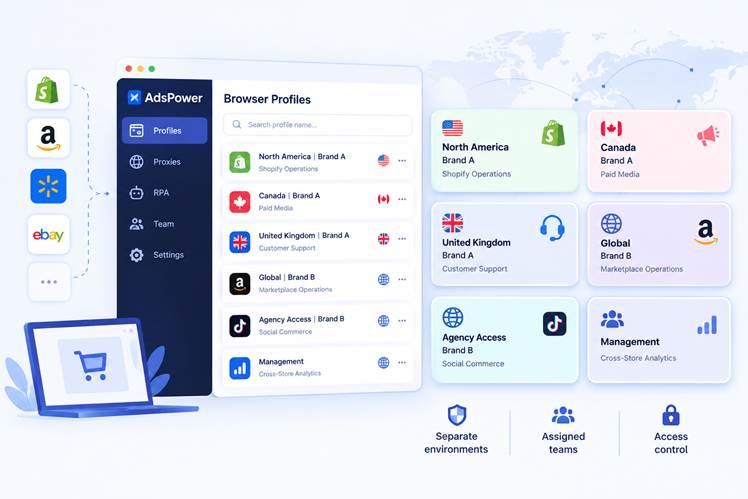
A retailer might maintain profiles such as:
North America | Brand A | Shopify Operations
Canada | Brand A | Paid Media
United Kingdom | Brand A | Customer Support
Global | Brand B | Marketplace Operations
Agency Access | Brand B | Social Commerce
Management | Cross-Store Analytics
The naming convention is not a minor detail. Labels should be clear enough that an employee can select the correct environment during a busy shift without opening it first.
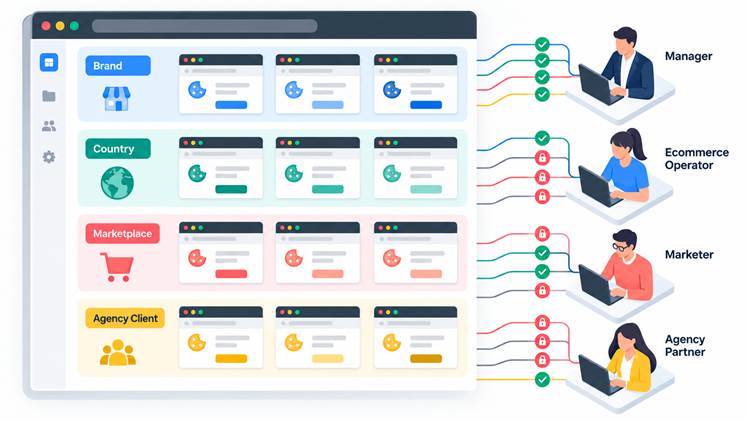
Multi-store management works best when each storefront is treated as an operational unit with an assigned environment, responsible team members, and defined access rules. Retailers can organize environments by country, brand, marketplace, or client depending on how the business is structured.
This model also improves continuity. A new employee does not have to reconstruct a working setup from scattered instructions. If someone leaves the organization, the company can remove that person’s access while retaining the environment required to operate the store.
Browser environment tools are sometimes treated as highly specialized technology. For legitimate retail teams, their practical value is more straightforward: they provide a structured way to maintain separate working environments at scale.
An anti-detect browser such as AdsPower can help authorized teams create and manage individual browser profiles for different stores, markets, and operational responsibilities.
Within AdsPower, browser profiles can be grouped and labeled according to a retailer’s own structure. One organization may group profiles by brand, while another may organize them by country, marketplace, or agency client. Each profile maintains its own browser data and working context.
Team permissions add another layer. Managers can assign environments to the people responsible for them instead of distributing every credential to every employee. This does not replace the native security controls of Shopify, Amazon, advertising platforms, or other services. It complements them by making access at the browser-workspace level easier to organize.
Browser profiles can be organized around the retailer’s structure, while access is assigned according to each team member’s responsibilities.
The purpose is operational separation and authorized team management. Retailers must still comply with the policies of every marketplace, advertising service, and commerce platform they use. A managed browser environment should make legitimate work more consistent, not provide a reason to ignore platform requirements.
Technology works best after the retailer has defined who owns each store, which systems are involved, and where approval is required. The following process provides a practical starting point.
Begin with an inventory of storefronts, marketplace accounts, advertising dashboards, customer communication channels, analytics platforms, and supplier portals.
For each system, record its brand, region, internal owner, approved users, business purpose, and data sensitivity. Include the native permission controls already available inside the platform.
This exercise often identifies problems before any new technology is introduced. Teams may discover inactive accounts, overlapping responsibilities, contractors who still have access, or important systems without a clear owner.
A useful test is simple: if an employee sees an unfamiliar login alert, does the company know exactly who should investigate it? If the answer depends on asking around, ownership is not yet clear enough.
A single environment for an entire department is often too broad.
A merchandising specialist updating product pages may not need advertising billing access. A media agency may need campaign dashboards but not customer order records. A support contractor may require access to one regional store without seeing another market’s operation.
Profiles should reflect the smallest practical area of responsibility. This makes the workspace easier to understand and limits unnecessary access.
Retailers should also adopt a consistent naming format. A simple structure such as Market | Brand | Function is easier to scan than a collection of profile names created independently by different employees.
Once profiles are established, managers can assign them to the relevant employees or external partners.
This is more reliable than asking each person to recreate browser configurations on a personal device. It reduces dependence on informal instructions such as “use the second Chrome profile” or “ask the previous account manager which extension to install.”
Access should be reviewed after role changes, agency transitions, seasonal hiring, and market closures. A quarterly review may be sufficient for a stable team, while rapidly changing organizations may need a monthly process.
The review should answer three questions:
Does this person still require access?
Is the access appropriate for the person’s current role?
Does the environment contain anything the person does not need?
Not every browser action has the same business impact.
Opening a reporting dashboard is different from changing a product price. Preparing a post is different from publishing it. Checking whether a campaign is active is different from increasing its daily budget.
Retailers should document the actions that require additional approval. These commonly include refunds, pricing changes, new permissions, banking information, advertising budgets, and public brand communications.
This step is essential before automation. If the company has not decided where human approval belongs, automation can make an unclear process run faster without making it safer.
The best first candidates for automation are frequent, rules-based, reversible, and easy to verify.
A retailer might begin with a workflow that opens an assigned browser profile, visits an approved reporting page, checks whether expected information is available, and prepares the result for an employee. The final interpretation remains with a person.
AdsPower offers RPA for predefined browser processes and a Local API for organizations that want to connect profile management with internal systems. RPA may suit repeatable visual tasks, while API access gives technical teams more flexibility for custom integrations.
A limited pilot is more useful than an ambitious rollout. Start with one store, one workflow, and a clearly defined fallback procedure. Run it long enough to encounter ordinary variations rather than judging it after one successful demonstration.
One of the most common automation mistakes happens before a workflow is ever built: the team assumes that everyone performs the task in the same way.
Ask three experienced operators to complete a routine store check, and they may take three different paths. One verifies inventory first. Another checks recent orders. A third opens a reporting tool before entering the store dashboard.
Automation does not resolve that inconsistency. It simply turns one version of the process into a repeatable sequence.
A practical discovery method is to ask an experienced operator to perform the task while describing each decision aloud. Record where the person pauses, checks another source, or makes a judgment based on context.
Those pauses reveal the boundary between a stable rule and human expertise.
Teams should also measure more than time saved. A useful pilot tracks correction rates, failed steps, wrong-store actions, manual recovery time, and the number of exceptions requiring employee judgment.
A process that runs quickly but regularly needs repair may be less valuable than a slower workflow that is transparent and easy to audit.
Rules-based automation works well when every step is known in advance. Retail operations also contain requests expressed in ordinary business language:
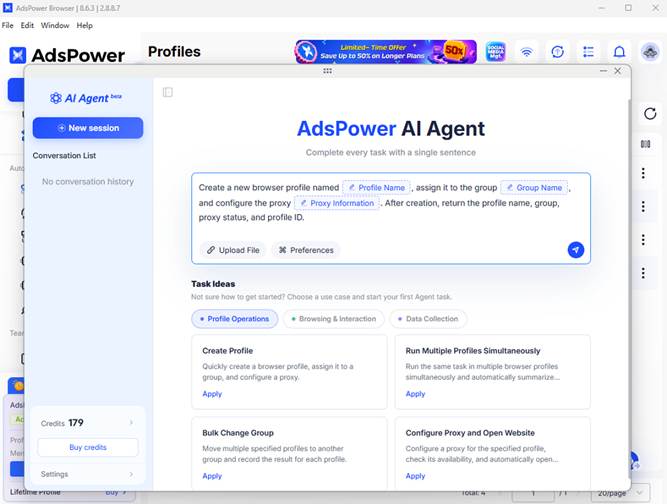
“Create a new browser profile named XXX, assign it to the group XXX, and configure the proxy Proxy Information. After creation, return the profile name, group, proxy status, and profile ID.”
“Open the browser profile with ID XXX,open platform XXX, and use the current account to publish XXXXXX. Pause the task and report the reason if verification, upload failure, or publishing restrictions occur.”
AdsPower’s recently launched AI Agent allows users to create and operate browser profiles through natural-language instructions. It can also perform selected browser tasks, including publishing approved content to accounts. Organizations can connect their own MCPs and Skills to extend the workflows available to the agent.
This gives employees another way to interact with the operational environment. Instead of navigating each configuration screen manually, an authorized user can describe the intended task conversationally.
Natural language does not eliminate the need for governance. A vague request can be just as ambiguous to an AI agent as it would be to a new employee.
Before allowing an agent to participate in production workflows, retailers should define which profiles it may access, which actions it may complete, and which steps require confirmation. The team also needs a recovery process for unexpected page changes, authentication requests, incomplete information, or actions that fall outside the approved workflow.
For many retailers, automation will operate in layers:
Manual profiles for sensitive or unfamiliar work
RPA for stable, repetitive browser sequences
APIs for connections with internal systems
AI Agent and MCP integrations for natural-language task coordination
Human approval for consequential decisions
The strongest system is not necessarily the one with the highest level of automation. It is the one that assigns the appropriate level of automation to each task.
The best automation candidates are routine, rules-based, and easy to verify. These may include opening the correct browser profile, navigating to approved pages, collecting authorized operational information, running standard checks, or preparing content for review.
Actions involving pricing, refunds, advertising budgets, customer disputes, permissions, or public brand communications should retain human oversight. The higher the potential impact on customers, payments, or platform compliance, the stronger the approval process should be.
Retailers should apply the same principle when choosing multi-store management technology. Profile capacity and feature count matter less than a few practical questions:
Can environments be organized around actual stores, brands, and team roles?
Can managers limit access and review sensitive actions?
Can the system progress from manual workflows to RPA, API, and AI-assisted operations?
Is there a clear recovery process when a workflow fails or a platform changes?
A flexible platform should allow retailers to automate gradually instead of forcing every task into the same model. Manual work, RPA, APIs, and AI agents each have a place. The right choice depends on the risk, frequency, and complexity of the task.
Automation is most useful when it reduces repetitive work while keeping responsibility visible.
New storefronts can be launched quickly. Building a team that operates them consistently takes longer.
As retailers expand across brands, marketplaces, and countries, mixed browser sessions, shared setups, unclear permissions, and undocumented routines create more opportunities for error. Dedicated browser profiles give each store a recognizable working context, while team permissions align access with responsibility.
RPA and APIs can handle stable processes, and AI agents make selected tasks easier to initiate through natural-language instructions. Together, these capabilities show how browser profile management is becoming part of the operating infrastructure for distributed e-commerce teams.
The goal is not to automate every decision. It is to ensure that employees and automated processes enter the correct store with the correct permissions and context. With that foundation in place, retailers can add new markets and channels without adding the same level of operational confusion.
Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 13 articles we published covering key developments in Canadian retail.
Groupe Dynamite is shifting its retail growth focus toward higher-productivity stores internationally, particularly in the U.S. and U.K., while optimizing its mature Canadian network through selective closures and renovations. Empire Company Limited is rejecting supplier price hikes related to new Canada-U.S. tariffs, leveraging its diverse sourcing options and past experience to manage cost pressures without passing them to consumers. Canadian retail continues to expand amid economic challenges including tariffs, rising costs, and shifting consumer priorities.
Apple’s introduction of the high-priced iPhone Duo and elevating Pro model prices signal a shift in Canada’s premium smartphone market, emphasizing financing, trade-ins, and in-store demonstration to support affordability perceptions. Fraud imposes significant hidden costs on Canadian retailers, extending beyond direct losses to include time and resources spent managing disputes and operations.
Firehouse Subs has reached a milestone with the opening of its 200th Canadian restaurant in Calgary, doubling its national presence since 2024 and reinforcing its focus on key markets. Consumer insolvencies in Canada reached nearly 400 daily filings in the year ending January 2026, with bankruptcies rising faster than consumer proposals, indicating growing financial distress among households. Canadian retailers face urgent challenges due to new U.S. tariffs impacting nearly 900 product categories, requiring careful reassessment of pricing strategies to safeguard margins without alienating price-sensitive consumers.
Canadian retail properties showed strong performance in the first half of 2026, with tight vacancy rates and rising demand particularly in suburban and grocery-anchored centers. Ryde: has introduced a new sleep-focused functional shot containing melatonin and other ingredients to help adults fall asleep faster on occasional difficult nights. Winnipeg-based entertainment company Activate is entering the Australian market with its first venue opening at Melbourne’s Highpoint Shopping Centre in early 2027, featuring interactive game rooms powered by RFID technology.
INDOCHINO’s Fall/Winter 2026 campaign, Hold the Room, highlights made-to-measure tailoring designed for multiple occasions across a weekend, emphasizing versatility beyond single events. As retailers approach peak shipping season, heightened order volumes increase the risk of lost or damaged shipments, threatening margins and customer satisfaction.