Home Blog Page 82

June spending holds steady as Canadians balance essentials and experiences: RBC

Gustavo Fring photo
Gustavo Fring photo

Growth in RBC Canadian cardholder spending held relatively stable in June as consumers continued to balance higher costs for essentials while selectively spending on seasonal experiences such as sporting events, according to an RBC report.

Abbey Xu
Abbey Xu

“Our estimate of core retail sales from cardholder transactions (excluding purchases of gasoline and autos) edged up 0.5% in June on a three-month average, similar to May, suggesting spending momentum remained positive despite ongoing budget pressures from higher energy prices,” said Abbey Xu and Rachel Battaglia, economists at RBC.

“Spending on discretionary goods led the way, posting the strongest gain among major categories on a three-month average. Essentials’ spending—including gasoline—also contributed to growth, while discretionary services rebounded after softening in May. Excluding gasoline, essential spending rose 0.5% on a three-month average, a welcome improvement after earlier signs of easing.

“The breadth of spending increases across categories points to households maintaining a cautiously optimistic view heading into the summer even as they remain selective about bigger-ticket discretionary purchases.”

Rachel Battaglia
Rachel Battaglia

The RBC report provided the following details:

  • Gasoline spending continued to outpace other categories, rising 2.3% on a three-month average. Gas prices were still up on a three-month average due to higher oil prices, but declined about 10% seasonally adjusted in June.
  • Entertainment and arts posted the second strongest gain at 1.7%, underscoring continued appetite for experience-related spending as summer activities pick up, including spending likely related to the FIFA World Cup.
  • Spending on clothing extended its positive trend, while dining also increased 0.7%, reversing weakness from prior months as consumers grew more comfortable with meals out with the improving weather and social activity.
  • Travel remained the outlier, continuing its decline on a three-month average, although the pace of contraction moderated in June. Households appear to remain cautious about larger discretionary purchases, but may be warming to travel deeper into summer.
  • Provincial trends were broadly positive with most regions posting spending growth on a three-month average. Ontario and British Columbia tied for the strongest performance, while Saskatchewan and Prince Edward Island were the only provinces to see declines.

More from Retail Insider:

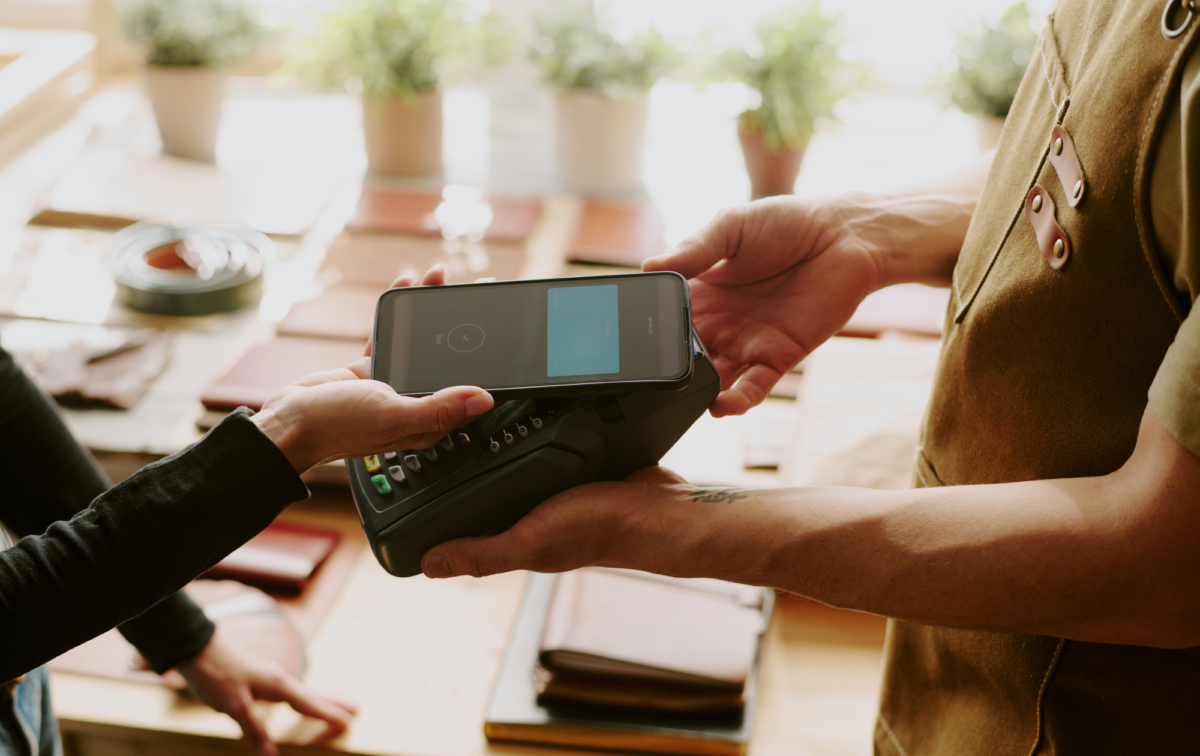
Retailers risk losing sales as more shoppers expect tap-to-pay, Oobit survey finds

Pavel Danilyuk photo

Slow checkout lines and outdated payment terminals aren’t just an inconvenience anymore, they’re costing retailers real sales. Oobit surveyed 1,000 U.S. adults and found that a meaningful share of shoppers are walking out the door the moment a business can’t keep up with how they actually want to pay. For retailers still relying on swipe-only setups, the data is a clear signal that the checkout experience itself has become a competitive risk.

Key Findings:

  • Over 1 in 4 American adults (28%) have walked away from a purchase because the merchant didn’t accept tap-to-pay.
  • 44% say a no-tap business feels outdated, a perception problem that compounds the lost sales.
  • Gen Z shoppers are more than twice as likely as baby boomers to abandon a non-tap purchase (36% vs. 14%), a warning sign for retailers trying to win younger customers.
  • More than half of Americans (56%) used phone tap-to-pay in the past 30 days, meaning the customers retailers are losing aren’t a fringe group, they’re the mainstream.
  • 1 in 4 American adults (25%) leave their wallet at home either deliberately or without thinking, including just over 1 in 10 (11%) who say they no longer feel they need it.
  • More than 2 in 5 Gen Z Americans (41%) treat their phone or smartwatch as their primary payment method, compared to 1 in 4 American adults nationally (25%).

You can explore the full study here.

In an interview with Retail Insider, Bernard Fisher, CMO, Oobit, discusses the survey findings.

Bernard Fisher
Bernard Fisher

Question: Your survey found that 28% of consumers have abandoned a purchase because tap-to-pay wasn’t available. What does that tell us about how consumer expectations at checkout have evolved?

Answer: In this context, the number seems to be a clear indicator that tap-to-pay has reached the level when it should not be considered nice to have but expected. In light of 27% of adults deciding not to complete transactions because a shop did not accept tap-to-pay and 44% of respondents finding it old-fashioned when a store did not accept taps, checkout friction has become a deal-breaker for many customers. People have grown accustomed to paying in one swipe. As soon as a retailer expects them to fish a card out of a pocket, the convenience of paying in one click breaks and the consumer does not hesitate to leave.

Q: Gen Z is far more likely than baby boomers to walk away from retailers that don’t accept tap-to-pay. How should retailers adapt their payment strategies to meet the expectations of younger shoppers?

A: The fact that members of Generation Z are almost twice as likely (36% vs. 14%) to avoid stores that do not accept taps indicates how much this trend can grow in the near future and how the retail market will change. Retailers interested in attracting young consumers cannot consider contactless payments a premium service and need to ensure that their terminals are equipped with NFC capabilities. Besides, retailers need to train their employees and consider potential implementation of cryptocurrencies and stablecoins stored in a wallet. Members of Generation Z and younger consumers who tend to use smartphones as primary devices are the most convenient group concerning in-wallet cryptos.

Q: Beyond avoiding lost sales, what other business benefits do retailers gain by modernizing their payment systems, such as improved customer loyalty or operational efficiency?

A: There are several ways how faster checkout can benefit retailers, even if they are not directly visible in a single transaction. Shorter queues mean increased checkout throughput during busy hours and are particularly important for quick-service and high-volume retail. Modern payment infrastructure, especially linked to mobile devices, provides for richer transactional data for developing personalized loyalty programs. Finally, the perception aspect: 44% of adults perceive no-tap checkout as being “outdated.” By modernizing the payment process, a retailer signals customers that it is a modern and reliable company, not only fast.

Oobit photo
Oobit photo

Q: What are the biggest barriers preventing some retailers—particularly small and independent businesses—from adopting newer payment technologies, and how can they overcome them?

A: However, there is little reason to doubt that the barriers to implementing faster payment are usually related to cost, complexity, and inertia instead of the skepticism towards the technology itself. Terminal upgrade, renegotiation of processor contract, staff training all take some time and initial investment, which is hard to justify for a business with low margins. Moreover, many independent retailers stick to whatever infrastructure their processor provided initially and never update it. For example, modern POS providers already provide for NFC capability as a part of the package. Therefore, many smaller businesses are able to upgrade their checkout process simply by switching processors at a natural renewal date without any large investments.

Q: With ongoing economic uncertainty and consumers being more selective about where they spend, how important is a seamless checkout experience in helping retailers remain competitive and capture every potential sale?

A: When consumers are more selective about purchases, they become less patient in terms of payment and less willing to experience any unnecessary friction. Seemingly small issues can become reasons to abandon the shopping idea. Moreover, combined with the fact that nearly half of all adults find losing their phone more problematic than losing a wallet, payment convenience became an integral part of the approach to spending money. In such conditions, a retailer has to care not only about the quality and pricing of its products. Payment process became a part of the customer value proposition.

More from Retail Insider:

Why consumer behaviour is becoming harder to predict in the AI shopping era

cottonbro studio photo

Why is consumer behaviour becoming harder to predict?

Consumers are changing faster than marketers can keep up. Economic uncertainty, AI-powered shopping tools, and shifting media consumption habits are making traditional audience segments less effective.

Mike Ford, CEO of Skydeo, says the old purchase funnel is dead. 

“People bounce between TikTok, an AI assistant, a store, and an app — sometimes in the same hour — and change their minds mid-stream. Demographics won’t save you anymore. You have to read what someone is actually doing right now, because that’s the only reliable signal of what they’ll buy next,” he said.

Ford said AI-powered shopping tools are the biggest shift since mobile.

“Shopping is becoming a conversation instead of a search. Nobody’s comparing 40 products anymore. They ask an AI and it hands them one answer. So the new fight isn’t for a search ranking. It’s to be the recommendation. And the whole journey collapses from days of research into a single conversation.”

So what data signals should retailers and brands prioritize today, and which traditional metrics are becoming less reliable?

“Behaviour beats demographics, full stop. Someone who searched hiking gear, walked into an REI (Recreational Equipment store), and bought a tent is telling you exactly what’s next. Knowing they’re 35 and live in a certain ZIP code tells you almost nothing. Impressions and clicks are the metrics I’d trust least. They measure attention, not intent,” explained Ford.

He said the best retailers stopped treating channels as separate campaigns. 

Mike Ford
Mike Ford

“A customer might find a product through an AI assistant, check it on social, touch it in a store, and buy it in the app. The winners build for that whole path. They’re also using AI to adjust creative and targeting in real time instead of waiting for the quarterly review, and investing in audience intelligence so they catch trends before their competitors do,” added Ford.

“The challenge is speed. Consumer behaviour is changing faster than most marketing orgs can react. The opportunity is that brands have never had richer behavioural data. Combine purchase data, location, and search behaviour and you can anticipate what customers need instead of chasing them after the fact. The whole game is moving from understanding audiences to understanding intent. The brands that make that jump win.”

Skydeo is a U.S.-based audience intelligence and data analytics company that helps retailers, brands and marketers identify and target consumers based on real-time behavioural signals rather than traditional demographic data.

More from Retail Insider:

Why smart retail brands are investing more in in-store experiences despite e-commerce growth

Vitaly Gariev photo
Vitaly Gariev photo

There’s a counterintuitive story sitting right now at the centre of retail: in a world of infinite digital options, physical presence has become a competitive advantage — not a legacy cost. The brands figuring that out are pulling ahead on both trust and conversion. 

The conventional wisdom is that e-commerce has made physical retail an afterthought. The data says otherwise. In-store retail media ad spending is expected to climb 33% in 2026. Nearly three-quarters of Gen Z shop in-store weekly. And experiential campaigns — when done right — are delivering returns of 3:1 to 5:1 on spend. 

The question isn’t whether in-person brand moments work. It’s why so many brands still can’t execute them

Also: 80% of consumers say in-person events are the most trusted way to discover new products — and 85% are more likely to make a purchase after engaging with a brand in person. 

Meanwhile, e-commerce keeps growing. So why are smart brands investing more in physical experiences, not less? 

In an interview with Retail Insider, Jeff Snyder, founder and Chief Inspiration Officer at Inspira Marketing, elaborates on what’s happening.

Question: What are the biggest mistakes brands make when trying to turn in-store experiences into actual sales rather than just foot traffic?

Answer:
When someone interacts with your brand in person, whether it’s a pop-up or live demo, they internalize it. That kind of engagement drives long-term brand relationships because it simultaneously taps into emotion, memory, and relevance.

The biggest mistake brands make when launching in-store experiences is failing to define what they want to achieve before designing the experience. The second mistake follows closely behind: not setting clear KPIs to measure progress toward that goal. We know experiential marketing delivers on emotional engagement, brand loyalty, and long-term value, but if the actual objective is increasing on-site sales or CRM signups, the experience needs to be architected so that the outcome happens organically.

Take a new product launch as an example. Cross-channel storytelling, pre-seeded social content that builds demand ahead of time, and influencer content introducing the product before it hits the shelves all work together to prime consumers. By the time someone engages with the product in-store, the groundwork has already been laid, and increased sales follow naturally, while the in-person experience builds relevance and long-term affinity for the brand, not just the product.

Jeff Snyder
Jeff Snyder


Q: Why are some brands succeeding with experiential retail while others still struggle to execute meaningful in-person activations?

A:
It comes down to creating community and a sense of belonging. Shoppers gravitate toward stores that immerse them in multi-sensory brand worlds rather than simply presenting products on a shelf. When we think about retailers doing this well, a few come to mind right away: Sephora offers personalization and education, Alo hosts in-store workout classes, and Nike’s House of Innovation in New York turns retail into a showcase and innovation studio. Apple lets customers try new products and take classes on the spot. Even Home Depot and Brass Pro Shops pull this off in their own ways, proving the approach works across very different categories.

Brands and retailers are now driving engagement through hyper-local, multi-touch strategies. I expect experiences to keep moving toward something more community-based and tailored, with local stores and small businesses curating products and moments around local tastes, perhaps leaning on AI to understand what those tastes are. In practice, that looks like community collaborations, food tastings, and pop-ups built for a neighbourhood rather than a national template.

Q: How has the path from an in-store brand interaction to a purchase decision changed in the last few years, particularly with Gen Z consumers?

A:
Once Gen Z is standing in the store, the phone doesn’t go away; it becomes part of the decision. Gen Z expects a frictionless omnichannel shopping experience, using their phones to compare prices, check reviews, and browse online while shopping in physical stores.

Gen Z might discover a product on social, price-compare in-app, and transact in-store, meaning the “research” phase doesn’t end when they walk through the door. They’re often pulling up reviews, comparing prices against other retailers, and checking whether a friend or influencer they trust has posted about the exact item in their hand. In fact, they may be crowdsourcing the decision on social from the try on room. It’s an entirely different decision-making process than prior generations.

For brands, that changes what physical stores need to deliver. It’s no longer competing against other brick-and-mortar shops; it’s competing against whatever’s on the shoppers’ screen in that moment. QR codes, in-store social proof, and staff who can speak to what’s being said online now matter as much as the product display itself.

Vitaly Gariev photo
Vitaly Gariev photo

Q: You’ve said winning brands think more like experience designers than merchandisers — what does that mindset look like in practice? 

A: Thinking like an experience designer means starting with the feeling you want to leave someone with, then building backward from there, rather than starting with shelves and merchandise and hoping something sticks. Where a merchandiser thinks about placement, an experience designer thinks about the story someone is walking into, what they’ll touch, how they’ll move through the space, and what they’ll want to share after. The best retailers are already doing that. They’re paying attention to the areas shoppers gravitate toward, where they slow down, and what they come back to.  

Q: With in-store retail media spending rising so quickly, how should brands measure ROI and determine whether an experiential campaign is truly effective?

A: In-store retail media is growing fast. In-store retail media ad spending in the U.S. is forecasted to grow an average of 31% through 2028. With that much money invested, brands need real proof it’s working. That means tracking a full stack of signals together: foot traffic lift against pre-campaign baselines, dwell time in the experience zone, conversion from engagement to purchase, and customer acquisition cost compared to other channels.

The real shift is connecting the in-store moment to what happens after someone leaves. If someone shows up to an event, then buys something in an email follow-up, or online a week later, or back in-store next month, that all counts as one connected result. Loblaw and Sam’s Club, for example, now have systems that follow a consumer’s activity for months after an event, so brands can see what really worked long-term instead of guessing. Brands that get the most out of experiences are the ones that decide upfront, before the event ever happens, what they’re trying to achieve and how they’ll know if it worked.  

More from Retail Insider:

Daily Synopsis: July 14, 2026

Welcome to the Daily Synopsis by Retail Insider. We highlight key developments in Canadian retail across 9 articles published today.

Hong Kong-based Bakebe found early success at CF Markville with its interactive baking experience appealing strongly to families, illustrating growth in experiential retail. Meanwhile, Canadian wholesale and retail employment rebounded in June but is still nearly 72,000 jobs below last year’s level, raising workforce concerns amid sector expansion efforts.

Retailers like Aritzia and Group Dynamite are outperforming by focusing on affluent younger women, showing strong sales growth and profit margins. Canadian retailers also face a new challenge with shoppers increasingly using AI for product discovery, requiring enhanced content and data to remain competitive. Optional coverage highlights youth job growth led by the restaurant sector and financial pressure on Canadians impacting discretionary spending.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

How to Choose a Room Air Conditioner Brand in 2026: What Actually Matters Beyond the Label

Shopping for a room air conditioner has become more complicated than simply comparing BTU ratings or choosing the brand you’ve heard of before.

Today’s buyers face a growing range of window air conditioners, inverter systems, smart features, and energy certifications. At the same time, manufacturers are solving different problems in different ways. Some focus on quieter operation, others on installation flexibility, while others invest in smarter controls or improved energy efficiency.

As a result, choosing a room air conditioner brand in 2026 is less about finding a single “best” company and more about choosing the brand whose design philosophy best matches your home, your room, and how you actually use an air conditioner.

Start With Your Room, Not the Brand

One of the biggest mistakes consumers make is choosing a brand before understanding what their room requires.

A bedroom, a home office, a studio apartment, and a large living room all present different cooling challenges. Room size, window type, sun exposure, insulation, ceiling height, and even how often doors are opened can influence how an air conditioner performs.

Before comparing manufacturers, it helps to answer a few practical questions:

Is a window air conditioner compatible with your window?

Do you rent or own your home?

How many hours will the unit operate each day?

Is indoor noise an important consideration?

Do you want remote or voice control?

These factors often have a greater impact on satisfaction than the brand name on the front panel, so the right choice starts with the room, not the label.

Look Beyond Cooling Capacity

Cooling capacity remains important, but it is only one part of the buying decision. A better comparison looks at how a unit performs over time, not just how much cooling power it lists.

Modern room air conditioners are increasingly evaluated on how efficiently they maintain comfortable temperatures rather than on how quickly they reach them.

For many households, inverter technology has become one of the most meaningful developments in recent years. Unlike traditional fixed-speed compressors that repeatedly start and stop, inverter systems continuously adjust compressor speed to match changing cooling demand. The result is typically more stable indoor temperatures, improved energy efficiency, and quieter day-to-day operation.

Rather than asking whether a unit has the highest BTU rating, buyers may benefit more from asking how consistently it performs throughout an entire day of use.

Good Product Design Solves Everyday Problems

Technical specifications rarely tell the whole story. The real difference often appears in how design choices solve everyday problems.

Many of the most noticeable improvements in room air conditioners now come from engineering decisions that address everyday inconveniences.

For example, traditional window air conditioners often prevent the window from opening after installation. Some newer designs approach that limitation differently, subject to window compatibility and proper installation, while positioning portions of the system farther from the indoor living space.

Air conditioners have also evolved beyond simply increasing cooling capacity. Airflow management, installation design, and controls now play important roles in overall performance, particularly in rooms where maintaining steady comfort becomes more challenging.

These kinds of design choices may not stand out on a specification sheet, but they often become the features owners appreciate most after several months of daily use.

Smart Features Should Be Practical

Wi-Fi connectivity has become increasingly common across home appliances, but not every smart feature adds meaningful value. The key question is whether the feature fits naturally into daily cooling needs.

The most useful systems simplify everyday cooling rather than adding unnecessary complexity.

Remote scheduling, temperature adjustments before arriving home, voice control through existing smart-home ecosystems, and maintenance reminders can all improve the ownership experience when they integrate naturally into daily routines.

Consumers may find it more useful to evaluate how well smart features fit their lifestyle than simply checking whether an app exists.

Independent Recognition Carries More Weight Than Marketing Claims

Air conditioner brands often describe themselves using terms such as “leading,” “innovative,” or “No. 1.” Those statements should be evaluated in light of any supporting independent research with clearly defined methodologies. That is why the details behind a claim matter as much as the claim itself.

When evaluating brand claims, consumers may wish to consider several questions:

Who conducted the research?

What product category was measured?

Was the ranking based on production volume or retail sales?

What years were included in the study?

Is the claim still within its stated validity period?

Understanding the scope behind a claim is often more valuable than the headline itself.

For example, Midea’s own marketing materials reference a Euromonitor International recognition related to residential inverter air conditioners. As with any brand-cited ranking, that claim should be read against its exact source, product category, measurement basis, research period, and validity period — it should not be interpreted as overall market leadership across every room air conditioner category. It is most useful here as an example of how context shapes the meaning of a claim.

Innovation Often Shows Up in Everyday Use

Consumers rarely experience “innovation” through marketing language. They experience it while living with a product, through the details that shape everyday use.

A quieter bedroom at night.

A window that may allow the window to open and close after installation, when properly installed in a compatible window.

Cooling that may feel more consistent throughout the afternoon.

An air conditioner that better maintains indoor comfort during extended operation.

These improvements are often the result of engineering decisions that receive far less attention than BTU numbers but can have a greater influence on long-term satisfaction.

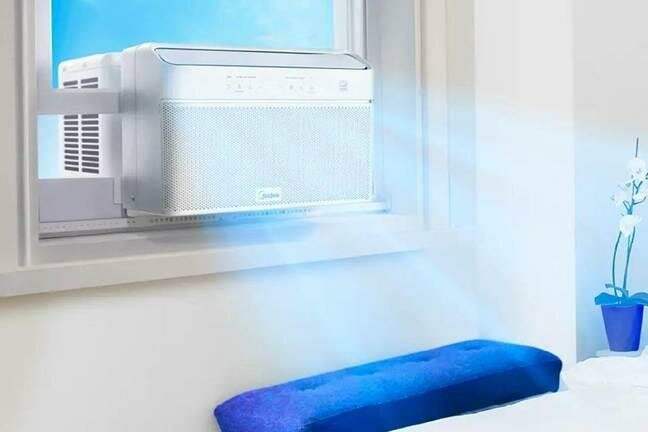
The Midea U-Shaped Smart Inverter Window Air Conditioner illustrates this approach by combining inverter technology with a U-shaped structure that may allow the window to open and close after installation, subject to window compatibility and proper setup. Likewise, the Midea DUO uses a

hose-in-hose airflow design intended to help improve room cooling, with the 12,000 SACC configuration designed for spaces up to approximately 550 square feet (based on manufacturer testing; actual performance and coverage may vary depending on room characteristics, installation, and operating conditions).

Rather than representing isolated features, these products reflect the broader point of this article: buyers should focus on brands that solve practical household challenges rather than simply increase cooling capacity.

A Better Way to Compare Brands

Instead of asking which company builds the “best” room air conditioner, consumers may find it more useful to compare brands using a consistent set of criteria. A simple framework makes that comparison easier to apply.

Consider questions such as:

Does the product fit the room size?

Does the installation work with your living situation?

Does the design address common usability issues?

Does it include technology that improves everyday comfort?

Are important claims supported by independent sources?

Looking at brands through these practical considerations often leads to more informed purchasing decisions than relying solely on popularity or advertising.

Final Thoughts

The room air conditioner market continues to evolve as manufacturers compete on more than cooling capacity alone. The result is a market where efficiency, thoughtful engineering, smart-home integration, and independently verifiable product leadership all matter more than they once did.

Efficiency, thoughtful engineering, smart-home integration, and independently verifiable product leadership have become increasingly important factors in how consumers evaluate brands.

Rather than searching for a universal winner, buyers in 2026 are likely to make better decisions by identifying which products solve the problems that matter most in their own homes. In that context, choosing a room air conditioner brand becomes less about the unit’s logo and more about the experience the product is designed to deliver. The clearest takeaway is simple: choose the brand that best fits your room, your needs, and your daily use.

Product performance, energy usage, noise levels, cooling coverage, smart-feature functionality, and user experience may vary depending on product specifications, installation, room characteristics, environmental conditions, and individual usage patterns. Consumers should review product specifications and claim disclosures before purchase from midea.com .


Why Emotional Resilience Is Becoming Retail’s Must Valuable Skill

Various skills are required to succeed in the retail industry, particularly when handling customer-facing roles. Previous generations always felt that the most valuable skill for a retail employee was the ability to talk face-to-face with someone and provide them with good customer service. It revolved more around some of the “traditional” skills you see in a job interview, but the retail industry of today faces more challenges than ever, and this has led to the emergence of a specific skill that should now be at the forefront of every retailer’s mind: emotional resilience. 

What is Emotional Resilience?

Most people have heard of the concept of emotional intelligence, but emotional resilience is slightly different. According to one of the experts on this topic, Dr Jodie Lowinger, emotional resilience refers to a person’s ability to adapt to emotionally demanding situations while being able to function effectively. 

Importantly, this does not mean that someone is immune to being affected by stressful situations at work. The critical aspect of emotional resilience is that you’re able to process these situations and push through them without developing any long-lasting mental health issues. 

In a retail environment, it’s easy to see how someone’s emotional resilience can be tested. All it takes is one angry or unhappy customer screaming at you to create a very stressful situation. Someone without emotional resilience may take this interaction and see the following results: 

  • They lash out at the customer because they can’t take it anymore
  • They handle the situation well but then break down afterwards, and it impacts the rest of their day

An emotionally resilient person can deal with this horrible interaction, acknowledge that it was stressful and awful to deal with, but then recover from it without letting the situation impact their day or their performance at work. 

Why Emotional Resilience Matters in Retail

Emotional resilience can be a valuable skill in all aspects of life, but it is particularly important in the retail sector for several reasons. To begin, retail is one of the main industries that involves a lot of face-to-face or one-on-one interactions. This means that customer interactions are bound to be more stressful automatically – but there’s one key piece of research that underpins why emotional resilience is more important now than ever. 

Customer Care Measurement & Consulting released its latest National Customer Rage Survey towards the end of last year (2025), and it found two damning statistics: 

  • 77% of consumers experienced a problem with a product or service in the past 12 months
  • 64% of those who reported an issue said they felt “rage” – and 50% of these consumers stated that they raised their voice

For retail workers, this means two things: customers are more frequently complaining about products/services, and they’re also getting angrier while they do it. Being a retail worker now means you have to prepare for the fact that you might get screamed at, even if you’ve done nothing wrong. 

If you are unable to deal with frequent conflicts, then you are unlikely to be able to do your job. Moreover, there are consequences that happen when employees don’t have the emotional resilience to deal with angry or upset customers. 

The Consequences of No Emotional Resilience

Retailers with a team of emotionally resilient workers tend to see more success than those who lack this skill. Why? Because the inability to stay resilient in the face of emotionally demanding situations can lead to the following: 

  • Losing customers: Someone who can’t deal with an angry customer and may lash out at them will result in that customer leaving and never returning. Even worse, that customer may post negative reviews online that convince other customers to leave – and prospective ones to stay away. It can all stem from someone being unable to keep their cool in the face of adversity. Is it fair to the employee? No, but that’s why emotional resilience is such a valuable skill. 
  • Losing employees: What’s more likely to happen in these situations is that the employee simply deals with the barrage of abuse they get from a customer until the conflict is resolved as well as possible. While this may not result in negative reviews, it could well result in the employee having an emotional breakdown. They can’t handle the stress anymore, and they decide to leave. This can happen more often than you realise, leading to high employee turnover for your retail business. Turnover costs money and destabilises a business, which is yet another reason that emotionally resilient employees are worth their weight in gold. 

It is, essentially, a double-edged sword for retail companies. Poor levels of emotional resilience can cost money and reduce profits, either from bad customer service creating negative reviews or employees quitting because they can’t handle the pressure. 

How To Develop Emotional Resilience in a Retail Team

Hiring people who display the key signs of emotional resilience will be the best approach, but this is also a skill that anyone can learn and develop. For retail teams, it’s normally a case of: 

  • Talking openly about stress and providing key stress management ideas to employees
  • Learning how to regulate emotions in high-pressure situations
  • Improving shift management and encouraging regular breaks

The most important thing is to make it clear that your retail employees shouldn’t try to suppress their stress or emotions. It’s all about learning how to regulate them during conflicts and then finding ways to deal with them after. That’s why breaks are so important for a retail team: improve scheduling so staff can take more frequent breaks, especially during busy periods, allowing them time to relax and cool down. If you can create a supportive work environment, then that also helps, as everyone can look after one another. 

Emotional resilience isn’t about keeping your emotions inside and pretending that you’re not bothered by highly stressful situations. That’s incredibly unhealthy and will lead to burnout and long-term mental health concerns. Instead, it has become the most valuable skill in retail because it enables workers to deal with conflicts and push on through difficult situations without letting the stress get to them. 

Emily Fernandez and Evolve Med Spa Grow With Precision

A company can get bigger without becoming more memorable. Evolve Med Spa has tried to do the opposite, building a brand that clients recognize through the experience itself as much as the name on the door. Emily Fernandez has guided that work as co-founder and VP of operations, helping the company grow from one location in Hoboken to 14 locations across New York, New Jersey, Pennsylvania, and Maryland.

That kind of growth matters more in a field where people are often seeking medical aesthetics, medical spa treatments, aesthetic medicine, clinical skincare, and non-surgical rejuvenation with a high level of expectation already in place.

Evolve Med Spa Built a Regional Name From One Local Start

The business opened in 2020, a year that demanded unusual resilience from any company built around in-person treatment. Evolve Med Spa formed an early bond with clients in Hoboken, NJ and that local support gave the brand real momentum. One location soon became the start of a much wider regional presence.

That expansion held together through a leadership team that kept operations close to the client experience. Each new location carried the same expectations around communication, order, and care. Growth moved forward with a clear sense of continuity from the first office onward.

That discipline has become part of what clients now associate with the brand. Emily helped build that structure alongside Dr. Oz Fernandez, co-founder and medical director, and Austin Jacobus, co-founder and VP of clinical.

Their roles gave the company a clear internal balance. Operations, medical direction, and clinical education all moved together, which gave Evolve Med Spa a steadier foundation as new locations opened. In an industry where growth can stretch systems thin, that alignment became part of the company’s signature.

Emily Fernandez, Austin Jacobus and Dr. Oz Ferneandez Helped Turn Consistency Into a Growth Strategy

Consistency can sound simple until a company starts scaling. A second center asks for stronger communication. A fifth center raises the stakes even higher. By the time a brand reaches 14 locations, every weak point becomes easier to spot. Fernandez helped guide Evolve Med Spa through that pressure by treating growth as an operational question as much as a branding one.

That discipline has helped the company hold onto a recognizable identity across its footprint. Clients may arrive for dermal fillers, neurotoxin treatments, or microneedling, but they’re also stepping into a company culture built around client-centered experience, clinical expertise, and professional skincare protocols.

Recognition Followed the Company’s Expansion

The company’s rise has drawn attention across several markets. Evolve Med Spa has collected repeated honors for Best Med Spa, along with category wins tied to fillers, injectables, and facials from The Hoboken Girl and The Montclair Girl. It has also earned Best of New Jersey, Best of Bridgewater, and other regional territories connected to its footprint.

A two-page regional feature in the May 2026 issue of Vogue added another layer of visibility. That kind of placement gave the brand a high-profile editorial signal, though it also reflected something the company had already been building for years: a name associated with strong standards, local trust, and a clear point of view about equality.

Evolve Med Spa Keeps Its Eye on the Long Game

Fernandez has described the company’s larger vision in terms of growth without dilution, and that goal runs through the full story of Evolve Med Spa. The brand began with one office and a close connection to its first clients. Today it stands as a 14-location company with a broader reach and an even bigger test in front of it: carrying the same care, standards, and sense of purpose into each new chapter.

That’s what gives the company’s story its pull. Evolve Med Spa has grown quickly, though its strongest message lives in how carefully it has handled its growth. For Emily Fernandez, that discipline has become a defining part of the brand itself.

Retail Insider “Luxury Report”: Control, Concentration and the Rise of Canada’s Premier Retail Nodes

Canadian luxury retail is becoming increasingly concentrated around a relatively small number of premier destinations, with brands placing greater emphasis on flagship stores, customer relationships and curated retail environments. Those trends are explored in Q2 2026 Luxury: Control, Concentration and the Rise of Canada’s Premier Retail Nodes, authored by Craig Patterson as part of Retail Insider Reports. Retail Insider Reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

The report examines Canada’s luxury retail market, including brands positioned at the highest end of the market and characterized by exceptional craftsmanship, heritage, exclusivity, prestige and premium customer experiences. Coverage spans luxury fashion, jewellery, watches, beauty, accessories and related retail developments, while exploring how investment, real estate strategy and customer engagement continue to evolve across the sector.

General Themes

  • Investment Concentrates Around Premier Nodes – Luxury brands are directing investment toward a select group of highly productive retail destinations rather than pursuing broad expansion.
  • Flagships Take Priority – Directly operated flagship stores are giving brands greater control over merchandising, pricing, inventory and customer relationships.
  • Luxury Geography Is Shifting – New mixed-use developments and established luxury districts are reshaping where international brands choose to invest.
  • Experience Drives Differentiation – Hospitality, clienteling and immersive store environments are becoming increasingly important competitive advantages.
  • Resale Continues to Mature – The secondary luxury market is broadening access while becoming a complementary part of the luxury ecosystem.
  • People Matter More Than Ever – Store execution, relationship building and product expertise continue to distinguish leading luxury retailers.
  • Canada Remains Attractive – Despite softer global luxury conditions, international brands continue to view Canada as a long-term strategic market.

Retail Insider Coverage

Retail Insider’s reporting throughout the quarter documented many of the developments that underpin the report’s conclusions. Coverage followed the opening of Vancouver’s Oakridge Park, expansions by Brunello Cucinelli, the continued evolution of luxury retail in Yorkville, the arrival of international brands including Chow Tai Fook, and Canada Goose’s new retail concept. The publication also examined changing luxury retail practices through features on store execution and staffing, illustrating how operational excellence has become central to premium retail performance.

Additional reporting covered developments in luxury resale through Mine & Yours and Angels Wear Preloved, digital expansion by luxury beauty retailer Rennaï, and major flagship investments across Canada’s leading luxury markets. Together, these stories reveal an industry placing greater emphasis on destination quality, customer relationships and long-term brand stewardship rather than rapid store growth.

Broader Industry Coverage

The report suggests that Canada’s luxury market is entering a more mature phase in which a handful of retail ecosystems command an increasing share of investment. Integrated developments that combine retail, residential, hospitality, dining and public spaces are becoming increasingly attractive to international brands seeking locations capable of supporting premium experiences and long-term customer engagement.

The findings also extend beyond luxury retail itself. They point to broader changes in commercial real estate, leasing strategy and retail operations as brands seek greater ownership of distribution, customer data and merchandising. At the same time, luxury resale, omnichannel engagement and elevated service expectations continue to influence how retailers compete for affluent consumers across multiple categories.

Editor’s Take

Luxury retail in Canada is becoming increasingly selective. Rather than measuring success by store count alone, brands are concentrating investment where they can achieve greater control over the customer experience and operate within highly productive retail ecosystems. Oakridge Park exemplifies this shift, while Yorkville, Yorkdale and emerging luxury districts in Calgary and Montreal demonstrate that competition is increasingly centred on quality of location, operational execution and long-term relationship building rather than expansion for its own sake.

Conclusion

The full Q2 2026 Luxury: Control, Concentration and the Rise of Canada’s Premier Retail Nodes explores these trends in greater detail, examining the companies, developments and market forces shaping Canada’s luxury retail sector. Readers can access the complete report, along with the full collection of Retail Insider Reports, through the Retail Insider Report Hub.

Bakebe Finds Early Success at CF Markville as Experiential Retail Continues to Grow

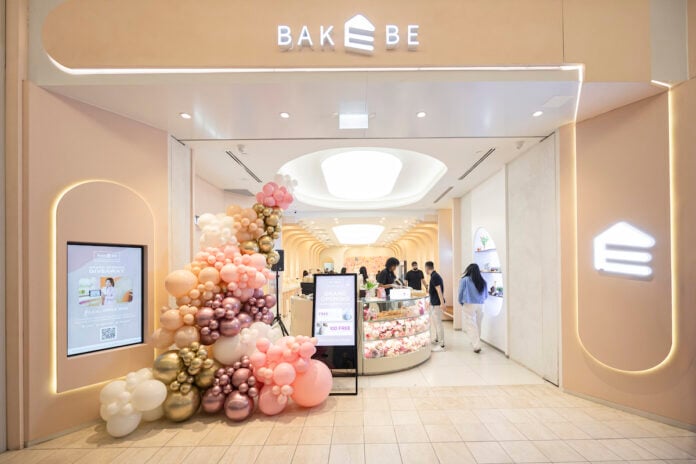
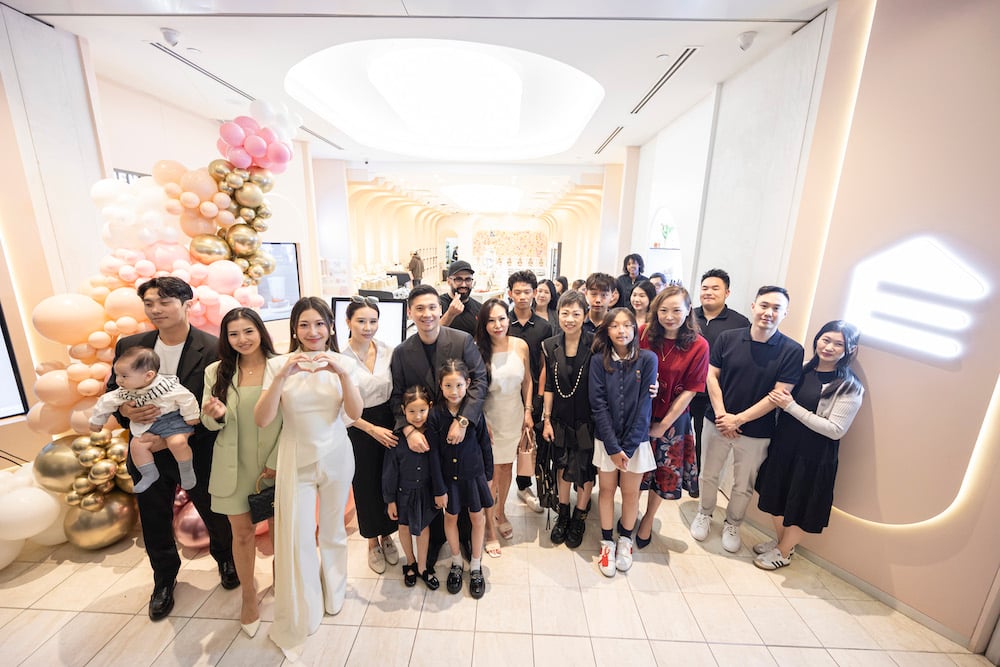
Bakebe grand opening at CF Markville in Markham, ON. Photo: Hubert Hua, AWeek Marketing

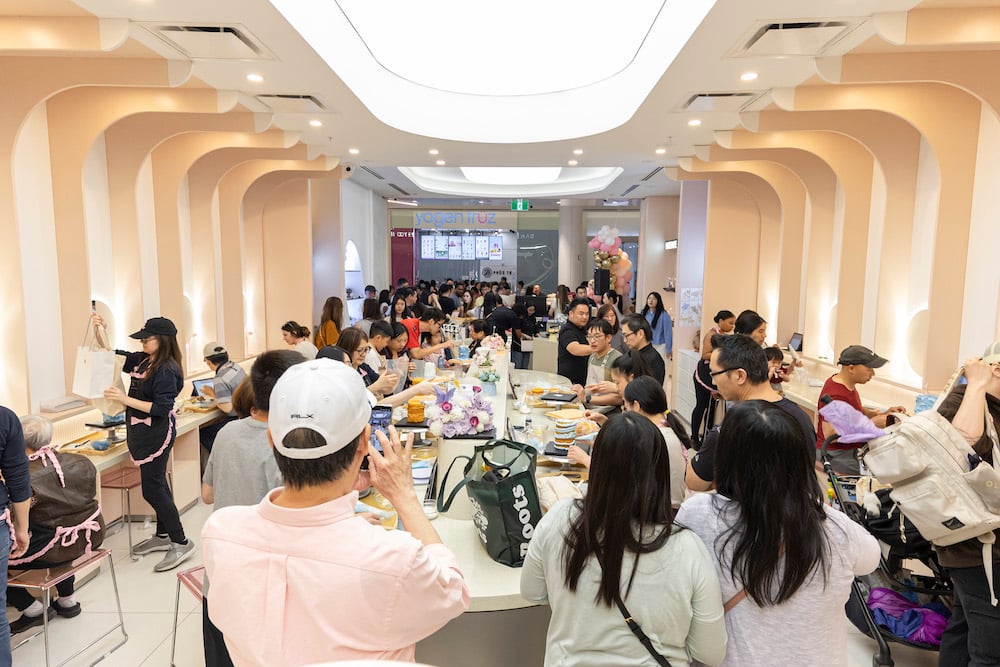
Hong Kong-based Bakebe has officially entered the Canadian market, opening its first Canadian and North American location at CF Markville in Markham with a concept that reflects a broader shift in how shopping centres are evolving. Within days of opening, the interactive baking studio found that Canadian families had become its strongest customer segment, while custom birthday cake pre-orders exceeded internal projections by 40 percent.

The early response offers another example of how regional shopping centres are expanding beyond traditional retail by introducing tenants that encourage customers to spend more time at a property through interactive, experience-driven activities. Across Canada, landlords continue to diversify their tenant mix with concepts centred on entertainment, wellness, food, recreation, and social engagement, recognizing that many consumers increasingly value memorable shared experiences alongside shopping.

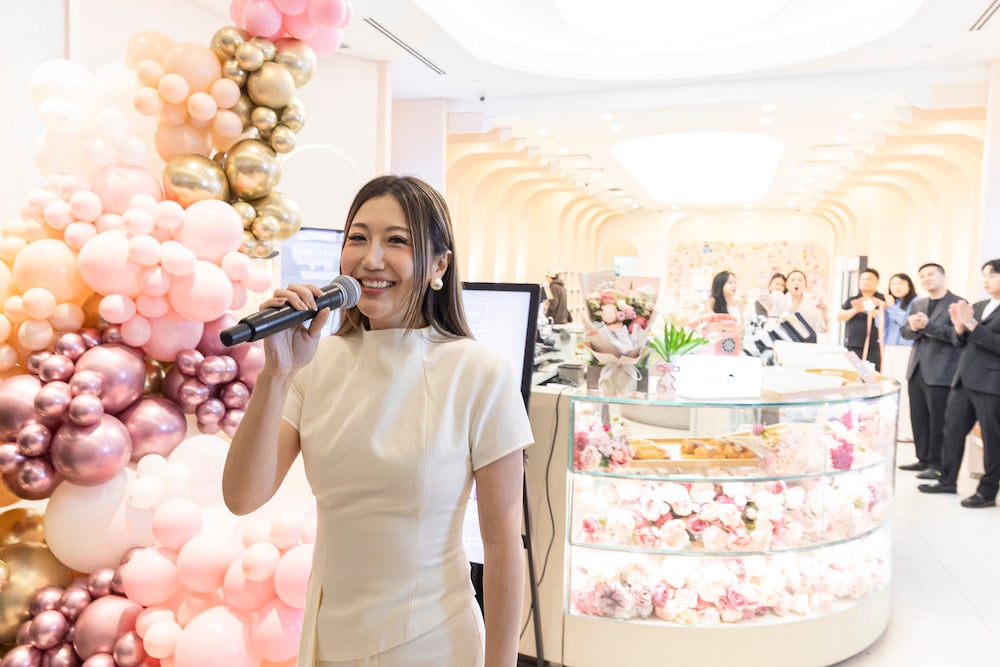
For Bakebe founder and CEO Venus Chi, the Canadian launch has reinforced the universal appeal of the concept, which has already expanded from Hong Kong into Malaysia and the Philippines.

“What surprised me most is how warmly local families have embraced us,” Chi told Retail Insider. “At first, I thought young adults might be our main guests, but we quickly saw so many parents and children signing up for baking sessions together.”

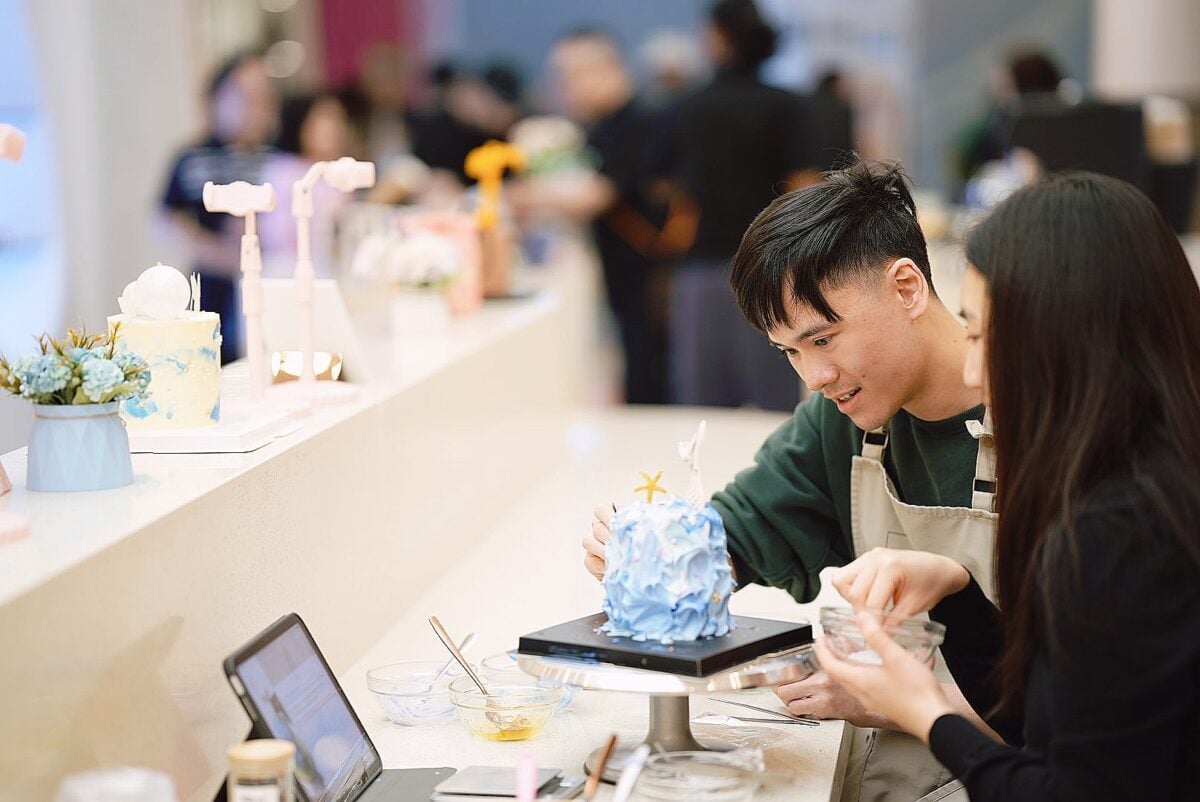
Founded in Hong Kong in 2018, Bakebe introduced an app-guided co-baking concept that allows guests to prepare cakes and desserts using interactive digital instructions at fully equipped workstations. Visitors choose a baking or decorating project, with all ingredients and equipment provided on-site while staff remain available to assist throughout the process. The model removes many of the barriers associated with traditional baking classes, making the experience accessible to beginners while still appealing to more experienced home bakers.

Bakebe’s Canadian expansion is being supported by Toronto-area-based Accencis Group, a brand development, investment and operating company that helps introduce international consumer and hospitality brands to the Canadian market. Bakebe joins a growing portfolio that includes brands such as % Arabica, Rumble Boxing, Midori Ramen and The Captain’s Boil.

Venus Chi speaks at Bakebe’s grand opening at CF Markville in Markham, ON. Photo: Hubert Hua, AWeek Marketing

Markham Offered the Right Foundation for Canadian Expansion

While the Greater Toronto Area represented a logical first step into Canada, Chi said CF Markville offered a combination of demographics, accessibility, and community that aligned closely with Bakebe’s long-term vision.

“CF Markville felt like the right place to begin our Canadian journey because it is surrounded by such a vibrant and family-oriented community,” she said. “Since Bakebe started in Hong Kong, it was meaningful for us to open in Markham, where many people already have a connection to Hong Kong culture and could understand the heart of our brand.”

Markham’s diverse population and strong family demographics made it an attractive launch market, while CF Markville’s established position as one of York Region’s leading regional shopping centres provides Bakebe with access to customers who already visit the property for shopping, dining, and leisure activities.

Rather than viewing the Canadian studio simply as another international location, Chi said the goal is to establish Bakebe as a place where people celebrate milestones and spend quality time together.

“We are creating a warm space where families, friends, couples, and groups can connect through baking,” she said.

Bakebe grand opening at CF Markville in Markham, ON. Photo: Hubert Hua, AWeek Marketing

Early Customer Behaviour Is Shaping the Canadian Business

The opening has already influenced how Bakebe approaches the Canadian market.

After observing guest behaviour during the launch, the company expanded activities designed specifically for groups, including parent-child baking experiences that previously proved successful in Hong Kong, along with colourful cupcake decorating sessions for couples and friends.

Bakebe has also broadened its food and beverage offering with fresh pastries from DUO Café and premium handcrafted drinks, encouraging guests to relax before or after their baking session.

Chi said Canadian customers have also shown strong interest in ingredient quality and allergy-conscious options.

“They care deeply about the details, from the recipes to options that feel safe and thoughtful for their families, such as nut-free and low-allergen choices,” she said.

The company believes these observations will continue shaping its Canadian operation as it introduces new programming and seasonal experiences.

Venus Chi with partners from Accencis group and family members at the Bakebe grand opening at CF Markville in Markham, ON. Photo: Hubert Hua, AWeek Marketing

More Than a DIY Baking Studio

Although Bakebe is best known for its app-guided workshops, the Canadian operation is built around multiple complementary revenue streams.

Free-style cake decorating workshops became the studio’s most popular offering during the opening period. These express sessions provide prepared cake bases, allowing guests to focus on decorating and creative expression instead of baking from scratch.

“Our free-style cake decorating workshops ranked number one,” Chi said. “Most guests don’t come here to produce a flawless cake. They just want to relax and enjoy themselves.”

The business also offers custom cakes through advance ordering as well as ready-made cakes available for walk-in customers. According to Chi, custom birthday cake pre-orders exceeded the company’s original expectations by approximately 40 percent during the launch.

Private events are expected to become another important component of the business. Bakebe is already hosting birthdays, family celebrations, and brand activations, with bridal showers, corporate team-building sessions, and other group events expected to contribute to future growth.

“What makes these events special is that guests are not just standing around or taking photos,” Chi said. “They are decorating, laughing, sharing ideas, and creating memories through a hands-on experience.”

For shopping centres, concepts like Bakebe offer advantages beyond individual customer visits. Birthday parties, corporate bookings, holiday programming, and repeat workshops create multiple reasons for guests to return throughout the year while often bringing groups of visitors to a property who may also shop or dine before and after their scheduled activity.

Bakebe grand opening at CF Markville in Markham, ON. Photo: Olivia Hon

Experiential Retail Continues to Expand

Bakebe’s arrival reflects a broader evolution taking place across Canada’s shopping centre industry.

As retailers compete with the convenience of online shopping, many landlords are introducing businesses that cannot easily be replicated digitally. Interactive food concepts, entertainment venues, fitness operators, and immersive attractions are increasingly complementing traditional retailers, helping transform shopping centres into destinations where consumers can spend an afternoon rather than simply complete a transaction.

Chi believes that shift is evident in customer behaviour.

“I think young people are looking for more than shopping when they visit a mall today,” she said. “They are looking for places where they can spend meaningful time with friends and loved ones.”

She added that Bakebe gives visitors “a reason to pause, gather, create, and enjoy something together,” turning a shopping trip into a shared activity that extends beyond a retail purchase.

Bakebe grand opening at CF Markville in Markham, ON. Photo: Olivia Hon

Growth Plans Focus on Building Local Connections

Looking ahead, Bakebe plans to strengthen its presence in the Greater Toronto Area before pursuing broader expansion across Canada. While the company has previously identified Vancouver, Montreal, and Calgary as potential long-term markets, Chi said the immediate priority is establishing a strong foundation in Ontario.

Expansion will involve more than opening additional studios. Bakebe plans to introduce seasonal workshops tied to holidays, collaborate with local brands and retailers, and develop relationships with schools, community organizations, and neighbourhood groups.

“Our hope is that Bakebe becomes more than a one-time visit,” Chi said. “We want it to become part of the community.”

The performance of the Markham location will likely help shape the company’s Canadian growth strategy in the years ahead. If the early response continues, Bakebe could become another example of how international experiential retail concepts are finding opportunities within Canada’s evolving shopping centre landscape while demonstrating that consumers continue to seek destinations that combine creativity, hospitality, and shared experiences.

More from Retail Insider: