Home Blog Page 86

Cozey expands sleeper sofa category with two new products

Cozey photo
Cozey photo

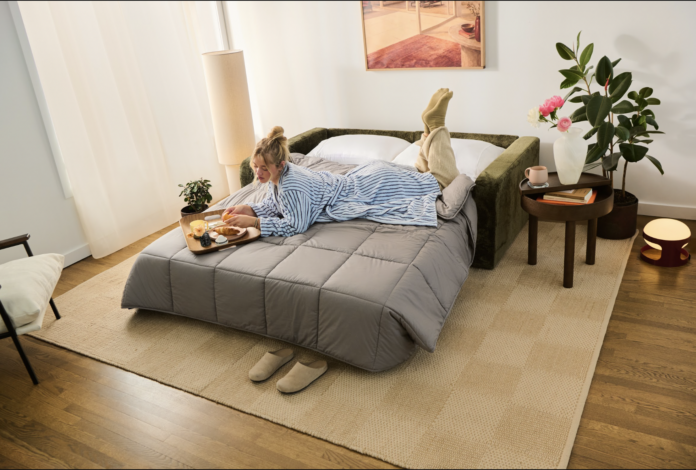
Montreal-based furniture company Cozey is expanding its sleeper sofa category with two new products, the Orian Sofa Bed and the Atmosphere Sofa Bed, as it broadens its range of multifunctional furniture.

The launches add sleeper functionality to two different designs, including an existing modular collection, with the company positioning the products as options for customers looking to accommodate guests or make more efficient use of living space.

Two new sofa beds

The Orian Sofa Bed combines a compact modular design with a contemporary silhouette and converts from a sofa into a queen-size bed using a pull-out mechanism.

The product is available with optional storage modules and comes in five colourways across Chenille, Aquaforte™ and Performance fabrics. It starts at $1,395 CAD for a two-seater.

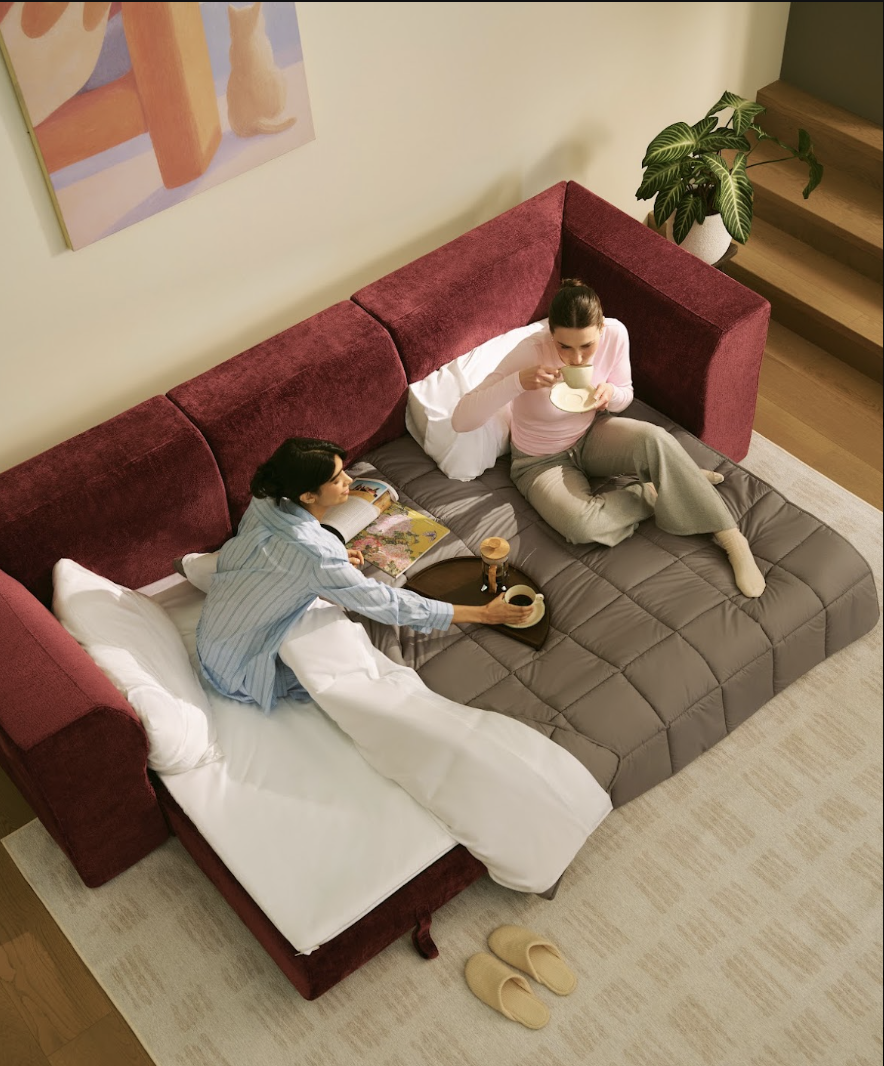
The Atmosphere Sofa Bed extends Cozey’s Atmosphere modular collection with an integrated sleeper option. The company says it is the first time sleeping functionality has been incorporated into the collection.

The Atmosphere Sofa Bed is available in more than 15 colourways across Corduroy, Chenille and Performance fabrics. Customers can select from four arm configurations: High Angled Square, Regular Square, Rounded or Armless.

The product starts at $2,290 CAD for a two-seater.

Frédéric Aubé, Founder and CEO of Cozey

“The way people use their homes has changed significantly over the past few years, and we’re seeing growing demand for furniture that works harder without sacrificing design,” said Frédéric Aubé, CEO and Founder of Cozey. “With the Orian and the Atmosphere Sofa Bed, we’re evolving the category with solutions that are intuitive, beautifully designed, and adaptable in ways that support everyday living, whether you’re furnishing a smaller space or simply looking for more flexibility at home.”

Building on earlier sleeper sofa

The two launches follow the introduction of Cozey’s Neptune Sofa Bed in 2023, the company’s first sleeper sofa.

According to the release, the Neptune was developed with a mechanism that allows it to convert into a queen-size bed without a bulky pull-out system and without requiring additional modules or ottomans.

The Atmosphere Sofa Bed also expands an existing modular collection that includes additional storage modules, giving customers more configuration options within the line.

Cozey photo
Cozey photo

The company says the new products are part of its broader expansion across furniture categories, with a focus on multifunctional designs intended to accommodate different uses within the home.

Cozey describes itself as a North American furniture company focused on customer-centric design, quality and innovation. The company says its mission is to make adaptable and timeless furniture accessible to consumers, while also emphasizing the well-being of its customers, employees and partners.

The new sleeper sofas add to that product strategy by combining seating and sleeping functions in two distinct designs and price points.

More from Retail Insider:

Equifax survey finds one in four Canadians expect to make only minimum credit-card payments

Vitaly Gariev photo
Vitaly Gariev photo

Nearly one in four Canadians surveyed by Equifax Canada say they expect to make only the minimum monthly payment on their credit cards, as more households report using credit and savings to cover everyday expenses.

The survey of 1,532 Canadians also found that seven per cent expect they will fall behind on their credit-card payments, while 56 per cent expect to pay their balances in full each month.

The findings point to growing financial pressure among some households, with 40 per cent of respondents saying they are spending more overall than they were a year ago, compared with 18 per cent who are spending less.

Credit and savings used for essentials

The survey found that Canadians are increasingly drawing on credit and savings to manage household expenses.

Twenty-nine per cent of respondents said they are using more credit than they were a year ago to pay for groceries, utilities and other essential living expenses. Another 23 per cent said they are drawing on savings to cover day-to-day costs, while 20 per cent said they are relying more on credit cards and lines of credit.

At the same time, 35 per cent said they have reduced contributions to savings, investments or education funds. Forty-four per cent said they worry they are not saving enough for retirement, while 41 per cent are concerned about unforeseen emergency expenses.

“The results point to mounting financial pressure for many households,” said Rebecca Oakes, Vice-President of Advanced Analytics at Equifax Canada. “The survey indicates that a significant percentage of Canadians surveyed (29 per cent) are using credit and savings to manage everyday expenses, while 35 per cent are cutting back on contributions to save for their future and expecting to make only minimum credit card payments. When these pressures begin to overlap, households can lose financial flexibility quickly.”

The survey also found that 32 per cent have reduced spending on essential living expenses, including groceries and utilities.

Discretionary spending also down

Canadians surveyed reported cutting back on discretionary expenses as well. Sixty-seven per cent said they have reduced spending on entertainment and leisure, while 40 per cent have cut spending on personal care.

The survey found that 60 per cent of respondents are actively avoiding taking on new debt. At the same time, 13 per cent said they are borrowing more to cover basic living expenses, while eight per cent said they are opening new credit cards or taking on new loans.

Financial confidence has also weakened. Twenty-nine per cent of respondents said they are less confident in their ability to manage financial demands than they were a year ago, compared with 23 per cent who said they are more confident. Forty-seven per cent said their confidence is about the same.

“Financial pressure often builds gradually, and making only the minimum payment can sometimes feel like a way to manage through a difficult month,” said Julie Kuzmic, Head of Consumer Advocacy and Compliance at Equifax Canada. “However, balances can take much longer to repay and cost considerably more in interest. Anyone seeing their balances continually rise with little hope at repayment should review payment obligations, prioritize due dates and explore options with their lenders or a reputable credit counsellor before their financial situation limits their options.”

Vitaly Gariev photo
Vitaly Gariev photo

Families, younger adults report greater pressure

Households with children reported greater financial pressure than those without children.

Fifty-one per cent of respondents with children said they are spending more than they did a year ago, compared with 35 per cent of those without children.

Among households with children, 42 per cent said they are using more credit than last year to pay for essential living expenses, compared with 24 per cent of households without children. Thirty-three per cent of respondents with children expect they will only be able to make minimum monthly credit-card payments.

Forty-five per cent of those with children said they are concerned about supporting family members, including children’s education or aging parents, compared with 18 per cent of those without children.

Respondents under 55 also reported greater financial pressure than older respondents. Thirty-six per cent of those under 55 said they are using more credit for essential expenses than they were a year ago, compared with 18 per cent of those aged 55 and older.

Among respondents under 55, 42 per cent said they are spending more overall than a year ago, compared with 36 per cent of those aged 55 and older. Thirty-one per cent expect they may only be able to make minimum monthly credit-card payments, compared with 16 per cent of older respondents.

Twenty-two per cent of respondents under 55 said they are struggling to pay down debt because of high housing or mortgage costs, compared with 11 per cent of those aged 55 and older.

Only 47 per cent of Canadians under 55 expect to pay their credit-card balance in full each month, compared with 69 per cent of those aged 55 and older.

More from Retail Insider:

Taco Bell brings Enchirito to Canada in limited Southwestern Ontario test

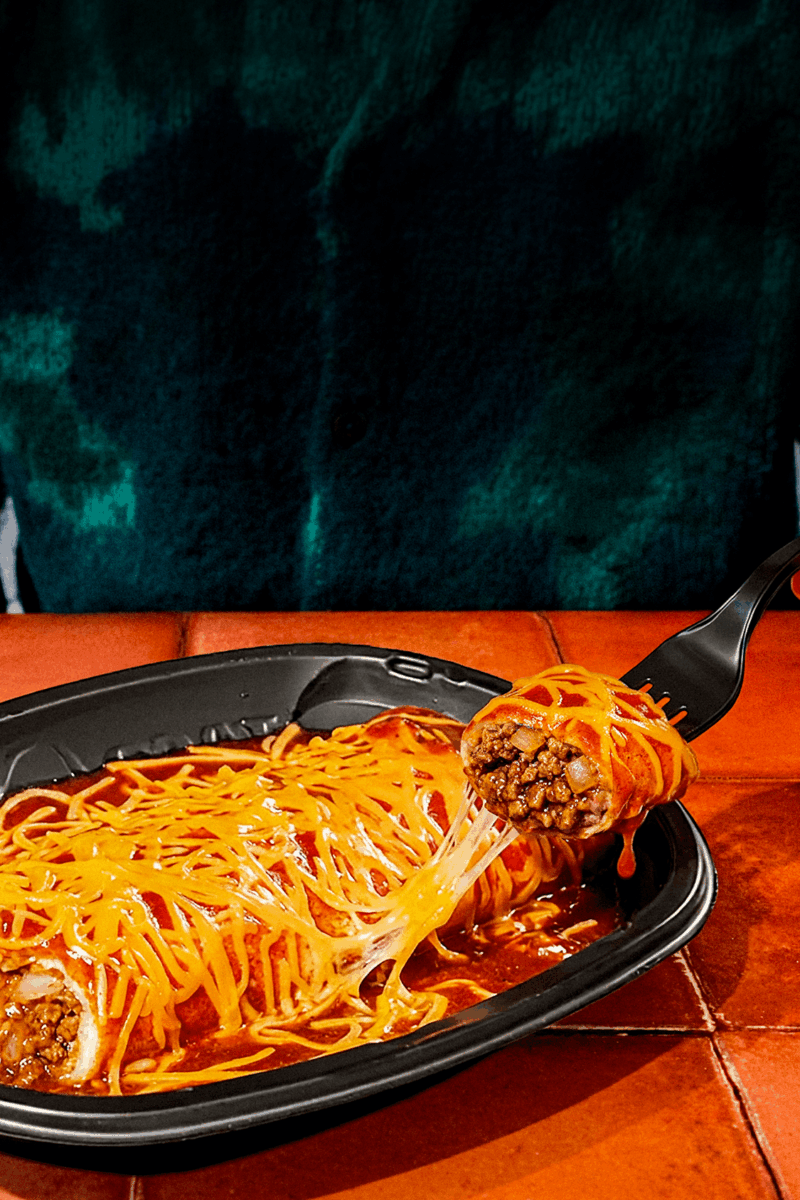
Image: Taco Bell Canada

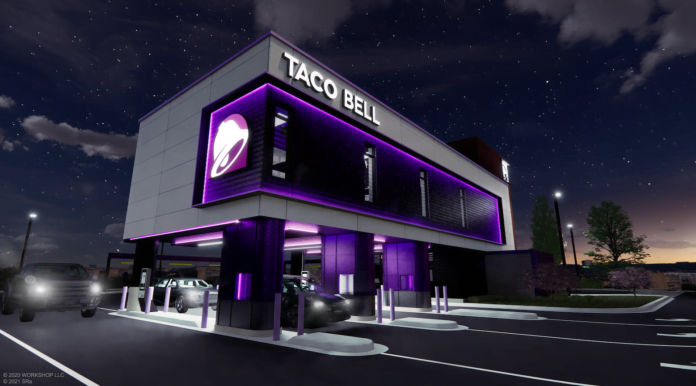
Taco Bell has brought the Enchirito to Canada for the first time, but only customers at 15 participating restaurants in Southwestern Ontario will be able to buy the menu item during a two-week launch.

The Enchirito is available for $3 plus applicable taxes from July 30 through Aug. 13 at restaurants in Amherstburg, Chatham, Kingsville, LaSalle, Niagara Falls, Sarnia, Wallaceburg and Windsor.

Limited rollout

Rather than introduce the item across its Canadian network, Taco Bell Canada is using the Southwestern Ontario launch as a controlled test of demand and restaurant operations.

“We know Canadians love discovering iconic Taco Bell menu items, so we wanted the Enchirito’s Canadian debut to feel special,” said Meera Patel, Director of Marketing. “We’re starting small. These communities get the first taste, and the bragging rights, and the response will help shape what happens next.”

The company says the limited rollout will allow it to assess guest demand, operational execution and overall performance before deciding whether to bring the Enchirito to other Canadian markets.

If the launch performs well, the item could be expanded to additional regions across Canada. Guest response during the promotion will help inform those future plans.

What customers are getting

The Enchirito, a Taco Bell menu item dating to the 1970s, combines elements of an enchilada and a burrito. It consists of a soft flour tortilla filled with seasoned beef, refried beans and onions, topped with red sauce and shredded cheddar cheese and heated until the cheese is melted.

“Being among the first restaurants in Canada to serve the Enchirito is an exciting moment for our teams and our guests,” said Puja Gupta, Franchisee of Gupta Foods. “We are proud to help introduce this Taco Bell icon to Canada and look forward to seeing the response across our communities.”

The $3 price applies at participating restaurants, while pricing may be higher through delivery platforms. Availability and participation may vary by restaurant.

Participating locations

The Enchirito is being offered at 527 Sandwich Street South in Amherstburg; 328 St. Clair Street in Chatham; 329 Main Street East in Kingsville; 3770 Montrose Road in Niagara Falls; 1337 London Road in Sarnia; 60 McNaughton Avenue in Wallaceburg; and 2301 Sandwich Parkway West in LaSalle.

The Windsor locations are 300 Tecumseh Road North, 301 Ouellette Avenue, 1655 Manning Road, 1790 Huron Church Road, 3058 Dougall Avenue, Devonshire Mall at 3100 Howard Avenue, 3419 Tecumseh Road East and 6707 Tecumseh Road East.

More from Retail Insider:

Plaza Retail REIT reports higher second-quarter profit

Plaza REIT photo
Plaza REIT photo

Plaza Retail REIT recently reported higher profit and operating income in the second quarter as leasing, rent increases and improved cost recoveries helped drive growth across its retail property portfolio.

The Fredericton-based real estate investment trust said that profit and total comprehensive income rose 31.2 per cent to $16.6 million in the three months ended June 30, compared with $12.7 million in the same period a year earlier.

Net operating income increased 4.3 per cent to $19.9 million from $19.1 million, while revenue rose 1.2 per cent to $32.2 million.

The results come as Plaza continues to adjust its portfolio, including selectively selling properties while directing capital toward developments, intensifications and other initiatives.

“We delivered solid growth through the first half of 2026, supported by continued execution across our portfolio,” said Jason Parravano, President and Chief Executive Officer.

“FFO (Funds From Operations) per unit increased to $0.105 for the quarter, $0.202 year-to-date, up 5.0% and 7.4% respectively, compared with the same periods in the prior year (or 8.3% year-to-date after adjusting for certain timing and severance impacts). AFFO (Adjusted Funds From Operations) per unit increased to $0.078 for the quarter, $0.152 year-to-date, up 16.4% and 7.0% respectively, compared with the same periods in the prior year (or 8.0% year-to-date after adjusting for certain timing and severance impacts). Our FFO and AFFO payout ratios also improved to 69.2% and 92.2% year-to-date, respectively, strengthening our financial flexibility and demonstrating that the structural changes made to the business over the past year are producing sustainable results and predictable growth.”

Operating results

Plaza said quarterly NOI (Net Operating Income) increased by $828,000 from a year earlier, with the gain attributed to higher revenue from leasing and rent escalations, as well as improved cost recoveries.

Same-asset NOI increased 2.7 per cent in the quarter and 2.3 per cent for the first six months of the year. Committed occupancy was 97.6 per cent.

“Operating fundamentals remained resilient. Total NOI increased by 4.3% for the quarter, 3.4% year-to-date, and same asset NOI increased by 2.7% for the quarter, 2.3% year-to-date. Committed occupancy remained strong at 97.6%, supported by continued tenant demand, contractual rent growth and leasing activity across our essential retail portfolio.”

For the six months ended June 30, revenue was $64.7 million, up 2.8 per cent from $62.9 million a year earlier. NOI increased 3.4 per cent to $38.7 million from $37.4 million.

The year-to-date increase in NOI was attributed to higher leasing revenue, rent escalations and improved cost recoveries, partly offset by higher operating expenses.

Portfolio and capital allocation

Plaza said its strategy includes selling some properties while continuing to add space through development and other projects.

“We remain focused on improving the quality, scale and earnings capacity of our portfolio,” said Parravano. “While we have selectively sold certain properties this year, we will continue to add square footage through developments, intensifications and other strategic initiatives. This reflects a deliberate approach to capital allocation. We are recycling capital from mature or non-core assets into opportunities that can generate stronger returns, improve portfolio quality and contribute to sustainable cash flow growth.”

The trust’s portfolio at June 30 consisted of interests in 189 properties totalling approximately 8.8 million square feet across Canada, along with additional land held for development.

Plaza said the portfolio consists largely of open-air centres and stand-alone small-box retail outlets and is predominantly occupied by national tenants focused on essential needs, value and convenience.

Higher profit

Plaza’s quarterly profit was also affected by changes in the fair value of investment properties. The $5.1 million net increase in fair value during the quarter was $3.8 million higher than in the same period of 2025.

For the first six months of the year, profit and total comprehensive income was $29.4 million, compared with $22.0 million a year earlier, an increase of 33.9 per cent.

The year-to-date results included a $2-million increase in the share of profit of associates, which Plaza attributed mainly to a non-cash fair-value adjustment to underlying investment properties and changes involving 5400 Laurier Ouest Limited Partnership and the acquisition of Plazacorp Ontario-1 Limited Partnership.

The change in fair value of investment properties accounted for another $3.8 million of the year-over-year increase in profit.

“Our progress is measured not simply by the number of properties we own, but by the quality and scale of our real estate, the cash flow it generates, and the value created on a per unit basis. With growing FFO and AFFO, improved payout ratios and a pipeline of projects advancing across the portfolio, we believe Plaza is well positioned to continue creating long term value for unitholders.”

More from Retail Insider:

Daily Synopsis: Aug 7, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 11 articles we published covering key developments in Canadian retail.

Winnipeg-based Quarks expanded its Canadian footwear footprint as it nears 50 years in business with a focus on regional markets and sustainable growth. Tim Hortons plans stronger Canadian growth through 80 new stores, 400 renovations, and expanded beverage and loyalty programs. Leon’s Furniture reported higher Q2 net income despite a slight sales decline, driven by cost control and strategic investments.

Canada’s freight market is shifting unevenly with truckload transportation strengthening, influencing retail supply chain strategies discussed in this analysis.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web

What Retail Market Research Teaches Us About the Future of Shopping

Ever noticed how shopping feels different than it did even five years ago? Not just the fact that half your purchases arrive on the doorstep now. It’s the whole rhythm of it. The way people browse, compare, hesitate, and eventually buy. Retailers have been paying close attention to all of this, mostly because they have to. And the tool doing a lot of the quiet heavy lifting behind the scenes is market research.

The truth is, most of the big shifts in retail didn’t happen by accident. Someone studied shopper behaviour, spotted a pattern, and acted on it. So what exactly has all that research been telling us? Quite a lot, as it turns out.

Shoppers Want Convenience, But Not at Any Cost

Here’s the thing about convenience. Everyone says they want it, and they genuinely do, but research keeps showing there’s a limit. People love one-click checkouts and same-day delivery. What they don’t love is feeling like a data point being squeezed for every last penny.

Studies into shopping habits have picked up on this tension again and again. Customers will happily hand over their email for a discount, then get irritated when they’re bombarded with twelve promotional messages a week. Funny how that works. The research suggests the future isn’t just about making things faster. It’s about making things feel respectful too.

Picture this: trying to buy a pair of shoes and being asked to create an account, verify your phone, and answer a survey before you can even see the price. Most people bail. Retailers who’ve done their homework know this, and they’re stripping back the friction rather than adding to it.

The Blurred Line Between Online and In-Store

Remember when online shopping and physical shopping felt like two separate worlds? That’s pretty much over. People now research on their phones while standing in a shop. Or they’ll spot something in a store window, then order it online later that night from the sofa.

Market research has been tracking this back-and-forth movement for years, and the findings are clear. Shoppers don’t think in channels. They just think about the thing they want. Whether it comes from a warehouse or a shelf barely registers.

This part’s a bit tricky for retailers, honestly. Because it means the old habit of treating the website and the shop floor as separate businesses doesn’t hold up anymore. The ones getting it right are stitching the two together so a customer can start in one place and finish in another without a hitch.

Personalisation Is Expected, Not Impressive

A while back, personalised recommendations felt kind of clever. Now? People barely notice them, and they get annoyed when they’re wrong. Recommend a lawnmower to someone in a flat with no garden and you’ve just reminded them the algorithm doesn’t really know them.

Good research digs into what personalisation actually means to shoppers, and it’s usually more subtle than a “you might also like” widget. It’s about remembering preferences, respecting past choices, and not making people repeat themselves. This is where solid Kadence market research helps brands understand the difference between helpful and creepy, which is a line that shifts depending on who you ask.

Values Are Doing Some of the Shopping Now

Something interesting has crept into the data over the past decade. People increasingly care about where their stuff comes from. Sustainability, fair treatment of workers, honest sourcing. These aren’t fringe concerns anymore.

But here’s where it gets interesting. Research also shows a gap between what people say and what they actually buy. Someone might rate ethics as hugely important, then grab the cheaper option anyway. Retailers who only listen to the survey answers get caught out. The ones who watch real behaviour alongside stated opinions get a much truer picture.

That gap, by the way, is exactly why good research matters so much. Ask the wrong question or trust the surface answer and you build a strategy on sand.

So Where Does This Leave Shopping?

Somewhere more human, oddly enough. All this data and behavioural study keeps pointing back to fairly simple wants. People want to feel understood. They want things to be easy without feeling manipulated. And they want to trust the brands they hand their money to.

The retailers who thrive over the next few years probably won’t be the ones with the flashiest tech. They’ll be the ones who actually listened. Turns out understanding your customer never really goes out of fashion.

Retail Event Strategies That Help Brands Stand Out

Retail events offer brands a chance to create meaningful face-to-face connections that digital marketing alone cannot replicate. Whether you’re preparing for a trade show, pop-up activation, or community event, the right retail event strategies can increase visibility, attract qualified prospects, and strengthen long-term customer relationships. Success depends on careful planning, attractive event design, engaging customer experiences, strategic budgeting, and effective post-event follow-up. These strategies help businesses maximize event results while building stronger relationships and achieving measurable marketing outcomes.

Design an Event Space That Attracts Attention

Your event space should communicate your brand within seconds. Clean layouts, bold graphics, effective lighting, and open traffic flow encourage visitors to stop instead of walking past. For outdoor promotions, a Custom canopy tent provides both weather protection and strong visual branding while making your location easier to spot. Consistent colors, clear messaging, and professional displays create trust before conversations even begin.

Visitors often decide quickly whether to approach a booth, making first impressions essential. An organized layout helps attendees move comfortably, while high-quality visuals reinforce brand identity. Positioning important products or demonstrations in visible areas can increase engagement.

Practical design choices also influence visitor experience. Comfortable meeting spaces, accessible displays, digital screens, and interactive elements can make the booth more welcoming without creating clutter. Every design element should support a consistent brand story that remains memorable after the event.

Engage Visitors With Interactive Experiences

People remember experiences more than displays. Live demonstrations, hands-on product testing, educational sessions, and interactive technology keep visitors engaged and create opportunities for meaningful conversations. Instead of overwhelming attendees with information, focus on solving a specific customer problem. High-quality printed displays from providers such as expoprint can reinforce key messages throughout the visitor journey without distracting from personal interaction.

Interactive experiences turn passive visitors into active participants. Product trials, guided demonstrations, touchscreens, and live presentations help attendees understand the value of your offering more effectively than traditional presentations.

Staff training is equally important. Friendly and knowledgeable team members who listen carefully create stronger relationships than scripted sales pitches. Authentic conversations build trust and increase the chance that visitors will remember your brand.

Digital tools can also extend engagement. QR codes, digital catalogs, online sign-ups, and contests provide additional value for attendees while helping brands collect useful customer information for future communication.

Balance Budget, Branding, and Materials

Not every investment delivers equal value. Prioritizing elements that improve visitor experience usually produces better results than spending heavily on giveaways alone.

InvestmentPrimary BenefitPriority
Booth structureVisibility and professionalismHigh
Branded signageBrand recognitionHigh
Interactive demonstrationsVisitor engagementHigh
Promotional giveawaysTraffic generationMedium
Digital lead captureConversion trackingHigh
Staff trainingBetter customer interactionsHigh
Product samplesHands-on experienceMedium

A balanced budget combines durable branding materials with experiences that encourage meaningful conversations instead of simply increasing foot traffic.

Promotional merchandise may attract attention, but it creates more value when combined with strong engagement. Investing in reusable displays, professional graphics, and trained staff often provides better long-term returns while maintaining a consistent brand image.

Reviewing previous event performance also helps optimize spending. If certain materials or activities create limited engagement, those resources can be redirected toward areas that improve customer experience and results.

Measure Success After the Event

The event isn’t over when attendees leave. Strong follow-up determines whether conversations become customers.

  • Organize leads within 24-48 hours.
  • Send personalized follow-up messages.
  • Measure conversions against your original goals.
  • Review visitor feedback and staff observations.
  • Apply lessons to improve future events.
  • Compare results with previous events.
  • Update CRM records for future sales conversations.

Consistent measurement helps identify which retail event strategies generate the strongest return on investment and deserve more attention in future campaigns.

Quick follow-up keeps your brand fresh in attendees’ minds. Personalized emails, calls, or product recommendations are more effective than generic messages. Combining conversion data with visitor feedback provides a clearer understanding of strengths and areas for improvement.

Frequently Asked Questions

How can a small brand stand out at a trade show?

Focus on a clear message, distinctive visuals, engaging demonstrations, and authentic conversations rather than competing only on booth size. Meaningful interactions often create stronger impressions.

How do you measure retail event success?

Track qualified leads, sales, customer engagement, conversion rates, and return on investment against your original goals. Both data and attendee feedback help evaluate performance.

Conclusion

Outstanding retail events are built through thoughtful planning, engaging experiences, and disciplined follow-up not bigger budgets alone. By refining your retail event strategies before, during, and after every event, you can create stronger customer connections, improve lead quality, and turn each activation into a measurable business opportunity. When goal setting, booth design, visitor engagement, and performance analysis work together, retail events become powerful tools for strengthening brands, building customer relationships, and supporting sustainable growth.

From The Desk: Navigating Growth and Resilience in Canadian Retail

Canadian retail continues to demonstrate resilience as growth strategies and operational agility come to the fore this week. From expansion plans in grocery and specialty segments to evolving consumer engagement models, retailers and commercial real estate stakeholders face a complex yet opportunity-filled landscape. The intersection of strategic portfolio moves, rising costs, and marketplace innovation underscores the need for adaptability.

In the backdrop, ongoing regulatory and supply chain pressures persist, demanding a balance between cost management and customer experience. Notably, key leadership changes signal renewed focus on international growth and operational excellence. As the industry approaches late summer, these developments set a clear tone for the strategic decisions shaping retail’s near future.

Retailer News

The retail landscape is marked by significant footprint expansions and experiential retail innovations. Tim Hortons’ aggressive Canadian growth plans include 80 new restaurant openings alongside enhancements to cold beverages and loyalty programs as it fights to reclaim momentum from recent sales slowdowns. Similarly, Fendi’s standalone boutique at Oakridge Park illustrates luxury retail’s targeted return to independent outlets, capitalizing on Vancouver’s rising prominence in the North American luxury scene.

In grocery, T&T Supermarket is advancing its national reach with the first Manitoba store planned for CF Polo Park, reinforcing growing consumer demand for diverse ethnic food offerings. At the same time, Realm Fitness’ transformation of a Calgary industrial property into a vibrant community and retail hub highlights a promising blueprint for repurposing non-traditional spaces into high-engagement destinations, blending retail with wellness and lifestyle amenities.

Retailers are also navigating capital and operational structuring challenges. Birks’ voluntary NYSE American delisting reflects its efforts to manage heavy debt burdens while recommitting to retail excellence. Meanwhile, brand and portfolio consolidation continues with Baffin joining the Royer Group and Jamieson Wellness’ C$2.5 billion acquisition by Kirin, underscoring renewed confidence in Canadian brands within global strategic portfolios.

Finally, retailers are adapting to a more complex operating environment. The uneven shifts in Canada’s freight market and emerging security risks extending past theft remind the sector of the multifaceted challenges requiring integrated real estate and operational responses.

The financial pulse of Canadian retail this week reveals a nuanced picture of growth, occupancy strength, and shifting consumer behaviours. Retail real estate remains robust with RioCan’s record 98.8% retail occupancy and SmartCentres reporting steady leasing gains, both reflecting strong demand amid supply constraints. Parallel to this, Slate Grocery REIT’s leasing activity above prior rents underscores grocery-anchored retail’s continued appeal as an inflation-resistant asset class.

Consumer spending trends remain fragmented. Although Canadian retail sales grew 4.0% year over year in May, largely fuel-driven, discretionary sectors such as home furnishings continue to struggle, as described in a report on retail sales growth. This dynamic is mirrored in furniture retail with Wayfair’s data indicating Canadian lag behind U.S. recovery. Conversely, specialty retail like eyecare shows promise, with Kits Eyecare’s record revenue highlighting successful niche positioning.

Retailers in foodservice report positive momentum. Restaurant Brands International’s strong Q2 consolidated sales demonstrate resilience in quick-service dining, while beverage innovations by McDonald’s Canada and recent consumer beverage preferences suggest strategic new growth avenues.

Underlying these results, evolving regulatory and operational complexities are well documented in the Retail Insider policy report, outlining the collision between affordability policies and rising retail costs. Similarly, the logistics report reveals a shift toward supply chain optionality as a coping strategy in a volatile environment, which is altering real estate and inventory planning.

Retailer People News

Leadership changes and strategic hires are shaping retail’s forward trajectory. Second Cup’s appointment of Joe Walker as CEO to spearhead its international franchise growth, particularly in the Gulf region, signals ambitions to diversify beyond Canada’s borders through focused leadership with global experience. In financial and operational governance, Leyad’s recent senior appointments of Juan Calixto Tria and Alex Ratté fortify its asset management capabilities amid continued portfolio expansion.

Meanwhile, Goodfood’s leadership change alongside its creditor protection filing highlights operational challenges in the online meal delivery sector, reflecting broader pressures from liquidity constraints and restructuring. Sleep Country’s expansion strategy, including the acquisition of Sleep Number and forthcoming store concepts, demonstrates a multi-brand portfolio approach designed to capture diverse segments and geographic reach, according to their CEO’s recent interview.

Retailer Op-Eds

Thought leadership this week underscores how import strategies can impact category vitality and consumer retention. For instance, the argument that Australian beef imports may sustain Canadian beef aisle engagement amidst domestic price pressures introduces important dialogue on how supply diversity supports category health and customer traffic. This perspective is particularly relevant for grocers and retail real estate owners who depend on stable foot traffic driven by staple and high-demand categories.

Editor’s Take

This week’s developments showcase a Canadian retail sector actively balancing growth ambitions with operational resilience in a complex market. The expansion plans by major players such as Tim Hortons and T&T Supermarket reflect confidence in demand growth even as rising costs and regulatory complexities, highlighted in policy and logistics reports, remind executives of the necessity to embed flexibility into supply chains and real estate strategies. Grocery-anchored retail remains a sturdy platform, as seen in REIT leasing strength and specialty food firms’ robust earnings.

Leadership changes at companies like Second Cup and Goodfood signal a broader pivot towards international markets and turnaround execution, respectively, underscoring the vital role of experienced management in navigating growth amid uncertainty. Meanwhile, luxury and experiential retail moves, including Fendi at Oakridge Park and Realm Fitness’ innovative hub, signal diversification in retail real estate usage and tenant mix strategies critical for maintaining foot traffic in evolving urban centres.

Overall, this week confirms that successful Canadian retailers and real estate operators are those who integrate data-driven market insights with strategic portfolio management, leadership continuity, and operational agility. Aligning product offerings, store formats, and community engagement within a demanding economic environment will be key to sustaining competitive advantage as the sector advances.

This Week’s Articles

Retailer News

Retailer People News

Retailer Op-Eds

News From Around the Web

Real-Time Visibility is the Operating System Between Promise and Doorstep

Retailers cannot govern delivery experience, 3PL performance, capacity promises, or driver workload if no one sees the same live picture of the order. Real-time visibility is the connective tissue that makes every other delivery discipline possible. | Cluster focus: Real-time tracking and visibility

A completed stop is not the same as a visible journey

Many retail networks still treat tracking as something that happens after dispatch, or only when a customer calls. The order leaves the warehouse, the carrier portal updates intermittently, store teams check a separate screen, and customer care searches three systems before answering a simple question: where is my order? PromoPro UK highlights how important it is for retailers to provide customers with a clear and reliable view of their delivery journey.

That fragmentation was tolerable when delivery was a minority channel. It is not tolerable when the van, the pickup counter, and the apartment lobby are part of the brand experience. A shopper who bought a two-hour window expects live truth, not a static “out for delivery” badge that appeared forty minutes ago. Operations expects the same. When dispatch, the store, the driver, and the contact centre each hold a partial version of the day, exceptions are discovered late, recovery starts after the complaint, and the retailer pays twice: once in logistics cost, once in trust.

Real-time visibility, properly defined, is not GPS dots on a map. It is a shared, order-level timeline that connects the promise, fulfilment readiness, route execution, and customer communication, live enough that someone can intervene before something breaks. The commercial stakes are measurable: in a Q2 2026 Locus survey of more than 1,000 U.S. online shoppers, 20 % now rank reliable delivery as their single most important factor in choosing a retailer, 26% expect free returns and another 10 % rank convenient returns first, together rivalling the 34 % who still put raw speed on top. Reliability is what real-time visibility exists to protect.

Why batch updates and carrier portals fail retail

Third-party portals and nightly reconciliations were built for freight visibility, not for hourly retail promises. They show movement between hubs. They rarely show whether the store finished picking, whether the driver is still waiting at the loading bay, or whether a condominium access rule will push the next stop outside the sold window.

Retail scorecards then diverge. Carriers report on-time departures. Care teams measure contacts per thousand orders. Finance sees redelivery invoices. None of those views reconstructs the single question a household asks: will you keep the promise you sold me?

Batch visibility also trains the organisation to react. A delay becomes visible after the window slips. A route deviation appears in a weekly report. A temperature excursion on a chilled run surfaces when the customer opens the box. By then, the cheapest recovery options are gone. And the demand feeding these networks is getting harder to predict, not easier: the same survey found 45 % of U.S. consumers now use AI to research or decide what to buy, and among those shoppers 39 % try new brands more often and 37 % buy more items per order. Larger, less predictable baskets mean more exceptions per thousand orders, which is exactly the wrong moment to be discovering them in a weekly report. Real-time visibility is not a customer nicety; it is how retailers avoid turning a fixable exception into a refund, a one-star review, and a lost repeat purchase.

Signals the network is flying blind

  • WISMO contacts spike on promotion days even when headline on-time rates look stable.
  • Store and dispatch disagree whether an order was ready before the route left.
  • Care agents give different ETAs because they cannot see the same events as the driver app.
  • Exceptions are logged after the customer calls, not when the geofence breach, halt, or pick delay occurred.
  • National averages look healthy while one city or daypart fails quietly because nobody monitors live adherence by cluster.
  • 3PL and owned-fleet data sit in separate tools, so hybrid networks cannot explain a missed promise from one timeline.

Build one timeline every stakeholder can trust

Retail leaders should define real-time visibility at the order level, not the vehicle level. For each journey, the operating picture should connect the promise shown at checkout, pick and pack status, dispatch assignment, live route progress, proof capture, and customer-facing updates, timestamped, reason-coded, and owned.

That timeline belongs to commercial governance, not only to transport. The chief customer officer needs it to protect the post-purchase experience. The COO needs it to intervene before an SLA breach. Customer care needs it so agents stop improvising answers. The 3PL needs it so disputes are about facts, not narratives.

Start with the events that matter to the shopper: confirmed, picked, loaded, en route, approaching, delivered, or the credible alternative when the plan changes. Then attach the internal events that explain those states: late pick release, vehicle delay, access failure, re-sequenced stop, proactive delay notice sent. If those events live in different systems, the retailer does not have real-time visibility. It has parallel stories that converge only after something fails.

Separate tracking display from tracking control

A branded tracking page reduces support load when it reflects live execution. It increases frustration when it is a marketing layer on stale data. Retailers should hold both capabilities to the same standard: accuracy, channel consistency, and permission to act.

Customers should see useful progress, not only a map aesthetic, and a clear next step when the plan changes. Operations should see the same facts plus the levers: reassign, rebook, notify, escalate. Drivers should not be the unofficial integration layer, texting dispatch photos because the official workflow cannot capture access problems or cancellations in time.

For click-and-collect and store-origin delivery, real-time visibility must start before wheels roll. A customer told to arrive at 6 p.m. should not discover at 5:55 that picking is still in progress. Store readiness belongs inside the live journey, not in a back-office chat thread the tracking page never sees.

Design alerts for intervention, not post-mortems

Real-time visibility earns its value when it triggers action before the promise breaks. Retail networks should alert on leading indicators: pick completion slipping against a locked route, travel time diverging from plan, unplanned halt, geofence breach, unauthorised deviation, temperature threshold on chilled goods, or driver capacity that can no longer absorb late insertions.

Each alert should map to an owner and a play. Some events warrant automatic customer notification. Some require dispatcher review. Some should block further slot sales in a postal cluster until capacity is restored. Vague “exception occurred” messages recreate the same ambiguity that made batch reporting useless.

Segment alert thresholds by basket type and geography. A five-minute slip on a dense urban grocery route is not the same as a five-minute slip on a long regional bulky run. Visibility without segmentation produces noise; noise produces ignored alerts; ignored alerts produce the same customer call the system was meant to prevent.

Unify all-mile and all-channel execution

Omnichannel retail rarely moves goods through one leg. The survey found 84 % of U.S. shoppers order multiple items at once, and 31 % routinely order four or more, which means split shipments, multiple nodes, and multiple providers behind a single order confirmation. One basket may be picked in-store, handed to an owned van, transferred to a 3PL for the final mile, or fulfilled through a carrier network with its own status language. Real-time visibility fails when each leg has a separate portal and no shared order ID logic, because the customer bought one order, not four journeys.

Retailers should require a control-tower view across owned fleet, store dispatch, and contracted carriers, hub to doorstep, with granular updates at node, route, and stop level. That is how hybrid networks explain a delay without asking the customer which provider they think they used.

Integrations matter, but the commercial requirement comes first: one authoritative timeline exportable for claims, care, and continuous improvement. A provider dashboard the retailer cannot join to order data creates visibility for the 3PL and blindness for the banner.

Reduce WISMO by telling the truth early

Most “where is my order?” contacts are not curiosity. They are anxiety caused by silence, contradictory messages, or a promise that no longer looks credible. Proactive updates, specific, timed, and tied to a next option, usually cost less than the contact they prevent. The loyalty math cuts both ways: in the same Locus research, 42 % of shoppers said fast resolution of the post-purchase moment makes them much more likely to buy from that retailer again, while 8 % said slow resolution would push them to avoid the retailer entirely. That 8 % is avoidable churn sitting inside the post-purchase process, and visibility is usually the missing ingredient.

Measure visibility quality alongside contact rate: percentage of journeys with proactive delay notice before breach, time from exception to customer message, match rate between agent screen and customer tracking page, and repeat-contact rate on the same order. A pretty tracker that reduces contacts by five % but leaves fifteen % of delays unannounced is still a brand liability.

Write the communication rules before peak. When to widen the window, when to offer pickup, when to credit, and what language care may use without escalation. Real-time visibility should feed those rules automatically where possible, not depend on a supervisor noticing a red row during lunch.

Practical moves for the next planning cycle

  • Publish an order-level visibility standard: required events, timestamps, owners, and customer-facing mirrors.
  • Run one live exception drill, late pick, mid-route slip, access failure, and score how long each team took to see the same fact.
  • Align care, customer tracking, and dispatch on one timeline; treat mismatch as a defect, not a training issue.
  • Require structured exception codes that drive action, not generic “in transit” statuses.
  • Review ten customer contacts that should never have happened because the event was visible internally first.

Inside the Locus control tower: real-time visibility built for intervention

The requirements above describe a control tower in the operational sense, not the wall-screen sense, and it is worth examining how Locus builds one. The Locus control tower assembles the order-level timeline this article prescribes across owned fleets, store dispatch, and contracted carriers, including a network of more than 1,000 carrier partners, so hybrid networks stop reconciling providers in spreadsheets. Every journey is tracked hub to doorstep at node, route, and stop granularity, with live ETAs recalculated continuously against actual route progress rather than the morning plan. The alerting layer watches the leading indicators that matter to retail: pick completion slipping against a locked route, travel-time divergence, unplanned halts, geofence breaches, route deviations, and temperature thresholds on chilled goods. Critically, alerts arrive attached to levers, not just colours: dispatch can reassign or re-sequence from the same screen, trigger a proactive customer notification, or flag a postal cluster where capacity can no longer absorb new slot sales.

The tower stays truthful because the field feeds it. The Locus Driver Companion App returns live task status, structured exception codes, and multi-format proof of delivery, including item-level scans, photos, signatures, and chain of custody, so the timeline reflects what happened at the curb rather than what the back office assumes. The same events mirror outward to a branded customer tracking page and inward to customer care, which means the agent’s screen and the shopper’s screen cannot disagree; a WISMO contact that still arrives is answered from evidence in seconds. Store readiness sits inside the same journey, so a click-and-collect customer is warned before driving, not at the counter. And every event is timestamped, reason-coded, and exportable, which turns 3PL disputes, claims, and weekly reviews into arguments about facts.

The pattern this eliminates is familiar to any retailer running on portals: a leading Canadian grocery brand delivering perishables across more than 30 cities found that once a shipment left the dock, nobody could see it, and the first signal of a late order was usually the customer, after the freshness window had closed. On the Locus platform, delays began announcing themselves, and customer support resolution accelerated 10 to 20 times because care finally worked from one live screen. Retailers evaluating any control tower, Locus included, should judge it on a messy midday: late release, route deviation, and a proactive customer update from one system of record. Map aesthetics matter less than whether anyone can intervene while the promise is still saveable.

Make real-time visibility a weekly retail discipline

Borrow the rhythm merchandising already uses. Pick one visibility KPI for the quarter, proactive delay notice rate, timeline match rate, or exception-to-action time, and review it weekly with an owner who can change escalation rules, not only report them.

The retailers that treat tracking as a post-delivery report will keep paying for it in contacts, refunds, and fragile 3PL relationships. The retailers that treat real-time visibility as the connective tissue between promise and doorstep will govern delivery as a brand function, with enough lead time to recover when the day diverges from the plan.

Start with one high-volume journey in one geography. Reconstruct twenty missed promises from a single shared timeline. The pattern you find, late pick, silent deviation, stale customer page, should tell you whether the problem is technology, process, or both. Fix that before scaling a tracking programme that only decorates the same blind spots.


Retail Insider “Policy & Regulation Report”: Affordability Promises Collide With Retail Costs

Retail Insider’s latest report, Q2 2026 Policy & Regulation: Affordability Promises Meet Retail Operating Realities, examines a widening gap between political efforts to address consumer prices and the costs retailers encounter throughout their operations.

Authored by Craig Patterson as part of Retail Insider Reports, the report analyzes Q2 2026 developments in Canadian retail policy and regulation. Its scope includes government policy, legislation, taxation, trade rules, competition policy, labour policy and public-sector decisions affecting retailers, landlords, suppliers, restaurants and consumers.

Retail Insider Reports are designed to deliver executive-level insights across major retail sectors and can be accessed through the Retail Insider Report Hub.

General Themes

  • Affordability Beyond the Shelf: Freight, tariffs, wages, packaging requirements, recycling obligations, theft and supply disruptions can raise prices before retailer margins enter the equation.
  • Regulation as an Operating Cost: Language laws, import documentation, food-safety enforcement and other compliance requirements are becoming embedded in retail cost structures.
  • Retail Crime as Public Policy: Theft and violence now affect employee safety, insurance, store design, inventory access, operating hours and decisions about where retailers operate.
  • Real Estate Under Scrutiny: Competition Bureau attention on grocery property controls could change leasing practices, market entry and the redevelopment of large retail spaces.
  • Trade Risk in Retail Planning: CUSMA uncertainty, tariffs, rules of origin and forced-labour import requirements complicate sourcing, pricing and inventory decisions.
  • Labour Pressure Across Markets: Immigration policy, local hiring, wage pressure and worker availability continue to influence foodservice, logistics and customer-facing operations.
  • Public Grocery Economics: Government-operated grocery proposals respond to genuine affordability concerns but face difficult questions about procurement, scale, staffing, technology and taxpayer exposure.
  • Urban Policy and Retail Vitality: Public safety, housing, transit, infrastructure, homelessness and office occupancy all influence the prospects of downtown retail districts.

Retail Insider Coverage

Retail Insider’s Q2 coverage traced how affordability pressures move through the full retail system. Reporting examined fertilizer costs, supply disruptions and recycling rules alongside food fraud and faulty meat scales. Coverage of government-operated grocery proposals included Toronto’s proposed four-store test and commentary questioning whether public stores could overcome the low margins and scale requirements of grocery retail.

The quarter’s reporting also followed the Competition Bureau’s multi-year scrutiny of grocery property controls, Restaurants Canada’s call for temporary foreign worker cap increases in rural areas, and Tim Hortons’ campaign to hire 10,000 local workers. Retail Council of Canada’s position on theft and violence helped frame retail crime as a national safety and operating-cost issue rather than a conventional loss-prevention concern.

Broader Industry Coverage

The report finds that regulation is becoming a material cost driver across Canadian retail. Each obligation may serve a clear policy purpose, but their cumulative effect can be substantial, particularly for small and mid-sized businesses without large compliance teams. Provincial differences in packaging, recycling and language requirements add another layer for companies operating nationally.

The implications also extend to investment and expansion. Competition policy may alter how landlords and grocers use exclusivity clauses, while Quebec language requirements influence market-entry planning and digital operations. Trade uncertainty affects orders placed months in advance, and persistent safety problems can influence store hours, staffing and the viability of individual locations.

The Grocery Code of Conduct offers a different approach to affordability. Rather than concentrating only on final prices, the voluntary framework seeks to improve transparency, predictability and dispute resolution between retailers and suppliers. Its implementation reflects growing recognition that affordability and competition are shaped throughout the supply chain.

Editor’s Take

Q2 2026 exposed a fundamental tension in Canadian retail policy. Governments are under pressure to make consumer goods more affordable, yet many policies add costs or complexity to the systems that produce, import, distribute and sell those goods. Retailers with strong compliance capacity, supply-chain visibility, labour planning and real estate flexibility will be better positioned to manage this environment. Smaller operators and companies entering new markets face greater pressure as regulatory risk becomes part of everyday business strategy.

Conclusion

Read the full Q2 2026 Policy & Regulation: Affordability Promises Meet Retail Operating Realities for the report’s analysis of affordability, competition, trade, labour, compliance, public safety and retail real estate.

The full report and other Retail Insider Reports are available through the Retail Insider Report Hub.