Home Blog Page 87

Crombie REIT Reports Strong Rent Growth Driven by Grocery-Angled Retail

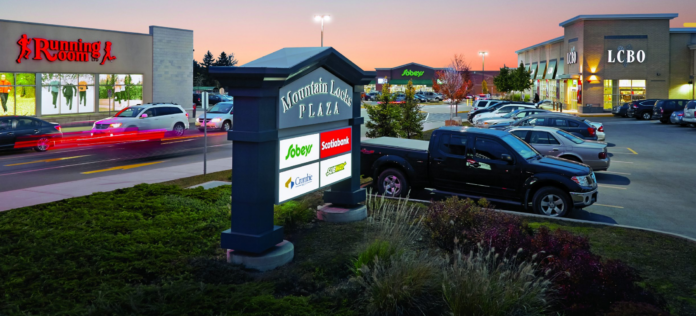
Mountain Locks Plaza in St. Catharines, ON. Photo: Crombie REIT

Crombie Real Estate Investment Trust is continuing to secure sharply higher rents across its Canadian retail portfolio, providing further evidence of strong demand for well-located grocery-anchored space.

The Halifax-based landlord completed 121,000 square feet of lease renewals during the second quarter of 2026 at first-year rents 11.3 per cent above the expiring rates. When measured against the weighted average rent over the full term of the renewed leases, the increase was 12.7 per cent.

It marked Crombie’s seventh consecutive quarter of double-digit renewal rent growth. Committed occupancy remained near a record high at 97.5 per cent, while commercial same-asset property cash net operating income increased 3.2 per cent. Crombie also had approximately 160,000 square feet of committed space awaiting tenant possession through 2026 and 2027, at an average first-year rent of $28.45 per square foot.

The results reflect the structure of Crombie’s portfolio, which combines long-term supermarket leases with smaller units that return to market more frequently. Grocery stores provide stable traffic and income, while limited availability of surrounding retail space is allowing the landlord to capture higher rents as leases expire.

Grocery Anchors Support Retail Leasing Strength

Crombie’s properties are concentrated around grocery stores and other necessity-based uses that draw customers throughout the week. These anchors can be difficult to replicate, particularly in established communities where available development sites are limited and construction costs remain high.

“A grocery store brings people to the property week in, week out, and that steady traffic is what makes our space valuable to every retailer around it,” Mark Holly, president and chief executive officer of Crombie REIT, said during the company’s second-quarter earnings call.

Nearly 90 per cent of Crombie’s non-grocery units are approximately 15,000 square feet or smaller. Management said this is the format sought by a wide range of necessity-oriented retailers and service businesses, with relatively little new supply being created to meet that demand.

The grocery anchor generally remains in place under a long-term lease, giving the property a stable operating foundation. Smaller units surrounding it typically have shorter lease terms and return to market more frequently, allowing Crombie to reset rents as leases expire. The 11.3 per cent increase reported during the quarter applies to Crombie’s renewal activity across the portfolio, which was driven primarily by its retail properties, and does not represent an increase specifically on Sobeys or Safeway leases.

Rental growth has persisted across several reporting periods. Crombie said annual minimum rent has compounded at close to four per cent annually over the past three years, supported by renewals, contractual rent increases and new leasing.

The company reported similarly strong leasing in the first quarter of 2026, completing 232,000 square feet of renewals at first-year rents 12.1 per cent above expiring rates. Commercial same-asset property cash NOI increased 3.7 per cent during that period. For the full year, management expects same-property growth to reach or exceed Crombie’s long-term target range of two to three per cent.

The sustained renewal gains point to retailers holding onto productive locations, particularly where comparable replacement space is difficult to secure. For smaller retailers and service businesses, space next to a productive grocery store can provide recurring customer traffic that may be difficult to reproduce elsewhere in the same trade area.
Mark Holly

Empire Relationship Shapes the Portfolio

Empire Company, the parent of Sobeys, is central to Crombie’s business model. It is the REIT’s largest tenant, a major unitholder and a strategic partner in the development and modernization of grocery properties across Canada.

Empire occupied approximately 12.1 million square feet at the end of the second quarter and accounted for 61.5 per cent of Crombie’s annual minimum rent. More than 90 per cent of Crombie’s retail properties are anchored by an Empire banner, while the weighted-average remaining lease term for Empire properties was approximately 9.7 years.

The relationship gives Crombie a large base of long-term grocery leases and allows the landlord and retailer to coordinate capital investments in stores and surrounding properties. It also creates substantial exposure to a single corporate group, making Crombie more concentrated than many diversified retail landlords.

Crombie invested $10.6 million during the second quarter through its modernization program with Empire. Across the first six months of 2026, the company invested approximately $17 million in 21 grocery-store modernization projects.

Under the program, Crombie provides capital for renovations and upgrades at grocery properties it owns, receiving a defined return on the investment and, in some cases, an extension of the grocery tenant’s lease. Management continues to target returns of approximately six to eight per cent across its non-major investment program, with grocery modernizations generally producing returns near the middle of that range.

Renovating an anchor store can also improve the wider property through an updated customer experience and additional traffic for surrounding tenants. Crombie has pointed to the Sobeys at Topsail Road Plaza in Newfoundland and Labrador as an example of its modernization program, while the addition of an A&W at a property in Spryfield, Nova Scotia, illustrates its strategy of creating additional commercial space at existing sites.

These investments allow Crombie to add value to properties already in the portfolio through store improvements, new pads and incremental retail space, generally on shorter timelines than major redevelopment.

Crombie Steps Up Acquisition Activity

Crombie is reinforcing its necessity-based real estate strategy through acquisitions, completing close to $150 million in purchases during the first half of 2026. During the second quarter, the REIT acquired Ocean Park, an approximately 30,000-square-foot freestanding Safeway in Surrey, British Columbia, for $12.7 million, excluding transaction and closing costs.

The store is located within an established retail node serving the Ocean Park community. Holly described it as the type of necessity-based property Crombie wants to own for the long term, adding another stabilized grocery asset to the REIT’s Western Canadian portfolio.

Earlier in the year, Crombie acquired retail-related industrial properties in Whitby, Ontario, and Saint-Hubert, Quebec. The two properties total approximately 539,000 square feet and were purchased for a combined $129.8 million, expanding the REIT’s exposure to real estate supporting grocery and retail distribution.

Crombie also purchased additional land at an existing property in Moncton, New Brunswick, giving the company full ownership of a site previously divided among several parcels. After the quarter, it acquired two parcels in Windsor, Nova Scotia, where a commercial development application is being advanced.

Management said the acquisition market is presenting more opportunities than it did six months or a year ago, although the REIT continues to be selective.

“The team is very active,” Holly said. “We are seeing more opportunities at this point in the year than we would have seen six months ago or a year ago.”

Crombie is evaluating acquisitions based on their ability to contribute to property income, longer-term funds from operations growth and the quality of the overall portfolio. Over the past four years, the company has acquired approximately $375 million to $400 million of property, sold about $100 million and added roughly 500,000 square feet to its portfolio.

The REIT has sufficient balance-sheet capacity to continue making acquisitions without matching each purchase with a property sale. Management said dispositions remain available as a source of capital and could be used where proceeds can be redirected into properties with stronger long-term growth prospects.
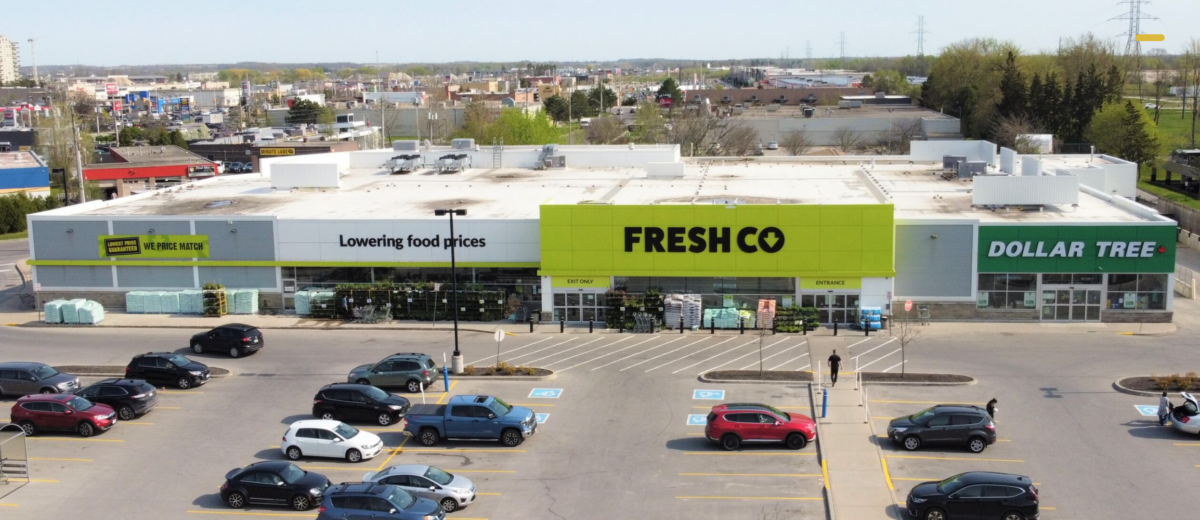
London Pine Valley FreshCo, London, ON. Image: Crombie REIT

Smaller Projects Take Priority

Crombie is currently directing more of its capital toward grocery modernizations, smaller intensification projects and income-producing acquisitions than major new developments. Approximately 29,000 square feet of development was underway across intensification projects and greenfield commercial builds during the second quarter. These investments can generally be completed more quickly than major developments and are expected to produce returns within Crombie’s six to eight per cent target range.

Management does not intend to begin another major development in the near term. Crombie continues to pursue zoning, development permits and other approvals for larger sites, preserving options to build, sell or partner on those properties as market conditions evolve.

Crombie’s only active major development, the Marlstone residential project in Halifax, reached substantial completion during the quarter. The 291-unit rental building is part of the Scotia Square complex and was more than 30 per cent leased by the end of July, with management describing July as its strongest leasing month to date.

Achieved rents at the Marlstone were above the underwriting established when the project was approved in 2023. Stabilization remains expected during the second half of 2027, with a projected yield on cost of between 4.5 and 5.5 per cent.

With the Halifax development substantially complete, Crombie’s near-term capital priorities are weighted toward investments capable of contributing to property income on shorter timelines, while larger development sites continue moving through the approval process.
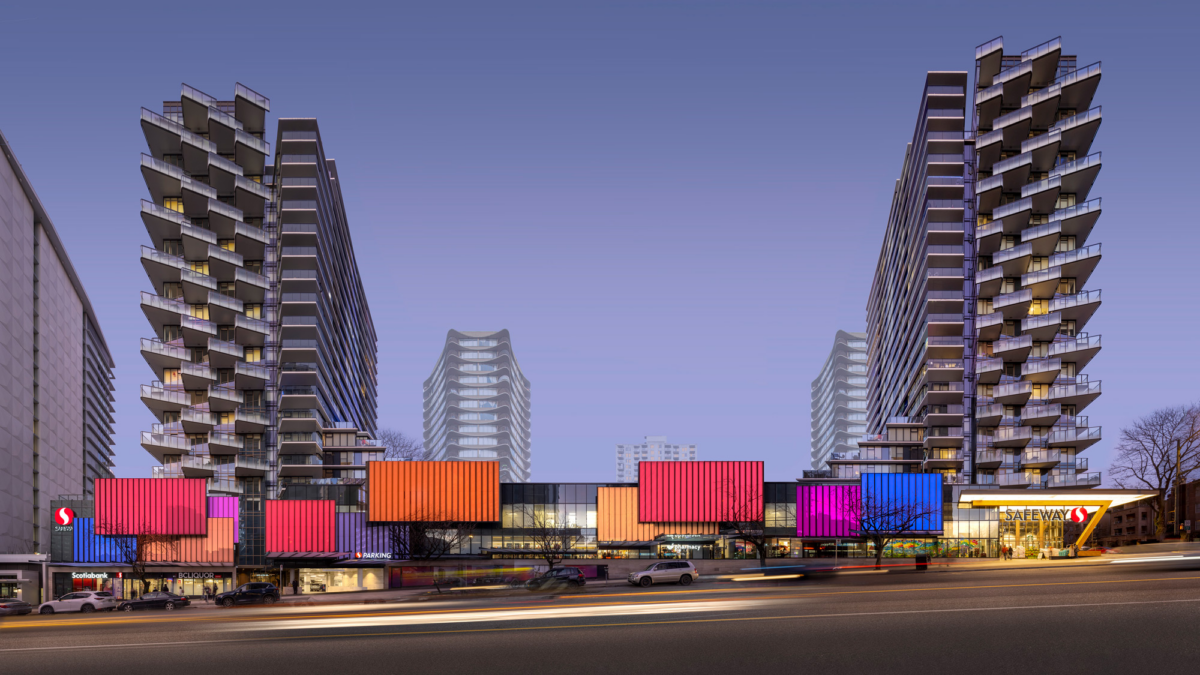
The Zephyr at Davie Street. Image: Crombie REIT

Retail Leasing Strength Extends Beyond Crombie

Crombie’s performance comes as other major Canadian retail landlords report similarly high occupancy and strong renewal activity.

Choice Properties REIT, which owns a large portfolio of Loblaw-anchored properties, reported retail occupancy of 97.4 per cent during the second quarter. The landlord also renewed 50 Loblaw leases covering approximately 3.6 million square feet at an average increase of 8.8 per cent.

RioCan REIT has also reported high retail occupancy and substantial leasing spreads across its more urban portfolio, supported by sustained tenant demand and limited additions of competing retail space.

The portfolios differ considerably. Crombie and Choice have deeper exposure to grocery-anchored properties, while RioCan is more heavily concentrated in major urban markets. The companies also calculate and disclose leasing spreads differently, limiting direct comparisons between individual percentages.

Across these portfolios, productive Canadian retail properties are operating at high occupancy while landlords continue to secure higher rents as leases expire. Conditions vary by property and market, with the strongest demand concentrated in established locations with productive anchors, recurring traffic and space that tenants cannot readily replace.

Crombie is heavily exposed to that segment of the market. Its grocery anchors provide recurring customer traffic and long lease terms, while smaller surrounding units create more frequent opportunities to capture rental growth.

As Crombie modernizes grocery stores, adds commercial space and selectively acquires necessity-based properties, the REIT is directing more capital toward a segment of Canadian retail real estate where limited new supply and high occupancy continue to support landlord pricing power.
More from Retail Insider:

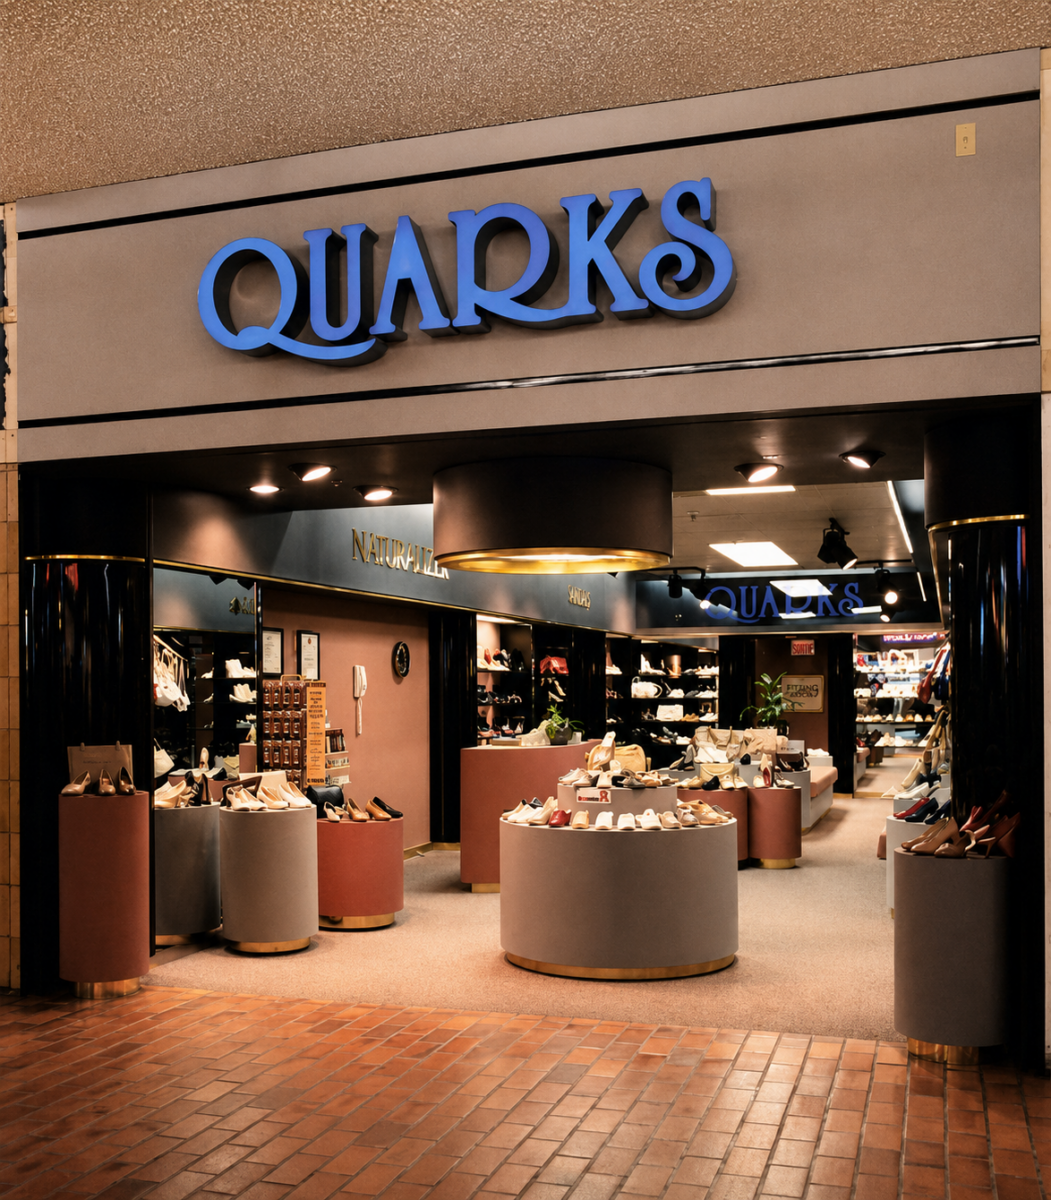
How Quarks Built a Canadian Footwear Business Over Nearly Five Decades

Quarks store at Mayfair Centre in Victoria, BC, April 2026. Photo: Quarks

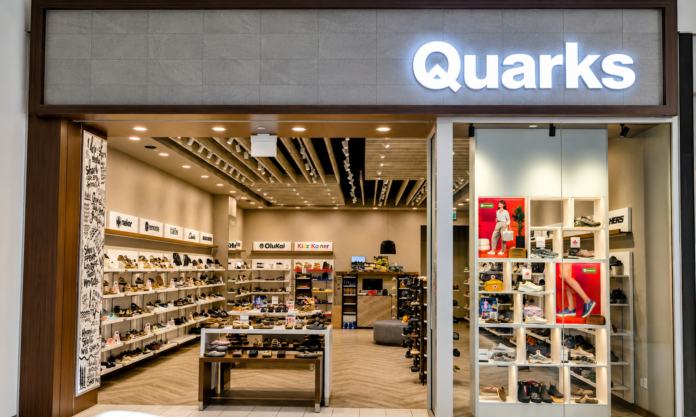
Quarks will celebrate its 50th anniversary in February 2027 at a time when the Winnipeg-based footwear retailer continues to expand its Canadian store network. Earlier this year, the company opened its 40th store at Mayfair Shopping Centre in Victoria and is preparing another location in Saskatoon, extending a business that began with a single store at Westwood Village Shopping Centre in Winnipeg in 1977.

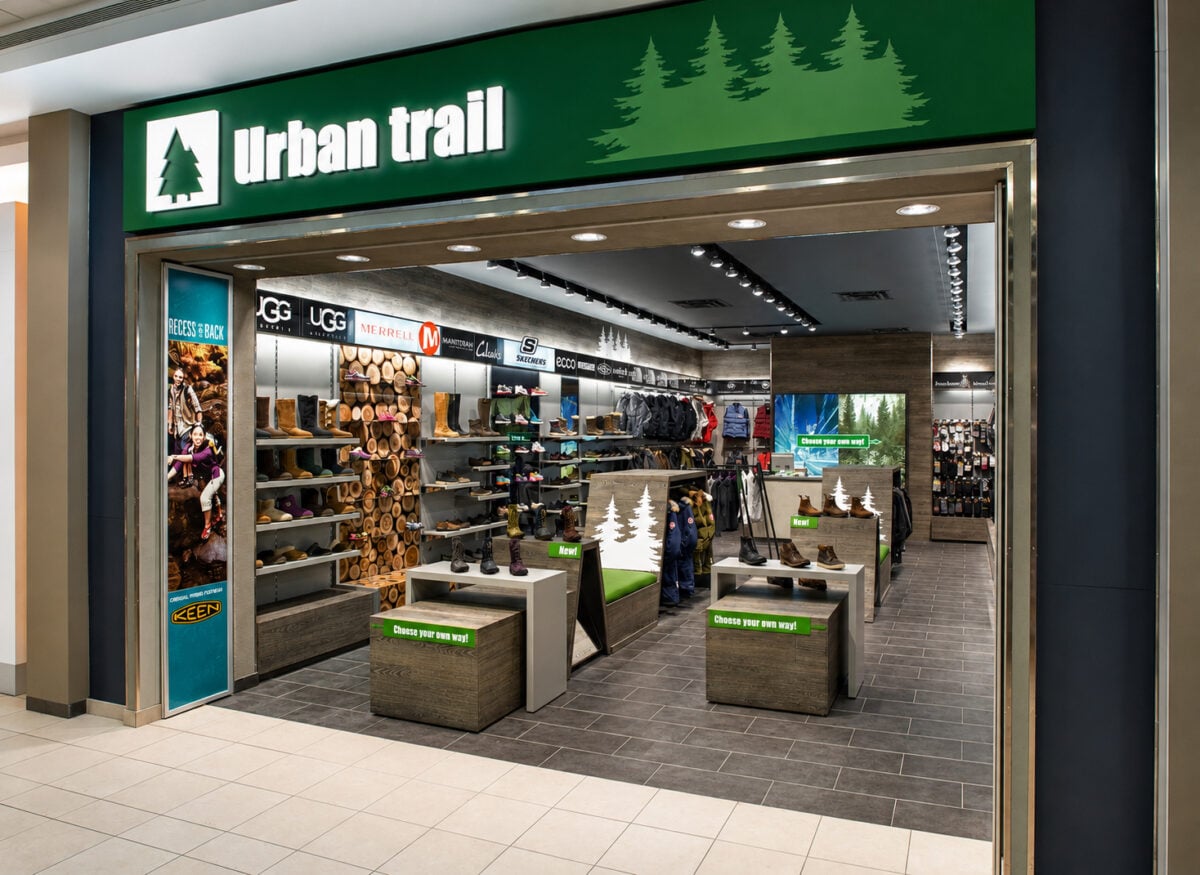
Today, The Quark Group operates the Quarks and Urban Trail banners across six provinces, specializing in branded comfort, casual and outdoor footwear. Its growth has taken place through decades of change in Canadian retail, including the rise of e-commerce, evolving consumer preferences, the casualization of fashion and the arrival of new international competitors.

Retail Insider spoke with President Kristy Krahn and Vice Presidents Doug Quark, Tom Quark and Ryan Krahn to discuss the evolution of the family business and the principles that continue to guide it. Although each oversees different areas of the company, the conversation repeatedly returned to the same themes: understanding customers, making thoughtful business decisions and building a company capable of succeeding over the long term.

As the discussion unfolded, one point became especially clear. While Quarks is approaching an important anniversary, the Quark and Krahn families are spending very little time looking backward. Their attention remains firmly on the future, whether discussing new stores, merchandising, digital retail or how the business continues to evolve in a changing marketplace.

Urban Trail at CF Polo Park in 2013. The award-winning store was designed by Ruscio Studio. Photo: Quarks

Building the Business

The story behind Quarks began before the company itself was established. Founder Dave Quark entered the footwear industry in Saskatchewan before continuing his career in Manitoba, working with retailers including Walkaway Shoes, Sterling Shoes and McDonald’s Shoes. Along the way, he developed experience in merchandising, operations and customer service while earning a reputation for improving underperforming stores. By the mid-1970s, he believed he had the knowledge and confidence to build a successful footwear business of his own.

The Quark Group was incorporated in late 1976, and the first Quarks store opened at Westwood Village Shopping Centre the following February. During its early years, the company concentrated on establishing itself in Winnipeg, gradually building a loyal customer base while refining its merchandising and operating model.

A pivotal moment came in 1984 when Dave and Jane Quark sold a 50 per cent interest in the business to Albert and Susan Krahn, creating an equal partnership that would shape Quarks for decades to come. The following year, the partners relocated the business to Unicity Shopping Centre, marking Quarks’ first location in an enclosed regional mall. By 1987, recognizing that a second successful store would be necessary to support both young families, they opened another Quarks location at Garden City Shopping Centre.

The partnership proved to be highly complementary. Dave brought vision, merchandising expertise and a strong marketing instinct, while Albert contributed financial discipline and strategic leadership. Together, they established many of the principles that continue to guide the company today.

Doug Quark still laughs when recalling one of the company’s earliest lessons in retail economics. When the business moved into an enclosed shopping centre, the original name, Quark Shoes, was shortened because the sign company charged by the letter for the storefront signage. Reducing the name by a single word reduced the cost.

It is a simple story, but it reflects the practical mindset that surfaced repeatedly throughout the interview. Whether discussing real estate, merchandising, technology or expansion, the Quark and Krahn families consistently emphasized building a stronger business instead of making the biggest statement. That approach became one of the foundations of Quarks’ long-term success.

Quarks store at St. Vital Centre, Winnipeg, in 1989. Photo: Quarks

Expanding Across Canada

Quarks’ first significant expansion outside Manitoba involved entering Saskatchewan through Moose Jaw and Yorkton in 2002, identifying communities where customers wanted access to recognized footwear brands but where the business believed it could establish sustainable, long-term operations.

“We thought we could thrive in these smaller centres that don’t have many shoe stores,” Doug Quark said.

That strategy became a defining characteristic of the company’s growth. Quarks gradually added stores throughout Saskatchewan before moving into Alberta, British Columbia, Ontario and New Brunswick. Markets including Red Deer, Lethbridge, Medicine Hat, Thunder Bay, Nanaimo, Prince George, Saint John and Fredericton became important additions to the chain as it expanded across Canada.

Regional markets offered several advantages. Occupancy costs were often more manageable than in Canada’s largest metropolitan areas, competition could be less intense and customers still wanted access to the same national and international footwear brands available in major cities. The approach also allowed the company to strengthen its operations gradually while maintaining close relationships with landlords, suppliers and employees.

Kristy Krahn said the company has never viewed expansion as an objective in itself.

“We’ve never expanded just for the sake of expansion,” she said. “We’re really thoughtful with where we go and when we go there.”

The retailer’s store count reflects that philosophy. Quarks reached 10 locations by 1994, 20 by 2008, 30 by 2014 and 40 this year. Some years brought several openings, while others passed without adding a new location. Opportunities were evaluated individually, with decisions based on the strength of the market, the available real estate and the company’s ability to operate each store successfully over the long term.

Longstanding industry relationships have also played an important role. The company has worked with Jeff Berkowitz of Aurora Retail Group for more than 15 years, relying on his understanding of shopping centres and retail real estate as new opportunities emerged across Canada.

Listening to the discussion, it became apparent that the Quark and Krahn families rarely measure success by the number of stores they operate. Instead, they spoke about creating sustainable businesses, building long-term partnerships and ensuring that every new location contributes to the health of the company as a whole.

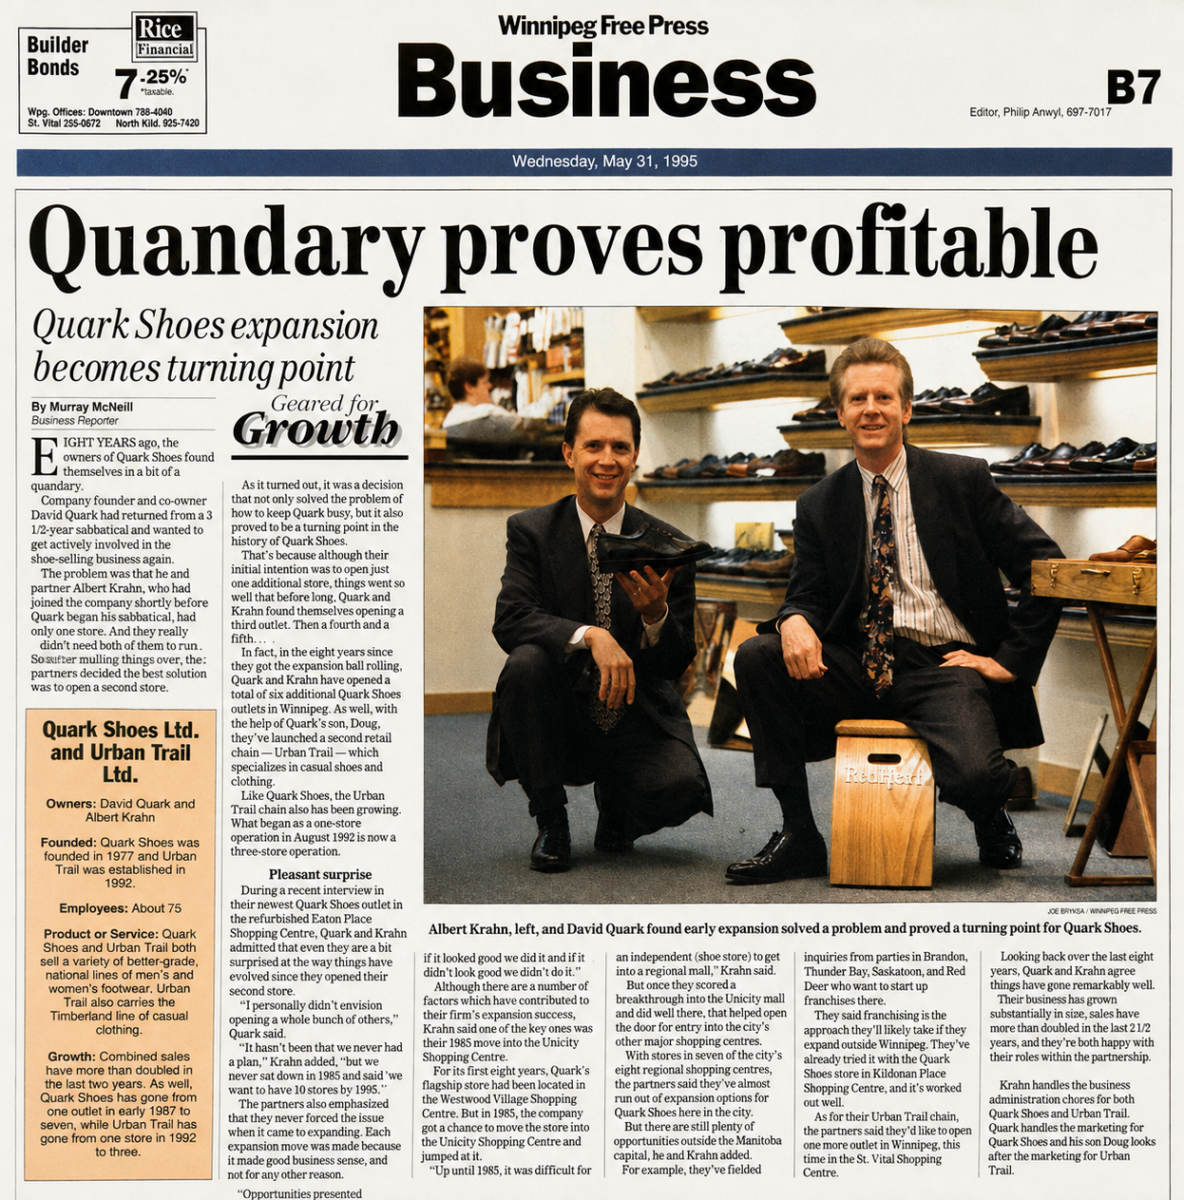
Credit: Winnipeg Free Press, 1995 (clipping provided by Quarks)

Changing With the Customer

While Quarks has remained disciplined in its approach to growth, the footwear business itself has changed dramatically over the past five decades. When the company opened its first store in 1977, dress shoes occupied a much larger share of the sales floor. Canadians generally dressed more formally for work, comfort footwear represented a smaller segment of the market and many of today’s leading brands had yet to establish themselves.

Quarks evolved alongside those changes. Today’s assortment reflects the growing demand for comfort, versatility and recognizable brands, with stores carrying labels including Birkenstock, UGG, Blundstone, Merrell, Clarks, Skechers, Rieker and Remonte.

Doug Quark summarized the company’s merchandising philosophy with a simple observation.

“We sell trendy shoes, but we’re not trendsetters.”

That philosophy extends well beyond individual products. Rather than chasing every emerging trend, Quarks watches how consumer preferences develop before making significant merchandising commitments. The company also values long-term relationships with suppliers, recognizing that enduring partnerships often produce better results than continually replacing established brands with the latest newcomers.

“We’ve built our reputation not on creating the trends, but recognizing them and making sure that we bring the right products to our customers at the right time,” Kristy Krahn said.

Tom Quark has watched another interesting shift unfold over the years. Decades ago, mothers, daughters and grandmothers frequently shopped for different styles of footwear. Today, it is increasingly common to see several generations purchasing the same brands, particularly Birkenstock, UGG and Blundstone. The observation reflects broader changes in Canadian lifestyles, where comfort has become an everyday expectation rather than a specialized category.

The company continues to see its role as a curator of trusted brands rather than a trendsetter. Customers visit Quarks knowing they will find recognized labels, knowledgeable advice and an assortment that reflects both current demand and the company’s long experience in the footwear business.

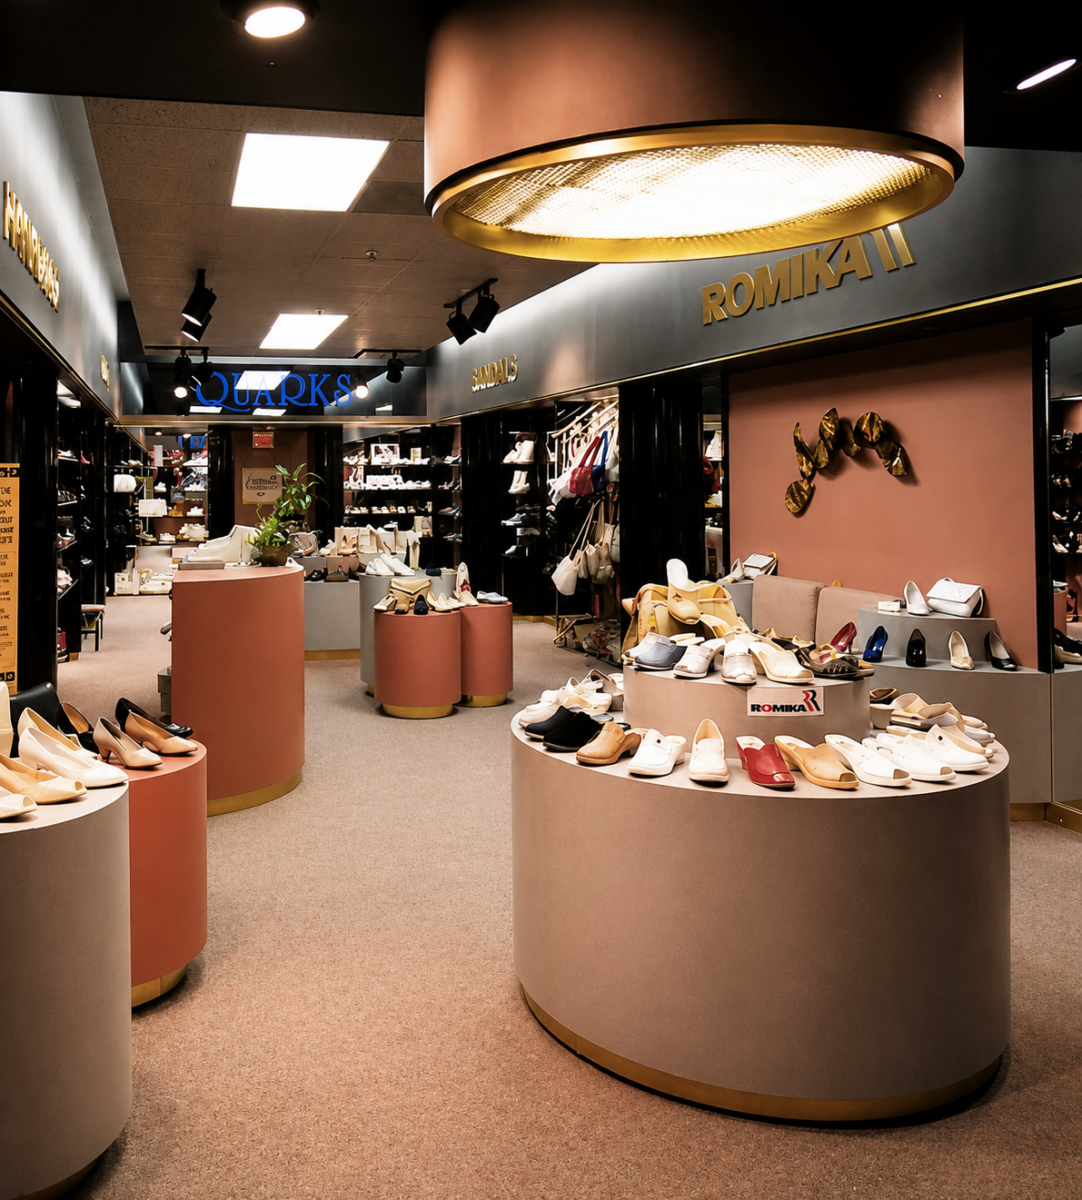
Quarks store at Unicity Mall in Winnipeg, 1985. Photo: Quarks

Service as a Competitive Advantage

Although the footwear business has evolved dramatically since Quarks opened its first store, one aspect of the customer experience has remained largely unchanged.

The company continues to believe that footwear is best sold with knowledgeable service. Associates are encouraged to greet customers, understand how footwear will be used, discuss fit and comfort, and recommend products that meet individual needs. That approach reflects a belief that purchasing shoes is often more personal than many other retail categories, particularly when customers are looking for comfort, support or a specific fit.

“Our associates aren’t just cashiers,” Tom Quark said. “They’re actually helpful people who listen.”

Kristy Krahn said the company organizes its culture around four core values: care, listen, advise and serve. Those principles influence everything from hiring and employee development to the way staff interact with customers on the sales floor.

Listening to the discussion, it became apparent that the Quark and Krahn families view service as part of the product itself. Customers may initially visit Quarks because they recognize brands, but the company believes knowledgeable advice remains one of the reasons shoppers continue returning.

That commitment has become increasingly relevant as traditional footwear departments have disappeared from many Canadian department stores. Consumers who once relied on experienced footwear associates now have fewer places to receive that level of assistance, creating an opportunity for specialty retailers that continue to invest in service.

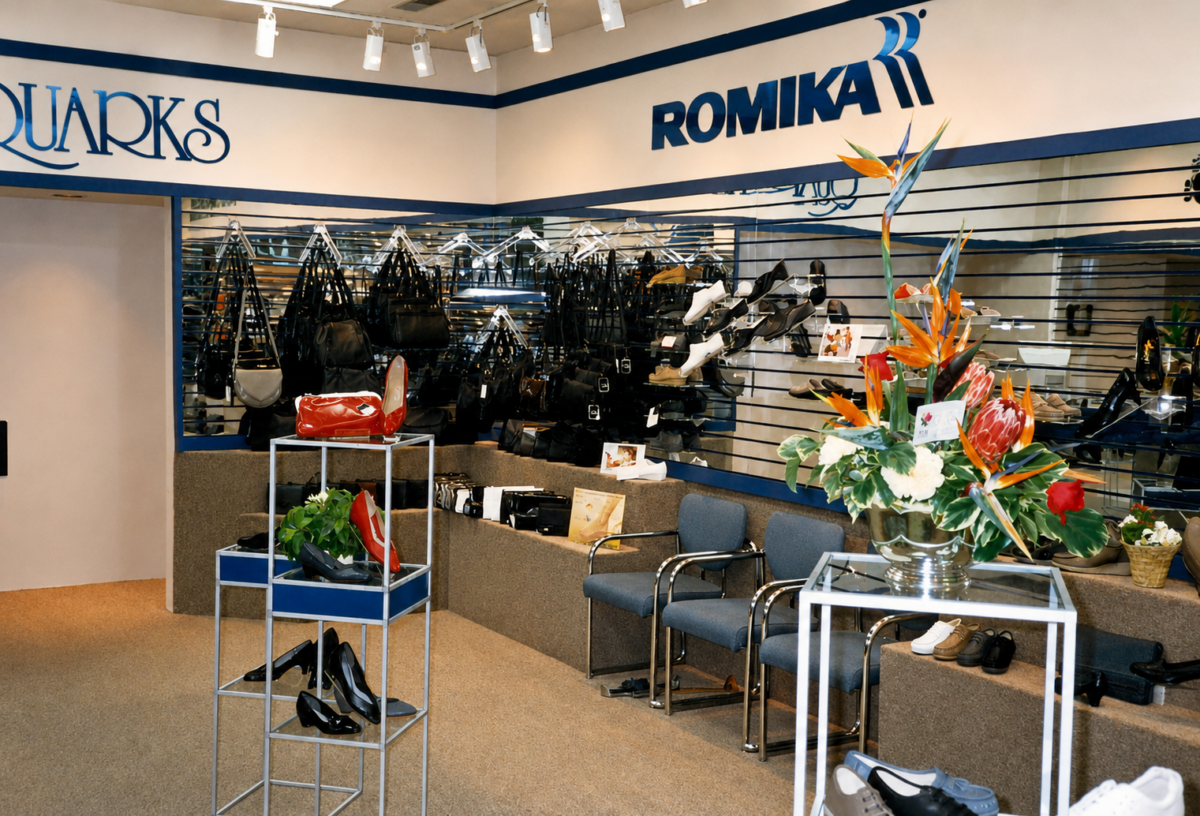
Quarks Westwood store in the late 1970s. Photo: Quarks

Physical Stores and Digital Retail Working Together

Quarks has embraced e-commerce while continuing to invest in physical retail, viewing the two channels as complementary rather than competing with one another.

The company began selling online on a relatively modest scale before steadily expanding its digital business. Like many retailers, Quarks experienced a significant increase in online sales during the pandemic. Unlike some businesses that saw demand return almost entirely to stores, much of that growth remained after restrictions ended.

Ryan Krahn said customers have become increasingly comfortable purchasing footwear online, particularly when buying brands and styles they already know. Improvements in shipping, returns and exchanges have also made online footwear shopping easier than it once was.

Rather than treating e-commerce as a separate business, Quarks has focused on connecting it with the in-store experience. Customers can reserve products online before travelling to a store, ensuring that the correct size is waiting when they arrive. For many shoppers in the regional communities Quarks serves, that convenience eliminates uncertainty and makes the trip more worthwhile.

The relationship works in the opposite direction as well. Ryan Krahn said the company has consistently observed stronger online sales after opening new stores, suggesting that physical locations continue to build awareness of the Quarks brand while introducing customers to its broader assortment.

To support its continued digital growth, Quarks partnered with London, Ontario-based Northern Commerce in 2025, selecting a larger agency with deeper retail specialization to help strengthen its e-commerce and digital marketing capabilities.

For the Quark and Krahn families, the discussion is no longer about choosing between stores and online shopping. Customers move comfortably between both channels, and the business has adapted to support that behaviour.

Quarks store at Unicity Mall in Winnipeg, 1985. Photo: Quarks

Investing in the Future

As Quarks has expanded, the company has continued investing in its stores as well as its people.

The recently opened Victoria location reflects the retailer’s latest store design, creating a brighter, more contemporary environment while introducing an expanded children’s footwear department. Another store is planned for Saskatoon, continuing the company’s gradual expansion across Western Canada.

Today, Quarks employs approximately 310 people throughout the year, with staffing increasing during the holiday season as the retailer operates approximately 15 seasonal pop-up stores. Although the business has grown significantly since its early years in Winnipeg, it remains closely involved in the communities where it operates.

One initiative that has become particularly important is Walking People Out of Poverty, a fundraising partnership with Opportunity International Canada. The program supports entrepreneurs, particularly women, in developing countries through access to financial services and business opportunities. Quarks also participates in local food bank campaigns, footwear donation initiatives and community programs organized by individual stores across Canada.

Leadership responsibilities have also evolved as the second generation has assumed greater responsibility for the business. Kristy Krahn currently serves as President and oversees finance, human resources and real estate. Doug Quark focuses primarily on buying and store design, Tom Quark plays a key role in merchandising, while Ryan Krahn leads much of the company’s digital strategy and e-commerce development.

That transition reflects a succession process that has unfolded gradually over many years. After Dave Quark retired, Albert Krahn continued leading the company as President and Chief Financial Officer alongside the second generation, helping ensure that the values and long-term perspective established by the founders continued as leadership responsibilities evolved.

Looking Ahead

As Quarks approaches its 50th anniversary, the milestone represents an opportunity to recognize the people who helped build the company while continuing to prepare for its next chapter.

The Quark and Krahn families believe one of the retailer’s strengths is that it has never tried to become something it isn’t. Instead, Quarks has remained focused on serving customers through recognizable footwear brands, knowledgeable staff and a measured approach to expansion that reflects the realities of each market it enters.

Kristy Krahn said those priorities remain unchanged.

“Our focus is really going to remain the same as it has since 1977,” she said. “We want to continue to grow thoughtfully, steward the business responsibly and have a positive impact in the communities and amongst the people that we serve.”

The company also plans to place greater emphasis on its Canadian heritage as it approaches the anniversary. Although Quarks has operated in communities across the country for decades, many customers are still surprised to learn the retailer was founded in Winnipeg and remains Canadian owned.

That history has been shaped by two families whose complementary strengths helped build a business that has endured through changing markets, changing consumer preferences and changing generations of leadership. Dave Quark’s vision for the customer experience, combined with Albert Krahn’s financial discipline and strategic leadership, established a foundation that continues to guide the company today.

Nearly five decades after the first Quarks store opened its doors, the conversation around the boardroom table is no longer about how the company reached its 50th anniversary. It is about where the next opportunity will be found, how the business can continue serving its customers and how the next generation can build on what came before.

Every Quarks store represents years of relationships with customers, employees, suppliers, landlords, and the communities it serves. As the company prepares for its next chapter, the focus remains the same as it has been since 1977: grow thoughtfully, serve customers well and continue building a business that will be as strong for the next generation as it has been for the last.

More from Retail Insider:

Tim Hortons Targets Stronger Canadian Growth With New Stores, Beverages and Loyalty

Photo: Tim Hortons

Tim Hortons is pressing ahead with 80 new Canadian restaurants, hundreds of renovations and a broader beverage and loyalty strategy after sales growth at existing locations nearly stalled during the second quarter.

Comparable sales at Tim Hortons restaurants in Canada increased just 0.1% during the three months ended June 30, down sharply from the growth recorded over the previous year. The result stood out against stronger consolidated performance at parent company Restaurant Brands International, where Burger King and the company’s international operations drove much of the quarter’s momentum.

RBI executives attributed the slowdown largely to Tim Hortons’ own marketing and product calendar while maintaining that the broader Canadian foodservice environment remained relatively stable. Management is now counting on restaurant development, cold beverages, afternoon food occasions, a stronger promotional calendar and a forthcoming Canadian Tire loyalty partnership to generate renewed momentum.

Canadian Sales Growth Slows Sharply

The second-quarter result continued a marked deceleration for Tim Hortons in its home market. Canadian comparable sales grew 3.6% during the same quarter last year, followed by growth of 2.8% in the fourth quarter of 2025 and 1.5% in the first quarter of 2026. By the second quarter, growth had slowed to almost zero.

RBI Chief Executive Officer Josh Kobza said Tim Hortons maintained its leadership positions in coffee, breakfast and baked goods, but acknowledged that the company’s marketing calendar did not produce the results management had expected. The brand was also comparing against several major product launches from the previous year.

Results improved as the quarter progressed, according to management, helped in part by the return of Tim Hortons Melts. Kobza described Melts as one of the menu items customers had most frequently requested.

RBI did not primarily blame the slowdown on a weakening Canadian consumer.

Kobza characterized the country’s broader economic conditions as relatively stable and said Canadian foodservice sales grew by approximately 3% during the quarter. Some chains were performing better than others, he said, but Tim Hortons’ performance remained largely within the company’s control. That assessment places greater weight on the brand’s ability to restore growth through stronger products, marketing and execution.

Why Tim Hortons Is Still Opening Restaurants

The slowdown has not changed Tim Hortons’ Canadian development plans. The company expects to open approximately 80 restaurants across every province in 2026, compared with more than 50 openings last year. Most will be conventional drive-thru locations, which RBI says can provide franchisees with investment payback periods of less than three years.

The openings form part of a previously announced $400-million Canadian investment by Tim Hortons and its restaurant owners. Restaurant owners are expected to contribute approximately $270 million, while Tim Hortons will invest about $130 million. The program also includes renovations at roughly 400 existing locations.

Approximately 60 restaurant owners are involved in the new development program, while about 280 owners are participating in renovations. The level of franchisee investment indicates continued confidence in Canadian development even as comparable-sales growth has softened.

New restaurants can produce attractive returns even during a period when growth across the established restaurant base has slowed, particularly as population growth and development create new opportunities for convenient quick-service locations.

Tim Hortons and its restaurant owners operate approximately 4,000 locations in Canada, giving the brand extensive national coverage. Opening another 80 restaurants will add system sales and expand that footprint, but producing stronger growth across thousands of established restaurants will have a much larger effect on the Canadian business.

Building Business Beyond Breakfast

Cold beverages and afternoon visits have become central to that effort. Tim Hortons recently introduced matcha nationally, providing a new platform aimed partly at customers who may not visit the chain for its traditional hot coffee and breakfast offerings.

Kobza said matcha has a strong connection to cold beverages and afternoon consumption, a period Tim Hortons is working to develop as a larger part of its business. The strategic value of the launch therefore extends beyond a single drink, giving Tim Hortons a platform for additional innovation while helping the chain compete for visits outside its dominant morning daypart.

Tim Hortons is also installing new fountain equipment across its Canadian restaurant network. Management says the equipment will improve operational efficiency while supporting a wider range of cold beverages, including Soda Swirls, the company’s entry into the “dirty soda” category in which soft drinks are combined with flavoured syrups, cream or other ingredients.

RBI said Tim Hortons has increased the pace of cold-beverage innovation and expects more launches over the next six to 12 months. The broader goal is to create additional reasons for customers to visit throughout the day.

A customer who already associates Tim Hortons with morning coffee may need a different product or occasion to return later in the day. Matcha, fountain beverages and additional food options are intended to build those incremental visits, bringing Tim Hortons into greater competition with chains that have developed substantial businesses around iced drinks, customized beverages and afternoon snacks.

Canadian Tire Partnership Targets Frequency

Tim Hortons is also preparing to launch its loyalty partnership with Canadian Tire during the second half of 2026. The partnership will allow customers to connect their Tims Rewards and Triangle Rewards accounts, continuing to collect Tims Rewards points while also earning Canadian Tire Money on eligible Tim Hortons purchases.

Linked customers are expected to receive offers through both programs, while eligible Triangle credit-card users will have additional earning opportunities. The arrangement brings together two of Canada’s most prominent loyalty ecosystems and connects a high-frequency restaurant purchase with a broader retail rewards program.

For Tim Hortons, the partnership provides another mechanism for encouraging repeat visits by giving customers an additional reward when choosing the chain for routine food and beverage purchases.

RBI highlighted the Canadian Tire relationship several times during its earnings call, positioning it as an important component of the brand’s second-half strategy. The launch also comes as restaurant operators across Canada continue to compete heavily on value, an area where Tim Hortons says it maintains a leading consumer perception.

New Competition Approaches

Tim Hortons’ effort to accelerate beverage innovation comes as Dunkin’ prepares to return to Canada. During RBI’s earnings call, an analyst asked management whether Tim Hortons needed to move more quickly as a prominent northeastern U.S. chain prepared to re-enter the market.

The reference was to Dunkin’, which has signed a Canadian master-franchise agreement with Montreal-based restaurant company Foodtastic. The first returning Dunkin’ location is expected to open in late 2026 or early 2027. Foodtastic has discussed a long-term opportunity for hundreds of Canadian restaurants, although those figures represent an ambition and not a near-term development commitment.

Dunkin’ previously operated extensively in Canada before leaving the market in 2018. Its returning Canadian business will begin from a dramatically smaller base than Tim Hortons, while Foodtastic brings established restaurant-development experience through a portfolio that includes Second Cup, Freshii and other concepts.

RBI executives showed little concern about the prospect of renewed competition. Kobza said restaurant markets are always competitive and pointed to Tim Hortons’ accelerating cold-beverage pipeline as evidence that the company is responding to changing customer preferences.

RBI Executive Chairman Patrick Doyle emphasized Tim Hortons’ scale, franchisee network, value position and continuing restaurant investment. He argued that recent competitive announcements would not fundamentally alter the Canadian landscape over the longer term.

Dunkin’ is unlikely to challenge Tim Hortons’ national scale in the near term, but its return could add competition in individual markets and beverage categories. The questions from analysts also show the attention being paid to Tim Hortons’ ability to innovate as competitors pursue many of the same cold-beverage and afternoon occasions.

The Test for the Second Half

Tim Hortons has several initiatives planned for the remainder of the year. The company has launched matcha, returned Melts to the menu and is preparing a Harry Potter: Back to Hogwarts promotion featuring themed baked goods and beverages. New breakfast flavours and another major holiday partnership are also planned.

Those promotions could generate short-term traffic, while the more consequential question is whether Tim Hortons can create customer behaviour that continues after individual campaigns end. Cold beverages, afternoon food, restaurant renovations and the Canadian Tire loyalty partnership are all intended to create more frequent and varied reasons to visit.

Tim Hortons enters the second half with considerable advantages in Canada, including extensive national scale, established consumer awareness and restaurant owners willing to invest substantial capital in new and existing locations.

The second-quarter result showed that those advantages do not automatically translate into continued comparable-sales growth.

The planned 80 openings will expand the system and add sales. The bigger test is whether Tim Hortons can generate more visits across the approximately 4,000 Canadian restaurants it already has.

The performance of its beverage pipeline, promotional calendar and loyalty partnership over the coming quarters will help show whether the 0.1% result was a temporary interruption or an indication that growth in Tim Hortons’ mature home market is becoming more difficult to generate.

More from Retail Insider:

Wholesale and retail sector lead a surge in job growth in July, but level still off from a year ago: Statistics Canada

AI25.Studio Studio photo

Employment increased by 75,000 (+0.4%) in July and the employment rate rose 0.1 percentage points to 60.9%. The unemployment rate declined 0.1 percentage points to 6.4%, the lowest rate since July 2024, reported Statistics Canada on Friday.

Employment increased in wholesale and retail trade (+21,000; +0.7%); finance, insurance, real estate, rental and leasing (+18,000; +1.2%); professional, scientific and technical services (+17,000; +0.8%); as well as in construction (+16,000; +1.0%). In contrast, employment declined in public administration (-15,000; -1.2%) and agriculture (-9,600; -4.3%), noted the federal agency.

“Wholesale and retail trade (+21,000; +0.7%) recorded the largest employment increase across industries in July. Despite the monthly increase, employment in this industry was down by 50,000 (-1.7%) compared with 12 months earlier, largely reflecting a downward trend observed from January to May 2026,” said Statistics Canada.

Overall employment rose among core-aged people (25 to 54 years old) (+51,000; +0.4%), mostly for women in that age group (+33,000; +0.5%), it said.

The unemployment rate for core-aged women fell 0.3 percentage points to 5.2%, while it held steady for core-aged men (5.8%), youth (12.6%), and people aged 55 and older (5.2%).

There were more people working in Ontario (+52,000; +0.6%), British Columbia (+18,000; +0.6%), Manitoba (+5,900; +0.8%), and Nova Scotia (+4,600; +0.9%).

Average hourly wages among employees were up 2.8% (+$1.01 to $37.17) on a year-over-year basis in July, following growth of 3.3% in June (not seasonally adjusted), added Statistics Canada.

MART PRODUCTION photo

Since April, total employment was up by 181,000 (+0.9%), driven by a rise in full-time work (+193,000; +1.1%), said Statistics Canada.

The employment rate—the proportion of the population aged 15 and older who are employed—increased by 0.1 percentage points to 60.9% in July. The rate was up 0.2 percentage points compared with 12 months earlier, it said.

“In July, the number of private sector employees rose (+58,000; +0.4%), as did the number of self-employed workers (+44,000; +1.6%). These gains were partially offset by a decline in the number of public sector employees (-27,000; -0.6%). Since April, employment growth has been concentrated among private sector employees (+146,000; +1.1%) and self-employed workers (+73,000; +2.7%),” explained Statistics Canada.

Unemployment rate by province and territory, July 2026

Thumbnail for map 1: Unemployment rate by province and territory, July 2026

Restaurants Canada said restaurants were the biggest creator of youth jobs in July compared to last year, according to Statistics Canada’s latest Labour Force Survey.

“In the first seven months of 2026, the restaurant and accommodation industry employed an average of 51,400 more young people than during the same period last year, a 11.4% increase, with restaurants accounting for 85% of those jobs,” said the national organization in a LinkedIn post. “Restaurants are Canada’s leading source of first-time jobs and career-building opportunities, representing one in six youth jobs.

“As youth unemployment remains a national challenge, investing in restaurants means investing in the next generation of Canada’s workforce.”

Andrew Grantham, Senior Economist, CIBC Capital Markets, said the report suggests that growth momentum seen in the second quarter may have carried on into the start of Q3.

“However, at 6.4% the unemployment rate is still roughly half a per cent higher than where we estimate full employment lies, and therefore not yet at a level that will fuel domestically-driven inflation. As a result we continue to see the Bank of Canada remaining on hold this year and into the start of 2027.”

Doug Porter, Chief Economist, BMO Capital Markets, said: “Not unlike the GDP bounce from weakness at the turn in the year, the job figures are very much echoing the rebound. But, perhaps also like the GDP results, the recent job growth likely exaggerates the underlying strength in the economy. Even with the flashy headlines, we suspect that the yearly trend in both is more indicative of economic reality—job growth of just under 1% y/y and GDP growth of just under 2% y/y. Still, the big July gains are a hint of building momentum after the Q2 rebound, even as trade uncertainty still looms over the outlook. With wage growth taming further and energy prices more moderate, the BoC won’t take on a more hawkish tone yet, though a strengthening economic backdrop will could eventually push them in that direction if it persists.”

Andrew Hencic, Senior Economist, TD, said it was another strong labour market report.

“Beyond just the jobs gains, the fall in the unemployment rate was encouraging given hiring outpaced a sizeable 61K gain in the labour force. This shows the economy was able to absorb more labour market slack in July. When coupled with the strong bounce-back in activity in the second quarter, some additional momentum on jobs in July is nice to see,” he said.

“The labour market is showing clear signs of recovery, but the 6.4% unemployment rate continues to signal an economy operating with some slack. Together with the prospect of new tariffs coming into effect on August 19th, the downside risks to the economy remain. We continue to expect the unemployment rate to gradually decline in the coming months as the economy deals with the volatility in energy prices and potentially more trade headwinds. Given this backdrop we expect the Bank of Canada to stay on hold for the rest of the year.”

More from Retail Insider:

Canada’s Freight Market Is Shifting Unevenly. Here’s What Retailers Should Watch

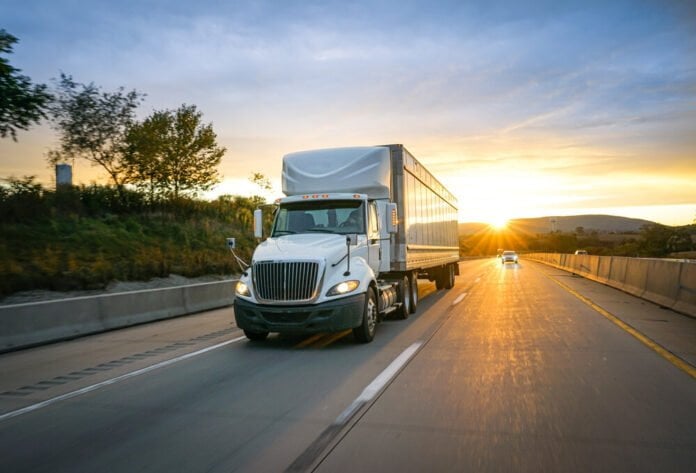
White semi truck on a highway. Photo: iStock

Canada’s freight market is becoming increasingly uneven, creating new challenges for retailers trying to balance transportation costs, inventory levels and customer service expectations.

Gary Newbury

TFI International’s latest quarterly results suggest truckload transportation is strengthening while other parts of the freight market remain under pressure, reinforcing what supply chain experts say is becoming a more selective transportation environment. For retailers preparing for the important fall and holiday selling seasons, those differences could influence everything from inventory planning to transportation contracts and fulfillment costs.

“Canada’s freight market is not recovering in one piece,” said Gary Newbury, a Canadian supply chain strategist. “Conditions are strengthening in parts of truckload and specialised transportation, while steel, forestry and some consumer-facing activity remain comparatively weak.”

He said retailers should be cautious about planning around national averages or broad statements that the freight market is improving.

“The next capacity squeeze is likely to emerge by lane, service and product category before becoming visible in market-wide data,” Newbury said. “Transportation networks should be segmented into stable, vulnerable and potentially constrained flows, with capacity and contingency arrangements concentrated where the commercial exposure is greatest.”

Freight activity tells only part of the story

TFI reported stronger overall results during the second quarter, supported by improvements in its truckload and logistics businesses. Less-than-truckload transportation presented a different picture, with shipment volumes increasing while revenue per shipment declined, illustrating the pricing pressures that continue across parts of the market.

Company executives said pricing actions are expected to reduce lower-value freight while improving profitability. Management also described Canadian less-than-truckload demand as remaining relatively soft.

For retailers, the results illustrate an important point: higher shipment volumes do not automatically produce better financial performance.

“More freight did not automatically create more bottom-line value,” Newbury said.

The same principle applies throughout retail supply chains. Additional orders can create warehouse handling costs, split deliveries, returns, expedited replenishment and customer-service expenses that are not immediately apparent when a sale is recorded.

“Retailers can make the same mistake as carriers: pursuing additional volume that adds activity and complexity without adding sufficient margin,” Newbury said.

That distinction has become increasingly important as retailers serve customers through stores, e-commerce, marketplaces and direct-to-consumer channels. Two orders with identical sales values may generate very different profits depending on shipping distance, product size, delivery requirements and return rates.

Retailers selling furniture, appliances, home improvement products or seasonal merchandise may also experience freight conditions differently than businesses shipping smaller products such as apparel, cosmetics or accessories.

Driver Inc. enforcement may reshape parts of the market

Recent federal tax reporting and enforcement measures are beginning to reshape parts of Canada’s trucking industry.

The Canada Revenue Agency has lifted a moratorium on penalties for trucking companies that fail to report certain qualifying service payments. Beginning with the 2025 tax year, trucking businesses are required to report payments exceeding $500 to Canadian-controlled private corporations operating in the industry on T4A slips.

The measures are intended to improve tax compliance and address arrangements associated with the Driver Inc. model, under which some drivers provide their services through corporations instead of being treated as employees.

Federal officials have said non-compliance has allowed some operators to undercut compliant competitors while reducing employee protections and benefits.

During TFI’s earnings call, Chairman, President and CEO Alain Bédard said additional reporting requirements are beginning to affect the Canadian market, although Driver Inc. remains an issue.

Newbury said the gradual removal of artificially inexpensive capacity could lead to higher freight rates in some areas, although he believes retailers should view those increases in context.

“If artificially cheap capacity leaves the market, some rates will rise, but this should be viewed as the removal of an unsustainable subsidy rather than a new logistics cost,” he said.

Many large retailers already conduct financial, insurance and safety reviews before selecting transportation partners. Newbury believes they should also identify where their supply chains depend on unusually low freight rates, extensive subcontracting or financially fragile carriers.

“The greater risk is not paying slightly more; it is discovering during a peak period that the capacity being relied upon was never economically or legally sustainable.”

As retailers prepare for seasonal shipping peaks later this year, understanding where transportation capacity is genuinely resilient may prove more valuable than simply securing the lowest available rate.

Looking beyond the freight invoice

Transportation costs no longer dominate headlines as they did during the pandemic, but they continue to influence retail profitability.

The Bank of Canada’s second-quarter Business Outlook Survey found that many Canadian businesses continue to face higher costs associated with fuel, shipping and transportation while experiencing limited ability to pass those increases along to customers.

Newbury said retailers should continue monitoring landed costs while developing a more detailed understanding of cost-to-serve by product, customer and sales channel.

The quoted freight rate is only one component of transportation cost.

Inventory carrying expenses, split shipments, emergency expedites, service failures, customer-service recovery and markdowns can quickly outweigh the savings achieved through a lower transportation contract.

A delayed shipment of seasonal merchandise may reduce full-price selling opportunities and increase markdown exposure. An unreliable carrier can also create additional labour costs, replacement shipments and customer-service issues that ultimately exceed the difference between competing freight rates.

Understanding those trade-offs allows retailers to evaluate transportation decisions within the broader context of profitability instead of focusing exclusively on the freight invoice.

Scenario planning needs decision triggers

Tariffs and Canada-U.S. trade uncertainty continue to influence transportation planning across several industries.

TFI said freight related to steel and forestry products remains comparatively weak, reflecting ongoing trade uncertainty and slower activity in those sectors.

Many retailers already model different tariff, sourcing and demand scenarios. Newbury said the greater challenge is deciding in advance when those plans should change.

“What tariff, freight rate, exchange rate, or lead-time threshold will cause inventory to be repositioned, orders to be reduced, or supply to move elsewhere?” he said. “Who has authority to act, and within what working-capital limits?”

Those questions become increasingly important because inventory, merchandising, finance and transportation decisions are closely connected.

“Without those decisions being agreed in advance, scenario planning risks becoming an impressive collection of spreadsheets followed by the usual emergency meeting,” Newbury said.

Predetermined decision points can help retailers respond more quickly when market conditions change while reducing the temptation to overreact to short-term disruption.

Preparing for a more selective freight market

Newbury expects Canadian transportation capacity to tighten gradually and unevenly during the next 12 months instead of developing into a broad nationwide shortage.

That outlook generally aligns with TFI’s latest results, which point to stronger conditions in truckload transportation while other parts of the freight market continue to recover more slowly.

Retailers may benefit from protecting transportation capacity on priority routes without making unnecessary commitments across their entire distribution networks.

In an environment where freight conditions vary significantly by product category, region and transportation lane, flexibility may prove more valuable than securing the lowest freight rate or carrying additional inventory.

“The advantage will not belong to the retailer holding the most inventory or securing the lowest freight rate,” Newbury said. “It will belong to the one able to identify the trade-offs earlier and act before uncertainty becomes cost.”

More from Retail Insider:

Jamieson Wellness enters into definitive agreement to be acquired by Kirin in C$2.5 billion transaction

Jamieson Wellness photo

Jamieson Wellness Inc., manufacturer and marketer of Canada’s #1 vitamins, minerals and supplements brand, announced Thursday that it has entered into a definitive arrangement agreement with Kirin Holdings Company, Limited where Kirin has agreed to acquire all of the issued and outstanding common shares of Jamieson at a price of C$45.75 per share in cash.

The transaction values Jamieson at approximately C$2 billion on a fully diluted equity value basis and approximately C$2.5 billion on an enterprise value basis. The consideration represents a 27% and 32% premium to the 20-day volume-weighted average price and 60-day VWAP on the Toronto Stock Exchange, respectively, for the period ending June 24, the last full day of trading prior to the media report and the company’s press release confirming the initiation of a process in regard to a potential transaction, said a news release.

“Today marks an exciting new chapter for our Company and for our iconic 104-year-old brand,” said Mike Pilato, President and CEO of Jamieson Wellness. “I am incredibly proud that our business will continue to flourish globally under the stewardship of a company with an even longer history and a deep commitment to health and wellness.

“From the beginning, it was clear that Kirin recognizes the importance of our heritage, our people, and our Canadian roots. Just as importantly, they are committed to investing in our brands. As a global C$22 billion leader in beverage, natural health, and consumer health, they bring the expertise, reach, and resources to help take our brands to the next level while preserving what has made Jamieson successful for more than a century.

“I want to sincerely thank our team, whose passion, commitment to our values, and entrepreneurial spirit have built this remarkable company over generations. Their belief in our Purpose of Inspiring Better Lives Every Day has enabled us to create a business that is respected both in Canada and around the world. I also want to thank our Board of Directors, partners, customers and shareholders for their trust and support throughout our journey. I firmly believe this transaction represents the best possible outcome for our Company, our talented team, and our shareholders. I look forward to working closely with our new colleagues as we continue building on our momentum from Toronto to drive growth globally for many years to come.”

“The Board carefully evaluated this transaction and unanimously concluded that it represents the best path forward for our Company and our shareholders,” said Tim Penner, Chair of the Board of Jamieson Wellness. “Throughout this process, our priority was to find a partner that not only recognized the significant value of our business and brands, but also shared our long-term commitment to our Purpose and values, innovation, and responsible growth.

“We are particularly pleased to have found a partner that appreciates the extraordinary heritage of this 104-year-old Canadian company and is committed to preserving and building upon that legacy. While today marks the end of one chapter in our company’s history, it also marks the beginning of an exciting new one. We believe this partnership will ensure that this iconic Canadian company, its brands, and its values continue to thrive for generations to come.”

“We are delighted to welcome Jamieson Wellness to the Kirin Group,” said Takeshi Minakata, COO of Kirin. “Kirin has deep respect for the Company’s rich heritage, the trust it has built with consumers, and the values that have guided its success over generations. This Transaction represents an important milestone in Kirin’s long-term growth strategy and a significant step in expanding our Health Science business into North America, the world’s largest vitamins and dietary supplements market. We look forward to supporting Jamieson Wellness’ continued success and creating sustainable value together for consumers, employees, shareholders, and communities.”

Jamieson Wellness photo

“The acquisition of Jamieson Wellness marks an important step in advancing Kirin’s Health Science vision to become a global leader in preventative health,” added Alastair Symington, CEO & Managing Director of Blackmores Limited. “It brings trusted brands, strong capabilities in innovation, brand building, manufacturing and go-to-market execution, and a scalable platform in the important North American market. Together, Kirin, Blackmores, FANCL and Jamieson Wellness strengthen a global platform now connecting North America, Asia and Oceania. By bringing together the distinctive strengths of our brands, the rich heritage of our businesses and the depth of talent from within our organisations, we will be better positioned to deliver preventative health solutions to more consumers globally while accelerating sustainable growth and long-term value for our customers.”

Kirin Holdings Company, Limited is a global company operating across five core business domains spanning Alcoholic Beverages, Non-alcoholic Beverages & Health Science, Non-alcoholic Beverages, Health Sciences, and Pharmaceuticals. The company traces its roots to Japan Brewery, established in 1885, which later became Kirin Brewery in 1907. Since then, Kirin has expanded its business operations by leveraging fermentation and biotechnology as core strengths. The company entered the pharmaceutical field in the 1980s, which has since grown into a global business. In 2007, the company transitioned to a pure holding company structure as Kirin Holdings, and it is now strengthening its Non-alcoholic Beverages & Health Science domain.

Jamieson Wellness is dedicated to “Inspiring Better Lives Every Day” with its portfolio of innovative natural health brands. Established in 1922, the Jamieson brand is Canada’s #1 vitamins, minerals and supplements brand. The company’s youtheory brand, acquired in 2022, is an established and growing lifestyle brand in the U.S. Combined, these global brands are available in more than 50 countries worldwide. The company also offers a variety of innovative VMS products as well as sports nutrition products to consumers in Canada with its Progressive, Smart Solutions, Iron Vegan and Precision brands.

Jamieson Wellness’ head office is located at 1 Adelaide Street East Suite 2200, Toronto.

More from Retail Insider:

Slate Grocery REIT reports second-quarter results, citing leasing gains and rent growth potential

Photo: Slate
Photo: Slate

Slate Grocery REIT reported second-quarter results Thursday, saying it completed more than 569,000 square feet of leasing activity during the period as it continued to see rental growth across its U.S. grocery-anchored real estate portfolio.

The real estate investment trust said leasing activity during the three months ended June 30, 2026 included renewals completed at higher rents and new agreements above existing in-place rental rates, while maintaining occupancy across its portfolio.

“We continue to have strong conviction in the outlook for our portfolio of high-quality grocery-anchored real estate,” said Blair Welch, Chief Executive Officer of Slate Grocery REIT. “In the second quarter, our team completed over 569,000 square feet of leasing at consistently high rental spreads. With our in-place portfolio rents still meaningfully below market, we believe the REIT is well positioned for continued long-term growth.”

Rent growth and occupancy

The REIT said renewals during the quarter were completed at 16.7 per cent above expiring rents, while new leasing deals were completed at 41.0 per cent above comparable average in-place rent.

Slate Grocery REIT reported that same-property net operating income, adjusted for completed redevelopments, increased by $3.8 million, or 2.3 per cent, in the second quarter on a trailing 12-month basis.

As of June 30, 2026, portfolio occupancy was 93.6 per cent. The REIT said average in-place rent across its properties was $13.10 per square foot, compared with a market average of $24.79 per square foot, leaving room for potential future rent increases.

Debt profile and valuation

The REIT reported that its weighted average interest rate was 5.0 per cent, with 90.2 per cent of its debt carrying fixed interest rates. It said the debt profile provides stability for near-term financing costs.

Slate Grocery REIT said its weighted average capitalization rate remains above its weighted average interest rate on outstanding debt, allowing it to maintain positive leverage. The REIT said the combination of valuation levels and continued growth in net operating income is expected to support portfolio valuation over time.

Portfolio strategy

The REIT owns and operates grocery-anchored real estate in major U.S. metropolitan markets. It said its portfolio includes properties anchored by grocery tenants and that it expects the assets to provide cash flow and potential capital appreciation over the longer term.

Slate Grocery REIT is managed by Slate Asset Management, a global alternative investor and manager focused on essential real estate and infrastructure assets.

More from Retail Insider:

Premium Brands reports record second-quarter revenue and earnings, revises 2026 outlook

Premium Brands photo

Premium Brands Holdings Corp. reported record second-quarter revenue and earnings on Thursday, while revising its 2026 sales and adjusted EBITDA guidance to reflect delays in certain product launches and customer promotional activity.

The specialty food producer and distributor said second-quarter revenue reached a record $2.4 billion, up 26.3 per cent, or $495 million, from the same period a year earlier. Organic sales growth was 7.5 per cent during the quarter.

Premium Brands owns specialty food manufacturing and differentiated food distribution businesses with operations across Canada and the United States.

Revenue and earnings increase

The company also reported record second-quarter adjusted EBITDA from continuing operations of $225 million, an increase of 29.5 per cent, or $51.2 million, from the second quarter of 2025. Adjusted earnings per share from continuing operations rose to a record $1.53, up 17.7 per cent, or 23 cents per share, from a year earlier.

Premium Brands said it generated record second-quarter steady state free cash flow of $116 million, or $2.22 per share, while net free cash flow for the quarter totalled $68.4 million. The company’s total debt-to-EBITDA ratio improved to 3.8:1 from 4.1:1 at the end of the first quarter of 2026.

“Our second quarter results provide an early indication of our earnings and cash flow potential as the investments we have made in recent years to position our company to benefit from fundamental changes occurring in the food industry begin to generate returns. Our sales grew by 26.3%, including 7.5% organic growth, our adjusted EBITDA and earnings per share grew by 29.5% and 17.7%, respectively, our total debt-to-EBITDA ratio fell to 3.8 : 1, and we are now once again generating solid net free cash flow,” said George Paleologou, president and chief executive officer.

Premium Brands photo

Outlook revised

The company said it completed the sale of its 74 per cent interest in Shaw Bakers and announced the shutdown of an older value-added beef processing facility during the quarter.

Premium Brands revised its 2026 sales and adjusted EBITDA guidance ranges, saying the changes were based mainly on delays in certain new product launches, including a customer’s decision to postpone several large promotions that had been scheduled for the second half of 2026 until early 2027.

Despite the revised guidance, the company reaffirmed that it remains on track to exceed its five-year plan targets for 2027 sales of $10 billion and adjusted EBITDA of $1 billion.

Growth strategy

The company said its U.S. Specialty Foods business made progress on its core growth initiatives during the quarter, generating organic volume growth of 10.7 per cent despite delays affecting some customer promotions and new product launches.

“As outlined in my recently published letter to shareholders titled “A New Food Order”, consumers’ growing focus on health and wellness, along with their evolving sophistication in measuring and tracking personal health data, is disrupting the food universe in unprecedented ways. Our portfolio of best-in-class premium food products that cater to three key mega food trends, namely high in protein, convenience and premiumization, combined with our new state-of-the-art production capacities and innovation capabilities, uniquely position us to capitalize on this disruption,” added Paleologou.

Premium Brands photo

Acquisitions and dividend

Premium Brands also said it continues to evaluate acquisition opportunities while maintaining its focus on strengthening its balance sheet.

“On the acquisitions front, we are evaluating several attractive opportunities, however, any transaction we complete will be done within the context of continuing to strengthen our financial position,” stated Mr. Paleologou.

Separately, the company’s board of directors approved a cash dividend of 85 cents per common share for the third quarter of 2026. The dividend will be paid on Oct. 15, 2026, to shareholders of record at the close of business on Sept. 30, 2026.

The company also said that, unless otherwise indicated in writing at or before the time a dividend is paid, each dividend paid in 2026 or a subsequent year will qualify as an eligible dividend for the purposes of the Enhanced Dividend Tax Credit System.

More from Retail Insider:

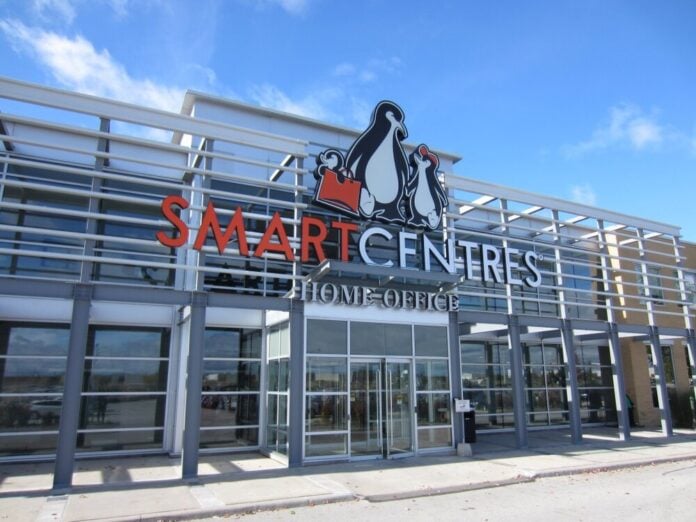
SmartCentres reports steady leasing gains in second quarter as occupancy rises, FFO unchanged

PHOTO: SMARTCENTRES

SmartCentres Real Estate Investment Trust reported higher occupancy, continued leasing activity and stable funds from operations in the second quarter, while posting a net loss driven largely by fair value adjustments on investment properties and financial instruments.

The Toronto-based REIT said occupancy reached 98.1 per cent as of June 30, up from the previous quarter, while funds from operations (FFO) per unit held steady at $0.58 compared with the same period a year earlier. Net operating income for the quarter totalled $139.9 million, down one per cent from the second quarter of 2025, while the trust reported a net and comprehensive loss of $147 million, compared with net income of $109.2 million a year earlier.

The results reflected continued leasing activity across the retail portfolio, progress on development projects and changes in the valuation of investment properties that weighed on earnings during the quarter.

“Building on Q1, we are pleased to report continued momentum in leasing demand and operational performance in Q2,” said Mitchell Goldhar, executive chairman and chief executive officer of SmartCentres. “Occupancy moved up to 98.1% with approximately 247,000 square feet leased during the quarter and rent growth of 12.0% (excluding Anchors). Same Property NOI increased by 2.6% (4.4% excluding Anchors), with very strong customer traffic and a strengthened tenant base. As of today, four of our six vacated Toys “R” Us locations have now been leased, at higher rents, with better tenant quality and covenants.

“Our development pipeline continues to add to the bottom-line with the initial opening of two self-storage projects in Quebec. In addition, two self-storage locations in British Columbia and one location in Alberta are currently under construction which will continue to add to the growth of the portfolio. Lastly, our two Premium Outlets continue to outperform with strong sales, rental growth and 99% occupancy; and the planned expansion at the Toronto Premium Outlets remains on track for construction commencement in Q4 of this year.”

Occupancy and leasing strengthen

The REIT said its in-place and committed occupancy rate increased by 0.5 percentage points from the first quarter to 98.1 per cent. Same-property net operating income rose 2.6 per cent from the same period in 2025, or 4.4 per cent excluding anchor tenants, supported by lease-up activity and higher rents.

SmartCentres said it extended 86 per cent of leases maturing in 2026. Rent growth on those renewals reached 12 per cent excluding anchor tenants and 6.6 per cent including anchor tenants.

Leasing activity remained active during the quarter, with approximately 247,000 square feet of vacant space leased. Three former Toys “R” Us locations were leased by the end of the quarter, with another leased after quarter-end. The REIT also said demand continued for newly developed retail space across its portfolio.

Development pipeline progresses

Construction continued on a 200,000-square-foot Canadian Tire flagship store in Toronto’s Leaside neighbourhood, with delivery to the tenant expected in the fourth quarter of 2026.

The REIT also acquired a 17-acre parcel in Winnipeg for about $10.1 million as part of its retail development program. The site is expected to be anchored by a Walmart operating under a 20-year lease.

Residential development also advanced during the quarter. SmartCentres said construction of the ArtWalk condominium project in Vaughan Metropolitan Centre continued, with about 93 per cent of the 340 units pre-sold. The underground parking structure has been completed, while formwork reached the ninth floor during the quarter.

Construction also began on a 65-unit rental building within the ArtWalk development, sharing the underground parking structure and related infrastructure with the condominium project.

The REIT expanded its self-storage portfolio during the quarter with the partial opening of facilities in Montreal (Notre Dame) and Laval East, Que. Construction continued on projects in Burnaby and Victoria, B.C., both expected to open in 2027, while work began on a facility in Edmonton (Allard) and construction contracts were awarded for another Edmonton location on 127 Avenue NW. The REIT and its partner are also seeking municipal approvals for two additional self-storage sites in Ontario and British Columbia.

SmartCentres photo
SmartCentres photo

Fair value losses weigh on earnings

Despite stable operating performance, SmartCentres reported lower earnings because of valuation adjustments.

Net operating income declined by $1.4 million from a year earlier, primarily because fewer townhome closings were completed following the sale of the final remaining townhome unit in the Vaughan NW project during the quarter. The decline was partly offset by higher rental income generated through leasing and renewals across the commercial portfolio.

FFO per unit was unchanged at $0.58, while FFO with adjustments declined to $0.54 per unit from $0.55 a year earlier. The REIT attributed the decrease primarily to higher interest costs and general and administrative expenses, partly offset by increased rental income.

The REIT’s net loss of $147 million compared with net income of $109.2 million in the second quarter of 2025. SmartCentres said the change primarily reflected a $196.2-million fair value loss on investment properties, driven by market conditions and the anticipated timing of construction starts for certain future development properties, partly offset by lower discount rates at selected retail properties.

The quarter also included a $42.4-million fair value loss on financial instruments, primarily related to changes in the value of units classified as liabilities following an increase in the REIT’s unit price.

More from Retail Insider:

Daily Synopsis: August 6, 2026

Welcome to the Daily Synopsis by Retail Insider. We hope you enjoy the 12 articles we published covering key developments in Canadian retail.

Birks Group will delist from the NYSE American and move to the OTCQB market as part of its financial restructuring amid improving sales and profitability. Mattel’s shifting Canadian strategy focuses on games, collectibles, and a Barbie reset to invigorate the toy market. Realm Fitness has created a 2,500-member community in a repurposed Calgary industrial space blending fitness, retail, and social events.

T&,T Supermarket is opening its first Manitoba store at CF Polo Park in Winnipeg by 2028, expanding its footprint. McDonald’s Canada’s new beverage platform is driving afternoon traffic and incremental sales with premium-crafted drinks. Optional coverage includes Baffin joining the Royer Group, and Corby selling the Lamb’s rum brand to focus on growth categories.

🗞️ The Day’s Retail Insider Article List

🌐 Canadian Retail News From Around the Web will return Monday. Have an excellent weekend.