Canada’s tight retail real estate market is giving landlords greater leverage in lease negotiations, with high occupancy and limited new supply allowing owners of well-located properties to push rents higher. Getting deals done, however, is becoming more complicated as retailers face higher occupancy and construction costs while landlords invest substantial amounts of capital into new stores and the redevelopment of former department-store space.
The issue was discussed at JLL‘s Retail Spotlight & Reception at TIFF Lightbox on October 5, ahead of ICSC@CANADA in Toronto, where Alan MacKenzie, CEO of JLL Canada, pointed to historically low retail vacancy while cautioning against viewing the market entirely through the lens of landlord leverage. MacKenzie encouraged what he described as a “partnership model” between landlords and tenants, with owners focused on getting transactions completed instead of extracting the last possible dollar from a deal, while tenants also need to demonstrate flexibility as the economics of developing and operating retail space change.
Public results from some of Canada’s largest retail landlords show why the negotiating environment has shifted. Occupancy is approaching capacity across some portfolios, while new and renewed leases are being completed at substantially higher rents.
Retail Occupancy Approaches Its Ceiling
RioCan REIT reported committed retail occupancy of 98.8% at the end of the second quarter of 2026, a record for the company. Its blended leasing spread reached 23.1%, including a 20.7% spread on renewals and 40.8% on new leasing.
The average net rent on RioCan’s new leases during the quarter was $37.73 per square foot, compared with an average of $23.58 per square foot across occupied space at quarter-end. The figures show how substantially available space can be repriced as leases expire and new tenants enter the portfolio.
The conditions extend beyond one landlord. CBRE’s Canadian retail research has found tight vacancy across several property formats and markets, with limited availability becoming an obstacle for retailers looking to expand in some high-growth areas.
For landlords with strong properties, those conditions provide an opportunity to increase rents and become more selective about which tenants receive scarce space. Retailers looking to grow, meanwhile, have fewer alternatives when the locations they want are already close to full occupancy.
Higher Rents Come With Higher Landlord Costs
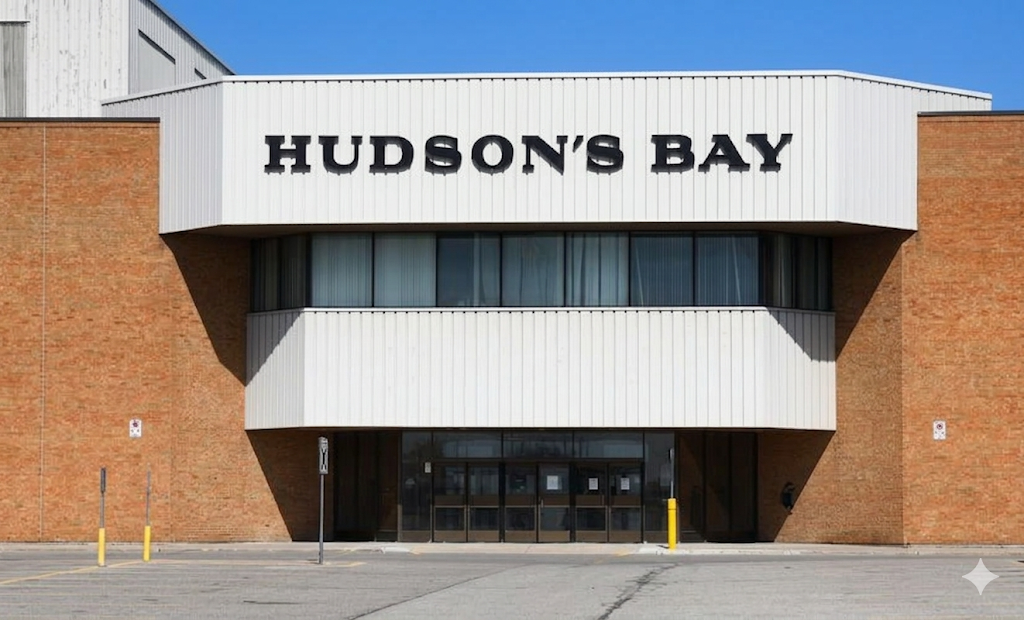
The collapse of Hudson’s Bay provides an unusually large example of those economics. Primaris REIT has been working to replace HBC across its enclosed-mall portfolio, where the former department-store spaces have created substantial vacancy as well as an opportunity to introduce multiple new tenants.
By late June, Primaris said approximately 881,400 square feet, representing 84% of its former HBC space, was either leased or in advanced negotiations. For the 608,500 square feet already committed or subject to conditional agreements at the time, Primaris expected annual rent to increase from approximately $3.7 million under HBC to $14.9 million from replacement tenants, an increase of almost 300%.
Capturing that additional rent requires substantial investment. Primaris expects to spend between $175 million and $225 million redeveloping its former HBC premises, reflecting the cost involved in converting department-store boxes for multiple new occupants.
Large anchor spaces often need to be physically divided, with new storefronts, entrances, mechanical systems and other infrastructure added before replacement tenants can operate. Landlords may also contribute directly toward tenant improvements, making the strength of the tenant, length of the lease and rent being paid important parts of the investment decision.
The Primaris example illustrates both sides of the current market. Replacing historically low department-store rents can produce significantly more revenue for landlords, but achieving that increase can require major capital investment before replacement tenants open their doors.
Retailers Face Their Own Cost Pressures
Higher rents are arriving alongside increased construction, labour and other operating costs, meaning retailers have to evaluate the total cost of opening and operating a store rather than rent alone. A location can generate substantial sales and still fail to meet a retailer’s investment criteria if occupancy and operating costs become too high.
The pressure is particularly visible in the restaurant sector. CBRE has noted that quick-service restaurant operators continue to expand while dealing with margin pressure from higher rent, labour and food costs, with some operators increasingly looking for existing restaurant locations that can be converted at a lower cost than building new premises from scratch.
A Canadian restaurant leasing survey found that 48% of respondents expected rent and occupancy costs to increase in 2026. Strong demand for second-generation restaurant space has allowed landlords to seek higher rents and stronger security from some operators, although tenant-improvement allowances and other landlord contributions remain part of the negotiation for certain deals.
Expansion therefore does not mean a retailer will accept the economics of every available site. Retailers can continue adding stores nationally while declining individual locations where rent, construction costs or required capital make the expected return unattractive.
Who Pays for Retail Expansion?
The negotiation becomes particularly important when a new store requires significant capital. Landlords generally want higher rent, longer lease terms and tenants with strong financial covenants, particularly when the owner is investing money into the premises.
Retailers, meanwhile, are trying to keep occupancy costs within acceptable levels while limiting the amount of capital required to open a location. A landlord that contributes heavily toward a new store needs sufficient rent and lease security to justify that investment, while the retailer has to determine whether the resulting occupancy cost leaves enough room for the location to generate an acceptable return.
MacKenzie’s call for a partnership approach reflects that reality. Low vacancy gives landlords bargaining power, but maximizing every component of a transaction does not necessarily produce the strongest long-term deal if the resulting store economics are difficult for the tenant to sustain.
Strong Tenants Still Have Leverage
Low vacancy does not necessarily mean all negotiating power has shifted to landlords. A shopping centre operating close to full occupancy can afford to be more selective about its tenant mix, considering which retailers provide stronger financial covenants, generate more traffic, complement existing tenants and are likely to remain productive over a long lease term.
That also makes successful retailers more valuable. A landlord may have several companies interested in a location, but a retailer with strong sales, a proven operating model and the ability to draw customers to the property can still bring considerable negotiating power to the table.
The result is a wider divide between stronger and weaker properties and tenants. Retailers with marginal store economics may face more difficult renewal negotiations at high-performing centres, while landlords with weaker properties can still find themselves competing for the retailers they want.
Not Every Landlord Has the Same Leverage
The difference between RioCan and Primaris illustrates why Canada’s retail market cannot be described uniformly. RioCan’s 98.8% committed retail occupancy reflects a portfolio heavily weighted toward necessity-based and mixed-use properties in major Canadian markets, while Primaris, which owns enclosed shopping centres across the country, reported committed occupancy of approximately 91.1% in the second quarter as its portfolio absorbed vacancies created by Hudson’s Bay.
The HBC closures have produced substantial empty space at some enclosed malls even as other types of retail property remain almost completely leased. Former department-store spaces also present a different leasing challenge because of their size, configuration and redevelopment requirements.
Location matters as well. A small unit in a highly productive grocery-anchored centre in a growing community may attract several competing tenants, while a large former anchor space requiring millions of dollars of redevelopment can produce an entirely different negotiation.
New Supply Remains Difficult to Build
More construction would eventually provide retailers with additional choices, but Canada’s retail development pipeline remains constrained. Elevated land and construction costs have made new retail projects more difficult to justify, particularly when existing market rents are below the level required to generate acceptable development returns.
Projects that do proceed increasingly require sufficient pre-leasing and rents that support the cost of construction. Tight supply therefore supports higher rents and can make new development more economically feasible, but those same occupancy costs can limit the number of retailers able to justify opening stores in newly constructed space.
The market increasingly rewards strong properties and strong retailers. Owners of high-performing real estate have more ability to choose tenants and negotiate higher rents, while retailers capable of generating strong sales, traffic and lease security remain attractive enough to retain bargaining power of their own.
As landlords redevelop former department stores and retailers continue looking for growth opportunities, the details of the lease are becoming increasingly important. Rent, lease term, tenant allowances and capital investment will determine which deals move forward and which proposed stores remain on the drawing board.