Home Blog Page 36

Loblaw Plans More No Frills and Maxi Stores in $1.2B Expansion

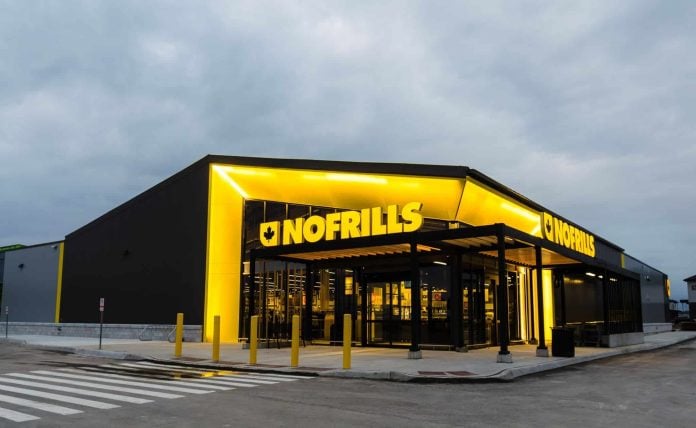
New concept No Frills store in Komoka. Image: Loblaw Companies

Loblaw Companies Limited is directing more of its capital toward discount grocery, with the country’s largest retailer planning approximately $1.2 billion in capital expenditures through the remainder of 2026.

The Brampton-based company expects to open approximately 75 grocery, pharmacy and other locations this year, compared with about 70 anticipated at the beginning of 2026. Loblaw says the increase reflects the performance of recently opened stores and confidence in the formats receiving investment.

About half of Loblaw’s previously announced $2.4-billion capital program for 2026 has already been deployed. The remaining investment will support additional openings, renovations and continued testing of new store concepts across Canada.

Grocery expansion will be concentrated predominantly in the No Frills and Maxi hard-discount banners, where Loblaw has been seeing strong results from newer locations.

“We’re very happy with how our new stores are performing,” Loblaw President and CEO Per Bank said. “As they mature, we’re seeing strong double-digit same-store sales growth. That gives us confidence in our expansion strategy and in continuing to invest behind the formats customers are choosing.”

Loblaw has opened 38 new grocery and pharmacy locations so far in 2026, including 21 grocery stores and 17 Shoppers Drug Mart locations, with dozens more scheduled before year-end.

Hard Discount Takes a Larger Role

Loblaw began the year expecting to spend approximately $2.4 billion in 2026 and open about 70 locations, including 31 No Frills and Maxi stores and 34 Shoppers Drug Mart, Pharmaprix pharmacies and care clinics.

By its second-quarter earnings call on July 30, management was already indicating that Loblaw was on track to open approximately 75 locations during the year. Executives also pointed to strong results from recent openings, with newer stores entering the comparable-store base producing double-digit comparable sales growth.

Those results help explain Loblaw’s increasing emphasis on discount. Bank told analysts in July that the company considers consumers’ preference for discount to be a long-term shift, making No Frills and Maxi increasingly important to its development plans.

Loblaw opened four No Frills stores and three Maxi locations during the second quarter. Management has also highlighted its conversion of a former No Frills in Bathurst, New Brunswick, to Maxi. According to Bank, sales at the location more than doubled following the conversion.
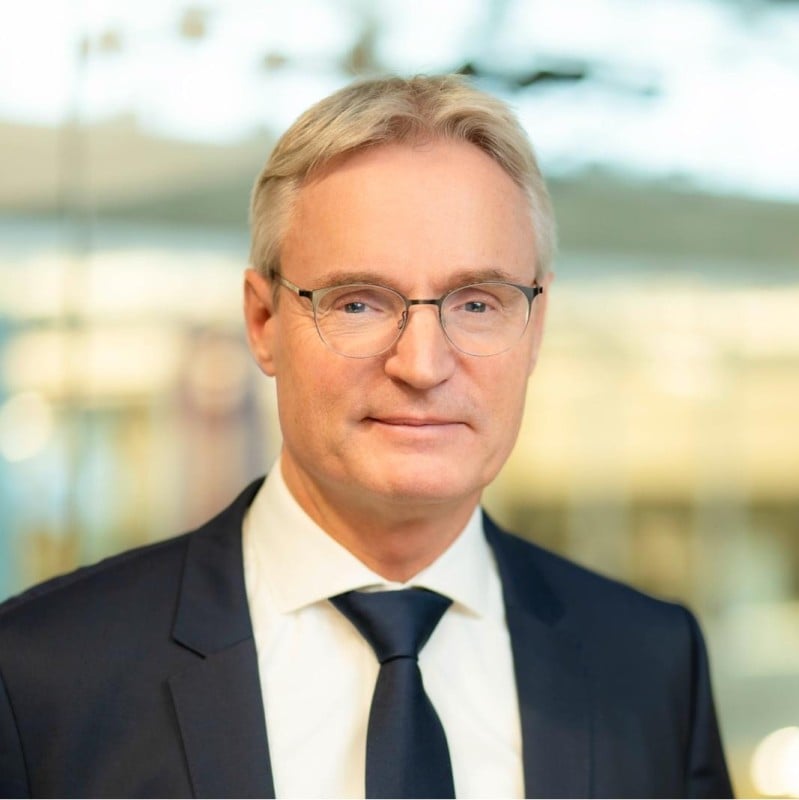
Per Bank
Per Bank

Canadian households remain highly attentive to price and promotions. Loblaw says the share of its grocery sales purchased on promotion has increased four percentage points since 2022, while promotional sales of its No Name private-label products have risen 18%.

“Canadians are being thoughtful about every dollar they spend,” Bank said. “We see that in how they shop our stores, the brands they choose, and how they use our loyalty and ecommerce solutions.”

Those spending patterns are influencing Loblaw’s development strategy. Its growing commitment to No Frills and Maxi indicates that management expects hard discount to remain an important part of the Canadian grocery market even as inflationary pressures change.

New No Frills Formats Target Different Markets

Loblaw is also using its expansion program to experiment with the size and design of No Frills stores.

A location that opened July 30 in Dutton, Ontario, provides one example. At approximately 8,000 square feet, the store is considerably smaller than a conventional supermarket and carries a curated assortment of about 4,000 products intended to provide a full grocery shop for Dutton and surrounding rural communities.

The smaller footprint could broaden the range of communities available to No Frills, particularly in markets that may not require or support a conventional supermarket. If the model performs well, it could give Loblaw another option for growing the banner outside larger urban and suburban markets.

Loblaw is testing a different approach in nearby Komoka, Ontario. The No Frills that opened there in March introduced a redesigned environment incorporating a hybrid timber-and-steel structure and a warmer interior, departing from some elements traditionally associated with the banner’s warehouse-style stores. The location also includes an expanded fresh and prepared-food offering.

The two Ontario locations test different approaches to future No Frills growth. Dutton pairs a smaller footprint with a tightly edited assortment for a rural market, while Komoka explores a more contemporary store environment with a broader food offering. Both retain the banner’s discount positioning.
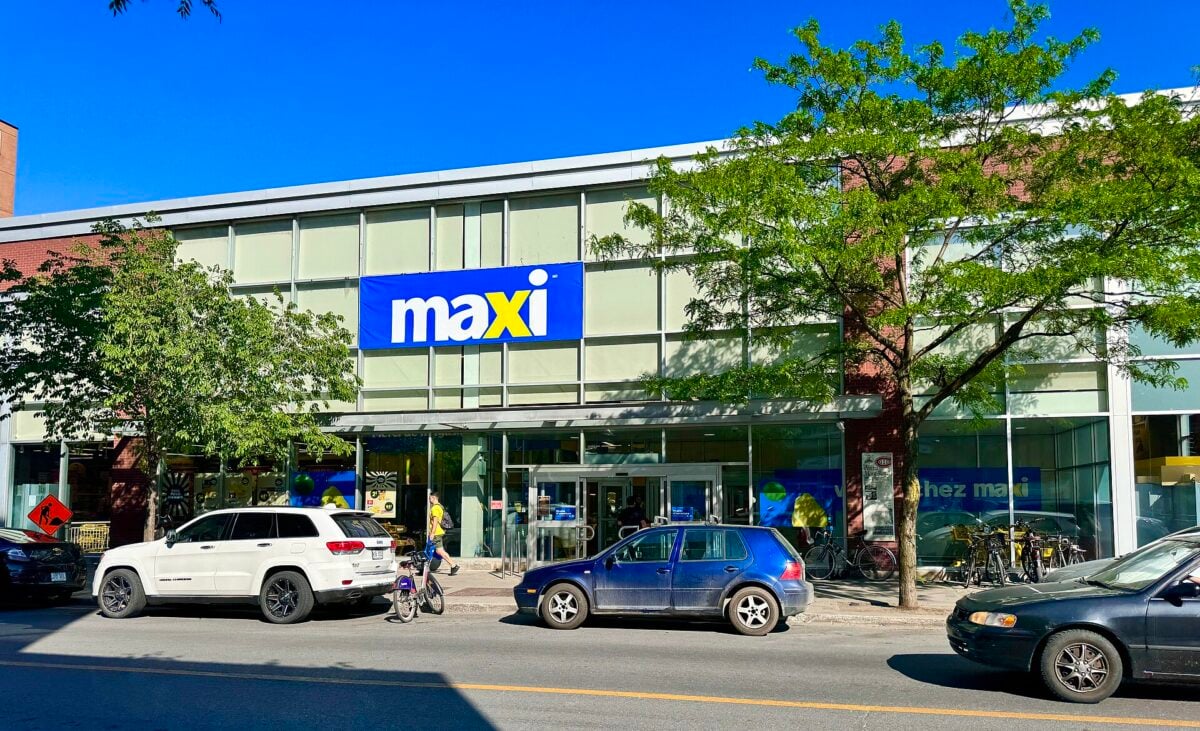
Maxi supermarket chain, Montreal, Quebec. Image: Hkeely at https://commons.wikimedia.org/wiki/File%3AA_Maxi_supermarket_chain_grocery_store_in_Montreal%2C_Quebec%2C_Canada_01.jpg

More Than 190 Existing Locations to Be Renovated

New construction represents only part of Loblaw’s 2026 capital program. More than 190 existing locations are scheduled for renovations this year, with projects ranging from improvements to fresh-food departments to updates elsewhere in stores.

The spending will modernize portions of a grocery network that includes more than 1,100 stores across multiple banners and price segments. Loblaw is also investing in its pharmacy network, adding Shoppers Drug Mart and Pharmaprix locations while updating existing stores.

Food is becoming part of that work at Shoppers Drug Mart. Seventeen locations have completed what Loblaw describes as a food realignment, with 43 expected to be completed by year-end. The changes include a greater emphasis on convenience, value and multicultural products, alongside updates to beauty and other front-store categories.

Canada’s Discount Grocery Competition Intensifies

Loblaw’s expansion comes as other major Canadian grocers continue adding capacity at the discount end of the market.

Metro has been expanding Food Basics in Ontario and Super C in Quebec through new stores and conversions. Food Basics opened its 156th Ontario store in Mississauga in July, the fifth of eight locations the banner expected to open during 2026.

Empire Company Limited is pursuing further expansion of FreshCo. The Sobeys parent had 161 FreshCo locations as of June 17, including 53 in Western Canada and 108 in Ontario, and expects to open approximately 15 additional stores across Western Canada, Ontario and Atlantic Canada during fiscal 2027. The expansion will bring FreshCo to Atlantic Canada for the first time.

The investments underway at the country’s major grocers are changing the composition of Canada’s supermarket network. Loblaw is adding No Frills and Maxi stores, Metro continues to build its Food Basics and Super C networks, and Empire is taking FreshCo into additional markets.

For Loblaw, No Frills provides an established discount platform across several provinces, while Maxi gives the company a substantial network in Quebec and a growing presence in Atlantic Canada.
Shoppers Drug Mart (Image: Dustin Fuhs)

Shoppers and Digital Channels Also Grow

Loblaw’s capital program extends beyond grocery, with pharmacy openings and renovations remaining a significant part of its 2026 plans.

The company has opened 17 Shoppers Drug Mart locations so far this year and continues to expand pharmacy and healthcare services across its network. Changes to food, beauty and front-store categories are also being tested as Loblaw updates existing locations.

Digital sales are growing alongside the physical network. Loblaw reported ecommerce sales growth of 19.3% year over year during the second quarter, while PC Express delivery sales increased by more than 40%. Click-and-collect sales were relatively stable.

The growth in delivery is notable alongside Loblaw’s investment in discount stores. The company is expanding lower-price physical formats while continuing to build digital channels around convenience, loyalty and ecommerce.

T&T Provides Another Avenue for Expansion

T&T Supermarket represents another area of expansion for Loblaw, although its growth strategy differs considerably from No Frills and Maxi.

The Asian supermarket chain opened its first California store in San Jose in June, building on its expansion into Washington state. Bank told analysts that San Jose recorded the highest first-week sales of any store opening in Loblaw’s history. Two additional California locations are planned for 2026.

T&T continues to expand in Canada as well, giving Loblaw another grocery banner with growth potential as the company builds its network at home and in the United States.
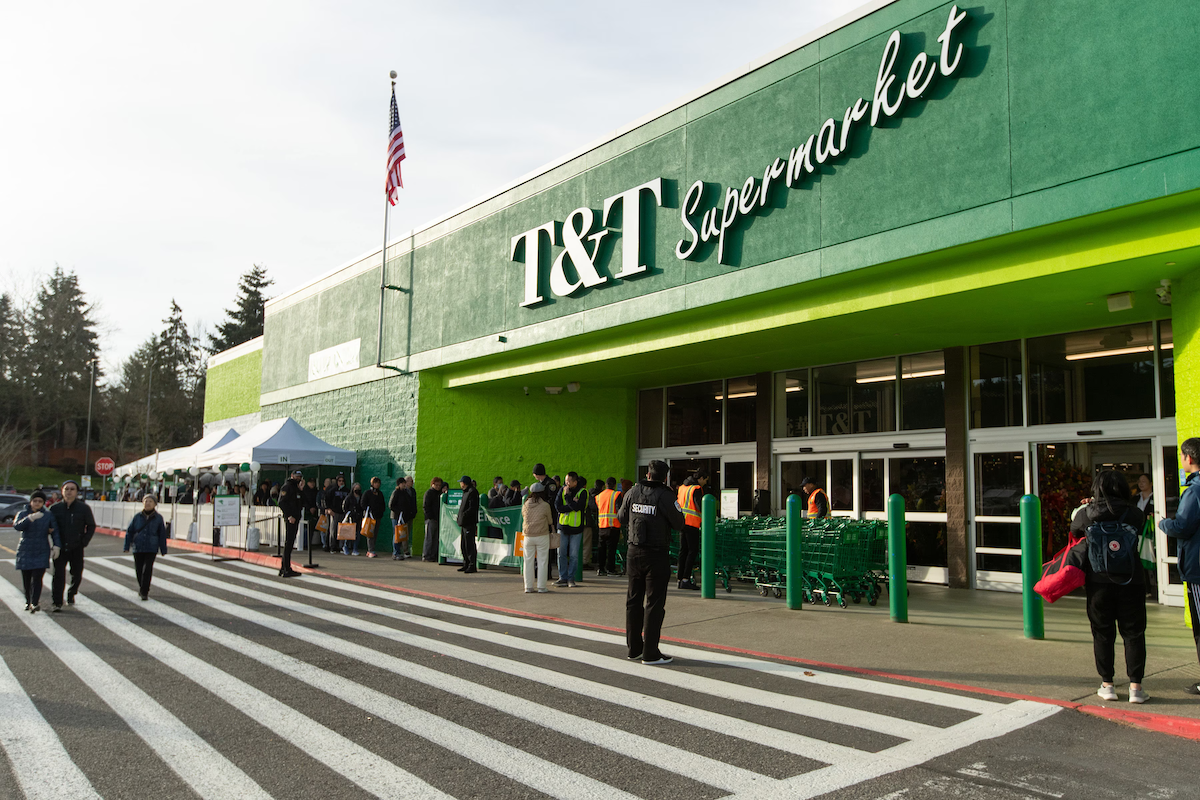
T&T Supermarket in Bellevue, Washington. Photo: T&T Supermarket

A $10-Billion Investment Program Through 2030

Loblaw’s $2.4-billion capital program for 2026 represents the second year of its five-year plan to invest approximately $10 billion in Canada by 2030. The company expects this year’s program to support approximately 9,700 retail and construction jobs.

The spending is gradually changing Loblaw’s physical network. Hard discount is taking a larger role in grocery development, No Frills is being tested in different footprints and configurations, existing supermarkets and pharmacies are being renovated, and the company continues to add locations and services through Shoppers Drug Mart.

The expansion of No Frills and Maxi is one of the clearest indications of where Loblaw sees opportunity in Canadian grocery. Newer stores are producing strong results, competing grocers are adding discount capacity of their own, and Loblaw is continuing to put capital behind formats aimed at shoppers who remain highly focused on price.
More from Retail Insider:

Tapo Canada launches direct-to-consumer online store

Tapo photo
Tapo photo

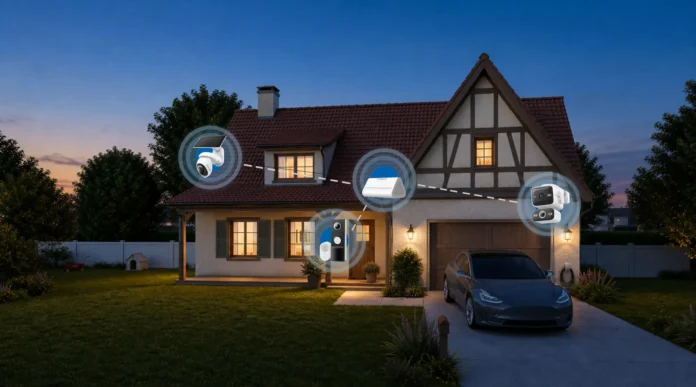
Smart home brand Tapo is launching a direct-to-consumer online store in Canada, giving consumers another way to purchase the company’s connected home and security products.

The new e-commerce operation allows Canadians to buy Tapo products directly from the brand while the company continues to sell through online and physical retailers across the country.

Tapo, a smart home brand owned by TP-Link, said the online store is intended to expand the ways Canadian consumers can access its product portfolio as the company grows its presence in the market.

“The launch of Tapo’s online store marks an exciting next chapter in our Canadian growth,” said Benjamin Liu, general manager of TP-Link Canada. “We’re giving Canadians more choice in how they shop Tapo, while making it easier to discover our growing ecosystem of smart home solutions in one place. Whether they’re looking to strengthen home security, add greater convenience or build a more connected home, we want smart technology to be simple, accessible and easy to bring into everyday life.”

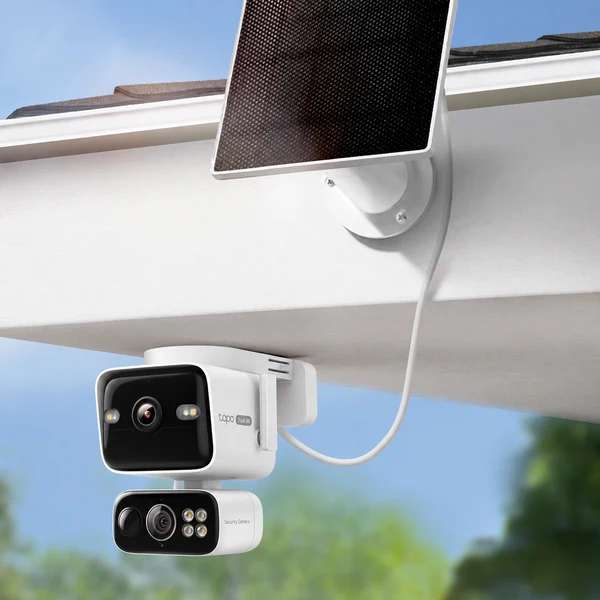
The Tapo product lineup includes indoor and outdoor security cameras, 2K and 4K security products, solar-powered and wire-free cameras, smart locks and video doorbells.

The portfolio also includes smart home hubs, motion and contact sensors, water-leak and temperature sensors, smart lighting and Wi-Fi products.

The launch gives Tapo a direct sales channel in Canada in addition to its existing retail distribution, allowing consumers to shop the company’s products through its own online storefront.

The Canadian online store launched Aug. 25.

Tapo is the smart home brand of TP-Link and offers connected products including cameras, sensors, lighting and automation devices.

TP-Link was founded in 1996 and provides networking devices and smart home products for consumers and businesses. The company distributes its products in more than 170 countries and says it serves billions of users worldwide.

More from Retail Insider:

Subway Canada launches under-$5 menu as consumers weigh lunch costs

Subway photo
Subway photo

Subway Canada has introduced a new menu of breakfast, lunch and snack items priced below $5 as consumers continue to balance the cost of eating out with convenience and freshness.

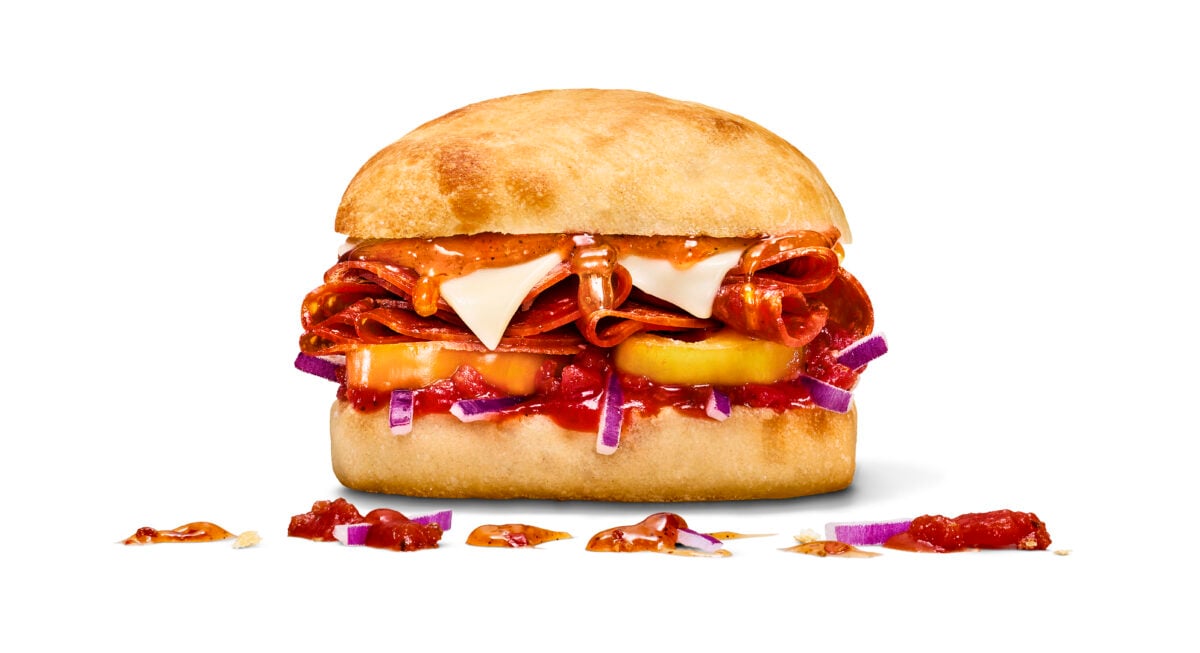
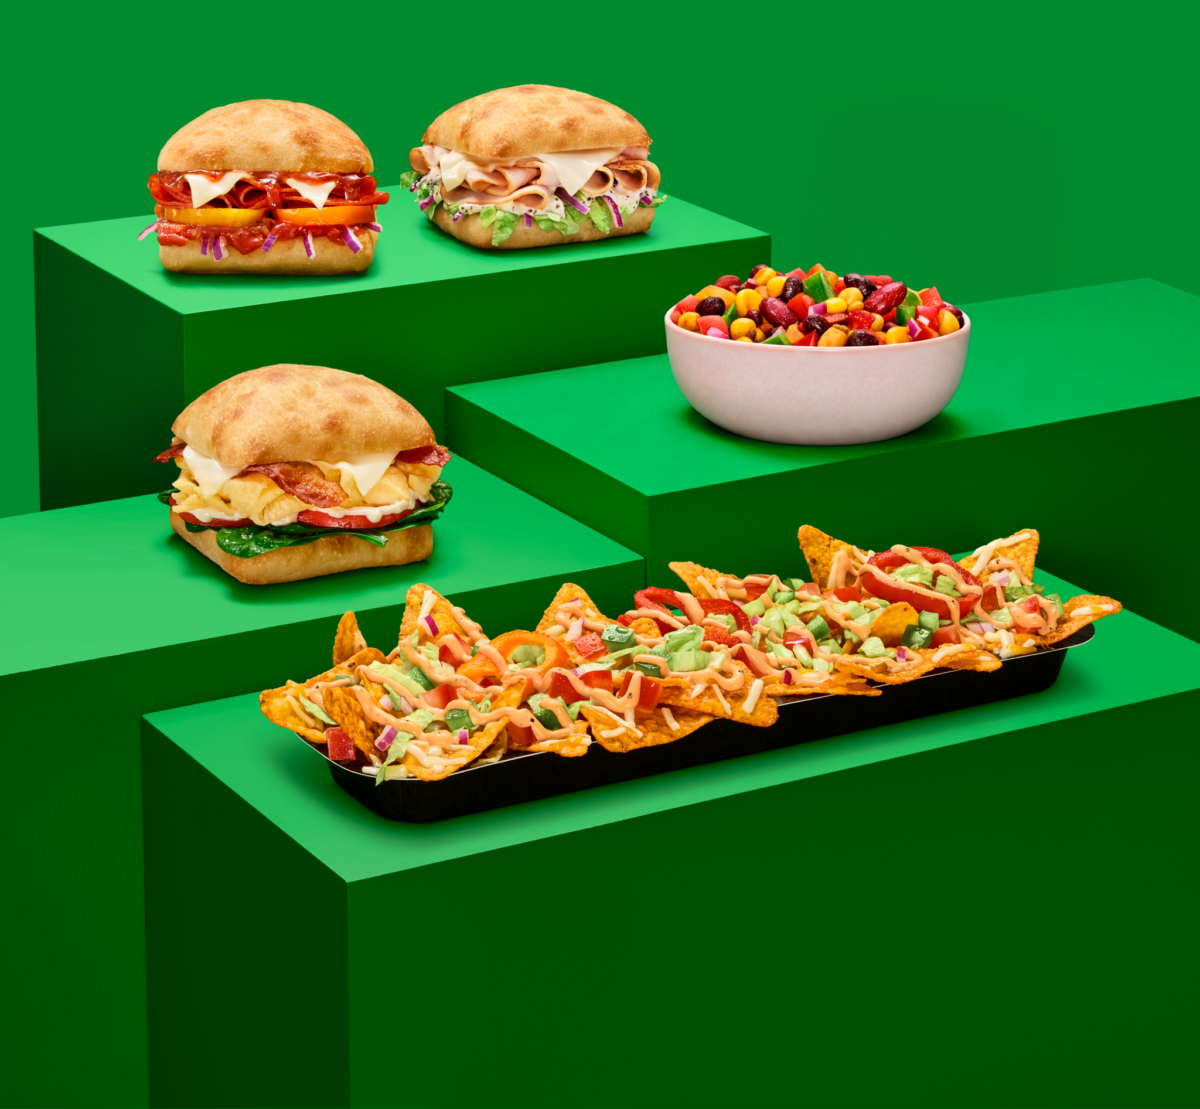
The Fresh For Less Menu, launched Aug. 26, includes limited-time items such as Hot Honey Pepperoni Pizza Snackwiches, Turkey Caesar Snackwiches and Doritos Sweet Chili Heat Footlong Nachos, along with breakfast sandwiches, sides and snacks.

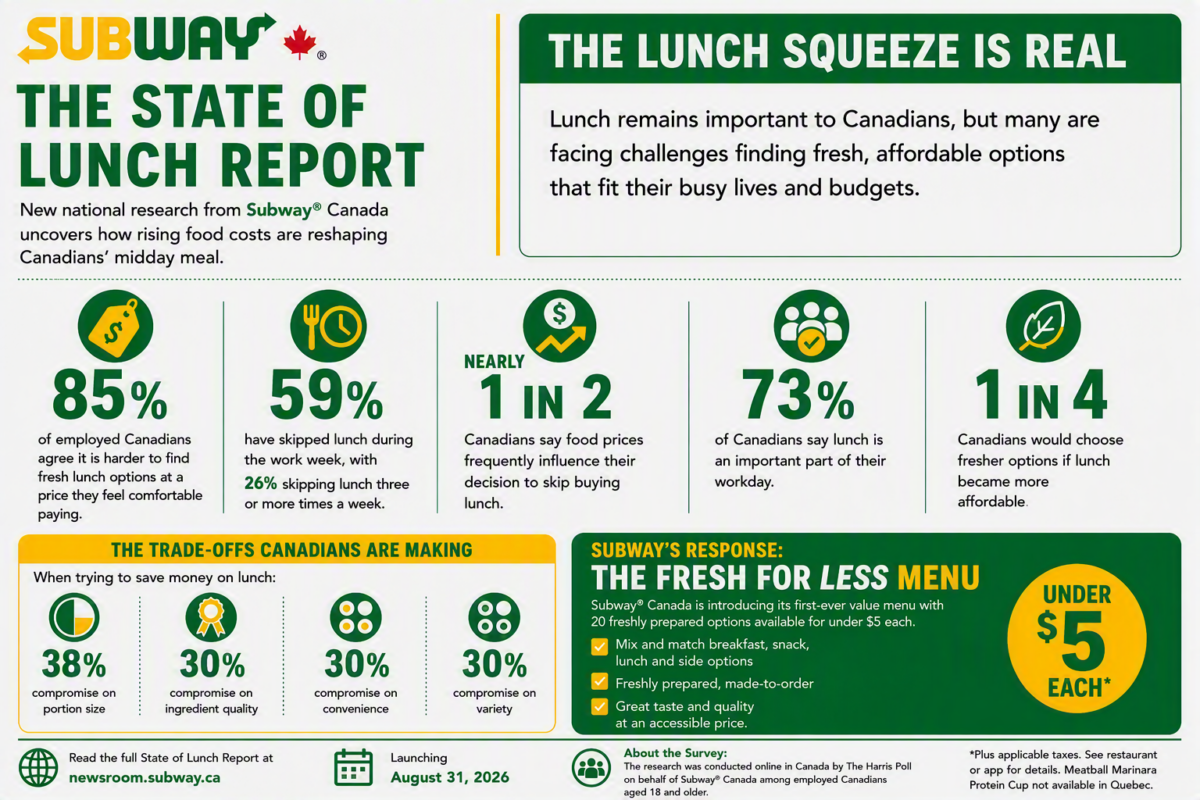
The launch follows research commissioned by Subway Canada that found 85 per cent of employed Canadians say it is harder to find fresh lunch options at a price they are comfortable paying.

The company’s inaugural State of Lunch Report also found that while lunch remains important to Canadian workers, affordability, convenience, freshness and quality are increasingly factors in decisions about what — and whether — to eat during the workday.

“The newly launched Fresh For Less Menu gives Canadians greater choice and flexibility, with options under $5 that they can mix and match throughout the day,” said Denny Downie, managing director and head of marketing at Subway Canada. “Our State of Lunch Report found that lunch is an important part of the workday for Canadians, but rising food costs are making it harder to find the freshness and quality they want at a comfortable price. The Fresh For Less Menu brings those priorities together, without asking Canadians to settle on flavour, quality or variety.”

The menu includes six Snackwich options served on ciabatta bread, including the new Hot Honey Pepperoni Pizza and Turkey Caesar varieties, as well as Turkey Ranch, Honey Mustard Ham, BLT and Three Cheese.

The breakfast selection includes Sausage & Egg, Bacon & Egg, Cheese & Egg, Sausage & Cheese and Ham & Egg Breakfast Ciabatta Sandwiches, which can be customized with sauces and vegetables.

New side and snack offerings include a Meatball Marinara Protein Cup containing 21 grams of protein, Doritos Sweet Chili Heat Footlong Nachos and Mini Cookies available in eight- and 12-piece packages. The Meatball Marinara Protein Cup is not available in Quebec.

Other sides include Doritos Nacho Cheese Footlong Nachos, Fiesta Beans & Corn Salad, Potato Rings and soup.

The State of Lunch Report found that 73 per cent of employed Canadians consider lunch important, while 59 per cent said they have skipped lunch during the work week.

The research also found that consumers are making compromises to keep lunch spending within their budgets. Thirty-eight per cent said they compromise on portion size when trying to save money, while 30 per cent said they have compromised on ingredient quality, convenience or variety.

One-quarter of employed Canadians said they would choose fresher options if lunch became more affordable.

The findings point to what Subway describes in its report as the “Lunch Squeeze,” reflecting the challenge consumers face in balancing cost with other priorities when deciding what to eat during the workday.

Subway photo
Subway photo

The survey was conducted online by The Harris Poll Canada in August 2026. The results were weighted by age, region and education, and by language in Quebec, to match Census data and make the sample representative of the Canadian workforce population.

The Fresh For Less Menu is available for a limited time at participating Canadian Subway restaurants. Prices and participating locations may vary, with additional charges for add-ons, taxes and delivery fees.

More from Retail Insider:

NerdWallet Canada study finds ‘doomspending’ spans generations

Vitaly Gariev photo
Vitaly Gariev photo

Canadians are spending money on things they do not need despite financial and economic concerns, with a new NerdWallet Canada study finding the behaviour is widespread across age groups and can carry significant financial consequences.

The research found that 66 per cent of Canadians said they had spent money in the previous six months on something they wanted but did not need, at least partly because concerns about their finances, the economy or the future made enjoying the present feel more important. Forty-five per cent said they had done so more than once.

Among Canadians who reported the behaviour, 75 per cent said the spending had a financial consequence, equivalent to half of all Canadians surveyed.

NerdWallet Canada refers to the behaviour as “doomspending,” describing it as buying things people do not need because the future feels uncertain or saving money seems pointless.

The study found that the most common reason cited by those who spent was getting a lift in mood or a distraction from stress, at 54 per cent. That was followed by wanting something enjoyable to look forward to, at 47 per cent.

Only 21 per cent said an uncertain future influenced their decision to make the purchase.

The spending also extended across a range of everyday categories. Takeout, clothing, personal-care products, electronics, games and hobby-related items were among the purchases most commonly identified by respondents, while travel and concert tickets were also cited, though less frequently.

“Doomspending is easy to picture as a few big splurges. The purchase list tells a more ordinary story: takeout, clothing, personal-care products, electronics, games and hobby-related items. Travel and concert tickets showed up too, but less often. Taken together with the leading motivation — a lift in mood or distraction from stress — the categories suggest that doomspending often involves accessible, immediate comforts,” said Jordan Lavin, a financial expert with NerdWallet Canada.

Two in five respondents who reported doomspending, or 40 per cent, said saving the money instead would not have made a meaningful difference to their financial situation.

The research also found differences in the financial impact across age groups. Among doomspenders aged 35 to 54, 32 per cent said they had taken on or increased debt, compared with 21 per cent overall.

Lavin said the term used to describe the behaviour may not fully capture the motivations reported by consumers.

“The “doomspending” label puts doom and dread at the centre of this behaviour. The motivations put something else there. Worry was the price of admission to the question — but what respondents described next was the appeal of what a purchase could do right away: relief from a bad mood, or something pleasant waiting a few days out.”

The findings suggest that the behaviour is not limited to large discretionary purchases or a particular generation, according to the study.

“Doomspending suggests that a bleak future drives the behaviour. But mood relief, something to anticipate and the sense that saving a small amount would not change much were all more common than the explicitly future-focused response. The effects were not uniform. For some Canadians, doomspending displaced another discretionary purchase; for others, it meant using savings, increasing debt or cutting necessities.”

More from Retail Insider:

Canadian Retailers Enter Holiday 2026 With Spending Momentum and Price-Sensitive Shoppers

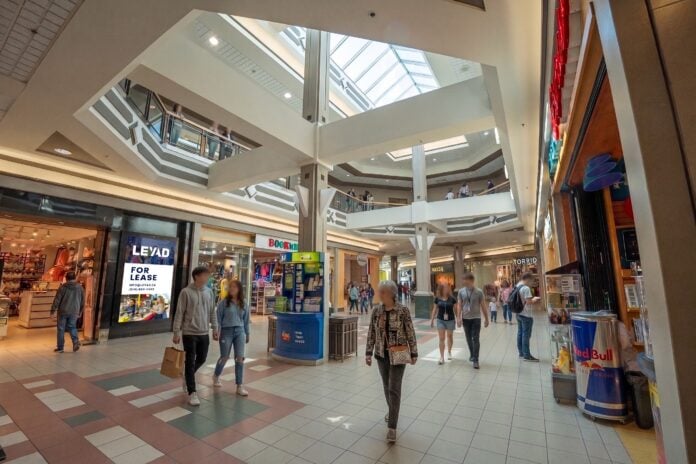
Intercity Shopping Centre in Thunder Bay, Ontario (CNW Group/Leyad)

Canadian consumers are showing renewed spending momentum heading into the 2026 holiday season, even as economic uncertainty and persistent price sensitivity continue to influence how and where they shop.

Caila Schwartz
Caila Schwartz

Salesforce is seeing Canadian consumers spend more and place more orders than they were a year ago, according to Caila Schwartz, Director of Industry Insights at Salesforce. The company’s latest data points to a potentially strong holiday period for Canadian retailers, although shoppers are expected to remain highly focused on value, promotions and convenience.

“We’re seeing that the Canadian consumer is feeling a lot more pessimistic about the state of the economy than what we’re seeing in the U.S.,” Schwartz told Retail Insider. “But what’s interesting is that we’re not seeing that have a direct impact on buying activity. The Canadian consumer is still shopping and still spending.”

Schwartz said Canadians are spending more than they were at this point last year, while order volumes have also increased through the summer. Earlier in the year, health and beauty performed particularly well, followed by strength in traditional back-to-school categories later in the summer, although she said no single category has defined the broader spending trend.

“We’re now starting to see a Canadian consumer that’s spending again,” she said. “We anticipate that will continue to remain strong through the fall, and we anticipate a pretty strong holiday performance.”

Salesforce has not yet released its formal Canadian holiday sales forecast, which Schwartz said is expected later in the fall.

The improving spending picture follows s11everal years in which inflation, higher borrowing costs and other economic pressures weighed heavily on Canadian households. Recent Canadian retail data has also shown periods of strengthening sales and e-commerce activity, although consumer conditions remain uneven heading into the final months of the year.

Canadian Shoppers Remain Highly Price Sensitive

Despite the spending momentum, Salesforce data shows 56 per cent of Canadian consumers say they are concentrating their spending on essentials, while 51 per cent say they are pulling back on splurge purchases. Another 35 per cent say they are trading down to lower-priced products.

Inflation and fuel prices remain among the economic issues consumers are most concerned about, according to Schwartz. Shoppers may be willing to spend, but they are becoming increasingly deliberate about when they make purchases and the value they expect in return.

That behaviour could intensify competition during Cyber Week. Black Friday falls on November 27 this year, giving retailers one additional shopping day between Black Friday and Christmas compared with 2025, but Schwartz said the selling period remains relatively compressed compared with some previous years.

Consumers are also beginning their holiday consideration process earlier, watching marketing campaigns, assessing promotions and planning purchases well before Cyber Week. Salesforce is nevertheless seeing more of the actual spending become concentrated around the major promotional period.

“Shoppers are paying attention earlier in the season, so they’re looking at the marketing messages, they’re anticipating the deals, they’re planning out their spend,” Schwartz said. “But we’re seeing more and more of the actual spending concentrate back into that Cyber Week period because ultimately shoppers want deals. They want a good price.”

Years of Black Friday promotions have conditioned consumers to expect substantial discounts, she added, making it increasingly difficult for retailers to persuade some shoppers to buy early.

Deal-Seeking Could Extend Beyond Cyber Monday

One of the more unusual trends identified by Salesforce illustrates how willing shoppers have become to wait.

Schwartz said the Tuesday immediately following Cyber Monday produced better average discounts last year than either Black Friday or Cyber Monday. She believes retailers were attempting to capture consumers who had made it through the traditional Cyber Week promotional period without completing their purchases.

“The Tuesday after Cyber Monday has kind of become a not-so-well-advertised discounting moment,” Schwartz said. “It had better discounts on average than what we saw on Black Friday and Cyber Monday.”

Schwartz expects continued price sensitivity to produce similar behaviour this year, potentially extending promotions as retailers attempt to convert hesitant customers. Retailers will be trying to generate transactions while protecting margins already under pressure from fulfilment, returns and other operating costs.

Free Shipping Adds Another Margin Challenge

Shipping could become an especially important part of that equation. Salesforce says free shipping is the top requested benefit among consumers and is expected to be a leading factor in where shoppers choose to buy during the holiday season.

Providing it is becoming more expensive. Schwartz said Salesforce expects brands to pay about seven per cent more in shipping costs this holiday season, increasing pressure on retailers to provide the convenience shoppers expect without absorbing the entire cost.

Higher thresholds for free shipping could become increasingly common. Retailers can also use their store networks to reduce fulfilment costs through buy-online-pick-up-in-store, ship-from-store and return-to-store options.

“I think there are opportunities to incentivize the shopper to choose those options,” Schwartz said. “I think we’ll see higher free-shipping thresholds just to offset those shipping costs.”

Loyalty programs could become another lever, with retailers offering shipping benefits to members rather than providing them universally.

Returns present a related challenge. Schwartz said return rates have been rising during recent holiday seasons, adding another cost retailers will be looking to manage. Some are turning to AI-powered product recommendations and guided shopping tools to help customers select the right products and reduce behaviours such as “bracketing,” where shoppers purchase several versions or sizes of an item with the intention of returning most of them.

Schwartz also expects retailers to continue adjusting return policies as part of broader efforts to protect margins.

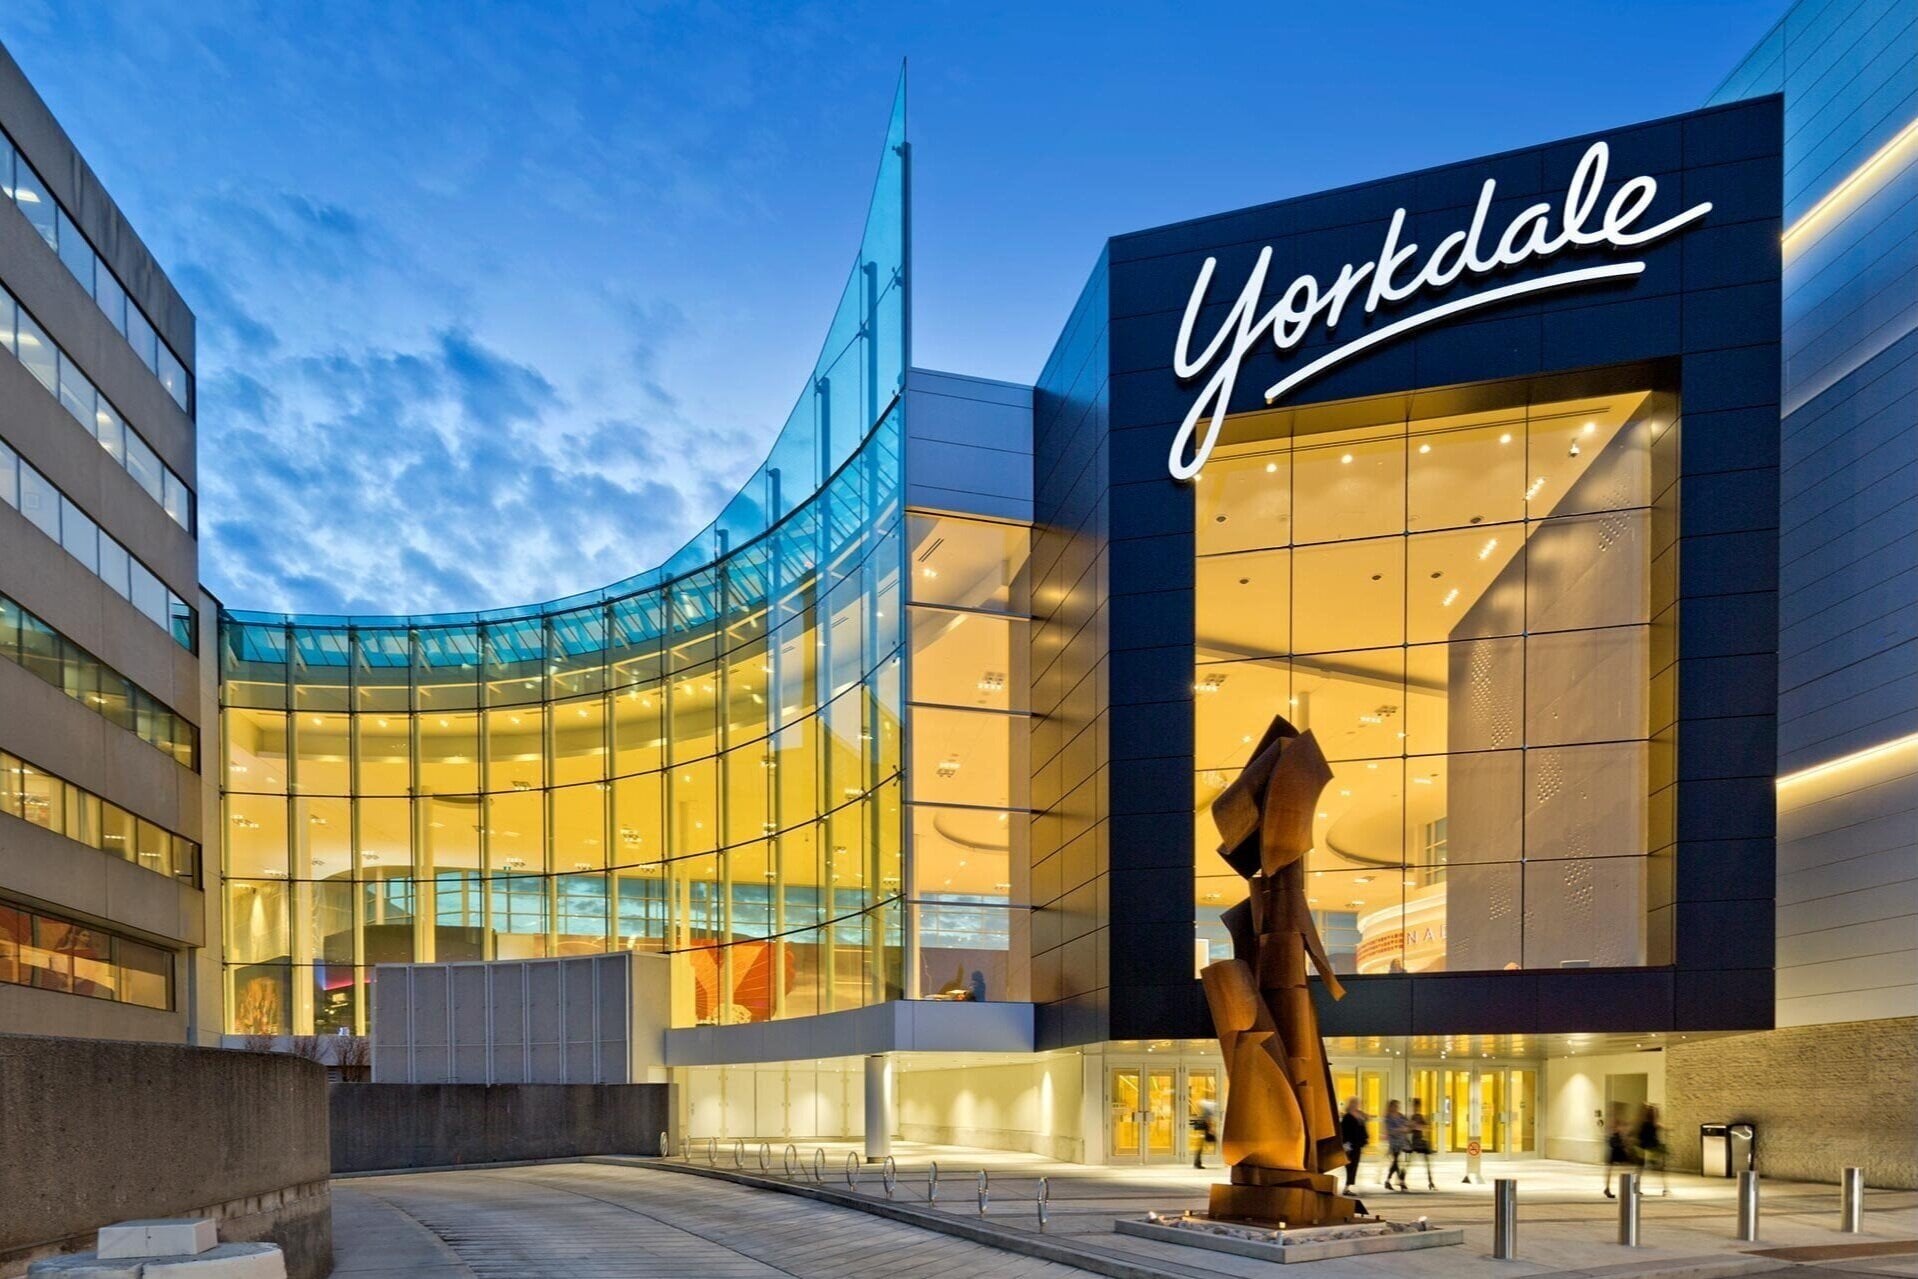
Yorkdale Shopping Centre Exterior

Canadian Consumers Still Want to Shop in Stores

Despite the evolution of e-commerce and digital product discovery, physical retail is expected to remain central to the Canadian holiday shopping experience.

Salesforce research found that 77 per cent of consumers across the markets it tracks expect to shop in physical stores this holiday season. In Canada, that figure rises to 83 per cent.

“The store is still very alive and well,” Schwartz said.

The appeal includes established advantages of physical retail: customers can see and touch merchandise, discover products and leave immediately with their purchases. There is also an experiential component that appears to be resonating with younger consumers.

Schwartz said Salesforce is seeing interest among Gen Z and Millennial shoppers in some of the traditional rituals associated with Black Friday, including visiting stores early in the morning. For some younger shoppers who grew up with widespread e-commerce, the activity surrounding a major physical shopping event has become part of the attraction.

Physical and Digital Shopping Continue to Converge

The distinction between an online shopper and an in-store shopper is also becoming increasingly difficult to make.

Salesforce found that 42 per cent of shoppers have researched a product online before walking into a store, while roughly 80 per cent use their phones while shopping in physical retail environments. They may be comparing prices, researching merchandise, checking social media for inspiration, accessing loyalty programs or interacting with an AI assistant while inside a store.

“The boundaries between physical and digital shopping are very hazy for today’s modern consumer,” Schwartz said.

Salesforce consequently predicts that approximately 38 per cent of holiday retail spending this year will involve what it describes as hybrid sales, where both physical and digital touchpoints contribute to completing the purchase.

Product information, inventory availability, pricing, loyalty programs and fulfilment therefore need to work across channels as consumers move through their shopping journeys. With 83 per cent of Canadians expecting to shop in stores, the relationship between digital and physical retail could be particularly important in Canada this holiday season.

AI Adds Another Layer to Holiday Shopping

Artificial intelligence will also influence how consumers discover and evaluate products this holiday season.

Schwartz said roughly 11 to 12 per cent of Canadian shoppers now report turning to AI tools first in their buying journey, a substantial increase from last summer. Consumers are using services including ChatGPT, Gemini and Perplexity, along with AI assistants on social platforms, for product recommendations and to find pricing, promotions and coupons.

Retailers will also have to contend with increasing amounts of non-human website traffic as AI systems crawl product pages and collect information. Schwartz said managing that activity while keeping sites performing reliably will become particularly important during peak periods such as Cyber Week.

The broader implications of AI for product discovery and retail commerce extend beyond the holiday season as the technology becomes a larger part of consumer shopping behaviour.

A Growing Divide Among Canadian Consumers

The economic backdrop adds another complication. Schwartz said Salesforce is seeing signs of a deepening K-shaped economy, with higher-income consumers displaying greater optimism and purchasing power while lower- and middle-income households remain under heavier financial pressure.

Those differences have implications for how retailers approach customers during the holiday period. Product selection, pricing, promotions and marketing may need to reflect substantially different financial circumstances across consumer groups.

“Thinking about your personas, how you’re marketing to these specific customers, what types of journeys you’re putting them on and how you’re structuring your holiday marketing around that is going to be really important,” Schwartz said.

The divide helps explain the apparent contradiction in the Canadian consumer outlook. Retail spending can strengthen while significant numbers of households limit discretionary purchases, trade down and search aggressively for discounts.

For retailers, Holiday 2026 could bring stronger sales alongside a demanding competitive environment. Canadian shoppers are showing a willingness to spend, but they are also entering the season expecting value, convenient fulfilment and shopping experiences that move easily between digital and physical channels.

Salesforce’s current data suggests the demand will be there. The challenge for retailers will be capturing it while managing the cost of promotions, shipping, returns and fulfilment that could otherwise erode the benefit of stronger sales.

More from Retail Insider:

Why Ecommerce Execution Is Becoming StoreClaw’s Competitive Moat

For years, enterprise retailers have had an advantage during Q3 and Q4 because they could execute faster. More people meant faster listing updates, pricing changes, inventory management, and advertising adjustments—work that smaller sellers often had to handle manually.

That advantage is beginning to shift as sellers turn to AI for more than content creation. StoreClaw’s back-to-school data shows growing adoption of connected tools alongside increased use of image, video, and listing generation. The signal is straightforward: as peak season becomes more complex, sellers increasingly need AI that can help execute across their operations, not simply generate another piece of content.

The Data Behind the Shift

According to StoreClaw’s back-to-school data between July 7–21 and July 22–August 4, the share of heavy U.S. users connecting StoreClaw to live operating platforms rose from 11.4% to 15.6%, a 4.2-percentage-point increase. The number of connected users increased 19.6% over the same period.

AI usage is shifting in other ways, too. Image and video creation increased 4.5 percentage points, from 7.3% to 11.8%, while AI-generated listing copy rose 2.6 percentage points, from 10.7% to 13.2%. Sellers aren’t simply looking for help writing faster. The data suggests growing demand for AI that can support the broader work of getting products to market across multiple channels.

That matters heading into Q3 and Q4, when speed can determine whether a seller captures a demand surge or spends the season trying to catch up. As StoreClaw co-founder Steven Zhou puts it, enterprise retailers have historically won peak seasons by out-resourcing smaller competitors on speed and execution. AI-driven operations are beginning to change that equation.

Why Large Platforms Won’t Build This

The operational problem is also one that major eCommerce platforms have little incentive to solve on their own. Amazon benefits when sellers operate more effectively on Amazon. Shopify benefits when merchants build and grow within Shopify. Neither has the same incentive to create a neutral layer that helps sellers coordinate Amazon, Shopify, eBay, TikTok Shop, and other channels from one place.

That creates an opening for a cross-platform operating layer. StoreClaw has native connections to Amazon, Shopify, eBay, WooCommerce, TikTok Shop, and more than 20 other platforms, bringing fragmented operational data and workflows into a more unified environment.

The distinction is important: StoreClaw isn’t competing with those platforms for the seller’s storefront. It is addressing the work that happens between them.

Why General Purpose AI Can’t Execute

General-purpose AI can suggest a product description, identify potential keywords, or help interpret a business problem. But without access to a seller’s actual listings, advertising data, competitor activity, inventory, pricing, and sales channels, it lacks the context needed to turn those suggestions into reliable execution.

StoreClaw is built around that context. Its listing workflow can analyze competitor reviews for recurring customer pain points, structure primary and long-tail keywords, and check content for marketplace requirements before publication. Its advertising intelligence works from actual campaign data to identify wasted spend, surface negative keywords, and optimize bids.

The difference isn’t simply what the AI can generate. It is what the system knows about the business and what it can do with that information.

What the “Dirty Work” Actually Looks Like

The “dirty work” is the accumulation of operational tasks sellers have to repeat: finding products, updating listings, monitoring competitors, managing advertising, and keeping information aligned across channels.

StoreClaw packages many of these processes into more than 30 pre-built Skills covering product selection, SEO, pricing, listing creation, advertising intelligence, competitor tracking, and other eCommerce workflows. Product-selection tools evaluate signals including audience fit, demand, content trends, and supply shifts. Competitor tracking monitors price, promotions, reviews, keywords, and stock.

These are operational shortcuts. Instead of building a process for every task—or moving between a collection of disconnected tools—sellers can move more directly from identifying an opportunity or problem to taking action.

Proof in the Results

The reported results from StoreClaw users show how that execution can translate into business outcomes. For INCENZO, a three-person Shopify fragrance team, 18 hours of weekly SEO work were automated alongside 142% organic traffic growth and a 57% reduction in CAC. Amazon LED decor seller Twinkle Star cut product launch time from five to seven days to 1.5 days, while conversion increased from 9.3% to 14.1% and GMV grew 120%.

Ruvalino increased repeat purchases from 11% to 18% and organic search share from 8% to 19%. LuxClub reduced ACoS from 35% to 22%, saved $80,000 per month in ad spend, and increased sales 47% quarter over quarter.

Across the four sellers, the results span traffic, acquisition, conversion, advertising efficiency, revenue, and retention. Internal StoreClaw data also shows high retention among sellers who move from one-off usage into continuous execution, suggesting that the value becomes more durable when AI becomes part of the operating workflow.

StoreClaw’s moat isn’t the AI model itself; it’s the operational layer built around it. The cross-platform integration, pre-built Skills, and store-level data give AI the context to execute.

That is what makes the “dirty work” strategically important. General-purpose AI can provide increasingly capable answers, while major platforms remain focused on their own ecosystems. The opportunity sits in between: helping sellers get the work done across the fragmented channels where modern eCommerce actually happens.

Sources

  1. StoreClaw. StoreClaw Concludes Participation in MDS Singapore Summit 2026. August 2026.
  2. StoreClaw. Back-to-School Data & PR Key Takeaways. August 2026.
  3. StoreClaw. User Cases. 2026.

Street Poller

Shane Ginsberg, CEO and Founder of Street Poller Media, on Why Street Interview Ads Aren’t New, But Converting Them Into Trackable Performance Marketing Is

Contrary to popular belief, some of the most effective advertising formats leveraged today are hardly new strategies at all. They are old entertainment formats that somebody eventually figured out how to monetize on modern platforms. The man-on-the-street interview is a clear example. Audiences have enjoyed watching strangers react to unexpected questions on camera for decades, including comedic television segments that ran throughout the 1980s and 1990s, long before anyone considered running one as a paid advertisement on Instagram or TikTok

Street Poller Media founder Shane Ginsberg is unusually direct about this history, particularly as the CEO and Founder of the category’s leader. He does not claim to have invented the format. He has pointed to man-on-the-street bits from decades of television as evidence that the underlying concept has been entertaining audiences far longer than his company has existed.

Ginsberg was, however, among the first (if not the first himself) to recognize that a decades-old entertainment format could be converted into short-form paid advertising with real, trackable, attributable results on social media. In his mind, the format was proven, now he just had to prove the application

That distinction matters because of what it replaces. A traditional television or radio buy, even a substantial one, produces a vague and largely unattributable lift in awareness. A brand can spend a hundred thousand dollars on a television placement and have no reliable mechanism for tracing a specific sale back to that specific spot. Marketers have spent decades building proxies and models to estimate the relationship, but the fundamental attribution problem never really got solved. It got approximated.

A street interview ad running as a paid placement on Meta, TikTok, or YouTube Shorts carries the same granular tracking infrastructure as any other digital ad unit. Cost per install, cost per acquisition, return on ad spend, and conversion rate are all measurable in real time and attributable to a specific piece of creative. A brand can determine within days whether a particular question, a particular location, or a particular interviewer generated a better return than the alternatives, and reallocate spend accordingly.

That combination, the entertainment value of a proven decades-old format paired with the measurement infrastructure of modern paid social, is what Ginsberg has identified as the actual innovation behind the business. Neither element was novel on its own. Man-on-the-street content had been entertaining audiences since broadcast television. Performance attribution had been standard practice in digital advertising for years. What had not existed was anyone systematically applying the second to the first.

The timing was not arbitrary either. The infrastructure required to make the format work commercially, meaning vertical video platforms with algorithmic distribution, mature attribution tooling, and audiences accustomed to consuming short unscripted clips, only converged relatively recently. A street interview ad in 2010 would have had nowhere efficient to run and no reliable way to measure whether it worked.

There is a broader lesson in the sequence for marketers evaluating emerging formats. The question worth asking is often not whether a piece of content is novel, but whether existing distribution and measurement infrastructure has caught up to something that was already proven to hold attention. Street interviews had generations of evidence behind them as entertainment. What changed was that the tools finally existed to determine, precisely, how much a given interview was worth in revenue.

Build-A-Bear Refocuses Strategy as Canadian Store Network Evolves

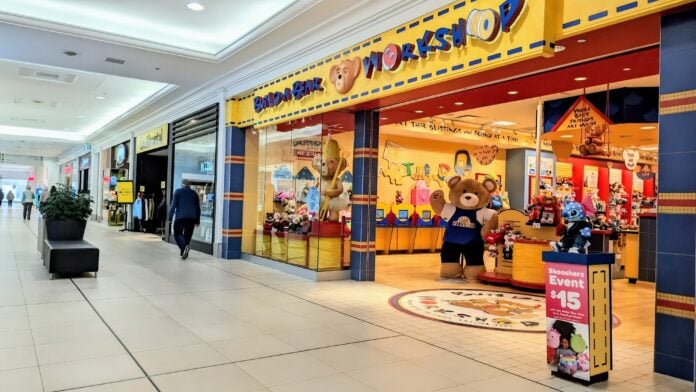
Build a Bear at Mic Mac Mall (Image: Cushman & Wakefield)

Build-A-Bear Workshop is refocusing its product strategy around customization and the in-store experience after a weaker-than-expected summer assortment contributed to declining traffic and sales during the retailer’s second quarter.

The St. Louis-based company operates a network of company-managed stores in Canada, with recent activity including a new location at Cataraqui Centre in Kingston, Ontario. Canada remains one of Build-A-Bear’s core corporate markets as the retailer expands internationally and works to broaden its appeal across age groups.

At the same time, the company has learned that some of its recent product innovation moved too far away from the stuffing, dressing and personalization process that has defined Build-A-Bear for nearly three decades.

“The reality is we pushed it too far,” CEO Chris Hurt told analysts during the company’s second-quarter earnings call Thursday.

Management is already seeing signs that a return to products built around the traditional Build-A-Bear model is resonating. The company’s recent Halloween launch delivered the highest non-fourth-quarter sales week in its history, while early third-quarter traffic and sales have improved from the first half of the year.

Summer Product Strategy Misses the Mark

Build-A-Bear entered the summer facing difficult comparisons with 2025, when collections including its Fruit Stand assortment, Sanrio Sweet Shop and products tied to How to Train Your Dragon helped drive strong sales.

For 2026, the company pushed further into product innovation with concepts including Slushy Plushies and other trend-oriented merchandise. Some of those products were less dressable and customizable than traditional Build-A-Bear characters and did not perform as management expected.

Build-A-Bear has traditionally used the summer period to experiment with emerging trends because occasions such as Valentine’s Day, Easter, Halloween and the holiday season tend to have more established product expectations.

After five consecutive years of record annual results, management believed there was room to push the summer assortment further. The results are now influencing how the company approaches future product development.

Products that retained the familiar Build-A-Bear formula performed considerably better. Chummy Shark, a dressable character included in the Make Your Own Summer collection, sold out during the quarter.

Build-A-Bear’s proprietary Promise Pets collection also continued to generate higher-than-average spending per transaction, supported by customers adding clothing and accessories.

Management said innovation will remain important, with future assortments expected to place greater emphasis on the interactive elements associated with the brand.

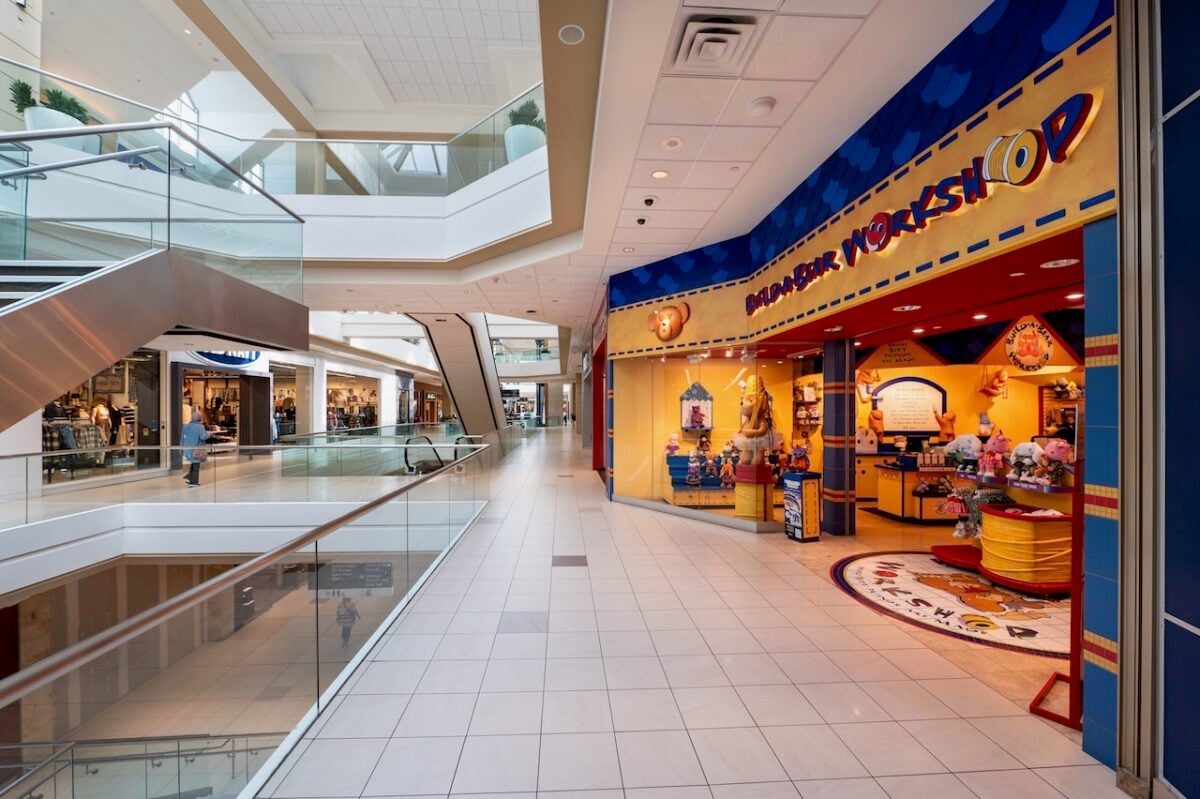
Build-a-Bear at Bayshore Shopping Centre (Image: James Park)

Weaker Traffic Pressures Results

Second-quarter revenue fell 7.2 per cent to US$115.3 million, while e-commerce demand declined 15.6 per cent. Pre-tax income dropped to US$11.6 million from US$15.3 million a year earlier.

Transactions declined primarily because of lower store traffic. Increased promotional activity, partly aimed at moving underperforming summer merchandise, contributed to a 340-basis-point decline in gross margin to 54.2 per cent.

Build-A-Bear subsequently lowered its fiscal 2026 outlook. The company now expects annual revenue of US$500 million to US$525 million, down from its previous forecast of US$530 million to US$550 million.

Pre-tax income is expected to reach US$60 million to US$68 million, compared with the previous forecast of US$72 million to US$78 million.

Despite the reduced outlook, management expects 2026 to remain one of the stronger years in Build-A-Bear’s history.

Halloween Provides an Early Rebound

Early third-quarter results are giving management some confidence that merchandise was an important part of the summer slowdown.

Build-A-Bear’s Halloween assortment moved closer to its traditional formula, combining seasonal and trend-oriented characters with opportunities to stuff, dress, accessorize and personalize them.

The launch generated the highest non-fourth-quarter sales week in company history. Build-A-Bear also recorded its third-highest U.S. e-commerce sales week, trailing only the Black Friday weeks of 2020 and 2025.

Hurt said traffic and sales have improved sequentially during the early third quarter, although performance remains slightly below the company’s previous expectations.

This year’s Halloween assortment includes returning fan favourites and new characters designed for clothing, accessories and other personalization options.

The performance highlights the importance of the workshop to Build-A-Bear’s retail model. The process of creating and personalizing a character remains a central point of differentiation for the brand.

Canada Remains a Company-Operated Market

Canada holds a different position within Build-A-Bear’s global network than many of the international markets where the company is currently expanding.

Canadian stores are part of Build-A-Bear’s corporately managed North American operations rather than its international franchise network.

The company’s Canadian footprint spans shopping centres in Ontario, Alberta, British Columbia, Manitoba and Nova Scotia.

Recent activity includes a new Build-A-Bear Workshop at Cataraqui Centre in Kingston. The retailer also operates at CF Markville in Markham, while its CF Polo Park store in Winnipeg was repositioned within the shopping centre as part of broader changes at the property.

Build-A-Bear does not disclose Canadian sales separately, and management did not provide Canada-specific financial results during Thursday’s call.

The Canadian network provides an established platform for a business that remains closely tied to physical retail. Stuffing, dressing and personalizing characters are activities largely designed around participation inside Build-A-Bear workshops.

The importance of that model became particularly apparent during the second quarter as products offering fewer opportunities for interaction struggled to generate the response management had anticipated.

Adults and Collectors Broaden the Audience

Build-A-Bear is also expanding the audience for its products and stores.

The company increasingly identifies teens and adults as an addressable market alongside families and children, supported by nostalgia, pop culture, licensing, gifting and collectability.

Its assortment includes products tied to properties such as Pokémon, Sanrio, Harry Potter, The Nightmare Before Christmas and How to Train Your Dragon, allowing Build-A-Bear to reach fandoms extending beyond its traditional child customer.

Hurt said the company has demonstrated an ability to turn emerging trends into longer-lasting parts of its assortment. Characters including Spring Green Frog and Capybara began as trend-oriented products before becoming established offerings.

Seasonal launches are another part of the strategy, particularly as limited and returning characters generate online attention and user-created content.

Canada is included directly in the licensing push. Build-A-Bear launched a Sanrio Halloween collection Thursday featuring Berry and Cherry from Lloromannic. Hurt said Build-A-Bear is the first retailer in the U.S., Canada and U.K. to offer Lloromannic in plush form.

Canada has also been included in the retailer’s traffic-driving promotions. In June, its “Feeling the Squeeze? Get a Hug” promotion offered selected Make-Your-Own furry friends for C$15 at participating Canadian workshops.

Physical Expansion Continues

Location expansion remains one of four strategic pillars outlined by management, alongside organic growth, wholesale and outbound licensing, and gifting and personalization.

Build-A-Bear ended the second quarter with 674 locations across 37 countries. It added five net locations during the quarter and 12 during the first half of fiscal 2026.

The company continues to expect at least 50 net new experience locations this year, with most expected to be operated by international partners. The target does not represent a specific Canadian expansion plan.

Build-A-Bear is also experimenting with a more elaborate version of its store concept.

A multi-level location at ICON Park in Orlando, expected to open during the third quarter, will introduce an appointment-based design studio where customers can work with consultants to create one-of-a-kind characters.

Other additions include expanded embroidery and clothing customization, enhanced voice-recording options, a scent bar and a Build-A-Bear Bake Shop with guided dessert experiences.

Management intends to evaluate the concepts and potentially apply successful elements elsewhere in its store portfolio. No Canadian rollout of the features has been announced.

Wholesale Growth Falls Short

Build-A-Bear’s efforts to extend the brand through wholesale have progressed more slowly than anticipated.

A multi-million-dollar Walmart program from last year will not be repeated in 2026, while other wholesale opportunities are taking longer to develop. The company consequently reduced its commercial segment outlook from growth of at least 20 per cent to approximately flat performance for the year.

Management continues to view wholesale as a longer-term opportunity after the Walmart program demonstrated demand for Build-A-Bear-branded products through third-party distribution.

Build-A-Bear Approaches 30th Anniversary

Build-A-Bear will mark its 30th anniversary in 2027 with a year-long program that will include bringing popular characters from its archives back into the assortment.

The initiative is designed to reconnect longtime customers with characters they may remember from earlier visits while introducing them to a new generation.

Build-A-Bear will begin building toward the anniversary in October with a special version of longtime mascot Bearemy.

The anniversary comes as nostalgia, collectability and adult consumers take on greater importance within the company’s strategy. Licensed characters and emerging trends will remain part of the assortment as Build-A-Bear looks for additional ways to reach those audiences.

The company’s experience this summer has also provided a clearer direction for future product development. Build-A-Bear plans to continue pursuing new characters and consumer trends while maintaining the interactive elements that have helped define its stores since the company was founded.

More from Retail Insider:

Why Saskatoon Retailers Are Prioritizing CPR-Certified Staff

Walk into any busy Saskatoon shopping centre on a Saturday afternoon and you’ll see the same thing: full parking lots, long checkout lines, and floor staff who are stretched thin. Most of the time, that’s just retail. But every so often, something goes wrong — a customer collapses, a stockroom accident happens, a delivery driver gets hurt loading pallets. In those moments, the person closest to the incident is usually a part-time associate, not a manager. That’s why more retail operators are looking into CPR training near Saskatchewan Polytechnic and asking a harder question: is our floor staff actually ready for an emergency, or are we just hoping nothing happens? 

It’s a fair question to ask. Retail isn’t an office job. Staff are on their feet all shift, moving product, dealing with the public, and working around forklifts, box cutters, and hot equipment in the back of the house. The risk profile looks a lot more like a warehouse than a boardroom, but the training budget rarely reflects that. 

What Does Saskatchewan Law Actually Require of Retail Employers? 

Under Saskatchewan’s Occupational Health and Safety Act, employers have a legal duty to keep workers safe on the job, and that duty extends to having a real plan for medical emergencies. WCB Saskatchewan publishes clear guidance on the numbers: workplaces need a set ratio of trained first aid attendants on-site, and the exact requirement scales with headcount and how far the location sits from the nearest hospital. 

That math looks different from store to store. A shop a few blocks from a downtown hospital has different obligations than a big-box outlet on the edge of the city, far from emergency services. Retail HR teams that haven’t reviewed this in a while might be surprised by what’s actually required today — and by how quickly a WCB inspection can turn a quiet gap into a documented problem. 

Why Does a Retail Floor Carry More Risk Than an Office? 

Think about who actually walks through a store’s doors. Customers of every age and health condition come through, some managing heart conditions, some with severe allergies, some who are simply older and more prone to falls. Add in the hazards most shoppers never see: 

  • Stockroom ladders and overhead shelving 
  • Pallet jacks and delivery dock traffic 
  • Box cutters at nearly every register 
  • Compactors and baler equipment in the back room 
  • Walk-in coolers and freezers in grocery and food-service locations 

Now compare that to a typical office floor. Fewer members of the public, fewer moving hazards, fewer surprises. Retail carries more exposure per square foot, which is exactly why a once-a-year safety video tends to fall short on a sales floor. 

A cardiac event is a good illustration of why the gap matters. Heart & Stroke Foundation data shows that survival odds after cardiac arrest drop sharply for every minute that passes without CPR and defibrillation. A staff member who knows how to start compressions and use an AED in that first minute can be the difference between a customer walking out fine and a very different outcome. 

What’s the Real Cost of Skipping This? 

The honest answer is: usually nothing, right up until the one time it isn’t. Most shifts end without incident, which is exactly why first aid training tends to slide down the priority list behind scheduling, shrink, and sales targets. Then something happens — a slip in the stockroom, a customer’s blood sugar crashes near the fitting rooms — and the gap becomes obvious to everyone, including whoever has to explain it afterward. 

There’s also a quieter cost that doesn’t show up on an incident report. Staff who’ve never been trained tend to freeze or hesitate in a real emergency, even good employees who would otherwise handle the situation well. That hesitation is the actual risk. Training doesn’t just teach the steps; it removes the freeze response so people act instead of standing there wondering what to do next. 

How Much Time and Money Does Certification Actually Take? 

This is usually where the conversation stalls. Retailers picture a full lost shift and a training bill that doesn’t fit the budget. In practice, most Standard First Aid and CPR/AED Level C courses run a single day, often with an online theory portion completed at home before a shorter in-person skills session. That blended format cuts the in-store scheduling headache considerably, since staff aren’t pulled off the floor for the classroom half of the course. 

Spread across a handful of trained employees per location, most Saskatoon retailers find the real cost sits well below what they assumed going in — especially once it’s weighed against even one liability claim, one WCB penalty, or one bad customer experience tied to an untrained response. 

What Should a Saskatoon Retail Manager Do This Quarter? 

A first aid gap is easier to close before an inspection than after one. A short internal review usually covers what matters most: 

  • Count how many certified first aid attendants each location currently has on staff 
  • Compare that number against WCB Saskatchewan’s current ratio requirements for your headcount and distance from hospital 
  • Book certification around the blended learning format so fewer shifts are disrupted 
  • Keep certificates on file and renewal dates tracked, since WCB officers will ask for them during a review 

None of this requires a big program or a big budget. It just requires someone to actually run the numbers instead of assuming the current setup is fine. 

If you are looking for CPR and first aid training near Saskatchewan Polytechnic, downtown Saskatoon, or surrounding communities, you may reach out to Coast2Coast First Aid & Aquatics in that area. 

FAQS 

Q: How many employees actually need first aid certification under Saskatchewan law? 

A: It depends on headcount and how far your location is from the nearest hospital. WCB Saskatchewan sets the ratio, so a small downtown store and a large suburban location can have different obligations even in the same city. 

Q: Does CPR certification expire, and how often does retail staff need to renew? 

A: Most CPR/AED certifications follow a standard renewal cycle, typically around every three years, though some employers choose to recertify staff more often given turnover. Building renewal dates into your HR calendar avoids letting certificates lapse unnoticed. 

Q: Can retail staff complete first aid training without missing a full shift? 

A: Yes. Blended learning courses let staff complete the theory portion online, at home or before a shift, then attend a shorter in-person session for hands-on skills. This cuts down significantly on lost floor time compared to a full-day, in-classroom-only course. 

Q: What’s the difference between Standard First Aid and CPR/AED Level C for a retail setting? 

A: CPR/AED Level C covers cardiac emergencies and choking response for adults, children, and infants. Standard First Aid builds on that with broader injury response — cuts, burns, sprains, and other incidents more common in a stockroom or loading dock. Many retailers train key staff in Standard First Aid and cross-train the rest of the floor in CPR/AED. 

Q: What should a retailer do if a WCB officer flags a first aid gap during an inspection? 

A: Treat it as a scheduling problem, not a crisis. Identify which locations and shifts are short on certified staff, book training as soon as possible, and document the corrective action taken. Most WCB officers are looking for a credible plan and a timeline, not perfection on the spot. 

Huda Beauty teams with Cardi B on new Ultra Snatched makeup collection

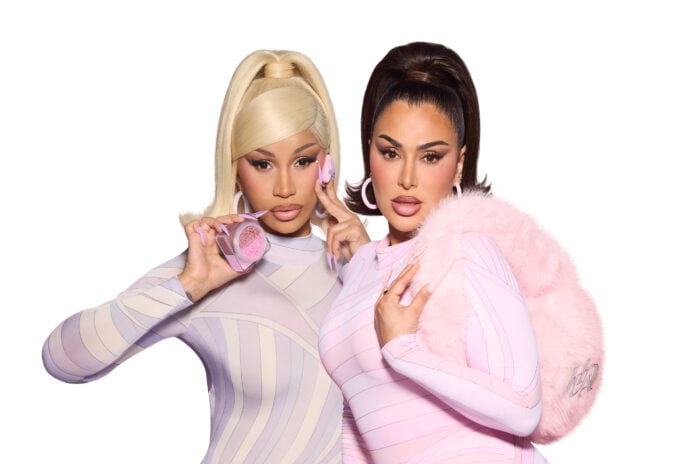
HB UltraSnatched - Cardi B and Huda Kattan

Huda Beauty is expanding its Easy Bake makeup franchise with a new collection developed in partnership with global superstar Cardi B, as the cosmetics brand adds new pink and lilac shades to its loose and pressed setting powders.

The Ultra Snatched collection includes two Easy Bake Loose Setting Powder Duos priced at $43 and two Easy Bake Pressed powders priced at $40. The launch is being supported by a campaign featuring Huda Beauty founder Huda Kattan and Cardi B.

The collection extends the brand’s Easy Bake line with a colour palette built around bright pink and cool lilac tones. Huda Beauty says the products are designed to brighten, lift and blur the appearance of the complexion.

The launch campaign, called “Snatched Baddies,” features Kattan and Cardi B and is rolling out across social media, digital channels and stores.

According to Huda Beauty, Cardi B participated in shaping the campaign’s creative direction alongside Kattan. The campaign centres on the pair trading lives as their respective worlds collide, highlighting the new collection and its makeup routine.

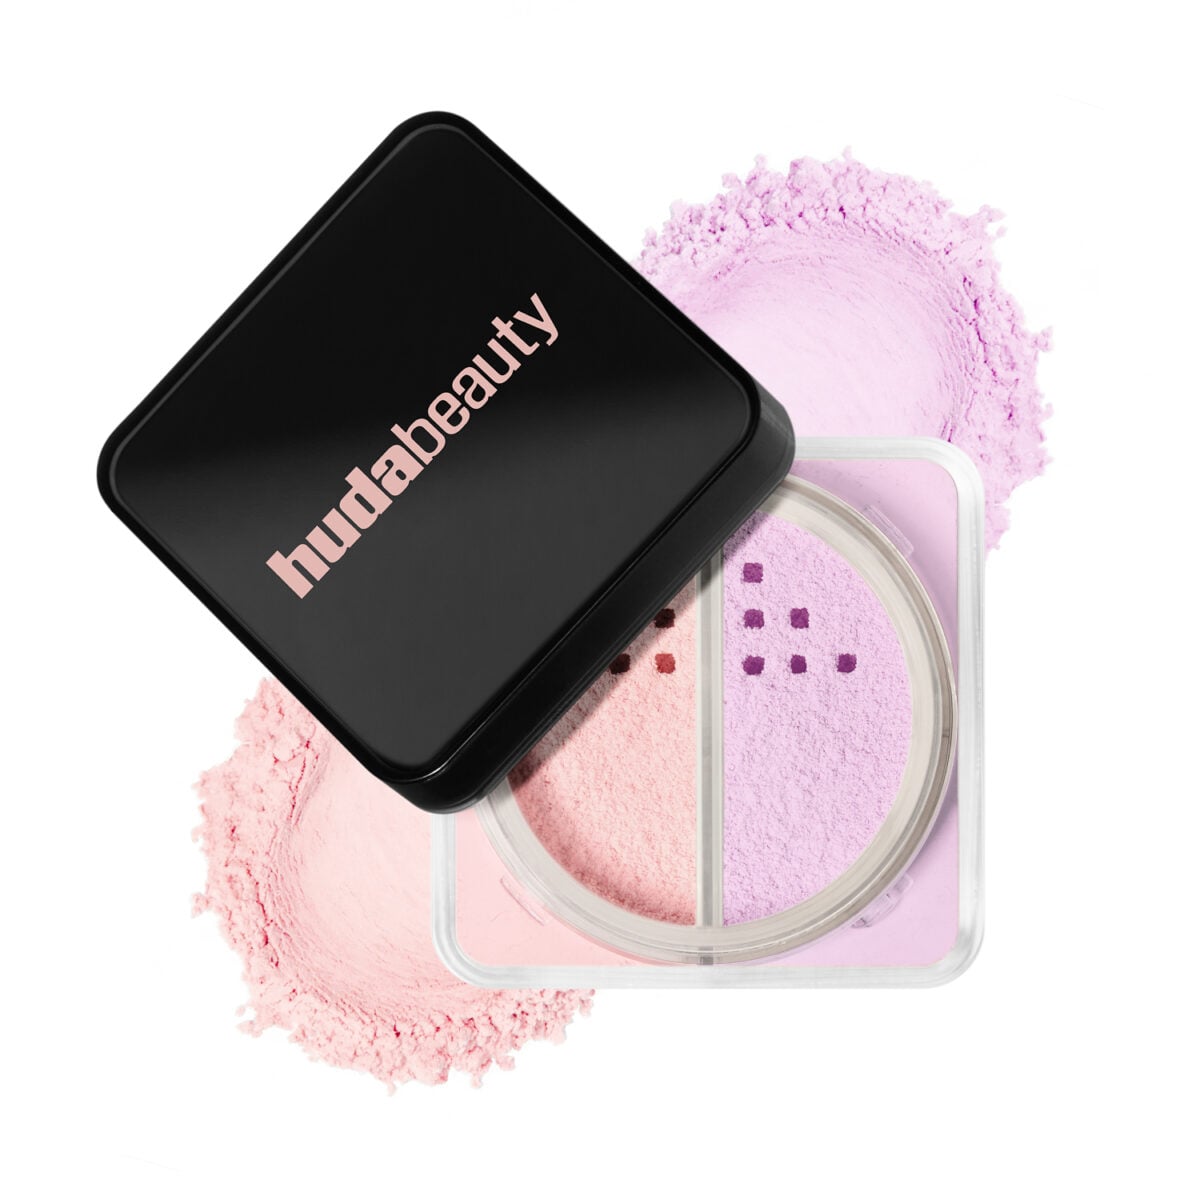
The Easy Bake Loose Setting Powder Duos contain two complementary loose powders that can be used separately or blended together. An adjustable selector allows users to choose one shade or combine both powders.

Huda Kattan photo
Huda Kattan photo

The company says the formula provides up to 18 hours of wear and an airbrushed finish without flashback.

The Cherry Lilac duo is intended for fair to light skin tones and includes Cherry Blossom Cake, described as a sheer soft pink, and new Lilac Muffin, a soft, cool-toned lilac. The shades can also be mixed to create a pinky-lilac blend.

The Pink Ube duo is intended for medium to tan skin tones and includes Pink Velvet Cookie, a deep rosy pink, and Ube Birthday Cake, an electric lilac. The combined shades create a rosy-mauve blend.

The Easy Bake Pressed powders are available in Ube Birthday Cake and Pink Velvet Cookie. Huda Beauty describes the pressed formula as a superfine, portable powder designed to provide up to 12 hours of shine control with a matte finish.

Huda Kattan
Huda Kattan

Ube Birthday Cake is described as a medium shade with cool lilac undertones, while Pink Velvet Cookie is intended for tan skin tones with warm pink undertones.

The company is also promoting the collection through its “Snatch Map” application technique, which involves strategically applying the loose powder duo to brighten and lift the complexion before layering the pressed powder.

The Ultra Snatched launch brings together Huda Beauty’s established Easy Bake franchise with Cardi B’s involvement in the campaign and product rollout, while adding new shades and formats to the collection.

More from Retail Insider:

Huda Beauty image
Huda Beauty image